



Coffee Market 2026: Why 5.4% CAGR and $360B by 2032 Change Everything

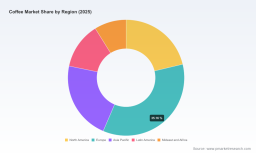
Navigating the Next Wave: Strategic Trends and Commercial Opportunities in the Global Coffee Market
The global coffee market has entered a phase of structural expansion characterized by resilient demand, evolving consumption patterns, and shifting competitive dynamics. Over the past five years, the industry has demonstrated consistent growth, with total market revenue climbing from approximately USD 191.69 billion in 2020 to an estimated USD 249.34 billion in 2025. This trajectory positions the sector on a projected compound annual growth rate of 5.4 percent through 2032, suggesting that the market will likely surpass USD 360 billion by the end of the forecast period. Such expansion is not merely a function of volume increases; it reflects deeper transformations in how coffee is sourced, processed, distributed, and consumed across both developed and emerging economies. For executives and investors, the current landscape presents a mix of substantial opportunity and complex risk, requiring a nuanced understanding of the forces shaping value creation across the supply chain.
PW Consulting Automotive & Machinery Research Center
Despite the optimistic top-line trajectory, the market faces several intersecting challenges that will define strategic decision-making in the near term. First, price volatility remains a persistent feature of the commodity cycle, with recent months illustrating how quickly supply-side improvements can compress margins and alter trading dynamics. Second, regulatory tightening around sustainability and deforestation is introducing new compliance requirements that affect every node from plantation to point of sale, particularly for operators with significant European exposure. Third, the gap between premiumization trends and everyday affordability is widening, forcing producers and retailers to navigate competing consumer expectations while managing input costs. These challenges are not isolated; they interact with each other and with broader macroeconomic conditions, creating a landscape where agility and data-informed positioning matter more than ever.
Key Drivers Reshaping Market Dynamics
Technological Innovation and Processing Breakthroughs
Innovation across the coffee value chain is moving beyond incremental product tweaks to encompass fundamental shifts in how beans are sourced, roasted, packaged, and delivered. Advances in cold-chain logistics, single-serve extraction systems, and ready-to-drink formulation have expanded the reach of coffee beyond traditional hospitality settings and into everyday retail and on-the-go consumption. At the same time, digital tools for traceability, quality control, and demand forecasting are becoming increasingly central to operational efficiency, especially for roasters and distributors managing complex multi-origin portfolios. Recent industry events have highlighted this momentum, with major trade exhibitions showcasing new equipment, product formats, and supply chain connectivity initiatives that connect producers directly with roasters and buyers. These platforms are not merely promotional; they signal a maturing ecosystem where technical differentiation and relationship-based sourcing are converging to create defensible competitive positions.
Espresso Coffee Market
Regulatory and Sustainability Imperatives
Policy and regulatory developments are no longer peripheral concerns; they are central to market access, cost structures, and brand positioning. The introduction and ongoing implementation of due diligence requirements tied to deforestation have raised the compliance bar for coffee imports, particularly within Europe, where traceability and origin verification are becoming table stakes rather than optional differentiators. Parallel trade policy shifts in key importing markets have also begun to alter cost dynamics for specific origin countries, with recent tariff adjustments removing long-standing barriers for certain Southeast Asian coffee exports. These regulatory and trade developments create a dual effect: they increase short-term administrative and verification burdens for supply chain operators, while simultaneously opening new sourcing and distribution pathways for businesses that can adapt quickly. Companies that proactively build compliance infrastructure and diversify origin portfolios are better positioned to convert regulatory pressure into competitive advantage rather than cost drag.
Shifting Consumer and B2B Demand Patterns
Demand-side behavior continues to evolve along two reinforcing axes: premiumization and convenience. Consumers across multiple regions are showing greater willingness to pay for perceived quality, origin transparency, and specialty attributes, while simultaneously expecting faster, more consistent access through ready-to-drink formats, subscription models, and expanded away-from-home channels. For business-to-business buyers, the demand picture is equally dynamic, with foodservice operators, office coffee providers, and retail chains seeking flexible supply arrangements, consistent quality, and menu differentiation that aligns with local taste preferences. The intersection of these trends is reshaping product mix decisions, channel strategies, and pricing architectures. Suppliers that can segment their offerings effectively, balancing premium narratives with accessible everyday options, are capturing a broader share of wallet across consumer and institutional buyers.
Supply Chain Reconfiguration and Cost Structure Evolution
Cost structures in the coffee sector are being reshaped by a combination of commodity cycles, logistics complexity, and origin-level production dynamics. Periods of improved harvest expectations can rapidly lower benchmark prices, creating favorable acquisition conditions for roasters and manufacturers but also compressing returns for producers and intermediaries who depend on price upside. At the same time, the cost of compliance, certification, and sustainable sourcing initiatives is becoming a more visible component of total cost of ownership, influencing which supply relationships are economically viable over the long term. The net effect is a market where supply chain design matters as much as product quality. Companies are increasingly evaluating resilience, traceability, and contractual flexibility alongside traditional cost metrics, recognizing that a lean but brittle supply chain can be more risky than a slightly more diversified and transparent one.
Competitive Landscape and Strategic Positioning
The competitive architecture of the coffee market is defined by a mix of global brands, commodity traders, and specialty-focused operators, each pursuing distinct pathways to scale and differentiation. Large multinational roasters and food-and-beverage companies continue to leverage brand equity, extensive distribution networks, and portfolio breadth to capture share across retail, foodservice, and ready-to-drink channels. Their advantage lies in the ability to standardize quality, manage large-volume procurement, and cross-sell across multiple consumer touchpoints. At the same time, major commodity handlers and green coffee traders occupy a critical intermediary role, providing origination, logistics, and risk management capabilities that link producing regions with industrial and retail buyers. Their strategic relevance is reinforced by the complexity of global sourcing and the growing need for verified, multi-origin supply streams.
Alongside these scale-oriented players, premium and specialty-focused companies are carving out positions based on origin storytelling, quality curation, and direct producer relationships. This segment benefits from the broader premiumization trend and from consumer interest in transparency and authenticity, but it also faces the challenge of balancing margin goals with ethical sourcing commitments. Recent industry gatherings have underscored this dynamic, with producer-roaster forums and specialty product award events highlighting the increasing importance of direct relationships, product innovation, and origin-level differentiation. The competitive landscape is therefore not a simple hierarchy; it is a layered ecosystem where brand power, supply chain control, product quality, and sustainability credentials each contribute to market position in different ways.
Several patterns are emerging in how leading players are adapting. Portfolio expansion into ready-to-drink and single-serve formats is allowing established brands to capture convenience-driven demand without sacrificing core retail and foodservice presence. Vertical integration and strategic sourcing relationships are being used to secure supply, reduce variability, and strengthen traceability narratives. At the same time, the market is seeing both consolidation pressure among mid-tier players seeking scale and fragmentation at the specialty end, where new entrants and regional roasters compete on authenticity, local taste profiles, and agile product development. This coexistence of consolidation and differentiation suggests that the next phase of competition will reward companies that can combine operational scale with credible specialty positioning and adaptive supply chain design.
Forward Outlook: Trends and Opportunities for 2026 and Beyond
Deepening Premiumization with Portfolio Segmentation
The premiumization trajectory is expected to continue, but its manifestation will likely become more segmented rather than uniformly upward. Consumers and business buyers will increasingly differentiate between everyday coffee needs and occasion-driven premium consumption, prompting companies to structure portfolios that serve both segments without cannibalizing each other. This creates opportunities for tiered product architectures, origin-specific lines, and format-specific innovation that align quality signals with price points and channel context. Businesses that invest in clear segmentation logic and can maintain quality consistency across tiers will be better equipped to capture growth without eroding margin integrity.
Supply Chain Transparency as a Commercial Asset
Traceability, sustainability verification, and origin storytelling are transitioning from compliance obligations to commercial assets. As due diligence requirements mature and consumer awareness of sourcing practices deepens, transparent supply chains will increasingly influence purchasing decisions, partnership selection, and brand trust. Companies that embed verification, auditable sourcing, and clear communication into their operations can convert regulatory and reputational pressures into differentiators, particularly in markets where sustainability claims are scrutinized and rewarded. The commercial opportunity lies not only in reducing risk but in using credible transparency to justify premium positioning, secure institutional contracts, and build long-term producer relationships.
Channel Convergence and Format Innovation
The boundary between on-trade and off-trade consumption continues to blur as ready-to-drink products, retail formats, and foodservice offerings converge around convenience, consistency, and experience. This convergence is encouraging product and packaging innovation designed for portability, shelf stability, and rapid preparation, while also requiring companies to manage channel-specific requirements around logistics, pricing, and brand presentation. For operators, the opportunity is to design offerings that travel well across channels without losing their identity, leveraging format innovation to extend reach into new consumption moments. The risk is that channel complexity can erode efficiency if portfolio and supply decisions are not coordinated, making integrated planning essential.
Actionable Guidance for Decision Makers
For manufacturers and roasters, the priority is to align product portfolios with the dual forces of premiumization and convenience while reinforcing supply chain resilience. This means evaluating whether current sourcing and production models can support both premium and value-tier offerings without compromising quality or cost efficiency, and whether traceability capabilities are strong enough to meet evolving compliance expectations and consumer expectations alike. Building flexibility into contracts, diversifying origin exposure, and investing in format innovation can help protect margins during commodity swings while positioning the business to capture new demand moments.
For investors, the strategic focus should be on identifying operators with credible differentiation, disciplined cost structures, and the ability to navigate regulatory and supply chain complexity. Scale alone is not sufficient in a market where premiumization, sustainability requirements, and channel convergence are reshaping competitive logic. Investment theses that account for traceability readiness, portfolio balance across formats and channels, and the quality of producer relationships are more likely to capture durable value. Equally important is monitoring how trade policy shifts and commodity cycles alter relative cost advantages across origin markets, since these dynamics can create both dislocation and entry opportunities.
For procurement and supply chain leaders, the emphasis should be on building sourcing strategies that combine cost discipline with resilience and verification. Relying on a narrow set of origins or suppliers may deliver short-term efficiency but increases exposure to climate variability, regulatory change, and price volatility. Diversifying portfolios, securing multi-year relationships with transparent producers, and integrating compliance requirements early in the sourcing process can reduce disruption risk while strengthening negotiating posture. Procurement decisions increasingly influence not only cost but also brand credibility and market access, making them a strategic lever rather than a purely operational one.
The coffee market is moving into a period where growth will be shaped less by uniform expansion and more by how effectively companies translate shifting consumer behavior, regulatory pressure, and supply chain complexity into coherent strategy. The operators that succeed will be those that treat transparency as a commercial advantage, segment portfolios with discipline, and design sourcing and production systems that can absorb volatility while capturing premium and convenience-driven demand. For decision makers seeking a deeper view of market sizing, segment trajectories, origin-level dynamics, and competitive benchmarking, the full PW Consulting market research report provides a more detailed breakdown of the data and customized recommendations for specific business contexts.
Coffee Machine Market
For detailed analysis of this topic, please visit the official page: Coffee Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


