



Solar Encapsulation Materials Market: Why 7.83% CAGR and EVA's Lead Change Strategy

Global Solar Encapsulation Materials Market: Strategic Trends & Commercial Opportunities
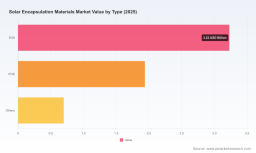
The solar encapsulation materials marketplace has matured from a commodity-driven segment into a strategically critical layer of photovoltaic module performance and longevity. During the 2020-2025 historical period, the sector demonstrated steady expansion, driven by accelerating photovoltaic deployment, material innovation, and shifting module architectures. Current valuations place the overall market at approximately 5.87 billion USD for 2025, with a projected trajectory toward 9.95 billion USD by 2032. This expansion reflects a compound annual growth rate of 7.83 percent across the 2026-2032 forecast window, signaling sustained structural demand rather than cyclical fluctuations.
Behind these headline figures lies a more nuanced transformation. Encapsulation has evolved from a passive protective function to an active enabler of module efficiency, reliability, and warranty economics. This shift is reshaping competitive dynamics, supply network configurations, and investment priorities. Decision-makers evaluating exposure to solar value chains must look beyond volume growth and understand the material, technological, and geographic realignments that are redefining commercial viability in this segment.
Market Snapshot and Structural Realities
The encapsulation sector operates at the intersection of polymer engineering, module architecture, and long-term performance guarantees. Crystalline silicon photovoltaic systems continue to anchor the majority of demand, reflecting their dominant position across utility-scale, commercial, and residential installations. Within the material mix, ethylene vinyl acetate (EVA) retains a leading position, accounting for roughly 55 percent of the market in 2025, while polyolefin elastomer (POE) represents the fastest-growing category, driven by compatibility with advanced cell architectures and improved moisture and potential-induced degradation resistance.
Regional demand is distributed across major solar manufacturing and deployment hubs, with North America holding a notable share, Asia Pacific maintaining strong volume leadership, and Europe sustaining steady consumption supported by local manufacturing incentives and project pipeline development. The market remains moderately concentrated, with the top three suppliers capturing approximately 62.5 percent of revenue and the top five reaching around 75.0 percent. This structure indicates that scale, formulation expertise, and module-maker relationships confer meaningful advantages, even as demand fragmentation across geographies and module types creates room for specialized entrants.
Key Challenges and Inflection Points
Despite the constructive growth outlook, the market faces structural frictions that will determine which participants capture value in the next cycle. Three challenges stand out as particularly decisive.
LED Encapsulation Market
Material specification pressure and warranty economics. Twenty-five-year module warranties have become standard expectations rather than premium differentiators. Encapsulants must now demonstrate high gel content, robust moisture barriers, and sustained potential-induced degradation resistance under diverse operating conditions. Failure to meet formulation thresholds increases financial exposure for module makers and complicates downstream bankability. The requirement for gel content above 50-70 percent for POE and EPE formulations, and above 75-80 percent for EVA, illustrates how material performance has become a gatekeeper for commercial acceptance.
Architecture transitions reshaping demand composition. The rise of TOPCon, heterojunction, bifacial, and tandem-oriented concepts is changing encapsulant requirements. Traditional EVA formulations optimized for earlier-generation cell designs require reformulation or replacement when paired with high-efficiency back-contact structures, bifacial light management, or emerging perovskite combinations. Suppliers that can deliver co-extruded solutions tailored to these architectures are gaining strategic relevance, while general-purpose material providers face margin and volume pressure.
Supply network localization and geopolitical realignment. End-users and manufacturers increasingly prioritize supply resilience over lowest-cost sourcing. The expansion of U.S. production capacity for high-performance encapsulants reflects a broader effort to reduce import dependencies and align material availability with domestic module assembly and deployment timelines. At the same time, emerging manufacturing centers in South and Southeast Asia are driving regional demand for cost-competitive yet specification-grade encapsulants. These parallel forces are bifurcating procurement strategies between premium localized supply and volume-driven regional sourcing.
Strategic Drivers Reshaping the Market
Technology Innovation and Formulation Breakthroughs
Encapsulation technology is moving rapidly from commodity film production to engineered material systems that support incremental module efficiency gains and durability requirements. Co-extruded structures are gaining prominence because they enable layered functionality, such as improved UV stabilization, enhanced moisture resistance, or tailored optical properties, without requiring separate processing steps. For bifacial modules, premium anti-reflective and optimized encapsulant films can deliver absolute efficiency improvements in the range of 0.5-1.0 percent, which translates into meaningful energy yield differences over a project lifecycle. This performance link justifies price premiums in the order of 15-25 percent for specification-grade films and reinforces the commercial logic of advanced material investment.
Recent product activity confirms the pace of innovation. Next-generation co-extruded POE and EPE formulations optimized for TOPCon and bifacial modules have advanced toward commercialization, with some offerings demonstrating enhanced potential-induced degradation resistance beyond 300 hours. In parallel, new encapsulant film generations incorporating UV down-conversion technology and ultrafast-cure EVA variants have entered the market alongside capacity expansions designed to support higher-volume deployment. These developments indicate that material innovation is no longer confined to laboratory feasibility; it is being scaled into commercial supply pipelines linked to module-maker qualification cycles.
Policy, Regulation, and Warranty-Driven Standards
Regulatory and financing environments are tightening the performance bar for encapsulants indirectly but powerfully. Long-duration warranties, bankability requirements, and durability expectations are translating into practical formulation thresholds. Advanced encapsulants for bifacial and next-generation modules must meet stringent moisture barrier and potential-induced degradation resistance requirements to support extended warranty commitments. This has elevated the importance of certificate-backed validation, standardized testing, and consistent batch quality.
At the same time, industrial policy and trade dynamics are reshaping where production is located and how supply chains are structured. Domestic capacity expansion in the United States is reducing exposure to cross-border disruptions for high-performance encapsulants used in advanced module types. This localization trend is not merely about cost; it is about securing predictable supply for products where qualification cycles are long and switching costs are high. In parallel, export-oriented manufacturers in Asia are aligning production with regional demand centers and international qualification requirements, creating a more geographically diversified but increasingly specification-sensitive competitive landscape.
Demand-Side Evolution and Module Architecture Shift
Demand growth is being shaped by both volume and value. Solar installation continues to expand across utility, distributed, and commercial segments, but the more strategically important shift is the changing composition of module technology adoption. Crystalline silicon remains the backbone of the market, yet the rising share of high-efficiency variants is altering encapsulant selection criteria. Bifacial modules, TOPCon cells, and back-contact configurations increasingly require materials that preserve optical performance while protecting cell interfaces over decades of operation.
For module manufacturers, this means encapsulant choice is becoming a design decision with direct implications for energy yield, degradation profile, and total cost of ownership. For buyers of finished modules, encapsulant quality is increasingly visible through warranty terms, degradation guarantees, and long-term performance expectations. As a result, encapsulant material is transitioning from a hidden component to a value-differentiating element in product positioning, especially in competitive segments where efficiency and reliability claims are scrutinized during procurement and financing.
Supply Chain and Cost Structure Dynamics
Cost structure evolution is being driven by raw material economics, processing complexity, and the premium attached to specification-grade products. Polyolefin-based materials are growing faster than established EVA streams, supported by their compatibility with advanced module designs and improved durability profiles. However, higher-performance films often involve more complex extrusion and formulation requirements, which affect conversion economics and supplier capability thresholds.
The cost dynamic is not simply about raw material price movement; it is about the widening spread between standard and premium encapsulants. Suppliers capable of delivering consistent high gel content, UV stabilization, and co-extrusion performance can capture meaningful margins through specification differentiation, while undifferentiated commodity production faces intensifying competition and pressure from regional capacity additions. This bifurcation is encouraging strategic positioning around either volume reliability or advanced material differentiation, with limited middle ground for players unable to meet either cost or specification targets consistently.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The competitive field combines large multinational polymer and materials companies with specialized regional manufacturers that have built strong relationships with module makers and emerging production hubs. Several patterns define current strategic positioning.
Hangzhou First PV Material Co., Ltd. has established a strong position as a large-scale producer of EVA and POE encapsulation films for crystalline silicon modules, with a product focus that extends to TOPCon, heterojunction, bifacial, and high-efficiency applications. Its scale and breadth allow it to address mainstream and advanced architectures simultaneously, making it a relevant reference point for suppliers seeking to balance volume and specification growth.
Jiangsu Sveck New Material Co., Ltd. has built a profile around EVA, POE, and high-performance co-extruded encapsulant films, with particular emphasis on serving module manufacturers in emerging markets such as Vietnam and India. This geographic orientation reflects an understanding that demand growth is not limited to established hubs and that regional supply proximity can reduce logistics risk and improve responsiveness.
Shanghai HIUV New Materials Co., Ltd. has focused on high-performance polymer materials and UV-resistant encapsulation technologies, emphasizing long-term stabilization and durability. This durability-centered positioning aligns with warranty-driven procurement and suggests a strategy oriented toward performance assurance rather than lowest-cost volume.
Changzhou Betterial Film Technologies Co., Ltd. has moved toward advanced polymer film solutions for photovoltaic encapsulation, including tandem perovskite and back-contact module technologies. This forward-looking product direction illustrates how some suppliers are positioning for next-generation cell concepts before they reach mass deployment, aiming to secure early qualification advantages.
Zhejiang Sinopont Technology Co., Ltd. is expanding its development of high-barrier co-extruded encapsulation films and TOPCon-compatible POE materials, reinforcing the broader industry emphasis on formulation precision for advanced cell architectures. Similarly, Hanwha Solutions, Mitsui Chemicals, Kuraray, SKC, Bridgestone, and Coveme represent established material capabilities and regional strengths, while U.S. and European names such as 3M, STR Holdings, Dow, DuPont, and Eastman contribute advanced polymer chemistry and specialty encapsulant expertise.
RenewSys India and Alishan Green Energy illustrate the growing role of Indian manufacturers in EVA, POE, EPE, and TPO supply. Alishan's recent moves are particularly notable: the company launched a new generation of encapsulant films including low-acid EVA, EPE-NT, and EPE-DC with UV down-conversion technology, expanded capacity to approximately 6.6 GW, and continued toward a 10 GW target by the end of 2026. This scale-up, combined with product differentiation, signals that emerging-market suppliers are not only competing on cost but are also building specification-grade portfolios for advanced applications.
Evolution of Market Structure
The market is simultaneously consolidating at the top and fragmenting in the middle. Concentration among leading suppliers reflects the advantages of scale, formulation depth, qualification track records, and long-standing relationships with module manufacturers. At the same time, technological differentiation is creating niches for specialized players focusing on co-extrusion, UV management, ultrafast curing, or next-generation cell compatibility.
Chip Encapsulation Resin Market
This dual dynamic suggests that the competitive frontier will not be defined purely by price. Instead, it will be shaped by the ability to meet specific module requirements, support qualification timelines, maintain batch consistency, and provide supply continuity in a geopolitically sensitive environment. New entrants with differentiated technology can gain traction in targeted segments, but broad-based competition is intensifying where specifications are relatively standardized and regional capacity is expanding. As manufacturing footprints shift and advanced module adoption accelerates, the landscape is likely to reward suppliers that can combine technical precision with dependable commercial execution.
Forward Outlook: Trends for the Next 3-5 Years
Trend 1: Advanced, Co-Extruded, and Architecture-Specific Encapsulants Will Become the New Baseline for Premium Modules
Over the next several years, co-extruded and architecture-tailored encapsulants will move from differentiated offerings to expected components in high-efficiency and bifacial modules. TOPCon and bifacial adoption will continue to expand, and suppliers that can deliver formulations optimized for moisture resistance, UV behavior, and potential-induced degradation control will be better positioned to secure qualification and repeat procurement. The commercial implication is clear: module manufacturers will increasingly weigh encapsulant performance as part of product design rather than treating it as a generic input.
For suppliers, this trend favors investment in formulation engineering, testing infrastructure, and application-specific product lines. For buyers, it means selection criteria will shift toward proven compatibility with target cell architectures and verifiable long-term stability. The opportunity lies in aligning encapsulant development with module roadmaps early, reducing rework and qualification delays.
Trend 2: Regional Supply Localization Will Deepen Where Premium Modules Are Made and Deployed
Localization of high-performance encapsulant production will continue in regions where advanced module manufacturing and project deployment are concentrated. In the United States, facility expansions for advanced encapsulants are strengthening domestic supply for bifacial, TOPCon, and next-generation high-efficiency modules, mitigating import dependencies from Asia. This pattern is likely to encourage parallel investments in other regions seeking to secure material availability for domestic manufacturing and export-quality production.
PW Consulting
The strategic implication is that supply chain design will become more regionalized and more sensitive to qualification continuity. Suppliers that can build localized capacity or reliable regional partnerships will increase their relevance to customers who prioritize resilience and predictable delivery. At the same time, cost-competitive regional producers in Asia will continue to serve volume demand, creating a market structure where premium localization and efficient regional supply coexist.
Trend 3: Durability-Weighted Procurement Will Redefine Value Comparison Across Materials
Procurement decisions will increasingly incorporate lifetime performance considerations rather than initial material cost alone. Warranty expectations, degradation profiles, and bankability requirements are pushing buyers to evaluate encapsulants through the lens of long-term reliability. Gel content thresholds, moisture barrier performance, and potential-induced degradation resistance are becoming practical decision metrics because they directly affect warranty exposure and asset longevity.
This shift creates opportunity for suppliers that can document durability with consistent quality and credible validation. It also introduces risk for manufacturers that compete primarily on price without robust formulation control. Over time, the market will likely see more explicit differentiation between standard and premium encapsulant tiers, with premiums justified by efficiency, durability, and qualification readiness rather than brand alone.
Risks and Uncertainties
While the outlook is favorable, several uncertainties could alter the pace or direction of value capture. Raw material cost volatility and polymer feedstock dynamics can affect margins, especially for suppliers with limited pricing power. Overcapacity in commodity-grade production could compress returns if demand growth does not absorb new capacity in certain regions. Qualification cycles are lengthy and can delay the commercial payoff of advanced formulations, creating execution risk for companies investing ahead of module adoption curves. Finally, technology transitions in next-generation cells, including tandem and back-contact concepts, remain uneven in timing and scale, which could shift encapsulant demand patterns faster than suppliers anticipate.
Actionable Guidance for Decision-Makers
For Module Manufacturers
Treat encapsulant selection as a product architecture decision rather than a procurement commodity exercise. Align material qualification with your cell technology roadmap, prioritizing suppliers that can demonstrate compatibility with bifacial, TOPCon, and other advanced designs while maintaining batch consistency. Build early-stage testing and qualification into development plans to reduce launch risk and avoid late-stage redesigns. Where warranty and bankability requirements are stringent, prioritize documented durability metrics such as gel content, moisture barrier performance, and potential-induced degradation resistance alongside cost.
For Investors and Strategic Buyers
Evaluate exposure to encapsulant suppliers based on technology differentiation, regional supply positioning, and qualification relationships rather than volume alone. Companies with credible co-extrusion capabilities, UV and durability-focused formulations, and the ability to scale advanced materials for high-efficiency modules are better positioned to capture premium segment growth. At the same time, assess whether capacity expansions are aligned with actual regional demand and whether pricing power is sustainable given regional supply additions. Portfolio value will increasingly depend on a supplier's ability to serve specification-grade demand without being dragged into undifferentiated commodity competition.
For Procurement and Supply Chain Leaders
Diversify sourcing strategies to balance premium localized supply with regional volume options, especially where module assembly, deployment, and warranty exposure create supply continuity requirements. Use qualification lead times to build relationships with suppliers that can support long-term consistency rather than short-term spot pricing. Incorporate performance-based criteria into purchasing decisions, including durability validation and compatibility with target module architectures. This approach reduces switching risk and strengthens resilience against supply disruptions, qualification delays, and regional production shifts.
The strategic significance of encapsulation materials will continue to rise as module architectures become more advanced and warranty expectations more demanding. Market participants that understand the interplay between formulation innovation, regional supply strategy, and procurement-driven durability requirements will be best positioned to manage risk and capture value. For professionals seeking deeper segmentation detail, competitive benchmarking, and tailored scenario analysis across regions and applications, the full PW Consulting research report provides expanded data sets and customized strategic guidance to support immediate planning decisions.
For detailed analysis of this topic, please visit the official page: Solar Encapsulation Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


