



Gas Detectors Market Surges Past $6.2B Why the 6.5% Growth Trajectory Changes Everything

Strategic Trends and Commercial Opportunities in the Global Gas Detectors Market
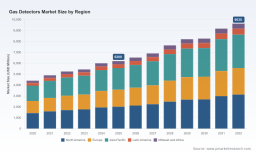
The global gas detectors market has entered a phase of sustained expansion, driven by tightening safety regulations, technological maturation, and a structural shift toward connected, real-time monitoring solutions. Over the historical period from 2020 through 2025, the market advanced from approximately $4.4 billion to $6.2 billion, reflecting steady year-over-year growth as industrial operators, municipal authorities, and energy infrastructure providers increasingly prioritized early detection and continuous environmental monitoring. Looking ahead to the 2026–2032 forecast window, the trajectory points toward a compound annual growth rate of 6.5 percent, with total market value projected to reach nearly $9.6 billion by the close of the period. This growth is not merely a function of incremental replacement cycles; it represents a broader realignment in how organizations conceptualize safety infrastructure, moving from passive, compliance-driven installations toward active, data-integrated monitoring ecosystems.
Market Structure and Concentration Dynamics
The market demonstrates a moderately concentrated structure, with the top three competitors collectively accounting for roughly 58 percent of overall revenue and the top five firms capturing approximately 72 percent. This concentration signals the presence of entrenched incumbents with established distribution channels, mature product portfolios, and significant brand recognition across industrial and municipal verticals. However, the remaining market share is distributed among a diverse set of regional specialists, application-focused manufacturers, and emerging players targeting niche monitoring requirements. The coexistence of dominant global players and agile niche suppliers creates a competitive environment where differentiation increasingly hinges on connectivity capabilities, regulatory compliance readiness, and application-specific engineering rather than raw sensor performance alone.
Key Challenges and Inflection Points
Despite the favorable growth trajectory, the market faces several structural challenges that will shape competitive outcomes over the next five years. First, the regulatory landscape is fragmenting across jurisdictions, with local building codes, pipeline safety mandates, and occupational health standards imposing divergent performance and installation requirements. Organizations operating across multiple regions must navigate inconsistent certification pathways and compliance timelines, which increases integration complexity and raises total cost of ownership for multi-site deployments. Second, the transition from standalone detection hardware to connected, networked monitoring systems introduces cybersecurity, data interoperability, and lifecycle management concerns that many traditional manufacturers are still addressing through product development and service model adaptation. Third, supply chain volatility for specialized sensing components, calibration gases, and semiconductor-based detector elements continues to pressure margins and constrain rapid scale-up for new product lines. These challenges are not insurmountable, but they require strategic foresight and investment in cross-functional capabilities that extend beyond core hardware engineering.
Key Drivers Shaping Market Evolution
Technological Innovation and Sensor Advancement
Advancements in sensor technology are fundamentally reshaping product capabilities and expanding the addressable use cases for gas detection. Infrared-based sensing, enhanced electrochemical cell designs, and improved catalytic bead configurations have increased detection precision, reduced false alarm rates, and extended operational life in harsh environments. Simultaneously, the integration of wireless communication modules, edge computing capabilities, and cloud-anchored fleet management platforms has transformed portable and fixed detectors from isolated warning devices into interconnected nodes within broader safety and asset monitoring networks. Manufacturers that have embedded connectivity into their product architectures are enabling centralized visibility across large facility footprints, real-time alarm escalation, and predictive maintenance workflows that reduce downtime and improve response coordination.
Policy and Regulatory Momentum
Regulatory activity has accelerated across multiple jurisdictions, creating both compliance-driven demand and opportunities for early-adopting solution providers. Recent municipal and federal requirements have mandated natural gas alarms and zoned detection systems in specific residential and commercial building categories, establishing new installation baselines and product specification thresholds. Pipeline safety rules have further emphasized the need for commercially available leak detection equipment that meets defined performance standards, pushing operators to upgrade legacy monitoring approaches with validated, interoperable solutions. Occupational safety guidelines continue to reinforce the requirement for routine air monitoring in hydrogen sulfide and other hazardous gas environments, with renewed emphasis on training, device qualification, and documented compliance. Collectively, these regulatory shifts are converting safety detection from an optional best practice into a codified operational necessity across housing, energy transport, and industrial processing sectors.
Demand-Side Shifts in Operational Behavior
Demand patterns reflect a broader organizational move toward proactive risk management rather than reactive incident response. Facilities managers, safety directors, and operations leaders are increasingly seeking integrated monitoring strategies that combine area-fixed systems with personal and portable units, enabling layered protection across confined spaces, process zones, and perimeter areas. Fleet operators and emergency response organizations are prioritizing devices that support centralized management, automatic reporting, and integration with existing workforce safety platforms. This behavior shift is particularly pronounced in sectors where downtime carries high financial and reputational costs, and where regulatory scrutiny has intensified following high-profile incidents and investigative reports highlighting gaps in residential and commercial fuel-gas detection practices.
Supply Chain and Cost Structure Considerations
Cost structures are being reshaped by the increasing incorporation of digital services, calibration management programs, and extended warranty or lifecycle support offerings. While core sensor and housing costs remain important, the total value proposition now includes software licensing, data subscription models, remote diagnostics, and on-site service networks. Organizations that have built robust service ecosystems are able to smooth revenue streams and deepen customer stickiness, while those that remain purely hardware-focused face margin compression from price competition and component cost variability. Supply chain resilience has therefore become a strategic differentiator, with leading players investing in component sourcing diversification, inventory buffering for critical sensor elements, and regional manufacturing or assembly footprints to reduce exposure to logistical disruptions.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market's leading companies have built their positions through a combination of broad product portfolios, established industry credibility, and targeted application specialization. Large diversified manufacturers offer comprehensive fixed and portable solutions spanning multi-gas monitoring, flame detection, and hazardous-area certification, allowing them to serve integrated safety programs across industrial, utility, and mining environments. Specialized safety companies have strengthened their standing through reputation for rugged reliability, confined-space expertise, and strong relationships with industrial customers who prioritize worker protection and compliance documentation. European and North American manufacturers alike have advanced their positions by embedding connectivity into flagship portable and fixed product lines, enabling fleet-wide visibility and compliance tracking. Mid-tier and niche players have carved out defensible positions by focusing on specific gas targets, such as hydrogen-specific monitoring for emerging energy applications, or by delivering bespoke fixed detection engineering for demanding process environments.
Strategic Themes Among Leading Players
Several strategic themes are evident across the competitive field. One is the convergence of personal protection and area monitoring into unified safety architectures, with product lines designed to share communication protocols, data standards, and management interfaces. Another is the emphasis on hydrogen-ready and multi-gas flexible detection, reflecting the expansion of new energy infrastructure and the need for equipment that can adapt to shifting gas compositions and operational scenarios. A third theme is the strengthening of aftermarket and service capabilities, including calibration programs, detector refurbishment, and remote health monitoring, which convert one-time capital purchases into recurring engagement models. Trade show participation and product launch cadence have become important signals of market intent, with companies showcasing fire-rescue, civil protection, and industrial detection solutions at major international events, while simultaneously rolling out new portable monitor series and updated product catalogs to refresh portfolios and address emerging application requirements.
Market Evolution: Consolidation, Differentiation, and Entry Dynamics
The competitive landscape is evolving along multiple axes. Consolidation pressure remains present among mid-sized suppliers seeking scale in manufacturing, distribution, or service delivery, while larger incumbents continue to evaluate targeted acquisitions or technology partnerships that can accelerate connectivity, sensor diversification, or geographic reach. At the same time, market differentiation is increasingly likely to occur at the application and integration level rather than through generic hardware specifications alone. New entrants and regional specialists can find viable openings by addressing underserved gas targets, tailoring solutions to specific regulatory frameworks, or offering lighter-cost portable options for emerging markets and smaller contractors. However, successful entry typically requires credible certification coverage, reliable supply relationships, and a clear path to either service attachment or channel partnership, given the importance of compliance assurance and lifecycle support in customer purchasing decisions.
Future Trends and Commercial Implications
Trend 1: Connected Safety Ecosystems as the New Baseline
Over the next three to five years, connected detection architectures are expected to become a standard expectation rather than a premium differentiator. Fixed and portable devices will increasingly operate as integrated elements within facility-wide safety and operational technology environments, with data flowing into centralized dashboards, automated alarm escalation workflows, and compliance reporting systems. For manufacturers, this trend creates opportunities to expand software and service attach rates, develop interoperable data standards, and position hardware as entry points to broader subscription-based monitoring programs. For end users, the implication is a shift in procurement criteria toward platform compatibility, data retention policies, integration effort, and total lifecycle cost, rather than sensor price alone.
Trend 2: Regulatory Normalization Across Residential, Pipeline, and Industrial Domains
Regulatory momentum across building codes, pipeline safety mandates, and occupational monitoring requirements is expected to continue normalizing gas detection as a codified infrastructure component. As codes and standards become more explicit about installation zoning, performance thresholds, and maintenance obligations, demand for compliant, certifiable equipment will broaden beyond traditional heavy industrial settings into municipal housing, commercial buildings, and energy transport operations. This opens addressable market expansion for manufacturers with proven certification portfolios and documented compliance support, while raising the bar for competitors that lack established testing records or regional code familiarity. Organizations that invest early in aligning product specifications with emerging code expectations will be better positioned to capture procurement cycles as mandates take effect.
Trend 3: Application Expansion Into New Energy and Specialized Environments
The growing focus on hydrogen-related monitoring, combined with continued demand in oil and gas, chemicals, mining, and emergency response contexts, is broadening the application base for both fixed and portable systems. New energy infrastructure, fleet management requirements, and specialized confined-space operations are driving interest in detectors that can handle evolving gas compositions, support rapid deployment, and integrate with existing safety and logistics workflows. This expansion creates opportunities for companies that can deliver application-engineered solutions, flexible calibration and sensor swap options, and clear guidance on deployment best practices. The corresponding risk is that rapid application diversification can strain product development resources and complicate quality assurance if not managed with disciplined platform architecture and careful validation protocols.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Prioritize platform-level design that allows sensor modules, communication interfaces, and management software to evolve without requiring full product line replacements. Invest in certification coverage and compliance documentation that align with the most demanding regional requirements, as these credentials increasingly function as market-access prerequisites rather than optional endorsements. Strengthen aftermarket and service capabilities, including calibration programs, remote diagnostics, and detector lifecycle management, to build recurring revenue and deepen customer retention. Evaluate targeted partnerships or technology acquisitions that can accelerate connectivity, data interoperability, or application-specific detection capabilities, particularly where internal development timelines would lag market expectations.
PW Consulting Automotive & Machinery Research Center
For Investors and Strategic Planners
Focus due diligence on companies that demonstrate a credible transition from hardware-only revenue models to integrated hardware-plus-service portfolios, as this shift often correlates with improved revenue visibility and customer lock-in. Assess exposure to regulatory-driven demand across pipeline safety, residential and commercial building codes, and occupational health mandates, since these drivers can create durable procurement cycles that are less sensitive to short-term industrial cyclicality. Monitor competitive signals such as product launch cadence, trade show positioning, and fleet-management integration capabilities, which often indicate which players are executing effectively on market evolution rather than reacting to it. Be attentive to margin dynamics in sensor supply chains and to the cost implications of connectivity features, as these factors will shape profitability trajectories across the forecast period.
For Procurement and Safety Operations Leaders
When evaluating detection solutions, expand evaluation criteria beyond unit price to include total cost of ownership, interoperability with existing safety platforms, data access and retention terms, calibration and service arrangements, and the supplier's ability to support multi-site compliance documentation. Prioritize architectures that enable layered protection across fixed area monitors, portable units, and personal devices, ensuring coverage continuity as personnel and operations move across zones. Require clear evidence of certification alignment with applicable regional codes and standards, and confirm that the solution provider can deliver training, refresher support, and documented maintenance processes that satisfy both internal safety programs and external audit requirements.
Worldwide Carbon Dioxide Detector Market
Closing Perspective
The gas detectors market is moving through a period of meaningful structural change, where growth is being driven not only by incremental replacement demand but by a broader redefinition of safety detection as a connected, compliance-embedded, and application-diversified capability. Organizations that align product strategy, service design, and regulatory readiness with these shifts will be best positioned to capture value as the market advances toward the end of the decade. The commercial opportunities are substantial, but realizing them requires disciplined investment in platform architecture, certification coverage, and lifecycle support, paired with a clear understanding of where regulatory, technological, and demand-side momentum are converging. For decision-makers seeking deeper granularity on segment dynamics, regional demand patterns, competitive benchmarking, and customized scenario planning, a comprehensive research report provides the detailed data and structured analysis necessary to translate these strategic themes into precise, actionable plans.
Radiation Detector Market
For detailed analysis of this topic, please visit the official page: Gas Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


