



Full Body Scanner Market 2026: Why 9.8% CAGR Signals a Structural Shift

The Invisible Shield: Strategic Trends and Commercial Opportunities in the Full Body Scanner Market
Global security screening has entered a phase of accelerated evolution. The full body scanner market, valued at approximately $390 million in 2025, has expanded from a niche security technology into a critical infrastructure component spanning aviation, critical facilities, and institutional protection. With a projected compound annual growth rate of 9.8 percent through 2032, the market is expected to surpass $745 million by the end of the forecast period. This trajectory reflects more than steady demand growth; it signals a structural shift in how governments, transport operators, and facility managers approach threat detection. The sector is moving from reactive, checkpoint-based screening toward continuous, intelligent, and minimally disruptive security architectures. For executives and capital allocators, understanding the forces reshaping this space is no longer optional. It is a prerequisite for positioning assets, product roadmaps, and procurement strategies in a landscape where regulatory expectations, technological maturity, and operational throughput are converging.
Market Landscape and Structural Friction
The size and growth rate of the full body scanner market tell a clear story of expanding adoption, but the underlying dynamics reveal where pressure points are forming. Demand has been historically anchored in transport security, particularly aviation checkpoints, where passenger volumes, regulatory mandates, and threat evolution keep procurement cycles active. At the same time, the market is broadening into critical infrastructure protection and institutional environments, driven by heightened awareness of concealed threats and the need for non-intrusive screening in sensitive zones.
This expansion is not frictionless. Three structural challenges are shaping how the market will mature over the next several years.
Balancing Throughput with Privacy and User Experience
Security technology has long faced the tension between thoroughness and speed. Full body scanners must detect concealed objects without creating bottleneck conditions or eroding public trust. As deployments scale beyond major international hubs into regional airports, mass transit facilities, and correctional or government environments, operators are increasingly sensitive to passenger and visitor experience. Solutions that reduce false alarm rates, shorten inspection cycles, and avoid ionizing radiation are becoming competitive differentiators rather than optional features. Equipment that imposes excessive operational friction risks underutilization, regardless of technical capability.
Certification Complexity and Interoperability
The regulatory environment for people screening continues to tighten, and that reality is reshaping procurement timelines. Advanced imaging systems must meet detection capability standards, operational safety requirements, and increasingly specific deployment guidelines. Recent clarifications in checkpoint planning guidance and the certification of specific millimeter-wave and transmission X-ray platforms illustrate how compliance is becoming more structured and more demanding. The upside is clearer procurement criteria. The downside is longer validation cycles, region-specific certification pathways, and the need for vendors to demonstrate performance under standardized conditions. For buyers, this creates a more predictable but more rigorous evaluation process. For suppliers, it raises the barrier to entry and rewards platforms with proven certification histories.
Market Fragmentation and Contracting Dynamics
Market concentration remains relatively modest, with leading players holding a combined share that leaves substantial room for regional specialization, application-specific deployments, and localized service ecosystems. That structure has benefits: it allows differentiated solutions to gain traction in specific verticals. It also creates complexity for enterprises trying to standardize equipment across multiple sites or geographies. Procurement teams must weigh the advantages of specialized systems against the operational burden of managing multiple platforms, training regimes, and maintenance contracts. As large-scale events and multi-site security programs accelerate, the pressure to harmonize equipment while retaining flexibility will intensify.
Core Drivers Reshaping Demand and Capability
Behind the headline growth numbers, several interconnected drivers are redefining what buyers expect from full body screening technology and how suppliers compete.
PW Consulting
Technology Innovation: From Detection to Intelligent Interpretation
The most consequential shift is the move from raw imaging toward AI-assisted detection and automated threat interpretation. Modern millimeter-wave and transmission X-ray platforms are increasingly designed to reduce operator workload by highlighting anomalies, classifying object types, and lowering false alarm rates. This matters operationally because screening throughput is no longer determined solely by hardware speed. It is increasingly defined by the total inspection workflow, including alarm resolution, repatron screening frequency, and staff training requirements. As systems become more interpretable and adaptive, they enable faster passenger flow, more consistent detection outcomes, and broader deployment in environments where highly specialized operators may not be available.
Policy and Regulatory Momentum
Regulatory activity is acting as both a constraint and a catalyst. Updated checkpoint planning guidance has helped clarify expectations for advanced imaging technology deployments, while certification milestones for specific scanner families have established new reference points for airport and checkpoint use. In parallel, policy discussions are expanding the scope of where body imaging equipment can be deployed, with legislative activity opening doors to screening in correctional and institutional settings. The practical effect is twofold. First, compliance is becoming more standardized, which favors established platforms with documented certification trails. Second, new application areas are being formally recognized, creating incremental demand beyond traditional transport security.
Demand-Side Evolution Across Sectors
Demand is no longer driven by a single sector’s procurement cycle. Aviation remains a central anchor, but the rationale is broadening. High-profile international events, expanding mass transit networks, and increased attention to facility hardening are pushing security planners to evaluate full body scanners as part of layered screening architectures. The growing emphasis on non-ionizing solutions also reflects changing risk calculations. Operators in high-throughput environments want effective detection without introducing additional radiation exposure concerns or complex safety protocols. This is particularly relevant as screening moves into settings where public familiarity with security procedures may be lower and user acceptance becomes a critical success factor.
Cost Structure, Service Models, and Deployment Economics
The commercial character of the market is shifting alongside the technology. Procurement decisions increasingly factor in total cost of ownership rather than upfront hardware price alone. Maintenance agreements, calibration requirements, software updates, and operator training all influence the economic case for a given platform. At the same time, contract activity around large-scale and time-bound deployments demonstrates that buyers value vendors who can deliver not only equipment but also integration support, site readiness, and rapid scale-up. Contracting patterns suggest that suppliers with end-to-end deployment capability and strong regional service networks are gaining an advantage, especially when security programs must be stood up quickly for events, new terminals, or expanded checkpoint areas.
Competitive Positioning and the Evolving Playing Field
The competitive landscape is defined less by a single dominant platform than by a combination of technological pedigree, certification status, and vertical specialization. Several established players illustrate the different ways companies are positioning themselves.
X-Ray Security Scanner Market
Differentiation Through Detection Architecture
Some suppliers compete primarily on non-invasive transmission X-ray technology designed to identify concealed objects within the body. Their value proposition centers on a specific detection approach that addresses threat concealment in a way that complements or differs from millimeter-wave imaging. In a market where operational requirements vary by site and threat profile, this kind of specialization can be strategically valuable for buyers seeking a particular screening modality or a layered security design.
Security Screening Market
Millimeter-Wave Leadership and Certification as a Moat
Other providers have built their positioning around millimeter-wave microwave imaging, emphasizing full body coverage, AI-assisted detection of metallic and non-metallic objects, and certification pathways aligned with aviation passenger screening. Recent certification achievements and major contract awards underscore how regulatory validation and large-scale deployment readiness can become competitive moats. When a platform is certified for airport use and subsequently selected for high-visibility deployments at host-city airports or national checkpoint networks, it signals not just technical capability but also operational reliability and compliance maturity. For competitors, that raises the stakes. For buyers, it reduces procurement uncertainty.
Throughput, Integration, and Checkpoint Design
A third dimension of competition is the ability to deliver high-throughput screening that integrates smoothly into checkpoint architecture. Systems marketed around accurate, non-ionizing detection and operational efficiency appeal to operators managing heavy passenger flow. In this context, differentiation often comes from ergonomics, footprint, throughput consistency, and the ability to minimize secondary screening disruptions. As checkpoints evolve into more modular and scalable environments, suppliers that can adapt equipment to varied spatial constraints and passenger volumes are better positioned to win multi-site contracts.
Market Evolution: Consolidation Pressure and Vertical Expansion
The market is not yet dominated by a small set of incumbents, but consolidation pressures are emerging. Larger security and technology groups with broad portfolios can cross-sell screening equipment alongside broader detection, integration, and services offerings. At the same time, niche specialists can thrive by dominating specific applications, regions, or regulatory environments. New entrants are likely to face a steep climb unless they bring a clear advantage in detection performance, certification readiness, cost structure, or deployment speed. The more probable trajectory is a hybrid landscape: a handful of scaled platforms with broad certification and service coverage, supplemented by specialized solutions for targeted use cases. Buyers will increasingly compare vendors not just on hardware specs but on the completeness of their deployment, training, and lifecycle support model.
Forward Trends: Where the Market Is Heading
Looking ahead over the next three to five years, several trends are likely to shape both demand patterns and commercial strategy.
Trend One: AI-Assisted Screening Becomes the Baseline Expectation
Intelligent interpretation will move from premium feature to expected capability. As operators face pressure to maintain throughput while improving detection consistency, systems that reduce reliance on subjective image interpretation will gain preference. This trend opens commercial opportunities for vendors that can demonstrate measurable improvements in alarm resolution, staff efficiency, and repeat screening rates. It also raises the importance of software lifecycle management, because AI-driven functionality depends on continuous updates, performance monitoring, and operational calibration. Buyers should anticipate that screening technology will increasingly be evaluated as a software-dependent service as much as a hardware purchase.
Trend Two: Application Expansion Beyond Traditional Transport Hubs
Full body scanners will continue to penetrate institutional, critical infrastructure, and event-driven settings. Legislative and regulatory movements that authorize body imaging equipment in correctional and similar environments point to a wider acceptance of these systems where access control and concealed threat detection are priorities. Large-scale international events and expanded transport networks will further encourage temporary and permanent deployments. The opportunity here is not simply more units, but new procurement models: short-term rental or rapid-deployment contracts, multi-site standardization programs, and modular checkpoint designs that can be scaled up or down depending on traffic and threat conditions.
Trend Three: Compliance and Certification as Strategic Procurement Filters
As detection standards become more explicit and certification pathways more established, compliance status will increasingly act as a gatekeeper in procurement decisions. Platforms with documented approvals and alignment to updated checkpoint requirements will enjoy shorter evaluation cycles and stronger positioning in regulated environments. The flip side is that buyers will need to plan for longer lead times when introducing new systems, especially if site-specific validation or regional certification is required. Suppliers that invest early in certification and documentation will be better equipped to capture demand when security programs are refreshed or expanded.
These trends carry risk as well. Rapid technological evolution can shorten product lifecycles and pressure margins. Regulatory shifts can alter deployment opportunities in unexpected ways. Public acceptance and privacy considerations can influence where and how screening is deployed, particularly in non-aviation environments. And for buyers, overcommitting to a single platform too early can create lock-in if operational needs or certification requirements change.
Strategic Actions for Decision Makers
The market’s direction suggests different priorities depending on the reader’s role, but several actions are broadly relevant.
For Manufacturers and Technology Providers
- Double down on certification readiness and documentation. In a market where compliance increasingly shapes procurement, a clearly validated detection capability and a traceable certification record can shorten sales cycles and improve win rates.
- Treat software and AI-assisted functionality as core products, not add-ons. Differentiation will depend on false alarm reduction, throughput consistency, and updateability. Plan for lifecycle support, including calibration, performance monitoring, and operator-facing software improvements.
- Build deployment and service capacity for scale-up events. Multi-site and event-driven contracts reward vendors that can deliver equipment, integration, training, and support quickly and reliably.
For Investors
- Evaluate companies on total deployment capability, not just hardware specs. Certification momentum, service networks, and contract execution history are indicators of commercial durability.
- Look for exposure to application expansion. Transport remains essential, but growth in critical infrastructure and institutional settings can diversify revenue streams and reduce dependence on any single procurement cycle.
- Monitor regulatory catalysts. Certification approvals, updated checkpoint guidance, and new authorization frameworks can shift demand faster than macroeconomic indicators, creating asymmetric opportunities for well-positioned vendors.
For Procurement and Security Program Leaders
- Prioritize total operational impact over sticker price. False alarm rates, throughput, training burden, and maintenance requirements often determine whether a system performs well in live conditions.
- Align equipment choices with layered security architecture. Full body scanners should complement existing screening methods and fit the operational profile of the site, whether that is high-throughput aviation or controlled-access institutional environments.
- Plan for certification and integration timelines early. New deployments may require validation, site preparation, and staff training that extend beyond hardware delivery. Building that into the program schedule reduces disruption and improves adoption.
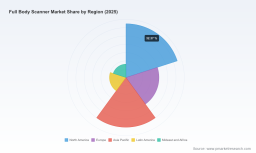
The full body scanner market is transitioning from a security niche into a broader screening infrastructure category, shaped by intelligent detection, evolving compliance expectations, and expanding application scope. For organizations operating in this space, the value of precise segmentation data, company-level benchmarking, and scenario-based forecasting is rising quickly. A detailed research report can help translate these macro trends into actionable planning inputs, including market size breakdowns by region and type, application-level demand patterns, competitive positioning across key vendors, and procurement-relevant developments that may affect deployment timing and vendor selection. For decision makers weighing product strategy, capital allocation, or multi-site security programs, that level of detail can shorten evaluation cycles and reduce uncertainty when it matters most.
For detailed analysis of this topic, please visit the official page: Full Body Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


