



Silicon Monoxide Market: Why 15.1% CAGR Reshapes Automotive & Electronics Demand

Silicon Monoxide Market: Strategic Trends and Commercial Opportunities (2025–2032)
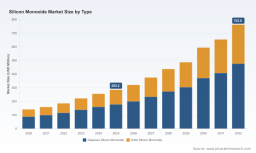
The silicon monoxide market has entered a phase of accelerated expansion, driven by converging demands across advanced electronics, energy storage, and industrial coatings. Over the historical period from 2020 to 2025, the market demonstrated consistent upward momentum, with revenues climbing from approximately $141 million to $285 million. This trajectory is projected to continue through the forecast period ending in 2032, with an estimated compound annual growth rate of 15.1 percent. By the close of the decade, the market is expected to surpass $760 million, reflecting a structural shift rather than a cyclical upswing. The growth is not uniform across all verticals or geographies; it is concentrated in application areas where material purity, thermal stability, and barrier properties are becoming critical differentiators.
For executives and investors tracking specialty materials, this market presents a compelling case study in how a relatively niche inorganic compound is transitioning into a strategic enabler for multiple high-growth industries. The challenge lies in navigating a fragmented supply base, evolving regulatory frameworks, and rapidly changing end-user specifications. Understanding where value is being created—and where vulnerabilities are emerging—requires moving beyond headline figures to examine the underlying technological, policy, and supply chain dynamics.
Market Status and Core Challenges
The current market structure reflects a balance between established industrial uses and emerging high-performance applications. Gaseous and solid forms of silicon monoxide serve distinct processing requirements, with each format catering to specific deposition, coating, or synthesis workflows. The revenue split between these formats underscores a mature but still evolving production ecosystem, where manufacturers are increasingly pressured to deliver consistent purity levels while scaling output. Similarly, demand is distributed across automotive and transportation, consumer electronics, energy and power systems, and a range of secondary applications. This distribution signals that no single industry dominates the growth narrative; instead, multiple sectors are pulling the market forward, each with its own technical thresholds and procurement cycles.
Geographically, the market exhibits a multi-polar character. North America, Europe, and Asia Pacific each command significant shares, while Latin America and the Middle East and Africa represent smaller but gradually expanding footholds. This geographic spread is not merely a reflection of historical manufacturing capacity; it is increasingly shaped by localized supply chain strategies, trade flows, and regional industrial policies. The presence of verified exporters across multiple continents, alongside targeted trade activity in emerging markets, indicates that silicon monoxide is moving through a globalization phase where sourcing flexibility and regulatory compliance are becoming as important as price competitiveness.
Several structural challenges complicate this growth trajectory.
- Purity and consistency requirements are intensifying. As silicon monoxide finds its way into battery anodes, thin-film deposition, and high-barrier packaging, end users are demanding tighter control over impurities and particle morphology. Inconsistent feedstock quality or variable reaction conditions can disrupt downstream performance, making quality assurance a competitive moat rather than a baseline expectation.
- Regulatory and trade compliance is fragmenting. Classification under inorganic compound duty frameworks, coupled with shifting export documentation requirements and country-specific trade data reporting, adds layers of complexity for cross-border procurement. Companies that treat compliance as an afterthought face delays, cost overruns, and potential supply interruptions.
- Supply chain concentration risks are emerging. While the market remains relatively fragmented at the top, with the top three and top five players holding modest combined shares, the underlying production ecosystem depends on high-temperature reaction processes and reliable silicon feedstock. Any disruption in upstream material availability or energy-intensive manufacturing capacity can create bottlenecks that ripple through multiple application sectors.
For decision makers, these challenges are not merely operational headaches; they are strategic inflection points. Companies that proactively address purity standardization, trade compliance, and feedstock resilience will be better positioned to capture premium segments, while those that compete primarily on price risk margin compression as customer expectations rise.
Key Demand Drivers Analysis
Technological Innovation and Material Breakthroughs
The most powerful accelerator for silicon monoxide demand is the ongoing push toward higher-performance materials in energy storage and electronic fabrication. In lithium-ion battery development, silicon-based anodes are attracting sustained attention for their potential to increase energy density compared with conventional graphite formulations. Silicon monoxide plays a role in this ecosystem both as a precursor and as a functional component in coating and synthesis workflows. Manufacturers that can deliver high-purity forms tailored to anode development are aligning themselves with a long-term technological shift rather than a short-term procurement trend.
At the same time, vacuum deposition and sputtering applications continue to rely on silicon monoxide evaporation sources and related deposition materials. As thin-film processing becomes more precise in semiconductor-adjacent and industrial coating environments, the need for stable evaporation behavior, predictable particle size, and reproducible deposition rates is increasing. This is driving suppliers to refine product forms—pieces, powders, and customized evaporation sources—so that downstream users can reduce process variability and improve yield.
Policy and Regulatory Environment
Regulatory conditions are shaping market access and cost structures in subtle but meaningful ways. In key markets such as the United States, silicon monoxide is classified under inorganic compound duty frameworks that generally allow duty-free treatment, lowering the tariff barrier for cross-border trade. While this may appear to be a minor detail, it has practical implications for sourcing strategies, especially for manufacturers that operate across multiple jurisdictions or assemble final products from globally sourced components.
Beyond tariffs, export documentation and trade transparency are becoming more prominent. Verified export activity across multiple shippers and destinations over recent periods indicates that the trade network is active but still relatively dispersed. For companies engaged in import/export operations, the ability to navigate shipment verification, country-of-origin documentation, and destination-specific requirements is increasingly a differentiator. Regulatory clarity can reduce lead times and working capital friction, while ambiguity can create hidden costs that erode competitiveness.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user behavior is changing on two fronts. In consumer electronics, the drive toward smaller, more durable, and better-protected devices is reinforcing interest in barrier materials and thin-film coatings where silicon monoxide can contribute. In industrial and energy sectors, procurement teams are increasingly evaluating materials not just on specification sheets but on total cost of ownership, including process stability, waste reduction, and integration ease. This shift is pushing suppliers to offer more than raw material; it is encouraging value-added formats, technical support, and application-specific packaging.
The automotive and transportation segment reflects a broader transition toward electrification and lightweighting, where material performance and supply reliability matter more than ever. As vehicle manufacturers and their tier suppliers reassess component sourcing in response to electrification roadmaps and regional content requirements, silicon monoxide’s role in battery-related workflows and specialized coatings positions it as a material worth monitoring in procurement strategies.
Supply Chain and Cost Structure Evolution
The production of silicon monoxide typically involves high-temperature reactions between silicon and silicon dioxide, or carbon-based reduction of silicon dioxide, with high-purity silicon feedstock underpinning consistent quality. This process architecture means that energy costs, feedstock availability, and reaction control are central to margin dynamics. As energy markets fluctuate and industrial energy efficiency becomes a broader corporate priority, producers that can optimize thermal processes, reduce waste, and maintain tight purity control will gain an advantage.
At the same time, the supply base is expanding in certain regions, with manufacturers offering silicon monoxide pieces, powders, and chemical-grade products for coating and inorganic chemical portfolios. This diversification increases buyer options but also raises the importance of qualification and vendor evaluation. Buyers that build rigorous technical assessment processes can secure better terms and more reliable supply, while those that rely on spot purchasing without technical due diligence may encounter inconsistent performance.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized producers, broad-line material suppliers, and regional manufacturers targeting distinct application niches. Rather than competing as a single undifferentiated market, participants are carving out positions based on purity ranges, product forms, application alignment, and geographic reach.
Several companies illustrate the strategic diversity currently shaping the market.
- Osaka Titanium Technologies Co., Ltd. has positioned itself around high-purity silicon monoxide for food packaging barrier applications and lithium-ion battery anode development. This dual focus reflects a strategy of linking material quality to high-value downstream uses, where purity and consistency directly influence customer outcomes.
- RD Mathis Company concentrates on evaporation sources, pieces, and deposition materials for vacuum technology. Its approach emphasizes process enablement, supplying the forms and configurations that deposition users need to reduce setup complexity and improve reproducibility.
- American Elements offers silicon monoxide in multiple purities and forms for research, sputtering targets, and industrial applications. This breadth-based model appeals to customers who require flexibility across R&D and production environments, and who value a supplier capable of supporting varied procurement scenarios.
- Stanford Advanced Materials (SAM) leverages manufacturing experience to supply high-quality silicon monoxide for electronic and industrial uses. Its long-standing production background supports a reliability narrative that resonates with buyers seeking stable supply and predictable specifications.
- Unilong Industry Co., Ltd. focuses on pieces and powder for coating and material applications, targeting customers that need practical forms for surface engineering and coating workflows.
- Hebei Yanxi Chemical Co., Ltd. and Hefei TNJ Chemical Industry Co., Ltd. operate within the inorganic chemical space, supplying silicon monoxide as part of broader chemical portfolios. Their presence highlights how the material is integrated into wider chemical supply chains, where procurement efficiency and portfolio breadth can be as important as isolated product specs.
The strategic positioning of these players reveals several differentiation levers. Some compete on purity and application alignment, others on product form and process support, and still others on portfolio breadth and regional availability. What is notable is that none of these approaches is inherently superior; rather, their effectiveness depends on the customer’s technical requirements, procurement model, and risk tolerance.
Market evolution is likely to follow a path of partial consolidation alongside continued specialization. On one hand, buyers increasingly prefer suppliers that can demonstrate consistent quality, regulatory familiarity, and application expertise, which may favor larger or more integrated players over time. On the other hand, the diversity of end uses—from packaging barriers to battery development to vacuum deposition—creates room for specialized manufacturers that can serve narrow but high-value segments. New entrants may find opportunities by focusing on underserved application niches, offering custom particle or form factors, or building stronger technical service capabilities around deposition and coating processes.
For competitive strategy, the key question is not simply who has the largest footprint, but who can reduce uncertainty for the buyer. Suppliers that combine reliable purity, clear trade documentation support, and application-relevant product forms are better positioned to command preference in procurement decisions, especially as customers move from spot buying toward longer-term supply relationships.
Future Trends Forecast
Looking ahead three to five years, several trends are likely to shape the market’s direction and create actionable opportunities.
Carbon Monoxide Market
1. Higher-purity, application-tailored forms will become the norm in premium segments. As silicon monoxide is integrated into more performance-sensitive workflows, buyers will increasingly differentiate between commodity-grade supply and specification-driven material. This will reward suppliers that invest in controlled reaction conditions, consistent particle morphology, and transparent quality documentation. The commercial opportunity lies in shifting from price-based competition to value-based positioning, where reliability and specification alignment justify premium margins.
2. Battery-related and energy storage workflows will continue to be a strategic growth vector. The broader interest in silicon-based anode development and energy density improvements is not a short-lived trend; it reflects a structural interest in next-generation storage materials. Silicon monoxide’s role in these workflows may evolve as formulations and processing methods mature, but the directional signal is clear: materials that support battery performance and manufacturing consistency will remain in focus. Companies that build application expertise and supply readiness for this vector can capture a growing share of demand, provided they can navigate technical qualification cycles and scale requirements.
3. Trade transparency and regional sourcing strategies will intensify. With active export flows across multiple shippers and destination markets, procurement teams are likely to place greater emphasis on supply visibility, documentation reliability, and regional resilience. This trend creates opportunities for suppliers that can offer predictable lead times, clear compliance support, and flexible sourcing arrangements. At the same time, it introduces risk for companies that rely on opaque supply chains or assume that duty-free classification automatically translates into frictionless trade. Regulatory interpretation, documentation quality, and destination-specific requirements will continue to matter.
PW Consulting
These trends carry inherent uncertainties. Technological adoption in battery anodes may proceed at different speeds across vehicle platforms and cell manufacturers. Energy costs and feedstock availability could affect production economics, particularly for energy-intensive synthesis routes. Trade documentation and compliance expectations may become more stringent in certain jurisdictions, adding cost and administration even where tariffs remain favorable. Decision makers should therefore treat growth opportunities as conditional on operational readiness, not as automatic outcomes of market expansion.
Actionable Guidance for Decision Makers
The market’s direction offers different implications depending on a company’s role in the value chain. The following recommendations are designed to translate market dynamics into practical next steps.
For Manufacturers and Material Suppliers
Focus on specifying and communicating purity, form consistency, and application fit rather than competing solely on unit price. Customers in deposition, coating, and battery-related workflows are increasingly weighing total process performance, so suppliers that provide clear technical documentation, reproducible product forms, and responsive support can differentiate more effectively. At the same time, review production economics with energy efficiency and feedstock reliability in mind, since these factors will influence margin stability as demand scales.
For Investors and Strategic Planners
Evaluate exposure to silicon monoxide not as a single market bet but as a cross-cutting enabler across electronics, energy storage, and industrial coatings. The most resilient opportunities are likely to be tied to suppliers or downstream users that can demonstrate application-specific value, reliable compliance handling, and the ability to serve multiple verticals without diluting quality. When assessing potential investments or partnerships, pay attention to qualification readiness, supply chain transparency, and the company’s ability to navigate trade documentation and regional sourcing requirements.
Silicon 28 Market
For Procurement and Sourcing Leaders
Strengthen technical qualification processes before committing to volume supply. Given the variability in product forms and purity ranges across the supply base, spot purchasing without specification alignment can create downstream variability and hidden costs. Build a shortlist based on documented purity consistency, form suitability for the intended process, and trade compliance reliability. Where possible, favor suppliers that can support predictable documentation and lead times, as these attributes reduce operational friction in multi-source or multi-region procurement strategies.
For organizations that need deeper segmentation, region-specific trade dynamics, and customized scenario planning, a more detailed research view can help translate these strategic signals into precise procurement, investment, and production decisions. A comprehensive report is available for teams that require granular data, application-level breakdowns, and tailored recommendations aligned with specific operational objectives.
For detailed analysis of this topic, please visit the official page: Silicon Monoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


