



Party Balloon Market: Why 6.5% CAGR and Shifting Demand Reshape 2026–2032

Party Balloon Market: Strategic Trends and Commercial Opportunities in a Maturing Sector
The party balloon market has evolved from a simple seasonal commodity into a nuanced segment of the broader event and decorative products industry. What was once dominated by volume-driven latex sales is now shaped by sustainability mandates, supply chain reconfiguration, and a clear bifurcation between residential and commercial demand. For executives and investors, the sector presents a steady growth trajectory but demands strategic repositioning to capture value in a landscape that is increasingly defined by regulatory compliance, material innovation, and regional capacity shifts.
Market Snapshot and Core Challenges
A Baseline of Measured Expansion
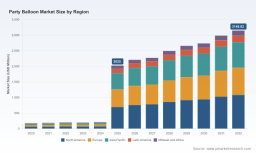
The overall market has demonstrated consistent growth over the past half-decade, with revenue climbing from roughly 180 million at the start of the period to more than 2.7 billion by the current baseline year. Forward projections indicate a compound annual growth rate of approximately 6.5 percent through the end of the forecast horizon, ultimately reaching nearly 3.15 billion in annual revenue. This expansion reflects both enduring consumer demand for decorative event products and a structural uplift from commercial applications, where balloon installations, themed retail displays, and corporate event styling contribute a larger share of revenue than residential use.
The geographic footprint remains broad but uneven. North America and Europe continue to anchor demand, supported by mature event cultures and retail infrastructure, while Asia Pacific has emerged as a meaningful growth engine, driven by rising disposable incomes, expanding middle-class consumption, and a growing professional event decoration sector. Latin America and the Middle East and Africa contribute smaller but steady portions of the total, often characterized by localized production, seasonal demand spikes, and price-sensitive consumer segments.
Within the product mix, latex balloons remain the dominant category, supported by their lower unit cost, versatility, and widespread acceptance in both retail and professional decoration channels. Foil balloons occupy the second position, valued for their longer float time, printed customization potential, and role in seasonal and commercial displays. Bubble balloons and other specialty formats represent a smaller but strategically important niche, appealing to premium event decorators and consumers seeking distinct visual effects. The commercial application segment has grown to a position of clear importance, reflecting how balloons are increasingly used as part of broader experiential marketing, hospitality, and retail environments rather than solely as casual household decorations.
Three Pressures Shaping the Market's Next Chapter
Despite the encouraging growth path, the sector is navigating three interconnected challenges that will define competitive outcomes over the next several years.
First, regulatory scrutiny around environmental impact is rewriting the rules of material choice and product use. Restrictions on non-biodegradable balloon manufacturing and release, alongside broader single-use plastic directives in major markets, have pushed manufacturers and distributors to reconsider formulations, end-of-life pathways, and public messaging. At the same time, multiple governments across the U.S., EU, UK, and Australia have limited the release of helium balloons due to environmental concerns. These measures are not only affecting how products are sold but also reshaping customer expectations around responsible decoration practices.
Second, cost volatility in core raw materials is eroding margin predictability. Natural rubber prices in Southeast Asia have shown upward movement, with recent readings above the two-dollar-per-kilogram threshold, adding pressure to input costs for latex-based products. In a market where many price points are already competitive and volume-driven, sustained raw material inflation can force difficult trade-offs between price maintenance, product quality, and supplier relationships.
Third, trade and classification friction is introducing new complexity into cross-border supply chains. Enhanced customs scrutiny around tariff classification for recreational items, including latex balloons, has increased compliance overhead and the risk of shipment delays. For manufacturers and traders that rely on multi-country sourcing, packaging, and distribution networks, this environment demands more rigorous documentation, better classification discipline, and potentially reshuffled sourcing maps.
Key Drivers Reshaping the Sector
Sustainability as a Strategic Filter, Not a Marketing Add-On
Environmental regulation and consumer sentiment are moving sustainability from a peripheral concern to a core strategic filter. The cumulative effect of single-use plastic directives and helium release restrictions has made biodegradability, material sourcing, and product behavior after use central considerations for both manufacturers and professional decorators. Companies that can credibly offer responsibly produced latex, clearer usage guidance, and alternatives that reduce environmental impact are better positioned to retain customers in markets where compliance and reputation increasingly overlap.
PW Consulting
This dynamic is also spurring product and process innovation. Some manufacturers are emphasizing professional-grade offerings with stronger quality consistency and a more defined sustainability narrative, which helps them command attention in event and retail channels where trust and differentiation matter. The shift is not simply about materials; it is about building a coherent story around responsible production, use, and disposal that aligns with customer expectations and regulatory requirements.
Commercial Demand and the Rise of Purpose-Built Applications
A major structural driver is the increasing importance of commercial applications. Balloons are no longer limited to spontaneous home celebrations; they are integrated into retail environments, hospitality venues, brand activations, and professional event styling. This shift favors products and formats that offer stronger visual impact, better durability, and reliable consistency across larger installations. Foil balloons, with their printed customization potential and longer display life, and bubble balloons, which create distinctive premium effects, are particularly relevant in these contexts.
For businesses serving this segment, the commercial channel changes the economics of the market. Repeat B2B relationships, volume orders, and the need for dependable supply become more important than one-off consumer purchases. It also raises the bar for product uniformity, packaging, and after-sales support. Companies that can standardize offerings and build dependable supply relationships are better placed to capture the higher-value commercial segment, which now accounts for a substantial portion of total revenue.
Supply Chain Reconfiguration and Capacity Expansion
Capacity investments are reshaping the supply landscape in ways that will influence cost structures and regional competitiveness. Recent expansion announcements signal a deliberate push to increase production throughput and strengthen proximity to key demand centers. One major latex manufacturer opened a new plant in Mexico with annual capacity reaching 400 million units, while another specialist in latex balloons added a new facility in Colombia, investing roughly 40 million dollars to add monthly capacity of 60 million balloons.
These moves point to a broader trend: producers are looking to scale efficiently, diversify geographic exposure, and reduce dependence on concentrated supply nodes. For downstream buyers, such expansion can translate into greater availability, more competitive pricing over time, and improved resilience against localized disruptions. At the same time, it raises the stakes for manufacturers that have not yet modernized capacity, automated production, or diversified their manufacturing footprint. The ability to meet growing demand while controlling costs will increasingly separate leaders from followers.
Retail Channel Dynamics and the Helium Factor
Helium availability and cost remain an underappreciated influence on market behavior. Restrictions on helium balloon releases, combined with the operational realities of sourcing helium for inflated products, are nudging both consumers and event professionals toward air-filled options, alternative materials, and display techniques that do not rely exclusively on floating effects. This is not a collapse of demand but a reorientation of how balloons are used. Retailers, decorators, and event planners are adapting with creative designs that prioritize visual impact, longevity, and practicality over floating duration alone.
For manufacturers, this environment rewards product portfolios that perform well in both air-filled and helium-filled applications, as well as packaging and presentation that help customers deploy balloons effectively in constrained conditions. The broader implication is that product utility is being redefined, and the winners will be those who can support new usage patterns without sacrificing the festive appeal that drives the category in the first place.
Competitive Landscape: Positioning, Differentiation, and Evolution
Diverse Leaders, Distinctive Value Propositions
The market's competitive field includes a mix of established manufacturers with broad regional reach, specialists focused on professional and retail channels, and producers leveraging automation or sustainability narratives to stand out. Several companies illustrate the range of strategic approaches now in play.
- Pioneer Balloon Company, based in Wichita, Kansas, manufactures high-quality latex, microfoil, and bubble balloons for professional event and party decoration. Its recent operational move to open a new latex plant in Mexico illustrates a capacity-forward strategy aimed at supporting scale and regional availability.
- Belbal, headquartered in Poland, focuses on premium natural latex balloons in a wide range of sizes, colors, and retail formats. Its positioning emphasizes product range and retail readiness, appealing to distributors and decorators who need consistent variety.
- Gemar Balloons, located in Casalvieri, Italy, combines latex and foil manufacturing with an emphasis on sustainability and professional-grade products. Its narrative links quality and environmental responsibility, a combination that resonates with events and commercial buyers seeking credible differentiation.
- CTI Industries, in the United States, produces both helium-filled and air-filled latex and foil balloons for retail and event use, aligning its offering with the practical needs of multiple channels and usage scenarios.
- Sempertex, based in Colombia, specializes in latex balloons for party and event decoration markets and has reinforced its expansion trajectory with a significant new facility investment, adding monthly output in the tens of millions of units.
- Balonevi, in Turkey, produces natural latex balloons with automated production for global party and event applications, highlighting the role of automation in meeting scale and consistency requirements.
- Anagram International, in the United States, is a leading manufacturer of foil and latex balloons for birthdays, parties, graduations, and events, reflecting a broad consumer-event orientation with strong brand recognition in key occasions.
- Latex Occidental, in France, manufactures latex balloons with global brand partnerships and private-label production, showing how contract and brand-aligned manufacturing can extend reach without necessarily building a consumer-facing brand of its own.
- Maple City Rubber Company, also in the United States, produces Tuftex latex balloons and related party balloon products, representing a long-standing manufacturing presence with a focus on latex-based product consistency.
How the Leaders Differentiate
Across these players, a few strategic themes emerge. Some compete primarily on scale and capacity, using production expansion and geographic diversification to secure supply advantages and cost leverage. Others lean into product quality and professional-grade consistency, targeting event decorators and commercial clients who value reliability and repeatability. A further group uses sustainability and responsible sourcing as a point of differentiation, aligning product attributes with regulatory trends and buyer preferences. Private-label and partnership-based models also remain relevant, allowing manufacturers to serve multiple channels without heavy consumer branding investment.
The implications are clear. No single formula dominates. Instead, competitive success depends on aligning the company's strengths with the segment it serves. A producer focused on retail volume will need a different set of capabilities than one built around professional event supply or B2B commercial contracts. The companies that perform best will be those that can combine reliable quality, sensible cost management, and a credible response to environmental and regulatory expectations.
Consolidation, Fragmentation, and the New Entrant Question
The market's concentration remains relatively modest, with the top few firms holding a minority share of total revenue. This fragmented structure suggests room for continued competition but also hints at potential consolidation over time, especially as capacity investments raise the cost of staying competitive and as buyers increasingly prefer suppliers that can meet broader requirements around volume, compliance, and consistency. At the same time, niche entry points exist for companies that serve specific regions, product formats, or premium event segments. New entrants that can offer differentiated materials, localized production, or specialized customer support may find opportunities even in a market where several established players already operate.
Party Supplies Market
One to watch is the interplay between capacity growth and raw material dynamics. Expanding production can improve availability and potentially moderate pricing pressure, but only if input costs and trade conditions are manageable. If raw material inflation persists or trade friction intensifies, capacity expansion alone will not guarantee margin health. Companies that pair investment with flexible sourcing and disciplined cost control will be better positioned to convert growth into profitable outcomes.
Three Trends to Watch and the Opportunities They Unlock
Trend One: Sustainability Moves From Compliance to Competitive Advantage
Over the next three to five years, sustainability will increasingly function as a competitive parameter rather than a compliance checkbox. Buyers in commercial and professional channels will likely favor suppliers that can demonstrate responsible material sourcing, clear usage guidance, and product characteristics aligned with environmental expectations. This opens opportunities for manufacturers that invest in credible sustainability practices, communicate them clearly, and integrate them into product design and packaging. It also creates room for innovation in biodegradable formulations, alternative material blends, and usage models that reduce environmental impact without sacrificing appeal.
The opportunity lies in turning a constraint into a point of differentiation. Companies that act early can build trust with event professionals, retail partners, and brand customers who are under their own pressure to demonstrate responsible sourcing and product choices. The risk is that vague or inconsistent claims will be scrutinized more closely, especially in markets where regulatory expectations are rising and customers are becoming more literate about material and environmental issues.
Trend Two: Commercial Applications Drive a Higher-Value Segment
As commercial use continues to grow in importance, the market will increasingly reward products and services tailored to B2B and professional environments. This includes stronger consistency across batches, formats suited to larger displays, packaging that supports professional handling, and service levels that meet the demands of repeat business. The commercial segment's growth also suggests opportunities in related services and support, such as design guidance, bulk ordering systems, and dependable logistics for time-sensitive events.
Businesses that recognize this shift can pursue higher-value relationships rather than competing solely on unit price. The associated risk is that commercial buyers will become more demanding over time, expecting suppliers to deliver on quality, timing, and compliance with little room for disruption. Suppliers that fail to adapt to these expectations may find themselves relegated to lower-margin, less differentiated transactions.
Party Costumes Market
Trend Three: Regional Capacity and Trade Realignment Will Shape Cost and Availability
Continued capacity additions in the Americas, combined with ongoing scrutiny of trade classification and customs processes, point to a period of regional realignment. Some production is likely to move closer to major demand centers, reducing exposure to long, complex supply routes and improving responsiveness. At the same time, raw material price movements, especially in natural rubber, will remain a swing factor for input costs and overall margin potential. These dynamics create opportunities for players that can manage regional sourcing intelligently, maintain flexible production, and plan for volatility rather than assuming a stable cost base.
For commercial strategy, this means that supply chain resilience will increasingly be part of the value proposition. Buyers will appreciate suppliers that can demonstrate reliable delivery, clear tariff and classification handling, and contingency planning for input cost swings. The uncertainty lies in the pace and direction of trade policy changes and raw material trends; businesses that build scenario flexibility into their sourcing and pricing approaches will be better prepared for whatever path emerges.
Strategic Actions for Decision-Makers
For Manufacturers and Brand Owners
- Align product portfolios with commercial demand by strengthening consistency, packaging, and formats suited to professional installations, while maintaining credible options for retail consumers.
- Treat sustainability as a core design and communication priority, ensuring that material choices, usage guidance, and product claims are coherent and defensible in regulated markets.
- Use capacity and geographic diversification strategically, balancing expansion with disciplined cost control and flexible sourcing to protect margins when raw materials and trade conditions move against you.
For Investors and Strategic Buyers
- Evaluate companies on the basis of their ability to convert capacity growth into profitable volume, not just on installed capacity alone. Margin resilience under raw material and trade pressure is a critical indicator of durability.
- Look for businesses with clear segment focus and credible differentiation, whether through quality, sustainability, commercial service, or regional reach, rather than undifferentiated volume plays.
- Monitor regulatory and trade developments closely, since shifts in classification, environmental rules, and helium-related practices can change the attractiveness of specific products and channels relatively quickly.
For Procurement and Channel Partners
- Prioritize suppliers that can demonstrate consistent quality, dependable delivery, and a clear approach to compliance and environmental expectations, especially when serving commercial or professional clients.
- Diversify sourcing where feasible to reduce exposure to concentrated supply or single-region risk, and maintain clear documentation around classification and customs requirements to avoid delays.
- Plan for input cost variability by combining long-term relationships with flexible purchasing strategies, and consider product alternatives that can preserve visual impact while reducing dependence on the most volatile inputs.
Navigating the Road Ahead
The party balloon market is moving through a period in which steady growth coexists with structural change. Demand remains healthy across residential and commercial channels, but the rules of competition are being rewritten by sustainability expectations, raw material dynamics, and supply chain realignment. Companies that treat these forces as strategic signals rather than background noise will be better placed to capture the next wave of growth.
For those seeking a more detailed view of the segment, including granular breakdowns and customized guidance, the full research report provides a deeper look at the data, regional and category dynamics, and scenario-based implications for different business models. It is designed to support practical decision-making with focused analysis that goes beyond the headline numbers.
For detailed analysis of this topic, please visit the official page: Party Balloon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


