



Spirometer Market 2026: How 6.63% CAGR and COPD Demand Reshape Growth

The Spirometer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The spirometry equipment and software market has entered a phase of steady, structurally supported expansion. From a baseline of approximately $450 million in 2020, the sector reached roughly $680 million by 2025, reflecting a compound annual growth rate of 6.63 percent across the 2026-2032 forecast window. This trajectory is not merely a function of unit volume growth; it represents a broader repositioning of spirometry within diagnostic workflows, occupational health programs, and decentralized care models. The market's maturation is increasingly tied to software-enabled diagnostics, connectivity standards, and reimbursement frameworks rather than hardware shipment cycles alone.
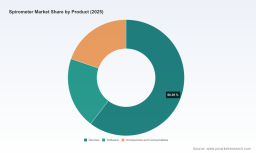
The current configuration reveals a market where device-based solutions still command the largest revenue share, though software and consumables are closing the gap as clinicians prioritize workflow efficiency, data interoperability, and repeatable testing protocols. Regionally, mature markets continue to anchor demand through established occupational screening programs and reimbursement pathways, while high-growth regions are accelerating adoption through expanded primary care access, rising chronic respiratory disease burdens, and public health initiatives that emphasize early detection. This dual dynamic creates a landscape where pricing pressure, regulatory alignment, and channel strategy differentiate winners from laggards.
PW Consulting
Key Challenges and Inflection Points
Despite the constructive growth profile, three structural challenges are reshaping decision-making for manufacturers, distributors, and care providers.
The first challenge centers on regulatory data-transfer compliance. Spirometry is increasingly embedded in government-backed surveillance programs, most notably occupational health monitoring, where electronic reporting standards have become a de facto product qualification gate. As of May 2026, only a defined set of manufacturers met the current NIOSH Coal Workers’ Health Surveillance Program electronic data transfer requirements for CWHSP reporting. This regulatory narrowing does not simply limit the supplier field; it creates a structural advantage for companies with compliant software architectures, validated data pipelines, and auditable reporting workflows. For commercial teams, compliance has moved from a technical checkbox to a competitive moat.
The second challenge involves reimbursement economics and the margin tension between test volume and per-test payment. In the United States, the Medicare Physician Fee Schedule average reimbursement for spirometry testing under CPT 94060 stood at $38.97 per test as of January 2026. This figure anchors expectations for laboratory and clinic economics, but it also intensifies the need for throughput efficiency, reduced retest rates, and integration with broader respiratory care pathways. Devices that minimize setup time, improve patient coaching, and simplify interpretation can materially affect the financial viability of testing programs, especially in high-volume primary care and occupational settings.
The third challenge is accessibility and inclusive design, which is becoming a more prominent procurement requirement rather than a peripheral consideration. Equipment that accommodates patients with mobility limitations or varied clinical environments can widen the addressable user base and reduce operational friction. Recent compliance milestones, such as specific examination and procedure chairs achieving US Access Board standards for accessible medical diagnostic equipment in February 2026, illustrate how accessibility is moving into broader equipment ecosystem decisions. For spirometry providers, the implication is clear: clinical utility increasingly depends on how well a testing solution fits into the physical and operational realities of the care setting.
Key Demand Drivers
Technology Innovation and the Shift Toward Connected Diagnostics
The most durable driver of market expansion is the transition from standalone measurement devices to connected, software-centric diagnostic tools. Modern spirometry is increasingly evaluated on data handling, interpretation support, and integration with electronic health records or occupational health platforms. Portable and PC-based systems with dedicated connectivity software are gaining traction because they reduce administrative burden and improve data consistency across dispersed testing sites. Smartphone-compatible designs further extend the operational reach of spirometry into home monitoring and decentralized care, especially where patients need repeated assessments rather than single-visit diagnostics.
This shift is visible in product developments that emphasize ambulatory and point-of-care use. In February 2026, a new digital spirometer designed for ambulatory care clinics entered the market to support asthma, COPD, and respiratory monitoring workflows. The significance of this release lies not only in the hardware itself, but in the targeted deployment context: outpatient and ambulatory environments where rapid turnaround, ease of use, and chronic disease follow-up are central. Alongside such developments, advanced diagnostic combinations are emerging. At Medicall 2025 in September 2025, a photonic gas analyzer was demonstrated in combination with spirometry for real-time lung health monitoring, signaling an acceleration toward multi-parameter respiratory assessment rather than isolated airflow measurement.
Policy and Regulatory Environment as a Demand Filter
Regulatory and standards-based requirements are increasingly shaping procurement decisions, product roadmaps, and market access. Spirometry has always been subject to performance standards, but the current environment places greater weight on electronic data compatibility, validated reporting, and adherence to recognized testing protocols. Compliance with ATS/ERS standards remains a baseline expectation for clinical credibility, while occupational surveillance requirements create additional architectural obligations for software and data export capabilities.
The regulatory landscape also affects competitive positioning by rewarding manufacturers that can demonstrate continuity between device performance, software reporting, and program-specific data needs. For organizations operating in government-affiliated screening or occupational health programs, the selection criteria often go beyond unit price. They encompass whether the system can reliably produce compliant output, support longitudinal tracking, and reduce the administrative risk of rejected or incomplete submissions. In this sense, policy does not only stimulate demand; it filters it toward solutions with demonstrable compliance and integration readiness.
Demand-Side Behavior and the Growing Role of Chronic Respiratory Care
Demand is increasingly driven by the clinical and operational realities of chronic respiratory disease management. COPD and asthma continue to represent the largest application focuses within spirometry, reflecting both prevalence and the need for repeated monitoring over time. As care models shift toward earlier diagnosis, ongoing disease tracking, and patient-enabled testing, spirometry is being evaluated less as a one-time test and more as a recurring data source within long-term care pathways.
This demand evolution favors solutions that are easier to deploy across care settings, simpler for non-specialist staff to administer, and capable of producing consistent results across repeated tests. In primary care, occupational health, and home-based monitoring, the value proposition increasingly depends on reducing the skill barrier for testing while preserving diagnostic reliability. The commercial implication is that manufacturers and solution providers must design for workflow realism: staff turnover, time pressure, patient variability, and the need for fast, interpretable outputs.
Supply Chain and Cost Structure Considerations
Cost structure remains a critical strategic variable, particularly as the market expands beyond traditional hospital purchasing into ambulatory clinics, occupational programs, and decentralized testing. Device price, consumable replacement cycles, software licensing models, and service support all influence total cost of ownership. In high-volume environments, the economic case for spirometry can hinge on durability, calibration stability, and the cost of repeat testing due to poor patient technique or device inconsistency.
At the same time, supply chain resilience and service availability are becoming differentiators. Organizations that can provide reliable repair support, clear replacement pathways, and responsive technical assistance reduce downtime risk for testing programs that depend on continuous operation. In practical terms, the cost discussion is no longer limited to acquisition price; it increasingly includes lifecycle reliability, support responsiveness, and the administrative burden of keeping testing programs compliant and operational.
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with a limited group of established players accounting for a substantial share of revenue. This concentration reflects the importance of regulatory validation, clinical reputation, software maturity, and long-standing relationships with occupational health programs and diagnostic procurement teams. At the same time, the competitive field is not static. It is being reshaped by connectivity-driven product updates, expanding geographic reach, and targeted releases aimed at ambulatory and primary care settings.
Several manufacturers illustrate the diversity of strategic positioning in the current market.
- One Swiss-linked company has built a recognizable position around portable and PC-based spirometers with dedicated connectivity software, including a product line recognized for NIOSH-approved data transfer in occupational health surveillance. Its strategic value lies in the combination of portability, software readiness, and alignment with program-specific reporting requirements.
- An Italian manufacturer has emphasized smart, smartphone-compatible spirometers and oximeters for both professional and home use, with broad international availability and regulatory approvals across multiple markets. This approach highlights a consumer-and-clinic bridging strategy, where usability and connectivity are central to expansion.
- A United States-based manufacturer has focused on desktop and handheld spirometry built around proprietary measurement technology and compliance with recognized testing standards. Its positioning suggests a clinical-grade emphasis suited to settings where standardized performance and repeatability are paramount.
- Another United States company offers PC-based spirometry platforms paired with dedicated interpretation and workflow software, reinforcing a strategy centered on integrated diagnostic support rather than hardware alone.
- A large medical equipment provider continues to supply hospital and clinic-oriented spirometry systems, leveraging scale, broad distribution, and integration into wider respiratory and diagnostic portfolios.
- A United States manufacturer has moved toward digital spirometry integrated with practice management software for ambulatory care, aligning product design with outpatient workflow needs and chronic respiratory monitoring.
- A domestically focused United States manufacturer emphasizes PC-based and portable devices designed and supported within the United States, with strong repair support as a competitive element. This model underscores the value of service reliability in procurement decisions.
- A French manufacturer offers portable spirometry with expert software support, reflecting a compact-system strategy aimed at settings that need portable capability without sacrificing data management functionality.
- A United States manufacturer produces desktop spirometers approved for occupational surveillance use, reinforcing the importance of program-specific compliance in niche but strategically important segments.
- An Italian developer has extended into wireless portable spirometry for metabolic and pulmonary testing, illustrating the broader movement toward flexible, multi-use diagnostic tools.
Strategic Positioning and Differentiation
Across these players, differentiation is increasingly defined by three overlapping dimensions: regulatory and data-transfer readiness, workflow integration, and deployment flexibility. Companies that combine validated diagnostic performance with software that simplifies reporting, interpretation, and connectivity tend to stand out in both clinical and occupational settings. In parallel, manufacturers that make spirometry easier to use in ambulatory, primary care, and home-based environments are extending the market beyond traditional specialty testing locations.
Pricing strategy also varies by positioning. Some providers compete on breadth of portfolio and integration within larger diagnostic ecosystems. Others compete on specialized compliance, repair support, or portable usability. What unites the stronger positions is a clear match between product design and the operational environment in which testing actually occurs.
Audiometer Market
Market Evolution: Consolidation, Fragmentation, and New Entry
The next phase of market evolution is likely to feature a blend of consolidation and targeted fragmentation. Consolidation will remain attractive where economies of scale, software development capacity, and distribution reach determine competitiveness. Larger platforms may seek to absorb complementary technologies that expand respiratory assessment capabilities or strengthen data interoperability. At the same time, fragmentation is probable around specific use cases: ambulatory monitoring, occupational surveillance, home-based tracking, and combined diagnostic modalities.
New entrants and adjacent technologies are likely to challenge incumbents not by replicating conventional spirometry, but by adding complementary measurement, improving connectivity, or reducing the friction of repeated testing. The practical result is a market where competitive advantage will depend less on device presence alone and more on whether a solution can be embedded into compliant, efficient, and patient-accessible care workflows.
Future Trends and Commercial Opportunities
Trend 1: Software-Defined Spirometry as the Norm
Over the next three to five years, spirometry is expected to be increasingly evaluated as a software-defined diagnostic service rather than a standalone instrument purchase. Data transfer, reporting automation, interpretation support, and integration with existing clinical systems will become central purchase criteria. Commercial opportunities will arise for providers that can reduce the administrative load of testing, improve data quality, and support longitudinal monitoring across multiple sites or care settings. The most valuable offerings will likely be those that make spirometry easier to scale without sacrificing compliance or diagnostic consistency.
Trend 2: Expansion into Decentralized and Ambulatory Testing
Ambulatory care, primary care, and occupational health settings are likely to drive a growing share of demand, especially where chronic respiratory conditions require ongoing monitoring rather than episodic diagnosis. Products designed for quick setup, intuitive coaching, and portable deployment will benefit from this shift. The commercial opportunity here lies in reaching environments that need respiratory testing but cannot rely on specialist workflows or complex equipment setups. Solutions that fit these environments can broaden the effective market and create recurring demand through follow-up monitoring.
Trend 3: Multi-Parameter Respiratory Assessment and Adjacent Technologies
Spirometry is increasingly likely to be combined with complementary measurements and real-time monitoring technologies, reflecting a broader move toward comprehensive lung health assessment. Demonstrations of gas analysis integrated with spirometry for real-time monitoring indicate the direction of travel: richer diagnostic signatures, faster clinical insight, and more actionable follow-up. For manufacturers and investors, this trend offers opportunities in integrated device design, software interpretation, and partnerships that bring together respiratory testing with adjacent diagnostic capabilities. The risk is that fragmentation may increase unless interoperability and standards keep pace with innovation.
Spectrometer Market
Risk and Uncertainty
Several uncertainties could alter the pace or shape of growth. Reimbursement adjustments may influence testing volume and program economics, particularly in public payor environments. Regulatory requirements may evolve, changing which products remain eligible for specific surveillance or reporting programs. Competitive pressure from connected consumer-grade devices and adjacent diagnostic tools may challenge traditional positioning if differentiation erodes around accuracy, compliance, or clinical trust. Finally, supply chain disruptions and service capacity constraints can affect uptime and total cost of ownership, especially for organizations that depend on uninterrupted testing schedules. These risks do not negate the market outlook, but they emphasize the need for procurement and investment decisions grounded in compliance readiness, workflow fit, and lifecycle economics.
Strategic Recommendations for Decision-Makers
For Manufacturers and Solution Providers
Prioritize software interoperability and data-transfer compliance as core product attributes, not optional features. In regulated and high-volume environments, the ability to produce compliant electronic output and integrate with existing reporting workflows can be a decisive differentiator. Continue to invest in portable, ambulatory-friendly designs that reduce the skill burden for testing staff while preserving diagnostic reliability. Equally important is service and repair capability, which directly affects customer retention and total cost of ownership perceptions.
For Investors and Strategic Buyers
Look beyond unit shipment narratives and focus on recurrence, software-led economics, and compliance-linked defensibility. The most compelling opportunities are likely in platforms that can support repeated testing, chronic disease monitoring, and occupational or public health reporting with minimal operational friction. Evaluate whether a company’s competitive position depends on transient distribution advantages or on durable attributes such as regulatory alignment, integration depth, and support infrastructure. In this market, defensibility increasingly comes from workflow lock-in and compliance readiness rather than hardware alone.
For Procurement Leaders and Care Providers
Evaluate spirometry purchases through total cost of ownership and operational fit rather than sticker price. Consider how the solution affects setup time, retest rates, staff training burden, and reporting compliance. In occupational and government-linked programs, verify data-transfer eligibility early in the selection process to avoid downstream administrative risk. For ambulatory and primary care environments, prioritize devices and software that match the real conditions of the setting: limited staff time, varied patient populations, and the need for repeatable results. Accessibility and inclusive design should also be weighed where they affect patient throughput and equitable service delivery.
Conclusion
The spirometer market is moving from a hardware-centered diagnostic category toward a more connected, workflow-dependent, and compliance-shaped segment of the broader respiratory care landscape. Growth is supported by chronic disease management needs, occupational surveillance requirements, and product evolution that favors portability, software integration, and expanded care settings. At the same time, the market rewards participants that can demonstrate regulatory readiness, reduce administrative burden, and fit the operational realities of ambulatory, primary care, and decentralized testing.
For organizations seeking to act on these dynamics with segment-level detail, procurement benchmarks, and customized strategic recommendations, a comprehensive research report can provide the deeper segmentation data and scenario planning needed for execution-level decisions.
For detailed analysis of this topic, please visit the official page: Spirometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


