



Industrial Plugs and Sockets Market: 5.4% CAGR Trajectory and Strategic Shifts to 2032

Industrial Plugs and Sockets Market: Strategic Trends and Commercial Opportunities
The industrial plugs and sockets market is entering a phase of structured evolution, driven by tightening safety regulations, technological integration, and shifting demand patterns across heavy industry. Valued at approximately USD 2.8 billion in 2025 and projected to expand at a compound annual growth rate of 5.4 percent through 2032, the sector reflects broader dynamics in industrial electrification, infrastructure modernization, and hazardous-environment power management. While the headline figures convey steady growth, the underlying landscape reveals nuanced shifts in product differentiation, compliance demands, and competitive positioning that decision-makers must navigate with precision.
Market Overview and Core Challenges
A Market Shaped by Scale and Fragmentation
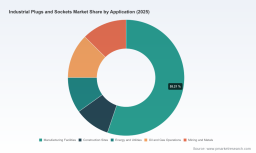
Recent years have seen consistent revenue expansion, with the market moving from USD 2.3 billion in 2020 to an estimated USD 2.8 billion in 2025. The forecast period through 2032 indicates a trajectory toward USD 4 billion, underscoring sustained demand for reliable power connection solutions. Growth is broad-based but unevenly distributed, with Asia Pacific representing the largest regional revenue share, followed by North America and Europe. The product mix remains balanced between industrial plugs and sockets, with sockets holding a slight margin in total revenue, while application demand is concentrated in manufacturing facilities, with meaningful contributions from oil and gas operations, mining and metals, energy and utilities, and construction sites.
PW Consulting Automotive & Machinery Research Center
The competitive structure remains moderately fragmented. The top three players account for roughly 28 percent of market revenue, while the top five reach approximately 45 percent. This concentration suggests that while established manufacturers hold meaningful share, the market still accommodates regional specialists and niche innovators. Fragmentation is both a vulnerability and an opportunity: it creates room for targeted entrants in specific applications or geographies, but it also means price compression and compliance standardization remain persistent pressures.
Key Challenges at the Current Inflection Point
Three interrelated challenges define the current market environment:
- Compliance and standardization complexity. Industrial plugs and sockets must align with IEC 60309-1 and IEC 60309-2 to ensure global interchangeability, dimensional compatibility, and safety performance across industrial and hazardous environments. As standards evolve to incorporate provisions for data communication within power connectors, manufacturers face the dual burden of maintaining electrical robustness while enabling monitoring and control capabilities. This raises design complexity, testing costs, and time-to-market for next-generation products.
- Safety and hazardous-location performance. Demand for ATEX-rated connectors, switch-rated receptacles, and solutions that reduce arc-flash exposure continues to rise, particularly in oil and gas, mining, and heavy manufacturing. Delivering inherently safe designs without sacrificing current capacity or durability requires advanced engineering and rigorous certification, which can constrain margins for suppliers that lack specialized capabilities.
- Supply chain and conductor material transitions. Guidance from leading manufacturers on connecting aluminum conductors to industrial plugs and sockets signals a broader shift toward cost and weight optimization in power distribution. Aluminum is increasingly considered for its material economics, but it introduces connection integrity, thermal expansion, and corrosion considerations that demand revised termination practices and product design adjustments. Suppliers must adapt fasteners, contact materials, and user guidance to maintain reliability while supporting lower system costs.
Key Drivers of Market Change
Technological Innovation and Functional Convergence
Product architecture is moving beyond passive power transfer toward integrated safety and intelligence. Switch-rated industrial plugs and receptacles that allow safe make-and-break under load are gaining visibility at industry events, reflecting demand for reduced downtime and lower risk during maintenance and equipment changeover. At the same time, standards bodies and component suppliers are exploring data communication within power connectors to support real-time monitoring, load telemetry, and condition-based maintenance. This convergence of power, safety, and signalling functions is reshaping product roadmaps and creating premium tiers for applications where uptime and visibility carry high economic value.
Heavy-duty twist-lock and pin-and-sleeve platforms continue to serve as the backbone for manufacturing, construction, and utility applications, but differentiation increasingly comes from ancillary capabilities: interlocked receptacles, power distributors, and configurations that simplify installation in space-constrained or corrosive environments. Manufacturers that can combine high current ratings with compact form factors, robust sealing, and user-friendly termination are better positioned to capture share in demanding segments.
Policy and Regulatory Environment
Regulatory updates are reshaping both product requirements and panel integration options. Revisions to standards such as UL 508A for industrial control panels have expanded application options for HVAC and motor controller installations, influencing how industrial plugs and sockets are specified within broader control architectures. In parallel, investigations and clarifications around industrial control and signal distribution, as well as multi-point interconnection power cable assemblies, underscore the growing scrutiny of how power and signal pathways are designed and certified.
For global suppliers, IEC 60309 alignment remains the baseline for cross-border interoperability. The incorporation of data communication provisions within these standards signals a longer-term shift: products that today are evaluated primarily for electrical safety and mechanical durability will increasingly be assessed for their ability to support monitoring, identification, and integration with industrial control systems. Companies that proactively design for this trajectory can reduce retrofit risk and align with procurement teams seeking future-proof assets.
Demand-Side Shifts in Industrial Operations
Operational priorities are changing the value proposition of industrial connectivity. In manufacturing facilities, the largest application pool, uptime, quick changeover, and worker safety are paramount. Switch-rated and interlocked solutions appeal where frequent equipment cycling or temporary power connections increase exposure to arc hazards or unplanned outages. In oil and gas and mining, hazardous-location certification and durability under extreme conditions remain non-negotiable, but buyers also weigh total cost of ownership, including maintenance intervals and replacement logistics.
Construction sites and energy and utilities segments add a different dynamic: portability, ruggedness, and rapid deployment matter as much as compliance. As projects adopt more modular and temporary power architectures, demand grows for connectors that can withstand repeated handling, environmental exposure, and uneven load profiles without compromising safety. Meanwhile, the broader push toward industrial electrification and decentralized power distribution is expanding the footprint of industrial connectivity beyond traditional factory floors into microgrids, temporary generation, and hybrid power setups.
Supply Chain and Cost Structure Dynamics
Material selection and termination practices are becoming strategic levers. The increasing attention to aluminum conductor compatibility reflects efforts to manage weight and cost in power distribution, especially where copper pricing or logistics constraints pressure project economics. However, aluminum introduces connection-specific challenges that require revised torque practices, contact surface treatments, and user education. Manufacturers that publish clear guidance and design connectors to accommodate these realities can reduce installers' risk and strengthen trust in their product lines.
At the same time, the balance between standardization and customization affects cost structures. Highly customized configurations can command premiums but complicate inventory and certification. Standardized, multi-application platforms with modular options often deliver better margin stability and faster scale, provided they meet the safety and interchangeability expectations of diverse end markets. Suppliers are therefore incentivized to build platforms that cover broad current and voltage ranges while allowing targeted adaptations for hazardous locations or specialty installations.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The market features a mix of specialist manufacturers and broad industrial groups, each pursuing distinct advantages:
- Specialist high-current and hazardous-environment focus. Companies with deep expertise in high-current industrial plugs and sockets and ATEX-rated connectors emphasize current range, certification breadth, and application-specific guidance. Their value proposition centers on reliability in extreme conditions and the ability to support aluminum and other conductor options with clear installation practices.
- Switch-rated and electrically safe technology. A segment of manufacturers has built differentiation around switch-rated industrial plugs and receptacles that enable safe load break and make operations. Visibility at electrical safety workshops and power generation events highlights the strategic importance of safety-centric product narratives, especially where arc-flash mitigation and maintenance safety are procurement priorities.
- Standard-compliant heavy-duty platforms. Broad industrial suppliers offer twist-lock, pin-and-sleeve, and IEC 60309-aligned products spanning a wide range of current and voltage ratings. Their strength lies in scale, cross-application compatibility, and integration with larger electrical ecosystems, including control panels, distribution equipment, and OEM installations.
- CEE and pin-and-sleeve durability. Other established manufacturers focus on CEE and pin-and-sleeve configurations designed for demanding industrial settings, emphasizing mechanical durability, sealing, and long service life. Interlocked receptacles and power distribution accessories extend their portfolios into installation efficiency and operational convenience.
These positions are not mutually exclusive, and many players overlap across categories. What separates leaders is the coherence of their strategy: clear alignment between product capabilities, certification portfolio, application focus, and customer support. Companies that can speak credibly to both electrical safety and operational efficiency tend to earn stronger specification wins in complex projects.
Market Evolution and Structural Shifts
The competitive landscape is likely to evolve along three lines. First, consolidation may continue at the upper end as larger industrial groups seek to broaden their connectivity portfolios and capture cross-selling opportunities within electrical infrastructure. Second, differentiation will increasingly favor suppliers that combine safety certification with monitoring readiness, especially as data communication provisions in power connectors move from concept toward specification. Third, new entrants and regional specialists can still gain traction in under-served applications or geographies, particularly where local compliance knowledge, distribution networks, and pricing agility offset the advantages of global scale.
Light Switches and Electrical Sockets Market
Recent activity illustrates these dynamics. Participation in major trade shows and safety workshops keeps safety-focused and switch-rated solutions in front of specifiers and engineers, reinforcing brand credibility in hazardous and high-risk environments. Product guidance on conductor compatibility and installation practices reflects a customer-centric approach that reduces field risk and supports adoption. Meanwhile, exhibition of new industrial plugs and sockets at large trade platforms signals ongoing portfolio refresh and the importance of visibility in price-sensitive and volume-driven segments.
Future Trends and Commercial Opportunities
Trend 1: Safety-First and Switch-Rated Solutions Will Expand Beyond Niche Use
As electrical safety awareness grows and arc-flash mitigation becomes a more explicit procurement criterion, switch-rated and inherently safe industrial plugs and sockets are likely to move from specialized applications into broader industrial use. The opportunity lies in packaging these solutions with clear guidance, training, and panel integration support so that buyers can justify the premium through reduced downtime, safer maintenance, and lower risk exposure. Manufacturers that can demonstrate measurable safety and operational benefits will be well positioned to capture share in manufacturing, oil and gas, and mining environments where human interaction with live connections is frequent.
Trend 2: Connectivity With Monitoring Readiness Will Redefine Value Tiers
The incorporation of data communication provisions within power connectors points toward a future where industrial plugs and sockets contribute to real-time monitoring and control. Even if full intelligence is adopted gradually, products designed with communication readiness in mind will face lower retrofit risk and better alignment with digitalization agendas in factories and utilities. Commercial opportunities include premium lines for condition monitoring, identification, and integration with industrial control architectures, as well as platform strategies that let customers add functionality incrementally. Suppliers should prepare for a market where electrical performance and data enablement are evaluated together rather than as separate concerns.
Trend 3: Conductor Material Flexibility and Installation Support Will Influence Specification
As aluminum conductors gain consideration for cost and weight reasons, the ability to support multiple conductor types safely will become a differentiator. Products that maintain connection integrity, include clear termination guidance, and account for thermal and corrosion behavior will reduce installer uncertainty and broaden applicability. This trend creates opportunities for manufacturers to publish practical guidance, train distribution partners, and design connectors that simplify proper installation. In project-driven markets, the supplier that makes correct installation easiest often gains an edge in specification and repeat business.
Risks and Uncertainties to Monitor
- Standards evolution pace and interpretation. If data communication and monitoring features become more firmly embedded in compliance expectations, suppliers that have not prepared design and testing pathways may face rework or specification disadvantages.
- Certification and regional variance. Hazardous-location certifications and panel standards can differ across jurisdictions, creating complexity for global product plans and slowing entry in certain markets.
- Material and cost volatility. Shifts in conductor material preferences, component costs, and logistics can pressure margins, especially for suppliers with rigid platform designs or limited flexibility in termination solutions.
- Safety claim substantiation. As switch-rated and electrically safe solutions gain attention, buyers will expect rigorous evidence of performance. Overstating capabilities without robust testing and certification could erode trust and invite scrutiny.
Strategic Recommendations for Decision-Makers
For Manufacturers and Product Strategists
Build platform strategies that balance standardization with targeted differentiation. Core product lines should cover broad current and voltage ranges with IEC 60309 alignment and robust mechanical design, while premium variants address safety-centric and monitoring-ready needs. Invest in certification breadth for hazardous locations and clearly document installation practices, especially for aluminum conductor compatibility, to reduce field risk and strengthen specifier confidence. Use trade presence and technical events not only for visibility but to gather specifier feedback on safety, uptime, and integration priorities that should shape the next product iteration.
For Investors and Capital Allocators
Focus on suppliers with coherent safety and application narratives, credible certification portfolios, and the ability to support emerging monitoring requirements without abandoning core electrical performance. Companies that can articulate total cost of ownership benefits—reduced downtime, safer maintenance, simpler installation—tend to command stronger positioning than those competing primarily on price. Watch for consolidation signals among broader industrial groups and for regional specialists that have built defensible niches in hazardous environments or specific geographies. Assess whether portfolio initiatives toward data communication readiness are backed by concrete design and testing progress rather than aspirational messaging.
For Procurement and Engineering Leaders
Evaluate industrial plugs and sockets against a broader set of criteria than electrical rating alone. Include safety performance under load, hazardous-location certification where relevant, compatibility with conductor materials in your installations, and the availability of clear guidance and training. Where uptime and maintenance safety are critical, consider switch-rated and interlocked options and validate claims with documentation and reference experience. For facilities planning longer-term digitalization, prioritize products designed with monitoring and identification readiness to reduce future integration friction. Engage suppliers early in specification to align termination practices, panel integration, and compliance requirements before procurement locks in a configuration.
Industrial Connectors Market
Closing Perspective
The industrial plugs and sockets market is not merely expanding; it is reconfiguring around safety, intelligence, and material flexibility. Steady growth through the end of the decade provides a favorable backdrop, but the real differentiation will come from how well suppliers and buyers navigate compliance complexity, hazardous-environment performance, and the gradual integration of monitoring capabilities into power connectors. For manufacturers, the imperative is to build coherent platforms that combine electrical robustness with safety and future readiness. For investors, the opportunity lies in companies that can translate technical capabilities into measurable operational value. For procurement and engineering teams, the priority is to specify with a wider lens that includes installation safety, conductor compatibility, and long-term integration needs.
Detailed segmentation data, company-level benchmarks, and application-specific forecasts can sharpen these decisions further. For decision-makers seeking granular revenue splits, regional dynamics, and tailored scenario analysis, a comprehensive research report offers the depth required to translate market-level trends into concrete product, investment, and procurement strategies.
For detailed analysis of this topic, please visit the official page: Industrial Plugs and Sockets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


