



Household Dehumidifiers Market: Why Portable Units Drive 4.25% CAGR Growth

Global Household Dehumidifiers Market: Strategic Trends and Commercial Opportunities Through 2032
The global household dehumidifiers market has reached a defining inflection point. Valued at approximately USD 135.5 million in 2025, the sector has demonstrated consistent expansion over the past five years, with historical revenues climbing from USD 110.0 million in 2020 to USD 135.5 million in 2025. Looking ahead, the market is projected to grow at a compound annual growth rate of 4.25 percent through 2032, reaching an estimated USD 181.0 million by the end of the forecast period. This trajectory reflects structural shifts in how households and commercial properties manage indoor environmental quality, rather than temporary post-pandemic adjustments or cyclical weather patterns.
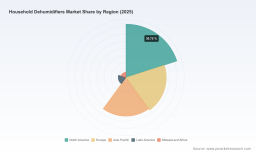
Beneath these headline figures lies a more nuanced operational reality. Growth is not evenly distributed across product formats, geographic corridors, or use cases. Portable units continue to dominate volume-driven logistics and retail distribution, while integrated whole-home systems command higher margin structures and longer installation cycles. The residential application segment anchors the majority of demand, yet hospitality and specialized facility deployments are steadily expanding as property managers recognize humidity control as a cost-of-ownership and asset-preservation issue. Regional concentration patterns reveal mature markets with high penetration rates alongside emerging corridors where climate volatility, urbanization, and awareness campaigns are accelerating adoption curves.
For executives and investors, the central challenge is no longer whether the market is expanding, but how the structural fractures within it will reshape competitive advantage over the next half decade. Three dynamics will determine who captures value and who faces margin compression.
Regulatory Decarbonization Is Rewriting Product Architecture
Beginning in early 2025, regulatory frameworks in both the United States and Europe have materially altered the refrigerant landscape for dehumidification equipment. U.S. EPA AIM Act provisions have initiated a phasedown of hydrofluorocarbon use across refrigeration, air conditioning, and heat pump equipment, including household dehumidifiers. Simultaneously, EU Regulation (EU) 2024/573 mandates the phase-down of high-GWP refrigerants and prohibits the placement of new equipment using refrigerants above 750 GWP, effective throughout 2025. These rules are not incremental compliance tweaks; they require redesigns of compressors, refrigerant circuits, thermal management systems, and service protocols.
For manufacturers, this translates into higher upfront engineering costs, qualification cycles, and supply chain retooling. For distributors and installers, it introduces potential inventory obsolescence if legacy stock is not aligned with revised specifications. The strategic implication is clear: regulatory alignment is transitioning from a back-office compliance function to a product differentiation lever. Companies that embed low-GWP architectures, transparent lifecycle documentation, and service-friendly component designs early will reduce retrofit risk and position themselves for procurement mandates in climate-conscious regions.
Indoor Air Quality Awareness Is Reshaping Demand Patterns
Consumer expectations around residential environments have shifted permanently. Rising awareness of mold risks, respiratory comfort, and humidity-driven structural deterioration has elevated dehumidification from a seasonal convenience to a baseline indoor air quality consideration. Extreme weather events have repeatedly highlighted how quickly moisture accumulation compromises building integrity, furniture, and occupant health, driving households and property operators to treat environmental control as preventative infrastructure rather than reactive mitigation.
This behavioral shift changes purchasing logic. Buyers are evaluating longevity, serviceability, noise profiles, and integration with broader home automation ecosystems alongside raw moisture removal capacity. The result is a growing premium on products that deliver consistent performance with lower operational friction. Manufacturers that communicate tangible indoor air quality benefits, backed by verifiable efficiency data and straightforward maintenance pathways, are capturing share in segments where trust and repeat usage matter more than short-term promotional pricing.
Desiccant Dehumidifier Market
Trade Policy and Cost Structures Are Introducing Regional Volatility
Tariff evolution and component cost dynamics are adding new layers of complexity to market execution. Recent revisions to the U.S. Harmonized Tariff Schedule apply duties to dehumidifiers with rated water removal capacity below 35 liters per day, altering the economics of entry-level and travel-oriented portable units. At the same time, fluctuating costs for compressors, electronic controls, and insulated housings continue to pressure margin structures, particularly for manufacturers relying on high-volume, low-differentiation product lines.
The commercial implication is a recalibration of where volume and margin can be sustainably captured. Markets with transparent tariff schedules and stable component sourcing are becoming more attractive for scaled production, while regions with fragmented import rules require more localized assortment strategies and pricing discipline. Companies that treat trade exposure as a strategic variable, rather than a periodic finance issue, are better positioned to protect profitability during demand surges and supply disruptions alike.
Key Drivers Shaping the Next Phase of Market Growth
Technology Innovation and the Shift Toward Intelligent, Efficient Operation
Advances in compressor engineering, sensor integration, and adaptive control algorithms are redefining performance expectations. Smart inverter-compressor platforms are enabling more precise humidity modulation, reduced cycling, and smoother energy draw across varying loads. Artificial intelligence-assisted operation is increasingly supporting automatic adjustment to ambient conditions, occupancy patterns, and seasonal transitions, reducing the need for manual intervention and improving user satisfaction in continuous-use scenarios.
PW Consulting
Energy efficiency has become a central battleground. Recent product launches illustrate the industry's direction. The introduction of next-generation whole-home dehumidification systems has emphasized flexible installation configurations, enhanced serviceability, extended lifecycle design, and measurable energy efficiency improvements. In parallel, new dehumidifier series have emerged with reported energy consumption reductions in the fifteen to twenty percent range compared to prior generations, alongside meaningful decreases in associated carbon emissions. These developments signal a broader market move toward products that deliver lower total cost of ownership, not just competitive sticker prices.
Policy and Regulatory Environment as a Competitive Filter
Regulation is functioning as both a constraint and a catalyst. The synchronized push toward lower-GWP refrigerants in the United States and Europe is compelling a rapid transition away from legacy fluid systems. This transition is accelerating innovation in refrigerant selection, heat exchanger design, and leak-detection protocols, while also filtering out manufacturers that lack the engineering resources or supply chain agility to adapt quickly.
For the industry, the policy environment is also shaping procurement behavior. Facility operators, hospitality groups, and property portfolios are increasingly specifying equipment that aligns with internal sustainability targets and regional compliance requirements. As a result, regulatory readiness is becoming a qualifier for larger, multi-unit deployments where replacement cycles are long and reputational or compliance risk is material. Companies that anticipate specification changes and build compliant product lines ahead of mandate deadlines will find themselves in a stronger position during tender processes and channel negotiations.
Demand-Side Behavior and the Normalization of Environmental Control
Consumer and commercial demand is being reshaped by a combination of health awareness, climate variability, and improved product usability. Households are purchasing dehumidifiers with a longer-term perspective, prioritizing quiet operation, straightforward emptying or drainage options, and integration with everyday living spaces. At the same time, commercial operators are expanding deployment in hospitality, storage-adjacent facilities, and specialty environments where moisture control protects assets and supports guest or occupant comfort.
This demand evolution is also changing the adoption pathway. Instead of treating dehumidification as an occasional purchase triggered by a single wet season, buyers are increasingly factoring it into broader home improvement and property management planning. That shift supports steadier repeat demand and creates opportunities for bundled offerings, including complementary air filtration, monitoring, and maintenance services. The businesses that benefit most will be those that align product design and messaging with longer ownership horizons and real-world usage patterns.
Supply Chain Recalibration and Component Cost Dynamics
The cost structure of dehumidifier manufacturing is increasingly influenced by compressor availability, electronic component pricing, and logistics complexity. As product designs grow more sophisticated, the dependence on precision components and integrated control boards rises, making supply continuity and quality consistency more critical. At the same time, regional manufacturing footprints and trade classifications are influencing where cost advantages can be sustained.
Strategic leaders are responding by diversifying component sourcing, standardizing modular architectures where possible, and aligning production schedules with regional demand signals rather than relying solely on centralized volume assumptions. This approach reduces exposure to abrupt cost spikes and improves responsiveness when demand shifts across product types or end-use segments. In practice, supply chain resilience is becoming a margin-protection strategy as much as an operational one.
Competitive Landscape and the Emergence of Differentiated Positioning
The competitive field is consolidating around a blend of large multinational appliance groups, specialized climate technology players, and regional brands with strong channel access. Market concentration remains relatively tight, reflecting the importance of brand trust, distribution reach, and compliance readiness in a market where performance claims and energy credentials directly influence purchase decisions.
Strategic Positioning Across Leading Players
Several manufacturers are pursuing distinct value propositions that illuminate where the market is heading. Midea Group continues to lead in portable and smart Cube-series units, leveraging ENERGY STAR certification and pump options to address the high-volume residential and light commercial segments. Its positioning reflects a focus on accessible feature sets, energy credentials, and retail-friendly product architectures that simplify consumer comparison.
Resideo Technologies has concentrated on whole-home dehumidification through its Honeywell Home line, emphasizing flexible installation, enhanced serviceability, and improved lifecycle performance. The recent launch of a next-generation whole-home dehumidifier highlights the company's emphasis on installation adaptability, service-friendly design, and energy efficiency gains. This approach targets property owners and installers who value long-term maintainability and specification flexibility over short-term unit price alone.
LG Electronics has advanced smart inverter-compressor models for residential indoor air quality control, integrating energy-efficient AI operation into its residential portfolio. The strategic signal here is clear: intelligence and efficiency are being packaged together, positioning the product as part of a connected home environment rather than a standalone utility appliance.
Other participants are carving out defensible niches through compact design, integrated consumer features, and broad retail distribution. Danby Products provides compact and portable units with integrated features tailored to consumer homes. Frigidaire, under Electrolux, manufactures Gallery and other series portable dehumidifiers widely tested for home use, reinforcing a familiar appliance brand presence in mainstream channels. GE Appliances, now part of Haier, supplies portable models integrated with smart controls for household humidity management, aligning convenience with digital connectivity. Whirlpool Corporation produces efficient portable units within its consumer appliance portfolio, relying on distribution breadth and brand familiarity. Honeywell International continues to supply residential and whole-home dehumidifiers with an emphasis on indoor air quality, maintaining a strong association with environmental control credibility. De'Longhi S.p.A. markets compact models for European and global household markets, capitalizing on design-conscious positioning and established regional presence. TCL Technology offers smart portable dehumidifiers through global consumer channels, reflecting the expansion of tech-enabled appliances beyond traditional appliance conglomerates.
Market Structure Evolution: Consolidation, Fragmentation, and New Entry Points
The competitive landscape is evolving along two simultaneous paths. At one end, larger players are strengthening their hold through multi-category portfolios, cross-category brand leverage, and compliance-ready engineering platforms. At the other, specialized and regional entrants are exploiting gaps in compact design, localized service networks, and targeted smart features. The net effect is a market where share gains are increasingly determined by how well a company aligns product architecture with regional regulations, installation ecosystems, and consumer usage expectations.
New entry opportunities are emerging in segments where energy performance, noise reduction, connectivity, and serviceability can be packaged into compelling user experiences. However, the barrier to durable advantage is rising. Low-cost, undifferentiated portable units face intensifying pressure from both tariff adjustments and consumer expectations for efficiency and reliability. In contrast, whole-home and integrated residential solutions reward companies that can demonstrate installation flexibility, component longevity, and verifiable efficiency gains. The market is therefore moving toward a bifurcated structure in which commoditized volume competition coexists with premium, specification-driven differentiation.
Outlook for the Next Three to Five Years
Efficiency and Intelligent Control as Standard Expectations
Over the next several years, energy efficiency and adaptive control will transition from differentiating features to baseline requirements. As regulatory pressure on refrigerants and energy performance continues, and as consumers become more accustomed to automated environmental management, products that cannot deliver measurable efficiency improvements and low-friction operation will face growing displacement risk. The commercial opportunity lies in bundling performance credibility with user experience: intuitive controls, predictable maintenance intervals, and documented energy savings that justify purchase decisions and reduce service burden.
Regulatory Compliance as a Launchpad for Specification Wins
Compliance readiness will increasingly function as an entry ticket for larger residential and commercial deployments. Procurement teams, property operators, and channel partners are likely to prioritize equipment that already aligns with evolving refrigerant rules and energy expectations, especially in regions where sustainability mandates and indoor air quality standards are tightening. Companies that invest early in compliant architectures and transparent documentation will be better positioned to secure multi-unit projects, installer partnerships, and repeat procurement cycles. The risk, for laggards, is a narrowing path to specification lists and a growing reliance on price competition in shrinking legacy segments.
Segmentation Tension Between Volume Portability and Integrated Systems
A persistent tension will shape strategic choices across the market. Portable units will continue to serve mass-market convenience, seasonal needs, and flexible deployment scenarios, but margins in this segment will depend on efficient production, disciplined assortment management, and clear consumer value messaging. Whole-home and integrated residential systems will command stronger value capture where installation complexity, serviceability, and long-term performance can be communicated credibly. Businesses will need to decide whether to compete broadly across both tiers or concentrate on the segment where their engineering, distribution, and service capabilities can sustain defensible economics.
Underlying these trends is a set of uncertainties that decision-makers should monitor closely. Policy implementation details may shift as regulatory agencies refine enforcement approaches. Trade classifications and tariff applications could alter the relative attractiveness of specific capacity thresholds and import routes. Component cost volatility, particularly in compressors and control electronics, may compress margins for manufacturers with limited sourcing flexibility. Finally, consumer adoption could diverge from projections if economic conditions slow discretionary home improvement spending or if competing indoor air quality solutions gain traction in overlapping use cases.
Worldwide Home Use Dehumidifier Market
Strategic Implications for Decision-Makers
For Manufacturers and Product Leaders
Product roadmaps should treat regulatory alignment, energy efficiency, and serviceability as core design constraints rather than late-stage compliance tasks. Prioritizing low-GWP architectures, modular component designs, and installation-friendly configurations will reduce future retrofit exposure and improve competitiveness in specification-driven deployments. Where portable units remain central to the portfolio, differentiation should come from usability, noise performance, pump or drainage options, and verifiable efficiency credentials rather than capacity claims alone. Where whole-home or integrated systems are emphasized, the value story should center on lifecycle performance, installer-friendly service access, and compatibility with broader residential environmental control ecosystems.
For Investors and Strategic Allocators
Investment attention should focus on companies with credible pathways to compliant product lines, resilient component sourcing, and clear positioning in the segments most likely to command sustainable margins. The market's growth is real, but profitability will increasingly separate along lines of engineering capability, regulatory preparedness, and channel execution. Avoid assuming uniform returns across all product types or regions. Instead, evaluate exposure to tariff-sensitive capacity segments, dependence on single-source components, and the ability to participate in multi-unit or service-supported deployment models where repeat revenue and specification lock-in can strengthen long-term economics.
For Procurement and Channel Decision-Makers
Purchasing strategy should weigh total cost of ownership alongside unit price, particularly where installation complexity, maintenance frequency, and energy draw will influence multi-year operating costs. Specification decisions are increasingly affected by refrigerant compliance, serviceability, and efficiency documentation, especially in properties with sustainability targets or long replacement cycles. Diversifying supplier options, validating lifecycle claims, and aligning assortment choices with regional regulatory timelines will reduce the risk of stranded inventory or premature obsolescence. In channels where consumer education matters, prioritized messaging around quiet operation, intuitive controls, and energy performance is more likely to support repeat satisfaction than emphasis on short-term promotional discounts.
The Household Dehumidifiers Market is entering a phase where growth and differentiation are increasingly intertwined. Regulatory shifts, efficiency expectations, and evolving demand patterns are reshaping the economics of product design, distribution, and procurement. Companies that treat these forces as strategic inputs, rather than isolated operational constraints, will be better equipped to capture value across both volume and premium segments. For decision-makers seeking granular segmentation data, regional margin scenarios, and customized competitive benchmarking, the full PW Consulting research report provides the detailed supporting analysis needed to translate these market-level trends into precise commercial action.
For detailed analysis of this topic, please visit the official page: Household Dehumidifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


