



X-ray Security Scanner: Asia Pacific’s 6.5% CAGR Drives a 11.5B Market

The X-Ray Security Scanner Market: Strategic Shifts and Commercial Opportunities in a High-Growth Security Landscape
The global X-ray security scanner market is undergoing a structural transformation. Valued at USD 7.4 billion in 2025, the sector is projected to expand at a compound annual growth rate of 6.5 percent, reaching approximately USD 11.5 billion by 2032. The trajectory from 2020 through 2032 reflects a market that has moved beyond post-9/11 security baseline spending into a phase defined by technological modernization, regulatory recalibration, and shifting threat perceptions across transportation and commercial infrastructure. Market concentration remains moderate, with the top three players collectively accounting for roughly 24.6 percent of global revenue and the top five capturing approximately 26.2 percent. This fragmented yet strategically consolidating landscape creates distinct pathways for differentiated positioning, whether through hardware innovation, software-enabled analytics, or integrated service architectures.
Behind the headline growth figures lies a market navigating several inflection points. Operators are balancing throughput requirements against deeper imaging fidelity, budget-constrained public agencies are weighing capital expenditure against lifecycle costs, and end-user environments are demanding detectors that can distinguish organic from inorganic threats without interrupting passenger or freight flow. At the same time, regulatory mandates are pushing older single-view tunnels toward replacement, privacy considerations are redirecting certain screening applications toward alternative modalities, and supply chain volatility is reshaping procurement timelines and vendor selection logic. Understanding where these pressures converge is essential for manufacturers, investors, and procurement leaders seeking to align their strategies with the next cycle of demand.
Market Landscape and Core Challenges
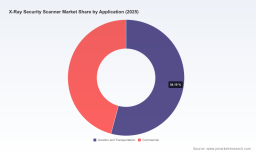
The revenue distribution across the market in 2025 underscores a clear structural emphasis on body screening and aviation-transformation applications, which together represent the dominant share of installed and deployed systems. Baggage and parcel scanning continues to anchor volume demand, while commercial facilities increasingly integrate X-ray and complementary imaging solutions to address cargo, logistics, and critical infrastructure screening requirements. The regional spread indicates that Asia Pacific, Europe, and North America collectively drive the bulk of procurement activity, with emerging corridors in Latin America and the Middle East and Africa expanding at a pace that reflects both infrastructure investment and heightened border security postures. Rather than treating these splits as static allocations, decision makers should view them as indicators of where modernization budgets, replacement cycles, and capacity upgrades are concentrating.
Three challenges define the current market turning point.
1. The Dual-View to Computed Tomography Transition
Single-view and dual-view X-ray tunnels remain workhorse systems in many checkpoints, but volumetric imaging is increasingly mandated for higher-risk freight and compressed throughput environments. The shift is not merely a hardware upgrade; it changes installation footprints, operator training requirements, power and cooling demands, and maintenance contracts. Procurement teams that underestimate the integration complexity of CT-based checkpoint systems risk deployment delays, while suppliers that fail to offer phased migration paths or retrofit-compatible architectures may lose share to competitors with more flexible transition strategies.
2. Cost Structures and Unit Economics
Checkpoint-grade systems carry significant capital intensity. Advanced CT screening units for checkpoints command unit prices in the range of USD 2.5 million to USD 3.2 million, roughly four times the cost of traditional dual-view tunnels. This pricing differential forces operators to prioritize deployments, negotiate financing structures, and evaluate total cost of ownership rather than sticker price alone. In parallel, tariff adjustments on certain pallet scanning equipment have prompted buyers and suppliers to revisit sourcing strategies, vendor selection criteria, and deployment timelines, adding uncertainty to procurement planning and inventory positioning.
3. Privacy, Public Perception, and Modality Substitution
Public acceptance remains a strategic variable. Privacy objections have slowed the deployment of backscatter-based systems in certain public venues such as stadiums, nudging operators toward millimeter-wave alternatives and other imaging approaches that balance detection performance with user experience. Although this dynamic pertains more directly to walk-through and stand-off modalities than to conventional X-ray tunnels, it influences the broader screening ecosystem by shaping procurement preferences, policy debates, and the willingness of end-users to adopt newer technologies in high-visibility locations.
Key Drivers Shaping the Market
Market momentum is being propelled by a combination of technological breakthroughs, regulatory pressure, evolving end-user behavior, and shifting cost and supply chain dynamics. These drivers interact in ways that create both urgency and selectivity in procurement decisions.
Technological Innovation and Threat Detection Fidelity
The most consequential technology trend is the migration toward computed tomography and multi-view imaging within checkpoint and cargo screening environments. CT-based systems improve material discrimination, reduce false alarms, and allow operators to rotate and slice reconstructed images, thereby increasing detection confidence while supporting faster passenger and baggage flow. Alongside imaging hardware, software-driven analytics, automated threat recognition, and digital twin integration are reshaping how scanning systems deliver value. Suppliers that pair high-fidelity imaging with integrated software layers can differentiate on operational outcomes rather than raw hardware specifications. Recent commercial activity illustrates this emphasis: Rapiscan Systems received a USD 19 million order to support deployment of non-intrusive inspection solutions, followed by a USD 15 million order for cargo and vehicle inspection systems and services. These placements reflect demand for end-to-end inspection capabilities that span baggage, parcel, freight, and vehicle contexts, with mobile threat detection integrated into the operational workflow.
Policy and Regulatory Pressure as a Demand Catalyst
Regulation continues to function as a powerful demand accelerator. EASA rules now require freight above 150 kg to undergo volumetric imaging, a mandate that is accelerating the replacement of single-view tunnels with higher-capability systems. In the United States, the Transportation Security Administration allocated approximately USD 1.3 billion for 469 CT units in 2025, signaling a decisive commitment to modernization at scale. Regulatory certifications also matter for market access and buyer confidence; for example, OSI Systems received ECAC/EU G1 certification for trace detection solutions for airport security in April 2026, reinforcing the importance of recognized approvals when operators evaluate systems for international deployment. These policy signals help de-risk procurement decisions and create multi-year installation pipelines that suppliers can plan around.
Demand-Side Evolution Across Aviation and Commercial Sectors
Demand is increasingly shaped by end-user priorities that extend beyond baseline compliance. Aviation and transportation stakeholders seek solutions that reduce passenger wait times, improve lane throughput, and provide actionable visualization for operators. Commercial entities, including logistics hubs, warehousing environments, and critical infrastructure operators, are expanding screening footprints to address cargo verification, internal theft and contraband detection, and facility-level security layering. This diversification means that manufacturers must tailor value propositions to distinct operating environments: checkpoint speed and ergonomics in aviation, while robustness, scale, and integration with warehouse management or cargo handling systems in commercial contexts. The relative revenue weight of aviation-transportation and commercial applications in 2025 confirms that both segments remain central to growth, but their requirements and purchasing cycles differ meaningfully.
Supply Chain Realities and Cost Architecture
Supply chain conditions continue to influence market behavior. Component availability, semiconductor constraints, and the cost of precision mechanical and sensing elements affect lead times and final system pricing. Tariff adjustments on selected pallet scanning equipment have already compelled buyers and suppliers to revisit vendor selection, sourcing strategies, and deployment timelines. In response, some operators are dual-sourcing critical subassemblies, negotiating longer-term service agreements to stabilize lifecycle costs, and planning deployment schedules with greater flexibility. Suppliers that can demonstrate resilient supply chains, transparent pricing, and modular architecture are better positioned to secure commitments in an environment where procurement teams are risk-aware and timeline-sensitive.
Security Screening Systems Market
Competitive Landscape and Leading Strategies
The competitive field combines established security hardware specialists, diversified defense and aerospace players, and regionally strong manufacturers with growing international reach. Market share is distributed rather than dominated, which rewards clear positioning and executable go-to-market strategies. Several companies illustrate the breadth of strategic approaches currently shaping the market.
Worldwide Security Laser Scanner Market
Rapiscan Systems, based in the United States, emphasizes Orions and Z Portal systems for baggage, parcel, freight, and vehicle inspection, with mobile threat detection integrated into its offering. The company’s recent order flow and certification activity reflect a strategy centered on non-intrusive inspection breadth, regulatory alignment, and service-supported deployments. Smiths Detection, headquartered in the United Kingdom, focuses on HI-SCAN and SDX X-ray systems for checkpoint and cargo screening, positioning around proven checkpoint performance and cargo inspection reliability. L3Harris Technologies, also U.S.-based, highlights ASCT and RSM-7 X-ray screening systems tailored for aviation and defense contexts, leaning into mission-grade robustness and integration with broader security and defense ecosystems.
Nuctech Company Limited, based in China, offers TSA-600 and T2000 X-ray systems for airports and cargo, pursuing scale, cost competitiveness, and expanding international deployments. Gilardoni S.p.A. of Italy concentrates on security X-ray scanners for baggage and parcel inspection, with a focus on precision imaging and specialized inspection workflows. 3DX-Ray, also U.K.-based, targets portable and cabinet X-ray security scanners for threat detection, serving applications where mobility and compact form factors are critical. Analogic Corporation, in the United States, develops advanced X-ray imaging systems for security screening, emphasizing image quality and engineering depth. Leidos, another U.S. player, provides AXM and L-3 X-ray systems for security applications, leveraging large-scale systems integration capabilities. Astrophysics Inc., based in the United States, promotes American-made X-ray security scanning systems for critical infrastructure, aligning with procurement preferences for domestic sourcing in sensitive environments. VOTI Detection, headquartered in Canada, focuses on 3D Perspective X-ray scanners for border and cargo screening, emphasizing volumetric reconstruction suited to border and freight inspection contexts.
Several strategic patterns emerge from this landscape. First, incumbents are expanding beyond hardware into software-assisted interpretation, service contracts, and lifecycle management, because recurring revenue and operational outcomes increasingly determine win rates in competitive tenders. Second, differentiation is shifting from single-dimension specifications to integrated value propositions that combine imaging fidelity, throughput, ergonomics, certification, and support responsiveness. Third, the market is experiencing selective consolidation pressure: larger players with diversified portfolios can cross-sell across aviation, cargo, and commercial segments, while smaller specialists compete by focusing on portable systems, cabin formats, or niche inspection workflows. At the same time, regional sourcing preferences and tariff-related adjustments are prompting buyers to diversify supplier bases and re-evaluate vendor risk, which opens opportunities for manufacturers that can demonstrate reliable delivery, clear compliance posture, and adaptable deployment models.
PW Consulting
Forward-Looking Trends and Commercial Implications
Looking ahead to the 2026 through 2032 horizon, several trends are likely to define where value concentrates and how competitive advantage is earned.
Trend 1: CT and Multi-View Adoption Will Move From Exception to Expectation in High-Traffic Checkpoints
As regulatory mandates and throughput requirements compound, volumetric imaging will become standard in major aviation corridors and high-volume cargo nodes. The commercial implication is a multi-year replacement and upgrade cycle that favors suppliers capable of offering migration pathways, site-ready installation packages, and operator training programs. Manufacturers that can reduce integration friction and demonstrate measurable improvements in alarm resolution times will capture disproportionate share in this cycle. Investors should watch for recurring service revenue, spare parts pipelines, and software license structures that accompany hardware deployments, because these elements increasingly determine long-term margin profiles.
Trend 2: Software-Defined Screening and Automated Interpretation Will Redefine Value Capture
Image reconstruction is only part of the value chain. Automated threat recognition, alarm classification, and operator decision support are becoming critical differentiators. Systems that reduce cognitive load, shorten training curves, and integrate with broader security information workflows will be preferred in environments where staffing constraints and consistency requirements are acute. This trend creates opportunities for companies that can bundle analytics, analytics updates, and remote support into their offerings, and it raises the stakes for hardware-only entrants that lack a credible software roadmap. A key uncertainty is the pace at which algorithms and recognition models must be updated to keep pace with evolving threat profiles and regulatory expectations, which can pressure both development cycles and certification timelines.
Trend 3: Procurement Diversification and Sourcing Resilience Will Shape Vendor Selection
Recent tariff adjustments and component supply volatility are pushing procurement teams to diversify vendor lists, dual-source critical subassemblies, and re-evaluate deployment timelines. This environment rewards suppliers with transparent supply chains, predictable lead times, and the ability to offer modular or staged deployments that align with budget cycles. For buyers, the commercial opportunity lies in negotiating total cost of ownership-based contracts that include maintenance, calibration, and software support, rather than optimizing narrowly on initial capital outlay. For manufacturers, the opportunity lies in designing architectures that can be configured flexibly across regions and use cases without fragmenting production too extensively. A persistent risk is that tariff and trade policy shifts may continue to disrupt pricing assumptions and delivery schedules, particularly for pallet scanning equipment and certain cargo inspection platforms, requiring continuous monitoring of policy trajectories and supplier exposure.
Strategic Actions for Decision Makers
The market’s direction rewards proactive positioning. The following actions are most relevant depending on role and objectives.
For Manufacturers and Technology Providers
Prioritize integrated value propositions that combine imaging capability, automated interpretation, and service-led lifecycle support. Develop migration paths that allow operators to transition from dual-view to CT-enabled systems without full rip-and-replace disruptions. Strengthen supply chain visibility and offer modular architectures that can be adapted to regional requirements and procurement constraints. Where relevant, pursue recognized certifications and demonstrate compliance with major regulatory frameworks, because these credentials reduce buyer risk and expand addressable markets. Differentiate on operational outcomes such as alarm resolution speed, operator training time, and throughput under real-world conditions rather than on specifications alone.
For Investors and Strategic Capital Allocators
Assess companies based on their ability to capture recurring revenue through services, software, and maintenance contracts, not only on hardware sales. Favor portfolios with exposure to the aviation-transportation and commercial segments that are benefiting from modernization mandates and expanded screening footprints. Monitor the competitive impact of tariff adjustments and sourcing diversification on margins and market share, particularly in pallet and cargo scanning segments where procurement behavior is being re-evaluated. Track the pace of CT adoption in checkpoint environments as a leading indicator of capital intensity, installation pipelines, and supplier differentiation opportunities. Be mindful of policy-driven demand spikes that can create short-term revenue surges but may also compress margins if supply chains are not scaled appropriately.
For Procurement Leaders and End-User Organizations
Structure acquisitions around total cost of ownership, including installation, training, calibration, software updates, and service response times. Plan for phased deployment where possible to align capital expenditure with budget cycles and operational readiness. Evaluate vendor resilience carefully, including lead time stability, parts availability, and the ability to support multiple sites or modalities from a single integration framework. Where privacy-sensitive environments are involved, consider modality trade-offs and user experience implications alongside detection performance to ensure adoption and public acceptance are not compromised. In cargo and freight contexts, align system selection with regulatory requirements for volumetric imaging above specified weight thresholds to avoid future compliance risk and replacement pressure.
Closing Perspective
The X-ray security scanner market is entering a phase in which growth is increasingly tied to technology modernization, regulatory alignment, and the ability to deliver measurable operational outcomes. Revenue expansion from 2025 toward 2032 will be shaped by the pace of CT adoption, the maturation of software-assisted interpretation, and the resilience of supply chains under tariff and component pressures. Competitive advantage will accrue to organizations that treat screening systems as part of a broader security and operational workflow rather than as isolated hardware purchases.
For executives, planners, and investors seeking granular segmentation data, regional demand trajectories, detailed company benchmarking, and customized procurement scenarios, the full PW Consulting study provides a more comprehensive view of the market’s subsegments, competitive moves, and forward scenarios. The complete report extends the analysis into deeper segmentation detail, deployment pattern trends, and strategic recommendations tailored to specific operating contexts and investment horizons.
For detailed analysis of this topic, please visit the official page: X-Ray Security Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


