



Microgrid Technology Market: Why an 18.5% CAGR to $73.9B Redefines Energy Infrastructure Through 2032

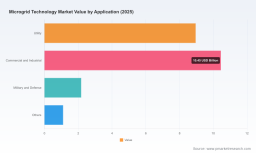
Beyond Grid Dependency: Strategic Trends and Commercial Opportunities in the Microgrid Technology Market
The microgrid technology market is undergoing a structural transformation. Valued at approximately 12.5 billion USD in 2020, the sector expanded to 22.7 billion USD by 2025 and is projected to reach 73.9 billion USD by 2032, reflecting a compound annual growth rate of 18.5 percent over the forecast period. This trajectory signals more than incremental adoption; it indicates a shift from pilot-scale experimentation toward mainstream infrastructure deployment. As distributed energy resources mature and operational priorities evolve, microgrids are transitioning from niche resilience solutions to foundational components of modern energy architecture. For enterprise leaders, the implication is clear: microgrid integration now intersects with capital allocation, regulatory navigation, supply chain strategy, and operational continuity.
The current phase of market development is characterized by accelerated technical validation, yet the pathway from concept to commercial scale remains uneven. Several structural friction points define the present landscape. First, the economics of deployment vary significantly depending on site complexity, load criticality, and regional regulatory frameworks. While standardized configurations benefit from predictable cost curves, customized installations for hospitals, industrial campuses, and critical facilities require substantial engineering investment and multi-stakeholder coordination. Second, the transition toward bidirectional power flows and inverter-based architectures introduces new operational dependencies. Legacy interconnection standards, fragmented approval processes, and evolving cybersecurity expectations create coordination layers that can delay project timelines. Third, the market remains moderately concentrated, indicating that scale advantages, proprietary control systems, and integrated service offerings continue to shape competitive positioning. These dynamics collectively suggest that market growth will increasingly favor organizations capable of aligning technical performance with regulatory clarity, financial structuring, and long-term service reliability.
Key Drivers Shaping Market Trajectory
Technological Innovation and System-Level Integration
The maturation of microgrid technology is being driven less by any single breakthrough and more by the integration of previously siloed capabilities. Advanced energy management systems now coordinate distributed generation, storage, and load-shifting with greater precision, enabling facilities to maintain critical operations during grid disturbances. Controller architectures have improved response times for islanding and reconnection, while hybrid configurations increasingly combine solar, battery storage, and alternative generation pathways to reduce reliance on any single resource. These capabilities are especially relevant in environments where continuity is non-negotiable. Recent projects illustrate this trajectory: one of the largest hospital-based renewable microgrid systems in the United States came online with integrated solar generation, long-duration battery storage, and fuel cell backup designed for emergency power continuity. Within months, the installation transitioned into operational backup mode, demonstrating how integrated microgrid platforms can move from construction to active resilience support while contributing to regional renewable transition objectives. Technological progress is therefore not only enhancing system performance but also expanding the envelope of use cases where microgrids can deliver measurable operational value.
Policy and Regulatory Evolution
Regulatory frameworks are becoming both an enabler and a constraint. On one side, public-sector emphasis on grid resilience, decarbonization, and energy security is encouraging distributed infrastructure investment. On the other, the absence of uniform interconnection standards and the complexity of multi-party approvals can complicate deployment, particularly for single-property installations that must coordinate with internal facilities teams, financial stakeholders, and external authorities including utilities, planning departments, and fire marshals. A recent community guide addressing regulatory barriers highlighted how these coordination requirements can slow project execution for hospitals and other critical facilities, especially when stakeholder alignment and jurisdictional approvals are not mapped early in the development cycle. At the same time, new certification initiatives are beginning to establish baseline expectations for device-level security and interoperability. The introduction of an industry-wide cybersecurity certification program for microgrids, inverter-based devices, and distributed energy resources reflects a broader shift toward standardized safeguards as systems become more digitally managed and networked. For market participants, regulatory developments are no longer background conditions; they are active design parameters that influence architecture choices, procurement timelines, and deployment risk.
Demand-Side Realignment Across Sectors
Demand for microgrid solutions is being reshaped by changing expectations around cost predictability, operational continuity, and sustainability performance. Commercial and industrial operators are increasingly evaluating on-site generation and storage as a means to reduce exposure to grid volatility and support corporate energy objectives. Healthcare institutions, in particular, have emerged as a strategically important segment because their load profiles include mission-critical services that cannot tolerate extended outages. Recent deployments have paired solar arrays with combined heat and power systems to deliver meaningful cost reductions alongside carbon footprint improvements, demonstrating how microgrid installations can serve both financial and operational mandates. In parallel, the growth of remote and constrained infrastructure settings continues to support off-grid and hybrid configurations where grid dependence is impractical or too costly. The common thread across these demand patterns is a move from passive consumption toward active energy management, where facilities treat generation, storage, and control systems as part of a broader continuity and efficiency strategy rather than as standalone capital projects.
Supply Chain and Cost Structure Dynamics
Cost structures across the microgrid value chain are evolving as component maturity, manufacturing scale, and system integration practices improve. Still, cost trajectories are not uniform. Construction expenses can vary substantially by generation mix, storage technology, and site-specific engineering requirements, particularly when advanced energy management optimization is needed to support sensitive loads during outages. Hospital-grade installations, for example, may involve higher per-megawatt investment thresholds because of the need to maintain continuity for intensive care units, operating environments, and other critical functions. At the same time, the long-term financial case for microgrids is increasingly strengthened by their ability to reduce dependency on external supply conditions and provide more predictable generation cost profiles. In certain configurations, operators have realized substantial energy cost reductions by shifting toward fixed generation capabilities and lowering exposure to grid pricing variability. These economic dynamics create a nuanced deployment environment: while upfront capital requirements can be meaningful, lifecycle economics and resilience benefits are becoming more quantifiable, encouraging a longer-range view of return on investment.
Competitive Landscape and Strategic Positioning
Differentiated Value Propositions Among Leading Participants
The competitive environment is shaped by a mix of established industrial players and specialized technology providers, each emphasizing distinct aspects of the microgrid value chain. ABB has positioned itself around integrated microgrid technology solutions that span controllers, energy management systems, and hybrid renewable integration, emphasizing reliable power supply across varied operating conditions. Siemens focuses on microgrid controllers and integrated power solutions designed for seamless islanding and scalability, with particular relevance to critical facilities that require dependable operational transitions. Schneider Electric emphasizes platform-based approaches that combine energy management with renewable integration, targeting commercial and critical infrastructure applications. Eaton differentiates through energy storage systems and DC microgrid solutions aimed at efficient power distribution and backup performance. Honeywell concentrates on energy management and control systems optimized for critical facility resilience, while GE Vernova provides advanced controllers and hybrid solutions oriented toward utility and industrial use cases. S&C Electric Company has built its profile around ultra-fast islanding capabilities that support seamless power continuity, and Bloom Energy offers solid oxide fuel cell technology as an always-on clean generation pathway without combustion. On the project and deployment side, organizations such as Faraday Microgrids and Ameresco have developed focused approaches around hospital-based renewable systems and solar canopy configurations delivered under power purchase arrangements, reflecting the growing importance of tailored deployment models in sensitive institutional environments.
Market Structure and Evolution Patterns
Market concentration suggests that scale, integration depth, and service continuity remain influential in shaping competitive advantage. Organizations with broad component portfolios, established control architectures, and the ability to manage complex interconnection requirements often hold an advantage in higher-stakes deployments. At the same time, the landscape is not consolidating into a single model. Instead, it is evolving along multiple axes: some incumbents are deepening system-level integration and software-driven management capabilities, while specialized entrants continue to compete on niche performance characteristics, such as rapid islanding, fuel cell integration, or sector-specific design expertise. The result is a market in which differentiation increasingly depends on the ability to combine hardware reliability, software intelligence, cybersecurity readiness, and financial structuring flexibility. New entrants and project developers are likely to continue carving out positions where specialized load requirements, regional regulatory knowledge, or novel procurement structures create room for tailored solutions. Over time, the market may see further consolidation among integrated platform providers, alongside continued fragmentation in specialized applications where customization and stakeholder management are central to success.
Microgrid Market
Forward-Looking Trends and Commercial Implications
Scaling of Sector-Specific Microgrid Architectures
Over the next three to five years, one of the most consequential trends is likely to be the expansion of microgrid designs optimized for specific institutional and industrial load profiles rather than generic configurations. Healthcare facilities, data-centric campuses, manufacturing sites, and critical public infrastructure each impose distinct requirements on redundancy, response time, load prioritization, and fuel or storage mix. As deployment experience accumulates, architectures are expected to become more standardized within these segments while retaining the flexibility needed for site-specific constraints. The commercial opportunity lies in developing repeatable design templates, financing structures, and operational service models that reduce project risk and accelerate execution. Organizations that can package proven architectures with predictable performance parameters and clear approval pathways will be better positioned to capture demand in sectors where continuity and compliance are paramount. A related risk is that sector-specific standards and approval expectations may diverge across jurisdictions, increasing complexity for multi-site operators and slowing replication unless coordination frameworks improve.
Integration of Cybersecurity and Interoperability as Core Requirements
As microgrids become more digitally managed and interconnected, cybersecurity and interoperability are expected to move from auxiliary considerations to core procurement criteria. Certification programs and baseline security expectations introduced for inverter-based devices and distributed energy resources indicate that buyers will increasingly evaluate control systems not only on performance but also on vulnerability management, update pathways, and vendor accountability. This shift creates opportunities for suppliers that can demonstrate robust security architectures, transparent certification status, and compatibility with broader facility management and grid-interconnection requirements. It also raises the stakes for system designers, because fragmented device ecosystems or opaque security practices can become integration liabilities. A key uncertainty is the pace at which standards, testing protocols, and procurement specifications will harmonize across regions and customer segments. Until then, cybersecurity readiness may function as both a competitive advantage and a compliance hurdle, depending on the market and project type.
PW Consulting Information & Electronics Research Center
Financial Structuring and Lifecycle Value Optimization
The financial narrative around microgrids is likely to become more sophisticated as operators weigh upfront capital against long-term resilience and cost predictability. In settings where grid dependency carries operational or budgetary risk, microgrids can support fixed-cost generation profiles and reduce exposure to external supply volatility. This makes lifecycle modeling, performance guarantees, and service agreements increasingly important in project evaluation. Financing approaches such as power purchase structures, resilience-based procurement, and shared infrastructure models may broaden access for organizations that prefer operational expenditure frameworks over traditional capital investment. The opportunity for suppliers and developers will lie in aligning technology choices with financial outcomes, including maintenance costs, degradation profiles, storage replacement cycles, and control system longevity. The risk is that unrealistic expectations around savings or performance could undermine project credibility if real-world operating conditions, regulatory constraints, or load complexities are underestimated. Sustainable adoption will depend on transparent modeling and disciplined interpretation of site-specific economics.
Micro Turbine Market
Strategic Implications for Decision-Makers
For Technology Manufacturers and Solution Providers
- Prioritize integration depth over component-only positioning. Architectures that combine control, storage coordination, renewable integration, and cybersecurity readiness will increasingly shape procurement decisions in critical and commercial environments.
- Build repeatable segment playbooks. Tailored design templates for hospitals, industrial facilities, and commercial campuses can reduce sales cycle friction and improve deployment predictability if they account for approval pathways, load prioritization, and local interconnection requirements.
- Treat security and certification as product attributes. Demonstrated compliance with emerging cybersecurity baselines and interoperability expectations can become a differentiator, especially where buyers must justify resilience investments to internal audit, compliance, or governance stakeholders.
For Investors and Capital Allocators
- Evaluate markets through the lens of deployment complexity, not just addressable demand. Segments with high continuity requirements and manageable approval pathways may offer more reliable project conversion than highly fragmented or regulation-constrained environments.
- Watch for consolidation signals among integrated platform providers and specialized deployers. Scale advantages in control software, service networks, and financing partnerships may drive concentration in some segments, while niche expertise remains valuable in others.
- Underwrite lifecycle economics carefully. Savings potential, resilience value, and operational risk reduction can be meaningful, but returns depend on realistic assumptions around engineering costs, storage and component longevity, and ongoing management requirements.
For Procurement Leaders and Facility Operators
- Map regulatory and stakeholder dependencies early. Single-property deployments can face coordination challenges with internal teams and external authorities, so early alignment across facilities, finance, planning, utilities, and safety stakeholders is essential to avoid timeline delays.
- Define critical load priorities before sizing solutions. The value of a microgrid depends heavily on how well its architecture supports the loads that matter most during an outage, making load analysis and redundancy planning central to project design.
- Include cybersecurity and service continuity in evaluation criteria. Procurement decisions should account for device security baselines, management updates, vendor support models, and the operational implications of islanding and reconnection performance.
The microgrid technology market is expanding within a landscape defined by technical integration, regulatory maturation, and increasingly demanding operational expectations. Growth is being shaped not only by the appeal of distributed generation and storage, but also by the need for resilient, secure, and financially defensible energy architectures. For organizations evaluating entry, expansion, or procurement decisions, the most valuable next step is to move beyond headline market sizing and examine the segmentation, cost structures, regulatory pathways, and competitive dynamics that determine project viability in specific contexts. Detailed segmentation data, company-level positioning assessments, and customized strategic analysis can sharpen these decisions and reduce execution risk. PW Consulting offers comprehensive research supporting deeper evaluation of these dimensions for decision-makers seeking a fuller understanding of where value is being created and how to act on it.
For detailed analysis of this topic, please visit the official page: Microgrid Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


