



Machine Stretch Film Market: Why 5.5% CAGR from 2026 to 2032 Redefines Packaging Strategy

Strategic Trends and Commercial Opportunities in the Machine Stretch Film Market
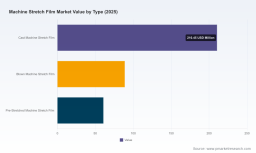
The machine stretch film market has entered a period of structural transformation, moving beyond incremental volume growth to a phase where material science, regulatory pressure, and supply chain resilience redefine competitive advantage. Valued at approximately $360 million in 2025, the market has expanded from roughly $280 million in 2020, reflecting a compound annual growth rate of 5.5 percent through the 2026-2032 forecast horizon. This trajectory is not merely a function of increased pallet wrapping activity; it signals a deeper shift in how logistics operators, manufacturers, and retailers approach load containment, material efficiency, and end-of-life accountability. The market's composition reveals a clear hierarchy in product architecture and application demand, with cast extrusion technologies and logistics-driven use cases commanding the largest revenue shares. Yet the headline figures only scratch the surface. Beneath the growth curve lies a landscape where raw material volatility, extended producer responsibility mandates, and performance differentiation are forcing incumbents and new entrants alike to recalibrate their operating models.
Rebuilding Margins in a Volatile Input Environment
One of the most persistent challenges shaping strategic decision-making is the pricing instability of primary and recycled polyethylene feedstocks. In May 2026, linear low-density polyethylene prices in North America hovered between $1.13 and $1.16 per kilogram, while regional increases of 8.7 to 12.6 percent were reported across Asia and Europe. This input pressure compounds with tighter availability of recycled LLDPE pellets, which traded between 55 and 60 cents per kilogram in 2025 and faced continued upward pressure into 2026 due to supply constraints. For film producers, this environment erodes the traditional cost-pass-through mechanism, particularly in commoditized blown film segments where differentiation is limited. Companies that rely on volume-based pricing without performance or sustainability premiums are seeing margin compression, while those with integrated resin strategies or advanced extrusion capabilities are better positioned to absorb fluctuations without sacrificing competitiveness.
Regulatory Compliance as a Design Constraint, Not an Afterthought
The regulatory landscape has shifted from voluntary sustainability commitments to mandatory material sourcing and reporting requirements. As of August 2025, five U.S. states mandate post-consumer recycled content in plastic packaging, with stretch film falling under flexible packaging targets within extended producer responsibility frameworks. Minnesota's Packaging Waste and Cost Reduction Act, implemented in phases through 2025 and 2026, requires producers to comply with EPR plans that explicitly cover stretch film. Simultaneously, EU and U.S. EPR schemes active in 2026 include mandatory recycled content goals that directly influence production formulations and material procurement. These regulations are no longer peripheral compliance exercises; they are redesigning the economics of film production. Manufacturers must balance recycled content integration with tensile strength, cling, and puncture resistance requirements, while avoiding penalties or market access restrictions in jurisdictions with tightening standards. The operational implication is clear: compliance is becoming a product development parameter, not a post-production adjustment.
Performance Expectations Outpacing Traditional Formulations
A third inflection point lies in the growing disconnect between standardized film specifications and the operational realities of automated wrapping lines. High-throughput distribution centers, robotic palletizers, and precision load containment requirements demand films that maintain stability at high pre-stretch ratios, resist punctures during high-stack storage, and deliver consistent cling without excessive material usage. Traditional blown films often struggle to meet these combined performance thresholds, creating sustained demand for cast and pre-stretched alternatives that offer tighter gauge control, higher elongation, and reduced consumption per pallet. The challenge for producers is to engineer formulations that satisfy these operational demands while navigating recycled content mandates and input cost volatility. Companies that treat performance and sustainability as competing priorities are losing ground to those that integrate both into a single product architecture.
Key Drivers Reshaping Market Dynamics
The market's trajectory is being pulled by four interconnected forces that are redefining how machine stretch films are engineered, sourced, and deployed. Understanding these drivers is essential for executives evaluating capacity investments, procurement strategies, or portfolio positioning.
Advanced Extrusion and Multi-Layer Architecture
Technological progress in nano-layer extrusion and precision gauge control is fundamentally altering the performance ceiling of machine-applied stretch films. Multi-layer coextrusion enables manufacturers to distribute material properties across functional layers, achieving higher stretch ratios and improved load containment without increasing total film weight. Recent product launches demonstrate this shift in action. A major producer commissioned a new 55-layer nano-layer extrusion line in Ohio, delivering machine stretch films with up to 350 percent stretch and approximately 25 percent material reduction. Another specialist introduced pre-stretched film lines incorporating 35 percent post-consumer recycled content while maintaining tensile strength at 22 MPa for machine applications. These developments illustrate a broader industry movement: performance and material efficiency are no longer trade-offs but co-engineered outcomes. For downstream users, this translates into fewer film changes, lower consumption per wrap cycle, and more predictable load stability on automated lines.
Extended Producer Responsibility and Recycled Content Mandates
Policy frameworks are accelerating the integration of recycled polyethylene into machine-grade films, transforming what was once a niche sustainability offering into a compliance-driven baseline. With multiple U.S. states and EU jurisdictions enforcing recycled content targets within EPR schemes, producers are reformulating products to meet minimum thresholds without compromising machine performance. One integrated packaging group launched pre-stretched lines with 35 percent PCR content, while two other major producers introduced stretch film lines featuring 30 percent post-consumer recycled content for high load stability. These milestones reflect a structural shift: recycled content is becoming a spec requirement, not a marketing differentiator. The operational impact extends beyond formulation. Procurement teams must secure consistent recycled resin supply, quality control protocols must adapt to variable feedstock characteristics, and sales teams must articulate performance equivalence to customers transitioning from virgin-only films.
Demand-Side Pressure for Load Containment and Throughput Optimization
End-users are increasingly prioritizing films that reduce waste, minimize changeover downtime, and maintain integrity under high-stack or long-transit conditions. Logistics and distribution operations, which represent the largest application share, are operating with thinner margin buffers and higher throughput expectations, making film consumption a visible cost lever. Food and beverage applications add further complexity, requiring films that balance cling, clarity, and regulatory compliance for perishable or branded goods. Agriculture and industrial packaging sectors demand puncture resistance and weather tolerance, while still seeking material efficiency gains. The common thread across these segments is a preference for films that deliver predictable performance at lower total usage, rather than simply lower price per kilogram. This behavior is reshaping purchasing criteria: total cost per wrapped pallet, line efficiency, and load rejection rates are gaining weight over raw material price alone.
Feedstock Sourcing and Supply Chain Recalibration
The combination of virgin resin price increases and recycled pellet supply constraints is forcing companies to rethink sourcing strategies. Regional price divergence means that producers with geographically diversified resin procurement or localized recycling partnerships can mitigate cost shocks more effectively than those dependent on single-region supply chains. Some manufacturers are integrating recycled polyethylene directly into machine-grade products through new resin blending protocols, while others are investing in closed-loop recovery programs with large logistics customers. The broader implication is that supply chain resilience is becoming a competitive differentiator. Companies that secure predictable access to qualified recycled and virgin feedstocks, while maintaining formulation flexibility, are better equipped to sustain pricing stability and service reliability amid market turbulence.
Worldwide Puncture Resistance Stretch Film Market
Competitive Landscape and Strategic Positioning
The machine stretch film market is characterized by a concentrated core of established producers alongside specialized manufacturers and regional suppliers navigating distinct competitive niches. The top three players collectively account for approximately 55 percent of market revenue, while the top five extend their share to around 70 percent. This concentration reflects the technical barriers to high-performance extrusion, the importance of integrated resin and film production capabilities, and the value of long-term relationships with large logistics and industrial customers. Yet the landscape is not static. Product launches, formulation innovation, and regulatory-driven reformulation are creating pockets of differentiation that allow smaller or regional players to compete on performance specificity rather than sheer scale.
Performance Engineering as the Primary Differentiator
Leading manufacturers are competing on measurable performance attributes rather than generic film availability. One producer emphasizes nano-layer extrusion lines that deliver up to 350 percent stretch with material reduction, targeting automated pallet wrapping operations where film consumption and load stability are critical. Another manufacturer highlights Rite-Gauging technology for consistent pre-stretch and reduced usage, alongside high-cling and high-load containment variants designed for demanding distribution environments. A specialist producer focuses on clarity, stretch performance, and high-strength applications tailored to automated wrapping systems, while a separate player offers series films engineered for pre-stretch levels exceeding 300 percent, high load containment, and puncture resistance. These positioning strategies reflect a shared insight: customers are willing to pay for reliability, reduced consumption, and line compatibility, provided the performance claims are verifiable and consistent.
PLA Biodegradable Stretch Film Market
Sustainability Integration as a Operational Imperative
Sustainability is increasingly embedded into product portfolios rather than marketed as a separate line. Producers are launching films with 30 percent post-consumer recycled content, integrating recycled polyethylene into machine-grade products through new resin protocols, and aligning formulations with EPR and recycled content mandates. One European supplier emphasizes sustainability and performance in its machine-applied stretch films, while a global packaging group positions its machine stretch films within an integrated portfolio focused on performance and cost efficiency. This convergence of sustainability and performance is reshaping competitive dynamics. Companies that treat recycled content integration as a core engineering challenge, supported by consistent feedstock access and robust quality assurance, are building defensible positions. Those that rely on superficial sustainability claims without performance validation risk losing credibility with procurement teams that must meet both cost and compliance targets.
Market Evolution: Consolidation Pressure and Niche Differentiation
The market is experiencing simultaneous forces of consolidation and fragmentation. Scale advantages in resin procurement, extrusion capacity, and distribution networks favor larger producers, particularly in mature regions where automated wrapping infrastructure is widespread. At the same time, regional suppliers and specialists are carving out positions by focusing on specific performance needs, localized service, or regulatory-aligned formulations. New entrants face high technical and compliance barriers, but opportunities exist for companies that can address underserved application requirements, offer verifiable performance improvements, or provide flexible supply arrangements in regions with growing logistics infrastructure. The likely trajectory is a market where a concentrated core sets baseline performance and pricing expectations, while specialized players compete on formulation precision, application-specific engineering, and regional responsiveness.
Forward Outlook: Three Critical Trends for 2026-2032
The next several years will be defined by how quickly producers, investors, and procurement leaders adapt to the intersection of performance demands, regulatory constraints, and input cost dynamics. Three trends are likely to shape strategic outcomes.
Recycled Content as a Baseline, Not a Premium
Mandatory recycled content targets will continue to normalize PCR integration across machine stretch film portfolios. As more jurisdictions enforce minimum thresholds and EPR frameworks tighten, films without qualified recycled content will face procurement disadvantages or market access limitations. This trend creates opportunities for producers with proven formulation stability, consistent recycled resin supply, and transparent compliance documentation. It also introduces risk for companies that overpromise on recycled content without ensuring tensile strength, cling, and puncture resistance remain within specification. The commercial opportunity lies in offering films that meet or exceed regulatory requirements while delivering measurable performance parity or improvement, thereby converting compliance from a cost center into a competitive asset.
PW Consulting
Material Efficiency and Automated Line Optimization
The push toward higher stretch ratios, tighter gauge control, and reduced consumption per pallet will intensify as distribution centers seek to lower total wrapping costs and improve line throughput. Films that enable consistent pre-stretch, minimize changeover variability, and maintain load stability under automated operation will see sustained demand. Producers investing in multi-layer extrusion, precision dispensing compatibility, and application-specific formulations are well positioned to capture this shift. The risk lies in over-engineering films for narrow use cases without ensuring broad compatibility across wrapping equipment and load types. Success will depend on balancing performance specificity with practical deployability across diverse operational environments.
Regional Divergence in Regulatory and Supply Dynamics
Regulatory mandates, recycled resin availability, and virgin resin pricing will continue to diverge across regions, creating uneven competitive conditions. North America and Europe are likely to see faster adoption of EPR-aligned formulations and recycled content integration, while Asia Pacific and emerging markets may experience more gradual regulatory rollout but stronger volume growth driven by expanding logistics infrastructure. LLDPE price increases of 8.7 to 12.6 percent in Asia and Europe, alongside North American price levels around $1.13 to $1.16 per kilogram, illustrate the regional cost landscape that producers must navigate. Companies with flexible sourcing strategies, localized production, or regionally tailored product lines will be better equipped to manage these divergences. The uncertainty centers on the pace and uniformity of regulatory enforcement, the stability of recycled resin supply, and the potential for trade or tariff shifts that could disrupt feedstock flows.
Strategic Actions for Decision Makers
Translating these trends into actionable strategy requires different priorities depending on a company's role in the value chain. The following recommendations highlight where focused effort can yield the strongest returns.
For film manufacturers and producers: Prioritize formulation engineering that treats recycled content and performance as integrated design parameters. Invest in extrusion capabilities that enable higher stretch ratios, consistent gauge control, and material reduction without sacrificing load containment or puncture resistance. Secure diversified resin sourcing to mitigate regional price volatility, and develop transparent compliance documentation that supports procurement teams navigating EPR and recycled content mandates. Differentiate through verifiable performance claims and application-specific solutions rather than volume-based pricing alone.
For investors and portfolio strategists: Evaluate exposure to producers with demonstrated capabilities in advanced extrusion, recycled content integration, and regional supply resilience. Favor companies that can articulate clear performance advantages, maintain formulation flexibility amid input cost fluctuations, and align product portfolios with regulatory trajectories. Monitor consolidation dynamics and niche differentiation opportunities, particularly in regions where logistics infrastructure is expanding and automated wrapping adoption is accelerating. Assess risk around recycled resin supply constraints, virgin resin price divergence, and regulatory enforcement variability.
For procurement leaders and logistics operators: Shift evaluation criteria from price per kilogram to total cost per wrapped pallet, incorporating film consumption, line efficiency, load rejection rates, and compliance readiness. Prioritize suppliers that provide consistent performance at high pre-stretch levels, maintain quality across recycled and virgin blends, and offer documentation that supports EPR and recycled content reporting. Engage early with formulation changes to ensure compatibility with existing wrapping equipment and load profiles, and consider supplier partnerships that provide feedstock transparency and supply stability amid market volatility.
The machine stretch film market is moving into a phase where technical precision, regulatory alignment, and supply chain resilience determine competitive outcomes. The companies that succeed will be those that treat performance, sustainability, and cost efficiency as interconnected objectives rather than competing priorities. For executives seeking granular segmentation data, regional pricing dynamics, competitor benchmarking, and customized strategic scenarios, the full research report provides the detailed framework needed to translate these market-wide insights into precise operational and investment decisions.
For detailed analysis of this topic, please visit the official page: Machine Stretch Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


