



Smartphone Power Management ICs Market: Beyond the 5.5% CAGR Story

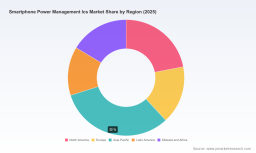
The Strategic Shift in Smartphone Power Management ICs: Navigating Growth, Complexity, and Competitive Realignment
The smartphone power management IC (PMIC) market has entered a phase of steady, structurally driven expansion. Total revenue across the sector reached approximately 185.0 million in 2025, building on a consistent climb from 140.0 million in 2020. Over the 2026–2032 forecast horizon, the market is projected to grow at a compound annual growth rate of 5.5 percent, reaching 267.0 million by 2032. This trajectory reflects more than incremental handset volume growth. It signals a fundamental reallocation of value within mobile power architectures, where efficiency, integration, and thermal-aware design are quietly reshaping procurement priorities, product roadmaps, and competitive positioning.
Market Context and Structural Challenges
The revenue curve over the past five years shows a market that has absorbed supply chain volatility, component shortages, and shifting OEM priorities without losing momentum. Growth has been broad-based, but not uniform. The underlying dynamics point to a sector that is consolidating technical requirements while fragmenting competitive approaches. Several structural challenges define the current inflection point.
First, power density and thermal constraints are tightening faster than conventional discrete approaches can accommodate. As smartphone processors, display panels, and RF subsystems draw higher peak currents and operate across wider voltage ranges, PMICs must deliver more precise sequencing, faster transient response, and lower quiescent loss. The burden on system designers is rising, and the margin for error in battery life and thermal performance is shrinking.
Second, the competitive base is broad and increasingly layered. Market concentration remains moderate, with the top three participants holding roughly 22.5 percent of revenue and the top five reaching about 28.5 percent. This distribution indicates a market that is not dominated by a single architecture or vendor, but instead shaped by multiple design houses, foundry relationships, and region-specific OEM requirements. The result is a landscape where differentiation depends less on scale alone and more on the ability to integrate power management with application processors, charging protocols, and system-level firmware.
Third, procurement cycles and platform lifecycles are creating timing friction. Handset OEMs are extending platform validation windows, demanding longer availability commitments, and tightening qualification procedures for power components that sit close to the battery and core rails. Suppliers that cannot guarantee continuity, documentation consistency, and design-in support risk losing position even when their technical specifications are competitive.
Core Drivers Reshaping the Market
Several interlinked forces are accelerating change in smartphone power management. Understanding these drivers is essential for anyone making sourcing, investment, or product planning decisions.
Technology innovation is moving from incremental efficiency gains to architectural integration. Multi-channel PMICs, battery management blocks, and voltage regulation stages are increasingly combined into fewer packages with more programmable control. This integration reduces board space, simplifies power sequencing, and allows OEMs to tailor rail behavior to specific workload profiles. At the same time, fast-charge support, power-path management, and adaptive voltage delivery are becoming baseline expectations rather than premium features. The practical effect is that PMIC selection now influences not only battery endurance, but also user perception of charging speed, thermal comfort, and device reliability.
Power Management IC (PMIC) Market
Policy and regulatory pressure is reinforcing the efficiency trajectory. Energy consumption standards, battery safety expectations, and e-waste considerations are pushing manufacturers toward designs that minimize loss, extend usable battery life, and simplify end-of-life handling. While regulations vary by region, the directional signal is consistent: mobile devices must do more with less energy, and power management is a primary lever for compliance. This environment rewards suppliers that can provide documented efficiency curves, predictable thermal behavior, and evidence of robust fault protection.
Demand-side behavior is also changing the value equation. Consumers expect devices that hold charge longer under mixed usage, recharge quickly without excessive heat, and maintain consistent performance across battery states. Enterprise and premium consumer segments add further requirements, including longer product support windows, tighter supply continuity, and more transparent component provenance. These expectations increase the stakes for PMIC designers, because power management is increasingly visible to end users through charging behavior, thermal performance, and charge-cycle longevity.
Supply chain and cost structure dynamics continue to shape sourcing strategies. Component availability, packaging constraints, and the cost of qualifying alternative parts have made resilience a first-order concern. OEMs and contract manufacturers are diversifying supplier bases where possible, while also seeking partners that can provide stable lead times, clear revision control, and design flexibility. In this environment, cost competitiveness is still important, but it is increasingly weighed against risk mitigation, technical support, and the ability to sustain designs through multiple product generations.
Competitive Landscape and Strategic Positioning
The market features a diverse set of participants, each pursuing a distinct path to relevance. The strategic differences among them reveal where value is being created and how the competitive map is evolving.
Texas Instruments maintains a broad portfolio spanning multi-output PMICs for smartphone battery charging, voltage regulation, and power sequencing. Its positioning rests on depth of reference design, long-standing mobile phone PMIC heritage, and continued development of modern battery management solutions. For system architects, this breadth translates into optionality across charging topologies and rail configurations, supported by a documentation and design-in ecosystem that reduces integration risk.
Analog Devices emphasizes fast-charge support and power-path management, with PMICs integrated alongside battery chargers and low-dropout regulators in mobile platforms. Its differentiation lies in precision power delivery and a focus on charge behavior that aligns with user experience expectations. This approach appeals to designs where charge timing, battery health, and stable operation across load transients are prioritized.
NXP Semiconductors offers configurable power sequencing and fault protection optimized for smartphone CPUs, GPUs, and memory rails. Its value proposition centers on flexibility and protection in handheld environments, where rail ordering and fault handling can materially affect system stability. This makes NXP relevant for platforms that require tailored sequencing across heterogeneous processing blocks.
Renesas Electronics, including its Dialog Semiconductor capabilities, supplies multi-channel PMICs and sub-PMICs for smartphones, tablets, and RF modules, with advanced buck-boost and power distribution solutions. The strategic emphasis is on distribution efficiency and multi-rail control, which supports complex handheld architectures that must balance performance, leakage, and thermal headroom.
ON Semiconductor focuses on efficiency and integration in mobile power management for consumer electronics. Its approach targets loss reduction and functional consolidation, which matters in designs where board area and energy waste are tightly constrained. Richtek Technology contributes PMICs for portable and handheld devices, including buck-boost converters and battery charge controllers, with a practical focus on charging control and conversion efficiency in smartphone applications.
ROHM Semiconductor provides linear and switching regulators along with power management switch ICs tailored for mobile phones and displays. Its portfolio supports designs that need a mix of regulation styles and switching elements, particularly where display and handset rail requirements intersect. Skyworks Solutions is associated with PMICs in next-generation smartphones, including wireless networking and power delivery solutions, positioning power management closer to connectivity and RF subsystem needs.
Qualcomm Technologies integrates Snapdragon SoCs with Power Managers for optimized power delivery, fast charging, and efficiency. Its advantage comes from tight coupling between application processors and power management, enabling coordinated behavior across compute, charging, and delivery paths. MediaTek develops PMICs for smartphones and IoT, including multi-buck and LDO-based power distribution and charging solutions, with a focus on scalable integration across broad handheld and connected device portfolios.
These profiles illustrate a market where differentiation is multidimensional. Some players compete on integration breadth and reference design maturity. Others compete on precision charging, sequencing flexibility, or processor-coupled optimization. The practical implication for decision makers is that PMIC selection is no longer a single-specification purchase. It is a platform decision that affects charging experience, thermal behavior, validation effort, and long-term design continuity.
The competitive structure is evolving along three directions. Consolidation is occurring where suppliers can bundle power management with adjacent functions and reduce total integration cost. Differentiation is intensifying where charging speed, efficiency, and protection features become decisive in premium segments. New entry and regional specialization remain possible where local support, cost structures, and design-in relationships create niches that broader portfolios do not fully address. The moderate concentration levels suggest that the market will remain competitive, but that coordinated advantages in integration, support, and platform alignment will increasingly separate leaders from followers.
Forward Trends and Commercial Implications
Looking ahead across the 2026–2032 period, three trends are likely to shape commercial outcomes.
Integrated, programmable power architectures will become more central to smartphone design. As rail counts, workload variability, and charging expectations increase, PMICs that offer configurable sequencing, adaptive regulation, and tighter coordination with processors and charging protocols will gain preference. The commercial opportunity lies in reducing validation complexity, improving thermal performance, and enabling faster design cycles for OEMs that need to support multiple handset variants from a common power architecture. Suppliers and partner ecosystems that can provide flexible configuration options, clear firmware or control interfaces, and predictable behavior across operating conditions will be better positioned to capture design wins.
Efficiency and thermal-aware design will move from optimization goals to qualification gates. With battery life, charging comfort, and regulatory expectations all trending upward, PMICs that minimize loss, manage transients cleanly, and support stable operation under fast-charge conditions will become harder to substitute. This creates opportunity for vendors that can document efficiency across load profiles, provide robust protection features, and help OEMs meet both performance and compliance targets. The risk is that efficiency claims become commoditized unless supported by measurable system-level outcomes and reproducible validation data.
Supply resilience and lifecycle continuity will increasingly influence sourcing decisions. As platform cycles lengthen and qualification costs rise, procurement teams will favor suppliers that can demonstrate stable availability, disciplined revision control, and the ability to support designs over multiple generations. The commercial implication is that relationship depth, technical support, and continuity planning may become as important as unit pricing. This trend also raises the bar for smaller or less established participants, while rewarding suppliers that can commit to long-lived design support and transparent change management.
Worldwide Consumer Electronics Power Management IC Market
These trends are not guaranteed to unfold uniformly. Risks include component pricing volatility, shifting OEM platform strategies, and the possibility that integration advantages concentrate value among a smaller set of platform-aligned suppliers. There is also uncertainty around how quickly charging protocols, battery technologies, and regulatory expectations will evolve, which could alter the relative importance of specific PMIC features. Decision makers should therefore treat power management strategy as a living assessment rather than a fixed specification exercise.
PW Consulting
Actions for Executives, Investors, and Procurement Teams
For handset and component manufacturers, the priority is to align power management choices with platform strategy rather than treat PMICs as interchangeable commodities. That means evaluating integration depth, sequencing flexibility, fast-charge behavior, and supplier support alongside unit cost. Designs that can reuse a common PMIC architecture across multiple models, while retaining enough programmability to tune rail behavior, will typically reduce validation burden and improve lifecycle economics. Manufacturers should also weigh the value of tighter coordination between processor platforms and power delivery, especially where charging experience and thermal performance are differentiators.
For investors, the relevant question is where value is likely to accrue as integration and efficiency requirements intensify. Companies that can combine multi-channel control, battery management, and regulation in cohesive solutions, while maintaining strong design-in support and stable product lifecycles, are better placed to defend positioning in a moderately concentrated market. Attention should also be paid to suppliers whose roadmaps align with fast-charge adoption, thermal-aware design, and platform-level integration, since these are the areas where commercial differentiation is most likely to widen. Portfolio exposure should be assessed with an eye on continuity risk, qualification lead times, and the ability to sustain designs through multiple product generations.
For procurement and sourcing leaders, the practical focus should be on resilience and traceability without sacrificing technical fit. Qualifying multiple sources where feasible, verifying revision-control discipline, and requiring clear documentation for configuration and protection features can reduce downstream risk. Procurement teams should also evaluate supplier capacity to support long-lived platforms, because the cost of re-qualification and design changes often outweighs narrow unit-price advantages. In parallel, sourcing strategies should reflect the growing importance of charging behavior and thermal performance in end-user satisfaction, since these attributes are increasingly tied to PMIC selection.
Across these roles, the common theme is that smartphone power management is becoming more strategic, less commodity-like, and more tightly linked to platform outcomes. The market’s growth trajectory is steady, but the real value is shifting toward architectures and suppliers that can reduce integration risk, improve efficiency and charging behavior, and sustain designs through changing requirements. Detailed segmentation data, region- and type-level revenue splits, application breakdowns, and supplier-level assessments can sharpen these decisions significantly. For teams that need granular sizing, competitive mapping, and tailored sourcing or investment implications, the full research report provides the deeper quantitative and strategic detail needed to move from market-level direction to actionable plans.
For detailed analysis of this topic, please visit the official page: Smartphone Power Management Ics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


