



Kiosk Market 2026: Why 15.6% CAGR and Asia Pacific Expansion Change Everything

The Kiosk Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
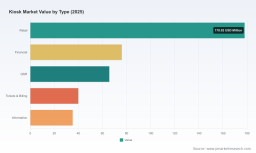
The global kiosk market has evolved from a niche self-service experiment into a foundational layer of modern retail, financial services, hospitality, and public sector infrastructure. With a base-year market valuation of approximately USD 394.9 million in 2025 and a projected trajectory to USD 1,089.4 million by 2032, the sector is expanding at a compound annual growth rate of 15.6% across the 2026–2032 forecast window. Historical momentum reinforces this trajectory: the market moved from USD 191.3 million in 2020 to USD 343.89 million in 2024, reflecting a structural shift rather than a cyclical spike. This growth is not merely a function of unit proliferation. It represents a broader realignment in how organizations design customer touchpoints, manage labor allocation, and deploy connected hardware at scale. Understanding where the market stands today, what is driving its acceleration, and how incumbents are positioning themselves is essential for executives navigating procurement decisions, capital allocation, and product roadmap planning.
Despite the optimistic trajectory, the kiosk sector is confronting a set of structural tensions that will define competitive outcomes over the next several years. First, hardware reliability and total cost of ownership have emerged as critical pressure points. Deployments are increasingly expected to operate continuously in high-traffic environments, yet component cost volatility and supply chain friction are compressing margins for manufacturers and raising the bar for operational durability. Second, the regulatory and standards landscape is tightening around payment security, accessibility, and network modernization, forcing vendors to align hardware architecture with compliance requirements that vary across jurisdictions. Third, the market is experiencing a strategic fork in the road between standardized, high-volume deployments and highly customized, vertical-specific solutions. Companies that attempt to serve both models without clear architectural boundaries risk dilution, while those that commit to a distinct value proposition are capturing defensible share. These dynamics are not temporary headwinds; they are reshaping the basis of competition.
Key Drivers Reshaping the Kiosk Market
Technology Innovation and Hardware-Software Convergence
The most consequential driver of market expansion is the convergence of hardened hardware, embedded computing, and intelligent software layers. Kiosk deployments are no longer standalone terminals; they are becoming managed nodes within broader digital ecosystems. Recent product activity illustrates this shift clearly. In February 2026, KIOSK Information Systems launched ergonomic Windfall Series kiosks built with AOPEN hardened processing units, a move explicitly aimed at addressing reliability concerns in digital front-door deployments. That same company expanded its software ecosystem in March 2026 through a partnership with OpenTech Alliance to deploy INSOMNIAC self-storage software on the Windfall Series, signaling a broader trend toward bundling purpose-built applications with durable hardware platforms. The implication for the market is straightforward: competitive advantage is increasingly determined by how seamlessly hardware, operating software, and vertical applications integrate, rather than by hardware specifications alone.
Beyond core hardware, digital payment architecture is reshaping the design constraints of kiosk systems. PCI PIN on Glass rules now apply to kiosk hardware supporting contactless payments, requiring manufacturers to embed secure cryptographic handling directly into the display and input chain. This regulatory-technical intersection is pushing vendors to rethink bill-of-materials architecture, certification cycles, and long-term software support. Companies that treat compliance as an afterthought face retrofit costs and deployment delays, while those that design for secure payment workflows from the outset are shortening time-to-market and reducing integration risk for end customers.
Self-service Kiosk Market
Policy, Regulatory, and Infrastructure Dynamics
Regulatory and infrastructure developments are simultaneously easing some constraints while introducing new cost structures. On the connectivity side, the FCC’s March 5, 2026 Report and Order reduced regulatory burdens on network modernization for broadband infrastructure, a change that supports more reliable back-end connectivity for distributed kiosk fleets. Improved connectivity lowers the operational risk of cloud-managed kiosks and remote monitoring, which in turn makes large-scale deployments more viable for retail, hospitality, and public-sector operators. This is a meaningful enabler, particularly for organizations that depend on centralized fleet management and real-time software updates.
At the same time, hardware cost pressures are intensifying. Semiconductor tariffs on components raised build and operating costs for kiosk hardware in 2026, squeezing manufacturers that rely on imported processing units, displays, and peripheral controllers. Compounding this, regional infrastructure policies are reshaping the broader technology cost environment. In Alberta, a new policy effective December 31, 2026 requires data centers drawing 75 MW or higher to pay a 2% levy on computer hardware, and states advanced grid infrastructure accountability policies in 2026 are requiring data centers to offset upgrade costs. While these measures target large-scale data infrastructure, they reflect a broader policy environment in which compute and hardware expenditures are increasingly scrutinized. For kiosk vendors and enterprise buyers alike, this environment reinforces the importance of total-cost modeling, energy efficiency, and lifecycle planning rather than focusing solely on upfront unit pricing.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, the kiosk market is being pulled forward by two reinforcing behavioral shifts. Consumers and business customers increasingly expect fast, consistent, and contactless self-service options, particularly in QSR, retail, and financial services environments where queue reduction and transaction speed directly influence satisfaction and throughput. Enterprises, meanwhile, are reevaluating labor deployment models. Self-service kiosks are no longer viewed simply as cost-reduction tools; they are increasingly positioned as service-quality multipliers that free skilled staff for higher-value interactions while standardizing routine transactions. This reframing broadens the addressable use cases and supports adoption beyond traditional high-volume settings.
Accessibility is another demand-side force that is moving from compliance checkbox to competitive differentiator. In August 2025, LG Electronics USA unveiled Gen 2 accessible self-ordering kiosks developed with a Tech for All consultant, designed for users with vision, mobility, and hearing disabilities. This product direction signals a broader market expectation: inclusive design is becoming a baseline requirement rather than a niche feature. Organizations deploying kiosks in public-facing roles are increasingly evaluated on how well their self-service infrastructure serves a full spectrum of users, and vendors that embed accessibility into hardware ergonomics, software navigation, and payment workflows are gaining an advantage in regulated and high-visibility environments.
Supply Chain and Cost Structure Evolution
The cost structure of kiosk manufacturing and deployment is undergoing a measurable transition. Component tariffs, processing unit availability, and durable enclosure requirements are pushing manufacturers to reconsider sourcing strategies, standardization levels, and build-vs-integrate decisions. At the same time, the rise of hosted and software-driven add-ons is changing how value is captured across the stack. In November 2025, Datacap Systems launched a Virtual Gift Card program as a hosted digital gift card add-on for kiosk deployments, an example of how software services can layer onto hardware platforms to create recurring revenue and enhance the end-user experience without requiring a full hardware redesign. This hybrid model—durable hardware combined with modular software services—offers a path to offset hardware margin pressure while improving customer stickiness. For manufacturers, the strategic question is whether to build these software capabilities internally, partner for them, or integrate third-party hosted services into a managed offering.
Competitive Landscape and Leading Strategies
The kiosk market is characterized by a mix of specialized hardware manufacturers, vertically focused solution providers, and broader technology companies extending into self-service deployments. Market concentration reflects a moderately consolidated environment, with the top three players holding roughly 60% of market share and the top five approaching 65%. This concentration suggests that scale, brand trust, and deployment ecosystems matter, but it also leaves meaningful room for specialized players that serve distinct verticals or accessibility needs. The competitive dynamics are best understood by examining how leading companies differentiate rather than by treating the market as a single commodity battleground.
NIOSK Information Systems exemplifies a deployment-oriented strategy centered on design, manufacturing, monitoring, and support across retail, self-storage, healthcare, government, and hospitality. Its February 2026 Windfall Series launch and March 2026 OpenTech Alliance partnership reflect a clear emphasis on reliability and application-specific integration, particularly in self-storage and digital front-door use cases. This approach positions the company as an end-to-end partner for organizations that want a single point of accountability for hardware durability and software ecosystem compatibility. Elo Touch Solutions, by contrast, anchors its offering in self-service kiosks and touchscreens for retail, QSR, and healthcare, leaning on display and interface expertise that matters in high-interaction environments. Its competitive leverage lies in touch fidelity, ergonomic design, and application familiarity across sectors where user interaction quality directly affects throughput and satisfaction.
LG Electronics USA has carved out a distinctive position around accessibility with its Gen 2 self-ordering kiosks designed for vision, mobility, and hearing disabilities. This is not merely a product feature but a strategic positioning that aligns with regulatory expectations and inclusive service mandates. Diebold Nixdorf brings a different angle, providing intelligent kiosks for banking, retail, and the public sector with IoT and cloud management capabilities. Its strength is in managed infrastructure thinking: kiosks as connected, monitorable assets within a broader fleet, which appeals to organizations that prioritize remote oversight, predictive maintenance, and integration with existing enterprise systems. NCR Corporation complements this landscape with AI-powered self-service and contactless kiosks for retail and hospitality, leaning into intelligent transaction handling and contactless experience design. Together, these players illustrate a market where differentiation is increasingly defined by the combination of hardware durability, software intelligence, accessibility, and fleet management maturity.
The broader field further highlights the fragmentation of specialized use cases. Companies such as Redyref, Olea Kiosks, MetroClick, Advanced Kiosks, Pyramid Computer, Acrelec, Coates Group, Meridian, ZIVELO, Embross, Neumo, AOPEN, Posiflex, and HiStone each emphasize distinct value propositions, from interactive digital building directories and ADA-compliant self-service units to hardened processing units, Android-based kiosk computers, and QSR-focused self-ordering hardware. Acrelec’s position as a large global hardware and software supplier for self-ordering in QSR and retail underscores how vertical specialization can scale internationally, while Neumo’s focus on DMV and government self-service kiosks shows how public-sector requirements create durable, regulation-driven demand. HiStone’s expansion from a primarily domestic Chinese market into international channels points to the growing cross-border flow of kiosk hardware and the increasing relevance of cost-competitive manufacturing in the global supply picture.
The competitive evolution is moving along three observable paths. First, there is consolidation pressure among suppliers that can offer integrated hardware, software, and managed services at scale, particularly in retail, QSR, and banking. Second, there is continued differentiation among niche leaders serving accessibility, public-sector, and bespoke environments where customization and compliance outweigh volume economics. Third, new entrants and adjacent technology providers are exploring the space through modular computing, Android-based platforms, and hosted software add-ons, lowering barriers for organizations that want to assemble solutions rather than buy fully integrated units. The likely outcome is a layered market: a concentrated core of scaled providers competing on reliability, fleet management, and vertical breadth, surrounded by specialized manufacturers and software partners competing on accessibility, custom design, and application-specific functionality.
Kiosk Printer Market
Future Trends and Commercial Opportunities (2026–2032)
Trend 1: Managed, Cloud-Integrated Kiosk Fleets Become the Default Expectation
As deployments scale, the operational model is shifting from standalone installation to managed fleet infrastructure. Cloud-managed monitoring, remote updates, and IoT-enabled diagnostics are becoming baseline expectations rather than premium features. The practical effect is that buyers will increasingly evaluate kiosk investments through the lens of uptime, maintenance cost, and software lifecycle support, not just unit price. For manufacturers, this creates an opportunity to build managed service layers that improve stickiness and reduce support fragmentation. For enterprise buyers, it opens the door to predictable operating models and faster issue resolution across distributed locations. The risk is that vendors without robust backend management capabilities will face growing pressure as customers compare total operational performance rather than hardware specs at purchase time.
PW Consulting Information & Electronics Research Center
Trend 2: Accessibility and Inclusive Design Move from Compliance to Brand Value
Accessibility will increasingly function as both a regulatory requirement and a commercial differentiator. Product activity such as LG’s Gen 2 accessible self-ordering kiosks indicates where the market is heading: inclusive ergonomics, multimodal interaction, and payment workflows designed for a broader range of users. As public-facing deployments expand in retail, hospitality, transportation, and government settings, organizations that treat accessibility as a design standard rather than a retrofit will reduce compliance exposure and improve user experience quality. The commercial opportunity lies in developing modular accessibility features that can be integrated across product lines without fragmenting manufacturing scale. The uncertainty is in how quickly standards and customer expectations will converge across regions, which could create uneven compliance timelines and redesign pressure for vendors with global footprints.
Trend 3: Software-Layered Revenue Models Offset Hardware Cost Pressure
With semiconductor tariffs and broader hardware cost pressures reshaping build economics, the market is likely to see more hosted software add-ons, digital payment enhancements, and application-specific services layered onto kiosk platforms. Datacap’s hosted digital gift card add-on is a useful signal of this direction: value is increasingly created through software services that enhance the transaction experience and create recurring engagement without requiring a full hardware redesign. Over the next several years, this trend should encourage more partnerships between hardware manufacturers and software providers, as well as more packaged solutions that combine durable hardware with modular services. The strategic opportunity is to design hardware platforms that can accommodate third-party software integration cleanly, reducing customization cost while enabling faster feature deployment. The risk is fragmentation if integration standards remain inconsistent, which could raise implementation complexity and slow adoption in larger enterprise environments.
Strategic Recommendations for Decision Makers
For Kiosk Manufacturers and Solution Providers
Prioritize architectural clarity between standardized high-volume platforms and customized vertical solutions. The pressure on hardware costs and the rising importance of fleet management make it risky to blur the line between mass-deployable units and bespoke builds. Companies should define a core hardware roadmap that supports modular software integration, accessibility features, and secure payment workflows, then selectively layer vertical applications through partnerships or hosted services. Product activity such as the Windfall Series launch and the INSOMNIAC software partnership demonstrates the value of pairing durable hardware with a focused software ecosystem, and that model is likely to become more relevant as buyers compare total cost of ownership across multi-year deployments.
Equally important is designing for compliance and lifecycle support from the outset. PCI PIN on Glass requirements, accessibility expectations, and connectivity modernization all influence hardware and software choices. Manufacturers that internalize these constraints early can reduce retrofit risk, shorten certification cycles, and present a more dependable value proposition to enterprise buyers managing large, distributed fleets.
For Investors Evaluating the Kiosk Sector
Assess companies based on their ability to manage the hardware-software-service balance rather than on unit volume alone. The most durable growth stories are likely to come from players that can combine reliable hardware platforms with recurring software or managed-service elements, because that mix improves resilience against component cost volatility and creates stronger customer retention. Vertical specialization also deserves attention: accessibility-focused designs, government and public-sector deployments, and QSR self-ordering solutions each have distinct demand drivers and compliance profiles that can support steadier demand than undifferentiated self-service hardware. Investors should also monitor supply-side risk, particularly around component tariffs and regional hardware levies, since these factors can affect build costs, margin structure, and the timing of price adjustments across the value chain.
For Enterprise Buyers and Procurement Teams
Evaluate kiosk investments as multi-year operational commitments, not one-time hardware purchases. The relevant metrics should include uptime performance, remote management capability, accessibility compliance, secure payment architecture, and the supplier’s ability to support software updates and application integration over time. Buying decisions should weigh the trade-off between standardized platforms, which typically offer better scale economics and simpler support, and custom solutions, which may better fit specialized environments but can increase maintenance complexity and lifecycle cost. Procurement teams should also clarify which software services will be hosted, which will be managed internally, and how payment and accessibility requirements will be maintained as standards evolve.
Given the pace of change in hardware cost structures, regulatory expectations, and software-enabled feature sets, detailed segmentation data and customized deployment guidance can materially improve planning accuracy. PW Consulting’s complete research report provides deeper breakdowns across regions, application segments, and solution types, along with tailored recommendations for procurement strategy, vendor evaluation, and investment prioritization. For decision makers looking to translate these market-level trends into specific procurement choices or capital allocation plans, the full report offers the granular intelligence needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Kiosk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


