



Marine Audio System Market: How 5.8% CAGR and OEM Demand Shaped 2026 Growth

Navigating the Marine Audio System Market: Strategic Trends and Commercial Opportunities
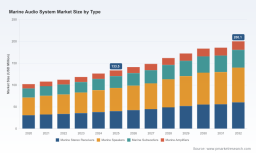
The marine audio system market has evolved from a niche accessory category into a strategically significant segment of the broader recreational and commercial marine electronics ecosystem. Driven by rising boat ownership, increasing expectations for premium onboard experiences, and rapid innovation in weather-resistant audio engineering, the sector has demonstrated consistent expansion over the past five years. With total market revenue climbing from approximately $102.15 million in 2020 to $133.5 million in 2025, and a projected trajectory toward $200.1 million by 2032, the industry is posting a compound annual growth rate of 5.8%. This growth is not merely a reflection of steady consumer spending; it signals a structural shift in how marine vessels are designed, equipped, and experienced.
For executives, investors, and procurement leaders, the market presents a compelling but complex landscape. Growth has been broad-based across component types, with marine speakers commanding the largest share of revenue, followed by stereo receivers, subwoofers, and amplifiers. End-use dynamics are heavily weighted toward original equipment manufacturer (OEM) partnerships, though aftermarket demand remains a meaningful secondary channel. Geographically, the market is distributed across mature and emerging regions, with Asia Pacific, North America, and Europe each representing substantial revenue pools, while Latin America and the Middle East and Africa contribute smaller but growing segments. Despite the optimistic trajectory, the market remains moderately fragmented, with the top three firms accounting for roughly 25.4% of revenue and the top five reaching approximately 35.6%. This concentration level suggests room for both consolidation and disruptive positioning, depending on product architecture, channel strategy, and integration capabilities.
Core Challenges and Inflection Points
The marine audio sector operates at the intersection of harsh environmental demands, stringent quality expectations, and rapidly shifting consumer preferences. Three structural challenges are shaping the competitive landscape and creating decisive inflection points for firms that can respond with agility.
-
Environmental durability versus cost optimization: Marine-grade audio components must withstand prolonged exposure to salt spray, ultraviolet radiation, humidity, and vibration. This requires specialized enclosure materials, UV-stable polymers, corrosion-resistant terminals, and robust sealing architectures. As boat builders and consumers increasingly expect premium acoustic performance alongside durability, suppliers face mounting pressure to balance material and manufacturing costs without compromising reliability. Custom rotomolding and injection-molded polymer processes, along with marine-certified quality control protocols, elevate production complexity and limit the ease of low-cost commoditization.
-
Integration complexity and interoperability standards: Modern marine vessels are becoming tightly networked environments where audio systems must communicate with chartplotters, navigation displays, engine telemetry, and onboard entertainment hubs. Compatibility with established marine networking protocols has become a baseline expectation rather than a differentiator. Products that cannot seamlessly interface with broader vessel electronics risk exclusion from premium OEM platforms and aftermarket installer preferences. This creates a technical barrier that rewards firms with modular architectures, proven integration pathways, and active participation in marine electronics ecosystems.
-
Channel fragmentation and brand differentiation: The market serves both high-end custom installations and volume-driven consumer segments, each with distinct pricing, service, and performance expectations. Aftermarket demand introduces variability in installer skills, regional distribution networks, and brand visibility, while OEM relationships require long lead times, certification rigor, and scalable production consistency. Firms that rely solely on price competition or generic consumer-audio adaptations often struggle to maintain margins, whereas those that cultivate clearly defined performance positioning and marine-specific engineering narratives tend to secure more resilient demand.
Key Drivers of Market Evolution
Technological Innovation and Performance Breakthroughs
Audio technology tailored for marine environments has advanced beyond basic weatherproofing. Digital signal processing, networked audio architectures, and real-time speaker modeling are enabling higher-fidelity reproduction in spaces where acoustic challenges—such as engine noise, wind, and uneven cabin geometry—have historically limited performance. Recent product launches highlight this trajectory. At a major marine industry event in October 2025, Hertz Marine unveiled a DSP amplifier featuring A2B digital audio networking and real-time loudspeaker modeling, signaling a move toward smarter, more adaptive sound tuning for demanding onboard conditions. Alongside this, the introduction of new marine speaker and subwoofer lines underscored the industry's push to combine precise acoustic engineering with reinforced marine-grade construction.
Beyond amplification and tuning, the integration of directional audio concepts into production boat platforms illustrates how technology is reshaping product expectations. For the 2026 model year, certain boat manufacturers introduced built-in directional audio systems across their fleets, moving marine audio from retrofitted add-ons toward designed-in experiences. This shift is significant because it embeds audio performance into vessel value propositions at the point of sale, elevating the strategic importance of audio suppliers in early-stage boat design and procurement.
Policy, Regulation, and Quality Assurance Dynamics
Regulatory frameworks and certification expectations do not dominate marine audio as they might in automotive or aerospace, but quality and durability standards exert meaningful influence on product development, supplier selection, and market access. Marine audio products are increasingly expected to adhere to ISO 9001:2015 quality management practices to demonstrate consistent durability certification for marine conditions. While this may appear to be a procedural detail, it has real commercial implications: certification readiness affects OEM approval cycles, installer confidence, and the credibility of warranty and service promises.
At the same time, interoperability requirements are shaping product roadmaps. NMEA 2000 network compatibility has become a practical necessity for integrating marine audio with chartplotters and other vessel electronics. This is not merely a technical footnote; it defines which products can be specified into integrated systems and which must compete as standalone substitutes. Suppliers that build NMEA 2000 alignment into their product architecture from the outset gain smoother pathways into OEM platforms and professional installation channels, while those that treat compatibility as an afterthought face higher integration friction and narrower addressable demand.
Demand-Side Shifts in Consumer and Commercial Behavior
Consumer expectations in the marine sector increasingly mirror those in automotive and premium consumer electronics: seamless usability, high audio quality, and integration with broader digital experiences. Boat owners and operators are no longer content with basic background sound; they seek immersive, zone-capable audio that performs reliably across different vessel zones, from open decks to enclosed cabins. This demand is reinforced by the proliferation of leisure boating, the growing popularity of customized vessel builds, and the willingness of enthusiasts to invest in upgrades that enhance both recreation and perceived vessel value.
On the commercial side, boat builders are under pressure to differentiate models in a competitive manufacturing environment. Integrated audio has become part of that differentiation strategy, especially in mid-to-high-tier recreational vessels where onboard experience influences purchasing decisions. The trend toward factory-installed directional audio and integrated entertainment systems reflects a broader move toward treating audio as a core feature rather than a peripheral accessory. This shift expands the strategic relevance of suppliers that can deliver both component performance and design flexibility to meet model-specific requirements.
Supply Chain and Cost Structure Dynamics
The cost structure of marine audio is shaped by material selection, specialized manufacturing processes, and the need for consistent durability under harsh conditions. Enclosures and cones require polymers engineered for UV and salt resistance, while connectors, terminals, and sealing components must endure prolonged exposure without degradation. These requirements increase input costs and complicate sourcing compared with standard consumer audio. As a result, supply chains that can secure reliable material grades, maintain process discipline, and validate durability at scale gain a meaningful advantage.
At the same time, the landscape is being influenced by the expansion of custom OEM/ODM capabilities among manufacturers outside traditional market centers. Notably, a Chinese manufacturer announced expanded custom OEM/ODM capabilities for marine audio systems targeting U.S. distributors, reflecting a broader trend of specialized production capacity becoming available to support foreign channel partners. This does not simply represent lower-cost sourcing; it signals the emergence of alternative manufacturing pathways that can be tailored to marine durability requirements while offering flexible volumes and customization. For buyers and competitors alike, this creates both opportunity and strategic risk: opportunities to access specialized production and cost flexibility, alongside risks related to quality consistency, lead-time reliability, and channel control.
Competitive Landscape and Leading Strategies
Strategic Positioning and Differentiation Among Core Players
The marine audio market features a mix of performance-focused specialists, premium brands with broad product portfolios, and suppliers with strong integration or customization capabilities. The competitive logic is not uniform; firms are competing on different axes, and understanding those axes is essential for interpreting market momentum.
-
Performance specialists and marine-native engineering: Companies such as Wet Sounds and JL Audio have built reputations around high-performance marine audio engineered specifically for demanding environments. Their product portfolios typically span speakers, subwoofers, amplifiers, and tower or integrated systems, with emphasis on withstand capabilities and acoustic output suited to open-water and high-noise settings. Their differentiation often rests on a clear marine-first design philosophy, which appeals to enthusiasts, installers, and OEM partners seeking credible performance narratives.
-
Integrated ecosystems and electronics alignment: Suppliers with ties to broader marine electronics platforms can leverage interoperability and installer familiarity as strategic advantages. Garmin's Fusion line, for example, positions advanced marine audio entertainment systems within a networked vessel context, benefiting from alignment with chartplotters and other marine electronics. This ecosystem-oriented approach reduces integration friction for buyers who prioritize unified systems over discrete components.
-
Premium audio credence and cross-environment brand strength: Brands with strong heritage in consumer or mobile audio, such as Rockford Fosgate and BOSS Audio Systems, extend into marine with marine-grade construction and full-system offerings. Their strategy often relies on translating brand recognition and acoustic tuning expertise into the marine segment, while reinforcing durability features such as UV-treated materials, sealed architectures, and weather-resistant components. This can accelerate market acceptance among consumers who already trust the brand in other contexts.
PW Consulting -
Customization and ODM/OEM-enabled supply: China Future Sound illustrates a different competitive model: specialized marine audio OEM/ODM production built around salt spray, UV exposure, and marine durability requirements. Its positioning emphasizes flexibility in speakers, subwoofers, amplifiers, and enclosures for partners seeking tailored solutions. This model is particularly relevant for distributors and brands looking to scale custom products without holding all manufacturing in-house, and it highlights the growing importance of supplier capability in enabling channel and product strategy.
-
Material and acoustic engineering focus: Other players, such as Hertz Marine, Kicker Marine Audio, Poly-Planar, and Maxxsonics, compete on combinations of durability, acoustic quality, and marine-specific component design. Recent product activity, including new speaker and subwoofer lines and the use of UV-treated injection-molded cones and Santoprene surrounds, reflects a continuing emphasis on material durability and acoustic refinement. Where these firms differentiate is often in the specifics of construction, tuning philosophy, and how well they address the tradeoffs between performance, resilience, and cost.
Evolution of Market Structure
The market's moderate concentration suggests it is past the earliest fragmentation stage but not yet dominated by a few scale players. This structure creates multiple plausible evolutionary paths. One is gradual consolidation through OEM partnerships, distribution agreements, and selective acquisitions, particularly as integrated systems and certification readiness become more important. Another is continued segmentation, where performance specialists, ecosystem-integrated suppliers, and customization-focused manufacturers each serve distinct value propositions with limited direct overlap. A third is the entry of capable OEM/ODM partners that enable new brand and distribution models, potentially intensifying competition in specific channels while expanding overall product variety.
A key structural shift already underway is the move from aftermarket-led upgrades toward more embedded OEM design wins. As boat builders incorporate audio into model identity and vessel experience, the sales cycle lengthens and technical requirements tighten, favoring suppliers with proven integration records, scalable manufacturing quality, and the ability to meet model-specific acoustic and durability targets. This does not eliminate aftermarket demand, but it changes where value accrues: suppliers with strong OEM relationships and installer trust gain a more durable growth base, while those dependent on price-sensitive retail channels must work harder to defend margins.
Future Trends and Commercial Implications
Trend 1: Networked, software-defined audio becomes standard in higher-tier vessels
The combination of digital networking architectures, DSP-based tuning, and real-time modeling points toward marine audio systems that are more adaptive and easier to integrate with vessel electronics. Over the next three to five years, this trend is likely to deepen, especially in premium recreational boats and commercial leisure vessels where unified control, zone-based playback, and cleaner installation matter. The commercial implication is straightforward: suppliers that offer open, compatible architectures and tunable performance will be better positioned for OEM specification and professional installation, while closed or hard-to-integrate products may face growing exclusion risk.
Motorcycle Audio Systems Market
Trend 2: Durability and certification as differentiators, not baseline checkboxes
As buyers become more informed about marine environmental stress, durability validation and quality systems will increasingly influence purchasing decisions and channel preferences. This trend favors suppliers that can clearly demonstrate marine-grade construction, consistent process control, and credible warranty and service frameworks. The opportunity lies not just in meeting standards but in making durability understandable and verifiable to installers, dealers, and end users. Suppliers that can connect material choices, testing discipline, and real-world performance into a coherent narrative will have an edge in premium and mid-premium segments.
Trend 3: Customization and flexible manufacturing expand product and channel options
The expansion of custom OEM/ODM capacity, combined with growing demand for tailored speaker, subwoofer, and amplifier configurations, is likely to increase product variety and accelerate model-specific design cycles. For distributors and brands, flexible manufacturing partners can shorten time-to-market and support smaller-volume custom programs. For incumbents, this introduces both opportunity and pressure: opportunity to collaborate and scale specialized offerings, and pressure to maintain quality, lead-time, and cost advantages in the face of new supply options. The result may be a more pluralistic market in which customization capability becomes a strategic asset across multiple business models.
Risks and Uncertainties
Several factors could alter the trajectory of these trends. Material cost volatility and the expense of marine-grade polymers and corrosion-resistant components can compress margins if not managed through design efficiency or sourcing strategy. Interoperability expectations may shift as vessel electronics evolve, potentially requiring redesigns or retrofit strategies for products not built on adaptable architectures. Channel dynamics also remain uncertain: as OEM integration grows, aftermarket demand could become more polarized, with strong performance in premium upgrades and weaker growth in commoditized segments. Finally, the entry of new manufacturing partners can improve flexibility but also raises questions about quality consistency, warranty support, and long-term supply reliability, all of which can affect brand and distributor confidence.
Strategic Actions for Decision Makers
For Marine Audio Manufacturers and Suppliers
-
Treat durability and integration as co-equal priorities in product planning. Weather resistance alone is no longer enough; products must also align with networked vessel architectures and installer workflows. Prioritize architectures that simplify specification into OEM platforms and reduce integration friction for professional installers.
-
Invest in clear, credible performance narratives supported by materials, tuning, and process discipline. Margins are increasingly defended by differentiation that customers can understand and trust, whether through acoustic performance, robustness under real marine conditions, or predictable service outcomes.
-
Use flexible manufacturing and ODM partnerships strategically, not just for cost. Evaluate partners on quality consistency, certification readiness, communication, and ability to support custom programs at scale, especially if targeting U.S. distribution or OEM-adjacent channels.
Worldwide Home Audio System Market
For Investors and Strategic Buyers
-
Look beyond headline revenue growth and assess which companies are gaining share through OEM relationships, ecosystem alignment, and product architectures that reduce integration risk. Revenue is important, but the durability of that revenue depends on specification wins, installer trust, and repeatable quality.
-
Value certification and durability assurance as indicators of long-term competitiveness. Suppliers with mature quality systems and marine-specific validation are better equipped to secure OEM approval and sustain brand credibility in demanding environments.
-
Monitor the customization and ODM landscape for both partnership opportunities and competitive disruption. New manufacturing capabilities can lower barriers to entry for niche brands and accelerate product diversity, which may reshape channel dynamics and margin structures over time.
For Procurement Leaders and Channel Partners
-
Specify with interoperability and serviceability in mind. Products that align with established marine networking standards and offer straightforward installation paths reduce downstream risk and improve dealer and installer satisfaction.
-
Balance brand recognition with marine-native engineering validation. Familiar brands can reduce adoption friction, but marine-specific durability, tuning, and component construction should remain central evaluation criteria, especially for harsher environments and higher-use vessels.
-
Demand transparent material and construction specifications. Understanding enclosure materials, surround technologies, sealing approaches, and corrosion resistance helps procurement teams compare products meaningfully and forecast total cost of ownership more accurately.
The marine audio system market is entering a phase in which growth is increasingly tied to integration, durability credibility, and the ability to serve both OEM design cycles and aftermarket customization. The firms that will capture the most resilient value are those that can align product architecture with vessel electronics, communicate marine-grade performance with substance, and operate with the manufacturing discipline required for demanding environments. For decision makers seeking to move from broad market awareness to precise segment, channel, and product-level planning, a more detailed view of segmentation splits, regional dynamics, competitive benchmarks, and scenario-based forecasts can sharpen execution. The full research report provides that deeper breakdown, including granular sizing across product types, applications, and regions, alongside expanded competitive analysis and tailored strategic recommendations for specific business objectives.
For detailed analysis of this topic, please visit the official page: Marine Audio System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


