



Palletizing Machine Market 2026: Why 6.12% CAGR Signals Broader Automation Shift

Strategic Trends and Commercial Opportunities in the Palletizing Machine Market
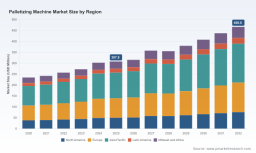
The palletizing machine market is navigating a period of structural transformation, moving beyond simple mechanization toward intelligent, adaptive automation. Over the historical window from 2020 through 2025, the sector expanded from approximately $234.5 million to $307.9 million, reflecting sustained capital investment in post-packaging material handling. This momentum is expected to carry forward through the 2026–2032 forecast horizon, with a compound annual growth rate of 6.12 percent pushing the market toward the $466.6 million mark by the end of the projection period. The trajectory is not merely a function of volume expansion; it is being reshaped by shifting labor economics, evolving safety frameworks, and the convergence of robotics with artificial intelligence. For executives and investors, the critical question is no longer whether to automate palletizing, but how to align equipment strategies with a landscape where conventional, robotic, and mixed configurations are competing on flexibility, integration depth, and total cost of ownership rather than throughput alone.
Core Challenges and Inflection Points
The industry is currently grappling with three interrelated challenges that are forcing strategic recalibrations across equipment manufacturers, system integrators, and end-users. First, the traditional dichotomy between conventional and robotic palletizers is blurring as mixed configurations and collaborative robots gain traction for low-to-medium volume operations. Buyers are increasingly evaluating mixed palletizers as a compromise between the simplicity of fixed automation and the flexibility of robotic cells, which complicates vendor selection and demands clearer total cost models. Second, safety standardization is tightening globally. Recent updates to industrial robot safety frameworks, including the ISO 10218-2025 revision published in March 2025 and the EN 415-4:2025 standard issued in December 2025, introduce differentiated robot classes for palletizing safety assessments and establish safety requirements spanning installation through operation. Compliance is no longer a checkbox exercise; it influences cell design, integration timelines, and lifecycle service obligations. Third, the valuation of automation is being recalibrated by labor economics. With median hourly wages for palletizer operators in the United States reaching $34.80 in 2026 and average fully-loaded costs approaching $55,000 per worker annually, the financial case for automation is stronger than ever, but so is the expectation for systems that reduce changeover complexity, minimize operator intervention, and deliver predictable uptime.
Worldwide Robotic Palletizers Market
These inflection points converge to reshape procurement criteria. Organizations are shifting from unit-price comparisons toward evaluating integration readiness, cross-line configurability, and the ability of equipment to coexist with broader warehouse automation ecosystems. The market is also witnessing a concentration dynamic where a limited set of players controls a meaningful share of revenue, yet the dispersion of mid-tier specialists and regional integrators creates pockets of agility and customization that large incumbents cannot always replicate quickly.
Key Drivers Reshaping the Market
Technological Innovation and Collaborative Flexibility
Technological advances are redefining what palletizing equipment can do in high-mix environments. Collaborative robot families are expanding beyond light assistance into industrial-grade palletizing applications, driven by ergonomic improvements, simplified programming, and safety architectures that reduce the need for extensive guarding. Recent product activity illustrates this direction. In May 2025, FAB America introduced wrist buttons across its CRX cobot lineup to enhance palletizing ergonomics, and by April 2026 debuted the CRX-3iA collaborative robot with new capabilities for palletizing and related tasks. Around the same period, ABB Robotics launched its PoWa cobot family for industrial-grade collaborative palletizing and subsequently rolled out updates to enhance performance. These developments signal a broader trend: collaborative systems are no longer peripheral solutions confined to low-speed tasks, but are increasingly positioned for scalable adoption where mixed SKUs, frequent changeovers, and space constraints make traditional large-cell robotics less attractive.
Palletizer Market
At the same time, mixed palletizing is benefiting from AI-driven decisioning and tighter integration with conveying infrastructure. FlexLink's AI-driven mixed palletizer, showcased at PACK EXPO Las Vegas in September 2025, highlights how software logic can improve stacking efficiency and safety while reducing manual reconfiguration. This shift is significant because mixed configurations have historically been constrained by complex setup routines and limited scalability. AI-enabled approaches lower the operational friction of running multiple product formats on a single line, which is particularly valuable for producers handling variable case sizes, promotional packs, and seasonal assortments.
Regulatory and Standardization Momentum
Regulatory and standards activity is acting as both a constraint and a catalyst. The publication of ISO 10218:2025 in March 2025, with differentiated robot classes for palletizing safety assessments, introduces a more granular safety evaluation framework that aligns system design with application risk profiles. The EN 415-4:2025 standard further establishes safety requirements for palletizers and depalletizers across installation and operation phases. For manufacturers, these updates compel earlier consideration of safety architecture in the product development cycle and influence how cells are commissioned and validated. For buyers, the emerging standards raise the importance of documented compliance, service support, and cross-border acceptance of safety certifications when evaluating global equipment portfolios.
Standards are also shaping integration strategies. As safety requirements become more application-specific, vendors that can provide pre-validated safety configurations, modular guarding options, and clear documentation are gaining a competitive edge in tender evaluations. This dynamic favors suppliers with integrated engineering capabilities and service networks that can support localized compliance without sacrificing throughput design objectives.
Demand-Side Shifts in Food, Beverage, E-Commerce, and Retail
Demand-side behavior is diversifying the use cases for palletizing equipment. Food and beverage production continues to drive substantial volume, but the nature of the demand is changing as lines accommodate more packaging formats, shorter runs, and faster SKU turnover. E-commerce and retail operations are expanding the role of palletizing beyond traditional distribution centers into fulfillment environments where mixed loads, layer integrity, and protection of high-value goods matter more than maximum line speed. These shifts increase the value of systems that can manage overhang constraints, bundle and tier configurations, and rapid format changes without sacrificing stability.
The commercial implication is that throughput alone is no longer the primary differentiator. Buyers are increasingly prioritizing adaptability, ergonomics, and the ability to integrate palletizing into broader warehouse and line-side automation. Companies such as Krones AG, which delivers complete palletizing systems for beverage and food production lines, and BEUMER Group, which provides palletizing and depalletizing solutions for bulk goods and packaged products, illustrate how complete-system thinking is gaining traction for sectors with complex product handling requirements. Meanwhile, palletizer specialists like Columbia Machine, with bundle and tier capabilities, and Symach, with conventional high-speed stacking without overhang, continue to compete on application-specific performance profiles.
Labor Economics and Total Cost of Ownership Reassessment
Labor cost dynamics are accelerating the reassessment of automation economics. The elevated cost of manual palletizer operation is compressing payback horizons for well-designed automation, but it also raises expectations for systems that reduce operator dependency and minimize downtime. As a result, the total cost of ownership calculus now includes not just acquisition cost, but integration complexity, changeover time, maintenance burden, and the degree to which a system can be redeployed across lines or product families. This environment favors equipment that offers modular scalability, intuitive interfaces, and serviceable architectures.
This driver is particularly impactful for mid-sized enterprises that previously found large robotic cells financially out of reach or operationally excessive. Collaborative and mixed configurations, when paired with compact automation cells and rapid deployment models, broaden the addressable market and create opportunities for vendors that can deliver predictable performance at lower integration overhead. The trend is visible in the emergence of versatile, scalable automation offerings and cobot-based compact systems from players such as Schneider Packaging Equipment and Vention, alongside integration-focused providers like TopTier and NOVA Automation.
Competitive Landscape and Evolving Strategies
Differentiation Through Integration, Payload, and Flexibility
The competitive field combines global robotics giants, complete-line specialists, and regional palletizer manufacturers, each pursuing distinct strategic positions. ABB provides robotic palletizing solutions including the IRB 760 high-speed full-layer palletizer and OmniCore controllers, anchoring its strategy in high throughput and control architecture. KUKA AG competes with the KR QUANTEC PA series, emphasizing enhanced payload and multi-line configurations for operations that require robust handling and flexible deployment across multiple packaging lines. FANUC Corporation manufactures industrial and cobot palletizing robots, including the CRX series with user-friendly wrist controls, aligning its approach with ease of use and broad application coverage. Yaskawa Electric Corporation supplies palletizing robots tailored for food and consumer goods applications with integrated systems, leveraging application-specific engineering and system-level delivery.
Beyond the robotics manufacturers, system-level and application-focused suppliers are carving out strong positions. Krones AG delivers complete palletizing systems for beverage and food production lines, positioning itself around end-to-end line integration. BEUMER Group offers palletizing and depalletizing systems for bulk goods and packaged products, appealing to sectors where material handling spans a wide range of formats. Honeywell Intelligrated extends the conversation into warehouse automation, providing integrated palletizing and broader material handling solutions. On the conventional and specialized side, A-B-C Packaging Machine Corporation manufactures high-performance palletizers for case and layer forming, Columbia Machine produces palletizing systems with bundle and tier capabilities for diverse industries, and Symach sells conventional palletizers featuring high-speed stacking without overhang. Schneider Packaging Equipment develops palletizing cells including cobot-based compact automation systems, while FlexLink supplies AI-driven mixed palletizing solutions integrated with conveying systems. Vention offers Rapid Series palletizers for versatile and scalable automation, TopTier provides low-infeed and conventional/robotic palletizing solutions for integration, and NOVA Automation manufactures industrial palletizing cells such as the IPC-25 for case handling.
Some of the most notable strategic signals are coming from product and event activity that emphasizes ergonomics, compact deployment, and AI-enabled flexibility. ABB Robotics' PoWa cobot family and subsequent performance updates, FANUC America's CRX wrist-button enhancements and the CRX-3iA debut, and FlexLink's AI-driven mixed palletizer featured at PACK EXPO Las Vegas in September 2025 collectively point to a market where usability and adaptability are becoming central value propositions. Marchesini's display of the WKR Compact Palletizer and introduction of new single or dual robotic palletizer options further illustrate how compact footprint and dual-configurability are being prioritized for environments where space and line flexibility matter. Honeywell's participation in PACK EXPO Las Vegas with warehouse automation solutions extending beyond palletizing highlights the growing relevance of ecosystem-level integration for buyers seeking cohesive material handling strategies.
Market Structure Evolution: Consolidation Pressure and Niche Agility
The competitive structure is evolving along two directions simultaneously. One is consolidation pressure at the upper end, where broad robotics portfolios, control platforms, and global service networks create advantages in large-scale deployments and cross-market standardization. The other is continued agility among specialized manufacturers and integrators who can configure cells for narrow applications, respond quickly to regional requirements, and tailor changeover procedures to local product mixes. This bifurcation creates a market where large portfolios compete on scale, reliability, and integration breadth, while specialists compete on configurability, application expertise, and faster deployment cycles.
The recent standards and event activity reinforces this dynamic. As safety requirements become more application-specific, suppliers with strong documentation, modular safety design, and cross-regional compliance support are better positioned to win multi-site and multi-market projects. At the same time, AI-driven mixed palletizing and cobot-based compact cells are reducing barriers for smaller and mid-tier operations, expanding the pool of potential adopters and increasing competition among vendors that can deliver straightforward integration without sacrificing performance. The outcome is likely to be a more segmented competitive environment where incumbents strengthen ecosystem positions while challengers win on usability, footprint, and application fit.
Future Trends and Commercial Opportunities
Trend 1: Collaborative and Mixed Configurations as Mainstream Options
Over the next three to five years, collaborative robots and mixed palletizing configurations are likely to move from specialized solutions to mainstream choices for many mid-volume and high-mix operations. The combination of ergonomic improvements, intuitive interfaces, and AI-assisted stacking logic is reducing the operational burden of frequent changeovers and small-batch production. For commercial strategy, this trend opens opportunities in sectors where product variability and space constraints previously limited the business case for automation. Vendors and integrators that can standardize modular cells, simplify commissioning, and provide clear guidance on safety compliance will be well placed to capture demand from organizations seeking automation without the complexity of large-scale robotic installations.
PW Consulting Automotive & Machinery Research Center
Trend 2: Ecosystem-Level Integration and Warehouse Automation Convergence
Palletizing is increasingly evaluated not as an isolated line function, but as part of broader warehouse and production automation. Buyers are looking for smoother interfaces with conveyance, warehouse management, and line-side material flow, which rewards suppliers that can offer integrated solutions and coherent service models. This convergence creates commercial opportunities for companies that can connect palletizing performance to overall material handling efficiency, reduce handoff friction, and support data-driven optimization across the workflow. It also raises the importance of open interfaces, interoperability, and serviceability, since downstream integration quality often determines whether a system delivers its intended throughput and flexibility in practice.
Trend 3: Compliance-Driven Design and Regional Deployment Considerations
The updated safety standards and differentiated robot classes are expected to shape product roadmaps and deployment strategies for the foreseeable future. As compliance documentation, modular safety design, and regional validation become more central to procurement decisions, opportunities will grow for suppliers that can provide pre-configured safety options, clear instruction sets, and support for local requirements. At the same time, regional deployment will remain sensitive to labor costs, facility layouts, and product mix, meaning that one-size-fits-all solutions will continue to face adoption limits. Companies that can balance global consistency with regional customization will have an advantage in multi-market rollouts and in facilities where safety, footprint, and changeover requirements differ significantly across sites.
Strategic Recommendations for Decision-Makers
For Equipment Manufacturers and System Integrators
Focus product and service portfolios on usability, modularity, and compliance readiness. The market is increasingly rewarding equipment that simplifies commissioning, supports rapid format changes, and integrates cleanly with conveying and warehouse automation. Invest in documentation and safety architectures that align with the differentiated robot classes and installation-to-operation requirements emerging from recent standards. Differentiation will increasingly come from how easily a solution can be deployed across lines, maintained over time, and redeployed as product mixes evolve.
For Investors Evaluating Automation and Robotics Exposure
Prioritize businesses that demonstrate integration depth, serviceability, and a credible path to serving mid-volume, high-mix demand. The growth trajectory is supported by a steady compound annual rate, but value capture will favor companies that can convert technological flexibility into repeatable deployment models and clear total cost of ownership advantages. Pay attention to players that are strengthening ecosystem positioning, AI-enabled mixed palletizing capabilities, and cobot-based compact solutions, as these areas are broadening the addressable market beyond traditional high-volume applications.
For Procurement and Operations Leaders Evaluating Palletizing Investments
Base evaluations on total cost of ownership, changeover complexity, safety compliance, and integration fit rather than peak throughput alone. As labor costs stay elevated and product variety increases, the value of palletizing equipment will depend heavily on how well it reduces manual intervention, supports mixed configurations, and aligns with existing material handling infrastructure. Request documented safety compliance, modular configuration options, and clearly defined service support before finalizing decisions, especially for multi-site or multi-region deployments where standard consistency and local adaptability both matter.
Closing Perspective
The palletizing machine market is entering a phase in which flexibility, integration, and compliance readiness will matter as much as raw throughput. Continued expansion toward the mid-$400 million range by the end of the forecast period reflects structural demand for automated material handling, but the winners will be those who can deliver predictable performance across changing product mixes, tighter safety expectations, and broader automation ecosystems. For organizations seeking deeper segmentation, regional granularity, and application-specific benchmarks, the full research report offers more detailed breakdowns and tailored recommendations to support investment timing, portfolio planning, and procurement strategy.
For detailed analysis of this topic, please visit the official page: Palletizing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


