



Automotive Glow Plugs Market: Why Diesel Demand and 4.17% CAGR Define Growth

Navigating the Automotive Glow Plugs Market: Strategic Trends and Commercial Opportunities Through 2032
1. Market Landscape and Core Challenges
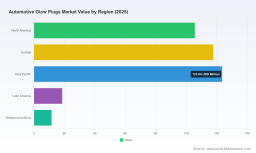
The automotive glow plugs market has demonstrated steady expansion over the past half-decade, reaching an estimated 377.41 million USD in 2025. Historical trajectories from 2020 through 2025 reflect consistent volume growth, interrupted only by a brief contraction in 2022 that was quickly overcome by renewed demand recovery. Looking forward to the forecast period of 2026 through 2032, the market is projected to advance at a compound annual growth rate of 4.17 percent, culminating in a valuation of approximately 504.69 million USD by 2032. This trajectory underscores the enduring role of glow plug systems in compression-ignition engines, even as broader powertrain transformations reshape the automotive components ecosystem.
1.1 Competitive Concentration and Market Structure
The industry operates under a moderately concentrated structure, with the top three participants commanding roughly 55.4 percent of total revenue and the top five firms accounting for approximately 72.6 percent. This concentration indicates that established suppliers hold significant leverage in OEM negotiations and aftermarket channel partnerships, yet sufficient fragmentation remains to allow specialized entrants and regional players to capture meaningful niches. Market participants must therefore balance scale advantages with agility in meeting region-specific regulatory and performance requirements.
1.2 Key Challenges and Inflection Points
- Regulatory pressure on diesel combustion systems: Tightening emission frameworks, particularly the Euro 7 standard for light-duty vehicles taking effect in 2026, impose more stringent particle number limits down to 10 nm. These requirements force glow plug suppliers to support sustained low-emission combustion rather than merely enabling cold starts, elevating performance expectations and testing complexity.
- Powertrain transition uncertainty: While diesel passenger cars continue to decline in several mature markets, commercial vehicles and certain off-highway applications retain strong reliance on compression-ignition engines. This divergence creates uneven demand patterns that complicate capacity planning and inventory strategies for manufacturers operating across both segments.
- Component integration and validation costs: Advanced glow plug designs increasingly incorporate sensing and control functionalities. Transitioning from purely resistive heating elements to multi-functional modules raises development expenses and extends qualification cycles, challenging suppliers that lack robust engineering resources or dedicated validation infrastructure.
For decision-makers, these challenges translate into a need for precise demand forecasting by vehicle class and region, disciplined investment in high-value product architectures, and proactive engagement with regulatory timelines. The firms that thrive will be those treating glow plugs not as commodity components but as integrated enablers of emissions compliance and combustion optimization.
2. Key Drivers Shaping Market Dynamics
2.1 Technology Innovation and Performance Breakthroughs
Technological evolution remains the strongest catalyst for differentiation and margin preservation in the glow plugs market. Ceramic glow plug technology, pioneered and continuously refined by leading suppliers, delivers faster heat-up times while maintaining durability under high-temperature diesel combustion conditions. This performance profile is increasingly critical for modern engine management strategies that demand precise temperature control during warm-up and idle phases to minimize particulate formation. In parallel, pressure sensor glow plugs with integrated piezo-resistive sensors represent a significant step toward intelligent combustion management. By providing real-time feedback for optimized injection timing, these systems improve cold-start performance and contribute to NOx reduction, aligning component functionality with broader engine-out emissions goals.
The commercial implications are clear. Suppliers that develop and standardize advanced thermal and sensing architectures can command premium positioning in both original equipment and replacement channels. Meanwhile, conventional sheathed-element designs remain relevant for cost-sensitive applications, but their differentiation potential is narrowing as higher-performance alternatives become more accessible. Manufacturers must therefore decide where to invest in next-generation platforms and where to sustain efficient production of established designs for high-volume, price-driven segments.
2.2 Policy and Regulatory Environment
Regulatory frameworks are reshaping the functional requirements of glow plug systems. The Euro 7 emission standards for light-duty vehicles, scheduled to take effect in 2026, tighten particle number limits and require sustained low-emission combustion in compression-ignition engines. This shifts the value proposition of glow plugs from basic cold-start assistance toward active participation in emission control during the entire warm-up and operational window. Suppliers that can demonstrate measurable contributions to particle reduction and combustion stability will be better positioned to secure OEM approvals and aftermarket credentialing.
For commercial players, regulatory alignment is no longer optional. Validation programs must account for extended service life, thermal cycling under stricter operating profiles, and compatibility with after-treatment systems. Companies that anticipate these requirements and integrate them into product development cycles will reduce the risk of late-stage design changes and sourcing disruptions.
2.3 Demand-Side Shifts in Vehicle Segments and Replacement Cycles
Demand patterns are being reweighted by vehicle segment dynamics. Commercial vehicles continue to represent the larger revenue pool within the glow plugs market, reflecting the durability requirements of fleet operations and the persistent use of diesel engines in heavy-duty and medium-duty transport. Passenger cars, while smaller in aggregate, remain an important channel in regions where diesel passenger vehicles retain meaningful market share. In the aftermarket, replacement demand is driven by accumulated vehicle parc, usage intensity, and the extended service intervals that can sometimes mask component wear until performance degradation becomes noticeable.
These demand-side realities create opportunities for suppliers with strong coverage in commercial vehicle platforms and comprehensive aftermarket part number portfolios. Broad application coverage, reliable fitment data, and proactive catalog maintenance are becoming as valuable as the physical component itself. Operators that can connect product performance with accurate replacement forecasting will capture greater share of wallet in both fleet service channels and independent repair networks.
2.4 Supply Chain and Cost Structure Evolution
Cost structures in the glow plugs market are influenced by material inputs, manufacturing precision, and the growing expense of validation and certification. Ceramic formulations and sensor-integrated designs elevate raw material and processing requirements, while sheathed metal elements continue to benefit from mature production processes. Regional supply arrangements also matter: concentration of production capacity in a limited set of manufacturing hubs can create efficiency gains but also introduces exposure to logistics volatility and regional demand imbalances.
Strategic cost management therefore requires more than purchasing leverage. It depends on platform standardization, selective automation in high-volume lines, and disciplined portfolio rationalization to avoid diluting margins across excessively fragmented part numbers. Companies that achieve this balance can protect profitability even as they advance technical content and meet evolving compliance expectations.
3. Competitive Landscape and Leader Strategies
3.1 Strategic Positioning of Leading Companies
The market is anchored by a group of highly specialized suppliers that combine engineering heritage, broad application coverage, and targeted innovation. Robert Bosch GmbH maintains a central position as a leading OE and aftermarket provider, leveraging patented sheathed-element technology for faster heating and extended glow durations. Its factory-tested supply model and deep integration with European diesel platforms reinforce a reputation for reliability and compliance readiness.
PW Consulting
Denso Corporation has built a strong identity around ceramic glow plug technology, with an aftermarket portfolio that exceeds OE specifications. As one of Europe’s largest suppliers and a pioneer in ceramic formulations, Denso emphasizes thermal performance and durability as core differentiators. The recent expansion of its premium aftermarket part numbers, covering a substantial number of OE part numbers, applications, and vehicles, illustrates a deliberate push to strengthen replacement channel relevance while maintaining technical leadership.
Niterra Co., Ltd. has emerged as a significant player by combining its heritage as a global spark plug leader with an expanding glow plug footprint. Its extensive European part number coverage across vehicles in operation reflects a strategy built on broad fitment and thermal technology optimization. A recent business transfer agreement to acquire Denso’s spark plug and glow plug business operations signals a clear intent to consolidate scale, streamline production for diesel applications, and capture additional aftermarket demand.
BorgWarner Inc. occupies a more focused niche, specializing in diesel cold-start systems and pressure sensor glow plugs that integrate piezo-resistive sensing. Its value proposition centers on combustion optimization, cold-start reliability, and emissions reduction, appealing to customers seeking performance and compliance benefits rather than commodity replacement parts.
Alongside these leaders, a broad set of manufacturers in Asia and Europe supports the market through focused manufacturing capabilities, region-specific distribution, and targeted coverage for passenger cars, light trucks, and diesel engines. These participants contribute to overall supply resilience and can compete effectively in channels where cost, responsiveness, and localized service matter.
3.2 Market Structure Evolution: Consolidation, Specialization, and Entry Dynamics
The competitive landscape is evolving along multiple axes. Consolidation is gaining momentum where scale, portfolio breadth, and manufacturing optimization create advantages. The acquisition move involving Denso’s spark plug and glow plug operations demonstrates how established players can strengthen market position by integrating complementary technologies and expanding production efficiency for diesel applications. At the same time, specialization remains attractive in high-value subsegments such as sensor-integrated glow plugs and premium ceramic solutions, where performance claims and validation data justify differentiated pricing.
Worldwide Automotive Coolant Heaters Market
New entry and regional expansion also continue to shape the market. Manufacturers with strong production discipline and the ability to deliver consistent quality across passenger cars and light commercial vehicles can secure footholds in aftermarket channels and selective OEM programs. The overall effect is a market that rewards both scale and specialization, with successful players typically combining one or more of the following: broad application coverage, proven thermal or sensing technology, regulatory readiness, and reliable aftermarket service support.
4. Future Outlook: Three Strategic Trends Through the Mid-2030s
4.1 Trend 1: Glow Plugs as Active Combustion Enablers
Over the next three to five years, glow plugs will increasingly be evaluated as part of the combustion optimization chain rather than standalone cold-start components. Sensor-integrated designs and advanced ceramic formulations will become more relevant in applications where emission compliance, start reliability, and engine-out pollutant control carry heightened importance. The commercial opportunity lies in bundling performance claims with application coverage and validation support, allowing suppliers to position higher-content products as enabling technologies rather than simple replacements.
The associated risk is the potential for over-investment in high-content architectures for segments where cost sensitivity remains dominant. Companies must calibrate product roadmaps to real demand mix, ensuring that premium offerings are aligned with platform commitments and regulatory timelines rather than introduced broadly without clear adoption pathways.
Worldwide Car Bulbs Market
4.2 Trend 2: Aftermarket Demand Becomes the Stability Anchor
As vehicle parc ages in several regions and commercial fleets maintain long service lives, aftermarket demand will remain a stabilizing force for the glow plugs market. Even where new-vehicle diesel volumes fluctuate, replacement requirements persist, creating a reliable revenue base for suppliers with comprehensive part number coverage and strong distribution relationships. The opportunity is to strengthen catalog accuracy, geographic reach, and service-level consistency so that aftermarket channels can be scaled efficiently while maintaining margin integrity.
The risk in this trend is channel fragmentation and price competition. Without disciplined portfolio management and clear differentiation, aftermarket supply can drift toward commoditization. Suppliers should therefore protect value by emphasizing fitment reliability, thermal performance, and compliance-relevant testing rather than competing solely on price.
4.3 Trend 3: Portfolio Consolidation Around High-Value Platforms
Market participants are likely to consolidate resources around platforms that combine technical content, regulatory readiness, and broad coverage. This will favor suppliers that can reduce complexity through shared core designs while still meeting segment-specific requirements for passenger cars, commercial vehicles, and diesel or gasoline applications. The strategic opportunity is to allocate capital toward platforms with the strongest performance differentiation and the widest addressable vehicle base, while retiring or rationalizing low-value duplication.
The risk is execution complexity. Consolidation requires careful change management, customer communication, and transition planning to avoid disruptions in OEM programs or aftermarket availability. Firms that manage this transition with transparent roadmaps and validated alternative designs will emerge with stronger cost positions and clearer market messaging.
5. Actionable Guidance for Decision-Makers
5.1 For Manufacturers and Tier Suppliers
- Concentrate engineering investment on architectures that deliver measurable benefits in heat-up speed, combustion support, or emissions-related performance, and align product roadmaps with the 2026 Euro 7 timeline and subsequent regulatory phases.
- Rationalize part number complexity where possible without compromising application coverage, using platform sharing and modular design to reduce cost while preserving fitment breadth for both passenger cars and commercial vehicles.
- Strengthen validation and qualification capabilities to shorten cycle times for sensor-integrated and ceramic-based designs, ensuring that technical claims are backed by documentation that OEMs and fleet customers can trust.
5.2 For Investors and Strategic Allocators
- Evaluate exposure by demand driver rather than by aggregate market size: prioritize companies with durable aftermarket coverage, clear technological differentiation, and demonstrated readiness for tighter emission standards.
- Watch for consolidation signals that improve production efficiency and portfolio coherence, while remaining alert to margin pressure if integration is pursued without corresponding value enhancement or channel strength.
- Consider the divergence between commercial vehicle stability and passenger car volatility when modeling demand, and assess whether target companies have the mix flexibility to manage uneven segment trajectories.
5.3 For Procurement and Fleet Decision-Makers
- Prioritize supply partners that can provide comprehensive part number coverage, accurate fitment data, and consistent quality documentation, especially for commercial fleets where downtime costs outweigh marginal component price differences.
- Evaluate advanced glow plug technologies in the context of total operating goals, including cold-start reliability, emission compliance, and service life, rather than selecting purely on initial purchase price.
- Establish clear specifications and validation expectations early in sourcing decisions to reduce the risk of fitment issues, performance variability, and downstream service complications.
The glow plugs market is not static. It is being reshaped by emission regulation, technological content, segment-specific demand, and selective consolidation. For organizations operating in or adjacent to this market, the strategic imperative is to understand where value is migrating and to align product, sourcing, and investment decisions accordingly. Detailed segmentation data, regional demand trajectories, and customized scenario modeling can sharpen these decisions further, and the full research report provides the depth required to translate market direction into concrete planning.
For detailed analysis of this topic, please visit the official page: Automotive Glow Plugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


