



Non-PVC IV Bag Market: Tracking the 6.98% CAGR Shift Toward Safer Solutions

Strategic Trends and Commercial Opportunities in the Non-PVC IV Bag Market
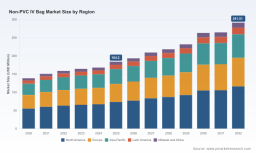
The non-PVC intravenous (IV) bag market has moved from a niche alternative to a structural imperative in clinical packaging. Driven by safety concerns, regulatory momentum, and supply chain resilience priorities, the segment is expanding at a compound annual growth rate of approximately 7.0 percent through 2032. From 2020 to 2025, market revenue grew from roughly USD 139 million to USD 184 million, with the trajectory accelerating as healthcare systems consolidate around DEHP-free and PVC-free infrastructure. Forward projections indicate revenue approaching USD 292 million by the end of the forecast period, reflecting sustained demand for infusion packaging that aligns with modern pharmacovigilance standards and procurement policies.
This expansion is not merely a volume story. It represents a shift in materials science, regulatory expectations, and manufacturing strategy that is reshaping competitive positioning across the value chain. For executives, investors, and procurement leaders, the non-PVC IV bag market offers clear signals about where capital, capability, and partnerships will be rewarded over the next several years.
Intravenous Fluid Bags Market
Market Status and Core Challenges
The market has matured rapidly over the past half-decade, but growth is uneven and constrained by structural frictions. While overall revenue is climbing steadily, participants must navigate a landscape where material performance, regulatory compliance, and capacity availability intersect in complex ways. The following challenges define the current inflection point.
Material Performance and Validation Hurdles
Non-PVC formulations must replicate or exceed the barrier properties, durability, and compatibility characteristics historically associated with PVC. Polyolefin and other alternative polymers have advanced significantly, yet scale-up validation remains costly and time-intensive. Clinical stakeholders require documented evidence on extractables, leachables, and drug-container interactions, which slows adoption for newer materials and raises the barrier for smaller entrants. This validation burden is particularly acute in multi-compartment and specialized infusion configurations, where performance requirements are more demanding.
Regional Regulatory Fragmentation
Regulatory and policy climates are diverging across jurisdictions, creating compliance complexity for manufacturers with global footprints. Some regions are moving toward explicit restrictions on phthalate-based plasticizers, while others continue to rely on broader pharmacopoeial standards. This fragmentation forces suppliers to maintain parallel product families and documentation sets, increasing operational overhead and complicating supply planning. At the same time, localized mandates and public tenders are accelerating the shift to DEHP-free and PVC-free options in specific markets, creating pockets of rapid adoption that do not always align with global rollout timelines.
Capacity Concentration and Supply Resilience
The market remains moderately fragmented at the top, with the largest three players holding just under 30 percent share and the top five reaching roughly 35 percent. While concentration is low enough to preserve competition, it also means that capacity additions and validation wins by leading suppliers can materially influence regional availability. Recent supply disruptions and drug shortage episodes have highlighted how container sourcing can become a limiting factor in critical care delivery. Procurement teams are increasingly treating container formats as part of supply resilience strategy rather than a commoditized accessory, which raises the strategic importance of reliable, qualified non-PVC capacity.
PW Consulting
Key Drivers of Market Change
Technology Innovation and Material Science Advances
Material innovation is the central engine of the transition. Polyolefin-based configurations now command the largest share of the product mix, reflecting their balance of safety profile, mechanical performance, and manufacturability. Polyester-based and ethylene vinyl acetate-based variants serve more specialized requirements, including tailored barrier properties and specific drug compatibility needs. Advances in film extrusion, multi-chamber design, and sterilization compatibility have expanded the range of therapies that can be packaged in non-PVC formats, including ready-to-use injectables and combination products. These advancements reduce the historical trade-offs between safety and performance, making non-PVC options viable across a broader set of clinical applications.
Recent product and regulatory milestones illustrate this momentum. A dual-chamber PVC-free and DEHP-free system received FDA clearance for an antibiotic combination, signaling that complex delivery formats are increasingly acceptable in non-PVC designs. In parallel, a major manufacturer coordinated with regulators to temporarily import saline in non-PVC containers to help mitigate shortages, underscoring how container qualification can directly support continuity of care. Another milestone saw an FDA-approved ready-to-use injectable in IV bags, reinforcing the broader shift toward premixed, non-PVC delivery formats that reduce handling risk and streamline clinical workflows.
Policy and Regulatory Environment
Regulatory direction is reinforcing the commercial case for non-PVC packaging. Pharmacovigilance pressures and public health policies are steadily elevating expectations around plasticizer exposure, particularly in vulnerable patient populations. In one notable example, state-level legislation has mandated that manufacturers notify customers of DEHP-free options and restrict DEHP-containing IV bags and tubing within defined timelines, setting a precedent that encourages broader adoption beyond the jurisdiction itself. These requirements are prompting healthcare systems to update procurement guidelines and push suppliers toward standardized DEHP-free portfolios.
Importantly, the regulatory environment is also enabling non-PVC containers to play a role in shortage management. FDA guidance has recognized non-PVC, DEHP-free IV bags as acceptable in drug shortage mitigation programs, including temporary import pathways for saline in non-PVC packaging. This linkage between regulatory clarity and operational resilience is a powerful catalyst: it positions non-PVC packaging not only as a safety choice but also as a contingency asset during supply stress.
Demand-Side Shifts in Clinical and Procurement Behavior
Demand is being reshaped by a combination of clinical preference, procurement policy, and therapeutic portfolio evolution. Blood and blood product transfusion remains the largest application area, reflecting the high sensitivity of these therapies to container interactions and the importance of minimizing extractables and leachables. Nutritional support and medication delivery applications continue to expand as premixed and ready-to-administer formulations gain traction, driven by goals to reduce preparation errors and improve bedside efficiency. Beyond these core uses, additional clinical applications are adding incremental demand as hospitals standardize container formats across service lines.
Procurement behavior is evolving in parallel. Group purchasing organizations and health systems are increasingly specifying DEHP-free and PVC-free options in contracts, while hospital pharmacies are favoring formats that support batch traceability, compatibility, and ease of use. This demand-side pull is amplified by manufacturers seeking to differentiate through safer packaging narratives and robust compatibility data, creating a reinforcing cycle between clinical confidence and commercial uptake.
Supply Chain and Cost Structure Dynamics
Cost structures are shifting as non-PVC materials move from specialized production to higher-volume manufacturing. Economies of scale are improving, particularly where producers have invested in dedicated eco-friendly facilities with multi-chamber capacity. Such scale advantages can compress per-unit costs over time and improve lead-time reliability, both of which matter to buyers seeking predictable supply. At the same time, raw material availability, film grade qualification, and sterilization pathway compatibility remain levers that influence margin and delivery performance.
Partnerships are becoming an important cost and capability strategy. A recent joint venture between an IV solutions manufacturer and a pharmaceutical partner was aimed at strengthening manufacturing and supply of intravenous solutions in North America, reflecting a broader tendency to align container and solution capabilities to reduce coordination risk and improve continuity. As these arrangements deepen, the market may see more integrated offerings that link bag formats, fill-finish processes, and therapeutic portfolios, changing how value is captured across the chain.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Key Players
The competitive field includes global infusion leaders, regional specialists, and material suppliers, each pursuing distinct positioning. Baxter International emphasizes a DEHP-free portfolio that includes non-PVC large-volume bags, leveraging scale and a broad infusion franchise to standardize safer container options across mainstream channels. B. Braun positions itself around a full line of DEHP-free and non-PVC IV bags and containers, differentiating on breadth of format coverage and a stated commitment to PVC- and DEHP-free offerings across drug, solution, and irrigation containers. ICU Medical focuses on an FDA-approved DEHP-free and non-PVC bag portfolio, aligning its container strategy with regulatory readiness and compatibility assurance for U.S. market access.
Regional and specialty players are carving out differentiated niches. A Korean manufacturer operates what is described as the world's largest eco-friendly non-PVC IV fluid plant with multi-chamber bag capacity, using scale and specialized format capability to serve high-volume, sustainability-aligned demand. A Spain-based supplier offers DEHP-free IV bags for pharmaceutical and medical solutions, emphasizing product-grade compatibility for pharma partners. A Germany-based producer supplies PP-based non-PVC films and tubes for IV solution packaging, positioning closer to the material and conversion layer. A Portugal-based company focuses on pharmacopoeia-compliant DEHP-free bags, appealing to buyers seeking documented compliance. A U.S.-based materials company provides high-quality non-PVC materials for infusion bags, enabling downstream converters and fillers. A UK-based materials supplier contributes polyolefin materials for IV and pharmacological bags, reinforcing the material ecosystem. A UAE-based producer operates a facility producing sterile IV bag solutions in non-PVC bags, expanding regional manufacturing optionality and localized supply.
Differentiation Levers and Competitive Dynamics
Leading players are differentiating along several axes: regulatory readiness, format breadth, material innovation, scale, and regional supply presence. Regulatory readiness is especially valuable where customers face tight compliance timelines or require documented DEHP-free options for tenders and policy mandates. Format breadth matters for health systems that want to consolidate container types across therapies and reduce training and handling variability. Scale and dedicated eco-friendly capacity help stabilize lead times and improve cost trajectories, while material and film expertise can shorten qualification cycles for new drug-container combinations. Regional manufacturing presence is increasingly important for supply resilience, local content expectations, and responsiveness to policies that encourage or require domestic sourcing.
Evolution of the Market Structure
The market is likely to evolve through a combination of consolidation among scaled players, deepening specialization among niche suppliers, and selective entry by companies that can bring compliant material platforms and regional capacity. Because concentration at the top remains moderate, there is room for multiple winners, but differentiation will depend on execution in qualification, supply reliability, and partnership ecosystems rather than on scale alone. The ongoing trend toward premixed and ready-to-use formats, together with drug shortage management needs, may encourage more integrated plays that connect bag formats with solution production and fill-finish capabilities. At the same time, suppliers that can offer standardized DEHP-free and non-PVC options with strong compatibility data will be better positioned to capture procurement mandates and public tenders as they expand.
Future Trends and Commercial Opportunities
Accelerated Standardization of DEHP-Free and Non-PVC Formats
Over the next three to five years, DEHP-free and non-PVC container formats are likely to become default expectations in an increasing number of procurement guidelines, especially where regulations and institutional policies are converging. This standardization will reduce the need for parallel inventories, simplify training, and strengthen the bargaining position of suppliers that can provide consistently qualified formats across large-volume and specialized applications. The commercial opportunity lies in offering harmonized portfolios that span blood and blood product transfusion, nutritional support, medication delivery, and other clinical uses, while maintaining documented compatibility and regional compliance. Suppliers that can demonstrate repeatable quality across these applications will be able to capture volume as health systems consolidate container specifications.
Integration of Container, Solution, and Fill-Finish Capabilities
A second trend is the deepening integration of container supply with solution manufacturing and fill-finish operations. Recent partnerships and Joint Ventures point toward closer alignment between bag formats and therapeutic availability, aiming to reduce coordination risk, improve lead times, and support continuity during shortage episodes. For market participants, this suggests value in building or partnering for end-to-end readiness, including sterilization pathways, multi-chamber capability, and validated compatibility with specific drug classes. The opportunity is not only in selling bags, but in enabling reliable, compliant delivery systems that meet hospital and pharmacy requirements for premixed and ready-to-use products. Companies that can connect material selection, format design, and fill-finish compatibility will be better positioned to compete for long-term supply agreements.
Regional Capacity Expansion and Supply Resilience as a Competitive Edge
A third trend is the expansion of regional capacity and localized supply, motivated by regulatory alignment, logistics resilience, and public procurement expectations. The emergence of large-scale eco-friendly non-PVC facilities and regional sterile manufacturing sites indicates that geography is becoming a strategic variable rather than a logistical afterthought. This creates opportunities for suppliers that can offer local content, shorter lead times, and regulatory familiarity, especially in markets where policies are accelerating the shift away from DEHP and PVC. The risk, however, is that capacity additions may outpace qualified demand in some regions or that differing pharmacopoeial standards will require duplicated validation efforts. Participants should plan for flexible capacity models and invest early in the documentation and testing needed to secure multi-market qualification.
Actionable Recommendations for Decision-Makers
For Manufacturers and Suppliers
- Prioritize standardized DEHP-free and non-PVC portfolios with documented compatibility across high-volume applications, especially where procurement mandates and tender language are tightening.
- Invest in multi-chamber and large-volume format capability, as these configurations are increasingly central to premixed and ready-to-use offerings and to shortage mitigation programs.
- Develop regional supply options and partnerships that reduce lead-time risk and align with local regulatory expectations, while maintaining the validation rigor required for multi-market access.
For Investors
- Evaluate exposure to companies with clear non-PVC material platforms, scaled eco-friendly capacity, and regulatory-ready portfolios, as these capabilities are likely to capture disproportionate share in a market that is moving from optional to standard.
- Look for value creation through partnerships that link container formats with solution production and fill-finish readiness, since integration can improve resilience and long-term contract eligibility.
- Consider the timing of regional capacity and policy catalysts, because local mandates and procurement shifts can create step-change demand that rewards companies with qualified supply already in place.
For Procurement and Clinical Operations Leaders
- Specify DEHP-free and non-PVC formats in contracts where possible, aligning container requirements with clinical safety goals and supply resilience planning, and request documented compatibility data to support adoption.
- Assess suppliers on format breadth, validation maturity, and regional availability, not just price, since container reliability and qualification status increasingly influence continuity of care.
- Coordinate across pharmacy, nursing, and supply chain functions to standardize container formats where clinically appropriate, reducing handling variability and strengthening the case for consistent non-PVC adoption.
For executives and investors seeking deeper segmentation, competitive benchmarks, and region-specific procurement dynamics, a detailed market study can translate these strategic signals into prioritization and timing decisions. A comprehensive report with granular segmentation and customized recommendations is available for teams that need to move from directional insight to execution planning.
IV Bags Market
For detailed analysis of this topic, please visit the official page: Non-PVC IV Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


