



Axial Fan Market: Why Asia Pacific & EC Adoption Drive 5.5% Growth

Axial Fan Market: Strategic Trends and Commercial Opportunities Beyond the Efficiency Mandate
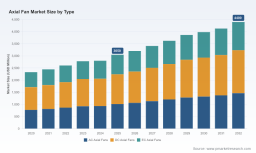
The axial fan market finds itself at a structural inflection point. From 2020 through 2025, the global market expanded from roughly $2.33 billion to an estimated $3.05 billion, reflecting a compound annual growth rate of approximately 5.5 percent across the forecast horizon through 2032. By the end of that forecast window, revenue is projected to approach $4.4 billion. These headline figures, however, only capture the quantitative surface of a deeper transformation. The market is no longer growing purely on installation volume or incremental replacement cycles. Growth is being reshaped by efficiency regulations, motor technology migration, regional supply chain realignment, and the growing expectation that airflow systems must operate as intelligent, energy-optimized components rather than standalone mechanical parts.
For executives and investors, the central question is no longer whether demand will continue, but where margin and differentiation will accrue. The market remains moderately fragmented, with the top three players holding roughly a quarter of total revenue and the top five closer to a third. That concentration level suggests both room for consolidation and persistent competition from specialized manufacturers who compete on application expertise rather than scale alone. The companies that will capture disproportionate value are those that can align product architecture with regulatory timelines, control component cost exposure, and convert efficiency mandates into commercial advantage rather than compliance cost.
Market Status and Core Challenges
The current market environment is defined by three intersecting challenges that are altering how axial fan manufacturers plan product roadmaps, pricing, and geographic exposure.
Efficiency Regulation as a redesign Imperative
Regulatory pressure is moving from incremental tightening to mandatory step changes. The EU ErP 2026 framework raises mandatory efficiency requirements for axial fans and cooling towers, while California Title 24 2025 standards increase efficacy expectations for axial-fan cooling towers in nonresidential applications. These are not marginal adjustments. They effectively reset the minimum performance baseline for new equipment in key commercial and industrial segments. Manufacturers that have historically competed on price or basic airflow capacity now face a redesign window in which motor type, blade geometry, and control logic must be evaluated together. The practical challenge is timing: product development cycles that are too slow will miss market entry points, while premature launches risk non-compliance or retrofit friction.
Cost Structure Exposure in a Volatile Input Environment
Axial fans rely on steel housings, aluminum blades, and electric motors as core components, which means manufacturers are directly exposed to commodity price movements and trade policy shifts. Recent US trade measures introduce additional duties on steel and aluminum articles, affecting imports of structural and mechanical components used in fan assembly. Even when manufacturers source from diversified suppliers, the cumulative effect shows up in landed cost, margin stability, and quotation reliability. For companies that operate on fixed-price downstream contracts, the risk is not simply higher material costs; it is the difficulty of passing through cost changes without eroding competitiveness or delaying orders.
Application Complexity and the Shift from Component to System Thinking
The market is increasingly evaluated through system-level performance rather than isolated fan specifications. HVAC, industrial ventilation, cooling towers, and electronics cooling each place distinct demands on airflow, noise, space, and control integration. End users and OEMs are less interested in standalone air movement and more focused on whether the fan solution integrates cleanly into broader thermal management, energy, or automation architectures. This creates a strategic challenge for manufacturers that remain organized around discrete fan models rather than application bundles, controls, and service pathways. The market is rewarding those who can reduce integration friction and improve operating efficiency after installation, not just at the point of sale.
Key Drivers Reshaping the Market
Motor Architecture Evolution and EC/DC Technology Adoption
The most significant technical driver is the continued migration toward electronically commutated and DC motor platforms in axial fans. EC and DC architectures enable higher part-load efficiency, variable speed control, and more granular performance tuning than traditional AC designs in many applications. That matters because efficiency is no longer measured only at peak output; real-world operation increasingly values performance across duty cycles, startup behavior, and controllability. Manufacturers expanding EC and DC portfolios are positioning themselves for a market where efficiency compliance and operational flexibility become bundled value propositions. The broader implication is that motor technology is becoming a strategic differentiator, not simply a component choice.
Policy-Driven Demand and Retrofit Economics
Policy and building performance standards are creating both new equipment demand and retrofit activity. As efficiency thresholds rise, a portion of the market shifts toward replacement and upgrade cycles, especially in nonresidential HVAC, commercial ventilation, and cooling tower environments where compliance deadlines interact with capital planning. At the same time, stringent energy expectations in key regions influence procurement criteria, making efficiency class and total cost of ownership more prominent in purchasing decisions. Demand is therefore being shaped not only by end-market growth, but by regulatory-driven renewal cycles and the economics of replacing lower-efficiency installed base equipment.
Application Demand Diversification Across End-Use Segments
Demand continues to broaden across multiple usage contexts rather than concentrating in a single dominant application. HVAC remains a major axis of demand, supported by building climate control needs and system modernization. Industrial ventilation adds another layer, where airflow reliability, durability, and integration with process environments matter as much as efficiency. Residential cooling and commercial building ventilation contribute additional demand streams with different price sensitivity, specification cycles, and channel dynamics. Meanwhile, automotive and adjacent applications provide smaller but technically demanding niches where performance consistency and long-life operation are critical. The strategic implication is that growth is not monolithic; each application segment has its own regulatory exposure, specification cadence, and competitive intensity.
Supply Chain Realignment and Regional Cost Dynamics
Supply chain considerations are becoming more strategic as manufacturers evaluate where to source motors, blades, housings, and electronic controls. Trade measures affecting steel and aluminum inputs, combined with the broader shift toward more localized or diversified sourcing, are influencing cost structures and lead-time planning. In this environment, manufacturers that can balance regional production footprints, manage component standardization, and maintain flexibility in assembly locations gain a practical advantage. The market is increasingly sensitive to the intersection of compliance, cost, and supply reliability, especially for companies serving multiple regions with different regulatory and procurement expectations.
Competitive Landscape and Leading Strategies
The competitive landscape is anchored by a group of manufacturers with strong engineering reputations, application-focused portfolios, and increasingly divergent strategic postures. Several patterns stand out.
Electric Fan Market
Efficiency Leadership through EC and Modular Platforms
German and European manufacturers such as Ziehl-Abegg and ebm-papst are widely recognized for their focus on high-efficiency EC motors and axial fans tailored to HVAC, industrial, and precision control applications. Their value proposition centers on combining energy savings with controllability and application-specific engineering. Multi-Wing has built a reputation as a global leader in modular axial fans and impellers for condenser, heat exchanger, HVAC, and industrial cooling environments, where modularity and application breadth support rapid configuration across end markets. These companies illustrate a common strategic theme: efficiency leadership is increasingly expressed through platform design, not just motor choice.
Regional Scale, OEM Integration, and Cooling System Footprints
Other players compete through strong regional presence and deep integration with specific downstream systems. Rosenberg and Airmaster Fan Company combine German engineering with a US commercial and industrial focus, while Delta Electronics and Sanyo Denki emphasize EC, DC, and DC axial fan series for electronics cooling and performance-intensive environments. In the United States, companies such as New York Blower Company, SPX Cooling Technologies, Evapco, and Baltimore Aircoil Company concentrate on in-line, custom, and cooling-tower-integrated axial fan solutions. This group demonstrates that competitive advantage is not only about fan efficiency in isolation, but about embedding the fan into larger system architectures where reliability, service, and specification support matter.
Consolidation and Portfolio Expansion
Corporate activity suggests the market is entering a more active phase of consolidation and capability building. Nidec Corporation's acquisition of an axial fan division expanded its production capabilities and reinforced its position across industrial and HVAC applications with EC and AC motor-based axial fans. At the same time, product and event activity from other manufacturers is signaling active portfolio refresh in response to upcoming efficiency requirements. Multi-Wing introduced ErP 2026-compliant axial fan series and DCmax series exceeding EU energy efficiency regulations, while also preparing to showcase its offering at the IVT Expo in Cologne. ebm-papst announced AxiTone and AxiEco plug-in axial fans for HVAC applications. Taken together, these moves indicate that leading players are using product launches, trade presence, and selective acquisitions to strengthen both technical credibility and market coverage ahead of regulatory implementation.
Strategic Implications of the Current Landscape
The competitive environment favors manufacturers that can combine several capabilities at once: efficiency compliance readiness, application-specific configuration, motor and control integration, and supply chain resilience. Pure price competition is becoming harder to sustain as regulatory floors rise and input costs remain volatile. At the same time, the moderate concentration of the market leaves space for both consolidation among larger players and continued niche strength among specialists. New entrants face a meaningful barrier unless they bring a clear advantage in motor efficiency, system integration, or a specific regional application niche. The more probable trajectory is continued differentiation, selective M&A, and a growing divide between platform-driven leaders and application-focused specialists.
Forward Trends and Commercial Implications
Efficiency Compliance Becomes a Market-Filtering Event
Over the next three to five years, efficiency regulation will increasingly function as a market filter rather than a generic compliance task. As ErP 2026 and related regional standards take hold, procurement specifications are likely to narrow the field of acceptable products in regulated segments, particularly in commercial HVAC, cooling towers, and nonresidential ventilation. The commercial opportunity lies in positioning product lines that not only meet the new thresholds, but offer clear advantages in part-load performance, controllability, and integration. Manufacturers that can document compliance and translate it into operating savings will have stronger specification leverage. The risk is that companies with slower redesign cycles may face shrinking addressable demand in regulated channels, especially where replacement decisions are tied to compliance deadlines.
Growth Concentrates Where System Integration and Intelligence Add Value
A second trend is the growing importance of intelligent airflow management and system-level compatibility. Axial fans are increasingly evaluated alongside controls, sensors, and broader thermal or ventilation strategies. That creates opportunities for manufacturers that offer configurable solutions, compatible control interfaces, and lower integration complexity. In HVAC and industrial ventilation especially, the value shift is moving toward solutions that help reduce energy consumption across real operating conditions rather than at nominal ratings alone. The corresponding risk is that product portfolios remain fragmented, making it harder to scale cross-application platforms and to support customers who want standardized efficiency and control behavior across sites or projects.
Cooling Fan Market
Regional Divergence in Sourcing, Pricing, and Specification Cycles
The third trend is regional divergence in both cost dynamics and specification behavior. Trade measures affecting steel and aluminum inputs, combined with different regional regulatory timelines, mean that manufacturers cannot assume a uniform cost or compliance pathway across markets. Some regions may see faster replacement activity driven by building performance standards, while others may be more sensitive to input cost pressure and import exposure. This divergence creates opportunities for companies that can adapt sourcing, regional product configurations, and service coverage to local requirements. The uncertainty lies in how quickly trade conditions, material costs, and compliance enforcement will evolve, and whether manufacturers can maintain margin stability while adjusting regional strategies.
PW Consulting
Actionable Considerations for Decision Makers
For manufacturers, the priority is to treat efficiency compliance as a product strategy event rather than a certification task. That means aligning motor architecture, blade and housing design, and control capabilities with the regulatory timeline in each target market, while also reducing dependency on exposed input categories where possible. Companies should assess whether their portfolio is concentrated in application segments facing the sharpest compliance shifts and whether modular or configurable platforms can help them respond faster to specification changes. In parallel, building stronger system-integration support and documentation can improve specification win rates in segments where total cost of ownership matters more than unit price.
For investors, the market suggests a preference for companies with credible efficiency roadmaps, application breadth, and some degree of supply chain or geographic diversification. The moderate concentration level indicates room for consolidation, but value creation will likely depend on whether acquisitions and internal investments translate into compliant, differentiated platforms rather than simply adding volume. Investors should pay attention to how quickly manufacturers are converting regulatory pressure into new product launches, how exposed they are to steel and aluminum cost dynamics, and whether their growth is anchored in segments with durable replacement cycles and system-level demand.
For procurement and engineering leaders, the practical implication is to broaden evaluation criteria beyond nominal airflow and initial price. Efficiency class, part-load behavior, motor type, lifecycle cost, and compatibility with existing control or ventilation architecture are becoming more relevant as compliance expectations rise and operating environments grow more complex. Where projects intersect with regulated nonresidential or cooling-tower applications, early alignment with compliant product options can reduce redesign risk and specification delays. Procurement teams should also weigh supply continuity and regional sourcing exposure, particularly for programs with multi-year rollout plans or standardized equipment lists.
Conclusion
The axial fan market is moving from broad-based growth to a more selective, efficiency-driven expansion path. The combination of regulatory tightening, motor technology migration, application diversification, and input-cost volatility is reshaping where competitive advantage comes from. Manufacturers that treat compliance as a platform opportunity, invest in integration and control readiness, and manage material exposure strategically will be better positioned to capture margin and specification share. For investors and buyers, the most valuable intelligence is increasingly at the level of segment readiness, regional cost dynamics, and product roadmap alignment rather than aggregate market size alone. Detailed segment breakdowns, regional comparisons, and customized scenario analysis can sharpen these decisions further, especially for organizations planning capital allocation, product investment, or multi-region procurement strategies in the 2026 to 2032 window.
For detailed analysis of this topic, please visit the official page: Axial Fan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


