



Category: Healthy Lifestyle
PW Consulting: Motorcycle Gear Market to Hit $27.4M by 2032 at 5.6% CAGR
By PW Consulting, 2026-09-16
Navigating the Motorcycle Gear Market: Strategic Intelligence for 2026 and Beyond
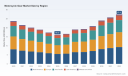
The global motorcycle gear market stands at a critical inflection point. Between 2020 and 2025, the sector experienced a period of structural contraction, with revenues declining from approximately 23.73 million USD to 16.15 million USD. This downward trajectory reflects a combination of post-pandemic demand normalization, supply chain recalibration, and shifting consumer spending patterns across rider demographics. However, the forecast period from 2026 through 2032 signals a decisive recovery. Market projections anticipate a compound annual growth rate of 5.6 percent, with revenues expected to climb steadily toward 27.4 million USD by the end of the decade. For executives, procurement leaders, and product strategists, these figures are not merely backward-looking indicators. They are early-warning signals that demand proactive positioning before the next growth cycle fully materializes.
Understanding why the market compressed, what is now catalyzing its rebound, and how competitive dynamics are reorganizing requires more than headline numbers. It requires a disciplined examination of type-level demand shifts, application-specific usage patterns, regional procurement behaviors, and the regulatory-material landscape that is actively reshaping product development pipelines. This report translates macro-level trajectories into operational intelligence. It is designed to help leadership teams validate product roadmaps, allocate inventory with precision, anticipate compliance exposure, and identify whitespace before competitors institutionalize their advantages.
The following analysis outlines the structural forces defining 2026 decision-making, previews the scope of our primary research, and demonstrates how competitive and regulatory intelligence can be converted into measurable strategic advantage.
Market Trajectory and the Strategic Meaning of the 2026 Inflection
The historical arc of the market carries a clear operational message. The contraction observed from 2020 through 2025 was not uniform across categories or user segments. Rather, it masked divergent behaviors: certain protective categories experienced faster erosion, while on-road application demand retained a structurally larger footprint than off-road usage. By 2026, the market begins its recovery at 16.63 million USD, a baseline that sets the stage for a multi-year expansion curve. The forecast steady climb toward 19.04 million USD in 2027, 19.32 million USD in 2028, and progressively higher figures through 2032 indicates that the sector is not simply rebounding. It is re-composing around new material priorities, evolving rider preferences, and tighter safety expectations.
For corporate strategists, the essential insight is that timing matters more than ever. Entering or expanding in this market after the recovery becomes visible to the broader industry often means accepting compressed margins and elevated competitive intensity. Companies that use 2026 to restructure product assortments, realign supply commitments, and benchmark regional demand behavior will be positioned to capture disproportionate share as the growth curve accelerates. The forecast horizon up to 2032 provides a sufficiently long runway to evaluate capacity investments, product lifecycle planning, and channel strategy without overcommitting to short-term volatility.
Core Report Scope: From High-Level Data to Operational Decision Support
This market research is structured to serve executives who need both strategic context and actionable breakdowns. Rather than stopping at aggregate market sizing, the report decomposes demand across multiple dimensions that directly influence product planning, sourcing, and go-to-market execution.
- Historical performance tracking from 2020 through 2025, enabling retrospective analysis of contraction drivers and category resilience.
- Forward-looking projections across the 2026-2032 window, giving strategy teams a consistent basis for capacity, pricing, and portfolio planning.
- Category-level analysis across helmets, jackets, gloves, protective gear, and other product types, allowing product leaders to identify where demand momentum is building and where saturation risk is rising.
- Application-based evaluation separating on-road and off-road usage contexts, which is critical for understanding rider behavior, feature prioritization, and seasonal or regional demand variability.
- Regional demand distribution across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, supporting market entry assessments and localized inventory strategy.
- Competitive concentration metrics that illuminate market share dynamics and help benchmark the balance between established incumbents and emerging challengers.
The report is deliberately built to avoid the trap ofabstract market narratives. Each section connects data to operational implications. For example, rather than presenting a single aggregate figure and moving on, the research situates that figure within type-level and application-level behavior so that sourcing teams can anticipate where volume is likely to concentrate. Rather than offering generic growth commentary, it ties expansion trajectories to the product and regional contexts that leadership teams actually manage day to day.
Competitive Landscape: Concentration, Positioning, and Strategic Differentiation
Market concentration remains a defining feature of the industry. With the top three players accounting for 44.5 percent of market share and the top five firms commanding 56.2 percent, the competitive environment is neither fragmented nor fully consolidated. This mid-range concentration creates a dual strategic reality. Incumbents benefit from scale, brand equity, and established distribution relationships, while smaller or regionally focused players can still win through specialization, agile product iteration, and segment-focused positioning.
The competitive set spans a broad geographic and product footprint. Italian manufacturers such as Alpinestars and Dainese continue to exert strong influence across premium protective and apparel categories, while Dutch brand REV'IT! Sport International has carved out a distinct position through functional rider apparel and modular gear design. On the American side, Fox Racing and Klim represent performance-oriented and adventure-touring segments respectively, each reinforcing different rider identities and usage contexts. Additional players including Leatt, Aerostich, FLY Racing, Rynox Gears, Sedici, Aether, Just1, Icon Motosports, Kushitani, Rukka, Sidi, Held, and Spidi contribute further variation in product specialization, regional reach, and price-tier positioning.
This diversity matters because the market is not being won on brand recognition alone. Competitive advantage increasingly derives from how effectively companies integrate protection performance, material innovation, rider comfort, and compliance assurance into a cohesive product story. Some manufacturers are widening their lead through heritage and scale. Others are gaining traction by targeting specific riding disciplines or by re-engineering product lines around emerging material and sustainability expectations. The report maps these positioning strategies in greater detail, providing a comparative lens that helps companies evaluate where they are exposed, where they can differentiate, and where partnership or acquisition logic may be warranted.
Dynamics Shaping 2026: Regulation, Sustainability, and Live Market Signals
The market is being reshaped by several concurrent forces. Regulatory scrutiny is one of the most immediate. In early 2026, NHTSA issued recalls affecting multiple helmet models, including Allwin Powersports Corp. LS2 Rebellion helmets in sizes XL and XXL produced between July 1, 2024 and July 30, 2025, as well as Micro DOT Helmet Co. Blister Original, Twister Original, and Twister 2.0 ABS helmets for non-conformance with FMVSS No. 218 impact protection standards. These actions are not isolated quality incidents. They reflect an intensifying compliance environment in which safety certification, component integrity, and production consistency are becoming strategic liabilities for manufacturers that underinvest in quality control.
Riding Gear Market
At the same time, the product frontier is shifting toward material innovation and sustainability. In late 2025, Dainese introduced a new line of eco-friendly motorcycle gear built from sustainable materials, signaling that environmental performance is moving from peripheral branding to core product architecture. Broader 2026 industry analysis reports a rising trend toward recycled membranes and biobased textiles in technical motorcycle gear, suggesting that material sourcing decisions will increasingly influence both cost structures and product differentiation.
Trade show activity reinforces the sense that the market is actively re-inventing itself. At EICMA 2025, multiple companies presented new motorcycle gear lines and apparel concepts. Klim showcased all-new protection and redesigned GORE-TEX gear alongside adventure and touring offerings with an integrated armor package. Bajwa Vision exhibited premium riding apparel and safety-compliant gear, while A-PRO SRL presented motorcycle clothing concepts. These live product disclosures indicate that innovation pipelines are active across both premium and mid-tier segments, and that companies are preparing for a period in which protection performance, weather management, and comfort are being redesigned in tandem.
Strategic Implications for 2026 Decision Makers
Taken together, the trajectory, competitive structure, and emerging dynamics point to several priorities for leadership teams operating in this space during 2026.
Motorcycle Gear Market
- Align product portfolio decisions with category-level momentum rather than relying on aggregate market narratives, especially as certain product types and application contexts demonstrate stronger recovery potential than others.
- Strengthen quality assurance and compliance readiness across helmet and protective categories, given the heightened regulatory attention and the financial and reputational risk associated with certification failures.
- Incorporate material innovation into near-term sourcing and design planning, as recycled membranes and biobased textiles are becoming relevant not only to sustainability messaging but also to differentiation and long-term cost strategy.
- Evaluate regional demand behavior with operational granularity, since market expansion will not unfold uniformly and inventory deployment, channel focus, and pricing strategy should reflect local rider profiles and purchasing conditions.
- Benchmark competitive positioning against both scaled incumbents and specialized challengers, recognizing that the 2026 environment rewards companies that can combine protection credibility with targeted product storytelling and agile line development.
These implications are not theoretical. They are the practical consequences of a market that has just emerged from contraction and is now entering a forecasted growth cycle with new regulatory, material, and competitive conditions. Companies that treat 2026 as a planning year rather than a reactive year will be far better positioned to convert growth into durable advantage.
Why This Report Matters Now
Market research is most valuable when it reduces uncertainty at the exact moment decisions are being made. This report is designed for that purpose. It gives executives a structured view of how the motorcycle gear market has behaved, how it is projected to evolve through 2032, and what competitive and regulatory forces are actively reshaping product strategy. More importantly, it translates those insights into a decision-ready framework that can inform portfolio planning, sourcing commitments, compliance investment, and regional expansion logic.
The full study goes further still. It provides the detailed segmentation context, comparative competitive profiling, and forward-looking scenario framing that leadership teams need to move from awareness to action. If your organization is preparing product launches, reassessing channel strategy, evaluating supplier relationships, or building a defensible position ahead of the next growth phase, the complete report offers the depth required to make those choices with confidence.
The market trajectory is becoming clearer. The strategic window is open now. For the full segmentation detail, competitive analysis, and 2026-2032 forecast intelligence that supports high-stakes decisions, access the complete Motorcycle Gear Market research report and turn market visibility into operational advantage.
For detailed analysis of this topic, please visit the official page: Motorcycle Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intranasal Drug Delivery Market to Hit $3.4B by 2032 at 8.98% CAGR
By PW Consulting, 2026-09-07
The Strategic Imperative: Navigating the Intranasal Drug Delivery Devices Market in 2026
The pharmaceutical landscape is undergoing a profound transformation, driven by the need for patient-centric administration routes that balance efficacy, compliance, and speed of onset. Among these, intranasal drug delivery has emerged as a critical modality, bridging the gap between systemic treatment and direct nose-to-brain pathways. As we stand in 2026, the market for intranasal drug delivery devices is not merely growing; it is evolving in complexity, demanding strategic foresight from stakeholders across the value chain. This article serves as a precursor to PW Consulting's comprehensive market research report, designed to equip executive teams, R&D directors, and investors with the analytical framework necessary to capitalize on the opportunities defining this sector.
Preclinical Toxicology Service Market
Understanding the trajectory of this market requires more than a superficial glance at headline figures. It demands a nuanced appreciation of how technological innovation, regulatory shifts, and clinical adoption patterns converge to create value. PW Consulting's latest study offers a deep dive into these dynamics, providing the intelligence needed to make informed decisions in a competitive environment. The following analysis highlights the strategic dimensions of the market and outlines the operational insights contained within our full report.
Car First Aid Kit Market
Market Trajectory and Growth Dynamics
The financial trajectory of the intranasal drug delivery devices market reflects a robust compound annual growth rate, signaling sustained investor and developer confidence. Based on historical data spanning from 2020 through 2025, the market has demonstrated consistent expansion, moving from a baseline position of approximately 1,224.29 million USD to reach an estimated 1,882.0 million USD in 2025. This historical performance sets a strong foundation for the forecast period extending through 2032.
Power Data Loggers Market
Looking forward, the market is projected to accelerate, with the overall revenue expected to climb significantly by the end of the forecast horizon. The growth rate, quantified at a CAGR of 8.98 percent, indicates that the sector is outpacing many traditional pharmaceutical delivery segments. This expansion is fueled by the increasing prevalence of chronic conditions requiring rapid intervention, such as migraine and seizure disorders, alongside the expanding utility of nasal delivery for vaccines and opioid reversal agents.
For strategic planners, this growth rate suggests a widening total addressable market. However, raw growth figures only tell part of the story. The value creation is distributed unevenly across different device types, therapeutic applications, and geographic regions. Our report dissects these macro trends to reveal where value is being generated most efficiently, allowing companies to prioritize high-yield segments without exposing sensitive granular data prematurely. The shift from early-stage adoption to mainstream integration is evident, particularly as key regulatory milestones pave the way for broader commercial deployment of intranasal systems.
Technological Segmentation and Device Innovation
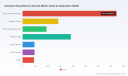
The intranasal delivery ecosystem is characterized by a diverse array of device architectures, each tailored to specific formulation requirements and clinical use cases. The market is broadly segmented into distinct system types, including multi-dose systems, unit-dose systems, and other specialized configurations. Multi-dose systems currently represent a significant portion of the market landscape, favored for their cost-efficiency and convenience in chronic management scenarios. Unit-dose systems, conversely, are gaining traction in emergency and acute care settings where precise, single-use administration is critical.
Beyond the dosing architecture, the technology landscape is defined by the mechanical and physical delivery mechanisms. Manufacturers are increasingly focusing on spray pumps, mucosal atomization devices, and dry powder inhalers. Each technology offers distinct advantages regarding drug deposition, particle size distribution, and ease of use. For instance, atomization technology has proven vital for mucosal delivery where rapid absorption is required, while dry powder systems are opening new avenues for biologic stability and nose-to-brain targeting.
PW Consulting's analysis delves into the technical specifications and performance metrics of these device categories. We evaluate the trade-offs between usability, dosing accuracy, and manufacturing complexity. This technical granularity is essential for pharmaceutical partners selecting a delivery platform for their drug candidates and for device manufacturers seeking to differentiate their portfolios. The report provides a comparative assessment of leading technologies, highlighting the innovation curves that will define competitive advantage over the next decade.
Therapeutic Applications and Clinical Drivers
The demand for intranasal drug delivery is inextricably linked to the therapeutic areas it serves. The market is segmented across a range of clinical indications, each with its own growth dynamics and adoption barriers. Allergy and nasal conditions remain a foundational segment, leveraging the established convenience of nasal sprays for local treatment. However, the most dynamic growth is occurring in systemic and central nervous system applications.
Migraine rescue represents a high-value segment, driven by the need for rapid onset of action that oral formulations often cannot match. Similarly, the use of intranasal devices for opioid overdose reversal has gained critical importance in public health strategies, necessitating reliable and accessible delivery mechanisms. Beyond these acute interventions, the market is seeing exploration in CNS and psychiatric applications, where the potential for nose-to-brain delivery offers a promising route to bypass the blood-brain barrier.
Other significant areas include seizure rescue, where speed is paramount, and the emerging field of nasal vaccines, which presents novel opportunities for immunization campaigns. The report provides a detailed mapping of these applications, analyzing the clinical evidence supporting device adoption and the commercial potential of each indication. By understanding the specific drivers and constraints within each therapeutic area, stakeholders can align their development pipelines with the segments offering the highest return on investment.
Competitive Landscape and Strategic Positioning
The competitive environment in the intranasal drug delivery devices market is defined by a mix of established device manufacturers and specialized players with deep technical expertise. Market concentration metrics indicate a moderately consolidated landscape, with the top players commanding significant market share. This concentration underscores the importance of scale, regulatory experience, and proprietary technology in securing a leading position.
Aptar Pharma stands out as a leading manufacturer with a comprehensive portfolio encompassing single-dose, two-dose, and multi-dose nasal spray pumps for both liquid and powder formulations. Their ongoing engagement in clinical trials, such as the recent utilization of their delivery system in a Phase II study for the SPONTAN nasal spray, highlights their role in advancing novel therapies. Similarly, Teleflex provides essential tools like the MAD Nasal Intranasal Mucosal Atomization Device, serving critical care and emergency settings.
European manufacturers also play a pivotal role. Bespak specializes in nasal drug-device combinations, including multi-dose aqueous sprays and unit-dose NasaDose systems. Nemera offers innovative platforms such as DryPowder and DriDose, expanding capabilities for nose-to-brain applications and forming new partnerships to broaden their portfolio. In the CDMO space, Hovione has emerged as an integrated partner offering API-to-device solutions, including single-use nasal dry powder devices, with recent announcements regarding commercial partnership availability.
Other key contributors include Silgan Dispensing, known for systems like the Gemini BE Nasal Pump and Monodose systems, and Kindeva Drug Delivery, which supports nasal MDI and spray combination products. Aero Pump continues to provide precision spray pumps for specialized applications. The landscape is further dynamic with new entrants and product launches, such as Zeteo Biomedical's introduction of ZTech-P Cygnus devices for precise metered-unit dosing of dry powder drugs and biologics.
Our report includes detailed company profiles, analyzing the strategic initiatives, recent developments, and market positioning of these key players. We examine how partnerships, platform expansions, and clinical validations are reshaping the competitive hierarchy. For instance, recent collaborations, such as the partnership between Nemera and Therakind to expand the DriDose platform, illustrate the trend toward ecosystem building and technology licensing. Understanding these moves is crucial for benchmarking and identifying potential partners or acquisition targets.
Regulatory and Reimbursement Ecosystem
Navigating the regulatory environment is a prerequisite for market entry and success. The classification and clearance pathways for intranasal devices significantly influence development timelines and costs. Devices for intranasal drug delivery are often classified under specific regulatory frameworks, with many falling under Class I categorization with 510(k) exemption in certain cases. However, the regulatory landscape is nuanced, with the FDA having approved multiple devices and systems under 510(k) clearance, including nasal spray pumps and mucosal atomizers.
Recent approvals and labeling updates further illustrate the evolving regulatory stance. Updated labeling for products such as epinephrine nasal sprays and naloxone nasal spray configurations signals increased acceptance and standardization of intranasal modalities. These regulatory milestones reduce uncertainty and encourage investment in device development. Nevertheless, manufacturers must remain vigilant about compliance requirements and classification nuances, which can vary based on device functionality and intended use.
Reimbursement policies constitute another critical pillar of market viability. In the United States, reimbursement policies for intranasal drug delivery devices are supported for approved nasal spray products and devices used in clinical settings. This support helps drive adoption in healthcare facilities and encourages prescription by clinicians. However, reimbursement dynamics can be complex, involving payer negotiations and coverage determinations that vary by indication and device type. Our analysis explores the reimbursement landscape, identifying the policy drivers that facilitate market access and the gaps that may pose challenges for new entrants.
Strategic Recommendations for 2026 Decision Makers
As we move through 2026, the strategic priorities for companies operating in this market must be aligned with the evolving realities of the sector. First, technological differentiation is paramount. With a robust growth rate and increasing competition, relying on commoditized device designs will erode margins and market position. Investment in novel delivery mechanisms, such as advanced dry powder systems or precision atomizers, offers a pathway to value creation. Companies should evaluate their R&D pipelines against the emerging needs of therapeutic areas like nose-to-brain delivery and biologic stabilization.
Second, strategic partnerships will be a key enabler of growth. The ecosystem is characterized by collaborations between device manufacturers, CDMOs, and pharmaceutical developers. Access to integrated platforms that offer API-to-device solutions can accelerate development cycles and reduce time-to-market. For device manufacturers, forming alliances with innovators in high-growth therapeutic segments can secure volume commitments and expand reach. For pharmaceutical companies, selecting a delivery partner with a proven track record and regulatory expertise is essential to mitigate development risk.
Third, market entry strategies must be informed by a detailed understanding of regional dynamics and concentration trends. While certain regions currently dominate in terms of revenue, emerging markets present untapped potential. Companies should assess the relative attractiveness of different geographies, considering factors such as regulatory maturity, reimbursement infrastructure, and local competitive intensity. The report provides the geographic intelligence needed to prioritize expansion efforts effectively.
Finally, keeping abreast of regulatory changes is non-negotiable. The FDA's ongoing approvals and labeling updates create opportunities for devices that align with current standards. Companies must proactively engage with regulatory bodies and monitor classification databases to ensure their products remain compliant and competitive. The report includes a comprehensive review of the regulatory environment, offering actionable insights for navigating approvals and maintaining market access.
Conclusion: Access the Full Intelligence
The intranasal drug delivery devices market represents a convergence of innovation, clinical need, and growth potential. The data indicates a strong upward trajectory, supported by a CAGR that outperforms many adjacent sectors and a broadening scope of therapeutic applications. However, capturing the value within this market requires more than a general understanding of growth trends. It demands precise, actionable insights into segmentation dynamics, competitive maneuvers, technological benchmarks, and regulatory pathways.
PW Consulting's full market research report offers a definitive resource for stakeholders seeking to navigate this complex landscape. The study provides detailed segmentation analysis, comprehensive company profiles, and forward-looking strategic assessments that go beyond the high-level overview presented here. By accessing the complete report, decision makers can obtain the granular intelligence necessary to formulate robust strategies, identify partnership opportunities, and optimize investment decisions for the forecast period through 2032.
To secure the competitive edge required in 2026 and beyond, we invite you to explore the full depth of our analysis. The detailed market size projections, segmentation splits, and competitive intelligence contained within the report are designed to support your strategic planning with accuracy and depth. Visit our source webpage to access the complete market intelligence and empower your organization with the insights needed to lead in the intranasal drug delivery devices market.
For detailed analysis of this topic, please visit the official page: Intranasal Drug Delivery Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
E-Liquids Market to Hit $2.47B by 2032, PW Consulting Reports 12.58% CAGR Growth
By PW Consulting, 2026-09-07
E-Liquids Market 2026: Strategic Intelligence for Navigating Growth, Regulation, and Consolidation
A Strategic Preview of PW Consulting's Latest Market Research
The global e-liquids market stands at a pivotal inflection point. As consumer preferences shift, regulatory frameworks tighten, and industrial capacity expands, the stakes for strategic decision-makers have never been higher. At PW Consulting, we recognize that navigating this complex landscape requires more than surface-level data; it demands a nuanced understanding of market mechanics, competitive dynamics, and future trajectories. Our newly released market research report on the E-Liquids Market offers precisely that depth. This article serves as a strategic preview, outlining the report's value proposition, high-level market architecture, and the critical intelligence it provides to executives operating in 2026 and beyond. The goal is not to disclose every figure, but to demonstrate the rigor and actionable insight that await those who delve into the full study.
Freeze-Dried Peaches Market
Macro Market Trajectory: Sustained Expansion in a Maturing Category
Over the past half-decade, the e-liquids sector has demonstrated remarkable resilience and growth. Historical data from the base year 2025 reveals a market that has consistently expanded its revenue base, moving from approximately $630 million in 2020 to a reported $1.125 billion by 2025. This progression underscores a compound annual growth pattern that reflects both increasing consumer adoption and the maturation of distribution channels. However, the true strategic significance lies in the forward-looking projections. Our forecast model, extending through 2032, indicates that the market is positioned to reach approximately $2.47 billion by the end of the forecast period. This trajectory implies a robust CAGR of 12.58 percent over the 2026 to 2032 window.
Glass Ionomer Cement for Filling Market
For corporate strategists, such numbers are not merely headline figures; they signal the velocity of opportunity. A growth rate exceeding twelve percent suggests that the category is still expanding faster than many mature consumer goods segments, yet the increasing market concentration and regulatory scrutiny hint at a landscape where structural advantages will dictate long-term winners. Our report dissects these macro trends without reducing them to simplistic extrapolations. We integrate historical performance, current demand drivers, and forward-looking scenario modeling to provide a comprehensive view of how the market will evolve across different economic and regulatory environments.
EMF Personal Protection Systems Market
Structural Dynamics: Regional Diversity and Product Segmentation
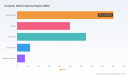
The e-liquids market is inherently fragmented by geography and product architecture, yet our analysis reveals underlying patterns that drive strategic allocation decisions. Regional performance varies significantly, with certain markets exhibiting established demand bases while others represent high-growth frontiers. Our segmentation framework captures these disparities, offering executives a clear lens through which to evaluate market entry, expansion, or consolidation strategies. Rather than presenting static splits, the report contextualizes regional revenue contributions within broader consumption trends, regulatory maturity, and supply chain accessibility.
On the product side, the market divides into distinct formats and flavor architectures that cater to divergent consumer behaviors. Pre-filled and bottled e-liquids represent substantial portions of total revenue, with each format responding to different usage occasions and distribution models. Flavor segmentation further complicates the picture, as tobacco, fruit, menthol, and other variants command varying levels of preference across demographics and jurisdictions. The strategic implication is clear: a one-size-fits-all approach is suboptimal. Companies must understand which segments offer sustainable margins, which are subject to regulatory headwinds, and how portfolio allocation can mitigate volatility. Our report maps these segmentation dynamics in granular detail, enabling readers to identify where their specific capabilities align with market demand.
Competitive Landscape: Concentration, Incumbency, and Emerging Players
Market concentration in the e-liquids sector is a defining characteristic. With the top three players collectively commanding approximately 62 percent of revenue and the top five accounting for roughly 78 percent, the industry exhibits a high degree of consolidation. This concentration has profound implications for pricing power, supply chain leverage, and barriers to entry. Incumbent tobacco giants, established vape manufacturers, and specialized liquid producers all compete within this ecosystem, but their strategic positions differ markedly.
Major corporations such as Philip Morris International, British American Tobacco, Imperial Brands, and Japan Tobacco International leverage their broader smoke-free portfolios to integrate e-liquids into wider product ecosystems. These players bring scale, regulatory experience, and global distribution networks, yet they also face internal portfolio balancing acts as they transition away from traditional combustibles. Meanwhile, companies like JUUL Labs, Logic Technology Development, NJOY, Hangsen, Vape Base, Ruthless Vapor, and Mister-E-Liquid represent a diverse spectrum of specialized operators. Some focus on proprietary pod systems, others on OEM/ODM manufacturing at scale, and still others on premium artisanal formulations. Each archetype faces distinct competitive pressures and growth levers.
Our report profiles these key companies in depth, analyzing their product architectures, geographic footprints, manufacturing capabilities, and strategic positioning. The objective is not to rank them simplistically but to illuminate the structural dynamics that shape competitive interactions. Readers will gain insights into how different players navigate regulatory approval pathways, manage flavor portfolios, and differentiate on quality or cost. This competitive intelligence is essential for benchmarking, partnership evaluation, and long-term positioning.
Regulatory Environment: Navigating Compliance as a Strategic Imperative
Few forces shape the e-liquids market as decisively as regulation. As of mid-2026, the regulatory landscape in key markets has become both more structured and more demanding. In the United States, the FDA has authorized a limited set of ENDS products for legal marketing, creating a tightly controlled environment where compliance is a prerequisite for market access. The agency's authorization of specific tobacco-flavored products and, more recently, non-tobacco and non-menthol flavored pod systems, signals an evolving approach that balances public health objectives with market realities. For manufacturers and distributors, understanding the authorization pipeline, submission requirements, and enforcement trends is no longer optional; it is a core component of strategic planning.
Across the Atlantic, the United Kingdom has introduced a new Vaping Products Duty, imposing a per-milliliter levy on all vaping liquids. This tax framework alters cost structures and Pricing strategies, requiring companies to reassess margin expectations and consumer price sensitivity. Simultaneously, state-level actions in the U.S., such as Virginia's certification and revenue collection mechanisms for liquid nicotine products, and Arkansas's compliance directory rules with penalties for non-compliance, illustrate a patchwork of jurisdictional requirements that demand meticulous operational oversight.
These regulatory developments are not isolated events; they are part of a broader trajectory toward greater oversight, traceability, and fiscal intervention. Our report integrates regulatory analysis directly into market dynamics, explaining how compliance costs, authorization timelines, and tax structures influence market entry decisions, product formulation, and regional prioritization. Executives who anticipate regulatory shifts rather than react to them will be better positioned to protect margins and maintain market continuity.
Recent Developments: Capacity Expansion, Trade Activity, and Authorization Milestones
The months leading into 2026 have produced several noteworthy developments that underscore the market's dynamism. In February 2026, VPZ announced a multi-million-pound investment to expand e-liquid manufacturing capacity and launch new retail locations, signaling confidence in sustained demand and a desire to capture greater market share through scaled operations. This type of capacity expansion reflects a broader industry trend where leading operators are investing in production infrastructure to meet growing order volumes and improve supply chain resilience.
In April 2026, the Total Product Expo featured a dedicated e-liquids and vapes category, highlighting robust commercial activity among independent retailers. Such trade events serve as barometers of industry health, revealing which product formats, flavors, and business models are resonating with downstream partners. The intensity of activity at these exhibitions often correlates with regional demand trends and the effectiveness of distributor networks.
On the regulatory front, May 2026 saw the FDA authorize the marketing of four Glas ENDS products featuring e-liquid pods with non-tobacco and non-menthol flavors. This authorization represents a significant milestone, expanding the palette of legally marketable flavor profiles and potentially opening new consumer segments. It also reinforces the importance of rigorous product development and submission processes for companies seeking to introduce differentiated offerings. Together, these developments illustrate a market where investment, commerce, and regulation are intertwining to shape competitive outcomes.
What the Full Report Delivers: Operational Intelligence for Decision-Makers
Beyond the macro narrative and headline trends, PW Consulting's E-Liquids Market report is designed as a practical decision-support tool. The study provides a comprehensive suite of analytical modules that translate data into strategy. These include detailed market sizing and forecast tables across multiple dimensions, scenario-based projections that account for regulatory and economic variables, and segmentation breakdowns that isolate growth drivers within specific product and regional categories.
The report also features extensive competitive profiling, mapping the capabilities, product lines, and strategic moves of key players across the value chain. Supply chain and distribution analysis are integrated to help readers understand how products move from manufacturing facilities to end consumers, where bottlenecks may emerge, and which logistical models offer cost advantages. Regulatory tracking and compliance frameworks are embedded throughout, ensuring that market forecasts are grounded in the realities of authorization pathways, tax structures, and jurisdictional requirements.
For strategic planners, the report offers actionable frameworks for market entry, portfolio optimization, M&A target identification, and capacity planning. By combining historical context, current market intelligence, and forward-looking projections, the study enables organizations to stress-test assumptions, prioritize investments, and align operational strategies with market realities. The depth of coverage ensures that readers do not simply observe trends but can act on them with confidence.
How to Use This Research in 2026 Strategic Planning
The strategic value of this report lies in its applicability across multiple functional domains. For senior leadership, the macro forecasts and segmentation insights support capital allocation decisions, helping identify which markets and product categories warrant investment versus restructuring. For commercial teams, the competitive profiles and regional demand patterns inform pricing strategies, distribution partnerships, and product positioning. For regulatory and compliance officers, the integrated analysis of FDA authorizations, UK duty structures, and state-level certification requirements provides a roadmap for maintaining market access while managing risk.
The report also serves as a valuable input for scenario planning. Given the market's sensitivity to regulatory changes, flavor preferences, and taxation, organizations benefit from frameworks that test how different outcomes affect revenue, margins, and competitive positioning. Our forecasting methodology incorporates these variables, allowing readers to evaluate best-case, base-case, and stress-case scenarios with discipline and clarity. This approach ensures that strategy is robust rather than brittle, capable of adapting as the environment evolves.
Conclusion: Gaining the Full Picture
The e-liquids market in 2026 presents a compelling mix of growth opportunity and strategic complexity. Market size projections suggest sustained expansion, regulatory frameworks are crystallizing around compliance and fiscal measures, and competitive concentration continues to reward players with scale, differentiation, and operational excellence. Navigating this environment requires intelligence that goes beyond surface-level metrics. PW Consulting's latest market research delivers precisely that, combining rigorous data analysis with practical strategic frameworks.
To access the complete market sizing, detailed segmentation breakdowns, in-depth company profiles, and full regulatory mapping, we invite you to explore the full report. The information previewed here represents only a fraction of the intelligence contained within the study. By diving deeper, decision-makers can unlock the granular insights needed to shape product strategies, allocate resources, and position their organizations for sustainable performance in a rapidly evolving market.
For detailed analysis of this topic, please visit the official page: E-Liquids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wood Pallet Market Outlook 2025-2032, CAGR 4.58%, Revenue Reaches $19.99 Billion
By PW Consulting, 2026-09-07
Strategic Intelligence Report: Navigating the Global Wood Pallet Market in the Post-2025 Era
As global supply chains recalibrate and regulatory frameworks tighten, the wood pallet market stands at a pivotal inflection point. For executives, procurement leaders, and strategic planners operating in 2026, understanding the structural forces shaping this foundational logistics component is no longer optional—it is a prerequisite for resilient operational design. PW Consulting’s upcoming Wood Pallet Market research report delivers the analytical depth required to navigate this evolving landscape with confidence. This preview outlines the macroeconomic trajectory, competitive architecture, regulatory inflection points, and operational dynamics that will define strategic decision-making over the coming forecast horizon.
Solid Cosmetics Market
Macro Trajectory: A Market Reshaping Under Structural and Cyclical Forces
Over the past half-decade, the wood pallet sector has demonstrated steady expansion, reflecting the underlying resilience of physical distribution networks and the continued reliance on standardized, reusable木质载具 across industrial ecosystems. Historical performance from 2020 through 2025 establishes a clear upward baseline, with total market valuation advancing from approximately 11.68 billion USD in the initial baseline year to 14.61 billion USD by 2025. This trajectory underscores more than cyclical recovery; it signals an organic structural expansion driven by sustained logistics throughput, manufacturing output stabilization, and the persistence of palletized material handling as a core operational standard.
Utility Accident Prevention Signs Market
Looking forward, the forecast window extending to 2032 projects continued upward momentum, with the overarching market anticipated to approach nearly 20 billion USD by the terminal year of the projection period. The anticipated compound annual growth rate of 4.58 percent across this decade-long horizon reflects a moderate yet durable expansion profile. Such a growth cadence implies that market participants will encounter a landscape where volume expansion is balanced by margin scrutiny, where capacity deployment must align with regional demand clustering, and where raw material procurement and compliance readiness will increasingly differentiate high-performing operators from passive followers.
Night Guards Market
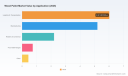
It is critical to recognize that these aggregate figures represent a synthesized view of a highly segmented ecosystem. The distribution of demand across geographic territories, material type classifications, and end-use verticals reveals distinct growth velocities and structural vulnerabilities. While regional development patterns reflect varying degrees of supply chain maturity, regulatory exposure, and industrial activity concentration, the report’s granular segmentation analysis isolates which territories and application verticals are positioning themselves as primary growth accelerators. Similarly, the breakdown of material type dynamics illuminates the ongoing tension between conventional softwood utilization and the gradual penetration of engineered and recycled alternatives, a shift that carries profound implications for capital allocation, lifecycle cost modeling, and environmental compliance strategy. Application-specific demand distribution further exposes how logistics and transportation corridors, manufacturing throughput, retail and digital commerce fulfillment, and specialized food and beverage handling channels each impose unique performance expectations on pallet specifications, turnaround cycles, and durability thresholds. Readers seeking the precise compositional breakdown, per-segment valuation mapping, and growth attribution analysis will find the complete dataset and scenario-based forecasting models exclusively in the full report.
Competitive Architecture: Consolidation, Scale, and Differentiation
The contemporary competitive landscape is characterized by a meaningful concentration of industry capacity among a cohort of established manufacturers, service-oriented recyclers, and vertically integrated packaging suppliers. With an estimated combined market share exceeding four-fifths held collectively by the top five participants, the sector exhibits pronounced scale economics, regional network density, and operational specialization. This concentration does not imply static market conditions; rather, it signals an active period of strategic realignment wherein capacity expansion, geographic footprint optimization, and service portfolio diversification are being deployed as competitive levers.
In the North American operating theater, several large-scale manufacturers have institutionalized end-to-end control over feedstock sourcing, production throughput, and post-use recovery. Organizations such as PalletOne Inc., headquartered in Bartow, Florida, have built operational models that span new pallet fabrication, recycled unit processing, custom crate engineering, and pallet repair services, effectively creating closed-loop value chains that mitigate raw material volatility while servicing broad national account portfolios. Similarly, Millwood Inc. manages an annual processing volume measured in the hundreds of millions of pallets, supplying both new and recycled units to enterprise clients and leveraging decades of engineering experience to standardize performance across high-volume distribution networks. Additional regional specialists, including Wooden Pallets LTD, which operates high-throughput facilities in Texas and Louisiana with daily production capacity exceeding fifteen thousand units, and Troymill Wood Products in Ohio, which maintains in-house heat treatment capabilities aligned with international phytosanitary standards, illustrate how localized manufacturing density and compliance-ready processing infrastructure serve as durable competitive advantages.
Across European and international markets, differentiation increasingly stems from engineering innovation, regulatory readiness, and sustainability positioning. Falkenhahn AG has positioned itself around innovative EPAL and wooden pallet solutions, aligning product design with standardized European exchange frameworks while introducing performance enhancements tailored to modern logistics requirements. PGS Group, operating from France, delivers both standard and custom wooden pallets alongside broader wooden packaging solutions, enabling clients to align pallet specifications with specialized supply chain parameters. Challenger Pallet emphasizes a sustainability-forward value proposition, offering custom, heat-treated, repaired, and remanufactured pallets while integrating new tree planting partnerships into its operational ethos. Kamps Pallets further exemplifies the operational convergence of manufacturing and recycling, pursuing enterprise-wide sustainability initiatives including Zero Waste Certification to align cost efficiency with environmental stewardship expectations.
Recent corporate activity reinforces the prevailing trend of consolidation and capability extension. UFP Industries executed acquisitions during the first half of the forecast reference period that expanded PalletOne’s northeastern footprint and further extended its pallet manufacturing network, signaling strategic intent to strengthen regional density and capture incremental share in high-throughput corridors. Concurrently, industry stakeholder organizations have secured regulatory and research milestones that reshape operational parameters. The National Wooden Pallet and Container Association successfully secured exclusion for wooden pallets from California’s newly structured Extended Producer Responsibility scheme, a development with direct implications for compliance cost structures and resource allocation. The same association was awarded a historic grant by the Pallet Foundation to advance U.S. softwoods research, an investment expected to enhance feedstock efficiency, material performance, and sustainability benchmarks across the domestic manufacturing base. Complementary industry recognition, such as the Gold Hermes Creative Award received by PalletCentral Magazine, reflects an ongoing effort to elevate industry communication standards, disseminate operational best practices, and strengthen sector-wide professional identity.
It is worth emphasizing that the full competitive assessment contained in the complete report extends beyond company-level profiles. It examines pricing architectures, service differentiation strategies, capacity utilization dynamics, vertical integration advantages, and the strategic implications of acquisition activity and partnership structures. The report further evaluates how market participants are positioning themselves relative to shifting regulatory baselines, raw material procurement strategies, and the growing relevance of circular economy frameworks within pallet lifecycle management.
Regulatory and Operational Dynamics: Compliance as a Strategic Differentiator
The operating environment for wood pallet producers, suppliers, and end-users is being redefined by an accelerating convergence of regulatory mandates, international trade requirements, and sustainability-driven procurement expectations. Compliance is no longer a peripheral administrative function; it has become a core determinant of market access, cost structure, and competitive positioning.
The European Union Deforestation Regulation represents one of the most consequential regulatory developments affecting the sector. Effective for large enterprises at the close of 2025 and scaled to apply to smaller operators by mid-2026, the regulation requires that new pallets classified under the relevant harmonized product code submit due diligence statements demonstrating deforestation-free origin. This requirement introduces a new layer of traceability, documentation, and supply chain verification that directly impacts sourcing strategies, supplier qualification processes, and cross-border trade workflows. Enterprises operating within or transshipping through European corridors must assess their preparedness to document provenance, manage compliance data, and align procurement practices with evolving due diligence expectations. Failure to do so carries not only regulatory exposure but also potential exclusion from procurement pipelines that increasingly treat compliance readiness as a baseline vendor qualification criterion.
Parallel to regional regulatory shifts, international phytosanitary standards continue to govern export-bound pallet movements. ISPM-15 compliance remains mandatory for pallets traversing international borders, requiring heat treatment and official stamping to satisfy phytosanitary requirements. Companies such as Troymill Wood Products have built operational capabilities around in-house heat treatment and export-compliant processing, illustrating how regulatory adherence can be integrated into production workflows rather than treated as an afterthought. In practice, the ability to guarantee compliance-ready output influences export reliability, reduces friction at customs inspection points, and strengthens supplier credibility within global logistics networks.
Beyond regulatory mandates, material utilization patterns and waste profiling continue to shape strategic conversations around circularity and environmental performance. Softwood lumber has historically accounted for the dominant share of lumber consumed in U.S. wooden pallet and container production, reflecting its structural suitability, availability, and cost profile. At the same time, standardized dimensions such as the 48 by 40 inch footprint have maintained persistent market dominance, reinforcing the importance of compatibility, interchangeability, and network-wide handling efficiency. From a waste and landfill perspective, industry data indicates that wood pallets represent a relatively small fraction of total wood landfilled across municipal solid waste and construction and demolition channels, a finding that supports ongoing industry positioning around reuse, repair, and recycling efficacy. These material and environmental dynamics intersect directly with procurement strategy, lifecycle cost analysis, and sustainability reporting requirements, particularly for enterprises seeking to align supplier selection with broader environmental, social, and governance objectives.
The complete report dedicates substantial analytical attention to how these regulatory and operational forces interact across regional contexts, material segments, and application verticals. It maps regulatory timelines, evaluates compliance readiness gaps, and identifies operational adjustments that can convert regulatory pressure into competitive advantage rather than cost burden.
Report Architecture and Actionable Intelligence
The Wood Pallet Market research report is structured to provide decision-makers with a comprehensive, operationally relevant intelligence framework. Rather than offering abstract market commentary, it delivers a meticulously segmented analysis supported by quantified valuation trajectories, segment-level growth attribution, and scenario-based forecasting calibrated to the projection window extending to 2032. The report is designed to serve multiple strategic functions simultaneously: market sizing for capital planning, segmentation analysis for portfolio alignment, competitive benchmarking for positioning strategy, regulatory mapping for compliance planning, and supply chain dynamics assessment for procurement and logistics optimization.
Core report components include a detailed historical reconstruction of market performance from 2020 through the base year of 2025, establishing the empirical foundation for forward-looking projections. The forecast section translates historical momentum and structural drivers into a quantified growth pathway, providing annualized and cumulative valuation expectations across the 2026 to 2032 period. Segmentation analysis disaggregates the market across geographic regions, material type classifications, and application verticals, enabling users to identify where demand concentration, growth velocity, and margin dynamics are most favorable. This segmentation framework is accompanied by interpretive guidance that contextualizes segment performance within broader macroeconomic, industrial, and regulatory trends.
The competitive landscape module profiles leading manufacturers, recyclers, and packaging specialists, examining their operational models, geographic footprints, service portfolios, and strategic positioning. This module is supplemented by a competitive dynamics assessment that evaluates concentration patterns, consolidation activity, differentiation strategies, and the implication of recent acquisitions and stakeholder milestones for future market architecture. Regulatory and compliance analysis provides a structured review of policy developments, international standards, and sustainability expectations that influence sourcing, export readiness, and procurement qualification. Industry context modules integrate raw material utilization patterns, dimensional standardization trends, and waste and recovery profiling to ground strategic analysis in operational reality.
Throughout the report, analytical outputs are designed to support concrete decision contexts: capacity expansion justification, supplier selection criteria, regional market entry evaluation, compliance investment prioritization, and sustainability strategy alignment. The objective is to equip executives with a defensible evidence base that reduces uncertainty and enhances strategic precision.
Strategic Imperatives for 2026 Decision-Making
As organizations move deeper into the forecast period, several strategic imperatives emerge for stakeholders operating in or adjacent to the wood pallet market. First, compliance preparedness must transition from reactive adjustment to proactive capability building. Regulatory frameworks, particularly those governing origin verification and export phytosanitary standards, are reshaping supplier qualification, procurement documentation, and cross-border logistics workflows. Enterprises that invest early in traceability infrastructure, compliance process integration, and supplier alignment will be better positioned to preserve market access and reduce friction in regulated corridors.
Second, competitive differentiation will increasingly depend on operational scale, network density, and service versatility. The concentration of industry capacity among a limited set of large-scale and regionally entrenched players underscores the importance of throughput efficiency, geographic coverage, and end-to-end service capabilities spanning new production, repair, recycling, and custom packaging. Organizations evaluating partnerships, procurement relationships, or capacity investments should assess not only unit pricing but also turnaround reliability, specification flexibility, and recovery infrastructure.
Third, material and sustainability dynamics will continue to influence strategic planning. The predominance of softwood feedstock, the persistence of standardized dimensional formats, and the growing relevance of recycled and engineered alternatives create a complex optimization space for procurement and product design teams. Enterprises must evaluate trade-offs among cost, performance, compliance, and environmental positioning, while recognizing that circularity initiatives, repair networks, and waste reduction outcomes can materially influence total cost of ownership and stakeholder expectations.
Finally, strategic foresight requires acknowledgment that the market’s growth trajectory, while steady, will not be uniform across regions, segments, or application channels. Companies that map growth concentration, understand segment-specific demand drivers, and align operational capabilities accordingly will be better equipped to capture incremental opportunity while mitigating exposure to slower-growth or higher-compliance-risk segments.
Conclusion
The global wood pallet market in 2026 presents a landscape defined by durable expansion, intensifying competitive realignment, and an accelerating regulatory and sustainability agenda. Aggregate market valuation trends indicate a sector moving steadily toward the threshold of twenty billion USD by the early 2030s, supported by a moderate compound annual growth rate that reflects balanced expansion rather than speculative acceleration. Beneath these headline figures lies a complex architecture of regional demand clustering, material type dynamics, application-specific performance requirements, and compliance-driven operational adjustments that demand granular, evidence-based analysis.
PW Consulting’s Wood Pallet Market research report is built to deliver that analysis. It provides the segmentation depth, competitive intelligence, regulatory mapping, and strategic context necessary to translate market complexity into actionable decision support. For executives seeking to validate capacity investments, refine procurement strategies, assess regional opportunities, or strengthen compliance readiness, the complete report offers the detailed datasets, scenario frameworks, and interpretive guidance required to act with precision.
To access the full segmentation breakdown, complete competitive profiles, regulatory timeline analysis, and forecast models, visit the source page to download the complete market research publication.
For detailed analysis of this topic, please visit the official page: Wood Pallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Motorcycle Gear Market Set for 5.6% CAGR Rebound to $27.4M by 2032
By PW Consulting, 2026-09-07
Navigating the Turn: Strategic Intelligence for the 2026 Motorcycle Gear Market
The global motorcycle gear market stands at a critical inflection point as it moves through 2026. After a period of contraction that characterized the early forecast horizon, industry dynamics are now shifting toward stabilization and renewed expansion. For stakeholders across manufacturing, distribution, and retail, understanding the nuanced interplay between regulatory pressures, sustainability mandates, and evolving rider preferences is no longer optional. It is a strategic imperative. This article serves as an executive overview of our latest comprehensive market research, designed to equip decision-makers with the contextual intelligence required to navigate the forecast period from 2026 through 2032.
Smart Seal Management Device Market
The market landscape has undergone significant recalibration over the historical review period. Revenue figures declined from 23.73 million USD in 2020 to 16.15 million USD in 2025, reflecting a complex array of macroeconomic headwinds, supply chain adjustments, and shifting consumer demand patterns. However, the trajectory is poised to reverse. The market is projected to reach 16.63 million USD in 2026, marking the beginning of a recovery phase that accelerates through the end of the decade. By 2032, total market revenue is expected to reach 27.4 million USD, driven by a compound annual growth rate of 5.6 percent over the forecast period. This structural rebound presents both opportunities and risks that demand rigorous analytical framing.
Roll-Off Garbage Trucks Market
Market Trajectory and Structural Recovery
The historical contraction observed between 2020 and 2025 was not uniform across all segments or geographies. It reflected a confluence of factors including post-pandemic demand normalization, inflationary pressures on raw material inputs, and transitional shifts in retail channels. Yet the upward inflection beginning in 2026 signals a market that is maturing rather than merely recovering. Growth will be underpinned by renewed participation in both on-road and off-road riding categories, alongside expanding safety awareness campaigns and regulatory reinforcement in key markets.
Water Resistant Paper Market
Our forecast modeling incorporates multiple scenario analyses to account for potential disruptions. The baseline projection anticipates steady year-over-year gains, with revenue climbing from 16.63 million USD in 2026 to 19.04 million USD in 2027, followed by incremental growth to 19.32 million USD in 2028 and 20.91 million USD in 2029. The acceleration becomes more pronounced as the decade progresses, with projections of 24.01 million USD by 2030, 25.74 million USD by 2031, and a terminal forecast of 27.4 million USD in 2032. This trajectory is not merely a function of volume expansion but also of value creation through premiumization, technological integration, and material innovation.
Key Drivers of the 2026–2032 Forecast Period
- Regulatory Reinforcement: Safety standards are becoming more stringent globally. Recent regulatory actions by the National Highway Traffic Safety Administration, including recalls issued in January and February 2026 for helmet models failing to meet FMVSS No. 218 impact protection standards, underscore the critical importance of compliance. Manufacturers who proactively align with evolving safety protocols will capture trust and market share, while laggards face reputational and legal exposure.
- Sustainability as a Competitive Differentiator: The industry is witnessing an accelerating shift toward recycled membranes, biobased textiles, and eco-conscious manufacturing processes. Dainese's October 2025 launch of a new line of eco-friendly motorcycle gear made from sustainable materials exemplifies this trend. Such initiatives are no longer peripheral; they are becoming central to brands' value propositions and consumer appeal.
- Trade Show Innovation and Product Cycles: Major industry gatherings such as EICMA continue to serve as bellwethers for product direction. In November 2025, multiple companies showcased next-generation lines, including Klim's all-new protection systems and redesigned GORE-TEX gear at Hall 14 booth I45, Bajwa Vision's safety-compliant riding gear at Hall 6 booth E-44, and A-PRO SRL's motorcycle clothing at Pad 10 Stand A70. These exhibitions highlight the pace of innovation and the competitive intensity that will define the forecast period.
- Material Cost Dynamics and Technical Integration: Emerging analyses for 2026 indicate a broader industry trend toward advanced technical fabrics that balance performance, durability, and environmental responsibility. Companies that can navigate material cost fluctuations while delivering superior rider protection and comfort will be best positioned to capture premium market segments.
Competitive Landscape and Strategic Positioning
The motorcycle gear market exhibits a moderately concentrated competitive structure. Our analysis indicates that the top three players command a combined market share of 44.5 percent, while the top five entities collectively hold 56.2 percent. This concentration reflects the presence of established incumbents with strong brand equity, extensive distribution networks, and deep technical expertise in protective equipment. However, the remaining market share is distributed across a diverse array of regional and niche players, creating a dynamic environment where innovation and agility can disrupt traditional hierarchies.
Several key companies define the competitive contours of this market. Alpinestars, headquartered in Asolo, Veneto, Italy, and Dainese, based in Colceresa, Vicenza, Italy, represent the Italian industrial tradition of high-performance protective apparel and remain formidable forces in both on-road and off-road segments. REV'IT! Sport International, operating from Oss, North Brabant, in the Netherlands, has built a reputation for versatile riding apparel that bridges urban commuting and touring use cases. Fox Racing, headquartered in Irvine, California, and Klim, based in Boulder, Colorado, are closely associated with off-road and adventure riding segments, where technical innovation in armor integration and weather-resistant materials is particularly pronounced.
The competitive field also includes Leatt from Cape Town, Western Cape, South Africa, which has carved a distinct position through its focus on neck protection and holistic rider safety systems. Aerostich, located in Newark, Ohio, and FLY Racing, based in Long Beach, California, contribute specialized offerings that cater to distinct rider profiles. From the Asian market, Rynox Gears, headquartered in Bangalore, Karnataka, India, represents the growing capabilities of regional manufacturers in delivering cost-competitive yet quality-assured products. European heritage brands such as Sedici and Just1, both based in Bologna, Emilia-Romagna, Italy, alongside Aether from Brooklyn, New York, and Icon Motosports from Eden Prairie, Minnesota, further illustrate the geographic diversity of the competitive landscape.
Additional notable participants include Kushitani from Ota City, Gunma, Japan, which brings precision engineering traditions to helmet and apparel design; Rukka from Iisalmi, North Savo, Finland, known for its emphasis on durability in harsh riding conditions; Sidi from Oleggio, Novara, Italy, a longstanding name in riding footwear and helmets; Held from Aalen, Baden-Württemberg, Germany, recognized for its technical textile expertise; and Spidi from Milan, Lombardy, Italy, which maintains a strong presence in rider apparel and protective accessories. Each of these companies brings distinct capabilities, regional advantages, and product philosophies that collectively shape the market's evolution.
Competitive Dynamics to Watch
- Innovation Velocity: Companies that can accelerate product development cycles while maintaining rigorous quality and safety standards will gain advantage. The showcase of new lines at EICMA 2025, including Klim's integrated armor package Rogue and Bajwa Vision's premium apparel, demonstrates the pace at which competitors are iterating.
- Regulatory Compliance as a Moat: The NHTSA recalls in early 2026 serve as a stark reminder that compliance failures can quickly erode brand credibility. Firms with robust quality assurance frameworks and proactive engagement with regulatory bodies will benefit from reduced risk and enhanced consumer trust.
- Sustainability Integration: As demonstrated by Dainese's sustainable material launch and broader industry movement toward recycled membranes and biobased textiles, environmental considerations are increasingly tied to purchasing decisions. Brands that embed sustainability into their core operations rather than treating it as a marketing afterthought will differentiate themselves.
- Geographic and Channel Diversification: The presence of manufacturers across Italy, the United States, India, Japan, Finland, Germany, South Africa, and the Netherlands reflects the global nature of the market. Strategic players are leveraging cross-regional distribution and localized product adaptations to capture demand in diverse riding cultures and regulatory environments.
Report Scope and Operational Utility
Our comprehensive market research report provides an in-depth examination of the motorcycle gear industry, structured to deliver actionable intelligence for strategic planning, investment allocation, and competitive positioning. The report integrates historical analysis, current market assessment, and forward-looking projections to create a holistic view of industry dynamics. It is designed to serve executives, product managers, supply chain leaders, and market entry strategists who require granular insight without unnecessary complexity.
The research framework covers multiple analytical dimensions. It begins with a thorough market overview that contextualizes size, growth trajectory, and structural drivers. Subsequent sections dissect the competitive environment, profiling key participants and analyzing their strategic moves, product portfolios, and market positioning. The report also examines segmentation across product categories, riding applications, and geographic regions, providing a detailed map of where value is created and how it flows through the supply chain.
Beyond static analysis, the report incorporates dynamic factors that will shape the forecast period. Regulatory developments, including recent NHTSA actions and broader safety standard evolution, are assessed for their implications on product design, compliance costs, and market access. Sustainability trends are explored not only as a consumer preference but as a supply chain and operational consideration, with attention to material innovation, manufacturing processes, and end-of-life considerations. Trade show activity and product launch patterns are analyzed as leading indicators of competitive intent and technological direction.
What Decision-Makers Will Gain
- Strategic Clarity: The report distills complex market signals into structured insights that support long-term planning. Rather than presenting isolated data points, it connects historical trends, current conditions, and future projections into a coherent narrative that informs strategic choices.
- Competitive Benchmarking: Detailed profiles of leading companies provide context for understanding competitive advantages, vulnerabilities, and potential partnership or acquisition opportunities. The concentration metrics and company analyses enable benchmarking against both direct rivals and adjacent market participants.
- Risk Assessment: By examining regulatory actions, material cost trends, and compliance requirements, the report helps organizations anticipate and mitigate risks. The inclusion of recent recall events and safety standard developments ensures that decision-makers are alert to potential disruption vectors.
- Opportunity Identification: The segmentation analysis and trend assessment highlight where growth is most likely to emerge. Whether in specific product categories, application segments, or regional markets, the report provides the analytical foundation for prioritizing investment and resource allocation.
- Forecasting Confidence: The baseline projections, supported by scenario analysis and sensitivity considerations, offer a reliable framework for financial planning and market entry decisions. The forecast period extension through 2032 allows for long-horizon strategy development.
Regional and Segment Perspectives
The market's geographic distribution reflects varied riding cultures, regulatory environments, and economic conditions across regions. North America represents a substantial share of market activity, followed by Europe and Asia Pacific. Latin America and the Middle East and Africa contribute additional demand, each with distinct growth trajectories and competitive dynamics. Our report examines these regional dimensions in detail, exploring how local factors influence product preferences, pricing structures, distribution channels, and regulatory compliance requirements.
Segmentation analysis provides further granularity. Product categories span helmets, jackets, gloves, protective gear, and other accessories, each with unique demand drivers and innovation cycles. Helmets and jackets represent significant portions of market activity, reflecting their centrality to rider safety and comfort. Gloves and specialized protective equipment address specific risk mitigation needs, while ancillary categories capture evolving consumer preferences for customization and functionality. The report analyzes these categories individually, assessing their contribution to overall market size, growth potential, and competitive intensity.
Application-based segmentation distinguishes between on-road and off-road riding contexts. On-road applications dominate market activity, driven by daily commuting, touring, and urban mobility trends. Off-road applications, while smaller in absolute terms, represent a segment characterized by high technical requirements, passionate user communities, and rapid product iteration. Understanding the nuances of each application environment is essential for companies seeking to tailor products, marketing messages, and distribution strategies to specific rider profiles.
Analytical Depth and Data Integration
- Historical Context: The report leverages historical data from 2020 through 2025 to establish baseline trends, identify cyclical patterns, and contextualize the current market position. This historical foundation supports more robust forecasting and scenario development.
- Forward Projections: The forecast period from 2026 through 2032 is modeled with attention to growth drivers, potential constraints, and external shocks. The 5.6 percent CAGR reflects a structured recovery and expansion path that is grounded in observable industry dynamics.
- Competitive Intelligence: Profiles of key companies are enriched with information on headquarters, product focus, and strategic orientation. This intelligence supports competitive analysis, partnership evaluation, and market entry planning.
- Trend Synthesis: The report synthesizes multiple trend streams, including regulatory evolution, sustainability adoption, material innovation, and trade show activity, into a cohesive assessment of where the market is headed and what it means for stakeholders.
Strategic Imperatives for 2026 and Beyond
As the market transitions from contraction to recovery, companies face a series of strategic choices that will determine their trajectory over the coming years. The first imperative is to strengthen compliance and quality assurance frameworks. The recent NHTSA recalls for helmet models that failed to meet impact protection standards illustrate the consequences of oversight. Organizations must invest in rigorous testing, transparent communication, and proactive engagement with regulatory bodies to safeguard brand integrity and market access.
The second imperative is to embed sustainability into product development and operations. The launch of eco-friendly gear by Dainese and the broader movement toward recycled membranes and biobased textiles indicate that environmental responsibility is becoming a market expectation rather than a niche preference. Companies that integrate sustainable practices into their supply chains, material selection, and manufacturing processes will not only reduce risk but also enhance brand appeal and align with evolving consumer values.
The third imperative is to accelerate innovation in protective technology and user experience. The product showcases at EICMA 2025, including Klim's new protection systems and redesigned weather-resistant gear, demonstrate the competitive value of continuous improvement. Riders increasingly expect gear that combines safety, comfort, durability, and style. Companies that can deliver on these dimensions while maintaining cost efficiency will capture premium segments and build loyalty.
The fourth imperative is to leverage competitive intelligence for strategic positioning. With a moderately concentrated market structure and a diverse field of participants, there are opportunities for differentiation through niche specialization, geographic expansion, channel optimization, and partnership formation. The report's analysis of key companies and market concentration provides a foundation for assessing where competitive pressure is highest and where whitespace opportunities may exist.
Actionable Next Steps
- Conduct Internal Benchmarking: Compare your product portfolio, compliance posture, and sustainability initiatives against the competitive landscape described in the report. Identify gaps and prioritize investments that address the most critical vulnerabilities and opportunities.
- Engage with Regulatory Trends: Monitor safety standard developments and recall patterns to anticipate compliance requirements. Proactive alignment with regulatory expectations reduces disruption risk and supports market access in key jurisdictions.
- Evaluate Material and Supply Chain Strategies: Assess the feasibility of integrating recycled membranes, biobased textiles, and other sustainable materials into your product lines. Consider the cost, performance, and brand implications of these transitions.
- Refine Market Entry and Expansion Plans: Use the regional and segmentation analyses to identify target markets, application segments, and distribution channels that align with your capabilities and strategic objectives. The forecast period provides a multi-year window for structured growth.
- Leverage Competitive Profiles: Use the company analyses to inform partnership discussions, competitive positioning, and product development priorities. Understanding the strengths and strategies of key players enables more informed decision-making.
Conclusion: The Value of Informed Strategy
The motorcycle gear market is entering a phase of renewal that will reward organizations equipped with deep market intelligence and strategic agility. The contraction of the historical period has given way to a forecast trajectory that points toward sustained growth, driven by regulatory reinforcement, sustainability adoption, technical innovation, and evolving rider expectations. The 5.6 percent CAGR projected through 2032 represents more than a statisticalexpectation; it reflects a structural shift in how the market creates value and competes for rider trust.
However, realizing the opportunities embedded in this trajectory requires more than optimism. It demands rigorous analysis, proactive risk management, and a clear understanding of competitive dynamics. The recent NHTSA recalls, the sustainability initiatives launched by leading brands, and the product innovations showcased at major trade events all signal a market that is becoming more complex, more regulated, and more competitive. Organizations that navigate this complexity with informed strategy will be best positioned to capture growth and build durable competitive advantage.
This article has provided a high-level overview of the market landscape, competitive environment, and strategic considerations that define the 2026 motorcycle gear market. It is intended to demonstrate the depth and relevance of our research while acknowledging that the full scope of intelligence requires access to the complete report. Detailed segmentation data, granular regional analyses, comprehensive company profiles, and scenario-based forecasting are available in the full publication. These elements provide the specificity and structure needed for precise strategic planning, investment decisions, and market entry execution.
We invite stakeholders to explore the complete Motorcycle Gear Market research report to gain the full complement of insights, data, and analytical frameworks that support confident decision-making. The market is evolving, and the organizations that thrive will be those that combine strategic vision with rigorous intelligence. Our report is designed to provide exactly that foundation, enabling leaders to navigate the turn with clarity and purpose.
For detailed analysis of this topic, please visit the official page: Motorcycle Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Party Supplies Market to Hit $25.3B by 2032, Driven by 8.5% CAGR
By PW Consulting, 2026-09-07
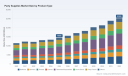
Strategic Horizon 2026: Navigating Volatility and Growth in the Global Party Supplies Market
The global consumer landscape is undergoing a profound transformation, where discretionary spending on celebrations has evolved from a post-pandemic surge into a structured, resilient economic pillar. For enterprise leaders, investors, and retail strategists, the Party Supplies Market represents a critical intersection of traditional retail dynamics, e-commerce acceleration, and complex supply chain management. As we enter 2026, the market stands at a pivotal juncture, characterized by moderate volatility in raw material costs, shifting regulatory frameworks, and a restructuring of key industry players. PW Consulting's latest comprehensive market research report is designed to cut through this noise, offering a data-driven roadmap for capital allocation and strategic planning.
Machine Downtime Monitoring Market
This introduction serves as a high-level overview of the market's trajectory, highlighting the key value drivers embedded within our full study. It is intended to demonstrate the depth of our analysis while underscoring the necessity of accessing the complete dataset for precise decision-making. The following sections outline the market size evolution, competitive restructuring, supply chain pressures, and the operational depth available in our proprietary research.
Small Animal Treats Market
Market Size Evolution and Growth Trajectory
Understanding the macroeconomic footprint of the party supplies industry is the foundational step for any strategic entry or expansion plan. Our analysis tracks historical performance from 2020 through 2025, providing a rigorous baseline before projecting forward momentum through 2032. The data indicates a resilient recovery and expansion phase, despite macroeconomic headwinds that impacted broader discretionary spending categories in recent years.
Worldwide Sevelamer Market
In 2020, the global market revenue stood at approximately 11,500.00 Million USD. This figure reflects the early pandemic environment where traditional event gatherings were restricted. However, as restrictions eased and consumer behavior adapted, the market demonstrated robust recuperation. By 2021, revenue climbed to 12,355.36 Million USD, signaling a strong rebound in social activities. The following year saw a slight contraction to 12,214.73 Million USD, a normalization phase often observed after rapid growth spikes. Yet, the underlying trend quickly resumed its upward trajectory, with 2023 recording 13,145.50 Million USD and 2024 reaching 13,413.15 Million USD.
The most recent baseline year, 2025, indicates a significant expansion to 14,500.00 Million USD. This growth sets the stage for the forecast period. Looking ahead, our models project the market to reach 15,582.86 Million USD in 2026. This progression suggests a steady compounding effect, with revenue estimates climbing to 17,061.98 Million USD by 2027, 18,260.48 Million USD by 2028, and surpassing the 20,000.00 Million USD threshold by 2029 at 20,301.07 Million USD. By the end of the forecast horizon in 2032, the market is anticipated to achieve a total revenue size of 25,300.00 Million USD.
These figures are not merely historical records; they are the basis for calculating the Compound Annual Growth Rate (CAGR) which stands at 8.5 percent over the forecast period. For strategists, this growth rate implies that the party supplies sector is outpacing many traditional consumer staples, driven by cultural shifts toward experiential living and sustained social engagement. However, accessing the full report is essential to understand how this growth is distributed across different product lines and regional markets, as aggregated data often masks critical variances in performance.
Competitive Landscape and Industry Restructuring
The party supplies ecosystem is defined by a mix of specialized manufacturers, broad-line retailers, and licensing giants. Our report provides an exhaustive profiling of key entities that shape the market dynamics. Understanding the competitive positioning of these players is vital for identifying partnership opportunities, assessing supply chain risks, and benchmarking operational efficiency.
Major Industry Players and Profiles
The market features a diverse array of corporations, each with distinct operational models. Party City Holdco Inc., headquartered in Woodcliff Lake, New Jersey, has historically been a dominant force, designing, manufacturing, and distributing party goods including balloons, tableware, decorations, and costumes under the Amscan brand. Operating as an integrated designer, manufacturer, and distributor with over 45,000 SKUs, their scale represents a benchmark for industry capacity. Similarly, New Amscan PC, LLC continues to leverage the Party City/Amscan legacy as a designer and distributor of celebration products.
In the realm of digital and licensing strategies, American Greetings Corporation provides party supplies and decorations alongside greeting products, while Hallmark Licensing LLC focuses on licensing party supplies and themed products featuring licensed characters. Artisano Designs differentiates itself by specializing in innovative party decorations and custom designs, catering to a segment that values uniqueness over mass production. Beistle Company and Unique Industries, Inc. focus on manufacturing paper products, decorations, balloons, and party essentials for retail distribution, forming the backbone of traditional physical retail supply.
Tableware and disposables remain a critical volume driver, with Chinet manufacturing disposable tableware and party serving products including plates, cups, and bowls. Oriental Trading Company provides bulk party supplies, decorations, favors, and themed products for events and businesses, serving both professional event planners and consumers. Shindigz specializes in party supplies, favors, and event decor including balloons and accessories, while Wilton Brands LLC offers party supplies, cake decorating tools, and event essentials including molds and tools.
Recent Strategic Moves and Market Shocks
The competitive landscape has been recently reshaped by significant corporate actions. In January 2025, Party City Holdco Inc. entered into a stalking horse agreement with New Amscan PC, LLC, an affiliate of Ad Populum, to sell the Party City brand and Amscan operating assets as part of a Chapter 11 process. This was followed in February 2025 by the completion of the auction and sale of the Party City brand, Amscan wholesale assets, and select lease portfolio for 20 million USD, a move aimed at preserving industry legacy amidst financial restructuring.
Beyond corporate restructuring, the broader retail environment is shifting. In April 2025, reports indicated that Amazon sellers of party supplies adjusted sourcing and pricing strategies amid new U.S. tariffs on imports, signaling cost pressures that ripple through the distribution channel. Furthermore, in September 2025, Michaels Companies expanded party supplies offerings to target specialty retail positioning, incorporating party goods alongside fabric. This move highlights a competitive retail shift where general merchandise retailers are encroaching on specialty party domains. Our full report analyzes the strategic implications of these events for market share distribution and pricing power.
Supply Chain Dynamics, Regulation, and Consumer Behavior
Strategic planning in 2026 requires a nuanced understanding of the external forces acting upon the supply chain and the regulatory environment. The party supplies market is not isolated from global geopolitical tensions, raw material volatility, or legislative changes designed to protect consumer safety.
Supply Chain Volatility and Cost Pressures
Global supply chain volatility has been a persistent challenge. Sector analysis from February 2026 indicates that raw material prices for party supplies have fluctuated up to 18 percent on a quarterly basis. This level of volatility complicates inventory management and margin forecasting for manufacturers and retailers alike. Additionally, new U.S. tariffs on Chinese-origin goods, announced in April 2025, have increased import costs for party supplies. This geopolitical factor has prompted Amazon sellers to shift sourcing and adapt pricing, creating a fragmented pricing landscape that requires sophisticated monitoring.
The retail channel itself is evolving rapidly. U.S. retail e-commerce sales reached 326.7 billion USD in Q1 2026, accounting for 16.9 percent of total retail. This infrastructure shift means that digital presence and logistics capability are no longer optional but central to market participation. Our research dissects how these channel shifts impact different product types and regional availability.
Regulatory Compliance and Safety Standards
Regulatory compliance is a critical risk factor. U.S. state statutes, such as Minnesota's lead and cadmium prohibition (Sec. 325E.3892), restrict the sale, manufacture, or distribution of children's and seasonal party supplies containing lead above 0.009 percent or cadmium above 0.0075 percent by weight. For manufacturers and importers, navigating these varying state-level regulations across the United States adds a layer of complexity to product design and sourcing. Failure to comply can result in significant liability and brand damage.
Consumer Spending Context
Despite these challenges, the underlying demand remains strong. In 2023, U.S. consumer expenditures on discretionary celebration items reached 15.4 trillion USD, with sustained growth supporting party supplies demand through 2024 and 2025. This macro-level spending power provides a robust tailwind for the industry, suggesting that even with cost pressures, the willingness to celebrate remains a priority for consumers. However, understanding how this spending translates into specific product categories requires the granular segmentation data available in our complete study.
Report Scope and Actionable Intelligence
PW Consulting's Party Supplies Market report is structured to provide immediate operational value. It goes beyond high-level estimates to offer a detailed breakdown of the market environment. The following sections outline the core components included in the full intelligence package.
- Historical and Forecast Data: Comprehensive revenue data from 2020 to 2032, allowing for trend analysis and long-term capacity planning.
- Product Type Segmentation: Detailed analysis of market share and growth rates across categories such as Balloons, Banners, Pinatas, Games, Tableware/Disposables, Home Decor, Party Favors, and Others.
- Regional Analysis: In-depth review of performance in North America, Europe, Asia Pacific, Latin America, and Mideast and Africa, highlighting regional specificities and growth drivers.
- Application Segmentation: Differentiation between Residential and Commercial applications, assessing demand volumes and pricing sensitivities in each sector.
- Competitive Benchmarking: Strategic profiles of key companies, including their recent developments, product portfolios, and market positioning.
- Market Concentration Metrics: Analysis of industry concentration levels to assess competition intensity and barrier to entry.
- Regulatory and Risk Assessment: Summarized FAQs and sector notes regarding compliance, tariffs, and supply chain risks.
While the macro trends indicate a healthy market, the real strategic advantage lies in the micro-data. Knowing exactly which product types are driving the CAGR, which regions offer the highest margin potential, and how the recent bankruptcy auctions will reshape supply density requires access to the full segmentation splits. For instance, while the overall market is growing, specific categories may be experiencing divergence due to material costs or shifting consumer preferences toward sustainability or digital integration.
Market Concentration and Structural Insights
Understanding the degree of competition is essential for new entrants and existing players alike. Our analysis includes market concentration metrics that provide visibility into the competitive intensity of the sector. The market concentration data indicates a CR3 percent of 38.2 and a CR5 percent of 52.1.
These figures suggest a moderately concentrated market where a handful of key players hold significant influence, but there remains substantial room for specialized competitors and regional players to thrive. The gap between the top three and top five players indicates that the fifth largest competitor holds a meaningful share, suggesting a competitive landscape that is not entirely oligopolistic. This structure allows for strategic maneuvering; companies can compete on niche customization, regional logistics, or specific product innovation rather than purely on scale. However, interpreting these concentration levels in the context of recent asset sales and retail expansions requires the detailed competitor analysis provided in the full report.
Conclusion: The Strategic Imperative for 2026
The Party Supplies Market in 2026 is characterized by a contradiction of robust growth and complex operational challenges. On one hand, the trajectory from 14,500.00 Million USD in 2025 to a projected 25,300.00 Million USD by 2032 offers a compelling case for investment and expansion. On the other hand, the environment is fraught with 18 percent quarterly raw material volatility, evolving tariff structures, and strict regulatory compliance requirements such as lead and cadmium restrictions.
Success in this market will not belong to those who simply observe the growth, but to those who can navigate the friction. It requires a clear view of how the recent restructuring of major brands like Party City affects supply continuity, how e-commerce growth to 16.9 percent of total retail changes customer acquisition costs, and how consumer expenditures of 15.4 trillion USD on discretionary items are actually allocated across specific party categories.
PW Consulting's comprehensive market research provides the necessary toolkit to decode these dynamics. By integrating historical performance, forward-looking forecasts, and competitive intelligence, this report enables stakeholders to make informed decisions regarding sourcing, product development, and market entry. The high-level insights presented here confirm the market's vitality, but the precise allocation of resources demands the detailed intelligence contained within the full study.
We invite industry leaders, investors, and strategic planners to utilize this overview as a foundation for deeper inquiry. The data supports a positive outlook, but the path to capturing value is paved with specific operational choices that only detailed market intelligence can illuminate. Access the complete report to unlock the segmentation specifics, regional nuances, and competitive benchmarks required to lead in the global party supplies market of 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Party Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Paraffin Wax Market Poised to Reach $14.13 Billion by 2032 at 5.6% CAGR
By PW Consulting, 2026-09-07
Unlocking Strategic Value in the Paraffin Wax Market: A 2032 Outlook
The global industrial landscape is undergoing a subtle but profound transformation, driven by the evolving utility of base materials across high-precision sectors. Among these, paraffin wax stands out as a critical component whose demand trajectory is increasingly linked to advancements in medical device manufacturing, histology, and specialized therapeutic applications. As organizations navigate the complexities of 2026 strategic planning, understanding the underlying forces shaping this market is not merely an operational necessity but a competitive imperative. This insight introduces the latest comprehensive analysis of the Paraffin Wax Market, designed to equip decision-makers with the foresight required to capitalize on emerging opportunities through 2032.
Casket Cloth Market
Recent data indicates a robust upward trajectory for the sector. The market, valued at approximately 9.65 billion USD in 2025, is projected to surpass 10 billion USD by 2026. This momentum is expected to sustain over the forecast period, culminating in a market valuation of 14.13 billion USD by 2032. Such growth, underpinned by a compound annual growth rate of 5.6 percent, signals a steady expansion that transcends cyclical volatility. However, aggregate figures only tell part of the story. The true value for enterprise strategy lies in dissecting the drivers, constraints, and competitive maneuvers that will dictate market share distribution in the coming years. Our latest research deliverable provides this granular intelligence, offering a roadmap for stakeholders to align their portfolios with high-growth vectors.
Worldwide Sublimation Ink Market
The Evolving Market Dynamics and Growth Drivers
The expansion of the paraffin wax market is not uniform; it is being reshaped by specific industry tailwinds that favor high-purity and specialized grades over commodity volumes. One of the most significant pivots observed in recent years is the increasing integration of paraffin wax into medical and laboratory ecosystems. Unlike traditional consumer applications, this segment demands rigorous adherence to quality standards, creating a barrier to entry that rewards established players with robust compliance frameworks.
Water Resistant Paper Market
A critical dynamic influencing the market is the regulatory environment surrounding medical-grade consumables. Standards such as ISO 13485 are now fundamental requirements for paraffin wax supplied for medical device consumables and histology. This regulatory layer ensures traceability and quality control, forcing manufacturers to invest in sophisticated quality assurance systems. For businesses operating in or entering this space, compliance is not just a checkbox but a strategic differentiator. Furthermore, the operational context for therapeutic applications is also shifting. Paraffin wax baths used in occupational therapy are recognized under specific OSHA guidelines as first aid heat treatments, which simplifies certain recordkeeping requirements while maintaining safety standards. This regulatory clarity supports a stable demand environment for therapeutic equipment and consumables in clinical settings.
Cost structures within the market are also evolving. Facilities utilizing medical-grade paraffin wax must invest in strict sanitization protocols, disposable liners, and routine wax replacement to ensure compliance. These operational necessities create a recurring demand stream for consumables, distinguishing the medical segment from one-off industrial uses. Additionally, the material properties of medical-grade paraffin wax, characterized by high purity, stable melting points, and excellent permeability, make it indispensable for tissue embedding and slide preparation in pathology labs. As healthcare infrastructure expands and diagnostic capabilities improve, the reliance on these high-specification materials grows, driving a consistent pull on the supply chain.
Raw material availability and refining capabilities remain foundational to market stability. Recent modernization efforts by major refining entities have focused on boosting output for high-value chemicals and specialty products, including paraffin waxes. Capacity upgrades and facility upgrades aimed at expanding production for specialty waxes used in medical device production indicate a long-term commitment from upstream suppliers to support downstream growth. These infrastructural investments are crucial for mitigating supply shocks and ensuring that the quality requirements of the medical and histological sectors are met without interruption.
Strategic Applications and Segmentation Levers
Understanding where value is generated is as important as knowing the total market size. The market is segmented by type, application, and region, each presenting unique strategic levers for manufacturers and investors. Our research delves deeply into these splits to highlight where consolidation is occurring and where pockets of growth remain underserved.
In terms of product type, the market is divided between fully refined, semi-refined, and other variants. The fully refined segment typically commands a significant share due to its suitability for applications requiring high purity, such as cosmetics and food packaging, though the medical histology sector heavily influences demand for specific refined grades. Semi-refined wax often serves industrial applications where extreme purity is less critical but cost efficiency is paramount. The strategic balance between these types depends on regional industrial capabilities and the specific mix of end-user requirements.
Application-wise, the spectrum ranges from consumer goods to highly technical industrial uses. Candles represent a traditional volume driver, but the growth premium is increasingly found in packaging and cosmetics, and most notably in medical and laboratory applications. In the medical context, the usage extends beyond direct therapeutic devices to include histology consumables for tissue embedding, sectioning, and infiltration. This application diversity means that risk is distributed across sectors; a slowdown in consumer discretionary spending on candles can be offset by steady growth in medical consumables and industrial packaging.
Regional dynamics further complicate the strategic picture. Demand is distributed across North America, Europe, Asia Pacific, and other emerging regions. Each geography presents distinct regulatory hurdles, logistics challenges, and competitive intensities. For instance, markets with stringent medical device regulations may favor established players with proven compliance histories, while developing markets might prioritize cost-effective solutions that balance quality with affordability. Our analysis maps these regional nuances to help clients identify where to allocate sales resources and where to localize production or distribution capabilities.
Competitive Landscape and Key Player Strategies
The market is characterized by a moderate concentration level, with the top three players holding a combined share of approximately 24.6 percent and the top five reaching 30.0 percent. This structure suggests a fragmented landscape below the top tier, offering ample space for niche players to compete on quality, service, or regional expertise. However, the dynamics among the key incumbents reveal a clear trend toward specialization and vertical integration in the medical and laboratory sectors.
Several key companies are defining the competitive frontier, particularly those focused on the medical and histology verticals.
- WR Medical Electronics Co. based in St. Paul, Minnesota, exemplifies the hardware-consumable ecosystem. They manufacture and distribute professional paraffin wax bath units classified as FDA Class II medical devices, alongside refill paraffin wax beads for physiotherapy and occupational therapy. Their strategy integrates device sales with recurring consumable revenue, reinforcing customer lock-in through compatibility and compliance.
- Epredia and Polysciences, Inc. represent the core histology consumables segment in the United States. Epredia supplies histology-grade and medical-grade paraffin waxes, including series like Histoplast, essential for tissue embedding and sectioning in pathology labs. Polysciences focuses on producing histology-grade paraffin wax pellets for tissue processing, catering to medical laboratory and device applications. Their offerings underscore the importance of grade specificity in driving value.
- CellPath Ltd. and Poth Hille & Co. Ltd. from the UK maintain strong positions in the European market, manufacturing and supplying histology consumables and paraffin waxes for cellular pathology and medical device-related tissue preparation. Their regional strength highlights the importance of local supply chains in meeting regulatory and delivery expectations.
- Citotest Scientific Co., Ltd. and Biosharp from China illustrate the growing influence of Asian manufacturers in the medical-grade consumables space. They produce and export medical-grade and pathology paraffin wax for hospital pathology labs and medical device consumables, often competing on price while increasingly adhering to international quality standards.
Recent developments among these and related players signal active strategic maneuvering. In May 2026, YSD Medical Equipment Co., Ltd. delivered 150 bags of medical-grade paraffin wax to a UK client for use in hospital pathology departments and third-party testing laboratories, demonstrating the cross-border flow of specialized consumables. Back in September 2025, Sinopec upgraded a refining and petrochemical project to expand capacity for specialty waxes including paraffin used in medical device production, securing upstream supply for high-value applications. Sasol expanded its micronized wax portfolio in February 2025 with new products targeting low-carbon applications, including those for medical packaging and devices, reflecting a shift toward sustainability-aligned materials. PetroChina modernized its Dalian refinery in July 2025 to boost output of high-value chemicals and specialty products, including paraffin waxes, reinforcing capacity resilience. Additionally, Therabath updated its professional paraffin wax bath product line in November 2025 with enhanced refill options meeting ISO 13485 and FDA Class II standards, highlighting the continuous product iteration required to maintain compliance and market relevance.
Comprehensive Research Coverage and Decision Support
Our latest market research report is engineered to translate these complex dynamics into actionable intelligence. It goes beyond surface-level data to provide a multi-dimensional view of the industry, enabling stakeholders to make informed capital allocation, production, and go-to-market decisions.
The report provides a detailed historical analysis covering the period from 2020 to 2025, establishing a baseline of market behavior against which future projections can be validated. This historical context is crucial for understanding how the market responded to past disruptions, regulatory changes, and economic shifts. Building on this foundation, the forecast period extending to 2032 offers a forward-looking perspective, allowing companies to model scenarios for capacity expansion, investment in R&D, and market entry strategies.
A core strength of the study is its segmentation analysis. It breaks down the market by type, application, and region, providing insights into the relative attractiveness of each segment. While aggregate market size and growth rates give the macro view, the segmentation data helps identify where margins are likely to be highest and where volume growth is most sustainable. For example, understanding the revenue contribution and growth rate of specific application segments helps manufacturers decide whether to focus on high-volume consumer goods or high-margin medical consumables. Similarly, regional segmentation assists in prioritizing distribution networks and localizing compliance efforts.
The competitive landscape section offers detailed profiles of key companies, analyzing their product offerings, strategic moves, and market positioning. This includes assessments of recent developments such as facility upgrades, product launches, and delivery agreements that signal shifts in competitive focus. By monitoring these activities, clients can anticipate competitor moves, identify potential partnerships, and benchmark their own strategies against industry leaders.
Furthermore, the report integrates industry context noise, such as regulatory updates, material cost implications, and raw material specifications, into the broader market analysis. This holistic approach ensures that factors influencing procurement, production costs, and compliance risks are not analyzed in isolation but are linked to market growth and segment performance. For instance, the requirement for strict sanitization protocols and disposable liners in medical-grade usage is factored into cost structures and demand forecasts for consumables.
Navigating the Roadmap to 2032
As the market advances toward 2032, the interplay between regulatory rigor, technological advancement in medical devices, and shifting consumer preferences in traditional segments will continue to shape the landscape. Companies that proactively align their operations with high-compliance standards, invest in specialized product grades, and maintain agile supply chains will be best positioned to capture value. The growth trajectory suggests that the market will remain a vital component of the broader industrial and healthcare ecosystems, offering sustained opportunities for those who look beyond the headline numbers.
This strategic overview serves as a prelude to the full depth of our Paraffin Wax Market research. To truly leverage these insights for 2026 decision-making, access to the complete dataset, including detailed segment splits, regional breakdowns, and granular competitive intelligence, is essential. The hidden nuances within the data hold the key to unlocking precise market entry strategies, optimal pricing models, and targeted growth initiatives. We invite stakeholders to engage with the full report to transform these macro trends into concrete competitive advantages.
For detailed analysis of this topic, please visit the official page: Paraffin Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
2032 Luxury Sunglasses Market Forecast Hits $19.78B as PW Consulting Reports 4.59% CAGR
By PW Consulting, 2026-09-07
The Luxe Lens: Navigating the 2026 Luxury Sunglasses Market with Strategic Precision
The global luxury sunglasses market stands at a pivotal intersection of heritage craftsmanship, brand prestige, and rapid structural transformation. As we move deeper into 2026, the sector is no longer defined solely by seasonal runway cycles or discretionary consumer spending. It is now shaped by macroeconomic realignment, tariff-induced supply chain recalibration, and the quiet but decisive consolidation of design houses under vertically integrated groups. At PW Consulting, we recognize that the executives navigating this landscape cannot afford broad directional narratives. They require granular, forward-looking intelligence that connects historical baselines, structural shifts, and competitive positioning into actionable strategic roadmaps. Our newly released Luxury Sunglasses Market research report is built precisely for that mandate.
PEGylation Technology Market
Drawing on our 2025 base-year analysis and a historical dataset spanning 2020 through 2025, this study projects the market trajectory through 2032. The overall revenue landscape, measured in billions of USD, traces a clear compound annual growth rate of 4.59 percent across the full forecast horizon. This expansion is neither linear nor uniformly distributed. Rather, it reflects deliberate portfolio optimization by dominant players, evolving consumer preferences across fashion and performance segments, and jurisdictional pricing dynamics that are actively reshaping margin structures. What follows is a strategic preview of how this report equips leadership teams with the analytical architecture needed to make high-conviction decisions in 2026 and beyond. The numbers shared here are directional; the complete intelligence is anchored in the full report.
Spanish Signs Market
The Arc of Growth: What the Macro Trajectory Signals for 2026 Decision-Making
Market expansion in the luxury eyewear space is rarely a story of volume alone. It is a story of value capture, brand equity leverage, and distribution discipline. The historical baseline illustrates steady revenue progression from the early 2020s through 2025, with the aggregate market reaching a meaningful scale that sets the stage for the 2026–2032 horizon. At the 2025 anchor point, total market revenue sits at a level that underscores both the resilience of premium consumer spending and the structural role of sunglasses as both functional armor and symbolic accessory. From there, the forward projection envisions continued ascent, culminating in the late 2031 to 2032 band where the market crosses into the next revenue tier.
Gallium Nitride Ultra-Thin Charger Market
For executive teams, this trajectory is not merely a backdrop. It is a planning scaffold. A sustained growth rate across a multi-year window implies that demand drivers are durable rather than cyclical spikes. It suggests that brand owners must invest in capacity alignment, assortment logic, and channel configuration well before the demand materializes. It also signals that pricing power, when executed with precision, can be sustained—but only when paired with rigorous cost management, transparent trade policy monitoring, and disciplined promotional architecture. The report translates this macro arc into scenario framing: how growth concentrates across product formats, how application demand shifts between lifestyle fashion and active-performance use cases, and where regional weighting creates both headwinds and tailwinds for sourcing, fulfillment, and localized brand building. We deliberately withhold the granular regional and application-level share breakdowns in this preview so that the complete segmentation logic, sensitivity ranges, and cross-tabulation matrices remain a proprietary asset within the full research suite.
Competitive Gravity: How the Market Structure Is Rewiring Strategic Options
No luxury category thrives without a clearly defined competitive architecture, and the luxury sunglasses market is notable for the concentration of capability among a relatively tight circle of players. Our analysis captures this through the lens of market concentration, where the top three participants command nearly half of total revenue and the top five extend that share into the mid-60 percent range. In practical terms, this means that category leadership is not fragmented across dozens of independent artisans or boutique labels alone. It is anchored by entities that combine design authority, manufacturing scale, licensed brand portfolios, and global distribution networks.
EssilorLuxottica, headquartered in Paris, exemplifies this integrated model. The group owns and manufactures iconic lines such as Ray-Ban and Oakley while also managing licensed luxury eyewear for brands including Tom Ford, Oliver Peoples, and Dolce & Gabbana. This duality—owning both mass-recognized leisure brands and high-end licensed fashion houses—gives the group remarkable portfolio breadth and the ability to cross-pollinate design language, supply chain efficiencies, and retail presence across tiers. Marcolin Group, based in Italy, operates with a similarly strategic posture, producing and distributing Tom Ford eyewear and a broader roster of designer luxury sunglasses that rely on strong fashion credibility and controlled distribution. De Rigo Rem, also Italian, manufactures and licenses luxury eyewear under the Police and Lozza names, leveraging brand heritage and specialty retail relationships to sustain premium positioning. Safilo Group continues to produce licensed luxury sunglasses, most notably for Gucci, aligning closely with fashion house calendars and brand imagery.
Alongside these large-scale operators, a distinct tier of independent and specialty craftsmanship players reinforces the category’s premium narrative. Garrett Leight, based in the United States, designs and sells handcrafted luxury sunglasses with premium materials, emphasizing material integrity, artisanal finishing, and differentiation through tactile quality rather than volume. Oliver Peoples, also U.S.-based and operating under EssilorLuxottica ownership, offers premium luxury sunglasses that marry historical design references with contemporary manufacturing standards, reinforcing the appeal of understated sophistication within the luxury segment.
For 2026 planning, the strategic implications are immediate. When concentration is high, competitive advantage often comes from portfolio orchestration rather than raw capacity. It comes from timing co-brand launches, controlling channel exclusivity, and managing the tension between accessibility and scarcity. It also comes from anticipating how rival groups respond to macro shocks. The full report maps these company profiles and their specific luxury offerings into a competitive benchmarking framework, allowing your team to compare portfolio composition, licensing dependencies, material strategies, and distribution footprints without the fragmentation that typically clouds eyewear market intelligence. The detailed competitive scoring, capability matrices, and positioning maps are included in the full study, where the analysis is calibrated for direct application to portfolio reviews and go-to-market planning.
Market Dynamics Under Pressure: Tariff Realignment, Pricing Strategy, and the Pause-Calibration Cycle
Strategic clarity in 2026 cannot be divorced from the regulatory and trade environment. The luxury sunglasses market is particularly sensitive to import structures, manufacturing geography, and duty architecture because a significant share of frames and components traverses multiple borders before final assembly, fulfillment, and retail placement. In April 2025, The Vision Council documented a substantial shift in U.S. import duties on optical products sourced from China. For sunglasses, the combined rate reached a striking 154.5 percent, aggregating base duties, Section 301 tariffs, and reciprocal duties enacted during that period. This escalation fundamentally altered the cost calculus for importers reliant on Chinese-sourced components or finished goods, forcing a rapid re-evaluation of landed cost, margin tolerance, and assortment composition.
The response from market leaders was swift and pragmatic. EssilorLuxottica, for example, implemented price increases in the U.S. market specifically to offset tariff impacts on imports originating from China and Thailand. This is not merely a pricing event; it is a strategic signal. It demonstrates how vertically integrated and portfolio-rich groups can recalibrate consumer-facing pricing while attempting to preserve brand equity and demand elasticity. It also highlights the need for scenario planning around sourcing diversification, regional fulfillment logic, and the balance between absorbing cost pressure and passing it through to end consumers.
At the same time, the trade policy landscape remains fluid. President Trump announced a 90-day pause on newly implemented country-specific reciprocal tariff increases for countries that have not retaliated, effective in April 2025. For market strategists, such pauses introduce both relief and uncertainty. They provide breathing room for supply chain reconfiguration and inventory positioning, but they also require ongoing monitoring because the pause does not reset the underlying tariff architecture for affected categories. The interplay between base duties, Section 301 measures, and reciprocal tariffs means that the effective cost of goods can shift quickly if negotiating positions evolve or retaliation dynamics change.
The full market research report integrates these dynamics into a structured analysis of the forces shaping demand, supply, pricing, and channel behavior. Rather than treating tariffs as an isolated regulatory note, we embed them within the broader dynamics section, examining how they interact with regional sourcing strategies, category pricing tiers, and the competitive positioning of brands that rely on specific manufacturing or component pathways. The objective is to give your team a framework for anticipating margin pressure, planning assortments with duty-aware logic, and evaluating which partners or sub-brands are structurally more exposed to trade volatility. As with the segmentation data, the detailed duty sensitivity analysis and region-specific implications are reserved for the complete report, ensuring that the most operationally sensitive intelligence is delivered in its full context, with the accompanying assumptions and scenario ranges.
What’s Inside: An Action-Oriented Research Architecture
Executive research is only as valuable as its usability. Our Luxury Sunglasses Market report is constructed to move beyond descriptive commentary and toward decision-ready structure. It is organized to support multiple use cases: annual strategic planning, portfolio review, competitive benchmarking, pricing and assortment optimization, and risk assessment related to trade and sourcing volatility. The architecture includes a historical baseline that contextualizes the 2020–2025 progression, an anchor analysis around the 2025 base year, and a forward projection covering 2026–2032 that extends to the late 2031 and 2032 horizon. Throughout, the narrative connects the aggregate revenue arc to the structural forces shaping category evolution.
The segmentation logic is built to reveal where demand concentrates, how product formats perform relative to each other, and how application use cases diverge in their purchasing drivers. The report examines the polarization of product types, exploring the role of polarized lenses in premium consumer preferences and the continued relevance of non-polarized offerings within specific luxury positioning strategies. It also accounts for other type categories that serve niche demands and specialty retail placements. The application analysis distinguishes between fashion-led consumption, where sunglasses function primarily as an accessory statement, and sports-oriented usage, where performance optics, frame durability, and fit become central to brand selection. A third application group captures residual demand scenarios, specialty use, and evolving categories that may gain relevance as consumer habits shift. The regional analysis frames where market activity is strongest and where growth potential is most strategically meaningful, without reducing the findings to simplistic share rankings. The complete segmentation splits—covering regional distribution, type breakdown, and application composition—are delivered in the full report with the underlying cross-tabs and scenario discussion required for precise planning.
The competitive section presents company profiles and recent developments in a format designed for strategic comparison. It maps how leading groups structure their luxury offerings, manage licensed brand relationships, and respond to category-level events. Recent developments included in the research highlight the pace and precision of strategic action. In March 2026, EssilorLuxottica extended its long-term licensing agreement with Dolce & Gabbana for the development, production, and worldwide distribution of prescription frames and sunglasses, reinforcing the strategic value of enduring brand partnerships. Also in March 2026, EssilorLuxottica unveiled the first Oliver Peoples x Jil Sander sunglasses collection, featuring titanium and acetate frames with crystal lenses, handmade in Japan—an indication of how luxury positioning is being elevated through material differentiation, limited-run craftsmanship, and designer collaboration. The same period saw EssilorLuxottica expand its AI glasses portfolio with new Ray-Ban Meta optical styles for prescription wearers, available for pre-order in the U.S., demonstrating how the company is threading wearable technology into a brand ecosystem that spans both fashion and function. The report ties these events to broader implications for portfolio strategy, brand collaboration cadence, material innovation, and premiumization pathways.
Implications for 2026 Strategic Decisions
The convergence of steady market expansion, high concentration among capable incumbents, and a volatile trade and pricing environment creates a clear mandate for 2026 strategy. Leadership teams should approach the year with five operational priorities in mind, each grounded in the analysis our report provides.
- Portfolio orchestration must be deliberate. With concentration anchored by groups that blend owned and licensed luxury brands, the ability to sequence launches, manage exclusivity, and align fashion calendars with premium demand cycles will differentiate performers from followers. The full report’s company profiles and brand-architecture analysis are intended to support portfolio gap analysis and collaboration prioritization.
- Pricing architecture requires scenario discipline. Tariff-induced cost escalation has demonstrated that pricing is not a static lever but a strategic response to supply chain structure. The research frames how major players have adjusted U.S. pricing to offset import impacts and what that implies for margin management, promotional restraint, and consumer perception.
- Sourcing and fulfillment logic must be re-examined through a duty-aware lens. The combined tariff environment for certain import pathways has reshaped landed cost assumptions. The full report’s dynamics section is designed to help teams evaluate exposure, compare sourcing pathways, and think through regional fulfillment options in a way that preserves premium positioning while protecting margin integrity.
- Product formulation should balance style statements with functional credibility. Polarized versus non-polarized preferences, along with sports-oriented performance demands, require assortment strategies that reflect the distinct drivers of fashion-led and activity-led purchase behavior. The segmentation analysis helps teams identify where intensity of demand justifies deeper investment and where niche formats warrant controlled exploration.
- Competitive monitoring must extend beyond revenue share to capability and brand leverage. Understanding which players hold licensed relationships, which emphasize handcrafted premium materials, and which are integrating technology-forward styles is essential for anticipating market moves. The report distills these capability signals into structured comparative analysis, enabling sharper positioning decisions.
Importantly, the report is not just a retrospective on where the market has been. It is a forward-looking instrument for sensitivity testing. Because the forecast period extends through 2032, leadership teams can use it to evaluate whether current investments are aligned with the pace and shape of growth, to stress-test assortment plans against changing regional and application demand, and to assess whether pricing and sourcing strategies remain robust under shifting trade conditions. The strategic value lies in the integration: macro growth, structural concentration, competitive behavior, and regulatory dynamics are not presented in isolation. They are connected so that the executive can see how a licensing extension, a material innovation, or a tariff pause might ripple through revenue potential, competitive positioning, and channel execution.
Why This Report Belongs in Your 2026 Decision Stack
In a category where brand heritage, material quality, licensed partnerships, and distribution control all contribute to premium value, information asymmetry is a competitive risk. The organizations that outperform in 2026 will be those that can translate market structure into portfolio choices, that can anticipate the margin implications of trade shifts before they become reactive pricing events, and that can read competitive moves as signals of broader strategic intent rather than isolated product launches. Our Luxury Sunglasses Market research is built to reduce that information asymmetry without oversimplifying the complexity underneath.
The report delivers a directional macro view grounded in a 2025 base year and a historical 2020–2025 trajectory, extended by a 2026–2032 forecast that maps the market toward its next revenue tier. It frames competitive concentration and company-specific luxury capabilities in a way that supports benchmarking and positioning review. It embeds the most recent trade and pricing developments into a dynamics analysis that connects regulation, sourcing exposure, and strategic response. And it keeps the most operationally sensitive data—precise regional composition, type and application share breakdowns, and detailed concentration figures—within the full research environment so that the intelligence remains actionable, protected, and ready for direct application to your planning process.
For executives who need to decide where to invest, which partnerships to extend, how to structure pricing in a duty-sensitive environment, and how to read the competitive field with confidence, this research is an essential input. The full report provides the complete segmentation detail, the full competitive benchmarking framework, the scenario ranges, and the integrated dynamics discussion that transform high-level growth trends into precise strategic guidance. Access the complete intelligence at the source page, where the full segmentation splits, company profiles, recent developments, and regulatory context are presented in their complete analytical form.
For detailed analysis of this topic, please visit the official page: Luxury Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Super Absorbent Pet Pad Market Hits $668M in 2025, Growing at 3.6% CAGR to $851M by 2032
By PW Consulting, 2026-09-07
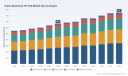
Strategic Intelligence for the Super Absorbent Pet Pad Market: Navigating Growth and Competition Through 2032
The global pet care industry has consistently demonstrated resilience and expansion, driven by deepening human-animal bonds and escalating standards of pet welfare. Within this broad landscape, the super absorbent pet pad segment represents a critical intersection of hygiene technology, material science, and consumer convenience. As we move further into 2026, understanding the nuanced trajectories of this market is no longer optional for stakeholders; it is a strategic imperative. Our latest research report, spanning historical analysis from 2020 through 2025 and a comprehensive forecast period extending to 2032, offers an unparalleled depth of insight designed to inform high-level decision-making.
Home Pet Deworming Medicine Market
This document serves as a strategic preview of that comprehensive study. It highlights the macro-economic currents, competitive pressures, and technological shifts defining the sector. While we outline the structural framework and operational utility of the full report below, specific quantitative data regarding regional performance tiers and segment-specific financial metrics have been reserved for the complete intelligence package available on our source webpage. This approach ensures that competitors do not gain asymmetrical access to the granular data required for precise strategic planning.
Worldwide External Bone Fixation Plate Market
Macro-Market Trajectory and Volume Dynamics
The super absorbent pet pad market has exhibited steady growth over the past half-decade, reflecting a compound annual growth rate that underscores consistent consumer demand. The market valuation in the base year of 2025 reached approximately 668.0 million USD. This figure represents a significant accumulation of value from the 2020 baseline of 550.0 million USD, indicating a robust expansion trajectory over the historical analysis window.
Organic Cane Sugar Market
Looking forward, our forecasting models project the market to attain a valuation of 686.12 million USD in 2026. The growth momentum is expected to continue, with projections suggesting a climb to 851.0 million USD by the end of the forecast period in 2032. This long-term outlook is anchored by a calculated CAGR of 3.6 percent. For strategic planners, this rate suggests a mature yet expanding market environment where volume growth is steady but requires operational efficiency and product differentiation to capture share effectively. The transition from the historical stability observed between 2023 and 2024 to the projected acceleration in the late 2020s implies shifting consumer preferences and potential saturation in standard categories, necessitating innovation in high-value segments.
It is important to note that while the aggregate market size provides a top-line view, the distribution of this value across geographic territories and specific product types varies significantly. The full report dissects these variations to reveal where concentration lies and where whitespace opportunities may exist. Access to the detailed segmentation revenue figures is essential for companies evaluating market entry or expansion strategies, as national-level aggregates can mask local volatility.
Structural Segmentation and Product Evolution
The market architecture is defined by distinct classifications that drive manufacturing strategies and retail offerings. Our analysis categorizes the landscape primarily by material technology, functional application, and geographic deployment. The technological divide is particularly pronounced, separating traditional standard polyacrylate solutions from advanced superabsorbent polymer enhanced variants and emerging biodegradable options.
The standard polyacrylate segment continues to hold substantial volume due to established supply chains and cost-effectiveness. However, the enhanced polymer variants are gaining traction among premium consumer segments seeking superior leakage protection and odor management. Meanwhile, biodegradable variants represent a high-growth potential niche, though they face specific headwinds related to raw material economics. Industry intelligence indicates that degradable super absorbent polymer alternatives to traditional sodium polyacrylate can carry unit prices 2 to 5 times higher than conventional materials. This cost differential raises overall pet pad selling prices and limits market penetration despite the environmental appeal, a dynamic that is critical for pricing strategy and portfolio mix decisions.
On the application side, the market is driven by training needs, housebreaking requirements, and specialized care scenarios. Training pads constitute the largest functional demand, reflecting the ongoing need for pet ownership onboarding solutions. Housebreaking pads follow as a secondary but consistent demand stream. A smaller but specialized segment involves whelping and incontinence pads, catering to specific veterinary and breeding use cases. The interplay between these applications influences inventory planning and marketing messaging. For instance, the performance metrics required for a whelping pad differ significantly from those of a standard training pad, impacting the specification of absorbency levels and grid technology.
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique regulatory environments, consumer behavior patterns, and distribution channel preferences. The full research study provides a deep dive into these regional nuances, identifying which markets are driving volume versus value and where import-export dynamics are shifting. Readers seeking to allocate capital or resources across borders must consult the detailed regional breakdown to avoid misallocation based on global averages.
Raw Material Economics and Supply Chain Sensitivity
Understanding the cost structure is vital for margin protection and pricing power. In the manufacturing of super absorbent pet pads, the super absorbent polymer (SAP) represents a significant portion of the input cost. Industry estimates suggest that SAP accounts for between 35 and 45 percent of total raw material costs. This makes the polymer the primary driver of product pricing and performance differentiation.
Fluctuations in SAP pricing or availability can have a disproportionate impact on profitability. Consequently, manufacturers are increasingly looking at long-term supply contracts and alternative material formulations to mitigate risk. The tension between cost efficiency and performance quality is a central theme in the operational section of our report. Companies that can optimize SAP usage without compromising absorbency ratings or tear resistance will possess a distinct competitive advantage. Furthermore, as environmental regulations and consumer awareness evolve, the cost implications of transitioning to sustainable materials remain a key risk factor that our analysis quantifies and contextualizes.
Competitive Landscape and Key Player Strategies
The market currently operates under a moderate concentration structure. The top three players hold a combined market share of approximately 41.5 percent, while the top five entities account for 52.8 percent of the total revenue. This indicates a landscape where dominant players retain significant influence, but there remains ample room for specialized manufacturers and regional leaders to compete on niche attributes such as customization, speed to market, or specific performance claims.
Several key companies define the current competitive dynamics. ElinTree, based in China, has positioned itself as a specialist in OEM and ODM customized pet training pads and underpads. Their offering emphasizes adjustable absorbency ranging from 500ml to 1200ml, coupled with odor control and eco-friendly materials. With CE, FDA compliance and ISO 9001 certification, they target clients requiring rigorous quality standards and customization capabilities.
Similarly, Hangzhou Haoyue Personal Care Co., Ltd leverages over 32 years of personal care production experience to supply high-quality disposable pet pads, including super absorbent puppy pads and custom underpads. Their longevity in the personal care sector provides a backbone of manufacturing reliability that appeals to bulk buyers and distributors.
Tianjin Yiyi Hygiene Products Co., Ltd is recognized as a leading manufacturer of disposable dog toilet pads. They operate large-scale production facilities focused on super absorbent, leak-proof training pads. Their strong OEM capabilities and significant US market presence make them a critical node in the supply chain for North American retailers and brands seeking reliable manufacturing partners.
On the retail and private-label side, Amazon Basics offers leak-proof, quick-dry super absorbent gel technology puppy and dog training pads. Their strategy emphasizes heavy-duty absorbent performance within a accessible price point, utilizing their massive distribution network to capture volume-driven market share. Glad for Pets complements this by producing activated carbon and standard super absorbent training pads with quick-drying and odor-locking features, maintaining a strong retail presence that reinforces brand visibility at the point of sale.
Recent developments highlight the dynamic nature of this competition. In January 2026, Consumer Reports conducted lab absorption and tear-resistance tests on 10 popular puppy pads, including super absorbent varieties. The testing identified distinct differences in performance without leakage, signaling to consumers that technical specifications matter and rewarding brands that can substantiate performance claims with independent data. More recently, in March 2026, HoneyCare launched a new lineup of dog training pads at the Global Pet Expo. This launch featured refreshed brand expression and showcased branded signage alongside super absorbent pet training pad products, indicating a trend toward premiumization and brand storytelling even within functional hygiene categories.
Our full report provides a detailed competitive benchmarking matrix that evaluates these players across multiple dimensions, including capacity, distribution reach, product portfolio breadth, and strategic moves. This level of detail is necessary for companies conducting competitor surveillance or evaluating potential partnership targets.
Regulatory Environment and Industry Standards
The regulatory framework governing pet products is evolving. While super absorbent training pads currently lack federal oversight equivalent to children's products under the CPSC or FDA, there is a clear industry movement toward standardization. ASTM International established a subcommittee on pet products (F15.05) in 2022, which has grown to include over 114 members from 10 countries. This body is developing voluntary safety standards for pet products, including pads.
The strategic implication of this development is significant. The subcommittee aims for major retailers to require compliance with these standards. For manufacturers and brands, this signals a future where certification may become a barrier to entry or a prerequisite for shelf space in key retail channels. Proactive engagement with these standards can mitigate future compliance risks and serve as a marketing differentiator. Our report analyzes the timeline and potential impact of these regulatory shifts, helping stakeholders prepare for a more formalized quality assurance landscape.
Operational Utility of the Full Research Report
This market research study is designed as a practical tool for strategic execution. It goes beyond high-level summaries to provide actionable intelligence across several functional areas. For strategy teams, the report offers a comprehensive market overview that contextualizes the super absorbent pet pad sector within the broader pet care economy. This includes historical data trends from 2020 to 2025 that establish baseline performance metrics, allowing for more accurate benchmarking of current operations against past performance.
The forecast section extends these insights through 2032, providing a long-term view that supports capital investment decisions, capacity planning, and R&D roadmapping. By understanding the projected growth trajectory and the associated CAGR, leaders can model different scenarios for market share acquisition and revenue growth. The segmentation analysis detailed in the full document allows for precise targeting. Whether a company is looking to expand into specific product types like biodegradable variants or focus on high-demand applications like training pads, the data provides the granularity needed to validate market size assumptions.
Furthermore, the competitive analysis section equips marketing and sales teams with the knowledge to position products effectively. Understanding the strengths and weaknesses of competitors like ElinTree, Amazon Basics, and Glad for Pets enables the development of counter-strategies. For example, if a competitor relies heavily on private-label distribution, a brand might emphasize direct-to-consumer engagement or specialized OEM partnerships to differentiate. The inclusion of recent developments, such as the Consumer Reports testing and HoneyCare's product launch, ensures that the intelligence is current and reflects the immediate market environment.
Supply chain managers will find value in the raw material cost analysis and the discussion on SAP dependency. Knowing that SAP constitutes 35 to 45 percent of costs highlights the need for procurement agility. The report discusses the implications of raw material price volatility and the potential trade-offs involved in switching to degradable polymers despite their higher unit costs. This information supports decisions regarding supplier diversification and inventory hedging.
Finally, the regulatory section provides a risk assessment framework. By outlining the activities of the ASTM subcommittee and the current lack of federal oversight, the report helps compliance officers and legal teams anticipate future requirements. Companies that align their quality control processes with emerging voluntary standards early may gain a first-mover advantage in securing retailer partnerships that mandate compliance.
Conclusion and Access to Deep Intelligence
The super absorbent pet pad market is poised for continued growth, driven by stable demand fundamentals and evolving product technologies. However, the path to capitalizing on this growth requires more than general market awareness. It demands precise data on regional performance, segment-specific revenue streams, and detailed competitive positioning. The macro indicators point to a market reaching 851.0 million USD by 2032, but the distribution of that value across the diverse segments and regions holds the key to strategic success.
This article has outlined the structural components, competitive players, and dynamic factors influencing the sector. It has highlighted the importance of SAP costs, the potential of biodegradable variants, and the emerging regulatory standards from ASTM. Yet, the specific percentages driving regional dominance, the exact revenue contributions of each product type, and the granular market share breakdowns remain part of the proprietary intelligence contained in the full report.
For executives, investors, and strategy professionals seeking to make informed decisions in 2026 and beyond, accessing the complete dataset is essential. The full research publication provides the necessary depth to validate assumptions, identify risks, and uncover opportunities that aggregate data cannot reveal. We invite you to visit the source webpage to obtain the comprehensive Super Absorbent Pet Pad Market research report, where the full spectrum of analysis, forecasts, and strategic recommendations is available for immediate application to your business planning.
For detailed analysis of this topic, please visit the official page: Super Absorbent Pet Pad Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glufosinate Ammonium Market to Hit $347.51M by 2032, 7.1% CAGR
By PW Consulting, 2026-09-07
Strategic Horizon for Glufosinate Ammonium: Navigating Market Dynamics and Growth Trajectories Toward 2032
The global crop protection industry stands at a pivotal juncture where chemical efficacy, regulatory shifts, and supply chain resilience converge to define competitive advantage. For stakeholders operating within the agrochemical value chain, the ability to anticipate market movement is no longer optional—it is a fundamental requirement for capital allocation, R&D prioritization, and market entry strategies. Our latest comprehensive research on the Glufosinate Ammonium Market delivers precisely this forward-looking intelligence, providing a rigorous analytical framework designed to support executive decision-making throughout the 2026–2032 forecast horizon.
Worldwide Cermet Market
This study arrives at a critical moment. Baseline valuations established in 2025 place the overall market size at approximately 215.0 USD Million, reflecting a robust trajectory from the 115.78 USD Million recorded in 2020. The compound annual growth rate (CAGR) of 7.1 percent projected across the 2026–2032 period signals sustained demand momentum, driven by expanding acreage under resistant crop varieties, evolving weed resistance patterns, and the strategic substitution of legacy chemistries. By the close of the forecast window, market revenue is anticipated to reach 347.51 USD Million, a figure that underscores both the sector’s resilience and the magnitude of opportunity for well-positioned players. Yet raw top-line projections tell only a fraction of the story. The strategic value of this research lies in its ability to decode the structural forces shaping growth, the competitive maneuvers redefining market share, and the regulatory catalysts that will alter supply-demand equilibriums in the years ahead.
Worldwide Velocity Meter Market
Decoding the Growth Catalysts and Structural Shifts
The 7.1 percent CAGR documented in this analysis is not a uniform expansion metric; it is the mathematical reflection of overlapping demand drivers, technological adoption curves, and policy-driven market adjustments. At the macro level, the transition from 181.81 USD Million in 2024 to 215.0 USD Million in 2025 demonstrates a notable acceleration, suggesting that end-user adoption cycles are shortening and that formulation innovation is unlocking new application windows. The forecast progression—from 233.71 USD Million in 2026 to 251.74 USD Million in 2027, followed by a measured 257.6 USD Million in 2028 and a strategic ramp toward 292.22 USD Million by 2029—reveals a market that is consolidating its growth base before entering a higher-velocity expansion phase. By 2030, valuations are expected to breach the 290 USD Million threshold, with subsequent years pushing toward the 320 and 347 USD Million marks. This trajectory carries significant implications for capacity planning, inventory strategy, and partnership structuring.
Bone Healing Implants Market
Several interlocking dynamics explain this upward momentum. First, the persistent challenge of herbicide-resistant weed biotypes continues to push growers toward non-selective and broad-spectrum alternatives with distinct modes of action. Glufosinate ammonium, particularly in its L-isomer formulation, has emerged as a critical tool in integrated weed management programs, especially where glyphosate-tolerant systems require rotational chemistry to preserve efficacy. Second, the expanding commercialization of glufosinate-tolerant crop traits is widening the addressable application base across multiple geographies, creating a feedback loop between trait adoption and chemical demand. Third, formulation science is steadily improving the operational profile of glufosinate-based products, enhancing rainfastness, translocation efficiency, and compatibility with adjuvants, thereby increasing grower willingness to adopt premium offerings.
Our report dissects these catalysts with granular attention to how they manifest across crop categories, application modalities, and regional deployment patterns. Rather than presenting static percentage allocations, the analysis maps the relative weight of each segment within the broader growth architecture, enabling readers to identify which crop families and usage contexts are most likely to drive incremental revenue. The methodology deliberately avoids oversimplified breakdowns, recognizing that segment performance is increasingly interdependent—shaped by cross-commodity price dynamics, seasonal pest pressures, and localized regulatory environments. This nuanced framing ensures that strategy teams can move beyond headline numbers and evaluate where to concentrate commercial resources, technical support, and supply chain investments.
Competitive Landscape: The Architecture of Market Leadership
Market concentration metrics place the industry in a state of structured consolidation. The combined market share of the top three firms sits at 35.2 percent, while the top five collectively command 42.5 percent. These figures point to an environment where scale, formulation IP, and regulatory registration portfolios confer durable advantages. Yet concentration does not imply stagnation. Behind these aggregate numbers lies a competitive ecosystem defined by differentiated positioning, geographic specialization, and targeted product development pipelines.
BASF Corporation, headquartered in Research Triangle Park, North Carolina, exemplifies the high-end formulation strategy. The company’s focus on L-Glufosinate Ammonium 211 herbicide—registered under EPA Reg. 7969-500 for non-selective weed control in cotton and other crops—reflects a commitment to L-isomer formulation technology that delivers consistent performance in demanding field conditions. In October 2024, BASF unconditionally registered this product for non-selective weed control in non-glufosinate-resistant cotton and additional crops, a move that broadens the commercial footprint of a differentiated offering and reinforces the company’s position as a global leader in isomer-specific chemistry.
On the other side of the competitive spectrum, UPL Limited, based in Mumbai, India, emphasizes operational versatility and scale-ready formulations. Its Glufosinate 280SL and technical-grade Glufosinate Ammonium offerings target post-emergence weed control in glyphosate-tolerant crops, addressing a high-volume application context where cost efficiency and reliable performance are paramount. The company’s ability to bridge technical-grade supply with formulated product distribution positions it as a key linkage point between upstream manufacturing capacity and downstream grower adoption.
The Chinese technical-grade manufacturing base represents a distinct and increasingly influential competitive layer. Shijiazhuang Richem Co., Ltd., operating from Hebei province, focuses on Glufosinate Ammonium technical grade (CAS 77182-82-2) for manufacturing and export, functioning as a critical node in global supply networks. GSP Crop Science Limited, headquartered in Ahmedabad, Gujarat, concentrates on Glufosinate Ammonium 13.5% SL formulations for broad-spectrum weed control, illustrating how domestic formulation 역량 can be leveraged to capture regional demand with cost-competitive product architectures.
Albaugh, LLC, based in Ankeny, Iowa, occupies a specialized niche focused on selective weed control in glufosinate-tolerant crops through its Glufosinate 280 SL herbicide (EPA Reg. 42750-258). This registration-specific positioning demonstrates how regulatory alignment with trait systems can create defensible commercial territories. Meanwhile, China’s leading technical-grade producers—Inner Mongolia Mingsheng, Lier Chemical, and Shandong Yisheng—command substantial production capacity and cost structures that shape global pricing benchmarks. Inner Mongolia Mingsheng, with a combined capacity approaching 100,000 t/a across leading firms in the region, and Shandong Yisheng, with a similarly scaled domestic production footprint, represent the industrial backbone of the technical-grade supply chain. Lier Chemical, operating from Sichuan province with capacity exceeding 11,000 t/a, adds further depth to the manufacturing ecosystem. Together, these producers account for 68 percent of total capacity and maintain production costs in the range of RMB 40,000–45,000 per ton, a cost discipline that directly influences export pricing, margin structures, and the competitive calculus of formulators worldwide.
The report provides a detailed competitive profiling framework that maps each entity’s strategic focus, registration portfolio, formulation technology, and geographic emphasis. By segmenting competitors along these dimensions, the analysis helps buyers, investors, and market entrants identify partnership opportunities, anticipate pricing pressure points, and evaluate where differentiation is most achievable. Rather than presenting a static leaderboard, the research constructs a dynamic view of how competitive advantages are created, defended, and eroded over the forecast period.
Regulatory Catalysts and Supply Chain Reconfiguration
Industry dynamics are increasingly defined by the intersection of regulatory updates and supply-side restructuring. Two developments in particular illustrate how policy and market behavior are converging to reshape the glufosinate ammonium landscape. In November 2025, the United States Environmental Protection Agency established tolerances for residues of glufosinate in rice and tea, effective immediately. This regulatory action expands the permissible use envelope for glufosinate-based products in crops where residue management has previously constrained application flexibility. The practical implications are significant: approved tolerance levels reduce compliance risk for growers, facilitate export market access for treated commodities, and encourage formulators to develop crop-specific recommendations that align with residue limits. The report maps the downstream effects of such regulatory decisions, including shifts in application timing, formulation selection, and market communication strategies.
On the supply and trade front, July 2025 marked a structural improvement in export clearance efficiency. The General Administration of Customs, China, implemented automated RCEP zero-tariff verification for pure L-glufosinate technical grade exports, improving clearance efficiency by over 40 percent. This policy enhancement reduces transaction friction, shortens time-to-market for export shipments, and reinforces the competitive position of Chinese technical-grade producers within regional trade frameworks. The report examines how such trade facilitation measures interact with capacity utilization rates, inventory cycles, and pricing transmission mechanisms across international markets.
Price dynamics in the technical-grade segment further illuminate the market’s structural behavior. As of May 2026, technical-grade glufosinate-ammonium prices stood at approximately RMB 46,000–47,000 per metric ton, with pure L-glufosinate commanding around RMB 65,000 per metric ton. This pricing environment emerged against a backdrop of low inventory levels—approximately 4,140–4,150 tons—combined with strong export demand. The resulting price rebound illustrates the sensitivity of the technical-grade market to inventory tightness and external demand signals. By contrast, production costs among leading Chinese producers remain anchored in the RMB 40,000–45,000 per ton range, creating a margin structure that supports continued investment in capacity optimization while maintaining export competitiveness.
These price and inventory dynamics do not operate in isolation. Stricter environmental inspections have accelerated the exit of non-compliant small and medium enterprises, concentrating production among top-tier manufacturers that can sustain compliance investments and operate at scale. The result is an oligopolistic consolidation trend that raises barriers to entry, stabilizes supply quality, and enhances the pricing influence of incumbents. The report tracks these consolidation signals, evaluates their implications for supply security, and provides scenario-based projections that help stakeholders assess how shifts in regulatory enforcement could alter the competitive map over the forecast horizon.
Report Contents: A Practical Toolkit for Strategic Execution
The research is structured to deliver actionable intelligence at multiple decision-making levels. At the strategic tier, the report provides a macro-analytical overview that connects market size progression, CAGR assumptions, and segment interdependencies into a unified narrative. This foundation enables executive teams to contextualize growth targets, evaluate market entry timing, and align capital allocation with the most resilient demand vectors. The analysis avoids superficial segment enumeration, instead presenting a structural map that clarifies how crop categories, application contexts, and regional deployment patterns interact to shape aggregate growth.
At the operational tier, the study delivers practical assessment tools for commercial and supply chain teams. Competitive profiling sections dissect the formulation strategies, registration portfolios, and geographic footprints of leading participants, including BASF Corporation, UPL Limited, Shijiazhuang Richem Co., Ltd., GSP Crop Science Limited, Albaugh, LLC, Inner Mongolia Mingsheng, Lier Chemical, and Shandong Yisheng. Each profile highlights the strategic logic behind product positioning, the role of isomer-specific or technical-grade offerings, and the implications for partnership and sourcing decisions. Recent developments—such as BASF’s October 2024 registration, the EPA’s November 2025 tolerance establishment, the July 2025 RCEP zero-tariff verification, and the May 2026 technical-grade price rebound—are incorporated into a forward-looking timeline that helps readers anticipate how regulatory and market events will cascade through pricing, availability, and adoption patterns.
Market dynamics analysis forms a central pillar of the report, synthesizing regulatory updates, cost structures, inventory conditions, and trade policy shifts into a coherent view of the operating environment. The study examines how stricter environmental enforcement has reduced the number of compliant producers, how capacity concentration among top-tier Chinese manufacturers shapes global cost benchmarks, and how trade facilitation measures alter export competitiveness. These insights are cross-referenced with segment performance indicators, enabling readers to identify which application modalities and crop contexts are most sensitive to supply-side changes and regulatory adjustments.
The forecast architecture provides scenario-based projections that connect baseline growth assumptions to plausible alternative trajectories. By modeling the interactions between trait adoption rates, weed resistance trends, regulatory tolerance updates, and supply chain capacity expansion, the report equips strategy teams with a flexible analytical toolkit. The scenarios are designed to support contingency planning, allowing stakeholders to evaluate how shifts in one variable—such as a change in residue tolerance levels or a disruption in technical-grade export clearance—could propagate through market size, pricing, and competitive positioning.
Throughout the document, the emphasis remains on decision utility. Data points are presented within analytical context, growth metrics are linked to underlying drivers, and competitive assessments are tied to strategic implications. The objective is to provide a research asset that can be directly integrated into market planning, sourcing strategy, product development prioritization, and risk assessment workflows. Detailed segment allocations, region-specific revenue figures, and granular application splits are preserved within the full report to maintain analytical rigor while ensuring that executive readers receive a clear strategic narrative.
Translating Intelligence Into Action: Strategic Imperatives for 2026 and Beyond
The glufosinate ammonium market is evolving along a trajectory that rewards strategic foresight, supply chain discipline, and regulatory fluency. For formulators, the opportunity lies in aligning product portfolios with the expanding tolerance envelope and the growing demand for isomer-specific, performance-optimized solutions. For technical-grade producers and exporters, the imperative is to navigate the interplay between cost discipline, inventory positioning, and trade facilitation gains while anticipating how consolidation trends will reshape competitive dynamics. For growers and distribution partners, the strategic task is to integrate glufosinate-based chemistries into rotational programs that preserve efficacy, manage resistance, and comply with evolving residue standards.
This research provides the analytical foundation to execute those tasks with precision. By connecting the 2025 baseline of 215.0 USD Million and the 7.1 percent CAGR to the structural forces shaping growth, the study enables stakeholders to move beyond reactive positioning and toward proactive strategy design. The competitive profiles, regulatory timelines, cost and inventory dynamics, and scenario-based forecasts collectively form a decision-support ecosystem that can be customized to specific market entry, expansion, sourcing, or investment objectives.
Detailed segment allocations, region-by-region revenue distributions, and application-specific breakdowns are available within the complete market study, where they are presented alongside the full methodological framework, data sources, and assumption documentation. This executive overview has been designed to convey the depth, rigor, and strategic relevance of the analysis while highlighting the core themes that will shape market performance through 2032. For organizations seeking to align their 2026 planning cycles with the most credible forward-looking intelligence on glufosinate ammonium, the complete report offers the comprehensive evidence base required to translate insight into actionable strategy.
For detailed analysis of this topic, please visit the official page: Glufosinate Ammonium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


