



Category: Healthy Lifestyle
PW Consulting: Whetstones Market to Rise from USD 148.5M in 2025 to USD 198.7M by 2032 at a 4.25% CAGR — North America Leads with USD 56.7M
By PW Consulting, 2026-08-05
Whetstones Market 2026: Strategic Imperatives from PW Consulting’s Whetstones Market Report
PW Consulting today publishes the Whetstones Market report, a practical, executive-grade study designed to inform board-level strategy, product roadmaps, sourcing decisions, and M&A planning for 2026. The report synthesizes five years of historical performance (2020–2025) with a seven‑year forecast (2026–2032). At the macro level, the global whetstones market reached USD 148.5 Million in 2025 and is projected to grow at a 4.25% CAGR through 2032, approaching USD 199 Million by the end of the forecast. This steady, mid-single-digit expansion underpins a set of high‑impact choices for manufacturers, distributors, and specialist retailers heading into 2026.
Whetstones Market
Why this report matters for 2026 decision‑making
- Actionable forecasting: We translate headline growth into scenario-calibrated demand curves for product families, channels, and manufacturing footprints—helping you stress-test capacity and inventory plans for the next 18 months.
- Competitive clarity without data noise: The study balances rigorous market sizing and concentration analysis with targeted qualitative insight—showing where competitive advantage is created, and deliberately holding back proprietary micro‑segmentation to drive direct engagement with PW Consulting for transaction-level intelligence.
- Regulatory and supply realism: Our modeling incorporates supply constraints, raw material dependencies, and compliance levers (including country-of-origin messaging) that materially affect brand positioning and margins in 2026.
Market dynamics shaping strategy in 2026
- Measured but resilient growth. After a period of volatility in the early 2020s, the market entered a recovery phase culminating in 2025’s USD 148.5 Million level. Continued product innovation, renewed interest from hobbyist and culinary segments, and steady industrial demand underpin the 4.25% CAGR to 2032.
- Fragmentation with scale pockets. The market remains fragmented—our concentration metrics show the top three firms account for approximately 21% of global revenue while the top five account for about 30%—creating opportunities for mid‑market consolidation and niche premium plays.
- Raw material and vertical integration risk. Natural novaculite deposits and the proprietary control of reserves remain strategic assets for specialist natural‑stone producers. Synthetic abrasives supply chains—based on aluminum oxide and silicon carbide chemistries—favor manufacturers that can secure long‑term supplier contracts or in‑house mixing capabilities.
- Regulatory and claims governance. Advertising and labeling—especially “Made in USA” assertions—are subject to FTC standards that affect premium positioning and procurement choices. Companies must align sourcing policies and documentation to avoid downstream risk and protect margin premiums.
- Channel and product innovation divergence. Two distinct innovation vectors are clear: high‑performance, precision ceramic and diamond‑coated systems for professionals and industrial users; and lower‑touch, DTC friendly starter kits and maintenance systems for hobbyists and the growing home‑cooking audience.
What the report delivers — practical content for immediate use
- Proprietary market model (2020–2032): downloadable, scenario‑driven Excel model with top‑down and bottom‑up levers for pricing, channel mix, and launch impacts.
- 90‑day tactical playbooks: product launch, premiumization, and channel rebalancing plans with measurable KPIs and resource templates.
- Supplier and resource map: strategic exposure analysis for natural and synthetic feedstocks, plus a supplier scorecard you can apply to your sourcing partners.
- Competitive battlecards: profiles and strategic implications for leading players, distribution partners, and relevant industrial buyers (customizable for M&A diligence).
- Regulatory compliance checklist: operational steps and documentation to support Made in USA claims and minimize marketing risk.
- Retail and e‑commerce optimization guide: curated recommendations for SEO, content testing (informed by recent independent product testing), and conversion levers for specialist categories.
- Risk and resilience heatmap: scenario stress tests for supply shocks, raw material price swings, and channel disruptions with mitigation playbooks.
Competitive landscape — profiles and strategic implications
The ecosystem mixes legacy stone specialists, diversified abrasives conglomerates, niche high‑performance ceramic innovators and systems players. Key firms profiled in the report include:
Whetstones Market
- Dan's Whetstone Company, Inc. (Pearcy, Arkansas, USA — https://danswhetstone.com): A vertically integrated natural‑stone specialist with quarry control and a full slate of Arkansas novaculite grades. Ownership of upstream reserves is a strategic moat that supports premium positioning—particularly where authenticity and provenance matter. Our analysis highlights scenarios where quarry control can be monetized via licensing, co‑branding, or captive supply models.
- Norton Abrasives (Saint‑Gobain) (Worcester, Massachusetts, USA — https://www.nortonabrasives.com): A diversified abrasives player with broad synthetic capabilities and industrial channel reach. Their scale in resin‑bonded and oil stones makes them a natural partner for OEMs and contract manufacturing; our sensitivity tests show they are best positioned to absorb raw material shocks.
- SHAPTON Co., Ltd. (Japan — https://shapton.co.jp/en/): Renowned for high‑performance ceramic stones targeted at demanding professional and precision segments. The company’s technical lead in ceramic abrasives creates margin and differentiation—our product roadmap section recommends how market entrants can compete by investing in adjacent performance claims and service-led bundling.
- Matsunaga Stone Co., Ltd. (King brand) (Osaka, Japan — https://matsunaga-corp.co.jp/en/): A long‑standing waterstone manufacturer with deep brand equity in household and professional culinary markets. Brand legacy and channel partnerships create a durable consumer moat, but innovation cadence will determine the degree of premium capture in the next five years.
- Work Sharp (USA — https://www.worksharptools.com): Systems‑oriented player offering bench and electric sharpening systems. Their business model shows the value of systems + consumables for lifecycle revenue—our playbooks include tactics for sharpening system producers to migrate customers to recurring consumable revenue.
- Falcon Tool Company , NORITAKE , and Gesswein : Each brings specialized niches—ruby and Degussit stones, industrial abrasives portfolios, and precision jewelry/toolmaking stones. These players illustrate a strategic truth: niche technical leadership can be scaled via channel partnerships or targeted M&A.
Recent third‑party testing and editorial coverage reinforce product differentiation trends. Independent reviews published in early 2026 (e.g., Food & Wine and Serious Eats) have continued to influence consumer purchase funnels by elevating specific premium sets and starter kits—demonstrating the tangible marketing lift that credible product testing can deliver. Dan’s Whetstone Company’s continued quarry operations in 2025 affirm the ongoing importance of feedstock control in value creation.
Whetstones Market
Strategic implications for 2026 — five prioritized moves
- Secure feedstocks or hedging arrangements. For firms reliant on natural novaculite or specialty abrasives, formal supply agreements or minority equity in quarry operations materially reduce margin volatility.
- Clarify provenance and compliance. Build audit trails and label governance to support premium Made‑in‑country claims without regulatory exposure.
- Pursue systems + consumables economics. Investments in sharpening systems or bundled service offerings can convert single‑purchase customers into recurring revenue streams.
- Segment go‑to‑market by innovation curve. Invest in ceramic and diamond technologies for professional/industrial tiers while optimizing DTC starter kits and content for hobbyist expansion.
- Evaluate consolidation targets. Given the market’s fragmentation, disciplined M&A—focused on bolt‑on technical capabilities or distribution reach—can lift scale economics rapidly.
How to act now: a 90‑day executive playbook
- Day 1–30: Download our market model and run three internal scenarios (base, upside, downside) against your 2026 budget.
- Day 31–60: Execute a supplier resilience audit—use the supplier scorecard in the report to rank vulnerability and negotiate contracts or contingencies.
- Day 61–90: Launch a pilot commercial experiment—test a bundled systems + consumable product in one region or channel, paired with product testing outreach to independent reviewers.
PW Consulting’s Whetstones Market report is designed to move strategy from conjecture to execution. The report contains detailed, proprietary segmentation tables, competitive revenue appendices, and scenario workbooks that we deliberately reserve for direct download to preserve transaction‑level confidentiality and to enable tailored advisory. For firms preparing capital allocation, channel pivots, or M&A in 2026, the report provides the evidence base and playbooks required to convert market trends into measurable business outcomes.
To access the full dataset, appendices, and our executable 90‑day playbooks, please visit the Whetstones Market report page on PW Consulting’s Whetstones Market portal. Reach out to our advisory team for customized briefings, diligence support, or M&A advisory informed by the report’s models and competitor analyses.
For detailed analysis of this topic, please visit the official page: Whetstones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Saddle Chairs Market Poised to Grow at a 5.85% CAGR Through 2032
By PW Consulting, 2026-08-05
Saddle Chairs Market: Strategic Preview for 2026 — Positioning, Risks, and Practical Playbooks
Executive summary
As enterprises and investors set budgets and channel strategies for 2026, the saddle chairs market presents a clear, measurable growth story with tactical complexity. PW Consulting’s latest market study — based on a 2025 base year and a 2026–2032 forecast horizon — finds the global market expanding at a mid-single-digit compound annual growth rate (CAGR of 5.85%). The market is already past the USD 300 million milestone in 2025 and is projected to traverse the USD 400–460 million band toward the end of the forecast. These headline metrics capture both steady demand from occupational health and rising adoption among hybrid office environments, and they frame strategic choices for manufacturers, distributors, workplace designers, and institutional buyers in 2026.
Saddle Chairs Market
Why this report matters to 2026 decision-makers
Many firms will approach 2026 with incremental product iterations and modest channel adjustments. That will be insufficient. Our research translates macro growth into three actionable decision levers that matter now:
Saddle Chairs Market
- Growth prioritization: Identify which go-to-market plays yield the highest uplift in a market growing at ~6% annually — from premium ergonomic differentiation to volume plays in industrial seating.
- Supply resilience: Convert near-term materials volatility into competitive advantage rather than cost shock, with contingency sourcing and design-for-substitution strategies.
- Customer segmentation and offering architecture: Reconfigure product portfolios around use-case bundles (e.g., saddle chairs paired with standing-desk ecosystems and healthcare-specific stool kits) to capture cross-sell and margin expansion.
Market trajectory and core demand drivers
The saddle chairs market’s trajectory is shaped by a confluence of secular and cyclical forces. Secularly, increasing awareness of ergonomic outcomes — driven by healthcare guidance and corporate wellness programs — continues to shift purchasing from ad-hoc seating to purpose-designed active-sitting solutions. Cyclically, the post-pandemic workplace transition to hybrid and activity-based layouts has lifted demand for seating that complements standing-desks and multi-posture work patterns.
Saddle Chairs Market
These dynamics manifest in three observable patterns: premiumization in professional environments (medical, dental, and design-conscious offices), steady demand in industrial and technical contexts (where durability and ESD compatibility matter), and a growing retail/SMB segment that purchases saddle seating as part of holistic ergonomic solutions. For 2026 planning, recognize that topline growth will be meaningful but will not erase the importance of disciplined unit economics and channel optimization.
Supply chain friction: material and manufacturing considerations
Operational risk has risen as a strategic variable. Our field and supplier interviews noted polyurethane foam — a key cushioning material for most saddle chair designs — experienced supply constraints in early 2026. That shortage translated into higher lead times and input-cost pressure for cushion-intensive SKUs. For managers planning 2026 sourcing and production, three pragmatic responses are essential:
- Inventory tiering: Maintain strategic safety stock for core SKUs while moving slower variants to Just-in-Time replenishment.
- Design-to-cost: Accelerate validated material substitutions and modular cushion platforms that reduce single-source exposure without degrading ergonomic performance.
- Sourcing diversification: Bring in regional secondary suppliers and qualify alternative chemistries to mitigate future shocks.
Regulatory and standards context
Saddle chairs sit within general furniture safety and material regulations — stability tests, flammability and chemical content standards, and product labelling. Our monitoring found no category-wide recalls in 2025–2026, but compliance remains non-negotiable, especially for medical and institutional sales. Buyers should demand documented test results and lifecycle safety data, while manufacturers must keep certification pipelines current to sustain institutional contracts.
Competitive landscape: who matters and why
The market features a mix of specialist ergonomic innovators, heritage design brands, and regionally focused industrial suppliers. Competitive advantage is rooted less in sheer scale and more in brand credibility with professional users, product ergonomics, and channel intimacy (dental/medical distributors, industrial OEM partnerships, and office specification channels). Key players to watch include:
- Salli Systems (Finland) — known for split-seat designs that target posture and circulation benefits; strong in professional and healthcare-focused channels.
- Score BV (Netherlands) — a factory-led manufacturer with end-to-end capabilities, active in workplace and clinical settings and visible through thought-leadership content for practitioners.
- HÅG (Flokk, Norway) — leverages iconic design lineage with chairs that support dynamic sit-stand movement and specification in modern offices.
- Humanscale (USA) — a global ergonomic brand which extends its seating portfolio with saddle-style stools emphasizing natural movement and healthcare ergonomics.
- Bambach Saddle Seat (Australia) — the original saddle-seat lineage, with a strong foothold in dental and clinical environments where spinal alignment claims matter.
- Treston (Finland) — a trusted industrial seating supplier focused on adjustable, durable saddle chairs for technical and production settings.
- Branch Furniture, ProNorth Medical, and RGP Dental — examples of regional and vertical specialists that translate ergonomic principles into market-specific products and distribution models.
Recent company activity underscores market momentum: ProNorth Medical launched a medical-focused saddle stool in late 2024 that highlights posture and productivity improvements; Score refreshed practitioner-facing content in 2025 to better articulate clinical workspace design — both moves indicating supplier efforts to own educational and specification touchpoints.
Segmentation insights without the spreadsheet
The full market is meaningfully differentiated by product type (backrest vs. backrest-free variants), application (medical/dental, office/commercial, industrial/personal), and region. Importantly for 2026 strategies, these segments do not move in lockstep. Medical and dental buyers gravitate to clinically validated designs and accessory ecosystems (armrests, foot supports, anti-microbial finishes), whereas office buyers increasingly value aesthetic integration with standing-desk systems and sustainability credentials. Industrial purchases prioritize durability, adjustability, and ESD-safe materials. Our report analyzes unit economics and margin profiles across these streams, enabling executives to prioritize SKU rationalization and channel investment without disclosing granular splits here.
Strategic playbook: recommended actions for market participants
Below are concrete strategic moves tailored to three stakeholder groups:
- Manufacturers and product teams:
- Fast-track modular platform initiatives that allow rapid configuration for medical, office, and industrial needs without separate tooling investments.
- Implement design-for-supply strategies to reduce dependency on single-source cushioning materials and shorten lead times.
- Invest in clinical validation studies and certification labeling to improve specification win rates in institutional tenders.
- Distributors and channel partners:
- Bundle saddle chairs with complementary products (standing desks, anti-fatigue mats, task-lighting) to lift average order values and deepen buyer relationships.
- Use content-led engagement (whitepapers, case studies) aimed at dentists, clinicians, and workplace ergonomists — content that Score and others are already deploying effectively.
- Build flexible inventory programs (consignment, subscription pilots) for large corporate and healthcare accounts worried about continuity of supply.
- Buyers and workplace planners:
- Prioritize proof-of-concept pilots that measure productivity and comfort against baseline seating to justify broader rollouts.
- Factor total cost-of-ownership — including durability, serviceability, and warranty — into procurement decisions rather than unit price alone.
- Require suppliers to disclose material sourcing and compliance test reports as part of tender documentation.
Risk matrix and contingency considerations for 2026
Decision-makers must weigh three primary risks:
- Input-material disruption: prioritize supply-chain agility over marginal cost savings.
- Misaligned commercialization: avoid assuming one-size-fits-all messaging across clinical and commercial buyers; invest in role-based value propositions.
- Competitive compression: as more established office brands enter the saddle segment, smaller specialists must reinforce niche credibility and service differentiation.
What’s in the PW Consulting full report
The report is engineered as a practical toolkit for board-level and operational decision-making. Core deliverables include:
- Validated market sizing and a year-by-year revenue model from 2020 through 2032 (base year 2025), including scenario analysis for material-cost shocks and accelerated hybrid-office adoption.
- Segment-level playbooks covering product architecture, pricing strategy, and channel economics for medical, office, and industrial end-use cases (note: detailed region- and application-level figures are reserved for the report to preserve our competitive data synthesis).
- Vendor benchmarking with qualitative scoring across ergonomics, service, regulatory compliance, and go-to-market strength for the leading manufacturers and niche specialists.
- Supply-chain diagnostics with alternative sourcing blueprints and near-term inventory strategies to mitigate polyurethane and other cushion-material shortages.
- Commercial templates — RFP language, pilot evaluation frameworks, and specification checklists — designed to accelerate procurement cycles for institutional and enterprise buyers.
Concluding perspective
The saddle chairs market in 2026 is neither a commodity race nor a boutique niche; it is a maturing category where product integrity, channel trust, and supply resilience determine winners. With global market expansion projected at a mid-single-digit CAGR and clear demand tailwinds from workplace transformation and clinical ergonomics, 2026 will reward organizations that convert analytic insight into operational action: reconfigure portfolios, shore up supply chains, and own the specification conversation. PW Consulting’s full Saddle Chairs Market report provides the validated data, competitive benchmarks, and tactical templates to do exactly that — and is available for teams who need the granular figures and executable attachments that underpin these strategic directives.
For detailed analysis of this topic, please visit the official page: Saddle Chairs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Laxative Prune Juice Market to Reach USD 661.59 Million by 2032 on a 3.5% CAGR
By PW Consulting, 2026-08-05
PW Consulting: Strategic Brief — Laxative Prune Juice Market Outlook 2026–2032
PW Consulting today publishes an executive preview of our new market intelligence whitepaper covering the global laxative prune juice market. Built on a 2025 base year and a 2020–2025 historical trace, the study delivers forward-looking guidance across a 2026–2032 forecast horizon. At the macro level, the market expanded from roughly USD 438 million in 2020 to an estimated USD 520 million in 2025 and is projected to reach the vicinity of USD 662 million by 2032, tracking at a compound annual growth rate of approximately 3.5% through the forecast period. These headline figures frame the actionable decision space for C-suite leaders, trading teams, and category managers preparing plans for 2026.
Laxative Prune Juice Market
Why this briefing matters for 2026 corporate choices
-
Timing: 2026 will be the first full planning year after a period of supply-side volatility and regulatory change; recommendations in this brief are oriented to be implemented within the next 12–18 months.
Laxative Prune Juice Market -
Portfolio prioritization: As growth remains steady but not explosive, firms must choose between defending share in legacy channels, investing selectively in premium/functional innovation, or pursuing margin recovery through efficiency and sourcing strategies.
Laxative Prune Juice Market -
Risk calibration: Raw-material cycles and trade-policy shifts materially change available levers for pricing and contract design; companies that stress-test scenarios now will avoid reactive decisions later in the cycle.
What the full report delivers (practical, execution-oriented)
-
Top-down market sizing and consensus-growth scenarios — including baseline, upside (demand-driven) and downside (supply-constrained) paths mapped to 2032.
-
Actionable competitor benchmarking — strategic profiles, capability maps and go/no-go indicators for incumbent brands and concentrate suppliers.
-
Channel playbooks — tactics for modernizing supermarket assortment, converting private-label buyers, scaling D2C and marketplace strategies, and optimizing trade spend for 2026.
-
Supply-chain resilience blueprint — procurement hedging templates, contract farming models, and short-cycle substitution options for ingredient scarcity.
-
New-product and reformulation roadmaps — clinical-to-market timelines for functional claims, sugar-reduction pathways and clean-label positioning.
-
Commercial growth playbook — pricing ladders, promotional cadence calendars and retailer negotiation frameworks designed to protect margin while maintaining velocity.
-
M&A and partnership screening tools — a prioritized shortlist of target capabilities, integration risk scores and estimated synergy envelopes.
-
Regulatory and trade-impact models — scenario matrices for tariff shifts and inspection regimes with recommended mitigation steps.
Market dynamics shaping strategy for 2026
The prune juice category today sits at the intersection of functional-food demand and mature beverage dynamics. Consumer drivers include aging demographics, growing acceptance of fiber-forward solutions, and substitutes from alternative laxative formats. Retail dynamics show a persistent reliance on legacy grocery formats, while digital channels continue to accelerate as a discovery and subscription avenue. On the supply side, raw-material risk is real: industry estimates point to a reduction in global prune production in the 2025/26 cycle, and California — historically the most significant production basin — reported a concentrated crop with below-the-previous-cycle tonnage but favorable quality metrics.
Policy changes are also re-shaping the playing field. Recent tariff suspensions in select importing countries have temporarily improved access to certain supply pools, while longstanding U.S. grading and inspection requirements continue to constrain low-cost imports. Price signals for fresh plums and prunes have shown meaningful movement in recent months, underscoring the need to incorporate agricultural PPI dynamics into procurement planning.
Finally, market concentration is moderate: the competitive structure is defined by several vertically integrated cooperative and corporate players, while a meaningful midtail remains active in concentrates, private-label supply and ingredient markets. This configuration creates both barriers and opportunities — scale can drive manufacturing efficiency, but nimble players can win on formulation, niche positioning and channel specialization.
Competitive landscape — profiles and strategic implications
-
Sunsweet Growers Inc. — A grower-owned cooperative that operates vertically from orchard to bottle. Recent initiatives include a consumer-facing product launch that repositions plum/prune flavor for taste-led buyers and a facility modernization program aimed at energy and emissions reduction. Sunsweet’s seasonal crop updates remain an important market signal for procurement teams; their integration model suggests a playbook focused on supply security plus brand-led innovation.
-
Del Monte Foods & Dole Food Company — Established consumer brands that leverage broad retail penetration. Their strategic levers are distribution density, promotional muscle and portfolio bundling; they are natural defenders of core grocery space and represent credible partners for private-label co-manufacturing.
-
Welch’s & Ocean Spray — Juice specialists with recent activity in low- or zero-sugar formulations and functional juice innovation. These firms are likely to test premiumized, health-claim-driven SKUs and to accelerate cross-category merchandising with complementary products.
-
Sun-Maid, Rauch, Valley View, California Prune Pack — Players focused on concentrates, industrial ingredients and B2B supply. Their importance grows in tight-supply scenarios as they enable scale for beverage manufacturers and co-packers seeking continuity.
Strategically, the field is a mix of brand-driven incumbents and ingredient specialists. For 2026, successful companies will coordinate upstream sourcing with downstream innovation — locking supply while testing margin-accretive formats such as concentrate-based instant mixes, single-serve sachets, and clinically supported functional claims.
Key risks and mitigation considerations
-
Raw-material volatility: Short-cycle crop variance requires layered hedges — forward buying, index-linked contracts, and partnerships with grower cooperatives to secure volume and quality.
-
Trade and regulatory shifts: Even temporary tariff suspensions alter input cost lines. Companies should model both continuation and reversal scenarios and maintain flexible routing and alternative-sourcing playbooks.
-
Channel displacement: Overinvesting in one route-to-market risks stranded inventory; firms should allocate test-and-learn budgets for e-commerce and subscription models while retaining core retail relationships.
-
Reputation and ESG: Energy-intensive processing and packaging expose firms to stakeholder scrutiny; capital investments in processing efficiency and Scope 1/2 reduction can become differentiators with large retail partners.
2026 Strategic Playbook — prioritized actions for executives
-
Initiate a 12-month supply-security program — combine forward contracts for at least one crop cycle with optionality via concentrate suppliers and co-manufacturers.
-
Deploy a two-track innovation pipeline — near-term reformulations (sugar reduction, clear labeling) to protect shelf space; mid-term functional launches (prebiotic/fiber claims) to open premium price points.
-
Rebalance commercial investments — shift a portion of trade spend to digital-first acquisition while creating a retailer-focused “no-regret” promotional calendar to defend losing-share risks.
-
Target operational efficiency projects — prioritize energy-saving retrofits and yield improvements where ROI pays back within 36 months; leverage available grants and incentives for decarbonization investments.
-
Run deal-sourcing sprints — create an M&A and partnership shortlist emphasizing concentrate capacity, private-label scale, or innovation capabilities; conduct quick-diligence on integration cost and channel overlap.
-
Stress-test pricing and tariff reversals — integrate tariff-reversal scenarios into pricing ladders and negotiate flexible freight/price clauses with major buyers.
-
Set KPIs and a cadence for market intelligence — weekly raw-material watch, monthly channel velocity dashboard, quarterly scenario rehearse with executive sponsors.
How PW Consulting supports execution
PW Consulting provides a hands-on engagement to translate the research into a 90–180 day activation plan: detailed regional and channel splits (data tables and dashboards), supplier and target-company maps, procurement-contract templates, SKU-level assortment simulations, and a bespoke financial model that ties scenario outcomes to P&L and cash-flow impacts. Our workshops combine cross-functional stakeholders to codify go-to-market pilots and operational investments so that the insights in this preview become concrete decisions in 2026.
Note: this press release follows a preview strategy — it surfaces market direction, competitive posture and recommended executive actions without disclosing the granular segmentation tables and proprietary microdata that are included in the full subscription report. Organizations that require the underlying regional, channel and type splits, access to our raw data, or a tailored scenario run should request the full report and consulting engagement.
To obtain the complete PW Consulting Laxative Prune Juice Market Report 2026–2032, including the full data appendices, competitor scorecards and executable playbooks, contact our client services or visit our website to arrange a briefing with our lead industry analysts.
For detailed analysis of this topic, please visit the official page: Laxative Prune Juice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pearls Market Hits USD 4,150 Million in 2025 as Global Demand Strengthens
By PW Consulting, 2026-08-05
Pearls Market 2026: Strategic Playbook for Decision-Makers — PW Consulting Pearls Market Report (Preview)
Executive Summary
As luxury tastes intersect with sustainability, the global pearls market has entered a new phase of strategic realignment. PW Consulting’s Pearls Market report — grounded in a 2025 base, a six‑year historical window (2020–2025) and a seven‑year forecast (2026–2032) — synthesizes market sizing, competitive dynamics, regulatory shifts, and consumer behavior to equip executives for high‑stakes 2026 decisions. The market is demonstrating resilient expansion with a mid‑single‑digit compound annual growth rate (CAGR of 5.25%), moving from a 2025 baseline of roughly USD 4.15 billion toward a multi‑billion dollar market by the early 2030s. Market concentration remains low (CR3 ≈ 18.5%; CR5 ≈ 24.2%), pointing to fragmentation and opportunity across the value chain.
Pearls Market
Why This Report Matters for 2026 Strategy
-
Timing: 2026 is the inflection point where investments in traceability, provenance storytelling, and sustainable farming begin to deliver differentiated margin and brand equity. Stakeholders who allocate capital and talent around proven sustainability standards will capture disproportionate share of premium channels.
Pearls Market -
Risk management: Heightened trade frictions and tariff debates in 2025–2026 — including discussions of significant import levies affecting key supply origins — mean sourcing strategies must be stress‑tested against geopolitical scenarios. Our scenario toolkit helps quantify margin and lead‑time impacts under alternative tariff and logistics scenarios.
Pearls Market -
Commercial execution: Consumer preferences are bifurcating — longevity and provenance command premiums in luxury segments while value and design innovation drive mass channels. Our playbooks map product, pricing, and channel choices to measurable revenue and margin outcomes.
What the Report Contains (Practical, Actionable Deliverables)
-
Market sizing and forward‑looking forecasts (2026–2032) with sensitivity testing across three macro scenarios; transparent methodology and a reproducible Excel model to run bespoke permutations.
-
Proprietary demand drivers framework linking macro variables (global luxury spend, tourism flows, retail channel evolution) to pearl demand; includes elasticities and lead indicators for near‑term revenue planning.
-
Go‑to‑market playbooks for suppliers, brands, and retailers: SKU rationalization, premiumization pathways, channel mix optimization, and CRM tactics tuned for pearl categories.
-
Supply chain resilience diagnostics: farming to finished jewelry mapping, inventory turn benchmarks, and mitigation strategies for tariff, climate, and biosecurity shocks.
-
Commercial due diligence templates and prioritised M&A target criteria for consolidators seeking scale in farming, processing, or branding capabilities.
-
Consumer insights and creative brief booklets for marketing teams: segmentation‑informed messaging pillars that reconcile provenance, science‑backed sustainability, and contemporary design narratives.
Methodology — Why Our Findings Are Robust
The analysis integrates primary interviews with producers, retailers and trade bodies, proprietary trade flow reconciliation, retail scanner data, and consumer panel research. Forecasts combine bottom‑up demand construction with top‑down macro plausibility checks. Where public standards and third‑party initiatives have evolved — notably the expanded industry guidance and science content published by trade organizations in 2025 — we incorporate the new taxonomy into classification assumptions and sustainability scoring. The report provides an auditable trail from raw input to directional outputs while deliberately withholding granular proprietary splits from this summary to preserve data integrity for subscribers.
Competitive Landscape: Strategic Implications for Established Players
-
Mikimoto (Tokyo) — A century‑plus brand with deep Akoya expertise. Strengths: unmatched heritage, channel control in high‑end segments, and technical mastery of quality grading. Strategic priority for Mikimoto: translate artisanal provenance into scalable digital storytelling and adapt seasonal inventory strategies to mitigate market cyclicality.
-
Tasaki (Kobe) — Vertical integration from farming to finished jewelry gives Tasaki control over quality and margin capture. Strategic priority: leverage its production control to experiment with premium‑tier innovations (graded traceability, limited‑edition collections) while protecting upstream farming sustainability credentials.
-
Paspaley (Darwin) — Premium Australian South Sea specialist with strong sustainability narrative. Strategic priority: consolidate premium channel partnerships and formalize provenance reporting to defend against price sensitivity in cyclical markets.
-
Jewelmer (Makati) — Niche leader in golden South Sea pearls with integrated cultivation and design. Strategic priority: scale storytelling to global luxury markets through selective retail partnerships and digital high‑touch commerce experiences.
-
Atlas Pearls (Subiaco) — Significant white/silver South Sea player focused on supply and distribution. Strategic priority: optimize supply chain transparency and diversify farm locations to reduce biosecurity and weather concentration risk.
-
Chow Tai Fook (Hong Kong) — Large retail network with heavy Asian market exposure. Strategic priority: use category management and localized assortments to maintain volume leadership while introducing higher margin provenance lines in flagship stores.
-
Zhejiang Grace Pearl Jewelry (Zhuji) — A freshwater pearl powerhouse embedded in China’s production ecosystem. Strategic priority: navigate trade headwinds by upgrading quality controls, pursuing certifications aligned to global buyers’ expectations, and expanding design‑led offerings for export markets.
Industry Dynamics & Recent Developments
-
Standards and trust: The industry’s knowledge base expanded materially in 2025 with an enlarged guidance suite that integrates sustainability case studies and new classification approaches. Expect rising buyer demand for verifiable science‑based claims — and for brands that can operationalize those claims across sourcing and marketing.
-
Collective action: The launch of a Global Pearl Development Community in late 2025 signals a step‑change in stakeholder coordination across producers, standards bodies, and supply chain actors. Early adopters of community protocols will find easier market access in institutional and luxury channels.
-
Trade and geopolitics: Ongoing tariff discussions and potential import levies on certain supply origins create short‑term price and availability volatility. Our report models tariff impacts and offers hedged sourcing scenarios to protect earnings while maintaining assortment breadth.
Strategic Playbook: What Leaders Should Do in 2026
-
For producers: Prioritise traceability investments and farmer partnerships that can be certified or benchmarked. Monetize provenance via limited runs and co‑branded programs with luxury houses.
-
For brands and retailers: Rebalance assortments toward curated, premiumized capsules that tell a provenance story — and back this with digital content and post‑purchase warranties supporting authenticity and care.
-
For investors and consolidators: Target bolt‑on acquisitions that add processing capacity, brand IP, or direct farm access to build vertically integrated margin engines in a fragmented market.
-
For policy and sustainability officers: Engage with emerging industry standards and the newly launched community platforms to influence classification frameworks and to secure early mover advantage on eco‑labels that buyers will trust.
How to Use This Report
This report is structured to be a working tool for 2026 planning cycles. Use the included Excel model to stress‑test your portfolio’s exposure to tariff shocks, channel shifts, and price elasticity. Apply the SKU rationalization playbook to identify immediate GM% improvements. Use the M&A due diligence checklist to prioritize targets that reduce concentration risk and accelerate premiumization.
Limitations & The Trailer Principle
To preserve commercial value and encourage rigorous engagement with the source material, this preview surfaces high‑level findings and strategic implications while withholding granular regional and application‑level splits, and proprietary price‑by‑segment tables. Subscribers to the full Pearls Market report receive the complete dataset, interactive dashboard, and the Excel forecast model supporting the analyses summarized here.
Next Steps — Access and Engagement
Executives seeking to operationalize these insights for 2026 planning are invited to access the full report and supplementary materials via PW Consulting’s Pearls Market portal. Available deliverables include the complete dataset (historical 2020–2025 and forecasts to 2032), scenario models, and bespoke briefing workshops with our senior industry analysts.
Closing Remarks
The pearls market stands at a crossroads between craft and commodity. Firms that invest now in traceability, agile sourcing, and narrative competence will turn a relatively fragmented competitive landscape into a platform for premium growth. PW Consulting’s Pearls Market report offers the evidence base and strategic playbooks to convert those investments into measurable advantage in 2026 and beyond — for the full data, models, and company‑level analytics, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Pearls Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 7.2% CAGR for Carob Chocolate Bars Market Through 2032
By PW Consulting, 2026-08-05
Carob Chocolate Bars Market: Strategic Imperatives for 2026 — A PW Consulting Executive Brief
Executive snapshot
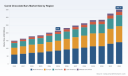
PW Consulting’s latest Carob Chocolate Bars Market report — with a 2025 base, historical coverage spanning 2020–2025 and forecasts through 2032 — frames a rapidly maturing niche within the health-forward confectionery landscape. The global market, estimated at USD 215.0 Million in 2025, is projected to grow at a compound annual growth rate (CAGR) of 7.2% over the 2026–2032 forecast window. By the start of the forecast period the market is expected to expand further, reflecting strengthening consumer demand for clean-label, lower-sugar, and plant-based confectionery alternatives.
Carob Chocolate Bars Market
Why this matters for 2026 decision-makers
For senior executives, investors, and category managers evaluating entry, expansion, or consolidation strategies in 2026, the carob bars segment offers a distinct risk-reward profile. Growth is steady enough to justify strategic investment yet dispersed across many small players and novel ingredient entrants — creating windows for product innovation, targeted distribution deals, and ingredient-portfolio differentiation. The PW Consulting report positions the 2026 planning cycle as a pivotal moment to convert proof-of-concept initiatives into scalable commercial plays.
Carob Chocolate Bars Market
Key strategic takeaways (headline)
- Growth runway: The sub-category is growing ahead of many traditional confectionery sub-segments, making 2026 an opportune year to prioritize investment in product development and commercial scale-up.
- Innovation premium: Consumers reward texture and taste parity with chocolate; investments in flavor enhancement and prebiotic ingredient integrations can command premium shelf pricing and cross-category placement.
- Distribution arbitrage: Early wins are available through health-focused retail channels and targeted online strategies, but mainstream supermarket listings remain the most effective step-change for scale.
- Supply resilience: Sourcing consistency for carob pod derivatives, and managing quality across geographies, will be a competitive differentiator as demand tightens.
What’s inside the report — actionable, field-tested deliverables
The PW Consulting report is constructed to be immediately actionable. It blends a quantitative market model with qualitative implementation tools that buyers and operators can deploy in the 2026 execution cycle:
Carob Chocolate Bars Market
- Forward-looking market-sizing model calibrated to 2025 as the base year and stress-tested across multiple demand scenarios, enabling revenue and margin planning for new launches and private-label lines.
- Go-to-market playbooks for three commercialization archetypes: artisanal/heritage brands, fast-growing D2C challengers, and incumbent confectionery manufacturers pursuing adjacent diversification.
- Retail access and negotiation toolkit, including shelf-space simulation templates, trade margin scenarios, and merchandising strategies tailored for health channels vs. mainstream grocery.
- Product development frameworks covering formulation trade-offs (sweetness, mouthfeel, functional claims), sensory-testing protocols, and an innovation roadmap for integrating prebiotic and clean-label ingredient claims.
- Supply chain and ingredient-risk diagnostics, with supplier shortlists, teardown of common quality issues, and recommended mitigation steps for sourcing volatility.
- Regulatory and labeling checklist for cross-border distribution, highlighting common pitfalls in nutritional disclosure and claims management that can delay market entry.
- Deal playbook for M&A and strategic partnerships, including valuation sensitives for growth-stage brands and practical integration guidance for ingredient licensors.
Competitive landscape — who to watch and why
Market structure remains fragmented, populated by vertically integrated microbrands, specialized ingredient suppliers, and a scattering of regional champions. The current competitive set demonstrates three complementary strategic vectors:
- Product-first artisans that emphasize provenance and premium organic positioning (examples include specialist producers founded around single-origin supply chains).
- Scale-driven challengers targeting mainstream health retailers with broad flavor portfolios and retail-ready packaging.
- Ingredient-focused entrants that push functional differentiation — e.g., prebiotic fibers and flavor technologies — enabling incumbents and newcomers to extend shelf-life and health positioning.
Representative companies illuminate these vectors. Several branded players have built recognizable platform propositions by combining vegan, allergen-friendly formulations with focused marketing and selective retail partnerships. A parallel cohort of ingredient innovators and research collaborations — including academic flavor-enhancement initiatives and new functional-ingredient launches — are increasing the technical bar for taste and digestive-health claims.
Recent signals shaping 2026 tactics
- Retail access expansion by established labels into national health-chain listings demonstrates the pathway from niche to scale; securing similar shelf presence in 2026 can be a high-leverage move for ambitious brands.
- Academic and private-sector flavor work shows tangible gains in taste parity; firms that can license or adopt validated flavor-enhancing techniques will shorten consumer trial cycles.
- Ingredient launches that emphasize gut-health benefits open cross-category co-marketing opportunities with functional-snack and nutrition brands.
Operational priorities for market entry and scaling
Translating market opportunity into profitable operations in 2026 requires concentrated execution across five priorities:
- Sensory-first R&D: Invest early in validated flavor and texture technologies; run consumer panels across target demographics and channels to prioritize SKUs that pass both taste and repeat-purchase thresholds.
- Sourcing strategy: Build multi-supplier networks for raw carob derivatives and establish forward-buying or contract farming options to stabilize supply and quality.
- Channel sequencing: Use digital D2C and specialty-health retail to validate product-market fit, then migrate winning SKUs into supermarket channels with adjusted pack sizes and trade terms.
- Brand architecture and claims: Design a tiered portfolio (e.g., premium organic, mid-market functional, value-accessible variants) with consistent brand storytelling that reduces cannibalization risk.
- Regulatory readiness: Pre-empt label compliance requirements and nutrition disclosure rules across jurisdictions to avoid time-to-shelf delays.
Risk landscape and mitigation
Key risks include raw-material supply shocks, taste acceptance barriers, and channel access friction. PW Consulting’s report maps each risk against pragmatic mitigants: diversified supplier contracts, staged product rollouts with an emphasis on repeat-trial drivers (pack formats, promotional sampling), and retailer-focused commercial terms supported by point-of-sale analytics. Scenario modules in the report quantify the potential impact of these risks on revenue and margin profiles to support contingency budgeting in 2026 planning.
Priority moves for different stakeholders
- For brand founders: Accelerate sensory validation and prioritize a single high-conversion channel before scaling assortment.
- For manufacturers and ingredient houses: Evaluate licensing or co-development agreements that fast-track flavor and functional claims into customer pipelines.
- For private equity and strategic investors: Focus diligence on supply-chain quality, repeat-buy metrics, and the cost trajectory to mainstream shelf placement.
Why PW Consulting’s research is uniquely actionable
This report is designed as more than a market map; it is a decision engine for 2026. Our market model is accompanied by executable assets — templates, negotiation scripts, sensory-validation matrices, and supplier selection criteria — enabling teams to move from strategic intent to operational implementation quickly. The analysis synthesizes primary interviews with founders, buyers, and ingredient suppliers, supplemented by field audits and proprietary demand-sensing algorithms.
Next steps and how to use the report in 2026 planning
Organizations preparing 2026 budgets should use this report to: (1) stress-test product roadmaps against demand scenarios; (2) prioritize channel investments; (3) price and margin-test premium variants; and (4) structure risk-adjusted supplier contracts. The report’s playbooks support rapid piloting and scaling while the strategic frameworks help allocate capital to initiatives that most directly accelerate repeat purchase and distribution breadth.
Access and engagement
PW Consulting has intentionally designed this publication to preview our analytical depth while reserving granular segment-level tables, supplier scorecards, and model workbooks for licensed subscribers and consulting clients. For teams that require full segmentation breakdowns, supplier shortlists, and the interactive forecast model to run custom scenarios, please visit the PW Consulting research portal or contact our industry team to request the complete Carob Chocolate Bars Market dossier and implementation workshop options.
For detailed analysis of this topic, please visit the official page: Carob Chocolate Bars Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Biometric Signature Pads Market Hits USD 480 Million in 2025
By PW Consulting, 2026-08-05
PW Consulting Releases Strategic Brief: Biometric Signature Pads Market — A 2026 Decision-Making Roadmap
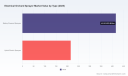
PW Consulting today publishes a focused industry briefing built from our full Biometric Signature Pads Market report (base year 2025, historical window 2020–2025, forecast 2026–2032). The briefing translates broad market dynamics into board-level signals and executable options for enterprises planning capital allocation, procurement, compliance, and product strategy in 2026. At a macro level, the market reached approximately USD 480.0 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.15% over the 2026–2032 forecast window, approaching an estimated market valuation in the high hundreds of millions by 2032. This release acts as a strategic trailer — it demonstrates the analytical depth of our research while reserving granular segment data for subscribing clients and the full report.
Biometric Signature Pads Market
Why this report matters for 2026 decision-makers
-
Fast-moving regulatory context: e-signature technologies are being actively interpreted within cross-border regulatory frameworks. Biometric pads play a critical role where dynamic biometric capture and device-level security are required to satisfy advanced electronic signature standards.
Biometric Signature Pads Market -
Investment timing: With mid-single-digit to high-single-digit growth through the forecast horizon, 2026 is a pivotal year for procurement cycles, pilot-to-scale transitions, and supply-chain reconfiguration.
Biometric Signature Pads Market -
Vendor and technology selection: Buyers must balance functional requirements (dynamic biometric capture, multi-factor integration, software interoperability) with non-functional needs (durability for high-volume environments, compliance for regulated sectors, lifecycle cost).
-
M&A and partnership opportunity mapping: The market displays moderate concentration, presenting whitespace for regional specialists, software integrators, and niche hardware innovators to consolidate share or strike strategic alliances.
Market dynamics that will shape decisions in 2026
-
Regulatory tailwinds and compliance hurdles — European frameworks such as eIDAS and associated ISO standards continue to define the legal viability of biometric signature capture in critical workflows. Enterprises operating in or serving EU customers will need to prioritize devices and implementations that can be validated against these frameworks if they seek feature parity with handwritten signatures for high-assurance processes.
-
Technology convergence — Product roadmaps point to tighter hardware-software integration: color LCDs, pressure- and motion-sensitive capture, fingerprint and NFC adjuncts, and hardened firmware for secure key storage. Vendors that offer certified cryptographic stacks and seamless API-level integrations with common back-office platforms will enjoy privileging in procurement evaluations.
-
Sectoral demand drivers — Banking, government services, healthcare, and retail continue to push use-cases that require in-presence, high-assurance signings. Each sector places different premium on speed, durability, auditability and ergonomics, which demands a segmented go-to-market approach despite an attractive overall growth trajectory.
-
Supply chain and cost pressures — Baseline tariffs on electronics components and ongoing logistics volatility are elevating the total cost of ownership for hardware-centric deployments. Procurement strategies in 2026 must include contingency sourcing, inventory hedging, and localized assembly options to protect margin and delivery timelines.
-
Product innovation signals — Recent product introductions demonstrate vendor focus on durability and regulatory alignment; for example, a late-2025 launch of a rugged color-display model with eIDAS-compliant feature sets underlines competition moving toward certified, enterprise-grade devices optimized for regulated environments.
Competitive landscape — what buyers and investors need to know
The Biometric Signature Pads market is characterized by a mix of established OEMs with deep channel relationships and specialist vendors that focus on security, standards compliance, or vertical integrations. PW Consulting’s competitive review profiles product portfolios, integration footprints, and strategic positioning for leading participants.
-
Topaz Systems (Simi Valley, CA) — Broad product set including LCD models and fingerprint-integrated devices; strong presence in financial services and healthcare workflows.
-
Scriptel Corporation (Columbus, OH) — Durable, pen-based solutions optimized for high-volume use and notable integrations with major healthcare record systems; appeals to enterprise customers with heavy daily signatures.
-
Wacom Co., Ltd. (Japan) — Leader in dynamic capture fidelity; devices emphasize pressure sensitivity and data richness for both authentication and forensic verification.
-
ePadLink (Interlink Electronics) (USA) — Combines hardware with its e-signature software suite, offering turnkey solutions for signatory workflows and enterprise application integrations.
-
StepOver GmbH (Germany) — Focused on rugged, eIDAS-aligned devices targeting public sector and regulated verticals; recent product refreshes underscore durability and compliance readiness.
-
Euronovate Group (Switzerland/Italy) — Niche specialist in graphometric pads with NFC and multi-touch options, positioning for in-presence, compliant signing scenarios.
-
Signotec GmbH (Germany) — High-security orientation with attention to organizational seals and ISO-compliance for professional electronic signatures.
Market concentration metrics in our analysis indicate that the top three companies account for a material share of industry revenues, and the top five expand that concentration meaningfully — a structure that creates both entry barriers and targeted opportunity zones for focused competitors or software-led disruptors.
What PW Consulting’s full report gives you — practical deliverables
-
Executive dashboard — concise market sizing (macro totals and growth scenarios), short-term (12–18 month) and medium-term (3–5 year) outlooks.
-
Vendor scorecards — side-by-side assessments on product features, compliance posture, integration readiness, service footprint, and pricing models.
-
Procurement playbook — vendor RFP templates, evaluation matrices, lifecycle cost comparison frameworks, and sample contractual clauses to manage firmware and supply risks.
-
Deployment and integration checklists — technical and operational guidance for in-branch, point-of-sale, and healthcare workflows including data capture validation and audit trails.
-
ROI and TCO models — customizable templates to quantify benefits from fraud reduction, process acceleration, and compliance risk mitigation under multiple adoption scenarios.
-
M&A and partnership mapping — prioritized targets and acquisition criteria for strategic buyers and private equity, with scenario-based synergy estimates.
-
Supply chain risk matrix — component sourcing maps, tariff sensitivity analyses, and mitigation playbooks for 2026 procurement planning.
We deliberately withhold granular segment-level figures and region/application split tables in this public briefing; subscribers to the full report access the full dataset, regional breakouts, and application-specific forecasts needed for transactional-level decisions.
Actionable strategic recommendations for 2026
-
Adopt a compliance-first procurement standard: For EU-facing operations or customers, prioritize devices with documented eIDAS functionality and certifications; require suppliers to publish evidence of cryptographic and device qualification.
-
Segment purchasing by usage profile, not only by price: High-throughput branches require durable, sealed devices with predictable service lifecycles; low-traffic or mobile use-cases can accept lighter-form factor or BYOD adjuncts combined with software-based capture.
-
Embed software integration requirements early: Insist on published APIs, SDK roadmaps, and ISV partnerships (e.g., EHRs, POS systems) to minimize post-deployment customization costs and maximize time-to-value.
-
Hedge supply chain exposure: Build secondary sourcing paths, negotiate lead-time clauses, and consider local assembly or pre-stocking for critical component lines to protect rollout commitments.
-
Use pilots to de-risk scale: Run short, instrumented pilots measuring capture quality, error rates, user acceptance, and reconciliation impacts before committing to enterprise-wide rollouts.
-
Explore strategic partnerships and bolt-ons: For software vendors and systems integrators, pursue partnerships with hardware specialists to offer full-stack, compliance-validated solutions that reduce buyer friction.
-
Price for lifecycle value: Shift procurement assessment criteria to lifecycle TCO and forensic value-add (auditability, traceability) rather than unit price alone.
How different stakeholders should use this research in 2026
-
Boards and CFOs — Use the macro growth and TCO scenarios to set multi-year budgets and to evaluate inorganic growth opportunities in adjacent verification technologies.
-
CIOs and CISOs — Apply the compliance and integration checklists to vendor selection and security validation; require proof points for device hardening and key management.
-
Procurement teams — Leverage the procurement playbook and vendor scorecards to tighten RFPs, reduce deployment surprises, and manage warranty and support commitments.
-
Private equity and strategics — Use the market concentration analysis and M&A mapping to identify roll-up targets or strategic bolt-ons that accelerate entry into regulated verticals.
PW Consulting’s full Biometric Signature Pads Market report is engineered to convert macro market intelligence into operational decisions. This briefing highlights the strategic contours enterprises must consider in 2026 — regulatory alignment, integration-first procurement, supply-chain resilience, and vendor selection discipline. For decision-makers ready to translate the market’s momentum into executable plans, the complete report provides the datasets, vendor benchmarking, and deployment tools required to execute with confidence.
To access the full report, detailed regional and application breakouts, vendor scorecards, and the downloadable toolkit for procurement and pilots, visit PW Consulting’s market research portal or contact our advisory desk to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Biometric Signature Pads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Spine Surgical Robots Market to Hit $370.8M by 2032 at 12.54% CAGR
By PW Consulting, 2026-08-02
Surgical Robots for the Spine Market — A 2026 Strategic Preview
Executive snapshot
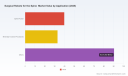
As surgical robotics for the spine transitions from early adoption to commercial scale, 2026 will be a make-or-break year for strategic positioning. PW Consulting’s new study illuminates the pathway from niche, capital-intensive innovation to a market segment poised for sustained growth: market revenue expanded from roughly USD 94 million in 2020 to an estimated USD 163.15 million in 2025, and under our central projection the market follows a robust compound annual growth trajectory (CAGR) of about 12.54% through the 2026–2032 forecast window. That growth reflects accelerating clinical acceptance, emerging reimbursement clarity, and rapid product innovation—especially around integrated planning, navigation and AI-enabled robotics.
Surgical Robots for the Spine Market
Why this research matters for 2026 decisions
- Board-level capital allocation: informs near-term investment priorities between platform R&D, go-to-market, and service infrastructure.
- M&A and partnership screening: identifies strategically valuable targets across hardware, software, and service adjacencies.
- Commercial strategy validation: quantifies demand trajectories and highlights which commercial models (direct sale, lease, refurbished, or managed service) de-risk adoption.
- Regulatory and reimbursement planning: translates recent clearances and payer trends into timing-sensitive go/no-go signals for U.S. and priority international markets.
What the report delivers — practical, deal-ready content
- Top-line market sizing and a transparent forecasting engine. We provide an audited historical series and scenario-based projections to 2032 that decision-makers can plug into corporate financial models.
- Adoption curve and hospital procurement playbooks. Actionable templates for evaluating capital investments, utilization thresholds, and surgeon training programs.
- Competitive capability matrix. A structured assessment of incumbent and challenger portfolios across hardware, navigation, software (AI/automation), clinical evidence, and service economics — enabling rapid competitive scenario planning.
- Regulatory & reimbursement timelines. Consolidated view of recent regulatory milestones, anticipated filings, and payer coverage trends with implications for market access timing.
- Clinical evidence synthesis. Meta-analysis of outcomes versus conventional techniques, key endpoints influencing payer decisions, and recommended post-market study designs.
- Commercial models & pricing playbook. Playbooks for lease, bundled-service, and device-plus-consumable approaches that align with hospital budget cycles.
- M&A and partnership decision framework. A prioritization matrix for targets (technology, geographic presence, service capabilities) and a valuation lens focused on recurring revenue potential.
- Primary research deliverables. Proprietary interview excerpts with hospital procurement leads, high-volume spine surgeons, and IM/OR administrators, complemented by an anonymized deal database.
Note: the report intentionally gates core regional and application splits within an interactive dataset to preserve proprietary insights and to guide buyers to the full study for mission-critical segmentation and pricing models.
Surgical Robots for the Spine Market
Market dynamics shaping 2026 strategy
Three structural forces are reshaping the spine robotics landscape:
Surgical Robots for the Spine Market
- Technology convergence. Integration of pre-operative planning, intraoperative navigation, and robotics—now augmented by AI-assisted trajectory planning—has shifted the competitive battleground from mechanical precision alone to platform-level ecosystems that embed software, analytics, and clinical workflows.
- Regulatory momentum and differentiation. Recent clearances for integrated platforms and mixed-reality navigation have accelerated commercial launches and raised the bar for what constitutes a compelling clinical offering. These regulatory milestones compress time-to-value for first movers who can demonstrate workflow efficiency and improved clinical endpoints.
- Economics of adoption. Hospitals are weighing material capital and recurring service commitments against clinical upside and case volume. Favorable payer signals in core markets have lowered one adoption barrier, but procurement remains sensitive to total cost of ownership and alignment with surgeon workflows.
Collectively, these forces are driving a market that is concentrated among a small number of incumbents but still offers pockets of attractive entry for differentiated challengers and asset-light providers (e.g., refurbished systems, software-only solutions, and managed-service models).
Competitive landscape — strategic read on core players
- Medtronic — With an integrated planning/navigation/robotics platform recently cleared for spine procedures, Medtronic is extending its play from navigation into full procedural orchestration. The company’s strength lies in broad clinical relationships and portfolio synergies that can bundle implants, navigation, and robotics into a unified customer proposition.
- Globus Medical — Focuses on a navigation-centric robotic platform optimized for screw placement and implant alignment. Globus combines a surgeon-focused roadmap with implant compatibility, positioning it as a pragmatic choice for hospitals prioritizing interoperability.
- Stryker — Recent limited releases of its spine-capable SmartRobotics applications signal a push to leverage a multi-specialty robotics ecosystem. Stryker’s advantage is an established robotics franchise and channel depth, supporting rapid commercial scale-up once full launches complete.
- Zimmer Biomet — The ROSA system emphasizes procedural support and real-time feedback, targeting surgical precision and efficiency. The company’s installed base in other surgical domains supports cross-selling opportunities.
- Brainlab — With mixed-reality navigation cleared for spine, Brainlab aims to differentiate on surgeon ergonomics and next-generation navigation integration; this may accelerate adoption where visualization and workflow are procurement priorities.
- Curexo — An emerging, cost-competitive entrant focused on precise pedicle guidance and accelerated North American market entry following recent regulatory progress. Expect Curexo to pursue a combination of clinical partnerships and targeted commercial deployments.
- R2 Surgical — Represents an important access vector via pre-owned and refurbished systems, which can materially expand the addressable market among budget-constrained facilities.
Market concentration metrics indicate that a handful of players account for a dominant share of current revenue, reinforcing the strategic importance of differentiation (software, consumables, service) and creative commercial models for new entrants.
Strategic options for 2026 — recommended plays by stakeholder
- Incumbents: Prioritize platform integration and service monetization. Invest in AI-enabled workflow automation, outcome-tracking registries, and center-of-excellence partnerships to lock-in usage and justify premium pricing.
- Challengers and scale-ups: Attack by cost-to-adopt and niche clinical differentiation. Consider modular offerings (software upgrades to legacy systems), asset-light deployment (leasing/refurbished), and clinician-first UX to penetrate mid-tier hospitals.
- Investors: Seek targets with strong recurring revenue potential (service contracts, consumables, software subscriptions) and clinical evidence pipelines. De-risk deals by linking earn-outs to adoption milestones and payor coverage achievements.
- Hospitals & health systems: Use utilization-based procurement and shared-ownership models to align capital commitments with case volume. Negotiate robust training and uptime guarantees, and insist on data-sharing agreements to capture value from outcome improvements.
How to use this study in your 2026 planning cycle
- Run the report’s forecast engine through three planning scenarios (base, accelerated adoption, and conservative uptake) to test capital allocation under varying reimbursement and clinical adoption assumptions.
- Apply the competitive capability matrix to stress-test your product roadmap—identify where incremental investment in software or services yields the highest defensive return.
- Use our procurement playbooks and hospital interview data to construct pilot programs that shorten sales cycles and generate high-quality real-world evidence for payers.
- Integrate the report’s clinical-evidence recommendations into regulatory filings and post-market study designs to accelerate coverage decisions and minimize payer resistance.
Conclusion — the strategic takeaway for 2026
The spine robotics market is transitioning into a phase where platform breadth, clinical evidence, and commercial ingenuity matter as much as mechanical precision. With a clear growth runway and decisive regulatory developments behind several major players, 2026 is the year to choose a position: double down on platform leadership; pursue a fast-follower, cost-focused model; or build an asset-light niche that exploits gaps in access and service. PW Consulting’s Surgical Robots for the Spine study provides the market sizing, scenario tools, and competitive intelligence to turn those choices into executable plans.
For the comprehensive interactive datasets (regional and application splits), full company profiles, valuation-ready financial models, and the decision-support toolkit referenced here, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Surgical Robots for the Spine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cycling Clothing Market to Grow at 5.6% CAGR, Reach USD 6.24M by 2032
By PW Consulting, 2026-08-02
Cycling Clothing Market 2026: Strategic Preview for Executive Decision‑Making
As PW Consulting’s lead industry analyst, I present a strategic preview of our new Cycling Clothing Market research, calibrated to inform decisive corporate action in 2026. This piece synthesizes macro trends, competitive dynamics, regulatory inflections, and practical playbooks that executive teams need to prioritize resources, reframe product roadmaps, and capture growth as the market transitions from recovery into a structurally higher‑growth phase.
Cycling Clothing Market
Market snapshot — what the headline numbers mean for strategy
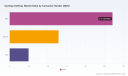
The market’s trajectory across the 2020–2032 window tells a nuanced story. After a decline from an earlier high in the early 2020s, the total market stabilised by the 2025 base year and is projected to resume sustained expansion through 2032. Our modelling shows a compound annual growth rate (CAGR) of 5.6% for the 2026–2032 forecast period, with total market value rising materially by the end of the forecast horizon (all values expressed in USD Million). Simultaneously, concentration metrics indicate a moderately fragmented marketplace: the top three players account for approximately 45.5% of market revenue while the top five reach about 65.2% — a structure that supports both scale advantages for incumbents and opportunity windows for well‑positioned challengers.
Cycling Clothing Market
Strategically, these headline figures imply three immediate imperatives for 2026: protect core margins during the stabilisation phase; invest selectively in product and channel experiments that can be scaled as demand returns; and prepare for consolidation and partnership opportunities as larger players pursue adjacent capabilities (sourcing, sustainability certification, digital direct‑to‑consumer channels).
Cycling Clothing Market
Why this research matters for 2026 decisions
- Operational planning: We reconcile historic volatility through a granular demand model that translates macro CAGR into mid‑year inventory cadence, supplier lead times, and working capital scenarios — essential for CFOs and supply chain leads reducing carry risk while preserving service levels.
- Product and R&D prioritisation: Our framework scores apparel investments across performance, sustainability, and regulatory friction to show which product bets will unlock margin and loyalty in 12–24 months.
- Commercial strategy: We map channel economics for premium, mass, and DTC routes, enabling CMOs to allocate media, partnerships, and retail shelf space against measured ROI expectations rather than intuition.
Competitive landscape — patterns, not just names
The licensed and branded cycling apparel field combines boutique premium houses, heritage domestic manufacturers, and price/scale players. Rather than repeating company facts, the strategic patterns you need to watch are:
- Premium lifestyle and performance brands (examples include several U.K., Italian, and Australian labels) are weaponising design, brand storytelling, and limited‑edition drops to command higher ASPs and margins. Their playbook: elevated materials, celebrity and team affiliations, and steeped community‑driven activations.
- Made‑in‑USA and heritage producers continue to defend specific demand pockets by leaning into domestic production, fit customisation, and localised fulfilment. This reduces lead‑time risk and enables premiumisation through craft narratives.
- Sustainability‑led challengers (including brands integrating recycled and natural fibres) are converting values into measurable purchase drivers — but only where supply cost curves and certification pathways are well mapped.
- Large value producers and Asia‑based manufacturers retain advantages on cost and scale for high‑volume SKUs, and they are accelerating product quality to close the gap with premium tiers.
From a M&A and partnership perspective, the market structure — moderate concentration with room for niche growth — makes bolt‑on acquisitions, licensing deals, and co‑development partnerships attractive routes for incumbent apparel firms, material innovators, and retail platforms seeking vertical integration.
Recent product and competitive signals (implications rather than cataloguing)
Early‑2026 product announcements point to two operational themes: accelerated rollout of recycled‑material lines across segments, and iterative fit/improvement updates for all‑day and endurance products. These moves confirm that sustainability is no longer a fringe play — it is a baseline expectation for new collections — and that fit and comfort remain core defensible attributes for higher‑price offerings.
For decision‑makers, this means supply chain investments must factor sustainability verification and traceability into lead‑time models, while product teams must reprioritise fit optimisation and lab testing as short‑cycle differentiators rather than long‑cycle branding exercises.
Regulatory and standards dynamics — a new constraint and source of advantage
The regulatory landscape for competitive cycling apparel tightened as of 2026. Licensing rules, ISO referenced quality and safety requirements, and pre-approval regimes for technical innovations now influence product roadmaps and go‑to‑market timing for competition kits. For apparel companies serving professional teams or pursuing validated performance claims, this regulatory tightening introduces both compliance cost and market differentiation potential.
Leaders will treat regulatory engagement as strategic: early submission of technical innovations for approval, proactive certification of production lines, and formalised compliance checklists reduce time‑to‑market friction and transform regulation from a gating risk into a trust signal for B2B and consumer channels.
What’s inside the full PW Consulting report (practical contents)
- Demand and supply model calibrated to 2020–2025 history and 2026–2032 forecast, with scenario sensitivity to fuel prices, leisure cycling participation, and pro‑team kit demand.
- Channel economics playbooks for premium, midmarket, and value segments, including CAC/LTV benchmarks, inventory turn targets, and suggested promotional cadences.
- Detailed product decision matrix scoring types (e.g., jerseys, bib shorts, base layers) against margin potential, development cycle, certification burden, and sustainability impact.
- Supplier and manufacturing map with lead‑time tiers, regional cost proxies, and risk flags for nearshoring vs. offshore strategies.
- Competitive profiles and capability heat‑maps for the major players: brand positioning, manufacturing posture, sustainability claims, and digital commerce maturity.
- Regulatory compliance checklist and an approval timeline template for technical kit innovations intended for sanctioned competition.
- M&A and partnership playbook with valuation anchors, integration risk matrix, and 6‑ and 12‑month KPI trackers.
Note: the full report contains the granular regional, application and product split details (our segmentation tables and revenue run‑rates) that the executive team will use to size investments and negotiate supplier contracts. This preview intentionally omits those specific split figures to preserve the strategic value of the full study.
Recommended 90‑day agenda for executives (how to use this research immediately)
- Portfolio triage: run a 90‑day product review using our decision matrix. Pause low‑margin, high‑inventory SKUs; accelerate small‑batch runs for high‑confidence innovations that clear regulatory hurdles quickly.
- Supply‑chain stress test: implement the supplier lead‑time and traceability templates to quantify exposure to recycled‑material bottlenecks and to identify two alternative suppliers per critical material.
- Sustainability and compliance sprint: certify at least one core SKU to an industrially recognised recycled‑content standard and register any performance innovations with the relevant governing body if competitive use is intended.
- Market activation: pilot a DTC limited run that doubles as a product lab — measure conversion, returns, and community sentiment to de‑risk larger rollouts.
- M&A scan: identify 3–5 boutique brands or material innovators from our map that unlock distribution or technical capabilities; prepare non‑binding exploratory outreach with confidentiality scaffolding.
Risks that should be baked into 2026 planning
- Regulatory delay risk: novel technical apparel requiring governing‑body approval may face months‑long timelines; plan commercialization buffers accordingly.
- Supply volatility for specialised recycled and natural fibres: certification and processing capacity can create intermittent shortages and price spikes.
- Brand premium fatigue: misaligned pricing without corresponding product experience (fit/performance) increases return rates and channel friction.
- Competition for talent and IP: fit engineering and materials R&D are strategic choke points; talent scarcity increases acquisition and retention costs.
Closing — the strategic payoff of timely, informed action
By 2026 the cycling clothing market is at an inflection: the macro projection is upward, market concentration allows for both scaling and niche disruption, and the twin drivers of sustainability and regulatory scrutiny are reshaping product roadmaps. Companies that translate the forecast and competitive patterns into disciplined product portfolios, supply‑chain resilience, and regulatory‑aware innovation will convert the projected CAGR into shareholder value rather than simply revenue growth.
PW Consulting’s full report equips leadership teams with the actionable models, supplier maps, and competitive diagnostics required to make those choices with confidence. For teams preparing budgets, negotiating supplier contracts, or evaluating M&A in 2026, the difference between a calibrated move and a speculative gamble will be the intelligence and templates contained in the full study.
To access the complete segmentation tables, scenario models, and the operational playbooks referenced above, please refer to our full subscription report or contact PW Consulting for a briefing and executive summary.
For detailed analysis of this topic, please visit the official page: Cycling Clothing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Indoor Bike Trainers to reach USD 2,070M by 2032 | 7.85% CAGR
By PW Consulting, 2026-08-02
Indoor Bike Trainers Market: Strategic Preview for 2026 Decision-Making
Introduction — why this briefing matters for leaders in 2026
As the indoor cycling ecosystem continues its rapid professionalization, corporate leaders — from OEM product chiefs to private equity investors and fitness-club operators — must convert market momentum into defensible value. PW Consulting’s forthcoming Indoor Bike Trainers Market study (base year 2025; historical series 2020–2025; forecast 2026–2032) synthesizes hard market performance with forward-looking scenario work to inform 12–36 month strategic choices. The market has moved from under USD 850 Million in 2020 to USD 1,222.0 Million in 2025, and our baseline projection anticipates continued expansion to approximately USD 2,070.0 Million by 2032 at a compound annual growth rate (CAGR) of 7.85%. This trajectory demands a recalibration of product roadmaps, supply chains and go-to-market plays in 2026 if organizations intend to capture disproportionate share and margin.
Indoor Bike Trainers Market
Market trajectory and the forces shaping growth
-
Structural growth: The market’s near-term growth post-2025 is driven by a secular shift toward connected training solutions, a maturing consumer segment that increasingly pays for blended hardware+software experiences, and steady adoption across both dedicated home athletes and commercial fitness operators. The growth profile from 2020 to 2025 reflects recovery and stabilization after pandemic-driven volatility, while the 2026–2032 forecast captures a transition from adoption-led growth to feature-driven upgrade cycles.
Indoor Bike Trainers Market -
Technology premiumization: Direct-drive, near-silent trainers, improved road-feel algorithms, and tighter platform interoperability have elevated perceived value. This is widening the total addressable market while enabling higher ASPs for manufacturers that can demonstrate credible training performance and software integration.
Indoor Bike Trainers Market -
Channel evolution: E‑commerce and D2C sales remain central, but hybrid fulfillment (direct, specialty retail, and subscription bundling with third-party training platforms) is emerging as the preferred commercial model for premium SKUs. Commercial buyers — from boutique studios to large gym chains — are developing procurement playbooks emphasizing service, spare-part availability and lifecycle TCO.
-
Consolidation dynamics: Market concentration is moderate. The top three firms account for approximately one-third of market revenues, and the top five under half of the market — a structure that creates both stability and opportunity. Investors and incumbents should expect selective M&A and OEM partnerships to accelerate as companies seek scale in manufacturing, firmware, or platform distribution.
Competitive landscape — what incumbents are doing and what it means
-
Wahoo Fitness (Atlanta, GA): Wahoo’s smart wheel-on and direct-drive lines — exemplified by successive KICKR iterations — underscore how product ecosystems (hardware + companion apps + accessory portfolio) can command customer loyalty. Strategy implication: incumbents should leverage accessory and subscription attach rates to defend ASPs and margin.
-
Garmin / Tacx (Olathe, KS): Tacx-branded direct-drive trainers emphasize immersive road feel and near-silent operation, which appeal to performance-focused riders. Strategy implication: differentiation via measurement fidelity and noise/thermal engineering remains a high-barrier capability.
-
Saris Cycling Group (Madison, WI): Saris’ product cadence — including recent innovations supporting new axle standards — demonstrates a practical route to product longevity through compatibility. Their January 2026 launch of thru-axle adapter kits for UDH-compatible bikes highlights the strategic value of standards alignment. Strategy implication: modularity and backwards-compatible adapters are low-cost levers to accelerate adoption among cyclists with diverse drivetrain standards.
-
Elite (Italy) and Van Rysel (France): European players combine product engineering with regional channel strength. Elite’s focus on performance-grade direct-drive units contrasts with Van Rysel’s value-driven approach targeting home trainers that pair with mainstream virtual platforms. Strategy implication: segmented value propositions — premium performance vs. value connectivity — will coexist; firms must decide to niche or span.
-
Specialists and accessory brands (Aosom, Kurt Kinetic, Feedback Sports, Graber, CycleOps): These firms round out the ecosystem with rollers, magnetic trainers, service stands and complementary hardware. Strategy implication: accessory ecosystems amplify switching costs and create aftermarket service revenue opportunities for product manufacturers willing to orchestrate partner networks.
Supply-side risks and regulatory friction you cannot ignore
-
Component exposure: High-performance direct-drive units rely on specialty components and rare-earth magnets. Price and availability volatility for these inputs can compress margins or force product redesigns. Organizations should run scenario analyses tied to magnet-price shocks and supplier concentration.
-
Labor and manufacturing cost pressure: Rising labor costs in key European manufacturing hubs are already affecting assembly economics for interactive trainers. Near-shoring and automation can mitigate exposure but require capital and retooling lead times that must be planned in 2026 budgets.
-
Regulation and standards compliance: Evolving axle and drivetrain standards (e.g., UDH) are not merely engineering issues — they carry certification and liability implications. Saris’ recent move to offer UDH-compatible adapter kits illustrates the strategic value of proactive standards compliance. Separately, high-profile safety incidents in adjacent categories — such as the recall activity seen in connected stationary bike products — raise the bar on product testing, warranty provisioning and public communication strategies.
Strategic plays to prioritize in 2026
-
Hedge your supply chain now: Build dual-sourcing plans for magnets and motor subassemblies, and create a quantified “stress” model that links component price/persistence to product mix and margin. Negotiate long-form supply agreements with price collars where feasible.
-
Modularize product architectures: Design for axle and drivetrain compatibility via field-upgradeable adapters to lengthen product life and reduce SKUs. This is a low-cost way to protect sales across evolving bike standards and increase resale value in secondary markets.
-
Monetize software: Pair hardware launches with subscription-based training content, performance analytics and cloud services. Expect software attach rates to materially lift lifetime customer value for premium trainers.
-
Pursue targeted M&A or partnerships: With top-five concentration below 50%, strategic acquisitions can rapidly expand manufacturing capacity, firmware IP or distribution reach. Focus on targets that close capability gaps (e.g., firmware teams, noise/thermal specialists, platform integrations).
-
Commercial channel playbooks: For fitness operators, emphasize service-level agreements, spare-parts logistics and upgrade programs rather than one-off hardware discounts. Total cost of ownership and uptime guarantees will be decisive in commercial procurement.
-
Data-driven product differentiation: Invest in higher-fidelity sensors and algorithms that improve ride realism and performance metrics — differentiators that support premium pricing and platform partnerships.
What the full PW Consulting report delivers — practical outputs for implementation
-
Comprehensive market model (2020–2032): demand forecasts by segment, scenario stress-testing templates and sensitivity tables for key inputs such as component costs, ASP trajectories and channel mix.
-
Competitive intelligence: product benchmarking matrices, patent and firmware-IP landscapes, pricing and warranty comparatives, plus a prioritized list of practical defensive and offensive moves for incumbents and challengers.
-
Supply-chain playbook: supplier scorecards, near-shoring vs offshoring cost models, inventory and lead-time optimization strategies and an actionable supplier risk register with mitigation milestones.
-
Commercial guides: go-to-market blueprints for premium D2C models, mid-market retail strategies and commercial-operator procurement plays — each with sales scripts, channel KPIs and sample contractual language for service agreements.
-
M&A and partnership pipeline: a screened list of acquisition and JV candidates, valuation frameworks tied to synergy capture and integration checklists focused on firmware, distribution and manufacturing capabilities.
-
Regulatory & safety checklist: certification timelines for axle/drivetrain compatibility, recommended product-testing regimens to reduce recall risk, and crisis communications templates informed by recent recall precedent in the broader connected exercise equipment segment.
Methodology note and confidence framework
Our forecast and recommendations synthesize primary interviews with OEMs, suppliers and commercial buyers, transaction-level channel data, and component-price series through 2025. We apply scenario analysis across three adoption curves (conservative, baseline, aggressive) and stress-test those against geoeconomic and component-supply shocks. The headline CAGR of 7.85% and the revenue path to roughly USD 2,070.0 Million by 2032 represent a base-case alignment that assumes steady product upgrade cycles and continued platform monetization.
Closing — the strategic value of acting in 2026
2026 is a pivotal year for firms in the indoor trainer ecosystem. The market’s growth is substantial and sustained, yet structural vulnerabilities — supply exposure, shifting axle standards, and evolving consumer expectations for software-enabled experiences — create windows of both risk and opportunity. PW Consulting’s report is designed as an executable playbook: it does not merely map where demand will be, but shows how to capture it with defensible, margin-accretive strategies.
To move from insight to impact, executives should prioritize supply‑chain hedging, modular product engineering and software monetization in their 2026 investment plans. For stakeholders seeking a full decomposition of segment-level share, regional dynamics, and the prioritized list of targets and tactical templates, the complete PW Consulting Indoor Bike Trainers Market report contains the confidential appendices and model workpapers that underpin the strategic recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Indoor Bike Trainers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tuberculin Market at USD 558M in 2025, 5.8% CAGR to 2032
By PW Consulting, 2026-08-02
Tuberculin Market 2026: Strategic Imperatives and What Decision‑Makers Must Know
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a concise, decision‑focused briefing on the global tuberculin market to inform executive choices in 2026. This introduction synthesizes the structural forces, regulatory inflection points, competitive dynamics, and pragmatic levers that will determine winners and laggards over the next investment cycle. The aim is to demonstrate analytical depth while reserving the granular, proprietary segment matrices for the full report—our “trailer” approach that surfaces insight and preserves the intelligence that supports decisive action.
Tuberculin Market
Market snapshot: scale, trajectory, and concentration
The tuberculin market is a stable, clinically essential niche medicine and device ecosystem built around skin test reagents (PPD and recombinant alternatives), administration consumables, and related diagnostic pathways. On an aggregate basis (base year 2025), global industry revenue sits in the high‑hundreds of millions (USD, million units), with a projected compound annual growth rate (CAGR) of 5.8% across the 2026–2032 forecast window. Under the central forecast, nominal market value approaches the low‑hundreds of millions by 2032—an outcome of steady demand, episodic public health campaigns, and selective product upgrades rather than rapid expansion.
Tuberculin Market
Market concentration remains relatively low by pharmaceutical standards: the three largest firms account for roughly one quarter of the market, and five firms for about one third. This fragmentation reflects the coexistence of legacy reagents, regional regulatory pathways, and differing procurement practices across public health programs and private markets—conditions that create opportunities for focused entrants and risk for unfocused incumbents.
Tuberculin Market
Why this matters for 2026 decision‑making
- Regulatory shifts are front‑row drivers. Recent reclassification and guidance moves (notably a March 2026 Federal Register action that clarified device class controls, and updated public health guidance) elevate compliance complexity and create short‑term operational hurdles for legacy product lines. Organizations must move from a compliance‑as‑cost mindset to a compliance‑as‑differentiator playbook—translating regulatory stability into predictable supply and faster tender access.
- Reimbursement and clinical guidance shape adoption more than raw innovation. CPT code structures and payer coverage determinations continue to influence testing volumes and the economic case for program administrators. For manufacturers, aligning labeling, coding, and clinical acceptance is a higher‑value activity than incremental reagent reformulation unless that reformulation clearly reduces total testing cost or improves sensitivity in a way payers will pay for.
- Supply chain and raw material governance are under renewed scrutiny. Reference strains, pharmacopeial monographs, and WHO standards underpin PPD production. Sourcing strategies that lock in compliant, transparent upstream processes mitigate regulatory stoppages and can be converted into procurement advantages with national public health customers.
Regulatory and reimbursement developments to act on in 2026
- Federal reclassification of tuberculin skin test devices to a Class II framework (March 2026) increases pre‑market and post‑market obligations—but it also creates a higher barrier for low‑quality entrants. Companies that proactively invest in controlled documentation, traceability, and post‑market surveillance will secure durable tender eligibility.
- Label updates from major suppliers (e.g., a 2026 label revision from a major vaccine subsidiary) underscore the need for active regulatory maintenance programs; static labeling will increasingly impede market access in institutional buyers’ procurement processes.
- Clinical guidance updates (notably revisions to testing guidance referenced by public health agencies in 2025–2026) will reweight the relative attractiveness of PPD formulations versus recombinant alternatives in specific patient cohorts. That creates narrow but critical windows for focused market campaigns and evidence dissemination.
- Reimbursement clarity (e.g., established CPT coding with broad payer recognition) supports stable unit economics for testing—but it makes cost‑per‑test the battleground for suppliers rather than wholesale price alone. Packaging, administration devices, and service bundles will be decisive value propositions.
Competitive landscape: incumbents, capabilities, and strategic gaps
The market features a mix of established vaccine manufacturers, diagnostics device specialists, and regionally dominant producers. Core players include multinational vaccine divisions with branded PPD products, medical device companies that dominate administration consumables, and national biotech groups supplying large public health programs. Each plays a distinct role in the value chain:
- Large vaccine subsidiaries maintain branded PPD reagents and occupy privileged positions in regulated markets through long‑standing relationships and robust pharmacovigilance infrastructures. Their advantage is regulatory muscle and brand trust; their risk is margin pressure as payers push for lower total testing costs and as new entrants introduce recombinant options.
- Medical device companies that focus on syringes and administration devices capture adjacent margin and can shape end‑user experience. Their strategic leverage is the ability to bundle consumables with reagent contracts, influencing procurement through convenience and standardized training programs.
- National and regional biotech groups sustain high volumes in large domestic programs. Their strengths are local manufacturing scale and procurement alignment, while their limits are international regulatory acceptance and export‑quality assurance for some markets.
Recent industry events (label updates, regulatory reclassification, and evidence‑based guidance changes) have already reordered supplier preferences among large institutional buyers. The net effect is an environment where compliance and demonstrated lifecycle management are becoming as important as reagent performance metrics.
What PW Consulting’s full Tuberculin Market study delivers (high‑value, actionable items)
Our full report is designed to be operationally prescriptive for 2026 planning cycles. Key deliverables include:
- Market sizing and validated demand scenarios (historical 2020–2025 validation and multiple 2026–2032 forecast paths) with sensitivity to epidemiologic scenarios and policy shocks.
- Regulatory matrix and readiness playbook—mapping Class II requirements, labeling expectations, and post‑market obligations across major jurisdictions, plus a compliance cost model for product lifecycle plans.
- Procurement and reimbursement playbooks that translate CPT, payer, and institutional tender dynamics into concrete pricing, bundling, and service strategies.
- Supply chain & raw material risk map—traceability profiles for reference strains, quality gating, contingency sourcing strategies, and supplier qualification templates aligned to WHO and pharmacopeial standards.
- Competitive intelligence dossiers—detailed company profiles, capability heatmaps, and strategic trajectories for incumbent and emerging suppliers.
- Commercial playbooks for new entrants and incumbents—go‑to‑market sequencing, evidence generation roadmaps, and salesforce/clinical liaison models tailored to public health programs and private healthcare buyers.
- Quantitative tools—scenario models and an executive dashboard that converts epidemiologic and policy inputs into expected volumes, revenues, and margin outcomes under alternate strategies.
Note: This briefing intentionally omits the full subsegment matrices and line‑item regional/application shares that underpin our scenario models; those datasets are available in the full report platform and are the primary conversion asset for procurement teams and investors.
Practical recommendations for different stakeholders
- Manufacturers with global ambitions: accelerate regulatory program investments now. Prioritize dossier readiness for Class II expectations, secure validated raw‑material contracts tied to WHO/P‑EP standards, and develop tender‑ready quality narratives. Convert compliance investments into a commercial advantage by packaging guaranteed supply timelines and documentation in tenders.
- Device and consumable suppliers: pursue bundled offerings with reagent partners and build training/service contracts that lock institutional buyers into multi‑year arrangements. Invest in human factors work that simplifies Mantoux administration and reduces operator variability—this is a high ROI area for buyers focused on program reliability.
- New entrants and innovators: target niche differentiation—recombinant formulations or administration technologies that demonstrably reduce total cost of testing or improve performance in defined populations. Use tightly scoped pilot programs with public health partners to generate the real‑world evidence needed to scale.
- Buyers and public health agencies: insist on traceability clauses and robust post‑market surveillance provisions when awarding multi‑year contracts. Use the reclassification moment to standardize supplier audit requirements and to require regulatory maintenance commitments as part of award criteria.
- Investors and M&A teams: prioritize targets with secure upstream strain access, documented quality systems, and demonstrated tender wins. Valuation premia will attach to firms that can show both compliance readiness and measurable program penetration in high‑volume national markets.
Risks and watchlist for 2026–2027
- Regulatory enforcement variability—uneven interpretation of Class II expectations across regions could create patchy market access and inventory dislocations.
- Clinical guidance shifts that favor alternative diagnostics in specific subpopulations—this would compress volumes for certain reagent formulations, making diversification important.
- Raw material constraints—production interruptions at key PPD producers or supply chain friction for reference strains will have outsized effects on public sector programs.
- Procurement squeezes that drive aggressive price and margin compression—necessitating service and outcomes‑based contracting to preserve sustainable economics.
Conclusion: the strategic playbook for 2026
Tuberculin remains a mission‑critical market characterized by modest growth but elevated strategic complexity. The combination of regulatory tightening, stable payer structures, and fragmented supplier positions means that advantage will accrue to organizations that pair disciplined compliance programs with procurement‑aware commercial strategies. In 2026, executives should treat tuberculin not as a commodity sell, but as a regulated program service where documentation, supply guarantees, and evidence generation win tenders and preserve margins.
PW Consulting’s full Tuberculin Market report contains the granular scenarios, supplier matrices, and tactical templates necessary to convert these insights into executable plans. For teams making budgetary, procurement, or M&A decisions this year, that detailed intelligence is the difference between tactical response and strategic leadership.
For detailed analysis of this topic, please visit the official page: Tuberculin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


