



Category: Healthy Lifestyle
PW Consulting: Tripterygium Glycosides Tablets Market Forecast to Reach USD 298.58 Million by 2032
By PW Consulting, 2026-07-13
Tripterygium Glycosides Tablets Market: Strategic Preview for 2026 Decisions
PW Consulting presents a forward-looking industry briefing on the Tripterygium Glycosides Tablets (TGT) market. This briefing synthesizes our newly completed market study (base year 2025, historical 2020–2025, forecast 2026–2032) and distills the strategic implications that matter for executives, investors, and policy-makers preparing for 2026. The analysis reveals a market on a steady growth trajectory driven by clinical demand within China, evolving scientific understanding, and concentrated manufacturing dynamics — while continuing to face safety, quality, and regulatory constraints that limit global roll-out.
Tripterygium Glycosides Tablets Market
Why this preview matters for 2026
-
Decision levers in 2026 will be less about market existence and more about competitive positioning, quality assurance, and pathway-to-internationalization. Our report equips leadership teams with the actionable frameworks required to make those choices under constrained regulatory visibility.
Tripterygium Glycosides Tablets Market -
With the global attention on autoimmune therapy innovation, TGT presents both a high-risk and high-opportunity profile: an established clinical footprint domestically, but persistent toxicity and quality-control concerns that make commercialization strategy and clinical development pathway design critical.
Tripterygium Glycosides Tablets Market -
For capital allocators, the timing of investments in manufacturing upgrades, clinical safety programs, and chemistry-quality standardization initiatives will determine 3–5 year returns. This briefing outlines the strategic trade-offs and priority initiatives for 2026.
Market trajectory and headline metrics
At the macro level, the TGT market demonstrates steady recovery and expansion following short-term fluctuations. PW Consulting’s market model places the 2025 market size at approximately 210.5 Million USD. Under our central scenario, the market is projected to expand at a compound annual growth rate (CAGR) of roughly 5.12% across the 2026–2032 forecast window, reaching an anticipated market value of just under 300 Million USD by 2032.
These aggregate figures underscore two important realities for 2026: first, market growth is significant enough to justify strategic investment in product quality and clinical evidence generation; second, the pace is measured — favoring disciplined, risk-managed capital deployment rather than aggressive expansion without remediation of known safety and supply-chain issues.
What the full report delivers (practical, executive-ready content)
PW Consulting’s full TGT market report goes beyond high-level charts. It contains practitioner-focused deliverables designed to be usable in boardrooms and corporate planning cycles:
-
Decision matrices for choosing between investments in GMP upgrades, analytical-method standardization, and R&D into toxicity mitigation strategies.
-
Clinical prioritization frameworks that align development programs with reimbursement pathways and domestic guideline positioning.
-
Supplier risk-scoring tools and an auditable methodology for assessing batch-to-batch chemical consistency and raw material traceability.
-
A phased go-to-market playbook for cross-border ambitions, including regulatory gap analyses, evidence generation roadmaps, and stepwise market-entry options.
-
Scenario-based financial models which quantify the impacts of alternative regulatory outcomes, safety-data releases, and pricing/reimbursement shifts.
Note: This preview intentionally omits the detailed regional, distribution-channel, and application-level splits contained in the full report. Those granular datasets, scenarios, and downloadable models are available on the source page.
Competitive landscape — players, positioning, and actionable intel
The TGT manufacturing landscape is concentrated and dominated by established domestic producers that combine clinical-supply relationships with legacy manufacturing capacity. Leading manufacturers in our assessment include Jiangsu Meitong Pharmaceutical, Zhejiang DND, Hunan Qianjin Pharmaceutical, Huangshi Feiyun Pharmaceutical, Shanghai Fudan Forward S&T, and Ningbo Liwah Pharmaceutical. These firms collectively shape supply dynamics, clinical study availability, and pricing pressure for standard TGT products.
-
Market structure: The market displays a moderate-to-high concentration among a small number of incumbents. That concentration creates both barriers and levers: incumbents can influence quality norms and clinical access, but they are also vulnerable to reputational risk if adverse-safety signals or quality inconsistencies are publicized.
-
Operational focus: Several manufacturers prioritize cost-effective domestic production and supply for clinical research; others are increasingly investing in standardization and analytical controls to reduce product heterogeneity.
-
Strategic moves to watch: product-supply agreements tied to clinical trials, investments in analytical-method validation, and partnership activity with research institutions aiming to mitigate toxicity concerns.
Our full report contains a company-by-company strategic assessment, sourcing footprints, margin-pressure analysis, and a short-list of acquisition/partnership candidates based on capability gaps and regulatory-readiness scoring.
Regulatory, clinical, and quality dynamics shaping 2026 strategy
TGT occupies a complex regulatory and clinical environment:
-
Regulatory scope: TGT is approved and widely used within China for rheumatoid arthritis and other autoimmune indications, but it lacks approvals outside China due to safety and quality-control concerns. For firms contemplating international expansion, 2026 strategy must prioritize robust toxicology, pharmacovigilance, and standardized manufacturing protocols.
-
Clinical positioning: TGT appears in domestic clinical guidelines as either a first-line or an add-on therapy in certain autoimmune contexts. This entrenched clinical use is a strategic asset but also binds manufacturers to higher standards of pharmacovigilance and post-market surveillance.
-
Safety profile: Peer-reviewed literature highlights hepatotoxicity, reproductive toxicity, and idiosyncratic drug-induced liver injury as material risks. These safety considerations directly influence labeling, monitoring requirements, and commercial messaging.
-
Quality heterogeneity: Analytical studies have identified significant variability in chemical composition across manufacturers — for example, consistent fingerprinting efforts have revealed dozens of shared and variable chromatographic peaks. This heterogeneity drives regulatory concern and complicates interchangeability claims.
For 2026, the imperative is clear: firms must invest in chemistry, manufacturing, and controls (CMC) excellence and clinical risk mitigation before pursuing scaled commercialization beyond domestic markets.
Recent developments to monitor going into 2026
-
Research momentum: A February 2026 review synthesized advances in mechanism elucidation, toxicity-reduction strategies, and clinical-applicability studies — signaling elevated scientific attention and potential pathways to safer formulations.
-
Clinical-supply linkages: In early 2025, one major manufacturer supplied TGT for a preclinical model of autoimmune encephalomyelitis, demonstrating continued use of TGT in experimental and translational research.
-
Implication: These developments expand the evidence base but also raise the bar for manufacturers: translational research activity increases scrutiny of product composition and safety characteristics.
Strategic recommendations for 2026
-
Prioritize quality harmonization programs: Invest in validated analytical fingerprints, batch-release criteria, and third-party reference standards. Firms that can credibly demonstrate product consistency will command strategic optionality.
-
Build clinical-safety evidence rather than relying solely on real-world domestic usage: Sponsor prospective pharmacovigilance studies and targeted toxicology programs to de-risk regulatory conversations outside China.
-
Leverage concentration dynamics tactically: Incumbents should consider defensive moves — securing supply agreements with leading clinical centers — while challengers should explore differentiation through demonstrable quality and safety improvements.
-
Prepare phased internationalization blueprints: Adopt a staged path to external markets that sequences enhanced CMC, focused clinical data packages, and regulatory engagement rather than immediate broad-market applications.
-
Engage payers and guideline committees proactively: For markets where reimbursement is formalized, early liaison with guideline bodies and payers will be critical to maintain domestic positioning and to support any abroad reimbursement cases.
How PW Consulting supports your 2026 playbook
PW Consulting’s full-market deliverable contains the operational tools you need to convert insight into execution: customizable financial models, supplier risk matrices, analytical-method templates, and a staged regulatory-engagement playbook aligned to the most likely 2026–2028 pathways. We also provide a confidential advisory offering to help boards and executive teams prioritize investment choices across manufacturing, clinical, and market-access tracks.
This preview is intentionally selective. Our analysis demonstrates the market’s attractive growth profile at the aggregate level and highlights the structural constraints that will determine winners and losers in 2026. For immediate access to the full dataset, granular region- and application-level splits, and the downloadable strategic toolkit, please consult the report landing page.
Closing note
Tripterygium Glycosides Tablets sit at the intersection of traditional clinical use and modern regulatory expectations. In 2026, the most successful organizations will be those that treat TGT not merely as a commodity but as a complex biologically active product requiring rigorous control, clear clinical strategies, and disciplined capital allocation. PW Consulting’s full report provides the playbook to do exactly that.
For detailed analysis of this topic, please visit the official page: Tripterygium Glycosides Tablets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Waist-Level Viewfinder Market Poised to Grow at a 1.45% CAGR Through 2032
By PW Consulting, 2026-07-13
Waist Level Viewfinder Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest Waist Level Viewfinder Market preview synthesizes primary research, pricing intelligence, and product-level analysis to inform strategic choices through 2026 and beyond. The market shows a steady, low-single-digit trajectory: from an estimated USD 27.68 Million in 2023, to USD 28.5 Million in the 2025 base year, with a forecast that reaches approximately USD 31.52 Million by 2032. Our compound annual growth rate assumption for the forecast horizon is 1.45% (2026–2032). These headline metrics underscore a mature, niche market with durable demand but constrained expansion — precisely the environment where targeted strategic moves and operational excellence determine winners.
Waist Level Viewfinder Market
Why this report matters for 2026 strategic planning
-
Market maturity and margin pressure: Modest aggregate growth masks divergent sub-market behavior. High-end, branded interchangeable viewfinders retain premium pricing power, while compact third‑party accessories are compressing margins in the broader accessory channel. A clear understanding of where value accrues is essential for 2026 capex, product, and channel allocation.
Waist Level Viewfinder Market -
Product innovation is re-shaping demand pathways: Prototype activity from major OEMs and a burst of affordable third‑party accessories have created parallel demand streams that require distinct go‑to‑market approaches.
Waist Level Viewfinder Market -
Concentration and partnership dynamics: The market exhibits meaningful concentration among a few incumbent players (our headline concentration metrics show top‑3 and top‑5 firm shares that reflect a market where both heritage brands and agile challengers matter for ecosystem formation).
What the full PW Consulting report delivers (practical, decision-ready content)
-
Clean, auditable sizing and forecast model — base year 2025; historical series 2020–2025; forward-looking projections 2026–2032 (USD Million).
-
Segment-focused scenario workbooks — demand scenarios calibrated to product types, distribution channels, and end‑use cohorts, with sensitivity levers for price, OEM participation, and accessory substitution.
-
Competitive positioning playbooks — detailed profiles, capability-maps, and value‑capture mechanics for leading OEMs, aftermarket specialists, and accessory manufacturers.
-
Commercial roadmaps — go‑to‑market templates for OEMs, accessory brands, and specialty retailers, including pricing architecture, channel mix optimization, and launch/timing checklists.
-
Product-development KPIs — recommended optical, mechanical, and integration metrics for hybrid optical/digital viewfinders, with tolerance bands and supplier qualification guidance.
-
M&A and partnership filter — acquisition candidate archetypes and an acquisition valuation compass tuned to niche manufactured goods and aftermarket services.
-
Retail and rental economics — unit economics for retail vs. rental strategies in professional studio and fine-art channels, and guidance on inventory exposure to used‑market dynamics.
High-level demand dynamics shaping 2026
The waist level viewfinder market is being driven by a mix of heritage and novelty. On one hand, established medium‑format ecosystems and professional studio workflows continue to value the waist‑level shooting posture for framing precision and creative control. On the other, the mirrorless renaissance has created a new addressable audience: photographers seeking tactile, retro-inspired shooting experiences without committing to bulkier systems.
Product-level dynamics are bifurcated. Boutique, interchangeable waist‑level finders — either as OEM accessories or bespoke high-end aftermarket items — retain margin resilience by catering to professional and enthusiast segments. At the same time, low-cost optical WLV accessories (aluminum housings, magnetic hoods, universal cold‑shoe compatibility) are proliferating, expanding adoption among hobbyists and mirrorless users but exerting price pressure across channels.
Notable 2025–2026 developments that crystallize these trends include multiple product launches from third‑party accessory makers and OEM experimentation with retro optical designs at major trade shows. In particular, a leading OEM showcased prototype digital cameras with waist‑level optical viewfinders at a 2026 industry show, signaling potential strategic interest in hybrid optical experiences that combine manual control with modern digital workflows. Complementing this OEM activity, third‑party manufacturers released compact aluminum optical finders priced to attract impulse purchases and accessory upgrades — a dynamic that increases shipment volumes but reduces average selling prices.
Competitive landscape — reading intent from incumbent and challenger moves
-
Hasselblad (Gothenburg, Sweden) — An iconic medium‑format manufacturer that incorporates waist‑level options into premium camera ecosystems. Hasselblad’s approach emphasizes integrated design, serviceability, and accessory ecosystems that sustain high ASPs. For market entrants, Hasselblad’s strategy illustrates the value of brand‑anchored accessory bundling and certified aftermarket channels.
-
Ulanzi (China) — A prolific accessory manufacturer focusing on compact, universally compatible optical WLVs. Ulanzi’s volumes and pricing put pressure on the low end but open distribution channels through online marketplaces and camera stores. Their product tactics highlight speed to market and channel penetration as a viable route for scale.
-
CHI / Chinotechs (China) — Producer of metal‑built finders with a retro aesthetic and multiple frameline options. CHI demonstrates how form factor and perceived craftsmanship can be monetized at modest price premiums in the mass accessory market.
-
Reflx Lab (China) — Compact universal accessories designed for cold‑shoe compatibility. Their existence underscores the modular accessory opportunity for mirrorless platforms.
-
Mamiya (Japan) — A historical medium‑format name with ongoing aftermarket relevance. Mamiya’s position is illustrative of long tails in used and service markets where legacy optics and finder systems retain value.
-
Canon (Tokyo, Japan) — Recent prototype demonstrations of SLR‑style digital cameras with waist‑level optical viewfinders suggest a deliberate exploration of retro‑optical user experiences from an OEM that can influence supply chain, distribution, and consumer expectations should it adopt limited production runs or offer accessory kits.
Strategically, the market is characterized by meaningful concentration: top‑tier players control a substantial share of value realization, while a competitive fringe drives volume. This structure favors alliance strategies — OEMs licensing design cues to third‑party makers, or accessory specialists securing OEM certification — and cautions against unconstrained price competition in commoditized segments.
Risks, white spaces and recommended moves for 2026
-
Risks: rapid commoditization from low‑cost accessories; supply chain dependence on a narrow set of component suppliers; intellectual property and design differentiation erosion; and demand sensitivity to retro trends. These create execution risk for new product launches and price vulnerability for incumbents.
-
White spaces: hybrid optical/digital viewfinders that integrate framing overlays or electronic assist; certification and warranty bundles that bridge OEMs and accessory makers; curated bundles for studio and landscape verticals; and rental/subscription models that monetize episodic professional demand.
-
Recommended 2026 moves: For OEMs — pilot limited‑edition retro models or certified accessory programs to capture both premium and mainstream interest without broad mass production risk. For accessory brands — codify quality tiers, pursue certification partnerships, and prioritize optical quality and mount reliability over marginal cost reductions. For investors — target niche manufacturing assets with low capital intensity and strong aftermarket service orientation. For retailers — curate differentiated assortments that combine heritage brands with best‑in‑class affordable accessories to protect margin and retention.
Methodology and data integrity
The findings are based on a transparent synthesis of primary interviews with OEM product managers, accessory manufacturers, specialty retailers, and studio operators; secondary pricing sweeps across major e‑commerce and brick‑and‑mortar channels; shipment proxies; and used‑market flow analysis. The modeling framework uses 2025 as the base year, covers historical performance from 2020–2025, and projects 2026–2032 in USD Million. Concentration metrics are included to assess competitive structure and strategic room for consolidation.
How to use this preview in your 2026 planning
This brief is designed as a strategic lead‑in: it equips decision makers with the market context, competitive signals, and directional levers necessary to prioritize product investments, channel strategies, and partnership conversations in 2026. For teams preparing product roadmaps, budget allocations, or M&A screens, the full PW Consulting report contains the operational worksheets, scenario models, and vendor matrices needed to move from insight to action.
To access the complete dataset, granular segmentation tables, and executable playbooks — including downloadable financial workbooks and supplier scorecards — please visit the PW Consulting report page or contact our industry team for a tailored briefing and enterprise license options. The public preview above intentionally omits fine‑grained segment tables to preserve the tactical value of the full research package.
For detailed analysis of this topic, please visit the official page: Waist Level Viewfinder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wallichinine Market Climbs to USD 5.2 Million in 2025, Poised for 4.2% CAGR Through 2032
By PW Consulting, 2026-07-13
Wallichinine Market 2026 Strategic Preview — PW Consulting Industry Brief
Executive summary
As life‑science companies, specialty chemical suppliers, and institutional investors prepare their 2026 plans, the Wallichinine market presents a classic niche-growth challenge: limited absolute dollar scale yet strategically disproportionate importance for specific R&D and procurement decisions. PW Consulting’s latest market research shows that the Wallichinine market reached roughly USD 5.2 Million (base year 2025) after steady expansion from the early 2020s, and is forecast to grow at a compound annual growth rate (CAGR) of approximately 4.2% through 2032, reaching an estimated USD 6.9 Million by the end of the forecast horizon. This preview highlights the implications of that trajectory for corporate strategy in 2026 while preserving the proprietary, segment‑level detail available in the full report.
Wallichinine Market
Why Wallichinine matters for 2026 corporate decisions
-
Research intensity over absolute volume: Wallichinine’s primary market is research use — pharmaceutical research, academic and clinical studies — rather than large‑scale commercial deployment. That makes supplier selection, purity control, and regulatory positioning disproportionately important relative to market size.
Wallichinine Market -
Procurement and continuity risk: Raw material sourcing (Wallichinine is predominantly isolated from Piper species) and single‑sourcing exposure can create brittle supply chains for organizations that depend on consistent, high‑purity material for sensitive assays. Procurement teams that optimize supplier diversification in 2026 can avoid outsized disruption costs.
Wallichinine Market -
Scientific inflection points: Emerging preclinical findings — for example, studies indicating activity as a PAF antagonist and potential reversal of ABCB1‑mediated multidrug resistance — mean that unexpected demand spikes or specification changes could arise quickly if translational research advances. Strategic monitoring of the scientific pipeline is therefore a 2026 imperative.
-
Regulatory clarity for RUO products: The supply chain for Wallichinine is explicitly positioned for research use only (not approved for human or veterinary therapeutic use). Companies that act on this market must ensure labeling, contractual terms, and compliance processes are tightly aligned to avoid regulatory or liability exposure.
Market trajectory and what the numbers mean
The market’s modest absolute scale masks two useful planning signals. First, historical growth from the low‑millions in 2020 to roughly USD 5.2 Million in 2025 reflects steady, research‑driven demand that survived episodic macro volatility. Second, the forecasted ~4.2% CAGR to 2032 implies predictable, incremental expansion rather than explosive commercialization — a landscape suited to targeted strategic moves (e.g., quality‑of‑supply differentiation, value‑added services, or focused alliances) rather than broadscale capacity expansion.
For procurement and R&D leaders, this means 2026 decisions should prioritize supplier quality, availability guarantees, and technical support rather than volume discounts alone. For investors and M&A teams, the market’s trajectory suggests value will accrue to companies that can lock in premium positions in high‑purity offerings, technical validation services, and rapid regulatory compliance for RUO pathways.
Supply chain and dynamics — practical considerations for 2026
-
Raw material sourcing: Wallichinine is primarily isolated from the stems of Piper wallichii and related Piper species. That botanical dependency introduces agricultural, seasonal, and geopolitical variables into sourcing strategies that procurement must model explicitly in 2026.
-
Purity segmentation: Market demand is concentrated around high‑purity grades for reference standards and sensitive assays. Buyers should require certificate of analysis (COA) consistency, stability data, and batch traceability as part of standard procurement terms.
-
Service expectations: Leading suppliers differentiate through documentation (method of isolation, spectral data), customized packaging and sizes for small‑batch research use, and rapid turnaround for urgent assay requirements. Expect these service elements to be decisive in 2026 negotiations.
-
Regulatory positioning: All players in the supply chain currently position Wallichinine strictly for research use only. Companies entering adjacent areas (e.g., translational studies that approach clinical contexts) must plan for regulatory consultation and enhanced QA/QC pathways well in advance.
Competitive landscape — who to watch
The Wallichinine supply ecosystem combines specialist manufacturers, life‑science reagent suppliers, and distributors. The competitive field is moderately concentrated: a small group of established vendors command meaningful influence over quality standards, reference‑grade supply, and commercial relationships. Strategic 2026 engagement should therefore prioritize a select set of due‑diligence activities rather than broad market scans.
-
Pharmaffiliates (India) — Known for supplying high‑purity Wallichinine as reference standards and life‑science reagents. Their emphasis on analytical documentation and reference standard services makes them a primary partner choice for labs needing traceable, validated material.
-
ChemFaces (China) — A natural products manufacturer offering high‑purity isolates derived from Piper species. Their upstream access to botanical sources and integrated isolation processes is an advantage for customers prioritizing supply chain transparency and cost‑effective high‑purity material.
-
Adooq Bioscience (USA) — A distributor/supplier that provides Wallichinine in multiple pack sizes for research use. Their strengths lie in logistics flexibility and customer service models tailored to academic and small‑scale industrial buyers.
-
BioBioPha Co., Ltd. (China) — A biochemical supplier with a focus on natural compounds; relevant for buyers seeking regional supply alternatives and catalogue breadth.
-
Alfa Chemistry (USA) and MedKoo Biosciences (USA) — Western suppliers that combine regulatory awareness and established distribution channels into research institutions; useful partners for organizations prioritizing compliance and traceability.
In 2026, competitive advantage will accrue to suppliers that can demonstrate: (1) consistent analytical verification tied to internationally recognized methods; (2) supply continuity plans for botanical raw materials; and (3) a clear compliance posture for research‑use distribution.
What the PW Consulting Wallichinine report delivers (operational, actionable content)
Our full study is intentionally crafted as a practitioner’s toolkit to support operational decisions in 2026. Highlights include:
-
Proprietary market model with historical series and scenario‑based forecasts (base year 2025; forecast 2026–2032) to support budgeting and volume planning.
-
Supplier due‑diligence framework and scorecard templates to operationalize quality, traceability, and responsiveness assessments.
-
Go‑to‑market playbooks for suppliers targeting pharmaceutical research vs. academic buyers, including pricing architecture, pack‑size strategies, and technical service offerings.
-
Procurement playbook for buyers: contracting language, COA requirements, contingency planning, and short‑list criteria for single‑source vs. multi‑source strategies.
-
Regulatory and compliance checklist specific to RUO positioning, labeling, and cross‑border transfer requirements.
-
Technology and scientific watchlist capturing preclinical advances (e.g., PAF antagonism, ABCB1 MDR reversal) that could trigger demand volatility.
-
Risk matrix and mitigation options covering botanical supply, geopolitical exposure, and specification drift.
-
Executive‑level M&A and partnership map highlighting logical strategic targets and the valuation drivers buyers should prioritize.
Strategic recommendations for 2026 decision‑makers
-
For suppliers: Invest selectively in high‑purity validation and customer‑facing technical documentation. These investments yield premium positioning in a market where trust and traceability matter more than scale.
-
For buyers (academic and industrial): Adopt a two‑tier sourcing strategy — primary trusted supplier(s) with contractual continuity clauses plus a validated alternate to protect against botanical or logistical shocks.
-
For investors and corporate development: Look for targets that own upstream botanical sourcing, proprietary isolation know‑how, or differentiated analytical capabilities. These are the value drivers that support margin expansion in a steady‑growth market.
-
For R&D managers: Maintain close coordination with procurement and regulatory functions. If a project’s translational pathway moves beyond RUO expectations, preemptive regulatory engagement will save time and cost downstream.
Risk scenarios to model in 2026
-
Supply interruption: A localized crop failure or export restriction could cause short‑term scarcity. Scenario planning should quantify the premium buyers would reasonably pay for continuity and identify substitution thresholds.
-
Scientific breakthrough: If translational validation accelerates, demand could shift from RUO channels toward larger‑scale, regulated supply needs — a dramatic shift for a market that currently remains research‑focused.
-
Regulatory tightening: Stricter RUO definitions or cross‑border compliance requirements could increase compliance costs and favor larger suppliers with established quality systems.
How to use this preview — and where to find more
This brief is designed as a strategic “trailer” that highlights the decision levers and operational playbooks necessary for effective 2026 planning while preserving the granular segmentation, supplier scorecards, and proprietary datasets that underpin our conclusions. The full PW Consulting Wallichinine Market report contains the detailed models, supplier scorecards, and downloadable procurement templates referenced here — including regional and application breakdowns, price‑trend matrices, and a validated vendor watchlist.
For teams building 2026 budgets, supplier tender schedules, or M&A target lists, the full report will convert the high‑level implications in this brief into executable plans. Visit PW Consulting’s report page to access the complete study, data appendices, and a customizable Excel model to stress‑test scenarios against your specific demand profile.
Closing perspective
Wallichinine exemplifies a class of specialty compounds where strategic foresight, supplier governance, and scientific monitoring matter more than sheer market scale. In 2026, organizations that translate the modest but stable market growth into disciplined procurement, validated supplier partnerships, and proactive scientific surveillance will capture the upside while insulating projects from supply and regulatory shocks. PW Consulting’s full report equips decision‑makers with the models and playbooks necessary to do exactly that.
For detailed analysis of this topic, please visit the official page: Wallichinine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Aluminum Bioclimatic Pergolas Market to Reach USD 1,382.9 Million by 2032
By PW Consulting, 2026-07-13
Aluminum Bioclimatic Pergolas Market — Strategic Preview for 2026 Decision-Makers
As executive teams plan their 2026 capital allocations and product roadmaps, PW Consulting presents a focused preview of our new market study on Aluminum Bioclimatic Pergolas. The sector is entering a phase of sustained expansion driven by product innovation, changing use-cases for outdoor living, and regulatory pressures toward energy efficiency and recyclability. This preview synthesizes the report’s highest‑value strategic insights without disclosing the full segmentation data reserved for the complete publication.
Aluminum Bioclimatic Pergolas Market
Market trajectory at a glance
Our analysis shows the market expanding from an assessed base of USD 850.0 Million in 2025 to an estimated USD 897.3 Million in 2026, with a forecast compound annual growth rate (CAGR) of 7.2% across the 2026–2032 horizon. By the end of the forecast period, the market is modeled to reach approximately USD 1,382.9 Million. The historical run (2020–2025) reflects consistent recovery and premiumization trends that underpin the projection: buyers are paying for durability, integrated climate control, and smart features rather than commodity shading alone.
Aluminum Bioclimatic Pergolas Market
Why this matters for 2026 planning
- Revenue scale and predictability: The market’s mid-single-digit to low‑double‑digit growth profile supports disciplined investments in product development and channel expansion while limiting exposure to highly speculative bets.
- Fragmented supplier base: Market concentration remains modest (CR3 ~18.5%; CR5 ~24.1%), indicating that scale advantages are emergent but far from entrenched — a window for new entrants and private-label strategies.
- Margin compression risks: Rising raw-material and processing costs create pressure points for manufacturers; pricing power will be earned through differentiation (smart integration, certification, warranties) rather than through cost leadership in many Western markets.
What PW Consulting’s full report delivers (practical, action-oriented)
- Proven market-sizing methodology and a validated 2020–2025 historical data set leading into our 2026–2032 forecast model.
- Segment-level demand drivers and elasticity assumptions across region, product type, and application—presented as scenario outputs to support stress testing and valuation work (note: granular split values are available in the full report).
- Competitive benchmarking with strategic profiles and capability maps for the leading suppliers, plus a vendor selection matrix for OEMs, distributors, and architectural specifiers.
- Go‑to‑market playbooks for incumbent brands and challengers: pricing ladders, channel mix strategies (direct vs. dealer networks), specification workflows, and digital sales acceleration tactics.
- Operational playbooks: supply-chain risk mitigation (inventory buffers, alloy sourcing strategies, extrusion partnerships), manufacturing footprint evaluation, and installation & aftersales service models.
- Regulatory and sustainability guidance: certification roadmaps, recyclable‑aluminum claims, and green‑building alignment to maximize project wins in commercial and public projects.
- Case studies and implementation templates for hospitality, residential retrofit, and commercial campus deployments, including sample ROI windows and lifecycle cost frameworks.
Competitive landscape — strategic takeaways
The sector is characterized by a mix of premium European design houses, North American innovators with smart‑home focus, and high‑volume Asian manufacturers. Key strategic behaviors we observed among leading vendors:
Aluminum Bioclimatic Pergolas Market
- StruXure Outdoor (Dahlonega, GA): Plays the premium, technology‑first angle — motorized louver systems, integrated heat/sound/screens, and app ecosystems. Their investment in certification for wind and snow load compliance and in updated product lines (notably 2025 launches) positions them strongly in markets where structural certification accelerates institutional and spec sales.
- Azenco Outdoor (Miami, FL): Combines motorized aluminum systems with product diversification (e.g., retractable fabric offerings). Recent trade show activity demonstrates a go‑to‑market emphasis on broadening the product portfolio to capture both high‑end and practical coastal-use cases.
- Renson & Solisysteme (Belgium and France): Represent the high-touch European premium segment, focusing on customization, integrated climate systems, and configurators that shorten the specification cycle for architects and designers.
- Palmiye & Kenan Metal (Turkey); AlunoTec & Seroban (China): Showcase scale-driven offers that prioritize cost-competitive production, waterproofing innovations, and export readiness. These players are logical partners for OEM supply and private-label strategies.
- Biossun & Gibus (France & Italy): Differentiate on sustainability and design craftsmanship — solar integration and artisanal finishes, respectively — helping them win hospitality and high-end residential projects.
For suppliers and investors, the strategic implication is twofold: (1) differentiation via systems integration (smart controls, energy capture, climate comfort) is a reliable route to margin expansion, and (2) geographic and channel diversification remain essential to balance seasonality and raw-material exposure.
Recent industry moves worth watching
- StruXure’s 2025 product upgrades (sound, heat, screens, app enhancements) signal an arms race in platform capabilities — expect increased R&D investment across peers.
- Azenco’s participation in major trade shows in early 2026 reflects intensified efforts to cross‑sell fabric and aluminum systems, implying converging product lines and bundled offers.
- Increased trade show visibility among smaller OEMs suggests a push to accelerate international distribution partnerships in 2026.
Market dynamics and risk factors
Several structural dynamics will shape 2026 decisions:
- Raw-material volatility: Aluminum pricing has been elevated, with primary and extrusion costs showing wide ranges. In late 2025 and through mid‑2026 market prices demonstrated material variation. Procurement strategies — hedging, term contracts, and alloy substitution — will materially affect gross margins.
- Sustainability and regulation: Green building standards increasingly demand recyclable materials and lifecycle transparency. Manufacturers that can certify recycled content and demonstrate end‑of‑life recovery will unlock specification advantages in institutional and commercial projects.
- Demand shift to year‑round usability: Buyers favor pergolas engineered for all‑season use (waterproofing, snow load performance, integrated heating). This favors suppliers who can marry structural certification with automation and climate control.
- Channel & specification dynamics: Architects and hospitality procurement teams prioritize certified performance and integrated solutions, while consumer buyers are driven by ease of installation, financing options, and aftersales service.
Actionable recommendations for 2026
PW Consulting advises the following prioritized actions for executives preparing 2026 plans:
- Product & certification strategy: Allocate R&D to obtain structural and energy‑efficiency certifications that shorten procurement cycles for commercial tenders. Consider modular systems that allow upgrade paths (e.g., add-on solar, sensors).
- Pricing & value packaging: Shift from pure hardware pricing to value bundles (installation + warranty + connected services). Offer lease/finance options to accelerate adoption in residential markets.
- Supply-chain resilience: Lock multi‑year extrusion agreements, evaluate nearshoring for high‑volume SKUs, and test alternative alloy mixes in pilot lines to protect margins.
- Channel optimization: Expand spec‑sales teams to engage architects and developers; build certified installer networks to lower delivery friction and protect brand experience.
- Digital & aftersales: Invest in configurators and AR tools for client visualization, and launch subscription-based maintenance plans to create recurring revenue streams.
- Partnerships & M&A: Consider bolt-on acquisitions for automation electronics, solar integration, or local installation platforms to accelerate capability delivery.
How PW Consulting helps
Our full Aluminum Bioclimatic Pergolas Market report provides the granular segmentation, vendor financial proxies, pricing decks, and downloadable implementation templates referenced above. It is designed to be directly actionable for commercial leaders, product strategists, supply‑chain chiefs, and private‑equity sponsors evaluating portfolio plays in outdoor living and building‑envelope adjacencies.
To access the full dataset, model files, and our step‑by‑step 90‑day playbook for market entry or growth acceleration, please visit the PW Consulting report page or contact our practice lead for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Aluminum Bioclimatic Pergolas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Josamycin Tablets Market to Reach USD 124.0 Million by 2032, Growing at a 3.82% CAGR
By PW Consulting, 2026-07-13
Josamycin Tablets Market — Strategic Outlook for 2026: Executive Insights from PW Consulting
As PW Consulting’s lead industry analyst, I present a concise, decision-focused preview of our latest Josamycin Tablets Market report. Built on a 2020–2025 historical base and a detailed forecast through 2032, this briefing highlights the strategic value of the report for executive teams planning resource allocation, commercial entry, supply-chain resilience, and M&A activity in 2026. The full report provides the granular regional, dosage, and indication splits that underpin the recommendations below — this executive preview intentionally omits core subsegment figures to guide readers to the complete deliverable.
Josamycin Tablets Market
Market snapshot and near-term trajectory
The josamycin tablets market has demonstrated steady expansion through the first half of the decade, rising from a modest base in 2020 to an estimated USD 95.5 Million in 2025. Our forecast indicates continued expansion through the 2026–2032 horizon, with the market projected to approach roughly USD 124.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of approximately 3.82% across the forecast period. This pace reflects a mature therapeutic category with pockets of growth driven by supply reconfiguration, localized manufacturing, and selective clinical adoption in markets outside North America.
Josamycin Tablets Market
Why this matters for 2026 corporate decisions
-
Portfolio prioritization: The steady, mid-single-digit growth profile suggests josamycin should be a strategic niche within broader anti-infectives portfolios rather than a capital-intensive primary focus. Companies should prioritize formulations and presentations with the best route-to-market and lowest regulatory friction in target geographies.
Josamycin Tablets Market -
Supply-chain strategy: Raw-material dynamics are material. Global josamycin active pharmaceutical ingredient (API) production reached roughly 80 tonnes in 2025, with average reported market pricing near USD 4,000 per kilogram. A concentrated API supply base — with China controlling a substantial share of antibiotic API capacity — creates both cost advantages and single‑source risks that must be actively managed through multi-sourcing, local inventory hedging, and quality‑assured partnerships.
-
Regulatory prioritization: Josamycin remains unapproved by the U.S. Food and Drug Administration, limiting direct commercial opportunity in North America. For companies with global ambitions, this means prioritizing regions offering clearer pathways to registration and commercialization in 2026 while monitoring potential regulatory shifts that could unlock longer-term expansion.
-
Commercial timing: We observe immediate commercial opportunity where originator withdrawals and supply gaps have created unmet demand. Firms able to scale localized manufacturing quickly — and demonstrate quality and continuity of supply — can capture share more efficiently than entrants relying solely on export supply chains.
-
M&A and partnership focus: With market concentration indicating a non-trivial share controlled by a small group of players, strategic partnerships (manufacturing supply agreements, licensing, or bolt-on acquisitions) offer faster, lower-risk access to marketable volumes and regulatory dossiers than greenfield entries.
What the report delivers — practical, transaction-grade intelligence
Our report is constructed for deployment use by corporate strategy, BD&L, procurement, and commercial teams. It contains:
-
Validated historic market sizing (2020–2025) and bottom‑up scenario forecasts (2026–2032) with sensitivity analyses.
-
Segmented demand modelling by geography, dosage form, and clinical indication (note: the preview omits detailed splits; the full report contains the complete tables and model files).
-
Pricing and cost curve analysis, including API cost pass-through models and break-even manufacturing thresholds for different production footprints.
-
Supplier due‑diligence templates and API quality risk matrices tailored to josamycin-specific synthesis and impurity profiles.
-
Regulatory pathway maps highlighting registration complexity across major and emerging markets, including practical timelines and cost estimates.
-
Commercial playbooks: go-to-market scenarios for direct distribution, local partnership, contract manufacturing, and licensing — each with revenue, margin and time-to-market estimates.
-
Competitive intelligence dossiers and capability maps for the principal manufacturers, plus a deal and pipeline tracker.
-
Operational checklists for manufacturing scale-up, formulation bridging, and post-marketing surveillance obligations.
Competitive landscape — implications for 2026
The competitive picture is characterized by a mix of legacy originators, regional generics producers, and newer localized manufacturers stepping into vacated supply niches. The market shows mid-level concentration (top‑three and top‑five concentration metrics are summarized in the full report), indicating the presence of large incumbents but also meaningful opportunity for agile regional players.
-
Promomed (Moscow) — Promomed’s establishment of full-cycle localized production and the October 2025 registration/launch of their josamycin dispersible formulation is a case study in fast, demand-driven capacity creation. Their initiation of a real-world clinical study in April 2026 underscores the commercial value of coupling supply with evidence generation to accelerate adoption in hospital and outpatient formulary decisions.
-
Pharmstandard — As a domestic generic manufacturer with established branded generics, Pharmstandard exemplifies how regional firms can monetize existing registration footholds and customer relationships when originators deprioritize markets.
-
Asian manufacturers (Guilin, LTL, Thai Meiji, Siam, Suzhou No.1) — Multiple producers across China, Japan and Southeast Asia supply finished-dose tablets and active ingredient to local and export markets. Their manufacturing depth and proximity to API supply create structural cost advantages — but also intensify price competition. Strategic buyers should evaluate supplier stability, regulatory history, and capacity flexibility when contracting.
-
Astellas Pharma — The historical role of the originator provides valuable clinical and regulatory precedent, even where its commercial footprint has shifted. Legacy dossiers, formulation know-how and prescriber familiarity with originator formulations represent both a barrier and an opportunity for new entrants seeking to secure reimbursement and formulary acceptance quickly.
Near-term tactical playbook (for 2026 execution)
-
Fast-follower manufacturing: Prioritize contract manufacturing agreements with suppliers who can provide validated batches and export documentation within 6–9 months. Where feasible, secure options for localized packaging or secondary formulation to accelerate tender eligibility.
-
API risk mitigation: Negotiate multi-year API contracts with tiered pricing linked to quality metrics; build a small strategic API buffer stock to absorb short-term disruptions that historically arise from synthesis bottlenecks.
-
Evidence and access: Sponsor pragmatic, real‑world studies (like the one initiated by Promomed) to substantiate local clinical performance and cost-effectiveness for payers and hospital procurement committees.
-
Regulatory sequencing: De-prioritize immediate North American investment unless a clear regulatory pathway materializes. Focus 2026 regulatory spend on markets with streamlined registration and tender-driven demand.
-
M&A and licensing: Target small-to-mid sized manufacturers with compliant facilities and existing registration dossiers — these assets accelerate time-to-revenue and limit R&D outlays.
Risk considerations
-
Regulatory risk: Continued lack of U.S. approval constrains addressable market size and may limit interest from large global buyers unless regulatory landscapes change.
-
Supply concentration: API market dynamics and reliance on a few geographies for synthesis create exposure to trade disruptions and price volatility.
-
Price erosion: Presence of multiple cost-competitive Asian and regional suppliers exerts downward pressure on margins; differentiation via service, supply security, and evidence is essential.
-
Reputation and compliance: Quality lapses at any node in the supply chain can produce immediate tender exclusion; rigorous supplier audit and quality control frameworks are non-negotiable.
How PW Consulting’s report supports dealmakers in 2026
For executives considering market entry, capacity investment, licensing, or M&A in 2026, our josamycin report supplies the empirical basis to size opportunities, model returns under multiple scenarios, and operationalize execution. The report’s market model is delivered in editable financial templates so deal teams can stress-test assumptions with proprietary cost and pricing inputs.
We intentionally keep this briefing at the strategic level. The full report contains:
-
Complete regional, dosage and indication splits and tables;
-
Company-level shipment and capacity estimates, with annotated sources;
-
Detailed API supply maps and supplier scoring;
-
Executable templates for RFQs, supplier audits, and regulatory timelines.
Next steps
If your 2026 planning requires precise market share estimates, supplier shortlists, or a tailored financial model that incorporates your cost base and strategic priorities, PW Consulting can provide the full Josamycin Tablets Market report and a bespoke client workshop to translate insights into an actionable implementation plan.
Contact our Business Development team to schedule a briefing and obtain the complete report package, including the downloadable market model and competitive dossiers. For teams preparing transaction memoranda or procurement strategies, we recommend securing the full dataset before finalizing any commitments.
— PW Consulting, Market Intelligence & Strategy Practice
For detailed analysis of this topic, please visit the official page: Josamycin Tablets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microtubule Inhibitor Drugs Market Poised to Expand at a 5.5% CAGR Through 2032
By PW Consulting, 2026-07-13
Microtubule Inhibitor Drugs Market: Strategic Bearings for 2026 — A PW Consulting Brief
As oncology portfolios and translational pipelines shift toward precision payloads and antibody–drug conjugates (ADCs), microtubule inhibitor drugs remain a cornerstone of cytotoxic and targeted combination strategies. PW Consulting’s latest market research — with a 2025 base year and a forecast horizon covering 2026–2032 — quantifies a steady expansion of the microtubule inhibitor market and distills practical imperatives for enterprise decision-makers entering 2026. This briefing highlights the report’s strategic value without disclosing the proprietary segmentation details reserved for subscribers.
Microtubule Inhibitor Drugs Market
Executive snapshot
Our analysis shows the global microtubule inhibitor market has demonstrated resilient growth through the early 2020s and is projected to continue expanding over the coming decade. After recovering and expanding in the 2020–2025 historical window, the market enters the 2026–2032 forecast period with a compound annual growth rate (CAGR) of approximately 5.5%. By the end of the forecast horizon, PW Consulting anticipates clear upside driven by novel ADC approvals, ongoing lifecycle management of legacy agents, and geographic and indication-level expansion.
Microtubule Inhibitor Drugs Market
Why this report matters for 2026 planning
- Investment prioritization: The market’s mid-single-digit CAGR combined with concentrated competitive dynamics requires disciplined capital allocation. Our report translates macro momentum into actionable thresholds for go/no-go decisions across discovery, clinical development, and commercialization.
- Portfolio optimization: Organizations can use the report’s scenario modelling to test combinations (e.g., microtubule inhibitors plus targeted therapies or immuno-oncology agents) and to rank indications and assets by commercial potential and de-risked development timelines.
- Commercial strategy: The evolution of ADCs and ADC-adjacent reimbursement frameworks is reshaping payer negotiations. The report provides a pragmatic playbook for launch sequencing, list-price architecture, and contracting strategies tailored to the oncology value chain in 2026.
- M&A and alliance targeting: With a market that remains meaningfully concentrated among leading manufacturers, the intelligence in this study supports targeted bolt-on acquisition screening and strategic partnerships to access payload technologies, linker chemistry, or regional commercialization capabilities.
Market trajectory — context, not numbers
Across the historical period we studied, established microtubule agents retained meaningful commercial value as both stand-alone therapies and payloads for ADC constructs. Looking forward, PW Consulting projects steady growth driven by four structural forces: (1) continued use of established microtubule-stabilizing and -destabilizing agents in core oncology indications; (2) the rapid maturation of ADCs that employ microtubule-inhibiting payloads, unlocking new indications and combination regimens; (3) geography-specific access expansion tied to regulatory and reimbursement evolution; and (4) life-cycle strategies by originators and generics that influence pricing and volume dynamics.
Microtubule Inhibitor Drugs Market
For executives, the headline numeric drivers are unambiguous: the sector’s baseline market size at the 2025 base year provides a robust foundation, and, under conservative assumptions, the market grows at roughly a mid-single-digit CAGR through 2032. This steady compounding underscores the need for multi-year strategic plays rather than near-term tactical wins alone.
Competitive landscape — who matters and why
The microtubule inhibitor ecosystem blends large integrated pharmaceutical players with specialist oncology developers. The report profiles leading firms whose portfolios and strategic moves will materially shape market structure and access in 2026:
- Pfizer Inc. — A long-standing marketer of paclitaxel formulations, Pfizer’s scale in manufacturing and global commercialization continues to anchor the market for taxane-class therapies. Their strategic options include differentiated formulations, sterile manufacturing scale-up, and potential ADC collaborations.
- Sanofi S.A. — With cabazitaxel in its oncology portfolio, Sanofi’s focus on post-docetaxel prostate cancer care and lifecycle management projects maintains a foothold in specialist indications. Sanofi’s development and label strategies will influence competitive positioning in second- and third-line settings.
- Bristol-Myers Squibb — Beyond stabilizers marketed for breast cancer, BMS’s investment in ADC payload strategies and combination programs makes it a notable competitor for clinical-stage partnerships and for securing therapeutic niches created by biomarker-led patient subsets.
- Eisai Co., Ltd. — As the marketer of non-taxane microtubule agents, Eisai demonstrates how differentiated mechanism-of-action within the class can sustain commercial relevance, particularly in indications needing novel cytotoxic modalities.
- Eli Lilly and Company — Lilly’s oncology capabilities and R&D investments provide optionality: either developing in-house microtubule-related innovations or acquiring payload/linker technologies to support ADC strategies against high-unmet-need tumor types.
- AbbVie Inc. — AbbVie’s recent regulatory milestone with a c‑Met-directed ADC bearing a microtubule inhibitor payload (accelerated approval in mid-2025) validates the commercial pathway for such constructs and signals how payer and regulatory bodies are evaluating these therapies.
Market concentration remains meaningful: top incumbents capture a material share of revenue, but pockets of white space remain for specialized payload providers, ADC innovators, and companies that can out-execute commercialization in selected oncology niches.
Regulatory and reimbursement dynamics shaping 2026 decisions
Two regulatory developments in our review underscore structural implications for 2026:
- Regulators have shown a willingness to grant accelerated approvals for ADCs that demonstrate strong early activity in biomarker-defined populations — a dynamic validated by recent approvals of c‑Met-directed and BCMA-directed ADCs in 2025. For strategy teams, this increases the value of biomarker-led early-phase trials and compels rapid evidence-generation plans to convert accelerated approvals to full approvals.
- Payer positioning around ADCs — particularly those with microtubule-inhibitor payloads — is evolving. In several markets, payers continue to view microtubule payload ADCs as high-value oncology options across multiple indications; this creates both pricing support and an imperative for robust real-world evidence (RWE) generation and outcomes-based contracting capabilities.
What the PW Consulting report delivers — practical, transaction-ready intelligence
We structure the report to be directly usable by C-suite leaders, business development teams, and commercial planners. Key operational deliverables include:
- Top-line market model (historical and forecast through 2032) with scenario toggles to test price, uptake, and approval timing assumptions.
- Segment-level playbooks (by molecule class and clinical indication) that translate clinical trial outcomes into commercial forecasts and margin sensitivities.
- A regulatory timeline and approval-risk heat map to prioritize indications and de-risk development portfolios in 2026 planning cycles.
- Payer engagement guides and reimbursement scenario matrices suitable for early HTA discussions and contracting pilots.
- An M&A and partnering screening toolkit highlighting capability gaps versus market opportunities and recommended deal structures for payload acquisition or commercialization partnerships.
- Commercial launch sequencing templates and Go-to-Market (GTM) templates designed to accelerate market entry while protecting price and access.
Strategic recommendations for executives planning in 2026
- Prioritize biomarker strategies: Accelerated regulatory pathways favor agents with clear companion diagnostic strategies. Invest in diagnostic partnerships early to shorten approval timelines and strengthen label claims.
- Treat ADC payloads as platform bets: For companies without established payload technologies, consider asset-light access via licensing or co-development rather than costly in-house builds unless a differentiated scientific rationale exists.
- Build payer evidence programs now: With payers increasingly receptive to ADCs but demanding robust comparative and RWE, allocate budget for post-approval registries and outcomes programs as part of launch preparations.
- Design portfolio de-risking playbooks: Use the report’s scenario models to map sensitivity to price erosion, generics entry, and combination-therapy cannibalization — then sequence clinical investments to maximize optionality.
- Monitor competitive concentration: Dominant players will continue to influence access and pricing dynamics. Look for niche indications or underserved geographies where mid-sized or specialized players can win despite concentration at the top.
Closing — the strategic value proposition
PW Consulting’s Microtubule Inhibitor Drugs Market report is built for decision-makers who need both a clear quantitative baseline and immediately actionable strategic guidance. It combines rigorous market-sizing (anchored on a 2025 base year and a transparent 2026–2032 forecast), competitive intelligence on incumbent and emergent players, and operational toolkits intended to shorten the time from insight to execution.
We deliberately present this briefing as a high-fidelity preview. The full analysis contains the granular segmentation, interactive financial models, and proprietary scenario outputs that are essential for deal teams, R&D strategy groups, and commercial leaders preparing for 2026. PW Consulting clients and subscribers can access the full dataset and modeling workbench to run bespoke scenarios aligned to their risk tolerance and strategic objectives.
For executive access to the full report and the accompanying analytical tools, please visit our report portal or contact your PW Consulting account lead for an enterprise briefing and secure model walkthrough.
For detailed analysis of this topic, please visit the official page: Microtubule Inhibitor Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Etifoxine Hydrochloride Market Poised to Expand at 5.2% CAGR Through 2032
By PW Consulting, 2026-07-13
Etifoxine Hydrochloride Market — Strategic Preview: PW Consulting Releases Actionable Intelligence for 2026 Decision-Makers
PW Consulting today publishes an executive preview of our forthcoming Etifoxine Hydrochloride Market report — a practice-focused intelligence package designed to inform board-level and commercial strategy through 2026 and beyond. Grounded in a rigorous historical analysis (2020–2025) and forward-looking forecasts for 2026–2032, this study synthesizes market sizing, regulatory context, clinical developments, supplier dynamics, and competitive positioning to help pharmaceutical, biotech, and investor clients convert uncertainty into prioritized action.
Etifoxine Hydrochloride Market
Headline macro takeaways
-
Base year and horizon: the report uses 2025 as its base year and models trends across a 2026–2032 forecast window, building on a historical series from 2020–2025.
Etifoxine Hydrochloride Market -
Market growth trajectory: the global Etifoxine Hydrochloride market is projected to continue a steady expansion, with a compound annual growth rate (CAGR) of approximately 5.2% over the forecast period. Our model shows identifiable inflection points tied to regulatory events and product launches that materially affect near-term uptake.
Etifoxine Hydrochloride Market -
Market scale context: PW Consulting’s topline model estimates the market in 2025 at USD 85.0 Million (revenue unit: Million USD) with a projected rise into the late‑cycle forecast, providing a quantifiable runway for commercial programs and portfolio prioritization.
-
Concentration and competitive structure: market concentration metrics indicate a moderately concentrated landscape (CR3 ≈ 45.5%; CR5 ≈ 58.2%), implying meaningful influence by several incumbents while leaving space for targeted entrants and niche players.
Why this report matters for 2026 strategic planning
-
Regulatory shifts are disrupting established assumptions. Recent regulatory outcomes and safety reviews have restricted usage in specific patient subgroups, while approvals and post-marketing commitments in key jurisdictions are changing how products are positioned commercially. Executives need granular regulatory scenario planning to avoid downstream reimbursement and liability risk.
-
Competitive moves are accelerating. Brand owners, generics manufacturers, and API suppliers are executing strategic launches and supply agreements that will re-draw commercial boundaries in several national markets. These moves affect access, price erosion timelines, and channel strategies.
-
Clinical re‑purposing and new indications could reshape demand. Ongoing and planned clinical trials exploring new therapeutic applications create upside optionality for companies that can align development and commercialization efforts early.
-
Supply‑chain resilience matters. API sourcing and manufacturing capabilities — including secondary sourcing and regulatory compliance of suppliers — are critical levers that influence time‑to‑market and margin performance.
What the report delivers — operational, decision‑grade content
-
Proprietary market model: transparent topline and scenario-based forecasts (2026–2032) with sensitivity testing for pricing, uptake curves, and regulatory outcomes. Note: detailed segment-level tables and region/application breakdowns are available in the full report (preview intentionally omits subsegment datapoints to preserve premium insights).
-
Go‑to‑market playbooks: tailored strategies for originators, first-to-file generics, and API suppliers covering launch sequencing, pricing frameworks, tender vs. retail channels, and payer engagement.
-
Regulatory & safety matrix: jurisdiction-by-jurisdiction summary of approvals, constraints, pharmacovigilance obligations and label risks, including scenario pathways for potential label revisions or additional contraindications.
-
Clinical pipeline tracker: live registry of ongoing and planned trials, prioritized by commercial impact and likelihood of success; includes trial design, enrollment assumptions, and expected data readouts.
-
Supply‑chain and manufacturing map: supplier profiles, capacity assessments, quality/regulatory compliance checks, and contingency pathways to mitigate single‑source exposure.
-
Competitive landscape & M&A readiness: profiles of incumbent players, disruptive entrants, ROIC-focused valuation frameworks, and a short‑list of high‑conviction partnership/acquisition targets.
-
Risk register and mitigation playbook: cross-functional risk assessments (regulatory, clinical, commercial, reputational) with prioritized mitigation tactics and KPIs for 12–36 month timeframes.
Competitive landscape — distilled insights
-
Biocodex (France) — legacy brand stewardship: Biocodex remains the steward of the established brand franchise in markets where Etifoxine has historical uptake. Their entrenched brand recognition and clinician familiarity confer a durable advantage on brand loyalty and formulary positioning in certain markets.
-
Sun Pharmaceutical Industries (India) — scale and regulatory momentum: Sun Pharma’s recent regulatory approvals and active post‑marketing surveillance commitments indicate a deliberate strategy to commercialize at scale where regulatory pathways permit. Their established commercial footprint and cost base enable competitive pricing strategies and rapid national rollouts.
-
API manufacturers (Metrochem API, Global Calcium, others) — strategic suppliers: multiple specialized API manufacturers have articulated Etifoxine in their portfolios, creating an increasingly diversified upstream supply environment. For companies considering entry or expansion, securing long‑lead API contracts and auditing supplier compliance will be decisive.
-
Regional generics entrants (e.g., Nizhpharm) — tactical launches: localized generic launches demonstrate how regional players can capture share quickly by leveraging approvals and country-specific supply chains. These entrants often drive rapid price compression in localized markets and can be attractive partners for licensing or distribution agreements.
Regulatory and clinical dynamics to watch in 2026
-
Safety‑driven label evolution: prior regulatory reviews have confirmed continued use in many patients but introduced clear contraindications tied to severe cutaneous and hepatic reactions. Companies must incorporate these constraints into promotion, labeling, and risk‑management strategies.
-
US absence and global opportunity mapping: Etifoxine is not approved in the United States; this absence creates a defined geographic boundary and opportunity set for companies focusing on Europe, Asia, and other markets where regulatory pathways are accessible.
-
Clinical re‑purposing signals: new trials, including studies assessing prevention of chemotherapy‑induced peripheral neuropathy (trial start dates aligned with 2026), could materially expand the clinical use case. Early engagement with principal investigators and payers will be critical if positive signals emerge.
-
Pharmacovigilance and post‑marketing commitments: regulators in several jurisdictions are expecting active PMS programs tied to newly approved products; these obligations influence launch timing and cost assumptions for market entrants.
Practical implications and recommended actions for 2026
-
For originators: protect brand equity through targeted education and safety communications, accelerate lifecycle programs for differentiated formulations or delivery, and evaluate selective licensing in markets where commercial reach is limited.
-
For generics and contract manufacturers: prioritize regulatory-ready dossiers and secure multi‑tier API supply; consider value-add services (e.g., bundled pharmacovigilance) to raise tender competitiveness beyond price alone.
-
For investors and M&A teams: use our scenario-driven valuation overlays to separate durable cashflow targets from opportunistic, timing‑sensitive plays — the market’s CR3/CR5 dynamics favor focused roll-ups in select regions.
-
For clinical developers: prioritize adaptive trial designs and engage payers early on novel indications to shorten the commercialization path if efficacy signals arise.
How to use PW Consulting’s report in boardroom planning
-
Integrate our forecast and scenario outputs into 2026 budgeting cycles to stress‑test revenue projections under divergent regulatory and competitive outcomes.
-
Adopt the supplied go‑to‑market playbooks as templates for country rollouts and tender strategies; customize based on internal capabilities and partnership options.
-
Leverage the supplier mapping and due‑diligence checklists to accelerate supplier qualification and reduce time‑to‑market risk.
-
Commission a tailored deep‑dive (PW Consulting engagement) to convert our high‑confidence recommendations into executable project plans with defined milestones and KPIs.
Access and next steps
This preview highlights the strategic value of the PW Consulting Etifoxine Hydrochloride Market report for 2026 decision-making. The full report contains the detailed segment tables, country-level opportunity matrices, pricing curves, and our proprietary scenario model that underpin the strategic recommendations above. To obtain the comprehensive dataset, modeling files, and bespoke advisory support, please contact PW Consulting’s market analytics team or visit our report landing page.
PW Consulting’s analysts stand ready to brief executive teams and investment committees on demand, and to tailor our findings into transaction‑ready diligence packages or operational playbooks that accelerate time to value in the Etifoxine Hydrochloride opportunity set.
For detailed analysis of this topic, please visit the official page: Etifoxine Hydrochloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pneumococcal Vaccination Market to Expand at 5.3% CAGR, Reaching USD 13.26 Billion by 2032
By PW Consulting, 2026-07-13
Pneumococcal Vaccination Market — 2026 Strategic Outlook
PW Consulting today publishes a focused industry briefing accompanying our full Pneumococcal Vaccination Market report. Drawing on a proprietary combination of primary interviews, public regulatory filings, supplier tender databases and our quantitative model, this briefing synthesizes the near-term inflection points that will shape boardroom decisions throughout 2026.
Pneumococcal Vaccination Market
Headline market view
By our accounting, the global pneumococcal vaccination market reached approximately USD 9.38 billion in 2025 (base year). Under our central forecast (2026–2032), the market is set to expand at a compound annual growth rate (CAGR) of 5.3%, crossing the USD 13.2 billion threshold by 2032. The market’s trajectory reflects simultaneous forces: incremental uptake in adult immunization programs, successive launches of higher‑valency conjugate vaccines, and differentiated pricing across private, public and donor-funded channels.
Pneumococcal Vaccination Market
Why this report matters for 2026 decision‑makers
- Immediate tactical value: tender and pricing playbooks tailored to regional procurement models and payer reimbursement mechanics.
- Actionable manufacturing intelligence: capacity and fill‑finish gap maps that expose short‑term bottlenecks and where to prioritize capital allocation or third‑party partnerships.
- Regulatory and commercialization timing: sequenced windows for adult and pediatric filings aligned with likely market entry scenarios.
- Risk‑adjusted financial scenarios: revenue and margin sensitivity to price compression, subsidy shifts, and production disruptions—designed for 2026 budgeting cycles.
What the full report delivers (practical content)
- Market sizing and forward model (2020–2032) with downloadable scenario workbooks and sensitivity levers to run your own assumptions.
- Comprehensive competitive assessment: capability matrices, pipeline timelines, regulatory milestones, and commercial footprint overlays.
- Procurement intelligence: tender dynamics, pricing benchmarks for private vs. public markets, and playbooks for negotiating with multilaterals and national immunization programs.
- Manufacturing and supply‑chain dossier: fill‑finish capacity maps, raw‑material risk scoring, cold‑chain economics, and recommended contingency actions for 2–8°C supply chains.
- Go‑to‑market playbooks by customer segment (public program, private payers, Gavi/PAHO channels) with KPIs and resource allocation templates.
- Strategic options and M&A screens: target profiles, valuation premia observed in recent deals, and integration pitfalls specific to vaccine biologics.
Market dynamics — the 2026 lens
Several contemporaneous dynamics are converging to make 2026 a pivotal year:
Pneumococcal Vaccination Market
- Pipeline evolution and regulatory cadence. Higher‑valency conjugate vaccines are progressing through late‑stage clinical development and regulatory review. Notably, a CHMP positive opinion in 2025 for a next‑generation adult PCV signalled an accelerated regulatory appetite in Europe, and leading manufacturers have initiated expanded pediatric programs in 2026. These events compress windows for differentiation and force incumbents and challengers to choose between competing on breadth of serotype coverage or on price and supply reliability.
- Local production and regional sourcing. Partnerships to establish local PCV production under multilateral procurement mechanisms have moved from pilot to execution in select markets, changing tender dynamics and creating new partnership opportunities for originators and contract manufacturers.
- Manufacturing and fill‑finish capacity expansion. New buildouts and dedicated PCV fill‑finish lines announced in 2026 reflect an industry response to previous capacity tightness. These investments reduce single‑sourced risk but will also increase competitive pressure where capacity becomes abundant.
- Cold‑chain and logistics constraints. Operational requirements (standard 2–8°C cold chain with limited high‑temperature tolerance) continue to be a cost and delivery constraint, particularly for decentralized immunization programs or emergency campaigns. Logistics plans and stability profiles materially affect both procurement costs and shelf‑life risk assessment.
- Pricing bifurcation. There remains a stark price divide between private markets in high‑income settings and donor‑subsidized markets; this differential is a permanent force shaping commercial strategy—sustaining margins in some channels while compressing them in others.
- Payer and reimbursement adjustments. Updated Medicare payment constructs and geographically adjusted rates introduced in recent years are changing commercial assumptions for adult vaccination programs in markets where public reimbursement is material to uptake.
Competitive landscape — concentrated, but opening
The market shows high concentration at the top: our analysis indicates that the three largest manufacturers account for the great majority of global revenue, with the five largest even more dominant. This concentration both stabilizes price points in certain channels and raises regulatory/political scrutiny in procurement processes.
Key strategic profiles we track (non‑exhaustive):
- Pfizer — A portfolio leader with broad product reach across pediatric and adult indications and an active high‑valency pediatric program initiated in 2026; strategy blends product breadth with strong channel relationships and targeted local production partnerships.
- Merck & Co. — A historically strong incumbent with established adult and pediatric franchises; regulatory progress on newer valency candidates has created optionality in adult markets and influenced tender terms in several jurisdictions.
- Sanofi and large low‑cost producers — Companies with WHO‑prequalified pediatric options and established public‑sector channels play a pivotal role in affordability and access agendas, particularly where Gavi and regional procurement mechanisms are influential.
- Emerging suppliers in India and China — Several manufacturers with WHO prequalification status or domestic approvals are reshaping local market dynamics and offer strategic partnership potential for originators aiming to expand capacity or price‑competitive supply.
Recent industry moves demonstrate shifting fault lines: a 2025 partnership to localize production under a multilateral revolving fund; a 2025 positive regulatory opinion for a next‑generation adult PCV; 2026 manufacturing expansions for dedicated PCV fill‑finish capacity; and initiation of a Phase 3 pediatric program by a major innovator in 2026. Each development has direct implications for tender outcomes, channel margin, and timing of market access.
Strategic implications and recommended actions for 2026
- Prioritize capacity resilience: confirm fill‑finish and cold‑chain commitments in contractual negotiations, including supply‑security clauses and rapid‑response logistics plans.
- Adopt a channel segmentation pricing strategy: preserve margin in private markets while deploying targeted low‑margin supply strategies for pooled procurement and donor‑funded tenders.
- Engage early with regulators and payers: accelerate adult and pediatric dossier strategies where regulatory timelines are compressed and where reimbursement rules materially affect uptake.
- Consider localized manufacturing partnerships: these can be defensive (protecting access to tenders) or offensive (cost and lead‑time advantages), but require careful contingent planning for tech transfer and quality governance.
- Monitor pipeline windows and adjust launch sequencing: product differentiation by valency will be a primary negotiating lever—time to market can trump marginal product features in certain procurement settings.
- Build M&A and alliance readiness: identify small‑to‑midcap biologics and CMOs with fill‑finish or cold‑chain strengths as potential bolt‑on targets to mitigate capacity constraints.
Methodology and trust anchors
The report uses a 2025 base year, historical coverage from 2020–2025 and a forecast horizon of 2026–2032. Financials are reported in USD (Millions) and our central forecast assumes a 5.3% CAGR across the forecast window. Inputs include company disclosures, regulatory filings, procurement tender databases, WHO/Gavi guidance, CDC stability data, and proprietary interviews with payers, immunization program directors and manufacturing executives. The full report contains the complete model, scenario toggles, and the data tables underpinning our headline curves.
How to obtain the full report and datasets
This briefing is intentionally targeted: it highlights the strategic inflection points and operational levers most relevant to 2026 planning while omitting full segmented tables to preserve the analytical value of the comprehensive model. For access to the full Pneumococcal Vaccination Market report, including regional, type and application breakdowns, detailed company scorecards, and the downloadable Excel model with scenario inputs, please visit the PW Consulting report page or contact our Market Intelligence team. The full deliverable is structured to support immediate integration into corporate budgeting, tender strategy, and manufacturing investment decisions.
PW Consulting stands ready to run customized deep dives—supply‑security stress tests, tender‑win probability models, or M&A diligence packages—tailored to the specific strategic questions your leadership needs to resolve in 2026.
For detailed analysis of this topic, please visit the official page: Pneumococcal Vaccination Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Rotator Cuff Injury Therapy Market to Grow from USD 1,949.82 Million in 2025 to USD 2,951.21 Million by 2032 at a 6.1% CAGR
By PW Consulting, 2026-07-13
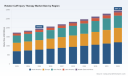
Rotator Cuff Injury Therapy Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market intelligence on Rotator Cuff Injury Therapy reframes the competitive horizon for medtech, orthopedics and provider organizations entering 2026. Built on a base year of 2025 and a historical window covering 2020–2025, our analysis projects a steady expansion at a 6.1% CAGR through 2032 — taking the market from an estimated USD 1,949.82 Million in 2025 toward roughly USD 2,951.21 Million by 2032. For executives weighing R&D prioritization, commercial investment, or M&A through the coming year, this report functions as both thermometer and roadmap: it diagnoses structural forces and prescribes pragmatic moves without disclosing all proprietary segment-level modeling in this preview.
Rotator Cuff Injury Therapy Market
Why this preview matters for 2026 strategic planning
-
Investment horizon clarity: The market’s mid-single-digit CAGR signals durable demand driven by aging demographics, rising surgical volumes, and expanding biologics adoption. This underpins capital allocation decisions — from clinical programs to sales footprint expansion.
Rotator Cuff Injury Therapy Market -
Regulatory and reimbursement inflection points: Recent guideline and clearance activity is reshaping clinical pathways and payer conversations; executives must realign clinical evidence strategies and reimbursement playbooks now, not later.
Rotator Cuff Injury Therapy Market -
Competitive posture and consolidation window: Market concentration metrics show meaningful presence by leading incumbents while leaving room for specialized entrants to capture niche share through differentiation or partnerships.
Key macro takeaways
-
Growth profile: The market is projected to continue growing at a 6.1% CAGR over the 2026–2032 forecast period, reflecting both replacement demand and expanded indications for augmentation technologies.
-
Concentration: Our competitive metrics indicate a mixed structure — the top three companies hold a meaningful share while the top five account for a clear majority of industry revenues. This produces both competitive pressure in core device categories and opportunities in adjacent biologic/augmentation niches.
-
Clinical economics: Updated clinical guidance and cost-effectiveness evidence increasingly favor repair strategies that incorporate biologics and advanced fixation techniques; lifetime societal savings versus nonoperative care are material for payer negotiations.
Industry dynamics shaping 2026 choices
-
Guideline-driven adoption: The AAOS 2025 Clinical Practice Guideline explicitly emphasizes bioinductive implants to reduce re-tear rates. This shifts clinical preference curves and raises the bar for product clinical evidence packages.
-
Regulatory momentum for augmentation devices: Multiple 510(k) clearances in 2025–2026 for reinforcement matrices and augmentation kits lower barriers to commercial entry for biologics and implant adjuncts — but also intensify competition around claims and label differentiation.
-
Payer nuance: Medicare reimbursement pathways remain complex. For example, modifier 22 (increased procedural complexity) succeeds in only a minority of arthroscopic rotator cuff cases — an operational reality that affects price realization and commercial value propositions.
-
Procedure economics: Hospital list prices for arthroscopic repairs—and published cost-effectiveness analyses—create a compelling commercial narrative for products that demonstrably reduce re-tear, reoperation and downstream societal costs.
Competitive landscape — what to watch
The market features several well-positioned incumbents and growing specialist players. Our strategic assessment focuses on how product portfolios, channel strategies and clinical evidence are likely to determine winners in 2026.
-
Arthrex, Inc. — Strengths: broad arthroscopic systems and knotless/knotted repair platforms with integrated augmentation options. Strategy implication: incumbency in instrumentation enables cross-sell of biologic adjuncts; potential acquirers should evaluate integration synergies.
-
Smith & Nephew plc — Strengths: bioinductive implant leadership and active engagement at key orthopedics forums. Strategy implication: visibility in clinical guidelines and trade shows amplifies adoption; competitors should anticipate accelerated clinician uptake where reimbursement supports it.
-
Stryker Corporation — Strengths: anchor technologies and alternative solutions (e.g., spacer devices) for massive irreparable tears. Strategy implication: portfolio breadth enables segmentation across simple to complex cases; partnerships with specialty biologic innovators could further extend reach.
-
Zimmer Biomet and Johnson & Johnson (DePuy Synthes) — Strengths: comprehensive implant and instrumentation portfolios, deep hospital relationships. Strategy implication: incumbency advantage in hospital purchasing requires challengers to offer clear incremental clinical or economic value.
-
CONMED, Atreon Orthopedics, Integra LifeSciences and others — Strengths: focused augmentation and biologic matrices, recent regulatory clearances. Strategy implication: these specialists are attractive targets for larger players seeking to fill biologic/augmentation gaps.
Recent tactical events underscore an accelerating tempo: Smith & Nephew’s high‑profile presence at AAOS 2026, Atreon’s 2025 FDA clearance and CONMED’s 2025 device approvals all signal that product innovation and regulatory wins will continue to drive share shifts in 2026.
Strategic imperatives for 2026
-
Prioritize evidence generation that maps to guideline endpoints. With clinical guidelines elevating bioinductive implants, companies must invest in outcomes studies that demonstrate reduced re-tear and cost-effectiveness versus alternatives.
-
Design reimbursement-first clinical programs. Given payer scrutiny (e.g., modifier 22 utilization dynamics), align trials and real-world evidence to reimbursement benchmarks and develop coding/coverage playbooks early in the commercialization path.
-
Segment GTM by clinical complexity. Differentiate offerings across simple repairs, complex tears and irreparable cases (including spacers and augmentation). Tailor messaging and distribution (ASC vs hospital vs specialist clinic) to unit economics and procurement behaviors.
-
Use partnership and M&A as fast-track options. The biologics and matrix space is consolidating; strategic acquisitions or co-development arrangements accelerate product breadth and clinical validation.
-
Operationalize value-based contracting pilots. Demonstrating reduced reoperation rates and lifetime cost savings creates leverage with payers and IDNs; pilot agreements can unlock preferential access and pricing premiums.
What PW Consulting’s full report delivers (practical, executable content)
-
Detailed 2026–2032 forecast model with sensitivity scenarios and key drivers, plus historical trend decomposition for 2020–2025.
-
Commercial playbooks by treatment type and end-user, including go-to-market tactics for hospitals, ambulatory surgery centers and physiotherapy channels.
-
Regulatory and reimbursement roadmaps tailored to the U.S. and major international markets, highlighting approval pathways, coding strategies and payer engagement templates.
-
Competitive benchmarking that scores technology portfolios against clinical, economic and operational attributes — and identifies M&A and partnership opportunities.
-
Clinical evidence matrix linking product claims to guideline-relevant endpoints and suggested trial designs to support market access.
-
Risk register and mitigation playbook addressing supply-chain, regulatory, price erosion and competitive entry scenarios.
Note: This preview intentionally omits granular regional and application-level splits and our full pricing sensitivity tables. Those segment-level models and underlying assumptions are included in the full report and online data portal to support transaction diligence and market-entry planning.
Immediate actions for executives in 2026
-
For R&D leaders: fast-track at least one mid-size clinical study that aligns endpoints with AAOS guideline recommendations and payer value metrics.
-
For commercial leaders: pilot value-based contracting in targeted IDNs where case volume and reimbursement complexity enable measurable KPIs.
-
For corporate development teams: prioritize M&A targets that provide biologic augmentation capability or label-extension potential; expect competitive auction activity for differentiated matrices.
-
For hospital/ASC operators: re-evaluate product formularies and pathway bundles to capture demonstrated reductions in reoperation and downstream costs.
Conclusion — the strategic choice
Entering 2026, the Rotator Cuff Injury Therapy market is neither a speculative frontier nor a saturated commodity field. It is a predictable-growth market with windows of rapid differentiation driven by guideline alignment, augmentation technologies and payer economics. Companies that synchronize clinical evidence, regulatory strategy and commercial models will capture outsized returns; those that delay will face margin compression and entrenched incumbents. PW Consulting’s full report supplies the segmented modeling, granular pricing analysis and operational playbooks necessary to convert this market trajectory into concrete enterprise value.
To access the full data-packed report, regional and treatment-level forecasts, and executable go-to-market templates, please visit our report page or contact PW Consulting’s healthcare strategy team.
For detailed analysis of this topic, please visit the official page: Rotator Cuff Injury Therapy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silicone Vasculature Models Market to Reach USD 490.24M by 2032 at 7.51% CAGR
By PW Consulting, 2026-07-13
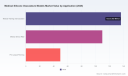
Medical Silicone Vasculature Models Market — Strategic Briefing for 2026 Decision Makers
As healthcare systems, device developers, and academic centres accelerate investments in realistic simulation, the market for medical silicone vasculature models is moving from niche laboratory tools to strategic platform assets. PW Consulting’s newly released market study (base year 2025; forecast 2026–2032) synthesizes market sizing, competitive dynamics, regulatory drivers, and go-to-market playbooks to support high-stakes 2026 decisions. This briefing highlights the study’s strategic value, the levers that will determine winners and laggards, and the practical next steps executives should adopt — while deliberately keeping detailed segment-level tables and model-by-model pricing behind our report paywall to preserve exclusive value for subscribers.
Medical Silicone Vasculature Models Market
Market at a Glance — Growth Trajectory and What It Means
The market for silicone vascular phantoms has expanded consistently over the last half-decade, reflecting growing demand from medical training, device development, and pre-surgical planning. Our sizing (USD, Million) shows a clear multi-year growth path from the low hundreds in 2020 to nearly USD 296 million in 2025, continuing to an estimated USD 490 million by 2032. This projects to a compound annual growth rate (CAGR) of approximately 7.51% across the forecast horizon.
Medical Silicone Vasculature Models Market
Why this matters for 2026 strategy:
Medical Silicone Vasculature Models Market
- Scale economics are emerging. The market is large enough that investments in manufacturing automation, in-house materials expertise, or contract manufacturing can materially improve gross margins.
- Predictable growth supports multi-year R&D roadmaps for advanced simulation products (e.g., multimaterial hybrids, patient-specific anatomies) and justifies capital allocation into equipment and clinical partnerships.
- Stable CAGR reduces the risk of speculative product bets; decisions can be staged across 18–36 month milestones informed by demand signals captured in this study.
Who Moves the Market: Competitive Structure and Strategic Implications
The competitive landscape is characterized by a mix of specialized fabricators, simulation-focused medtech firms, and academically-rooted spin-offs. Market concentration is modest: the top three players account for a meaningful share but not a dominant stranglehold, while the top five approaches half the market — a structure that enables both scale-focused consolidation plays and differentiated niche strategies.
- United Biologics (Irvine, CA) — known for anatomically representative models and a proprietary silicone formulation oriented to endovascular training and device demonstration.
- BDC Laboratories (Wheat Ridge, CO) — positions itself on engineering compliant mock vessels for cardiovascular device testing and simulation, with active trade-show engagement to drive OEM relationships.
- TrandoMed (Ningbo, China) — leverages 3D-print-driven manufacturing for neuro, coronary, and peripheral simulators at scale.
- Elastrat (Geneva), Mentice (Gothenburg), Preclinic Medtech (Shanghai), MedScan3D (Galway), and Swiss Vascular (Zurich/ETH spin-off) — collectively represent a set of providers that combine regional specialization, patient-specific capabilities, and academic linkage for R&D programs.
Recent signals you should factor into 2026 planning: ETH Zurich’s spin-off (Swiss Vascular) officially launched anatomically exact cerebral silicone models in mid-2025, a move that validated university-to-market pathways for high-fidelity phantoms. Meanwhile, established suppliers continue to engage target customers at industry venues (e.g., BDC’s presence at MD&M West in early 2026), underscoring the importance of direct clinical engagement for pipeline conversion.
Market Dynamics — Materials, Standards, and Supply-Chain Fragilities
From a sourcing and regulatory standpoint, three dynamics will determine near-term supplier viability and product acceptance:
- Raw material cost and specification. Medical-grade liquid silicone rubber (LSR) remains the input that sets floor economics for model pricing. Recent European LSR spot pricing clustered in a narrow band (roughly USD 7.20–7.77 per kg as of mid-2025), but manufacturers report variability driven by batch quality, additive packages, and supply-chain tightness — all of which materially affect unit cost on thin-margin, small-batch runs.
- Standards-led adoption. Compliance testing for cardiovascular devices increasingly references standardized silicone mock vessels (ISO 7198, ASTM F2477) and regulators encourage anatomically tortuous 3D models for simulated use testing — the FDA’s guidance on guidewire testing explicitly points to the utility of patient-like silicone anatomies. Firms that can certify models for standardized testing and provide traceable documentation will reduce friction in device validation cycles and command premium positioning.
- Manufacturing technology convergence. The intersection of high-resolution 3D printing, novel casting techniques, and hybrid composite approaches is redefining what “simulation fidelity” means. Buyers are demanding not just geometry but mechanical match (compliance, friction, and response to devices), which raises the bar for process control, quality systems, and data to demonstrate equivalence to biological tissue.
Strategic Playbook for 2026 — Where to Compete and How
Based on our multi-dimensional analysis, we recommend executives calibrate their 2026 actions across five strategic vectors:
- Segment focus: Prioritise use-cases with recurring demand and high willingness to pay — device R&D customers and simulation training programs with institutional purchasing cycles. Pre-surgical planning remains high-value but lower-volume; serve it with premium, patient-specific offerings partnered with clinical innovators.
- Product architecture: Adopt a tiered portfolio — commodity, configurable, and bespoke. Commodity lines can be automated; configurable offerings should be supported by an online configurator and SLA-backed delivery; bespoke patient-specific models require clinical integrations and higher margin expectations.
- Go-to-market: Build direct clinical champions and OEM co-development partnerships. Presence at clinical conferences and hands-on workshops is essential to shorten the sales cycle and create reference cases for device testing programs.
- Supply resilience: Lock in medical-grade LSR contracts and qualify redundant suppliers. Consider backward integration into critical elastomer compounding for firms with volume scale, or contract-manufacturer partnerships to shield capital outlay while ensuring traceability for regulated testing.
- Regulatory and quality systems: Invest in documentation and test-bench evidence that mirrors ISO/ASTM protocols and FDA simulated-use expectations. Certifications and validated test data will be differentiators for device OEM procurement.
Investment and M&A Considerations
With mid-single-digit market concentration and accelerating growth, the market is ripe for both horizontal consolidation and vertical capture. Private equity and strategic acquirers should evaluate targets against three criteria:
- Technical differentiation — proprietary materials, validated mechanical matching methods, or process patents.
- Customer access — entrenched relationships with device OEMs, hospitals, and training networks that create recurring revenue streams.
- Operational scalability — ability to convert bespoke workflows into semi-configurable, repeatable manufacturing processes.
Smaller players with strong clinical footprints are attractive tuck-ins for platform companies seeking to broaden their product suites with patient-specific capabilities. Conversely, large medtech OEMs could capture margin by internalizing model production for device testing and regulatory submissions.
What PW Consulting’s Full Report Delivers (Practical Content)
The study is engineered for executives who must act in 2026. It blends strategic narrative with operational toolkits, including:
- Verified market sizing and a 2026–2032 forecast model (USD, Million) with scenario toggles for adoption rates and pricing trajectories.
- A commercialization playbook detailing pricing architecture, channel economics, and a 12–24 month go-to-market sprint roadmap.
- Regulatory alignment matrices mapping product features to ISO/ASTM testing and FDA guidance to shorten device validation cycles.
- Supplier and raw-material procurement intelligence, including LSR market behaviour, risk-mitigation actions, and supplier qualification checklists.
- Competitive profiles and practical due-diligence templates for M&A or supplier selection — including capability heatmaps and integration risk scoring.
- Customer use-case playbooks for device OEMs, academic simulation centres, and hospital purchasing teams, with turnaround time and cost-to-serve benchmarks.
Note: To preserve strategic exclusivity, detailed subsegment allocations, individual company revenue lines, and model-level price lists are omitted from this public briefing and are available inside the full report.
Actionable Next Steps for 2026
- Run a 90-day supplier resilience assessment focused on LSR sourcing and qualifying a backup compounder.
- Pilot a configurable product line with one device OEM partner to validate margin uplift and shorten clinical adoption cycles.
- Allocate a small dedicated budget to regulatory evidence generation (bench tests aligned to ISO/ASTM and FDA scenarios) to unlock higher-margin device-testing contracts.
- Commission a valuation review if pursuing M&A — target assets that combine clinical relationships with technical IP.
Concluding Assessment
The medical silicone vasculature models market is at an inflection point: steady, predictable growth combined with rising technical and regulatory complexity creates a competitive landscape that rewards operational excellence, clinical intimacy, and materials mastery. For 2026, the smartest bets are not speculative new product lines but disciplined moves that translate product fidelity into repeatable business models: supplier contracts that control cost, regulatory evidence that shortens procurement cycles, and sales motions that convert clinical champions into long-term customers.
PW Consulting’s full market study provides the granular intelligence, financial models, and execution templates needed to turn these strategic imperatives into delivered value. For teams ready to convert market momentum into market leadership, the report is designed as a practical playbook — the next-step roadmap to decisive action.
For detailed analysis of this topic, please visit the official page: Medical Silicone Vasculature Models Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


