



Category: Healthy Lifestyle
PW Consulting: Water Bottles Market to hit USD 297.6 Million by 2032 at 5.0% CAGR
By PW Consulting, 2026-07-09
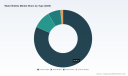
Water Bottles Market — 2026 Strategic Preview for Decision-Makers
As organizations plan priorities for 2026, the water bottles sector presents a compelling mix of steady growth, increasing concentration among leading players, and accelerating regulatory and supply-chain disruption. PW Consulting’s forthcoming Water Bottles Market study (base year 2025, forecast 2026–2032) synthesizes market-level data, competitive intelligence, and scenario modelling to convert noise into actionable strategy. This preview outlines the study’s strategic value and the decision levers that matter in 2026 — while reserving the granular segment-level tables and proprietary models for the full report.
Water Bottles Market
Market trajectory: a reliable growth runway
At the market level, the water bottles category has delivered consistent expansion through the early 2020s and is expected to maintain a mid-single-digit growth profile over the next several years. Our dataset (USD, Million) shows the global market expanding from the low hundreds of millions in 2020 to a 2025 base approaching the low 200s — and continuing to climb throughout the forecast horizon. A compound annual growth rate of approximately 5.0% underpins the outlook through 2032, reflecting the combined effects of consumer substitution toward reusable containers, premiumization (insulated and performance products), and rising institutional demand for durable, branded drinkware.
Water Bottles Market
For executives, two implications are immediate: first, scale still matters — market share gains compound in a steadily growing pool — and second, growth is predictable enough to support multiyear investments in manufacturing, channel partnerships, and sustainability initiatives, provided companies align with regulatory and input-cost realities described below.
Water Bottles Market
Why this report matters for 2026 decisions
-
Investment prioritization: We translate the headline CAGR into capital and commercial scenarios that show payback windows across product archetypes and channels, enabling CFOs to size production upgrades and marketing budgets with greater confidence.
-
Portfolio optimization: The study maps high-growth product characteristics (e.g., insulation performance, lid ergonomics, recyclability credentials) and connects those features to margin profiles and consumer willingness-to-pay — helping PMOs choose what to scale, sunset, or license.
-
Risk-adjusted supply strategy: We combine raw-material cost simulations, tariff exposures, and freight-surge scenarios into a solvable supplier-risk matrix so procurement teams can design hedges and nearshore alternatives for 2026.
-
Regulatory readiness: With binding EPR regimes and packaging mandates taking effect in major markets, the report provides a practical roadmap for compliance investments, product redesign priorities, and phased capex to meet recycling and recyclability thresholds without sacrificing brand equity.
Competitive landscape — what the major players are doing (and why it matters)
The category exhibits a moderate level of concentration — the top three firms command roughly half of industry sales, and the top five capture around three-fifths. This structure favors scale advantages in distribution and brand-building, but it still leaves meaningful opportunity for focused challengers and differentiated niche brands.
-
Nalgene (New York, USA) — Known for durable, BPA-free Tritan products aimed at outdoor and everyday use. Recent moves toward higher recycled-content materials signal an effort to convert sustainability credentials into competitive differentiation. Strategy implication: firms should watch Nalgene’s cost and supply choices for recycled polymers, and consider partnership or co-branding opportunities in outdoor channels.
-
Hydro Flask (Bend, OR, USA) — A leader in double-wall vacuum-insulated stainless steel bottles. Strengths are brand premiumization and channel penetration in lifestyle and outdoor retail. For rivals, the priority is either matching performance claims through R&D or attacking adjacent price tiers where insulation isn’t the purchase driver.
-
Klean Kanteen (Boulder, CO, USA) — Positioned on quality stainless steel and sustainability. Its recent collaboration with other premium drinkware brands to pursue collective sustainability initiatives demonstrates a strategic bet that coordinated industry action reduces regulatory risk and raises the baseline for eco-credentials.
-
Owala , YETI , Contigo , CamelBak , S’well , Tupperware , and Stanley — Each brand competes on a mix of design innovation (dual-drinking lids, leakproof systems), material choices (stainless, engineered plastics), and channel specialization (outdoor, cycling, retail, or direct-to-consumer). Collectively they illustrate that product design, brand storytelling, and distribution execution remain primary battlegrounds.
Regulatory and supply-chain forces reshaping 2026 strategies
The sector’s near-term dynamics are dominated by three interacting pressures that must be included in any 2026 planning exercise:
-
Expanded EPR and packaging mandates: New and extended producer responsibility laws in jurisdictions such as California, and pan-national rules in regions like the EU, are shifting the cost and design burden onto brand owners. Companies that proactively redesign for recyclability can avoid future compliance shocks and capture first-mover advantages in retailer listings and institutional procurement.
-
Tariffs and recycled-resin trade frictions: Escalating duties on imported recycled plastic resins and country-specific tariff spikes have made recycled inputs less fungible and, for some routes, materially more expensive. Procurement teams should reassess supplier concentration and consider blended resin strategies (local recycled + virgin mixes) to stabilize costs.
-
Freight volatility and regional disruption: Elevated freight rates on certain lanes and new war-risk surcharges in early 2026 have increased landed costs and extended lead times for Asia-origin components. Manufacturers with flexible multi-region manufacturing or nearshoring options will enjoy a competitive cost-of-service edge.
Recent industry moves that signal the market’s direction
-
Notable product and facility investments have emphasized sustainability and reuse-friendly design, including new bottling or packaging lines that prioritize recycled content and closed-loop thinking.
-
Collaborative sustainability initiatives — where brands pool resources to scale recycling collection, marketing, or material development — are emerging as an effective way to reduce regulatory and reputational risk while sharing the cost of infrastructure improvements.
-
Innovations in materials (recycled engineered polymers, high-grade stainless formulations) and lid mechanics (dual-drink, leakproof locking) continue to create differentiation even where core bottle geometry is commoditized. These incremental improvements often translate into meaningful margin expansion when tied to brand storytelling.
Critical strategic choices for 2026 — a decision framework
-
Manufacturing footprint: Decide whether to reconfigure capacity toward nearshore or regional hubs to reduce freight and tariff exposure. Use scenario modelling to quantify the trade-off between unit cost and service resilience.
-
Materials strategy: Set targets for recycled content and recyclability that meet upcoming EPR thresholds. Determine whether to insource compounding of recycled resins, partner with recyclers, or enter long-term supply contracts to secure feedstock.
-
Portfolio and pricing: Concentrate R&D and marketing spend on product features that deliver retrofittable upgrades or premium pricing (e.g., insulation, lid innovation, durability). Simultaneously retain a value tier for channels where price elasticity is high.
-
Channel strategy: Align distribution investments to the segments most responsive to premiumization and sustainability messaging, and prioritize channels that reward certified recyclability and verified lifecycle claims.
-
M&A and partnerships: With a moderately concentrated market, strategic acquisitions of niche brands, technology players (lid patents, insulation tech), or local recyclers can accelerate capability building while preserving margins.
What PW Consulting’s full report delivers
The complete study goes beyond this preview to provide the granular inputs and decision tools executives need in 2026:
-
Proprietary demand models and revenue forecasts at product- and channel-level granularity (interactive tables and downloadable datasets).
-
Scenario-based capex and IRR calculations for manufacturing footprint shifts, with sensitivities for freight, tariff, and recycled-material cost swings.
-
Supplier risk heatmaps and a shortlist of vetted suppliers across resin, stainless, and component categories together with suggested contracting clauses to de-risk volume and quality.
-
Competitive benchmarking for the top brands, including product feature scorecards, patent landscape snapshots, and a prioritized matrix of go-to-market tactics by channel.
-
Regulatory compliance playbooks tailored to major markets, with design-checklists to accelerate time-to-market for EPR-compliant SKUs.
Final recommendations for 2026 planning
Leaders who will win in 2026 will not simply react to regulatory and supply-chain shocks — they will anticipate them. Prioritize a three-part program: (1) shore up supply resilience through multi-supplier and regional-sourcing options; (2) accelerate product redesigns that embed recyclability and premium performance into the core value proposition; and (3) pursue collaborative sustainability initiatives that reduce compliance cost and build retailer trust. These moves map directly to the growth profile that underpins the market’s 5% CAGR and the structural advantages enjoyed by larger, coordinated players.
PW Consulting’s full Water Bottles Market report contains the tables, models, and tactical playbooks required to translate this strategic overview into executable 2026 plans. For the detailed segment breakdowns, supplier lists, and downloadable modeling files, visit our report page to access the complete study and interactive decision tools.
For detailed analysis of this topic, please visit the official page: Water Bottles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Frozen Yogurt Market Set to Grow at 4.9% CAGR Through 2032
By PW Consulting, 2026-07-09
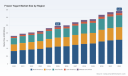
Frozen Yogurt Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
As PW Consulting’s senior industry analyst, I present a high‑impact orientation to our comprehensive Frozen Yogurt Market study (base year 2025). This briefing synthesizes the market’s trajectory, competitive dynamics, regulatory inflection points, and the practical levers executives should prioritize in 2026. It is intentionally concise — designed as a “trailer”: we demonstrate analytical depth and strategic foresight while reserving granular split data for the full report to which this briefing directs you.
Frozen Yogurt Market
Market trajectory at a glance
The frozen yogurt category has moved from a niche indulgence into a stable specialty dessert segment. Our historical series shows a recovery and steady expansion from USD 1.82 Billion in 2020 to USD 2.45 Billion in 2025. Under our base forecast (2026–2032) the market continues to expand, reaching USD 3.41 Billion by 2032, reflecting a compound annual growth rate (CAGR) of approximately 4.9% across the forecast window. These topline dynamics signal a resilient, mid‑single‑digit growth market that rewards targeted innovation, channel optimization, and operational rigor rather than broad, undifferentiated scaling.
Frozen Yogurt Market
Why this matters for 2026 corporate strategy
- Portfolio calibration: With mid‑single‑digit CAGR, incremental innovation and value capture through premiumization and specialty formats (e.g., tart, probiotic‑enhanced, botanical infusions) produce outsized returns versus high‑cost geographic expansion.
- Channel economics: Growth is uneven across retail, foodservice and emerging digital channels. Executives should prioritize channel mixes that improve margin capture and reduce distribution complexity while piloting direct‑to‑consumer models where logistics permit.
- Supply chain resilience: Production footprints that secure live cultures and dairy inputs — and that manage packaging and machine uptime — materially affect cost and quality. Securing co‑packing and private‑label capacity is strategic insurance in a constrained supplier market.
- Brand and franchise playbooks: The category favors brands that deliver consistent in‑store experiences, flexible licensing/co‑pack arrangements and strong retail/foodservice partnerships.
What this report delivers (practical, executable content)
Our full report is organized around decision‑centric modules that executives can action in 2026:
Frozen Yogurt Market
- Validated topline and forecast scenarios (2020–2032) with sensitivity analysis aligned to input costs, channel shifts, and premiumization trends.
- Go‑to‑market playbooks for brand owners, co‑packers and equipment suppliers — including unit‑level economics, pilot sizing matrices, and step‑by‑step franchise enablement checklists.
- Supply chain and operations diagnostics that map raw material risk (cultures, milk solids, packaging), alternate sourcing strategies, and a capital allocation guide for soft‑serve equipment and automation.
- A regulatory and compliance primer tailored to U.S. federal and state environments — compliance triggers, labeling considerations tied to live cultures, and practical mitigation tactics to prevent product recalls or plant licensing setbacks.
- Commercial due diligence templates for M&A and private‑label engagements, including valuation sensitivities and integration risk checklists.
We intentionally do not disclose the full regional, type, and application splits in this briefing. The report contains a rigorous segmentation matrix with cross‑tabulations; for proprietary split tables and market‑share detail, please consult the full study.
Competitive landscape — where advantage is being built
The category structure is currently modestly concentrated: the top 3 firms account for roughly 32.4% of the market and the top 5 about 44.2%. That concentration pattern creates opportunities for nimble challengers and contract manufacturers to capture share through specialization. Below is a strategic snapshot of the core competitive set and the strategic plays they illustrate.
- Nanci’s Frozen Yogurt (U.S.) — A wholesale dry‑mix manufacturer offering over 100 flavors and private‑label capabilities. Nanci’s is emblematic of a supplier strategy that leverages breadth of SKUs and formulation flexibility to win retail and regional foodservice contracts. For CPGs and chains seeking faster SKU innovation without expanding plant capacity, companies like Nanci’s are critical partners.
- Scott Brothers Dairy (U.S.) — Positioning around farm‑fresh milk and live‑culture credentials, Scott Brothers demonstrates the consumer premium available to supply chains that can prove provenance and microbial quality. Their model shows the commercial value of vertically linked sourcing in a category where authenticity and ingredient stories matter.
- Pinkberry (U.S.) — A brand‑led player that pairs signature product formulations with national retail and in‑store footprints. Recent 2026 activity (seasonal and co‑branded launches) highlights the importance of brand collaborations and limited‑time assortments to drive foot traffic and social media engagement.
- YoCream / Dannon Foodservice (U.S.) — As a manufacturer/foodservice supplier, YoCream represents the scale‑and‑distribution play. Recent recall history in the category underlines the operational and reputational risks inherent to broad distribution; food safety and packaging control are nonnegotiable.
- Menchie’s, Sweet Frog — Franchise and retail chains that combine proprietary mix profiles with franchising systems. Their 2026 co‑branded flavor launches underscore how licensing and partner IP drives incremental growth without heavy CAPEX for the brand owner.
- Wudel International, FrozenDessertSupplies.com, Spaceman USA — The supply‑chain enablers: mix suppliers, packaging specialists and equipment OEMs. They are crucial levers for margin improvement and reliability — equipment uptime and packaging innovation influence unit economics almost as much as recipe formulation.
Recent market moves to monitor (implications for strategy)
- Brand collaborations and seasonals have accelerated in 2026 (notable Pinkberry and Menchie’s launches). These tactics are effective for short‑cycle demand spikes and social engagement; companies should institutionalize rapid co‑brand launch capabilities.
- Retail/foodservice tie‑ups (e.g., quick‑service and c‑store partnerships) are expanding reach with low CAPEX for brands. Evaluate distribution economics carefully to avoid margin leakage.
- Quality and safety events (e.g., product recalls) remain a meaningful operational risk. Firms must invest in traceability, packaging inspection, and supplier audits as a prerequisite to scaling distribution.
Regulatory and technical dynamics executives cannot ignore
Regulation and technical standards shape permissible product claims, production requirements, and market access:
- Federal identity rules for frozen yogurt in the U.S. do not impose minimum milkfat or solids levels in the same way ice cream standards do. That regulatory flexibility enables product differentiation (dairy‑lean, low‑fat, non‑dairy formats) but also raises the bar for transparent labeling to maintain consumer trust.
- State and local rules can be restrictive: for example, certain U.S. states require specific plant licenses for semi‑frozen soft‑serve production. Site selection and plant design must incorporate these licensing regimes at the outset.
- Cultures matter: the Live & Active Cultures seal has a food‑tech implication — frozen yogurt must meet minimum live culture counts to substantiate probiotic claims. This affects formulation, cold‑chain management, and shelf life economics.
- Recall incidents (plastic contamination, packaging foreign objects) remain an industry vulnerability. Robust packaging QA and supplier governance are now table stakes for expanding into supermarket shelves and foodservice chains.
Strategic recommendations for 2026 (prioritized)
- Product & portfolio: Prioritize 2–3 high‑margin innovations (e.g., premium tart, probiotic‑forward, premium fruit‑infused) and limit SKU proliferation. Use seasonal collaborations to test new concepts without long‑term shelf commitments.
- Channel strategy: Optimize the retail/foodservice mix to capture margin—push for favorable slotting and co‑marketing in retail while piloting direct and subscription channels where distribution costs are manageable.
- Supply & operations: Lock in co‑packing agreements and diversify culture suppliers. Invest in packaging inspection and soft‑serve equipment redundancy to reduce recall and downtime risks.
- Corporate development: For acquirers, prioritize targets that bring either proprietary formulations with proven LTV or contract manufacturing capacity that reduces time‑to‑market for new SKUs.
- Compliance & risk: Conduct a regulation and contamination audit covering federal and state licensing, labeling claims around live cultures, and supplier packaging controls. Implement corrective action plans before scaling distribution.
How to use the full PW Consulting Frozen Yogurt Market study
The complete study contains the granular segmentation, channel economics, and named supplier scorecards necessary to execute the 2026 plays summarized here. If you are assessing a product launch, franchise expansion, M&A target, or supply agreement, the report’s datasets and actionable templates will compress decision timelines and reduce implementation risk.
Next steps
Access the full report for the detailed regional/type/application splits, the company benchmarking dashboards, and downloadable playbooks. The topline numbers and strategic guidance in this briefing show the path; the full study supplies the map, spokes, and timing required to move decisively in 2026.
For detailed analysis of this topic, please visit the official page: Frozen Yogurt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Blood Bags Market to Reach USD 549.73 Million by 2032 at 7.3% CAGR — PW Consulting
By PW Consulting, 2026-07-09
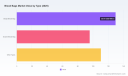
Blood Bags Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, decision-ready synthesis of our latest Blood Bags Market research. This brief is designed as a strategic “trailer” for executives who must move fast in 2026 — it reveals the trends, competitive dynamics, regulatory inflection points, and actionable playbooks that will determine who captures growth in a market expanding at a compound annual growth rate (CAGR) of 7.3% across our forecast window.
Blood Bags Market
Market arc in one view
Our modeling — anchored to a 2025 base year — shows the global blood bags market rising from an observed industry size of roughly USD 236.0 Million in 2020 to USD 335.7 Million in 2025, and continuing to grow to an estimated USD 549.7 Million by 2032. The structural momentum behind this expansion is durable: demographic pressures, strengthening collection and transfusion programs in emerging health systems, and sustained investment in domestic and mission-critical manufacturing capacity.
Blood Bags Market
Why this research matters for 2026 decision-makers
- Timing matters: 2026 is an inflection year for procurement cycles and capacity investments. Our forecast provides the market runway your capital and product roadmaps must target to avoid both undersupply and stranded capacity.
- Concentration is a strategic constraint: The market exhibits meaningful concentration (CR3 ≈ 60%, CR5 ≈ 65%), which creates both risk and opportunity for entrants, suppliers, and buyers seeking leverage.
- Regulatory windows will re-shape product adoption: Recent and pending regulatory guidance — from draft FDA clarifications on Buffy Coat methods to formal recognition of labeling standards — is changing the approval timelines and evidence requirements for blood collection systems.
- Procurement dollars are moving to domestic / defense-aligned suppliers: Public funding initiatives and procurement preferences (highlighted by recent awards) are shifting buyer behavior in ways that favor manufacturers capable of meeting military, FDA, and ISO standards simultaneously.
What is inside the full report (practical, transaction-ready outputs)
- Transparent market sizing and scenario-driven forecasts (2026–2032) with sensitivity analyses calibrated to policy, raw material, and manufacturing scenarios.
- Competitive scorecards and supplier capability maps covering manufacturing footprint, regulatory clearances, product family breadth, and technology differentiation.
- Regulatory pathway playbooks: step-by-step guidance for achieving FDA clearance or documented exemptions, and how to align submissions with recent Circular of Information updates.
- Supply chain risk matrices and sourcing playbooks — dual-sourcing templates, inventory buffering strategies, and cost-to-serve models.
- Commercial due-diligence checklists, contract negotiation playbooks, and pricing architectures for Tenders, GPOs, and defense procurement.
- Go-to-market blueprints for product launches, including field trial design, evidence generation, and payer / hospital adoption pathways.
- Financial models ready for M&A diligence and investment committees, including unit economics, break-even analyses, and accretion scenarios.
Competitive landscape — what leaders and challengers are doing
The market’s leading suppliers combine integrated systems, regulatory pedigree, and deep relationships with national blood services and hospital procurement teams. Our research synthesizes public profiles and proprietary interviews to deliver strategic reads on the core incumbent and challenger set:
Blood Bags Market
- Fresenius Kabi (Germany) — System integrator with dominant U.S. supply presence and full blood bag system offerings. Their scale underpins supply security and bargaining power in procurement negotiations.
- Terumo Corporation (Japan) — Strong in whole blood collection systems with donor-safety features; differentiated by product ergonomics and broad clinical adoption in APAC and EMEA.
- Haemonetics Corporation (U.S.) — Focused on blood management and apheresis platforms; competitive where integrated processing and automation meet clinical efficiency goals.
- Macopharma (France) — Niche strength in specialized bags (including cord blood systems) and a strategy informed by regulatory approvals for specialized applications.
- JMS Co., Ltd. (Japan) — ISO 13485-compliant manufacturing reputation; competitive on quality certifications and stable supply for clinical customers.
- Kawasumi Laboratories (Japan) — Product focus on single and multiple collection systems with safety enhancements for donor protection.
These profiles are mapped to strategic playbooks in the full report — enabling buyers to translate supplier capabilities into procurement scorecards and potential partnership targets into executable terms.
Recent developments that change the calculus in 2026
- Defense Health Agency (Dec 2025) awarded targeted funding to stimulate domestic manufacture of single-donor collection and storage bags. The award signals a concrete, government-backed channel for suppliers that can meet FDA, ISO, and military specifications.
- Regulatory updates (2024–2025) — including an FDA draft on Buffy Coat methods and the formal recognition of labeling guidance — materially alter design controls and clinical evidence expectations for blood bag systems.
- Standards-driven procurement (MTEC RFPs and other agency solicitations) now commonly require compliance with ISO 3826 and biocompatibility standards (e.g., ISO 10993), and expect pathways that achieve FDA clearance or documented exemption.
- Raw material concentration risks persist: supply chains remain exposed where a dominant supplier supplies the overwhelming majority of certain bag types in specific markets — a single-source exposure that demands strategic mitigation.
Dynamics to watch: risk vectors and opportunity windows
- Regulatory gating vs. time-to-market: New guidance introduces both compliance costs and predictable pathways. Early engagement with regulators reduces approval latency and creates a competitive advantage.
- Supply-chain sovereignty: Governments and large health systems are prioritizing domestic manufacturing for mission-critical disposables. Capability investments or partnerships that satisfy defense and regulatory specs unlock privileged channels.
- Product innovation and differentiation: Safety features, pathogen-reduction compatibility, and traceability (RFID/UDI) increasingly determine winning bids.
- Commercial consolidation: The market’s medium concentration suggests transactional activity — bolt-on M&A to close capability gaps, and selective divestitures where product families are non-core.
- Sustainability and material risk: Alternatives to traditional plastics and lifecycle cost assessments will become procurement criteria for large hospital systems over the next three years.
Recommended 2026 playbook for industry participants
- Implement a two-track regulatory strategy: pursue rapid market entry in select jurisdictions while running parallel evidence-generation programs for higher-bar markets.
- Prioritize dual sourcing for critical polymers and components; negotiate long-term supply agreements with capacity reservation clauses tied to demand triggers.
- Engage proactively with defense and public health procurement bodies — eligibility to compete on domestic preference programs often requires upfront investment but yields long-term contracts.
- Align R&D to modular product architectures that can be adapted between collection, storage, and processing systems without full redesigns.
- Pursue focused M&A to acquire certifications or manufacturing footprint versus building from scratch; use our financial templates to stress-test deal returns under multiple regulatory timelines.
- Embed scenario planning (regulatory delay, raw-material shock, demand surge) into capital allocation decisions; maintain a liquidity reserve sized to bridge worst-case approval lags.
- Deploy a commercial segmentation that values strategic accounts (national blood services, defense, large hospital networks) differently from transactional buyers, and tailor contracting terms accordingly.
What PW Consulting delivers beyond this brief
Our full Blood Bags Market report delivers the confidential granular segmentation, supplier-level revenue estimates, and executable templates that boards and deal teams need to move from intent to action. The analysis contains the proprietary models that produce the headline CAGR and market trajectory summarized here, plus supplier scorecards and ready-to-use diligence materials. For competitive, M&A, procurement, and regulatory leaders, those detailed datasets and annexes are the difference between a good strategy and a market-winning one.
Next steps for executive teams
- Request the full report to access the granular segmentation, supplier revenue splits, and interactive financial model (reserved for report subscribers).
- Schedule a PW Consulting briefing to run a tailored scenario workshop based on your product portfolio and target markets.
- Use our rapid diagnostic to identify three priority moves you can execute in 60–120 days to improve resilience and capture incremental share.
In an environment where regulation, procurement policy, and manufacturing strategy intersect, being prepared with evidence-based scenarios and practical playbooks is non-negotiable. Our research translates market momentum and risk into targeted actions for 2026 — enabling leadership teams to invest, partner, or pivot with confidence.
For detailed analysis of this topic, please visit the official page: Blood Bags Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Alzheimer's Drug Market to Reach USD 5.71M by 2032 (5.1% CAGR)
By PW Consulting, 2026-07-09
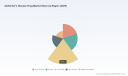
Alzheimer’s Disease Drug Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest industry primer synthesizes macro trends, competitive inflection points, and actionable playbooks to guide corporate strategy in the Alzheimer’s disease (AD) drug market as companies enter a decisive 2026. Anchored to a 2025 base year and projecting through 2032, the market is on a sustained growth trajectory — rising from roughly USD 3.07 Million (aggregate market measure) in 2020 to about USD 4.08 Million in 2025 and forecast at approximately USD 5.71 Million by 2032 — representing a compound annual growth rate (CAGR) near 5.1% across the forecast window. That headline growth masks substantive structural change: the emergence of disease-modifying therapies (DMTs), evolving dosing and delivery formats, fresh regulatory and reimbursement decisions across major payers, and an active symptomatic-treatment segment. This briefing explains why these dynamics matter for 2026 corporate decisions and what operational actions should follow.
Alzheimer's Disease Drug Market
Why this report matters in 2026
For life-science executives, investors, and commercial leaders, 2026 is not merely another reporting year — it is the inflection point where clinical validation intersects with payer uptake and route-to-patient logistics. PW Consulting’s Alzheimer's Disease Drug Market research is designed to convert market noise into decision-grade evidence. The study provides:
Alzheimer's Disease Drug Market
- Macro-level market sizing and forward-looking revenue scenarios calibrated to regulatory, clinical, and reimbursement levers;
- Competitive intelligence on incumbent prescription therapies, emergent DMTs and symptomatic drug entrants, and generics dynamics;
- Practical launch and commercialization playbooks (including payer engagement timelines, evidence-generation roadmaps, and channel strategies for IV versus subcutaneous dosing);
- Investment and M&A screening tools that prioritize targets based on strategic fit, technological adjacency, and commercial defensibility;
- Risk matrices and mitigation plans addressing manufacturing scale-up, biomarker access bottlenecks, and patient identification gaps.
These deliverables are structured to support decisions in 2026 across four critical domains: R&D prioritization, market access and pricing strategy, go-to-market sequencing, and capacity/infrastructure investment.
Alzheimer's Disease Drug Market
Market trajectory and what it means for strategy
The roughly 5.1% CAGR across 2026–2032 reflects three converging forces. First, the therapeutic landscape is shifting from a dominance of long-standing symptomatic agents toward a two-track market where DMTs gain share while symptomatic treatments remain essential for broad care. Second, incremental regulatory approvals and dosing innovations are reducing barriers to long-duration treatment and outpatient delivery. Third, payer frameworks are evolving: reimbursement decisions and inclusion in insurance innovation lists are beginning to determine real-world uptake speed.
The concentrated nature of the market — with the top three and top five commercial players accounting for material shares — suggests that while incumbents maintain strong positions, there is accessible room for differentiated entrants. This concentration profile supports strategic activity in niche innovation (e.g., agitation management, adjunctive therapies, diagnostics and biomarkers) and targeted commercial plays that exploit unmet clinical pathways.
Competitive dynamics: what recent moves tell us
- Eisai Co., Ltd. & Biogen Inc.: The co-commercialization of a landmark anti-amyloid therapy has shifted the competitive baseline. Notably, approval of maintenance dosing regimens and a subcutaneous autoinjector reflect a deliberate move to reduce treatment friction and broaden outpatient administration. Market access wins — including inclusion on select commercial insurance lists — illustrate how reimbursement endorsements materially accelerate patient access in key markets.
- Eli Lilly and Company: Approval of a limited-duration anti-amyloid regimen demonstrates an alternative clinical value proposition — shorter treatment courses that claim durable effects. This product design creates distinct commercial and clinical pathways compared to chronic DMTs and can reshape payer discussions around cost-effectiveness and coverage terms.
- Axsome Therapeutics: Expansion of non-antipsychotic options for agitation associated with dementia opens a pragmatic symptomatic niche with immediate commercial potential, particularly where safety and tolerability are prioritized by prescribers and caregivers.
- Teva Pharmaceutical Industries: As a major supplier of generics for symptomatic treatments, generics manufacturers will continue to be essential partners — and, in some cases, competitive pressures — in pricing and access negotiations.
Collectively, these moves emphasize three strategic imperatives: evidence generation beyond initial approvals (real-world outcomes and health economics), differentiation through delivery and dosing convenience, and early payer engagement to codify coverage policies aligned to clinical value propositions.
Operational priorities for 2026
- Recalibrate portfolio investment: prioritize programs with clear differentiators (e.g., shorter dosing duration, improved safety profile, clear biomarker-linked responders).
- Secure manufacturing and logistics capacity: prepare for mixed-delivery models (infusion centers plus subcutaneous self-administration) and anticipate cold-chain demands and device partnerships.
- Build a payer-ready HEOR docket: invest in modeling that links short-term clinical outcomes to long-term cost offsets and caregiver burden reduction.
- Accelerate diagnostics and patient-identification partnerships: collaborations with imaging, blood-based biomarkers, and primary-care networks are now commercially material.
- Design support ecosystems: caregiver education, adherence solutions, and digital monitoring tools to improve persistence and capture real-world evidence.
Scenario planning: three plausible 2026+ pathways (high-level)
- High-adoption DMT-led Scenario — Broad payer acceptance, accelerated diagnosis pathways, and rapid roll-out of outpatient administration. Strategic winners invest heavily in capacity, biomarker access, and patient support networks.
- Managed-access Scenario — Payers adopt restrictive coverage with performance-based agreements; uptake is meaningful but concentrated. Commercial strategies require sophisticated outcomes tracking and contracting capabilities.
- Fragmented Market Scenario — Uptake of DMTs remains modest due to diagnostic, logistical, or budgetary constraints; symptomatic treatments and supportive care retain dominance. Opportunity exists for adjunctive therapies and differentiated symptomatic agents.
Each scenario implies different capital, evidence, and partnership priorities. The full report includes quantified scenario outputs and decision-trigger matrices to help leadership choose contingency actions aligned to their risk appetite.
What the full PW Consulting report contains (practical content preview)
- Market sizing and forecast model (historical 2020–2025 benchmark and 2026–2032 scenarios), with sensitivity testing around payer adoption and dosing format penetration;
- Competitive landscape dossiers — company profiles, regulatory timelines, commercial playbooks, and innovation vectors for leading and challenger firms;
- Pipeline map and clinical-readiness assessment, including probability-weighted launch timing for key molecules;
- Payer and reimbursement playbook with templated outcomes-based contracting language and negotiation timelines;
- Go-to-market launch blueprints for IV vs. subcutaneous delivery including channel economics, clinic networks, and patient support programs;
- Operational readiness checklist (manufacturing, supply chain, device partnerships) and capital-estimate ranges for scale-up;
- RWE and HEOR study designs linked to regulatory and payer milestones; and
- M&A screening tool and prioritized shortlist of asset classes that accelerate market entry or defensibility.
To preserve the strategic value of this primer and to respect commercial sensitivities, granular segment-level splits and detailed regional/application percentages are intentionally withheld from this article. The full report contains those tables, interactive models, and downloadable decision-support templates.
Recommended 90-day executive agenda
- Initiate cross-functional payer-scenario workshops to align commercial and HEOR teams on evidence gaps and contracting options.
- Audit manufacturing and device partnerships against projected delivery models; secure contingency capacity where lead times are material.
- Map diagnostic access in priority markets and initiate strategic partnerships to shore up patient identification channels.
- Define an RWE trial portfolio focused on durability, safety in heterogeneous populations, and caregiver-focused outcomes.
- Conduct a rapid M&A and partnership screen to identify bolt-on capabilities (biomarkers, digital therapeutics, infusion networks).
Conclusion — why acting in 2026 matters
The Alzheimer’s drug market is moving from a period of clinical demonstration to a phase where delivery, payer architecture, and operational readiness determine commercial success. The market’s steady growth—underscored by a multi-year CAGR near 5.1% and a projected rise in aggregate value by 2032—creates opportunity, but winning in 2026 demands calibrated investments in evidence, manufacturing, and payer engagement. PW Consulting’s full Alzheimer’s Disease Drug Market report translates this complexity into executable strategy: scenario-validated forecasts, competitive playbooks, and operational checklists that allow leadership teams to make high-consequence decisions with confidence.
Access the full report for the detailed segment tables, interactive financial models, and the complete set of market-entry and defense playbooks that support high-quality 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Alzheimer's Disease Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HFCS Market to Reach USD 11.54 Billion by 2032, 3.4% CAGR (2026-2032)
By PW Consulting, 2026-07-09
High Fructose Corn Syrup Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Chief Industry Analyst, I present a focused strategic preview of the High Fructose Corn Syrup (HFCS) market to guide corporate leaders planning for 2026. This briefing synthesizes historical performance, near‑term forecasts, competitive moves, and policy-sensitive dynamics that will determine winners and losers through our forecast window (2026–2032). It is deliberately deep on implications and light on proprietary slice‑level numbers — a “trailer” designed to demonstrate rigor and to invite decision teams to review the full report for the segmented intelligence required for execution.
High Fructose Corn Syrup Market
Executive snapshot — where the market stands and where it is going
Measured on a consolidated basis (USD, revenue unit: Million), the HFCS market expanded from a 2020 baseline of roughly 7,200 million USD to a 2025 base year near 9,100 million USD. Looking forward from 2026 through 2032, our central scenario models a steady compound annual growth rate of 3.4%, carrying the market to approximately 11,540 million USD by 2032. This growth trajectory is neither runaway nor stagnant — it reflects a maturing global sweetener market where demand is being reshaped by reformulation, regional feedstock economics, and selective product innovations.
High Fructose Corn Syrup Market
Why 2026 is a pivotal planning horizon
- Capital allocation decisions crystallize in 2026. With major producers announcing capacity adjustments and innovation programs over 2024–2025, investment timelines and contract negotiations signed in 2026 will determine supply alignment into the next decade.
- Regulatory and trade levers are tightening. Tariff-rate quotas, domestic sugar programs, and localized interventions continue to influence relative economics between cane sugar and HFCS — making supplier diversification and scenario planning non-negotiable.
- Customer segmentation is redefining demand. Food & beverage manufacturers are balancing cost, labeling, and consumer perception in formulation choices that will shape volumes and margin mix into 2027 and beyond.
Dynamics driving the trajectory
- Feedstock economics and seasonal shocks. Corn price forecasts for the 2025/26 period sit modestly below multi-year averages. That baseline, combined with episodic regional disruptions (for example, drought-driven sugar price spikes in some markets), continues to make HFCS an agile cost alternative in certain geographies and categories.
- Policy architecture matters. The U.S. sugar program — with its tariff-rate quotas, price supports, and marketing allotments — remains a key determinant of domestic HFCS competitiveness. Even small changes to these instruments or to trade policy create outsized margin and volume swings for producers and large buyers.
- Demand-side transitions. Per-capita caloric sweetener deliveries in some mature markets continue to trend down, driven by reformulation and health-conscious consumption. That said, localized dietary preferences, product innovation (e.g., reduced-sugar textures), and episodic supply shocks can produce countervailing flows that sustain steady aggregate growth.
- Labor, logistics and capacity changes. Producers’ recent investments — both announced and implied — are rebalancing regional supply chains. These moves affect negotiating leverage, contract durations, and the value of forward‑buying strategies.
Competitive landscape — who matters and why
The HFCS market remains moderately concentrated, with the top three players controlling roughly half of industry volumes and the top five approaching six in ten — a profile that favors scale, integrated feedstock access, and proximity to key food‑manufacturing clusters. Leading firms to watch include:
High Fructose Corn Syrup Market
- Archer Daniels Midland Company (Chicago, IL) — A dominant U.S. producer with wet‑milling footprints across the Midwest. ADM’s May 2025 capacity expansion signals continued commitment to supply growth into beverage and industrial food channels. Source: https://www.adm.com/
- Cargill, Incorporated (Minneapolis, MN) — A global supplier whose plant network and customer relationships provide sourcing optionality for multinational food processors. Cargill’s positioning is critical in any scenario where procurement flexibility is prioritized. Source: https://www.cargill.com/
- Ingredion Incorporated (Westchester, IL) — Focused on both traditional HFCS grades and application support for formulators, Ingredion is a pivotal partner for manufacturers navigating reduced‑sugar textures. Source: https://www.ingredion.com/
- Tate & Lyle Americas (Chicago, IL) — Beyond production, Tate & Lyle has released formulation tools to support reduced‑sugar development, illustrating how ingredient players are moving up the value chain. Source: https://www.tateandlyle.com/
- Roquette America, Primient, Grain Processing Corporation — Each brings different strengths (European technology transfer, integrated corn refining, regional plant networks) that matter differently by geography and customer segment. Sources: https://www.roquette.com/, https://www.primient.com/, https://www.grainprocessing.com/
Recent industry moves to monitor: ADM’s 2025 U.S. capacity expansion, Coca‑Cola’s 2025 launch of a cane-sugar variant in the U.S., and Tate & Lyle’s 2025 release of a formulation tool aimed at reduced‑sugar sensory optimization. Each event shifts supplier-buyer negotiations and influences how HFCS is positioned in customer portfolios.
Strategic implications for corporate decision-makers in 2026
- Prioritize contract flexibility over price-only procurement. With feedstock price variability and policy sensitivities, contracts that allow for volume and grade flexibility, indexed pricing windows, and co‑innovation clauses will protect margins and market access.
- Embed policy scenario planning into commercial forecasts. Small adjustments to sugar policy or tariff regimes can materially change HFCS attractiveness in specific markets. Procurement and strategy teams should stress-test plans against at least three plausible policy shifts in 2026 planning cycles.
- Invest in formulation capability rather than just ingredient sourcing. The competitive edge in reduced‑sugar offerings will come from suppliers and manufacturers who can replicate mouthfeel and texture while managing cost. Firms should evaluate partnerships or licensing with ingredient companies offering sensory/formulation platforms.
- Evaluate regional exposure and dual‑sourcing strategies. Given localized drivers (e.g., sugar price spikes in drought‑affected regions), maintain dual‑sourcing with geographic separation to minimize production and logistics risk.
- Consider M&A and JV opportunities focused on downstream integration. The market concentration profile favors scale; large food processors and ingredient companies will find strategic value in acquiring complementary capacity or securing long‑term offtake through joint ventures.
What PW Consulting’s full market study delivers
Our comprehensive HFCS Market Report (base year 2025; historical 2020–2025; forecast 2026–2032) is built to convert insight into action. Highlights include:
- Top‑line market sizing with annualized figures from 2020 through 2032 (USD, revenue unit: Million) and transparent CAGR computations underpinning our scenarios.
- Scenario analyses that map price, policy, and demand shocks to volume and revenue outcomes across the forecast horizon.
- Practical procurement playbooks and contracting templates designed for immediate use by sourcing teams.
- Supplier scorecards and risk matrices that combine operational footprint, feedstock exposure, and innovation capability — enabling rapid counterparty selection.
- M&A and JV target shortlists, valuation frameworks, and integration checklists that reflect the market’s concentration dynamics.
- Regulatory impact assessments that translate tariff, quota, and domestic program changes into P&L and balance sheet sensitivities.
Note: In line with the “trailer” principle of this preview, detailed sub‑segment tables (regional splits, type and application breakouts, and transaction-level valuations) are not reproduced here. The full report contains those proprietary arrays and downloadable models designed for direct incorporation into corporate planning processes.
MW/Quant approach and confidence metrics
Our estimates combine bottom‑up supply data (plant capacities, announced expansions, and utilization assumptions) with top‑down demand modeling (category consumption trends, per‑capita sweetener trajectories, and trade flows). We overlay scenario analyses for policy shocks and feedstock price variance. Our CR3 and CR5 concentration metrics are derived from consolidated shipments and public disclosures; they are included in the full report to calibrate competitive strategies.
Action checklist for senior teams (Q1–Q3 2026)
- Reassess long‑term offtake terms and embed flexibility clauses; prioritize suppliers with near‑term expansions only if they also offer contractual protection against overcapacity.
- Initiate a 90‑day policy-scan with legal and trade teams to identify triggers that would compel reformulation or hedging actions.
- Launch formulation pilots with at least two ingredient partners that offer sensory‑first reduced‑sugar solutions.
- Map exposure to regional supply risk (drought, transport, labor) and secure contingency logistics contracts.
Closing — why this matters for 2026
The HFCS market is entering a phase where incremental changes in policy, feedstock price, and customer formulation choices compound into strategic inflection points. With the market base established near 9.1 billion USD in 2025 and a projected path to roughly 11.54 billion USD by 2032 at a 3.4% CAGR, decisions made in 2026 about supply contracts, investments in formulation, and positioning against sugar alternatives will disproportionately influence competitive outcomes through 2030.
PW Consulting’s full HFCS Market Report provides the granular, actionable intelligence — including the withheld segmentation datasets, supplier scorecards, and downloadable models — required to translate this preview into execution. Contact our advisory team to obtain the complete study and to book a tailored executive workshop that converts these insights into a 2026 operational plan.
For detailed analysis of this topic, please visit the official page: High Fructose Corn Syrup Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Baby Stroller Market to Hit USD 4.25B by 2032 at 5.97% CAGR
By PW Consulting, 2026-07-09
Baby Stroller Market 2026: Strategic Imperatives from PW Consulting’s Industry Outlook
As companies prepare budgets, product roadmaps, and M&A pipelines for 2026, a clear, evidence-based read of the baby stroller market is no longer optional — it is strategic. Our PW Consulting market study, built on a 2020–2025 historical base and a 2026–2032 forecast horizon, consolidates hard market sizing with tactical analysis to guide executive decisions. The headline: the global stroller market expanded from USD 2.12 Billion in 2020 to USD 2.83 Billion in 2025, and is projected to grow to approximately USD 4.25 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 5.97% over the 2026–2032 forecast period. In practical terms, 2026 represents a pivotal inflection year — the market is already moving beyond post-pandemic normalization into differentiated growth driven by product innovation, channel evolution, and regulatory pressure.
Baby Stroller Market
Why this study matters for 2026 decision-making
- Actionable forecasts calibrated to 2026 planning cycles: Our model provides near-term (2026–2028) and medium-term (2029–2032) scenarioss that align with board-level planning horizons — enabling CFOs to stress-test capex and pricing strategies against realistic demand curves.
- Regulatory and trade sensitivity baked into scenarios: With increased CPSC scrutiny, evolving EU GPSR/EN 1888 requirements, and material tariff volatility affecting supply chains, our scenarios quantify the P&L impact of compliance and tariff shifts so sourcing and legal teams can prioritize mitigation strategies.
- Competitive positioning playbooks: The report synthesizes competitor moves, product launches, and partnership activity into defensible playbooks for premiumization, value-tier defense, and channel expansion.
- Integration-ready recommendations: Each chapter concludes with prioritized initiatives — from SKU rationalization to direct-to-consumer (DTC) investments and retail incentives — that can be translated into 90–180 day operational plans.
Market dynamics shaping 2026 strategy
Three structural dynamics are coalescing to define winners and laggards in 2026:
Baby Stroller Market
- Premiumization and modularity: Premium and modular product propositions are attracting higher basket values as consumers trade up for durability, safety, and user experience. Several incumbent brands have accelerated launches that emphasize modular travel systems, compact folding mechanisms, and integrated infant safety systems.
- Regulatory intensity and safety as a differentiator: Mandatory standards such as the CPSC requirements and EU GPSR/EN 1888 are not only compliance checkpoints — they are competitive levers. Brands that incorporate validated safety features early can reduce recall risk and capture trust-driven premium share.
- Supply-chain and trade friction: Tariff regimes and logistics disruptions have materially affected landed costs. Recent industry data point to import tariffs and related adjustments that have forced manufacturers to revise pricing by material bands; as a result, nearshoring, multi-sourcing, and greater vertical control of critical components have moved to the top of corporate agendas.
Competitive landscape: what the leaders are doing
The stroller landscape is comprised of a mix of global manufacturers, speciality premium brands, and value-oriented players. Market concentration metrics suggest a moderately consolidated field: the top three players account for a meaningful slice of revenue and the top five further extend market control — a structure that still leaves room for mid-sized challengers and specialist disruptors.
Baby Stroller Market
- Goodbaby International (Hong Kong) continues to leverage scale manufacturing and a multi-brand distribution model to serve global price tiers and retail partners.
- Britax (UK) positions safety as a primary brand promise and has recently expanded its all-terrain range with enhanced safety features aligned with CPSC updates.
- Thule Group (Sweden) and Baby Jogger (US) are doubling down on active-family segments with all-terrain and jogging models, bringing performance engineering to the stroller category.
- Bugaboo, Nuna, UPPAbaby, and Cybex compete in the premium and design-led tier with high-margin, feature-rich models that emphasize suspension, lightweight materials, and modular interfaces.
- Stokke, Silver Cross, Peg Perego, and Chicco (Artsana) balance European design heritage with product differentiation across travel, urban, and newborn segments.
- Dorel Industries and Newell Brands serve as portfolio stewards for mass-market and specialty lines, enabling broad retail coverage and economies of scale in sourcing.
- Combi and Evenflo offer technological and value propositions in folding and convertible segments, enhancing appeal across digital marketplaces.
Recent product activity underscores these trends: Britax and Thule launched upgraded all-terrain models in early 2026, while Silver Cross introduced both a high-profile lifestyle collaboration and a compact newborn-focused stroller in late 2025 and early 2026. These moves illustrate a bifurcated market: performance and lifestyle innovation at the top end, and functionality and price competitiveness across mainstream channels.
Regulatory and trade pressures: immediate tactical implications
- Compliance-as-product-feature: The CPSC’s focus on restraint systems and ASTM stability testing, together with EU GPSR/EN 1888 material limits, mean product teams must treat compliance validation as a fundamental part of time-to-market planning. Early engagement with accredited test labs reduces launch delays and recall exposure.
- Tariff-driven margin management: Elevated import tariffs from key jurisdictions have prompted price adjustments and forced re-evaluation of sourcing geographies. Short-term mitigation tactics include strategic hedging, inventory pre-positioning, and reconfiguration of product assortments to favour lower-cost modules.
- Channel-specific safety disclosures: Digital marketplaces and global retailers increasingly require validated safety documentation at listing. Brands that build compliant, machine-readable certificate libraries can accelerate marketplace acceptance and reduce delisting risk.
What’s inside the PW Consulting report (practical, execution-oriented chapters)
- Executive summary and investor one-pager designed for boards and finance committees.
- Market sizing and forecast model (2020–2032) with scenario toggles for tariff, adoption, and regulatory outcomes.
- Segmentation frameworks by geography, product type, and age cohort — including forward-looking elasticity estimates and SKU-level demand drivers (note: detailed segment tables are available in the full report).
- Channel and go-to-market playbook: retail, DTC, marketplace, and subscription models with unit economics and margin sensitivity.
- Competitive intelligence dossiers for 15+ global players, including capability maps, go-to-market footprints, and M&A scorecards.
- Regulatory compliance checklist and a recall-risk reduction toolkit, keyed to CPSC, EN 1888, GPSR and key national standards.
- Supply chain stress-test: cost-to-serve modeling, tariff impact simulations, and sourcing diversification strategies.
- Innovation and product roadmap guidance: lightweight materials, suspension systems, fold mechanics, and modular accessories prioritized by expected ROI.
- Consumer insights and segmentation: purchase triggers, online path-to-purchase, and post-purchase service expectations.
- Practical 90-, 180-, and 365-day implementation plans with KPIs for commercialization, pricing, and channel growth.
High-level strategic recommendations for 2026
- Prioritize compliance-first product cycles. Integrate safety validation milestones into gate reviews and allocate budget for pre-certification testing to reduce product launch risk.
- Adopt a dual-sourcing strategy for critical components and consider nearshoring options to mitigate tariff volatility and logistics lead-time risk.
- Differentiate through service and ecosystem thinking: extended warranties, modular upgrades, and accessory ecosystems increase LTV and reduce price elasticity in competitive tiers.
- Rebalance channel investment: accelerate DTC capabilities for premium lines while optimizing retail partnerships and marketplace presence for mainstream tiers to protect shelf visibility and price integrity.
- Pursue targeted M&A and licensing to acquire niche technologies (folding mechanisms, lightweight frames) or distribution gaps — prioritizing partners that add either proprietary IP or fast-access to strategic channels.
- Embed sustainability and circularity into product design to capture consumer preference and preempt material-restriction regulation — programs for trade-in and refurbishment can create recurring revenue streams.
Closing: how PW Consulting helps you act on this market
For 2026, the stroller market is a classic example of an industry where operational execution and regulatory foresight create durable competitive advantage. Our study delivers both — granular forecasts to inform financial planning and practical toolkits to execute quickly and safely. If your 2026 plan includes new product launches, channel expansion, or M&A, the intelligence in this report turns uncertainty into prioritized action.
To access the full dataset, detailed segmentation tables, and competitor scorecards — including the validated scenario models you will need to stress-test 2026 budgets — please consult the full PW Consulting report. The executive playbooks it contains are designed so your management team can move from insight to action within a single quarter.
For detailed analysis of this topic, please visit the official page: Baby Stroller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Carpet Market to Top USD 100 Billion by 2032, 11.75% CAGR
By PW Consulting, 2026-07-09
Carpet Market 2026 Strategic Preview: Opportunities, Risks, and Decisions for Industry Leaders
As companies plan budgets, capital allocations, and go-to-market strategies for 2026, the carpet sector is emerging from a period of structural re‑rating. PW Consulting’s Carpet Market study (base year 2025, historical window 2020–2025, forecast 2026–2032) synthesizes market-scale dynamics, competitive actions, regulatory inflections, and raw‑material risk to produce a decision‑grade roadmap. The headline: the market is projected to expand at a compound annual growth rate (CAGR) of 11.75% from 2026 through 2032, with total market value moving from approximately USD 51.1 Billion in 2025 to a forecast near USD 100 Billion by 2032. That trajectory reshapes priorities for producers, distributors, real‑estate owners, and private equity investors alike.
Carpet Market
Why this preview matters for 2026 decisions
-
Investment timing and capacity planning: Rapid growth implies a narrower window to secure advantaged raw‑material contracts, manufacturing capacity, and logistics capacity. Companies that crystallize near‑term capex and off‑take strategies will capture structural margin benefits.
Carpet Market -
Product and portfolio bets: Sustainability, performance (durability, antimicrobial, allergy‑friendly), and modularity are the engines of premiumization. Strategic product introductions and reformulations in 2026 will determine market share asymmetries over the next five years.
Carpet Market -
M&A and partnership plays: Moderate market concentration (CR3 ~40%, CR5 ~50%) indicates meaningful scale benefits without insurmountable barriers to consolidation—2026 is a pivotal year to execute bolt‑on acquisitions or strategic alliances.
-
Regulatory and compliance risk: New standards and producer responsibility rules will create both costs and defensive moats. Early compliance strategies will be a source of competitive advantage.
Market trajectory — what the numbers imply (high level)
The segment has shown a multi‑year recovery and acceleration: from an estimated USD 30.0 Billion in 2020 to USD 51.1 Billion in 2025, with a projected step to approximately USD 58.7 Billion in 2026 and a path to roughly USD 100 Billion by 2032. At an 11.75% CAGR across the forecast window, the market is large enough to support premium niches and broadscale industrial plays, yet unconsolidated enough to reward differentiated strategies in manufacturing, distribution, and sustainability.
For executives, the implication is simple: the scale and pace make 2026 a “now or wait” pivot year. Delaying investment in product innovation, supply‑chain resilience, or circularity programs risks increased cost exposure and lost market share as demand scales.
Report content — what’s inside (practical, operation‑ready)
-
Macro and market‑size model: interactive topline model updated to a 2026 start with scenario toggles for demand shocks, raw‑material price regimes, and regional demand shifts.
-
Five scenario playbooks: baseline growth, accelerated premiumization, raw‑material shock, regulatory cost adoption (EPR), and rapid modularization—each with P&L and cash‑flow implications.
-
Go‑to‑market and channel strategy frameworks: distributor economics, specification selling to facilities managers, and a retailer/installer playbook.
-
Product roadmap templates: commercialization timeline templates for performance carpets (antimicrobial, allergen‑friendly), modular tiles, and recycled‑content offerings.
-
Supply‑chain and procurement playbook: hedging approaches for polymer feedstocks, supplier segmentation, and sourcing alternatives to manage crude‑oil‑linked volatility.
-
Regulatory and compliance checklist: implementation roadmap for upcoming producer responsibility requirements, updated installation standards, and Green Label/CRI certification integration.
-
M&A diagnostics and valuation multiples: target screening criteria, synergy capture templates, and a three‑tier integration playbook for bolt‑ons and platform deals.
-
KPIs and implementation scoreboard: 90‑day, 6‑month, and 18‑month milestones to de‑risk execution, calibrated for manufacturers and distributors.
Competitive landscape — what incumbents are doing (and what it means)
The market features a mix of global incumbents and regional specialists. PW Consulting’s analysis profiles strategy and capability vectors across the leading firms to reveal where disruption and consolidation are most likely.
-
Mohawk Industries, Inc. (Calhoun, GA) — broadloom and modular carpet tile with differentiated proprietary technologies (e.g., SmartStrand, Pur‑Ease). Recent moves enhance allergy‑friendly performance, underscoring a strategy that pairs product premiumization with brand reach. Implication: rivals must match both performance claims and scale to protect specification channels.
-
Shaw Industries Group, Inc. (Cartersville, GA) — breadth across broadloom and tile under Shaw Contract with recyclable backing (EcoWorx) and spill‑proof technology (LifeGuard). Product launches focused on pet‑and‑spill resilience highlight downstream differentiation for commercial and residential installers. Implication: lower total‑cost‑of‑ownership claims will pressure commoditized price points.
-
Interface, Inc. (Atlanta, GA) — modular tile and systems, carbon‑neutral emphasis. Interface’s sustainability positioning remains a high‑value defensive play in tendered commercial projects and corporate sustainability programs. Implication: buyers with ESG mandates will push specification toward carbon‑light suppliers.
-
Dixie Group, Inc. (Dalton, GA) — premium residential and commercial carpets via Masland Carpets. Niche brand premiumization offers margin insulation but requires tight inventory and design cycles to stay relevant.
-
Milliken & Company (Spartanburg, SC) — commercial tiles and broadloom with focus on durability and antimicrobial solutions. Strength in performance specifications favors long‑term contracts with facilities managers.
-
Beaulieu International Group (Waregem, Belgium) — tufted and needle‑felt carpets with sustainable yarn/backing technologies. European regulatory complexity and supply‑chain resilience drive localized innovation.
-
Engineered Floors, LLC (Dalton, GA) — emphasis on high‑definition realism in DreamWeaver tiles and broadloom; positioning targets both aesthetics and cost efficiency.
-
Mannington Mills, Inc. (Calton, GA) — continues active offerings in residential and commercial despite exits from certain segments; strategy appears to be selective focus on margin‑rich formats and distribution channels.
Recent product developments signal the direction of competition: Shaw’s 2025 Pet Perfect+ and expanded LifeGuard offerings, and Mohawk’s enhancement of SmartStrand with Pur‑Ease probiotic technology (announced early 2026) demonstrate that performance and health‑related features are now strategic imperatives, not niche extras.
Regulatory and raw‑material dynamics — what keeps CFOs awake
-
Standards update: Installation and performance standards were revised in 2026 to accommodate new materials and subfloor preparation processes, making installer training and compliance a near‑term operating cost for manufacturers and contractors.
-
Extended Producer Responsibility (EPR): Certain jurisdictions have introduced or are phasing in producer‑funded collection programs; producers should assume incremental compliance costs and new reverse‑logistics obligations when modeling 2026 budgets.
-
Raw material exposure: Polymers used in carpets (nylon, polyester) link closely to crude‑oil price swings. Procurement strategies that incorporate hedging, alternate resin use, and supplier diversification will materially affect gross margins under an 11.75% CAGR environment where volume growth can mask margin erosion.
-
Trade and tariffs: Imports represent a material, though not dominant, source of supply. Tariff shifts and logistics cost volatility remain meaningful inputs to near‑term sourcing decisions.
Actionable strategic recommendations for 2026
-
Prioritize product claims that reduce total cost of ownership and address occupant health: antimicrobial, allergen‑friendly, and spill‑resistant innovations convert specification to price premium.
-
Fast‑track EPR compliance playbooks: create pilots for take‑back programs and design for recyclability to convert regulatory cost into differentiation.
-
Hedge raw‑material exposure: implement layered procurement contracts (caps, collars, indexed supply) and evaluate substitution potential without compromising performance claims.
-
Target M&A to shore up modular tile capability and circularity tech: acquisitions that add closed‑loop recovery, backing recycling, or advanced extrusion capabilities will offer durable synergies.
-
Commercialize installation and maintenance services: capture downstream value by offering certified installation, cleaning, and refurbishment packages tied to warranties and performance metrics.
How to use PW Consulting’s full report
This preview is designed to orient executive priorities for 2026. The full report delivers the indispensable, transaction‑grade inputs: detailed segment economics, regional demand models, channel margin matrices, product‑level pricing curves, supplier scorecards, and an interactive scenario model that quantifies the impact of the regulatory, raw‑material, and demand uncertainties described here.
We intentionally withhold certain granular segmentation tables and proprietary competitive benchmarking in this overview to preserve strategic value for subscribers. If your 2026 planning requires quantified segment splits, supplier‑level cost curves, or bespoke M&A screening aligned to your balance‑sheet and operational footprint, the full dataset and consulting engagement options are available on the PW Consulting research page.
Closing perspective
The carpet market’s scale and accelerated growth present a rare combination: attractive near‑term top‑line expansion with simultaneous structural change driven by sustainability, health‑performance differentiation, and regulatory tightening. For boards and executive teams, 2026 is the execution year—those who align product roadmaps, procurement strategies, and regulatory responses now will secure superior returns as the market roughly doubles in size through 2032.
PW Consulting’s Carpet Market study converts this landscape into prioritized, executable initiatives. For firms seeking targeted playbooks—whether to win specification share, insulate margins from polymer volatility, or build circular advantage—the comprehensive report and advisory engagement provide the tools to act confidently in 2026.
For detailed analysis of this topic, please visit the official page: Carpet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Infant Radiant Warmer Market to Reach USD 323.28 Million by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-09
Infant Radiant Warmer Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic preview of our comprehensive Infant Radiant Warmer Market research — positioned specifically to inform C-suite and corporate strategy teams planning for 2026. This preview synthesizes market trajectory, competitive posture, regulatory inflection points and supply-side dynamics that will shape near-term choices. It intentionally signals key directional findings while withholding proprietary segment-level granularity to guide readers to the full report for executable detail.
Infant Radiant Warmer Market
Executive snapshot: Why this matters in 2026
-
The infant radiant warmer market has demonstrated steady expansion through the early 2020s, underpinned by rising neonatal care capacity, incremental technology adoption in NICUs and improving procurement budgets in both developed and emerging healthcare systems.
Infant Radiant Warmer Market -
On a macro basis, the market expanded from the low hundreds of millions in 2020 to an estimated USD 215.0 Million in the base year 2025 and is forecast to continue growing at a compound annual growth rate (CAGR) of approximately 6.98% through our 2026–2032 forecast window, reaching an estimated USD 323.3 Million by 2032. This trajectory creates a multi-year runway for product innovation, after-sales services and digital-enablement plays.
Infant Radiant Warmer Market -
Market structure remains moderately fragmented — leading vendors do not dominate the space to the degree seen in other hospital equipment categories — creating room for differentiated offerings, regional specialists and partnering strategies. Our concentration metrics indicate that the top three to five suppliers capture a modest share of the market, leaving meaningful share for mid-sized and local players.
Core market dynamics shaping 2026 decisions
-
Demand drivers: Growth is a function of NICU bed expansion, higher survival rates for preterm infants, and increasing clinical emphasis on thermal regulation as a component of bundle care. Hospital purchasing cycles are lengthening for capital equipment, but they are simultaneously allocating more to digital and service-enabled platforms.
-
Technology inflection: Vendors increasingly embed IoT telemetry, integrated monitoring and modular interfaces that link radiant warmers to NICU ecosystems. These capabilities drive differentiation beyond heating performance — from workflow optimization to remote asset management and predictive maintenance.
-
Regulatory and safety posture: Infant radiant warmers remain regulated under established Class II device frameworks in major markets and are subject to recognized IEC safety standards that have seen material technical revisions. Recent recalls tied to electrical safety testing shortcomings emphasize that manufacturers must demonstrate rigorous compliance and traceability across development and production to protect market access and brand trust.
-
Supply-side supply chain & manufacturing: Investments in precision component capacity have accelerated, easing prior constraints and enabling scale-up without compromising quality. We track material and component capacity growth that supports vendor roadmaps, though localized sourcing risk and logistics volatility persist for certain high-precision subassemblies.
-
Reimbursement and purchasing landscapes: Procurement behavior is heterogeneous. Reimbursement frameworks, hospital capital planning policies and NICU digitization strategies materially influence adoption of higher-spec, connected warmers versus cost-optimized models — a segmentation that the full report maps in detail.
What the PW Consulting report delivers — practical intelligence for 2026 action
-
Executive summary and investment thesis tailored for corporate strategy and investor audiences.
-
Five-stage market model covering historical performance (2020–2025) and a seven-year forecast (2026–2032) with scenario variants for conservative, base and accelerated adoption curves.
-
Detailed go-to-market playbooks: product positioning, pricing archetypes, service bundles, tendering tactics and hospital procurement navigational maps for tertiary, community and private maternity segments.
-
Regulatory matrix and risk-control checklist aligned to the latest IEC and FDA requirements, including protocols to minimize recall risk and to accelerate 510(k)/premarket submissions where required.
-
Supply chain and manufacturing heat map specifying critical components, capacity hotspots, single-sourced risks and recommended mitigation strategies (dual-sourcing, design-for-manufacturing adjustments and strategic inventory buffers).
-
Competitive intelligence dossiers on global incumbents and regional challengers, including product roadmaps, partnership footprints, pricing posture and M&A targets.
-
Commercial due diligence templates, buyer persona profiles, and a KPI-driven implementation roadmap to translate strategy into measurable adoption milestones and margin improvements.
Competitive landscape — positioning and recent moves
The market is characterized by a mix of global platform providers, specialized neonatal equipment manufacturers, and cost-competitive regional suppliers. Our report provides company-level playbooks; below are high-level strategic positions for the key players we monitor:
-
GE Healthcare (Chicago, USA) — A platform player integrating IoT-enabled warmers with hospital IT and monitoring systems. Recent product updates emphasize real-time neonatal and environmental telemetry for tertiary NICUs. Their scale and systems integration capability make them a strategic partner for large hospital networks seeking end-to-end device interoperability.
-
Drägerwerk AG & Co. KGaA (Lübeck, Germany) — Known for precision temperature control and deep NICU monitoring ecosystems. Dräger’s strength lies in clinical-grade integration and service networks across European and adjacent markets.
-
Atom Medical Corporation (Osaka, Japan) — Focuses on rapid-access designs and modularity for high-acuity settings. Active presence at NICU leadership forums underscores a clinician-centric commercialization approach.
-
Natus Medical (San Carlos, USA) — Differentiates via integration with neonatal screening and diagnostic workflows, appealing to NICUs pursuing combined diagnostic-therapeutic suites.
-
Fisher & Paykel Healthcare (Auckland, NZ) — Leverages respiratory care capabilities to offer humidified/non-humidified warmers tied to neonatal respiratory support — attractive for preterm care bundles.
-
Regional specialists — Phoenix Medical Systems, NICE Neotech, Heal Force, Fanem — These vendors compete on a combination of cost, localized service, and product configurations tailored to regional procurement norms. They account for a substantial portion of volume in price-sensitive segments and emerging market tenders.
Recent vendor activity tracked by our research includes trade show engagements, product catalog refreshes and targeted product updates that collectively reflect a market transitioning from hardware-only to hardware-plus-service propositions.
Regulatory and safety watchpoints
-
Compliance with the prevailing IEC safety standard for infant radiant warmers and region-specific premarket notification processes remains non-negotiable for market access. Technical revisions in the standard have raised the bar on testing and documentation.
-
Notable safety events in the prior two years highlight the reputational and commercial consequences of manufacturing and testing lapses. For strategy teams, the implication is clear: robust validation, supplier audits and third-party testing are strategic levers that can create defensible differentiation.
Supply chain and manufacturing implications
-
Precision component capacity has expanded meaningfully across the ecosystem, supporting scale-up plans without the quality trade-offs that characterized earlier cycles. Nevertheless, companies should assess single-source dependencies for critical elements (e.g., sensors, ceramic heaters) and build contingency plans.
-
Service and lifecycle revenue will be a key margin driver. Bundling preventive maintenance, remote diagnostics and consumable supply contracts is the single most effective way to increase customer lifetime value in a market where capital replacement cycles are moderate.
Strategic implications for 2026 — five recommended priorities
-
Invest in connectivity and clinical workflows: Hospitals now value warmers that integrate with monitoring and EHR systems — prioritize interoperability standards and API readiness.
-
Differentiate on service economics: Design aftermarket contracts (SLA tiers, predictive maintenance) that lock in recurring revenue and reduce total cost of ownership for buyers.
-
Prioritize compliance and testability early in R&D: The cost of late-stage remediation after a regulatory finding or safety event is material; accelerate design verification and supplier qualification.
-
Pursue partnerships to access distribution in price-sensitive regions: Local channel partners and manufacturing alliances reduce go-to-market friction and comply with procurement preferences.
-
Use M&A and licensing selectively: Given the moderate concentration in the market, targeted acquisitions of regional players or niche technology (e.g., non-invasive thermal sensors, integrated phototherapy modules) can yield rapid capability assembly.
How to use this preview — next steps
-
For CEOs and corporate development teams: Use the report’s scenario forecasts and competitive playbooks to prioritize market entries, JV targets and acquisition due diligence in 2026.
-
For product and R&D leaders: Leverage the regulatory matrix and validation checklists to shorten time-to-market while reducing recall risk.
-
For commercial leaders: Apply the go-to-market templates and tender-play frameworks to win institutional buyers and design higher-margin service offerings.
PW Consulting’s full Infant Radiant Warmer Market report contains the granular segmentation, regional demand profiles, product-level competitive scorecards and actionable financial models required to operationalize the strategic priorities outlined above. This preview demonstrates our analytic depth and the practical pathways available to market participants in 2026; the complete study holds the confidential, transaction-grade detail that implementation teams will require.
To access the full intelligence package — including the proprietary regional and application breakdowns, vendor scorecards and executable playbooks — visit PW Consulting’s report portal or contact our market strategy team for a briefing.
For detailed analysis of this topic, please visit the official page: Infant Radiant Warmer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Avian Influenza Vaccines Market to Top USD 240.61M by 2032
By PW Consulting, 2026-07-09
Avian Influenza Vaccines Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present a focused, high-resolution preview of the Avian Influenza (AI) Vaccines market intended to frame the strategic questions every executive must answer in 2026. This briefing synthesizes market trajectory, competitive shifts, regulatory inflection points and practical implications — while withholding granular subsegment figures to preserve the “trailer” ethos: enough depth to build confidence, not enough to replace the full report.
Avian Influenza Vaccines Market
Executive snapshot
The AI Vaccines market has expanded from its 2020 baseline through the most recent base year (2025) and is forecast to continue growing over the 2026–2032 horizon at a compound annual growth rate of 5.55% (revenues expressed in Million USD). PW Consulting’s model shows steady recovery and structural expansion driven by policy-led demand, diversified vaccine formats, and capacity investments across public and private producers. Market concentration remains modest: the top three firms account for roughly 28.5% of reported revenue, and the top five about 37.8%, indicating an industry with established leaders but meaningful room for challengers and regional specialists.
Avian Influenza Vaccines Market
Why 2026 is a decision inflection year
-
Regulatory momentum is reshaping market access. Conditional licensing pathways and exceptional-circumstance approvals introduced in 2024–2025 have compressed time-to-market for candidate vaccines. These pathways change how companies allocate R&D and commercial resources in 2026: go-fast strategies can capture immediate outbreak-driven demand, but they increase exposure to post-approval evidence requirements.
Avian Influenza Vaccines Market -
Supply-side expansion and manufacturing modernization are occurring at scale. Investments in fermentation-based plants and cell-culture platforms enable faster ramp-up and diversified antigen production — a competitive advantage for firms that tie capacity expansion to flexible product portfolios.
-
Public-sector funding commitments to vaccine innovation and outbreak mitigation alter return-on-investment calculations for both incumbents and new entrants. In 2025, major government programs and direct funding streams emphasized vaccine R&D and reduced reliance on depopulation strategies, creating new procurement channels and risk-sharing opportunities.
Market trajectory — what the headline numbers reveal
From PW Consulting’s historical dataset (2020–2025) and forecast (2026–2032), the market shows a trajectory consistent with transition from episodic outbreak response to a more structural vaccination paradigm in poultry health. The base-year snapshot (2025) and forward model indicate continued expansion through 2032, with the modeled end-point reflecting cumulative adoption of newer vaccine formats, policy-driven stockpiling, and incremental uptake across production systems. This is a capital-intensive, technology-sensitive market: small shifts in regulatory acceptance or large-scale outbreaks materially alter the spending curve within single years.
What the full report delivers — practical, transaction-ready intelligence
- Transparent market model (Million USD) with historical series and scenario-based forecasts through 2032, including sensitivity analyses for outbreak frequency and regulatory acceleration.
- Demand-driver mapping that links epidemiology, poultry production trends and procurement mechanics to short-, medium- and long-term revenue pathways.
- Regulatory playbook detailing conditional and exceptional-circumstance pathways in major jurisdictions, evidence expectations, and post-authorization compliance risks.
- Manufacturing and supply-chain heatmap highlighting capacity nodes, critical raw materials, fill-finish constraints and lead-time risk across production technologies (egg-based, cell-culture, fermentation-based).
- Competitive capability assessments and go-to-market archetypes for incumbents, regional specialists and biotech entrants, including commercial channel strategies and partnership templates.
- Transaction-ready M&A and JV scoring tools to screen targets based on technology fit, regulatory readiness, geographic foothold and scale economics.
- Country-level playbooks for priority markets, with procurement levers, stakeholder maps and recommended local engagement strategies (note: granular subsegment revenues and percentage splits are reserved for the full report).
Competitive landscape — what to watch in 2026
The market is being actively reshaped by a small group of global animal health companies and by national programs focused on rapid production capacity. The recent cadence of product approvals and commercial launches underscores a move from single-product responses to portfolio-based defense strategies.
-
Zoetis (Parsippany, NJ): The February 2025 conditional USDA license for an H5N2 killed-virus vaccine for chickens is emblematic of a strategy that prioritizes rapid regulatory entry through safety-and-serology-based submissions. For competitors and partners, the critical observation is how Zoetis balances conditional market access with the timeline and investment required to deliver confirmatory efficacy data.
-
Boehringer Ingelheim (Ingelheim, Germany): With the February 2025 launch of a trivalent poultry vaccine (HVT+IBD+H5) and subsequent positive opinions from the EMA CVMP under exceptional circumstances, Boehringer highlights a differentiation strategy by combining multi-pathogen protection with regionally tailored registrations. This multi-valent approach can raise switching costs for producers but requires careful cold-chain and administration training investments.
-
Ceva Animal Health (Libourne, France): Ceva’s availability of nucleotide-based vaccines for certain poultry species and its expanded fermentation-based manufacturing footprint illustrate a two-pronged route: technology diversification plus production scale. Their new capacity suggests a strategic bet on multi-component inactivated vaccines and faster ramping during outbreak cycles.
-
SK Bioscience (Seoul, South Korea): Focused on cell-culture platforms and national pandemic preparedness programs, SKB’s strengths lie in rapid mass-production capability and partnerships with public health agencies. Their trajectory makes them a logical collaborator for governments seeking domestic surge capacity.
Tactical takeaway: incumbents are leveraging differentiated regulatory strategies (conditional approvals, exceptional-circumstance submissions) and product architectures (monovalent vs. multivalent) to create commercial moats. New entrants and regional players are countering through specialized platforms and local capacity investments. Competitive advantage will be earned at the intersection of regulatory navigation, manufacturing flexibility and commercial deployment speed.
Key dynamics and risks that shape 2026 strategic choices
-
Regulatory uncertainty: Conditional or exceptional approvals shorten market access timelines but create downstream evidence obligations and potential market withdrawals if confirmatory studies fail to meet expectations.
-
Antigenic drift and strain variation: Vaccine efficacy and update cycles mimic patterns seen in human influenza — requiring agile R&D and potentially periodic reformulations.
-
Production bottlenecks: Fill-finish capacity, adjuvant availability and specialized cold-chain handling remain operational choke points in high-demand scenarios.
-
Procurement volatility: Government stockpiling and outbreak-driven buying create lumpy demand; contracting and pricing strategies must account for episodic spikes and long-tail maintenance needs.
Actionable 2026 playbook — prioritized moves for each stakeholder
-
Manufacturers: Prioritize regulatory portfolios where conditional pathways accelerate access and pair them with a clear, funded plan for post-authorization efficacy documentation. Hedge with multi-platform manufacturing options to reduce single-point capacity risk.
-
Mid-size firms & biotech entrants: Target partnerships for fill-finish and distribution to avoid high fixed costs while demonstrating niche differentiation (e.g., delivery systems, thermostable formulations, or species-specific platforms).
-
Investors & M&A teams: Use the PW M&A scoring matrix to screen targets that combine regulatory readiness, capacity optionality and government-contracted revenue streams. Pay particular attention to platform technologies that shorten antigen update cycles.
-
Government and procurement bodies: Design contracts that balance upfront demand guarantees with performance-based milestones to incentivize both capacity investment and continued efficacy evidence generation.
-
Poultry producers and integrators: Integrate vaccination strategy with biosecurity and surveillance investments; evaluate vaccines not only on unit cost but on production impact (mortality, downgrades, movement restrictions).
How PW Consulting’s full report informs the 2026 roadmap
Our comprehensive market study provides the quantitative backbone and qualitative insight needed to prioritize investments and operational changes in 2026. It combines a defensible revenue model (Million USD) with practical tools — regulatory timelines, procurement templates, and a ready-to-use M&A scoring framework — that convert strategy into executable initiatives. The preview above is intentionally selective: it signals where value is concentrated and what choices matter without disclosing core subsegment allocations that drive competitive advantage.
Next steps
-
Download the full PW Consulting Avian Influenza Vaccines Market report to access the complete dataset, regional and application breakouts, supplier scorecards, and executable playbooks for 2026 implementation.
-
Schedule a strategy workshop with our team to translate the report’s scenarios into a 12–36 month action plan tailored to your organization’s risk tolerance and portfolio strengths.
In a market where regulation, technology and capacity investments converge to determine winners, the decisions leaders make in 2026 will define market position for the decade. This briefing identifies the hinge points; the full report supplies the levers.
For detailed analysis of this topic, please visit the official page: Avian Influenza Vaccines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rubber Gloves Market to Reach USD 14,855M by 2032, Growing at 3.98% CAGR
By PW Consulting, 2026-07-09
Rubber Gloves Market — Strategic Outlook for 2026: A PW Consulting Preview
As companies plan budgets, capital projects, and supply-chain moves for 2026, the rubber gloves market presents a mix of stabilized growth, intensified regulatory scrutiny, and commercially material cost pressures. PW Consulting’s upcoming full study (base year 2025) synthesizes seven years of historical performance and a seven‑year forecast horizon (2026–2032) to give procurement leaders, manufacturing executives, and private equity sponsors the actionable guidance they need to convert market signals into defensible decisions.
Rubber Gloves Market
Macro snapshot: trajectory and market structure
The market has shown steady expansion since 2020, rising from a USD 10.0 billion baseline to USD 11.5 billion in 2025 (base year of our study). From 2026 through 2032 our model projects a compound annual growth rate (CAGR) of approximately 3.98%, producing a mid‑single‑digit expansion path that culminates in a market size north of USD 14.8 billion by 2032. These headline numbers reflect maturation after the COVID‑era spike, with growth driven by modest demand increases in healthcare and industrial channels, product innovation (synthetic formulations and task‑specific grades), and selective substitution between natural and synthetic chemistries.
Rubber Gloves Market
Concentration dynamics matter: the market remains moderately concentrated with the top three players controlling a majority share and the top five accumulating around seventy percent of industry sales. This oligopolistic posture shapes competitive behavior — from price leadership to capacity discipline — and creates windows for disruptive entrants who can demonstrate differentiated technology, traceable raw material sourcing, or compelling cost advantage.
Rubber Gloves Market
Why this study matters for 2026 decision‑makers
- Procurement & supplier strategy: With trade barriers and tariff shifts now a live threat to supply continuity, establishing resilient multi‑sourcing and nearshoring options is no longer optional. Our modelling quantifies the sensitivity of landed cost to tariffs and energy price swings so commercial teams can set defensible sourcing triggers and contract clauses for 2026.
- Regulatory compliance & quality investments: The regulatory landscape has tightened. The FDA’s Quality Management System Regulation (QMSR) harmonization with ISO 13485 took effect in early 2026 and several glove types remain subject to premarket pathways. Firms can use our compliance-risk matrix and gap remediation playbook to prioritize certification and submission timelines that align with product launch windows and tender cycles.
- Capital allocation & capacity planning: Capacity commitments are multi‑year bets. Our capacity/utilization scenarios help capital planners evaluate near‑term brownfield expansions versus longer‑term greenfield investments, accounting for energy intensity, labor cost trajectories, and differentiated product mixes.
- Product & go‑to‑market strategy: The pace of formulation innovation — including patented synthetic latex alternatives — means differentiation often trumps commodity scale. Our report provides commercial segmentation frameworks and go‑to‑market blueprints that accelerate premiumization strategies without sacrificing volume coverage.
What the PW Consulting report delivers (operationally usable content)
- Consolidated historical series (2020–2025) and scenario‑based forecasts to 2032 with explicit assumptions and sensitivity levers.
- A regulatory playbook covering FDA QMSR alignment, 510(k) pathways, EU market access requirements, and traceability expectations for natural rubber sourcing — with a prioritized remediation checklist for manufacturers and importers.
- Cost‑build templates and supplier benchmarking tools: raw material input models, energy and labor cost drivers (including energy’s non‑trivial share of nitrile production cost), and total landed cost calculators tailored for the major sourcing hubs.
- Competitive heatmaps and capability matrices: supplier profiles, capacity footprints, product certifications, and go‑to‑market posture to inform partner selection and M&A screening.
- Commercial playbooks: pricing playbooks under alternative tariff regimes, tender win strategies for institutional healthcare purchasers, and channel optimization for food‑safety and industrial buyers.
- M&A and JV decision frameworks: scenario modelling for bolt‑on acqui sitions, greenfield versus contract manufacturing, and integration risk checklists for post‑deal value capture.
- Risk dashboards: scenario simulations for demand shocks, raw material price spikes, trade barriers, and regulatory events with quantified EBITDA implications for each scenario.
Competitive landscape — positioning, recent moves, and strategic implications
The market’s incumbent set includes global majors and regionally focused specialists. Their strategic choices provide a useful map of where value and capability are consolidating — and where gaps remain for new entrants.
- Top Glove Corporation Bhd — A scale powerhouse oriented to high‑volume nitrile and latex dipping production. Its manufacturing playbook emphasizes throughput and global distribution reach, which makes it a price setter in many institutional channels. For decision makers, Top Glove’s moves underscore the importance of ensuring supply‑contract flexibility when relying on large‑scale producers.
- Sri Trang Gloves (Thailand) — A major supplier with differentiated initiatives around traceable natural rubber. Recent shipments of EUDR‑compliant natural rubber product demonstrate how traceability and sustainable sourcing can open premium commercial channels in Europe. Procurement teams should treat traceability as a commercial negotiation point, not just a compliance checkbox.
- Ansell Limited — Focuses on high‑performance nitrile formulations and chemical‑resistant task‑specific gloves. Ansell’s strategy shows the viability of margin accretion through R&D and branded medical grades; buyers seeking specialty protection increasingly prioritize task fit and lifecycle cost over unit price.
- Showa Group — A US‑based player expanding domestic capacity and leveraging regulatory approvals (e.g., FDA 510(k) clearances) to serve customers seeking on‑shore supply. The Showa case is a template for nearshoring strategies that reduce tariff exposure and lead times.
- Thai Rubber Gloves Company Limited & Kim Gloves — Both emphasize quality standards for latex and nitrile medical gloves, serving a mix of OEM and own‑brand channels. Their business models highlight the continued relevance of contract manufacturing and flexible private‑label strategies.
- Comfort Rubber Gloves Industries — The company’s recent FDA 510(k) clearance for nitrile patient examination gloves is evidence that smaller manufacturers can achieve regulatory differentiation to access institutional procurement lists.
- INTCO Medical — Launched a patented synthetic disposable latex product with broad regulatory compliance (FDA, EU CE, EN455, EN374). This illustrates how material innovation can create commercially defensible niches and exert pricing pressure on traditional latex offerings.
Regulatory and trade shocks — immediate action items for 2026
- QMSR compliance is now a gating criterion for market access into regulated jurisdictions. Companies should prioritize gap assessments and remediation projects with 9–12 month timelines.
- Tariff exposures have been materially rearranged by recent policy moves (notably steep import duties on certain nitrile supplies from specific origins effective January 2026). Firms must reevaluate sourcing contracts, negotiate tariff‑adjustment clauses, and activate contingency suppliers to avoid supply interruptions.
- FDA device classification and premarket pathways remain pivotal for medical grades. Entities marketing clinical‑grade gloves should confirm regulatory status and align labeling, testing, and traceability systems to avoid costly recalls or delistings.
Cost & operations — what to watch
Production economics are sensitive to a limited set of drivers. Energy accounts for a material portion of nitrile manufacturing cost, and regional labor and utility price differences can swing per‑unit economics meaningfully. Our cost‑build templates show how even modest energy or wage inflation changes can erode margin at scale, underscoring the importance of operational efficiency programs and long‑dated energy contracts for manufacturers.
Strategic playbook: five recommended moves for 2026
- Lock dual‑source contracts with pre‑agreed escalation triggers: Combine at least one regional supplier with one global supplier to mitigate tariff and lead‑time risk while preserving competitive pricing.
- Prioritize regulatory readiness: Make QMSR alignment and 510(k) readiness core line items in the 2026 compliance budget — noncompliance risks immediate market access loss and order cancellations.
- Invest in differentiated materials and certifications: Consider selective premium SKUs (traceable natural rubber, patented synthetics, chemical‑resistant nitrile) to reduce exposure to commodity downturns.
- Run capacity & cost stress tests: Use scenario models to test outcomes of energy price swings, tariff shocks, and demand contractions; prioritize projects with the fastest breakeven and highest optionality.
- Scan for value‑accretive M&A: Seek bolt‑on targets that strengthen traceability, speed to regulatory clearance, or access to near‑shore production footprints.
Conclusion — what this preview leaves off (and why you should read the full report)
This preview surfaces the strategic inflection points PW Consulting sees for 2026: steady market growth, concentrated supplier power, rising regulatory demands, and material cost sensitivity that together reshape buyer and producer behavior. The full PW Consulting Rubber Gloves Market report delivers the granular inputs and decision tools you need to execute on the five recommended moves above: detailed market splits, price curve matrices, supplier scorecards, and downloadable financial models that translate scenarios into P&L and cash‑flow impacts.
For commercial teams, operations leaders, and investors whose 2026 plans hinge on glove supply and pricing, the full report is not an academic readout — it is a playbook. PW Consulting clients and subscribers can access the complete dataset, templates, and bespoke consulting modules to turn these insights into executable plans.
For detailed analysis of this topic, please visit the official page: Rubber Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


