



Category: Healthy Lifestyle
PW Consulting: USB Wall Charger Market at USD 1,610.8M in 2025, 3.9% CAGR to 2032
By PW Consulting, 2026-07-09
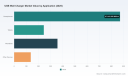
USB Wall Charger Market 2026: Strategic Preview for Decision-Makers
As companies prepare strategy and capital allocation plans for 2026, the USB wall charger sector presents a mix of steady market expansion, accelerating technology substitution, and regulatory inflection points that will determine winners and losers. PW Consulting’s full market study synthesizes historical performance, a 2026–2032 forecast, supplier economics, and competitive positioning into a decision-ready playbook. This introduction highlights the report’s strategic value and the high-level implications enterprise leaders must weigh — while intentionally withholding granular segment tables and proprietary models that are reserved for the full report.
USB Wall Charger Market
Market snapshot: steady growth, meaningful scale
Using 2025 as our base year, the global USB wall charger market stands at roughly USD 1.61 billion (Million-USD base). The market is projected to grow at a compound annual growth rate (CAGR) of about 3.9% through our 2032 horizon, reaching just over USD 2.09 billion by the end of the forecast window. These macro dynamics signal a mature market that nevertheless offers pockets of profitable innovation: energy-dense GaN power platforms, multi-port and hub-integrated form factors, and new premium segments tied to high-wattage power delivery for laptops and portable stations.
USB Wall Charger Market
Market structure remains moderately fragmented: the three largest participants account for less than one-third of global revenues, and the top five are responsible for approximately 37% of the market. That fragmentation creates strategic room for focused product differentiation, channel specialization, and M&A that can meaningfully shift standings.
USB Wall Charger Market
Why this research matters for 2026 decisions
- Portfolio prioritization: The study translates macro demand trends into actionable product roadmaps—identifying where to accelerate GaN adoption, where multi-port configurations will command price premiums, and where low-cost incumbency still wins.
- Regulatory timing and compliance: With harmonized standards and compliance windows shifting in 2026, the report maps the calendar and certification levers that materially affect time-to-market and go-to-market sequencing.
- Supply chain economics: We quantify BOM trade-offs and supplier cost points that determine margin levers across ABS, polycarbonate, and aluminum housings, helping procurement teams choose the right cost-quality balance.
- M&A and partnership screening: Given moderate concentration, the report provides an acquisition screening framework tuned to scale, IP, distribution reach, and product-roadmap fit for bolt-on growth.
What’s inside the full report (practical, executable content)
- Market sizing and a scenario-driven forecast model (base year 2025; forecast to 2032) with downloadable Excel projections and sensitivity sliders that let you stress-test demand against price, GaN adoption rates, and regulatory adoption timelines.
- Commercial playbooks: go-to-market templates for consumer, retail, and B2B channels; SKU rationalization matrices; margin waterfall models; and recommended price-positioning for premium PD and multi-port SKUs.
- Supplier and BOM analysis: contractor scorecards, casing cost benchmarks, and a decision matrix for material selection (ABS vs polycarbonate vs aluminum) including cost, manufacturability, and perceived premium trade-offs.
- Compliance and certification tracker: timelines and checklists for USB-IF and region-specific regulations that materially affect launch sequencing and inventory exposure.
- Investor and M&A annex: valuation comparables, playbook for integration, and a short list of criteria for prioritizing targets in a fragmented market.
Note: This public preview highlights themes and strategic implications. The detailed segment breakouts, proprietary demand curves, and exact regional/application revenue splits are intentionally withheld — they are available in the full report and the accompanying models.
Competitive landscape — how leading players are positioned
The competitive environment is defined by a split between branded consumer-electronics players pushing premium, differentiation-led hardware and component suppliers enabling those advances at the silicon and reference level.
- Anker Innovations (Shenzhen) - Anker’s edge lies in consumer brand equity and rapid GaN adoption across multi-port USB-C PD SKUs. Their PowerIQ and PD-focused platforms allow them to trade up consumers to higher-wattage chargers while maintaining channel breadth.
- Belkin International (Irvine) - Belkin leverages retail partnerships and a recognized accessory brand to place BoostCharge-series PD wall chargers into mainstream retail and enterprise channels, emphasizing certified compliance and premium retail experience.
- Aukey (Shenzhen) - Aukey competes on value-led GaN offerings, aiming to balance cost and performance through efficient supply chains and lean SKUs in online channels.
- Ugreen (Shenzhen) - Ugreen’s Nexode family combines multi-port PD capabilities with hub integration, targeting users who consolidate device charging around fewer, more capable wall units.
- RAVPower (US) and Baseus (Shenzhen) - Both push aggressive product iteration in GaN and high-power PD segments, with Baseus emphasizing industrial design and RAVPower focused on battery and accessory system integration.
- Mophie (ZAGG Inc.) (Irvine) - Mophie’s positioning is premium mobile accessory alignment, often tying charger SKUs to broader ecosystem products and retail channels.
- Phihong Technology (Taipei) - Notable for medical-grade and professional AC-DC solutions, Phihong occupies specialized, compliance-heavy niches where certification and reliability trump price.
- Texas Instruments (Dallas) and STMicroelectronics (Geneva) - As IC and reference-design suppliers, TI and ST define the capability frontier. TI’s high-power reference designs and ST’s hybrid PD controllers enable OEMs to accelerate new product launches and adopt the latest PD features without the full internal R&D burden.
Together these players demonstrate the industry’s dual axis of competition: consumer-brand differentiation and component-level innovation. Winning strategies combine both — branded OEMs partnering closely with TI/ST-equivalent suppliers to compress time-to-market on advanced PD and GaN platforms.
Recent catalytic developments shaping 2026 decisions
- STMicroelectronics launched a hybrid USB PD sink controller that accelerates premium sink designs — a practical enabler for higher-function wall units and cross-device power-sharing products.
- Texas Instruments’ integrated reference design for high-power applications simplifies development of ultra-high-wattage chargers and portable-station implementations that previously required bespoke engineering.
- The USB Implementers Forum updated PD compliance guidance, extending a grace period for certain silicon and end-products into late 2026 — a material timing consideration for product roadmaps and certification costs.
- The EU common charger initiative has already reshaped device port strategy for mobile phones and tablets, and its laptop extension in 2026 creates a new addressable market for higher-watt PD wall chargers in Europe.
Technology, regulation and cost realities — practical implications
Three converging forces will determine winners in 2026:
- Technology adoption: GaN and PD 3.x enable smaller, higher-efficiency chargers. Companies that master thermal management, EMI, and intelligent power negotiation will command higher ASPs.
- Regulatory clockspeed: The EU common charger law and extended USB-IF compliance windows create both constraining deadlines and temporary arbitrage opportunities. Firms must map certification cycles to inventory strategies to avoid stranded SKUs.
- Supply economics: Component and housing choices materially affect margin. Standard ABS housings remain the cheapest option, polycarbonate adds modest cost for better finish and durability, while aluminum enclosures elevate build perception and cost. These trade-offs must align with channel and pricing strategy.
Recommended strategic moves for 2026
- Prioritize a two-track product architecture: a modular, lower-cost family for volume channels and a premium GaN/PD family for retail and enterprise where margin is available.
- Lock strategic supply agreements for PD controllers and GaN FETs now. Component lead-times and qualification cycles will compress as demand shifts to higher-wattage PD and EPR-capable designs.
- Embed certification timelines into release milestones. Use the USB-IF grace period judiciously — do not delay fundamental design compliance under the assumption of indefinite extensions.
- Use the market’s fragmentation to seek bolt-on acquisitions or licensing deals that provide quick access to distribution, IP, or niche certifications (medical, industrial) that are otherwise expensive to build.
- Quantify housing decisions in TCO models: the perceived premium of aluminum must be justified by channel positioning and incremental ASP capture.
How to use PW Consulting’s full study
Executives should use the full report as both a tactical guide and a strategic decision engine. Operational teams will find the downloadable models and supplier scorecards essential for SKU rationalization and procurement negotiations. Strategy and corporate development teams can apply the M&A filters and market concentration analytics to prioritize targets and justify valuations. Regulatory and quality teams will get a practical compliance tracker to align certification, testing, and inventory strategies.
This preview showcases the analytical framing and the practical emphasis of our work while preserving the proprietary segment-level analyses, detailed regional and application splits, and downloadable financial models that form the core of the report. To access the full dataset, the scenario model, and supplier-level benchmarking that underpin the recommendations above, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: USB Wall Charger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pulmonary Function Testing Systems to Hit USD 5,948.2M by 2032 at 6.8% CAGR
By PW Consulting, 2026-07-09
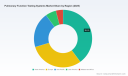
Pulmonary Function Testing Systems Market — Strategic Outlook for 2026 Decision‑Making
As healthcare systems recalibrate post‑pandemic priorities and device manufacturers race to embed connectivity and software intelligence into diagnostics, the pulmonary function testing (PFT) market stands at a decisive inflection point. Our latest PW Consulting market study (base year 2025; historical window 2020–2025; forecast 2026–2032) measures the global PFT systems market in USD Million and projects continued expansion at a steady compound annual growth rate (CAGR) of 6.8% through 2032. The study demonstrates that the market that consolidated its technical and regulatory foundations in the early 2020s is now poised to grow meaningfully across clinical, ambulatory and home care channels — a thesis that has direct implications for strategic investment, product roadmaps, and procurement decisions in 2026.
Pulmonary Function Testing Systems Market
Why this research matters to executives in 2026
- Investment allocation: With finite R&D and M&A capital, leaders need defensible scenarios that link product feature investments (connectivity, cloud analytics, multi‑parameter monitoring) to near‑term clinical adoption and long‑run services revenue.
- Regulatory preparedness: Tighter device regulation in key geographies and international certification expectations mean early regulatory design and clinical evidence generation are strategic necessities rather than compliance afterthoughts.
- Procurement prioritization: Hospital systems and diagnostic networks must balance capital purchases, lease/consumable economics, and staffing constraints — decisions that depend on credible forecasts of device utilization and lifetime service costs.
- M&A and partnership timing: Fragmentation in the supplier base creates entry points for consolidation — but timing matters. Our report gives decision‑grade intelligence for pursuing tuck‑ins versus platform acquisitions.
What this PW Consulting report delivers (practical, action‑oriented)
- Top‑line market sizing and a detailed forecast model (2026–2032) that stakeholders can adapt to their own price, adoption and reimbursement assumptions — presented in USD Million with a clearly documented methodology.
- Segmented market views by region, product type, and clinical application — modeled to reflect divergent adoption curves across settings (clinical labs, outpatient clinics, and home monitoring). Note: the public overview intentionally omits granular split tables to preserve the research premium.
- Competitive landscaping and vendor benchmarking: feature matrices, regulatory statuses (CE/FDA/ISO), distribution footprints, installed base estimates, and aftermarket economics.
- Technology and innovation roadmaps that map emerging modalities (oscillometry, portable spirometry with smartphone integration, integrated cardiopulmonary testing) to realistic adoption timelines and clinical use cases.
- Regulatory and reimbursement playbooks: what to prepare for under EU MDR and international ISO expectations, and how reimbursement pressure shapes clinical workflows and device utilization.
- Commercial strategies and go‑to‑market options: segmentation‑specific pricing models, service contract designs, and channel partnership templates for scaling sales and maximizing attach rates for consumables and software.
- Decision tools: scenario analysis (base, upside, downside), sensitivity tables and an M&A checklist that operationalizes strategic choices for 2026 planning cycles.
Market dynamics and strategic implications
Three dynamics dominate the near‑term strategic landscape. First, demand drivers remain structural: ageing populations and the persistent clinical burden of obstructive and restrictive respiratory disease sustain baseline demand for PFT capacity. Second, technological convergence — miniaturized, accuracy‑certified portable spirometers, cloud connectivity, and advanced signal processing — is expanding the addressable market beyond specialist labs into primary care and remote monitoring. Third, regulatory and procurement realities are shaping product design and commercialization cadence. The European MDR has clarified pathways and evidence expectations for diagnostic respiratory devices; international standards such as ISO 26782 and ISO 23747 are now de facto requirements for many institutional buyers; and hospital accreditation standards tighten expectations for infection prevention and device reprocessing workflows.
Pulmonary Function Testing Systems Market
For manufacturers and investors, these dynamics imply several strategic imperatives: prioritize modular platforms that can be field‑upgraded with analytics and cloud services; embed regulatory and clinical evidence generation early in product development; and design service‑led commercial models that capture recurring revenue from consumables, calibration and software subscriptions. For health systems, the central trade‑off is capital expense versus lifecycle cost: lower upfront spend on portable devices may increase demand for remote management and consumables, shifting the procurement evaluation from unit price to total cost of ownership and clinical throughput.
Pulmonary Function Testing Systems Market
Competitive landscape — who matters and why
The PFT supplier universe includes legacy medical device firms, diagnostic specialists, niche OEMs and software‑centric entrants. Market concentration is relatively low: the three largest vendors account for roughly a quarter of market revenues and the top five capture just above that level, indicating a fragmented market with meaningful room for product differentiation and consolidation. Our vendor analysis covers established players and disruptive challengers, assessing the strategic playbooks behind their positioning.
- Vitalograph: A long‑standing player in professional PFT equipment, Vitalograph continues to expand its diagnostics portfolio through partnerships and targeted product launches. Recent strategic collaborations indicate a deliberate push into advanced oscillometry and complementary modalities to broaden diagnostic reach.
- Jaeger (Vyaire/Jaeger heritage brands): Known for comprehensive lab‑grade systems, these offerings remain the standard in many hospital PFT labs. Their strength is integrated systems for full pulmonary diagnostic workflows, but they face pressure to add lightweight, connected solutions for ambulatory care.
- MGC Diagnostics: Focused on integrated systems and diagnostic software platforms, MGC’s value proposition centers on end‑to‑end testing and analysis — positioning that appeals to clinical labs and research institutions seeking robust reporting and trial‑grade data capture.
- Norav Medical: A representative of USB‑powered compact spirometers and mobile‑first devices. Recent product launches underline the growing commercial viability of small, standards‑certified devices suitable for clinics and home use.
- MIR Medical International Research: Differentiates through smart spirometers and smartphone‑compatible products that target both clinical and patient‑facing use cases, illustrating how consumerization trends are entering a regulated diagnostic space.
Recent industry events underscore these trends: strategic partnerships to expand modality portfolios, product launches of compact, standards‑certified devices suitable for decentralized testing, and regulatory clearances that enable new device integrations and trial uses. Our report documents these developments and maps them to competitive strength and strategic opportunity.
Actionable playbook for 2026 — four priority moves
- For device manufacturers: shift from a one‑time hardware sale mindset to subscription and services bundles (software, analytics, calibration services). Prioritize ISO and clinical standards compliance early to shorten procurement cycles in institutional customers.
- For hospital systems and diagnostic networks: pilot hybrid PFT models that combine an optimized central lab with decentralized screening using certified portable devices. Measure attach rates for consumables and software uptake when evaluating procurement options.
- For investors and M&A strategists: target bolt‑on assets that strengthen software/platform layer or add distribution in underpenetrated channels; use the market’s fragmentation to negotiate favorable valuations while focusing on companies with evidence generation capabilities and regulatory clearances in core markets.
- For payors and policy makers: align reimbursement strategies with clinical quality objectives, incentivizing validated remote monitoring and diagnostic workflows that reduce downstream exacerbations and admissions.
Key operational metrics we recommend tracking in 2026: installed base growth by channel, software ARPU and churn, attach rate for consumables and service contracts, time‑to‑approval for clinical evidence milestones, and utilization per device (tests/month). These KPIs translate directly into revenue predictability and the value of aftermarket streams.
How to use this study in your 2026 planning
This PW Consulting study is designed as a decision support toolkit. Use the top‑line forecasts and scenario models to stress‑test pricing and adoption assumptions for new product launches. Leverage the vendor benchmarking to validate partnership targets and to refine procurement scoring. Apply the regulatory and reimbursement mapping to build realistic clinical evidence plans and to set product launch timelines aligned with certification milestones.
To preserve rigor and commercial sensitivity, the public summary intentionally omits the detailed regional and application split tables, product‑level revenue breakdowns and granular market‑share rankings that underpin our conclusions. For executives preparing budgets, M&A pipelines, or product roadmaps in 2026, those segment‑level insights — together with the full sensitivity models and a downloadable financial model — are available in the full report.
Closing — PW Consulting’s commitment
PW Consulting’s Pulmonary Function Testing Systems Market study combines quantitative forecasting, vendor intelligence, regulatory mapping and executable commercial playbooks to help leaders make informed, timely choices in 2026. Whether your objective is accelerating product commercialization, refining capital allocation, or identifying consolidation targets, the report gives you the contextualized, practitioner‑grade analysis you need — and points clearly to the data and assumptions that matter most for operationalizing strategy.
For detailed analysis of this topic, please visit the official page: Pulmonary Function Testing Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
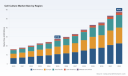
Cell Culture Market — Strategic Outlook for 2026: A PW Consulting Preview
The cell culture market sits at the intersection of biologics scale-up, advanced therapies, and laboratory innovation. Our latest market study, grounded in a 2025 base year and covering historical performance (2020–2025) with a scenario-driven forecast to 2032, shows a clear and sustained expansion: the global market has roughly doubled over the past half-decade and is projected to grow at a compound annual growth rate of 11.2% through the forecast window. By 2026 the market enters a phase in which regulatory flexibility, concentrated supplier positions, and raw-material fragility will materially change competitive dynamics — making strategic clarity essential for executives who must convert momentum into durable advantage.
Cell Culture Market
Why this study matters to 2026 decision-makers
- Investment timing and scale: The market’s robust mid-term growth creates a premium for correctly timed capacity investment. Our forecast converts headline growth into payback curves for different product and channel strategies, helping CFOs avoid both under- and over-capitalization.
- M&A and partnership prioritization: Consolidation and capability-led deals will be the fastest way to secure differentiated inputs for biologics and cell therapy customers. Our deal-prioritization framework ranks targets on technical fit, regulatory readiness, and integration risk.
- Portfolio optimization: With customers demanding defined media, xeno-free options, and GMP-ready inputs, product roadmaps must re-balance R&D, manufacturing, and commercial spend. We translate market growth into product-level revenue opportunity and relative margin dynamics without exposing third-party proprietary segment datapoints here.
- Supply-chain resilience: The market’s rising sensitivity to raw-material variability and logistic interruptions means procurement and quality leaders must move from transactional sourcing to strategic supplier management. Our supplier-risk heatmap and sourcing playbook are designed for immediate operationalization.
- Regulatory strategy: Recent regulatory shifts — including finalized flexible CMC expectations effective January 2026 and subsequent FDA draft guidance — create both faster routes to clinic and new quality obligations. The report maps those levers to program-level investment decisions.
What you get in the full report — practical, executable deliverables
- Dynamic market model (historical 2020–2025; forecast 2026–2032) with base-case, conservative, and upside scenarios. The model is fully editable so corporate planners can test their own assumptions.
- Executive playbooks: 90 / 180 / 360-day roadmaps that link analytic findings to immediate tactical moves across R&D, manufacturing, procurement, and commercial functions.
- Regulatory impact matrix that aligns jurisdictional changes (US, EU, key APAC regulators) to go-to-market consequences, compliance cost drivers, and approval timelines.
- Supplier risk heatmap and mitigation templates for raw materials and critical reagents, complemented by dual-sourcing scorecards and contract language examples that reduce single-source exposure.
- M&A screening tool with valuation ranges and integration-risk scoring — designed to fast-track target shortlists for corporate development teams.
- Commercial benchmarking and price-mix sensitivity analyses calibrated to current market conditions and projected customer mix changes through 2032.
- Interactive dashboards and downloadable datasets that underpin the study’s headline forecasts and allow senior leaders to run bespoke scenarios.
Competitive landscape — what leading players are doing and what it means strategically
The market displays a moderate-to-high concentration among the top suppliers. Our concentration analysis shows the three largest companies control a meaningful share of the market, with the top five capturing a sizable majority — a structure that creates both barriers to entry and pockets of partnership opportunity for companies that can offer complementary capabilities or unique supply assurances.
Cell Culture Market
- FUJIFILM Irvine Scientific — A specialist in serum-free and perfusion-optimized media with strong custom bioprocessing capability. Recent 2026 partnerships (commercial platform combining RUO stromal cells and a Canada–Japan collaboration on AAV production enhancers) demonstrate a strategy centered on platform partnerships. Strategic implication: competitors should expect FUJIFILM to push deeper into cell-therapy-adjacent services; partnerships or targeted investments in AAV optimization will be required to defend certain industrial segments.
- Thermo Fisher Scientific (Gibco) — Broad portfolio breadth and scale advantage remain core strengths. Thermo Fisher’s depth across mammalian, primary, stem, and 3D media positions it to defend volume markets while attacking higher-margin specialty niches through bolt-on technologies. For mid-sized players, differentiation against Thermo Fisher will require hyper-specialization or service-led models.
- Merck KGaA (MilliporeSigma) — GMP-validated manufacturing footprint and certification credentials remain a differentiator for customers requiring regulatory-ready inputs. Firms without certified GMP pathways should consider subcontract or joint-venture routes to retain or win biomanufacturing customers.
- Sartorius AG — Focus on xeno-free and animal-component-free solutions fits the industry’s trajectory toward defined reagents for therapeutic manufacturing. Opportunities exist for suppliers to co-develop with process-technology providers like Sartorius to accelerate adoption.
- Corning & Lonza — Corning’s labware and Lonza’s scale in scalable media and gene-therapy-relevant reagents create complementary competition dynamics: physical infrastructure plus biology. Strategic partnerships that bundle lab consumables with defined media can create sticky customer relationships.
- Specialists (PromoCell, STEMCELL Technologies, Cell Biologics) — These players are leveraging product specialization, GMP entry, and stem-cell-specific portfolios to capture premium niches. Notably, PromoCell’s 2025 GMP entry signals accelerated commercialization intent; incumbents should expect more vertical moves from specialists.
Regulatory and supply-side dynamics you cannot ignore in 2026
- Regulatory acceleration and conditional flexibility: With flexible CMC requirements finalized for certain cell and gene therapies (effective January 2026) and subsequent draft guidance from the FDA in mid-2026, developers have clearer, faster paths to clinical access — especially for small-patient-population programs. However, speed increases the premium on robust quality systems and supplier traceability.
- European expectations for reagent purity: EMA guidance emphasizes microbial purity expectations for cell culture reagents under GMP—therefore manufacturers must reconcile expedited development timelines with uncompromising contamination control obligations.
- Ongoing contamination-control enforcement: EU GMP Annex 1’s applicability has catalyzed elevated compliance activity for sterile operations; this remains an ongoing cost and capability consideration.
- Raw-material volatility: Variable raw-material quality and intermittent supply disruptions continue to be a primary operational risk. Commercial leaders should prioritize contractual levers, buffer strategies, and near-shoring where feasible.
Actionable 90/180/360-day playbook for executives
- 0–90 days: Run a sensitivity analysis of your top three product lines against the full report’s scenarios; initiate supplier quality audits for all single-source reagents; complete a regulatory gap analysis relative to new CMC expectations.
- 90–180 days: Execute prioritized mitigations — secure second-source agreements, scope GMP certification for key sites (or identify certified partners), and test at least one strategic partnership for platform or AAV-related capability.
- 180–360 days: Implement capacity investments or targeted M&A based on validated demand cases; lock in multi-year supply agreements; roll out revised commercial pricing informed by the report’s price-mix scenarios.
Why PW Consulting’s study is the right tool for 2026
Our analysis blends an editable, scenario-ready market model with proprietary primary research, supplier audits, and a regulatory-impacts framework designed for rapid executive use. We reveal the market’s overall trajectory and concentration dynamics (the top three and top five companies together account for a material proportion of demand), provide hands-on operational templates, and align strategic choices to the changing regulatory landscape — while deliberately withholding detailed segmentation outputs in this preview to protect analytical integrity and client value.
Cell Culture Market
For commercial teams, R&D leaders, and corporate development executives who must make decisions this year, the full report delivers the calibrated intelligence to move quickly and defensibly. To access the complete datasets, downloadable models, and our recommended transaction shortlist, please visit the PW Consulting publication page for the Cell Culture Market study.
For detailed analysis of this topic, please visit the official page: Cell Culture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
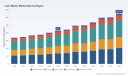
Lawn Mower Market — 2026 Strategic Preview
As global demand for lawn and garden equipment continues to shift toward electrification, automation and service-led business models, senior executives and investors face a compressed window in 2026 to realign product roadmaps, supply chains and distribution strategies. PW Consulting’s new Lawn Mower Market study (base year 2025, forecast 2026–2032) synthesizes primary research, proprietary forecasting and competitive due diligence to turn ambiguity into actionable choices. The market we model was approximately USD 215.0 Million in 2025 and is projected to expand at a 6.1% CAGR over the forecast horizon, reaching roughly USD 325.35 Million by 2032 — a growth profile that rewards disciplined execution but punishes misplaced capital and compliance blind spots.
Lawn Mower Market
Why this research matters for 2026 decision cycles
-
Prioritize capital with conviction: A mid-single-digit CAGR masks divergent trajectories at the product, channel and regional levels. Executives need high-resolution demand scenarios to avoid overbuilding gas-powered capacity or under-investing in battery and robotic platforms that are moving from early-adopter to mainstream in selected end markets.
Lawn Mower Market -
De-risk supply chains under rising input-cost pressure: Producer Price Index trends for steel and electronic components are elevating manufacturing cost volatility. Our analysis quantifies cost exposure across production footprints and identifies hedging and nearshoring strategies that materially improve margin resiliency.
Lawn Mower Market -
Navigate tightening safety and emissions policy: Regulatory moves — from the CPSC’s continued stewardship of walk-behind safety standards to state-level restrictions on small gasoline engines during high-ozone periods — are changing product certification timelines and go-to-market calendars. Companies that integrate regulatory scenario planning into product development reduce time-to-recall and aftermarket fallout.
-
Convert product innovation into recurring revenue: As battery, robotic and connectivity features create opportunities for subscription services, warranty up-sells and data-driven maintenance, manufacturers must realign sales incentives, dealer compensation and CRM systems to capture higher lifetime value.
What the full report delivers (practical, board-ready outputs)
-
Transparent market-sizing and forecasting model (2020–2032) with downloadable Excel workbooks, sensitivity toggles and alternate-policy scenarios to test revenue and margin outcomes under different electrification and regulation paths.
-
Commercial playbooks for product managers and business development teams: go-to-market sequencing, pricing ladders for battery vs. combustion platforms, channel split optimization and dealer incentive redesigns that increase sell-through while protecting gross margins.
-
Detailed supplier and input-cost heatmaps: cost-driver decomposition, single-supplier risk flags, and mitigation checklists for procurement and operations leaders.
-
M&A and partnership target lists with scoring across technical fit, channel access and integration risk — including short-form diligence notes and likely synergies under conservative and aggressive integration scenarios.
-
Regulatory risk matrix and product compliance tracker tied to the CPSC standard set, ANSI/OPEI norms and notable state-level actions that affect market access and product labeling timelines.
-
Commercial benchmark pack: pricing ladders, margin curves, aftermarket attach-rate estimates and service model case studies drawn from primary interviews with OEMs, dealers and fleet operators.
-
Field-validated adoption curves for robotic mowers, battery-electric platforms and connected services, including recommended pilot designs and KPI dashboards for commercial roll-outs.
Competitive landscape — concentration and strategic implications
The lawn mower market exhibits meaningful concentration: the top three firms capture a material share of global revenues (CR3 ~65.4%), and the top five firms account for an even larger proportion (CR5 ~78.2%). This structure creates both barriers and opportunities. Incumbents have scale advantages in manufacturing, distribution and aftermarket networks, while mid-tier specialists and fast-moving entrants can out-innovate on battery systems, software and direct-to-consumer models.
-
The Toro Company (Bloomington, Minnesota) — A dual-brand strategy positions Toro to serve both commercial fleets and residential channels. Strengths include deep dealer networks, proven zero-turn platforms and a capacity to scale new battery and automation offerings. Strategic priorities we observe: accelerating electrified variants, preserving channel economics during product transitions, and leveraging commercial fleet service agreements to grow recurring revenues.
-
Deere & Company (Moline, Illinois) — Deere’s customer base in professional and landscape segments gives it leverage on telematics and service contracts. Its durable ride-on and zero-turn portfolio is a competitive moat; strategic imperatives for Deere will center on aligning heavy-duty electrification with dealer investment cycles and ensuring battery total cost of ownership meets fleet operator thresholds.
-
Husqvarna Group (Stockholm, Sweden) — Husqvarna has been one of the most visible movers in robotic and battery-powered categories. Its R&D depth in robotics, combined with branded consumer reach, suggests it will continue to lead in autonomous small-plot applications. The tactical questions for Husqvarna relate to scaling service and software platforms beyond unit sales.
-
Stanley Black & Decker (New Britain, Connecticut) — Through brands such as Cub Cadet, SBD competes on product breadth and channel penetration. The company’s industrial distribution relationships can accelerate adoption of plug-and-play battery modules; success depends on harmonizing cross-brand platforms to reduce SKU complexity.
-
Metalcraft of Mayville / Scag (Mayville, Wisconsin) — As a specialist commercial manufacturer, Scag’s focus on rugged, high-throughput zero-turn models gives it a loyal contractor customer base. Protecting this edge will require continued investment in service logistics and OEM partnerships for electrified drivetrains.
-
EGO Power+ (Naperville, Illinois) — A pure-play battery-native contender, EGO’s product and battery architecture offers agility in consumer and prosumer segments. The strategic vector for EGO is scaling distribution while defending unit economics as incumbents roll out competing battery platforms.
Regulatory and input-cost environment — what to expect in 2026
-
Safety and conformity: The Consumer Product Safety Commission continues to assert influence over walk-behind mower safety (16 CFR part 1205). A December 2025 Federal Register notice indicates the CPSC’s intent to extend data collection and oversight — translating into longer certification lead times for modified models.
-
Standards alignment: ANSI/OPEI standards remain the reference point for testing and safety — the 2016 base standard and its reaffirmations affect test methodologies, labeling and warranty protocols. Product development calendars must include these test windows to avoid launch slippage.
-
Localized usage restrictions: State-level measures, such as Colorado’s seasonal limitations on certain gasoline-powered equipment during high-ozone months, are proliferating in regions focused on air quality. These rules create seasonal demand shifts and may hasten fleet conversions in impacted geographies.
-
Cost pressures: Rising Producer Price Index readings for steel and electronic components are causing input-cost upcycles. Manufacturers with single-supplier exposures or long lead-time contracts will face margin compression unless they deploy hedging, material substitution or price-indexed contracts.
Technology inflection and go-to-market catalysts
Battery and robotic technologies are the single biggest structural change vectors. The 2026 trade calendar, including major exhibitions such as Equip Exposition (October 20–23, 2026), will be important inflection points for product announcements and channel signaling. Expect three practical outcomes from these technology shifts:
-
Product rationalization: Firms will retire low-velocity internal-combustion platforms and concentrate development spend on modular electrified architectures to shorten development cycles.
-
Channel evolution: Dealers and rental channels will increasingly demand flexible financing for higher-priced battery units and integrated service packages, accelerating the need for OEM-managed pilot programs.
-
Service-led monetization: Remote diagnostics, predictive maintenance and battery-as-a-service models will emerge as differentiators for fleet customers, shifting value capture from initial sale to recurring service income.
Actionable implications by function
-
Product & R&D: Prioritize modular battery packs and common electronics platforms; factor regulatory testing windows into product launch timelines.
-
Supply Chain & Operations: Map single-source exposures for steel and semiconductors, and build alternate-sourcing lanes or nearshore options for critical assemblies.
-
Commercial & Pricing: Test bundled service subscriptions and move toward channel-consistent lease and finance programs that improve adoption of higher-priced electrified units.
-
M&A & Partnerships: Use tuck-ins to acquire battery-system IP, telematics SMEs or last-mile service providers that accelerate recurring revenue capture.
-
Regulatory & Compliance: Institute a product compliance calendar and integrate CPSC and ANSI/OPEI timelines into QA gating and marketing approvals.
How executives should use this preview in 2026
This preview is designed to inform strategic planning cycles, board deliberations and investor communications. Use it to calibrate three deliverables before Q3 2026 stakeholder meetings: (1) a prioritized investment list (capex and R&D), (2) a one-year pilot roadmap for battery/robotic introductions with measurable KPIs, and (3) a two-year supply-chain continuity plan that addresses single-supplier risks and material cost inflation.
For teams preparing divestiture or acquisition cases, the full report contains granular valuation scenarios, integration checklists and a ranked target list that reflects both technical fit and channel access. For product teams, the downloadable models demonstrate break-even thresholds for different powertrains under conservative adoption curves. For compliance and legal teams, the regulatory annex collates primary-source guidance, anticipated comment periods and suggested certification sequencing.
Next step — where the full intelligence is
This strategic preview demonstrates the scope and depth of PW Consulting’s Lawn Mower Market study while purposely withholding the granular segment-level splits and confidential interview transcripts that are central to deal execution and product strategy. For complete access to subsegment revenue breakdowns, channel performance tables, primary interview excerpts and the editable forecast models that underpin our conclusions, please consult the full report on our website or contact your PW Consulting advisor for data-room access and executive briefings.
For detailed analysis of this topic, please visit the official page: Lawn Mower Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pomegranate Market — A 2026 Strategic Preview for Decision Makers
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a concise but high-fidelity preview of our Pomegranate Market research — framed specifically for executives making portfolio, sourcing, and investment decisions in 2026. Built on a base year of 2025 with a historical lens covering 2020–2025 and a forward view to 2032, the work synthesizes commercial intelligence, agronomic evidence, and scenario-based forecasting. The market’s trajectory — underpinned by a compound annual growth rate of 6.8% in our primary scenario — is emblematic of a sector transitioning from niche premiumization to scaled ingredient and nutraceutical relevance.
Pomegranate Market
Why this study matters for 2026 corporate strategy
-
Timing: The market scale has expanded significantly over the past half-decade and, in our base-case forecast, continues to accelerate through the forecast window. That macro momentum creates distinct windows for first-mover advantage in processing capacity, branded premium positioning, and upstream consolidation.
Pomegranate Market -
Resource sensitivity: Pomegranates combine high per-hectare value with intensive seasonal labor and site-specific water requirements. Recent agronomic studies and field trials demonstrating irrigation scheduling and water-productivity gains are already shifting cost curves for efficient producers.
Pomegranate Market -
Fragmentation = opportunity: Market concentration metrics indicate a dispersed competitive set rather than an oligopoly. For strategy teams, that means a broader set of acquisition targets, supplier partnerships, and private-label bidding opportunities — but also higher complexity in sourcing governance.
-
Product pathway flexibility: Demand is emerging across fresh fruit, juices/extracts, and value-added nutraceutical and cosmetic inputs. Each pathway has different margin profiles, capital intensity, and time-to-market — making disciplined portfolio mapping essential.
What the full PW Consulting report delivers (practical tools)
-
Dynamic market model (2020–2032) with scenario toggles for yield shocks, input-cost inflation, and premiumization capture — exportable for integration into internal financial models.
-
Channel and product playbooks that translate demand-side signals into SKU and pricing strategies for branded and private-label propositions.
-
Supply-side heat maps and supplier archetypes that differentiate vertically integrated growers from bulk-ingredient processors and organic specialists.
-
Commercial due diligence templates and valuation compendia for M&A or JV transactions, calibrated to players across the value chain.
-
Operational diagnostic checklists for orchard-to-factory throughput, cold chain sizing, and harvest labor optimization.
-
Regulatory and ESG impact assessments, including water-risk scoring and traceability pathways for sustainability claims.
Market dynamics shaping 2026 decisions
-
Growth trajectory and scale: The category has shown steady expansion since 2020 and, with the forecast path we model, material growth persists through the early 2030s. This creates a compelling runway for capacity investments, but such investments must be matched to demand segmentation and margin pools.
-
Water resource and agronomy innovations: Recent field work in commercial orchards has demonstrated that optimized irrigation scheduling — reducing applied water to targeted rates relative to crop evapotranspiration — can improve fruit quality and yields while lowering production costs and reducing physiological defects. In regions with widely varying seasonal evapotranspiration, such as parts of the Western Cape, drip irrigation optimization materially improves economic water productivity.
-
Labor and capex intensity in advanced systems: Experience from high-density installations shows that pruning and multi-stage harvesting are the dominant operational cost lines, and that initial establishment costs for modern orchards can be substantial. These structural cost realities influence optimal farm-sizing, mechanisation decisions, and the payback horizon for planting-to-production cycles.
-
Leading production hubs and supply balance: Global production centers exhibit different risk and cost profiles — from large-volume producers with cost advantages to high-quality, vertically integrated branded growers supplying premium markets. Sourcing strategies must therefore balance cost, quality, traceability, and seasonality.
Competitive landscape — strategic takeaways
-
Branded, vertically integrated players: Companies that control orchards, processing, and branding are positioned to capture higher margins and protect shelf propositions through traceability and quality consistency. Their playbooks prioritize premium juice and fresh fruit channels as well as value-added extracts for nutraceutical positioning.
-
Specialist processors and regional suppliers: Family-owned and regional processors that focus on organic, cold-pressed juice, or paste/concentrate supply to industrial buyers represent critical nodes for OEM and co-manufacturing strategies. These suppliers are attractive partners or acquisition targets for companies seeking fast route-to-market for new SKUs without greenfield capex.
-
Ingredient exporters and price-competitive producers: Export-focused suppliers with scale in cultivation and pulp/concentrate production are natural counterparts for global CPG manufacturers aiming to secure bulk supply. Their competitive advantage is typically cost and scale rather than branding.
-
Fragmentation encourages deal-making: With market concentration metrics consistent with a fragmented landscape, M&A and off-take contracts are practical levers to consolidate sourcing, secure capacity, and integrate marginal margins. Strategically structured deals can also deliver supply assurances during seasonality and climatic variability.
-
Recent sector moves: Industry research has emphasized water efficiency gains and orchard modernization, while some producing regions have materially expanded planted area using high-density systems. These developments are already changing yield and cost baselines for 2026 planning.
Recommended strategic plays for 2026
-
Supply security first: Prioritize multi-year offtake agreements with suppliers that can demonstrate water-efficiency practices and traceability. Where feasible, combine contractual protection with equity stakes to align incentives and capture upstream margin.
-
Invest in drought-resilient agronomy and precision irrigation: Funding targeted trials or co-investing in irrigation optimization programs can yield rapid improvements in economic water productivity and reduce quality variability — a direct lever to improve gross margins on fresh and processed lines.
-
Segment the portfolio by time-to-margin: Use a three-track investment approach — fast-to-market branded SKUs via co-packing, medium-term value-add extracts and nutraceutical ingredients, and longer-term integrated orchards or capacity that require greenfield capital.
-
Pursue bolt-on acquisitions and strategic partnerships: Identify regional processors and organic specialists as priority targets for quick capacity and capability gains. Given the market’s fragmented structure, targeted deals can re-price sourcing and accelerate channel entries.
-
Operationalize ESG as a commercial advantage: Water stewardship, worker welfare in harvest operations, and verifiable traceability will be differentiators for premium channels and institutional buyers. Build metrics into supplier scorecards and commercial terms.
-
Stress-test scenarios: Model upside and downside cases for supply shocks, such as heatwaves or irrigation restrictions, and embed contingency plans — alternate sourcing corridors, safety stocks, and short-run process flexibility in processing facilities.
How PW Consulting partners with executive teams
-
Customizable deliverables: From downloadable financial models to actionable M&A target lists, we tailor outputs to board-level decision cycles and operational implementation teams.
-
Implementation support: Beyond strategy, we provide hands-on project management for supplier transitions, joint-venture negotiations, and capital allocation frameworks for orchard modernization.
-
Scenario war-gaming: Our workshops help leadership teams align around risk tolerances, ramp schedules, and go-to-market prioritization informed by real-world trial outcomes and regional production dynamics.
Important note on granularity: This preview highlights the strategic contours and operational levers that matter in 2026. To preserve the integrity of proprietary segment models and to support client-grade decisioning, granular regional and application-level splits, and unit-price tables are intentionally reserved for the full report and our dataset package. For teams ready to convert insight into investment or operational action, the full PW Consulting Pomegranate Market suite provides the complete segment-level intelligence, raw data exports, and bespoke scenario runs required for transaction-grade analysis.
To engage our team for a briefing or to request the full report and modeling toolkit, please contact PW Consulting’s industry practice. Our consultants will walk your executive team through the data, validate scenarios against your portfolio, and co-design the 12–36 month roadmap that captures the most value from the pomegranate opportunity.
For detailed analysis of this topic, please visit the official page: Pomegranate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laminate Flooring Market to Reach USD 2,691M by 2032 (6.98% CAGR)
By PW Consulting, 2026-07-09
Laminate Flooring Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our Laminate Flooring Market research—designed to equip executive teams, investors, product strategists and channel leaders with the context and judgement required for high-stakes decisions in 2026. This briefing synthesizes macro trajectory, structural dynamics, competitive posture, and the practical implications you must weigh this year. The full intelligence package—containing granular regional and application splits, supplier-level price models, and transaction-ready M&A targets—is available in the complete report and is intentionally withheld here to preserve the “trailer” value of this preview.
Laminate Flooring Market
Market Trajectory and What It Means for 2026 Planning
The laminate flooring market is emerging from a period of steady recovery and structural upgrade. Our compiled market series (base year 2025) shows the industry scaling from an estimated USD 1.30 billion in 2020 to USD 1.70 billion in 2025, then projecting to approximately USD 2.69 billion by 2032—a compound annual growth rate of roughly 6.98% across the forecast window. This growth reflects a confluence of demand-side substitution (hybrid and waterproof laminates displacing legacy surface options), product-performance improvements, and a renewed appetite from renovation and commercial retrofit programs.
Laminate Flooring Market
For 2026 specifically, two immediate planning priorities arise: (1) bridge short-term volatility in raw-material and transport costs with flexible procurement contracts and strategic inventory positioning; and (2) accelerate product and channel moves that capture growing demand pockets for durable, low-emission, and water-resistant laminates. Firms that treat 2026 as a tactical inflection—rather than a normal growth year—will secure both margin resilience and share gains in the medium term.
Laminate Flooring Market
Key Market Dynamics: Supply Chain, Regulation, and Materials
-
Input volatility and substitution pressure. Melamine-formaldehyde resins remain the primary surface binder in high-pressure laminate layers—delivering scratch and stain resistance that underpins product claims. However, melamine pricing demonstrated pronounced volatility in 2024 due to upstream ammonia and CO2 cost swings. Procurement teams should implement hedging mechanisms and supplier diversification to avoid margin erosion.
-
Regulatory and compliance gatekeepers. Emissions regulation is a material commercial constraint. Laminate products intended for North American and EU channels must meet stringent formaldehyde emission standards (including TSCA Title VI and regional equivalents) and applicable EN norms. Compliance is no longer optional; it is a competitive filter that accelerates the premiumization of certified, low-emission ranges.
-
Sustainability and traceability as commercial currency. Substrate cores increasingly rely on wood fibreboards sourced from sustainably managed forests. Buyers and specification teams in retrofit and new-build projects prize transparent chain-of-custody and quantified lifecycle claims—areas where early movers can command premium placement in specification-led channels.
Competitive Landscape: Strategic Postures to Watch
The market blends global platform players and regional innovators. Leading manufacturers are converging around several distinct product and go-to-market themes: waterproof/robust collections, advanced locking systems, sustainability credentials, and circular-economy positioning. Our research profiles key players and their strategic offers—here are the competitive vectors that matter to 2026 strategy:
-
Performance-led differentiation. Players such as Mohawk Industries and Shaw Industries emphasize waterproof laminate ranges with realistic wood visuals and advanced locking systems. These product platforms target both residential renovation and commercial light-retrofit demand where durability and quick installation reduce total project cost.
-
Premiumization through low-emission and health claims. Established brands (e.g., Armstrong Flooring) and specialist lines are leveraging low-VOC, low-emission performance to win institutional and specification-driven business—particularly where regulatory compliance is a procurement condition.
-
Hybrid and protective technologies at the consumer edge. Brands such as Mannington Mills and Pergo are doubling down on kid- and pet-friendly technologies, spill defense, and wet-protect systems—features that reduce the lifetime cost of ownership for end consumers and increase aftermarket stickiness.
-
Scale + sustainability play. European manufacturers (including Kronospan, Swiss Krono Group, Beaulieu and Tarkett) are integrating sustainable feedstocks, circular-economy practices, and embedded eco-resins into their propositions. Swiss Krono’s moves on Opti Wood water resistance and textured ranges exemplify product innovation married to environmental claims.
These strategic patterns create clear implications: channel partners must re-evaluate stocking strategies against differentiated SKUs; manufacturers should prioritize modular platforms that can be rapidly configured for either a waterproof premium line or a lower-cost core range; and procurement/operations teams will find advantage in closer supplier collaboration around shared cost-reduction and certification roadmaps.
Recent Industry Signals — What They Reveal
-
Egger Group’s relaunch of PVC-free, design-forward laminate programs signals a deliberate pivot toward tariff-sensitive sourcing and product quality differentiation in response to global trade frictions.
-
Trade-show activity in early 2026—highlighted by product showcases from HRFloor at TISE and the breadth of exhibitors at the NWFA Wood Flooring Expo—indicates manufacturers are investing in tangible, install-centric innovations (core tech, mineral cores, click systems) to support channel trials.
-
Association-level guidance (EPLF’s 2026 trends) underscores the mainstreaming of natural textures and sustainable design—an immediate cue for assortment managers and creative leads in marketing to align ranges and communication plans.
-
Incremental product upgrades, like Swiss Krono’s announced Global Range improvements for extended water resistance, are tactical responses to a market that increasingly values real-world performance over purely aesthetic claims.
What Our Report Contains (Operationally Useful Elements)
The full PW Consulting market study provides a practical toolkit for 2026 execution. Key deliverables include:
-
Validated historical and forecast market sizing (2020–2032) with scenario-based sensitivities tied to macroeconomic and raw-material inputs.
-
Detailed go-to-market playbooks for manufacturers, distributors and retailers focused on assortment optimization, channel economics, and SKU rationalization.
-
Supply-chain heatmaps and cost-to-serve models that quantify exposure to melamine and fibreboard price swings, plus suggested hedging and near-shoring levers.
-
Regulatory compliance matrices and an actionable roadmap to secure market access across major jurisdictions—including testing, labelling, and chain-of-custody steps.
-
Competitive benchmarking with strategic profiles, capability assessments, and a prioritized list of M&A and partnership targets—structured for immediate diligence.
-
Retail and specification channel insights, including conversion metrics, installation labor trends, and pricing elasticity models to guide promotional and premium-strategy decisions.
To preserve the value of this preview and guide targeted follow-up, the report intentionally omits granular regional and application splits in this public summary. Those detailed allocations, supplier cost curves, and transaction-level valuations are included in the secure report package.
Strategic Imperatives for 2026 — Five Actions to Prioritize
-
Lock strategic raw-material arrangements. Negotiate multi-year frameworks with flexible indexation clauses for melamine and fibreboard supply; consider securing limited-capacity guarantees for production-critical inputs.
-
Accelerate certification-led product migration. Fast-track low-emission and EN-compliant SKUs for markets where regulation is a market entry gate. Certification reduces friction in specification-driven sales and supports premium positioning.
-
Segment your portfolio by total-cost propositions. Configure lines into “durability-first” waterproof ranges and “value” lines; use installers and commercial channel pilots to validate differential pricing.
-
Operationalize sustainability claims. Invest in chain-of-custody documentation and lifecycle disclosure now—buyers are already demanding transparency and specifications are tightening.
-
Prepare tactical M&A and partnership plays. Prioritize bolt-ons that add proprietary surface technologies, mineral-core capabilities, or regional logistics footprints that shorten time-to-market and margin recovery.
Closing: Why This Matters Now
2026 presents a window where product innovation, supply-chain strategy, and regulation intersect to reshape competitive advantage. The market is large and expanding—our modeling points to meaningful upside through 2032—but the path to capture that upside requires precise, actionable moves in procurement, certification, and product architecture. PW Consulting’s full Laminate Flooring Market study provides the granular evidence base and executable playbooks executives need to convert market momentum into sustainable share and margin gains. For teams preparing 2026 budgets, strategic roadmaps, or acquisition screens, this is the moment to act with data-backed conviction.
Contact PW Consulting to access the comprehensive report package and the dataset that supports the scenarios summarized here. The full deliverable includes the withheld segmentation matrices, supplier cost models, and a curated shortlist of strategic targets prepared for immediate diligence.
For detailed analysis of this topic, please visit the official page: Laminate Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Astronomical Telescope Market to reach USD 730.94M by 2032 at 7.15% CAGR
By PW Consulting, 2026-07-09
Astronomical Telescope Market 2026 — Strategic Imperatives for Executive Decision-Making
Executive snapshot
Between 2020 and 2025 the global astronomical telescope market demonstrated steady expansion—from a base under USD 325 million to an estimated USD 451 million in 2025—reflecting healthy demand across hobbyist, educational and research segments. Our forward-looking model, which uses 2025 as the base year, projects continued momentum into the next decade: the market is expected to expand at a compound annual growth rate (CAGR) of roughly 7.15% through the 2026–2032 forecast window, reaching a materially larger market size by 2032. For 2026 strategic planning, that growth profile translates into concrete choices around product investment, channel coverage, and capital allocation that will determine who captures the higher-margin growth pockets and who competes on commoditized volume.
Astronomical Telescope Market
Why this report matters for 2026 corporate decisions
-
Time-sensitive portfolio prioritization — The market is bifurcating: the premium optical/precision manufacturing tier remains differentiated by materials, tolerances and service, while a parallel wave of smart, app-driven instruments is expanding accessible TAM among newcomers and educators. Companies must decide whether to double down on precision optics, accelerate smart-product roadmaps, or pursue a two-pronged strategy.
Astronomical Telescope Market -
Route-to-market optimization — Channel economics are shifting as consumer behaviours move toward app-integrated purchasing and remote-observation services. Distributor and retail strategies that were effective five years ago require re-evaluation against direct-to-consumer smart bundles and recurring-service models.
Astronomical Telescope Market -
Cost and supply resilience — Precision optics and specialized labor create persistent cost asymmetries between premium and entry segments. Sourcing, vertical integration, and contract manufacturing choices made in 2026 will materially affect margin profiles across the forecast interval.
-
M&A and partnership timing — With market concentration moderate (our CR3 and CR5 benchmarks indicate opportunity for consolidation but no dominant gatekeepers), 2026 is an attractive window to acquire complementary optics houses, mount specialists, or software/IP-rich smart-telescope startups to accelerate capability at lower organic cost.
Report contents — practical outputs for immediate use
PW Consulting’s Astronomical Telescope Market report is built as an executable decision toolkit for 2026 leadership cycles. It combines strategic insight with actionable deliverables:
-
Integrated market model (historical 2020–2025 and forecast 2026–2032) — driver-based scenario runs that allow you to stress-test pricing, channel mix and product introductions against the base CAGR and alternative demand trajectories.
-
Commercial playbooks — go-to-market templates for Premium Optics, Mid‑Range Imaging, and Smart Telescope segments with suggested KPIs, margin targets and launch timelines tuned to 12–24 month planning horizons.
-
Competitive benchmarking — a structured scorecard covering product portfolios, core technologies (optics, mounts, sensors), dealer networks and intellectual property positioning for leading vendors.
-
Technology and product roadmap — evaluation of near-term innovations (smart telescopes, sensor integration, mount automation) together with R&D priority matrices.
-
Sourcing & manufacturing playbook — cost-to-serve models, supplier risk heatmaps and recommendations for reshoring, co‑manufacturing or long‑term supply contracts.
-
Investment and M&A screen — a shortlist of capability adjacencies, synergies and valuation levers, plus modeled return scenarios against the market growth path.
-
Regulatory and standards guidance — readiness checklists aligned with ongoing ISO optical-system standardization and practical steps to reduce product certification friction for target markets.
Note: this article is an analytical preview. The full report includes granular segmentation tables, regional and application splits, and downloadable financial models available on the source page.
Competitive landscape — what incumbents and challengers are doing
The market structure is competitive but not concentrated to the point of winner-take-all dynamics. Established optics houses and newcomer smart-device builders are pursuing different value plays:
-
Celestron (Torrance, CA) — strategy centered on combining computerized mounts (NexStar), premium Schmidt‑Cassegrain optics (EdgeHD) and integrated home observatory experiences (Origin). Their breadth across hobbyist and imaging segments makes them a useful benchmark for companies seeking to balance volume products with higher-margin automated systems.
-
Sky-Watcher (Taichung, Taiwan) — strong in serious amateur optics and mounts (Esprit refractors, Skymax Maksutov, EQ mounts). Their engineering-led, mid-to-high range positioning highlights the importance of mount stability and optical performance for imaging customers.
-
Takahashi (Saitama, Japan) — premium optics play with fluorite apochromats and astrographs focused on optical performance. Their pricing and reputation underscore the ongoing premiumization opportunity for firms able to deliver superior optical materials and manufacturing precision.
-
Explore Scientific (Germany) — diversified portfolio across Dobsonians, refractors and new mount/eyepiece lines (Sidara series), indicating product ecosystem strategies—optics plus high‑performance accessories—that increase customer lifetime value.
-
Vixen & Astro‑Physics (Japan / USA) — niche technical excellence in mounts and refractors respectively; examples of how high engineering content supports sustainable premium margins.
-
Bosma, Apertura and Chinese OEMs — competitive pressure on cost and rapid product iteration. Their presence accelerates volume-market adoption but also compresses prices at entry tiers.
-
Vaonis & smart-telescope entrants — represent the fastest route-to-new-users via app‑centric, AI‑assisted observation. These products expand addressable demand among education and casual observers but require software and service competence beyond optics.
Recent product activity (new mounts, fluorite refractors, and updated smart devices) shows incumbents are both defending legacy strengths and experimenting with software/hardware convergence. Companies that can integrate optics excellence with robust software ecosystems will be advantaged.
Technology, standards and cost dynamics shaping 2026 choices
-
Smart & sensor convergence — improved compact sensors and on-device imaging pipelines have lowered barriers for deep-sky results from smaller apertures; software (alignment, stacking, AI) is a key differentiator.
-
Precision optics and materials — specialty glass, fluorite elements and manufacturing tolerances remain the core moat for premium vendors, but sourcing complexity and labor intensity increase unit cost, necessitating targeted price architecture.
-
Mounts and infra requirements — stability and tracking precision are gatekeepers for serious imaging; for ground-based installations, dark‑sky availability and installation costs are a persistent structural consideration for institutional customers.
-
Standards & regulation — ISO/TC 172/SC 4 is active in defining terminology and test methods for optical systems; firms should plan for compliance and take part in standards discussions (noting the committee’s upcoming timetable) to shape technical norms and ease market access.
Operational risks and mitigation levers
-
Raw-material and labor inflation — premium optics will remain exposed; mitigate via strategic supplier agreements, selective vertical integration, and product modularization to reduce bespoke tooling.
-
Channel displacement — anticipate shifting margins as DTC smart bundles and software subscriptions grow; protect margins by offering differentiated services (cloud processing, education packages, warranty & maintenance plans).
-
Competitive price pressure — defend margins through value-added accessories and branded ecosystems rather than pure price competition in entry tiers.
-
Regulatory uncertainty — maintain a standards roadmap and early compliance testing to reduce time-to-market risk for new optical platforms.
Recommendations for leadership in 2026
-
Define a clear product ambition: choose between premium optical leadership, smart‑device/platform focus, or a segmented-dual strategy with autonomous R&D tracks and dedicated go-to-market teams.
-
Invest in software and service capabilities—companies that combine optics with reliable imaging pipelines and subscription services will enjoy superior LTV economics.
-
Prioritize supply resilience for critical glass and precision components now—lock in multi-year agreements or equity in strategic suppliers to manage cost volatility.
-
Use M&A and partnerships to fill capability gaps (mounts, sensors, AI/processing) rather than attempting all capabilities organically in a short window.
-
Engage in standards work and certification pathways as part of product planning to minimize regulatory tail risk and to help shape favorable test methods.
How to use the full PW Consulting study
This article highlights the strategic contours that corporate executives and investors must weigh in 2026. The full Astronomical Telescope Market report contains the supporting datasets, region and application splits, detailed competitor scorecards, downloadable Excel forecast models and scenario dashboards that permit line-by-line decision analysis. If your 2026 planning cycle requires prioritized product launch calendars, M&A screens, or operational redesigns aligned with the projected market trajectory, the report provides the data and playbooks you will need to act decisively.
For firms that want an accelerated path from insight to execution, PW Consulting offers tailored sprints—market-entry roadmaps, commercial due diligence and integration playbooks—that convert the report’s strategic direction into executable 12–18 month plans.
For detailed analysis of this topic, please visit the official page: Astronomical Telescope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Solar Control Window Films Market to Reach USD 1,259.4M by 2032 (CAGR 7.85%)
By PW Consulting, 2026-07-09
Solar Control Window Films Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As organizations prepare their 2026 strategic roadmaps, the solar control window films market presents a blend of steady demand growth, material- and regulation-driven disruption, and concentrated competitive dynamics that together create near-term opportunity windows and executional risks. This preview of PW Consulting’s full market study synthesizes the data-driven view you need to shape procurement, R&D, commercial, and M&A decisions — while reserving the granular segmentation and scenario matrices for subscribers who access the full report.
Solar Control Window Films Market
Why this study matters for 2026 decision-making
-
Concrete growth trajectory. The market has expanded materially during the 2020–2025 period and, using 2025 as our base year, is projected forward under an expected CAGR of 7.85% across the forecast horizon. This trajectory transforms program-level economics: product portfolios that were marginal in 2023 become strategic revenue engines by the end of this decade.
Solar Control Window Films Market -
Policy and input-cost volatility require integrated planning. New regulatory constraints on adhesives and refrigerants, alongside ongoing movements in PET and specialty nano-ceramic inputs, mean that product design, sourcing, and pricing strategies must be aligned, not siloed.
Solar Control Window Films Market -
Consolidation is actively reshaping supplier leverage. Industry concentration metrics point to a mid-to-high single digit share for top players collectively, which affects supplier negotiation posture, OEM sourcing decisions, and the attractiveness of bolt-on acquisitions.
Market snapshot (what the numbers say)
Using 2025 as the reporting baseline, the solar control window films market is established and growing. Historical performance through 2020–2025 shows steady recovery and expansion as commercial construction and automotive retrofit activity regained momentum. Our projection, anchored to a 7.85% compound annual growth rate, models multiple demand inflection points — from sustainability-driven renovation cycles to automotive adoption of spectrally selective films — that jointly underpin attractive mid-term returns for well-positioned participants.
For executives considering capital allocation in 2026, two implications follow directly: first, investment in higher-value, differentiated film technologies (for example, ceramic and spectrally selective solutions) compounds return as volume grows; second, supply-chain and raw-material exposures become earnings-critical and should be managed proactively through contracting, vertical partnerships, or selective vertical integration.
What the full report contains (practical, executable insights)
-
Transparent sizing and forecast methodology — full roll-forward from historical shipments to revenue, with scenario sensitivity to raw material volatility, tariff shocks, and demand elasticity under differing energy- efficiency incentive regimes.
-
Price and margin roadmap — modeled ASP (average selling price) curves under alternative competitive intensity scenarios, with breakpoint analysis identifying when premium ceramic or metal-free films become margin accretive.
-
Supply-chain stress tests — supplier concentration maps, lead-time overlays, and multi-sourcing blueprints for polymer substrates, nano-ceramic coatings, and pressure-sensitive adhesive chemistries.
-
Regulatory impact matrix — quantified exposure to ISO 9050 performance thresholds, EU REACH and F‑Gas constraints, and key trade measures (including US import tariff implications) that change product compliance costs by use-case.
-
Commercial playbooks — GTM (go-to-market) frameworks for OEM partnerships, retrofit channel strategies, and B2B energy-service bundling opportunities that translate film performance into building energy savings and occupant comfort value propositions.
-
M&A and partnership scorecards — candidate lists, valuation multiple ranges, and integration risk checklists calibrated to the market concentration and the most likely roll-up pathways.
-
Competitive benchmarking — capabilities heatmaps across R&D, manufacturing footprint, sustainability credentials, channel reach, and IP ownership, enabling rapid gap analysis and capability-building roadmaps.
Competitive landscape — who matters and why
The market is anchored by a set of global incumbents with distinct competitive moats and tactical priorities. Our analysis of these players highlights how competitive advantage is formed and where executive focus can generate outsized returns.
-
3M Company (Saint Paul, Minnesota, USA): 3M’s multi-layer nano-technology and ceramic-based architectural films are purpose-built for long-term performance in heat rejection and UV protection. Their R&D intensity and direct access to advanced coating platforms make them a benchmark for premium solutions.
-
Eastman Chemical Company (Kingsport, Tennessee, USA): Eastman’s LLumar and Vista brands exemplify scale in both automotive and architectural channels. Their capability to blend brand equity with distribution depth is a reference model for channel-driven growth.
-
Saint-Gobain Performance Plastics (Courbevoie, France): Under the Solar Gard brand, their focus on advanced coatings for energy efficiency underscores how architecturally oriented product differentiation can command a premium with commercial property owners.
-
Avery Dennison Corporation (Glendora, California, USA): The Encore™ nanoceramic portfolio and metal-free constructions show how material innovation can solve the classic trade-off between heat rejection and visible light transmission, unlocking new specification wins.
-
Lintec Corporation (Tokyo, Japan): Recent product launches that leverage recycled PET demonstrate a distinct sustainability play — delivering performance while addressing corporates’ Scope 3 reporting and circular-materials commitments.
-
Madico Inc. (Norcross, Georgia, USA): A full-spectrum portfolio in architectural and automotive films, and an active consolidation posture, make this player one to watch for roll-up dynamics and channel consolidation.
-
Johnson Window Films (USA): Known for energy-efficient product lines such as the NightVision Series, their focus on commercial and residential markets positions them well in retrofit-driven demand.
-
Garware Hi-Tech Films Limited (Mumbai, India): As a major regional competitor, Garware’s polyester-based offerings and distribution reach in emerging markets demonstrate how cost-performance balance drives adoption outside mature markets.
Recent developments that change the playbook
-
Lintec’s July 2025 launch of a solar control film made entirely from 100% recycled PET resin is not just a product announcement — it signals how sustainability claims are evolving from marketing statements to manufacturing differentiators. For corporate procurement teams and sustainability officers, this raises the bar on supplier qualification criteria.
-
In February 2026, Madico Inc.’s definitive agreement to acquire Johnson Laminating & Coating and Johnson Window Films marks a material consolidation step. Expect acceleration in manufacturing integration, channel unification, and potential short-term SKU rationalization as scale economics are realized.
Supply-side and regulatory dynamics to factor into 2026 plans
-
Raw-material volatility remains a primary profit-ability driver. PET resin pricing has experienced upward pressure in certain markets due to tariff activity and supply tightness; conversely, short-term moves in polyester and nano-ceramic inputs have shown modest downward shifts, concentrated in Asia Pacific. Executives must therefore model both directional movements and regional supply concentration when negotiating long-term contracts or planning inventory hedges.
-
Regulatory compliance is increasingly granular. ISO 9050 measurement standards directly affect product positioning for energy-performance claims; REACH and EU F‑Gas frameworks are pushing reformulation away from certain adhesive chemistries toward lower-GWP alternatives. These shifts will change development timelines and compliance costs, particularly for firms selling into the European market.
-
Trade measures matter operationally. Import measures and tariffs, including specific US measures based on product subheadings and origin, can alter landed cost by material percentages — a non-trivial factor when evaluating nearshore vs. offshore manufacturing or the economics of regional distribution hubs.
Strategic implications and recommended moves for 2026
-
Procurement and supply resilience: move beyond single-supplier contracting. Implement staggered multi-year contracts with volume collars, and consider strategic partnerships with recycled-PET producers to lock in circularity claims at predictable cost.
-
Product portfolio rationalization: prioritize differentiation. Invest selectively in ceramic, spectrally selective, and metal-free technologies where premium pricing and specification stickiness justify R&D spend and tooling amortization.
-
M&A and alliance playbook: act on consolidation pockets. With industry concentration indicating meaningful share for top players, 2026 is an optimal year to pursue bolt-on acquisitions that add manufacturing capacity, distribution channels, or sustainability credentials — particularly in regions where regulatory complexity raises barriers to entry.
-
Compliance-forward innovation: embed regulatory foresight into product roadmaps. Anticipate ISO and chemical-compliance thresholds in product development gating criteria to avoid retrofit costs and market access delays.
-
Commercial channel optimization: offer energy-as-a-service or retrofit bundles. Translate film performance into measurable energy and occupant-comfort KPIs that facility managers can finance against, accelerating adoption in commercial real estate.
Conclusion — what leaders should prioritize in 2026
The solar control window films market in 2026 is not a “more of the same” story. It is a maturing market where product differentiation, material and regulatory strategy, and selective consolidation will determine winners. PW Consulting’s full study provides the tactical detail — price curves, supplier scorecards, heat-maps of regulatory exposure, and deal-screen frameworks — that executives need to convert market growth into durable competitive advantage. This preview outlines the strategic inflection points; the full analysis equips teams to operationalize them.
To access the complete forecast models, segmentation-level analytics, and executable playbooks that underpin these insights, contact PW Consulting or visit our report page for the full Solar Control Window Films Market study.
For detailed analysis of this topic, please visit the official page: Solar Control Window Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mobile Patient Lifts Market to Reach USD 557.0 Million by 2032 at 8.55% CAGR | PW Consulting
By PW Consulting, 2026-07-09
Mobile Patient Lifts Market — 2026 Strategic Outlook and Executive Primer
Executive snapshot
As healthcare systems accelerate investments in safe patient handling, the global mobile patient lifts market has moved from a niche clinical support category toward a strategic product family for hospitals, long‑term care operators and home‑care OEMs. Using 2025 as the base year, our analysis traces historical performance from 2020 and projects the market across a 2026–2032 forecast window. The market grew from roughly USD 210 Million in 2020 to approximately USD 315 Million in 2025. Under our central scenario the market continues to expand at a compound annual growth rate of 8.55% through 2032, with total demand approaching the mid‑hundreds of millions (USD) by the end of the forecast period.
Mobile Patient Lifts Market
Why this study matters for 2026 corporate decisions
-
Timing of product investment: Buyers and OEMs must decide in 2026 whether to accelerate development of next‑generation mobile lifts (lighter frames, integrated positioning, modular slings) or to pursue incremental refreshes. Our report quantifies trajectory under multiple adoption scenarios and links those to capex and time‑to‑market tradeoffs.
Mobile Patient Lifts Market -
Procurement & reimbursement alignment: Durable medical equipment rules and associated HCPCS codes materially affect hospital purchasing economics and home‑use reimbursement. The difference between being coded correctly (and supported by clinical evidence) versus being “unclassified” can change procurement outcomes. The study maps reimbursement pathways and payer behaviors across major markets.
Mobile Patient Lifts Market -
Regulatory and clinical risk management: FDA safety expectations, operator training obligations and MAUDE reporting dynamics are not peripheral—they determine recall risk and service costs. Our analysis translates these compliance factors into expected warranty and field action liabilities.
-
Service and aftermarket economics: As lifts become a platform for recurring revenue (slings, batteries, service contracts), the profit pool shifts. The report models service attach rates and scenarios for capturing higher lifecycle value.
What the report contains (practical, deployable modules)
-
Market sizing and multi‑scenario forecasts (2026–2032) with sensitivity testing tied to reimbursement and hospital capital spending cycles.
-
Buyer archetypes and procurement playbooks for hospitals, nursing homes and home‑care channels—KPIs, decision criteria and TCO templates to inform sales strategy and contracting.
-
Regulatory and reimbursement mapping: code applicability, documentation pathways, and an action checklist for evidence generation to secure favorable billing.
-
Competitive benchmarking: product feature matrices, price band analysis, service model comparisons and go‑to‑market velocity scoring for leading incumbents and emerging challengers.
-
Supply‑chain and manufacturing risk maps—critical material exposure (aluminum/steel frames, antimicrobial coatings), supplier concentration, and options for near‑sourcing versus global procurement.
-
M&A and partnership playbooks: candidate profiles, valuation comparables and integration risk checklists tuned to the sector’s current fragmentation dynamics.
Competitive landscape — who matters now
The market is commercially active but not dominated by a single conglomerate; incumbent device specialists and regional players compete across product ergonomics, sling ecosystems and service capabilities. Key commercial names analyzed in the study include:
-
Hillrom (Chicago, IL) — broad mobile lift portfolio for hospitals and home care, including heavyweight and compact models designed for institutional transfer workflows.
-
Arjo (Stockholm) — strong presence in ceiling and mobile systems; recent product evolution emphasizes maneuverability and single‑operator handling.
-
Handicare (Belgium) — focused on portable and foldable designs targeting home and institutional use where storage and transportability are priorities.
-
Baxter International (Chicago, IL) — distributes and supports established mobile lift platforms through channel partnerships.
-
Drive Medical (Port Washington, NY) — commodity and value‑focused portfolio with breadth across acute, long‑term and home segments.
-
etac (Sweden), Vancare (USA), Bestcare (USA), Winncare (France), and Invacare (Elyria, OH) — each brings niche strengths in portability, bariatric capacity, integrated ceiling/mobile solutions or cost‑efficient aftermarket support.
Across the competitive field we observe deliberate product differentiation: ceiling lifts versus mobile floor lifts; bariatric and full‑body capability versus lightweight transport models; and the emergence of service‑first propositions that bundle slings, preventative maintenance and digital monitoring.
Notable industry moves (recent timeline)
-
Arjo launched an upgraded mobile floor lift emphasizing maneuverability and single‑operator ergonomics (April 2025).
-
Multiple suppliers showcased portable solutions and Hoyer‑style lifts at regional medical expositions through 2025, signaling continued product marketing investment.
-
Suppliers introduced eco‑conscious slings and materials in 2025–2026, reflecting both procurement sustainability demands and cost pressure on disposable inputs.
Market dynamics and risk factors
Five dynamics will shape executive choices in 2026:
-
Reimbursement regimes and coding: Mobile lifts are routinely covered under durable medical equipment provisions and mapped to established HCPCS codes. Securing clear billing pathways needs product labeling and clinical documentation aligned with payer rules.
-
Regulatory scrutiny and post‑market obligations: Compliance with device safety standards, sling compatibility requirements and operator training guidance is non‑negotiable. Adverse event reporting systems require robust field surveillance and rapid corrective‑action capability.
-
Materials and manufacturing cost pressure: Aluminum and steel remain primary structural materials; advanced surface treatments (e.g., antimicrobial coatings) add differentiation and cost. Firms must balance material upgrade benefits versus margin dilution.
-
Labor and workflow trends: Features that enable single‑caregiver operation—dynamic positioning systems, quick‑connect spreader bars—reduce facility labor costs and materially affect value propositions to purchasers.
-
Aftermarket and service economics: Warranty exposure, sling replacement cycles and maintenance are rising contributors to total lifecycle cost and to vendor margin pools.
Strategic imperatives for 2026
-
Prioritize evidence‑backed product claims. Invest selectively in clinical trials or real‑world use studies that demonstrate reduced caregiver injury, improved transfer times and reimbursement support.
-
Design for the service lifecycle. Standardize modular components and remote diagnostics so service teams can reduce mean time to repair and increase service attach rates.
-
Map reimbursement pathways early. Ensure product documentation, training packages and coding justifications are ready before market entry to accelerate procurement decisions.
-
Differentiate through ecosystems. Winning offers will bundle slings, training, fleet management and predictable maintenance to lock in recurring revenue.
-
Use M&A strategically. Target bolt‑on acquisitions that add complementary sling systems, regional service footprints or ceiling‑lift capabilities rather than broad horizontal deals.
-
Hedge material risk. Establish secondary suppliers for critical aluminum/steel components and evaluate selective near‑shoring to shorten lead times for high‑velocity markets.
How PW Consulting’s study accelerates execution
This study is designed as an operational playbook for C‑suite executives and business unit leaders preparing 2026 budgets and three‑year roadmaps. It combines market sizing and scenario forecasts with procurement templates, competitor scorecards and a regulatory‑reimbursement action matrix that teams can operationalize immediately. Importantly, while this primer outlines the strategic direction and evidence base, detailed segment tables, price‑band modelling, regional channel economics and vendor‑level scorecards are retained in the full report to preserve commercial value for subscribers.
Next steps
For executives preparing product strategy, procurement bids or M&A diligence in 2026, the full PW Consulting Mobile Patient Lifts Market report provides the granular inputs and actionable templates necessary to de‑risk decisions and accelerate value capture. Contact our industry team to arrange a briefing or to obtain the complete dataset, segment tables and customized scenario runs tailored to your market entry or investment thesis.
For detailed analysis of this topic, please visit the official page: Mobile Patient Lifts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ice Cream Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, this preview distills the strategic levers that will matter for executive teams in 2026. Grounded in our base-year assessment (2025) and a forward-looking forecast through 2032, the analysis synthesizes macro market expansion, competitive positioning, cost dynamics, and regulatory inflection points to help you prioritize investments, M&A, and commercial actions. Note: this document intentionally demonstrates analytical depth while withholding the detailed sub-segmentation tables and regional/application breakdowns included in the full report — visit our source page for the complete dataset and models.
Ice Cream Market
Market trajectory at a glance
After a sustained recovery and expansion in the early 2020s, the global ice cream market reached an estimated USD 88.68 Million (base year 2025). Over 2020–2025 the industry expanded from USD 62.15 Million to USD 88.68 Million, reflecting a period of product innovation, channel evolution, and renewed consumer demand. Our forecast projects the market to grow to approximately USD 94.49 Million in 2026 and to USD 144.56 Million by 2032, implying a projected compound annual growth rate (CAGR) of 7.23% across the 2026–2032 forecast window.
Ice Cream Market
These headline numbers point to two strategic realities: the market is large and expanding at a rate that justifies near-term investment, and the growth pathway is uneven — concentrated in pockets of premiumization, health-oriented reformulation, and channel-specific innovation. The implication for 2026 decision-makers is clear: scale alone will not secure sustained outperformance; purposeful portfolio, cost and channel strategies will.
Ice Cream Market
Why this study matters for 2026 decisions
- Capital allocation and M&A prioritization. The market’s mid-term growth trajectory supports selective M&A and capex moves to secure capacity, proprietary formulations, and geographic footholds. Given demonstrated concentration at the top of the market, mid-sized targets can unlock rapid incremental share and margin expansion.
- Portfolio and reformulation timing. Regulatory changes and shifting health preferences are compressing product lifecycles. Firms that reprioritize SKUs and accelerate reformulations can protect shelf placement and margin.
- Commercial model redesign. Channels that dominated historically are being reconfigured by direct-to-consumer (D2C), foodservice partnerships, and retail convenience plays — each requires distinct pricing, packaging, and service economics.
- Supply chain resilience. Volatility in raw material prices and labor availability necessitates proactive sourcing, hedging, and manufacturing footprint decisions to preserve gross margin in 2026 and beyond.
What the full report delivers (practical, actionable content)
- Validated market sizing and a transparent methodology linking historical volumes (2020–2025) to forecast drivers (2026–2032).
- Scenario-based revenue and margin models (base, upside, downside) with sensitivity levers for raw material cost, pricing elasticity, and regulatory impacts.
- Go-to-market playbooks for retail, convenience, foodservice and D2C channels with pricing ladders, promotional elasticity matrices, and shelf-space optimization heuristics.
- SKU rationalization frameworks that identify candidates for reformulation, premiumization, or discontinuation based on margin-to-space economics.
- Supplier and input cost risk registry, including forward procurement strategies and contract design templates to mitigate milk and commodity volatility.
- Regulatory compliance checklist and reformulation roadmaps aligned to the latest labeling requirements and product standards.
- M&A playbook: target screening criteria, synergy assessment templates, and integration scorecards tailored to ice cream industry dynamics.
- Operational benchmarks and a KPI dashboard for manufacturing, logistics, and commercial performance.
Dynamics shaping 2026 strategy
Three dynamics will shape executive choices in 2026:
- Regulatory inflection. Mandatory labeling rules that took effect in January 2026 (notably 'High in' declarations for sugar/calories on packaged frozen desserts) are already prompting widespread reformulation. Companies face a trade-off: invest in lower-sugar formulations and potential margin pressure, or preserve recipes and adjust positioning (e.g., indulgence vs. better-for-you ranges).
- Raw material and production constraints. Supply-side shifts remain salient. Historical data shows a contraction in some production metrics over the long term, and input costs remain elevated — wholesale milk prices rose materially in the 2023 cycle, and feed and labor pressures persist into 2025–2026. These dynamics amplify the value of procurement sophistication and manufacturing flexibility.
- Channel and consumer evolution. Premium and experiential formats continue to attract discretionary spend, while convenience and single-serve innovations grow in relevance for on-the-go consumption. Concurrently, health and sustainability credentials influence shelf choice and willingness to pay.
Competitive landscape — implications for strategy
The industry exhibits meaningful concentration among global incumbents (our analysis shows a top-three concentration that captures a dominant share of the market and a top-five concentration even higher). This concentration creates an environment where scale unlocks negotiating leverage with retail partners, distribution reach, and investment in brand building; yet nimble challengers can win through product differentiation and local agility.
Key profiles and strategic takeaways:
- Unilever PLC (London) — Global brand scale and R&D muscle allow rapid rollout of premium innovation and broad distribution. Recent product launches underscore an ongoing push into premium limited editions and co-branded propositions; incumbents with diversified portfolios can absorb reformulation costs more readily.
- The Magnum Ice Cream Company (London) — Operates a broad international portfolio and leverages global manufacturing agreements to optimize cost and shelf prominence; brand-led premiumization remains a core strength.
- General Mills (Minneapolis) — With ownership of premium brands, the company balances national retail penetration with targeted channel efforts in convenience and foodservice.
- Blue Bell & Wells Enterprises (US-based) — Regional leaders with deep retail partnerships; their scale in certain domestic channels provides resilience but also exposes them to commodity swings.
- Nestlé S.A. (Vevey) — Global distribution networks and a multi-brand strategy enable portfolio optimization across price tiers and channels.
- Baskin-Robbins & Dairy Queen — Channel specialists that convert brand & retail experience into premium per-unit spend; strategic value lies in licensed footprints and co-branding opportunities.
- Amul (India cooperative) — Demonstrates how cooperative and local models can dominate cost-competitive domestic markets while supporting rapid scale-up of distribution.
- Straus Family Creamery — Niche organic positioning underscores the trade-offs of premium branding: strong margin potential but higher vulnerability to operational recalls and supply-chain disruptions (a voluntary recall in 2026 illustrates this risk).
Recent industry events reinforce these points: trade shows in early 2026 signaled robust buying intent (thousands of trade visitors and sizeable average order values), while product launches and recalls highlight the twin priorities of innovation speed and quality governance.
Priority actions for 2026
- Launch a ‘Reformulation Sprint.’ Rapidly identify high-risk SKUs under new labeling rules, calculate margin impacts, and prototype lower-sugar alternatives with prioritized manufacturing pilots.
- Negotiate medium-term supply contracts. Locking in input prices and diversifying milk sourcing (including alternative dairy ingredients) will protect gross margin as spot volatility persists.
- Rebalance portfolio toward high-margin channels. Use our channel profitability templates to reallocate commercial investment toward formats and routes-to-market that maximize ROI.
- Targeted M&A and partnerships. Focus on bolt-on acquisitions that extend premium offerings or add proprietary formulations; pursue JVs with regional distributors to accelerate market entry without heavy capex.
- Upgrade quality governance. Strengthen recall readiness and traceability systems to limit reputational and financial exposure.
- Invest in agile manufacturing. Flexible lines enable SKU proliferation with limited incremental fixed cost and reduce time-to-market for reformulated SKUs.
How PW Consulting can accelerate your 2026 agenda
Our full Ice Cream Market report includes the complete data tables, region and application breakdowns, and downloadable financial models used to generate the scenarios summarized here. For clients, PW Consulting offers tailored modules:
- Market-entry and growth roadmaps with financial modelling and execution timetables.
- M&A screening and diligence focused on synergy realization and integration risk mitigation.
- Commercial transformation: pricing architecture, trade promotion optimization, and assortment strategy.
- Operational resilience: sourcing optimization, contract design, and capex prioritization for agile manufacturing.
- Regulatory & reformulation playbook: ingredient substitution pathways, cost-to-reformulate analysis, and consumer acceptance testing protocols.
We designed this preview to identify the strategic inflection points you cannot afford to ignore in 2026. For the full intelligence — including region-by-region and application-level breakdowns, the complete competitive benchmarking matrix, and the financial models that underpin our forecast — please consult the complete PW Consulting Ice Cream Market report on our website or contact our advisory desk to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Ice Cream Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


