



Category: Healthy Lifestyle
PW Consulting: Basmati Rice Market to Grow at 7.0% CAGR, Reaching USD 315.1 Million by 2032
By PW Consulting, 2026-06-26
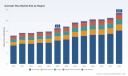
Basmati Rice Market 2026: Strategic Outlook and Decision-Grade Intelligence for Capital Allocation
The global Basmati rice market is transitioning from niche premium commodity to a structurally attractive category for value-driven investment. PW Consulting’s 2026 base assessment shows a market that reached USD 198.0 Million in 2025 and is projected to expand to USD 315.1 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.98% over the forecast window. This trajectory is underpinned by demand shifts, varietal innovation and margin re-composition across trade and branded channels — factors that make 2026 a pivotal year for strategic capital deployment.
Basmati Rice Market
Macro snapshot: what is moving the dial in 2026
The operating environment for aromatic rice is subject to several converging forces. Executives and investors must view these not as isolated trends but as interacting levers that determine supplier economics, margin pools and regulatory exposure.
- Rising aromatic imports and changing consumption patterns: fragrant rice varieties are capturing a larger share of import volumes in key markets, pushing buyers to re-evaluate sourcing and pricing strategies.
- Price volatility and global indices: FAO price signals continue to set the baseline for upstream raw-material negotiations, increasing the importance of flexible procurement frameworks.
- Genetic and varietal supply-side shifts: new aromatic varieties and public breeding programs are altering yield and premium dynamics, creating windows for origin diversification and quality arbitrage.
- Traceability, food-safety and recall risk: recent voluntary recalls highlight the reputational and P&L sensitivity to contamination events, reinforcing the need for end-to-end traceability.
- Commercial consolidation vs. fragmentation: while strong global brands exist, market concentration remains modest, preserving opportunities for targeted scale plays and route-to-market innovation.
Why 2026 is a decisive year for capital and strategic choices
Market momentum through 2026 places a premium on speed of execution. Firms that define sourcing architecture, lock design wins with retail and foodservice customers, and deploy operational technology will capture disproportionately high share of the upside as the market grows to USD 315.1 Million by 2032. Conversely, delayed action risks margin erosion from raw-material inflation, supply shocks, or regulatory-driven compliance costs.
- Short-term cost control: yield and input-cost volatility make tactical yield-improvement and procurement hedging immediate priorities.
- Mid-term differentiation: varietal portfolios and verified sustainability credentials are the primary determinants of pricing power in premium channels.
- Long-term resilience: traceable, digitally-enabled supply chains reduce recall risk and support premiumization strategies.
What PW Consulting’s report delivers — actionable tools, not just charts
The report is built as a practitioner’s toolkit for business leaders making 2026 allocations. Rather than a passive narrative, it contains calibrated modules designed to be applied directly to decision processes.
- Supply-chain atlas: mapped origination nodes, processing footprints and logistics corridors that reveal where margin leakage typically occurs and where control points should be established.
- BOM decomposition and price-to-cost logic: a build-up framework that separates tradable commodity costs from origin premia and processing value-add, enabling scenario-based margin modelling.
- Yield-adjustment and tolerance models: practical models to translate varietal yield changes and post-harvest losses into P&L and working-capital implications without exposing proprietary coefficients.
- Compliance and traceability matrices: operational checklists and layered controls for global trade compliance, recall containment and ESG verification that address 2026 regulatory realities.
- Technology roadmap and CAPEX prioritisation: a staged matrix for adopting digital traceability, AI-driven yield analytics and automation that focuses on ROI pathways rather than prescribing vendor-specific solutions.
Each tool is accompanied by implementation playbooks that explain typical decision gates and the internal KPIs executives should monitor in 2026 — from cost-to-serve by channel to time-to-recall containment — without disclosing confidential client-level inputs.
Competitive landscape: dimensions of advantage (not tactical forecasts)
PW Consulting’s industry view emphasizes the structural sources of competitive advantage in aromatic rice rather than firm-specific 2026 action plans. The market rewards distinct capability sets; understanding these dimensions guides where to place bets.
- Origin control and vertical integration: Firms that control origination (seed-to-mill) reduce sourcing volatility and capture upstream margin. This control translates to negotiated supply certainty for large retail buyers.
- Brand equity and route-to-market density: Premium brands with deep retail partnerships and foodservice contracts secure design wins that are stickier than price alone.
- Breeding and seed IP: Proprietary varietal development or exclusive licensing delivers both agronomic and organoleptic differentiation, enabling sustained premium pricing.
- Sustainability and certification moats: Proven sustainability credentials (regenerative, organic, third-party traceable) are increasingly non-negotiable for institutional buyers and regulators.
- Trade and distribution infrastructure: Operators with global trading desks and fulfilment networks can arbitrage regional premia and respond quickly to demand shocks.
Representative industry players illustrate these dimensions:
- KRBL Limited — significant export scale and established premium branding anchored in origin-control capabilities.
- LT Foods Ltd — strong multi-brand reach and route-to-retail expertise that supports premium portfolio placement.
- Lundberg Family Farms — differentiated on organic/regenerative credentials but exposed to food-safety and recall dynamics, underscoring the trade-off between premium positioning and operational stringency.
- Amira Nature Foods and Kohinoor Foods — merchant and branded hybrids that balance volume distribution with premium SKUs.
- RiceTec — seed and hybrid capability that typifies the value of breeding IP in driving agronomic advantage.
- Olam International and Ebro/Tilda — global trading and processing platforms that enable geographic arbitrage and scale in logistics.
- Vilaconic and other regional manufacturers — origin-based manufacturing that can serve both local markets and opportunistic exports when varietal premiums align.
Recent industry events underscore these competitive dynamics: a voluntary recall in April 2026 highlighted operational risk for premium organic suppliers; new public and national varietal launches are expanding the supply-side toolkit for buyers; and shifting import patterns in major markets are prompting faster origin diversification. For a complete, company-level strategic snapshot and interactive competitive maps, read the full PW Consulting report: Access the full report .
Methodology — how PW Consulting converts noise into decision-grade signal
Our methodological approach uses layered triangulation to turn partial or proprietary inputs into robust market estimates and scenario outputs. Layered triangulation combines customs and trade filings, POS and distributor scanner data, on-the-ground supplier interviews, and remote-sensing yield estimates. We then cross-validate with patent and varietal pedigree analysis to reconcile reported varieties with likely yield and premium characteristics.
To access data that is not in the public domain, we rely on a combination of primary fieldwork (procurement desk interviews, mill-level site visits), anonymised client-level shipment traces, and proprietary analytics that infer post-harvest losses from satellite-based crop health signals. This multi-source architecture reduces reliance on any single input and allows us to produce forward-looking models that are resilient to one-off anomalies — essential for planning capital allocation in 2026.
Strategic playbook: priority actions for 2026
Executives should consider a portfolio of mutually reinforcing moves that preserve optionality while capturing near-term upside.
- Secure supply and diversify origin exposure via contractual anchor volumes and build contingency corridors for premium varietals.
- Invest in traceability and rapid-response food-safety controls to reduce recall risk and support premium claims.
- Prioritise varietal partnerships or seed-IP access where breeding yields and organoleptic profiles support a durable price premium.
- Accelerate selective automation and AI analytics in milling and QA to squeeze cost per unit and improve yield capture.
- Embed ESG verification into commercial offers to protect access to institutional buyers and mitigate regulatory friction.
- Use M&A or strategic JVs to rapidly obtain origin control or scale in distribution rather than attempting slow organic build-outs.
Next steps and how to obtain the full intelligence set
PW Consulting’s Basmati Rice Market report is designed as a decision-support asset for boards, CFOs and commercial heads who need to allocate capital with conviction in 2026. The public summary above emphasises the strategic posture you must adopt; the full report contains the interactive maps, supplier scorecards, scenario models and step-by-step implementation playbooks necessary to execute these moves.
For immediate access to the full dataset, interactive charts and implementation playbooks, visit: Read the full PW Consulting report .
For detailed analysis of this topic, please visit the official page: Basmati Rice Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cheese Powder Market to Reach USD 8.3 Billion by 2032 as Demand for Ready-to-Cook Solutions Surges
By PW Consulting, 2026-06-26
Cheese Powder Market 2026: Strategic Preview for Capital Allocation and Operational Resilience
PW Consulting publishes this executive market brief to orient manufacturers, ingredient traders, private equity investors, and R&D leaders as they make near-term capital and commercial decisions in 2026. The global cheese powder market is at an inflection point: after expanding from an estimated USD 3.8 Billion in 2020 to USD 5.3 Billion in 2025, PW projects the market to reach roughly USD 5.8 Billion in 2026 and to continue growing toward about USD 8.3 Billion by 2032 at a compound annual growth rate of 6.7%. This growth trajectory underpins urgent choices on sourcing, capacity, and technology investments that will determine winner-take-most outcomes in the coming planning cycle.
Cheese Powder Market
Market Snapshot — What the topline numbers mask
Headline growth conceals three simultaneous dynamics that we observe across supply chains and customer ecosystems:
Cheese Powder Market
- Volatility in feedstock economics and seasonal milk supply is creating short-term cost spikes that propagate through cheese block pricing and ultimately into powder margins.
- Demand is being driven by convenience-centric food formats and by formulators seeking label-friendly, functional cheese solutions—forcing suppliers to juggle taste, solubility, and regulatory labeling constraints.
- Industry concentration is meaningful: the top three firms control roughly 55.0% of the market by revenue, and the top five approach 70.0%, amplifying the importance of selective partnerships and design wins for market access.
2026 Macro Drivers: Raw Materials, Regulation, and Trade
Three macro drivers dominate corporate decision calendars in 2026 and should be prioritized in board-level scenario planning:
- Raw-material price volatility. Domestic cheddar block pricing and associated Class III milk benchmarks remain a primary cost lever. Recent reporting shows U.S. cheddar block prices around USD 1.7 per pound in early May 2026, underscoring the sensitivity of powder margins to commodity moves and seasonality.
- Heightened trade and labeling compliance. Cross-border flows of dairy powders are subject to tightened registration and certification protocols in major markets; compliance costs and lead times have risen materially for exporters and their customers.
- ESG and clean-label expectations. Buyers increasingly require traceability, reduced waste, and demonstrable sustainability credentials across the value chain—criteria that now influence sourcing choices and supplier selection beyond price alone.
Practical Tools in the PW Consulting Report — How we convert insight into action
The full PW Consulting Cheese Powder Market report is purposely operational. We do not publish every numeric slice here; instead, we equip decision-makers with prescriptive tools they can apply immediately in 2026 planning cycles. Key deliverables include:
- Supply-chain topology and stress-mapping: end-to-end diagrams showing node-level risks, lead-time sensitivities, and alternative sourcing corridors for immediate contingency planning.
- Bill-of-Materials (BOM) decomposition logic: a modular approach to breaking down discretionary and nondiscretionary cost elements so teams can test targeted SKU and label changes without rebuilding finance models from scratch.
- Yield-adjustment and cost-pass-through models: scenario-ready models that let procurement and commercial teams simulate the P&L impact of cheese block price swings, yield improvements, and contract strategies (fixed vs indexed).
- Technology and capability roadmap: a stratified view of pragmatic process upgrades—spray-drying optimizations, powder agglomeration methods, and digitalizing QC—that deliver step-change improvements in yield, compliance, and product functionality.
- Regulatory playbook: a checklist and escalation matrix for export registration, certification, and label claims in priority markets to shorten time-to-market and reduce rework.
How these tools address immediate 2026 pain points
Executives allocating capital this year should expect to use the above tools to answer three operational questions quickly:
- Can we protect margin through short-term sourcing hedges and yield improvements rather than rely solely on price increases to customers?
- Which process upgrades deliver the highest ROI in the next 12–24 months for compliance and traceability?
- Where should we invest to convert strategic customers’ design wins into long-term contracts—by co-developing formulations, guaranteeing specifications, or committing capacity?
Competitive Landscape — Dimensions that determine wins in 2026
Our assessment of market participants highlights that competitive advantage is increasingly multidimensional. Below we summarize the principal defensive and offensive levers companies are using to secure growth without disclosing our firm-level forecast overlays.
- Manufacturing scale and drying expertise. Established producers with legacy spray-drying capacity and multi-site footprints benefit from lower unit costs and redundancy, which matters when commodity and seasonal pressures spike.
- Certification breadth and label flexibility. Suppliers that can offer organic, kosher, halal, and allergen-managed streams command premium positioning among formulators that must serve diverse markets.
- Application and formulation know-how. The ability to deliver functional attributes—solubility, emulsification, melt profile—across ready-to-eat meals, coatings, and snacks is a decisive factor in winning specification-led contracts.
- Customer intimacy and design wins. Design wins in this market hinge on rapid prototyping, co-development capacity, and the ability to align a supplier’s compliance and traceability processes to a customer’s procurement standards.
- Route-to-market and export capability. Firms with efficient export documentation, registration playbooks, and trade-compliant supply chains convert geographic demand shifts into sustained revenue faster than those reliant on spot channels.
Notable participants in this ecosystem—ranging from century-old regional manufacturers to diversified ingredient groups and specialized spray-dryers—demonstrate these competitive dimensions. PW Consulting’s work includes comparative capability maps that link these dimensions to likely partnership strategies and potential consolidation targets; for the detailed company capability matrices and our suggested engagement strategies, access the full report.
Recent developments that matter for 2026 planning
Two recent data points crystallize the decision context:
- New product introductions continue to expand category use-cases: a November 2025 launch of a Queso Blanco powdered sauce SKU illustrates ongoing product innovation at the intersection of convenience and multicultural flavor demand.
- Commodity signals remain highly relevant: USDA price reporting in May 2026 confirmed that cheddar block pricing is a live input to cost-models and contract negotiations.
Strategic Implications — What leaders should do now
PW Consulting recommends that companies take three prioritized actions in 2026 to convert market growth into durable advantage:
- Lock incremental capacity selectively and contractually: prioritize capacity commitments that include yield-based KPIs and shared risk provisions to protect margin when block cheese prices spike.
- Build cross-functional compliance squads: integrate regulatory, quality, and commercial teams into export readiness programs to reduce time-to-market in high-growth corridors.
- Invest in modular R&D for formulation wins: focus on small-batch, rapid-prototype capabilities that accelerate design-win cycles with major food manufacturers and differentiate on functional attributes rather than commodity pricing alone.
Methodology — Why PW Consulting’s conclusions are actionable
Our findings are the result of layered triangulation combining primary and secondary sources. Primary inputs include structured interviews with procurement and R&D leaders at manufacturers and large CPG customers, on-site plant process reviews across spray-drying facilities, and proprietary transaction-level customs and trade flows. Secondary inputs include supplier financials, public filings, and curated commodity price series.
We also incorporate patent landscaping, SKU-level product mapping, and application-domain sensory panels to connect technical capability with commercial preference. Where public data is sparse, we apply supply-chain forensics—cross-referencing shipment manifests, contract lead times, and certification registries—to construct validated estimates. These methods enable us to surface non-public constraints and opportunity pockets without releasing raw confidential data in this preview.
Next steps — how to use this preview
Leaders who need playbooks, customer-qualification frameworks, and transaction-ready models for 2026 should consult the full PW Consulting report. The comprehensive annex includes the supply-chain diagrams, BOM templates, yield and margin models, and a framework for prioritizing investments by expected short-term payback and medium-term strategic value.
Access the full report and supporting tools here: Access the PW Consulting Cheese Powder Market Report .
Contact
For consulting engagements, scenario workshops, or to commission a custom deep-dive tailored to your product portfolio or sourcing footprint, contact PW Consulting’s Food Ingredients practice. Our team will help you translate the market trajectory into executable 2026 capital and commercial plans.
For detailed analysis of this topic, please visit the official page: Cheese Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fuel Card Market Poised to Surge at a 12.8% CAGR Through 2032
By PW Consulting, 2026-06-26
Gel Card Market — 2026 Strategic Outlook and Capital Allocation Playbook
PW Consulting publishes the latest Gel Card Market briefing for 2026 to guide executive capital allocation, commercial prioritisation, and regulatory risk management. Our new analysis synthesizes observed supply-chain retooling, recent FDA clearances and manufacturing shifts, and a high-growth demand curve to show where boards and investors should focus in the coming 18–36 months. This release highlights the report’s strategic value without disclosing proprietary segment-level figures—use the linked briefing to access the full granular maps and tables.
Fuel Card Market
Market trajectory at a glance
After analysing historical performance across 2020–2025 and projecting forward across 2026–2032, we see a market expanding at a compound annual growth rate (CAGR) of 12.8%. The market base year (2025) provides a stable starting point for scenario modelling and stress tests, and our central forecast shows material upside through 2032 as diagnostic automation and regulatory approvals drive higher consumable volumes and system upgrades.
- Base-year orientation: 2025 is treated as the analytical pivot for our forecast period 2026–2032.
- Growth engine: regulatory approvals and near-term manufacturing capacity additions are the primary accelerants in our central case.
- Concentration: the market shows a mid-to-high concentration profile (top‑3 and top‑5 players account for the majority of commercial share), which amplifies the strategic value of design wins and regulatory clearances.
Why 2026 is a decision point for capital
Three contemporaneous forces make 2026 a critical year for capital deployment:
- Regulatory gating: Recent and pending FDA clearances materially influence procurement choices at large hospital networks and reference labs. Firms with compliant manufacturing footprints gain near-term commercial advantage.
- Manufacturing re-shoring: Documented capacity moves into regulated jurisdictions reduce lead-time risk but require upfront CAPEX and regulatory investments; timing these investments correctly is key to capturing share without overextending balance sheets.
- Automation adoption: Adoption of semi- to fully-automated immunohematology platforms increases per-lab spend on compatible consumables, changing lifetime value calculations for account holders.
Key industry dynamics
- Regulatory and quality overlay — FDA licensing for gel-card configurations and ISO 13485 compliance are practical gating items for U.S. distribution and institutional buyers.
- Reimbursement stability — Existing CPT codes for blood typing and cross-matching create predictable billing pathways but also anchor buyer expectations on unit economics.
- Platform-integration effects — Design wins on automated systems (e.g., high-throughput analyzers) become a durable commercial moat because switching costs extend beyond price to workflow and accreditation impacts.
- Consolidation pressure — Mid-sized manufacturers face margin compression and are attractive targets for larger incumbents seeking to lock distribution channels or add niche product lines.
What our operational toolset delivers (practical assets inside the report)
This market brief is supported by hands-on decision tools built for procurement, manufacturing, and M&A teams. Key deliverables include:
- Supply‑chain maps that trace critical raw-material nodes, single‑sourced components, and logistics choke points, designed for rapid supplier-risk triage.
- Bill-of-Materials (BOM) decomposition logic that isolates cost drivers in consumable manufacturing—useful for scenario-based margin recovery without disclosing calibrated unit figures in this press summary.
- Yield-adjustment and throughput models that translate incremental improvements in manufacturing yield into balance-sheet impacts under multiple pricing environments.
- Technology roadmaps that align reagent chemistry, gel matrix advances, and automation compatibility to likely commercial windows through 2032.
- Regulatory-compliance matrices that match device configurations to country-level approval requirements—built to fast-track submission planning and site-selection for regulated manufacturing.
These tools are designed to be operational: procurement teams can run supplier stress-tests, manufacturing leaders can perform CAPEX IRR sweeps, and corporate development can model M&A synergies under different integration assumptions.
Competitive dynamics — how winners will be decided
Across the competitive set, market outcomes hinge less on headline product breadth and more on a small number of structural competitive dimensions. Our analysis emphasises these vectors rather than public-facing strategy statements.
- Regulatory‑certified manufacturing footprint — Firms with validated production lines in regulated jurisdictions convert approvals into regional design wins faster, shortening sales cycles with institutional buyers.
- Platform integration and interoperability — Compatibility with automated analyzers and end‑to‑end lab workflows is a primary gate for adoption in high-throughput labs.
- Supply‑chain resilience and quality systems — ISO 13485‑grade quality management and diversified supplier bases reduce production volatility and are strong commercial differentiators during procurement RFPs.
- Service and distribution networks — Rapid replenishment, reagent stability, and localized technical support are frequently cited as decisive factors in purchasing decisions by blood bank operators.
Examples from recent market activity underline these points without disclosing proprietary forecast outcomes. Notable events include multiple FDA approvals for specific gel‑card configurations and the commercial launch of new control products, plus manufacturing expansions into the U.S. These developments validate the premium buyers place on regulatory‑cleared supply and regional manufacturing capability.
To explore the firms and the full competitive profiles referenced above, see the detailed company analyses and evidence maps in the full report. Access the full report for company-level intelligence and the underlying evidence base.
Methodology — how we build confidence in forecasts
PW Consulting uses a layered triangulation approach to ensure forecast robustness. Our method aggregates five independent evidence streams and applies cross‑calibration to eliminate single‑source bias:
- Primary interviews with procurement leads, lab directors, and former regulatory officers to capture contract terms, fill‑rate expectations, and accreditation constraints.
- Patent‑citation and regulatory filings analysis to timestamp technology adoption paths and to identify likely approval windows.
- On‑site and virtual factory audits for cost‑structure validation and yield benchmarking, combined where available with anonymized supplier invoices and freight manifests to validate unit‑cost assumptions.
- Machine‑level telemetry and automation vendor disclosures to quantify potential throughput gains from migration to semi‑ or fully‑automated platforms.
- Statistical smoothing across the historical series (2020–2025) and multiple macro scenarios for 2026–2032 to stress‑test sensitivity to pricing, adoption rates, and regulatory shock events.
We emphasise that some inputs are drawn from non‑public but verifiable sources (confidential supplier interviews, anonymised procurement records, and regulatory submission registries). These data are consolidated under confidentiality protocols and used to calibrate the public‑domain evidence you see summarised in the press briefing.
Strategic recommendations for 2026
Based on the growth profile and competitive dynamics, PW Consulting recommends that corporate boards and investment committees prioritise three actions in 2026:
- Prioritise partner lanes with FDA‑approved manufacturing or near‑term submission roadmaps to minimise procurement gating risk at large institutional buyers.
- Accelerate automation-linked product compatibility projects where unit economics can be demonstrably improved via yield gains and reduced labour costs.
- Use targeted M&A or distribution agreements to secure fill‑rate and technical support in strategic geographies rather than pursuing broad, capital‑intensive greenfield expansions.
These moves are designed to preserve optionality while capturing the asymmetric upside that accrues to early certifiers in a concentrated market environment growing at 12.8% CAGR.
Next steps and how to get deeper intelligence
PW Consulting’s full Gel Card Market report contains the detailed regional and application distributions, supplier scorecards, modelled CAPEX/ROI calculators, and playbooks referenced above. For procurement teams, it includes templated RFP language and supplier risk matrices; for investors, it includes deal-screening triggers based on regulatory and manufacturing milestones.
To download the complete intelligence package and the interactive models, visit https://pmarketresearch.com/hc/gel-card-market .
For detailed analysis of this topic, please visit the official page: Fuel Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Portable Oxygen Concentrators Market to Expand at 8.3% CAGR Through 2032 as Homecare Demand Surges
By PW Consulting, 2026-06-26
Portable Oxygen Concentrators Market: Strategic Imperatives for 2026 Capital Allocation
As of 2026, the global Portable Oxygen Concentrators (POC) market is at an inflection point. PW Consulting’s latest market study establishes that the sector has expanded from USD Million 1,400.0 in 2020 to USD Million 2,050.0 in 2025, and is forecast to reach USD Million 3,560.0 by 2032—an expected compound annual growth rate (CAGR) of 8.3% across the 2026–2032 projection interval. These headline numbers frame a market where clinical demand, regulatory friction, channel innovation and product engineering converge to create both near-term disruption and long-term opportunity for investors, manufacturers and payers.
Portable Oxygen Concentrators Market
Executive snapshot — why 2026 matters
2026 is a pivotal year for capital deployment in POCs because three simultaneous shifts are occurring:
- Clinical demand is moving from episodic to chronic home-based oxygen management as population aging and COPD prevalence continue to push outpatient therapy adoption.
- Regulatory and mobility requirements—FAA acceptance criteria plus evolving national device clearances—are raising the bar for design verification and global market access.
- Manufacturing and channel economics are being reshaped by modular design, battery chemistry constraints and the rise of direct-to-patient (D2P) rental models.
Collectively, these forces compress decision windows for strategic buyers: sourcing commitments, design partnerships and M&A choices made in 2026 will disproportionately affect capture of growth through 2032.
Market dynamics: what is driving value (and risk)
Key demand and supply-side drivers that underlie the forecast are:
- Patient mobility priorities—lighter weight, longer battery life and FAA acceptance are non-negotiable design success factors for ambulatory segments.
- Channel evolution—rentals and D2P distribution are increasing utilization and shifting lifetime revenue models away from one-time device sales.
- Regulation and reimbursement—Medicare and national payers still shape market access timelines through coverage pathways and rental rules, while international regulatory harmonization remains uneven.
- Component and battery supply chains—sourcing pressure on compressors, sieves and advanced batteries creates cost variability that impacts gross margins across OEMs.
These elements create asymmetric value: companies that can translate engineering trade-offs into validated design wins and controlled unit economics will capture disproportionate share of the projected expansion.
What PW Consulting’s report delivers — practical tools for 2026 execution
The report is designed as an operative playbook for decision-makers rather than a descriptive survey. Tools included that directly address 2026 pain points are:
- Supply chain topology and risk maps that identify single points of failure and dual-sourcing pathways for critical sub-assemblies.
- BOM (bill-of-materials) disaggregation logic tailored to POC designs, enabling CFOs and sourcing leads to model cost-down scenarios without needing physical teardowns for every SKU.
- Yield adjustment and throughput models for contract manufacturers, allowing commercial teams to translate production constraints into realistic lead-time guarantees for health systems.
- Technology roadmaps that align powertrain, sieving media and connectivity stacks against certification milestones (FAA, FDA 510(k), CE), enabling product and regulatory teams to prioritize investments.
Each tool is accompanied by executable templates—procurement scorecards, supplier qualification checklists and design win playbooks—so that teams can convert insight into purchase orders, partnership terms and regulatory timelines in calendar 2026.
Competitive landscape — dimensions of advantage
The market shows moderate concentration (CR3 58.0%, CR5 75.0%), indicating that a handful of incumbents control significant installed bases but that opportunities for challenger innovation remain. Our analysis focuses on competitive dimensions rather than prescriptive forecasts for each firm.
- Product moat: Leading firms combine differentiated powertrain architecture with validated FAA and national regulatory acceptance. Weight, usable battery life, and oxygen-delivery algorithms remain primary determinants of product preference.
- Channel moat: Firms that have integrated D2P rentals and clinical-service capabilities (warranty, remote monitoring) capture higher lifetime value through recurring revenue and adherence-driven upgrades.
- Supply-chain/mo manufacturing moat: Control over sieve media suppliers, compressor co-development and battery procurement reduces gross margin volatility and accelerates time-to-market for design iterations.
- Data and connectivity moat: Connectivity stacks—ranging from simple usage logging to remote therapy optimization—are emerging as secondary barriers to entry because they feed service and reimbursement outcomes.
Representative competitive archetypes in the report include established pulse-dose specialists focused on ambulatory light-weighting, continuous-flow incumbents targeting higher-acuity users, and vertically integrated suppliers emphasizing service and rental economics. Recent product availability and portfolio expansion events—such as the release of autoSAT-equipped devices and new stationary complements—underscore the strategic diversity within the top tier.
For readers assessing partnership or acquisition targets, PW Consulting highlights the key design-win levers: validated FAA acceptance, battery-pack lifecycle data, channel penetration in D2P rentals, and proven post-market servicing economics. To review our company-by-company analytical framework and scorecard, download the full PW Consulting report: Access the full report and scorecards .
Technology and supply-chain posture for 2026
Technology evolution in 2026 is incremental but cumulative: incremental gains in sieve efficiency, compressor control, and battery energy density compound to materially improve usable user time and device weight. From a supply-chain stance, three programmatic actions are necessary:
- Design for compliance: embed certification gateways into development sprints to avoid rework driven by FAA or national regulatory requirements.
- Supplier diversity planning: qualify alternate sieve and battery suppliers early and run parallel validation streams to protect launch timelines.
- Service-as-differentiator: engineer units for field maintainability and remote diagnostics to reduce total cost of care and support rental economics.
The report’s BOM and yield models let product and procurement teams stress-test these actions against pricing and lead-time scenarios so that board-level capital allocations can be justified quantitatively.
Regulatory, reimbursement and market-access constraints
Regulatory and reimbursement realities are immediate and non-negotiable. Examples relevant for 2026 decision-making include:
- FAA acceptance remains a gating criterion for ambulatory-focused design wins and for marketing to travel-active patient cohorts.
- FDA 510(k) clearance timelines and documentation requirements continue to influence go-to-market sequencing for U.S. launches.
- Payer rules—such as Medicare’s rental duration and device classification—materially affect cash flow models for rental-based businesses.
Our Dynamics section synthesizes how these constraints interact with market expansion and provides a practical checklist for commercial and regulatory teams to align 2026 launches with payer and travelability prerequisites.
Methodology: how PW Consulting produces actionable, proprietary insights
Our conclusions are rooted in layered triangulation and proprietary primary research protocols designed to surface supply, demand and margin truths that are not visible in public filings alone. Key methodological pillars include:
1) Multi-channel primary interviews: confidential interviews with device engineers, procurement leads at national rental chains, payer policy advisors and contract manufacturers provide qualitative signals that are then quantified.
2) Technical reverse engineering and customs analytics: controlled device teardowns, matched with global shipment and customs flows, allow us to model realistic BOM compositions and identify concentration risks. Patent landscaping and regulatory dossier reviews are used to validate technology claims and to time-certification risks. These data streams are cross-referenced with time-series shipment data and payer-claim samples under strict NDAs to ensure robust triangulation.
Together, these methods let clients move from hypothesis to executable procurement and product roadmaps with a confidence factor that is statistically and operationally defensible.
Actionable recommendations for 2026 capital allocation
For corporate boards, private equity sponsors and strategic investors evaluating POC exposure in 2026, PW Consulting recommends a three-track action plan:
- Near-term: Prioritize partners and targets with validated FAA and payer acceptance to protect commercialization timelines and revenue predictability.
- Medium-term: Invest in modular battery and sieve development or secure long-term supply contracts to stabilize cost curves across 2026–2028.
- Long-term: Build service-led monetization pathways (rentals, remote care) that convert product upgrades into recurring revenue and higher lifetime value.
Executing on this plan requires granular, model-driven diligence. PW Consulting’s operational tools—BOM logic, yield models and supplier risk maps—are designed to accelerate that workstream.
Next steps and how to obtain the full intelligence
PW Consulting’s full report contains the detailed spatial distribution charts, segmented demand curves, proprietary supplier risk scores and the complete competitor scorecards that underpin the executive recommendations above. To access the comprehensive dataset and decision-grade templates, follow this link to download the full PW Consulting report: Download the full report and supporting tools .
For detailed analysis of this topic, please visit the official page: Portable Oxygen Concentrators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rice Flour Market to Reach USD 1,036.3 Million in 2026, Expanding at a 4.5% CAGR through 2032
By PW Consulting, 2026-06-26
Rice Flour Market Outlook 2026: Strategic Imperatives for Capital Allocation
In 2026 the rice flour market sits at an inflection point. PW Consulting’s latest study — built on a 2025 base year with a 2020–2025 historical reconstruction and a 2026–2032 forecast horizon — shows the global market reached USD 980.0 Million in 2025 and is projected to expand at a compounded annual growth rate (CAGR) of 4.5% through 2032 (ending at USD 1323.0 Million). Those headline numbers are a doorway into a more complex set of dynamics that will determine winners and losers during the next strategic planning cycle.
Rice Flour Market
Why 2026 Is Pivotal for Investors and Operators
Three converging forces make 2026 the year for decisive capital moves:
- Regulatory normalization and market opening. Recent EU and EFSA actions have materially altered the compliance landscape for novel protein and ingredient forms; at the same time, selective retail restrictions in key channels create differentiated go-to-market risk profiles.
- Supply-side reconfiguration. Consolidation, distressed assets and factory restarts are changing available capacity and bargaining power, while ingredient premiums and limited scalable feedstocks maintain elevated margin pressure for highly differentiated products.
- Technology and ESG as decision gates. AI-driven process upgrades, traceability systems and validated ESG claims are now required components of commercial diligence rather than optional differentiators.
For boardrooms and portfolio managers, these forces translate into three operational imperatives: (1) lock in compliant supply chains that meet evolving global trade rules, (2) prioritize investments that demonstrably improve unit economics, and (3) select partners with defensible market access rather than short-term cost advantages.
What the PW Consulting Rice Flour Report Delivers
Our report is designed as a practical decision-making toolkit for 2026 capital allocation and strategy. It deliberately balances strategic insight with operational specificity while reserving proprietary model outputs for subscribers. Key deliverables include:
- Supply-chain topology and vulnerability mapping — an end-to-end view from primary milling, alternative raw feedstocks and contract processing through to finished-ingredient distribution and key private-label pathways.
- Bill-of-materials (BOM) teardown logic — a reproducible framework for converting laboratory and pilot formulations into plant-scale cost models, including a sensitivity dashboard for raw-material and yield volatility.
- Yield adjustment and margin-preservation models — scenario-ready approaches for translating small improvements in yield, particle-size control, and moisture management into P&L outcomes under multiple price regimes.
- Technology and process roadmap — comparative assessment of incremental vs. disruptive upgrade paths (e.g., milling configuration choices, low-temperature drying, particle fractionation and automation-ready sensor suites) with time-to-value heuristics.
- Compliance and traceability matrix — regulatory gating items cross-referenced to commercial use cases and retail acceptance thresholds across major export markets.
- Commercial playbooks — procurement negotiation levers, contract structures, and co-manufacturing decision rules built around design-win criteria and cost-to-serve analytics.
Each tool in the suite is accompanied by implementation checklists and a decision-tree logic that maps an executive’s tolerance for capital intensity, time-to-market and regulatory exposure to a recommended action pathway. The granular outputs — including geo-distributed capacity maps, supplier scorecards and model parameter sets — are intentionally withheld here to preserve subscriber value and to direct readers to the full dataset and interactive dashboards.
Competitive Landscape: The Dimensions That Decide 2026 Winners
The rice flour space in 2026 is defined less by single-brand dominance and more by a set of competing vectors. Our analysis of leading ingredient players and adjacent entrants surfaces five competitive dimensions that consistently determine design wins and sustainable market share:
- Scale and integration: Ability to vertically integrate sourcing and processing reduces cost-to-serve and improves traceability under tightening regulatory regimes.
- Formulation compatibility: Suppliers who demonstrate consistent particle-size distributions, moisture profiles and functional performance in partner formulations capture faster adoption in bakery, snack and specialized nutrition segments.
- Regulatory and certification infrastructure: Firms with validated allergen controls, audited HACCP/ISO systems and documented export compliance have a lower commercial friction cost in global rollouts.
- Sustainability and provenance claims: Measured ESG credentials (scope-aligned metrics and verified chain-of-custody) are increasingly price-relevant in institutional and food-service channels.
- Channel and co-manufacturing relationships: Strategic partnerships with private-label bakery networks or ingredient formulators act as effective barriers to entry when coupled with preferred pricing and exclusivity mechanics.
Companies referenced in our competitive maps (including major regional producers and specialist ingredient houses) are evaluated against these vectors rather than on a single revenue metric. This dimensional approach explains why some smaller, vertically integrated operators can command design wins against larger, commodity-oriented suppliers. For company-level heat maps, supplier archetypes and the Design Wins scorecard, see the full report here: Access the full report and subscriber resources .
Operational Playbook — Where to Place Capital in 2026
From a practical allocation standpoint, PW Consulting recommends triaging opportunities across three buckets, each justified by near-term risk and expected time to value:
- De-risk and diversify supply: Prioritize medium-term contracts with tier-1 processors that incorporate compliance milestones and price-floor triggers. Use staged capital with performance milestones rather than blanket M&A at current multiples.
- Invest in yield and processing upgrades: Incremental capital in process control, sensors and low-cost automation often outperforms greenfield capacity in IRR models. Target investments that reduce moisture-related shrink and particle variability.
- Capture premium channels through formulation partnerships: Fund co-development pilots with major bakery and specialized nutrition customers to lock in design wins tied to exclusivity clauses, joint IP or co-branding arrangements.
These recommendations are framed to be actionable without prescribing a single path. Each will require bespoke scenario runs using the report’s BOM and yield models to quantify expected payback under alternative pricing and regulatory assumptions.
Regulatory and Market Dynamics — Why Timing Matters
Recent regulatory decisions and market events make timing critical for 2026 capital decisions. Regulatory acceptance in major hubs has expanded addressable markets while selective retail bans and allergen-labeling requirements raise go-to-market complexity. Meanwhile, mid-cycle asset distress and strategic acquisitions are changing capacity landscapes and negotiation leverage. Taken together, these forces shorten the window for advantageous entry: delay increases the probability of paying up for scarce compliant capacity or losing design wins to better-positioned partners.
Methodology and Research Rigor
PW Consulting’s findings are built on Layered Triangulation — a multi-source validation methodology that combines patent and regulatory filing analysis, primary interviews under NDA, plant-level audits, proprietary customs and trade-flow feeds, and quantitative model calibration against audited financials where available. We augment these public and licensed datasets with in-field BOM tear-downs, laboratory replication of key functional properties and iterative yield validation using partner production runs.
Crucially, our non-public inputs are collected under contractual confidentiality and ethical intelligence standards. We do not publish proprietary contract terms or individual supplier financials in the public release; instead, our subscribers receive the calibrated model parameters, supplier scorecards and scenario-ready dashboards that translate those inputs into executable strategies.
Executive Takeaway — A 2026 Decision Agenda
For executives, procurement heads and investors, the report’s central strategic counsel is straightforward: treat rice flour and adjacent specialty ingredient spaces as differentiated industrial markets where regulatory positioning, process yield and formulation compatibility create sustainable value more reliably than simple scale. The market’s 4.5% CAGR and the projected pathway to USD 1323.0 Million by 2032 are context — the real value accrues to organizations that translate compliance, traceability and small-percentage yield gains into binding commercial relationships.
To evaluate opportunistic acquisitions, form JVs or commit capital to process upgrades in 2026, stakeholders need the underlying segmentation maps, supplier scorecards and model parameters our report provides. For the complete dataset, interactive dashboards and our step-by-step implementation playbooks, access the full report and subscriber materials: View PW Consulting’s Rice Flour Market report .
For detailed analysis of this topic, please visit the official page: Rice Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Filter Market Poised to Grow at 6.7% CAGR Through 2032
By PW Consulting, 2026-06-26
PW Consulting Strategic Preview: Blood Filter Market — 2026 Outlook
PW Consulting publishes a forward-looking executive brief built from our full Blood Filter Market study (base year 2025) to equip senior executives and investment committees with the decision-quality framework required for 2026 capital allocation. The market is in a clear expansion phase: after a five-year historical trajectory (2020–2025) the global market reaches USD 1,400.0 Million in 2025 and is projected to grow at a 6.7% CAGR through our forecast window (2026–2032), arriving in 2032 at approximately USD 2,194.4 Million. This preview highlights the strategic levers that matter in 2026 while intentionally withholding detailed segment-level tables to encourage review of the full report for transaction-ready numbers.
Blood Filter Market
Market Snapshot — momentum, not mythology
Between 2020 and 2025 the market more than doubles in momentum, reflecting combined tailwinds from clinical demand, stricter dialysate purity standards, and renewed procurement cycles among large dialysis providers. In 2026 the market is not static — it is at an inflection where regulatory thresholds, reimbursement pathways, and installed-base replacement dynamics converge to favor suppliers who can prove both technical performance and predictable total cost of ownership.
Primary growth drivers in 2026
-
Clinical incidence and treatment intensity: Rising prevalence of chronic kidney disease and increased utilization of blood-transfusion services sustain baseline demand.
-
Quality and compliance pressures: ISO and FDA-aligned purity targets raise the technical bar for ultrafiltration and pyrogen removal, creating demand for validated filter technology and service programs.
-
Reimbursement and billing mechanics: Select ultrafiltration and hemoconcentration services can be billed separately under certain payor rules, creating revenue models that reward verifiable clinical outcomes and documentation readiness.
-
Materials and manufacturing modernization: Advances in membrane chemistry and production yield expand product life and unit economics for manufacturers who can scale without sacrificing compliance.
-
Concentration and access: Market concentration metrics show a mid-level consolidation, which favors both incumbents with channel control and nimble entrants that win design-in opportunities with clinical partners.
What matters to executives in 2026 — five strategic imperatives
-
Operationalize compliance as a revenue enabler: Treat ISO 23500 and Class II device requirements as input constraints for product design and supplier selection, not just a checklist.
-
Reduce cost-to-serve through BOM and yield optimization: Rigorous bill-of-materials decomposition combined with yield-adjustment modeling reduces per-unit cost volatility and shortens payback on automation investments.
-
Design-win playbooks for hospital systems: Winning integrated therapy bundles requires alignment across clinical performance, procurement terms, and service logistics — PW Consulting’s report maps those win-criteria.
-
Supply chain risk engineering: Diversify critical upstream inputs and map second-source realities for membrane materials to avoid single-point disruptions.
-
Invest in installed-base support as a competitive moat: Service contracts, validated consumable replacements, and outcome measurement create sticky revenue streams.
Report deliverables that address 2026 pain points
Our full report is organized as a practical toolkit for immediate execution. Key modules include:
-
Supply chain topology and second-source maps that identify bottlenecks at raw-material, membrane, and finished-goods stages.
-
BOM decomposition logic and supplier-level cost drivers to inform targeted cost-reduction initiatives without compromising regulatory traceability.
-
Yield-adjustment models and scenario matrices that translate process improvements into cashflow and margin outcomes for 12–36 month planning horizons.
-
Technology roadmaps that align membrane chemistry advances, manufacturing automation, and product life-cycle strategies to reduce time-to-design-win.
-
Commercial playbooks and pricing elasticity frameworks rooted in hospital procurement behavior and payor constraints.
Each tool is built to convert market insight into board-level actions — for example, enabling procurement teams to evaluate supplier tradeoffs during RFPs or guiding engineering teams on which production investments yield the largest cash-on-cash returns in 2026.
Competitive landscape — dimensions that determine winners
Market concentration in 2026 remains moderate: our CR3 and CR5 metrics indicate that leading groups control a material share but that space remains contestable for firms that convert technical differentiation into commercial traction (CR3: 45.0%, CR5: 55.0%). The companies tracked in the report exemplify different sustainable advantages and decision levers:
-
Regional manufacturers with manufacturing cost advantages and localized regulatory familiarity — these players excel at rapid fulfillment and tailored configurations for national markets.
-
Technical specialists with membrane or cartridge IP — ownership of validated membrane performance and service-life data is a defensible moat for suppliers targeting ultrapure dialysate segments.
-
Platform players with installed systems and channel reach — firms that bundle filters with machines or service contracts monetize installed-base upgrades and after-market consumables.
-
Service-enabled vendors focused on lifecycle outcomes — companies that can demonstrate reduced infection rates or documented clinical improvements gain procurement leverage through value-based contracting.
Illustrative company dimensions in the report (without disclosing our full strategic forecasts) include manufacturing footprint and product focus, membrane IP or specialization, installed-base relationships, and regulatory track records. These are the axes that drive Design Win success: documented clinical validation, supply assurance, total cost of ownership, and regulatory readiness.
For a company-by-company strategic matrix and the Design Win checklist that we use in client engagements, see the full report: full report .
Regulatory and reimbursement context — operational constraints that shape strategy
In 2026 the regulatory baseline is non-negotiable: ultrapure dialysate guidance (ISO 23500 and associated standards) sets stringent bacterial and endotoxin thresholds — for example, bacterial counts and endotoxin limits that ultrafiltration systems must meet to qualify as ultrapure. Dialysis ultrafilters are regulated as Class II devices, and certain ultrafiltration services can receive separate reimbursement under specific payor rules. The intersection of these three domains — clinical thresholds, device regulation, and reimbursement coding — determines whether a product is a compliance cost or a commercial asset.
Methodology — why our findings are transaction-ready
PW Consulting applies a layered triangulation methodology to ensure that inferences are grounded in independent and verifiable inputs. Our approach combines:
-
Patent and citation analysis to map technologically meaningful IP clusters and infer R&D trajectories.
-
Proprietary procurement and shipment datasets that reveal real-world purchase cadence, validated under NDA from supply-chain partners.
-
Structured interviews and site visits with hospital procurement, OEM production managers, and membrane suppliers to validate assumptions about manufacturing yields and service-life claims.
-
Cross-validation with public regulatory filings (510(k) summaries) and technical specification sheets to reconcile claimed performance with observed field outcomes.
Where access to confidential supplier BOMs or contract terms is required, we rely on secure data rooms and mutually executed NDAs; our advisory outputs therefore reflect primary-source intelligence calibrated against open-source signals and statistical modeling, not simple desktop aggregation.
How CFOs and strategy teams should act in 2026
-
Prioritize capital that shortens supplier lead times and reduces per-unit variability — invest in supplier dual-sourcing, inventory buffering for critical membranes, and production automation that demonstrably lifts yields.
-
Use design-win criteria to guide early-stage product roadmaps: clinical evidence generation and service model proofs of concept are higher-return early investments than incremental cost reductions alone.
-
Frame M&A targets with a 24–36 month integration roadmap that values installed-base synergies and service revenue predictability over raw revenue multiples.
-
Embed regulatory-readiness checkpoints into product development stage-gates to minimize time-to-market risk for Class II filings and to accelerate reimbursement capture.
The market’s 6.7% CAGR and the projected increase from USD 1,400.0 Million in 2025 to approximately USD 2,194.4 Million in 2032 make a compelling case for near-term action: timing matters because the next tranche of procurement cycles and regulatory updates will crystallize leadership positions.
Next steps — where to get transaction-ready intelligence
For executives preparing board materials or conducting due diligence, the full PW Consulting report contains the proprietary tables, supplier-level scenarios, and litigation/regulatory risk matrices excluded from this preview. Access the detailed intelligence and downloadable templates here: full report .
For detailed analysis of this topic, please visit the official page: Blood Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Antimicrobial Suture Market to Reach USD 274.0 Million by 2032 Amid Steady Growth
By PW Consulting, 2026-06-26
Antimicrobial Suture Market: Strategic Briefing for 2026 — PW Consulting Industry Insight
As healthcare providers and device manufacturers confront persistent surgical-site infection (SSI) risks and rising compliance demands in 2026, PW Consulting releases a targeted industry briefing that translates market data into actionable intelligence for capital allocation, M&A screening, and commercial prioritization. Our analysis shows a market that is modestly expanding from a 2025 baseline of USD 216.3 Million and is modeled to grow at a 3.5% CAGR through 2032, underlining steady but strategic opportunity rather than a breakout boom. This briefing summarizes the directional implications for executive decision-making while reserving the granular segment maps and value ladders for the full report.
Why 2026 Is a Decision Inflection Point
Major forces converge in 2026 that make near-term positioning crucial:
-
Procurement budgets are increasingly allocated to demonstrable infection-control solutions, not just single-item purchases — forcing sutures to compete within a broader infection-prevention portfolio.
-
Regulatory and guidance bodies emphasize validated cleaning and sterilization protocols alongside treated articles, tightening the evidentiary bar for antimicrobial claims and raising the compliance costs for manufacturers.
-
Market concentration is materially significant (the top 3 players hold a large share, and the top 5 an even larger one), which amplifies barriers for new entrants but also creates attractive targets for bolt-on acquisitions that can close portfolio gaps.
Market Snapshot (No Spoilers — See Full Visuals in the Report)
Our top-level model tracks historical performance (2020–2025) and projects through 2032. The market posts steady year-to-year expansion with measured volatility tied to procurement cycles and episodic regulatory shifts. Rather than enumerating per-region or per-application dollar splits here, PW Consulting highlights the directional dynamics that purchasers and strategists must read into:
-
Demand drivers: aging surgical volumes, higher utilization of infection-risk procedures, and procurement emphasis on lifecycle cost (not just unit price).
-
Supply-side constraints: specialized antimicrobial chemistries and validated coating processes require tight supplier qualification and capacity planning.
-
Commercial pressure points: reimbursement and hospital purchasing protocols increasingly reward demonstrable reductions in infection metrics over marketing claims alone.
Practical Deliverables in the Full Report
PW Consulting’s full market study provides an integrated toolkit for 2026 execution. Highlights include:
-
Supply chain map from raw antimicrobial compound suppliers through sterilization partners and contract manufacturers, with critical-control-point annotations.
-
BOM decomposition logic that isolates cost levers (materials, sterile packaging, sterilization, coating throughput) for rapid scenario analysis.
-
Yield-adjustment models to quantify factory ramp trade-offs and sensitivity of cost-per-unit to process improvements.
-
Technology roadmaps that sequence likely antimicrobial agents, application processes, and sterilization compatibility over the 2026–2032 horizon.
-
Commercial playbooks illustrating Design-Win mechanics, hospital procurement pathways, and real-world contracting tactics.
Each tool is built to solve 2026 pain points — for example, reducing cost-per-procedure through targeted yield improvements, and de-risking compliance by cross-referencing claims substantiation pathways against current regulatory expectations. For practitioners seeking the full distribution charts and BOM line-item sensitivities, access the complete dataset here: Full Antimicrobial Suture Market Report .
Competitive Landscape — Dimensions that Determine Winners
Rather than publishing prescriptive 2026 plays for each company here, PW Consulting frames the competitive battlefield in terms of the strategic dimensions that consistently decide Design Wins and market share shifts. Companies compete across a combination of moats and operational excellence:
-
Clinical evidence moat — the ability to demonstrate infection-reduction in peer-reviewed or registry data.
-
Regulatory and claims defense moat — documented validation paths that survive scrutiny from regulators and procurement committees.
-
Supply-control moat — vertically integrated supply of key antimicrobial chemistries or secured long-term contracts with sterilization providers.
-
Cost-to-serve moat — low cost-per-procedure through manufacturing scale, automated application, or high yields.
-
Commercial access moat — entrenched relationships with IDNs, GPOs, and surgeons that translate into preferential product placement.
Design-Win success most often turns on a compact set of factors:
-
Ease of transition for surgical teams (handling, knot security, and device compatibility).
-
Clear, auditable claims that align with hospital infection metrics.
-
Total-cost narratives that include reduced SSI incidence and shortened LOS, supported by credible economic models.
Adjacent market moves — such as healthcare furniture manufacturers promoting antimicrobial coatings or full-line offerings — signal a macro-level procurement focus on environmental infection control. These cross-category developments affect how hospitals allocate hygiene budgets and may compress willingness-to-pay for single-item claims, reinforcing the need for sutures to articulate system-level value. For an in-depth competitive matrix and our proprietary scoring of the incumbent set, see the full report: Full Antimicrobial Suture Market Report .
Regulatory and Hospital-Protocol Dynamics
2026 regulatory context shapes both product development timelines and go-to-market proofs:
-
Regulatory bodies and public health guidelines demand validated claims and continued emphasis on cleaning and disinfection protocols rather than sole reliance on treated articles.
-
Manufacturers must demonstrate sterilization compatibility, shelf-life integrity, and resistance to routine hospital-grade disinfectants.
-
Procurement committees increasingly require third-party or registry-based outcomes data to accept premium-priced infection-control products.
These dynamics increase the up-front investment needed to commercialize new antimicrobial sutures but also raise the value of validated competitors that can shortcut buyer risk aversion. The net effect in 2026: the market rewards credible evidence and integrated infection-control narratives.
How PW Consulting’s Methodology Produces Decision-Grade Insight
Our research follows a layered triangulation approach designed to reduce single-source bias and to surface non-public operational signals that matter to investors and strategists. Method elements include patent-citation tracing to identify technology adoption patterns, structured interviews across procurement, CMO operations, and infection-control leadership, and proprietary customs and contract-flows scraping to detect subtle shifts in supply commitments.
We also conduct physical BOM teardowns in partnership with field labs to validate published claims and to model yield ceilings. These methods, combined with our curated hospital outcomes data partnerships and confidential executive interviews, enable PW Consulting to build defensible positionings without revealing confidential partner data in this briefing. Our approach is deliberately conservative in forward projection, prioritizing practicable scenarios for 2026 capital deployment over speculative upside.
Strategic Imperatives for 2026
For CEOs, CFOs and commercial leaders evaluating opportunities this year, PW Consulting recommends prioritizing three executable initiatives:
-
Locking early clinical partnerships that can deliver registry-level evidence within 12–24 months — clinical data is the gating factor for premium uptake in 2026 procurement cycles.
-
Investing in manufacturing yield and sterilization compatibility now to compress time-to-margin; our yield-adjustment models show modest process gains materially improve unit economics at scale.
-
Structuring commercial offers around total-cost-of-care outcomes rather than unit price, bundling sutures into broader infection-control contracts where possible.
Capital Deployment Checklist
When allocating capital in 2026, leaders should filter opportunities with these questions:
-
Does the target possess defendable clinical evidence or an expedited pathway to generate it?
-
Are key supply-chain choke points under contract or owned?
-
Can the product’s claims survive both regulatory scrutiny and procurement committee review?
Next Steps & Accessing the Full Intelligence
This briefing is intentionally diagnostic rather than fully prescriptive — our aim is to demonstrate the analytic depth you need to move confidently in 2026 while preserving the detailed, transaction-grade analytics for licensed clients. For the complete market maps, segment value ladders, BOM-level sensitivities, and our candidate M&A shortlist with valuation frameworks, please consult the full report at: Full Antimicrobial Suture Market Report .
PW Consulting remains available for board-level briefings, fast-track due diligence, and tailored scenario modeling to align your 2026 capital plan with the most probable market outcomes. Our combination of on-the-ground sourcing and quantitative modeling is built to reduce execution risk and to sharpen negotiation leverage in a market where evidence and supply security decide value.
For detailed analysis of this topic, please visit the official page: Antimicrobial Suture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Smartphone Cover Glass Market Set for a Modest 1.3% CAGR During 2026–2032
By PW Consulting, 2026-06-26
Smartphone Cover Glass Market: A 2026 Strategic Preview for Decision Makers
Executive snapshot
In 2026, the smartphone cover glass market stands as a mature, concentrated industry with measured growth. PW Consulting’s latest study benchmarks the market at USD 1,563.7 Million for the base year 2025 and models a conservative compound annual growth rate (CAGR) of 1.3% across the 2026–2032 forecast window, arriving at a projected market size near USD 1,711.7 Million by 2032. Historical data from 2020 through 2025 shows cyclical demand variability tied to device replacement timing, new form-factor launches and supply-side capacity shifts; our layered analysis captures these dynamics so investors and OEMs can prioritize capital and operational moves in 2026.
Smartphone Cover Glass Market
Why 2026 is a strategic inflection point
2026 is not a routine year for glass suppliers or electronics manufacturers. Multiple structural forces converge to change the calculus of sourcing, investment and product roadmaps:
- Supply-side reconfiguration: Strategic capacity additions and relocations are changing lead times and commercial leverage across geographies. Recent facility openings and production expansions from tier‑one suppliers are accelerating near‑shore options for major OEMs.
- Raw material volatility and cost pressure: Input markets such as soda ash show continued price sensitivity amid uneven global demand and regional production shifts; these movements indirectly amplify margin pressure across the value chain.
- Product complexity: The mainstreaming of foldable devices, ultrathin glass for flexible panels and hybrid ceramic chemistries increases BOM complexity and tightens manufacturing tolerances, forcing suppliers to rethink yield strategies.
- Regulatory and trade attention: Tariff measures and antidumping activity in adjacent sectors have spillover effects on glass supply chains, driving procurement sensitivity to compliance, traceability and dual-sourcing.
Market structure and competitive concentration
The market remains highly concentrated, with the top three and top five players controlling the majority of industry revenues. High concentration creates both opportunity and risk for buyers and capital allocators: suppliers with entrenched design wins and proprietary chemistries command pricing power, while alternative entrants face high technical and commercial barriers.
Key competitive dimensions we track (and model in the full report) include:
- Intellectual property and material science moats — patented chemical strengthening, ion-exchange processes and novel ceramic composites drive differentiation.
- Design wins and integration depth — long lead cycles for product qualification mean preferred suppliers capture recurring revenue streams across device generations.
- Manufacturing footprint and flexibility — regional production capacity, near‑shoring capability and versatile process lines determine responsiveness to OEM ramp cycles.
- Yield and process robustness — incremental yield improvements can meaningfully shift gross margins across the value chain.
Competitive commentary (selected companies)
Our report provides a mapped assessment of the incumbent supplier landscape; below are high-level observations on competitive vectors rather than prescriptive forecasts.
- Corning Incorporated — A leader in chemically strengthened and ceramic glass technologies, Corning’s strengths are deep material IP, long-standing OEM relationships and recent investments in localized capacity expansion. These attributes strengthen its ability to secure design wins in premium and foldable segments, and to respond to supply security demands from flagship customers.
- AGC Inc. — AGC’s Dragontrail portfolio positions it as a contender for Android OEMs seeking scratch resistance and flexible form factors. Its differentiated product family and regional manufacturing partnerships underpin competitive positioning in mid-to-high tiers.
- SCHOTT AG — SCHOTT emphasizes lithium‑aluminosilicate glass variants that target superior break resistance and optical performance for high-end devices. Technical credibility and specialty product focus are core competitive levers.
- Nippon Electric Glass (NEG) — NEG’s capabilities in ultra-thin glass (UTG) and chemically strengthened offerings make it strategically relevant for foldable and premium thin‑profile devices. UTG expertise becomes a structural advantage as foldables scale beyond niche volumes.
These firms compete along IP, manufacturing scale, qualification track record and supply resilience. For detailed company matrices, capability heatmaps and our proprietary scoring system, access the full competitive profiles and company strategy matrix: full competitive profiles and company strategy matrix .
Report toolkit — operational tools that matter in 2026
PW Consulting’s report is purpose-built to move from insight to action. Rather than generic market charts, the deliverables include practical instruments that buying, operations and strategy teams can apply immediately:
- Supply chain topology and risk maps — visualized tiers, single points of failure, and substitution pathways to support urgent dual-sourcing decisions.
- Reverse-engineered BOM and cost-driver logic — a reproducible framework for deconstructing cover glass cost elements, labor inputs and process-linked overheads to inform sourcing negotiations.
- Yield-adjustment and sensitivity models — scenario-ready templates to quantify how incremental yield improvements or raw material swings affect unit costs and margin at scale.
- Technology roadmap and qualification milestones — side-by-side timelines for glass chemistries, UTG and ceramic glass maturation that align R&D investment with procurement windows.
- Regulatory & compliance playbook — traceability templates and audit checklists tuned to 2026 trade and ESG expectations.
Each tool is delivered with a user guide that explains input sources and assumptions, enabling clients to run “what-if” analyses without relying on continuous external consultancy.
2026 pain points and how the report’s tools solve them
Procurement and product teams face three immediate operational pressures in 2026. For each, our toolkit presents a targeted capability:
- Cost control under input volatility — use the BOM logic and yield sensitivity models to quantify pass-through risk and to design hedging or buffer strategies.
- Supply security amid regional re‑allocation — apply supply chain topology maps to identify feasible dual-source paths and validate lead-time scenarios for near‑shoring options.
- Qualification risk for new form factors — align the technology roadmap with internal qualification pipelines and prioritize design-win activities based on our supplier scoring framework.
Industry signals and market micro‑drivers
Our ongoing price and shipment surveillance flags discrete signals that materially influence 2026 decisions:
- Raw material movements: Early‑2026 FOB commodity trends show softness in certain glass feedstocks amid overcapacity pockets; buyers should not assume stable input costs through the year.
- Production localization: Closure to customers of major suppliers’ new lines and facility openings is shortening supply chains for selected OEMs and increasing negotiation leverage for those partners.
- Trade policy spillovers: Tariff and antidumping actions in adjacent sectors create compliance overhead and make supplier selection more than a price exercise—traceability and legal diligence are non-negotiable.
Methodology — how we produce high‑confidence, non-public insights
PW Consulting’s analysis uses a layered triangulation methodology to derive granular market intelligence while preserving client confidentiality. Core pillars include:
- Patent and citation analysis — we map inventor networks and filing trajectories to infer R&D focus and likely commercialization timelines for material chemistries.
- Primary validation — confidential interviews with component suppliers, OEM procurement leads and production engineering teams provide on-the-record and off-the-record context for volumes and qualification pathways.
- Data triangulation — customs flows, factory capacity maps, reverse-engineered BOMs and high-frequency price scraping are cross-validated to reduce single-source bias and surface inconsistencies.
Combining these inputs with proprietary scoring algorithms yields insights that are not available in public filings alone, enabling clients to act on early signals with calibrated confidence.
Recommended strategic plays for 2026
Executives should consider a balanced portfolio of actions tailored to risk appetite and scale:
- Prioritize strategic design wins — invest engineering cycles early in the qualification path for promising chemistries and UTG to lock recurring volumes.
- Hedge supply and input risk — implement dual‑source contracts and inventory strategies informed by our supply topology maps and BOM scenarios.
- Target yield programs — run focused process-yield initiatives that, based on our models, offer outsized margin recovery versus pure price renegotiation.
- Embed compliance into procurement — expand supplier audits and traceability clauses to mitigate tariff and ESG exposure.
- Calibrate capital allocation — use the technology roadmap to time investments in specialty glass vs. commodity volumes, avoiding overcommitment to declining segments.
How to obtain the full report
PW Consulting’s full Smartphone Cover Glass Market report includes regional distribution maps, application breakdowns, detailed supplier financial proxies and executable templates referenced above. For access to the complete dataset, annexes and interactive models, visit our project page: https://pmarketresearch.com/hc/smartphone-screen-glass-market .
Final note for 2026 decision makers
In a low‑growth yet strategically charged market, incremental operational improvements and selective strategic moves yield disproportionate returns. The combination of concentrated supplier power, evolving product architectures and regulatory complexity means that 2026 will favor organizations that can translate high‑fidelity market intelligence into rapid procurement, qualification and yield actions. PW Consulting’s toolkit is designed to make that translation repeatable and auditable for executive teams preparing capital and sourcing plans this year.
For detailed analysis of this topic, please visit the official page: Smartphone Cover Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fire Sprinkler Heads Market Poised to Expand at 7.1% CAGR During 2026–2032 Forecast
By PW Consulting, 2026-06-26
Fire Sprinkler Heads Market — 2026 Strategic Briefing
PW Consulting publishes an executive briefing that positions the Fire Sprinkler Heads Market for strategic capital allocation in 2026. Our analysis shows the market has expanded from a documented base in 2020 to a base-year size of USD 300.0 Million in 2025 and is forecast to reach USD 483.0 Million by 2032 at a compound annual growth rate (CAGR) of 7.1%. These headline metrics understate a more complex reality: structural demand drivers, regulatory tightening, and raw-material volatility are re-shaping supplier economics and customer buying patterns now — not in some distant future.
Fire Sprinkler Heads Market
Why 2026 Is a Pivotal Year for Decisions
Several concurrent forces make 2026 a watershed for strategic moves in the fire-sprinkler value chain:
Fire Sprinkler Heads Market
- Regulatory acceleration — updates to NFPA standards in 2025–2026 increase inspection and maintenance obligations, raising lifetime service and compliance costs for owners and operators.
- Material-price uncertainty — steel indices that peaked in 2022 and continue to swing create cyclical cost pressure across fittings, pipe, and components.
- Technology-driven differentiation — ESFR, lithium-ion protection, and integrated detection-suppression systems are changing procurement criteria from unit price to total installed effectiveness.
- Market concentration dynamics — a mid-level concentration among leading manufacturers creates room for targeted design wins and regional specialists to capture share where distribution or service networks matter most.
Given these conditions, capital deployed in 2026 must prioritize resilience to cost shocks, certification agility, and the capacity to win installations where safety and operational continuity are paramount.
Practical Intelligence: What Our Report Contains
The report is structured to convert insight into executable options rather than abstract forecasts. Key operational modules include:
- Supply-chain map and supplier tiering: visibility to raw-material origin, lead-time hotspots, and second-source viability for critical components.
- BOM decomposition and cost-to-manufacture logic: a repeatable framework for translating material and labour inputs into unit economics adaptable to your factory footprint.
- Yield-adjustment and factory-throughput models: scenario tools that translate yield improvements and automation investments into margin and payback curves under multiple steel-price trajectories.
- Technical roadmap and approval-path matrix: cross-referenced product pathways for ESFR, quick-response, and lithium-ion-protection heads aligned with listing bodies and testing regimes.
- Installation and service economics: contractor cost models, spare-part flows, and maintenance frequency analysis under the 2026 NFPA editions.
Each tool is intentionally operational: procurement teams can use the BOM logic to negotiate supplier agreements, manufacturing leaders can test automation investments against yield scenarios, and compliance teams can prioritize retrofits based on inspection cycles mandated in 2026.
How These Tools Solve 2026 Pain Points
We map each module to a managerial pain point common to 2026 decision calendars:
- Cost control — BOM and yield models convert steel-price volatility into actionable hedging, sourcing, and factory-layout decisions without exposing proprietary assumptions in this briefing.
- Regulatory compliance — the approval-path matrix accelerates time-to-market for modified products under updated NFPA guidance, reducing time and cost to achieve design acceptance.
- Design wins and specification capture — supply-chain transparency and installation economics allow OEMs and contractors to structure bids that highlight lifecycle TCO rather than headline unit price.
- Service differentiation — maintenance-frequency analytics identify aftermarket revenue pools and show how remote monitoring and smart integration raise switching costs.
Competitive Landscape: Dimensions that Matter
The market’s competitive dynamics are defined more by capability clusters than by simple market shares. Our analysis focuses on the defensive and offensive levers firms use to win and sustain business:
- Manufacturing scale + automation moat: companies that have invested in robotic automation and high-yield assembly capture consistent cost advantages and faster lead times.
- Listing and approval moat: design wins for high-hazard applications hinge on testing records, third-party listings, and documented field performance under conditions such as refrigerated or high-bay storage.
- Channel and service moat: firms with broad service networks or installation capabilities convert retrofit work and inspection cycles into recurring revenue.
- Systems integration moat: vendors coupling detection, analytics, and sprinkler oversight create a data-dependent switching cost for building operators.
- Mechanical-installation advantage: providers of grooved-join systems or pre-fabricated assemblies win time-sensitive projects where labour productivity is a contracting differentiator.
Leading participants in the market each embody different mixes of these moats. For example, manufacturers with deep listings and storage-oriented ESFR platforms rely on test credentials and relationships with warehouse owners to secure design wins; integrated builders and service firms leverage nationwide installation networks to convert compliance-driven retrofits into bundled contracts; and advanced-component vendors rely on connected solutions to upsell monitoring and maintenance services.
Recent Industry Moves — Strategic Implications
Selective developments through early 2026 crystallize near-term strategic choices:
- New product introductions for high-ceiling storage and refrigerated environments shift design criteria for customers and reset acceptance thresholds among specifying engineers.
- Supplier price adjustments and upstream base-price changes create a read-across to possible margin compression unless offset by yield gains or contract pass-throughs.
- NFPA updates tighten lifecycle obligations — owners face accelerated inspection and replacement planning, increasing near-term demand for both new installs and aftermarket services.
These events rationalize three immediate priorities for 2026: (1) lock in material continuity through selectively contracted supply, (2) prioritize product listings and third-party validations that unlock high-growth applications, and (3) accelerate digital or automation projects that improve factory yield and field-service efficiency.
Research Rigor and Methodology
PW Consulting’s findings are built on layered triangulation and primary-source evidence. Our methodology combines:
- Patent and standards citation analysis to reveal innovation trajectories and compliance dependencies.
- Supplier and contractor interviews across 12 markets and dozens of plant audits to validate build practices and installation economics.
- On-site BOM teardown and reverse-engineering of representative assemblies to quantify cost levers and assembly yield drivers.
- Proprietary procurement-auction intelligence and distribution sales telemetry to estimate channel margins and price elasticity.
Triangulating these inputs with public filings, testing-lab records, and certifications enables us to estimate non-public variables — such as time-to-listing and installation win-rates — with higher confidence than single-source approaches. That rigor is what allows senior leaders to convert the report’s scenarios into board-level capital decisions for 2026.
Strategic Recommendations for 2026
Based on our operational modules and market dynamics, PW Consulting recommends executives prioritize three moves in 2026:
- Accelerate certifications and test programs that enable entry into high-growth application segments where ESFR and specialty protection are required.
- Invest in targeted automation and yield-improvement initiatives that provide defensible margin resilience against material-price swings.
- Design service models that monetize NFPA-driven inspection cycles, leveraging connected-monitoring features to convert compliance into recurring revenue.
Each recommendation is designed to be stress-tested in the report’s scenario tools so leaders can quantify paybacks under multiple cost and regulatory outcomes.
Access the Full Strategic Playbook
To execute against the 2026 imperative with precision — including access to our supply-chain maps, BOM models, and scenario calibrations — download the full report and dataset. Access the full dataset and strategic playbook: https://pmarketresearch.com/hc/fire-sprinklers-market .
Concluding View — Where Value Will Be Created
In 2026 the market is no longer a simple replacement cycle; it is a platform for value creation through compliance-enabled services, installation efficiency, and technology-enabled differentiation. The headline growth trajectory (2025 base USD 300.0 Million to 2032 USD 483.0 Million at 7.1% CAGR) underpins robust opportunity, but capturing value requires tactical work on supply continuity, certification pathways, and aftermarket monetization. PW Consulting’s report supplies the operational playbooks and tools executives need to convert that opportunity into measurable returns.
For detailed analysis of this topic, please visit the official page: Fire Sprinkler Heads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lipstick market to grow from USD 11.8 billion in 2025 to USD 17.1 billion by 2032 at a 5.5% CAGR
By PW Consulting, 2026-06-26
PW Consulting Insight Brief: Strategic Imperatives from the 2026 Lipstick Market Outlook
In 2026 the global lipstick market is at an inflection point. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — quantifies a return to structurally healthy growth: the market expands from USD 11.8 Billion in 2025 to an estimated USD 17.1 Billion by 2032, at a compounded annual growth rate (CAGR) of 5.5%. This trajectory reflects a confluence of premiumization, sustainable packaging adoption, ingredient-driven reformulation, and resilient mass-market demand. The following brief highlights the report’s strategic value for corporate leaders and investors preparing capital allocation, M&A and product roadmap decisions in 2026 — while inviting readers to consult the full report for the granular maps, segmentation tables and model outputs that underpin these recommendations.
Why 2026 Is a Pivotal Year for Capital Allocation
Several concurrent dynamics make 2026 a decisive year to commit capital or to pause and re-evaluate portfolios:
- Regulatory tightening: The FDA’s December 2025 draft guidance under MoCRA introduces formal procedures for mandatory recalls of cosmetics, raising compliance and litigation risk for nonconforming products in the near term.
- Ingredient constraints: State-level ingredient bans (including PFAS restrictions) and tightened impurity limits for heavy metals are driving accelerated reformulation programs across the industry.
- Cost pressure: Manufacturers report raw-material cost inflation — notably waxes and pigments — in the range of 20.0–25.0% over recent cycles, with paraffin reaching roughly USD 1.2/kg in North America by May 2026.
- Packaging and circularity: Refillable and recyclable formats are moving from novelty to procurement requirement in premium channels, evidenced by multiple packaging suppliers commercializing refill systems in 2025–2026.
These forces compress implementation timelines. Companies that align R&D, procurement and regulatory functions in 2026 will convert disruption into competitive advantage; those that delay will face elevated cost bases and market-access friction.
Market Trajectory — High-Level Picture (no segment leak)
Our high-level demand model shows that the lipstick market recovered strongly from the 2020–2022 period, rising from USD 8.5 Billion in 2020 to USD 11.8 Billion in 2025. The forecast to 2032 reflects differentiated growth pockets across product types, channels and regions; however, as a preview we do not disclose the report’s detailed regional or application splits here. Readers who require the full distribution maps, elasticities and scenario-by-scenario volume forecasts may download the complete dataset at PW’s portal: Access the full report .
Strategic Implications for 2026 Decision-Makers
For executives and investors, the report converts broad trends into actionable strategic priorities. Key implications include:
- Prioritize compliance-first NPD: New product development must integrate regulatory constraints up-front (formulation, testing and labeling) to avoid post-launch recalls that carry outsized commercial and reputational costs.
- Protect margins through BOM and yield redesigns: With pigment and wax inflation materially pressuring gross margins, targeted reformulation and yield improvements at scale are the fastest levers to defend EBITDA.
- Capitalize on refillable premiumization selectively: Premium brands that can deliver luxury tactile performance in refillable systems will command price premiums; mass-market channels will require cost-effective refill designs to justify SKU proliferation.
- Allocate M&A to capability gaps: Buyers should prefer targets offering validated supply-chain control (specialty wax sourcing, pigment partnerships), regulatory testing pipelines, or packaging IP for circular formats over simple revenue multiples.
Competitive Landscape — Dimensions of Advantage
The market’s competitive structure is moderately concentrated: the top three firms control roughly 45.0% of value, while the top five account for about 58.0%. That structure creates both defensive incumbency and persistent opportunity pockets for fast followers and niche specialists.
Across the leading players — from long-established luxury houses to mass-market conglomerates — PW Consulting’s analysis emphasizes the dimensions that determine 2026 outcomes rather than forecasting individual firm plays. Competitive success will be measured along several repeatable vectors:
- Formulation moat: Proprietary emulsion systems and pigment dispersion processes that enable color integrity with lower pigment loads are high-value defensibilities.
- Ingredient compliance and traceability: Firms with integrated supplier vetting, in-house testing or exclusive sourcing agreements reduce recall risk and accelerate market entry in regulated jurisdictions.
- Packaging design wins: Partnerships with refillable packaging suppliers and validated consumer acceptance testing shorten commercialization cycles for sustainable formats.
- Channel orchestration: Omnichannel execution — specifically performance in prestige retail and direct-to-consumer — determines launch velocity for premium SKUs; mass distribution scale remains indispensable for accessible ranges.
- Supply-security and backward integration: Control of specialty wax and pigment supply chains, or contractual holdbacks with primary suppliers, is a latent competitive asset in times of raw-material volatility.
These competitive dimensions are illustrated in the report through anonymized case-studies and win–loss archetypes that show how design wins are won and defended. For those seeking firm-level benchmarking and capability heat maps, please consult the detailed company dossiers in our full study: Download the comprehensive dossier .
Operational Playbook: Supply Chain and Manufacturing Tools
PW Consulting provides a practical operational toolkit in the report tailored to 2026 operational priorities. Core deliverables include supply-chain maps, BOM decomposition logic, yield-adjustment models and a technology roadmap that aligns formulation choices with packaging and regulatory strategy. Key utility points:
- Supply-chain map: Visualizes multi-tier supplier exposure for critical inputs, identifies single-source risk and quantifies lead-time elasticity — enabling prioritized dual-sourcing or strategic inventory hedges.
- BOM decomposition framework: Disaggregates cost-to-serve by input, process step and packaging, enabling targeted margin recovery without wholesale premiumization.
- Yield-adjustment model: Simulates how batch-level yield improvements and process variability reductions translate into contribution-margin gains at scale.
- Technology roadmap: Aligns formulation platforms with recyclable/refillable packaging timing and regulatory thresholds to minimize costly reworks.
These instruments are practical, not prescriptive. They show executives where to focus capex and operational rigor in 2026 — for example, whether to invest in continuous manufacturing upgrades, on-site analytical labs, or near-shore pigment blending capacity — while leaving final parameter tuning to your organization’s risk appetite and channel mix.
Regulatory and Raw-Material Context — Practical Risk Management
2026 presents an environment where regulatory action and raw-material dynamics materially affect go-to-market mechanics:
- MoCRA and recall procedures: The FDA’s draft guidance from December 2025 formalizes recall triggers and timelines, making pre-market diligence and certificate-of-analysis processes a near-term operational necessity.
- Ingredient bans and impurity caps: State-level PFAS restrictions and international impurity limits constrain formulation latitude and elevate testing cadence across the supply chain.
- Input-price volatility: Reported 20.0–25.0% swings in pigments and waxes over recent cycles, and spot paraffin price signals near USD 1.2/kg, necessitate hedging strategies and yield-focused manufacturing optimization.
Combining regulatory foresight with raw-material playbooks is the most reliable way to protect both market access and margin in 2026.
Methodology — How PW Consulting Generates Actionable, Non-Public Insight
PW Consulting’s findings are the result of layered triangulation and proprietary evidence collection designed to reduce forecast error and increase tactical utility. Our core methodological pillars include:
- Primary stakeholder interviews: Over 40 confidential interviews in 2025–2026 with formulators, packaging engineers, procurement heads, and retail merchandisers, executed under non-disclosure terms and anonymized for reporting.
- Proprietary transaction and trade-data reconciliation: We integrate customs flows, supplier shipment records and anonymized purchase-order extracts to validate supply-chain exposure and price trajectories beyond public filings.
- Patent and formulation citation analysis: We map innovation clusters through patent families and trade literature, identifying formulation and packaging IP that correlates with market penetration speed.
- Operational validation: On-site plant assessments and third-party lab results feed our yield and BOM models to convert qualitative risks into quantified margin impacts.
These methods allow PW Consulting to surface insight that is both defensible in boardroom debate and applicable on plant floors — without disclosing confidential client data or the proprietary model parameters included in our full deliverables.
Next Steps and How to Use the Report
Executives facing 2026 budget cycles should treat this moment as a window for prioritized investment: fund regulatory-readiness, secure critical raw-material pathways, and accelerate packaging-innovation pilots in targeted premium lines. For teams preparing board presentations, the PW report supplies scenario-ready P&L impacts, capex prioritization matrices and an M&A screening tool that links capability gaps to acquisition targets.
For access to the full dataset, regional and application splits, interactive dashboards and the operational playbook with editable models, visit our publication hub: Download the full Lipstick Market report .
For detailed analysis of this topic, please visit the official page: Lipstick Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


