



Category: Healthy Lifestyle
PW Consulting: Radiogardase Market to Reach $60.02 Million by 2032 with 4.2 Percent CAGR
By PW Consulting, 2026-09-01
Navigating the Radiogardase Market: Strategic Intelligence for 2026 and Beyond
The global preparedness landscape for radiological incidents is undergoing a quiet but critical transformation. As nuclear energy programs expand, industrial radiography activities intensify, and geopolitical tensions underscore the necessity of robust emergency response mechanisms, the demand for effective decorporation therapies has never been more pertinent. At the center of this niche yet vital sector lies Radiogardase, the primary pharmaceutical intervention for radiocesium and thallium exposure.
Radiogardase Market
PW Consulting is proud to introduce our latest comprehensive market research study, designed to equip stakeholders with the actionable intelligence required to navigate the complexities of the Radiogardase Market from 2026 through 2032. This report is not merely a collection of statistics; it is a strategic roadmap for decision-makers in government procurement, pharmaceutical manufacturing, healthcare logistics, and investment sectors. Understanding the trajectory of this market is essential for aligning supply chain resilience with national security priorities and commercial viability.
Radiogardase Market
Market Trajectory and Macro Economic Outlook
Our analysis begins with a robust examination of market performance over the past half-decade. Historical data from 2020 to 2025 reveals a consistent, albeit specialized, growth pattern. The market valuation has demonstrated resilience, moving from approximately 38.5 million USD in 2020 to a projected 45.0 million USD by the base year of 2025. This historical progression sets the stage for the forecast period, where we anticipate a steady compound annual growth rate of 4.2 percent.
Radiogardase Market
Looking ahead to 2032, the revenue trajectory suggests a maturation of the sector. The market is expected to climb from 46.75 million USD in 2026 to over 60.02 million USD by the end of the forecast window. Such growth is not driven by mass-market consumption but rather by the strategic accumulation of stockpiles, renewed regulatory focus, and the entry of new manufacturing capabilities in emerging regions. For executives planning capital allocation or government agencies managing budget lines for health security, these macro indicators provide the foundational confidence needed to commit to long-term procurement cycles.
It is crucial to note that this growth is underpinned by specific operational dynamics unique to the orphan drug status of Radiogardase. Unlike conventional pharmaceuticals, revenue streams are not solely dependent on routine prescription sales. Instead, they are heavily influenced by national stockpile replenishment cycles and institutional preparedness mandates. Our research dissects these nuances to ensure clients do not misinterpret revenue volatility as market instability.
Segmentation Dynamics: Channels and Applications
To truly leverage this market data, one must understand where value is being generated. Our report provides a deep dive into the distribution channels that sustain the ecosystem. The flow of product through government stockpiles versus clinical settings presents distinct challenges and opportunities. Institutions managing large-scale emergency reserves operate under different procurement protocols compared to hospitals and clinical settings involved in immediate patient care or specialized research.
Similarly, the indication landscape is segmented into radiological emergency response, industrial exposure management, and medical research applications. Each of these verticals carries different regulatory burdens, demand triggers, and pricing sensitivities. For instance, emergency response stockpiling is often governed by grant funding and national security directives, while industrial exposure management may be tied to occupational safety compliance in nuclear facilities. Our analysis highlights the strategic implications of these segments without oversimplifying the operational realities faced by supply chain managers.
stakeholders will find particular value in our breakdown of regional dynamics. The market is not uniformly distributed. Mature markets with established nuclear infrastructure exhibit different consumption patterns compared to emerging regions where new regulatory approvals are recently unlocking access. Understanding these geographical nuances is vital for manufacturers looking to expand their footprint and for distributors seeking to optimize logistics networks. However, the specific proportional breakdowns and regional revenue figures contain sensitive commercial intelligence that we reserve for our full report subscribers.
Competitive Landscape and Key Player Analysis
The Radiogardase Market is characterized by a high degree of concentration, reflecting the specialized manufacturing requirements and regulatory barriers associated with producing pharmaceutical-grade insoluble Prussian blue. Our competitive analysis identifies the key entities that define the supply landscape. HEYL Chemisch-pharmazeutische Fabrik GmbH & Co. KG stands as the primary manufacturer and marketer of Radiogardase®-Cs, producing 500 mg capsules for the decorporation of radiocesium and thallium. Their role is pivotal, serving as the anchor for the brand's availability in key Western markets.
In the United States, the distribution architecture is split to address different customer needs. Heyltex Corporation acts as the US distributor for institutional and government orders, having served this role since 2004. They function as the sole source provider for significant institutional acquisitions, making their supply chain reliability a critical factor for US strategic stockpile management. Conversely, for individual patient prescriptions, McGuff Compounding Pharmacy serves as the distribution point for physician-ordered cases. This dual-channel distribution model ensures that both mass emergency response and individual clinical needs are met, but it also introduces complexity in supply chain coordination that our report examines in detail.
On the manufacturing side, Haupt Pharma Wülfing GmbH, part of the Aenova Group, operates as a contract manufacturer for Radiogardase® capsules. Their involvement highlights the dependency of the market on specialized GMP facilities capable of handling the specific active ingredient requirements. The production of insoluble Prussian blue (ferric hexacyanoferrate(II)) is concentrated among few facilities, creating potential bottlenecks that procurement officers must anticipate.
Recent developments indicate a shifting competitive environment. In October 2025, Indian partners associated with INMAS (DRDO) achieved regulatory approval for Pru-Decorp™ and Pru-Decorp-MG. These formulations are equivalent to Radiogardase and are now commercially available in India following approval by CDSCO/DCGI. This entry marks a significant milestone in geographic diversification and may influence pricing dynamics and supply security in the Asia Pacific region. Additionally, in February 2025, HEYL updated the Summary of Product Characteristics for Radiogardase®-Cs, reflecting ongoing regulatory compliance and product lifecycle management.
Regulatory and Operational Dynamics
Operating in this space requires navigating a labyrinth of regulatory constraints. Radiogardase is available only by prescription in the US, a factor that limits commercial visibility but ensures controlled distribution during incidents. Its inclusion in the US Strategic National Stockpile underscores its status as a critical asset for homeland security rather than a routine retail product. This orphan drug status means the commercial market is inherently limited, and valuation is often driven by strategic value rather than pure sales volume.
Reimbursement models are equally specialized. Because the product is primarily stockpiled for radiological emergencies, routine sales are sparse. This affects cash flow projections for distributors and requires a different financial modeling approach than standard pharmaceutical products. Furthermore, the supply chain is sensitive to raw material constraints. Only pharmaceutical-grade insoluble Prussian blue is indicated for use, and research-use or non-pharmaceutical grade pigments must not be substituted due to safety risks. This strict requirement limits the supplier base to those with verified GMP compliance, reinforcing the barrier to entry for new competitors.
Our report details how these regulatory factors influence market behavior. We analyze the implications of prescription-only status on distribution latency, the impact of stockpile management on pricing stability, and the risks associated with raw material concentration. For investors and partners, understanding these non-market drivers is just as important as analyzing revenue forecasts.
Strategic Value for 2026 Decision Makers
Why is this research critical for 2026 planning? The answer lies in the intersection of preparedness and profitability. As the forecast period begins, organizations must decide whether to expand inventory, diversify supply sources, or enter new geographic markets. The approval of equivalent formulations in India, for example, opens new avenues for regional manufacturing but also introduces competitive pressure. Companies must assess whether to compete on cost, ally through licensing, or focus on niche high-value segments in mature markets.
Government agencies face the challenge of balancing budget constraints with the imperative of readiness. Our data helps justify procurement requests by projecting demand scenarios based on historical trends and geopolitical risk assessments. Manufacturers need to understand production capacity constraints and the lead times required to meet sudden spikes in demand triggered by news events or regulatory changes. Distributors must optimize their logistics to handle both steady institutional orders and sporadic individual prescription needs without compromising compliance.
Furthermore, the concentration of market power among a few key players means that partnership strategies are essential. For new entrants, the barrier to entry is high due to the specialized manufacturing requirements and regulatory hurdles. For existing players, the focus shifts to maintaining supply chain integrity and managing regulatory updates effectively. This report provides the intelligence needed to formulate these partnerships and mitigate risks associated with over-reliance on single sources.
What This Report Delivers
PW Consulting's Radiogardase Market research is structured to provide immediate utility. Beyond the top-line forecasts and CAGR figures, the document includes:
- Detailed profiles of key companies, analyzing their market position, capabilities, and recent strategic moves.
- An examination of supply chain vulnerabilities, specifically regarding the manufacturing of the active pharmaceutical ingredient.
- Analysis of regulatory landscapes across key jurisdictions, including US FDA directives and emerging approvals in Asia.
- Scenario-based forecasting that accounts for variable factors such as stockpile replenishment rates and emergency incident frequency.
- Insights into the distinction between emergency stockpile consumption and clinical prescription volumes.
We maintain a strict standard of data integrity. While we share the overarching growth narrative and total market valuation in this overview, the granular data required to build precise business cases—such as specific regional revenue breakdowns, segment-level market shares, and detailed distribution channel values—is reserved for the full report. This approach ensures that our clients receive unfiltered, high-fidelity intelligence without the dilution that occurs in public summaries.
Conclusion: Preparedness as a Strategic Asset
The Radiogardase Market may be niche, but its implications for public health and national security are profound. As we move into 2026, the convergence of geopolitical risk, nuclear energy expansion, and regulatory evolution creates a complex environment for stakeholders. Success in this sector requires more than just market awareness; it demands a deep understanding of the operational, regulatory, and logistical factors that drive value.
This research study serves as a cornerstone for that understanding. Whether you are a government procurement officer securing strategic assets, a pharmaceutical executive evaluating supply chain risks, or an investor assessing the viability of orphan drug markets, the intelligence contained within this report is tailored to support your objectives. We invite you to delve deeper into the data, access the full segmentation analysis, and leverage these insights to build a resilient strategy for the coming decade.
The future of radiological emergency response depends on informed decision-making today. PW Consulting is committed to providing the clarity needed to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Radiogardase Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Hemocoagulase Market Poised to Surpass USD 599 Million by 2032 with a 5.2 Percent CAGR
By PW Consulting, 2026-09-01
Strategic Intelligence for the Hemocoagulase Market: Navigating Growth Trajectory Through 2032
The global landscape for hemostatic agents is undergoing a structural shift, driven by expanding surgical volumes, evolving trauma care protocols, and the steady commercialization of biologic coagulation modifiers. Hemocoagulase, an enzymatic preparation derived from snake venom that accelerates fibrin clot formation, has transitioned from a niche hemostatic adjunct to a strategically relevant product class across multiple clinical segments. As the market moves beyond historical growth cycles, stakeholders require forward-looking intelligence that connects macroeconomic momentum with therapeutic adoption curves, regulatory evolution, and competitive positioning.
Hemocoagulase Market
This introduction to the Hemocoagulase Market research framework outlines the strategic questions that procurement leaders, commercial directors, and market access teams must address in 2026. Rather than offering isolated snapshots, the full study is designed to support actionable decision-making by linking demand drivers, formulation pathways, clinical usage patterns, and supply chain realities into a single analytical architecture. The purpose of this preview is to demonstrate the depth of the analytical approach while reserving the detailed quantitative segmentation, company-specific benchmarks, and scenario-based forecasts for the complete report.
Hemocoagulase Market
A Market in Structural Expansion
Over the past half-decade, the hemocoagulase sector has demonstrated consistent valuation growth, reflecting both sustained clinical utilization and the gradual broadening of procedural use cases. Historical expansion from the early 2020s through the base year has established a foundation of recurring demand, with recent annual valuations crossing the 400-million-dollar threshold and continuing upward as surgical throughput, hospital procurement cycles, and regional access programs mature.
Hemocoagulase Market
The forecast horizon extends through 2032, capturing a period in which formulation innovation, regulatory clearance pathways, and clinical evidence generation are expected to reshape purchasing behavior. The medium-term growth trajectory is supported by a compound annual growth rate of 5.2 percent, a pace that signals durable expansion rather than episodic volatility. Such an environment rewards organizations that can align supply planning, commercialization strategy, and clinical positioning with the evolving rhythm of demand rather than relying on static assumptions derived from a single fiscal year.
Importantly, the market structure is not homogenous. Growth is distributed across distinct formulations and clinical applications, each with its own adoption mechanics, procurement pathways, and risk considerations. A complete understanding of these dynamics requires segmentation analysis that captures how value shifts between injectable products and topical or powder formats, and how surgical hemostasis, trauma management, and clinical or dental settings contribute to total demand. The full report quantifies these contributions and explains the operational implications of each segment, without reducing them to simplistic share rankings.
Competitive Architecture and Strategic Positioning
The competitive environment in hemocoagulase is characterized by a concentrated core of established manufacturers alongside regional producers that serve specialized distribution channels. A small group of leading firms accounts for a substantial portion of total market revenue, underscoring the importance of understanding product differentiation, regulatory portfolios, and manufacturing continuity when evaluating partnership opportunities or competitive threats.
Chinese manufacturers dominate much of the production ecosystem, reflecting the country’s integrated biopharmaceutical capacity and the domestic regulatory framework supporting multiple approved hemocoagulase preparations. This includes bothropic-derived products used in surgical hemostasis and related formulations developed for broader coagulation management. Several of these companies maintain distinct commercial identities tied to specific brand positions, injection formats, and clinical communication strategies. At the same time, international activity continues to shape the market, with Indian-based producers advancing topical solutions for dental and minor surgical applications, and Hong Kong-linked enterprises maintaining positions in coagulation disorder management portfolios.
Competitive analysis in this research area must go beyond nameplate recognition. Different players operate with different venom-source dependencies, formulation strategies, and regulatory footprints, all of which influence supply resilience and price stability. The report examines how these structural factors affect each company’s ability to scale, adapt to regional registration requirements, and respond to changes in procurement specifications. Because the competitive balance is both concentrated and evolving, the full study provides a company-level assessment framework that helps buyers and investors evaluate long-term reliability, portfolio breadth, and the likelihood of market-share movement.
Formulation, Application, and Clinical Usage Dynamics
One of the most important strategic questions in this market concerns how demand is distributed between injectable solutions and topical or powder formulations. Injectable products remain central to controlled operative environments, where rapid and predictable hemostasis is essential. Topical and powder formats, by contrast, are expanding their relevance in settings where localized bleeding control is prioritized, including dental procedures and minor surgical wounds. Understanding the relative weight of these formats is critical for forecasting procurement requirements, inventory strategy, and clinical positioning.
On the application side, surgical hemostasis continues to anchor demand, reflecting the routine use of hemocoagulase across a wide range of procedures where bleeding management influences operative time, transfusion avoidance, and perioperative outcomes. Trauma management represents a distinct demand pathway shaped by emergency care protocols and pre-hospital or acute-care hemostatic needs. Clinical and dental applications, while smaller in aggregate scale, contribute to the overall growth rhythm by expanding the procedural footprint of hemocoagulase in outpatient and specialized care settings.
Clinical dynamics also bring important safety and monitoring considerations into strategic planning. Hemocoagulase use has been associated with the risk of hypofibrinogenemia, particularly where cumulative administration occurs, making fibrinogen monitoring a relevant concern for hospitals and formulary managers. This is not merely a clinical footnote; it influences procurement specifications, institutional adoption thresholds, and the way product information is positioned in competitive tenders. A thorough market assessment therefore integrates clinical risk management into commercial strategy, rather than treating it as a separate medical question.
Regulatory Landscape and Supply Chain Considerations
Regulatory frameworks play an outsized role in shaping market access and formulation approval pathways for hemocoagulase products. Multiple preparations, including bothropic and agkistrodon-derived variants, have been recognized for clinical use within China’s regulatory system, and these approvals affect both domestic procurement and the export positioning of manufacturers. At the same time, topical products in markets such as India are subject to packaging and distribution adjustments that can influence product availability, channel reach, and commercial pacing.
These regulatory elements are not static administrative details. They shape the speed at which new uses can be pursued, the breadth of approved indications, and the operational flexibility of manufacturers when demand shifts across regions or formulations. The report examines these pressures as part of a broader market dynamics framework, connecting registration status, labeling constraints, and regional distribution rules to commercial consequences.
Supply chain resilience introduces another layer of strategic complexity. Certain products depend on venom-derived raw materials sourced through specialized channels, which can create concentration risk within otherwise diversified manufacturing operations. While many producers have established reliable supply relationships, any disruption in toxin extraction, purification, or importation can influence production continuity and cost structures. In a market where clinical reliability and batch consistency are essential, raw material sourcing becomes a strategic variable, not just a procurement function. The full study maps these dependencies and their potential implications for product availability and competitive durability.
Recent Developments That Reshape Commercial Expectations
Recent activity across the sector illustrates how rapidly the operational environment can change. In late 2025, packaging and distribution amendments affected topical products in India, signaling ongoing regulatory attention to formulation presentation and supply-channel structure. Such changes may appear procedural at first glance, but they often precede broader adjustments in product reach, hospital stocking practices, and regional availability.
More clinically significant, research activity in 2026 has explored the intrapleural use of hemocoagulase in video-assisted thoracoscopic lung cancer surgery, highlighting expansion beyond conventional surgical hemostasis into specialized thoracic applications. This kind of clinical investigation is important because it can widen adoption pathways, introduce new procurement categories, and create fresh differentiation opportunities for manufacturers that can support evidence generation and institutional education.
For decision-makers, the lesson is that both regulatory adjustments and clinical exploration can alter demand expectations within a relatively short timeframe. A market study that ignores these developments risks being obsolete before it is read. The full report incorporates recent developments into both near-term momentum assessment and longer-term scenario planning so that organizations can anticipate change rather than react to it.
Why This Research Is Built for 2026 Decision-Making
The value of a market study lies not in restating obvious growth figures, but in providing a structured way to interpret them. Hemocoagulase demand is influenced by multiple interacting forces: procedural volume trends, formulation preference shifts, regulatory evolution, raw material constraints, concentration dynamics among leading producers, and emerging clinical applications. A useful analysis must bring these elements together in a way that helps teams make choices about sourcing, investment, pricing strategy, and market entry.
This research framework is designed with that objective in mind. It connects historical performance with forward projections, distinguishes between major formulation and application pathways, evaluates the competitive core and its vulnerabilities, and places regulatory and supply-side factors inside the commercial narrative. Just as importantly, it is intended to support decisions in a period when organizations need to plan for uncertain but directionally clear growth.
The complete report offers the detailed segmentation data, geographic allocation breakdowns, formulation share analysis, and company-level commercial profiles necessary to translate strategic questions into operational plans. Those specifics are deliberately reserved for the full document so that teams can evaluate the full analytical structure before committing to a purchasing or investment decision. In an environment where margins, availability, and clinical positioning are all tightly linked, having the complete intelligence set is not optional; it is a prerequisite for sound strategy.
The Strategic Takeaway for Boards, Buyers, and Investors
The hemocoagulase market is moving from steady expansion toward a more strategically contested phase, where formulation differentiation, regulatory agility, supply resilience, and clinical evidence will increasingly determine competitive outcomes. For organizations operating in this space, the central challenge is no longer whether demand exists, but how to position for the specific ways in which that demand will evolve across regions, applications, and product formats.
The full Hemocoagulase Market research report provides the analytical depth required to answer that challenge with confidence. It is structured to support procurement planning, commercial forecasting, competitive benchmarking, and investment evaluation by combining market-wide momentum with the segmenting detail that decision-makers need to act. For teams seeking to align their strategy with the 2026 growth environment and the years that follow, the complete intelligence package offers the missing bridge between high-level market direction and actionable execution.
For detailed analysis of this topic, please visit the official page: Hemocoagulase Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports 6.25% CAGR for Chelsea Bootie Market Through 2032 as Revenue Tops $3.25 Billion in 2025
By PW Consulting, 2026-09-01
Strategic Intelligence for 2026: Navigating the Evolving Landscape of the Chelsea Bootie Market
As senior strategists operating within a rapidly consolidating and sentiment-driven consumer goods sector, we have observed a distinct structural shift in how footwear brands are positioning heritage silhouettes for contemporary wardrobes. The Chelsea bootie, once a purely utilitarian staple, has matured into a cross-category hybrid that bridges casual comfort, everyday durability, and seasonal fashion relevance. With 2026 now fully underway, corporate decision-makers across retail, brand strategy, supply chain management, and private-label development require a diagnostic tool capable of translating granular market behavior into executable commercial roadmaps. The newly released PW Consulting market study on the Chelsea Bootie Market has been engineered precisely for that mandate, combining historical validation with forward-looking scenario modeling to support confident capital allocation, product roadmapping, and competitive positioning through 2032.
Chelsea Bootie Market
Earlier in the decade, the category benefited from pandemic-era lifestyle shifts that elevated slip-on comfort and low-maintenance footwear. By the 2023-2025 window, the market had stabilized into a more disciplined growth pattern, with total industry revenue climbing from a 2023 baseline and continuing to expand through the most recent historical year on record. The forecast interval extending into 2032 projects a steady annualized growth trajectory of approximately 6.25 percent, suggesting that underlying demand is no longer being driven exclusively by novelty or discretionary impulse, but by a more durable mix of style normalization, material preference evolution, and sustained product utility across age cohorts. Yet growth rates alone do not dictate strategy. The strategic value of this research lies in exposing where pricing power is being consolidated, how regional consumption rhythms differ in responsiveness, which material categories are absorbing margin pressure, and which competitive moves are beginning to reshape the category ceiling.
Chelsea Bootie Market
Why Macro Guidance Falls Short for Category-Level Decisions
Sector-wide footwear intelligence has notable limitations when applied to a specialized silhouette. Aggregate demand trends mask divergent elasticity between leather, suede and nubuck, and synthetic alternatives. Broad regional summaries obscure the fact that distribution channels, retail margin structures, and promotional intensity vary sharply even within mature markets. Category-level forecasts must also be interpreted through the lens of competitive concentration. The top three participants account for a measured share of total category revenue, while the top five expand that footprint to a modest but meaningful proportion of the overall market. This indicates a landscape that is neither fragmented beyond recovery nor dominated by a single price-setting champion. Instead, it reflects an industry where differentiation, product craftsmanship, and channel relevance still generate opportunities for strategic entrants, while scale players continue to defend volume through multi-brand portfolios and promotional cadence.
Chelsea Bootie Market
This is exactly the analytical gap our research was designed to address. The methodology does not treat the Chelsea bootie as a static SKU logic; it evaluates it as a living commercial construct shaped by material economics, craftsmanship positioning, seasonal color and finish cycles, gender-focused merchandising strategies, and consumer willingness to pay a durability premium. The resulting intelligence is intended for teams that need to decide whether to expand leather capacity, reposition suede offerings, engineer value-engineered synthetic variants, or adjust regional assortment depth ahead of the next fiscal cycle.
Translating Category Growth into 2026 Commercial Decisions
The 2026 operating environment introduces a combination of tailwinds and cost-side headwinds that directly affect product economics. Industry commentary from late 2025 and early 2026 points to tariff-related landed cost increases for imported footwear, with leather-based shoes facing additional duty exposure that has translated into expected price increases across the calendar year. Simultaneously, raw hide and skin price volatility has continued to influence U.S. leather market stability and production planning for footwear manufacturers. Analysts have noted that leather footwear and accessories prices may rise materially over the next one to two years as supply-side pressures propagate into finished goods. For leadership teams, these dynamics are not abstract input variables; they are profitability tests. The question is no longer simply whether demand for Chelsea booties remains resilient. The question is whether brands can protect margin curves through design constraints, material selection, sourcing geography, and tiered pricing strategies without eroding consumer appeal.
Our research integrates these operational realities with revenue trajectory modeling and competitive movement patterns. The forecast framework traces a forward path from the latest base-year valuation through 2032, providing a reference architecture for capacity planning, inventory policy, and assortment expansion. Importantly, the study avoids the temptation to reduce the category to a single growth narrative. Instead, it frames the market as a portfolio of interrelated segments where material mix, consumer orientation, regional consumption habits, and brand positioning interact continuously. Decision-makers are encouraged to think in terms of optionality: where organic volume can be captured, where premium pricing can be defended, where product refreshes must be timed to seasonal demand, and where sourcing transformations can reduce exposure to cost shocks.
What the Research Delivers: Executive-Level Diagnostics Across the Value Chain
The study was built to function as a working intelligence asset rather than a retrospective summary. It opens with a structured market definition and scope clarification so that internal stakeholders share a common vocabulary around what is and is not included in the Chelsea bootie category. From there, the report moves through a combination of historical analysis and forward modeling that supports scenario planning. The content architecture is designed to support multiple use cases, including brand portfolio planning, product development prioritization, distributor and retailer negotiation strategy, and competitive benchmarking.
- Detailed segmentation analysis that examines category behavior across material families, consumer orientation, and regional consumption rhythms, enabling teams to assess where volume concentration, pricing resilience, and product differentiation potential are aligned.
- A competitive landscape section that profiles leading participants, summarizes their design philosophies and merchandising emphasis, and connects brand-level strategy to broader market positioning so that strategic teams can identify white space, avoid head-on commodity competition, and evaluate partnership or acquisition logic.
- Material and sourcing dynamics analysis that interprets input cost pressure, supply chain volatility, and tariff exposure as strategic variables influencing margin structure, production scheduling, and product tiering decisions.
- Market structure assessment covering concentration indicators and competitive intensity, providing context for capacity planning, channel leverage, and the realism of share-gain ambitions.
- Forward-looking forecast building blocks for 2026 through 2032, enabling management to translate strategic assumptions into sensitivity discussions around volume, price, and mix.
- Historical context spanning earlier years to support trend interpretation, helping clients distinguish temporary distortions from durable shifts in consumer behavior and competitive tactics.
Each component is written with implementation in mind. The segmentation discussion is intended to inform line-planning decisions. The competitive synthesis is intended to support product roadmap debates. The cost and sourcing narrative is intended to help procurement and finance teams anticipate margin compression points before they become reactive cost-cutting exercises. Rather than leaving readers to assemble these threads independently, the study presents them as interlocking intelligence that can be used in executive reviews, category innovation sessions, and investment evaluation workflows.
Competitive Architecture: Craftsmanship, Style Continuum, and Channel Positioning
The competitive field in this category is defined by a wide spectrum of philosophies, ranging from rugged, weather-ready construction to fashion-forward platform interpretations, to premium handcrafted programs emphasizing ethical production and full-grain leather specifications. This diversity matters because it reveals where the category's value proposition is being interpreted differently by leading participants. Several Australian and European heritage-leaning players anchor their offerings in durability, water-resistant traits, and adaptable everyday styling, while multiple U.S. and UK-based labels compete on accessible pricing, classic silhouettes, and broader colorway options. Other brands emphasize premium finishes, lug-sole or platform variants, cushioning and fit benefits, or handcrafted construction with an emphasis on longevity and responsible sourcing.
This breadth of positioning means that the market is not merely competing on price; it is competing on how the product is framed to the consumer. Some labels position the Chelsea bootie as an everyday staple built to handle varied weather and regular wear. Others treat the silhouette as a fashion accessory with seasonal refresh potential and elevated visual identity. Still others use it as a commercial bridge between premium material craftsmanship and approachable retail economics. Strategic teams studying this landscape can draw a more nuanced conclusion: the most effective growth posture will likely come from matching product architecture to a clearly chosen value narrative, rather than trying to occupy every segment simultaneously.
Recent activity through early and mid-2026 reinforces the idea that the category remains in motion. In April 2026, one American-made manufacturer introduced a Chelsea boot with full-grain leather patterns and reinforced elastic gussets, signaling continued interest in enhanced construction details and durable daily-use engineering. In the same period, a handcrafted footwear brand promoted a Chelsea model with premium leather details, reinforcing the durability and material-quality angle that has become a recurring differentiator in higher-tier segments. Earlier in the 2025-2026 cycle, another label featured updated women's Chelsea models in its seasonal collections, highlighting continued refinement of fit, leather quality, and classic silhouette options. These moves are instructive because they demonstrate that innovation in this space is not always about radical design disruption. Often, it is about better execution within a familiar frame: stronger material choices, improved gusset or sole engineering, refreshed colorways, and clearer alignment with a target wearer profile.
Material Economics, Cost Exposure, and the Pricing Discipline Test
Material mix is one of the most consequential strategic variables in this category because it directly shapes perceived value, elasticity, and exposure to input price volatility. Leather continues to occupy a leading revenue share within the broader material breakdown, while suede and nubuck command a substantial portion of consumer interest, and synthetic or faux leather options represent an important value and accessibility tier. This distribution is strategically significant. It means that luxury-leaning positioning, durability claims, and tactile appeal can still be monetized through natural material narratives, but it also means that cost-side shocks in hide and leather sourcing can reverberate through margins if supply chain planning is not proactive.
At the same time, consumer segmentation shows a meaningful balance between women's and men's demand, with an additional unisex and children segment contributing a smaller but relevant share of category activity. This mix has planning implications. Women's footwear demand has historically supported broad stylistic experimentation, platform variation, and seasonal color rotation, while men's demand often emphasizes durability, comfort, and consistent everyday utility. Unisex and children demand introduces another layer of complexity around sizing, material durability, and price sensitivity. The study's segmentation treatment is designed to help brands evaluate whether they are over-indexing on a single demand center and under-serving adjacent opportunities, or whether a more diversified consumer strategy would improve seasonal resilience and reduce dependence on any one promotional cycle.
Regional dynamics further complicate product economics. Consumption patterns, retail formats, weather-related usage, and channel structures differ enough across major geographic zones that national or continental averages cannot safely substitute for category-specific regional intelligence. The research approach keeps regional analysis at a level of detail that supports assortment planning and pricing logic without exposing sensitive competitive benchmarks prematurely. For 2026 planning, this matters because a brand's ability to set appropriate price points, select the right material mix, and determine shipping and inventory timing depends on understanding where the category behaves as a seasonal fashion item versus where it functions more as a durable everyday purchase.
How Leadership Teams Should Use the Study in 2026
The research was structured to serve as a briefing asset for multiple internal audiences. For executive leadership, it offers a defensible view of category direction and the strategic questions that should govern investment choices. For brand and product teams, it provides segmentation context that can inform next-cycle design priorities, material selection decisions, and color and finish strategies. For commercial and supply chain leaders, it frames the cost environment in a way that makes pricing and sourcing decisions more anticipatory and less reactive. For competitive strategy and corporate development teams, it supplies a structured view of the key participants and their positioning logic, which supports share-gain assessment, partnership evaluation, and brand acquisition screening.
Several practical applications can be derived directly from the study's design. Teams can use the segmentation framework to test whether a proposed product line extension is genuinely differentiated or merely redundant within an already crowded value tier. They can use the cost and dynamics narrative to stress-test margin assumptions under different tariff and raw material price scenarios. They can use the competitive profiles to identify where a brand's craftsmanship story, material emphasis, or channel strategy may be misaligned with the consumer expectation it is trying to capture. And they can use the forecast architecture to translate strategic assumptions into discussable scenarios for 2026 planning and beyond.
The strategic value of this intelligence is not that it provides a single correct answer. The value is that it reduces ambiguity in a market where ambiguity is expensive. When input costs are volatile, tariff exposure is rising, and competitive players are refining their product stories around durability, fit, color variety, or premium finish, the organizations that perform best will be those that can integrate category behavior, material economics, and competitive movement into one coherent plan. The Chelsea Bootie Market research is built to help them do exactly that.
The Full Intelligence Package Awaits Direct Access
The overview presented here is intended to demonstrate the depth and structure of the analysis without disclosing the most actionable benchmarks, segment-level figures, regional revenue shares, and material- or consumer-specific breakdowns that form the backbone of the complete study. Those reserves are deliberate. In a market where pricing, sourcing, and assortment decisions require precision, the value lies not merely in directional narratives but in the verified quantitative and qualitative scaffolding underneath them.
The full PW Consulting report details the segmentation architecture, competitive positioning synthesis, market structure indicators, and forecast framework that can support product planning, pricing strategy, channel decisions, and corporate-level investment logic for the 2026 cycle and the years that follow. For teams responsible for converting market uncertainty into executable strategy, the complete study provides the level of specificity required to move from observation to action. The detailed breakdowns, scenario parameters, and competitive diagnostics described only in summary here are available in full within the complete research package, and they are designed to be immediately useful for cross-functional planning.
For organizations that need a rigorous, commercially oriented lens on the Chelsea Bootie Market as it stands in 2026, the research offers a ready foundation for that work. The goal is not simply to observe category expansion in aggregate terms, but to support decisions that capture the right mix of volume, price, and differentiation in a category shaped by craftsmanship narratives, material economics, and continuously shifting competitive moves. Detailed market intelligence of this kind is most valuable when it is applied early, before planning windows close and before cost headwinds become normalized cost expectations. Access to the full report gives decision-makers the precision they need to operationalize those insights with confidence.
For detailed analysis of this topic, please visit the official page: Chelsea Bootie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Pillar Padding Market to Reach 521.05 Million USD by 2032 Growing at 5.85 Percent CAGR
By PW Consulting, 2026-09-01
Strategic Padding for 2026: Navigating the Pillar Protection Market
The built environment places lives in the balance every day. Columns, beams, and exposed structural elements in high-traffic indoor and outdoor spaces demand protection that is both visible and durable. Pillar padding has evolved from a niche safety aftermarket into a strategic procurement category that intersects with facility design, risk mitigation, compliance, and total cost of ownership. For executives planning capital projects, renovation cycles, and portfolio risk strategies in 2026, the question is no longer whether structural padding is necessary, but how to select the right materials, partners, and specifications at scale. This new market research from PW Consulting frames the pillar padding sector as a disciplined growth story, anchored by consistent expansion, a maturing competitive field, and a regulatory tailwind that is reshaping procurement standards across multiple end-use environments.
Pillar Padding Market
Our analysis is built for decision-makers who need more than headline figures. The report translates macro momentum into operational discipline, mapping how material economics, specification trends, and competitive positioning converge to influence bid outcomes, project timelines, and long-term maintenance exposure. The following preview outlines the strategic architecture of the study and why it is designed to support 2026 planning with precision rather than approximation.
Pillar Padding Market
Market Architecture and Growth Trajectory
The pillar padding market has established a durable upward path over the historical window from 2020 through 2025, with revenue scaling from approximately $275.0 million to $350.0 million. This trajectory reflects not a cyclical spike but a structural shift in how facilities managers, project developers, and safety officers approach impact protection. Looking forward, the forecast window from 2026 to 2032 projects sustained expansion, with the market moving toward the mid-$500 million range by the end of the outlook period. The compound annual growth rate during this forecast horizon stands at 5.85, signaling a business that is growing faster than general construction spend while remaining disciplined enough to reward operators who invest in product differentiation, specification expertise, and compliant surface technologies.
Pillar Padding Market
A market growing at this pace typically rewards buyers and suppliers who focus on three levers: specification clarity, material performance, and lifecycle cost signaling. In practice, that means procurement teams are increasingly weighing not only unit pricing but also fire-rated surface compliance, impact absorption consistency, installation labor reduction, and long-term durability under repeated loading. The research captures these decision drivers and connects them to the broader revenue curve, helping readers understand how incremental specification choices compound into portfolio-level outcomes.
Importantly, the report is structured so that strategic readers can trace where growth is being generated without being given away the exact weighting of every segment. The teaser approach is deliberate. Executives should be able to trust the rigor of the modeling and the credibility of the narrative before they commit to deeper engagement. For that reason, this preview discusses directional patterns and decision logic, while reserving the full segment breakdown, regional revenue distribution, and application-level shares for the complete report.
Segmentation Logic and Strategic Implications
The pillar padding market is organized around three analytical dimensions that matter directly to purchasing and project planning. The first is type, where product architectures range from flexible foam-plus-cover systems to coated variants and high-density foam options. Each type answers a different operational requirement: some prioritize impact attenuation and visual consistency in athletic and recreational settings, others emphasize durability and cleanability in industrial environments, and a third group focuses on high-load protection in spaces subject to vehicle or equipment contact. The second dimension is region, which shapes procurement timing, specification preferences, code priorities, and the balance between domestic production and import reliance. The third dimension is application, which determines the performance envelope, installation constraints, and compliance expectations that suppliers must meet.
Strategically, segmentation is not just descriptive. It is the lens through which buyers identify where to standardize and where to customize. A facility portfolio with a mix of sports venues, warehouse interiors, and parking structures cannot treat pillar protection as a single specification. The report provides frameworks for mapping application requirements to product families, enabling procurement leaders to align standardized base specifications with local customization where it matters most. In doing so, it supports a more efficient trade-off between cost control and risk reduction.
From a supplier perspective, segmentation also reveals where competitive differentiation is actually achievable. Generic padding solutions face price pressure, but differentiated offerings with predictable fire-rated performance, tailored geometry fitting, and strong installation support can command more resilient margins. The research examines how leading players position themselves across these segments and what that implies for buyers evaluating bids in 2026.
Competitive Landscape and the Discipline of Differentiation
The competitive field is concentrated but active. The market exhibits a meaningful degree of fragmentation, with the top three participants accounting for roughly 28.5 percent of revenue and the top five extending to about 35.2 percent. This structure suggests that while scale players set important price and specification benchmarks, a broad second tier of specialists competes effectively through custom geometry, application-specific engineering, and regional reach. In such a landscape, procurement decisions are rarely about choosing the only available supplier. They are about matching supplier capabilities to project-specific requirements and compliance demands.
Several established manufacturers illustrate how this competition is playing out on the ground. Resilite Sports Products, headquartered in Northumberland, Pennsylvania, is known for custom structural padding, column wraps, and pillar padding built for sports facilities, gyms, and athletic venues using high-performance foam and vinyl coverings. That product orientation reflects a broader industry pattern: in recreational and athletic environments, buyers prioritize impact absorption, appearance consistency, and the ability to match wall and floor aesthetic systems.
Mancino Mats, operating in the United States, focuses on custom pole, pilaster, I-beam, and column padding for gym wall systems. Their approach highlights the importance of geometry flexibility and compatibility with existing wall padding aesthetics. In practice, this means suppliers are not just selling protection, they are selling integration. The more seamless the fit between padding systems and surrounding surfaces, the lower the installation friction and the higher the perceived specification value.
CoverSports, based in Philadelphia, offers L-shaped corner, column, beam, and pole padding solutions for indoor gym facilities using EnviroSafe padding materials. The emphasis on corner and specialty geometry is significant because corners and transitions are common points of impact and complaints in occupied facilities. Products that address these difficult zones cleanly can become anchor items in a broader safety specification.
Greatmats, also U.S.-based, supplies custom column pads and pole padding for gyms, playgrounds, and sports areas in a range of shapes, including round, square, and I-beam. Their catalog breadth underscores a market reality: a substantial share of procurement complexity comes from non-uniform structural forms. Suppliers that can standardize across multiple shapes without sacrificing fit tend to reduce change orders and installation delays.
On the compliance side, Sportsfield Specialties, headquartered in the United States, provides indoor column padding with high-quality foam and Class A fire-rated vinyl for schools, gyms, and sports facilities. This positioning is especially relevant given that many pillar padding products now use Class A fire-rated vinyl coverings to meet facility safety standards. In 2026, specification writers and safety officers are increasingly treating surface fire performance as a baseline requirement, not a premium add-on. That regulatory pressure strengthens the case for suppliers who can document compliance clearly and consistently.
The international side of the field includes specialist manufacturers such as Safety Padding in Dewsbury, West Yorkshire, which concentrates on carpark pillar padding, industrial post padding, and custom protective padding for pillars and columns. Bishop Sports and Leisure, based in Slough, offers pillar safety pads and protective sports equipment padding, while MMA Matting in Ashton-Under-Lyne produces round post pads and related protective matting solutions. Together, these firms illustrate how regional specialization and application focus remain viable even in a market with visible consolidation at the top.
Recent company activity reinforces the operational pace of the sector. In November 2025, Greatmats completed a pole padding installation to enhance safety at a community service facility, demonstrating how specification decisions translate directly into site-level risk reduction. Earlier in the year, Resilite emphasized wall and structural padding solutions for athletic facilities with a focus on impact absorption, while Greatmats expanded its guidance for pole padding selection across round, square, and I-beam column shapes. These developments matter to buyers because they signal which suppliers are actively refining product guidance, expanding footprint solutions, and aligning marketing with real project deployment.
Raw Material Economics and Cost Discipline
Specifying pillar padding in 2026 requires attention to input economics as much as to finished product features. Polyurethane-based systems still dominate important parts of the market, and managers need to understand how feedstock pricing and producer-level indices influence both unit costs and negotiation leverage. Market intelligence indicates that polyurethane prices in North America were around $3.34 per kilogram in May 2026, up 3.1 percent from the prior period, while the U.S. Producer Price Index for polyurethane foam formed and slab stock sat at 159.343 in April 2026, broadly stable from previous months. At the trade level, polyurethane FOB pricing in the United States was reported at $5,630.00 per metric ton in March 2026.
These numbers do more than quantify cost. They shape the negotiation environment. A modest upward movement in raw material pricing can compress supplier margins unless absorbed through scale, specification optimization, or disciplined contract timing. For buyers, the strategic response is to avoid one-dimensional price shopping and instead evaluate total delivered cost, including installation labor, rework risk, and replacement cycle expectations. Suppliers that can demonstrate stable production economics, predictable lead times, and material transparency position themselves as lower-risk partners in a market where raw material volatility can otherwise erode project budgets.
The report integrates this input-side intelligence with segmentation and competitive context so that readers can understand where cost pressure is likely to show up first and how to structure procurement accordingly. The goal is to convert macro commodity awareness into practical sourcing discipline.
Regulatory Dynamics and the Compliance Multiplier
Safety standards are a powerful force in this market, and pillar padding is one of those product categories where compliance directly influences specification adoption. Fire-rated surfaces, impact performance, and material durability are no longer optional refinements for many projects. They are baseline expectations, especially in schools, gyms, parking structures, and shared-use facilities where liability exposure and occupancy density are high. The increasing reliance on Class A fire-rated vinyl coverings is a clear example of how regulation and best practice are converging.
From a strategic standpoint, compliance is both a constraint and an opportunity. It constrains suppliers who cannot document their materials and finishes consistently. But it also creates a barrier to entry for undifferentiated competitors and rewards companies that can prove performance across multiple code frameworks. For buyers, the implication is straightforward: a clear, documented compliance profile reduces project risk, speeds approval cycles, and strengthens the business case for protective padding as part of responsible facility design. The research examines how compliance expectations are reshaping bidding behavior, specification language, and the relative attractiveness of different product families.
Read the Full Research for 2026 Decision Readiness
This preview is deliberately structured as a strategic teaser. It establishes the analytical frame, the competitive logic, and the material and regulatory context that matter to planners heading into 2026. What it does not do is reveal the full segment revenue distribution, the precise regional shares, or the detailed application-level splits that executives need to support budget modeling, bid strategy, and portfolio optimization. Those granular insights are central to the complete study and are reserved for readers who want to move from directional confidence to operational precision.
The full report is built for practical use. It takes the market trajectory from 2020 through 2025, extends the forecast to 2032, and connects those numbers to the decision points that procurement, project development, and risk management teams face today. It evaluates how top-tier and specialist suppliers compete, how material costs influence negotiation dynamics, and how compliance expectations are changing specification baselines. It also provides the framework needed to interpret where growth is being generated and how to align purchasing strategy accordingly.
If your planning horizon includes facility protection, retrofit programs, sports and recreational build-outs, industrial safety upgrades, or parking and structural risk mitigation, the pillar padding market deserves a more disciplined read than headline growth figures can provide. The complete version of this research delivers the segmentation detail, competitive intelligence, and cost and compliance context necessary to support confident decisions. Access the full market study to turn this preview into an actionable strategic plan for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pillar Padding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Veterinary Speculums Market to Reach 263.8 Million USD by 2032 with 5.2 Percent CAGR
By PW Consulting, 2026-09-01
Strategic Outlook for the Veterinary Speculums Market: 2026 and Beyond
As veterinary care evolves toward more precise diagnostic capabilities and specialized procedural interventions, the instruments that enable clinicians to see, access, and treat have become an increasingly strategic segment of the broader animal health supply chain. The Veterinary Speculums Market represents one such foundational category, serving as a critical enabler across small animal clinics, large animal and equine practices, and specialized surgical centers. Our newest market intelligence report offers decision-makers a comprehensive, data-grounded view of how this segment has matured, where it is heading, and what structural shifts will shape competitive positioning through the end of the decade.
Veterinary Speculums Market
This article previews the strategic architecture of the study, outlines the analytical depth embedded within the full research, and explains how executives can translate the findings into actionable planning for 2026 and the forecast horizon that follows.
Veterinary Speculums Market
Why Veterinary Speculums Deserve Boardroom Attention Now
For decades, veterinary instrumentation was treated largely as a commoditized procurement category. That assumption is increasingly misaligned with on-the-ground realities. Clinics and hospital networks are expanding procedural volumes, investing in advanced diagnostic workflows, and facing rising expectations from pet owners and livestock operators alike. In that environment, the quality, standardization, and supply reliability of core instruments such as speculums become operational differentiators rather than back-office line items.
Veterinary Speculums Market
The category spans multiple anatomical applications and animal classes, from oral examination tools to vaginal and otoscopic speculums used across companion and production animals. This diversity creates a complex purchasing landscape in which procurement teams must balance clinical performance, material durability, instrument standardization, and supplier consistency. A fragmented supply environment and varied product specifications further complicate category management, making disciplined market intelligence indispensable for both suppliers and large-scale buyers.
Our report was designed to cut through that complexity. Rather than offering surface-level snapshots, it maps the underlying demand drivers, supply-side constraints, competitive behaviors, and clinical-design trends that determine which players can scale profitably and which buying organizations can secure dependable access to high-quality instruments.
Market Trajectory: A Structural View of the Category’s Expansion
The overall market for veterinary speculums has followed a resilient expansion path over the past several years, shaped by steady clinical adoption, ongoing replacement cycles for consumable and reusable instruments, and gradual professionalization of veterinary service delivery. Historical valuation data for the 2020-2025 period reflects a market that navigated pandemic-era disruptions, supply-chain volatility, and shifting clinical priorities, before returning to a more predictable growth cadence as veterinary operations stabilized and reinvestment accelerated.
From a strategic planning perspective, the forward-looking trajectory is equally important. The forecast period extends through 2032, providing sufficient runway to evaluate capacity planning, product-development roadmaps, partnership opportunities, and entry or expansion decisions. Growth is expected to continue at a measured but durable pace, supported by ongoing procedural demand, clinic formation in developing markets, and incremental upgrades in instrument quality and standardization.
For executives, the central takeaway is not merely that the market is expanding, but that the composition of that expansion is shifting. Demand is not being driven by a single region or a single application. Instead, growth is distributed across multiple clinical settings and geographies, each with its own procurement rhythms, regulatory environment, clinical preferences, and competitive intensity. Understanding where volume concentrates, how substitution risks behave, and which design features are becoming table stakes is essential to building durable pricing power and supply resilience.
It is also worth noting that the category remains moderately fragmented at the top of the competitive hierarchy. The leading group of manufacturers and distributors does not command an overwhelming share of total market revenue, which means that newer entrants, specialized product innovators, and well-positioned regional players can still carve out meaningful positions if they align closely with clinical workflows and procurement expectations. For buyers, that fragmentation can translate into negotiation leverage but also into the challenge of standardizing instrument portfolios across locations, brands, and service requirements.
What the Full Report Delivers: Operational Intelligence, Not Just Headlines
Our research is built around the kinds of questions that actually drive procurement, product strategy, and competitive positioning. Rather than stopping at aggregate market size and growth rates, the report translates those macro signals into structured operational insight. The study is organized to help teams move quickly from awareness to action, with each section designed to inform a specific business decision.
Key areas covered include:
- Structural market sizing and forward demand modeling that establish the baseline trajectory of the category and the relative scale of its principal demand centers.
- A segment-level framework that examines how different instrument types and clinical applications contribute to overall demand, helping teams understand where specification and performance requirements vary most.
- A regional view that maps demand intensity and procurement characteristics across major geographic zones, providing context for distribution strategy, localization decisions, and supply-chain prioritization.
- A competitive landscape assessment that profiles leading manufacturers and distributors, evaluates their market positioning, and highlights the strategic implications of differing business models, product portfolios, and geographic footprints.
- An evaluation of the forces shaping market dynamics, including material selection, sterilization compatibility, product design conventions, clinical adoption patterns, and the regulatory environment governing animal-use devices.
- Recent innovation signals within the category, including novel instrument designs and clinical evaluation work that point toward the next generation of veterinary speculum functionality.
- Practical guidance for strategic planning, including implications for capacity planning, category management, product differentiation, partnership selection, and risk mitigation.
Each section is written to be usable in internal planning discussions. The report connects market data with procurement realities, clinical design considerations, and competitive behavior so that readers can assess not only what is happening, but why it matters to their own operating model.
Competitive Landscape: Strategy, Positioning, and the Battle for Clinical Relevance
The competitive environment in veterinary speculums is shaped by a blend of established instrument manufacturers, specialized veterinary equipment suppliers, and general surgical instrument companies with veterinary-facing product lines. The category rewards firms that can pair material reliability, design practicality, and dependable supply with clinical familiarity and strong distribution reach. In that respect, competitive advantage is less about volume alone and more about how effectively a company translates product quality and service reliability into repeatable procurement relationships.
Several companies stand out as important reference points in the competitive map. GerVetUSA Inc. has built a manufacturing-oriented presence around German-forged veterinary surgical instruments, with speculums designed for both small and large animals. Its positioning reflects a broader theme in the market: the emphasis on material quality and build consistency as a basis for clinical trust and repeat ordering. Jalal Surgical operates from a different geographic and manufacturing base, emphasizing high-quality veterinary speculums, including vaginal designs made from premium materials. Its profile underscores the importance of regional manufacturing capabilities and price-to-quality positioning in markets where procurement teams weigh durability against total cost.
Sklar Surgical Instruments contributes to the category through surgical instrument expertise that extends into veterinary applications, including vaginal speculum designs suitable for animal use. Jorgensen Laboratories, under its JorVet brand, offers specialized veterinary instruments with designs tailored to canine and large-animal examinations, reinforcing the role of application-specific product engineering in building clinical preference. Welch Allyn, now associated with Hillrom, brings an established diagnostic-instrument heritage into the veterinary space through reusable specula compatible with otoscopes, including bivalve and multiple size options. That background illustrates how companies with strong human healthcare or diagnostic-tool legacies can translate design credibility and standardization into veterinary settings.
Surgical Holdings operates from the United Kingdom with a focus on stainless steel obstetrical and vaginal speculums for large animals, highlighting the continued importance of large-animal and equine applications in the broader category. Medline Industries supplies reusable veterinary specula and other diagnostic instruments, positioning itself as a broad-based medical supplies provider with relevance to veterinary procurement workflows. Together, these players demonstrate that the competitive field is not monolithic. Some companies compete on specialized veterinary design expertise, others on manufacturing quality, and others on distribution breadth and institutional procurement relationships.
The strategic implication for both incumbents and challengers is that product portfolios cannot be treated as interchangeable catalogs. Clinical audiences differentiate based on animal class, examination type, sterilization requirements, instrument handling characteristics, and the predictability of supply. Companies that align their product strategy with those expectations, and that support them with consistent manufacturing and distribution, are better positioned to defend share and expand into adjacent application areas. For buyers, understanding these distinctions enables better specification choices and more effective category management across sites and service lines.
Industry Dynamics: Materials, Regulation, and Design as Strategic Levers
Several structural factors shape how the market behaves and how competitively positioned players can differentiate themselves. First, material performance continues to anchor purchasing decisions. Veterinary speculums are primarily manufactured from surgical-grade stainless steel, a choice driven by the need for corrosion resistance and suitability for frequent autoclave sterilization. In practice, that means instrument longevity, cleaning reliability, and tolerance for repeated sterilization cycles are not optional features; they are baseline expectations. Suppliers that fail to meet those standards risk rapid erosion of trust in clinical environments where instrument downtime and contamination risk are unacceptable.
Second, the regulatory environment for animal-use devices creates a distinct market dynamic. Unlike human-use equivalents, veterinary speculums are generally not subject to FDA premarket notification requirements. That difference reduces a layer of regulatory friction and can accelerate product introduction and iteration. At the same time, it shifts more of the quality-assurance burden onto manufacturers and buyers, who must rely on material specifications, design validation, sterilization compatibility, and clinical reputation to ensure consistent performance. For companies, that environment rewards disciplined manufacturing controls and transparent product documentation. For procurement teams, it makes supplier evaluation and specification management more important than ever.
Third, product design conventions are becoming a meaningful source of differentiation. Common instrument configurations have become familiar within veterinary workflows, and those conventions influence purchasing behavior and clinical adoption. For example, certain large-animal designs rely on multi-blade configurations with adjustment mechanisms suited to broader anatomical access, while specific canine vaginal examination designs incorporate locking or set-screw features to help maintain stable visualization during procedures. Over time, these familiar configurations can become de facto standards within particular practice types, making change management and clinical education important considerations for any supplier seeking to introduce a new design or displace an incumbent specification.
Innovation in the category is also beginning to reflect more targeted clinical needs. Recent development work has explored novel speculum designs intended to improve visualization and retraction in specific animal populations during transcervical procedures. Such efforts signal that product advancement is not limited to incremental material upgrades; it increasingly includes anatomy-specific engineering and procedural optimization. For companies, the strategic question is whether to compete through broad portfolio coverage, through specialized clinical solutions, or through a hybrid model that pairs standardized core instruments with targeted innovations for higher-value applications.
2026 Decision Priorities: What Leaders Should Do With This Intelligence
The forecast period begins with 2026, and the strategic choices made early in the year will influence positioning well beyond it. For equipment manufacturers and distributors, the priority is to determine where to commit resources in a market that is expanding steadily but not uniformly. Capacity investments, product-development timelines, and distribution partnerships all need to be calibrated against the segments and regions where demand is most durable and where competitive gaps can be exploited. A blanket expansion strategy is unlikely to outperform a more targeted approach built on specification alignment, clinical workflow fit, and reliable fulfillment.
For veterinary procurement leaders and institutional buyers, the report’s value lies in helping standardize decision-making across locations and service lines. Because the category spans multiple instrument types and animal classes, category managers need a clear framework for balancing quality, standardization, cost, and supply continuity. In moderately fragmented markets, there is often room to consolidate purchasing agreements and reduce variability in specifications, but doing so successfully requires visibility into which designs are clinically preferred, which suppliers have the most dependable production and sterilization-compatible materials, and where substitution would create operational risk.
For investors and strategic entrants, the key question is whether the market rewards scale, specialization, or distribution strength in a given geography. The competitive map suggests that multiple entry paths remain viable, especially where new designs, regional manufacturing advantages, or strong procurement relationships can create separation from existing suppliers. However, success depends on reading the category accurately: understanding that durability and sterilization compatibility are nonnegotiable, that clinical design familiarity can heavily influence adoption, and that demand is distributed across both developed and developing veterinary markets.
Conclusion: A Category Shaped by Clinical Practicality and Deliberate Competition
The Veterinary Speculums Market may appear, at first glance, to be a narrow instrumentation segment, but it sits at the intersection of clinical workflow, material reliability, procurement strategy, and regional demand growth. That makes it a useful lens for understanding how veterinary supply chains are evolving more broadly. Demand is expanding in a measured way, competitive intensity is real but not overwhelmingly concentrated, and differentiation increasingly depends on how well companies serve the practical realities of sterilization, design familiarity, and application-specific performance.
The full report translates these dynamics into a structured decision framework, giving leaders the context they need to plan production, shape procurement standards, evaluate competitors, and identify the segments of the market that offer the most favorable risk-adjusted opportunity. For organizations operating in or adjacent to this category, the intelligence is not simply about market size; it is about where durable advantage can be built in the years ahead.
To access the complete segmentation detail, competitive profiles, regional demand mapping, and forward-looking scenario analysis, we encourage decision-makers to review the full study through the source page. The macro trajectory outlined here provides the strategic frame, but the actionable specificity that supports exact planning choices is contained in the full market research.
For detailed analysis of this topic, please visit the official page: Veterinary Speculums Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Composite Acrylic Solid Surface Market to Reach USD 4,940 Million by 2032 Driven by 6.18% CAGR from 2026 to 2032
By PW Consulting, 2026-09-01
Composite Acrylic Solid Surface Market: Strategic Intelligence for 2026 Decision-Makers
The composite acrylic solid surface industry is entering a decisive growth phase, shaped by shifting design preferences, material innovation, and cost dynamics that demand executive-level clarity. For leaders navigating construction, interior fit-outs, hospitality upgrades, and high-end residential projects, the 2026 operating environment is no longer about incremental material choices; it is about understanding where value is created, where margins are pressured, and which competitors are wiring advantage into their product roadmaps. This new Composite Acrylic Solid Surface Market research from PW Consulting is built to operate as a strategic decision tool rather than a static industry overview. It translates market sizing, segmentation behavior, competitive positioning, and raw-material exposure into actionable intelligence for procurement, product strategy, channel planning, and investment timing.
Composite Acrylic Solid Surface Market
Our analysis is anchored in a multi-year historical view and extends through the 2026–2032 forecast horizon, enabling readers to assess both the trajectory they are already on and the inflection points likely to reshape competitive outcomes. The study reveals an overall market structure moving from a mature, fragmented base toward a more concentrated and design-led landscape, where product differentiation, regional supply competence, and feedstock management increasingly determine competitive performance. For organizations making decisions in this space, the central question is no longer whether the market is expanding, but how to position for durable advantage within it.
Composite Acrylic Solid Surface Market
Why This Report Matters for 2026 Strategy
Business leaders evaluating composite acrylic solid surface opportunities in 2026 face a market environment defined by simultaneous opportunity and constraint. Demand visibility is improving across multiple application types, yet input-cost volatility and environmental compliance expectations are adding complexity to product economics. In this setting, strategy quality depends on the quality of market intelligence. Organizations need a clear sense of how total market value has evolved, how the forecast trajectory compares with historical momentum, and which structural forces will most influence profitability over the next several years.
Composite Acrylic Solid Surface Market
This research was designed to answer those questions with analytical discipline. It places total market size and growth behavior in context, not as isolated figures, but as part of a broader operating narrative. The dataset reflects a market that has advanced materially from its earlier base and is projected to continue its upward trajectory through the end of the forecast period. That direction matters for capacity planning, regional investment, and portfolio decisions, but the real strategic value lies in understanding why the market is moving, where the strongest value creation is concentrated, and which segments are most exposed to cost or regulatory pressure.
A second reason this report is strategically relevant in 2026 is that competitive advantage in solid surface materials is increasingly built on product architecture and execution rather than brand presence alone. Leading suppliers are expanding color systems, refining surface performance, and exploring formulations that respond to sustainability expectations. At the same time, raw-material conditions are introducing cost variability that can separate efficient operators from less agile ones. Decision-makers need a structured view of these dynamics to anticipate margin pressure, evaluate launch timing, and assess partner or competitor behavior with greater confidence.
The report also supports go-to-market and sourcing strategy. For manufacturers, distributors, fabricators, and specifiers, the value of composite acrylic solid surface depends heavily on application fit, regional demand patterns, and the balance between premium and value-oriented product lines. Rather than presenting segmentation as a static list of splits, the study examines how value is distributed across regions and uses, how that distribution reflects underlying demand logic, and what it implies for commercial strategy. Readers gain a stronger basis for prioritizing markets, tuning product mix, and allocating sales or production resources where the opportunity-to-effort ratio is most favorable.
What the Data Reveals About Market Trajectory
The historical record shows a market that has consistently expanded beyond a low-base starting point and is now positioned for sustained growth. Over the 2020–2025 period, total market value progressed from an early baseline of approximately US$2,400 million to a 2025 level near US$3,250 million. That growth path reflects more than simple volume expansion; it indicates rising acceptance of acrylic solid surface solutions in spaces where durability, cleanability, and seamless aesthetics matter. The forecast period extends this movement with a compound annual growth rate of 6.18 percent, projecting the market toward a 2032 revenue base approaching US$4,940 million.
This trajectory is strategically important because it frames both the scale of opportunity and the timing of decision-making. A market expanding at this pace does not reward passive positioning. It rewards companies that can interpret demand signals early, align product and capacity choices with realistic demand curves, and anticipate how value shifts between segments over time. The forecast suggests continued momentum, but also implies that growth will not be uniform across all geographies or applications. Some markets will advance faster due to construction activity, renovation cycles, or design specification trends, while others will be shaped more by cost structures and competitive entry.
The segmentation architecture further clarifies where strategic attention should be directed. The market is organized around three major dimensions: region, product type, and application. Each dimension tells a different part of the story. Regionally, value distribution reflects the relative maturity of demand, the strength of local fabrication ecosystems, and the intensity of specification activity in different markets. In product terms, the balance between 100% acrylic and acrylic-polyester blends highlights a market that serves both premium performance expectations and cost-sensitive project requirements. From an application perspective, the split between residential and commercial uses points to different buying cycles, specification pathways, and performance priorities.
Importantly, the study does not reduce these splits to superficial share figures. Instead, it treats segmentation as a strategic lens. Regional patterns help identify where demand is concentrated and where growth may open next. Product-type patterns show how manufacturers are balancing performance, cost, and design flexibility. Application patterns reveal where end-use behavior favors aesthetic continuity, hygiene, repairability, or price competitiveness. This framing allows executives to evaluate not just how large each segment is, but how each segment behaves and how that behavior affects commercial planning.
Market concentration also provides a useful strategic signal. The report situates the competitive landscape within a structure where a limited number of leading players account for a meaningful portion of total market value, while still leaving substantial room for regional specialists and differentiated challengers. This mix matters because it shapes pricing behavior, innovation pace, and the feasibility of entry or expansion. In markets with noticeable concentration, scale, brand trust, and product breadth can create durable advantage. At the same time, the presence of capable mid-tier and export-oriented suppliers means that competition can still intensify through specialized offerings, regional cost positioning, or manufacturing efficiency.
Competitive Landscape: Winners, Challengers, and Strategic Positioning
A defining feature of the composite acrylic solid surface market is the coexistence of established global brands and capable regional manufacturers. The competitive environment is not a simple hierarchy; it is a layered field in which different companies compete on product identity, color and finish development, fabrication compatibility, regional supply reliability, and cost discipline. PW Consulting's report examines this landscape in a way that helps readers interpret not only who is present, but how each player is trying to win.
Among the companies profiled, DuPont Corian Design stands out as a pioneer whose reputation has been built on 100% acrylic and composite acrylic solid surface performance. Its offering emphasizes seamless, non-porous, repairable surfaces suited to countertops, sinks, and commercial applications. This product identity positions the brand in a premium-performance space where specification trust and long-term surface behavior are central. The company's recent April 2026 launch of the "Nature in Motion" color collection, with seven new aesthetics inspired by natural travertine and layered patterns for commercial applications, illustrates how leading players continue to reinforce differentiation through design-led innovation. For competitors and channel partners, developments like this matter because they raise the design bar in commercial specification and can influence buying preferences in higher-visibility projects.
LG Hausys, through HI-MACS, represents a major producer with a strong emphasis on acrylic-based sheets, broad color options, and sustainability-oriented product development. Its profile suggests a strategy that combines material consistency with visual variety and a growing focus on environmental performance. Samsung Staron is another significant presence, known for offering acrylic and composite options across a wide color range and positioning itself on the combination of affordability and quality for countertops and surfaces. Formica Group's Everform line extends the competitive field into acrylic-based seamless nonporous materials designed for countertops, wet walls, and commercial use, with manufacturing-friendly options produced in the USA. Wilsonart contributes a solid-surface line engineered with acrylic resins and minerals for durable, non-porous applications across residential and commercial settings, reinforcing the importance of hybrid material engineering in this category.
The competitive picture also includes strong Asian manufacturing and export-oriented players. Hanex, under Hanwha L&C, supplies acrylic and modified composite variants with a global orientation, emphasizing innovation and quality. Trinseo, through AVONITE, brings a product identity focused on design features within acrylic solid surfaces, while KingKonree specializes in modified acrylic solid surface sheets and finished products such as countertops and basins for export markets. LUXUStone adds further export capacity with multiple production lines supporting both pure acrylic and modified or composite acrylic solid surfaces. Collectively, these players demonstrate that the market is not confined to a narrow set of incumbents; it includes companies that compete through scale, export orientation, cost efficiency, and product breadth.
From a strategic standpoint, the most important insight is that competition is being fought on multiple fronts simultaneously. Some players compete on premium aesthetics and specification credibility. Others compete on cost, color range, or regional manufacturing advantage. Still others compete through formulation, fabrication compatibility, or sustainability positioning. The report maps these strategic postures so that readers can better anticipate competitive reactions, evaluate supplier relationships, and decide where differentiation will be hardest to replicate. This is especially valuable in a market where material performance, appearance consistency, and end-user perception can determine repeat business and project win rates.
Cost, Materials, and Regulatory Forces Shaping 2026 Profitability
Strategic interpretation of the market cannot be separated from the forces that affect cost and compliance. Composite acrylic solid surface production is fundamentally tied to acrylic resin economics, and acrylic resin economics are, in turn, exposed to petrochemical cycles. Methyl methacrylate is the primary feedstock for acrylic resin in composite acrylic solid surfaces, and regional price behavior can influence manufacturing costs in meaningful ways. In May 2026, regional pricing hovered around US$2.03 per kilogram in North America and US$2.18 per kilogram in Northeast Asia. These levels illustrate not only a current cost environment but also the kind of regional variation that can shape sourcing strategy, production location decisions, and competitiveness across export and domestic markets.
The broader point for executives is that feedstock dependency introduces volatility that can affect margins if not actively managed. MMA production relies on feedstocks such as acetone and propylene, meaning that price movement can respond to broader petrochemical cycles rather than to solid surface demand alone. In practical terms, this means that companies with stronger procurement planning, more flexible sourcing, or better process efficiency may be able to absorb cost pressure more effectively than competitors that treat input costs as a fixed external factor. The study incorporates this reality so that readers can evaluate where cost risk is most likely to appear and how it may influence product pricing, margin planning, and supplier selection.
Regulatory and sustainability expectations are adding a second layer of complexity. Environmental rules are increasingly focused on VOC emissions and sustainability in acrylic solid surface production, encouraging adoption of recycled content formulations and other lower-impact approaches. This is not merely a compliance issue; it is becoming a product strategy issue. As specification communities and end customers place greater weight on environmental performance, materiality, and transparency, suppliers that anticipate these expectations can use them as a point of differentiation. DuPont's sustainability reporting and EPD-related activity, for example, reflects how leading players are aligning product identity with environmental accountability. For others, the strategic implication is clear: sustainability is moving from a supportive attribute to a competitive variable that can influence specification choice and long-term brand positioning.
Taken together, raw-material volatility and sustainability regulation create a landscape in which cost control and product strategy must be managed jointly. A company that excels in one area but neglects the other may find its advantage narrowing. The report's treatment of these forces is intended to help decision-makers see the interaction between input economics, formulation choices, and market expectations, rather than treating them as separate concerns.
How the Report Is Structured for Actionable Use
This study is organized to support practical decision-making rather than passive reading. It begins with market sizing and forecast context, then moves into segmentation logic, competitive profiling, and the material and regulatory dynamics that affect profitability. The intent is to give executives a coherent framework they can use across multiple functions: product strategy, market entry or expansion, sourcing and supply planning, sales prioritization, and competitive benchmarking.
The segmentation discussion is presented as a strategic map. Instead of simply listing regional, product-type, and application splits, the report explains how these categories relate to one another and what they imply for commercial planning. This includes how regional value distribution corresponds to demand maturity and specification behavior, how product-type balance reflects different performance and price positions, and how application use cases shape buying criteria and project cycles. Readers can use this structure to assess where to concentrate effort, where differentiation is most defensible, and where competitive pressure is likely to intensify.
The competitive section profiles the key companies shaping the market, linking each player's strategic identity to its likely areas of advantage and exposure. This includes not only legacy strengths, but also recent moves such as new color collections, product line extensions, and manufacturing or export strategies that signal where competition is heading. By connecting company behavior to broader market logic, the report helps readers interpret competitor intent rather than merely catalog competitor presence.
The raw-material and regulatory sections are integrated into the market narrative so that cost and compliance are treated as strategic variables. This allows executives to consider how feedstock pricing, regional cost differences, formulation choices, and sustainability expectations may influence pricing power, margin stability, and product positioning over the forecast horizon. The report also examines market concentration to provide context on the balance between incumbency advantages and the potential for challenger growth.
Across all of these elements, the study is designed to answer the questions that matter most in 2026: where value is accumulating, which segments are most strategically sensitive, how competitive positioning is evolving, and what cost or regulatory shifts could alter the economics of the business. It is built to support both near-term decisions and multi-year planning, giving organizations a more reliable basis for acting under uncertainty.
Who Should Use This Intelligence and How
This research is relevant to a wide range of decision-makers, but its value is greatest for those who need to convert market complexity into concrete actions. Manufacturers and brand owners can use it to refine product architecture, evaluate color and finish development priorities, and assess where premium versus value positioning may yield stronger returns. Procurement and supply-chain leaders can use the material-cost and regional pricing context to strengthen sourcing strategy and anticipate volatility. Sales and specification teams can use the segmentation and application logic to target opportunities more effectively and to align messaging with the needs of residential versus commercial buyers. Investors and strategy teams can use the forecast trajectory, concentration structure, and competitive profiles to evaluate market entry, expansion, consolidation, or partnership options.
The report is also useful for organizations that compete indirectly in the value chain, including fabricators, distributors, and project developers, because it clarifies where demand is strongest, how specification behavior differs by application and region, and which product characteristics are most likely to influence selection. In a category where seamless appearance, repairability, non-porous performance, and design variety all matter, understanding the market from the supplier and specifier perspective can improve channel alignment and commercial execution.
Because the study is structured around decision relevance, it can be used as a reference point for multiple internal discussions. It supports questions such as: Which regions or applications deserve more resource allocation? Where does product differentiation need reinforcement? How exposed is the business to feedstock volatility, and what mitigations are available? Which competitors are most likely to shape pricing or specification trends in the next planning cycle? These are the kinds of questions that separate reactive market participation from deliberate strategic positioning.
What Is Reserved for the Full Report
To preserve the analytical value of the study, this overview intentionally conveys the strategic shape of the market without exposing the complete set of segment-level figures, regional breakdowns, application splits, or detailed company assessments that appear in the full research. The core market trajectory and growth rate are shared because they establish the broader context. The segmentation structure is explained because it clarifies how the market is organized and where strategic attention should be directed. The competitive landscape and material dynamics are summarized because they define the forces that will shape profitability and positioning.
What is reserved is the precise quantitative and comparative detail that executives need when they move from high-level direction to implementation. That includes the full segmentation values by region, type, and application; the deeper competitive profiling that supports supplier selection and benchmarking; and the detailed cost, concentration, and forecast-composition analysis that informs planning assumptions. Those elements are essential for operational decisions, and they are available in the complete PW Consulting Composite Acrylic Solid Surface Market report.
Conclusion: Turning Market Complexity into Strategic Advantage
The composite acrylic solid surface market in 2026 is not simply growing; it is evolving in ways that reward strategic clarity. Demand is expanding, product differentiation is intensifying, feedstock costs are introducing volatility, and sustainability expectations are reshaping how value is communicated and evaluated. In this environment, organizations that rely on intuition alone risk missing where the real margin, specification advantage, and competitive leverage reside.
PW Consulting's Composite Acrylic Solid Surface Market research is designed to give decision-makers a sharper lens on that evolution. It combines market sizing and forecast context with segmentation logic, competitive profiling, and material and regulatory analysis in a format built for strategy, not just observation. For executives who need to decide where to invest, how to position products, which suppliers or competitors matter most, and how to manage cost and compliance exposure, the study offers a structured foundation for judgment.
The full report develops these themes with the depth and specificity required for implementation. Readers who want the complete segmentation detail, competitive comparison, and forecast structure can access the full intelligence on the source page, where the analysis is presented in its full decision-ready form.
For detailed analysis of this topic, please visit the official page: Composite Acrylic Solid Surface Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Minimally Invasive Laser Therapy Device Market Poised for a 7.2% CAGR Through 2032
By PW Consulting, 2026-08-18
PW Consulting Strategic Brief: Minimally Invasive Laser Therapy Device Market — 2026 Strategic Imperatives
PW Consulting today publishes an executive briefing derived from our full market research report on the Minimally Invasive Laser Therapy Device market. Built from a five‑year historical audit (2020–2025) and a seven‑year forecast horizon (2026–2032), this briefing synthesizes the macro trends that will determine winners and laggards as firms plan 2026 budgets and strategic moves. The market reached approximately USD 5,200 Million (base year 2025) after steady expansion since 2020, and our model projects continued growth at a compound annual growth rate (CAGR) of ~7.2% through the forecast window. By the end of our forecast horizon the market is modeled to approach the high single‑digit billions benchmark, reflecting persistent clinical adoption, regulatory tailwinds, and service‑led commercial strategies.
Peripheral PMT Catheter Market
Why this briefing matters for 2026 decision cycles
- Capital allocation: With advanced laser platforms and image‑guided systems commanding sizable up‑front investment, 2026 will be a year when boardrooms need to validate ROI timelines for upgrades, purchases, and financing structures.
- Go‑to‑market prioritization: Shifts in coding, site‑of‑care economics, and outpatient capability change the addressable opportunity for devices versus service bundles—companies must choose where to focus limited commercial resources.
- M&A and partnership timing: Consolidation potential is concentrated in tech‑adjacent capabilities (imaging compatibility, digital workflows, remote service), and buyers will want validated scorecards ahead of diligence runs.
- Regulatory and reimbursement sequencing: New FDA clearances and CPT coding updates are altering both access and reimbursement value statements; 2026 is when firms translate these windows into adoption plans.
High‑level market dynamics shaping near‑term strategy
- Imaging‑integrated therapies are maturing. MRI‑guided laser ablation and other image‑assisted techniques are moving from specialized centers into more general neurosurgical and ophthalmic workflows, driven by product feature upgrades and clearances that increase compatibility with a wider range of imaging platforms.
- Reimbursement is beginning to align with value. CPT coding updates introduced for 2026, and supportive entries in physician fee schedules for certain laser‑based interventions, are improving procedure economics—particularly where minimally invasive approaches reduce length of stay or deliver outpatient feasibility.
- End‑user concentration favors hospitals, but the outpatient shift is accelerating. Hospitals remain the primary purchasers because of capital budgets and integrated services footprint; however, ambulatory surgery centers and specialty clinics are increasingly attractive targets for lower‑footprint systems and service‑based offerings.
- Capital intensity remains a barrier for smaller facilities. High initial costs and ongoing maintenance contracts influence procurement; flexible acquisition models (leasing, subscriptions, pay‑per‑procedure) continue to gain traction as diffusion enablers.
- Clinical evidence and workflow efficiency are decisive. Products that reduce procedural time, integrate with imaging and OR informatics, and demonstrate reproducible outcomes will outsell devices with similar raw performance but weaker clinical and economic evidence.
The competitive landscape: positioning the incumbents and new challengers
The market is neither a pure commodity nor monopolistic — a mid‑concentration structure leaves clear room for scale players to exert pricing and distribution influence while still offering niches for focused innovators. Our concentration analysis highlights that the top firms command a meaningful share of market revenues, but several adjacent specialists and emerging players remain capable of rapid share shifts depending on product and reimbursement developments.
N-Acetylglutamate Synthetase Deficiency (NAGSD) Market
- Medtronic — With its Visualase platform, Medtronic is positioned as a scale player in MRI‑guided ablation. Recent clearances and interface enhancements strengthen workflow efficiency—advantages in institutional procurement conversations. Strategy advisors should view Medtronic as a bellwether for the pace at which image‑guided neurosurgical lasers mainstream.
- ClearPoint Neuro — The company’s expansion of MRI compatibility materially increases addressable customers by lowering imaging constraints. For buyers and partners, ClearPoint represents a focused play on neurosurgical LITT with a differentiated systems integration approach; potential acquirers will value its imaging connectivity credentials.
- BVI Medical — With new endoscopic laser systems cleared for ophthalmic indications, BVI’s trajectory underscores how niche, procedure‑specific innovations can unlock adjacent specialty markets. Their integrated digital visualization capability is a differentiator in surgeon adoption curves.
- BIOLASE, Lumenis (Boston Scientific), Cutera, Alma Lasers (Sisram), Cynosure — These firms broadly address aesthetics, dermatology and dental medical laser segments. Their portfolios emphasize multi‑technology platforms and cross‑specialty applications, and they are increasingly important to buyers seeking consolidated technology stacks that address both medical and aesthetic revenue streams.
Recent regulatory and commercial catalysts to watch in 2026
- FDA 510(k) clearances in 2025 that expanded imaging compatibility and workflow improvements have reduced technical barriers for neurosurgical and ophthalmic adoption; similar pathways will continue to be a key speedometer for market access.
- AMA CPT updates in 2026 provide clearer channels for procedure valuation, which will influence hospital procurement committees and private payer negotiations through 2026–2027.
- Medicare payment policy and specialty fee schedule entries that recognize reduced resource use for certain laser ablation procedures will favor providers adopting minimally invasive options where clinical outcomes align with economic value.
What our full report delivers — practical, purchase‑ready intelligence
PW Consulting’s comprehensive market study goes beyond high‑level narrative. The full report contains actionable modules designed for commercial, clinical, and corporate transaction teams, including:
Pallet Organizer Robot Market
- Scenario‑driven market sizing and revenue models (multi‑case outlooks calibrated for conservative, base and aggressive adoption curves).
- Regulatory playbooks and likely clearance pathways with timelines mapped to product feature sets.
- Reimbursement capture toolkit: coding sensitivity analysis, payer engagement roadmaps, and price‑realization scenarios.
- Go‑to‑market segmentation frameworks and customer archetypes (hospital procurement, ASC, specialty clinics), with tailored value propositions and sales motion recommendations.
- Service and commercial models: lease vs. buy economics, managed service offerings, and remote diagnostics models that reduce total cost of ownership for buyers.
- Competitive scorecards and acquisition watchlists: comparative assessments of product fit, IP positioning, clinical evidence, and channel strength to guide M&A and partnership sourcing.
- Clinical adoption playbook: trial/registry design templates and key performance indicators that accelerate payer acceptance and surgeon buy‑in.
Four prioritized strategic moves for 2026
- Align R&D and regulatory timelines with CPT and reimbursement milestones. Firms that synchronize product launches with updated coding guidance will capture early adopters and favorable procedure valuation.
- Design flexible commercial models for constrained capital environments. Offerings that bundle service, training, and financing materially reduce procurement friction for community hospitals and specialty centers.
- Invest in imaging interoperability and workflow automation. Integration with existing imaging ecosystems (including broader MRI compatibility) is a differentiator in hospital purchasing decisions.
- Prioritize real‑world evidence generation. Early multicenter registries and outcomes studies that quantify reduced LOS, safety, and recovery metrics create defensible commercial claims and support payer discussions.
How PW Consulting partners with leadership teams
We work with executives to convert market intelligence into executable plans: transaction diligence and valuation, commercial due diligence, go‑to‑market roadmaps, reimbursement and health economics modeling, and regulatory strategy. For 2026 planning cycles we prioritize rapid, decision‑focused deliverables: a 90‑day go‑to‑market sprint, a three‑year investment case for product upgrades, and an M&A target shortlist with valuation sensitivity to reimbursement outcomes.
The present briefing intentionally highlights the strategic contours and decision levers without reproducing granular segment revenue slices and provider‑level projections that drive tactical execution. For leadership teams ready to move from strategic intent to a prioritized 2026 action plan, the full PW Consulting report contains the downloadable models, competitive scorecards, and target lists needed for board review and capital committee sign‑off.
Contact PW Consulting to request the full Minimally Invasive Laser Therapy Device Market report and to schedule a briefing workshop tailored to your organization’s 2026 priorities.
For detailed analysis of this topic, please visit the official page: Minimally Invasive Laser Therapy Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Passenger Car Vacuum Cleaner Market Poised for a 5.85% CAGR During 2026–2032
By PW Consulting, 2026-08-18
Passenger Car Vacuum Cleaner Market: 2026 Strategic Outlook — A PW Consulting Executive Brief
PW Consulting’s latest market research on passenger car vacuum cleaners, anchored on a 2025 base year with a forecast horizon stretching through 2032, delivers a focused, decision-grade perspective for executives preparing 2026 strategies. Our analysis shows the global market expanding at a compound annual growth rate (CAGR) of 5.85% over the forecast window, driven by cordless adoption, battery-technology gains, and evolving consumer cleaning behaviours. The market, having reached an estimated USD 218.5 Million in 2025, is projected to approach the mid-hundreds by 2032 — an outcome with practical implications for product roadmaps, channel investments, and M&A / partnership screening.
Worldwide Medical Gelatin Market
Why this report matters for 2026 planning
-
Timing: 2026 will be the first full planning cycle following several product refreshes and regulatory noise in 2024–2026. Companies that align R&D, manufacturing, and go-to-market investments to the trends identified in this report will capture disproportionate share as demand normalizes across channels.
Drinking Water Pipe Repair Market -
Clarity on growth pockets: While the market is mature in core economies, incremental growth is concentrated in product-enabling innovations (battery runtime, multi-surface wet/dry capabilities, and integrated blower functions). Our forecast and scenario analysis quantify the strategic value of prioritizing these features versus competing on price alone.
Medical Transport Coolers Market -
Operational levers: The report translates macro forecasts into operational KPIs — SKU rationalization thresholds, channel margin breakevens, and expected payback windows for cordless platform investments — enabling CFOs and product leads to model 2026 capital allocation decisions with higher confidence.
Macro snapshot (high level, non-segmented)
Across 2020–2025 the market trajectory reflected steady expansion from recovery and product innovation cycles; in 2025 global passenger car vacuum cleaner revenue reached approximately USD 218.5 Million. Looking forward, the market is expected to grow at 5.85% CAGR through 2032, reflecting steady demand for portable automotive cleaning solutions, the continued migration to cordless formats enabled by lithium-ion advancements, and channel-shifting dynamics favoring e-commerce and bundled retail offerings. These macro figures provide a defensible baseline for 2026 revenue planning and scenario stress-testing.
What the full report contains — practical, actionable content
-
Executive dashboards: One-page actionable dashboards outlining topline scenarios, sensitivity to battery-cost reductions, and channel performance models designed for rapid integration into board materials.
-
Go-to-market playbooks: Tactical recommendations for premium vs. value-brand positioning, prioritized feature sets for cordless models (runtime, filtration, attachments), and retail/commercial partnership templates to accelerate shelf and online presence.
-
Product development priorities: A ranked view of features that move purchase conversion and lifetime value, with guidance on trade-offs (e.g., adding wet/dry capability vs. increased weight and cost) and suggested minimum viable specifications for 2026 launches.
-
Channel and margin models: Unit economics by distribution route enabling rapid assessment of promotional spend, private-label feasibility, and subscription or service-add revenue streams (e.g., filter replacements and accessory kits).
-
Scenario planning and risk matrices: Three horizon scenarios (conservative, base, upside) calibrated to macro factors — raw material cost shifts, battery technology improvements, and tariff impacts — with playbooks for each.
-
Competitive benchmarking: Comparative capability maps, go-to-market timelines, and gap analyses for incumbent and challenger brands to support tactical responses and potential partnership targets.
Competitive landscape — who to watch and why
The market remains competitive but not highly concentrated; leading global brands compete alongside specialized manufacturers and value-focused OEM suppliers. Our competitive analysis focuses on product capability, platform leverage, channel strength, and recent strategic moves that matter to 2026 decision makers.
-
Black+Decker / Stanley Black & Decker — A dual approach: consumer-recognized handhelds under established brand names and cross-platform battery leverage via 18V/20V ecosystems. Their recent wet & dry vacuum introductions underscore a strategic push to capture multi-surface users who want a single household-to-vehicle solution.
-
Dyson — A premium playbook characterized by high-suction cordless models, HEPA-level filtration, and premium attachment ecosystems. Dyson’s Car+Boat launch (early 2025) signals continued emphasis on performance-differentiated, higher ASP products that appeal to quality- and brand-conscious segments.
-
Fanttik — Specialist challenger strategy centered on slim, lightweight cordless form factors and blower functionality. Recent product refreshes show how focused innovation in form and portability can create distinct appeal within automotive detailing niches.
-
Ryobi — A performance-oriented approach leveraging power-tool battery platforms to deliver higher suction and runtime for consumers who value performance and platform interoperability. This illustrates the strategic advantage of cross-category battery ecosystems.
-
ThisWorx and value brands — Compete on corded affordability and practical detailing attachments; these players are important in price-sensitive channels and complementary to aftermarket accessory sales strategies.
-
Worx, Bissell, Bosch, Philips — Each brings a variant of platform strength: Worx with modular systems, Bissell with pet-centric solutions transferable to vehicle interiors, Bosch with engineering robustness, and Philips with ergonomic consumer design. For incumbents, these differentiation strategies guide effective competitive responses and white-space identification.
Recent industry developments that will shape 2026 decisions
-
Product launches: Notable introductions from specialist and premium players between 2024–2026 (including blower-capable slim models and enhanced Car+Boat offerings) illustrate that product feature cycles remain the primary mechanism to shift share in this market.
-
Battery technology gains: Ongoing improvements in lithium-ion energy density and cost per run have materially changed the product-value trade-off for cordless models. Manufacturers that secure efficient battery sourcing or proprietary battery-management features will enjoy longer runtimes without unacceptable ASP increases.
-
Regulatory and trade considerations: Recent tariff commentary from major tool manufacturers indicates limited near-term disruption to 2026 guidance, but procurement teams should still model tariff sensitivity and diversify supply footprints to insulate margins.
-
Consumer habits: Persistent preference for cordless, quick-clean solutions continues to shape assortment and marketing — particularly for younger household formation cohorts and urban consumers with smaller vehicle footprints.
Strategic implications and recommended actions for 2026
-
Prioritize cordless platform investments where battery economics support acceptable payback periods. The PW Consulting model shows that modest battery-cost declines materially expand addressable premium segments.
-
Accelerate product bundling and accessory ecosystems: Filter and tool attachments are high-margin attachment opportunities that increase customer lifetime value and can fund introductory promotions.
-
Optimize channel mix by using data-driven pilots: Test premium direct-to-consumer launches in parallel with established retail and aftermarket distribution to identify optimal unit economics before wider rollouts.
-
Build supply resilience: Diversify component suppliers for batteries and key plastics, and model tariff scenarios as routine stress tests in annual planning cycles.
-
Targeted M&A and partnerships: Consider bolt-on acquisitions or partnerships for players with complementary technologies (e.g., filtration, blower modules) or strong direct-to-consumer capabilities to accelerate scale without starting from scratch.
Report deliverables that support execution
-
Interactive forecast models calibrated to client-specific assumptions (price points, SKU mixes, and channel strategies).
-
Competitive heat maps and playbooks that translate market positions into concrete countermeasures and product roadmaps.
-
Procurement and sourcing checklists to operationalize supplier diversification and battery-cost management.
Conclusion — the practical edge for 2026
For executives investing scarce budget and attention in 2026, the PW Consulting Passenger Car Vacuum Cleaner Market report provides a compact, tactical blueprint: a defensible baseline forecast (5.85% CAGR through 2032 from a 2025 base), prioritized product and channel actions, and decision-ready models to evaluate trade-offs between performance, cost, and speed-to-market. Our aim is to shorten the path from insight to action while preserving the confidential, detailed segment-level data behind the paywall — the exact segmentation and granular regional or application mixes are part of the full report and available through our portal.
To access the complete dataset, proprietary segmentation matrices, and downloadable scenario models that power 2026 planning, visit the PW Consulting Passenger Car Vacuum Cleaner Market page and request the full report and model package.
For detailed analysis of this topic, please visit the official page: Passenger Car Vacuum Cleaner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fine Surface Oriented Strand Board Market Poised for Growth — 5.85% CAGR Forecast Through 2032
By PW Consulting, 2026-08-18
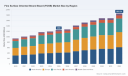
Strategic Preview: Why FOSB Will Be a Boardroom Priority in 2026
As global manufacturers and materials investors prepare their 2026 playbooks, Fine Surface Oriented Strand Board (FOSB) is rapidly moving from specialty niche to boardroom-level strategic consideration. PW Consulting’s latest market study—Fine Surface Oriented Strand Board (FOSB) Market (base year 2025, historical 2020–2025, forecast 2026–2032)—provides a concise, decision-grade perspective on why this engineered panel category demands attention now and how executive teams should respond during the coming planning cycle.
Matte Concealer Market
Headline Market Trajectory
The FOSB market reached roughly USD 1,250 Million in 2025 and is forecast to grow at a compound annual growth rate of approximately 5.85% over the 2026–2032 period. That steady expansion reflects widening adoption of fine-surfaced panels across furniture and interior applications, increased conversion of conventional OSB capacity to fine-surface grades, and improving specification traction in renovation and engineered-wood value chains. By the close of our forecast window, FOSB is projected to be materially larger than its 2025 base—underscoring the category’s transition from supplemental product to strategic portfolio item for a range of wood-based panel producers, distributors, and downstream manufactures.
Worldwide Poval Market
Why 2026 Is a Critical Inflection Year
- CapEx and commissioning timelines converge: Several large-scale investments announced in 2024–2025 are scheduled for commissioning in 2026, which will shift supply balances and competitive dynamics in selected markets.
- Specification tightening in interiors: End-market requirements—particularly for low-formaldehyde and fine aesthetic surfaces—are maturing, altering procurement criteria for furniture OEMs and interior fit-out chains.
- Input-cost volatility persists: Raw material dynamics (fast-rotation hardwoods and adhesive chemistries) and energy cost profiles continue to drive margin sensitivity across production footprints.
- Consolidation signals: Market concentration metrics show a moderate level of top-player share, leaving room for regional champions and technologically differentiated entrants to capture share.
Strategic Imperatives for C-Suites and Investors
For leaders preparing budgets and strategy cycles in 2026, the following moves are the highest-impact, near-term priorities:
Lifei Pian Market
- Re-assess product portfolios through an FOSB lens. Manufacturers should evaluate whether FOSB variants allow higher blended margins or enable access to premium downstream chains (e.g., pre-finished furniture and interior fit-outs). This requires a clear view of conversion costs, finishing requirements, and specification hurdles.
- Prioritize technology that preserves surface integrity. Investment in continuous-press lines, finishing technologies, and adhesive systems that enable low formaldehyde emissions is a differentiator. Equipment choices directly affect yield, scrap, and finishability—metrics that determine commercial viability in fine-surface markets.
- Build supplier relationships for feedstock resilience. Sourcing strategies for fast-growing eucalyptus and strategically managed softwood assortments reduce exposure to input-price spikes and availability constraints. Vertical integration or long-term sourcing agreements should be modeled in 2026 planning scenarios.
- Adopt a graded go-to-market segmentation. Not all regions or channels will absorb FOSB at the same pace. A phased commercialization plan—pilot supply to furniture OEMs, followed by scaled distribution into renovation and industrial segments—mitigates channel risk while accelerating specification wins.
- Embed low-emissions credentials into product design. Regulatory and procurement pressures make E0/E1-equivalent performance a baseline, not a premium. Certification roadmaps and testing plans should be included in product development budgets for 2026.
Competitive Landscape: What the Leading Players Are Doing
The competitive set is becoming more technology-driven and geographically diverse. Several established panel manufacturers and regional champions are taking distinct tactical approaches that will matter for 2026 strategic choices:
- Technology-led new capacity: Fletcher Building is executing a vertically focused strategy with a new fine-surface production line at its Laminex Taupo site, leveraging Dieffenbacher press technology to combine OSB cores with engineered fine-surface layers. The project’s commissioning timetable places initial output in mid-2026—an event that will be watched closely by competitors and customers.
- Regional scale and cost optimization: Chinese producers with multiple FOSB lines are scaling aggressively, improving unit economics and securing domestic furniture and interior markets with competitive cost positions and low-emission grades.
- Premium, feedstock-focused positioning: Producers using fast-rotation eucalyptus and MDI adhesives, targeting premium fine-surface panels for furniture and decorative uses, are differentiating on both aesthetics and formaldehyde credentials.
- Structural-to-fine-surface extensions: Major OSB players with broad structural portfolios are evaluating or piloting fine-surface variants, leveraging existing logistics and channel relationships to accelerate distribution.
PW Consulting’s analysis shows a market where the top three and top five producers hold a meaningful but not dominant share—creating opportunities for nimble entrants and regional integrators that can combine technology, feedstock access, and low-emission positioning.
Supply Chain and Regulatory Dynamics
FOSB is shaped by three interconnected supply-side realities:
- Feedstock choice matters: Fast-growing hardwoods (notably eucalyptus in certain geographies) and selected softwoods both underpin FOSB supply. Feedstock selection affects strand geometry, finish quality, and sustainability claims—so sourcing strategies need to be calibrated to end-use targets.
- Adhesive technology is a commercial lever: Adhesives—MDI and modified phenol-formaldehyde systems—drive both material performance and emissions profiles. Shifts in petrochemical inputs or regulatory constraints on emissions will change adhesive economics and may favor producers with access to alternative formulations or vertical integration.
- Emission standards shape market access: Low-formaldehyde grading is already a de facto requirement for many furniture and interior applications in key markets. Compliance pathways and testing documentation must be in place before large-scale commercialization.
Investment, M&A and Capacity Considerations for 2026
With multiple capacity projects scheduled to begin commercial runs in 2026, strategic investors and corporate development teams need to answer three investment questions:
- Does adding FOSB capability materially improve margin profile or is it better used as a defensive measure to protect structural OSB volumes?
- Is greenfield or brownfield expansion the superior route given local feedstock, energy, and labor markets?
- Which partnerships (technology suppliers, finishing specialists, or distribution networks) unlock the fastest route to specification acceptance in priority channels?
Our report includes scenario-modeled ROI and payback analyses for representative greenfield and upgrade projects, sensitivity-tested across adhesive pricing, energy, and finished-panel ASPs to help investment committees prioritize capital deployment in 2026.
What PW Consulting’s Report Delivers (Operationally Focused)
The Fine Surface OSB Market report is designed for executives and investors who need pragmatic, actionable insights—not just descriptive market sizing. Key deliverables include:
- Market sizing and seven-year forecast with base-year alignment to 2025 market conditions;
- Technology and CapEx playbook mapping equipment choices (continuous press, finishing lines) to yield and finish-quality outcomes;
- Supply-chain stress-tests showing how feedstock, adhesive, and energy volatility affect margins under multiple scenarios;
- Commercialization checklist for manufacturers entering fine-surface channels, including test protocols, certification needs, and retail/OEM specification pathways;
- Competitive positioning maps and acquisition screening criteria for strategic buyers and private equity;
- Executive dashboards and decision aids to integrate FOSB actions into 2026 budgeting and three-year strategy plans.
How to Use This Intelligence in Your 2026 Planning Cycle
Translate market insight into concrete actions by embedding three deliverables into your 2026 calendar:
- Preliminary business case (Q1 2026): Use our scenario templates to quantify the impact of introducing or scaling FOSB within your product portfolio.
- Supply and technology selection short-list (Q2 2026): Narrow equipment and adhesive partners using our techno-economic comparisons and pilot-run metrics.
- Go-to-market pilots (H2 2026): Initiate controlled supply to high-value furniture OEMs and interior fit-out projects to validate specifications and refine logistics before broader rollout.
Final Takeaway
FOSB presents a clear strategic opportunity: it can raise product value for manufacturers, offer differentiated low-emission options for specifiers, and create new consolidation and partnership pathways for investors. The 2026 planning horizon is decisive—projects coming online and evolving specification regimes will reshape competitive positions. PW Consulting’s FOSB study equips leadership teams with the analytical tools, scenario-tested financials, and practical roadmaps necessary to make high-confidence decisions in the coming cycle.
For executives preparing board materials and investment committees, the report functions as both a market compass and an implementation guide—showing not only where the sector is headed, but how to act in 2026 to capture the upside while managing input and regulatory risk. Visit our report page to access the full dataset, annexed scenario models, and interactive decision tools that are intentionally withheld from this preview to protect the proprietary analytical backbone of PW Consulting’s work.
For detailed analysis of this topic, please visit the official page: Fine Surface Oriented Strand Board (FOSB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Device Package Validation Market Poised to Reach USD 1,268.98 Million by 2032
By PW Consulting, 2026-08-18
Medical Device Package Validation Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
Executive snapshot
PW Consulting today releases a focused intelligence brief that translates the evolving dynamics of the medical device package validation market into a practical playbook for 2026 strategic decision-makers. Our model shows the market expanding from an estimated USD 780 million in 2025 to approximately USD 855 million in 2026, and projecting to grow at a compound annual growth rate (CAGR) of 7.2% across the 2026–2032 forecast window, reaching roughly USD 1.27 billion by 2032. These headline metrics underline an industry at once stable, technically demanding, and exposed to discrete supply- and regulation-driven inflection points—making targeted, evidence-based choices essential for manufacturers, contract service providers, investors, and regulators.
Duplex Scanners Market
Why this brief matters for 2026 decisions
Medical device packaging validation sits at the confluence of regulatory compliance, sterility assurance, supply-chain resilience, and sustainability policy. In 2026, organizations face three simultaneous pressures: accelerating validation complexity driven by stricter sterility expectations and distribution realism; cost and availability shocks in medical-grade packaging raw materials; and the need to demonstrate both regulatory compliance and environmental stewardship where relevant exemptions and eco-modulated fees are increasingly part of the conversation.
Finger Coats Market
Our brief converts those pressures into actionable options. It clarifies where to invest in internal capabilities versus outsourcing, how to structure contractual and technical requirements with third-party laboratories, and which operational levers preserve time-to-market without compromising compliance. Importantly, the document supplies scenario-calibrated financials that help leaders prioritize capital and operating budgets in 2026 and beyond.
Coated Upholstery Fabrics Market
What the report delivers — pragmatism over platitudes
- Proprietary market model and sensitivity scenarios — updated to 2025 base-year inputs and a 2026–2032 forecast horizon; headline market sizing and growth trajectories are included to support budgeting and M&A screening.
- Validation toolkit — practical templates for test plans and validation protocols mapped to ISO 11607 requirements, plus guidance on when to select accelerated vs. real-time aging, and comparative trade-offs between different integrity and distribution simulation approaches.
- Outsourcing decision framework — a stepwise evaluation matrix that quantifies the break-even between in-house testing and third-party labs based on throughput, regulatory risk, and capacity constraints.
- Procurement-ready RFP and SLA language — standardized clauses to align technical requirements, turnaround expectations, data integrity, and chain-of-custody documentation across vendors and geographies.
- Laboratory capacity and capability map — an operational view of accredited providers, lab specialties (e.g., integrity, microbial challenge, ISTA-certified distribution simulation), and geographic coverage to inform partnership selection and contingency planning.
- Cost-driver analysis — clear linkage between raw-material volatility and validation spend, including the operational implications of the recent rise in medical-grade polyolefin prices and associated coping strategies.
- Regulatory and policy horizon scan — an annotated digest of ISO 11607 continuity, state-level EPR developments with medical packaging exemptions, and near-term standards updates that could alter test requirements.
Competitive landscape — what leading providers reveal about the market
The market exhibits a mixed structure: concentrated enough that established specialists and global testing houses exert meaningful influence, yet fragmented enough to leave space for regional labs and niche providers. PW Consulting’s concentration analysis shows a moderate top-tier share, indicating established players capture a substantial portion of demand while mid-tier and regional labs continue to serve high-volume OEM workflows and localized needs.
Key players profiled in the brief illustrate differentiated strategic positions rather than purely competing on price. Specialist, compliance-focused laboratories emphasize deep ISO 11607 and ISO/IEC 17025 credentials and tailored validation services for terminally sterilized systems, while larger testing and inspection groups leverage global footprints and integrated regulatory consulting. Contract manufacturers and full-service outsourcing providers conjoin packaging validation with assembly and sterilization offerings to present turnkey solutions for OEMs looking to compress timelines.
Recent industry moves to watch
- Strategic capacity expansion by regional ISO 17025-accredited providers has reshaped East–West access in the U.S., reducing lead times for many OEMs and changing procurement geographies.
- Specialist laboratories are reporting elevated demand for temperature-controlled packaging validation and for updates to whole-package visual inspection protocols—reflecting an operational emphasis on distribution realism and sterility assurance under more exacting transport conditions.
- M&A and bolt-on acquisitions continue to be the primary avenue for lab groups to scale capabilities rapidly—enabling them to respond to both geographic demand and new technical testing needs without diluting core lab accreditations.
These movements are analyzed in the brief with outcome scenarios that link capacity additions and technology investments to likely price and turnaround impacts across 2026.
Regulatory and supply-chain dynamics shaping 2026 strategy
Two regulatory realities are central to near-term planning. First, ISO 11607-1 and -2 remain the bedrock standards for terminally sterilized packaging validation; understanding the nuanced expectations for design verification and process validation remains non-negotiable. Second, the evolving mosaic of state-level extended producer responsibility (EPR) frameworks introduces complexity for sustainability programs—while many medical device packaging types retain exemptions, eco-modulated fees and reporting requirements can affect material choices and supplier selection.
On the raw-material side, medical-grade polyethylene and polypropylene pricing rose materially since 2024, creating immediate cost pressure on packaging production and a downstream effect on validation budgets. The brief provides mitigation options—procurement hedging strategies, packaging design rationalization, and targeted investments in higher-throughput validation methods—that preserve regulatory defensibility without eroding margin unnecessarily.
Actionable recommendations for 2026
- Prioritize strategic lab partnerships: lock in capacity via master scheduling and volume commitments where testing throughput is mission-critical; where time-to-market is the priority, contract with multi-accredited providers that can provide end-to-end documentation and regulatory support.
- Integrate validation planning into early product design reviews: front-loading seal-strength criteria, material compatibility assessments, and distribution simulation scenarios can shorten validation cycles and reduce costly rework.
- Build a cost-resilience plan for packaging inputs: combine longer-term supply contracts, specification flexibility (subject to clinical and regulatory constraints), and scenario budgeting to absorb raw-material volatility.
- Use SLA-driven procurement and standardized RFP templates: clarity on turnaround times, data integrity expectations, and retesting triggers reduces ambiguity and shortens procurement cycles.
- Assess M&A and partnership targets with a capacity-risk lens: acquisition targets that deliver accredited testing capability and geographic reach can be faster and less risky ways to secure validation throughput than greenfield lab builds.
How PW Consulting’s brief supports executable decisions
This brief is designed for executives and operational leaders who must translate market signals into 2026 budgets, procurement strategies, and M&A screens. It pairs a rigorously audited market model and concentration metrics with practical artifacts—protocol templates, RFP language, supplier scorecards, and scenario P&L impacts—that can be put to use immediately. We intentionally maintain the higher-level market figures in this public summary while preserving detailed subsegment and regional breakdowns, test-type economics, and supplier-specific workload forecasts for the full report package.
Next steps — where to get the full intelligence
PW Consulting’s full Medical Device Package Validation Market report contains comprehensive regional and test-type splits, contract laboratory footprints, and downloadable validation templates that are deliberately withheld from this summary to protect proprietary analysis and to ensure readers derive maximum actionable value from the full deliverable. Organizations that require a briefing, licensing of the dataset, or tailored scenario runs for 2026 planning cycles can contact PW Consulting for immediate arrangements.
Final note
2026 will be a year in which small decisions around testing partner selection, packaging design trade-offs, and materials sourcing compound into either durable operational advantages or recurring compliance and time-to-market friction. PW Consulting’s brief equips leaders with the precise, operationally framed intelligence needed to choose advantage—balancing regulatory certainty, capacity resilience, and cost discipline. For teams preparing 2026 budgets, vendor strategies, or M&A pipelines, this is a tactical—and timely—resource.
For detailed analysis of this topic, please visit the official page: Medical Device Package Validation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


