



Category: Healthy Lifestyle
PW Consulting: Bovine Leather Goods Market to Grow at a 4.25% CAGR Through 2032, Led by Asia‑Pacific Demand
By PW Consulting, 2026-08-18
PW Consulting Intelligence Brief: Bovine Leather Goods Market — A Strategic Playbook for 2026 Executives
As global executives reset priorities for 2026, the bovine leather goods market presents a distinct set of strategic inflection points. PW Consulting’s new industry report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes macro trajectories, supply-chain stress tests, competitor positioning and actionable scenarios that directly inform capital allocation, sourcing and product strategy. At the top level, the market expanded through 2020–2025 before reaching an estimated USD 285.5 billion in 2025. Our forecast modeling—anchored to an expected compound annual growth rate of 4.25% across 2026–2032—anticipates continued expansion to a multi-hundred billion dollar market by the end of the forecast window.
Hydrogen Fuel Cell Check Valve Market
Why this report matters for 2026 decision cycles
- Timing of action: 2026 will be the year many firms move from defensive operational fixes to proactive restructuring—procurement redesigns, sustainability re-certification, and targeted M&A. Our study frames which moves are value-creating within a mid-single-digit growth market.
- Uncovering nonlinear risk: Beneath steady headline growth are year-to-year swings caused by raw-hide price volatility, tariff movements, and demand chunking across end markets such as footwear, automotive interiors and fashion. The report translates that noise into three prioritized risk scenarios executives must budget for.
- Competition is fragmented: Market concentration is low—leading players do not dominate to the degree seen in other consumer raw-material industries—creating opportunity for scale plays and selective consolidation. The market concentration metrics in our analysis quantify the strategic space for nimble brands and larger consolidators alike.
Key signals shaping 2026 strategy
- Demand dynamics: Continued premiumization in accessories and stable replacement cycles in footwear and furniture underpin base demand. Automotive interiors will remain cyclical but represent a strategic adjacency for manufacturers who can satisfy OEM specifications.
- Supply-side stressors: Raw-hides markets showed notable price fluctuations in early 2026, and wholesale ranges differ substantially across sourcing geographies. Tariff regimes and import controls continue to impose cost and lead-time risk for buyers that rely on cross-border procurement.
- Regulatory tightening: US and EU environmental and animal-welfare standards remain rigorous and are driving increased compliance costs upstream, while also creating barriers to entry for lower-cost producers who cannot adapt quickly.
- Sustainability as license to play: Certification and traceability are no longer marketing extras; they are commercial prerequisites for tier-one customers, particularly in Europe and North America.
What we cover — practical deliverables inside the report
PW Consulting’s market study is structured for immediate operationalization by strategy, procurement and product teams. Deliverables include:
Wetland Management Market
- Top-down market sizing and demand-scenario modeling through 2032, including sensitivity runs and year-by-year projections.
- Supply-chain mapping and supplier risk heatmaps, with actionable mitigation playbooks (indexation clauses, dual-sourcing blueprints, nearshoring assessments).
- Regulatory and tariff impact framework that converts policy shifts into P&L outcomes for sourcing strategies.
- Competitive scorecards: comparative analysis of leading producers, luxury houses and specialist tanneries to guide partnership, co-investment and M&A targets.
- Go-to-market playbooks for premium vs. mass segments, and for product adjacencies such as automotive interiors and furniture upholstery.
- Commercial templates and KPI dashboards to operationalize traceability, Leather Working Group certification and lifecycle reporting.
Competitive landscape — what incumbents are doing (and what that means for challengers)
The bovine leather goods ecosystem is populated by several distinct archetypes: luxury house integrators, specialist tanneries, heritage manufacturers and regionally focused brands. Each archetype implies a different partner or competitor strategy in 2026.
Atactic Polymethylpentene Market
- Luxury house integrators (examples include several Paris- and Milan-headquartered houses) maintain high margins through brand, vertical control and scarcity-driven positioning. Their priorities in 2026: tighter supply assurance, artisanal quality control and expanded services into resale and leather care ecosystems.
- Specialist tanneries and legacy manufacturers (for example, longstanding US tanneries with niche reputations) continue to capture premium artisan demand and supply high-value footwear and accessory customers. They are attractive partners for product-differentiation initiatives and B2B long-term contracts.
- Heritage and regional producers focus on made-in narratives and localized supply chains. Their agility makes them ideal for pilots on traceability and circularity but also exposes them to scale disadvantages when raw-material prices spike.
Representative firm-level implications:
- Luxury brands will continue to prioritize vertical control and traceability; partnerships with certified tanneries remain a priority.
- Mid-market brands should consider supplier consolidation or long-term offtake agreements to stabilize input costs, while investing in design-driven product differentiation.
- Smaller artisans and niche producers can monetize their craftsmanship through digital channels and limited-edition strategies, but must hedge supply risk.
Recent industry developments to watch in 2026
- Major trade shows scheduled through 2026—industry events remain a practical locus for new-product discovery, sustainability dialog and deal-making. These venues are increasingly used to signal supplier compliance and showcase traceability innovations.
- Trade associations and sustainability coalitions continue to expand exhibition footprints and collaboration forums, accelerating the diffusion of best practices on responsible leather production.
- Raw-material indices show volatility; early-2026 price points and 2025–2026 tariff movements should be factored into all near-term procurement contracts.
Practical strategic recommendations for 2026
PW Consulting recommends a three-track agenda for executives who want to both protect margin and capture upside in 2026.
- Stabilize supply and cost exposure
- Introduce layered procurement: short-term spot buffers combined with medium-term indexed contracts linked to objective raw-material indices.
- Deploy dual-sourcing for critical tanneries, and evaluate nearshoring for strategic SKUs to shorten lead times and lower tariff exposure.
- Differentiate through product and service
- Invest selectively in premium full-grain and artisanal lines where brand and craftsmanship deliver margin premiums; simultaneously, optimize cost structures for volume lines via process and material innovation.
- Build aftercare and circular services (repair, refurbishment, resale) to extend lifetime value and create new revenue streams.
- Turn regulation and sustainability into competitive advantage
- Pursue recognized certifications and supplier audits as commercial qualifiers rather than compliance costs.
- Prioritize traceability pilots that can be scaled; buyers increasingly require chain-of-custody evidence and will pay for verifiable provenance.
Risk monitoring and KPIs to operationalize
We recommend a concise monitoring set for executive dashboards in 2026:
- Raw-material price-to-revenue ratio (monthly)
- Percentage of spend under indexed long-term contracts
- Supplier certification penetration and audit completion rates
- Product margin by SKU cluster (premium vs. mass)
- Inventory days for critical leather SKUs
Scenario planning — three prioritized views
- Base case: Continued mid-single-digit CAGR with episodic price volatility—favors disciplined procurement and selective premium expansion.
- Downside (tariff/regulatory shock): Rapid margin compression in high-import portfolios—favors localization, hedging and inventory optimization.
- Upside (demand surge for premium leather goods): Capacity and quality become constraints—favors vertical partnerships, capacity investments, and prioritized allocations.
Closing — how PW Consulting helps you act in 2026
This briefing is a strategic preview intended to guide executive planning into 2026. Our full Bovine Leather Goods Market report provides the granular regional and application-level intelligence, supplier scorecards, financial models and scenario spreadsheets that operational teams need to execute the strategies summarized here. The full dataset includes detailed segmentation, year-by-year demand projections and prioritized partner lists designed to accelerate decision-making and reduce time-to-value.
To receive the full report and the executable playbooks referenced in this brief, visit our website or contact PW Consulting’s industry practice. The market is large, competitive dynamics remain mixed, and 2026 will reward organizations that pair disciplined supply-side risk management with differentiated brand and product strategies.
For detailed analysis of this topic, please visit the official page: Bovine Leather Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Home Shade Sail Market Reaches USD 1.56 Billion in 2025, Set for a 6.68% CAGR Through 2032
By PW Consulting, 2026-08-18
Home Shade Sail Market 2026: Strategic Preview for Business Leaders
PW Consulting’s new Home Shade Sail Market briefing — based on a 2025 base year and a detailed forecast running through 2032 — delivers a concise, action-focused lens for executives making strategic bets in 2026. The global home shade sail market has expanded from roughly USD 1.14 billion in 2020 to about USD 1.56 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.68% through 2032, reaching the neighborhood of USD 2.45 billion in the outer forecast year. For leaders weighing product investment, supply-chain reconfiguration, channel strategy or M&A, this research is designed as a decision-enabling toolkit rather than an academic digest.
Instant Oolong Tea Powder Market
Why this briefing matters for 2026 decision cycles
- Rapidly shifting demand patterns: Consumers are spending on outdoor living upgrades and prioritizing sun-protection products that combine performance with sustainability.
- Sourcing and tariff volatility: Evolving trade policies are making manufacturers reassess offshore dependence and contemplate nearshoring or domestic assembly to secure supply and pricing predictability.
- Channel disruption: Digital-first retail models are changing how residential buyers discover, specify and install shade sails — requiring a rethink of channel economics and service models.
- Low structural concentration: The market is still fragmented, with the top suppliers accounting for roughly a quarter of industry revenue, leaving substantial runway for scale plays and roll-up strategies.
These dynamics mean 2026 is not a “business as usual” year. Capital allocation, product roadmaps, channel investments and sustainability claims all require sharper, market-aligned choices — and a playbook to rapidly test and scale.
Sialic Acid Test Kit (Enzymatic Method) Market
What the headline numbers imply — reading between the lines
The headline CAGR of 6.68% reflects steady, demand-led growth rather than a short-lived spike. From 2020–2025 the market expanded materially as homeowners invested in patios, poolside shade and backyard rethinks; the forecast to 2032 assumes a continuation of that structural demand coupled with periodic regional volatility. For strategy teams this means two complementary priorities: protect core revenue with higher-margin, performance-led SKUs and pursue adjacent growth through service bundling (installation, maintenance, extended warranties) and premiumization.
Electronic Suitcase Lock Market
Importantly, volume growth alone will not guarantee margins. Competitive pressures, rising input costs for specialized HDPE fabrics and channel mix shifts mean that product specification, value capture and after-sales services will determine which players outperform market averages.
Competitive landscape — positioning and tactical implications
The competitive field includes long-standing fabric and sail specialists as well as nimble regional manufacturers. Notable players include GALE Pacific (Coolaroo), which leads in HDPE fabric technology and consumer warranty positioning; Sail Shade World, with a strong residential- and endorsement-led brand approach; established U.S. custom fabricators such as USA SHADE, Tenshon and Shade‑n‑Net; and B2B-focused manufacturers like Wholesale Shade and lower-cost custom suppliers targeting the home/backyard segment.
- Product leaders (e.g., established HDPE fabric brands) compete on technical performance, UV-block guarantees and warranty narrative. These features command price premiums with the right distribution and certification proofs.
- Custom manufacturers and regional fabricators win on lead time, localized service and contractor partnerships — a value proposition that gains favor where tariffs and freight add friction to imported offerings.
- Online-native brands and value players are compressing price points and accelerating discovery for DIY buyers; their rise increases the importance of direct-to-consumer logistics and easy-install SKU design.
For 2026, the strategic choices are clear: invest in product differentiation and certification if you want to protect premium positions; invest in speed-to-install and channel partnerships if you want to expand share in residential retrofit markets; or pursue consolidation to scale operational capabilities and reduce per-unit costs.
Supply chain, raw materials and regulation — actions to consider now
HDPE is the dominant fabric platform in the sector; premium grades offer high UV-block performance and long warranties, and the industry is rapidly framing sustainability claims around recyclability. At the same time, tariff uncertainty and international trade shifts are prompting manufacturers and distributors to rethink sourcing strategies and to evaluate domestic or regional production nodes for resilience.
- Immediate actions: run a sourcing stress-test for 12–18 months of demand, map supplier concentration risks and establish alternate fabric suppliers or local finishing partners.
- Medium-term actions: consider nearshoring or modular assembly centers to reduce freight and customs exposure; negotiate fabric supply agreements with performance clauses tied to delivery and quality.
- Regulatory vigilance: monitor tariff developments and certification requirements for UV performance claims — non-compliance risks both liability and brand damage.
Commercial tactics & go-to-market playbook for 2026
We recommend pragmatic, experiment-driven moves that leaders can deploy within a 90–270 day window:
- SKU rationalization plus premium wedge: reduce low-velocity SKUs and introduce a “performance” tier backed by tested UV-block credentials and a clear warranty structure.
- Service bundling: pilot packaged installation and anchoring services in select metros to capture contractor margins and improve customer lifetime value.
- Channel bifurcation: adopt a dual strategy — defend retail and contractor channels through exclusives and training, while scaling direct digital channels with optimized shipping and DIY-friendly instructions.
- Sustainability messaging: substantiate 100% recyclable HDPE claims with third‑party verification and communicate lifecycle benefits versus alternatives.
- Local inventory hubs: build small distribution points in high-demand regions to cut lead times and enable rapid response to weather-driven replacement demand.
These tactics should be A/B tested in priority markets, with KPIs tied to gross margin, fulfillment lead time and post-installation warranty claims.
Report content — the practitioner’s toolkit (what’s inside)
This PW Consulting briefing is intentionally practical. It combines high-level market context with executable deliverables designed for operating teams and boards. Key deliverables include:
- Market sizing and forecast model (2020–2032) with scenario runs: baseline, downside and accelerated adoption pathways calibrated to consumer-spend cycles and regulatory drag.
- Go-to-market playbooks and channel economics templates that let commercial teams model the margin impact of shifting sales between online, retail and contractor channels.
- Supplier risk matrix and sourcing optimization worksheet to evaluate offshoring vs nearshoring trade-offs by lead time, cost and tariff exposure.
- Competitor dossiers with strategic profiles on leading fabric brands and custom manufacturers, recent product and corporate developments, and playbook implications.
- Practical aids: installation partner scorecards, warranty language templates, and a consumer messaging matrix validated against homeowner purchase drivers.
We deliberately withhold granular segment tables (e.g., per-region and per-channel revenue splits) in this briefing to preserve the high-value, proprietary layers of the full report. Those tables are available through the report portal and are essential for detailed market-entry or M&A diligence.
How boards and exec teams should use the report
Use this briefing as a decision-acceleration instrument in 2026:
- Board workshop: calibrate the company’s three-year product and channel priorities using market scenarios and the competitor playbook.
- Investment review: apply the sourcing risk matrix and CapEx templates to validate any proposed manufacturing, assembly or acquisition decisions.
- Commercial sprint: deploy the channel economics templates to design a 90-day pilot that tests a premium HDPE SKU plus an installation service in two representative markets.
- M&A screening: use the competitor dossiers to prioritize targets that add scale, proprietary fabrics or regional distribution gaps in a cost-effective way.
Recent industry signals worth watching in 2026
Several near-term developments crystallize strategic risk and opportunity. Long-tenured fabric manufacturers are emphasizing warranty-backed, high-UV-block products, while editorial endorsements — including 2026 buying guides — are increasing consumer awareness and purchase velocity for ready-to-hang models. Simultaneously, tariff and trade policy shifts continue to pressure sourcing strategies, prompting discussions about domestic finishing and vertical integration. Finally, sustainability is moving from marketing to operations as firms aim to substantiate recyclable-HDPE claims with verifiable supply-chain practices.
Concluding guidance — where to focus in 2026
For 2026, firms that will succeed in the home shade sail market will combine three capabilities: technical credibility (verified UV performance and reliable warranties), channel agility (a digitally enabled direct presence plus robust contractor/retail partnerships), and supply resilience (diversified sourcing or local finishing). The market’s steady growth provides runway, but margin capture will favor those that translate fabric science into trusted consumer propositions and operationally disciplined fulfillment models.
PW Consulting’s full Home Shade Sail Market report contains the detailed segmentation tables, interactive financial models and tactical templates necessary to operationalize these recommendations. For decision-makers preparing budgets, supply plans and M&A pipelines in 2026, the full report is the single-source brief that converts market insight into executable initiatives — visit the PW Consulting report portal to access the complete package and the proprietary datasets required for transaction-grade diligence.
For detailed analysis of this topic, please visit the official page: Home Shade Sail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti-Scatter Grids Market Worth USD 420.5 Million in 2025, Forecast to Reach USD 666.25 Million by 2032 at a 6.79% CAGR
By PW Consulting, 2026-08-18
Anti-Scatter Grids Market: Strategic Imperatives for 2026 — PW Consulting Intelligence Brief
As healthcare providers and medical imaging vendors face intensified pressure to deliver higher image quality at controlled dose and cost, anti-scatter grids have re-emerged as a strategic leverage point across X‑ray and CT workflows. PW Consulting’s latest market research — underpinned by an expanded dataset through 2025 and a detailed 2026–2032 forecast — translates that technical importance into commercial opportunity: the global anti-scatter grids market reached USD 420.5 Million in 2025 and is projected to expand to approximately USD 666.25 Million by 2032, representing a compound annual growth rate (CAGR) of 6.79% over the 2026–2032 forecast horizon.
Medical Privacy Curtains Market
Why 2026 is a Pivotal Year for Decision‑Makers
- Tipping point between legacy and next‑gen solutions. Vendors and imaging OEMs are deciding whether to prioritize traditional aluminum‑ or carbon‑fiber interspaced grids, invest in 3D‑printed high‑density materials for CT, or accelerate hybrid approaches combining physical grids with advanced software correction. Early adopters of 3D‑printed tungsten solutions are already demonstrating measurable advantages in scatter rejection for high‑throughput CT applications.
- Regulatory and quality system harmonization. Enforcement trends around IEC standards for diagnostic grids and continued application of FDA classifications coupled with ISO 13485 expectations mean that suppliers who can demonstrate robust quality management and regulatory pathways will access larger contracts and fewer post‑market burdens.
- Value‑chain consolidation and concentration. Market concentration is material: the top three suppliers control a significant share of the market, and the top five account for well over half. This degree of concentration amplifies the importance of strategic partnerships, distribution networks and pre‑qualification programs for DR systems.
Data‑Driven Snapshot: Trajectory and Momentum
Between 2020 and 2025 the market expanded from approximately USD 310 Million to USD 420.5 Million — a sustained rebound driven by increasing digital radiography (DR) deployments, CT modernization cycles, and renewed hospital investment in diagnostic quality. Our 2026 baseline estimate positions the market north of USD 460 Million, with acceleration expected as vendors scale 3D manufacturing and healthcare systems renew capital equipment portfolios after pandemic‑era deferrals.
Dental Soft Tissue Diode Laser Market
For strategy teams, this macro trajectory validates two imperatives for 2026: (1) prioritize near‑term actions that capture share in the growing DR/CT upgrade cycle, and (2) invest selectively in higher‑margin, performance‑differentiated grid technologies that will command premium pricing in clinical settings where image quality and dose reduction are non‑negotiable.
Smart Mattress and Pillow Market
What the PW Consulting Report Contains — Practical, Transaction‑Ready Intelligence
- Market sizing and trend decomposition. A rigorous historical series (2020–2025) and a seven‑year forecast (2026–2032) with scenario analysis to stress test demand under different technology adoption and reimbursement assumptions.
- Supply‑chain and manufacturing playbook. Detailed maps of materials sourcing (including tungsten, molybdenum, aluminum, carbon fiber), fabrication pathways (traditional lamination vs 3D printing), and cost‑to‑serve models for custom large‑format grids used in modern DR detectors.
- Commercial benchmarking and pricing intelligence. Transaction‑level guidance for OEMs, distributors and hospitals on procurement levers, warranty and service models, and volume‑discount mechanics — designed to accelerate contract negotiations and shorten sales cycles.
- Regulatory & quality risk matrix. Practical checklists to align product development and manufacturing operations with IEC grid characteristics, FDA device classification and quality system requirements (21 CFR Part 820 and ISO 13485), reducing time‑to‑market and inspection risk.
- Go‑to‑market scenarios and partnership playbooks. Recommended M&A targets, distribution strategies, and channel models to capture share across mature and emerging markets, supported by quantified revenue and margin impact models (note: granular regional and application split data are available in the full report).
Competitive Landscape — Who Matters and What to Watch
The market is shaped by a blend of specialized manufacturers, OEM components suppliers, and high‑capability distributors. PW Consulting’s competitive profiles emphasize technology capability, manufacturing depth, go‑to‑market reach, and regulatory positioning.
- JPI Healthcare (South Korea) — A global leader in high‑precision carbon‑ and aluminum‑interspaced grids, including large‑format and custom solutions optimized for digital detectors. JPI’s recent public guidance on the advantages of physical grids over virtual grid software reinforces its positioning with hospital imaging leaders.
- Dunlee (Philips, Germany) — Innovator in 3D‑printed tungsten 2D grids for CT and fiber‑interspaced grids for radiography. The company’s emphasis on premium image quality and scatter rejection is exemplified by recent CT platform launches that bundle 2D grids for acute imaging environments.
- Reina Imaging (United States) — A master distributor and integrator in North America; its pre‑qualification for DR systems and multi‑brand portfolio enable rapid deployment and aftermarket capture for hospitals seeking validated grid compatibility.
- Nuclear Shields / Nuclear Fields (Netherlands) — Focused on 1D and 2D grids and collimators leveraging lead and tungsten. Their precision engineering supports both CT and specialized X‑ray systems requiring tight scatter control.
- Advin Health Care (India) — Represents a lower‑cost manufacturing node for standard radiology grids and supports regional procurement programs in emerging markets.
- Elmet Technologies (formerly H.C. Starck Solutions, US) — Supplies precision tungsten and molybdenum materials, enabling both traditional and advanced grid technologies; a critical supplier in any sourcing strategy that relies on high‑density materials.
Recent industry moves underscore the strategic inflection in 2026: Philips’ Rembra CT platform launch (April 2026) spotlighted 2D anti‑scatter grid integration for acute imaging; JPI’s February 2026 publications reinforced the clinical case for physical grids; and prior regulatory clears (e.g., recent 510(k) activity) illustrate accelerating product introductions that combine system and grid solutions.
Regulatory & Clinical Dynamics that Will Drive Procurement in 2026
- IEC standards for diagnostic and mammographic grids are becoming a default reference in product specifications; procurement teams should demand IEC‑compliant test reports as part of vendor qualification.
- In the US, grid products fall under Class 1 or Class 2 device categories and are subject to CGMP and quality system controls — vendors lacking ISO 13485 or appropriate FDA processes pose elevated supply risk.
- Clinical guidelines — for example, pediatric protocols that recommend grid removal for small field-of-view exams — will influence where hospitals invest in high‑end grids versus relying on workflow and software compensation. Savvy suppliers are packaging pediatric‑specific training and protocol checks into their value propositions.
Actionable Strategic Recommendations for 2026
- For OEM product leaders: Lock in dual supply lines for high‑density materials and accelerate prototyping of 3D‑printed grid architectures for CT. Prioritize demonstration studies that quantify dose reduction, SNR improvements and throughput impacts — procurement committees increasingly demand clinical evidence, not marketing rhetoric.
- For component suppliers: Commit to ISO 13485 certification and transparent material traceability. Build modular manufacturing capacity that can switch between aluminum/carbon fiber lamination and additive manufacturing to capture demand swings.
- For distributors and integrators: Strengthen DR system pre‑qualification programs and offer bundled service agreements that guarantee grid‑to‑detector compatibility and uptime. This is a compelling differentiator with hospital imaging departments balancing budgetary constraints and quality requirements.
- For private equity and corporate development teams: Target bolt‑on acquisitions that fill material, manufacturing or distribution gaps in concentrated geographies. The market’s CR3 and CR5 dynamics suggest meaningful synergy potential from supply consolidation and cross‑selling into OEM channels.
- For hospital procurement and radiology leaders: Reassess grid replacement cycles and negotiate outcome‑based contracts tied to image quality and dose metrics. Prioritize suppliers that can demonstrate regulatory readiness and robust service coverage for critical imaging assets.
Why PW Consulting’s Report Matters to Your 2026 Strategy
This report is structured to move teams from observation to execution. We combine granular supply‑chain maps, vendor scorecards, regulatory readiness audits and financial models that translate technical choices into balance‑sheet outcomes. Critically, the report is a decision tool — not a catalog — designed to reduce time to contract, minimize regulatory exposure and maximize margin capture across a market that our models forecast will grow steadily through 2032.
To maintain the competitive edge we outline above, companies need access to the full dataset — including regional and application splits, vendor market shares, price curves, and unit shipment forecasts — all of which are intentionally omitted from this brief to preserve the report’s role as your operational playbook. For procurement teams, technology scouts, and dealmakers preparing 2026 budgets and roadmaps, the full PW Consulting Anti‑Scatter Grids Market report delivers the executable intelligence required to act with confidence.
Next Steps
- Download the comprehensive report for full regional and application detail, vendor scorecards, and model‑backed scenario planning.
- Request a tailored briefing with PW Consulting’s senior analysts to translate the report’s findings into a 90‑day execution plan for your organization.
- Engage our M&A and sourcing specialists for confidential diligence support if acquisition, partnership or supply diversification is under consideration.
PW Consulting’s Anti‑Scatter Grids Market research synthesizes technical rigor with commercial pragmatism — enabling leaders to convert imaging science into measurable strategic advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Anti-Scatter Grids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automatic Breast Ultrasound Market Set to Nearly Double — From USD 685.0 Million in 2025 to USD 1,268.4 Million by 2032 at a 9.2% CAGR
By PW Consulting, 2026-08-18
Automatic Breast Ultrasound Imaging System Market: Strategic Imperatives for 2026 — A PW Consulting Insight
As healthcare providers, medical device manufacturers, and investors plan for the coming fiscal year, decision-makers require not only numbers but actionable context that links regulatory shifts, reimbursement dynamics, and technological inflection points to executable commercial strategies. PW Consulting’s newest market research—covering historical performance from 2020–2025 (base year 2025) and a forward-looking forecast for 2026–2032—provides that bridge for the Automatic Breast Ultrasound (ABUS) imaging systems market. Our analysis shows a clearly accelerating market, with the sector growing at a compound annual growth rate (CAGR) of 9.2% and an expected expansion from approximately USD 685.0 Million in 2025 to roughly USD 1,268.4 Million by 2032.
Photographic Continuous Lighting Equipment Market
Why this report matters for 2026 decision cycles
- Timing of regulatory and reimbursement shifts: Changes that became effective in early 2026 materially alter payment economics and thus product adoption curves for supplemental breast screening tools.
- Product and platform innovation: The market is experiencing a new wave of hardware, workflow and AI-enabled software introductions—creating winners and laggards on the basis of integration speed and go-to-market execution.
- Consolidation and competitive concentration: The market structure demonstrates significant concentration among a few leading OEMs, creating both opportunities for challengers and risks of supplier lock-in for customers.
- Provider capital allocation choices: Hospitals, imaging centers and point-of-care clinics must weigh acquisition cost, operational throughput and reimbursement realization to justify purchases in 2026.
Market snapshot (actionable headline figures)
PW Consulting’s base-year calibration finds the ABUS market at approximately USD 685.0 Million in 2025. Under our central-case assumptions, the market will grow at a 9.2% CAGR across the 2026–2032 forecast window, reaching an estimated USD 1,268.4 Million by 2032. This trajectory reflects accelerating adoption as technological maturation, reimbursement clarity and novel form-factors expand the addressable patient population and clinical use cases.
Anchor Channel System Market
Dynamics shaping near-term adoption
- Regulatory endorsement for adjunct use: The FDA’s approvals of multiple ABUS platforms for use as adjuncts to mammography in asymptomatic women with dense breasts continue to underpin clinical acceptance and payer consideration. These clearances reduce clinical ambiguity and enable standardized protocols in high-volume screening settings.
- Reimbursement mechanics: ABUS exams are billed using CPT code 76641 where applicable, providing existing billing infrastructure for organizations that integrate ABUS into supplemental screening workflows. Importantly, policy evolution at the state level—exemplified by Massachusetts’ expanded insurance coverage effective January 2026—creates near-term pockets of improved economics and real-world case studies for broader payor engagement.
- Technology divergence: The market is bifurcating along lines of system architecture and clinical workflow. Traditional automated volume scanners for full-breast, 3D acquisitions remain core to radiology departments and diagnostic centers. At the same time, new entrants with wearable and point-of-care platforms are lowering the access barrier for outpatient clinics and community screening programs.
- AI and reading efficiency: Concurrent-reading AI/CAD solutions—already moving through regulators and payer acceptance—are materially changing the labor economics of ABUS. Systems that tightly integrate hardware and validated AI workflows demonstrate shorter time-to-interpretation and improved reader concordance, strengthening value propositions for high-throughput sites.
Competitive landscape — reading the strategic plays
The ABUS market is characterized by a mix of large global OEMs with comprehensive portfolios and agile innovators focusing on differentiated clinical workflows. Market concentration metrics indicate that the top three players capture roughly 65% of market revenue, while the top five approach over 80%—a structure that rewards scale, channel breadth and installed-base services.
Polydextrose Market
- GE HealthCare (Chicago, Illinois, USA) — With the Invenia ABUS platform and the recent launch of an AI-enhanced Invenia ABUS Premium (March 2025), GE is doubling down on faster scanning and workflow efficiency as the primary lever to protect and extend market share. Its strengths lie in a broad installed base, strong reimbursement guidance, and strategic partnerships with AI developers and imaging networks.
- Siemens Healthineers (Erlangen, Germany) — Positioned with volume-scanning systems such as the ACUSON S2000 ABVS, Siemens competes on image quality, integration into enterprise imaging systems, and cross-modality workflow. Its approach is focused on aligning ABUS with mammography and tomosynthesis workflows in hospital and large outpatient settings.
- Delphinus Medical Technologies (Novi, Michigan, USA) — Delphinus’ SoftVue offers a differentiated whole-breast water-bath tomography method that emphasizes patient comfort and compression-free imaging. The company’s programmatic installations—such as the March 2025 implementation with a regional radiology association—highlight a service-led commercialization play targeting high-density screening cohorts.
- iSono Health (South San Francisco, USA) — iSono’s entry with a wearable, portable ATUSA platform (commercial launch January 2026) points to a disruptive access strategy: decentralize screening to point-of-care clinics and community settings. The success of this approach will hinge on validated clinical equivalence, practical reimbursement capture, and streamlined training models.
- SonoCiné and other innovators — Smaller suppliers and niche players continue to iterate on whole-breast automation and ergonomics, serving as important sources of clinical innovation and potential acquisition targets for larger OEMs seeking product portfolio breadth.
- QView Medical (Silicon Valley, USA) — As an AI-CAD vendor with FDA PMA approval for concurrent reading, QView exemplifies the emergent software layer that can be OEM-neutral or preferentially partnered—creating new routes to market and differentiation beyond hardware alone.
Operational and commercial implications for 2026
- For OEMs: Prioritize integrated AI workflows and validated clinical data that demonstrate throughput gains and improved sensitivity in dense-breast populations. Investment in service capability and regional reimbursement expertise will accelerate installations and reduce sales friction.
- For imaging providers: Evaluate ABUS adoption through a total-cost-of-ownership lens that includes interpretation time, reimbursement capture (CPT 76641 utilization), and incremental diagnostic yield. Pilot programs in states with expanded coverage (e.g., Massachusetts) can de-risk broader deployment.
- For payers and health systems: Targeted coverage policies that incentivize appropriate use in dense-breast screening pathways can reduce downstream treatment costs through earlier detection—anchoring the value case for broader coverage.
- For investors and corporates: The high concentration ratio suggests M&A opportunities for strategic acquirers seeking to combine hardware, AI, and service capabilities. Watch for tuck-in opportunities among innovators with unique form factors or AI-validated clinical outcomes.
Practical contents of the PW Consulting report (what you’ll get)
Our full report goes beyond headline estimates to provide operationally oriented intelligence that executives can act on in 2026. Highlights include:
- Scenario-based revenue forecasts and sensitivity analysis across our 2026–2032 horizon.
- Actionable go-to-market playbooks for OEMs, including channel segmentation, pricing levers, and service economics.
- Provider decision frameworks and ROI templates that quantify break-even points for hospitals, imaging centers and ambulatory clinics.
- Regulatory and reimbursement trackers with state-level coverage updates, coding guidance, and payer engagement templates.
- Detailed company profiles, product roadmaps, and competitive benchmarking—covering clinical differentiation, IP posture, and partnership opportunities.
To respect the “trailer” principle of this briefing—showing strategic depth while preserving the tactical granularity that drives commercial action—we deliberately withhold detailed regional, technology and end-user splits here. Those detailed segmentations, pricing matrices, and install-base forecasts are included in the full report and the accompanying downloadable data models.
Recommendations for C-suite teams preparing 2026 plans
- Close the payer conversation: Use early 2026 policy wins as leverage to run pilot projects that demonstrate revenue capture and downstream clinical impact. Data from these pilots will be decisive in broader procurement approvals.
- Partner on AI early: For OEMs, integrating validated CAD partners or developing in-house AI that can demonstrably reduce reading time is table stakes for competing in high-volume screening programs.
- Re-think channel strategy: Expect a widening buyer base—beyond radiology departments to primary care and outpatient clinics—especially as wearable and point-of-care systems commercialize. Channel economics and training models must adapt accordingly.
- Plan for consolidation: Given market concentration, mid-sized and smaller players should prepare for acquisition or partnership—while larger incumbents should evaluate inorganic options to fill technology or access gaps.
Conclusion and next steps
2026 will be a pivotal year for ABUS adoption. Regulatory clarity, state-level reimbursement expansions, and rapid product innovation are converging to expand the market opportunity materially over the next decade. Companies that align product development, payer engagement and field service capacity now will capture disproportionate share as the market grows at an expected 9.2% CAGR.
PW Consulting’s full Automatic Breast Ultrasound Imaging System Market report provides the detailed segmentation, commercial playbooks, and financial models necessary to convert these broad trends into executable strategies. For executives preparing capital allocation, product roadmaps, or M&A pipelines in 2026, the report is designed to be a practical guidebook—complete with downloadable models and scenario analyses.
Contact PW Consulting or visit our report page to access the full study and the underlying datasets that support our forecast and strategic recommendations.
For detailed analysis of this topic, please visit the official page: Automatic Breast Ultrasound Imaging System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PET and SPECT Scanners Market to Reach USD 9,090.84 Million by 2032, Driven by 6.5% CAGR
By PW Consulting, 2026-08-12
PET and SPECT Scanners Market: Strategic Imperatives for 2026 — A PW Consulting Industry Brief
As global healthcare systems prioritize precision diagnostics and molecular imaging scales into routine clinical care, executives must convert market intelligence into decisive capital and product strategy. PW Consulting’s new market research on PET and SPECT scanners combines a granular view of vendor dynamics, technology inflection points, regulatory shifts, and reimbursement evolution to illuminate where smart 2026 decisions will deliver the most durable returns.
BioBased Pipette Tips Market
Fast take: market size and trajectory
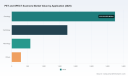
Our analysis shows the PET and SPECT scanners market continuing a steady expansion from the mid‑2020s into the early 2030s. The market reached an estimated USD 5,850 Million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of approximately 6.5% over the 2026–2032 forecast window. By the end of the projection period the market is expected to be materially larger, reflecting accelerating adoption of digital detectors, total‑body PET platforms, and expanded clinical use cases including oncology, cardiology, neurology and growing theranostics workflows.
Commercial Automatic Vacuum Packaging Machine Market
Why this matters for 2026 strategy
- Capital allocation: With a clear mid‑single digit CAGR and visible pockets of accelerated adoption, healthcare providers and imaging OEMs must prioritize investments in digital and high‑sensitivity platforms to avoid obsolescence and to capture higher throughput and reimbursement opportunities.
- Product roadmap prioritization: Companies should accelerate development and commercialization of systems that reduce scan times, improve image quality, and integrate AI‑driven workflow automation—these are the differentiators that buyers increasingly value.
- Service and aftermarket economics: As advanced systems penetrate the installed base, long‑term service agreements and software upgrades will become meaningful revenue levers alongside hardware sales.
What PW Consulting’s report delivers (practical, decision‑ready content)
This report is designed to be a playbook for commercial leaders, strategic planners, and procurement officers. It combines market sizing and growth forecasts with actionable modules that include:
Compact RV Refrigerator Market
- A validated top‑down market model (2020–2025 historical base, 2026–2032 forecast) that quantifies total market scale and growth drivers without divulging proprietary sub‑segment figures in this public summary.
- CapEx and purchasing behavior diagnostics that explain how and where capital budgets are being deployed across healthcare provider types, with practical guidance on procurement timing and trade‑offs for 2026 purchasing cycles.
- Technology adoption roadmaps—covering digital detectors, time‑of‑flight, total‑body PET, hybrid PET/MR systems, and digital SPECT—which tie technical capabilities to expected clinical workflows and ROI benchmarks.
- Regulatory and reimbursement scenario planning that models plausible policy moves and their impact on equipment demand and pricing dynamics, enabling finance teams to stress‑test investment cases.
- Competitor playbooks and go‑to‑market simulations that highlight partnership, channel and aftersales strategies tailored for regions and customer segments (detailed splits available in the full report).
- Deal and pricing guidance for OEMs and distributors, covering bundling, service contracts, and software subscription models to maximize lifetime customer value.
Competitive landscape — who matters and why
The market is concentrated, with leading vendors holding the majority of share. The top three players control roughly two‑thirds of the market, while the top five capture a substantially larger portion—underscoring a competitive environment where scale, installed base service capabilities, and innovation cadence matter.
- Siemens Healthineers (Erlangen, Germany) — Siemens remains a technology and regulatory frontrunner, extending its Biograph family and hybrid offerings. Recent regulatory movements and software approvals are enhancing image processing and scan efficiency, which strengthens its value proposition in tertiary and research institutions.
- GE HealthCare (Chicago, USA) — GE has accelerated total‑body research and clinical validation, and its recent product approvals and collaborations indicate a strategic push toward high‑sensitivity and high‑throughput systems tailored for large hospital networks and research centers.
- Philips (Amsterdam, Netherlands) — Philips continues to emphasize digital PET/CT architectures and Time‑of‑Flight technologies that enhance diagnostic accuracy, which is particularly attractive to clinical sites focused on oncology pathways.
- Canon Medical Systems (Otawara, Japan) — Canon’s hybrid PET/CT platforms and imaging integrations remain well positioned for centers seeking modality interoperability and strong service ecosystems.
- United Imaging Healthcare (Shanghai, China) — United Imaging has been disruptive with total‑body PET systems and competitive pricing strategies; its scale in China and growing international footprint make it a vendor to watch in tender and research procurement contexts.
- Specialist and regional players — Positron, Mediso, Neusoft, Spectrum Dynamics, and Shimadzu each bring niche strengths—cardiac PET focus, preclinical imaging, regional distribution partnerships, digital SPECT innovation, and specialized TOF PET systems respectively—that buyers should map to specific clinical and research needs.
Recent company developments (through early 2026) validate the competitive themes above: regulatory approvals for next‑generation systems, commercial wins in cardiac PET, and collaborations to evaluate total‑body PET. These events accelerate adoption curves and shift procurement conversations from “if” to “which vendor and when.”
Industry dynamics shaping 2026 decisions
- Reimbursement evolution: Payers in major markets are updating policies related to radiopharmaceuticals and imaging reimbursements. While the specifics vary by jurisdiction, the net effect is increased attention to diagnostic value and the economics of longer, higher‑value imaging exams—strengthening the business case for advanced scanners.
- Regulatory and software approvals: New clearances for hardware and AI‑enabled software that reduce noise and shorten scan times are reducing operational barriers for adoption and increasing site throughput. These approvals are shortening the time required to realize productivity gains from new systems.
- CapEx behavior: Surveys and field intelligence show a meaningful, though not universal, portion of PET imaging sites maintaining capital budgets for equipment refresh. There is a pronounced preference for digital detector systems among buyers with capital allocation capacity.
- Theranostics and clinical demand: The expanding clinical applications—particularly in oncology and cardiology—are creating higher utilization rates for advanced molecular imaging, shifting some value from single‑sale equipment economics to recurring revenue via radiopharmaceuticals, services and software.
Key strategic recommendations for 2026
- For OEMs: Prioritize modular architectures and software upgrade paths that protect customer investments and create subscription pathways. Align commercial incentives to bundled hardware‑software‑service offerings and accelerate clinical evidence generation through targeted collaborations with leading academic centers.
- For hospital systems and imaging networks: Adopt a differentiated acquisition strategy: invest in a mix of high‑sensitivity systems for centers of excellence and cost‑efficient hybrid platforms for community sites. Negotiate service contracts that emphasize uptime guarantees and predictable lifecycle costs.
- For investors and private equity: Target assets that combine strong installed base opportunities with software or service annuities. Due diligence should heavily weight regulatory risk profiles and the pace of adoption for total‑body PET and AI‑enabled enhancements.
- For payers and policy makers: Encourage evidence‑based reimbursement frameworks that link payment to diagnostic and therapeutic value, facilitating appropriate access while containing per‑case cost escalation.
What the full PW Consulting report enables you to do
Beyond the strategic themes summarized here, the full report provides the empirical foundation to shape executable plans: a defensible market sizing model, scenario analyses for reimbursement and regulatory outcomes, buyer personas and procurement playbooks, vendor scorecards, and region‑level go‑to‑market roadmaps. Importantly, the report includes transaction comparables and negotiation templates designed to shorten procurement cycles and optimize pricing and service terms.
Final note — the trailer approach
This brief intentionally highlights the market forces, vendor moves, and strategic pathways that will define success in 2026 while reserving the detailed sub‑segment data and region/application breakdowns for the full report. PW Consulting’s objective is to build confidence through insight and to invite decision makers to the full dataset where they can extract the granular analytics necessary to support capex approvals, M&A diligence, and competitive planning.
For organizations that must make immediate 2026 decisions—whether allocating capital, revising product roadmaps, or negotiating vendor partnerships—this research is engineered to move you from analysis to action with clarity and speed.
For detailed analysis of this topic, please visit the official page: PET and SPECT Scanners Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: System Kitchen Market Poised to Reach USD 55,821.7 Million by 2032
By PW Consulting, 2026-08-12
System Kitchen Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
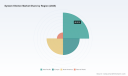
PW Consulting today publishes its flagship System Kitchen Market report, a pragmatic intelligence product built to influence boardroom decisions through 2026 and beyond. Anchored on a 2025 base year, the study synthesizes historical performance (2020–2025) and delivers a 2026–2032 forecast that models multiple macro, regulatory and commercial scenarios. At the headline level, the global system kitchen market is estimated at USD 38,500 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of approximately 5.45% over the forecast window—reaching a projected market size in the order of USD 55,821.7 Million by 2032. The market remains fragmented (CR3 ~18.5%, CR5 ~26.8%), a structural feature that shapes strategic choices for incumbents, challengers and financial sponsors.
Esports Gaming Headset Market
Why this report matters for 2026 decision-making
- Actionable scenario intelligence: The 2026 policy and trade environment is materially different from earlier years—our scenario toolkit quantifies the near-term impact of tariffs, commodity shocks and channel displacement so leaders can set defensible budgets and price decks now.
- Prioritization under capital constraints: With growth steady but not runaway, the report highlights where to allocate limited CapEx and working capital to maximize ROI—by product families, capabilities and go‑to‑market vectors (not just geography).
- M&A and partnership signals: Fragmentation plus sustained growth creates active arbitrage opportunities. The report surfaces target archetypes, valuation sensitivities and integration playbooks tailored for strategic and private equity acquirers.
- Supply‑chain resilience and cost management: Recent trade actions and raw‑material tariffs have magnified logistics and input risk; the study models end‑to‑end cost drivers and identifies quick wins for margin recovery.
- Commercial execution and channel transformation: From flagship showrooms to e‑commerce and developer channels, the research provides prioritized channel tactics and digital capabilities required to convert demand into higher‑margin sales in 2026.
What the PW Consulting report contains (practical deliverables)
- Market sizing and forward-looking forecast models: Base‑year calibration and flexible forecast scenarios (policy shock, slower consumer demand, high innovation uptake) with driver-level sensitivity.
- Demand archetypes and buyer personas: Granular profiles for the homeowner, renovator, developer and hospitality buyer—each mapped to preferred configurations, price elasticity and channel journey.
- Component and cost‑to‑serve breakdowns: Detailed costing templates for cabinetry systems, countertops, integrated appliances and hardware—designed for rapid benchmarking and margin remediation plans.
- Supply‑chain maps and logistics playbooks: Node‑level risk heatmaps, packaging and consolidation levers, transit optimisation and nearshoring decision matrices.
- Regulatory and tariff impact models: Scenario analysis quantifying the effects of trade policy shifts and input tariffs on landed cost, margin and competitive position.
- Channel & retail playbooks: Tactics for showrooms, specialty dealers, retail partners, developer sales and e‑commerce, including conversion metrics and organisational enablers.
- Competitive intelligence dossiers: Executive summaries and strategic SWOTs for market leaders, challenger brands and pivotal suppliers—built to inform partnership, supplier‑selection and defensive planning.
- M&A and inorganic growth frameworks: Valuation approaches, synergy capture plans and integration checklists for roll‑up strategies in a low‑concentration market.
- Sustainability and packaging decarbonization pathways: Practical investments and timeline estimates for emissions reductions across manufacturing, packaging and distribution.
Competitive landscape: strategic read‑throughs
We examined a cross‑section of industry names—from regional champions to global platforms—and assessed how their strategic choices will reconfigure competitive dynamics into 2026.
Mobile Virtual Network Operator Market
- Innovation in logistics and packaging as a competitive moat: LIXIL’s UL Kitchen example is instructive—reducing packaging volume and distribution CO2 materially improved landed economics and serviceability in dense urban markets. Firms facing labor constraints and distribution complexity should prioritize similar packaging and logistics redesigns to protect margins.
- Premium vs. volume playbooks: German manufacturers continue to demonstrate a bifurcated approach—some doubling down on premium, project-enabled offerings with high craftsmanship and sustainability credentials, while high‑volume producers push modular, cost‑efficient platforms. The choice is not binary; hybrid strategies (tiered platforms with localized customization) unlock scale while defending aspirational price points.
- Component suppliers shape product economics: Hardware and fittings partners remain pivotal to differentiation and quality. Strategic supplier partnerships (and selective vertical integration where scale allows) reduce time‑to‑market and improve margin predictability.
- Global low‑cost platforms vs. localized execution: Flat‑pack, mass‑market approaches retain reach advantages, but increasingly strict trade policies and higher transport/tariff burdens are elevating the returns to localised manufacturing footprints and developer channel partnerships.
Regulatory and raw‑material shocks: immediate implications
Two policy shifts demand urgent response in 2026. First, significant increases in import tariffs on finished kitchen products in key end markets have altered landed cost calculus; second, tariffs on timber and softwood inputs have elevated raw‑material volatility. Both combine to compress margins for actors who remain exposed to long, import‑dependent supply chains.
Community Software Market
- Strategic mitigations: nearshoring or regional assembly hubs to reduce tariff exposure; alternative material sourcing and engineered substitutes to control input cost; dynamic pricing and contract renegotiation to preserve margin.
- Operational playbook: re‑route SKUs to lower‑cost nodes, accelerate inventory turns through improved forecasting, and lock tiered supplier agreements with price‑adjustment clauses to limit short‑term inflationary hits.
High‑impact plays for 2026 (prioritised, executable)
- 1) Run differentiated scenario stress tests: Quantify P&L and cash flow under tariff, demand‑shock and commodity‑cost scenarios—set trigger points for executive action.
- 2) Cut logistics and packaging cost-to-serve: Short programs to reduce packaging volume, increase pallet optimisation and consolidate shipments—modeled after proven industry pilots.
- 3) Rebalance channel mix with conversion focus: Invest in digital configurators, virtual showrooming and up‑sell mechanics that increase average transaction value in digital and developer channels.
- 4) Accelerate modularity and platform commonality: Reduce SKU complexity, leverage shared component platforms to shorten lead times and lower inventory carrying costs.
- 5) Targeted M&A and alliance plays: Pursue bolt‑on manufacturing capacity or component suppliers to control cost exposure and accelerate market entry into protected geographies.
- 6) Embed sustainability into commercial strategy: Use packaging and distribution emissions reductions as both cost levers and differentiated branding—customers and developers increasingly reward verified steps.
How PW Consulting supports clients
PW Consulting combines industry specialization, proprietary forecast engines and hands‑on operational experience to help clients convert this research into measurable outcomes. Our services tied to this study include tailored scenario modeling workshops, merger integration planning, supplier negotiations support, channel transformation initiatives and implementation of packaging/logistics pilots. For executive teams seeking fast, evidence‑based decisions in 2026, our advisory teams provide short, outcome‑oriented sprints designed to de‑risk execution and accelerate payback.
The published report intentionally showcases strategic depth while withholding certain granular split tables and proprietary segmentation matrices to preserve commercial exclusivity. Readers who require the full intelligence package—including localized heatmaps, component‑level cost models, full competitor dossiers and the M&A target shortlist—can obtain the complete dataset and deliverables through PW Consulting’s System Kitchen Market report portal.
In a market that is neither static nor centrally concentrated, 2026 will reward organizations that combine disciplined scenario planning with pragmatic execution. This report is built to be the operational blueprint for that work.
For detailed analysis of this topic, please visit the official page: System Kitchen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Angiopoietin‑2 Market Reaches USD 3,450 Million in 2025 — Bispecific Antibodies Lead with USD 3,105.55M as Market Eyes 12.85% CAGR to 2032
By PW Consulting, 2026-08-12
Angiopoietin‑2 Market: Strategic Imperatives for 2026 — PW Consulting Market Intelligence Brief
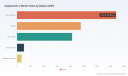
PW Consulting’s latest Angiopoietin‑2 Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) delivers a focused, decision‑grade view designed to shape executive strategy as organizations enter 2026. The market has experienced an extraordinary escalation over the past half‑decade — rising from a modest research‑market base in 2020 to an industry‑grade market by 2025 — and our projection model anticipates sustained double‑digit expansion across the forecast window (CAGR 12.85% for 2026–2032), culminating in a multi‑billion‑dollar opportunity by 2032 (all values reported in USD Million).
Hard Hat Accessories Market
Why this matters for 2026 decision cycles
Several converging forces make Angiopoietin‑2 (Ang‑2) a strategic inflection point for biopharma, diagnostics, and medtech leaders in 2026:
Smart Motion Sensor Light Market
- Clinical validation and label expansion of dual‑pathway therapeutics have elevated Ang‑2 from a research target to a commercial therapeutic axis.
- Rapid market scale‑up realized through 2025 has created both attractive revenue pools and heightened competitive intensity — a dynamic that materially affects pricing, access, and manufacturing decisions.
- Supply‑chain sensitivities for critical reagents and ELISA‑based diagnostics are now a line item on executive risk registers.
Leaders who move early in 2026 — aligning portfolio strategy, manufacturing resilience, and commercial access plans to these structural changes — will capture asymmetric value as the market matures.
Application Service Provider (ASP) Hosting Services Market
Performance snapshot and trajectory
Our topline model traces the market from approximately USD 80 Million in 2020 to USD 3,450 Million in 2025, reflecting a rapid evolution from niche research applications to broad clinical and commercial adoption. With a modeled compound annual growth rate of 12.85% across our forecast horizon (2026–2032), the market is projected to more than double in aggregate size by 2032 compared with the 2025 base. This trajectory is driven by concurrent demand in therapeutic innovations, companion diagnostics, and increased clinical use in retinal and oncology settings.
Report scope — what PW Consulting delivers
Our report is designed to be operational for teams making near‑term investment and go‑to‑market choices. Key deliverables include:
- Proprietary market model (2020–2032) with scenario and sensitivity analyses to stress test pricing, uptake, and reimbursement pathways.
- Segmentation framework across indications, drug classes, and geographies, mapped to practical implications for commercialization and regulatory strategy. (Note: detailed numerical splits and geo‑specific forecasts are included in the full report.)
- Competitive landscaping that synthesizes clinical, regulatory, and commercial moves for suppliers spanning reagents and diagnostics through to therapeutics.
- Supply‑chain risk matrix focused on reagent sourcing for ELISA and biologics production, including mitigation playbooks and supplier‑diversification strategies.
- Reimbursement and access playbook, including scenario plans for market entry, dosing paradigms, and payer negotiation tactics.
- M&A and partnership scorecards highlighting where inorganic moves and co‑development pacts could accelerate scale or insulate margins.
Competitive dynamics — who matters and why
The competitive landscape is already concentrated. Our concentration analysis indicates the top three players control a dominant share of the market, with the top five collectively owning an even larger proportion. This concentration creates both advantages (clear market leaders with scale and regulatory momentum) and opportunities (niche entrants and innovative business models can win by focusing on differentiated value propositions or underserved segments).
Key organizations profiled in the study span reagents/diagnostics and therapeutic developers:
- R&D Systems (Bio‑Techne) — Minneapolis, USA ( https://www.rndsystems.com): a well‑established supplier of quantitative Ang‑2 ELISA kits used across research and translational workflows, essential for biomarker measurement and early‑stage clinical programs.
- Abcam — Cambridge, UK ( https://www.abcam.com): offers streamlined ELISA solutions facilitating high‑throughput biomarker screening and translational lab workflows.
- Thermo Fisher Scientific (Invitrogen) — Waltham, USA ( https://www.thermofisher.com): a major reagent and kit supplier with broad market reach and supply‑chain influence.
- Sigma‑Aldrich (Merck) — Darmstadt, Germany ( https://www.sigmaaldrich.com): provides antibodies and assay components that underpin both research and diagnostic pipelines.
- Sino Biological — Beijing, China ( https://www.sinobiological.com): competitive in price‑sensitive research markets and an important supplier for Asia‑Pacific translational programs.
- F. Hoffmann‑La Roche Ltd (Genentech) — Basel, Switzerland ( https://www.roche.com): commercialized a category‑defining bispecific therapy that inhibits both VEGF‑A and Ang‑2, shifting standards of care in retinal disease.
- Boehringer Ingelheim — Ingelheim, Germany ( https://www.boehringer‑ingelheim.com): advancing bispecific/nanobody constructs that target VEGF and Ang‑2 in oncology, representing a strategic push beyond ophthalmology.
Recent, market‑moving developments included regulatory and clinical events that materially affect access and pipeline sequencing. Notably, faricimab (commercialized as Vabysmo) has seen label and formulation expansions, strengthening the therapeutic case for dual‑pathway approaches in retinal disease, while clinical publications on VEGF/Ang‑2‑targeting nanobodies underscore translational progress in oncology.
Dynamics shaping 2026 strategy
Four dynamics should drive any 2026 planning horizon:
- Therapeutic validation and label expansion: Dual‑pathway therapeutics moving into expanded indications and device/formulation permutations (e.g., prefilled syringes) materially change treatment algorithms, dosing cadence, and budget impact calculations for payers.
- Commercial concentration and barrier effects: High market concentration among a few incumbents increases the importance of differentiated clinical evidence or novel access models for new entrants.
- Diagnostics as a strategic lever: Biomarker quantification and ELISA‑based assays remain central to patient selection, trial enrichment, and companion diagnostics strategies — making supply reliability and assay standardization critical.
- Supply and raw material risk: ELISA kit manufacture and biologics production are exposed to reagent price volatility and capacity constraints; procurement strategies and vertical integration options will materially affect gross margin outlooks.
Actionable recommendations for C‑suite and investment committees
Based on our scenario work and stakeholder interviews, PW Consulting recommends the following for teams executing 2026 initiatives:
- Prioritize clinical differentiation: invest in head‑to‑head or real‑world evidence demonstrating dosing interval advantages, quality‑of‑life improvements, or payer‑relevant health‑economic benefits.
- Lock supply early: secure multi‑year supply agreements for critical ELISA reagents and biologics raw materials; evaluate contract manufacturing partners with validated scale‑up roadmaps.
- Design flexible commercialization pathways: prepare for staggered label and reimbursement rollouts across indications; build modular commercial teams that can pivot between ophthalmology and oncology markets.
- Explore partnership and licensing plays: incumbents may be open to co‑development or regional licensing to extend reach; smaller innovators should use focused evidence packages to win partnership terms that preserve upside.
- Stress‑test pricing models: incorporate scenario analyses that model competitive entry, biosimilar pressures, and payer rebate dynamics to ensure resilient margins under multiple trajectories.
What’s confidential in the brief — and why you’ll want the full report
To preserve strategic value for clients and partners, this briefing intentionally outlines high‑level trajectories, concentration metrics, and tactical imperatives while withholding detailed numerical splits across regions, indications, and drug classes. The report contains the full quantified segmentation, detailed company revenue estimates, payer‑level reimbursement scenarios, and downloadable modeling files that allow you to re‑run sensitivities against your specific hypotheses. Executives evaluating market entry, capital allocation, or M&A activity in 2026 will find those granular datasets indispensable.
Use cases: how clients are applying this intelligence
Early 2026 adopters of our insight are using the research to:
- Inform board‑level capital allocation for late‑stage clinical programs and manufacturing capacity expansions.
- Structure procurement and supplier diversification plans to mitigate reagent price shocks.
- Negotiate partnership terms with larger incumbents by leveraging our commercial uptake scenarios and payer impact models.
- Design market access dossiers that reflect updated labels, dosing paradigms, and health‑economic outcomes.
Final perspective
The Angiopoietin‑2 market has moved from nascent research interest to a commercially material sector within a few short years. For leaders making choices in 2026, the combination of significant market growth (CAGR 12.85% across 2026–2032), concentrated incumbency, and supply‑chain complexity sets a narrow window of opportunity: act early to secure supply, validate differentiated clinical and economic value, and structure partnerships that accelerate scale without forfeiting strategic optionality.
PW Consulting’s full Angiopoietin‑2 Market report delivers the granular forecasts, competitor revenue estimates, and go‑to‑market playbooks needed to operationalize these insights. For access to the complete datasets, model files, and bespoke advisory support to tailor the findings to your portfolio, please visit our report page.
For detailed analysis of this topic, please visit the official page: Angiopoietin 2 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pet Calming Food Market to Climb from USD 415M in 2025 to USD 708.9M by 2032, Growing at a 7.95% CAGR
By PW Consulting, 2026-08-12
PW Consulting Strategic Brief — Pet Calming Food Market Outlook (Operational Guide for 2026)
Executive synopsis
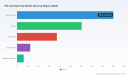
As pet owners increasingly prioritize behavioural wellness, the pet calming food market has emerged from niche supplement shelves into a category commanding boardroom attention. PW Consulting’s new market research—anchored on 2025 as the base year and projecting through 2032—provides the forward-looking metrics and executable playbooks that commercial teams, product leaders, private equity investors, and retail strategists will use to set 2026 priorities. The market exhibits near‑double‑digit tailwinds, with a multi‑year compound annual growth rate (CAGR) of 7.95% for the forecast window, and a 2025 baseline that confirms the category has matured beyond early adopter spend patterns. Market concentration remains modest (CR3 ~28.5%, CR5 ~39.2%), indicating meaningful room for new entrants, consolidation, and vertical integration.
X-ray Detection Metal Detector Market
Key macro indicators to inform 2026 strategy
- Base year and trajectory: PW Consulting uses 2025 as the base year for its forecasts. The category’s baseline sales trajectory and the compound growth assumption described above underpin scenario plans for new product launches, channel expansion, and M&A diligence in 2026.
- Concentration and competition: The measured CR3 and CR5 imply a fragmented competitive landscape—large incumbents coexist with an active independent brand layer. This structure favors targeted M&A, co‑brand distribution agreements, and private‑label partnerships in the near term.
- Regulatory and quality levers: Pet calming food is governed by food‑labeling and safety guidance under bodies such as AAFCO and applicable FDA frameworks. Third‑party assurances (for example, NASC auditing) are increasingly decisive in commercial conversations, affecting placement with vet channels and premium retailers.
Why this report matters for decisions in 2026
- Prioritization clarity: The report translates market momentum into prioritised initiatives—where to invest in product efficacy evidence, which channel mixes produce the fastest payback, and which ingredient bets have defensible sourcing strategies.
- Investment and M&A intelligence: With fragmentation and differentiated margin pools across formats, investors need valuation templates and integration playbooks. Our analysis pinpoints the levers that drive accretive transactions and measurable synergies.
- Commercial execution: Brands and retailers receive concrete go‑to‑market modules—SKU rationalisation, assortment cadence for seasonal spikes (e.g., fireworks, travel), pricing tests, and subscription retention tactics tuned to behavioural wellness buyers.
- Risk mitigation: The sector’s sensitivity to recalls and ingredient reputation (e.g., recalls and contamination events) makes quality management a business‑critical function. We provide actionable compliance checklists and rapid response frameworks.
What the PW Consulting report delivers (practical, operational content)
- Proprietary market model: A dynamic forecast engine (2026–2032) that powers scenario analysis—base, upside, and downside—allowing teams to stress‑test rollouts and capital plans under different growth assumptions.
- Channel playbooks: Tactical guidance for national retailers, veterinary channels, e‑commerce marketplaces, and D2C/subscription models, including channel‑specific margin expectations and promotional architectures.
- Product development roadmap: Formulation priorities, clinical evidence sequencing, and sample study designs to demonstrate efficacy for calming claims without crossing into therapeutic drug claims.
- Ingredient sourcing and supplier map: Risk‑ranked supplier lists for core calming ingredients (e.g., L‑theanine, L‑tryptophan, ashwagandha variants, chamomile, valerian), volatility scenarios, and contingency sourcing strategies to insulate gross margins and supply continuity.
- Regulatory and quality toolkit: Labeling templates compliant with food guidance, a NASC audit preparation checklist, and an incident response protocol for recalls or supplier quality events.
- Commercial templates: Pricing matrices, promotional calendars calibrated for pet seasonality, KPI dashboards for SKU rationalisation, and retail pitch decks that translate clinical evidence into buyer outcomes.
- Investment and M&A playbooks: Valuation comparables, integration checklists, and a roadmap for capturing cross‑sell uplift post‑acquisition.
Competitive landscape — actionable takeaways
Our competitive analysis synthesises public brand positioning, recent launches, and clinical/quality signalling. Key players include established global CPG/animal health firms and high‑growth independents. Highlights from the competitive layer:
Golden Lotus Oral Liquid Market
- Nestlé Purina PetCare — Leverages veterinary channels and science‑led positioning (example: Pro Plan Veterinary Supplements Calming Care). Their scale and vet relationships make Purina a benchmark for evidence‑based product rollouts and retailer negotiations.
- Zesty Paws — A fast consumer brand with strong soft‑chew formulations and D2C/omnichannel momentum. Recent historical events underline the impact of product quality incidents on brand equity and retailer trust.
- Pet Honesty — Focused on naturally framed formulations (hemp, chamomile, valerian), their positioning highlights the premium natural wellness shopper segment and retail demand for clean‑label stories.
- Boops Pets — Recent product innovation (KSM‑66 ashwagandha chews launched March 2026) combined with NASC auditing demonstrates the premium returns on coupling novel ingredients with third‑party validation.
- Virbac — Brings pharmaceutical‑grade know‑how to the market via L‑theanine formulations, illustrating the advantage of clinical heritage when marketing to veterinary professionals.
- NaturVet and Ceva Animal Health — Represent the breadth of the market from mass channel play to pheromone and snack‑based calming solutions; they demonstrate that therapeutic adjacencies and non‑oral solutions still hold commercial value.
Taken together, these players illustrate three competing strategic models in 2026: (1) science‑led, vet‑channel incumbency; (2) fast‑moving consumer brands that prioritise marketing and omnichannel reach; (3) ingredient/innovation specialists that monetise new adaptogens and verified extracts. The PW report maps where each model wins and the typical investment profiles that enable them.
Bag-in-Box with Oxygen Barrier Market
Strategic playbook for 2026 — prioritized actions
- Lock quality and certification first: Pursue NASC (or equivalent) auditing and implement supplier qualification KPIs before expansion. Quality signalling materially affects listing decisions and consumer trust.
- Invest in targeted clinical evidence: Short, species‑specific trials that deliver meaningful behavioral endpoints (validated scales, veterinarian reporting) have outsized impact on premium shelf placement and vet endorsements.
- Secure ingredient resilience: Build dual‑source agreements for core actives and hedge price exposure for specialty extracts. Consider toll‑manufacturing options to control lead times and cost of goods.
- Adopt a channel‑specific SKU strategy: Use lean assortments in new retail accounts with fast replenish cycles, while testing premium concentrates via D2C with subscription bundles for higher LTV.
- Prepare M&A scouting filters: Look for assets that add critical capabilities—clinical evidence, exclusive ingredient licences, or retail distribution—over purely revenue‑scale targets.
- Operationalise recall readiness: Implement real‑time lot tracking and communications templates; run tabletop exercises with legal and commercial teams at least once per fiscal year.
Near‑term triggers and monitoring framework
- Sales velocity and SKU productivity across channels (weekly cadence in first 12 weeks post‑launch).
- Vet endorsements and clinical citations achieved (quarterly tracking).
- Ingredient cost indices and supplier lead‑time alerts (monthly).
- Listing wins/losses at national retailers and independent vet channels (monthly/quarterly).
- Regulatory guidance changes and industry advisories affecting labeling claims (continuous monitoring).
- Reputation events (product quality incidents, recalls), with time‑to‑response and post‑event recovery KPIs.
How PW Consulting’s methodology supports operational decisions
The report blends primary channel checks, trade interviews, veterinary advisory panels, and a bottoms‑up supply chain mapping exercise. Our forecasting engine is scenario‑capable—allowing teams to simulate outcomes from different investments in evidence generation, advertising spend, and channel expansion. Importantly for 2026 planners, the model is delivered with editable input tabs so commercial leaders can rebase assumptions to their specific launch timing, gross margin targets, and geographic footprints.
Next steps — where to get the full intelligence
This strategic brief is a preview of the practical intelligence in PW Consulting’s Pet Calming Food Market report. The full report contains the proprietary segmentation detail, channel‑by‑channel forecasts, unit economics by product form, and downloadable commercial templates you will need to execute in 2026. To access the complete dataset, scenario models, and vendor‑negotiation templates, please visit our report page (full content is gated to subscribers and clients).
In a category defined by trust, evidence, and reliable supply, 2026 will be the year leaders convert scientific credibility into commercial advantage. PW Consulting’s report equips executive teams with the near‑term playbook and the forecasting rigor to do exactly that.
For detailed analysis of this topic, please visit the official page: Pet Calming Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pet Food Insect Protein Market Poised to Soar at a 14.5% CAGR
By PW Consulting, 2026-08-12
Pet Food Insect Protein Market: Strategic Briefing for 2026 Decisions
Executive summary
PW Consulting’s new Pet Food Insect Protein Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) identifies insect-derived proteins as one of the fastest-growing substitutions in pet nutrition. Our modeling shows the global market scaling from an estimated USD 380 million in 2020 to approximately USD 750 million in 2025, and accelerating into a near-term inflection with an anticipated market value approaching USD 906 million in 2026. Under our central forecast the sector expands at a compound annual growth rate of approximately 14.5% across the 2026–2032 projection window, reaching just under USD 2.0 billion by 2032.
Cook Condiment Pack Market
This release is a strategic “trailer”: it highlights the report’s analytical depth and immediate relevance for board- and C-suite-level decisions in 2026 while intentionally withholding detailed segment-level tables and proprietary model outputs to encourage direct access to the full report.
Refurbished Angiography Equipment Market
Why 2026 is a pivot year for corporate strategy
-
Regulatory normalization and commercial scale-up coincide in 2026. Ingredient approvals (notably the recognition of black soldier fly-derived materials in key jurisdictions and the first mealworm authorization for dog food) reduce regulatory execution risk for new product introductions, shifting the barrier to entry from “can I sell?” to “how quickly and profitably can I scale?”.
Adenovirus Purification Kit Market -
Capital deployment decisions will determine competitive roles. As large-scale insect protein facilities come online and incumbents expand capacity, unit economics and contract structures will increasingly bifurcate value capture between ingredient producers and branded pet-food manufacturers.
-
Consumer acceptance is maturing. More than half of global insect production is now directed towards pet food applications — a signal that procurement pipelines, retailer acceptance, and consumer trial rates have moved beyond niche status to meaningful market traction.
What this means for corporate decision-making in 2026
-
Prioritize supply certainty over short-term price arbitrage. With premium black soldier fly (BSF) protein commanding a premium in the current supply stack (industry guidance points to a range in the low single-digit USD per kilogram to the mid single digits for premium grades), first-mover contracts with scalable producers will protect throughput for new product launches and limit disruptive spot-price exposure.
-
Design dual-track regulatory and commercialization plans. Companies should run parallel streams: (a) ensure ingredient dossiers and claims are validated for priority markets, and (b) pilot differentiated SKUs that capitalize on sustainability and allergen-differentiation claims where permitted.
-
Reassess R&D roadmaps to convert novelty into repeatable nutrition. Nutritional parity, palatability testing, and digestive-tolerance profiles must be integrated into product-development timelines. Investing in co-formulation pilots with ingredient partners can compress time-to-shelf and build defendable product propositions.
-
Use pricing and channel strategies to protect margins. Premium positioning, subscription models, and targeted treat lines provide higher tolerance for raw-material premiums while building repeat purchase behaviors.
Competitive landscape — who matters and why
The market is meaningfully fragmented: the top three players account for a minority share of aggregate supply, and the top five do not create a tightly concentrated oligopoly. This fragmentation creates windows for both scale-driven ingredient producers and nimble niche brands.
-
Innovafeed (Paris, France) — large-scale BSF ingredient producer with strategic capacity in Europe and North America. Their investments in North American operations signal an intent to be a backbone supplier to premium pet-food formulations. For brands seeking guaranteed throughput and tailored functional ingredients, Innovafeed sits in the shortlist.
-
Ÿnsect (Évry-Courcouronnes, France) — mealworm specialization and trailblazing authorizations (first mealworm protein authorization in the US for dog food) position Ÿnsect as a partner for differentiated, high-margin launches. Their Sprÿng-branded ingredients enable unique claims that matter in premium segments.
-
Protix (Netherlands) — an established global leader in BSF ingredients, notable for deep partnerships with pet-food brands. Protix’s product pipeline and commercial partnerships make them a counterparty for co-branded or co-developed nutritional propositions.
-
EnviroFlight (Darling Ingredients) (USA) — US-based BSF producer with approved ingredient status for dogs and cats. Their strategic parentage provides scale advantages and route-to-market synergies for companies prioritizing North American penetration.
-
Enterra, Yora, Jiminy’s, Entomo Farms, Tomojo, petgood — these producers and brands exemplify two viable go-to-market archetypes: ingredient specialists (supplying processors and brands) and vertically integrated brand challengers (bringing complete diets and treats to market). Their presence underscores viable paths for both B2B and B2C strategies.
Recent market signals you must factor into 2026 planning
-
Facility expansions and funding rounds (e.g., multiple scale-up announcements across Europe and North America) reflect new capacity that will materially change availability in 2026 and beyond.
-
Certifications and sustainability scoring improvements (reported improvements to sustainability certifications and scoring for producers) are rapidly becoming procurement gatekeepers for retail and distributor partners.
-
Product launches from leading ingredient suppliers expand the menu of claims and functional formats available to brands, reducing technical barriers to entry but increasing the need for brand differentiation.
Report contents — practical, actionable deliverables
PW Consulting’s Pet Food Insect Protein Market report is designed for executives who must translate market trends into board-level decisions in 2026. The analysis is intentionally operational and includes:
-
Robust market sizing and top-line forecasts (2020–2032) with scenario variants reflecting regulatory shifts, feedstock constraints, and pricing volatility.
-
Supply-chain due diligence: feedstock sourcing maps, processing-capacity analyses, margin waterfall for ingredient grades, and unit-cost benchmarking.
-
Regulatory playbook summarizing approvals, claims-per-market, and time-to-authorization estimates so legal and regulatory teams can prioritize dossier filings.
-
Commercial playbooks: go-to-market strategies for B2B ingredient suppliers and B2C brands, retail adoption frameworks, and pricing/packaging experiments calibrated to consumer willingness-to-pay.
-
Partner and supplier shortlist: profiles and commercial suitability assessments for leading producers, including investment, co-development, and off-take options (note: the public summary omits the detailed shortlists and proprietary scoring matrix available in the full report).
-
Investment decision tools: financial models, sensitivity analyses, and M&A readiness checklists designed to accelerate deal diligence.
-
Risk matrix and mitigation playbooks covering biological risk, regulatory change, consumer sentiment shocks, and commodity feedstock pressure—and recommended monitoring KPIs for executive dashboards.
Priority actions for 2026 (recommended roadmap)
-
Execute secure supply agreements with tier-1 producers while negotiating options for capacity expansion or first-refusal for additional tonnes as plants ramp up.
-
Fast-track regulatory filings where commercial pilots prove palatability and nutritional claims, using pilot-market learnings to accelerate global rollouts.
-
Invest in branded propositions that convert sustainability into repeatable consumer behavior—e.g., subscription models, targeted treat lines, and veterinary-endorsed positioning for hypoallergenic niches.
-
Integrate cost-to-serve and raw-material scenarios into 2026 P&L and working-capital planning—the price environment for premium BSF grades and mealworm proteins will remain a determinant of margin expansion.
-
Consider bolt-on acquisitions in ingredient processing or distribution to secure route-to-market and to capture incremental margin as volumes scale.
Why PW Consulting — and next steps
Our report synthesizes primary interviews with producers, brand leaders and regulators, proprietary cost models, and scenario-driven forecasts to deliver an execution-oriented intelligence package. For executives preparing 2026 capex, M&A, commercial, or R&D decisions, this is not an academic exercise: it is a practical blueprint for where to allocate capital, which partnerships to prioritize, and how to de-risk rollouts.
To obtain the full report (which includes the detailed segmentation tables, regional and application splits, supplier shortlists with scoring, and downloadable financial models), visit the PW Consulting insights page linked in the accompanying distribution or contact our research team to arrange a briefing and tailored deep-dive for your organization.
For detailed analysis of this topic, please visit the official page: Pet Food Insect Protein Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gluten‑Free Baking Flour Market Poised to Expand at an 8.35% CAGR Through 2032
By PW Consulting, 2026-08-12
Gluten-Free Baking Flour Market: Strategic Preview for 2026 — Actionable Insights from PW Consulting
As companies set priorities for 2026, the gluten-free baking flour market presents both a clear growth runway and a set of nuanced operational challenges that will determine winners and laggards. PW Consulting’s new market study — built from a five-year historical baseline and a 2026–2032 forecasting horizon — provides executives with the directional intelligence required to make high‑confidence decisions next year. This article summarizes the report’s strategic value, outlines high‑impact themes, and previews the practical toolset included in the full study (available on our website). Consider this a tactical trailer: we reveal the forces shaping the market and the choices they create, while reserving the granular segmentation tables and proprietary model outputs for report subscribers.
Human Sperm (PSA) Detection Kit Market
Why 2026 is a Pivotal Year
The global gluten‑free baking flour market has transitioned from a niche health trend to mainstream food–ingredient growth. Our model places the market at approximately USD 5.2 billion in 2025 and projects persistent expansion driven by consumption shifts, product innovation, and retail channel evolution. Under our baseline scenario, the market grows at a compound annual growth rate (CAGR) of about 8.35% through the 2026–2032 forecast window, reaching north of USD 9 billion by 2032. That trajectory creates meaningful opportunity for scale players, ingredient suppliers, and premium artisanal brands alike — but it also raises the bar on supply chain discipline, regulatory compliance, and brand differentiation.
Worldwide Switch Adjustment Charge Pump Market
High‑Level Market Architecture and Competitive Dynamics
-
Market structure: The sector exhibits moderate concentration. The top three firms account for a material share of market revenue and the top five extend nearly half of the market’s sales, indicating room for both national brands and regional specialists to coexist.
3D Printed Ankle Foot Orthoses Market -
Competitive archetypes: Across retail and commercial channels we observe three repeatable strategies — (1) heritage brands leveraging trust and scale to own mainstream retail; (2) premium specialists positioning on functionality and chef‑grade performance; and (3) ingredient suppliers and co‑packers addressing commercial bakers and private‑label programs.
-
Recent signals: Quality‑control incidents and allergen recalls in 2024–2025 have elevated buyer scrutiny and accelerated investments in cross‑contact prevention and traceability. Regulatory momentum — including ongoing rulemaking and consultation on cross‑contact prevention — will convert a soft risk into a procurement and manufacturing requirement for many firms in 2026.
What PW Consulting’s Report Delivers (Practical, Non‑Theoretical)
Our study is designed for immediate operational use by CPG strategy teams, procurement heads, commercial bakers, M&A groups, and R&D leaders. Key deliverables include:
-
Demand scenarios and revenue model: Three demand scenarios (base, upside, downside) with monthly resolution for 2026 to help sales planning and capacity allocation.
-
Price and input deck: A raw‑material price tracker and sensitivity analysis spotlighting rice, almond, and coconut flour cost dynamics and margin implications for common blend formulations.
-
Supply‑chain playbook: Step‑by‑step guidance to reduce cross‑contact risk, build scaled segregation at ingredient inflows, and implement low‑cost traceability for co‑packers.
-
Go‑to‑market templates: SKU rationalization criteria, modern trade negotiation levers, and e‑commerce conversion tactics tailored to gluten‑free consumers.
-
M&A and partnership shortlist: A prioritized targets list and valuation frameworks for bolt‑on acquisitions and tolling relationships — built around capability, footprint, and regulatory posture.
-
R&D and formulation playbook: Practical recipes for 1:1 substitution blends, instructions for achieving repeatable crumb structure, and ingredient swap tables with cost/quality tradeoffs.
-
Regulatory compliance checklist: Operational controls aligned to current labeling rules and best practices for managing an extended regulatory comment period on cross‑contact prevention.
Raw Materials and Margin Levers
Ingredient selection is the single most important determinant of product economics and consumer experience. Rice flour remains a foundational base for many blends, supported by its neutral flavor and fine texture; industry estimates put the global rice flour market in a scale that reinforces its centrality to gluten‑free blends. Almond‑based options, particularly blanched almond flour, command a measurable premium in texture and mouthfeel — blanched product typically clears a 15–25% price premium over natural almond flour — and so offers a clear route to premiumization if procurement and margin strategies are aligned.
For commercial bakers and ingredient suppliers, the strategic choices are straightforward but not easy: secure diversified raw‑material contracts to reduce spot exposure, evaluate partial vertical integration where grain sourcing is strategic, and codify specification standards to avoid costly allergen recalls and product withdrawals.
Regulation and Quality: From Reactive to Defensive Advantage
Regulatory clarity around gluten thresholds remains one of the strongest demand enablers for market growth. Current labeling rules continue to define a threshold for “gluten‑free,” while regulators are actively soliciting stakeholder input on cross‑contact prevention protocols. Firms that invest in upstream segregation, validated sanitation protocols, and continuous monitoring will not only reduce recall risk but will also earn preferred supplier status with large retailers and foodservice customers.
Our operational checklist converts compliance obligations into revenue protections: validated cleaning regimes, contract language for third‑party tollers, allergen testing frequency calibrations, and consumer-facing transparency that reduces shopper hesitation.
Competitive Brief (What the Major Players Signal for 2026)
-
Bob’s Red Mill Natural Foods — a leader in dedicated gluten‑free production, offering wide ranges of 1:1 baking flours and specialty blends. Their model underscores the value of dedicated facilities in managing cross‑contact risk and brand trust.
-
King Arthur Baking Company — emphasizes functional 1:1 substitution blends for home bakers, demonstrating the power of recipe engineering and educational marketing to broaden usage occasions.
-
Cup4Cup — niche premium multipurpose blends positioned for professional performance, showing how culinary provenance can support price premiums in foodservice and artisan retail channels.
-
General Mills — brings scale and retail distribution muscle to the category through branded mixes and mainstream accessible offerings; a reminder that category growth attracts large CPG play.
-
Cargill and ADM — represent the supply‑side backbone, enabling commercial bakers with bulk flours and tailored ingredient solutions; their participation highlights the importance of B2B contracting and co‑development.
-
Ardent Mills and Hain Celestial (Arrowhead Mills) — embody blended strategies that span commercial and retail offers, focusing on ancient‑grain positioning and organic/premium claims.
Together, these archetypes illustrate where to compete: trust and scale in mainstream retail, performance and provenance in premium segments, and commodity‑grade reliability for large commercial bakers.
Risk Matrix and Early‑Win Tactics for 2026
-
Operational risk: Allergen cross‑contact and supplier traceability. Early win: implement two‑tiered testing (supplier audit + incoming goods test) for high‑risk ingredients.
-
Input‑price volatility: Nut and grain prices can swing rapidly. Early win: lock partial forward coverage for premium inputs and negotiate volume flex with co‑packers.
-
Channel shift: E‑commerce continues to gain share as consumers seek specialty formulations. Early win: launch a direct‑to‑consumer pilot with subscription bundles and targeted content that reduces CAC.
-
Reputational risk: Recalls can erode brand goodwill quickly. Early win: pre‑position crisis playbooks and consumer remediation protocols to shorten response times.
How to Use This Intelligence in Boardroom Decisions
For CEOs and boards, the report’s top strategic levers for 2026 condense to three choices:
-
Invest to secure margins — through procurement excellence and formulation engineering that optimize premium vs. value SKUs.
-
De‑risk supply and compliance — by moving from audit‑light supplier networks to validated, segmented supply chains with contractual protections and contingency stock.
-
Differentiate through experience — by converting functional parity into brand preference via packaging, recipe content, and culinary partnerships that showcase superior bake performance.
Each lever maps to concrete KPIs in the full report: margin workflows, supplier scorecards, SKU productivity thresholds, and a recommended 12‑month rollout calendar to operationalize investments without overextending working capital.
Concluding Perspective and Next Steps
The gluten‑free baking flour market in 2026 is not an abstract growth story; it is a set of tradeoffs executives must manage between scale, quality, and authenticity. With a multi‑billion‑dollar base and an 8.35% CAGR through the forecast horizon, the category will reward disciplined operators who pair product innovation with operational rigor. At PW Consulting we designed this study as a practical instrument: to be unpacked by strategy teams as they define budgets, prioritize R&D, and evaluate M&A through 2026.
To access the full evidence base — including our proprietary segmentation matrices, supplier scorecards, and the downloadable playbooks referenced above — visit the report page on the PW Consulting site. The complete report contains the granular forecasts and model inputs necessary to run sensitivity analyses and to build customized scenario plans for your business unit.
For bespoke briefings, scenario tailoring, or to commission a focused supplier due‑diligence engagement aligned to the PW model, contact our industry team. Our consultants can convert these insights into an executable 12‑month plan targeted to your market position and ambition.
For detailed analysis of this topic, please visit the official page: Gluten-Free Baking Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


