



Category: Healthy Lifestyle
PW Consulting: Aldosteronism Treatments Market Poised to Grow at a 5.5% CAGR Through 2032, Says New Report
By PW Consulting, 2026-07-13
Aldosteronism Treatments Market 2026: Strategic Intelligence for Execution — PW Consulting Insight
Executive snapshot
As health systems recalibrate care pathways and pharmaceutical portfolios in response to shifting clinical guidelines and breakthrough approvals, our new Aldosteronism Treatments Market report delivers the kind of actionable intelligence executives need to make high-confidence decisions in 2026. Anchored on a 2025 base year, our macro forecast shows the global market growing at a steady compound annual growth rate (CAGR) of 5.5% through 2032, expanding from roughly USD 2.15 billion in 2025 to just over USD 3.12 billion by 2032. That trajectory reflects not only secular demand for proven mineralocorticoid receptor antagonists (MRAs) and potassium-sparing diuretics, but also the emergence of novel mechanism entrants that will reshape therapeutic choice and payer dynamics.
Aldosteronism Treatments Market
Why 2026 is a pivotal inflection point
Three intertwined developments make 2026 a strategic watershed for companies operating in aldosteronism and related hypertensive indications:
Aldosteronism Treatments Market
- Clinical-guideline momentum: The Endocrine Society’s 2025 guideline update elevated the clinical profile of primary aldosteronism screening and reaffirmed MRAs (particularly spironolactone) as a foundational medical therapy. This has accelerated demand signals from specialty care and primary care alike — but also sharpened price and access scrutiny across payers.
- Regulatory innovation: The May 2026 FDA approval of baxdrostat (Baxfendy), the first-in-class aldosterone synthase inhibitor for add-on uncontrolled hypertension, broadens clinical choices and creates immediate commercial questions about positioning in primary aldosteronism management, where trials are ongoing.
- Generic backbone and supply stability: Established generic suppliers continue to anchor treatment affordability and reimbursement pathways, preserving broad access while exerting margin pressure on originator brands.
What the report delivers — practical, transaction-oriented outputs
PW Consulting’s report is designed not as academic narrative but as an operations playbook for 2026 decision-makers. Key components include:
Aldosteronism Treatments Market
- Proprietary market sizing and an auditable forecast model (2026–2032) that integrates incidence/prevalence trends, screening uptake projections and therapy-mix scenarios to quantify upside and downside cases.
- Scenario-based commercial models for novel entrants versus generic incumbents, enabling CFOs and commercial leads to stress-test price erosion, formulary acceptance and net revenue outcomes under alternative access environments.
- A validated competitive map with tactical dossiers for the principal market participants — including originator and generic players — assessing pipeline positioning, lifecycle levers and likely go-to-market strategies.
- Regulatory and reimbursement playbooks tailored to major payer archetypes, with step-by-step recommendations for reimbursement dossiers, evidence generation sequencing and contracting approaches.
- Launch and HCP engagement checklists that convert trial readouts and guideline changes into measurable demand-creation and adoption milestones.
- Risk matrices addressing manufacturing and API continuity, pricing pressures, and real-world safety surveillance commitments that affect commercialization timelines and valuation.
Competitive landscape — who matters (and why)
The competitive environment combines established branded players, high-profile novel entrants and a deep pool of generics manufacturers. Understanding each archetype’s strategic objectives is essential to designing effective commercial and partnering decisions in 2026:
- Major branded incumbents: Companies with marketed MRAs (including long-standing drugs) retain durable clinical credibility and established formulary channels. Their priorities in 2026 will be defending share through evidence generation, indication expansion where permissible, and selective lifecycle pricing.
- Innovator entrants: The approval of baxdrostat is the clearest example of how a novel mechanism can alter clinical algorithms. Innovators with pipeline molecules will need differentiated positioning (e.g., patient subpopulations, biomarker-driven use) and a compelling health-economic narrative to displace entrenched generics.
- Generics and contract manufacturers: A robust generic supply base underpins competitive pricing and payer willingness to reimburse. Generics providers will compete on cost, supply reliability and tender responsiveness — making them essential partners or adversaries depending on corporate strategy.
For executives evaluating alliances, licensing or M&A, the report’s company dossiers synthesize product portfolios, regulatory status, and near-term launch catalysts across the competitive set.
Market dynamics and drivers to watch in 2026
Several interdependent dynamics will determine commercial outcomes over the next 12–36 months:
- Screening and diagnosis rates: Uptake of systematic screening pathways materially expands addressable patient populations. Segments tied to improved detection will see disproportionate revenue impact versus those reliant on routine hypertension care.
- Guideline-driven prescribing: With guideline updates favoring particular MRAs for primary aldosteronism, real-world utilization patterns may shift without immediate price changes — but cumulative impact on volume is significant.
- Payer negotiation environment: Generic availability moderates list prices and accelerates formulary placement; novel entrants must therefore build robust value dossiers and prepare for outcomes-based contracting or restricted access in early years.
- Clinical evidence flow: Near-term readouts from trials of aldosterone synthase inhibitors in primary aldosteronism will be determinative for label expansion and commercial adoption; our timeline models show staggered inflection points tied to these data releases.
- Supply-chain resilience: The generic API market is mature but requires active mitigation of single-supplier risk for certain intermediates; contract manufacturing contingency planning remains a hands-on priority.
Strategic imperatives for 2026 — recommended actions
Executives can translate market insights into immediate actions. The following are priority plays we recommend for different corporate archetypes:
- Innovator pharma with late‑stage assets — Accelerate targeted evidence generation. Prioritize head-to-head or add-on studies in well-phenotyped primary aldosteronism cohorts to demonstrate incremental benefit versus MRAs. Build a payer-value dossier that quantifies hospitalization avoidance, diagnostic-driven cost offsets, and patient-centric outcomes.
- Branded market defenders — Deploy lifecycle management that combines real-world evidence (RWE) programs, line-extension strategies and selective value-based agreements. Emphasize safety and long-term outcomes where generics cannot match trial-backed claims.
- Generic manufacturers — Strengthen tender-response capabilities and secure multi-supplier API contracts. Differentiate on supply reliability and bundle services (e.g., adherence programs) that raise switching costs for institutional buyers.
- Private equity and corporate development teams — Use the report’s scenario models to stress-test acquisition targets: evaluate not only current market share but also the target’s evidentiary assets, payer relationships and manufacturing footprints that protect cash flows under margin compression.
- Market-access and commercial teams — Prepare tiered launch plans that define payer-subpopulation segmentation, milestone-based contracting frameworks and HCP education campaigns timed to guideline and trial catalysts.
Actionable timing: a 12–24 month calendar
Timing matters. Our report maps a pragmatic calendar for 2026 commercial moves tied to regulatory, guideline and trial-event milestones. Highlights include:
- Immediate (0–6 months): finalize reimbursement strategy templates, secure API supply agreements, and initiate RWE protocols keyed to guideline recommendation changes.
- Medium term (6–18 months): deploy selective payer pilots and outcomes-based contracts for novel entrants; prepare segmented marketing campaigns for high-yield specialist channels.
- Longer term (18–36 months): scale manufacturing post-launch, extend indications supported by pivotal readouts, and consider consolidation opportunities if consolidation economics are favorable.
Why this report is strategically valuable for 2026 decisions
Senior leaders told us they need four things from market intelligence in 2026: speed, practicability, strategic clarity and defensibility. This report delivers all four. Our blend of auditable market sizing (with transparent assumptions), scenario-based commercial economics, competitor dossiers, and a prioritized action plan turns broad market trends into executable initiatives — while preserving the commercial confidentiality required for high-stakes negotiations.
What we deliberately withhold — and why
In line with our “trailer” approach, this public briefing signals the lines of opportunity and risk without reproducing the granular, proprietary segmentation tables and payer-specific price models that underpin transaction-level decisions. Buyers of the full report receive the detailed regional and product-split matrices, downloadable model workbooks, and supplier-level supply-chain maps necessary to operationalize the recommendations. This preserves the competitive value of the dataset and enables customized consulting engagements where required.
Next steps — how to use our work
For teams preparing budgets, launches, or M&A due diligence in 2026, we recommend three immediate steps:
- Obtain the full report and model workbook to run company-specific scenarios against our baseline and stress cases.
- Set up a PW Consulting strategy workshop to convert report recommendations into an internal 90‑day execution plan aligned to your commercial, regulatory and manufacturing calendars.
- Engage our market-access specialists to draft payer- and HTA-tailored evidence packages in parallel with ongoing clinical programs.
Closing
The Aldosteronism Treatments Market in 2026 presents a rare combination of steady baseline growth and disruptive opportunity. Between durable generics, a changing guideline landscape, and the arrival of novel mechanisms, the choices companies make this year will determine competitive positioning for the next decade. PW Consulting’s report brings the evidence, scenarios, and pragmatic playbooks executives need to act — while protecting the proprietary detail that turns insight into commercial advantage. Contact our research team to license the full report and model, and schedule a tailored strategy session to align these insights to your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Aldosteronism Treatments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Purpura Treatment Market to Grow at 5.85% CAGR — From USD 520.0 Million in 2025 to USD 774.21 Million by 2032
By PW Consulting, 2026-07-13
Purpura Treatment Market 2026: Strategic Imperatives from PW Consulting’s New Research
PW Consulting’s latest market study, Purpura Treatment Market: Competitive Dynamics, Access Constraints and Strategic Options (base year 2025), delivers an actionable intelligence package designed for executive teams making critical decisions in 2026. Drawing on a full historical review (2020–2025) and forward projections through 2032, this briefing highlights the high-level market trajectory, disruptive regulatory and clinical events of 2025, and the near-term choices that will determine winners and laggards across the purpura treatment value chain.
Purpura Treatment Market
Market trajectory at a glance
The purpura treatment market demonstrated resilient growth through the first half of the decade, expanding from USD 391.33 Million in 2020 to USD 520.00 Million in 2025. Our baseline forecast projects continued expansion through 2032, with a compound annual growth rate (CAGR) of 5.85% over the 2026–2032 horizon and an expected market size approaching USD 774.21 Million by 2032. That mid-single-digit CAGR masks important structural shifts: product-class evolution, changing label footprints, and payer-driven utilization rules that are re-shaping where and how value is captured.
Purpura Treatment Market
Why 2026 is a strategic inflection point
-
Regulatory momentum in 2025 altered the addressable population and commercial pathways. Several approvals and indication expansions broadened pediatric and later-line options, creating fresh opportunities — and new reimbursement complexity — for manufacturers.
Purpura Treatment Market -
Therapeutic innovation is moving beyond incremental differentiation to mechanism-driven segmentation. New entrants and novel MOAs (e.g., BTK and FcRn modulators) are shifting treatment algorithms for chronic and refractory patients, prompting payers and clinicians to re-evaluate sequencing rules.
-
Supply-side constraints — most notably for IVIG therapies reliant on human plasma collection and fractionation — are elevating operational risk and creating strategic leverage for manufacturers that can secure stable supply chains or invest in alternative biologic platforms.
Key 2025 developments that change 2026 playbooks
-
Regulatory approvals expanded therapeutic choice: the approval of the first BTK inhibitor for adults with persistent or chronic immune thrombocytopenic purpura (ITP), and the pediatric approval of certain thrombopoietin receptor agonists, both materially change commercial and clinical positioning.
-
Positive late-stage data from combination approaches and biologic agents suggest potential to reshape standard of care in subpopulations previously managed primarily with corticosteroids, immunosuppressants or IVIG.
-
Ongoing legal and commercial activity for established small-molecule agents continues to affect market access strategies — influencing formulary placement and contracting tactics in core developed markets.
Competitive landscape: who matters and why
The purpura treatment market exhibits a moderate concentration among leading biopharma companies, but therapeutic leadership is dynamic. Our report examines the strategic positioning and near-term prospects of the following firms, each of which plays a distinct role in shaping market structure and access:
-
Amgen Inc. — strong presence in thrombopoietin receptor agonists with established franchise products that continue to serve as anchor therapies for chronic and relapsed patient cohorts. Commercial continuity and lifecycle planning will be central to defending share.
-
Novartis AG — advancing combination strategies and late-stage programs that, if approved, could reframe prior-treatment expectations and influence sequencing alongside TPO-RAs.
-
Swedish Orphan Biovitrum (Sobi) — now positioned with expanded pediatric labeling and formulation innovations that improve patient adherence and broaden the addressable population.
-
Sanofi — the entry of a BTK inhibitor for adult chronic/persistent ITP represents a novel oral mechanism in this treatment continuum, with implications for both inpatient and outpatient management pathways.
-
Rigel Pharmaceuticals — continues to commercialize a SYK inhibitor in chronic ITP while navigating intellectual property and market defense activities that affect availability and pricing dynamics.
-
Grifols S.A. — a principal provider of IVIG therapies; its supply chain characteristics and donor-dependence create systemic exposure to plasma availability and fractionation throughput.
-
argenx SE — as a pioneer in FcRn blockade, the company’s biologic adds an important non-traditional MOA for immune-mediated purpura cases, and experience in differentiated labeling and reimbursement negotiation will be instructive for peers.
Each company’s strategic playbook — including lifecycle management, label expansion, formulary negotiation, and supply security — is analyzed in the full report. Our case-level assessments link clinical trial results, regulatory milestones and operational moves to near-term revenue and access scenarios.
Practical, operational content in the full report
PWC’s (PW Consulting’s) Purpura Treatment Market report is intentionally designed to be a working tool for commercial, medical affairs, market access and corporate development teams. Key deliverables include:
-
Top-down and bottom-up forecasting models from 2026–2032, with scenario variants that isolate the impact of major regulatory approvals, payer policy shifts and supply disruptions.
-
Commercial playbooks detailing pricing, tendering and contracting strategies across major reimbursement archetypes, including decision trees for prior-authorization and step-therapy responses.
-
Go-to-market blueprints for new molecular entities, covering label positioning, high-value investigator networks, and targeted pediatric engagement plans where recent approvals have expanded eligibility.
-
Supply chain stress tests and mitigations for plasma-derived products, including inventory planning templates and strategic partner assessment frameworks.
-
Competitive reaction matrices that translate trial readouts, legal outcomes and product launches into plausible competitor moves and countermoves.
-
Customizable dashboards and data tables (regional, channel and product-class splits) that enable executives to prioritize investments without re-running the model.
To preserve the report’s commercial value for paying clients, the public summary intentionally omits granular regional and segment-by-segment revenue breakdowns. Executive teams requiring those line-item tables will find them in the full report package, downloadable from our website.
How executives should use this analysis in 2026
-
R&D and portfolio prioritization — Re-score pipeline assets against newly validated mechanisms (e.g., BTK, FcRn) and allocate trial resources to indications and combinations that open differentiated label pathways.
-
Market access and pricing strategy — Anticipate stricter prior-authorization criteria; design payer dossiers that emphasize head-to-head clinical benefit, real-world bleeding-risk reductions and total cost of care.
-
Commercial focus and segmentation — Reassess field deployment and specialty pharmacy partnerships to capture pediatric populations and outpatient shifts driven by oral therapies.
-
Supply chain resilience — For IVIG-dependent portfolios, institute plasma sourcing contingencies, alternative manufacturing partnerships, and demand-smoothing contracts with large buyers.
-
M&A and partnership screening — Target assets that reduce reliance on constrained raw materials, accelerate biologic manufacturing capability, or offer access to pediatric formulations.
-
Regulatory and legal readiness — Build contingencies for accelerated approvals and patent disputes that can affect market windows and exclusivity duration.
Implications for investors and partners
Investors should view the purpura treatment sector as a growth market characterized by selective pockets of high strategic value: mechanism-first biologics, pediatric-enabling formulations, and stable plasma-sourcing platforms. The mid-single-digit CAGR belies the asymmetric upside possible for companies that secure differentiated labels and payer coverage in key subsegments. Conversely, firms that fail to adapt to evolving sequencing expectations or secure supply may face compression in realized prices and volumes despite nominal market expansion.
What we recommend next
-
Immediate: Convene cross-functional scenario workshops using the report’s downloadable baseline and downside cases to stress-test 2026 budgets and launch plans.
-
Near-term: Engage with PW Consulting for a tailored session that maps your portfolio against the report’s competitor reaction matrices and supply-risk index.
-
Commercial: Re-align payer-value messages to reflect 2025 regulatory changes and ensure evidence packages are updated for pediatric and refractory subpopulations.
Accessing the full intelligence
This release is a strategic preview intended to signal where value will be created and captured across the purpura treatment market through 2032. For clients requiring the full set of model outputs — including regional splits, product-class allocations and company-level revenue estimates — the complete report, interactive dashboards and client workshop options are available on our report page. Visit our website to download the complete dossier and schedule a briefing with PW Consulting’s purpura treatment practice.
For detailed analysis of this topic, please visit the official page: Purpura Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Lacrimal Stent Tube Market to Surge to USD 317.85 Million by 2032, Growing at a 5.48% CAGR
By PW Consulting, 2026-07-13
Lacrimal Stent Tube Market 2026 — Strategic Trailer for Executive Decision-Making
Executive summary
PW Consulting’s latest market research on the lacrimal stent tube market establishes a clear trajectory for industry participants preparing strategy in 2026 and beyond. Using 2025 as the analytical base year, the global market is estimated at approximately USD 218.5 Million and is forecast to grow to roughly USD 317.9 Million by 2032. This expansion reflects a compound annual growth rate (CAGR) of about 5.48% across the 2026–2032 forecast window. These headline figures anchor a broader narrative: a steady, clinically driven market with room for product innovation, selective consolidation, and commercial expansion — particularly for firms that align clinical evidence, regulatory readiness, and reimbursement strategy into a single go-to-market plan.
Lacrimal Stent Tube Market
Why this report matters for 2026 strategic planning
-
Timing for investment: The mid-single-digit CAGR signals a market that rewards targeted, not scattershot, investment. Companies must prioritize initiatives that accelerate adoption within established clinical pathways rather than pursuing broad, undifferentiated expansion.
Lacrimal Stent Tube Market -
Regulatory and reimbursement are value levers: Given the predominance of 510(k)-eligible device filings and the presence of a discrete CPT code for lacrimal intubation procedures, companies that synchronize regulatory filings with reimbursement engagement will shorten sales cycles and improve commercial uptake.
Lacrimal Stent Tube Market -
Clinical evidence differentiates premium positioning: Incremental improvements in stent materials, coatings, or procedural adjuncts can translate into durable pricing and preference when backed by compelling clinical data.
-
M&A and portfolio plays: Market concentration metrics indicate a moderately concentrated market; strategic acquisitions or exclusive distribution partnerships can materially improve share and channel control for mid-sized players.
Market dynamics and practical implications
The lacrimal stent tube market is being shaped by predictable clinical demand, material science refinements, and procedural coding that supports economic viability for surgeons and facilities. Several operational and regulatory realities should frame 2026 decisions:
-
Regulatory pathway: Most lacrimal stents and intubation sets fall under FDA Class II device pathways and are commonly cleared through 510(k) submissions. Firms planning product introductions should budget for thorough bench and comparative testing aligned to 510(k) expectations and build early dialogue with notified bodies for non‑US rollouts.
-
Reimbursement environment: A CPT code exists for probing with stent insertion, which simplifies the commercial discussion with payors. However, clinical coding alone does not guarantee optimal hospital formularies — manufacturers need value dossiers and hospital economic models to drive OR adoption.
-
Material and sterilization: Silicone remains the dominant material due to biocompatibility and handling characteristics; suppliers should continue to invest in medical-grade silicone formulations and validated sterilization processes (radiation or otherwise) that meet ISO standards, while ensuring sterile single-use labeling and supply-chain traceability.
-
Clinical usage patterns: Stents are typically temporary to maintain patency during healing periods but certain bypass procedures require long-term solutions; product line strategies should address both temporary and durable use cases with differentiated evidence packages.
Competitive landscape — what the market structure tells us
The market exhibits moderate concentration (CR3 approximately 45.2%, CR5 approximately 58.7%), indicating that while a handful of companies command meaningful share, opportunity exists for challengers who execute well on clinical, regulatory, and commercial fronts. Key incumbent profiles reviewed in the report include:
-
FCI Ophthalmics (Pembroke, MA, USA) — a comprehensive lacrimal portfolio including self-retaining and monocanalicular systems; ongoing focus on expanding plug and stent offerings and on clinical engagement to support adoption.
-
Kaneka Medical (Osaka, Japan; US operations) — offers hydrophilic-coated, self-retaining stent systems targeted at congenital and acquired nasolacrimal duct obstruction; product differentiation emphasizes ease of use and insertion performance.
-
bess medizintechnik (Germany) — European instrumentation and stenting solutions for ENT and ophthalmic surgeons, positioning through surgical instrument ecosystems and service support in head-and-neck procedures.
-
Aurolab (Madurai, India) — cost‑competitive silicone intubation kits aimed at high-volume settings and emerging markets, with a focus on clinical staples such as DCR and canalicular repair.
-
Gunther Weiss Scientific Glassblowing Co. (Hillsboro, OR, USA) — a legacy provider of specialized glass Jones tubes for bypass procedures, reflecting niche but durable demand for non-silicone long-term solutions.
-
Beaver-Visitec International (BVI Medical, Waltham, MA, USA) — part of a broader ophthalmic surgical portfolio; recent portfolio strengthening gestures indicate a platform approach to specialty procedural markets including lacrimal care.
Recent company moves documented in our research — portfolio strengthening at a major ophthalmic platform, continued product focus and conference presentations by leading stent manufacturers — underline a competitive environment where clinical visibility and breadth of offering matter.
What the full report contains — practical, executable tools
Designed for strategy teams, business development leaders, and clinical affairs groups, the full PW Consulting report delivers actionable intelligence without the noise. Highlights include:
-
Validated market sizing (historical and forecast) with an integrated Excel model for scenario testing across price, volume, and adoption assumptions.
-
Segmentation analytics by channel, product type, and clinical application, with sensitivity tables (note: segmented revenue tables and percent splits are proprietary within the report).
-
Regulatory map and filing playbook — a checklist for 510(k) readiness and global filing sequencing.
-
Reimbursement and hospital procurement playbook — sample value dossiers, OR economics calculators, and payer engagement templates.
-
Competitive profiles with capability maps, product feature comparisons, and acquisition target shortlisting.
-
Supply-chain and manufacturing risk assessment tailored to medical-grade silicone and sterilization operations, including ISO-compliance review points.
-
Commercial launch and adoption playbook — surgeon training models, KOL engagement strategies, and distributor selection criteria.
-
Strategic scenarios and M&A valuation frameworks calibrated to market concentration and growth dynamics.
These deliverables translate the market’s macro growth (CAGR and headline revenue path) into operational decisions and KPIs for 2026 execution.
Actionable strategic recommendations for 2026
-
Prioritize platform differentiation through evidence: Fund a focused clinical series that demonstrates improved clinical outcomes or OR efficiency — even modest gains can justify premium pricing and preferential formulary placement.
-
Sequence regulatory filings to minimize time-to-revenue: Treat 510(k) submissions as cross-functional projects; align bench validation, sterilization validation, and labeling early to avoid rework.
-
Leverage reimbursement mechanics: Use the existing CPT coding as a baseline but create hospital-level ROI calculators and bundled pricing models for ambulatory surgery centers.
-
Consider bolt-on M&A or exclusive distribution to accelerate scale: Given the market’s mid-level concentration, strategic acquisitions can double down on channel control and access to OR networks.
-
Optimize supply-chain resilience: Secure medical-grade silicone supply and validated sterilization capacity; pilots for alternative materials/coatings should include manufacturability gates.
-
Differentiate service offerings: Training, procedure kits, and data-supported follow-up services can create stickiness beyond the device sale.
Closing — why PW Consulting’s perspective is strategic intelligence, not speculation
The lacrimal stent tube market’s predictable growth path and clinical specificity reward disciplined strategy. Our report combines top-line forecasting with granular, transaction-grade analysis to bridge boardroom strategy and field execution. The “trailer” above highlights the strategic implications you need for 2026 planning while preserving the proprietary segmentation, revenue tables, and model outputs that underpin confident commercial decisions.
Next steps
To access the complete report (including proprietary segmentation, downloadable Excel modeling, and the full competitor dossier), contact PW Consulting’s market intelligence team or visit our publications page. For tailored advisory engagements — M&A diligence, regulatory roadmap development, or launch readiness workshops — reach out to our strategy group to schedule a briefing and receive a confidential excerpt of the study.
For detailed analysis of this topic, please visit the official page: Lacrimal Stent Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Green Superfood Market Set to Expand at a 6.95% CAGR Through 2032, Report Says
By PW Consulting, 2026-07-13
Green Superfood Market 2026: Strategic Imperatives for Corporate Decision-Makers
Executive summary
PW Consulting’s new Green Superfood Market report (base year 2025; forecast period 2026–2032) synthesizes quantitative market sizing, competitive intelligence, regulatory dynamics, and actionable go-to-market frameworks to help executives make high-consequence decisions in 2026. The global market, having expanded through the first half of the decade, reached a material scale by 2025 and is projected to grow at a compound annual growth rate (CAGR) of 6.95% across the 2026–2032 forecast window. This expansion reflects both continued consumer demand for nutrient-dense plant-based supplements and an intensifying need for robust quality, supply chain resilience, and differentiated product positioning.
Green Superfood Market
Why this report matters for 2026 planning
2026 will be a year of selective consolidation and rules-based differentiation in green superfoods. Companies will not only compete on formulation and brand storytelling, but increasingly on certifications, traceability, and contamination-proof manufacturing. Our report provides the empirical foundation and the practical playbook that decision-makers need to: prioritize R&D investments, structure procurement contracts for raw materials, rationalize SKUs and channel strategies, and assess M&A targets against realistic synergies and regulatory exposures.
Green Superfood Market
Market trajectory and macro view
After steady growth through 2020–2025, the green superfood market has entered a higher-confidence phase. The market scale reported for 2025 confirms a robust consumer base and a resilient retail channel mix. Under our central forecast, the market is set to expand meaningfully through 2032, underpinned by health-conscious consumption, premiumization trends, and growing e-commerce penetration. The modeled CAGR of 6.95% frames a planning horizon in which mid-term investments in quality systems and brand trust are likely to deliver outsized returns relative to short-term promotional spend.
Green Superfood Market
Key demand and supply drivers
- Consumer health positioning: Continued appetite for daily nutrition and preventive wellness supports recurring purchase behavior for green powders and blends.
- Formulation depth: Ingredient stacks that combine greens, probiotics, adaptogens, and functional botanicals are moving from novelty into expected product features.
- Certification and trust signals: With dietary supplements regulated as foods in many jurisdictions (and lacking pre-market approval), third-party certifications such as NSF and USDA Organic have become decisive purchase filters for mainstream buyers.
- Raw material dynamics: Ingredients such as spirulina remain foundational because of their nutrient density and generally recognized as safe (GRAS) status, but sourcing concentration and crop/regenerative practices are shaping supplier selection and cost profiles.
- Channel complexity: Online retail continues to enable direct-to-consumer scale and product iteration, while brick-and-mortar channels still drive trial and reach among value-conscious cohorts.
Competitive landscape — actionable takeaways
The market remains fragmented: the three- and five-firm concentration ratios indicate limited dominance by a few national brands, leaving room for regional specialists and private label entrants. Strategic implications for incumbents and challengers differ:
- Amazing Grass (Newport Beach, CA): A well-established player with a clear organic and plant-based positioning. Strengths include consumer recognition and an accessible portfolio of supergreen blends. Tactical advice: double down on supply chain transparency and expand clinical substantiation for flagship SKUs to defend shelf and digital visibility.
- Garden of Life (Palm Beach Gardens, FL): Known for nutrient-dense raw organic formulations and broad distribution. Strengths in formulation credibility and retail relationships. Tactical advice: leverage brand trust to pilot subscription models and enhance clinic-to-consumer education to lift lifetime value.
- AG1 / Athletic Greens (Carson City, NV): Positioned as a premium, research-forward daily greens drink with extensive ingredient layering and sports certifications. Recent product updates emphasize probiotics and flavor innovations. Tactical advice: reinforce clinical claims with published trials and consider tiered SKUs to broaden addressable consumer segments without diluting premium perception.
- Navitas Organics, Sunfood, Terrasoul, Suncore Foods: These ingredient- and product-focused firms play critical roles across the value chain. They excel with organic sourcing claims and supply of bulk ingredients. Tactical advice: companies that control upstream sourcing should monetize traceability (e.g., traceable QR codes, regenerative sourcing premiums) to capture margin and strengthen buyer relationships.
Recent shock events and regulatory noise
Early 2026 recalls tied to potential Salmonella contamination in several green superfood products have materially shifted the risk calculus. These events spotlight the dual realities that (1) recalls can rapidly erode consumer trust across brands and categories, and (2) quality systems and upstream testing protocols are now primary competitive differentiators.
- Regulatory environment: dietary supplements remain regulated as food in key markets, meaning products are not subject to pre-approval before market entry. In this context, third-party certifications (e.g., NSF Certified for Sport, USDA Organic) serve as market signals that materially influence consumer purchase intent and retail listing decisions.
- Operational responses: manufacturers and brand owners must prioritize hazard analysis, supplier audits, and retention testing. Investment in audit-ready documentation and rapid-response recall playbooks is no longer optional for national-scale players.
Practical contents in the PW Consulting report (what’s inside)
The report combines market-level analytics with executable tools for practitioners. Highlights include:
- Full market model (historical and forecast) with sensitivity scenarios and downside stress cases to support budgeting and valuation exercises.
- Quality and compliance playbook: templates for supplier qualification, lot-release testing, and recall scenario planning tailored to green powder supply chains.
- Formulation benchmarking matrix that compares ingredient stacks, functional claims, and certification footprints across representative competitive sets.
- Go-to-market blueprints for four archetypal strategies: premium DTC, mainstream retail scaling, ingredient-supplier monetization, and private-label consolidation.
- M&A target-screening algorithm and synergy calculators for potential roll-up strategies in manufacturing, ingredient sourcing, and direct-to-consumer brand consolidation.
- Channel economics models that quantify acquisition cost, repeat purchase rates, and lifetime value by channel archetype (for planning marketing and inventory allocation).
- Executive risk register and mitigation roadmap addressing contamination, raw-material shortages, price volatility, and regulatory shifts.
Strategic playbook for 2026 priorities
- Quality-first capital allocation: Allocate capex to testing labs, traceability systems, and supplier diversification before expanding SKU breadth.
- Certification roadmap: Fast-track certifications that align with target consumer segments—sports certifications for athlete-focused mixes, USDA Organic and regenerative claims for premium wellness audiences.
- Channel mix optimization: Use tiered SKUs to separate trial/entry products from subscription-grade SKUs; invest in retention mechanics for DTC while maintaining strategic retail partnerships for reach.
- M&A and partnership criteria: Prioritize targets that provide vertical control of high-risk raw inputs (e.g., spirulina sourcing) or that add validated manufacturing capacity with strong audit histories.
- Brand trust engineering: Publish third-party test results, implement transparent lot tracking, and use evidence-based marketing (clinical endpoints, not only ingredient lists).
Risk assessment and mitigations
The sector’s key near-term risks are operational (contamination, supplier disruption), regulatory (inconsistent labeling rules across markets), and reputational (high-profile recalls). Mitigants recommended by our analysis include:
- Mandatory supplier scorecards and dual-sourcing strategies for critical ingredients.
- Investment in in-house or partnered analytical testing capacity to reduce time-to-detection and liability exposure.
- Insurance structuring and contractual liability clauses to protect from downstream recall costs.
- Active consumer communication strategies that emphasize traceability and third-party validation.
How to use this report in boardroom decisions
Executives should use the PW Consulting model to stress-test scenarios (e.g., contamination-induced demand shocks, ingredient price surges, accelerated certification uptake) and to align capital allocation with the most defensible long-term value drivers: quality systems, traceable sourcing, and credible scientific substantiation of claims. For private equity and corporate development teams, the report’s valuation and synergy modules enable rapid triage of targets according to realistic integration costs and upside on margin improvement.
Trailer note — where to find the granular tables
To respect the “trailer” approach: this press release intentionally demonstrates analytical depth while withholding granular segment-level tables, regional and application breakouts, and specific price- and channel-level revenue figures. The full PW Consulting Green Superfood Market report contains those detailed tables, downloadable models, and company scorecards. Visit the PW Consulting site to access the complete dataset, Excel model, and the full list of practical templates and checklists described above.
Final thought
2026 will favor organizations that convert market growth into durable competitive advantage by institutionalizing quality, delivering evidence-led formulations, and aligning distribution strategies with consumer trust signals. PW Consulting’s Green Superfood Market report equips leaders with the evidence base and operational templates to make those trade-offs with confidence.
For detailed analysis of this topic, please visit the official page: Green Superfood Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Rotavirus Vaccine Market Poised for Expansion — 5.3% CAGR Projected Through 2032
By PW Consulting, 2026-07-13
Rotavirus Vaccine Market 2026: Strategic Roadmap for Decision-Makers
Executive summary
PW Consulting’s latest Rotavirus Vaccine Market report positions executives and policy-makers to make high-confidence decisions as the market transitions into a new phase of supply stability, product diversification, and incremental demand growth. Drawing on a comprehensive historical review (2020–2025) and a robust forecast to 2032, the report shows the global rotavirus vaccine market expanding at a compound annual growth rate (CAGR) of 5.3%. The market is estimated at approximately USD 2,450 Million in 2025 and is projected to reach roughly USD 3,520 Million by 2032.
Rotavirus Vaccine Market
This briefing highlights the report’s strategic value for 2026: it synthesizes supply-side events, regulatory shifts, donor and national immunization dynamics, and competitive positioning into an executable playbook — while intentionally withholding granular segment-level figures to encourage engagement with the full report for procurement- and entry-specific intelligence.
Rotavirus Vaccine Market
Why this report matters for 2026 decisions
-
Timing: 2026 is the first year of our forecast window and a decision inflection point for manufacturers, procurers, and governments. Investments in capacity, presentation changes, and tender strategies made in 2026 will determine market trajectory and commercial access across the 2026–2032 period.
Rotavirus Vaccine Market -
Predictability: After episodic supply disruptions through 2022–2023, market indicators in 2024–2025 show improving availability. Our scenario analysis quantifies the supply–demand buffer required to avoid country-level stock-outs under conservative and upside demand scenarios.
-
Consolidation pressure: Market concentration is high (CR3 ≈ 88.5%, CR5 ≈ 94.2%), meaning a small set of global and regional players will heavily influence pricing, presentation availability, and procurement negotiations. Strategic partnerships and bilateral supply agreements will be decisive.
-
Innovation horizon: Clinical and formulation innovation (including interest in non-replicating/inactivated approaches and novel delivery technologies) signals a medium-term shift in product profiles that 2026 procurement strategies should begin to accommodate.
Key strategic themes for 2026
-
Supply diversification and presentation strategy — optimize resilience. The return of several liquid and blow-fill-seal (BFS) presentations and planned product transitions require procurement teams to model presentation-specific cold chain volumes, storage costs, and country-level logistic constraints. The report includes a procurement playbook that helps buyers simulate trade-offs between lower cold-chain volume presentations and supplier concentration risks.
-
Transition management for discontinued formats. Manufacturers and donors must manage country transitions that arise from planned discontinuations and presentation changes. Our operational checklist identifies legal, clinical, and communication steps — minimizing vaccination interruption and preserving uptake.
-
Policy alignment with funders and NIPs. New introductions and scale-up in routine immunization continue across low- and middle-income countries with donor support. The report maps programmatic windows when donor funding, national budget cycles, and supply availability align — critical for submitting tenders and negotiating long-term supply agreements in 2026.
-
Commercial strategies for concentrated markets. With three to five firms dominating supply, entrants and incumbent manufacturers must pursue differentiated value beyond price: service-level guarantees, presentation innovation, and localized manufacturing or fill-and-finish partnerships. The report provides a set of negotiation levers and contracting templates designed for high-concentration procurement contexts.
-
R&D and pipeline positioning. Emerging approaches — including inactivated antigens and microarray patch delivery — are moving into early human trials. Firms should prioritize adaptive clinical and regulatory strategies now to shorten time-to-market for next-generation products and create favorable reimbursement narratives.
What the PW Consulting report contains (practical deliverables)
-
Market sizing and high-level forecast (2026–2032) with sensitivity scenarios that stress-test demand shocks and supply interruptions.
-
Procurement playbook: tender design, contractual clauses for supply interruptions, cold chain costing templates, and supplier scorecards tailored to public and private-sector buyers.
-
Go-to-market roadmaps for manufacturers and new entrants: presentation strategy, pricing benchmarks, regulatory pathways, and market access sequencing for priority countries.
-
Operational transition guides for countries switching presentations or suppliers, including clinical communication templates, inventory depletion strategies, and immunization schedule harmonization examples.
-
Competitive intelligence dossiers on leading suppliers with capability matrices, likely capacity expansion timelines, and partnership opportunities. (Note: granular regional and application splits are reserved for the full report.)
-
Supply chain risk register and mitigation options, incorporating cold chain footprint analytics and supplier diversification scenarios.
-
Regulatory & policy playbook: prequalification timelines, dossier harmonization strategies, and payer engagement templates to accelerate national introductions.
Competitive landscape — who matters and why
The industry is shaped by a mix of global multinational vaccine producers and major regional manufacturers. Core companies profiled in the report include:
-
GlaxoSmithKline Biologicals SA — incumbent monovalent live-attenuated supplier with WHO-prequalified presentations and recent regulatory momentum in major markets. Their portfolio and presentation formats (including BFS) are central to many national strategies.
-
Merck & Co., Inc. — provider of pentavalent live oral vaccine options, playing a differentiated role in certain procurement channels outside primary Gavi supply networks.
-
Bharat Biotech International Ltd. — an increasingly influential supplier offering WHO-prequalified monovalent products in multiple presentations, with strong ties to large immunization programs.
-
Serum Institute of India Pvt. Ltd. — pentavalent vaccine manufacturer with significant supply footprints for donor-procured markets; recent product changes require attention from procurement planners.
-
PT Bio Farma — advancing neonatal vaccine candidates intended for national program adoption, representing a possible category shift for neonatal dosing strategies.
-
Lanzhou Institute of Biological Products — maintains licensed, regionally focused presentations with implications for domestic markets and export potential.
Recent industry developments have direct operational consequences for 2026 planning. Notably, our monitoring captured a regulatory update from a major supplier in early 2026; clinical progress on next-generation inactivated candidates in 2025; planned discontinuations of specific lyophilized presentations that started to influence country-level tendering in 2025; and the gradual normalization of supply following disruptions in 2022–2023.
Policy, supply chain, and innovation dynamics
-
WHO prequalification landscape: Multiple WHO-prequalified oral live-attenuated presentations from several manufacturers provide a baseline of quality-assured options, but the reliance on oral live vaccines leaves the market sensitive to shared raw material and cold chain constraints.
-
Cold chain economics: Presentation format materially affects storage and transport costs. Some newer BFS and liquid presentations reduce per-course cold-chain volume — a non-trivial advantage for countries with constrained storage capacity.
-
Introduction pathways: Donor-supported introductions and national immunization program decisions continue to be a major demand driver. PW Consulting’s country-level timing models identify near-term windows where introductions are most feasible from a funding and operational perspective.
-
Innovation trajectory: The emergence of inactivated candidates and microarray patch delivery could reframe long-term access economics and simplify administration. For 2026, monitoring early-phase clinical readouts and regulatory strategies will be essential for R&D prioritization.
Actionable recommendations for 2026
-
Buyers: implement a two-tier procurement strategy — secure medium-term agreements with incumbent suppliers to guarantee baseline supply while selectively tendering for volume-flexible suppliers that offer logistical advantages.
-
Manufacturers: accelerate presentation and cold-chain optimization projects to win tenders where logistic constraints drive procurement decisions; evaluate partnerships for localized fill-and-finish to de-risk supply commitments.
-
Donors & NGOs: prioritize funding windows that align with national budget cycles to maximize introduction success and minimize mid-year programmatic disruptions.
-
Investors & innovators: target early-stage assets that reduce cold-chain dependence or open neonatal dosing windows, and support regulatory pathway acceleration to capture first-mover advantages in next-generation categories.
Conclusion — what to do next
2026 is a decisive planning year. The global rotavirus vaccine market is on a steady growth path (CAGR 5.3% across our forecast period), supply conditions are stabilizing, and product innovation is beginning to reshuffle strategic priorities. PW Consulting’s Rotavirus Vaccine Market report translates these dynamics into executable plans for manufacturers, procurers, funders, and policy teams.
To preserve the report’s role as an operational tool, we have deliberately summarized high-level market sizing and strategic guidance here while reserving detailed segmented data, country-level forecasts, and transactional templates for the full report. These withheld elements — including granular subnational demand estimates, presentation-level cost models, and tender-by-tender readiness checklists — are essential for implementing the 2026 actions described above.
For immediate access to the full dataset, country timelines, and the procurement playbook that will enable confident 2026 decisions, please visit the PW Consulting Rotavirus Vaccine Market report page or contact our advisory team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Rotavirus Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti‑Asthmatics & COPD Drugs Market to Rise from USD 45,500 Million in 2025 to USD 60,686 Million by 2032 on a 4.2% CAGR
By PW Consulting, 2026-07-13
PW Consulting Strategic Brief — Anti‑Asthmatics & COPD Drugs Market Outlook: Positioning for 2026
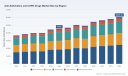
PW Consulting’s latest market intelligence on Anti‑Asthmatics and COPD Drugs synthesizes epidemiology, commercial dynamics, regulatory inflection points, and competitive trajectories to equip life‑science and payer executives for decisive action in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, our proprietary model projects the global market continuing its multi‑year expansion trajectory — from an estimated USD 45,500 Million in 2025 toward a mid‑cycle six‑figure magnitude by 2032 — representing a forecast CAGR of 4.2% across the 2026–2032 period. Market structure remains moderately concentrated (CR3 ≈ 45%, CR5 ≈ 60%), creating both scale advantages for incumbents and niche opportunities for innovators.
Anti Asthmatics And Copd Drugs Market
Why this report is a strategic asset for 2026 decision‑making
-
Actionable forecasting: Our forward‑looking model translates macro demand drivers and policy shifts into pragmatic scenarios that materially affect launch sequencing, capacity planning, and revenue recognition over 2026–2032.
Anti Asthmatics And Copd Drugs Market -
Commercial playbooks: The report converts clinical and payer intelligence into executable go‑to‑market strategies — from evidence generation plans that optimize formulary access, to contracting ladders and channel tactics for inhaler device rollouts.
Anti Asthmatics And Copd Drugs Market -
Regulatory & reimbursement foresight: We integrate late‑breaking regulatory decisions and coding/reimbursement developments to flag near‑term access risks and levers (e.g., product‑specific coding, value‑based contracting and government pricing agreements) that should be negotiated in 2026.
-
M&A and partnership intelligence: By scoring technology clusters, margin profiles and competitive moats, the report identifies the most compelling inorganic and co‑development targets aligned to both respiratory biologics and novel small‑molecule inhaled mechanisms.
-
Risk‑adjusted investment guidance: A mapped risk register and sensitivity testing enables R&D and commercial leaders to prioritize assets with resilient returns under plausible downside scenarios.
High‑level market dynamics shaping 2026
-
Dual innovation vectors: The market is being reshaped by two parallel waves — biologics expanding into phenotype‑driven indications, and novel inhaled mechanisms delivering incremental symptomatic and exacerbation control. These waves create differentiated headroom for premium-priced therapies while putting pressure on commoditized bronchodilator classes.
-
Guideline and diagnostic updates: Recent GOLD updates (2025–2026) and guideline revisions are recalibrating treatment algorithms and diagnostic thresholds, which alters addressable patient populations and shapes prescription patterns across primary care and specialty settings.
-
Reimbursement architecture evolving: Product‑specific coding and payer coding decisions — exemplified by recent J‑code assignments — materially accelerate uptake when coupled with favorable real‑world outcomes, but also raise the bar for post‑launch evidence generation.
-
Sustainability as a procurement criterion: Transition toward next‑generation low‑GWP propellants and device sustainability is now a procurement consideration for large payers and integrated delivery networks; manufacturers that de‑risk transition timelines gain commercial advantage.
-
Pricing pressure and public contracting: Recent pricing agreements and public sector negotiations in major markets signal heightened emphasis on affordability and may compress net pricing for established molecules, shifting strategic focus to value demonstration and differentiated clinical outcomes.
Competitive landscape — strategic implications for incumbents and entrants
-
AstraZeneca — With a comprehensive inhaled portfolio and strategic emphasis on triple therapies, next‑gen propellants and biologics, AstraZeneca combines scale with targeted innovation. Recent presentations of clinical and real‑world evidence underscore their play for both clinical leadership and sustainable device positioning.
-
Boehringer Ingelheim — Device platform strength remains a core asset. The Respimat soft‑mist platform and established maintenance therapies anchor Boehringer’s role in chronic care delivery; their device differentiation supports adherence and product lifecycle extensions.
-
GSK — Single‑inhaler triple therapies and a broad inhaler franchise position GSK to defend share in maintenance care. Recent public pricing agreements highlight a willingness to trade list pricing for volume and formulary access — a dynamic that competitors must model into 2026 contracting strategies.
-
Novartis — Focused on long‑acting bronchodilators and device ergonomics, Novartis competes through incremental therapeutic and device improvements — a playbook suitable for markets where generics and payers prioritize demonstrated adherence benefits.
-
Verona Pharma — The launch of a novel inhaled mechanism represents a rare therapeutic inflection in COPD. Early adoption dynamics and coding/reimbursement wins illustrate the runway for differentiated small‑molecule entrants, provided real‑world effectiveness and access pathways are rapidly established.
-
Sanofi & Regeneron — The extension of biologics into selected COPD phenotypes represents a structural market change: phenotype‑guided therapy creates incremental spend per patient and a new segment of high‑value care where payers will demand biomarker‑linked value propositions.
-
Teva, Merck, Chiesi — Generics and legacy brands sustain volume pools, while regional specialists exploit device and supply chain agility. Their role in pricing and distribution dynamics remains pivotal for payers focused on affordability.
Recent tactical inflection points we track
-
Regulatory expansions of biologic indications for COPD in late 2024 altered the competitive calculus for phenotype‑targeted care.
-
New product‑specific reimbursement codes and early uptake signals for novel inhaled mechanisms are accelerating commercialization timelines for first movers.
-
Publicized pricing agreements by major manufacturers are reshaping negotiation norms and payer expectations for 2026 contracting.
-
Industry commitments to low‑GWP pMDI transitions are prompting manufacturers to accelerate supply chain and device investments to meet 2025–2026 implementation windows.
What the PW Consulting report delivers (practical contents)
-
Executive summary and investor‑grade outlook with scenario outputs calibrated to regulatory and reimbursement contingencies.
-
Detailed market‑sizing model (2020–2025 historical; 2026–2032 forecast) with transparent assumptions, model logic, and sensitivity knobs for price, uptake and adherence.
-
Go‑to‑market playbooks including launch sequencing, RWE generation roadmaps, payer negotiation templates, and promotional channel optimization.
-
Competitive benchmarking and pipeline heatmaps, plus acquisition target screening and valuation heuristics for bolt‑on and transformational opportunities.
-
Regulatory and reimbursement roadmap, mapping guideline changes, coding events and payer policy shifts to likely commercial impact windows.
-
Operational checklists for manufacturing scale‑up, device reformulation (including low‑GWP transitions), and supply‑chain resilience.
-
Interactive dashboards enabling executives to interrogate outcomes under user‑defined policy and market scenarios (note: granular subsegment values and regional splits are reserved for licensed report access).
How to convert insight into decisions in 2026
-
Prioritize evidence investments that unlock reimbursement: For innovators, accelerating targeted RWE and health‑economic dossiers tied to phenotype definitions will be decisive for formulary adoption.
-
Lock in coding and pathway access early: Securing product‑specific reimbursement codes and drafting contracting pilots with major payers should be an immediate commercial objective for late‑stage assets.
-
Design device and sustainability roadmaps: Manufacturers must reconcile device upgrades (adherence, ease of use) with low‑GWP transitions to meet procurement criteria without disrupting supply.
-
Recalibrate portfolio mix: Expect continued margin compression in commoditized bronchodilators; redeploy capital into phenotype‑defining biologics or differentiated inhaled mechanisms that offer premium pricing and defensible evidence packages.
-
Use M&A selectively to accelerate capability gaps: Bolt‑on acquisitions that add inhaled mechanism novelty, biologic delivery, or device sustainability IP can shortcut multiphase development timelines and create cross‑selling synergies.
Bottom line
The Anti‑Asthmatics and COPD drugs market is entering a structurally interesting phase where steady topline growth (projected at a 4.2% CAGR over 2026–2032) coexists with disruptive pockets of innovation and policy‑driven access dynamics. For executives planning 2026 priorities, the immediate imperatives are clear: shore up reimbursement pathways, accelerate real‑world evidence strategies, plan for sustainable device transitions, and selectively invest in assets that deliver demonstrable clinical differentiation.
PW Consulting’s full report provides the empirical builds, scenario models, and tactical playbooks necessary to convert this market intelligence into executable 12‑ to 36‑month plans. To access the complete forecast tables, segmentation analysis, competitive scorecards and downloadable models — and to schedule a strategy briefing with our senior respiratory practice leads — visit PW Consulting’s report page or contact our commercial team for licensing details.
For detailed analysis of this topic, please visit the official page: Anti Asthmatics And Copd Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Used and Refurbished Medical Devices Market Set to Grow at 11.2% CAGR During 2026–2032
By PW Consulting, 2026-07-13
Used and Refurbished Medical Devices Market: Strategic Imperatives for 2026
PW Consulting’s latest market research—built on a 2025 base and a 2026–2032 forecast horizon—shows the used and refurbished medical devices market entering a phase of accelerated, structurally-driven expansion. Our analysis places the market at approximately USD 17,250 Million in 2025 and projects growth to roughly USD 36,268 Million by 2032, implying a compound annual growth rate (CAGR) of 11.2% through the forecast period. These macro-dynamics, combined with regulatory shifts and evolving provider procurement behaviors, create a high-consequence decision environment for OEMs, independent refurbishers, health systems and investors in 2026.
Used And Refurbished Medical Devices Market
Why this matters for 2026 corporate decision-making
-
Financial leverage under tighter CapEx—Hospitals and health networks are under persistent pressure to expand diagnostic and therapeutic capacity while containing capital outlays. Refurbished equipment offers a materially lower capital outlay profile and rapid deployment option that directly addresses 2026 budget cycles and value-based contracting timelines.
Used And Refurbished Medical Devices Market -
Regulatory realism—Recent and coming regulatory clarifications increase compliance expectations for parties engaged in refurbishment and remanufacturing. Firms that anticipate and operationalize those expectations will convert regulatory cost into competitive differentiation.
Used And Refurbished Medical Devices Market -
Commercial scale opportunity—The market’s steady CAGR means scale matters: nimble independents can win share in specific niches, while established OEM refurbishment programs can monetize installed-base stewardship and sustainability credentials.
-
ESG and procurement alignment—Sustainability is now a TCO (total cost of ownership) and procurement metric. Demonstrable carbon and waste reductions from high-quality refurbishment programs amplify purchasing rationales beyond sticker price.
Core market dynamics shaping strategy
-
Regulatory shifts and compliance risk: The regulatory landscape is the single largest near-term operational variable. Two recent milestones require immediate attention: the FDA’s guidance that clarifies the boundary between servicing and remanufacturing, and the introduction of Quality Management System Regulation (QMSR) requirements that incorporate ISO 13485 principles into device CGMP. Collectively, these changes raise the compliance bar for refurbishment processes that materially change device performance or intended use; in practice, they can trigger premarket obligations for devices effectively “remanufactured.”
-
Provider procurement behavior: Health systems continue to prioritize cost-per-case and throughput metrics. Our interviews and TCO modeling show refurbished systems routinely deliver meaningful CapEx savings versus new purchases— savings that directly influence decision timelines and vendor selection criteria during 2026 budget cycles.
-
OEM vs independent refurbisher dynamics: OEM-backed refurbishment programs are investing to deliver “OEM-comparable” warranties, service networks and sustainability claims. Independent players, meanwhile, compete on price, multi-vendor flexibility and localized service footprints. Market concentration metrics indicate that the top tier of players controls a material but not dominant share—creating space for both consolidation and focused growth plays.
-
ESG and lifecycle messaging: High-quality refurbishment programs can deliver measurable carbon footprint reductions versus new manufacture. These environmental gains are being codified into procurement evaluation frameworks and are becoming a value lever in competitive bids.
Competitive landscape — what incumbents and challengers are doing
The competitive field is composed of three complementary clusters: global OEM refurbishment programs, established multi-vendor refurbishers and regional specialty operators. Leading OEMs have formalized certified refurbishment portfolios with warranties and service support designed to mirror new-equipment value propositions. At the same time, specialized independents emphasize multi-vendor expertise, quicker lead times and cost competitiveness for specific modalities.
-
OEM-backed programs: Market leaders are formalizing refurbishment offerings that combine OEM parts, certified refurbishment workflows and extended warranties—intended to capture customers that require both cost-efficiency and minimized clinical risk exposure. These programs are explicitly positioned to retain customers across the equipment lifecycle and to monetize secondary markets for end-of-life assets.
-
Independent multi-vendor providers: These players scale by offering flexible trade-in, retrofit and redeployment services across equipment types. Their competitive advantage in 2026 will hinge on service footprint, spare-parts logistics and demonstrable compliance with emerging quality standards.
-
Specialty and regional operators: Niche operators serve specialized modalities or geography-specific needs (e.g., oncology, mobile imaging). Their success depends on clinical partnerships and bespoke service models that larger players may not economically serve.
From a market-power perspective, leadership is meaningful but not monopolistic: the top three firms control a substantial minority of the market while the top five command roughly half—creating room for acquisitive consolidation and niche insurgency alike.
Practical implications and 10 strategic moves for 2026
-
Operationalize regulatory readiness: Immediately assess refurbishment workflows against the new QMSR and FDA remanufacturing guidance. Identify process gaps (documentation, traceability, validation) and prioritize remediation to avoid business interruptions.
-
Reframe warranties and service SLAs as value engines: Compete on certainty—extended warranties, guaranteed uptimes and rapid spare parts delivery materially reduce buyer hesitation.
-
Invest in lifecycle data and asset intelligence: Implement asset-tracking and usage-analytics programs to demonstrate performance parity and predict maintenance windows; this data supports premium refurb pricing and reduces clinical risk perception.
-
Forge procurement-oriented ESG propositions: Quantify carbon and waste savings, then embed them into commercial bids to capture procurement budgets increasingly tied to sustainability metrics.
-
Pursue adjacencies: Create modular financing and rental-leasing offers to address varying hospital CapEx profiles and shorten sales cycles.
-
Build regulatory-first M&A playbooks: For acquirers, prioritize targets with documented quality systems and validated refurbishment processes to minimize post-deal integration compliance work.
-
Differentiate through clinical partnerships: Use clinician endorsements, case studies and peer-reviewed outcomes to accelerate adoption in conservative specialty areas.
-
Standardize multi-vendor interoperability: Ensure refurbished systems meet contemporary interoperability and cybersecurity expectations to reduce buyer friction.
-
Scale service networks selectively: Concentrate physical service investments around high-density demand corridors to optimize response times and spare parts inventory turns.
-
Quantify total cost of ownership: Present procurement committees with side-by-side TCO models that include acquisition, service, downtime risk and decommissioning costs—moving the conversation from price to value.
What PW Consulting’s report delivers — practical content for execution
This report is designed as a decision-ready playbook for 2026. Core deliverables include:
-
A validated market-sizing model with historical reconstruction (2020–2025), a 2026 base and a granular forecast to 2032—allowing users to stress-test scenarios at enterprise planning cadences.
-
Regulatory impact maps that translate the latest FDA guidance and QMSR requirements into specific operational checkpoints and compliance costs for refurbishment workflows.
-
Vendor intelligence dossiers profiling global OEM programs and leading independent refurbishers, including business model archetypes, service footprints and go-to-market plays.
-
Commercial playbooks—pricing, warranty structuring, leasing and channel strategies—calibrated to hospital procurement behavior and value-based care incentives.
-
M&A readiness assessments and target-screening criteria for acquirers seeking to scale through consolidation or capability acquisition.
-
Tools and templates: TCO calculators, compliance gap checklists, and RFP language to operationalize the adoption of refurbished assets within provider organizations.
Note: We intentionally preserve the full regional and product-split detail for the complete report to ensure our subscribers receive the proprietary segmentation and pricing matrices that underpin the public-facing projections.
Immediate actions for executives planning 2026
-
CEOs and strategy leads—integrate refurbished-device scenarios into three-year strategic plans; treat refurbishment as a distinct P&L stream rather than an afterthought.
-
CFOs—model mixed portfolios of new, refurbished and leased equipment to optimize capital allocation under different reimbursement and utilization scenarios.
-
COOs and quality leaders—prioritize QMSR alignment programs and supply-chain resilience measures to ensure continuity of service and regulatory compliance.
-
Business development teams—evaluate partnership or acquisition prospects among independent refurbishers to accelerate geographic or modality coverage.
Closing: why 2026 is a strategic inflection point
With broad market momentum, meaningful regulatory tightening and procurement practices increasingly favoring value and sustainability, 2026 presents a narrow window for incumbents and challengers to lock in structural advantages. Firms that move early to embed compliance into operations, articulate credible TCO and ESG narratives, and align commercial models with provider budget realities will capture disproportionate upside as the market approaches the USD 36+ billion opportunity by 2032.
PW Consulting’s Used and Refurbished Medical Devices Market report equips leadership teams with the analytical foundations and execution tools required to make those 2026 choices with confidence. For a full set of proprietary segmentations, modality-level forecasts, vendor scorecards and executable playbooks, access the complete report through PW Consulting’s market research portal or contact our advisory team for tailored briefings.
For detailed analysis of this topic, please visit the official page: Used And Refurbished Medical Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Hepatitis Test Diagnosis Market to Reach USD 5,104.07 Million by 2032, Expanding at a 6.2% CAGR
By PW Consulting, 2026-07-13
Hepatitis Test Diagnosis Market — Strategic Insights for 2026 Decision‑Makers
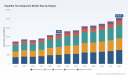
PW Consulting’s latest market research synthesizes the critical evidence executives need to align product, regulatory and commercial strategies in the hepatitis diagnostics space as they enter 2026. Anchored on a comprehensive time series and forward forecast, the study finds that the global hepatitis test diagnosis market reached approximately USD 3,350 Million (base year 2025) and is forecast to expand to roughly USD 5,104 Million by 2032, representing a compound annual growth rate (CAGR) of 6.2% over the 2026–2032 forecast window. This growth trajectory, combined with shifting regulatory and reimbursement landscapes, makes 2026 a pivotal planning year for life‑science leaders, laboratory networks, payers and investors.
Hepatitis Test Diagnosis Market
Why this report matters for 2026 strategy
-
Actionable foresight: The market is moving beyond incremental product upgrades toward systemic changes driven by point‑of‑care molecular testing, multiplex rapid diagnostics and new screening recommendations. Executives who recalibrate now will capture the largest share of the next growth phase.
Hepatitis Test Diagnosis Market -
Regulatory inflection points: Recent regulatory reclassifications and approvals change development timelines, capital allocation and go‑to‑market sequencing — making precise impact analysis indispensable for product roadmaps and submission strategies.
Hepatitis Test Diagnosis Market -
Commercial leverage: As reimbursement criteria evolve and screening protocols broaden, the window to secure favorable coverage, build lab partnerships and scale distribution is limited. The report translates macro trends into concrete commercial priorities for 2026.
What the report delivers (practical, decision‑ready content)
-
Market sizing and trend analysis (historical base: 2020–2025; forecast period: 2026–2032) with downloadable financial models in USD (Million).
-
Segmentation frameworks by region, test type and end‑user with scenario‑driven demand modeling (note: granular subsegment figures are reserved for the full report to preserve proprietary insights and to guide stakeholder conversations).
-
Competitive benchmarking and capability mapping for leading suppliers across molecular, immunoassay and rapid formats.
-
Regulatory and reimbursement trackers that quantify timing and materiality of policy moves across major markets.
-
Commercial playbooks: product positioning, pricing sensitivity analysis, channel strategies, and lab‑network partnership templates.
-
Risk register and mitigation actions covering supply chain shocks, regulatory uncertainty and payer reimbursement shifts.
Key market dynamics shaping 2026 decisions
-
Technology diffusion: The near‑term commercial story is twofold — continued dominance of centralized immunoassays in high‑volume settings and accelerated adoption of decentralized molecular/POC assays for screening and linkage to care. Point‑of‑care RNA testing and multiplex rapid diagnostics are changing screening workflows and shortening diagnosis‑to‑treatment timelines.
-
Regulatory momentum: Notable regulatory events have lowered barriers to market for some classes of hepatitis assays and clarified pathways for others. For example, recent reclassification of certain HBV assay devices in major markets reduces regulatory timelines for follow‑on entrants, while high‑profile approvals and waivers for POC molecular HCV tests validate the clinical utility of decentralized RNA testing.
-
Screening policy evolution: Expanded public health guidance — including recommendations for broader HBV screening panels — will reshape test demand composition and create opportunities for both multiplex rapid diagnostics and comprehensive laboratory‑based screening algorithms.
-
Reimbursement realignment: Updates to payer coverage criteria mean pricing power will vary by test format and clinical indication; developers must calibrate evidence generation to reimbursement endpoints, not just regulatory clearance.
-
Consolidation and concentration: Market concentration metrics indicate a moderately concentrated supplier base at the top end, with room for specialist and mid‑sized players to win niche segments through differentiated technology or service models.
Competitive landscape — strategic implications
The market is anchored by several global diagnostics companies that combine installed platform footprints, reagent portfolios and service capabilities. Major incumbents offer comprehensive immunoassay platforms, high‑throughput molecular systems, and a growing set of rapid, point‑of‑care options. Recent corporate and regulatory developments demonstrate how quickly competitive advantage can shift:
-
Large platform providers maintain scale advantages for high‑volume clinical laboratories through integrated immunoassay and molecular portfolios, enabling bundled offers that hospitals and reference labs find attractive for cost and workflow simplicity.
-
Specialist molecular and POC players have proven they can accelerate diagnosis and linkage to care when regulatory pathways permit CLIA waivers or comparable decentralization allowances. Those firms can rapidly scale through strategic partnerships with laboratory networks and non‑traditional care settings.
-
Regulatory and quality milestones materially affect market access. Recent approvals and prequalifications for multiplex rapid and POC molecular tests demonstrate how product endorsements by regulators and global health agencies increase adoption velocity among public health purchasers.
-
Market concentration measures (CR3 ~48.4%; CR5 ~64.2%) point to meaningful leadership at the top, but also to an addressable market for technology‑led challengers and regionally focused players. This structure implies both competitive barriers and tactical entry points for innovators.
Selected recent events have immediate strategic relevance: high‑profile regulatory approvals and WHO prequalification of multiplex rapid tests validate both clinical and procurement pathways for combined screening approaches; meanwhile, regulatory reclassification in major markets reduces uncertainty for certain assay classes; and payer policy updates adjust the economics for screening across indications. Each of these developments is analyzed in the report to map time‑to‑impact on revenue and adoption curves.
Strategic recommendations for 2026 (what to do next)
-
For product developers: Prioritize regulatory intelligence and modular design. Align clinical evidence plans with payer endpoints and target WHO prequalification where procurement from public health programs is strategic.
-
For platform incumbents: Defend high‑throughput share while investing selectively in decentralized molecular and multiplex rapid capabilities through partnerships, in‑licensing or targeted M&A.
-
For laboratory networks and hospitals: Rebalance procurement toward a mixed portfolio — maintain centralized throughput for confirmatory testing while piloting POC molecular solutions in high‑yield clinical pathways to reduce time to diagnosis.
-
For payers and health systems: Use the next 12 months to update coverage criteria and contracting approaches that incentivize validated rapid linkage‑to‑care solutions, rather than purely lowest‑cost testing.
-
For investors and private equity: Look for assets that combine clinical differentiation with regulatory clarity and addressable contract pipelines; mid‑market consolidation vehicles with platform synergies remain compelling.
How PW Consulting helps — tools and engagement models
-
Data‑driven financial models and scenario planning customized to client portfolios and geographies.
-
Regulatory impact assessments and submission roadmaps tied to commercial rollout sequencing.
-
Commercial playbooks with channel strategies, pricing sensitivity analysis and partnership templates.
-
Due diligence services for M&A and licensing, including competitive threat mapping and integration planning.
-
Executive workshops to translate market forecasts into 90‑, 180‑ and 365‑day action plans.
PW Consulting’s Hepatitis Test Diagnosis Market report is intentionally crafted to be a strategic catalyst for 2026 planning cycles. The full report contains the granular segmentation, regional breakout, product‑level forecasts and downloadable models that you will need to operationalize the recommendations above. For access to the complete dataset, company scorecards, and bespoke advisory engagements, please visit our report landing page or contact PW Consulting’s healthcare team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Hepatitis Test Diagnosis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Radial Artery Compression Hemostatic Equipment Market to Surge to USD 1,014.33 Million by 2032, Growing at a 7.15% CAGR
By PW Consulting, 2026-07-13
Radial Artery Compression Hemostatic Equipment Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on Radial Artery Compression Hemostatic Equipment provides a focused, strategy-first view designed to inform executive decisions in 2026. The market has evolved from a niche post-procedural accessory into a category with measurable commercial expansion and clinically driven innovation. This preview highlights the high-level, decision-relevant findings and strategic implications without disclosing the proprietary segment-level intelligence contained in the full report—intelligence that will be critical for product launches, partnership negotiations, pricing strategy, and M&A underpinned by concrete data and scenario analysis.
Radial Artery Compression Hemostatic Equipment Market
Market snapshot — the macro trajectory you must plan for
PW Consulting benchmarks the market on a 2020–2025 historical base with 2025 as the reporting year and provides forecasts through 2032. The category demonstrates steady, above-market growth driven by sustained uptake of transradial access in interventional cardiology and an expanding set of hemostatic solutions. Our model shows a compound annual growth rate (CAGR) of 7.15% over the forecast window, reflecting a combination of procedure-volume expansion, product innovation (including distal radial solutions and adjunct hemostatic materials), and incremental pricing pressures as new entrants scale.
Radial Artery Compression Hemostatic Equipment Market
To orient planning: the market reached a clear inflection point in the mid-2020s and is expected to exceed a billion USD by the end of the forecast. That macro trajectory creates a predictable runway for investments in product development, clinical evidence generation, and distribution scale-up—while also compressing timelines for competitive differentiation and commercialization.
Radial Artery Compression Hemostatic Equipment Market
Why 2026 is a strategic hinge year
- Clinical practice reach: The steady conversion of catheterization programs to radial-first access protocols, coupled with growing distal radial adoption, raises demand for devices that enable patent hemostasis without compromising patient comfort or throughput.
- Product innovation cadence: New mechanical designs, adjunct hemostatic dressings, and combined-system offerings are moving from pilot to commercial scale. Incumbents and challengers are now required to demonstrate both clinical outcomes (e.g., RAO reduction) and workflow benefits (time-to-discharge, nursing time).
- Regulatory predictability: Most device variants follow a Class II, 510(k)-type pathway in major markets, shortening time-to-market for iterative improvements while emphasizing the need for robust equivalence and clinical comparators.
- Competitive consolidation risk: The category exhibits meaningful concentration among a small set of established suppliers; 2026 is likely the year where the next wave of partnerships and acquisitions is decided.
What the PW Consulting report delivers (practical, executable content)
The full report is built to convert insight into action. Key deliverables—crafted for commercial, clinical affairs, and corporate development teams—include:
- Validated market-sizing and three-tier scenario forecasts (base, upside, downside) with transparent methodology and sensitivity tests to procedure volumes, pricing shifts, and adoption curves.
- Competitive landscaping and vendor scorecards that evaluate clinical differentiation, IP posture, distribution strength, and scale economics—prepared to inform partner selection and target screening.
- Commercial playbooks: go-to-market pathways for incumbents, challengers, and OEMs entering the category (including pricing levers, bundling options with cath lab disposables, and hospital procurement strategies).
- Clinical-evidence roadmaps showing the studies and endpoints payers and hospital committees will prioritize—mapping study design to likely reimbursement and hospital adoption outcomes.
- Regulatory and quality acceleration templates aligned to typical Class II/510(k) pathways, with common pitfalls and mitigation strategies to reduce review cycles.
- Operational models for manufacturing scale-up, cost-of-goods sensitivity, and supply-chain resilience—especially relevant for single-use mechanical devices and hemostatic consumables.
- Deal flow intelligence and M&A match-making criteria focused on high-value subsegments, plus a short-list of potential targets and partnership archetypes (kept in the paid report to preserve commercial sensitivity).
Competitive landscape — what separates winners from followers
The competitive field combines long-established medical-device players with nimble specialist firms and regional manufacturers. Leading firms have built defensible positions through product recognition in procedural protocols, broad distribution, and clinical advocacy. Notable features across the competitive set include:
- Clinical-anchored product leadership: Devices that support patent hemostasis protocols and demonstrably reduce radial artery occlusion (RAO) command clinician preference. Transparent, adjustable bands that allow visual site assessment continue to be the baseline requirement.
- Portfolio breadth vs. niche focus: Large incumbents leverage multi-product portfolios and global sales channels to bundle hemostatic solutions into cath-lab supply contracts; specialist manufacturers compete on focused innovation, operator ergonomics, and cost-competitive designs.
- Recent notable moves: Market leaders continue to iterate—Terumo’s launch of a distal-specific variant in 2026 underscores the shift toward patient comfort and motion-preserving designs for distal radial procedures. These incremental launches shape adoption curves and provide signals about feature sets purchasers will demand.
- Regional and cost-competitive entrants: Emerging manufacturers, particularly from high-volume markets, exert price pressure and can be attractive partners for localized scale-up, but they frequently lack the clinical relationships and regulatory breadth that tilt strategic value toward established names.
PW Consulting’s vendor assessment in the full report ranks manufacturers on clinical evidence, device ergonomics, IP, regulatory footprint, and channel strength. The market shows a moderate-to-high level of concentration among the top three to five players—an important context for any M&A or partnership strategy.
Strategic implications by corporate role
- For incumbents: Prioritize incremental innovations that protect clinical outcomes while addressing workflow (speed of hemostasis, nursing time) and patient experience. Use bundled contracting and evidence-based reimbursement narratives to defend price points. Consider bolt-on acquisitions that add complementary consumables or regional market access.
- For challengers and startups: Focus on a narrow, demonstrable clinical advantage (e.g., distal radial efficacy, hemostatic dressing integration, or faster time-to-discharge). Partner early with high-volume centers for real-world evidence and employ targeted regional launches where procurement cycles favor agility over brand legacy.
- For investors and corporate development teams: Target assets with clear clinical differentiation and defensible unit economics. The sector’s concentration metrics mean strategic scale can quickly tilt margin profiles—use those metrics to size required investment for national rollouts versus licensing pathways.
- For hospital procurement: Emphasize total cost of care and throughput gains over unit price. Devices that shorten observation time or reduce RAO-related complications produce measurable downstream savings and improved capacity utilization.
Risks, regulatory realities, and clinical gating factors
- Regulatory pathways are generally well-defined (Class II / 510(k) in major markets), but careful predicate selection and robust equivalence data are essential to avoid prolonged review cycles.
- Clinical skepticism around new designs is resolved through targeted outcome studies focused on RAO, patient-reported comfort, and workflow metrics. Early payer and hospital engagement accelerates adoption.
- Margin compression from lower-cost entrants is a near-term reality; mitigating strategies include differentiation through bundled solutions, consumable lock-in, and claims of improved throughput.
How to use PW Consulting’s intelligence in 2026 planning
Three practical next steps for teams acting on this market:
- Run a quick-win pilot: identify 2–3 high-volume centers for rapid real-world evidence capture on device ergonomics and throughput impact—use PW Consulting’s study templates to accelerate IRB and data collection.
- Prioritize regulatory and clinical dossiers that map directly to purchaser decision criteria—design evidence packages around endpoints that matter to value committees (RAO rates, observation time, nursing burden).
- Screen M&A and partnership targets using our vendor scorecards to evaluate strategic fit against channel reach, clinical differentiation, and manufacturing scalability—then model 24-month integration scenarios to guide offer structures.
Closing — why the full report matters for 2026
In an environment where clinical practice patterns, incremental product innovation, and concentrated supplier economics intersect, the difference between a well-timed market entry and a missed opportunity is data plus execution. PW Consulting’s full Radial Artery Compression Hemostatic Equipment Market report provides the granular segmentation, regional flows, vendor scorecards, pricing curves, and acquisition targets that senior leaders need to make informed 2026 investments. This preview outlines the direction and decision levers; the full deliverable gives the numbers, maps, and playbooks required to act confidently.
For executives preparing product launches, negotiations, or M&A activity in 2026, the time to align clinical evidence, regulatory strategy, and commercial scale is now. Contact PW Consulting to access the complete report and the proprietary appendices that underpin our forecasts and recommendations.
For detailed analysis of this topic, please visit the official page: Radial Artery Compression Hemostatic Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Omni Wheel Market Poised to Grow at a 7.85% CAGR Through 2032
By PW Consulting, 2026-07-13
Omni Wheel Market 2026 Preview — Strategic Imperatives for Enterprise Decision‑Makers
Executive summary
PW Consulting’s new Omni Wheel Market preview synthesizes fresh market sizing, competitive intelligence and practical playbooks aimed at executives making procurement, product and M&A decisions in 2026. The omni wheel market has expanded steadily since 2020 and reached an estimated USD 245.5 million (base year 2025). Our forecast framework projects a compound annual growth rate (CAGR) of 7.85% over the 2026–2032 period, with the market approaching an estimated USD 416.66 million by 2032. These headline numbers mask meaningful heterogeneity by application, duty class and geography — detail that we intentionally reserve for the full report to support client-level decisioning.
Omni Wheel Market
Why this report matters for 2026 corporate decisions
-
Investment prioritisation: As automation and confined-space logistics accelerate, omni wheels increasingly determine robotic platform performance and total solution economics. Buyers must align sourcing, product spec and R&D roadmaps to seize short-term efficiency gains and long-term platform differentiation.
Omni Wheel Market -
Supplier risk & procurement timing: Engineering polymers and concentrated supply bases create near-term cost and availability sensitivity. Tactical procurement windows and hedging strategies can materially improve margins on high-volume programs.
Omni Wheel Market -
M&A and partnership targeting: The mid-market is consolidating. With the top vendors controlling a meaningful share of the market, well-timed partnerships or tuck-ins can yield rapid access to differentiated IP and channel reach.
-
Regulatory and safety-driven opportunities: Ergonomic material‑handling mandates and focus on worker safety create commercial pull-through for 360° mobility solutions in warehouses, healthcare and intralogistics.
Market dynamics shaping 2026 — what to watch
-
Automation-driven demand: Omni wheels are being adopted across AGVs, conveyor transfers, sortation and robotics where tight turning radii and multi-directional control unlock space and throughput gains. Demand profiles reflect both retrofit activity and OEM platform integration.
-
Raw material pressure: Production is polymer‑intensive — Polyoxymethylene (POM) via injection molding remains the dominant material for many high-performance designs. Recent pricing trends (notably in April 2026) show material cost uplifts across regions, which amplify the importance of cost-pass-through clauses and design-for-cost initiatives.
-
Supply concentration and competitive friction: Market concentration is meaningful — the combined shares of the largest players create an environment where strategic supplier relationships and differentiated product features matter more than commodity pricing alone.
-
Product differentiation: Performance polymers, wheel geometries and modular mounting systems are primary levers suppliers use to claim premium positions. Innovations that reduce wear, improve load stability and simplify installation are becoming commercial table stakes.
-
Channel stratification: A two-track go‑to‑market model—direct OEM partnerships for mission-critical systems and distributor-led channels for educational and light‑duty segments—continues to evolve. Channel choices materially affect lead times and service guarantees.
What the PW Consulting report contains — practical, decision‑ready content
We designed the report to be a working tool for 2026 planning cycles. Highlights include:
-
Verified market sizing and seven‑year forecast (2026–2032) in USD million, built from a bottoms‑up model calibrated to primary vendor shipments and buyer intake.
-
Scenario and sensitivity analysis that quantifies upside/downside outcomes under alternative automation adoption and raw‑material price paths, using a 7.85% central CAGR as the baseline.
-
Vendor profiles and scorecards: technical capabilities, channel footprints, IP posture and recent product or commercial moves — enabling immediate supplier shortlists for sourcing and partnership discussions.
-
Procurement playbook: contract clauses, inventory strategies, and a supplier risk matrix tied to material-price volatility and single‑sourcing exposure.
-
Go‑to‑market and product roadmaps: positioning guidance for OEMs, distributors and systems integrators, plus commercial templates for pricing, warranty and aftermarket service.
-
M&A and venture themes: heatmaps identifying attractive targets by capability and gap fills for platform owners looking to accelerate capability through acquisition.
-
Operational appendices: testing standards, recommended bench metrics for wear and load performance, and a technical glossary to standardize cross‑company conversations.
-
Interactive data assets: downloadable dashboards and models for scenario planning (full regional and application breakouts are included in the gated deliverable).
Note: this release intentionally previews the report scope while withholding granular segment-level data to preserve the value of the full dataset.
Competitive landscape — who we profile
The report profiles leading manufacturers, distributors and kit‑providers who are influencing product design, channel strategy and end‑user adoption. Highlights include:
-
OMNIA Wheel Ltd (Rotacaster Wheel Pty Ltd) — Beresfield, New South Wales, Australia ( https://www.omniawheel.com/). A market leader in patented multi‑directional omni wheels, focused on industrial robotics, conveyor transfers and mission‑critical mobility. Recent activity includes product range updates and high‑visibility trade show engagements signaling an emphasis on sortation and conveying markets.
-
WestCoast Products & Design LLC — Madera, California, United States ( https://wcproducts.com/). Distributor and component supplier serving industrial, automation and educational channels with logistics and robotics hardware portfolios; valuable for OEMs seeking North American distribution reach.
-
VEX Robotics — Greenville, Texas, United States ( https://www.vexrobotics.com/). Drives adoption through educational and competitive robotics kits; an important demand generator and talent pipeline for future commercial applications.
-
Active Robots — Bath, Somerset, United Kingdom ( https://www.active-robots.com/). Supplier/manufacturer with reach into research and industrial automation; notable for component breadth and rapid prototyping support.
-
TOK America, Inc. — United States ( https://tok-usa.com/). Polymer wheel and motion control manufacturer with production expertise in engineering polymers such as polyacetal; relevant for OEMs needing custom material formulations.
-
NEXUS Robot — Hong Kong, China ( https://www.nexusrobot.com/). Supplier of multiple wheel sizes and configurations, influential in APAC educational and light industrial segments.
-
MATRIX ROBOTICS — Taiwan ( https://matrixrobotics.com/). Focused on educational kits and training, extending market awareness and accelerating developer ecosystem adoption.
OMNIA Wheel’s recent trade show presence (MODEX 2026) and staged product refreshes illustrate how established vendors are using marketing and incremental innovation to defend premium positions. Distributors and kit providers continue to broaden market entry points, increasing overall addressable demand while fragmenting price sensitivity at the low end.
Actionable recommendations for 2026
-
Immediate (0–6 months): run a supplier stress test and three‑quarter procurement forecast tied to polymer price scenarios; prioritize multi‑sourcing for high‑volume SKUs.
-
Near term (6–12 months): pilot integration of omni wheels on one AGV or conveyor line with a performance‑based contract to validate TCO assumptions and quantify throughput gains.
-
Medium term (12–24 months): evaluate strategic partnerships or minority investments in differentiated wheel technology suppliers to secure IP and shorten time‑to‑market for premium designs.
-
Cross‑functional: update product specifications to include modular mounting standards and standardized performance metrics to reduce engineering rework and speed supplier qualification.
-
Commercial: adopt contract language for material‑price pass‑through and tiered pricing triggers to de‑risk margin erosion from polymer volatility.
How to use the research and next steps
The Omni Wheel Market preview is designed to inform your 2026 strategic planning cycle with a clear, executable set of recommendations and risk mitigants. For procurement and product teams needing detailed regional and application-level splits, vendor scorecards, full scenario models and downloadable dashboards, the full report and interactive assets are available from PW Consulting’s Omni Wheel Market report page. Our team is prepared to run customised workshops that translate the insights into a bespoke sourcing strategy, product roadmap or M&A shortlist tailored to your operating footprint.
Contact PW Consulting to request the full deliverable, arrange a briefing, or commission a tailored companion study that embeds your internal cost, channel and product assumptions into our models.
For detailed analysis of this topic, please visit the official page: Omni Wheel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


