



Category: Healthy Lifestyle
PW Consulting: Putty Impression Material Market hits USD 550M in 2025; 5.5% CAGR to 2032
By PW Consulting, 2026-07-13
Putty Impression Material Market — Strategic Outlook for 2026
Executive preview
As dental practices and dental laboratories recalibrate product mixes, procurement channels, and clinical workflows entering 2026, the putty impression material market is revealing a steady, investable rhythm. Our latest PW Consulting study — built on a 2020–2025 historical base with a 2026–2032 forecast horizon — shows a market that reached roughly USD 550 million in our base year (2025) and is forecast to grow at a mid-single-digit compound annual growth rate (CAGR of 5.5%) through the 2026–2032 period. This trajectory reflects durable clinical demand, incremental product innovation, and steady replacement cycles in restorative and prosthetic dentistry.
Putty Impression Material Market
Why this study matters for 2026 decision cycles
-
Timing: 2026 is the inflection year for many strategic choices — from commercial expansion to manufacturing investments and M&A integration timetables. The market momentum documented in this report gives executives a quantified basis for capex phasing and go-to-market sequencing.
Putty Impression Material Market -
Risk calibration: Regulatory noise (e.g., ongoing FDA premarket notification guidance classifying many dental impression materials as Class II devices) and periodic raw-material swings mean that margin pressure and time-to-market risk are real. The study integrates these dynamics so leadership teams can stress-test scenarios before committing resources.
Putty Impression Material Market -
Competitive intelligence: Concentration metrics and company-level profiling enable sharper targeting of partnership, channel, and product-differentiation opportunities — useful input for 2026 commercial planning cycles.
Market trajectory — what the numbers are telling us
The market’s mid-single-digit CAGR is evidence of a market that is neither hyper-disruptive nor stagnant. Growth is being driven by a combination of steady clinical volumes in restorative and implant dentistry, product refinement that enhances ease-of-use and clinical confidence, and continued adoption in emerging practice settings. Importantly, the market exhibits moderate concentration — meaningful scale among the top players but sufficient fragmentation for nimble challengers and regional specialists to win niche positions. These structural attributes imply that well-executed tactical plays (product performance, channel coverage, and regulatory readiness) can deliver disproportionate returns in 2026.
Key growth drivers and demand signals
-
Clinical reliability and workflow efficiency: Putty-based impression systems remain preferred where dimensional stability and tear strength are prerequisites for accurate crown, bridge, and implant prosthetics. Incremental improvements in set times and hydrophilicity are shortening chair time and reducing remake rates — a direct value proposition for practitioners.
-
Product innovation across price bands: From premium pre-mixed cartridge systems to economical tray putties, product stratification is enabling manufacturers to address both high-volume dental chains and independent clinics.
-
Emerging practice models: Growth in implantology and digital-restorative workflows (where accurate analog impressions remain a complement to intraoral scanning in certain indications) is sustaining demand for high-performance putties.
-
Cost dynamics: Medical-grade silicone feedstock prices (commonly observed in industry channels as a mid-range cost-per-kilogram) and packaging/mixing technologies materially influence unit economics for both branded and private-label offerings.
Supply-side and regulatory considerations
-
Raw material volatility: Manufacturers with secured medical-grade silicone contracts and diversified sourcing have an edge on margin stability. For firms planning to scale production in 2026, early procurement commitments and vertical supplier engagement are recommended.
-
Regulatory posture: Compliance with device-class relevant premarket notification pathways remains a gating factor for speed-to-market in major geographies. Firms that embed regulatory strategy into early-stage product development will shorten commercialization lead times and reduce surprise costs.
-
Reimbursement interplay: In certain clinical contexts, impressions for custom prostheses intersect with reimbursable procedures under existing CPT/medical billing codes. Capturing this revenue nuance requires provider-education programs and payer-engagement strategies.
Competitive landscape — what incumbents and challengers are doing
The market is shaped by a mix of global incumbents and regionally strong specialists. Leading manufacturers are leaning into product reliability claims (tear strength, dimensional stability), clinician-friendly formats (putty/wash, one-step systems), and differentiated user experiences (easier mixing, faster set times). Below is a concise qualitative assessment of principal players and their strategic posture.
-
3M (Solventum) — St. Paul, MN: A broad portfolio approach combining legacy trust and clinician familiarity. Flagship putty offerings emphasize precision for restorations and a trusted channel presence among dental distributors. Their strengths are brand trust, distribution scale, and R&D cadence targeted at chair efficiency.
-
Dentsply Sirona — Charlotte, NC: Focused on high-hydrophilicity VPS formulations optimized for both putty/wash and single-step techniques. Their product strategy is tightly aligned with digital restorative workflows and multi-product bundles for practices and labs.
-
Ivoclar Vivadent — Schaan, Liechtenstein: Positions itself on clinically demonstrable precision and moisture displacement performance. Ivoclar’s offerings target clinicians who prioritize reproducibility in challenging intraoral environments.
-
Coltène/Whaledent — Altstätten, Switzerland: Emphasizes one-step detail and high-fidelity materials for a range of clinical indications, appealing to practitioners seeking a balance of performance and ease-of-use.
-
Kettenbach Dental — Eschenburg/US presence: A specialist strategy focused on A-silicone kneadable and cartridge formats for precision impressions. Kettenbach targets clinical users and labs prioritizing material handling and consistency.
-
HUGE Dental (Shandong Huge Dental Material Corporation) — Shanghai/US presence: An aggressive product-innovation trajectory with recent launches that improve tear strength and dimensional stability while pursuing cost-competitive positioning for high-volume tray putties.
Recent moves matters — examples to watch in 2026
-
Product refreshes from regional manufacturers are tightening the gap on legacy incumbents by delivering measurable improvements in tear resistance and mixing convenience. These moves increase price competition in certain channels and raise the bar for claims substantiation.
-
Partnerships that combine putty materials with dispensing or adjunct products (e.g., bone substitutes, mixing dispensers) are creating bundled propositions that increase average order value and strengthen distributor relationships.
-
Watch for regulatory clarity and enforcement patterns — timely certification and aligned labeling can be a decisive differentiator in 2026 when procurers prioritize low-friction suppliers.
Strategic implications — three prioritized plays for 2026
-
Operational defensibility: Secure feedstock, refine formulation-to-cost pathways, and test dual-sourcing to protect margin and avoid supply shocks. For firms entering 2026 with expansion plans, locking favorable supplier terms is a high ROI move.
-
Commercial bundling and channel engineering: Create bundled provenance with dispensing systems or lab services to increase switching costs. Leverage distributor training programs to convert trial into repeat purchases.
-
Evidence-led marketing and regulatory playbook: Invest in targeted clinical studies that validate claims around tear strength, dimensional stability, and workflow time-savings — and align those studies with regulatory dossiers to accelerate market uptake.
What the full PW Consulting report delivers (practical contents)
-
Demand model and scenario analysis calibrated to the 2025 base year and projecting to 2032, with upside/downside sensitivity for material costs, regulatory delays, and clinical adoption shifts.
-
A supply-chain map identifying critical upstream dependencies and cost drivers, and practical mitigation playbooks for procurement and manufacturing leads.
-
Detailed competitive profiles, channel economics, and a commercialization playbook (product-market fit, launch sequencing, distributor activation templates).
-
M&A and partnership scouting framework: criteria-driven shortlists and valuation heuristics for tuck-ins, private-label opportunities, and strategic alliances.
-
Regulatory and reimbursement appendix that translates device classification and billing opportunities into actionable go/no-go checklists for market entry.
How to use this intelligence in 2026
-
For CEOs and corporate development teams: use the scenario outputs to time acquisitive activity and allocate integration resources across production, regulatory, and commercial functions.
-
For product and R&D leaders: prioritize formulations and device-design attributes that reduce clinician friction and create defensible performance claims; align trials with regulatory submission timelines.
-
For commercial leaders: rebalance portfolio SKUs across channel requirements — high-touch distributor enablement for premium products and cost-competitive solutions for volume channels — and deploy targeted evidence packages that accelerate trials into repeat buys.
Closing note — what we’re intentionally withholding
This introduction highlights the strategic fabric of the putty impression material market while intentionally omitting granular segment-level figures and regional splits that are included in the full PW Consulting report. That deeper segmentation — material-type performance by channel, regional demand breakdowns, and application-level revenue splits — is available in our comprehensive model and is essential for transaction-level or launch-specific decisions. If your 2026 plan requires that granularity, the full dataset and scenario models will provide the segment inputs and sensitivities you need.
Next steps
Contact PW Consulting to request the full report, the downloadable dataset, or a bespoke briefing that maps the findings directly to your strategic choices for 2026. Our team can run a tailored scenario analysis applying your cost, distribution, and regulatory assumptions to show expected P&L and cash-flow implications under alternate market conditions.
For detailed analysis of this topic, please visit the official page: Putty Impression Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: At-Home Laser Hair Removal Market to Grow at 7.5% CAGR to 2032
By PW Consulting, 2026-07-13
At-Home Laser Hair Removal Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking synthesis of the At-Home Laser Hair Removal market that is designed to inform executive decision-making in 2026. This preview synthesizes macro growth dynamics, competitive positioning, regulatory headwinds, and actionable strategic options — demonstrating the intellectual depth of our full study while preserving the proprietary segmentation and model outputs accessible in the complete report.
At Home Laser Hair Removal Market
Why this market matters in 2026
The at-home hair removal category has matured from niche gadgetry to a mainstream consumer health-and-beauty segment. Our analysis uses 2025 as the operational baseline and projects through 2032: the market is on a clear growth trajectory, expanding at a compound annual growth rate (CAGR) of approximately 7.5% over the forecast window. The market has shown consistent growth from the early 2020s and crosses the billion-dollar threshold in the early years of the forecast period — a scale that changes the calculus for large consumer electronics firms, beauty conglomerates, private equity, and specialty medtech incumbents.
At Home Laser Hair Removal Market
Growth is being driven by a combination of improving device efficacy, consumer comfort with home-use medical devices, digital enablement (apps, sensors), and distribution channel evolution. These forces create a rich set of entry points and scaling pathways for incumbents and new entrants alike, but also raise the bar on regulatory compliance and evidence-based claims.
At Home Laser Hair Removal Market
What PW Consulting’s full study delivers (practical, transaction-grade intelligence)
- Market sizing and growth model: robust, auditable build-up from 2020 historicals through a 2026–2032 forecast. The full model translates macro assumptions into revenue curves, scenario runs, and sensitivity analyses tailored to alternate adoption and pricing paths.
- Commercial playbooks: go-to-market blueprints for direct-to-consumer (DTC), retail partnerships, and professional-clinic hybrid models, including launch sequencing, messaging, and unit economics benchmarks.
- Product and R&D roadmaps: prioritized feature stacks (safety sensors, cooling, targeted energy delivery, ergonomics) aligned to consumer segments and regulatory constraints, with cost/benefit trade-offs for hardware vs. service-led differentiation.
- Regulatory and claims advisory: 510(k) pathway considerations, labeling compliance, safety documentation templates, and a mitigation matrix for enforcement risks tied to unregistered or misbranded devices.
- Commercial diligence and M&A playbook: valuation adjacencies, integration checklists, top risks for scaling production, and a three-tier scenario (consolidation, premiumization, subscription-led) for investors.
- Channel and pricing diagnostics: elasticities, recommended MSRP bands by route-to-market, and subscription/consumable economics for lifetime revenue maximization.
- Operational readiness: supplier maps, critical component risk log (optics, diode lasers, cooling modules), and quality management/practical checks for scaling manufacturing while preserving regulatory compliance.
Competitive landscape — who moves the market
The category displays moderate concentration: market share among the top three players is meaningful but leaves substantial room for challengers and regional champions. This dynamic supports both defensive moves by incumbents and targeted attack strategies by focused entrants.
- Tria Beauty (San Leandro, CA): Differentiates with a true diode laser positioned for permanent hair reduction. Their product strategy centers on delivering higher energy density than many IPL devices and on owning the consumer laser narrative.
- Philips (Amsterdam): Leverages consumer electronics scale and brand recognition with its Lumea IPL line and SenseIQ capabilities. Its strength is in product ecosystems and mainstream retail distribution.
- Braun / Procter & Gamble (Germany / P&G): Competes on rapid-treatment claims and smart skin-adaptive technologies, using P&G’s global marketing and retail reach to sustain penetration across core markets.
- Ulike (China / Seoul R&D): Aggressive product cadence and value-oriented innovation such as cooling-enabled designs target rapid adoption in APAC and DTC channels.
- Cyden / SmoothSkin (UK): Focuses on high flash-count devices and precision heads, optimizing device lifecycle economics and the user experience for repeat usage.
- Iluminage Beauty (Hong Kong / Shenzhen): Pursues a safety-and-efficacy angle with elōs (IPL + RF) technology and positioning around broader skin-tone compatibility and clinical clearance.
Recent market activity underscores competitive intensity: a major industry player launched a high-flash IPL device with integrated skin-tone sensing in early 2026, and another notable manufacturer showcased new pro-grade home devices in 2025. These moves highlight a dual dynamic — product premiumization at the top end, and rapid iteration among value brands.
Regulatory and safety realities that shape strategic choices
Regulation is not a background variable — it is a primary driver of R&D, labeling, and go-to-market timing. In the U.S., at-home IPL and laser devices are regulated as Class II medical devices and typically require 510(k) clearance when marketed with indications for permanent hair reduction. Enforcement actions against unregistered or misbranded low-cost devices have been publicized, increasing distributor risk and consumer skepticism.
Consequently, strategy must account for:
- Clinical evidence generation and documentation early in the product development lifecycle;
- Design controls and risk management aligned to FDA guidance for over-the-counter light-based hair removal;
- Clear consumer labeling and training materials, with built-in safety limits (skin-tone contraindications, sun-exposure guidance);
- A compliance-first approach to claims, advertising, and cross-border market entries.
Demand-side signals and product implications
Consumer preference trends favor devices that combine safety sensors, cooling for comfort, and demonstrable efficacy within a 2–12 week window of consistent use. There is also rising interest in model differentiation for male users and for broader skin-tone inclusion. For incumbents and new entrants, this implies a triage of product priorities:
- Core efficacy supported by clinical endpoints;
- Comfort features (cooling, ergonomic applicators) that reduce perceived friction;
- Digital layer (apps, treatment reminders, usage telemetry) that increases adherence and unlocks subscription economics;
- Modular platforms that allow upsell of attachments or performance upgrades without full hardware replacement.
Strategic imperatives for 2026 decision-makers
Executives planning moves in 2026 should prioritize the following, in sequence and with clear go/no-go criteria:
- Regulatory-first product strategy: validate clearance strategy (510(k) or equivalent), estimate time-to-market, and budget for clinical studies. Without this, distribution risk and marketing levers will be severely constrained.
- Channel and brand architecture: decide whether to pursue premium DTC, mass retail, or a hybrid clinic-plus-home approach. Each path has distinct margin and inventory implications.
- R&D investments to close efficacy and safety gaps: cooling tech, skin sensors, and energy delivery modulation deliver outsized consumer value and justify premium pricing.
- Service and recurring revenue design: consumable replacement (filters/gels), app subscriptions, and extended-warranty bundles materially improve lifetime value.
- M&A and partnership lens: target bolt-on acquisitions that deliver either regulatory paperwork (clinical data, existing clearances) or proprietary optics/diode modules to accelerate time-to-market.
- Operational resilience: map single-source risks for critical components and qualify secondary suppliers early to avoid production shocks.
Risk matrix — what can derail 2026 plans
- Regulatory enforcement and adverse announcements about unregistered devices that reduce consumer confidence;
- Underestimating clinical evidence needs, which delays launches or constrains claims;
- Supply-chain disruptions for optics and diode lasers during acceleration phases;
- Price compression from low-cost entrants that undercut long-term unit economics.
KPIs and near-term milestones we recommend tracking
- Regulatory milestones: submission dates, expected clearance windows, and post-market surveillance plans;
- Clinical endpoints: time-to-visible-reduction, safety event rates, and adherence statistics in pilot cohorts;
- Commercial metrics: cost-per-acquisition by channel, repeat-purchase rates for consumables, and device attach rates for services;
- Operational metrics: lead time for critical components, yield rates in pilot manufacturing, and quality event counts.
Closing — the strategic value of the full PW Consulting report
The market’s scale, validated growth trajectory, and evolving technological and regulatory landscape make 2026 a pivotal year. Our full At-Home Laser Hair Removal Market report provides the granular segmentation, audited models, competitor benchmarking, and go-to-market playbooks needed to make confident, defensible decisions — whether you are validating an acquisition, scaling a product line, or entering the market for the first time.
This preview outlines the strategic contours and immediate decision levers. For the proprietary segmentation tables, scenario-driven financial models, and the transaction-grade diligence annex that supports board-level investment decisions, consult the full report on our website or contact PW Consulting’s industry team for an executive briefing.
For detailed analysis of this topic, please visit the official page: At Home Laser Hair Removal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silicone Hydrogel Colored Contacts to Reach USD 2,060.68M in 2026
By PW Consulting, 2026-07-13
Mpc Silicone Hydrogel Colored Contact Lenses Market — Strategic Outlook for 2026
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused industry primer designed to orient executive teams, product leaders, and M&A sponsors for high-stakes decision making in 2026. Our latest study uses a validated primary-and-secondary research engine to model the MPC silicone hydrogel colored contact lens market from a 2025 base year through 2032. At the macro level the market surpassed USD 1,850 Million (≈ USD 1.85 billion) in 2025 and is forecast to expand at a 6.5% CAGR over the 2026–2032 period, approaching roughly USD 2,875 Million by 2032. Market concentration is meaningful — the three largest players account for approximately 65% of the market, and the top five nearly 79% — a dynamic that shapes pricing power, channel access and consolidation risk.
Mpc Silicone Hydrogel Colored Contact Lenses Market
Why this report matters for 2026 decisions
- Growth window with product differentiation: A steady mid-single-digit CAGR creates a predictable expansion runway, but durable advantage will come from material-level differentiation (MPC integration), oxygen performance and clinical evidence of comfort for sensitive/dry-eye users.
- Regulatory and clinical inflection: Colored contact lenses remain regulated as medical devices in major markets. FDA expectations on labeling, clinical substantiation, and post-market surveillance create both barriers and strategic levers.
- Concentration and competitive posture: High CR3/CR5 metrics mean incumbents can shape wholesale/distribution policies and command premium placement — newcomers must design go-to-market plays that intentionally circumvent entrenched pathways.
- Channel and consumer shifts: E-commerce and direct-to-consumer pilots accelerate reach but optical retail and clinical endorsement still matter for prescription compliance and safety messaging.
- Material science convergence: MPC (2-methacryloyloxyethyl phosphorylcholine) combined with silicone hydrogel delivers a rare mix of high oxygen transmissibility and improved surface hydration — a critical attribute for extended-wear comfort and reduced protein/biofilm risk.
What the report delivers — practical, decision-ready outputs
We designed the deliverables for executives who need to convert insight into immediate action. Highlights include:
Mpc Silicone Hydrogel Colored Contact Lenses Market
- Proprietary market model (base year 2025; forecast 2026–2032) with scenario toggles for adoption curves, pricing sensitivity and regulatory lag.
- Competitive intelligence dossiers on leading and challenger players, synthesizing product portfolios, technology claims, go-to-market footprints, recent launches and likely strategic intent.
- Go-to-market playbooks for three archetypes: incumbent manufacturers, niche premium challengers, and digital-first retailers — each with tactical KPIs and implementation milestones for 12 and 24 months.
- Regulatory pathway templates and a checklist for FDA-aligned clinical evidence, label claims and post-market surveillance; practical timelines and cost buckets to inform budgeting and submission sequencing.
- Supply chain risk mapping and manufacturing scale scenarios to support decisions on onshore vs. offshore capacity, CMO selection, and inventory buffering for seasonal demand peaks.
- Commercialization levers — pricing frameworks, channel-margin models, promotional strategies and clinical marketing assets that protect brand premium while accelerating trial.
- A prioritized M&A and partnership screening matrix to identify targets that fill capability gaps (e.g., MPC chemistry expertise, manufacturing scale, clinical data repositories or digital retail reach).
Competitive landscape — what to watch
The report profiles established and emergent players, with an emphasis on technology claims, execution risk and strategic runway. Key observations:
Mpc Silicone Hydrogel Colored Contact Lenses Market
- Glocolens (South Korea): Promotes Giselle‑MPC™ Technology and emphasizes FDA‑approved MPC biomaterial for hydration and antimicrobial properties. Their narrative centers on clinical-grade moisture retention and comfort claims — a potential differentiator in premium segments.
- Bionics Sciences (Malaysia / Korean brand): Recent product launches signal intent to scale a monthly MPC + silicone hydrogel offering with a focus on extended comfort and breathability — watch for distribution partnerships that translate product promise into prescription conversions.
- GEO Medical / Geo Coloured Lenses (South Korea): Strong brand recognition in decorative and fashion segments; relevant where design vibrancy and biocompatibility converge to drive repeat purchase.
- Interojo (Clalen) (South Korea): Emphasizes oxygen transmissibility in its Clalen O2O2 series — a competitive play that addresses medical clearance and clinician comfort with claims tied to physiologic safety parameters.
- EyeCandys (Singapore / Global): Retailer and brand hybrid that curates extensive MPC & silicone hydrogel SKUs; positions itself for dry/sensitive-eye demographics and for channels that prioritize consumer education and comfort-first messaging.
- CooperVision (United States): Legacy strength in PC-type chemistries (phosphorylcholine) and broad distribution muscle. While primarily oriented to clear lenses, their material heritage and regulatory experience are non-trivial competitive assets should they deepen colored lens plays.
Recent industry signals (to incorporate into 2026 planning)
- Bionics Sciences launched an MPC + silicone hydrogel monthly colored lens in early 2026 — an explicit move to commercialize MPC benefits in mainstream SKUs.
- Glocolens introduced Giselle‑MPC™ in mid‑2025, anchoring its value proposition on FDA‑approved MPC biomaterial and lab-substantiated hydration claims.
- Collectively these moves indicate a technology wave where MPC claims are transitioning from niche clinical messaging to central commercial differentiators.
Strategic implications and recommended actions for leadership (2026)
Below are the prioritized actions we recommend for different corporate profiles. Each action is calibrated to preserve optionality while accelerating capture of the high-comfort, premium-colored-lens segment.
- For incumbent manufacturers: Fast-track an MPC integration roadmap or license agreements. Parallel investments in clinical trials demonstrating sustained moisture and reduced protein/biofouling will defend premium ASPs and support label claims accepted by clinicians and regulators.
- For challengers and niche brands: Focus on a tight set of SKUs that pair standout design with robust comfort claims. Pilot DTC campaigns with clinic-referred sample programs to build prescriber endorsement without ceding margin to legacy wholesale channels.
- For retailers and e-commerce platforms: Build clinical content and patient triage flows that enable safe prescription fulfillment; partner with clinical networks to reduce friction and to position comfort claims credibly to consumers with dry or sensitive eyes.
- Regulatory & clinical strategy: Invest early in a clinical dossier that measures hydration retention, oxygen transmissibility and microbiological performance. This portfolio will accelerate approvals, reduce label risk and support premium pricing.
- M&A / partnerships: Look for bolt-on assets with MPC chemistry know-how, manufacturing scale in high-compliance jurisdictions, or digital channels validated for prescription conversion. Given high market concentration, targeted acquisitions can meaningfully shift competitive posture.
- Operations: Secure manufacturing capacity for silicone hydrogel substrates and MPC surface treatments; de‑risk supply by qualifying secondary suppliers and establishing clear quality-by-design metrics tied to clinical performance.
How PW Consulting supports your 2026 agenda
Our full study includes the quantitative models, primary interview excerpts, and scenario playbooks necessary to accelerate decisions in 2026. Clients benefit from:
- Customizable financial models (top-line, margin, CAPEX/OPEX) with sensitivity toggles for alternative adoption curves and regulatory timelines.
- Competitor heatmaps and capability gap analyses aligned to go-to-market archetypes.
- Regulatory submission timelines and clinical-protocol templates designed to reduce time-to-market and to support differentiated claims.
- Implementation roadmaps for pilot commercialization programs (retail + DTC + clinical partnerships) with 90/180/360-day milestones.
Final note — where this brief leads
This note is intentionally selective: it surfaces the strategic contours and actionable implications of MPC silicone hydrogel colored contacts but omits the granular segment share and channel revenue tables that materially inform pricing, SKU mix and regional rollouts. Those detailed maps — including disaggregated forecasts, channel economics, and company-level benchmarking — are available in the full PW Consulting report and associated interactive model. For executive teams setting 2026 budgets, R&D priorities or M&A screens, this study converts a predictable growth environment into concrete options with quantified trade-offs and execution checklists.
Contact PW Consulting to license the full market model, request a tailored executive briefing, or commission a rapid due‑diligence run to vet targets and pilots for your 2026 strategic plan.
For detailed analysis of this topic, please visit the official page: Mpc Silicone Hydrogel Colored Contact Lenses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fungal Infection Diagnosis Market to hit USD 6.07 Million by 2032 at 7.5% CAGR
By PW Consulting, 2026-07-12
Fungal Infection Diagnosis Market — Strategic Outlook for 2026 Decisions
The landscape for fungal infection diagnostics is entering a phase of deliberate commercialization and clinical consolidation. Our PW Consulting Fungal Infection Diagnosis Market study (base year 2025) shows a market that has expanded steadily from the 2020 base period, reaching an estimated USD 3.65 Million in 2025 and forecast to grow at a compound annual growth rate (CAGR) of 7.5% through 2032 — when the model projects a market size north of USD 6 Million. For executive teams planning investments or repositioning portfolios in 2026, this research provides the actionable intelligence needed to translate regulatory shifts, reimbursement dynamics, and platform innovation into measurable commercial outcomes.
Fungal Infection Diagnosis Market
Why 2026 Is a Pivotal Inflection Point
-
Regulatory momentum. Recent clearances and authorizations have reshaped the go-to-market calculus for fungal diagnostics: a De Novo authorization for a PCR assay addressing Candida auris and label expansions for direct-from-blood molecular panels meaningfully broaden clinical use cases and infection‑control workflows.
Fungal Infection Diagnosis Market -
Clinical demand is maturing. Rising numbers of immunocompromised patients, expanded invasive-procedure volumes in tertiary centers, and heightened hospital infection‑prevention focus are increasing demand for rapid, reliable fungal testing across acute-care and laboratory settings.
Fungal Infection Diagnosis Market -
Platform convergence and stewardship. Molecular panels, antigen assays, and rapid β‑D‑glucan screening are converging in clinical pathways. Hospitals are increasingly demanding rapid diagnostic results that integrate with antimicrobial stewardship programs to reduce empiric antifungal use and length of stay.
-
Commercial opportunity windows. With a projected 7.5% CAGR across 2026–2032, the market is neither nascent nor saturated — it rewards targeted clinical evidence generation, regulatory strategy, and nimble commercialization.
What the PW Consulting Report Delivers
This study is built to support operational decision-making in 2026. Key deliverables include:
-
Market model (USD Million): historical series (2020–2025), a 2025 base, and scenario-based forecasts for 2026–2032 with sensitivity to adoption, pricing, and regulatory outcomes.
-
Market dynamics and demand drivers: clinical adoption curves, hospital procurement behaviors, and integration into stewardship and infection-control pathways.
-
Regulatory & reimbursement tracker: timelines for recent clearances and practical guidance for navigating De Novo/510(k) strategies and CPT coding impacts.
-
Competitive intelligence and supplier matrix: profiles of incumbent and emerging providers, product positioning, strengths/weaknesses, and likely strategic moves.
-
Commercial playbooks: launch sequencing, pricing strategy, clinical evidence roadmaps (including pediatric considerations), and channel tactics for hospitals, reference labs, and point‑of‑care settings.
-
M&A and partnership screen: prioritized targets and fit criteria for inorganic growth, licensing, and co-development to accelerate time-to-market.
-
Primary-source annexes and editable data tables: underlying assumptions, unit economics, and addressable‑market spreadsheets to feed internal financial models.
Note: this introductory brief intentionally omits granular region, type, and application split figures; full segmentation tables and downloadable datasets are included exclusively in the complete report.
Competitive Landscape — Who Matters and Why
The fungal diagnostics market shows a concentrated competitive structure (top-three firms control a majority share; top-five approach three-quarters of market value), which creates both barriers and corridors of opportunity. Incumbent companies have entrenched positions via cleared assays, platform footprints in hospital labs, or strong partnerships with reference labs. Key strategic profiles include:
-
Associates of Cape Cod, Inc. — Known for the Fungitell® family (including a STAT single-sample format), the company offers a rapid screening assay for (1→3)-β-D‑glucan that remains the clinical standard for many invasive fungal infection workups. Their single-sample, rapid formats create clear use cases for emergency and inpatient triage workflows.
-
T2 Biosystems, Inc. — The T2Candida Panel is distinct as a direct‑from‑blood molecular diagnostic with demonstrated clinical impact on time‑to‑result and antifungal stewardship. Its pediatric label expansion in 2024 materially increases addressable hospital networks and demonstrates the strategic value of pursuing pediatric indication pathways.
-
DiaSorin Molecular LLC — The De Novo authorization for a direct PCR test targeting Candida auris underscores the regulatory pathway advantage of early, novel assay submissions addressing urgent infection‑control needs. Their product is strategically positioned for hospital surveillance and colonization-control programs.
-
Bio‑Rad Laboratories — With an FDA‑cleared antigen assay for Aspergillus galactomannan, Bio‑Rad represents incumbent strength in antigen-based diagnostics for invasive aspergillosis — a product class that complements molecular panels in comprehensive diagnostic pathways.
-
Bruker Daltonik GmbH — The MALDI Biotyper CA System and its clinically validated libraries enable rapid species identification from cultured isolates and provide interoperability with clinical microbiology workflows. Their platform’s role in species ID is a defensive asset against rapid molecular assays seeking to displace culture-dependent steps.
-
GenMark Diagnostics, Inc. and BD — Both provide multiplex PCR panels and integrated platforms used in blood-culture identification, which drives adoption through workflow efficiency and established lab footprints.
Recent regulatory and product events — De Novo authorization for a C. auris PCR (July 2024), pediatric clearance for a direct-from-blood molecular panel (September 2024), and single‑sample β‑D‑glucan test authorization (July 2024) — materially affect go-to-market tactics and competitive defenses. These moves expand clinical addressable markets and reduce friction for infection-control adoption in hospitals and children’s facilities alike.
Strategic Implications for 2026 Decision‑Makers
-
Prioritize label-expansion and pediatric strategies. The market reward for pediatric clearances is immediate access to large hospital networks and can speed payor acceptance in pediatric-centric institutions.
-
Invest in evidence for stewardship outcomes. Payers and hospitals increasingly require demonstration of downstream value (reduced antifungal days, shorter LOS). Comparative-effectiveness data — not only analytical performance — drives procurement decisions.
-
Design modular commercial models. Given the mix of hospital laboratories, reference labs, and infection-control programs, flexible pricing (subscription, reagent‑only, and instrument lease) increases uptake among differing buyer personas.
-
Leverage regulatory pathway knowledge as market access advantage. De Novo and pediatric clearances achieved by peers create playbooks that new entrants can emulate to accelerate adoption, but they also raise the bar for clinical validation.
-
Plan for platform interoperability. Labs prefer assays that integrate with LIMS and stewardship dashboards. Investments in connectivity and interpretive reporting improve product stickiness.
-
Use competitive concentration to inform M&A: with a concentrated top end of market, well‑targeted M&A or licensing deals can be the fastest route to meaningful scale — but price discipline is essential given incumbent valuation premiums.
Risk Matrix & Scenario Planning
-
Regulatory risk: stricter post-market requirements or novel CLSI standards could extend timelines for new assays. Mitigation: staged clinical studies and early regulatory consultations.
-
Reimbursement uncertainty: coding and reimbursement policy shifts can impact unit economics. Mitigation: proactive engagement with payors, capture of real-world outcomes that demonstrate cost offsets.
-
Competitive displacement: platform players with broader panels may commoditize single-analyte tests. Mitigation: focus on unique clinical value (speed, sensitivity, infection-control utility).
-
Epidemiologic volatility: pathogen prevalence shifts (e.g., local C. auris outbreaks) influence short-term demand. Mitigation: maintain flexible manufacturing and regional surveillance intelligence.
Immediate Next Steps for 2026
-
Run a rapid gap analysis against the report’s playbooks: identify which clinical claims and evidence packages are required to unlock the largest near-term hospital contracts.
-
Define a prioritized regulatory roadmap: choose between De Novo, 510(k) with predicate strategies, or expanded labeling for pediatric use based on product maturity and clinical data availability.
-
Establish partnerships with reference labs and infection-control networks to pilot deployment and capture real-world outcomes quickly.
-
Evaluate M&A targets using the report’s fit criteria to accelerate scale in underserved clinical settings or to acquire complementary platform capabilities.
For executives preparing budgets and product plans in 2026, the PW Consulting study transforms market projections into an executable plan — from clinical evidence investments to commercialization tactics and M&A priorities. To preserve competitive advantage and foster confident investment decisions, the full report includes the complete regional and application split tables, granular segment modeling, and the underlying financial workbooks required to run bespoke scenario analyses. Access the complete dataset and company dossiers through the PW Consulting report portal to obtain the detailed segmentation and downloadable models that are intentionally omitted from this public summary.
For detailed analysis of this topic, please visit the official page: Fungal Infection Diagnosis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rice Cracker Market to reach USD 26.92B by 2032 at 3.1% CAGR
By PW Consulting, 2026-07-12
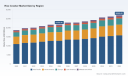
Rice Cracker Market — 2026 Strategic Preview for Decision-Makers
As global snacking continues its steady evolution, rice crackers have moved from regional specialty to a mainstream, multi-modal category with clear strategic implications for 2026 planning cycles. PW Consulting’s latest study (base year 2025) synthesizes five years of historical dynamics and projects the market forward across 2026–2032. In aggregate terms the market stood at approximately USD 21,784 million in 2025 and is forecast to grow to roughly USD 26,920 million by 2032, reflecting a compound annual growth rate of 3.1% over the forecast window. This preview highlights the study’s enterprise-level value: what to act on now, which signals to monitor, and where to drill into proprietary datasets to build 2026 budgets, product roadmaps, and M&A plans.
Rice Cracker Market
Why this matters for 2026 corporate decisions
- Stable, predictable expansion with selective disruption: The category’s mid-single-digit trajectory masks important pockets of acceleration — premium hand-crafted variants, vacuum-fried innovations, and convenience-led formats — as well as structural headwinds such as raw-material volatility. Leaders who treat the market as a portfolio of micro-opportunities will outpace those managing to a headline CAGR alone.
- Supply chain and raw-material risk are material: USDA and FAO indicators point to year-on-year fluctuations in rice availability and pricing that will influence input cost and sourcing strategies through 2026. Companies must translate macro crop forecasts into procurement and hedging actions today.
- Regulatory and labeling shifts are non-negotiable: Updated definitions of “healthy” in major markets place constraints and opportunities on formulation, front-of-pack claims, and marketing. Early compliance-first product launches will capture shelf space and distributor preference.
- Consolidation window is opening: The category exhibits moderate concentration — scale matters for distribution, private label partnerships and cost-to-serve economics, but regional champions and specialized manufacturers still command advantage in innovation and speed-to-market.
What the full PW Consulting report delivers (practical takeaways)
- Transparent market-sizing methodology and scenario-based forecasts (base year 2025; 2026–2032 outlook) with downloadable models for sensitivity testing.
- Actionable segmentation maps across geography, product type and channels — labeled for commercial prioritization and investment-readiness. (Note: high-level segmentation exists in the full dataset; this preview intentionally withholds line-item splits.)
- Channel playbooks for retail, modern trade and foodservice including SKU assortment strategies, private-label economics, and promotional elasticity assumptions.
- Product innovation scanner: sensory and process taxonomies (e.g., frying vs. vacuum-frying, glutinous/non-glutinous formulations), margin implications, and suggested pilot recipes for health-forward and premium lines.
- Competitor benchmarking templates and vendor heatmaps that link capability gaps to potential partners and acquisition targets.
- Supply-chain stress tests incorporating USDA and FAO crop scenarios, rice-price shocks, and cost passthrough mechanics to help finance teams stress test P&Ls.
- Regulatory impact matrix covering labeling changes and country-specific claim pathways (with recommended wording and pack-design mitigations).
- M&A and investment playbooks with prioritized targets and integration checklists to accelerate due diligence.
Competitive landscape — what to watch
The rice cracker competitive map is a mix of entrenched local champions and export-oriented specialists. Key players we profile in depth include Kameda Seika Co., Ltd., Fujian Hanwei Foods Co., Ltd., Thai-Nichi Industries Co., Ltd., Namchow (Thailand) Ltd., and Want Want Holdings Limited. Each offers a distinct strategic lesson:
Rice Cracker Market
- Kameda Seika Co., Ltd. (Tokyo) — A dominant domestic player with a broad portfolio and strong brand equity; scale advantage in Japan underpins R&D investment and distribution depth. Its experience highlights how broad assortments and strong domestic channels can insulate margin pressure.
- Fujian Hanwei Foods Co., Ltd. (Fujian) — Specializes in vacuum-fried variants and export-led snack lines; recent product introductions show how processing innovation can create premium price points while addressing texture and health perceptions.
- Thai-Nichi Industries Co., Ltd. (Thailand) — Longstanding exporter of Japanese-style rice crackers; their playbook is instructive for positioning heritage product formats in new retail channels and for leveraging B2B export partnerships.
- Namchow (Thailand) Ltd. — Active in global trade shows and promotional channels; recent exhibition activity underlines the importance of experiential marketing in generating distributor interest for thin-format novelties.
- Want Want Holdings Limited (Taiwan) — A major regional manufacturer and exporter with established production capacity in Vietnam; their footprint offers a model for lower-cost regional manufacturing coupled with multi-market brand strategies.
Recent corporate moves — trade-show participations and new product launches across 2025–2026 — spotlight two themes: (1) suppliers are investing in premium and plant-based innovations to capture higher-margin segments; and (2) export-oriented players are doubling down on trade promotion to secure distribution in fast-growing overseas channels. PW Consulting’s profiles include capability matrices, recent M&A noise, and go-to-market readiness scores for each company.
Rice Cracker Market
Market dynamics and risk signals
- Raw material volatility: Public-source forecasts indicate a material decline in certain crops in 2026/27 and broadly weaker global milled rice output year-on-year. Those shifts translate to input cost pressure and sourcing risk that directly affect gross margins for commodity-based SKUs.
- Price momentum: FAO rice price indices in early 2026 showed short-term upticks versus the prior month, even as year-on-year pressures moderated. Expect episodic input-driven price moves rather than a steady trend.
- Regulatory change: Evolving definitions of “healthy” and tightened front-of-pack requirements mean some existing formulations will need relabeling or reformulation to retain shelf claims in major export markets.
- Consumer preference shifts: Demand is bifurcating between value-driven, high-velocity snack formats and premium, craft-oriented variants that command better margins. Health-forward positioning — lower oil, whole-grain or alternative flours, and clean labels — continues to gain.
- Channel evolution: E-commerce and convenience channels are accelerating adoption of impulse snacks and bundle-based offers; foodservice demand is recovering post-pandemic but expects different pack sizes and shelf-life requirements.
Priority recommendations for 2026 (what good looks like)
- Immediate (0–12 months): Lock in multi-supplier rice contracts with price collars or indexation clauses; prioritize SKU rationalization to protect margin on high-cost inputs; initiate regulatory gap audits for labeling and health-claim compliance.
- Near-term product moves (6–18 months): Pilot 2–3 premium SKUs (e.g., vacuum-fried or artisanal hand-grilled variants) targeted at wholesale channels and high-margin e-commerce. Use limited-time flavors to test repeat-purchase mechanics before full roll-out.
- Operations & cost-to-serve (12–24 months): Invest selectively in automation and yield improvements in frying/drying steps; evaluate co-manufacturing or leased capacity in lower-cost jurisdictions to diversify production risk.
- Commercial & channel (12–36 months): Reconfigure assortment by channel: emphasize larger multipacks and private-label value SKUs in modern trade, and premium single-serve formats for travel retail and convenience. Negotiate trade-fund trade-offs tied to joint marketing investment.
- M&A & partnerships (18–36 months): Prioritize targets that add either unique processing capability (e.g., vacuum-frying), regional distribution control, or proprietary flavor intellectual property. Integration playbooks should focus on SKU delisting and shared procurement synergies.
- Long-term resilience: Build traceability programs upstream to control rice sourcing volatility; consider strategic equity stakes in upstream milling or co-op sourcing arrangements.
How PW Consulting’s report accelerates execution
This study combines a rigorous, auditable forecast model with playbooks, financial templates and competitor intelligence designed to accelerate decision-making. For executives allocating 2026 CapEx, planning launches, or sizing M&A transactions, the report translates macro scenarios into P&L outcomes and a prioritized action matrix. Importantly, while this preview highlights the study’s strategic frames and select company-level analysis, the full research contains granular segmentation, regional and application splits, price and margin matrices, and downloadable spreadsheets that operational teams can apply directly to 2026 budgets.
Next steps — where to dig deeper
If your organization is evaluating expansion, product innovation, sourcing changes, or M&A in rice-based snacks for 2026, PW Consulting’s full report provides the calibrated datasets, competitor scorecards and executable playbooks needed to move from strategy to execution. For procurement leads, R&D heads and corporate development teams, the most valuable next step is access to the underlying segment tables and scenario models — these are intentionally omitted from this preview to protect analytical value. Visit the source webpage to access the full dataset, interactive models, and a confidential briefing with our senior analysts.
For detailed analysis of this topic, please visit the official page: Rice Cracker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cigarette Market at USD 808.49M in 2025, 2.45% CAGR to 2032
By PW Consulting, 2026-07-12
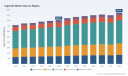
Cigarette Market 2026: Strategic Preview for Decision Makers
As PW Consulting’s Lead Industry Analyst, I offer a concise but strategically rich preview of our full Cigarette Market study — a report designed to equip senior executives with the situational awareness and decision-ready frameworks needed for 2026. Below I surface the macro signals, competitive implications, and high‑impact decision levers that every C‑suite, investor, and policymaker should factor into near‑term plans. This piece intentionally demonstrates our analytical depth while reserving the granular segment tables and company‑level data sets for the full report available via our platform.
Cigarette Market
Market snapshot: what the headline numbers reveal
Using 2025 as the base year, our market architecture shows a mature global market that is neither collapsing nor booming — but evolving. The market size in 2025 reached approximately USD 808.5 Million (base year 2025, historical series 2020–2025). Our forecast period (2026–2032) projects a compound annual growth rate (CAGR) of 2.45%, with the market continuing to expand modestly through 2032 under a set of industry‑specific structural drivers and regulatory pressures.
Cigarette Market
- Stability with pockets of volatility: the aggregate trajectory to 2032 implies steady growth punctuated by discrete year‑to‑year variations driven by policy, pricing actions, and supply shocks.
- Concentrated competitive structure: the market exhibits a high degree of concentration among a few global incumbent groups, a dynamic that intensifies the strategic importance of scale, distribution reach, and regulatory influence.
Why these macro facts matter for 2026 decisions
- Capital allocation under constrained growth: a contained CAGR around 2.45% means that incremental revenue from organic volume expansion will be modest industry‑wide. Management teams must therefore prioritize margin expansion (pricing, cost control, product mix) and selective inorganic moves that increase strategic control of growth levers.
- Regulatory sensitivity: with multiple regulatory inflection points expected to take effect or evolve in the 2026–2028 window, firms face asymmetric execution risk. Proactive regulatory scenario planning — rather than reactive cost‑cutting — is the superior value protection strategy in 2026.
- Supply chain resilience as competitive moat: volatility in tobacco leaf and clove markets and periodic natural‑resource shocks can compress margins suddenly. Firms that invest in diversified sourcing, direct farming partnerships, and financial hedges will preserve competitive profitability.
Report practicalities — what the full study gives you
The PW Consulting Cigarette Market report is intentionally operational. It is structured for executives who need to act now, not just theorize. Key deliverables include:
Cigarette Market
- Granular market sizing and validated forecasts (2026–2032) with sensitivity scenarios reflecting regulatory, taxation, and consumer preference shocks.
- Decision-ready playbooks: pricing and promotion playbooks for taxed markets, go‑to‑market templates for accelerated online penetration, and SKU rationalization frameworks aimed at preserving margins.
- Competitive benchmarking and capability maps: relative position analyses across manufacturing scale, distribution reach, alternative product portfolios, and regulatory affairs capability.
- M&A and partnership heatmaps: prioritized targets and partnership modes aligned to complementary gaps (e.g., next‑gen heated systems, reduced‑risk products, direct retail presence).
- Country and regulatory dashboards: curated regulatory timelines, excise tax scenarios, and enforcement risk indicators tailored to executives and public affairs leads.
- Supply chain and sourcing risk matrix: supplier concentration, critical raw material exposures, and recommended mitigation levers, including farming partnerships and inventory strategies.
These assets are supported by primary interviews, proprietary shipment intelligence, and cross‑validated public disclosures. The full report contains downloadable data tables and dashboards not reproduced here — designed to be used directly in board decks and investor diligence.
Competitive landscape — how the incumbents are shaping market structure
The market remains oligopolistic. A small number of global players control the lion’s share of manufacturing, brand equity, and distribution muscle. This concentration underpins strategic behaviors we expect to influence 2026 outcomes:
- Scale and brand stewardship. Global leaders leverage scale for cost advantages and deploy flagship brands to defend premium margins. Expect continued focus on sustaining leadership brands while selectively incubating alternate product formats.
- Portfolio diversification toward reduced‑risk products. Incumbents are increasingly balancing combustible portfolios with heated‑tobacco and nicotine alternatives as hedges against regulatory and demand shifts.
- Geographic and channel optimization. Firms are reconfiguring exposure across markets and accelerating channel investments (including e‑commerce and direct‑to‑consumer pilots) where regulatory frameworks permit.
Key players covered in the report include global groups with varied strategic postures: established multinational manufacturers based in Europe, North America, and Asia, each combining legacy combustible portfolios with differing commitments to next‑generation formats. Our company profiles synthesize public disclosures, shipment intelligence, and recent strategic moves to create actionable competitor playbooks you can use in boardroom debates.
Recent events and regulation shaping 2026 strategy
Several concrete developments provide a near‑term roadmap of risk and opportunity:
- Product innovation is accelerating: recent launches of advanced heated tobacco systems and compact reduced‑risk devices underscore intensifying competition in non‑combustible formats. These product introductions are not mere extensions; they are strategic hedges that alter channel, marketing and regulatory engagement needs.
- Tax and enforcement updates are reshaping economic returns: changes in taxation across major jurisdictions and emergent enforcement priorities for novel products elevate the cost of market entry and intensify compliance demands for 2026.
- Price adjustments in response to fiscal changes: manufacturers in several markets have adjusted pricing to absorb excise and structural tax changes while protecting margins — a tactical play that has implications for illicit trade dynamics and volume elasticity assumptions.
- Raw material and agronomic exposures: direct sourcing strategies and leaf price fluctuations materially affected last‑year profitability for major manufacturers; firms with greater vertical integration or long‑term contracts fared better.
Strategic recommendations for 2026
The path to preserving and growing value in 2026 is multidimensional. Based on our scenario analysis and stress tests, we recommend executives prioritize these actions:
- Rebalance the portfolio toward margin resilience. Optimize SKU breadth and pricing architecture to prioritize margin contribution per point of distribution.
- Accelerate investment in next‑gen products selectively. Prioritize segments where regulatory clarity is emerging and consumer acceptance is evident; treat others as opportunistic pilots until policy risk subsides.
- Fortify supply chains and farmer partnerships. Expand direct sourcing where feasible, and put in place commodity price hedges and buffer inventories for critical leaf inputs.
- Deploy scenario‑based regulatory playbooks. Build a small, empowered team to run rapid regulatory impact analyses and prepare communications and lobbying strategies tied to discrete policy milestones through 2028.
- Use M&A and partnerships defensively and offensively. Consider acquisitions that close capability gaps (e.g., heating technology, digital loyalty platforms), and use JV structures in high‑risk jurisdictions to share execution risk.
- Digitize distribution thoughtfully. Expand online channels where legally permissible and integrate them with loyalty and harm‑minimization communication strategies to capture customer lifetime value.
How PW Consulting can support execution
Our full Cigarette Market package equips clients with a playbook for immediate execution and a living data set for ongoing monitoring. Specific services include market entry due diligence, merger integration roadmaps, pricing optimization models, regulatory intelligence subscriptions, and custom scenario workshops for executive teams.
Importantly, this preview omits the granular segment and regional tables that matter when you move from strategy to execution. The full report contains those datasets, including downloadable tables, slice‑and‑dice dashboards, and company‑level market share matrices that enable transactional decisions and board reporting.
Next step — access the intelligence you need
For 2026, the difference between tactical survival and strategic progress will be how quickly organizations convert high‑level signals into prioritized actions. Our comprehensive report provides the data, scenarios, and operating playbooks to do exactly that. Visit our report landing page to access the complete dataset, segmented analysis, and client‑only tools that translate these insights into executable plans.
For detailed analysis of this topic, please visit the official page: Cigarette Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fishing Nets Market to reach USD 331.04M by 2032 at 6.5% CAGR
By PW Consulting, 2026-07-12
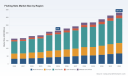
Fishing Nets Market — 2026 Strategic Outlook (PW Consulting)
The global fishing nets market is at a tactical inflection point. After steady expansion through the early 2020s, the sector’s total recorded market value reached an estimated USD 215.0 Million in our base year (2025). PW Consulting’s forecast shows the market reaccelerating across 2026–2032 at a compound annual growth rate (CAGR) of 6.5%, moving toward an expected market size north of USD 330 Million by the end of the forecast horizon. For executives sizing production investments, negotiating supplier contracts, or evaluating M&A and product-innovation plays, those topline dynamics are the starting point — not the full story. This preview explains why our Fishing Nets Market study is a decision-useful asset for 2026 planning while intentionally preserving the granular segment tables and regional splits found only in the full report.
Fishing Nets Market
Why this study matters for 2026 decisions
- Capital allocation that matches market tempo. The macro growth rate and trajectory clarify the window for scale investments in automated manufacturing, high-value material integration, and recycling capacity. Knowing the likely market envelope reduces the risk of overbuilding fixed assets or missing first-mover advantage.
- Supplier and raw-material strategy. Raw-material choices (from conventional polyamides to high-performance fibers and emerging biodegradable polymers) are driving lifecycle economics. The study quantifies how material selection alters total cost of ownership, replacement cadence, and end-of-life liabilities — insights essential to multi-year procurement contracts.
- Regulatory and circular-economy de-risking. Rapid regulatory shifts in key jurisdictions are transforming end-of-life handling and creating recovery opportunities. Our analysis shows which compliance-driven investments will become table stakes versus which can be monetized through secondary markets.
- Competitive playbook for consolidation or niche defense. With market concentration remaining modest, targeted roll-ups or capability-focused partnerships can materially change competitive position. We provide the market maps and valuation sensitivities required to execute informed M&A screening.
- Product and go-to-market prioritization. The report translates growth dynamics into prioritized product roadmaps and channel strategies for commercial, aquaculture and recreational segments, enabling faster time-to-value for R&D and pilot programs.
What the full report delivers (operationally focused)
- Executive summary and investment thesis tailored for C-suite decision points in 2026.
- Market-sizing methodology and reconciled historical series (2020–2025) with a transparent forecast model for 2026–2032, including sensitivity scenarios around fuel, polymer pricing, and accelerated regulation.
- Segment and subsegment analyses with modular dashboards (region, material, application) — note: the preview omits the detailed split tables to preserve strategic confidentiality.
- Material-cost and lifecycle cost models comparing conventional polymers, high-performance fibers, and biodegradable alternatives.
- End-of-life pathways and circular-economy playbooks — technical feasibility, capital requirements, and revenue recovery curves for recycling/upcycling options.
- Technology and manufacturing benchmarking: manual, semi-automated and fully automated lines, labor productivity, and capex-per-tonne comparisons.
- Competitive landscape and supplier shortlists with capability matrices, commercial terms benchmarking, and partnership targets.
- Regulatory tracker and scenario planning for major jurisdictions affecting fisheries and marine waste.
- Actionable 90-day and 12-month playbooks for procurement, product development and M&A teams.
Competitive landscape: strategic implications from leading players
The sector combines legacy craft specialists, regionally concentrated manufacturers, and a growing set of technology-led suppliers. Market concentration metrics indicate a fragmented global footprint (with the top three and top five shares at modest single-digit to low-double-digit levels), which creates opportunity for scale-driven consolidation or capability-driven differentiation.
Fishing Nets Market
- Garware Technical Fibres Ltd. (Mumbai, India) — A vertically integrated specialist with in‑house fiber-to-finished-product capability and proprietary low-drag formulations. Garware’s advantage is control over the value chain, enabling rapid iterations on material science and premium positioning for high-tenacity requirements. Strategic question for competitors: can you match material IP or win on service and lifecycle economics?
- Duluth Fish Nets (Duluth, Minnesota, USA) — A heritage handcrafted specialist serving domestic fleets and recreational users. Duluth’s moat is brand trust and bespoke capability. For buyers prioritizing customization or nearshore supply, artisanal operators remain defensible despite automation trends.
- Altela (France) — A transformer and supplier to netmakers offering competitive cost and lead-time optimization. Companies like Altela are critical to the low-cost tier of the value chain and can become acquisition targets for producers seeking to vertically integrate sourcing efficiency.
- King Chou Marine Technology Co., Ltd. (Taiwan) — Focused on polyethylene and nylon nets plus aquaculture cage systems for offshore operations. Its strength lies in high-performance offshore solutions — an attractive capability given the growing offshore aquaculture investments.
- Euronete (Portugal) — Automated manufacturing and close OEM integrations make Euronete a go-to supplier for fleet-scale contracts. OEM ties can produce long-term, high-volume contracts that act as a barrier to smaller players.
- Bridon International Ltd. (UK) — A ropes-and-twine specialist supporting demanding North Sea and North Atlantic operations. Bridon demonstrates how complementary product lines (ropes, twines) add stickiness to commercial relationships.
- Van Beelen Industry & Trade (Netherlands) — Dyneema®-based solutions extend service life and lower replacement cost of ownership for deep‑sea fleets. This material-led value proposition is central to discussions on premiumization and TCO-driven procurement.
- Khon Kaen Fishing Net Factory (Thailand), Shyh Yung Fa Fishery Equipment (Taiwan), Memphis Net & Twine (USA) — These regional manufacturers provide scale, processing competence, and near-market responsiveness. They exemplify the varied routes to competitiveness: low-cost scale, processing technology, and domestic proximity.
Market dynamics, recent developments and tactical risks
Several contemporaneous signals are reshaping strategic priorities for 2026:
Fishing Nets Market
- Sustainability and circularity are moving from compliance to commercial opportunity. Initiatives to collect and upcycle end-of-life nets (including a recent national startup program and institutional cleanup projects in Europe) indicate both reputational and feedstock value. Regulatory shifts in key markets are reclassifying recovered nets in ways that enable recovery and recycling economics to be captured by the private sector.
- Material innovation is bifurcating the market. Trials of biodegradable polymers and adoption of high-performance fibers like Dyneema® change replacement cycles and lifetime costs. Early pilots show biomass and operational performance benefits in aquaculture trials — a clear signal for operators to pilot and measure, not merely to speculate.
- Trade and tariff levers are influencing component costs. Targeted tariff relief in certain markets for floats and buoys reduces input cost volatility for net assemblers and creates localized opportunities for cost arbitrage.
- Ghost-net remediation is a reputational and regulatory flashpoint. High-visibility collection ops increase pressure on producers and fleets to demonstrate end-of-life pathways, with implications for product warranties and service offerings.
Practical 90‑day plan for management teams
- Run an internal TCO exercise for current net suites vs. Dyneema and biodegradable pilots; define three fleet/test sites and KPIs (durability, catch-efficiency, replacement cadence).
- Initiate supplier bilateral audits focused on circularity and traceability; shortlist 2–3 strategic partners for supply agreements and recycling commitments.
- Map regulatory exposure across your operating jurisdictions and create compliance-triggered investment thresholds (e.g., when recovery obligations create a payback case for in-house recycling).
- Finance: model consolidation scenarios using our valuation sensitivities to prioritize bolt-on acquisitions or JV structures that accelerate entry to recycling and automation capabilities.
- R&D/Marketing: design a pilot launch for eco-labelled nets targeting fleets and aquaculture customers willing to pay for verified lifecycle impact reductions.
PW Consulting’s full Fishing Nets Market report provides the quantified inputs, supplier scorecards and the scenario models required to execute the 90‑day plan above. This preview outlines the strategic levers — the full intelligence package contains the granular matrices and proprietary data necessary to operationalize them.
Next steps
For executives preparing 2026 budgets or seeking M&A and procurement advantage, the full report is the working tool: it includes the segment-level tables, regional dashboards and supplier scorecards referenced but intentionally withheld in this overview. Contact PW Consulting to obtain the full study, request a bespoke briefing, or commission a tailored workshop that translates these strategic directions into board-ready action plans.
For detailed analysis of this topic, please visit the official page: Fishing Nets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
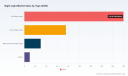
Night Light Market — Strategic Outlook for 2026: Executive Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused introduction to our forthcoming Night Light Market study. This executive preview is designed to orient corporate leaders, product strategists, and investment committees preparing for decisions in 2026. It highlights the strategic value of the full report, summarizes the macro dynamics that will shape vendor and investor outcomes, and outlines the actionable, decision-grade deliverables contained in the full study — while intentionally withholding core segment-level datapoints to preserve the report’s commercial value.
Night Light Market
Why this study matters for 2026 decisions
The night light category has evolved from a commoditized accessory into a diversified node at the intersection of lighting, IoT, safety regulation, and consumer gifting. Our market model — calibrated to a 2025 base year and a forecast horizon through 2032 — shows steady expansion driven by product innovation, channel shifts, and energy-transition dynamics. The global market expanded from the mid-hundreds of millions of USD in 2020 to an estimated total market size of USD 295 Million in 2025, and our modelling projects growth to roughly USD 400 Million by 2032 at a compound annual growth rate (CAGR) of 4.5% over the forecast period.
Night Light Market
That steady CAGR masks important inflection points relevant to 2026 planning: rising adoption of integrated commercial fixtures, the mainstreaming of rechargeable and motion-activated devices, and regulatory scrutiny that elevates product safety as a competitive moat. For firms contemplating product roadmaps, pricing shifts, or cross-border manufacturing decisions in 2026, the implications are clear — incremental revenue gains will accrue to players that pair design for compliance with channel-specific propositions (retail gift, e‑commerce, commercial lighting) and lower total cost of ownership for end customers.
Night Light Market
Core strategic themes you need to watch
-
Product-to-channel alignment: Night lights now span purpose-built commercial fixtures and impulse-purchase consumer goods. Commercial product innovations — exemplified by integrated flush-mount downlights with built-in night functionality — represent a materially different buyer, sales process, and lifetime-value profile than gift-oriented novelty night lights. 2026 strategies must separate channel economics and tailor SKUs accordingly.
-
Energy transition as a demand signal: Nighttime luminosity data and urban energy transition metrics are emerging as leading indicators for demand shifts. Recent high-resolution visualizations of nighttime light changes underscore geographic shifts in energy consumption and industrial activity — signals that buyers and planners can use to anticipate growth pockets and distribution priorities.
-
Compliance and product safety: Historical regulatory actions continue to inform design requirements. Robust design-for-compliance is non-negotiable in 2026; firms that proactively engineer to avoid recalls and fines will gain time-to-market advantages and channel trust.
-
Supply chain and tariff sensitivity: Material composition (plastics, glass, connectors) and tariff classification are routine but consequential drivers of landed cost. Procurement and IP-aware sourcing strategies can preserve margin even in modestly inflationary environments.
-
Low-power and off-grid innovation: Motion-activated and solar-powered variants change total cost-of-ownership dynamics. With active-mode consumption often measured in fractions of a single digit of watts, energy-efficient designs reduce buyer sensitivity to operational cost and open opportunities in sustainability-focused specifications.
What the full report delivers (practical, operational assets)
-
Transparent market sizing and forecast model: An auditable Excel model covering 2020–2025 historicals and 2026–2032 forecasts. The model includes alternate scenarios, sensitivity levers for raw material cost, and a reconciled demand-driver approach (end-use adoption, per-household penetration, and channel conversion rates).
-
Go-to-market playbooks by channel: Tactical revenue plans for retail, e‑commerce, and commercial channels — including SKU rationalization, margin ladders, promotional cadence, and suggested partner profiles for 2026 launches.
-
Supply chain and cost-mitigation toolkit: Component bill-of-material comparisons, tariff exposure mapping, and a supplier-risk dashboard that identifies single‑source dependencies and levers for onshore/nearshore resilience.
-
Regulatory & product safety checklist: Design-for-compliance templates, a prioritized remediation roadmap for common failure modes, and a compliance budget benchmark for 2026 product programs.
-
Technology and sustainability assessment: Competitive benchmarking across LED, motion-activation, rechargeable battery systems, and solar-integrated options, plus a practical rubric for quantifying lifecycle and energy-savings claims in B2B tenders.
-
50+ company profiles and M&A scorecard: Profiles of established suppliers and emergent challengers, including financial proxies, strategic fit matrices, and acquisition valuation bands targeted at strategic and financial buyers.
-
Commercial scenarios and playbooks for 2026: Tailored recommendations for market entry, SKU simplification, bundling, private-label strategies, and co‑development partnerships with commercial lighting integrators.
Competitive landscape — focused takeaways
Our competitive mapping identifies a mix of specialized manufacturers, gift/novelty suppliers, and incumbent commercial lighting brands. Market concentration is moderate: the top three firms account for roughly 40% of market share, and the top five account for about 55%. This structure leaves room for regional champions and differentiated product plays, but also rewards scale in distribution and compliance capabilities.
-
Fuzhou Maz-Tek Electronic Co., Ltd.: A China-based manufacturer with breadth in LED night lights and motion-activated toilet/night solutions. Their strength lies in turnkey manufacturing and gift-market packaging — an efficient partner for retailers seeking fast SKU churn. Strategic consideration: pursue co-development agreements that lock in volume while migrating higher-margin custom designs to controlled IP clauses.
-
Onefire: Focused on portable, rechargeable LED night lights for home and travel. Onefire exemplifies how rechargeable form factors capture higher ASPs and better repeat purchase economics through accessory and battery programs. Strategic consideration: portable/rechargeable leaders are natural acquirers for accessory ecosystems and consumer-facing subscription services.
-
Ankeral: Supplier of custom cartoon night lights positioned for gift and impulse retail. Their value is in licensing and co-branding — an effective short path to retail shelf presence. Strategic consideration: licensing partnerships can be leveraged to enter high-margin gifting segments but require robust IP and quality controls to mitigate recall risk.
-
Cooper Lighting Solutions: A U.S.-based incumbent in commercial lighting whose product strategy increasingly blurs the line between ambient fixtures and night-light functionality. Their January 2026 launch of flush-mount LED downlights with integrated night light functionality exemplifies the premiumization of night-time illumination in commercial spaces. Strategic consideration: lighting incumbents can bundle specification-led night-light features into larger projects, raising switching costs for specifiers and installers.
Recent developments that alter the playbook for 2026
-
Nighttime luminosity research: A high-resolution visualization released in April 2026 highlights shifting urban brightness patterns tied to energy transition and industrial relocation. For market planners, these datasets act as early indicators for geographic demand reallocation and will be embedded in our predictive geospatial module.
-
New product introductions: The move by commercial lighting incumbents toward integrated night-light fixtures underscores an urgent need for consumer-market players to defend premium spaces via differentiated features or channel specialization.
-
Regulatory and raw-material realities: Legacy product-safety precedents — including historic recalls — remain a design constraint. Tariff classifications and raw material sourcing (plastic and glass components) directly affect landed costs and product returns; our report includes an actionable tariff-impact model and supplier diversification pathways.
-
Energy-efficiency and off-grid adoption: Motion-activated devices typically consume under a few watts when active, and solar-powered variants have demonstrable household-level savings in early adopter geographies. These technical differentials materially change purchase rationales for both residential buyers and specification-driven commercial buyers.
Recommended 2026 actions — prioritized
-
Embed compliance into product development: Make design-for-compliance a gating criterion for all 2026 launches; the cost of retrofits after a recall far exceeds pre-launch assurance spending.
-
Segment your portfolio by channel economics: Separate commercial-spec, retail-impulse, and gifting SKUs; assign distinct margin and inventory policies to each.
-
Pursue selective nearshoring or dual-sourcing: Use tariff-exposure mapping to prioritize nearshore capacity for higher-margin SKUs while maintaining offshore cost leadership for commoditized lines.
-
Invest in low-power differentiation: Prioritize motion-activated, rechargeable, and solar-integrated SKUs where lifecycle benefits can be quantified and sold to B2B buyers.
-
Target bolt-on M&A for channel access: Identify targets with established retail relationships or IP in aesthetic design to accelerate shelf presence without the 12–18 month organic build cycle.
Next steps — how to use the full report
This preview is a strategic orientation. The full Night Light Market report from PW Consulting provides the granular, auditable data and executable templates required to operationalize the recommendations above — including the complete segmentation tables, regional and application splits, SKU-level pricing, and vendor scorecards that are intentionally omitted here to preserve the report’s commercial utility.
For strategy teams preparing 2026 budgets, product leaders sizing SKUs, and corporate development teams screening targets, the full study delivers the evidence base and playbooks needed to move from hypothesis to execution. Access to the complete dataset and proprietary models will enable you to run scenario simulations using your own cost and channel assumptions.
To request the full report and the accompanying modelling files, or to commission a tailored strategic workshop that applies the study’s insights directly to your 2026 planning cycle, please contact PW Consulting via our report webpage.
For detailed analysis of this topic, please visit the official page: Night Light Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tumor Ablation Market Poised for 6.23% CAGR Through 2032
By PW Consulting, 2026-07-12
Tumor Ablation Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest Tumor Ablation Market study is built as an action-oriented intelligence asset for executive teams, M&A groups, product leaders and health-economic strategists planning for 2026 and beyond. The global tumor ablation market has moved from a niche interventional oncology discipline into a strategically relevant growth segment for medtech portfolios. Our research synthesizes historical performance, regulatory and reimbursement inflection points, competing technologies, and an investment-prioritized forecast to convert market signals into boardroom-ready choices.
Tumor Ablation Market
Why this study matters for 2026
- Clear timing of inflection: After steady historical expansion, the market reached USD 214 Million (base year 2025) and is modeled to continue expanding through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.23%. That trajectory creates distinct windows for investment, commercialization and consolidation decisions in the next 12–24 months.
- Reimbursement & regulatory catalysts: 2026 introduces new CPT codes for several ablation modalities and indications, while Breakthrough Device designations and device clearances are reshaping market access pathways. These non-price factors are becoming as decisive as clinical performance in adoption.
- High concentration with targeted disruption opportunities: Market concentration (CR3 = 62.5%; CR5 = 75.0%) indicates dominant incumbents control the majority of revenue, yet structural fragmentation by modality, anatomic indication and price point creates repeatable niches for challengers and regional specialists.
Market trajectory — the numbers you need to budget against
For planning purposes, PW Consulting uses a conservative base-year anchoring (2025) and transparent driver assumptions to produce scenario-ready forecasts. The market grew from the low hundreds of millions at the start of the decade to USD 214 Million in 2025 and is expected to continue to expand to a substantially larger base by 2032 under a 6.23% CAGR across the 2026–2032 forecast. Our model blends clinical adoption curves, unit economics, device lifecycle timelines and reimbursement timing to give finance teams the probabilistic outcomes they need for capital allocation and valuation stress-testing.
Tumor Ablation Market
We deliberately do not disclose granular region, modality or indication revenue lines in this preview—those segmentation tables, interactive models and sensitivity runs are available in the full report to paying subscribers. The teaser avoids handing away targeted opportunity maps that clients pay us to build and execute.
Tumor Ablation Market
Dynamics shaping 2026 decisions
- Reimbursement shifts: The introduction of new CPT codes in 2026 for irreversible electroporation (IRE) in liver and prostate ablation, plus discrete codes for benign and malignant breast tumor ablation, materially lowers a key barrier to adoption. Providers now have clearer billing pathways which accelerates procurement cycles for hospitals and ASCs that have been reimbursement-constrained.
- Regulatory catalysts: Recent Breakthrough Device designations and device clearances (including notable microwave and cryo systems) shorten time-to-market for high-potential platforms. Regulatory momentum also raises the floor for clinical evidence expectations; early entrants without compelling outcomes data face tighter adoption timelines.
- Technology substitution and clinical workflow: The market is no longer a duel between single modalities—clinicians increasingly choose modality by lesion type, anatomic access and competing clinical endpoints (local control, procedure time, complication profile). Hybrid workflows and adjunct imaging (MRI-guided or CT-guided systems) are becoming differentiators rather than niceties.
- Capital intensity and hospital economics: High upfront CapEx for ablation platforms remains a restraint on broad hospital deployment despite rising cancer incidence. Financing structures, rental models, and outcome-based contracting are now core negotiation topics between medtech sellers and large hospital systems.
Competition: what incumbents and challengers are doing
The competitive landscape mixes global medtech giants with focused interventional oncology specialists and regional OEMs. Strategic playbooks differ by scale: large entrants prioritize integrated offerings and channel leverage; challengers compete on niche clinical evidence, pricing flexibility, and rapid feature iterations.
- Medtronic (Ireland) — Leverages cross-portfolio synergies for bundled clinical solutions. Their microwave and bone ablation offerings are positioned for multi-indication adoption; expect continued investment in ease-of-use and lesion-mapping workflows.
- Boston Scientific (United States) — Focuses on radiofrequency systems and sensing innovations that reduce procedural uncertainty. They are likely to pursue partnerships with imaging and navigation vendors to lock in procedure-level share.
- AngioDynamics (United States) — A nimble innovator in microwave, recent 510(k) clearance for an upgraded Solero system (Sep 2024) reinforces their product-refresh cadence and user-interface-led differentiation.
- Johnson & Johnson / Ethicon (United States) — Brings scale and distribution muscle to RF and cryo modalities; their commercial strength favors bundled supply deals with large health systems.
- Siemens Healthineers / Varian (Germany) — By coupling imaging and ablation platforms they aim to control the peri-procedural workflow; Varian’s IntelliBlate microwave clearance demonstrates the value of that integration strategy.
- Focused players (Hologic, Stryker, Merit, IceCure, Galil, Profound, Monteris, and others) — These companies compete in deep clinical niches (breast, bone, kidney, prostate, brain) where focused evidence-generation and KOL relationships can deliver outsized returns. IceCure’s FDA approval for a renal indication (Jan 2025) is emblematic of how indication-level wins can alter a small player’s trajectory.
Across the competitive set, the most consequential differentiators in 2026 will be: demonstrated clinical outcomes vs. standards of care, integration with imaging/navigation, capital and consumable economics, and reimbursement-readiness (codes + payer coverage). PW Consulting’s vendor assessment matrix in the full report scores competitors across all these dimensions to support procurement and partnering decisions.
Practical, actionable content inside the full PW Consulting study
The report was developed to be directly operational for clients. Key deliverables include:
- Market sizing and probabilistic forecasts (2026–2032) with scenario sensitivity to reimbursement timing, pricing pressure and adoption curves.
- Commercial playbooks: go-to-market sequencing (hospital vs. ASC), pricing levers, consumable margins and recommended financing models for capital-constrained customers.
- Reimbursement playbook and coding timeline: how to translate new CPT codes and coverage signals into an accelerated adoption plan for device and service vendors.
- Clinical evidence roadmaps: required study designs and endpoints to win hospital pharmacy & therapeutics, IR committees and payer coverage for the next three years.
- M&A and partnership heatmap: acquisition targets, strategic partners and white-space opportunities by modality and indication that align to a range of investment theses.
- Competitive benchmarking and vendor scorecards: strengths, weaknesses, and go-forward tactics for the 15 core companies profiled.
- Interactive financial model: client-customizable assumptions for unit volumes, device ASPs, utilization rates and margin scenarios.
How to use this intelligence for 2026 planning
- PE / M&A teams: Use our scenario models to stress-test EBITDA accretion under alternative adoption and reimbursement timelines; our heatmap identifies bolt-on targets that fill modality gaps or accelerate access to strategic geographies.
- Product & R&D leaders: Prioritize evidence generation aligned to payer-critical endpoints; invest in integration with imaging/navigation to improve the value proposition beyond single-use device features.
- Commercial leaders: Reconfigure sales territories and incentive plans to capture ASC-led growth, and design hybrid CapEx/consumable pricing where hospital procurement cycles remain elongated.
- Clinical affairs & HEOR: Sequence studies to secure coverage decisions as CPT codes take effect—designed real-world evidence now wins as much business as randomized trials in many indications.
Closing perspective: timing, risk and upside
2026 is a planning inflection: reimbursement clarity, selective regulatory wins and continued clinical acceptance create a favorable but nuanced growth environment. The 6.23% CAGR baked into our base forecast projects steady expansion but does not preclude upside from faster-than-expected reimbursement uptake or broader ASC adoption models. Conversely, capital constraints and competing oncology priorities could slow adoption in some hospital systems.
For executives who need to convert opportunity into quantifiable action: the primary near-term levers are portfolio alignment (which modalities and indications to back), evidence sequencing (which clinical programs to fund now), and commercial model redesign (how to price and finance access). PW Consulting’s full report contains the granular segmentation, device-level economics and interactive tools your team will use to operationalize those decisions.
Next steps
This preview intentionally omits the full segmentation tables, regional and indication-specific revenue figures and the granular vendor-by-indication market shares to preserve the tactical value of the full engagement. Access the complete Tumor Ablation Market report for the detailed datasets, proprietary vendor scores, and the interactive financial model that will enable your 2026 strategic plan.
For detailed analysis of this topic, please visit the official page: Tumor Ablation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: GMP Cytokines Market to Reach USD 223.9M by 2032 at 9.5% CAGR
By PW Consulting, 2026-07-12
GMP Cytokines Market — Strategic Outlook for 2026 Decision-Makers
As the advanced therapy ecosystem moves from promise to commercial scale, GMP-grade cytokines have emerged from a niche reagent category into a strategically critical input for cell and gene therapy manufacturing. PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—maps this transition with quantitative rigor and practical advice. The global GMP cytokines market, having expanded from an emerging USD-level segment in 2020 to a materially larger market by 2025, is expected to sustain a high-single-digit compound annual growth rate (CAGR) through the forecast period. That trajectory captures both accelerated clinical activity and the early waves of commercialized ATMPs that will shape procurement, manufacturing and partnership decisions in 2026 and beyond.
GMP Cytokines Market
Why this study matters for 2026 corporate strategy
-
Timing: 2026 is the hinge year for many organizations—clinical programs are entering pivotal phases, and manufacturers are deciding whether to scale capacity or optimize current facilities. Our analysis translates market momentum into decision triggers: when to lock in long‑lead suppliers, when to expand internal reagent production, and when to pursue strategic alliances.
GMP Cytokines Market -
Risk-to-reward clarity: With regulatory scrutiny and supply‑chain intensity rising for ancillary materials used in ATMPs, the study isolates the operational risks that most materially affect COGS, batch success rates and time-to-clinic—enabling procurement and R&D leaders to prioritize mitigations that deliver tangible ROI within 12–24 months.
GMP Cytokines Market -
Investment calibration: The market’s projected expansion at an approximate mid‑single‑digit to high‑single‑digit CAGR implies that selective capacity investments and licensing arrangements can achieve attractive payback. Our scenarios translate that growth into capacity-demand bands so CFOs and business development teams can evaluate greenfield versus contract manufacturing strategies.
Data-driven pulse: market scale and growth dynamics
PW Consulting quantifies a clear multi-year growth pathway. The market has experienced sustained growth through 2020–2025 and is projected to rise materially over the 2026–2032 forecast window at an approximate CAGR of 9.5%. The baseline sizing and trend analysis in the report combine historical shipment data, leading supplier disclosures and validated demand models from cell and gene therapy programs to produce a credible runway for manufacturers, suppliers and investors deciding in 2026 whether to scale, partner or diversify.
Important: in this executive preview we surface aggregate scale and growth rates to frame strategic choices; deliberately withheld are the granular regional, application and type-specific splits that corporate teams tell us are most valuable for supplier selection and pricing negotiation. Those segment-level tables and scenario matrices are available in the full report.
Market structure and concentration
The GMP cytokines market shows a moderate-to-high level of supplier concentration. A small group of established life-science companies and specialist reagent producers command a significant share of validated GMP supply, while regional and cost-competitive entrants serve price-sensitive clinical customers and emerging markets. For decision-makers in 2026, that structure creates both opportunity and constraint: premium suppliers offer deep regulatory files and integrated services, whereas newer entrants provide flexible pricing and targeted portfolios. The report quantifies concentration bands and maps supplier archetypes to commercial strategy options—information essential to negotiating supply agreements and contingency plans.
Competitive landscape: capabilities that matter
Leading suppliers are differentiating along several axes that will shape procurement choices in 2026:
-
Regulatory completeness and documentation: Full ATMP-ready regulatory packages reduce release friction and clinical risk. Several major providers explicitly position PeproGMP-style documentation or comparable files as a core commercial differentiator.
-
Manufacturing scale and format innovation: Weldable bag formats, dedicated GMP suites and expanded facilities are shifting the economics of supply and on-site integration with cell manufacturing platforms.
-
Product breadth vs. focus: Some firms compete on a broad interleukin/interferon portfolio with global distribution; others specialize in a narrower set of high-demand cytokines optimized for immune‑cell expansion.
Representative supplier moves underscore these themes. Recent product launches expanded GMP cytokine ranges targeting immune-cell expansion optimization; suppliers showcased novel packaging formats tailored for aseptic workflows; and one major player announced further capacity expansion in early 2026 to support ATMP demand. Collectively, these developments signal an industry shifting from ad-hoc reagent sourcing to purpose-built GMP supply chains.
What the report covers — practical, decision-ready modules
PW Consulting’s study is organized to support near-term corporate decisions, with modules that include:
-
Market sizing and validated demand models (historical 2020–2025 and forecast 2026–2032).
-
Segmentation frameworks across type, application and region that translate into procurement playbooks. Note: segment-level tables and interactive drilldowns are contained in the full report to preserve commercial sensitivity in this preview.
-
Supplier scorecards and manufacturing maps—assessing regulatory compliance, format innovation, production scale and geographic footprint.
-
Price benchmarking and margin sensitivity analyses that connect cytokine sourcing choices to product COGS and commercial-readiness timelines.
-
Risk registers addressing supply-chain fragility, raw-material classification (including contemporary guidance on ancillary material risk), regulatory change vectors and contingency strategies.
-
Actionable 12–36 month growth and sourcing playbooks tailored for biopharma, CMOs, and reagent suppliers—spanning dual sourcing, in‑house manufacture, licensing and localized production.
Strategic imperatives for 2026
-
Lock the right form of regulatory readiness: For sponsors moving toward pivotal studies or early commercialization, vendors’ ATMP-ready regulatory packs materially shorten release timelines. Prioritize suppliers that provide validated regulatory support as part of commercial contracts.
-
Dual-track sourcing to balance resilience and cost: Establish primary suppliers for validated, release‑ready cytokines and secondary, cost-competitive partners for scale-up or non‑critical use cases. The report provides decision trees to quantify when to internalize production versus outsource.
-
Design procurement around packaging and process compatibility: Bag formats, low‑hold volumes and aseptic interfaces reduce handling risks in closed manufacturing platforms; select suppliers whose product forms integrate with your platform strategy.
-
Prioritize animal-free and defined materials: As allogeneic and off-the-shelf product strategies proliferate, animal-component‑free cytokine formulations lower downstream regulatory risk and align with long-term commercialization requirements.
-
Revisit pricing and long‑term contracts in light of capacity expansions: Facility investments and new product launches announced through late 2025 and early 2026 will affect lead times and negotiating leverage. Use our scenario models to time multi-year agreements.
Competitive snapshots (selection)
Key players exemplify the strategic choices available to buyers:
-
Established life-science integrators are leveraging acquisitions and expanded GMP suites to offer breadth plus integrated CDMO-style services, enhancing convenience for cell therapy manufacturers seeking streamlined vendor management.
-
Specialist cytokine manufacturers are focusing on regulatory support, animal-free formulations and portfolio depth for immune cell expansion—attributes attractive to sponsors focused on minimizing development friction.
-
Cost-competitive regional suppliers are gaining traction with price-sensitive clinical-stage customers in fast-growing markets by offering regional logistics advantages and tailored pricing models.
Regulatory and raw-material considerations
Regulatory frameworks and ancillary material classifications increasingly shape procurement risk. Contemporary guidance places certain human-derived and engineered cytokines into elevated risk tiers for cell and gene therapy manufacturing, which affects supplier qualification and audit requirements. In practice, this means that buyers must evaluate not only GMP certificates but also the depth of regulatory file support, change‑control history and manufacturer auditability. The full report maps regulatory implications to supplier selection criteria and provides templates for technical due diligence.
How leaders are using this intelligence in 2026
Early adopters of the study’s playbooks are taking four concrete steps:
-
Reconfiguring supply contracts to include regulatory deliverables and batch-level traceability clauses.
-
Accelerating qualification of secondary suppliers to reduce single-source exposure for critical cytokines.
-
Negotiating strategic capacity reservations with suppliers expanding production in response to ATMP demand signals.
-
Aligning internal process development milestones with supplier roadmaps to de-risk scale-up during pivotal clinical windows.
Next steps — where this preview leads
This briefing presents the high-level market trajectory and the strategic implications that will drive procurement, manufacturing and partnering decisions in 2026. It purposefully omits the granular region/type/application matrices and supplier-level pricing models that corporate teams rely upon for contract negotiations and capital allocation. PW Consulting’s full GMP Cytokines Market report provides those detailed data tables, scenario-specific demand curves, supplier scorecards and executable playbooks that translate this strategic framing into tactical actions.
For executive teams preparing 2026 budgets and GTM plans, the choice is simple: treat GMP cytokines as a routine consumable or treat them as a strategic input whose sourcing, format and regulatory posture materially influence clinical timelines and margin outcomes. Our research equips you to make that call with confidence.
For detailed analysis of this topic, please visit the official page: GMP Cytokines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


