



Category: Healthy Lifestyle
PW Consulting: Total Artificial Heart Market to Grow at 11.5% CAGR Through 2032
By PW Consulting, 2026-07-12
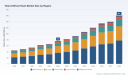
Total Artificial Heart Market: Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a forward-looking brief that frames the Total Artificial Heart (TAH) market through a 2026 decision lens. This introduction synthesizes the directional signals, regulatory inflection points, clinical outcomes, and competitive moves that will shape corporate strategy in the near term — while intentionally withholding the granular segment-level tables and proprietary model outputs contained in our full report to incentivize direct engagement with the source study.
Total Artificial Heart Market
Macro picture: growth trajectory and why it matters for 2026
The TAH market has shown sustained expansion over the recent historical window and is entering a period of accelerated commercialization and clinical validation. Our base-year analysis (2025) places the global TAH market at roughly USD 76 million, a meaningful increase from the early-2020s baseline. Using an 11.5% compound annual growth rate (CAGR) across the forecast horizon, the market is projected to approximately double in size by the end of the 2026–2032 forecast period, reflecting both rising clinical adoption and product innovation.
Total Artificial Heart Market
For corporate leaders, this pattern signals a classic early-growth opportunity: demand is expanding fast enough to justify near-term strategic investments, but the market is not yet saturated or highly consolidated — meaning moves taken in 2026 can materially affect long-term market position. The quantitative trajectory in our model also underscores the asymmetric payoff of timing: companies that deploy capital to address key clinical and regulatory bottlenecks now stand to capture disproportionate value over the next five to seven years.
Total Artificial Heart Market
Why 2026 is a pivotal inflection for TAH strategies
- Regulatory clarity and novel pathways: The U.S. and European regulatory environments have both evolved recently. As of 2026, one legacy system retains sole market approval in the U.S. for the bridge‑to‑transplant indication, while new entrants have achieved breakthrough designations and lifecycle engagements with regulators. These developments create discrete windows for market entry, conditional approvals, and staged rollouts that corporate legal and regulatory teams must prioritize this calendar year.
- Clinical validation is accelerating: Longitudinal outcome reports and in vitro hemocompatibility studies published in 2026 are reducing clinical uncertainty around durability and blood-damage profiles — two of the most sensitive adoption criteria for surgeons and payers.
- Reimbursement levers are usable: Current coding pathways and payer coverage for bridge‑to‑transplant implants offer a practical commercialization route in many major markets, but reimbursement nuances differ by jurisdiction and require localized value dossiers and economic evidence packages.
- Technology divergence is creating strategic options: Competing engineering approaches — from pneumatic drivetrains to magnetically levitated rotors and bio‑mimetic systems — are producing differentiated clinical footprint and go‑to‑market propositions. Choice of technology will determine partnerships, supply chains, and clinical claims for years to come.
Competitive landscape: what the leading players’ moves mean
Three types of industry actors define the current competitive topology: legacy, emerging clinical-stage innovators, and new-generation developers focused on blood compatibility and durability.
- Established incumbent(s): Legacy systems with long implant histories remain central to surgical practice and hospital procurement decisions. Incumbent brands benefit from clinician familiarity, an installed base, and existing reimbursement pathways, but they face pressure on incremental innovation and hemocompatibility metrics.
- Clinical-stage disruptors: A subset of firms are advancing radical engineering approaches (e.g., MAGLEV, fully enclosed bio‑mimetic systems) via early feasibility studies, Breakthrough Device pathways, and total product lifecycle collaborations with regulators. These entrants have the potential to change the competitive calculus once pivotal data are published.
- Evidence-focused challengers: A number of companies are prioritizing head-to-head and long-term outcome studies to establish superiority on hemolysis, thromboembolic events, and device longevity — endpoints that will heavily influence surgeon preference and payer willingness to reimburse premium pricing.
Concrete examples from recent months crystallize these dynamics. Clinical outcome announcements have extended the observed durable support durations for certain TAH implants, demonstrating that multi‑year bridging to transplant is feasible in contemporary practice. Simultaneously, in vitro research released by developers has shown material differences in blood damage between devices — an essential input for hospitals and payers assessing device tradeoffs. Finally, regulatory milestones, including breakthrough designations and post‑approval conformity under updated European standards, are actively reshaping each firm’s path to scale.
Regulatory and reimbursement dynamics — tactical priorities for 2026
- Engage early with lifecycle regulators: Firms pursuing U.S. entry should prioritize early engagement to leverage expedited pathways and to design post‑market commitments that align with payers’ evidence expectations. Acceptance into lifecycle programs can materially shorten time to broader commercialization.
- Build payer-grade economic evidence: For bridge‑to‑transplant use, existing surgical procedure coding is recognized by most large payers in key markets. However, translating device-level clinical outcomes into hospital budget impact and cost-effectiveness narratives is non-trivial — and it must be done by 2026 if reimbursement negotiations are to go smoothly in subsequent approval phases.
- Anticipate regional regulatory divergence: The recent re-certifications under updated European medical device rules create a stricter conformity baseline in some markets. Companies should plan differentiated regulatory‑to‑market sequences rather than assuming single-path global rollouts.
Operational and commercial implications
Operational leaders must balance rapid capacity expansion against uncertain early-stage demand patterns. Manufacturing scale decisions should be modular: establish validated, quality‑assured production lanes that can ramp with secured reimbursement and hospital program commitments. Commercial teams should prioritize center-of-excellence partnerships, surgeon training programs, and real-world evidence initiatives that reduce adoption friction.
For business development and corporate development teams, 2026 is a window for opportunistic M&A and strategic alliances. Targets that can accelerate clinical evidence generation, improve hemocompatibility, or simplify the extracorporeal console footprint will fetch premium valuations. Given current competitive dispersion, well-timed tuck‑ins or co-development deals offer a quicker route to differentiated product portfolios than greenfield development alone.
What our full report delivers (practical contents)
PW Consulting’s comprehensive TAH study goes beyond directional commentary to furnish the operational playbook that decision makers need in 2026. Highlights include:
- Proprietary market-sizing and forecasting model (historical 2020–2025, base 2025, forecast 2026–2032) with sensitivity scenarios and demand drivers.
- Clinical evidence compendium and meta‑analysis that harmonizes published outcomes, device‑level hemocompatibility data, and registry inputs.
- Regulatory pathway maps for major jurisdictions, including recommended milestones and submission playbooks for both accelerated and conventional routes.
- Reimbursement playbook: coding, coverage, and value dossier templates tailored to hospital procurement and payer negotiation.
- Commercial go‑to‑market frameworks: center-of-excellence criteria, surgeon training curricula, and hospital ROI calculators.
- Manufacturing and supply‑chain readiness assessment, including CAPEX estimates, scale‑out strategies, and risk mitigation for critical components.
- M&A and strategic partnership screening matrix, including prioritized technology targets and valuation levers.
- Investor and board briefing materials, scenario-based risk analyses, and recommended KPIs for 12–36 month execution horizons.
How to use these insights in 2026 — recommended next steps
- Boardroom (0–3 months): Validate or reset strategic priorities using the PW market baseline and downside/upside scenarios; authorize focused investments in regulatory and clinical evidence programs that will de‑risk reimbursement conversations.
- R&D and clinical (3–9 months): Rebalance development roadmaps to prioritize hemocompatibility and durability endpoints that are driving payer and surgeon choice; integrate head‑to‑head and long‑term follow‑up studies into clinical plans.
- Regulatory and reimbursement (3–12 months): Initiate parallel submissions where feasible; build payer dossiers in tandem with pivotal studies rather than as an afterthought.
- Commercial and operations (6–18 months): Lock in pilot hospital partners, deploy training programs, and stage manufacturing scale to align with confirmed reimbursement navigation outcomes.
- Corporate development (ongoing): Screen for acquisitions or licensing that accelerate claims differentiation, reduce time to market, or broaden service offerings around TAH implants.
Final perspective
The TAH market in 2026 presents a rare combination of rapid growth, meaningful clinical uncertainty resolution, and regulatory momentum. Taken together, these factors create an environment where decisive, evidence-driven investments can materially alter a company’s competitive trajectory. PW Consulting’s full study provides the actionable intelligence, financial modeling, and operative templates necessary to translate strategic intent into market leadership — while retaining the granular segmentation, scenario-specific forecasts, and proprietary modeling in our subscription-grade deliverable.
For access to the full model, segmentation breakdowns, and executable playbooks referenced here, please consult the complete Total Artificial Heart Market report on our website or contact your PW Consulting representative. The granular data and templates you’ll find there are designed to convert 2026 strategic choices into measurable wins across regulatory, clinical, and commercial dimensions.
For detailed analysis of this topic, please visit the official page: Total Artificial Heart Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lab Animal Housing Cage Market to reach USD 418.3M by 2032 (4.45% CAGR)
By PW Consulting, 2026-07-12
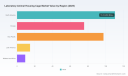
Laboratory Animal Housing Cage Market — Strategic Primer for 2026 Decisions
Executive snapshot
As life-sciences organizations recalibrate capital plans and operational models in 2026, laboratory animal housing cages sit at the intersection of regulatory compliance, animal welfare, and high-throughput research productivity. PW Consulting’s new market study — built on a 2020–2025 historical foundation and projecting through 2032 — quantifies a steady market expansion driven by modernization of housing systems, regulatory tightening, and the adoption of digital monitoring and high-density platforms. In revenue terms (USD, Million), the market expanded from the mid-200s in 2020 to an estimated 307.5 in the 2025 base year, and under a 4.45% compound annual growth rate is projected to reach the low-400s by 2032. Combined with a moderately concentrated vendor structure (CR3 ~62.5%, CR5 ~73.0%), these dynamics create clear windows for selective investment, product differentiation, and consolidation plays.
Laboratory Animal Housing Cage Market
Why this research matters for corporate strategy in 2026
-
Capital allocation: The market’s steady CAGR and trajectory through 2032 create a predictable backdrop for multi-year CapEx planning. Organizations weighing refurbishment versus full system replacements can map replacement cycles against forecasted price and product evolution to optimize total cost of ownership and depreciation schedules.
Laboratory Animal Housing Cage Market -
Product and technology roadmaps: The convergence of IVC (individually ventilated cages), digital home-cage monitoring (AI/RFID), and high-autoclave longevity plastics means product roadmaps must prioritize interoperability, lifecycle durability, and data-enabled welfare metrics to stay relevant to tiered customers (academic, CRO, pharma).
Laboratory Animal Housing Cage Market -
Regulatory-driven demand: Stricter enforcement and accreditation expectations are creating upstream demand for advanced environmental control and enrichment-compliant systems. Firms that can demonstrate validated environmental parameters, sanitation workflows, and documented welfare outcomes will enjoy pricing power and faster procurement cycles.
-
M&A and partnership timing: With a high-three and high-five concentration already apparent, 2026 is a tactical year for bolt-on acquisitions to fill capability gaps (digital monitoring, regional service footprints) or for incumbents to pursue vertical integration into services and analytics offerings that extend contract lifetime value.
Market dynamics and what’s driving growth
Three structural forces underpin the market outlook. First, regulation and accreditation—regional directives and international standards—are increasing the baseline technical requirements for housing systems, notably in environmental stability, enrichment, and documented sanitation routines. Second, operational efficiency pressures (facility space constraints, labor costs, and biosecurity) are accelerating adoption of high-density IVC platforms and modular systems that lower per-animal handling time. Third, digitalization—ranging from RFID-enabled census systems to AI-powered behavioral monitoring—shifts the value proposition from hardware alone to integrated hardware+software service models. Together these forces lift average selling prices for advanced systems and create recurring revenue opportunities through consumables, maintenance, and analytics subscriptions.
Regulatory and operational context — implications for product specification
-
EU and AAALAC requirements increasingly mandate environmental enrichment and specified thermal/humidity ranges; compliance is not optional for customers targeting high-quality research outputs. Equipment that can demonstrably maintain and log environmental parameters will edge out legacy static options.
-
Inspection regimes and GLP/OLAW/FDA performance standards elevate the importance of validated sanitation intervals and microenvironment monitoring. IVC platforms capable of validated two‑week change cycles under monitored conditions reduce operational disruption for facilities and are now a procurement preference.
-
Procurement officers increasingly evaluate lifecycle costs rather than simple capital outlay—durability through repeated autoclave cycles, filter replacement cadence, and service network density materially affect TCO and procurement scoring.
Competitive landscape — who to watch and why
The supplier base features a mix of specialized hardware manufacturers and a growing set of players bundling digital services. Market concentration metrics highlight a market where a few well-established vendors capture a majority share, while a healthy tail addresses specialized needs and price-sensitive segments. Key industry participants included in our analysis demonstrate distinct competitive positions:
-
Tecniplast (Italy) — strong in modular IVC and integrated digital ventilation solutions; active trade-show presence and continuous engagement with husbandry education strengthen brand credibility in institutional accounts.
-
Allentown Inc. (USA) — notable for ergonomic design and growing partnerships that integrate AI monitoring; recent product introductions focus on reusable, space-optimized IVC platforms addressing facility constraints.
-
Lab Products, LLC (USA) — broad portfolio across species and housing types; differentiated by patented multi-species solutions and a full-service equipment approach.
-
Thoren Caging Systems (USA) — emphasizes interchangeability and operational ergonomics, targeting high-throughput facilities with modular rack systems.
-
Alternative Design Manufacturing & Supply (USA) — plays the value segment with consultative services to optimize facility-level economics.
-
Zoonlab GmbH (Germany) — regional compliance specialist with deep alignment to European regulatory norms and environmental control systems.
-
Innovive, SSCI, Animal Care Systems, NUAIRE — collectively span high-density platforms, specialty ventilation, and accessory ecosystems; each offers capabilities that make them attractive M&A targets or partners for firms seeking to expand product breadth or service reach.
Recent commercial activity underscores directional trends: showcase and educational engagement to drive thought leadership (supplier trade shows), strategic industry partnerships integrating AI monitoring with physical housing, and product introductions focused on ergonomics and reusable platforms. These moves confirm a market shifting from pure hardware sales to solution bundles that reduce facility friction.
What’s inside the full PW Consulting report (practical deliverables)
The complete study delivers the operational intelligence your 2026 plans need, including—but not limited to—:
-
Proprietary market model (2020–2032) with scenario toggles for adoption curves, price trajectories, and policy shock sensitivity — exportable to corporate planning tools.
-
Validated supplier scorecards and a matrix of technology capabilities, service coverage, and installation lead-times to accelerate vendor selection.
-
CapEx vs. Opex scenarios and a TCO calculator tuned to autoclave cycles, filter consumables, replacement cadences, and service agreements for 5–10 year horizons.
-
Procurement playbooks and RFx templates aligned to AAALAC, GLP, and regional regulatory checks to shorten evaluation timelines and reduce bid-to-award cycles.
-
Commercial playbook for OEMs (pricing, channel, as-a-service models) and an M&A screening list with integration risk matrices for roll-up strategies.
-
Operational readiness and retrofit roadmaps for facilities transitioning from static to ventilated or digitalized platforms, including sample implementation timelines and labor impact estimates.
Note: In keeping with our “trailer” principle, this preview intentionally omits granular regional, type, and application split tables and the full supplier ranking data. These core slices are available in the authoritative report package and interactive model.
Strategic playbook — recommended actions for 2026
-
Prioritize interoperability: ensure new product designs expose APIs or standardized interfaces for third-party monitoring and RFID systems to accelerate adoption in institutional settings.
-
Shift commercial focus from one‑time sales toward service bundles: warranties, consumables subscriptions, and analytics subscriptions reduce churn and increase customer lifetime value.
-
Invest selectively in regional service hubs: lead-time-sensitive buyers favor vendors with local calibration, validation, and emergency repair capabilities.
-
Align R&D with compliance roadmaps: map upcoming accreditation and policy trends into product specifications two to three years ahead to avoid costly retrofits.
-
Use M&A to acquire capability gaps (digital monitoring, analytics, or regional sales/service footprint) rather than to chase volume alone; integration of software-first assets yields faster margin expansion.
How to use the full report
If your strategic planning, procurement roadmap, product roadmap, or M&A pipeline intersects animal housing equipment, the full PW Consulting study supplies the granular input you need — from downloadable financial and adoption models to supplier due-diligence templates and regulatory compliance checklists. The detailed regional and application splits, supplier rankings, and price-band matrices are purposely gated in the full deliverable to preserve model integrity and to enable live walkthroughs with our advisory team.
Closing
2026 presents a pragmatic window for decisive action: the market is neither nascent nor saturated, enabling well-positioned players to capture share through technology-enabled productization, service monetization, and regulatory-aligned innovation. PW Consulting’s laboratory animal housing cage market study converts market direction into operational levers and procurement instruments — the essential toolkit for leadership teams seeking to translate a steady market trajectory and a concentrated supplier base into measurable competitive advantage.
For detailed analysis of this topic, please visit the official page: Laboratory Animal Housing Cage Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Preclinical Tomography Market to reach USD 490.93 Million by 2032 (9.14% CAGR)
By PW Consulting, 2026-07-12
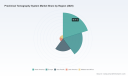
Preclinical Tomography System Market: Strategic Imperatives for 2026 — A PW Consulting Preview
The preclinical tomography systems market is moving from a niche, research-focused arena into a strategically important industrial segment that shapes drug-development timelines, translational science, and the business models of medical-imaging vendors. Our latest market study, calibrated to a 2025 base year, shows the global market expanding materially over the coming decade — growing from roughly USD 170.9 Million in 2020 to an estimated USD 266.4 Million in 2025 and projected to continue on a steady trajectory to just under USD 491.0 Million by 2032. That trajectory implies a compound annual growth rate of approximately 9.14% for the forecast window. For executives making capital-allocation, product, regulatory and M&A choices in 2026, understanding the structural forces behind this growth is now table stakes.
Preclinical Tomography System Market
Why this study matters for decisions in 2026
- Market momentum is driven by intersecting scientific and regulatory pressures — new therapeutic modalities (gene and cell therapies), tighter preclinical imaging standards, and institutional demand for reproducible imaging biomarkers.
- Competitive dynamics favor vendors that combine hardware performance with software and service-led differentiation: image quality is necessary but no longer sufficient.
- Regulatory and ethical frameworks are raising the bar for validation, GLP readiness, and documentation — purchasers increasingly treat regulatory maturity as a procurement criterion.
- Concentration in the vendor base means strategic moves (alliances, accretive M&A, platform bundling) can materially change a supplier’s competitive footprint.
What the PW Consulting report delivers (operational, decision-ready content)
- Forward-looking market sizing and topline scenario models (2026–2032) built from device-level and end-user demand drivers, with sensitivity analysis tied to regulatory and technology adoption scenarios.
- Technology deep dives that contrast CT, nuclear modalities (PET/SPECT), and hybrid solutions — covering imaging performance, throughput economics, maintenance profiles and lifecycle TCO (total cost of ownership).
- Commercial playbooks for vendors and buyers: procurement RFP templates, service-level agreement (SLA) benchmarks, and example ROI calculations for in-house units versus managed imaging centers.
- Regulatory-impact mapping that translates FDA, EMA and ICH guidance into practical product-development and submission checklists for both hardware and software components.
- Vendor benchmarking and competitive positioning including product portfolios, route-to-market models, service networks and software stacks — enabling short-listing and partner selection.
- Strategic M&A and partnership frameworks identifying value-creation levers (capacity consolidation, software integration, regulatory footprint expansion) and a checklist for pre-deal regulatory and clinical diligence.
- Risk matrices and mitigation playbooks spanning supply-chain vulnerabilities, IP and standardization risk, and ethical/regulatory compliance for animal-model imaging.
- Appendices with methodology, model assumptions, and verifiable primary-source citations to support board-level decision-making.
Data-driven insights you can act on in 2026
1) Demand drivers are structural, not cyclical. The expansion of complex biologics and cell/gene therapies amplifies demand for multimodal preclinical imaging: longitudinal safety profiling, imaging biomarkers for pharmacodynamics, and non-invasive endpoints for regenerative therapies all require higher precision and repeatability. That creates a steady, predictable replacement and upgrade cycle for research institutions and CROs.
Preclinical Tomography System Market
2) Regulatory convergence raises the cost of entry but elevates competitive advantage. New and updated guidance — including ICH-level recommendations for multimodal assessment, EMA protocols on imaging biomarkers, and FDA expectations around 510(k) demonstrations tied to IEC/ISO/NEMA standards — mean vendors that invest in early regulatory alignment will shorten customer qualification cycles and capture procurement momentum from heavily regulated buyers.
Preclinical Tomography System Market
3) Product differentiation is shifting from raw hardware specifications to integrated solutions. Innovations that matter in procurement conversations include detector technologies (e.g., CMOS-based micro-CT), hybrid modality platforms that reduce cross-center variability, and software-driven reconstruction/quantification that produce regulatory-grade biomarkers. Vendors who can deliver validated imaging workflows, software traceability and lifecycle service programs win higher long-term margins.
4) Service and business-model innovation are pivotal. Imaging-as-a-service (managed centers or pay-per-scan models), long-term service contracts with outcome-linked KPIs, and subscription-based analytics software are increasingly part of procurement conversations. Strategic partnerships with academic medical centers or CROs that bundle capacity with validated workflows accelerate market access and lower end-user onboarding friction.
5) The competitive map rewards selective consolidation. The market shows meaningful concentration at the top of the value chain, with a small number of established suppliers capturing a substantial share of commercial spend. That structure favors disciplined M&A — mid-sized, complementary acquisitions can quickly expand technological capabilities (e.g., adding validated PET/SPECT modalities or AI quantification layers) and geographic footprints.
Competitive snapshot — implications for suppliers and buyers
- Bruker Corporation has reinforced its position with advanced micro-CT lines oriented to in vivo and ex vivo imaging, emphasizing high-resolution solutions and compact benchtop performance. Recent product introductions increase competitive pressure in applications where resolution and imaging versatility are purchase front-runners.
- SCANCO Medical focuses on in vivo micro-CT platforms with large field-of-view solutions that appeal to translational programs requiring longitudinal bone and structural imaging; their positioning matters for buyers prioritizing field-coverage and high-resolution throughput.
- Mediso’s nanoScan multi-modality systems and recent regulatory milestones for nuclear modalities reflect a concerted push into validated multimodality offerings — an important strategic vector where regulatory clearance can be a market-access accelerant.
- Partnerships between imagingOEMs and academic centers or CROs (for example, recent collaborations announced by several equipment suppliers) are increasingly used to establish pre-vetted, co-branded imaging centers and to co-develop workflows that reduce adoption friction for end users.
Regulatory and ethical dynamics that should inform 2026 planning
- 510(k) and device-equivalent pathways now demand alignment with recognized standards for performance and safety, and acceptance in regulated markets often requires rigorous documentation of measurement traceability and software validation.
- EMA and ICH expectations for imaging biomarkers and multimodal assessment create opportunities for vendors who can provide validated, reproducible imaging endpoints as part of commercial propositions to pharmaceutical customers.
- Existing animal-welfare legislation and related documentation requirements increase the operational burden on buyers; this encourages adoption of non-invasive, longitudinal imaging and favors suppliers that can demonstrate GLP-ready workflows and ethical compliance tooling.
Clear, actionable recommendations for 2026 decision-makers
- For vendors: prioritize a “hardware + software + service” product strategy. Invest in validated reconstruction pipelines, regulatory evidence generation and modular service offerings that raise switching costs.
- For investors and acquirers: focus diligence on regulatory state, software IP and installed-service economics. Targets that add multimodality capabilities or software-led workflow validation drive higher strategic value than narrowly focused hardware plays.
- For research institutes and pharma: evaluate procurement not only on purchase price and spatial resolution but on lifecycle cost, regulatory readiness and the supplier’s ability to deliver validated biomarkers and reproducible workflows.
- For CROs and managed-service operators: scale selectively through partnerships with equipment OEMs and academic centers to create co-branded service nodes that reduce client onboarding time and support regulatory-grade data generation.
- For policy and procurement teams: require vendor governance evidence for software validation, traceability, and GLP-aligned SOPs as part of RFP scoring to reduce post-deployment compliance risk.
Where this preview stops — and what the full PW Consulting report delivers
This preview intentionally highlights strategic themes and validated directional metrics to help prioritize 2026 actions. To preserve the utility of our analytical models for paying clients, this document stops short of disclosing fine-grained segmentation and regional/application-level monetization that are included in the full study. The full report provides detailed regional and application forecasts, vendor market-shares across segments, pricing and ARPU benchmarks, full vendor scorecards, downloadable financial models, scenario-based procurement templates and a structured M&A playbook.
If your 2026 planning horizon includes procurement decisions, product roadmaps, M&A, or regulatory investments in preclinical imaging, the full PW Consulting study is designed to be an operational toolkit — not merely a market narrative. Visit our website to access the complete report and the associated interactive models that will allow your team to run bespoke scenarios and quantify the ROI of alternative strategic options.
PW Consulting — helping leaders turn preclinical imaging market momentum into measurable advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Preclinical Tomography System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Doorbell Market Poised for 17.9% CAGR Through 2032
By PW Consulting, 2026-07-12
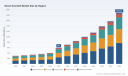
Smart Doorbell Market 2026: Strategic Preview for Executives
As Smart Doorbells evolve from novelty to foundational layers of the smart home and commercial perimeter, 2026 will be a defining year for strategic positioning. PW Consulting’s newest Smart Doorbell Market study — built on a 2025 base and projecting through 2032 — quantifies the scale, pace, and strategic levers that matter to manufacturers, channel partners, investors, and systems integrators. The market is growing rapidly (compound annual growth rate of 17.9% over the forecast window) and is expected to expand materially from a 2025 base. This preview synthesizes the report’s most consequential, decision-ready insights while intentionally reserving the granular segment tables and vendor scorecards for the full report.
Smart Doorbell Market
Market Snapshot (what the top‑line means for 2026)
-
Scale and velocity: The smart doorbell market exhibits high double‑digit growth on a multi‑year basis. From the 2025 base, the market is projected to more than triple by the end of the forecast period, reflecting both device replacement cycles and new household/commercial adoption.
Smart Doorbell Market -
Near‑term inflection: 2026 represents a transition from early adoption into mainstreaming for several form factors and monetization models — a window in which strategic bets on platform openness, upgradeability, and privacy will determine winner‑takes‑more outcomes.
Smart Doorbell Market -
Competitive posture: While recognizable consumer brands anchor demand, the market remains accessible to well‑executed challengers offering platform differentiation (local storage, no‑subscription propositions, or tighter ecosystem integrations). The competitive landscape shows moderate concentration with meaningful room for product and service innovation to shift share.
Why this study matters for 2026 corporate decisions
-
Capital allocation and portfolio prioritization — With the market expanding rapidly, the report maps where incremental R&D and capex will generate the highest ROI (software enabling features, edge AI, and hybrid storage models), and where price competition will compress margins.
-
Go‑to‑market timing — The analysis identifies the optimal cadence for product launches and channel pushes to capture early adopters vs. mainstream buyers, including tradeoffs between subsidized devices for subscription uptake and premium, subscription‑free propositions.
-
M&A and partnering signals — We highlight capability gaps (edge AI, secure identity management, low‑latency cloud infrastructure) that are attractive bolt‑on candidates for 2026—2027 consolidation, and the commercial thresholds where partnerships outperform acquisitions.
-
Regulatory and trust investments — The report quantifies the business impact of meeting stricter privacy and cybersecurity requirements (GDPR‑aligned storage choices, ISO/IEC 27001 practices) and helps prioritize compliance investments that materially reduce churn and litigation risk.
What the full report contains (practical outputs you can act on)
-
Proprietary market model with base‑year 2025 benchmarking and point forecasts through 2032, sensitivity scenarios for price erosion, component shortages, and accelerated AI adoption.
-
Operator playbooks: detailed go‑to‑market templates for device OEMs, telco bundlers, and retail distributors — including launch timing, pricing fences, and service bundling recommendations.
-
Vendor scorecards and SWOTs: comparative analysis of product portfolios, ecosystems, service monetization, and technical differentiators (edge AI, dual‑power designs, PoE vs wireless strategies).
-
Compliance and security roadmap: a prioritized list of certifications, architectural patterns (end‑to‑end encryption, local storage options), and contractual clauses to reduce regulatory and reputational risk.
-
Commercial impact matrices: projected ARPU and lifetime value tradeoffs across subscription models, local‑storage propositions, and professional monitoring agreements.
Competitive landscape: practical takeaways on leading players
-
Ring (Amazon ecosystem): Strength lies in brand recognition and deep Alexa integration. Its hybrid portfolio—battery and wired options with two‑way audio and package detection—keeps it competitive in mainstream channels. Strategic challenge: balancing surveillance capabilities with privacy expectations and regulatory scrutiny.
-
TP‑Link (Tapo series): Competes on value and technical features (2K+ video, dual power options) and emphasizes no‑subscription cloud alternatives. Its advantage is channel reach and aggressive pricing; risk is maintaining margin while scaling advanced AI features.
-
Ubiquiti (UniFi Protect): Positions as a prosumer/professional solution with strong integration into broader security ecosystems. Appeals to installers and integrators seeking unified management and higher configurability.
-
REOLINK: Differentiates with NVR/local storage options and subscription‑free AI capabilities—important for privacy‑sensitive segments and markets with restrictive data rules.
-
Lumi/Aqara: Stands out through smart‑home platform integrations (including HomeKit Secure Video) and local processing features like facial recognition where regulation permits.
-
Anker (eufy brand): Focus on local storage and premium hardware (dual‑camera setups) appeals to users who prioritize privacy and one‑time purchase economics over subscription services.
-
Blink (Amazon): Notable for long battery life and tight Alexa integration; recent 2026 product updates expand field of view and improve person detection—an incrementally important defensive innovation.
-
SimpliSafe: Integrates doorbells into professionally monitored systems and leverages its security bundle positioning; a strong channel into customers willing to pay for monitored services.
-
Arlo: Competes on camera quality, wide‑angle optics, and color night vision; its cloud service remains a core monetization channel.
Dynamics and regulatory guardrails that will shape winners
-
Spectrum and interoperability: Regulatory constraints on Wi‑Fi/Bluetooth spectrum (FCC) and growing emphasis on interoperable smart home standards will raise the bar for RF design and coexistence testing.
-
Privacy and data sovereignty: GDPR and similar data protection frameworks are driving demand for end‑to‑end encryption, transparent data handling, and local storage options. Companies that bake privacy into core value propositions achieve differentiated trust premiums.
-
Cybersecurity expectations: Increasing adoption of formal information security frameworks (e.g., ISO/IEC 27001) by vendors and channel partners is becoming a commercial requirement — particularly for B2B and enterprise deployments.
-
Operational cost dynamics: Skilled assembly and testing labor in leading manufacturing hubs elevates BOM and time‑to‑market considerations. Supply chain and localization choices materially influence pricing and margin outcomes.
Actionable 90‑day playbook for executives
-
Audit product roadmap against three vectors: privacy-by-default, subscription vs. one‑time revenue mix, and edge AI capabilities. Prioritize features that materially impact purchase decisions (false‑alarm reduction, package detection quality, chime behavior).
-
Run a channel segmentation test: deploy two refined SKUs — one subscription‑centric, subsidized model for mass retail; one premium, subscription‑free privacy model for direct and pro‑installer channels — and measure conversion and churn.
-
Lock down compliance: certify core product lines to recognized security standards and establish GDPR‑compliant data flows for EU markets. Include local storage and key‑management options in product spec to mitigate regulatory friction.
-
Evaluate strategic partnerships: prioritize cloud and identity partners that offer low‑latency regional endpoints and robust access controls. For hardware OEMs, prioritize NRE partnerships that reduce time to market for PoE and PoE++ doorbells.
-
Prepare for M&A defensibility: identify capability gaps that are best filled via acquisition (edge inference IP, identity matching tech, secure OTA infrastructures) and map target profiles.
Closing: how PW Consulting’s study helps you decide in 2026
Decisions in 2026 hinge on tradeoffs between rapid customer acquisition and sustainable monetization, platform openness and privacy assurances, and hardware differentiation versus software‑led upgrades. PW Consulting’s Smart Doorbell Market study supplies the numbers, the scenarios, and the tactical playbooks you need to quantify those tradeoffs and act with conviction. The report’s models and vendor level diagnostics are intentionally concentrated behind the paywall to preserve actionable value; this briefing is designed to surface the strategic implications while guiding you to the detailed segmentations, channel economics, and vendor scorecards that will inform capital allocation, product roadmaps, and M&A choices in 2026.
For detailed analysis of this topic, please visit the official page: Smart Doorbell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Sea Water Nasal Spray Market — Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market research sets a new benchmark for strategic decision support in the sea water nasal spray sector. Using 2025 as the analytical base year and projecting through 2032, the study models a clear growth trajectory: the market expanded from under USD 180 million in 2020 to roughly USD 220.5 million in 2025, and it is forecast to approach USD 344.4 million by 2032 at a compound annual growth rate (CAGR) of 6.7%. For executives planning investments, product launches, or M&A activity in 2026, these macro dynamics—combined with regulatory shifts, reimbursement nuances, and evolving clinical evidence—create a set of non-linear risks and opportunities. This article synthesizes the strategic implications of those dynamics without disclosing the report’s proprietary segment detail (available on the PW Consulting source page).
Sea Water Nasal Spray Market
Why this study matters now
-
Timing: 2026 is the inflection year for several structural forces: regulatory tightening in major markets, a renewed emphasis on post-market clinical follow-up (PMCF) under medical device rules, and material-sourcing pressure that affects formulation economics.
Sea Water Nasal Spray Market -
Demand composition: Increased focus on respiratory hygiene, pediatric nasal-care routines and expanding hospital pharmacy channels for prescribed indications are reshaping the route-to-market calculus for both branded and private-label players.
Sea Water Nasal Spray Market -
Investor attention: A mid-range market concentration profile means the sector is attractive for scale-driven buyers, but clinical and regulatory assets (evidence dossiers, PMCF completions, sterile manufacturing capabilities) materially affect valuations.
What the PW Consulting report delivers (practical contents)
-
Comprehensive market sizing (historical 2020–2025) and probabilistic forecasts (2026–2032) with scenario and sensitivity models to stress-test price, cost, and channel assumptions.
-
Demand-driver deep dives that connect epidemiology, consumer behaviour, and clinical pathways to addressable demand by channel (OTC retail, hospital pharmacy, private label, e-commerce).
-
Regulatory and quality playbook: EU MDR IIa implications, PMCF templates, FDA sterility and preservation expectations, and a manufacturability checklist for unit-dose versus multi-dose formats.
-
Competitive benchmarking and strategic profiles (brand, clinical evidence, channel reach, manufacturing footprint) for the major players and relevant challengers.
-
Commercial playbooks for premiumization, private-label growth, pricing elasticity, and reimbursement capture—complete with Excel models and go-to-market roadmaps.
-
M&A and partnership decision tools: target scoring, synergy modelling, and integration risk checklists tuned to the sea water nasal spray value chain.
High-level market signals for 2026 strategy
-
Growth is steady and investible: a mid-single-digit CAGR (6.7%) supports both organic expansion and bolt-on M&A strategies focused on scale, channel control, and clinical differentiation.
-
Moderate consolidation: concentration metrics indicate room for market leaders to expand share, while well-capitalized challengers and private-label suppliers can still capture profitable niches.
-
Regulatory uplift drives evidence premium: classification and post-market obligations in major markets increase the cost of entry and favour incumbents or new entrants with robust clinical programmes.
-
Reimbursement pathways are asymmetric: selected clinical indications enjoy hospital pharmacy reimbursement in parts of Europe, creating a two-tier market where evidence-backed products access lower price elasticity channels.
-
Supply-side constraints matter: source water acquisition and validated sterile manufacturing affect COGS and product format choices; suppliers who secure reliable, traceable marine sources and validated sterility processes will hold cost advantages.
Competitive landscape — strategic read of core players
-
Sofibel SAS (Sterimar): Strong brand equity in pediatric hygiene and an active clinical programme give them an advantage in claim differentiation. Strategic focus for challengers: pursue targeted PMCF studies in niche indications and accelerate micro-spray format expansion to capture infant-care loyalty.
-
Laboratoires Gilbert SAS (Marimer): Heritage formulation expertise and established distribution networks support both retail and institutional channels. Strategic options include leveraging reimbursement dossiers to win hospital formulary listings and deepen private-label manufacturing arrangements.
-
Urgo Group (Humer): Multi-channel marketing and OTC presence create a consumer-funnel advantage. For 2026, a defensive strategy for Urgo is to pair brand campaigns with point-of-sale and digital therapeutic education directed at caregivers and chronic rhinologic patients.
-
Quinton Marine Water Biotechnology Laboratory: A biotechnology-led narrative and premium positioning allow Quinton to command innovation-minded segments. Partnerships with clinical research organisations (CROs) to generate evidence for novel indications will underpin premium pricing justification.
-
Gerolymatos International S.A.: Rapid portfolio expansion via strategic transactions and a recent pipeline of clinical publications position Gerolymatos as a consolidator with hospital-channel ambitions. Their private-label scale should be considered by manufacturers seeking volume contracts rather than brand-led growth.
Recent sector developments illustrate these dynamics: clinical study completions and publications (e.g., multicentre infant trials and hospital real-world surveys), product-line innovation (microspray baby hygiene formats), and portfolio expansion through affiliate acquisitions. These moves highlight the twin priorities of evidence generation and channel diversification.
Operational imperatives — manufacturing, quality and product formats
-
Sterility and preservation protocols are non-negotiable. FDA guidance and EU regulation require validated sterility assurance and preservation-effectiveness testing; this raises CAPEX and operational complexity for aqueous unit-dose and multi-dose formats.
-
Unit-dose vs multi-dose: the choice is an economic as well as regulatory one. Unit-dose eases sterility maintenance but increases packaging cost and logistics complexity; multi-dose requires validated preservative systems and expiry strategies.
-
Supply-chain resilience: traceable marine sourcing (high-quality coastal sources) reduces reputational and quality risk but comes with cost volatility—buyers must stress-test supplier contracts under multiple price and availability scenarios.
-
Clinical programmes as a differentiator: expect hospital procurement and reimbursement pathways to prioritise products with demonstrable PMCF data. Building a clinical timeline is therefore a product-development imperative, not a marketing optionality.
Investor and M&A lens for 2026
-
Value inflection points: validated PMCF, reimbursement coverage in hospital channels, and vertically integrated manufacturing are the primary drivers of premium valuation multiples.
-
Due diligence priorities: clinical evidentiary robustness, regulatory compliance history (including device classification and PMCF status), supply-chain traceability, and private-label contracts are more informative than headline revenue growth alone.
-
Acquisition playbooks: buyers should target targets that unlock immediate channel synergies or remove manufacturing constraints—e.g., adding sterile-fill capacity or acquiring hospital distribution footprints.
90‑day action plan for executives
-
Week 0–4: Rapid portfolio audit and regulatory gap assessment—identify SKUs lacking PMCF or sterility-validation documentation.
-
Week 4–8: Commercial pilots—deploy targeted channel pilots in reimbursed hospital settings and e-commerce subscription models to validate pricing and adherence dynamics.
-
Week 8–12: Secure supply continuity—negotiate longer-term marine source contracts, lock sterile-fill capacity or align with contract manufacturers; initiate focused PMCF or RWE studies for priority SKUs.
-
Deliverable: a crisp investment memo that quantifies near-term margin levers and a 12–24 month roadmap for evidence-generation and channel scale-up.
How to use this research in boardroom decisions
-
Translate the report’s scenario outputs into capital allocation choices: prioritise investments that lower regulatory and supply risks while accelerating entry into reimbursed channels.
-
Use the competitive profiles and CR metrics to inform M&A bid ranges—target assets that complete your channel coverage or provide sterile-manufacturing scale.
-
Adopt the report’s PMCF templates and regulatory checklists early to reduce time-to-market friction and prevent rework-driven capex.
Note on disclosure: this commentary intentionally omits proprietary, granular segmentation tables and detailed regional/application share metrics that are part of the full PW Consulting study; those tables and the underlying spreadsheets are available via the report source page for clients and registered users. The material above captures the strategic essence and actionable pathways we recommend for corporates, investors and manufacturers preparing 2026 initiatives in the sea water nasal spray market.
For tailored strategic briefings, scenario modelling, or to review the full segmentation and company dossiers, PW Consulting’s industry team is available to run a focused executive workshop and provide the underlying financial models that underpin these conclusions.
For detailed analysis of this topic, please visit the official page: Sea Water Nasal Spray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: E‑Liquids Market Set to Accelerate at 12.58% CAGR Through 2032
By PW Consulting, 2026-07-12
E‑Liquids Market 2026 Preview: Strategic Imperatives for Corporate Decision‑Makers
Executive snapshot
As PW Consulting’s lead industry analyst, I present a concise, strategy‑focused preview of our full E‑Liquids Market research (base year 2025). This preview is deliberately diagnostic: it synthesizes the macro trajectory you need to inform 2026 decision‑making while withholding core, segment‑level datasets reserved for the full report. The objective is to equip boards, corporate development teams, and commercial leaders with the directional intelligence required to prioritize actions this year — and to motivate retrieval of the complete study for execution‑level detail.
E-Liquids Market
Where the market stands and where it’s heading
The global e‑liquids industry has moved from niche to scale within a five‑year window. Our historical model captures steady expansion from 2020 through 2025, and the market is now materially larger in commercial terms than it was at the start of the decade. PW Consulting’s forecast extends through 2032, reflecting a compound annual growth rate of 12.58% across the 2026–2032 horizon. In practical terms, the sector is expected to more than double from its 2025 base over the forecast period, driven by a combination of product innovation, expanded distribution, and shifting regulatory clarity in major markets.
E-Liquids Market
This growth is not homogeneous: pockets of rapid commercialization sit alongside geographies and channels that are still in regulatory or infrastructure catch‑up. The consequence for 2026 is stark — companies that align capital allocation, regulatory engagement, and go‑to‑market models now will secure disproportionate share and margin expansion through the latter half of the decade.
E-Liquids Market
Why the 2026 decision window matters
- Regulatory inflection: Several major regulatory events have crystallized legal pathways for market entry and product authorization. As of May 2026 the U.S. Food and Drug Administration has authorized a limited set of ENDS products (45 in total), underscoring that authorized status is an enforceable commercial moat. Concurrent measures — such as the UK’s Vaping Products Duty introduced in 2026 — are re‑pricing consumption economics in key markets and will influence channel dynamics and pricing strategies.
- Capacity and channel reconfiguration: Recent capital investments by standalone retailers and manufacturers signal that supply‑side constraints are loosening in some markets. This creates opportunities for branded players to renegotiate shelf economics, secure bespoke SKUs, and improve service levels to high‑value retail partners.
- Consolidation pressure: Market concentration is meaningful. The top three firms account for a substantial share of global revenue, and the top five take an even larger slice. This concentration accelerates winner‑take‑most dynamics in certain product formats and route‑to‑consumer models — a reality that should inform M&A and partnership prioritization.
What the full PW Consulting report delivers (practical, execution‑oriented)
Our complete study is built to be applied directly to strategic planning cycles. Highlights include:
- Proprietary demand models that map price elasticity by product architecture and channel (retail, online, and specialty outlets), enabling precise sensitivity testing for repricing and tax pass‑through strategies.
- Scenario simulations of regulatory outcomes (authorization timelines, category‑level duties, and state/ provincial certification regimes) and their P&L impact across portfolio variants.
- Channel profit‑pool analysis that identifies high‑margin distribution nodes, retailer economics, and the point at which vertical integration becomes accretive versus outsourcing.
- Supply‑chain stress tests and capex blueprints: capacity build vs. contract manufacturing tradeoffs, lead‑time sensitivities, and inventory strategies tailored for a high‑growth, high‑regulation sector.
- M&A and partnership scorecards that rank targets by strategic fit (technology/IP, regulatory readiness, channel access, and cultural integration risk).
- Actionable playbooks for commercial execution: SKU rationalization, premiumization pathways, private‑label opportunities, and consumer retention tactics under tightening regulation.
Competitive landscape — strategic positions and implications
The E‑Liquids market comprises global tobacco‑multinational portfolios, established independent brands, and a broad OEM/ODM base supplying label‑agnostic product. That tripartite structure shapes both competition and opportunity.
- Large tobacco multinationals: These firms leverage scale, regulatory experience, and deep retail relationships to defend premium channel positions and accelerate product authorization where feasible. Their strategic playbook in 2026 will emphasize portfolio rationalization toward smoke‑free revenue streams and selective licensing or M&A to plug capability gaps.
- Independent brands and specialty manufacturers: Independents retain credibility in innovation, flavor development, and direct consumer engagement. They are the principal drivers of rapid product experimentation and frequently act as upstream talent pools for acquisition by larger players seeking differentiated SKUs.
- OEM/ODM manufacturers and wholesalers: A globally distributed supplier base services both incumbent majors and entrepreneurial brands. Their capacity expansions and quality compliance capabilities are a critical bottleneck — and a commercial lever for firms that secure preferential production agreements.
Representative players include well‑known global and regional names across each cluster — from established manufacturers of pod‑based systems and e‑liquid formulations, to wholesalers and premium flavor houses — each occupying materially different strategic postures. PW Consulting’s competitive maps and capability matrices in the full report give boards an instant line of sight on which relationships to pursue, which competitors to monitor, and where to deploy commercial defenses.
Regulatory dynamics and operational risks
Regulation remains the single largest non‑market risk. Recent developments — including FDA product authorizations, state‑level certification regimes, tax introductions in the UK, and penalties for compliance failures at the subnational level — illustrate the rapidly evolving compliance landscape.
- Authorization regimes create first‑mover advantage: Approved pathways confer de‑facto market access; firms with early authorization can secure shelf space and retailer endorsement that are hard to dislodge.
- Taxation and duties will reset price elasticities: New excise regimes change consumer calculus and channel competitiveness, particularly where duty differentials exist across adjacent jurisdictions.
- Local certification and reporting: Emerging state and provincial registration requirements increase administrative overhead and the cost of non‑compliance can be punitive. These rules favor firms with established regulatory affairs capability or those that can absorb compliance cost through scale.
Strategic priorities for 2026
We recommend a prioritized three‑track program for firms that intend to lead or defend their position in 2026:
- Regulatory investment: Build or acquire regulatory capability immediately. Companies should pursue prioritized authorization pathways for strategic SKUs and create a regulatory‑linked product roadmap that aligns R&D spend with expected authorization timelines.
- Supply resilience and manufacturing optionality: Secure manufacturing capacity through a mix of owned capacity and strategic OEM partnerships. Negotiate contingency clauses and volume options to mitigate lead‑time shocks as demand scales.
- Commercial model pivot: Reassess channel mix and SKU portfolio under new duty regimes. Identify high‑margin retail nodes and adapt packaging/volume strategies to minimize tax drag and preserve price positioning.
M&A, partnerships and capital allocation
Given the concentration dynamics in the market, M&A remains a high‑leverage route to scale. PW Consulting’s acquisition playbooks prioritize targets that deliver one or more of the following: regulatory readiness (authorized or near‑authorized products), proprietary formulation or flavor IP, privileged retail distribution, or cost‑efficient manufacturing that can be scaled quickly.
Partnerships with specialist OEMs or regional retailers can be an alternative to outright purchase, delivering speed to market with lower upfront capital. In either case, deal diligence must stress regulatory history, laboratory standards, and compliance traceability as valuation‑critical factors.
Methodology and data integrity
The full report synthesizes historical shipment and revenue data (2020–2025 base), primary interviews across manufacturers, retailers and regulators, and PW Consulting’s proprietary demand model. Forecasts through 2032 integrate scenario analysis for authorization rates, excise policy adoption, and consumer substitution effects. Market concentration metrics are based on our reconciled revenue model and reflect the current competitive structure.
Next steps — where to get the full intelligence
This preview is intentionally high‑level; the full PW Consulting E‑Liquids Market report contains the granular segment and regional breakdowns, channel‑level profit pools, SKU‑level elasticity inputs, and a prioritized 18‑month action plan tailored to executives. If your 2026 strategy, capital allocation, or M&A pipeline touches the E‑Liquids category, securing the full dossier is a strategic imperative.
Contact PW Consulting to obtain the comprehensive report and the companion executive workshop — we will walk your leadership through scenario simulations specific to your portfolio and develop a bespoke playbook that translates industry momentum into defensible, near‑term outcomes.
For detailed analysis of this topic, please visit the official page: E-Liquids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intranasal Drug Delivery Devices Market to reach USD 3,435.95M by 2032 (8.98% CAGR)
By PW Consulting, 2026-07-12
Intranasal Drug Delivery Devices: Strategic Imperatives for 2026
As PW Consulting’s lead industry analyst, I present a concise, decision‑focused introduction to our latest market research on Intranasal Drug Delivery Devices. This is not a data dump — it is a strategic lens. The intranasal device landscape is transitioning from niche adjuncts to mainstream clinical platforms, driven by advances in formulation science, a growing roster of acute-care indications, and faster clinical paths for device‑linked therapies. Our study — anchored on a 2025 base year and a 2026–2032 forecast horizon — quantifies these shifts and turns them into actionable guidance for executive teams planning moves in 2026.
Intranasal Drug Delivery Devices Market
Why this study matters for 2026 decision cycles
-
Timing: With the market exhibiting robust momentum entering 2026, companies face high‑impact choices on R&D allocation, partnership structures, and manufacturing scale. Our study models these dynamics through to 2032, enabling leaders to test scenarios against a credible growth trajectory.
Intranasal Drug Delivery Devices Market -
Clarity on growth: The intranasal device market has expanded materially since 2020, with our compiled topline showing steady escalation to a 2025 base and continued expansion through 2032. The forecast period carries an expected compound annual growth rate (CAGR) of 8.98% — a pace that supports both build and buy strategies for new entrants and incumbents alike.
Intranasal Drug Delivery Devices Market -
Competitive posture: The market is moderately concentrated — the three largest players capture a substantial share of sales, with the top five occupying an even larger portion of market value. That concentration shapes supplier negotiation power, R&D economics, and the competitive premium for validated platform technologies.
Macro snapshot (for orientation)
-
Historical trajectory and forecast framing: Our model chains historical revenues from 2020 through 2025 into a detailed 2026–2032 forecast. The topline growth supports a view of intranasal devices moving from tactical rescue or symptomatic treatment roles into broader therapeutic and preventive applications, including nose‑to‑brain targeting and dry‑powder biologics.
-
Market concentration: The current structure shows a clear leader cohort and a non‑trivial tail of specialty suppliers. CR3 and CR5 metrics indicate an oligopolistic core with room for focused challengers to capture niche adjacencies through innovation or commercial partnerships.
What the report contains — practical modules for strategic teams
-
Executive playbooks: Decision trees and capital allocation frameworks that quantify the trade‑offs between in‑house platform development, licensing, and M&A across different strategic objectives (e.g., rapid market entry vs. long‑term platform control).
-
Technology and platform benchmarking: Comparative assessments of multi‑dose vs. unit‑dose, liquid vs. dry‑powder platforms, and atomization technologies — including performance metrics, manufacturability, and clinical adoption risk profiles.
-
Regulatory and reimbursement playbook: Practical pathways for 510(k) strategies, essential predicate mapping, and payer engagement templates tailored to intranasal device indications (acute rescue, chronic symptomatic therapy, vaccination delivery, and nose‑to‑brain biologics).
-
Supply chain and manufacturing stress‑tests: Scenario tools that model capacity, lead‑time, and cost impacts for scale‑up decisions — critical for companies planning to service emergency‑use or high‑volume indications.
-
Commercial go‑to‑market roadmaps: Segmented channel strategies, hospital vs. retail deployment models, and OEM partnership guides that accelerate adoption while preserving device and formulation IP.
-
Financial valuation templates: Sizing and valuation models that translate technological differentiation and regulatory milestones into enterprise value under multiple strategic paths.
Competitive landscape — who matters and why
Established device manufacturers and integrated CDMOs form the competitive core. Key players include platform suppliers with scale, CDMOs offering API‑to‑device integration, and specialist firms focused on precision metering or powder delivery. The strategic differences among them are instructive:
-
Aptar Pharma: A clear platform leader with breadth across single‑dose and multi‑dose systems and a track record of being selected for clinical programs. Aptar’s scale and clinical validation capability make it a default partner for sponsors seeking rapid translational pathways.
-
Teleflex: Known for mucosal atomization devices geared to emergency and clinical settings; Teleflex remains a go‑to for acute‑care delivery where rapid onset and ease of use under stress are prerequisites.
-
Bespak and Silgan Dispensing: European and US engineering specialists respectively, who combine customization with compliant manufacturing footprints — strategic partners for branded drug sponsors needing bespoke device formats or private‑label supply.
-
Hovione and Nemera: Represent the convergence of formulation science and device engineering. Their CDMO and platform capabilities reduce hand‑offs between API formulation and device design, an increasingly valuable proposition for biologic nasal therapeutics and dry‑powder platforms.
-
Kindeva and Aero Pump: Offer specialized spray and metering technologies that matter when precision dosing, particle size control, and nose‑to‑brain targeting are competitive differentiators.
Recent industry movements (2026) underscore the strategic inflection: platform commercializations, partnerships linking device platforms to therapeutic developers, and visible clinical utilization of established device systems in Phase II programs. These actions demonstrate both market validation and an accelerating commercialization timetable for intranasal therapeutics.
Regulatory and reimbursement context
-
Regulation: The FDA continues to provide well‑trod pathways for intranasal devices, with many device types cleared under 510(k) routes. Certain device classes benefit from streamlined classifications, but sponsors must still navigate labeling updates and device‑specific predicates when linking a delivery system to a new active pharmaceutical ingredient.
-
Reimbursement: Payer coverage for intranasal products is maturing — particularly for on‑label, acute‑care devices used in clinical settings. Reimbursement visibility is highest for rescue and emergency indications, which impacts pricing models and commercial channel decisions.
Strategic implications and recommended moves for 2026
-
Prioritize platform validation before scale: For sponsors with novel nasal formulations, invest early in compatibility and breath‑test studies with candidate delivery systems. Selecting a validated device early reduces downstream regulatory friction and time‑to‑market.
-
Evaluate partnership over acquisition for near‑term access: Given the compact cohort of scale suppliers and the premium of in‑market validation, strategic alliances, co‑development agreements, and supply‑backed licensing often yield faster commercial entry with lower upfront capital.
-
Hedge across device types: Maintain optionality across liquid and dry‑powder formats where scientific rationale supports it. Our modeling shows material upside for nose‑to‑brain biologics delivered via dry powder, but execution risk and manufacturing complexity differ materially from multi‑dose aqueous sprays.
-
Prepare regulatory and reimbursement dossiers in parallel: Build the evidence package for clinical efficacy, ease‑of‑use, and health economics early. Payer and hospital formulary acceptance will be easier to secure if device usability and cost‑offsets (e.g., reduced emergency visits) are demonstrable.
-
Design supply‑chain resilience: For high‑volume or emergency‑use indications, secure dual sourcing and capacity guarantees. The concentration of core suppliers creates single‑point risks that can be mitigated through early capacity agreements or modular in‑house capabilities.
-
Differentiate on outcomes, not just engineering: Invest in clinical programs and real‑world studies that quantify time‑to‑effect, patient adherence, and downstream economic benefits. Devices that demonstrate superior outcomes command premium contracting opportunities.
What to expect from the full PW Consulting report
The full study translates the topline growth trajectory and competitive portrait into executable initiatives. It includes proprietary scenarios, supplier scorecards, regulatory playbooks, and ready‑to‑use commercial models. Importantly, while this introduction outlines the strategic contours, the report preserves the granular segmentation and financial details behind our forecasts — the intelligence required to finalize 2026 budgets, M&A targets, and product roadmaps.
Closing — a pragmatic invitation
Intranasal drug delivery is no longer an experimental sideline; it is a strategic platform with definable commercialization pathways and measurable investment levers. Whether you are a pharmaceutical sponsor deciding between in‑licensing and platform development, a device OEM sizing capacity investments, or a private equity investor evaluating carve‑outs, our report equips you to convert market momentum into disciplined action. For the full dataset, segmented market matrices, and bespoke scenario runs calibrated to your enterprise assumptions, access the complete PW Consulting Intranasal Drug Delivery Devices Market report.
For detailed analysis of this topic, please visit the official page: Intranasal Drug Delivery Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Paraffin Wax Market: A Strategic Briefing for 2026 Decision Makers
Executive summary
As the paraffin wax market transitions from legacy volume growth into a phase where specialty applications, regulatory traceability, and low-carbon product variants shape strategic positioning, 2026 will be a pivotal year for corporate decision makers. Our PW Consulting market model — built on a 2025 base year and projecting through 2032 — estimates the global market at USD 9.65 Billion in 2025, rising to an estimated USD 10.03 Billion in 2026 and to USD 14.13 Billion by 2032, representing a compound annual growth rate of 5.6% across the forecast window. These headline metrics mask an industry that is simultaneously fragmented, technically exacting, and subject to capital-led capacity shifts; this briefing explains why those dynamics matter for investment, procurement, product strategy, and M&A choices in 2026.
Paraffin Wax Market
Market trajectory and what it means for decisions in 2026
The mid-single-digit CAGR projected through 2032 reflects a market supported by steady demand from traditional applications (e.g., candle and packaging) and a rising, higher-value demand set from medical and technical uses such as histology, medical consumables, and specialty packaging for regulated products. The incremental growth is driven less by broad-based volume expansion and more by qualitative shifts: higher-specification medical grades, traceability and compliance requirements, and premium low-carbon product launches. For strategy teams, three implications are immediate:
Paraffin Wax Market
- Prioritize product differentiation over raw-volume plays. Growth pockets will favor suppliers that can demonstrate purity, controlled melting point behavior, and reproducible performance in pathology and device contexts.
- Reassess capacity investments with a supply-chain lens. Upstream refinery modernizations announced by major petrochemical players will change regional supply balances; buyers and midstream producers must stress-test contracts for flexibility and delivery assurance.
- Factor regulatory and operational compliance into total cost. Medical-grade usage requires investments in sanitization, consumables (disposable liners), and routine replacement protocols that materially affect unit economics.
Competitive landscape — players to watch (strategic takeaways)
The paraffin wax market for medical and technical applications sits at the intersection of commodity refining and precision consumables. Our analysis highlights two clusters of suppliers: manufacturers who focus on medical devices and therapy equipment and those who supply histology and laboratory-grade consumables.
Paraffin Wax Market
- WR Medical Electronics Co. / Therabath (St. Paul, MN) — a differentiated supplier with an end-to-end professional paraffin bath offering (Class II FDA devices) and ISO-compliant refill options. Their product-centric model (devices plus consumables) creates recurring-revenue channels and a compliance-focused value proposition—an attractive template for firms seeking to move up the value chain through equipment+consumables bundling.
- Epredia — a supplier of histology-grade paraffins targeted at pathology labs and medical device manufacturing. Vendors serving histology require close alignment with lab workflows and regulatory traceability; partnerships with diagnostics and pathology equipment OEMs are high-value strategic options.
- Polysciences, Inc. — supplies histology-grade pellets and leverages technical grade consistency as its market edge. Their model underscores the premium commanded by formulation and granularity control—capabilities that are increasingly important in regulated environments.
- CellPath Ltd., Poth Hille & Co. Ltd., Citotest Scientific, Biosharp — regional specialists and histology consumable suppliers that exemplify how geographic proximity, local regulatory compliance expertise, and laboratory distribution networks create defensible niches. For multinational buyers, the presence of capable regional suppliers reduces sourcing risk but also complicates price negotiation and standardization.
Strategic implications for incumbents and new entrants:
- Product platform plays (device + consumable) reduce churn and increase lifetime value—consider piloting bundled offerings in regulated end-markets.
- Technical differentiation (purity, melting point stability, permeability) is a defensible moat; invest in product validation and third-party certifications like ISO 13485 to accelerate adoption among clinical and laboratory customers.
- Regional players present acquisition opportunities for fast channel access; market concentration remains relatively low (CR3 ~24.6%, CR5 ~30.0), signaling consolidation potential but also integration complexity.
Supply-side developments and risk vectors
Macro supply-side moves are reshaping competitive dynamics. Recent refinery modernizations and specialty wax capacity expansions by major chemical companies are shifting the supply landscape and introducing new competitive pressures in both commodity and specialty segments. At the same time, product innovation around micronized and low-carbon waxes creates new premium niches, particularly for sustainable medical packaging and device applications.
Key considerations for risk management:
- Capacity additions by large refiners can compress margins for undifferentiated paraffins; companies focused on commodity grades should evaluate hedging, longer-term offtake agreements, or vertical integration to protect margins.
- Specialty and low-carbon product launches open pricing power, but they require investment in formulation, validation, and supply chain traceability—budget these as up-front commercialization costs rather than incremental margin gains.
- Demonstrable delivery examples—such as recent bulk deliveries of medical-grade paraffin to hospital pathology departments—underscore that logistics, certification, and third-party testing are often the gating factors for new contracts, not price alone.
Regulatory, operational and purchasing considerations
Medical-grade paraffin is governed by a combination of international standards, clinical practice interpretations, and operational hygiene protocols. Two operational realities deserve explicit attention in 2026 strategy workstreams:
- Regulatory and quality frameworks: Suppliers targeting medical device consumables and histology must comply with traceability and quality-system expectations (explicitly including ISO 13485 in many procurement specifications). Certification status is increasingly a prerequisite for supplier shortlisting, and audit-readiness should be assumed as a baseline.
- Operational hygiene and hidden cost items: Facilities using paraffin baths and histology waxes must invest in sanitization protocols, disposable liners, and routine wax replacement cycles to maintain compliance and reduce cross-contamination risk. These recurring operational costs materially affect the total cost of ownership for buyers and should be quantified in procurement decisions.
A final regulatory nuance: paraffin wax baths used in occupational therapy have interpretations under safety and recordkeeping frameworks that reduce administrative burden in some jurisdictions. That distinction matters when quantifying operational risk and liability for therapy-device adopters versus clinical histology labs, which face far higher traceability and documentation requirements.
What our full report delivers (practical, execution-focused content)
PW Consulting’s Paraffin Wax Market report goes beyond headline growth assumptions to provide the tactical inputs procurement, product, and M&A teams need for 2026 execution. Highlights include:
- A validated market-size and forecast model (2020–2032) with scenario planning for supply shocks, low-carbon adoption rates, and regulatory tightening.
- Detailed competitive profiles and capability maps for manufacturers and suppliers focused on medical, histology, and specialty packaging channels—identifying potential partners, acquisition targets, and white-space opportunities.
- Operational playbooks for buyers and OEMs: compliance checklists (including ISO 13485 alignment), sanitization and replacement protocol cost templates, and vendor qualification scorecards.
- Commercial strategies for premiumization: go-to-market frameworks for launching low-carbon and specialty wax variants, pricing levers, and sample validation pathways for clinical labs.
- Risk and contingency matrices covering feedstock volatility, refinery capacity shifts, and logistical failure modes—paired with mitigation options such as multi-sourcing, buffer inventory sizing, and contract structuring.
Note: this briefing intentionally omits the granular segment-level figures and regional/application splits. Those detailed breakouts and downloadable datasets are available in the full report and on our source page for teams that require transaction-ready intelligence.
Immediate actions for 2026 planning cycles
- Supply assurance: initiate or renew long-term supply audits with high-specification suppliers and evaluate clause-level protections for capacity reallocation scenarios.
- Product & regulatory: accelerate ISO 13485 certification or supplier audits where medical-grade or histology use is a target segment; treat certification as a commercial enabler, not a compliance checkbox.
- Commercial: pilot device+consumable bundles to lock in recurring revenue and accelerate clinical integration, using a small set of reference customers for rapid validation.
- M&A & partnerships: screen regional histology specialists and equipment-focused suppliers as potential tuck-ins to capture higher-margin, recurring consumable flows.
Conclusion — why this matters for 2026
Heading into 2026, the paraffin wax market presents a blend of steady aggregate growth and meaningful strategic inflection points. Organizations that recognize the shift from commoditized supply toward quality-differentiated, traceable, and sustainability-oriented offerings will capture disproportional upside. Conversely, those that treat the market as a simple volume play risk margin pressure from large capacity entrants and missed opportunities in higher-value medical and technical segments. PW Consulting’s full dataset and playbooks equip leaders to make those trade-offs with precision; for teams preparing budgets, supply contracts, or M&A pipelines this year, the time to convert analysis into action is now.
How to access the full intelligence
The summaries and strategic frameworks above are calibrated to inform 2026 decision making while preserving the full, transaction-ready detail for the licensed report. For the complete segmentation data, supplier scorecards, and downloadable financial models, please visit our report landing page or contact your PW Consulting account lead to arrange a briefing and model license.
For detailed analysis of this topic, please visit the official page: Paraffin Wax Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luxury Sunglasses Market to Hit USD 19.78B by 2032 at 4.59% CAGR
By PW Consulting, 2026-07-12
Luxury Sunglasses Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a strategic preview of our comprehensive Luxury Sunglasses Market research—designed to arm executives with the perspective required to make high-consequence decisions in 2026. The luxury sunglasses category is evolving along multiple vectors: premiumization of everyday eyewear, technological convergence (notably AI-enabled optics), shifting channel economics, and an increasingly complex trade-and-tariff environment. This preview highlights the implications of those dynamics, integrates headline market metrics, and outlines the actionable playbook our full report delivers—without disclosing the proprietary segment-level detail you’ll find in the source document.
Luxury Sunglasses Market
Market at a Glance: The Macro Trajectory
After steady expansion through the early 2020s, the global luxury sunglasses market reached an estimated USD 14.45 billion in our 2025 base year. Our modeled outlook forecasts continued growth through 2032, taking the market toward roughly USD 19.8 billion by the end of the forecast horizon. That trajectory reflects a compounded annual growth rate (CAGR) of approximately 4.59% across the forecast period, underpinned by sustained consumer demand for heritage brands, rising premiumization in emerging channels, and product innovation that adds utility and desirability beyond seasonal fashion cycles.
Luxury Sunglasses Market
Concentration metrics underscore a moderately consolidated competitive landscape: the top three firms account for nearly half the market, while the top five control well over sixty percent. This structure produces both strategic advantages and points of fragility—scale delivers bargaining power with suppliers and channels, but concentration also raises barriers to disruptive entrants and intensifies the strategic importance of licensing, vertical integration, and selective M&A.
Luxury Sunglasses Market
Why This Matters for 2026 Strategic Choices
-
Portfolio Prioritization: With predictable, mid-single-digit market growth, 2026 will favor companies that optimize mix—balancing high-margin heritage lines with selective innovation that expands addressable price points without diluting brand equity.
-
Channel Reconfiguration: Retail and digital channels are recalibrating; omnichannel proof points and experiential retail will continue to command a premium. Decisions in 2026 about store footprints, concession strategies, and e-commerce investments should be informed by scenario-based channel economics in our full report.
-
Supply-Chain Resilience: Recent trade measures and tariff escalations have concretely altered landed costs and supplier selection. Our research shows that companies that proactively reconfigure sourcing in 2025–2026 can protect margin and service levels while competitors make reactive price moves.
-
Tech-Infused Differentiation: Adoption of AI-enabled eyewear is moving from novelty to commercial product lines for leading firms. For premium players, the strategic question in 2026 is how to integrate smart functionality without undermining craftsmanship—this will inform R&D allocation and partner selection.
Key Strategic Imperatives (Actionable Guidance)
-
Protect and Extend Brand Equity: Luxury success in 2026 is about curated scarcity and storytelling. Brands should implement differentiated distribution frameworks—exclusive drops, selective licensing, and bespoke retail experiences—to preserve price integrity while enabling controlled scale.
-
Make Sourcing a Strategic Asset: Tariff volatility and concentrated manufacturing footprints make near-shoring and multi-sourcing mandatory strategic options. Executives should adopt a supplier risk matrix that balances cost, lead time, quality, and geopolitical exposure.
-
Invest in Experience-Led Commerce: Brick-and-mortar still matters for luxury sunglasses—try-on experience, personalization, and aftercare create defensible margins. Integrate digitally enabled in-store services and invest in staff certification programs to lift conversion.
-
Monetize Technology Thoughtfully: Smart sunglasses and AI-enhanced optical features are areas of growth—but success hinges on partnerships with tech players, IP controls, and clear consumer value propositions. Avoid technology for its own sake; plan product roadmaps tied to distinct use cases and premium pricing tiers.
-
Use M&A and Licensing as Strategic Accelerants: Targeted acquisitions and licensing can accelerate entry into adjacencies (e.g., luxury sports eyewear, sustainable materials) and quickly build capabilities that would otherwise take years to develop organically.
Competitive Landscape: Who’s Shaping the Market
The luxury sunglasses ecosystem is populated by global conglomerates, specialist manufacturers, and design-led independents. A handful of players exert outsized influence through brand portfolios, licensing agreements, and scale production.
-
EssilorLuxottica (Paris, France): A dominant force that blends manufacturing scale with an extensive brand and license portfolio—owning headline brands and stewarding premium licensed partnerships. Recent corporate activity underscores its push into hybrid product categories and premium tech-enabled eyewear: notable developments in 2026 include an extended licensing agreement for a major luxury fashion house, a high-profile collaborative capsule under a heritage premium brand, and an expanded AI glasses lineup with optical prescription support. These moves illustrate a strategy that layers heritage positioning with functional innovation to protect market share and expand wallet share among affluent consumers.
-
Marcolin Group (Italy): A specialist in designer optics, Marcolin continues to pursue growth through partnerships with high-fashion labels and disciplined craftsmanship narratives. Their consolidation of designer licenses positions them to monetize premium brand associations while maintaining a manufacturing edge.
-
De Rigo (Italy): Focused on licensed luxury eyewear, De Rigo’s strength lies in flexible production capabilities and brand collaborations that serve premium price tiers. Their model emphasizes agility and bespoke production runs—attributes that gain prominence when scarcity and exclusivity drive consumer demand.
-
Safilo Group (Italy): Safilo’s portfolio and licensing relationships with top-tier fashion houses keep them central to the premium sunglasses value chain. Their approach balances brand stewardship with scale distribution partnerships.
-
Garrett Leight & Oliver Peoples (United States): These design-led brands exemplify the independent, artisan segment—handcrafted materials, heritage aesthetics, and selective distribution channels. They serve as important benchmarks for premium craftsmanship and are often acquisition targets or strategic partners for larger groups seeking brand cachet.
Recent Industry Catalysts and Regulatory Headwinds
Two regulatory and market developments have immediate strategic relevance for 2026 planning:
-
Trade and Tariff Disruption: In 2025, combined import duty rates on optical products from certain origins spiked materially. The resulting increase in landed costs has led major manufacturers and retailers to adjust pricing and sourcing strategies. Some leading firms implemented price adjustments in affected markets to protect margins, while others accelerated supplier diversification and near-shoring initiatives.
-
Political and Administrative Responses: Short-term pauses and policy reversals—such as temporary moratoria on newly implemented reciprocal tariffs—introduce uncertainty into planning horizons. Companies must build flexible procurement and pricing playbooks that accommodate abrupt duty swings without eroding brand value.
What the Full Report Contains (Practical, Executable Content)
Our full Luxury Sunglasses Market study is designed as a playbook for 2026 strategic execution. Highlights include:
-
Industry-grade market model calibrated from 2020–2025 and projecting through 2032 (base year 2025), including sensitivity analyses across demand, pricing, and tariff scenarios.
-
Proprietary concentration and competitive maps, plus M&A candidate shortlists and valuation heuristics tailored for premium eyewear.
-
Channel economics by route-to-market, including premium digital conversion metrics, concession economics, and experiential retail benchmarks that drive top-line and margin optimization.
-
Comprehensive supplier and sourcing matrix with cost-to-serve, lead-time elasticity, and a geopolitical risk index—actionable for procurement reorganization and contingency planning.
-
Product strategy frameworks for integrating smart features into luxury portfolios—decision criteria, partner models, IP safeguards, and go-to-market sequencing.
-
Sales and pricing playbooks with premiumization levers, dynamic pricing scenarios, and promotional cadence tuned to protect brand equity while growing unit volume.
Note: This preview intentionally omits granular segment-level figures and region/application splits to preserve the exclusive value of our proprietary datasets and forecasting detail. The full report supplies those calibrated splits and scenario outputs to inform precise financial planning and P&L modeling.
Near-Term Tactical Checklist for 2026 Leaders
-
Audit your sourcing map by Q2 2026 and implement at least two alternative supplier pathways for critical components.
-
Run a pricing pass informed by tariff scenarios—identify SKUs that can absorb cost without brand erosion and those that require repositioning or delisting.
-
Define a clear product roadmap for tech-enabled eyewear that includes partnership milestones, IP checkpoints, and a pilot market plan.
-
Initiate at least one strategic licensing or acquisition evaluation aimed at closing a capability gap (e.g., artisanal craftsmanship, technological integration, or premium distribution reach).
Conclusion: Decisions that Will Define 2026
The luxury sunglasses market in 2026 will reward leaders who combine rigorous cost and supply-chain discipline with imaginative brand stewardship and disciplined product innovation. The macro backdrop—moderate, steady growth and meaningful market concentration—creates opportunities for scale players to consolidate advantage and for nimble independents to command higher margins through exclusivity and craftsmanship. Regulatory uncertainty and trade dynamics raise the strategic premium on operational flexibility and scenario planning.
For executives preparing budgets, capital plans, or M&A strategies in 2026, our full report supplies the empirical foundation and executable recommendations to convert insight into advantage. To access the proprietary segment-level data, channel models, and scenario toolkits that underpin the guidance above, please consult the full PW Consulting Luxury Sunglasses Market report on our website.
For detailed analysis of this topic, please visit the official page: Luxury Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Body Composition Analyzers Market to Reach USD 847.35M by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-12
Body Composition Analyzers Market — Strategic Outlook for 2026 Decision-Makers
Executive preview
The body composition analyzers market stands at a strategic inflection as we move into 2026. After steady expansion through the early 2020s, the market has reached a level that calls for deliberate, evidence‑based corporate action: our model shows clear, sustained growth through the 2026–2032 forecast window at an aggregate compound annual growth rate of approximately 6.98%. This trajectory translates into meaningful scale for vendors, channel partners, and strategic investors over the next business cycle — and it creates both predictable opportunities and emergent risks that should shape 2026 planning cycles.
Body Composition Analyzers Market
This introduction outlines the strategic value of PW Consulting’s full market study for executives who must convert market potential into executable plans without wading into raw data dumps. Below we highlight the study’s practical intelligence, the dynamics that will matter most in 2026, and concrete strategic options that companies should prioritize now. (Note: detailed segment tables and granular regional/application splits are intentionally withheld here to preserve the report’s role as the primary source of actionable numbers.)
Body Composition Analyzers Market
Why this study matters for your 2026 decisions
- Investment prioritization: With moderate, sustained market growth confirmed, the high‑value question for 2026 is not whether to invest, but where to allocate limited R&D and commercial resources across device classes, software, and services.
- Regulatory and reimbursement timing: Device clearance and CPT coding remain gatekeepers for clinical adoption. Understanding the regulatory cadence and reimbursement levers is essential to hitting revenue inflections at the right time.
- Go‑to‑market differentiation: As clinical and consumer segments converge around data accuracy, interoperability, and user experience, the next wave of winners will blend hardware performance with software ecosystems and validated clinical outcomes.
- M&A and partnership signal‑reading: A market with measured growth often consolidates around validated technologies and distribution reach. Strategic acquisitions and partnerships can accelerate product portfolios or plug capability gaps far faster than organic development.
What the PW Consulting report delivers — practical, transaction‑grade intelligence
- Comprehensive market sizing and trend decomposition (base year 2025; historical series and a 2026–2032 forecast) with scenario modeling for conservative, base, and upside cases.
- Technology deep dives comparing bioimpedance, BIS, DXA, caliper‑based and emerging hybrid approaches — tradeoffs summarized in clinical applicability, cost to manufacture, and ease of regulatory clearance.
- Demand segmentation analysis across clinical, fitness/wellness, research/academic, and home‑use end markets — presented with tactical buyer personas and procurement pathways so commercial teams can tailor offers.
- Regulatory and reimbursement playbook mapping: key approvals, coding status, and jurisdictional nuance to align product development timelines with market access windows.
- Competitive benchmarking and vendor scorecards that synthesize product capability, clinical validation, distribution strength, and margin dynamics — enabling M&A screening and partner selection.
- Commercial playbooks: pricing sensitivity matrices, channel design recommendations, and sample go‑to‑market launches (clinic pilot → enterprise roll‑out → consumer extension).
- Investor and corporate valuation appendices: revenue waterfall models, unit cost assumptions, and three‑year integration scenarios for potential acquisitions.
Market dynamics and the near‑term inflection points executives must track
Several forces are converging to shape competitive outcomes through 2026 and beyond:
Body Composition Analyzers Market
- Clinical validation as a differentiation moat: Buyers in hospital and diagnostic settings prize accuracy and regulatory standing. Devices with well‑documented clinical reproducibility will secure higher ASPs and longer procurement cycles.
- Regulatory density and device proliferation: The U.S. FDA ecosystem shows broad device registration activity — a fact that underscores both industry dynamism and the need for clearances for clinical adoption. Vendors that anticipate device controls, premarket requirements, and post‑market surveillance obligations lower commercialization risk.
- Reimbursement remains a gating factor: Existing procedural coding that supports whole‑body bioelectrical impedance analysis continues to exist as a monetization pathway for providers. Strategic engagement with payors and early documentation of clinical utility will accelerate hospital uptake.
- Channel bifurcation between clinical and consumer markets: Hospitals and diagnostic centers demand validated systems and clinical workflows; fitness and home segments prize convenience, connectivity, and cost. A single product rarely satisfies both; modular product lines and scalable software layers bridge the opportunity.
- Data and interoperability: The value of body composition output is amplified when integrated into EHRs, telehealth platforms, and remote monitoring ecosystems. APIs, standards‑based data models, and partnerships with digital health vendors will be competitive differentiators.
- Supply chain and manufacturing economics: Components, testing protocols, and calibration services drive cost and lead time. Near‑term supply resilience planning is table stakes for 2026 rollouts.
Regulatory and reimbursement snapshots that change go‑to‑market timing
- The U.S. market registers a high number of devices in the FDA database, signaling both opportunity and validation pressure for new entrants. Compliance timelines should be integrated into product roadmaps rather than treated as post‑launch tasks.
- Coding for whole‑body bioelectrical impedance analysis remains available under an established CPT designation — an attractive monetization lever for clinical deployments that can be leveraged when outcomes are documented.
- Recent clearances and approvals underline the competitive dynamics: contemporary 510(k) clearances and CE marks have signaled clinical acceptance for specific DXA and medical BIA systems. These milestones materially alter procurement conversations and should inform competitive response plans.
Competitive landscape — reading strategy from capability
The market is populated by established medical device OEMs and specialized BIA/BIS providers. Each cluster of players follows a distinct playbook:
- Incumbent medical OEMs focus on whole‑body DXA systems and hospital workflows, leveraging long sales cycles and service networks to maintain premium positions.
- Specialist BIA/BIS vendors compete on portability, speed, and clinical reproducibility for outpatient clinics, sports medicine, and research institutes.
- Consumer electronics and wellness brands prioritize connectivity, price, and UX to penetrate home and fitness channels.
Representative vendor characteristics you will find profiled in the full report:
- Companies offering FDA‑cleared, multi‑frequency, segmental BIA analyzers that target clinical and fitness settings by emphasizing reproducibility and professional workflows.
- Manufacturers of whole‑body DXA systems that position lean/fat and bone density outputs as clinical reference standards for diagnostics and treatment planning.
- Providers of Bluetooth‑enabled wellness monitors aimed at consumer and clinic hybrid models, stressing interoperability and cloud‑based monitoring.
- Specialist portable analyzer vendors that pursue rapid, point‑of‑care use cases with compact hardware and streamlined measurement protocols.
Strategic imperatives for 2026 — prioritized actions
- Lock in clinical validation early: Fund prospective clinical studies that align with payor evidence standards; early published outcomes accelerate hospital procurement and reimbursement conversations.
- Design modular product families: Separate clinical core (validated measurement engine, compliance features) from consumer UX and connectivity add‑ons. This reduces time‑to‑market across channels while protecting clinical claims.
- Invest in software ecosystems: Interoperability, analytics, and longitudinal patient tracking unlock recurring revenue models and stickier customer relationships.
- Map regulatory pathways across priority geographies: Prioritize clearances and CE approvals that unlock the largest strategic customers first; use these wins to fund market expansion and local partnerships.
- Targeted M&A and partnerships: Consider tuck‑ins for algorithm IP, cloud analytics, or channel access rather than pursuing large transformational acquisitions that distract from core execution.
Why PW Consulting’s full report is a decision lever
Our 2026 edition is designed as an executable tool for boards, corporate development teams, and commercial leaders. It combines a rigorous historical time series (2020–2025), a base‑case forecast and alternative scenarios for 2026–2032, validated competitive intelligence, and buyer‑level insights that support operational plans and investor diligence. The report includes reproducible financial models, an M&A scorecard, and templates for pilot deployments that your teams can adapt immediately.
For leaders who need the numbers behind the strategy — complete regional and application breakdowns, granular product segmentation, vendor market shares, and proprietary unit economics models — the full dataset and appendices are available on our report page. Accessing the primary dataset will enable you to stress‑test your 2026 budget, prioritize R&D investments, and build a defensible go‑to‑market timeline that aligns regulatory, clinical, and commercial milestones.
PW Consulting’s Body Composition Analyzers Market study is structured to move you from insight to action: not just what the market looks like, but precisely what to do about it in 2026.
For detailed analysis of this topic, please visit the official page: Body Composition Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


