



Category: IT & Electronics
Salon Software Market to Reach USD 468.4M by 2032, Growing at 10.5% CAGR - PW Consulting
By PW Consulting, 2026-07-23
Salon Software Market 2026: Strategic Signals for Leaders — A PW Consulting Preview
Executive snapshot
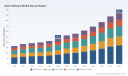
As salons and wellness providers accelerate digital adoption, the global salon software market has moved from early adoption into a phase of steady commercialisation and consolidation. Using 2025 as the base year, PW Consulting’s market model places global industry revenue at USD 233.5 Million in 2025 and projects a compound annual growth rate (CAGR) of 10.5% through the 2026–2032 forecast window. By 2032 the market is expected to nearly double relative to 2025 levels, reflecting persistent demand for appointment management, payments, client lifecycle tools and embedded marketplace discovery.
Salon Software Market
Historic performance underpins the outlook: between 2020 and 2025 the market expanded from the low‑hundreds to today’s base, demonstrating both resilient demand among independent providers and growing spend by multi‑location operators. That trajectory — faster SaaS adoption, richer platform capabilities, and renewed M&A activity — shapes a strategic agenda for 2026 decisions.
Salon Software Market
Why this research matters for 2026 decision cycles
-
Investment prioritisation: The market’s mid‑teens structural growth dynamics mean limited capital should be directed to features and channels that accelerate stickiness (client retention, automated rebooking, recurring revenue) rather than one‑off acquisition incentives.
Salon Software Market -
M&A and partnership timing: Consolidation is both a risk and an opportunity. Players looking to scale quickly should decide between organic product investment and targeted tuck‑ins that unlock marketplace demand or geographic distribution.
-
Product roadmaps: The fastest path to ROI in 2026 will be modular platform strategies — core booking + payments + client CRM — augmented by optional AI and analytics components sold as premium layers.
-
Regulatory compliance as market entry barrier: Changes in EU/UK data regimes will reshape product design and cross‑border expansion playbooks; compliance is a commercial advantage for platforms that can guarantee simple, auditable controls for SMB customers.
Market dynamics and key themes
-
Cloud first, but nuance matters: Cloud‑based SaaS remains the dominant architectural choice for new deployments, offering faster onboarding and centralized updates. However, product differentiation now comes from integration depth (POS, inventory, payroll) and vertical tailoring for multi‑unit vs. solo operators.
-
Marketplace and discovery economics: Platforms that combine booking with discovery and marketplace features capture higher lifetime value by reducing client acquisition costs for salons. Operators should assess the trade‑off between taking marketplace fees and driving organic bookings through salon marketing.
-
AI and automation adoption: Early deployments (concierge assistants, automated client outreach, dynamic scheduling) improve utilization and client retention, but they require robust training data and privacy‑first design to earn salon trust.
-
Fragmented competitive landscape: The market remains moderately fragmented; the largest vendors account for roughly a quarter to a third of global vendor revenues, with a long tail of regionally focused specialists and point solutions. That structure favors both vertical consolidation and continued niche innovation.
-
Regulatory and privacy headwinds: Recent regulatory shifts — notably EU proposals that introduce SMB exemptions and the UK Data (Use and Access) Act adjustments — lower some compliance friction for basic scheduling use‑cases but increase scrutiny on transparency and cross‑border data disclosures. Platforms must balance simplified compliance flows for low‑risk SMBs with the transparency required under evolving EU/UK enforcement practices.
Competitive landscape — strategic positions and implications
The vendor universe ranges from single‑practitioner solutions to enterprise suites. Understanding each player’s strategic move helps buyers and investors prioritise partnerships and targets.
-
Vagaro (United States, https://www.vagaro.com) — A cloud‑first player focused on beauty and wellness professionals. Recent M&A and partnership activity (notably an acquisition in early 2025 and a major partnership in 2026) signals an aggressive scale strategy combining product breadth with distribution via salon networks. Strategic implication: attractive partner for channel expansion but expect integration complexity post‑deal.
-
Booksy (Poland, https://biz.booksy.com) — Strong in appointment management with integrated payments and CRM. Booksy’s core strength lies in mobile‑first workflows and a broad SMB footprint; it remains an acquisition target or regional consolidator.
-
Fresha (United Kingdom, https://www.fresha.com) — Emphasises a marketplace model with discovery at its core. Fresha is a bellwether for platforms that monetise through client leads rather than pure subscription fees.
-
Phorest (Ireland, https://www.phorest.com) — Differentiates through inventory, payroll and retention tools for both independent and multi‑location salons. Its positioning is compelling for operators seeking an integrated back‑office experience.
-
Mindbody (United States, https://www.mindbodyonline.com) — Historically a wellness heavyweight. The sector’s recent aggregation into larger wellness operating systems (notably a March 2026 merger activity) redefines competitive dynamics for traditional full‑suite providers and creates new scale economies for marketing and distribution.
-
GlossGenius (United States, https://glossgenius.com) — Targets solo stylists with an elegant UX and simple monetisation. Its success highlights the premium clients place on ease of use for micro‑businesses.
-
Mangomint (United States, https://www.mangomint.com) — Focuses on multi‑location operations; recent product launches enhance omnichannel client communication. Tactical implication: feature parity with enterprise suites but with lower total cost to small chains.
-
Boulevard (United States, https://www.boulevard.co) — Positions itself as a premium client experience platform, attractive to higher‑end salons and medical‑aesthetic operators requiring enterprise‑grade controls.
-
Zenoti (United States, https://www.zenoti.com) — Enterprise‑oriented with AI concierge and advanced marketing automation. Zenoti represents the upper bound of capability for multi‑unit operators willing to pay for deeper analytics and automation.
-
Acuity Scheduling (United States, https://www.acuityscheduling.com) — Favoured by small to medium salons for scheduling simplicity and payment integration; its lightweight model underscores opportunities for channel integrations and white‑label partnerships.
Recent moves to watch (signal map)
-
Consolidation acceleration: A notable merger in early 2026 combined several wellness brands into a larger operating system, shifting distribution and marketing dynamics across the market.
-
Buy‑side playbooks: Larger vendors continue to acquire point solutions (scheduling, payments, discovery engines) to accelerate cross‑sell — a pattern that will drive valuation premia for targeted tuck‑ins.
-
Feature competition: New communication and AI features launched across vendors prioritise client engagement and automation, raising the bar for product roadmaps in 2026.
What the PW Consulting report delivers (practical, decision‑ready content)
Our full report is structured to convert insight into action. Highlights include:
-
A transparent market model (base year 2025) with historical calibration and scenario forecasts to 2032, including high/central/low cases that quantify revenue sensitivity to adoption rates, pricing changes and consolidation.
-
Buyer and use‑case segmentation that maps willingness to pay, feature elasticity, and churn risk for solo practitioners, multi‑location chains and enterprise wellness operators — presented as decision matrices and actionable personas.
-
Vendor benchmark and capability matrix: feature, pricing, integration maturity and partner ecosystems — scored against PW Consulting’s GTM readiness framework.
-
M&A heatmap and target shortlist methodology: identification criteria, valuation multiples observed in the market, and playbooks for integration that preserve retention and accelerate cross‑sell.
-
Compliance & privacy checklist tailored for EU/UK/US cross‑border operations, with pragmatic controls that reduce implementation friction for SMB customers while meeting higher‑risk enterprise needs.
-
Product and monetisation blueprints: suggested bundles, premium feature ladders, and channel incentive structures designed to lift average revenue per customer without increasing churn.
-
An 18–24 month roadmap for executives: prioritised investments, quick wins, and a test‑and‑learn plan for AI pilots and marketplace rollouts.
Action recommendations for 2026
-
Prioritise modular SaaS investments that derive revenue from recurring services (retention tools, loyalty, automated marketing) rather than one‑off integrations.
-
Use M&A to fill distribution gaps or acquire discovery channels, not just product parity. The best targets accelerate customer acquisition or deliver high margins on cross‑sell.
-
Design privacy‑first AI pilots: start with opt‑in concierge features that demonstrably increase bookings; measure lift before full roll‑out and document consent flows to preempt regulatory scrutiny.
-
Lock in channel partners (salon groups, franchise systems, payment providers) early — strategic distribution wins in 2026 translate to durable market share by 2028.
-
Request vendor scorecards and scenario outputs from advisors. Key inputs you should demand: granular segmentation by deployment type, detailed vendor capability scores and the underlying assumptions driving the 2032 upside case.
Next steps — why access the full report
This preview highlights the strategic contours and the most consequential moves shaping the salon software market in 2026. The full PW Consulting report contains the granular modelling, vendor scorecards and playbooks executives need to translate growth forecasts into executable plans. If you are allocating product, partnership or M&A capital in 2026, the detailed scenarios and acquisition readiness checklists in our report will materially shorten your decision cycle and reduce execution risk.
For access to the complete dataset, vendor scorecards and our full set of recommendations — including downloadable models and an interactive decision matrix — please consult the full Salon Software Market report from PW Consulting.
For detailed analysis of this topic, please visit the official page: Salon Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Healthcare BPO Poised to Reach $845.9M by 2032 at 10.7% CAGR — PW Consulting Market Brief
By PW Consulting, 2026-07-23
Healthcare BPO Market — Strategic Briefing for 2026 Decision-Makers
As healthcare providers, payers, and life sciences firms confront mounting margin pressure and increasingly complex regulatory demands, the business process outsourcing (BPO) market for healthcare is evolving from a labor-arbitrage play into a strategic capability enabler. PW Consulting’s latest Healthcare BPO Market research positions executives to translate market dynamics into observable, executable choices in 2026. The market is on a sustained growth path — anchored to a 2025 base and expanding at an expected compound annual growth rate (CAGR) of 10.7% across the 2026–2032 forecast window — with total addressable market figures roughly doubling over that period. This briefing summarizes the strategic value of the full report while intentionally reserving proprietary segmentation and granular metrics for the primary study.
Healthcare BPO Market
Why this research matters right now
-
Timing: 2026 is a hinge year for outsourcing strategy. Near-term regulatory updates and reimbursement shifts mean outsourcing choices made this year will shape operating models and financial outcomes for the next business cycle.
Healthcare BPO Market -
Investment prioritization: With constrained budgets, health enterprises must decide which parts of the revenue cycle, clinical support, and payer administration to outsource, automate, or keep in-house.
Healthcare BPO Market -
Vendor strategy: The vendor landscape is consolidating, yet remains sufficiently fragmented that careful partner selection yields measurable advantage in cost, quality, and speed-to-value.
-
Capability transformation: BPO arrangements are increasingly hybrid — combining global delivery, onshore centers, RPA/AI acceleration, and embedded clinical expertise — requiring new governance and transition playbooks.
What the full report delivers (practical, actionable modules)
-
Market sizing & forecast framework — transparent methodology and year-by-year projections across the 2020–2032 window that support scenario planning and investment cases.
-
Demand-driver analysis — granular insights on reimbursement reform, readmission penalties, workforce dynamics, and technology adoption that drive near- and medium-term outsourcing demand.
-
Vendor scorecards and selection playbook — standardized evaluation criteria, negotiation levers, and an RFP template calibrated to outsourcing objectives (cost, compliance, transformation).
-
TCO and ROI models — configurable templates to quantify short- and long-term benefits from contract structures that combine fixed, variable, and outcome-based pricing.
-
Transition and governance blueprints — step-by-step runbooks for service transfer, SLAs, joint steering committees, and continuous improvement cycles.
-
Technology integration guidance — practical approaches for infusion of RPA, NLP/AI-assisted coding, and cloud-native platforms into outsourced operations without disrupting clinical workflows.
-
Regulatory and privacy checklists — map of compliance controls and contractual clauses for cross-border data handling and audit readiness.
-
Case studies and negotiation playbooks — real-world examples that highlight pitfalls and success patterns from recent strategic partnerships.
Data-driven insights to inform your 2026 playbook
The headline numbers matter because they change decision thresholds. With the market expanding at roughly 10.7% annually through 2032, executives should expect capacity, vendor capabilities, and solution maturity to improve rapidly — but so will competition for talent and proven transformational vendors. Key implications:
-
Prioritize modular contracts. A fast-growth market delivers new service models and pricing constructs frequently. Contracts that allow phased scope expansion and outcome-based elements protect against vendor lock-in and capture upside from performance improvements.
-
Accelerate digital enablement inside BPO engagements. High-growth forecasts reflect accelerating adoption of automation and AI in coding, claims adjudication, and clinical documentation. Organizations that combine outsourcing with an explicit automation road map realize higher margins and faster break-even.
-
Rebalance geography with risk. Labor cost differentials remain relevant, but regulatory pressure and data residency requirements increase the importance of hybrid delivery — pairing offshore scale with nearshore/onshore centers for sensitive processes.
-
Embed clinical expertise. As payers and providers shift to value-based care, outsourced services that combine clinical judgment (risk adjustment, utilization review, readmission management) with operational excellence will command premium pricing and deliver greater downstream savings.
Competitive landscape — how to navigate vendor choices
The market shows a mid-tier concentration (with the top three and five vendors accounting for meaningful but not overwhelming shares), which creates both opportunities and risks: large incumbents can deliver scale and integration; mid-sized specialists often lead on niche capabilities and client intimacy. Our report profiles strategic players and recent moves; below is a high-level synthesis focused on decision-relevant differentiation.
-
Optum — Positioned as an integrated services provider with deep revenue cycle management capabilities and a growing international delivery footprint. Optum’s investments in onshore and offshore operations signal a focus on scale, compliance, and end-to-end service offerings. Expect strong performance where clients seek integrated clinical and administrative services backed by extensive platform investments.
-
Ensemble Health Partners — A specialist in end-to-end revenue cycle partnerships, increasingly active in strategic alliances with health systems. Recent partnership announcements demonstrate momentum in long-term revenue cycle outsourcing arrangements tied to operational transformation objectives, making them a contender for health systems seeking embedded partnership models rather than transactional outsourcing.
-
TruBridge — Focused on community and rural hospital markets with offerings that bridge EHR, financial operations, and RCM outsourcing. Their niche positioning is valuable for organizations that prioritize tailored services and local-market sensitivity.
-
GeBBS Healthcare Solutions — Noted for technology-enabled RCM and risk adjustment services. Firms seeking vendor partners for coding accuracy, analytics-led performance, and payer-focused operations will find GeBBS’ model compelling.
Recent vendor developments underscore this dynamic: strategic partnership activity has increased among revenue cycle specialists, while major incumbents continue to invest in regional delivery capacity and capabilities. A balanced vendor strategy — pairing a scale provider for commoditized transaction processing with a specialist for high-value clinical-adjacent processes — is a defensible default for many organizations in 2026.
Regulatory and risk considerations that should shape contracting and governance
Regulatory moves are not distant background noise; they materially affect cost and operational risk. Recent program updates reinforce the need to link outsourcing objectives to clinical and financial outcomes:
-
Readmission penalties and condition-specific outcome measures mean providers must ensure outsourced care-coordination and post-discharge workflows are auditable and integrated with clinical teams.
-
Medicare fee schedule and reimbursement updates alter revenue drivers and may change the math of which functions are best outsourced versus retained.
-
Data protection and cross-border flows require contractual clarity on data ownership, breach response, and audit rights; look for vendors that offer certified controls and transparent sub‑processor models.
Recommended 90/180/365 day actions for 2026
-
90 days — Rapid assessment: Run a two-week “as-is” diagnostic on high-dollar operational pockets (e.g., claims backlog, denials, clinical documentation). Deploy our quick RFP template to shortlist vendors and request automation roadmaps and compliance certifications.
-
180 days — Pilot and contract design: Launch a 3–6 month pilot with a chosen provider using an outcomes-linked pilot agreement. Establish steering committees, define success metrics, and lock in SLAs with step-down transition milestones. Build a TCO model that incorporates expected automation gains.
-
365 days — Scale and transform: Move from pilot to scaling phase, renegotiating terms based on proven performance. Formalize continuous improvement cycles and jointly invest in automation and analytics capabilities that drive further margin and quality improvements.
Conclusion — strategic value of the report for 2026 leaders
PW Consulting’s Healthcare BPO Market research is designed as a decision-readiness tool for 2026: it translates macro growth and regulatory context into executable sourcing strategies, vendor-selection heuristics, and implementation playbooks. By combining rigorous forecasting with operational templates and vendor intelligence, the study helps leaders reduce time-to-decision, de-risk transformation, and capture the productivity gains that a maturing outsourcing market can deliver.
For comprehensive segmentation, vendor scoring, and the proprietary datasets that underpin our conclusions — including the full time-series market sizing, scenario models, and downloadable negotiation tools — consult the full report at our source page. The summary above demonstrates the analytical depth you can expect; the report itself contains the detailed inputs and practical artifacts required to operationalize a winning 2026 outsourcing program.
For detailed analysis of this topic, please visit the official page: Healthcare BPO Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dual Interface IC Card Market to Reach USD 19.42M by 2032 at 6.0% CAGR
By PW Consulting, 2026-07-23
Dual Interface IC Card Market 2026: Strategic Preview and Decision Playbook
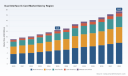
PW Consulting presents a forward-looking executive primer on the Dual Interface IC Card market designed specifically to inform strategic decisions throughout 2026. Drawing on a base year of 2025 and a historical window covering 2020–2025, our analysis synthesizes market trajectory, supply-chain stressors, regulatory shifts and competitive positioning into a compact, operationally focused guide. The full study — with downloadable models, regional and application-level splits, supplier scorecards and M&A screening tools — is available on our website; this preview is intended to establish trust through methodological clarity while intentionally withholding core segment tables so that readers are motivated to access the complete intelligence.
Dual Interface IC Card Market
Market trajectory at a glance
The Dual Interface IC Card market has shifted from recovery to steady expansion. After a compound rebound during the 2020–2025 period, the market reached a concentrated inflection by the base year 2025. Our forecast through 2032 assumes normalization of pandemic-era disruptions and an ongoing shift to contactless-enabled form factors; applying our baseline scenario, the market grows at a mid-single-digit CAGR (6.0%) across the 2026–2032 forecast window. In plain terms: the market that registered material growth through 2025 is projected to expand materially into the next decade, creating a predictable volume and revenue runway for incumbents and new entrants alike.
Dual Interface IC Card Market
Why this study matters for 2026 decision-making
- Investment timing and capacity planning: With lead times and component risk elevated, capital decisions made in 2026 for capacity expansion or tooling changes will have multi-year consequences. Our models translate CAGR-driven demand into high/medium/low capacity scenarios and break-even timelines under varying pricing and cost-inflation assumptions.
- Procurement and supply resilience: The study decomposes semiconductor and module supply risk into actionable mitigation playbooks — from dual-sourcing strategies to buffer inventory sizing — which are immediately applicable to procurement cycles initiated during 2026.
- Commercial strategy and pricing: As the market grows, margin dynamics will shift by technology choice (contact vs. contactless stack) and issuance model (centralized personalization vs. on-demand). The full report provides elasticities and TCO models to support pricing and channel decisions in 2026 tenders and RFQs.
- M&A and partnership screening: Given persistent fragmentation in the value chain, 2026 is a window for targeted M&A or JV activity. Our transaction playbook identifies strategic objectives that can be accomplished through acquisition versus partnership and provides a short-listing methodology for targets based on technology fit, client portfolios and manufacturing footprint.
Key operational themes shaping 2026
- Supply-chain pinch points and regulation: Elevated tariffs and nascent trade remedies in 2025–26 are already affecting procurement economics for semiconductors, substrates and assembly services. Simultaneously, extended lead times for discrete components and MOSFETs — routinely exceeding industry norms — mean that production ramp plans must assume multi-quarter sourcing windows rather than weeks. The study maps these regulatory and component constraints into scenario matrices that quantify cost and lead-time exposure by procurement strategy.
- Modularization and personalization on demand: Market demand is bifurcating between large-volume, standardized issuance and smaller, on-demand personalization models (e.g., instant issuance at branch or kiosk). We evaluate technology choices — coil-on-module, module-level dual-interface packaging and commi cards — and how these affect unit economics, lifecycle management and service delivery for issuers.
- Security, identity and credential convergence: As payment schemes, government ID projects and transportation systems increasingly demand multi-application cards, product roadmaps that emphasize secure element capabilities, contactless performance and lifecycle support gain strategic value. Our technical gap analysis helps R&D leaders prioritize chip features (e.g., DDA, biometrics support) against anticipated regulatory and customer requirements through 2032.
- Sustainability and cost-to-serve: Sustainability demands — recyclability of card substrates and emissions from complex supply chains — are emerging commercial differentiators. The report quantifies the cost-to-serve impact of greener materials and localized issuance, enabling CFOs to weigh capex vs. marketing benefits.
Competitive landscape — strategic implications
Our competitive mapping synthesizes public positioning, product capability and strategic moves by core players operating in the dual-interface space. Key profiles emphasize technology specialization and market roles rather than absolute market share figures.
Dual Interface IC Card Market
- Infineon Technologies AG (Germany, https://www.infineon.com): A dominant technology supplier with advanced coil-on-module and dual-interface packaging IP. Their field-proven module approaches shorten integrator timelines and are well suited to customers prioritizing lifespan and interoperability. For buyers, Infineon is a strategic partner for high-performance contact/contactless implementations and a key supplier to watch for roadmap alignments.
- IDEMIA Group (France, https://www.idemia.com): A leader in EMV contact and contactless payment products, IDEMIA’s portfolio emphasizes global scheme compatibility and metal-interface options. Their strength is end-to-end issuance and identity solutions, making them an attractive partner for issuers aiming to consolidate personalization and lifecycle services.
- Giesecke+Devrient (G+D) (Germany, https://www.gi-de.com): Combines EMV-certified dual-interface cards with deep personalization services and project execution capabilities. G+D is a typical partner where program security, regulatory compliance and large-scale government projects are prioritized.
- CPI Card Group Inc. (United States, https://cpicardgroup.com): CPI’s on-demand personalization and issuance capabilities have been bolstered by acquisition activity — notably a strategic transaction in mid-2025 that expands their on-demand production footprint. This kind of horizontal consolidation is a signal that the market values flexible issuance models.
- Eastcompeace Technology (China, http://www.eastcompeace.com) & Watchdata Systems (China, https://www.watchdata.com): Regional suppliers with strong ties to domestic card schemes and transportation/ETC programs. They are important partners for any issuer or scheme operator seeking localized manufacturing and cost-competitive supply chains.
- Kona I (South Korea, https://www.kona-i.com): A chip supplier focused on Java Card platforms and advanced security features (DDA, biometrics). Their product strategy supports issuers seeking feature-rich chips for complex multi-application programs.
Across the competitive set, the market shows a mix of technology specialization, system integration capability and personalization services. The net effect is a landscape where vertical specialization and horizontal consolidation both create opportunities for buyers and sellers — but the access to secure, qualified supply remains a decisive differentiator in 2026.
Practical outputs included in the full report
The full PW Consulting Dual Interface IC Card Market study is built for practitioners. Highlights include:
- Scenario-based demand models (2026–2032) with downloadable files that allow you to re-run forecasts under custom assumptions for ramp timing, price erosion and component inflation;
- Supplier risk heatmaps and procurement playbooks that convert lead-time and tariff exposure into specific sourcing decisions (dual-source candidates; localization thresholds; vendor qualification checklists);
- Commercial playbooks for issuers and manufacturers — go-to-market templates, price/volume negotiation levers, channel economics for instant issuance vs. central personalization;
- CapEx/Opex impact analysis for manufacturing footprint moves and molding/packaging investments; unit economics for coil-on-module and module-level integration choices;
- Regulatory impact matrix mapping potential tariff scenarios and Section 232 developments to cost and timing outcomes, plus recommended industry engagement tactics;
- M&A and partnership screening toolkit — objective scoring, synergies calculator, and a prioritized list of capability clusters to acquire versus partner for 2026 strategic initiatives;
- Implementation checklists: pilot to scale transition templates, test-and-validation plans for new module technologies, and lifecycle management playbooks covering field failures and card replacement logistics.
Recommended actions for executives in 2026
- Start procurement risk mitigation now: lock in multi-quarter component schedules and qualify at least two geographically diversified suppliers for critical semiconductors and substrates.
- Run a tiered S&OP stress test: use PW’s scenario models to stress-test capacity plans against tariff escalations, lead-time shocks and price inflation; prioritize options that minimize time-to-issuance disruption.
- Accelerate personalization and instant-issuance pilots where margins permit: on-demand models materially reduce distribution friction and create stickiness with issuers and end customers.
- Prioritize partnership with technology suppliers that have proven dual-interface integration IP, and insist on lifecycle support SLAs; this reduces integration risk and shortens time-to-market.
- Prepare an M&A/strategic-partner playbook: target assets that close technology gaps (chip IP, module packaging) or expand flexible manufacturing and personalization capability.
- Engage policymakers and industry bodies: coordinated industry input on tariffs and semiconductor policy can mitigate worst-case regulatory outcomes; this is as much a strategic priority as supply-chain reconfiguration.
Conclusion — the strategic window for 2026
2026 is a year where tactical execution will define strategic winners in the Dual Interface IC Card market. The combination of steady market expansion at an expected 6.0% CAGR for the forecast period, structural supply-chain risk and an active competitive landscape means that decisions taken this year about sourcing, capacity, partnerships and M&A will ripple throughout the decade. PW Consulting’s full report provides the granular regional and segment-level forecasts, supplier rankings and executable playbooks that leaders need to convert uncertainty into competitive advantage. For teams preparing capital plans, procurement strategies or commercial transformations in 2026, the difference between reactive moves and proactive positioning will hinge on access to the detailed scenario outputs and operational tools contained in the complete study.
To obtain the full dataset, regional and application split tables, supplier scorecards and the downloadable forecast models that support the analyses summarized here, please visit our Dual Interface IC Card Market report page.
For detailed analysis of this topic, please visit the official page: Dual Interface IC Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PA Systems Market 2026: Strategic Imperatives — A PW Consulting Preview
Executive summary
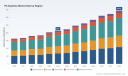
As organizations re-evaluate safety, experience and operational resilience in a post-pandemic, hyper-connected world, the public address (PA) systems sector has re-emerged as a strategic infrastructure play. Our new market study — anchored in a 2025 base year, covering 2020–2025 history and projecting through 2026–2032 — quantifies a market that is expanding steadily, with a compound annual growth rate of approximately 6.98% over the forecast window. From specialized voice-evacuation platforms to IP-native network speakers and portable live-sound arrays, the market is being reshaped by regulatory pressure, standards-driven procurement, and the migration to audio-over-IP combined with heightened cybersecurity expectations.
PA Systems Market
Market at a glance (strategic macro facts)
-
Base-year perspective: Our study uses 2025 as the analytical anchor and traces the sector’s evolution across a five-year historical window before projecting to 2032 using scenario-tested growth drivers and risk vectors.
PA Systems Market -
Growth trajectory: The market growth is material and sustained — driven by upgrades in public safety, venue modernization, and commercial audio experience investments — producing mid-single-digit annualized expansion through the late 2020s.
PA Systems Market -
Competitive structure: Concentration levels remain low-to-moderate (measured CR3/CR5 indices), indicating a fragmented supplier landscape where global brands coexist with regional specialists and system integrators.
-
Why this matters in 2026: Buyers and suppliers who align product roadmaps, certification strategies, and channel models with regulatory and networked-audio trends will capture disproportionate upside in procurement cycles starting this year.
Why this study is strategically valuable for 2026 decision-makers
-
Bridge from compliance to competitive advantage — Procurement teams must now consider voice-alarm certification, monitoring requirements and integration with fire and safety architectures as strategic differentiators, not merely line-item costs.
-
Technology adoption roadmap — Our analysis maps the acceleration of IP-based audio (including Dante and other media-over-IP protocols), the proliferation of networked speaker endpoints, and the implications for system latency, management consoles and lifecycle economics.
-
Risk-informed procurement — With requirements such as EN 54-16 and NFPA 72 influencing design and acceptance criteria in multiple jurisdictions, the study provides a decision-ready framework for risk weighting vendors and specification clauses.
-
Market timing for investment and M&A — The combination of modest concentration and steady growth creates clear windows for bolt-on acquisitions, geographic expansion and product-line consolidation targeted at vertical niches (transport hubs, stadiums, healthcare, education).
What the full report delivers — practical, action-oriented content
-
Robust market-sizing model: Our Excel-native model contains a bottom-up approach that reconciles historical shipments, ASP dynamics, lifecycle replacement cycles and services revenue to produce defensible forecasts through 2032.
-
Scenario analyses: Three market scenarios (baseline, accelerated adoption, constrained spend) with sensitivity testing on component pricing, certification timelines and public-budget cycles to inform capex vs. opex decisions.
-
Vendor scorecards: Qualitative and quantitative assessments across technology maturity, compliance posture, channel coverage, service capability and cybersecurity readiness for leading suppliers and selected regional integrators.
-
Go-to-market playbooks: Field-tested recommendations for manufacturers and distributors on channel segmentation, partner enablement, pricing ladders, bundled services (maintenance, monitoring, managed audio), and proof-of-concept templates for strategic customers.
-
Procurement & RFP templates: Clause-level language addressing EN 54-16 / NFPA 72 conformance, redundancy and survivability requirements, monitoring/health-reporting obligations, and cybersecurity baselines (including crypto, authentication and patching responsibilities).
-
Regulatory and standards map: A practical registry of jurisdictional requirements, certification pathways and test labs for voice-evacuation and life-safety PA deployments — useful for legal, compliance and engineering teams.
-
Dealer & integrator playbook: Sizing guidance for service contracts, spare-parts economics, training programs and field-safety audits that improve gross margin capture and reduce reputation risk.
-
Decision-read dashboards: Executive summary dashboards that translate market drivers into investment thresholds, project payback windows and strategic KPIs.
Competitive landscape — concise, actionable perspective on core suppliers
-
TOA Electronics (Kobe, Japan) — Strengths in engineered PA equipment (amplifiers, intercoms, speakers): TOA’s custom IP‑based PA and intercom systems make it a default choice for architects and systems integrators in complex venues. Strategic implication: OEMs and specifiers should evaluate TOA for bespoke integration projects where tight systems engineering and lifecycle support matter.
-
Axis Communications (Lund, Sweden) — An early mover in network audio and IP speakers, Axis continues to expand design versatility (notably with Dante support and beam-shaping features). Axis also emphasizes cybersecurity (notable cryptographic certifications). Strategic implication: For customers prioritizing cyber-hardened, networked audio with security-first procurement, Axis represents a compelling option — especially where IP consolidation with video/security is planned.
-
Guangzhou DSPPA Audio Co., Ltd. (Guangzhou, China) — Broad product range across amplifiers, speakers and integrated voice-alarm platforms positions DSPPA as a cost-competitive, full-line supplier for large-scale deployments. Strategic implication: Consider DSPPA for price-sensitive, volume deployments while validating certification and service arrangements for life-safety use cases.
-
Valcom (United States) — Focused on emergency paging, mass notification and institutional verticals (schools, hospitals): Valcom’s strength is in specialized paging and notification integration — an attractive partner for system integrators targeting public institutional contracts.
-
AFA Protective Systems, Inc. (United States) — Custom installations for fire/life safety; emphasis on design-build services for regulated facilities. Strategic implication: AFA is a potential M&A or partnership target for manufacturers seeking field-proven installation and commissioning capability.
-
Zenitel (Norway) — Specialist in PAVA/voice-evacuation systems compliant with EN 54-16 (also UL/CSA): Zenitel is a go-to for mission-critical environments where standards compliance is mandatory. Strategic implication: Certification pedigree makes Zenitel attractive for cross-border infrastructure projects where adherence to strict standards reduces acceptance risk.
-
JBL Professional (Harman, United States) — Strong in live-sound and professional PA markets with powered speakers and line arrays; JBL’s brand equity supports premium, performance-driven applications such as stadiums and touring events.
-
Yamaha Pro Audio (United States) — Portable PA and integrated mixer solutions for events and mobile production; recent model refreshes signal continued investment in flexible, hybrid-use products suited to both live-event and fixed-install scenarios.
Industry dynamics shaping supplier and buyer decisions
-
Standards and life-safety regulation — EN 54-16, NFPA 72 and equivalent regional requirements are the primary drivers of specification changes in public and commercial buildings. These standards affect system architecture, speaker monitoring, priority messaging and acceptance testing.
-
Cybersecurity and network convergence — Networked audio creates efficiency but expands the attack surface. Buyers increasingly demand cryptographic validation, secure boot, and proven patch-management processes; vendors are responding with certified components and hardened firmware.
-
Transition to managed services — With endpoints proliferating, clients are open to O&M outsourcing, managed monitoring and subscription-based health services that reduce institutional maintenance burden and provide predictable revenue for suppliers.
-
Product innovation vectors — Expect continued investment in DSP-based intelligibility enhancement, beam-steering for targeted announcements, and better integration between PA and mass-notification systems to meet both routine and emergency use cases.
Strategic recommendations — immediate actions for 2026
-
Embed certification as product strategy: For vendors, secure EN 54-16 / UL / CSA compliance where relevant early in the roadmap; for buyers, require certification evidence and factory acceptance test procedures in RFPs.
-
Prioritize cybersecurity in procurement: Require vendors to disclose cryptographic posture (e.g., FIPS-level compliance where applicable), firmware-update policies and incident response SLAs.
-
Design for serviceability: Build TCO models that place significant weight on maintenance, spare parts and remote-monitoring capabilities; these line items often drive total lifecycle costs more than initial hardware spend.
-
Evaluate strategic partnerships over one-off buys: Systems integrators and regional specialists can accelerate deployments and reduce acceptance risk; consider partnering or acquiring to gain local certification and field capability.
-
Use scenario planning for capital allocation: Apply the report’s scenario outputs to determine optimal timing for large upgrades (e.g., stadiums, transport hubs) to align with funding cycles and vendor roadmaps.
How to use this preview and next steps
This preview outlines the contours of a market that is both maturing and fragmenting — where regulatory compliance, networked-audio architectures and service-based revenue models will determine winners and losers. The full PW Consulting report contains the detailed segment-level tables, regional and application breakdowns, vendor scorecards, forecast models and downloadable decision tools that senior procurement, product and corporate development teams require to act in 2026.
Final note
We have intentionally withheld detailed regional and application-level tables in this preview to focus on strategic implications. Members and licensed purchasers of the PW Consulting PA Systems Market study gain full access to the granular data, supplier assessments, model files and RFP templates needed to convert insight into action. For a tailored briefing or to license the full deliverables (including the forecast model and vendor scorecards), contact your PW Consulting account director to schedule a strategy session.
For detailed analysis of this topic, please visit the official page: PA Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Building Management System Market 2026: A Strategic Preview for Executive Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-calibrated preview of our new Building Management System (BMS) Market study. This briefing distills the evidence and scenarios executives must weigh in 2026—highlighting the commercial inflection points, competitive dynamics, regulatory levers, and the practical modules in the full report that will materially affect capital allocation, M&A, product roadmaps, and go-to-market plays.
Building Management System Market
Why this study matters for 2026 strategy
The BMS market is in the middle of a structural acceleration. From a PW Consulting vantage, the market expanded steadily through our historical window and enters an aggressive growth phase underpinned by digitalization, regulatory tightening, and new procurement economics. Using 2025 as the base year, the overall market reached an estimated USD 158.4 Million and, under our central assumptions, is projected to grow to roughly USD 415.2 Million by 2032—equivalent to a compound annual growth rate of about 14.87% across the 2026–2032 forecast period.
Building Management System Market
For corporate leaders, that profile is not an academic projection: it signals a compressed timeline to capture scale economics, to validate recurring-revenue models, and to make decisive bets on platform architectures (open vs. vertically integrated), data monetization pathways, and strategic partnerships. In short, 2026 is the year to move from pilot to industrialization.
Building Management System Market
Core drivers shaping 2026 decisions
- Regulatory and incentive acceleration – New and updated regulations in major jurisdictions are raising the minimum expectations for performance measurement, lifecycle emissions accounting, and energy performance calculations. In parallel, tax credits and retrofit incentives in key markets increasingly condition eligibility on demonstrable BMS integration. These changes shift BMS from “optional efficiency upgrade” to a compliance and economic catalyst for retrofits.
- Platformization and AI – Major vendors and innovative challengers are embedding analytics, predictive maintenance, and energy optimization into BMS stacks. AI-driven operations are moving from pilot projects to operational rollouts, enabling measurable OPEX reductions and, in some cases, new revenue streams for managed services.
- Service-led monetization – The market is evolving toward subscription and outcome-based contracting; product releases and service launches in 2025–2026 show incumbents pivoting to digital-first services with remote monitoring and predictive support as cornerstones.
- Wireless and installation economics – Advances in wireless sensor networks and reductions in installation costs are redefining retrofit ROI, opening larger addressable markets among mid-size commercial and light industrial assets.
- Fragmented leadership but rising concentration risks – While the market remains competitive, our concentration metrics indicate a notable share of activity tied to a relatively small set of global players—creating both strategic threats and M&A opportunities for ambitious challengers.
What the full report contains (practical modules)
PW Consulting’s full Building Management System Market study is intentionally practical and structured to move teams from insight to action. Key components include:
- Executive Playbook – A one-page synthesis of 10 actions for CEOs, CIOs, and Heads of Real Estate to align operating models with BMS-driven value creation.
- Scenario-based Forecasts – Three scenarios (baseline, accelerated adoption, and downside) with explicit assumptions for energy prices, regulatory uptake, and IoT deployment rates across the 2026–2032 horizon.
- Buyer’s Guide and TCO Models – Modular, downloadable spreadsheets to model CapEx, incremental Opex, energy savings, and payback under multiple financing structures (outright purchase, subscription, EPC-linked contracting).
- Supplier Scorecards & Selection Toolkit – A standardized evaluation rubric for vendor short-listing, including security posture, interoperability, data governance, service SLAs, and upgrade pathways.
- Deployment Blueprints – Step-by-step implementation roadmaps for greenfield and retrofit projects, with recommended governance structures, typical timelines, and risk mitigation playbooks (cybersecurity, interoperability, and vendor lock-in).
- M&A and Partnership Playbook – Valuation frameworks and diligence checklists for acquiring software-enabled BMS businesses, plus integration templates for OEM partnerships and channel programs.
- Regulatory Impact Matrix – Jurisdiction-by-jurisdiction assessment of current and imminent regulation, with quantified implications for compliance costs and incentive capture.
We intentionally treat granular segment shares and unit-level forecasts as gated deliverables: readers are shown high-level trajectories and strategic implications here, with the full dataset and downloadable models accessible through the report portal.
Competitive landscape: what incumbents and challengers are signaling
The competitive map is dominated by global industrial and building systems incumbents advancing three concurrent plays: platform openness, services-led monetization, and technology consolidation through software. Key players we analyze in depth include:
- Johnson Controls (Cork, Ireland) – Their Metasys platform continues to push the open-building automation argument, emphasizing high-device scalability and integrated energy intelligence. Recent product releases underscore a move to multi-server resilience and preconfigured energy suites that shorten time-to-value.
- Schneider Electric (Paris, France) – EcoStruxure’s evolution toward integrated building and power management, coupled with a subscription-friendly licensing pivot, signals a strategy to lock in enterprise customers with centralized software management and professional services bundles.
- Honeywell International (Charlotte, United States) – Honeywell’s adoption of AI and cloud-native services in its Forge/EBI portfolio illustrates the playbook of embedding advanced analytics into operations and packaging outcomes as managed services.
- Siemens AG (Munich, Germany) – Siemens is positioning its Desigo CC ecosystem as a unified control layer, focusing on digital infrastructure and enterprise-scale interoperability.
- Trane Technologies, ABB, Carrier, Bosch, Legrand, Emerson, Delta Electronics, Azbil, Hitachi – Each of these firms brings distinct assets—HVAC optimization, power monitoring, electrical integration, and regional channel strength—that collectively shape competitive dynamics. Their strategies range from vertical integration to platform partnerships and regional service expansion.
Recent launches and updates in 2025–2026 provide tactical signals: product releases emphasizing device-scale scalability, AI-powered operations suites, and managed digital-first services all point to a near-term competitive battleground in service delivery and data value capture.
Regulatory and market “noise” executives must factor
- European Union regulations revised lifecycle and energy performance methodologies, introducing lifecycle GWP assessments and new calculation frameworks that raise compliance complexity for building owners and BMS providers.
- In certain large markets, retrofit tax credits and incentive programs now condition eligibility on integrated BMS installation—making BMS a gatekeeper for subsidy capture.
- Infrastructure economics are shifting as wireless networking adoption reduces installation barriers, but also raises questions about long-term cybersecurity and device lifecycle management.
Each of these points is not just a compliance tick-box: they materially change procurement architectures, financing models, and partner ecosystems. Our regulatory impact matrix in the full report quantifies these effects for prioritized markets and offers mitigation strategies.
Strategic implications and recommended 2026 actions
Based on the market trajectory and competitive signals, PW Consulting recommends that decision-makers prioritize the following actions in 2026:
- Declare a platform position – Choose clearly between “open integrator” and “full-stack owner” strategies. Each has different partner economics, upgrade obligations, and revenue models; indecision yields vendor lock-in and missed service revenues.
- Operationalize BMS as a service line – Pilot subscription and outcomes-based contracts with a short list of anchor customers; build remote operations centers and service SLAs that can be scaled.
- Leverage incentives and compliance windows – Map eligible retrofit pipelines to available tax credits and incentive programs to accelerate conversion and improve project economics.
- Invest selectively in AI and cybersecurity – Prioritize analytics capabilities that deliver measurable OPEX reductions in the first 12 months; fund cybersecurity architecture commensurate with enterprise risk and regulatory expectations.
- Target M&A for capability gaps – If scale is required quickly, pursue tuck-ins for software analytics, wireless sensor stacks, or regional service networks rather than large-scale platform acquisitions that dilute focus.
Closing: what to do next
The BMS market’s projected expansion—driven by digitalization, policy, and new deployment economics—creates a narrow window for strategic capture. Our full report contains the granular datasets, sensitivity models, and supplier-level comparisons that boards and executive teams need to operationalize the recommendations above.
As a preview, this briefing outlines the strategic contours and practical modules that matter most in 2026. For the detailed segment-level figures, regional scenarios, downloadable TCO models, and the supplier scorecards referenced here, access the full Building Management System Market report on our site. PW Consulting’s team stands ready to convert these insights into a tailored action plan aligned with your portfolio and risk appetite.
For detailed analysis of this topic, please visit the official page: Building Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Photomask Market to Hit USD 5,919M by 2032 at 5.8% CAGR
By PW Consulting, 2026-07-22
Semiconductor Photomask Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive snapshot
The global semiconductor photomask market has moved from a niche supporting role to a strategic chokepoint in advanced semiconductor supply chains. Our base-year analysis (2025) anchors a multi-year time series that shows the market expanding from roughly USD 3,000 Million in 2020 to USD 4,010 Million in 2025, with a modeled trajectory that reaches approximately USD 5,919 Million by 2032. The forecast period (2026–2032) carries a compound annual growth rate of 5.8% (USD, revenue unit: Million), reflecting a steady blend of demand from advanced logic, FPD (flat panel displays), and diversified applications that include optical devices and MEMS.
Semiconductor Photomask Market
Why this matters to corporate decision-makers in 2026
-
Photomasks are no longer a commoditized input; they are strategic assets that determine wafer development cycle time, yield at cutting-edge nodes, and time-to-market for next-generation devices.
Semiconductor Photomask Market -
Macro policy shifts—large national incentive programs, tariff regimes, and proposed trade investigations—are remapping where and how photomask capacity is built and financed. Companies that treat photomasks as a sourcing risk rather than a routine buy face higher technical and commercial surprise costs.
Semiconductor Photomask Market -
Technology transitions (e.g., migration to EUV and sub-3nm process integration) change the game: mask blank supply, defect control, and inspection capabilities are decisive in supplier selection and capacity planning.
What our full PW Consulting report delivers (practical, actionable content)
-
Proven market-sizing methodology and reconciled historicals (2020–2025) plus an auditable forecast model (2026–2032) with scenario toggles for node-adoption speed, regional demand shifts, and raw-material disruptions.
-
Supply-chain maps that trace mask blank origins, specialty material inputs (high-purity quartz and coating chemistries), and capital equipment flows into final mask facilities—highlighting single points of failure and realistic substitution pathways.
-
Technology roadmaps linking lithography node evolution to mask complexity, blank specifications, inspection thresholds, and cost-per-mask levers. This section explains when incremental R&D or new-capacity spend yields the highest strategic return.
-
Competitive benchmarking and capability scorecards across merchant suppliers and captive internal mask operations—covering capacity footprint, node-readiness, EUV capabilities, blank sourcing resilience, and service-level performance.
-
Scenario-based financial templates for CapEx prioritization, supplier contractual structures (e.g., volume commitments, price collars, option frameworks), and near-term working-capital stress testing under tariff and disruption scenarios.
-
A practical procurement playbook and implementation checklist for 12–24 month horizons, including negotiation levers, KPIs for supplier performance, and contingency triggers for near-shoring or dual-sourcing.
Note: this preview intentionally omits the granular regional and application split tables that appear in the full report—those detailed tables and downloadable models are available on the report landing page.
Competitive landscape: players, positioning, and recent strategic moves
The photomask market exhibits a moderate degree of concentration (CR3 ~45%, CR5 ~60%), which creates a strategic dynamic where a small set of vendors exert meaningful influence on capacity lead-times, technology co-development, and pricing behavior. Our qualitative and quantitative benchmarking identifies the following structural positions among core suppliers:
-
Photronics Inc. — A merchant leader with a global fabrication footprint across North America, Asia, and Europe. Recent corporate disclosures emphasize sustained capital investment in U.S. and Korean facilities to capture demand from advanced logic and specialty segments. Photronics’ strengths are scale, service breadth, and an established customer base for IC and FPD masks; areas to monitor are their integration with blank suppliers and the pace of throughput improvements at newer sites.
-
Tekscend Photomask Corp. (rebranded from Toppan Photomask) — A global provider with a diversified manufacturing presence. Notable recent developments include a significant state-level production expansion in the United States (capacity-add grant-supported) and a new advanced facility groundbreaking in Singapore. These moves underline Tekscend’s push to align capacity geographically with customer ecosystems while leveraging local incentives—an instructive blueprint for suppliers seeking to mitigate tariff and logistics risk.
-
Dai Nippon Printing (DNP) — Positioned as a developer and supplier of photomasks for advanced EUV lithography nodes. DNP’s emphasis on supporting 3nm and 2nm process ramps makes it a key strategic partner for leading-edge fabs. Their technology-oriented roadmap suggests premium capabilities in defect control and multi-layer patterning readiness.
-
Hoya Corporation — A dominant supplier of EUV mask blanks and photomask blanks generally. Control over mask-blank supply is an important commercial lever; Hoya’s dominance in blank materials has implications for upstream negotiation power and downstream lead-times, especially where blank quality limits throughput at advanced nodes.
-
SK-Electronics — A major supplier with a strong regional position and capabilities across mask types. Their scale in critical geographies makes them a natural partner for regional fabs and OEMs seeking alignment with local manufacturing ecosystems.
Recent industry moves—facility expansions backed by public grants, new greenfield projects in Southeast Asia, and merchant players’ public workstreams on capacity—signal an active reshaping of the sector. For buyers and investors, the lesson is clear: map supplier roadmaps to your node and geographic exposure, and prioritize partners with both technology match and capacity commitment.
Supply-chain and regulatory dynamics shaping 2026 decisions
-
Raw-material constraints: a notable share of mask manufacturers report supply issues for high-purity quartz substrates and specialty materials. This is not an isolated procurement inconvenience; it translates into lead-time volatility and margin leakage for both suppliers and buyers.
-
Policy and trade: recent policy developments—large federal incentive programs for domestic fabs, unilateral tariff actions on semiconductors, and proposed trade investigations—create a policy overlay that materially affects location economics and capital subsidy calculus. The CHIPS-era funding environment opens incentives for local capacity, while tariffs and export-control regimes escalate the strategic value of diversified manufacturing footprints.
-
Export controls and industry lobbying: the industry is already engaging with regulators over proposed controls and supply-chain security frameworks. Companies must weigh compliance costs and customer friction against the strategic need to access certain markets and technology inputs.
Actionable strategic playbook for 2026 planning cycles
-
Align capacity investments with node adoption curves: prioritize investments that address mask complexity and inspection capacity rather than only raw throughput.
-
Secure raw-material continuity: negotiate multi-year supply agreements, explore strategic inventory positioning, and invest in qualifying alternative substrates to reduce single-source exposure.
-
Use government incentives as leverage: build funding scenarios into CapEx models to access grants and tax incentives, and sequence investments to capture local subsidies while maintaining global customer reach.
-
Adopt scenario-based contracting: incorporate flexible volume options, price collars, and performance SLAs to manage demand swings and technological uncertainty.
-
Prioritize supplier co-development: where advanced EUV masks or blank quality are determinative, consider joint R&D arrangements, co-located pilot lines, or equity stakes to secure preferential access.
-
Prepare M&A playbooks focused on capability, not just capacity: attractive targets include specialist blank suppliers, inspection/repair technology vendors, and regional fabs with complementary customer lists.
-
Operationalize risk metrics: integrate mask-lead-time and blank-quality KPIs into product development gating decisions and supplier scorecards.
How to use this report in your 2026 decision process
-
For CFOs and strategy teams: embed the report’s scenario templates into multi-year CapEx frameworks to stress-test investment timing and returns under tariff and material shortage scenarios.
-
For procurement and supply-chain leaders: deploy the procurement playbook and supplier scorecards to re-run supplier selection for the top five mask families that impact your roadmap.
-
For corporate development and BD: use the competitive benchmarking to screen acquisition targets or strategic alliances that accelerate EUV readiness or regional coverage.
-
For R&D and process engineers: the technology roadmap provides the prioritized mask capabilities that materially affect yield uplift and time-to-first-silicon for advanced nodes.
Closing: the strategic choice for 2026
The photomask market sits at a strategic inflection: incremental investments, supplier choices, and policy responses made in 2026 will disproportionately shape costs, cycle times, and competitive advantage through the next node cycle. PW Consulting’s full Semiconductor Photomask Market report equips decision-makers with the quantitative models, supplier intelligence, and implementation playbooks required to act with confidence. This preview highlights the core levers—capacity alignment, raw-material resilience, supplier co-development, and policy-aware CapEx planning—while the full report contains the granular segmentation, downloadable financial models, and detailed company profiles you'll need to operationalize strategy.
To access the full dataset, scenario model, and proprietary supplier scorecards, please visit the PW Consulting report page for Semiconductor Photomask Market or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Semiconductor Photomask Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IC-Substrate Market Set to Expand at 6.63% CAGR Through 2032
By PW Consulting, 2026-07-22
IC-Substrate Market — 2026 Strategic Briefing (PW Consulting)
Introduction: Why this research will shape 2026 corporate strategy
As semiconductor systems pivot to AI, high-performance computing (HPC), and electrified mobility, IC-substrates have moved from a commodity tier to a strategic bottleneck. Our IC-Substrate Market study, anchored on a 2025 base year and projecting through 2032, quantifies that transition and translates it into actionable choices for executives planning investments, procurement, and product roadmaps in 2026. The market — measured in USD (Million) — reached a clear inflection by 2025 and our forecast through 2032 reflects a sustained compound growth trajectory at a 6.63% CAGR. This briefing distils the research’s strategic value: what to act on now, what to monitor, and how to position organizations to capture asymmetric upside while mitigating supplier and material risks.
IC-Substrate Market
Macro snapshot and what it means for 2026 decisions
The IC-substrate market expanded materially through the 2020–2025 period and enters 2026 with momentum. Our baseline captures both the accelerating demand from AI and HPC servers as well as resilient volumes from mobile, automotive, and telecom platforms. With an explicit, model-driven forecast out to 2032 showing steady growth to the mid-term, the takeaway for 2026 is straightforward: firms cannot treat substrates as a passive input. Strategic sourcing, capacity coordination, and product architecture choices made this year will determine supply cost, time-to-market, and competitive positioning over the next five years.
IC-Substrate Market
Supply-side dynamics that will determine winners and losers
-
Material bottlenecks and price transmission — Persistent shortages in fiberglass and base resins are already affecting ABF and other advanced substrate lines. Supply tightness has led to upstream price moves that propagate through substrate makers and into OEM bill-of-materials, making short-term cost escalation a real planning variable for 2026 budgets and long-term contracts.
IC-Substrate Market -
Capacity wave with timing risk — Leading manufacturers are executing sizable capacity programs targeted at AI/HPC substrates. These investments will change available throughput materially, but they come with ramp risk: commissioning, qualification, and logistic readiness will create uneven relief across product classes and regions. Firms should expect a phased easing of constraints rather than an immediate market surplus.
-
Technology bifurcation — Two technology tracks are emerging as strategic focal points: higher-density ABF and flip‑chip technologies optimized for server compute, and glass‑core / multifunctional substrates aimed at performance-per-watt and photonics integration. Each requires different supplier capabilities and raw material mixes, forcing procurement segmentation and differentiated supplier performance metrics.
Competitive landscape: strategic profiles and implications
The market exhibits moderate concentration, with the top-three and top-five players accounting for a meaningful share of global supply — an important structural fact for 2026 negotiators. Leading vendors have adopted divergent strategies that create distinct competitive dynamics:
-
Capacity-first incumbents — Certain tier‑one substrate manufacturers are pursuing aggressive capacity expansions focused on AI server demand. Their strategy: secure scale to lock in long-term contracts with hyperscalers and cloud providers. For corporate purchasers, this means a differentiated access map: some suppliers will have priority allocation to high-value customers as new lines ramp.
-
Technology differentiation players — A subset of firms is investing in glass-core and multifunctional core technologies to capture HPC, photonics, and RF-intensive applications. These moves are aimed at commanding product premiums and creating stickiness with OEMs that value feature-rich substrates over commoditized cost plays.
-
Margin managers — In response to raw material cost pressure, several manufacturers are adjusting pricing and upgrading product mixes toward premium segments. Buyers that delay renegotiation risk absorption of price hikes; proactive sourcing teams can convert volatility into preferred-supplier arrangements or hedged contracts.
-
Regional policy and funding impacts — Public funding and industrial policy (including targeted semiconductor initiatives) are materially influencing where new capacity is sited and how quickly it comes online. These programs alter the competitive calculus for firms choosing to invest in local capacity, joint ventures, or supply agreements tied to regional incentives.
Practical contents of the PW Consulting report (what you can use tomorrow)
Our report is designed as a decision tool, not just a market narrative. Key operational modules include:
-
Granular market-sizing model (2020–2032) with scenario toggles — run sensitivity on demand shocks, material price inflation, and accelerated AI server adoption curves to quantify P&L and capex needs.
-
Supply-demand mapping and capacity tracker — vendor-level capacity buildouts, technological capability overlays, and timing risk assessments so procurement and manufacturing teams can sequence supplier engagements and qualification activities.
-
Raw material stress tests — simulate the impact of fiberglass and resin scarcity on lead times, price inflation, and substitution pathways, and evaluate mitigation levers including strategic inventory, alternative chemistries, and long-term purchase agreements.
-
Competitive benchmarking — capability heatmaps for leading substrate suppliers, including their technological focus, capacity posture, and recent strategic moves, with an impartial matrix to inform sourcing and partnership decisions.
-
Investment and M&A playbook — ROI models for greenfield vs. brownfield capacity, joint-venture structures, and bolt-on acquisition scenarios that reflect current funding landscapes and policy incentives.
-
Commercial tactics — pricing stress scenarios and contracting templates that protect margins while preserving supply continuity during 2026 ramps.
Strategic recommendations for 2026 (concise playbook)
-
Prioritise supply security over spot-price chasing — lock in critical volumes for AI/HPC substrate families via multi-year agreements with step-up clauses tied to ramp milestones.
-
Diversify the material base — accelerate validation programs for alternative laminates and glass-core variants to reduce exposure to fiberglass and resin volatility.
-
Align product roadmaps with substrate roadmaps — co-develop substrate-aware packaging roadmaps with suppliers to optimize yield, thermal performance, and cost of ownership across 2026–2028 device generations.
-
Use policy funding to de‑risk capital — where access to regional incentives or semiconductor funds exists, structure capacity expansion or partnership deals that leverage public financing to compress payback periods.
-
Maintain optionality — structure supply agreements with staged commitments and volume corridors to capture upside without overpaying during transient oversupply periods.
90/180/360 day decision milestones
-
0–90 days: Run an exposure map — quantify current substrate exposure by product family and identify single-supplier and single-material risks. Initiate priority supplier conversations to freeze near-term allocation.
-
90–180 days: Negotiate flexible, hedged agreements — convert exposure into structured contracts with price adjustment corridors, qualification timelines, and redundancy clauses. Begin co‑validation projects for alternative materials.
-
180–360 days: Execute strategic investments and partnerships — finalize JV or investment thesis for capacity participation where economics justify and start executing product co‑development agreements aligned to substrate availability timelines.
How PW Consulting’s report supports board-level decision making
This study was built to inform capital allocation, procurement strategy, and product architecture choices at the board and executive levels. It converts market dynamics into KPIs — supply continuity probability, material-cost inflation impact on gross margin, and capacity ramp risk-adjusted IRR — that are directly comparable across investment alternatives. For companies evaluating M&A, greenfield investment, or large-volume procurement contracts, the report provides the sensitivity analyses and scenario outputs necessary to justify decisions to investors and stakeholders in 2026.
Closing: the value of a granular yet actionable lens
IC-substrates have shifted from a manufacturing input to a strategic vector that determines performance, time-to-market, and margin capture in an AI‑differentiated semiconductor landscape. Our research balances actionable operational tools with a strategic narrative: it reveals where and how the market is moving, while reserving detailed segmentation matrices and supplier-level volumes for the full report — intentionally, to encourage direct engagement and ensure you receive the most up-to-date, secured intelligence. For teams making 2026 decisions, this is the moment to transform substrate risk into strategic advantage.
Next steps
-
Contact PW Consulting to access the full IC‑Substrate Market report and interactive models, or to commission a bespoke supplier risk workshop tailored to your product and procurement footprint.
For detailed analysis of this topic, please visit the official page: IC-Substrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
GaN-on-Diamond Substrates to Hit $99.11M by 2032 at 17% CAGR - PW ConsultingPW Consulting: MMA Market to Reach USD 272.5M by 2032 at a 7.9% CAGR
By PW Consulting, 2026-07-22
GaN on Diamond Semiconductor Substrates: Strategic Imperatives for 2026
As demand for higher power density, lower thermal resistance, and reliable operation in extreme environments accelerates across satellite communications, defense electronics, and high-frequency telecom, GaN on diamond substrates are evolving from niche technology to a strategic materials platform. PW Consulting’s latest market study (base year 2025) quantifies a clear trajectory: the global market has more than doubled since 2020 and—at a compound annual growth rate of 17%—is forecast to expand materially through 2032. For 2026 planning cycles, this creates a decisive window for companies and public-sector buyers to convert technology advantage into commercial scale, but that window will close quickly without deliberate choices on supply, product architecture, and ecosystem partnerships.
GaN on Diamond Semiconductor Substrates Market
Market trajectory at a glance
- The GaN on diamond substrate market grew from the low tens of millions in 2020 to USD 33.0 Million in 2025, reflecting accelerating adoption in RF power, satellite comms, and defense. Early commercial traction and government contract awards underpin that progression.
- Our baseline projection shows a sustained expansion to roughly USD 99.11 Million by 2032, driven by a mix of defense procurement, satellite constellation rollouts, and commercial RF power amplification needs that favor diamond’s thermal performance.
- With an underlying CAGR of 17% across the forecast window, the market transitions from R&D-led purchases to volume-driven commercialization over the next several years—creating investment timing risk that favours early movers with disciplined execution.
Why 2026 is a strategic inflection point
- From a technology lifecycle perspective, 2026 is the moment when demonstrated device-level performance (thermal conductivity, power density, and reliability) converges with first industrial efforts to scale diamond wafer production. Firms that resolve scale economics or secure privileged supply lines will gain meaningful time-to-market advantage.
- Public funding and defense procurement cycles (notably DARPA and DoD programs) are actively pulling GaN on diamond into mission-critical roadmaps. Contract wins in 2024–2025 have already created near-term demand visibility that suppliers and system integrators should incorporate into capacity planning for 2026.
- Geopolitical supply considerations and concentration in upstream diamond synthesis capacity create both risk and opportunity: regionalization of supply (e.g., recent consortium and joint-venture builds) will alter sourcing strategies and raise the value of onshore or allied-country production footprints.
Competitive landscape and strategic positioning
The market remains oligopolistic but not monopolized—our concentration metrics indicate that the top three suppliers control a meaningful but not overwhelming share of market revenue, with the top five expanding that influence. This structure produces distinct strategic profiles:
GaN on Diamond Semiconductor Substrates Market
- Element Six (Didcot, UK)—a materials-technology incumbent with a deep portfolio in synthetic diamond substrates. Their recent launch of ultra-high-purity single-crystal wafers reinforces a premium product strategy targeted at RF and power device makers that prioritize thermal performance and device lifetime.
- Akash Systems (California, USA)—a specialist with a focus on satellite communications and applications requiring diamond-enabled cooling. Recent public funding awards enhance their ability to scale R&D into flight-qualified hardware.
- Qorvo, Inc. (Greensboro, USA)—an integrated device maker that has moved GaN on diamond into power amplifier products, using system-level integration to capture value beyond raw substrates.
- RFHIC (Anyang, South Korea), Coherent Corp. (San Jose), and Blue Wave Semiconductor (USA)—each brings complementary capabilities, from epi-wafer supply to application-specific commercialization, creating a competitive map where materials suppliers, device manufacturers, and system integrators compete and partner simultaneously.
Recent strategic moves—acquisitions by device incumbents, JV-based capacity expansions in Asia, and product launches focused on single-crystal diamonds—indicate that firms are pursuing both vertical integration and regional redundancy as primary risk mitigations. For prospective entrants and incumbent suppliers alike, the strategic choice is whether to compete on material purity and substrate IP, on device integration and system value capture, or on rapid capacity build-out supported by government incentives.
GaN on Diamond Semiconductor Substrates Market
Supply chain dynamics and risk factors
- Manufacturing complexity: Chemical vapor deposition (CVD) diamond synthesis and bonding processes remain capital- and know-how-intensive. High per-wafer fabrication costs and yield sensitivity to process variation limit near-term price erosion, constraining broad-based cost-down in 2026 unless new manufacturing breakthroughs reduce unit costs.
- Capacity constraints: Global diamond wafer production is concentrated and modest in absolute scale. Even with announced investments and consortia forming to increase regional capacity, lead times for qualified production capacity remain significant—making inventory and contractual levers critical negotiation tools.
- Geopolitical and regulatory headwinds: Supply chain snarls tied to geopolitical tensions have already created regional imbalances in substrate availability. Concurrently, defense-driven specifications and contracting (e.g., DARPA/DoD programs) accelerate specialized demand that will prioritize qualified, certified suppliers and may fragment the market for national-security reasons.
- Cost structure: The high cost of diamond wafers—driven by synthesis energy intensity and stringent quality controls—means buyers will face trade-offs between performance uplift and bill-of-material increases. Transitioning from prototype to producible architectures requires engineering that minimizes added system cost while preserving the thermal advantages.
Strategic playbook for 2026
We recommend a tiered set of moves depending on organizational posture:
- For device/system OEMs: Lock in supplier options via staged contracts (option to buy) to secure capacity without overcommitting capital; invest in co-development agreements that reduce integration risk; prioritize product roadmaps where thermal improvements enable new performance tiers or lifecycle cost reductions.
- For materials suppliers and manufacturers: Focus on yield improvement programs, reproducible process flows, and qualification pathways aligned with defense and space standards. Consider selective vertical integration or strategic partnerships to capture downstream margin and lock in long-term demand.
- For investors and M&A teams: Look for targets with defensible IP in diamond synthesis, bonding technologies, or device-level process recipes. The next 12–24 months are an inflection window where technology valuation will reflect near-term qualification wins and contractual runway rather than long-term volume forecasts alone.
- For public-sector procurement and policy makers: Use contracting mechanisms and funding programs to de-risk domestic capacity builds (matching grants, offtake guarantees, and coordinated standards development) while ensuring competition and export controls are balanced with industrial capabilities.
What PW Consulting’s report delivers (practical, actionable content)
Our full industry study is structured to support operational decisions for 2026 planning cycles and includes the following deliverables:
- Granular market sizing and demand scenarios with a transparent methodology from historical (2020–2025) to forecast (2026–2032).
- Detailed supplier and technology landscape maps, including supplier capability matrices, technology readiness assessments, and pathway analyses for single-crystal versus polycrystalline approaches.
- Supply-chain diagnostics and mitigation playbooks—dual-sourcing templates, inventory hedging strategies, and a staged-capex model for capacity expansion.
- Commercial go-to-market frameworks for device makers and substrate suppliers: pricing sensitivity models, contract structures preferred by defense customers, and channel strategies for satellite and telecom verticals.
- M&A and partnership playbooks that prioritize IP, scale economics, and route-to-market advantages, including valuation benchmarks and integration risk checklists.
- Regulatory and contracting briefings specific to defense and space procurement, with recommended compliance pathways and certification timelines.
Note: this summary intentionally omits core segmented figures—such as regional market shares, application-level revenue splits, and some price curves—to preserve the premium value of our data products. The full report contains these granular breakdowns, downloadable datasets, and interactive scenario tools designed to be integrated into corporate planning models.
Concluding counsel
GaN on diamond substrates represent a high-leverage node of differentiation for companies operating at the intersection of RF power, satellite communications, and defense systems. The technology’s pathway from specialist material to industrial input will be decided in the 2025–2027 window: those who secure qualified supply, align product roadmaps to cost-efficient manufacturing, and exploit policy-driven demand will capture outsized value. PW Consulting’s market forecast—backed by a 17% CAGR through 2032 and detailed scenario analysis—serves as the empirical foundation for those choices.
To access the complete dataset, granular segmentation, and executable templates that underpin the above insights, visit our GaN on Diamond Semiconductor Substrates Market page or contact PW Consulting’s advisory team for a tailored briefing aligned to your strategic priorities for 2026.
For detailed analysis of this topic, please visit the official page: GaN on Diamond Semiconductor Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Data Diodes Market 2026: A Strategic Primer for Enterprise Decision-Makers
As organizations confront an elevated threat environment and a more prescriptive regulatory landscape, one-way transfer technologies — commonly known as data diodes — have moved from niche hardening measures into mainstream cyber-architecture plays for high-assurance segmentation. PW Consulting’s latest market study (base year 2025) shows the Data Diodes Market on a steady expansion path, growing at a compound annual rate of roughly 7.15% over our forecast horizon and projecting meaningful uplift into the early 2030s. For leaders planning investments in 2026, the research translates market trajectories into procurement strategies, integration blueprints, and operational KPIs designed to reduce risk while optimizing spend.
Data Diodes Market
Why 2026 Is a Pivotal Year for Data Diode Decisions
- Regulatory and standards alignment is accelerating. Governments and critical-infrastructure operators are continuing to codify unidirectional transfer as an accepted control (for example, in OT/ICS guidance aligned with NIST 800-82 and equivalent national frameworks). Vendors are responding with certifications targeted at graded classification and industrial standards, which materially affects acceptable supplier lists and deployment timelines.
- OT/IT convergence demands practical, low-risk integration patterns. Utility, transportation, and manufacturing operators are increasingly moving operational metrics and telemetry to centralized analytics and cloud stacks. The safest pragmatic pattern for many controlled environments is a one-way bridge — the data diode — coupled with sanitization and protocol-aware gateways.
- New form factors and use cases are expanding addressable demand. The market is no longer driven solely by large data-center cross-domain transfers. Portable incident response devices, DIN-rail industrial modules, TEMPEST-graded products and software-hardware hybrids are broadening procurement categories and shortening buy cycles for targeted pilots.
- Labor and operational economics favor automation. Manual data transport remains surprisingly costly to operate; industry analyses show routine physical-media workflows can impose recurring labor and logistics costs that are non-trivial on a per-site basis. Shifting to controlled automated transfer reduces both human exposure and long-run operating expense — a near-term ROI lever for capital approval.
What the PW Consulting Report Provides — Practical, Actionable Assets
- Executive decision pack: One-page investment thesis and board-ready talking points that map stated risk appetite to suggested adoption cadence.
- Market sizing & forecast methodology: Transparent assumptions, sensitivity testing, and scenario outputs based on our 2020–2025 historical baseline and the 2026–2032 projection window to help internal finance teams stress-test budgets.
- Vendor evaluation framework: A scored rubric covering assurance level (certifications and lab attestations), throughput and latency characteristics, protocol support (OT protocols such as OPC UA/MQTT, SCADA integrations), ruggedization and form factor, and total cost of ownership components.
- Procurement and RFP templates: Pre-built requirements language that captures minimum acceptable certifications, tamper-evidence, service-level commitments, and integration obligations for SI/OT vendors.
- Integration playbooks: Step-by-step deployment patterns for typical OT-to-IT flows, incident response workflows using portable diodes, and secure telemetry pipelines to cloud analytics — complete with monitoring and validation checklists.
- Risk and compliance mapping: Matrixes aligning diode solutions with common standards and national certifications, and guidance on where to escalate for classified-data transfers.
- Financial models: TCO calculators and payback simulations that explicitly incorporate labor-savings, incident-cost avoidance, maintenance, and upgrade cycles.
- Use-case deep dives: Industry-focused modules (energy, defense, transportation, manufacturing, government) that blend technical architectures with procurement timing and stakeholder RACI matrices.
Competitive Landscape — Who Matters and Strategic Implications
The competitive field is composed of specialized one-way hardware vendors, industrial-automation-focused manufacturers, and cybersecurity software firms that bundle diode hardware with protocol-aware services. Several vendor archetypes dominate strategic thinking for 2026 deployments:
Data Diodes Market
- High-assurance defense specialists: Firms offering government-validated protocol filtering diodes and high-end certifications are natural choices for national defense, classified cross-domain transfer, and critical national infrastructure programs. These suppliers compete on assurance ratings, certification pedigree, and integration experience for classified workflows.
- Industrial and OT integrators: Companies with DIN-rail modules, ruggedized units, and native support for industrial protocols (e.g., OPC UA and MQTT) position themselves for distributed deployments across substations, trackside, and process plants.
- Software-hardware hybrids: Vendors pairing one-way hardware with sanitization, file-scaling, and orchestration software focus on pragmatic IT/OT isolation and cross-domain replication for enterprises that prioritize operational continuity.
- Form-factor innovators: Emerging products such as pocket-sized incident-response diodes and purpose-built railway modules are shortening project lead times and enabling new response and forensics workflows.
Representative market signals to monitor:
Data Diodes Market
- Product & certification moves: The recent introduction of pocket-sized incident-response diodes and the verification of high-throughput protocol-filtering diodes by national authorities signals vendor maturity and faster operational adoption.
- Vertical-specific launches: Solutions engineered for railway EN compliance or TEMPEST-graded modules for defense customers indicate increasing vertical granularity and procurement-defined productization.
- OT software integrations: Vendor integrations with major SCADA/OT platforms demonstrate routable, vendor-neutral patterns that reduce integration risk.
Vendor Notes — Strategic Positioning to Watch
- Owl Cyber Defense: Focused on U.S. Government-validated protocol filtering diodes and a newly introduced portable incident-response diode. Their portfolio is notable for high-throughput validated protocol enforcement and emerging OT integrations that shorten deployment cycles for utilities.
- OPSWAT: Emphasizes file sanitization and unidirectional gateways for IT/OT isolation; its approach is complementary when organizations need layered sanitization plus one-way transport.
- Advenica: Delivers devices certified to national armed forces standards and has recently launched domain-specific units for railway trackside use — a clear signal of vertical productization.
- Patton Electronics: Provides industrial-grade DIN-rail data diodes with explicit support for industrial messaging stacks, tailoring for plant-floor and substation topologies.
- Waterfall Security Solutions & Fibersystem AB: Offer integrated and TEMPEST-grade options respectively, where the purchase decision turns on environmental constraints and the need for electromagnetic security.
- Large defense primes & integrators: Players offering EAL-level certified diodes and cross-domain solutions are positioned for procurement lists in defense and high-classification programs.
Recommended 90 / 180 / 360-Day Roadmap for 2026
- 0–90 days: Complete an inventory of cross-domain flows and map data sensitivity. Run a short-list vendor RFI using PW Consulting’s template; prioritize pilots where operational risk and data volume justify immediate action.
- 90–180 days: Execute one or two pilots (a telemetry pipeline and an incident-response use case). Validate protocol compatibility, logging fidelity, and integration with SIEM and OT monitoring stacks.
- 180–360 days: Formalize procurement terms, include certification and sustainment clauses, and scale to additional sites. Operationalize monitoring, and implement maintenance and upgrade SLAs tied to availability and assurance testing.
How to Make the Business Case
Beyond erosion of attack surface, the business case for data diodes should be couched in avoidable-incident economics, compliance exposure reduction, and measurable operational savings. For many sites, replacing manual media transfer workflows with controlled one-way transfer reduces recurring labor exposure and mitigates the human element in cross-domain handoffs. PW Consulting’s TCO models quantify these levers and show that, depending on the operational profile and the chosen deployment form factor, payback can be achieved through a combination of reduced manual handling costs, fewer incident-response hours, and avoided regulatory penalties.
What We Withhold in This Preview — And Why It Matters
This briefing intentionally demonstrates the market’s contours, vendor dynamics, and practical pathways to adoption while withholding granular segmentation tables, region-by-region share numbers, and detailed vendor scorecards. Those segmented figures — which include detailed breakdowns by region, product type, and application — are core, monetized assets of the full PW Consulting study. If you are evaluating vendor shortlists, vendor lock-in risks, or exact procurement volumes and pricing benchmarks, the complete report provides the necessary line-level detail, side-by-side comparator matrices, and downloadable procurement templates to operationalize a buying decision.
Next Steps — How to Use This Intelligence
- Request the full vendor scorecards and the specific regional and application segmentation to finalize your supplier due diligence.
- Deploy our RFP templates and integration checklists during vendor evaluation to reduce procurement cycles and ensure minimum certification requirements are met.
- Use the financial model in the full report to run your expected-state vs. baseline-state TCO analysis for board approval.
In short, the Data Diodes Market is transitioning from specialized defense tooling to a mainstream control pattern for risk-averse enterprises. With the market expanding at a steady rate and vendors delivering both higher-assurance and more deployable form factors, 2026 is the moment for decisive, well-scoped pilots that link security outcomes to operational metrics. For the complete segmented intelligence, vendor rankings, and procurement-ready artifacts, access the full PW Consulting study and accelerate your 2026 roadmap with confidence.
For detailed analysis of this topic, please visit the official page: Data Diodes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DNS Security Software to Reach USD 310M by 2032, Growing at 8.9% CAGR
By PW Consulting, 2026-07-22
DNS Security Software Market 2026: Strategic Insights for Senior Decision-Makers
Executive teaser
As organizations move deeper into cloud-first architectures and adversaries weaponize DNS as an attack surface, DNS security has shifted from a niche IT concern to a board-level strategic priority. PW Consulting’s forthcoming DNS Security Software Market report positions CISOs, procurement leads, and technology strategists to make decisive 2026 investments. Drawing on a rigorous historical baseline and a multi-scenario forecast, this research translates market dynamics into actionable choices — while deliberately reserving the granular segment tables for the full report to preserve competitive intelligence value.
DNS Security Software Market
Why 2026 is an inflection point
-
Market momentum: From a disciplined historical base through 2025, the DNS security market has expanded steadily; our dataset shows a clear trajectory that accelerates through the forecast window. In nominal terms, the market grew from the low hundreds of millions (USD, Million) in 2020 to a materially larger base by 2025, and is projected to continue expanding to the end of the forecast period.
DNS Security Software Market -
Compound growth: The market’s projected compound annual growth rate (CAGR) of 8.9% underpins the transition from tactical adoption to strategic procurement, emphasizing the need for multi-year vendor roadmaps and procurement frameworks that capture future functionality (AI detection, encrypted DNS, posture management).
DNS Security Software Market -
Regulatory catalysts: New procurement and security guidance — including mandates for support of encrypted DNS protocols for federal resolvers and guidelines advocating AI-enabled DNS defenses for critical infrastructure — will materially accelerate enterprise adoption cycles and change vendor selection criteria.
What this research delivers (practical, operational outputs)
This study is built to be a working tool for 2026 decision-making. It is organized to provide prescriptive outputs that translate research into procurement-ready artifacts:
-
Market sizing and trend diagnostics — a validated historical series and scenario-based projections (base year 2025; forecast period 2026–2032) to underpin multi-year budget planning and vendor negotiations.
-
Buyer’s playbook — differentiated procurement checklists keyed to organization size, cloud posture, and regulatory exposure; decision matrices for cloud-native versus hybrid deployments; and TCO modeling templates you can re-parameterize with internal metrics.
-
Vendor benchmarking — qualitative and quantitative scoring across functional domains (resolver security, DNS firewalling, DDoS resilience, DNS posture management, telemetry and threat intelligence, and integration maturity) to simplify shortlist creation and RFP design.
-
Use-case deep dives — operational runbooks for common enterprise scenarios (multi-cloud DNS governance, branch/remote worker DNS protection, service provider partnerships), including example IR workflows and SLA expectations.
-
Regulatory compliance mapping — alignment matrices that map product capabilities to the latest regulations and guidance, helping teams document procurement rationales for auditors and boards.
-
Investment and M&A signals — market concentration analysis, growth pockets, and capability white-spots that inform build-vs-buy deliberations and inorganic growth plays.
High-level market characterization
The DNS security market is neither a pure commodity space nor a tightly concentrated oligopoly. Our concentration analysis indicates a market structure where a limited set of global incumbents exert meaningful influence, but specialist and regionally focused vendors continue to occupy white spaces important to particular buyer profiles. The combination of an expanding overall market and a moderate top-player concentration creates opportunities both for incumbent defense (feature expansion, partnerships) and for new entrants to secure niche positions through rapid innovation.
Competitive landscape — who to watch and why
-
Cisco Systems (San Jose, CA): Cisco Umbrella remains a reference architecture for cloud-delivered DNS-layer security tied to a broad security platform. Strengths: integrated threat intelligence, scale in enterprise accounts, and a strong channel ecosystem for enterprise uptake.
-
Infoblox (Santa Clara, CA): Known for protective DNS and Threat Defense solutions, Infoblox combines DNS appliance heritage with managed and cloud capabilities — making it attractive for organizations that require tight control over DNS infrastructure and lifecycle management.
-
Cloudflare (San Francisco, CA): Cloudflare’s resolver and DNS firewall services bring high-performance global edge delivery, built-in DDoS mitigation, and simple developer-oriented deployment models — a compelling fit for digital-native enterprises seeking rapid time-to-protection.
-
Akamai Technologies (Cambridge, MA): With Edge DNS and recent investments in DNS Posture Management (launched June 2025), Akamai is extending DNS protection into asset discovery and multicloud governance — a notable move for security teams looking to reduce blind spots across hybrid environments.
-
F5 Networks (Seattle, WA): F5’s BIG-IP DNS and associated modules emphasize DNS-level control with advanced traffic engineering and protection capabilities — valuable for organizations with complex load balancing and on-premises service delivery needs.
-
Verisign (Reston, VA): Verisign’s managed DNS and security services combine authoritative DNS experience with enterprise-grade DDoS defenses and threat intelligence — often selected by critical infrastructure and high-availability use cases.
-
Neustar (Reston, VA): Neustar UltraDNS positions itself on authoritative DNS resilience and security features, addressing enterprises and service providers needing predictable performance under stress.
Recent partnership and product activity — for example, IGIT’s collaboration with NS1 and Cisco for agile EMEA deployments and Akamai’s 2025 posture management launch — illustrate two market dynamics we flag in the report: (1) vendors are closing integration gaps through partnerships, and (2) posture and visibility features are rapidly rising as purchase drivers.
Dynamics shaping vendor selection and product roadmaps
-
Encrypted DNS becomes a procurement must-have. Executive-level procurement requirements (notably in public sector contexts) are already elevating encrypted DNS protocol support from “nice-to-have” to “mandatory” for resolver vendors.
-
AI-enabled detection is transitioning from lab demos to procurement criteria. CISA guidance and national cybersecurity strategies are encouraging adoption of analytics that can detect DNS anomalies linked to sophisticated infrastructure attacks.
-
Visibility and posture management matter as much as blocking. Teams increasingly prioritize asset discovery, continuous configuration assessment, and automated remediation in addition to traditional prevention functions.
-
Hybrid and cloud-native coexistence. Procurement decisions must account for mixed architectures: cloud-first resolvers, on-prem authoritative controls, and edge delivery models each carry trade-offs in cost, latency, and security controls.
Strategic recommendations for 2026 planning
-
Move from point solutions to platform thinking: When specifying DNS security, define the broader controls you need (resolver, authoritative, posture, telemetry) and prioritize vendors that demonstrate a clear integration roadmap rather than a single-feature advantage.
-
Embed regulatory requirements into RFP templates: Require encrypted DNS support and AI-capable telemetry by default where applicable; build contractual clauses that reflect evolving federal and sectoral guidance.
-
Adopt a phased deployment playbook: Start with high-risk domains and remote-user protections, then expand into posture management and multi-cloud governance, using performance and failure-mode metrics defined upfront.
-
Use vendor scorecards defensibly: Weight resiliency and threat intelligence lineage heavily for high-availability and critical infrastructure contexts; prioritize integration depth for organizations with rich security stacks.
-
Plan for supplier lifecycle: Given the market’s moderate concentration and the presence of strong incumbents, prepare contingency plans (multi-vendor fallbacks, exit clauses) to avoid single-vendor lock-in for mission-critical DNS services.
How PW Consulting’s report helps you act
Our full report delivers the raw forecast model, executable procurement artifacts, and a vendor capability matrix that teams can operationalize in 60–90 days. The research is designed to reduce procurement cycle time, de-risk vendor selections, and align technology choices with regulatory expectations and adversary trends. To preserve strategic value, we present detailed market splits, regional and deployment breakdowns, and vendor-specific scorecards only in the complete report package.
Next steps
For CISOs, procurement heads, and strategy teams preparing 2026 budgets: use the high-level frameworks and recommendations above to sketch your preferred architecture and shortlist. Then consult the full PW Consulting DNS Security Software Market report for the granular segmentation, vendor scoring, and procurement-ready templates required to finalize vendor selection and contract negotiations.
Accessing the comprehensive dataset and appendices will provide the granular visibility (including historical series, supplier concentration analytics, and implementation playbooks) required to execute with confidence. PW Consulting’s research is built not to tell you which supplier to pick, but to ensure your choice aligns with a defensible, auditable, and future-proof strategy.
For detailed analysis of this topic, please visit the official page: DNS Security Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


