



Category: IT & Electronics
PW Consulting Forecast: Wireless Communication Intelligent Module Market to Hit USD 61.87 Billion by 2032, Growing at a 13.5% CAGR
By PW Consulting, 2026-08-18
PW Consulting: Strategic Outlook — Wireless Communication Intelligent Module Market 2026 Preview
As PW Consulting publishes its latest market research on the Wireless Communication Intelligent Module market, this briefing highlights the report’s strategic value for executives preparing decisions in 2026. The industry is at an inflection point: advancing chipset platforms, shifting regulatory regimes, and steepening infrastructure costs are combining with robust end-market demand to reshape competitive advantage. Our full report provides the granular scenarios, vendor scorecards, and playbooks that senior leaders need; this press release summarizes the high‑level findings and the concrete ways decision-makers should act in the coming 12–18 months.
Worldwide Electric Spray Nasal Washers Market
Executive summary: Why this report matters now
Between 2020 and 2025 the global Wireless Communication Intelligent Module market grew rapidly, reflecting broad IoT adoption, automotive telematics rollouts, and enterprise digitalization. Our market model shows overall sector expansion continuing into 2026 and beyond, with a multi-year compound annual growth rate (CAGR) of 13.5% across the 2026–2032 forecast window. By the 2026 base year in our analysis, the total market scale has moved into a new band that requires companies to shift from volume-driven strategies to differentiated, software-enabled value propositions.
3D Mining Software Market
For 2026 business planning, this means two imperatives: (1) secure technological pathways that map to 3GPP releases and emerging connectivity modalities, and (2) harden supply‑chain and cost models to absorb upstream inflation and infrastructure-driven price pressure. Executives that use our scenario-tested guidance will be better positioned to allocate R&D, prioritize certification pipelines, and select partners for scale.
Worldwide Double Valve Moka Pots Market
Market trajectory and high‑level metrics
Our top‑line model — built from five years of historical observation (2020–2025) and extended through 2032 — quantifies the market’s momentum and the durability of growth drivers. After accelerating from the mid‑teens in the earlier half of the decade, the market reaches a new plateau in 2026 consistent with service densification, new device classes, and upgrades to industrial connectivity. The forecast to 2032 incorporates multiple technology cycles and yields a robust outlook for module manufacturers, systems integrators, and chipset partners alike.
Concentration dynamics are notable: market share is meaningfully clustered among a small number of global vendors, with the top commercial participants collectively controlling a majority of revenue. This concentration creates both opportunity and risk — scale benefits for incumbents, and white-space openings for challengers that can combine cost, certifications, and application expertise.
Competitive landscape — who moves the market
Our competitive review evaluates product roadmaps, go‑to‑market models, certification footprints, and channel strategies for leading module vendors and ecosystem players. The report’s vendor dossiers include independent assessments of technology readiness, platform diversity (cellular, GNSS, short‑range, LPWAN), and aftermarket services such as lifecycle management and security.
-
Quectel Wireless Solutions Co., Ltd. (Shanghai): Positioned as a global leader in cellular IoT modules, with recent strides expanding 5G RedCap and Release 17 support. Quectel’s broad certification activity underscores its priority on rapid market access for device OEMs.
-
Fibocom Wireless Inc. (Shenzhen): Focused on integrated CPE and Wi‑Fi innovations; recent product introductions show convergence of cellular and Wi‑Fi advancements into single-box customer premises solutions.
-
u‑blox Holding AG (Thalwil): Known for integrated positioning and communications modules, u‑blox continues to target automotive and industrial OEMs with GNSS‑integrated platforms and short‑range connectivity expertise.
-
Telit Cinterion (Irvine): An end‑to‑end IoT supplier leaning into high‑reliability industrial and transportation use cases; recent 5G NR module launches and trade show demonstrations emphasize mission‑critical connectivity.
-
Sierra Wireless / Semtech (Canada/USA): Concentrates on industrial broadband and M.2 5G module segments, where integrated router and module strategies matter to infrastructure customers.
-
SIMCom (Shanghai), Murata (Japan), Thales (France), and operator‑affiliated suppliers (e.g., China Mobile IoT Company): Each brings a differentiated mix of cost engineering, embedded form factors, certification breadth, or vertically integrated distribution — creating multiple axes of competition.
Recent 2026 product activity — including multiple 5G NR and RedCap introductions, Wi‑Fi 8 CPE integrations, and targeted certifications for regional markets — signals a calendar year in which suppliers are racing to validate new silicon and close partner ecosystems. Our report catalogs these launches and evaluates their commercial implications for module adoption curves and OEM BOM strategies.
Industry dynamics shaping 2026 commercial choices
Three non‑technical forces will materially influence executive decisions this year:
-
Regulatory change: 2026 regulatory moves — notably U.S. initiatives to lower barriers for transitions from legacy networks to IP‑based infrastructures and legislative spectrum pipelines — are expanding medium‑ and long‑term capacity for IoT and broadband deployments. Our regulatory impact module models the timing of these changes and the implications for certification and regional go‑to‑market sequencing.
-
Infrastructure and input‑cost pressure: Price volatility in fiber and other upstream inputs — exemplified by sharp increases in certain fiber‑optic cable costs — combined with survey evidence of rising fiber deployment expenses, is driving network operators and module OEMs to revisit capital allocation, site economics, and total cost of ownership assumptions for connectivity solutions.
-
Supply‑chain resilience: Lead times, materials cost swings, and the need for multiple certified variants require firms to adopt stress‑tested sourcing strategies. The report includes supplier‑tier risk assessments, dual‑sourcing scenarios, and inventory optimization playbooks tailored to module manufacturers and OEMs.
What the PW Consulting report contains — practical, decision‑ready deliverables
Our deliverable suite is designed to be operational from day one. Highlights include:
-
Market model and forward‑looking TAM: A transparent market model spanning 2020–2032 with configurable scenarios for technology adoption rates, pricing trajectories, and application mix (note: the public summary intentionally withholds certain subsegment datapoints to preserve analytical value; clients can access full granularity through our source portal).
-
Vendor scorecards: Multi‑factor evaluations covering technology depth, certifications, field reliability, go‑to‑market reach, and service capabilities.
-
Go‑to‑market playbooks: Playbooks tailored to module vendors, OEMs, carriers, and systems integrators — covering pricing strategies, channel partnerships, certification sequencing, and vertical prioritization.
-
Regulatory & spectrum impact analysis: Scenario maps showing how recent FCC and legislative actions could shift capacity timelines and market windows by region and use case.
-
Supply‑chain stress tests: What‑if simulations for raw‑material shocks, certification delays, and labor‑driven deployment cost surges, with recommended mitigation measures.
-
M&A and partnership roadmap: Strategic options based on market concentration dynamics, technology adjacency, and the economics of scale for connectivity platforms.
Strategic recommendations for 2026 decision-makers
Executives should prioritize three near‑term actions to translate market growth into sustainable advantage:
-
Prioritize platform longevity and certification agility. Invest selectively in modules and reference platforms that support current 3GPP releases and have clear upgrade paths for subsequent releases. Early certification in target markets shortens commercial ramp time for OEM customers.
-
Hedge supply and cost risk. Implement dual‑sourcing for critical components, revisit flexible manufacturing contracts, and model scenarios that incorporate rising fiber and deployment costs so commercial bids reflect true TCO.
-
Differentiate with software and services. Margin expansion will come from device‑centric software, security services, and lifecycle management offerings. Consider bundling connectivity‑as‑a‑service tiers and post‑shipment support to lock in OEM relationships.
How to use this research in corporate planning
Procurement leaders can use the supplier risk matrices to rework contract terms. Product teams should align roadmaps to the module readiness and certification calendars we enumerate. Strategy and corporate development teams will find the M&A decision framework useful for prioritizing bolt‑on targets or strategic partnerships. Finally, sales leaders will gain from the vertical prioritization playbooks that balance short‑term revenue capture with long‑term strategic positioning.
Looking ahead — positioning for the next technology inflection
The 2026 planning horizon is one of both consolidation and creative disruption. While incumbent module vendors retain advantages in volume, certification, and channel access, rapid innovation at the edge — including new low‑power modalities, integrated positioning, and hybrid connectivity stacks — will enable fast followers with focused execution to carve durable niches. Our forecast and scenario work allow clients to stress test these outcomes and select a portfolio of strategic initiatives that hedge downside while capturing upside.
Accessing the full analysis
This press release outlines the strategic relevance of PW Consulting’s Wireless Communication Intelligent Module market research. The full report contains the detailed market tables, segment‑level forecasting, vendor profiles, and actionable playbooks that corporate leaders need to operationalize these insights. To preserve the report’s value to paying clients, select subsegment datapoints and proprietary models are available in the complete document on our website.
For board briefings, commercial planning workshops, or bespoke advisory support, PW Consulting’s industry practice is available to translate the report’s findings into prioritized initiatives and implementation roadmaps for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Wireless Communication Intelligent Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Flashcard App Market Projected to Expand at a Robust 13% CAGR Through 2032
By PW Consulting, 2026-08-18
Flashcard Apps Market 2026: Strategic Imperatives from PW Consulting’s New Market Flash Report
PW Consulting’s latest Flashcard APP Market report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes quantitative foresight and actionable strategy for executive teams planning investments and product roadmaps in 2026. The market has more than doubled in scale since 2020 and is set to continue expanding at a robust compound annual growth rate of 13.0% through 2032. This release distills the report’s strategic value for product, M&A, and commercial leadership while preserving the full granular intelligence for subscribers and site visitors.
Online Payment Platform Market
Why the 2026 Decision Window Matters
The flashcard app category is maturing from a niche study aid into an embedded layer of digital learning ecosystems. Market sizing in our report shows a clear trajectory: a material acceleration in monetization and institutional adoption across education and professional learning between 2023 and 2026, with the total market more than doubling since 2020 and continuing on to near-term seven‑year forecasts. This macro momentum alters the investment calculus in three ways:
Germacrene D Market
- Time-sensitivity: Firms that finalize product-market fit and platform integrations in 2026 capture disproportionate share as network effects and content libraries deepen.
- Capital allocation: Steady high-single-digit to low-double-digit CAGR implies attractive IRR for platform and content plays, but execution risk favors experienced operators and well-capitalized entrants.
- Regulatory and cost dynamics: Data privacy and cross-border compliance are increasing operating costs and shaping architectural choices (see Dynamics section below).
Report Scope and Practical Outputs
The Flashcard APP Market report is designed as a practical playbook for commercial and product teams. It combines rigorous topline modeling with implementation-grade deliverables that support 2026 decision-making, including:
GPU Server Rental Service Market
- Topline market sizing and a 2026–2032 forecast model (presented in USD, revenue units in Millions) with sensitivity scenarios covering low-, base-, and high-growth paths.
- Competitive landscaping and vendor scorecards with strengths/weaknesses mapped to product, go-to-market, content assets, and developer ecosystems.
- A monetization matrix comparing subscription models, freemium funnels, institutional licensing, and content marketplace strategies—paired with conversion benchmarks.
- Actionable GTM playbooks for three archetypes: platform incumbents, niche-specialist entrants (e.g., medical/credential prep), and embedded-LMS partners.
- M&A screening framework with target attributes, valuation multiple bands, and integration checklists tailored to acquisition and partnership plays.
- Operational impact analysis: TCO templates that quantify incremental compliance and hosting costs under varying data residency and encryption architectures.
To preserve competitive advantage for our clients, the public summary intentionally omits detailed regional and end-user splits and other sensitive tables; these are available in full to subscribers and on the report landing page.
Competitive Landscape — Who Matters and Why
The flashcard ecosystem sits at the intersection of open-source tooling, large consumer platforms, and vertically focused startups. The market concentration metrics in the report reflect a category where a small number of players hold meaningful share but specialized offerings and open ecosystems continue to create pockets of contestability. Our consolidated competitive analysis focuses on several incumbent and emergent players:
- Open-source incumbents that emphasize customizability and offline-first workflows. These solutions remain essential for users who prioritize privacy, extensibility, and local data ownership. Recent stewardship changes in the open-source community have reinforced sustainability and stewardship pathways for these projects.
- Large consumer platforms that couple UGC (user-generated content) libraries with AI-driven study aids and deep integrations into chat and collaboration tools. Their strength is scale: a vast content base, classroom integrations, and growing AI toolkits that automate content generation and personalization.
- Confidence- or evidence-based platforms that optimize for long-term retention through proprietary algorithms. These providers appeal to professional and exam-prep segments where measurable learning outcomes justify higher price points.
- Note-taking/knowledge-management hybrids that convert structured notes into spaced-repetition workflows—appealing to power users who want single-pane personal knowledge systems.
- AI-first content generators that auto-transform documents, slides, and PDFs into study sets, compressing content prep time for both learners and instructors.
Recent industry events illustrate directional competitive moves: stewardship transitions in open-source projects to ensure sustainability; large-scale AI integration from dominant consumer platforms that embed card generation directly into conversational interfaces; and product updates from collaborative deck platforms that improve installer experience, search, and domain-specific content curation. Each development recalibrates the competitive map and the set of defensible moats.
Regulatory, Cost, and Infrastructure Dynamics
Three regulatory trends materially influence strategy and unit economics for 2026:
- Data privacy compliance: GDPR-level obligations have raised average storage and processing costs—industry studies indicate an increase on the order of ~20% for firms handling personal educational data—forcing architectural and pricing decisions.
- Cross-border access regimes: Legal constructs that permit governmental access to data hosted by domestic companies create tension with data residency promises and complicate EU–US compliance for U.S.-based vendors.
- Net neutrality and traffic treatment: While not a direct revenue lever, neutral traffic rules preserve equitable access but increase dependence on solid CDN and offline strategies to manage user experience under constrained networks.
For decision-makers, the clear takeaway is to prioritize privacy-by-design, include probabilistic cost buffers for compliance, and architect for encryption and granular residency controls—especially if targeting institutional contracts.
Strategic Recommendations for 2026 Executives
Our analysis yields five high-priority moves executives should consider in 2026 to secure advantage:
- Invest in AI augmentation, not just automation. Integrations that help users create, vet, and adapt cards—while surfacing confidence and retention metrics—drive both engagement and willingness to pay.
- Hedge platform risk with hybrid offerings. Combine lightweight offline/desktop capabilities with cloud-first sync and collaborative features to appeal to both privacy-conscious users and institutional buyers.
- Build compliance as a differentiator. Offer clear data residency options, exportable user data, and transparent access policies to win contracts from privacy-sensitive education institutions and healthcare buyers.
- Prioritize content partnerships over pure library accumulation. Strategic content licensing and co-branded decks for high-value verticals (e.g., medical, credentialing) deliver premium ARPU and reduce dependency on user-generated supply alone.
- Use M&A selectively to acquire community, content, or machine-learning capabilities—especially where consolidation can accelerate reach into vertical niches and reduce time-to-market for AI-enhanced features.
Signals to Watch and Tactical Triggers
We recommend monitoring four high-impact indicators through 2026 that should trigger tactical pivots:
- Enterprise license wins in higher education and corporate L&D—signal readiness to price and support institutional deployments.
- Adoption and retention lift from AI card-generation features—if AI increases short-term MAU and long-term retention, reallocate spend toward model ops and content moderation.
- Regulatory or legal shifts affecting cross-border data—immediate operational and contractual adjustments will be required if new rulings alter data access expectations.
- Consolidation events among the top competitive cohort—acquisitions that materially increase content or user scale should prompt defensible counter-strategies (partnerships or M&A).
What the Full Report Delivers (and What We Hold Back)
The public brief outlines the macro story and our strategic vantage. The full Flashcard APP Market report provides the complete, subscribable intelligence you need to execute in 2026:
- Comprehensive regional and end-user segmentation tables and scenario-driven financial models (revenue units in USD Millions), including downloadable spreadsheets for sensitivity testing.
- Detailed company profiles and product feature matrices, plus playbooks tailored to each strategic archetype and acquisition targets ranked by strategic fit and valuation guidance.
- Benchmarked metrics for monetization, engagement, and retention across product types and go-to-market models—useful for OKR and KPI setting in 2026.
- Legal and compliance checklist templates, hosting cost models, and an implementation roadmap to meet GDPR and cross-border access constraints with minimal disruption to growth.
Per the “trailer” principle, we intentionally withhold granular regional and application splits from this public summary. These detailed tables and model inputs are available in full on the PW Consulting report page for subscribers and clients.
Next Steps for Executives
For leaders preparing budgets, product roadmaps, or M&A agendas in 2026: allocate time this quarter to review the full model, run sensitivity scenarios against your unit economics, and engage PW Consulting for a tailored workshop. Our advisory practice can convert the report’s broad insights into firm-specific action plans—covering pricing experiments, partnership funnels, and acquisition diligence blueprints.
Contact PW Consulting through our corporate channels to request the full report and schedule a 2026 strategy workshop. The public brief above provides the directional narrative; the subscription report provides the decision-grade matrices you will use to execute.
For detailed analysis of this topic, please visit the official page: Flashcard APP Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Mental Health Counseling Market Poised for Expansion with an 8.12% CAGR, Finds New Report
By PW Consulting, 2026-08-18
Mental Health Counseling Service Market 2026: Strategic Priorities for Leaders — PW Consulting Market Intelligence Brief
Executive synopsis
PW Consulting’s latest market research — anchored on a detailed base year of 2025 and extending through 2032 — identifies the Mental Health Counseling Service Market as a structurally growing, opportunity-rich sector for health systems, payers, digital health platforms, and strategic investors in 2026. Our models show the market more than doubling from early-decade levels and continuing to expand at a projected compound annual growth rate of 8.12% over the 2026–2032 forecast window. For 2025 we estimate the market at approximately USD 16.5 billion; by 2032 our mid-case scenario projects a market size on the order of USD 28.5 billion. These headline trajectories are symptomatic of secular demand, delivery-model innovation, and shifting reimbursement and regulatory levers that will define actionable strategy in 2026.
Autonomous Digital Experience Management Market
Why this matters for 2026 decision cycles
Executives setting priorities for the coming 12–18 months must translate top-line growth into durable, risk-adjusted value. That requires early moves on six interlocking fronts:
Quantum Photonic Devices Market
- Workforce resilience: The sector faces severe labor constraints that will pressure capacity and cost baselines into the next decade.
- Reimbursement arbitrage: Recent policy changes are improving revenue prospects for outpatient behavioral services, making payer contracting and coding optimization immediate ROI opportunities.
- Delivery mix optimization: Telehealth and hybrid delivery models continue to reshape unit economics and patient acquisition dynamics.
- Employer and benefits innovation: Demand from employers for integrated mental health benefits is accelerating adoption and retention levers.
- Regulatory risk management: Federal and state-level policy actions in 2026 are altering the reimbursement and grant landscape; these must be scenario-planned.
- M&A and capability build: The market remains fragmentary, creating both roll-up and bolt-on opportunities for buyers seeking scale and clinical integration.
Data-driven context (what the numbers tell us)
PW Consulting’s longitudinal sizing shows a clear structural expansion: mid-decade values are materially higher than 2020 levels, driven by a combination of higher utilization, broader access through virtual channels, and increased payer investment in mental health benefits. The projected 8.12% CAGR for the forecast period is an industry-level lens that synthesizes utilization growth, price/reimbursement trends, and delivery model shifts — and it is the basis for our scenario valuations, channel prioritization and workforce planning benchmarks.
Polymer Heart Valves Market
Importantly, while headline growth is meaningful, the market’s competitive structure and operational constraints mean that growth capture is uneven. We have modeled provider-level margins under multiple payer mixes and delivery mixes and tested sensitivity to labor inflation and reimbursement adjustments — all of which are included in the full report’s interactive models.
Market dynamics shaping strategy in 2026
- Workforce shortages and labor cost pressure. HRSA projections indicate a substantial shortfall of licensed mental health professionals through the 2030s. PW Consulting’s demand-supply stress-testing aligns with HRSA’s view: material capacity gaps will increase per-visit labor costs and extend wait times unless organizations invest in alternative staffing models, apprenticeship pipelines, and clinician retention programs.
- Reimbursement evolution. Medicare’s 2026 adjustments — including an increased conversion factor for outpatient psychological services — alongside legislative momentum to boost reimbursement parity for allied mental health providers create near-term revenue tailwinds. These changes improve the payor economics of ambulatory counseling and facilitate new contracting approaches with employers and ACOs.
- Policy noise and funding shifts. Federal grant reconfigurations and program terminations in early 2026 have tightened community provider funding in certain regions. This increases the strategic imperative for diversified revenue (payer contracts, employer-sponsored programs, digital subscriptions) and for operational buffers in community-facing services.
- Telehealth regulatory continuity. Telehealth remains a cornerstone delivery channel with continuing policy extensions that sustain utilization. However, reimbursement and licensure nuances remain a critical execution risk for multi-state operators.
Competitive landscape: what leading players are doing
The competitive set is diverse — including clinic-based networks, virtual-first platforms, employer-focused vendors, and digital therapeutics companies. PW Consulting’s qualitative benchmarking highlights several common strategic postures:
- Integrated outpatient networks (example: LifeStance Health). Clinic-and-telehealth models focus on combining in-person continuity with virtual follow-up to shorten wait times and improve clinical outcomes. These operators prioritize clinician network expansion and payer contracting to drive stable revenue streams.
- Virtual-first incumbents (examples: Teladoc Health / BetterHelp, Talkspace). These firms optimize scale through direct-to-consumer channels, subscription pricing, and AI-enabled triage. Their strategic risks center on reimbursement dependence and clinician supply constraints as utilization grows.
- Hybrid local providers (example: Thriveworks). Emphasis on appointment accessibility and clinician experience positions them to capture demand from patients preferring continuity; their playbook is provider network depth and local brand recognition.
- Employer-centric platforms (examples: Lyra Health, Headspace Health). These firms structure B2B contracts, care navigation, and outcomes measurement to lock in enterprise customers — creating predictable recurring revenue but requiring strong ROI evidence for employers.
Across these archetypes, 2026 strategic moves we expect to accelerate include clinician recruitment and apprenticeship programs, vertical integration with psychiatric medication management services, deeper payer partnerships, and targeted M&A to acquire clinical capacity or technology capabilities.
Recent industry developments and strategic implications
- April 2026 strategic partnerships to expand psychiatric services illustrate an ongoing trend: providers are consolidating clinical capability to strengthen referral and medication-management pathways.
- Facility expansions announced in mid-2026 reflect continued public sector investment in crisis and rehabilitation capacity — a call to action for private providers to align service lines with state tendering and public contracting.
- Education and workforce innovations, including the launch of new apprenticeship programs, signal an emergent pathway to mitigate long-term clinician shortages; leaders should evaluate partnership models with academic institutions to create preferential hiring channels.
Actionable recommendations for 2026 strategic planning
Based on scenario testing and client engagements, PW Consulting recommends the following priority actions for organizations seeking to capture growth while insulating margins:
- Adopt a blended delivery playbook: invest in telehealth as a capacity lever while protecting in-person services for high-acuity and retention-critical cohorts.
- Accelerate workforce innovation: deploy apprenticeship programs, tiered clinician roles (peer specialists, behavioral health associates), and clinician retention incentives tied to productivity and outcomes.
- Lock in payer economics: renegotiate outpatient bundles and value-based contracts that reflect recent Medicare dynamics and anticipated parity improvements for allied providers.
- Pursue selective M&A for capability and geography: prioritize targets that offer clinical depth, employer contract books, or proprietary care navigation platforms rather than pure volume plays.
- Build employer-focused value propositions: quantify ROI (reduced absenteeism, improved productivity) and offer integrated navigation + outcome measurement to secure multi-year enterprise deals.
- Stress test regulatory and grant exposures: maintain contingency plans for grant funding volatility and model cash-flow impacts on community-facing services.
- Measure outcomes and cost per episode: invest in analytics to demonstrate clinical impact and cost-offsets — a precondition for premium contracting with payers and employers.
What’s included in the full PW Consulting report (practical takeaways)
The full report is structured for executive use and operational translation. It includes:
- A detailed market-sizing and forecasting engine with scenario toggles for reimbursement, labor cost, and delivery mix.
- Provider-level margin simulations and payer-reimbursement sensitivity analyses to inform contract negotiations.
- Practical go-to-market playbooks tailored to clinic networks, virtual platforms, and employer-facing vendors, including sales and clinical staffing models.
- Competitive profiles and strategic option matrices for the leading national and regional players.
- M&A screening criteria, valuation benchmarks, and an integration checklist focused on clinician retention and continuity of care.
- Regulatory and grant-risk matrix with mitigation strategies and state-level policy monitoring templates.
To honor the “trailer” principle: while this brief highlights strategic findings and operational implications, the full report contains the granular segmentation tables, provider-level benchmarks, and downloadable financial models that operational teams use to build 2026 budgets and three-year strategic plans.
Concluding perspective
As 2026 unfolds, organizations that treat mental health counseling as a strategic growth pillar — not just a social imperative — will unlock commercial and clinical value. Market expansion creates room for innovation, but realizing that potential depends on proactive workforce strategies, precise contracting, and disciplined integration of digital and in-person care. PW Consulting’s market intelligence provides the modeling, benchmarks, and implementation tools senior leaders need to convert the industry’s growth trajectory into resilient, scalable enterprise value.
Next steps
Executive teams preparing 2026 budgets and strategic plans should request PW Consulting’s full Mental Health Counseling Service Market report and accompanying financial models. The full deliverable includes interactive scenario tools and a confidential advisory session to translate findings into a prioritized action plan for your organization.
For detailed analysis of this topic, please visit the official page: Mental Health Counseling Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HSA Provider Market Poised for Rapid Growth — 11.55% CAGR Forecast Through 2032
By PW Consulting, 2026-08-18
Health Savings Account Provider Market 2026: Strategic Imperatives from PW Consulting’s New Market Report
As employers, financial institutions, benefits administrators, and fintechs finalize 2026 plans, Health Savings Accounts (HSAs) have moved from niche tax-advantaged instruments to a central pillar of employee financial and health benefits strategy. PW Consulting’s latest HSA Provider Market report (base year 2025) quantifies that transition and translates it into clear choices for boardrooms and product teams. The report models a market that expanded rapidly in the early 2020s and — under conservative assumptions — is set to continue growing at double-digit rates: a compounded annual growth rate of 11.55% across the forecast window. Our analysis, rooted in historical performance through 2025 and forward-looking scenarios to 2032, is designed to inform commercial strategy, M&A prioritization, and regulatory planning for 2026 and beyond.
Video Intercom Indoor Unit Market
Why 2026 Is a Strategic Inflection Point
HSAs are no longer simply a compliance checkbox. They are now a multifaceted tool bridging health benefits, retirement savings, and employee financial wellness. The market’s historical trajectory — with sustained year-over-year revenue expansion between 2020 and 2025 — and our forecast to 2032 signal not just larger addressable spend, but evolving buyer expectations around digital experience, investment choice, and interoperability with broader benefits ecosystems.
Spore Testing Incubator Market
For 2026 decisions, three dynamics converge to create urgency:
Business Security Systems Market
- Scale and capital attraction: the HSA market is rapidly aggregating assets and accounts, creating balance-sheet and fee-income opportunities for scaled incumbents and attractive exit prospects for investors in growth-stage platforms.
- Integration expectations: employers demand seamless interoperability across HSAs, FSAs, HRAs, payroll, and retirement systems — an integration frontier that benefits vendors with open APIs and strong partner networks.
- Regulatory baselines: 2026 IRS contribution limits and HDHP pairing rules remain an anchor for plan design; advisory teams must model policy sensitivity into product roadmaps and pricing.
Macro View: Market Size, Growth, and Concentration
PW Consulting’s model traces overall market revenue from the early 2020s through 2025 and projects forward to 2032. The market grew materially during the 2020–2025 period and, under our base case, continues to expand to reach nearly three times the 2020 scale by the end of the forecast window. At the heart of that expansion is steady account growth, rising asset balances, and increasing adoption of investable HSA balances by consumers.
Key high-level figures you will want on the dashboard:
- Documented historical expansion through 2025, followed by sustained projected growth across 2026–2032 at an 11.55% CAGR in revenue terms.
- An industry structure showing moderate concentration: the top three providers control a meaningful share of market flows, and the top five increase that share further — a dynamic with implications for competition, pricing, and partnership strategies.
We deliberately present macro sizing and concentration to guide strategic choices while reserving granular subsegment shares for the full report — a necessary balance to preserve the proprietary value of our segmentation analysis and provider benchmarking.
What the Report Delivers: Actionable, Board-Level and Product-Level Tools
PW Consulting’s HSA Provider Market report is built for decision-makers who need executable intelligence, not just descriptive data. Highlights include:
- Dynamic market model (2020–2032). A downloadable Excel-based model with scenario toggles for contribution limits, HDHP penetration, investment adoption rates, and fee pressure to stress-test revenue and asset outcomes.
- Provider scorecards. Multi-dimensional benchmarking covering product breadth, fees, investment capabilities, integration maturity, employer sales channels, and customer experience metrics — intended to support vendor selection, partnership prioritization, and diligence checklists.
- Commercial playbooks. Go-to-market and employer-targeting strategies for incumbents, regional banks, and fintech entrants; playbooks include value propositions, pricing levers, and channel partnerships tailored to scale and customer segment.
- M&A and partnership pipeline. A prioritized list of capability targets (API providers, payroll integrators, investment custodians, emergency savings specialists) with suggested valuation multiples and integration roadmaps derived from our transaction benchmarking.
- Regulatory scenario analysis. Impact matrices that quantify the P&L and balance-sheet implications of incremental IRS rule changes, contribution-limit shifts, and HDHP eligibility dynamics.
- Operational readiness checklist. Recommended investments across platform engineering, fraud/compliance controls, and customer service that materially reduce churn and lift assets-under-management per participant.
Competitive Landscape: What Winners Do Differently
The competitive environment combines traditional financial institutions, large benefits administrators, and digitally native fintechs. Our competitor analysis synthesizes public filings, vendor interviews, and transaction activity to draw strategic insight on where each provider is positioned.
- Fidelity Investments — Leverages scale and investment depth to offer low-cost HSAs with expansive investment menus and integration with retirement. Its strength lies in driving long-term asset growth through seamless rollover and retirement-focused messaging.
- HealthEquity — A dominant administrator in employer-sponsored HSAs, emphasizing compliance, analytics, and an integrated consumer-directed benefits suite. Recent financials indicate strong account acquisition and a robust asset trajectory, reinforcing its channel leadership with mid- to large-employer markets.
- HSA Bank — A bank-backed player combining traditional deposit services with investment options and focused recent expansion into emergency savings solutions via acquisition activity, reflecting a trend toward broader employee financial wellness bundling.
- Lively — A digitally native entrant prioritizing UX, transparent fees, and support for smaller employers. Its product-led growth approach illustrates how modern platforms can accelerate adoption among SMBs and individual-direct segments.
- Optum Bank — Integrated within a large healthcare ecosystem, Optum leverages clinical and benefits data to promote HSA adoption as part of broader health management programs, an advantage in complex employer environments.
- Bank of America — Represents the traditional banking path: integrated treasury and deposit services with straightforward HSA offerings attractive to consumers favoring consolidated banking relationships.
Recent provider moves underscore strategic themes to watch in 2026. Notably, HSA Bank’s acquisition to build emergency savings capability signals a push toward holistic employee financial wellness. HealthEquity’s recent financial results demonstrate aggressive account acquisition and revenue momentum. Independent market research also confirms that aggregate HSA assets and accounts are increasing materially, reinforcing scale benefits for incumbents with investment platforms.
Regulatory and Market Signals to Monitor
Regulation remains a shaping force: 2026 IRS rules on contribution limits and the requirement that HSAs be paired with qualifying high-deductible health plans (HDHPs) set the baseline for product design and employer communication. Our scenario module quantifies how modest shifts in contribution ceilings or HDHP eligibility materially alter asset growth and fee income for providers — an essential input for underwriting new products or pricing strategies.
Strategic Recommendations for 2026 Planning
Based on our modeling and market interviews, we recommend the following actions for stakeholders preparing 2026 strategies:
- Prioritize integration capability. Ensure vendor RFPs and internal roadmaps include API-first requirements and pre-built connectors to payroll and benefits platforms to reduce friction in employer deployments.
- Differentiate via investability. Incentivize and simplify the pathway from cash balance to investable HSA balances; even modest increases in investment adoption materially raise provider economics.
- Bundle thoughtfully. Evaluate adding emergency savings and other near-term liquidity products to improve retention and deepen customer relationships, while quantifying incremental compliance risk.
- Target employer segments with tailored GTM. SMBs, mid-market, and enterprise buyers require distinct sales motions; align pricing and service SLAs accordingly and leverage channel partners where direct sales are cost-prohibitive.
- Build M&A playbooks. For fast-follow entrants, prioritize tuck-ins that solve integration and distribution gaps; for incumbents, assess bolt-on acquisitions to capture emerging fintech capabilities.
- Stress-test regulatory scenarios. Quantify balance-sheet and revenue sensitivity to conservative and downside regulatory changes to inform capital and pricing strategies.
- Invest in analytics. Deploy customer analytics to identify “convertible” cash balances and design nudges that increase investable flows and long-term retention.
Next Steps: How to Use the Full PW Consulting Report
The public summary above highlights the strategic contours we believe will shape 2026 decision-making. The full PW Consulting HSA Provider Market report delivers the operational DNA and proprietary segmentation necessary to execute: granular segment share maps, provider-level fee comparisons, downloadable market models, prioritized M&A target lists, and sample contract language for partnership integrations. To preserve the commercial integrity of our benchmarking, core subsegment shares and the provider scorecard metrics are provided in the full report package available via our distribution portal.
Leaders who download the report will receive:
- Access to the interactive market model with scenario toggles and downloadable outputs for finance and strategy teams;
- The full provider scorecard and M&A pipeline with suggested valuation ranges;
- A 90-day implementation checklist tailored to product, sales, and compliance teams to accelerate 2026 initiatives.
Conclusion
HSAs in 2026 represent a strategic crossroad: a larger, faster-growing market with clearer winners emerging based on integration capability, investability, and employer channel strength. PW Consulting’s new HSA Provider Market report equips boards, product leaders, and corporate development teams with the forecasting, benchmarking, and playbooks necessary to convert market momentum into defensible growth. For teams that must make consequential choices in 2026 — from platform investments to M&A — our report turns raw market expansion into actionable strategy.
To obtain the complete report and the underlying models and scorecards, visit our report page or contact PW Consulting’s HSA practice lead. The full dataset and provider-level insights are included in the paid report package — essential reading for any organization that intends to lead, rather than follow, in the competitive HSA landscape.
For detailed analysis of this topic, please visit the official page: Health Savings Account (HSA) Provider Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Epoxy Molding Compound (Low Dk/Df) Market Set to Reach USD 1,254.72 Million by 2032 at an 8.25% CAGR
By PW Consulting, 2026-08-18
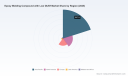
Epoxy Molding Compound with Low Dk/Df Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
PW Consulting’s new market study on Epoxy Molding Compound (EMC) with low dielectric constant/dissipation factor (low Dk/Df) delivers a focused, actionable intelligence package for executives steering product, procurement, and M&A strategies in 2026. The global market has shown a robust recovery and expansion trajectory, rising from roughly USD 490 million in 2020 to USD 720.5 million in 2025, and is forecast to reach approximately USD 1,254.7 million by 2032 at a compound annual growth rate (CAGR) of 8.25% during 2026–2032. Concentration metrics indicate a market dominated by a handful of incumbents (CR3 ~58.5%; CR5 ~72.3%), creating a landscape where supplier choices, pricing power, and strategic partnerships materially affect commercial outcomes.
Resistive Level Sensor Market
Market snapshot: why 2026 matters
2026 represents a pivotal inflection for low Dk/Df EMCs. The transition from incremental to architecture-driven demand — driven by high-frequency communications, advanced packaging for AI/HPC modules, and next-generation automotive electronics — is accelerating end-users’ need for tailored dielectric performance. At the same time, input-cost shocks, trade-policy shifts, and selective consolidation among materials suppliers are compressing the window for companies to reset sourcing and portfolio priorities.
SOA Amplifier Module Market
-
Growth momentum: The market’s historical expansion through 2025 set a strong foundation; our forecast projects sustained mid-single-digit to high-single-digit annual growth, reflecting both volume gains and a premiumization of specifications.
Inorganic Amargosite Market -
Supplier concentration: With the top three and top five suppliers accounting for a material share of revenues, strategic supplier engagement and dual-sourcing strategies are no longer optional for firms that cannot tolerate single-source risk.
-
Cost push: Raw material price volatility — notably in epoxy precursors — has been a recurring theme into early 2026, forcing many manufacturers to revisit pricing, contract terms, and hedging practices.
What this report delivers — the operational intelligence for 2026
Our study bridges market sizing and forward-looking playbooks. Beyond the headline forecast, the report equips decision-makers with:
-
Scenario-based demand models that link telecom rollouts, AI/HPC module adoption curves, and automotive electrification timelines to EMC volume and specification mix — enabling CFOs and product managers to stress-test revenue and margin assumptions under different technology adoption paths.
-
Procurement scorecards that map supplier capabilities (material chemistry, production footprint, qualification timelines) to buyer risk profiles, with recommended mitigation strategies including regional dual-sourcing, safety-stock targets, and specification rationalization.
-
Technology-readiness assessments that rank EMC chemistries and form-factors against high-frequency and reliability requirements, highlighting where incremental formulation work or packaging redesigns unlock meaningful system-level benefits.
-
M&A and partnership playbooks tailored to 2026: valuation multiples in material subsectors, target archetypes (technology-led vs. scale-led), and integration risks that commonly undermine post-deal synergies.
-
Regulatory and trade impact matrices that translate tariff changes and chemical listings into actionable cost and timing implications for sourcing and qualification programs.
Strategic implications by functional owner
-
Chief Procurement Officers — Prioritize contract designs that include cost-pass mechanisms and volume-flex provisions tied to raw material indices; accelerate qualification of alternate sources in lower-cost geographies where feasible.
-
Head of R&D / Packaging — Invest selectively in dielectric-optimized EMC formulations and collaborate with substrate and assembly partners to capture system-level differentiation rather than chasing incremental material performance alone.
-
Corporate Development — Focus on tuck-ins that complement specification breadth or shorten qualification cycles; the market’s concentration means smaller strategic acquisitions can provide disproportionate access to qualified customer relationships.
-
Product Line Managers — Re-evaluate product roadmaps to prioritize modules where EMC performance unlocks premium pricing or reduces downstream test and rework costs.
Competitive landscape — who matters and why
The EMC low Dk/Df market is characterized by a small group of global incumbents with deep formulation expertise and significant qualification footprints. Core players we profile include established Japanese, Taiwanese, Chinese, and US-based material specialists. Each brings distinctive strengths:
-
Resonac Corporation (Japan) — Known for EMCs suitable for high-frequency modules and organic substrates; the company’s focus on RF-grade formulations positions it well for telecom and SiP demand.
-
Sumitomo Bakelite (Japan) — A major supplier with mature product lines for semiconductor encapsulation and advanced packaging; strategic pricing actions in recent years reflect its role as a price leader in certain segments.
-
Kyocera Corporation (Japan) — Offers environmentally conscious, non-halogen grades and has a credibility edge in high-reliability, high-temperature applications.
-
Chang Chun Group (Taiwan) — Active in high-performance electronic materials and positioned to serve regional OEM clusters with localized supply and development support.
-
Jiangsu HHCK / Hysol Huawei (China) — Strategic consolidation through recent equity transactions has expanded capability and market access, particularly in domestic supply chains.
-
SolEpoxy (USA) — Niche specialty player supplying dielectric and optically clear grades, attractive for customers seeking alternative chemistries or nearshoring partners.
-
Shin-Etsu Chemical (Japan) — Longstanding presence in EMCs for semiconductor packaging with deep process control and qualification expertise.
Recent industry moves color the competitive dynamics. In 2025–2026, suppliers have adjusted pricing to reflect raw material inflation, and there has been targeted consolidation among regional players to secure scale and qualification breadth. These developments tighten bargaining levers for buyers and compress timelines for qualification of alternative suppliers.
Supply chain dynamics and regulatory noise
Two interlinked themes define 2026 supply-side risk:
-
Input-cost volatility — Epoxy precursor prices rose materially in parts of Northeast Asia into early 2026. Major resin producers announced price increases reflecting higher feedstock and operating costs, and oversupply pockets in some regions have amplified short-term price swings. Buyers should assume that spot volatility will persist through 2026 and design contractual hedges accordingly.
-
Trade and regulatory shifts — Changes to tariff exemptions and chemical listings in key markets have reintroduced trade frictions that previously had been dormant. These policy changes create re-routing incentives and inventory build-ups that will affect lead times and landed cost for sensitive compositions.
The net effect is that firms must balance cost optimization with qualification speed: aggressively chasing the lowest quoted price without ensuring qualification resiliency can increase time-to-market and inventory write-offs.
Practical next steps for 2026
For executive teams planning for 2026, the report recommends a 90–180 day action agenda and a medium-term strategic program:
-
Immediate (30–90 days): Conduct a supplier risk heatmap tied to your product lines’ qualification lead-times; initiate price-reopener clauses for contracts negotiating in volatile feedstock environments.
-
Short term (90–180 days): Fast-track qualification of at least one alternate EMC supplier for mission-critical products; run a cost-to-serve review to capture the real landed cost impact of tariffs and freight variances.
-
Medium term (6–12 months): Invest in co-development projects with suppliers that can shorten qualification cycles and secure formulation exclusivity for high-value modules; evaluate strategic investments in regional production or long-term off-take agreements where scale is a barrier to entry.
Why PW Consulting’s report is the strategic tool you need
This research is designed as a decision support instrument for 2026. It pairs a rigorous top-down market sizing framework (historical trends through 2025 and a detailed forecast through 2032 at an 8.25% CAGR) with pragmatic playbooks that translate industry dynamics into executable steps across procurement, R&D, and corporate development. The study’s concentration analysis clarifies competitive levers, while scenario models illuminate how shifts in telecom buildouts, AI/HPC module adoption, and automotive electronics will cascade into material demand and specification mix.
Importantly, the report follows a “trailer” logic: we provide the strategic scaffolding, risk maps, and implementation pathways that professionals need to make high-confidence 2026 decisions, while preserving proprietary subsegment datasets and granular regional/application splits for our subscribing clients. This approach ensures a concise executive view here, and a deep, auditable dataset in the full publication that supports quantitative planning and contract negotiation.
Concluding recommendation
As the EMC low Dk/Df market moves from specification-driven growth into a phase where supply-chain and regulatory forces will materially influence commercial outcomes, 2026 will separate companies that are reactive from those that are proactively rearchitecting sourcing, product, and M&A strategies. Leaders should treat materials strategy as a cross-functional priority: the right sourcing decisions, co-development bets, and partnership models executed in 2026 will yield outsized returns through the forecast window.
For teams ready to convert this strategic perspective into a concrete implementation plan — supported by the underlying data and scenario models — PW Consulting’s full report contains the detailed segmentations, supplier matrices, and quantitative tools necessary to operationalize decisions. Visit our report page to access the full dataset, appendices, and client-only advisory workshops.
For detailed analysis of this topic, please visit the official page: Epoxy Molding Compound with Low Dk/Df Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Voltage Pressure Sensor Market Poised to Expand at a 6.2% CAGR Through 2032
By PW Consulting, 2026-08-18
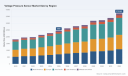
Voltage Pressure Sensor Market 2026 Strategic Brief: Why PW Consulting’s Report Will Shape Your Next Move
Executive snapshot
As the voltage pressure sensor market moves into its next growth phase, boardrooms and product teams face a familiar but intensifying challenge: turning sensor-level technical choices into firm-level competitive advantage. Our new market study—anchored on a 2025 base and projecting through 2032—shows the sector expanding at a steady compound annual growth rate (CAGR) of 6.2%. From the historical period (2020–2025) through the forecast horizon (2026–2032), the market evolves from roughly USD 1.8 billion in 2020 to an estimated USD 2.45 billion in 2025 and is projected to approach approximately USD 3.73 billion by 2032.
Conductive Agent for Lithium-ion Batteries Market
Those headline figures matter for capital planning, but they are only the starting point. The report translates aggregate momentum into the tactical constructs executives need in 2026: where to invest in sensing technologies, how to harden supply chains against material bottlenecks, and which competitive plays (partnership, build, or buy) will deliver the fastest route to differentiated sensing offerings.
Power Tool Chargers ODM and OEM Market
Why 2026 decisions need this intelligence
-
Product roadmaps: Sensor selection (MEMS piezoresistive vs. capacitive vs. strain gauge, ceramic options, thin-film designs) impacts accuracy, cost, and qualification timelines. The report links technology choices to realistic time-to-market and qualification-risk profiles tailored for semiconductor cleanrooms, industrial OEMs, HVAC, and other prioritized end markets.
Attack Surface Assessment Market -
CapEx and procurement planning: With wafer supply and stainless-steel availability influencing production lead times, procurement strategies must be informed by scenario-based forecasts that quantify timing and price volatility risk.
-
M&A and partnership screening: Market concentration metrics in the study highlight opportunity windows where bolt-on acquisitions or strategic alliances can move the needle without requiring prohibitive multiples or lengthy integration timelines.
-
Regulatory & certification sequencing: Compliance (EMC resilience, overpressure safety) drives design trade-offs. The report lays out a regulatory sequencing matrix so product teams prioritize certifications that unlock the largest addressable customers first.
What the report contains — practical tools for strategists
-
Dynamic financial model (USD Million base): An interactive model that maps historic demand (2020–2025), the 2025 base-year sizing, and forward-looking scenarios to 2032. Executives can toggle adoption rates, price erosion, and technology mix to simulate P&L and cash-flow impacts of alternative strategies.
-
Scenario analysis: Three distinct industry scenarios—Conservative, Baseline (CAGR 6.2%), and Accelerated—illustrate how macro shocks (raw material shortages, accelerated cleanroom automation adoption) affect market timing and margins.
-
Go-to-market playbooks: Tailored GTM templates for OEM suppliers, module integrators, and pure-play sensor manufacturers that include channel strategies, OEM qualification roadmaps, and aftermarket services blueprints.
-
Supply-chain heat map: A supplier map highlighting single-source dependencies (e.g., silicon wafer availability) and material risk factors (e.g., stainless steel lead times) with mitigation levers and contract structures.
-
Technology decision matrix: Side-by-side trade-offs across accuracy, drift, temperature performance, cost-to-manufacture, and qualification time for major technology families—MEMS piezoresistive, capacitive, strain gauge, ceramic, and thin-film—so R&D and product teams can prioritize investments.
-
Competitive dossiers and recent-moves timeline: Actionable intelligence on leading suppliers, their technology footprints, and near-term product developments to inform counter-strategies and partnership targets.
Competitive landscape: what leading suppliers reveal about trajectory
The market remains moderately consolidated—our report documents concentration metrics that matter for strategic planning: the top three suppliers collectively account for a material share of industry revenue, and the top five amplify that concentration further. Those concentration ratios create a marketplace where tactical moves by a well-capitalized player can rapidly shift partner and customer dynamics.
Core vendors illustrate the strategic patterns companies are following today:
-
Honeywell International Inc. continues to push into high-precision, contamination-sensitive applications. Its 2025 launch of the 13MM series—targeted at semiconductor cleanrooms and industrial environments—highlights a trend: premium differentiated products that command longer qualification cycles but superior pricing and stickiness.
-
TE Connectivity emphasizes ruggedization and MEMS-based piezoresistive solutions for harsh environments across industrial, automotive, and aerospace segments—a signal that industrial-grade MEMS remains a primary avenue for value capture.
-
Specialists such as Setra Systems and TT Electronics keep competition focused at the high-accuracy and OEM-integration ends of the market, where certification and reliability drive procurement choices.
-
Smaller, agile manufacturers—Core Sensors, Stellar Technology, Huba Control, Gems Sensors, All Sensors (Amphenol), and Ashcroft—demonstrate rapid product iteration and configurability for OEMs and hazardous-location applications, which is particularly relevant for customers seeking short lead-time customization.
-
Recent product activity—Core Sensors’ 2026 differential transducer release and catalog refreshes by global component suppliers—signals a steady cadence of incremental innovation rather than disruptive, single-event shifts. For incumbents and new entrants alike, the competitive playbook will prioritize continuous product improvement, channel expansion, and selective co-development agreements.
Supply chain, regulation and raw material risks
Two material realities are central to 2026 planning. First, the upstream supply chain—most notably silicon wafers used for MEMS piezoresistive sensors and stainless steel for diaphragms and housings—remains a gating factor for production agility. Second, regulatory requirements (EMC resistance, overpressure safety standards) increasingly shape design choices and cost structures. The net effect is that suppliers with vertically integrated or long-term strategic sourcing contracts will realize shorter qualification cycles and more reliable gross margins.
Our report includes a prioritized mitigation matrix: dual-sourcing thresholds, in-region strategic inventory buffers, and cost-pass-through clauses that legal and procurement teams can operationalize within 90–180 day timelines.
Technology and application dynamics
Application demand is being reshaped by two parallel forces: the precision needs of semiconductor manufacturing cleanrooms and the proliferation of IoT-enabled predictive maintenance in industrial operations. These drivers pull the market toward higher-accuracy, lower-drift solutions that can be integrated into digital monitoring stacks. At the same time, cost-sensitive segments continue to prefer robust, lower-cost architectures where long-term reliability and simple calibration are more valuable than peak precision.
Technology trade-offs are therefore strategic: MEMS piezoresistive variants deliver a compelling mix of accuracy and volume manufacturability for high-end industrial and semiconductor use cases; capacitive and strain gauge solutions remain attractive in scenarios where thermal stability or specific pressure ranges are prioritized; ceramic and thin-film approaches are winning in corrosive or highly compact OEM contexts. Our technology decision matrix provides the comparative scoring executives require to prioritize R&D and supplier selection without guessing market fit.
Strategic recommendations for 2026
-
Prioritize wafer supply security: Enter multi-year supply agreements or strategic investments in wafer partners if MEMS is core to your roadmap.
-
Race to certification where it matters: Sequence EMC and overpressure approvals to unlock the largest and most profitable OEM contracts earliest.
-
Adopt configurable product platforms: Build modular electronics and firmware to shorten customization cycles for OEM customers and reduce SKUs.
-
Targeted M&A: Use concentration metrics to guide acquisition size—accretive buys in the mid-market can rapidly expand addressable channels without major integration drag.
-
Invest in aftermarket services: Subscription-based analytics, sensor-health monitoring, and calibration-as-a-service raise customer switching costs and recurring revenue.
-
Hedge material price risk: Implement staged contract escalation clauses and regional inventory nodes to blunt stainless-steel and semiconductor material shocks.
-
Partner for cleanroom credentials: Collaborate with end-customers and test houses early to co-develop qualification plans that reduce time-to-revenue for high-precision sensors.
Why PW Consulting’s report is different
-
Proprietary, scenario-ready market model with downloadable inputs so teams can adapt forecasts to organization-specific assumptions.
-
Actionable supplier and technology matrices built from primary conversations with industry participants and validated against transactional data.
-
Operational playbooks that translate market intelligence into 90–180 day executable plans for procurement, R&D, and commercial teams.
-
Clear escalation frameworks for material and regulatory risk—designed to be handed directly to supply-chain and compliance leaders.
Next steps
For executives making 2026 commitments—whether capex, M&A, or product-portfolio pivots—this report provides both the strategic narrative and the operational tools to act with conviction. To access the full segmentation, interactive model, and the complete competitor dossiers that underpin our recommendations, please visit the PW Consulting report page for download and advisory engagement options.
For detailed analysis of this topic, please visit the official page: Voltage Pressure Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Large Model for 3D Generation Market Poised to Reach USD 4,105.79 Million by 2032 at a 38.5% CAGR — Diffusion Models and Gaming Drive Growth
By PW Consulting, 2026-08-18
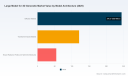
Strategic Imperatives from PW Consulting: Large Models for 3D Generation Market — What Corporate Leaders Must Know for 2026
Enterprises planning product roadmaps, content pipelines, or platform strategies in 2026 face a rapidly expanding market for large AI models that generate production‑ready 3D assets. PW Consulting’s latest market study — anchored on 2025 as the base year — shows the sector growing at an exceptional compound annual growth rate of 38.5% through our forecast window, with the market progressing from early traction in 2020 to a multi‑billion dollar opportunity by the early 2030s. This seismic trajectory is changing how organizations think about digital asset production, creative workflows, and the economics of virtual representation.
Data Sovereign Cloud Service Market
Why this market trajectory matters to enterprise decision‑makers right now
-
Strategic timing: The rapid CAGR means that pilots launched in 2026 can move from experimentation to core production capability within a two‑ to three‑year horizon. Executives must therefore align budgets and roadmaps to avoid being late adopters in high‑velocity product cycles.
Basalt Unidirectional Fabric Market -
Platform vs. point solution tradeoffs: The value proposition is shifting from bespoke tooling toward platformized services that combine generative models, asset stores, and integration frameworks. Choosing a partner today often determines which ecosystems and standards an organization will inherit.
Worldwide Universal Adhesives Market -
Cost and infrastructure implications: Training and fine‑tuning frontier 3D models is capital‑intensive. Industry analyses indicate that hardware can represent roughly half or more of total development costs for frontier AI training, with energy representing a measurable but smaller share. These economics will define decisions about cloud vs. on‑prem, co‑development partnerships, and hardware procurement.
-
Risk profile shift: As models produce increasingly production‑ready textured and PBR assets, enterprises must move beyond purely technical pilots to tackle IP provenance, commercial‑use licensing, and regulatory compliance as core program elements.
What PW Consulting’s report delivers — practical, decision‑grade tools
Our study is designed as an operational playbook for 2026 executive planning. It combines market sizing and trend forecasting with pragmatic modules that translate strategic intent into executable programs:
-
Scenario‑based demand forecasts and sensitivity analysis calibrated to enterprise adoption pathways, enabling CFOs to stress‑test capital allocation across alternative rollouts.
-
Vendor evaluation frameworks and procurement scorecards that prioritize integration risk, model fidelity, throughput, and total cost of ownership rather than headline accuracy metrics alone.
-
Deployment roadmaps and checklists for integrating generative 3D models into existing pipelines (game engines, e‑commerce platforms, CAD ecosystems), including recommended milestones for pilot, scale, and operations phases.
-
ROI templates and unit economics tools tailored for creative organizations, digital twins, and asset marketplaces to quantify time‑to‑value and payback horizons.
-
Risk matrices and compliance playbooks addressing dataset provenance, licensing, content safety, and supply chain transparency.
-
Architectural decision guides contrasting centralized training, federated fine‑tuning, and edge inference patterns for different use cases and regulatory contexts.
Competitive landscape — the players shaping the ecosystem in 2026
The market is defined by a mix of nimble startups driving rapid model innovation, large platform incumbents integrating capabilities into creative toolchains, and infrastructure firms enabling scale. A non‑exhaustive view of influential providers helps illuminate strategic choices:
-
Meshy AI (Sunnyvale, CA) focuses on text‑to‑3D and image‑to‑3D flows that produce production‑ready textured models with physically based rendering (PBR) materials. Its emphasis on immediate asset usability suits game studios and e‑commerce teams seeking rapid content throughput.
-
Tripo AI (San Francisco, with roots in China) has positioned itself around pipeline‑optimized outputs for game and manufacturing workflows. In March 2026 Tripo announced substantial funding and a new model family designed to generate geometry natively in spatial space — a signal that investors are backing verticalized, production‑grade solutions.
-
Luma AI (Palo Alto, CA) advances photorealistic 3D and spatial intelligence capabilities, appealing to enterprises that prioritize realism and integration with spatial computing platforms.
-
Tencent (Shenzhen) has released a global 3D creation engine that combines text‑to‑3D and image‑to‑3D inputs with emphasis on PBR fidelity and production toolsets, reflecting a platform play from a major tech conglomerate (global launch in late 2025).
-
NVIDIA (Santa Clara, CA) continues to be a foundational infrastructure and platform enabler, providing model primitives and toolchains that plug into omniverse workflows and accelerate both training and deployment scale.
-
Adobe (San Jose, CA) integrates generative 3D features into Creative Cloud and Substance toolchains, emphasizing licensed datasets and commercial safety as part of the product promise.
-
Autodesk joined the competitive mix with a generative 3D model launch in April 2026 aimed at character and object creation within design workflows, signaling established enterprise software vendors are accelerating product integrations.
Collectively, these firms illustrate how the market is evolving along three axes: model fidelity and texture realism; pipeline integration and interoperability; and commercial assurances around data licensing and provenance. Enterprises must evaluate partners not just on raw capability, but on the ecosystem they enable — asset management, versioning, and enterprise‑grade governance.
Operational dynamics: compute, costs, and sustainability
Enterprises must confront the economics of model development. Industry analyses show that hardware costs can account for a very large share of training expenses for frontier models, while energy costs, though smaller in relative terms, are non‑negligible at scale. These realities have five practical consequences for 2026 planning:
-
Cloud vs. on‑prem calculus: For many organizations, hybrid approaches — initial cloud training with on‑prem inference and edge caching — will be the optimal mix to balance cost, latency, and compliance.
-
Partnership economics: Co‑funded training arrangements, model licensing, and managed services reduce upfront capex and transfer operational risk to vendors that specialize in large‑scale model operations.
-
Sustainability and reporting: Visibility into energy consumption and carbon accounting will increasingly be a procurement criterion and a public reporting obligation for larger enterprises.
-
Optimization levers: Model distillation, parameter efficiency, and mixed‑precision training are practical levers to bring down operating costs without compromising production readiness.
-
Edge delivery and latency: For real‑time applications (e.g., AR/VR, interactive gaming) the marginal cost of inference at edge will factor heavily into commercial feasibility.
Regulation, IP, and data ethics — front‑row considerations
Regulatory and IP dynamics are moving from theoretical to operational. Several leading vendors emphasize licensed datasets and provenance as competitive differentiators; enterprises should likewise require demonstrable dataset lineage and commercial usage rights as part of procurement. Key considerations include:
-
Provenance and licensing: Require auditable training data provenance and indemnities where possible; evaluate vendor practices for dataset curation and third‑party content licensing.
-
Content safety: Integrate safety filters and moderation flows into asset pipelines to mitigate reputational and legal risks.
-
Standards and interoperability: Advocate for, and adopt, interoperable asset formats and metadata standards to avoid lock‑in and preserve reusability.
Actionable playbook for executives in 2026
Based on our analysis, PW Consulting recommends the following prioritized actions for enterprise leaders:
-
Define a three‑layer adoption portfolio: foundational pilots (6–9 months), tactical scale projects (12–24 months), and strategic platform investments (24+ months).
-
Build procurement scorecards that weight model fidelity, integration lift, governance, and total cost of ownership — not just benchmark metrics.
-
Negotiate flexible commercial terms: opt for staged commitments tied to integration milestones and clear IP/usage guarantees.
-
Form compute partnerships: explore co‑investment, managed training services, or vendor‑provided inference tiers to manage capital exposure.
-
Mandate dataset lineage and safety controls in contracts; require vendors to disclose training dataset provenance and licensing practices.
-
Invest in internal capability: hire or retrain staff for model validation, asset QA, and tooling integration rather than relying solely on vendor handoffs.
-
Participate in standards bodies and industry consortia to reduce vendor lock‑in risk and influence interoperability norms.
-
Run comparative ROI pilots across two or more vendor models to hedge execution and quality risk while learning integration requirements.
Concluding perspective — why PW Consulting’s report should be on your 2026 agenda
The large model for 3D generation market presents both an extraordinary growth opportunity and a set of execution challenges that extend far beyond model accuracy. The strategic choices made in 2026 — about partners, infrastructure, governance, and product integration — will define whether an organization captures disproportionate value or remains an afterthought in new content ecosystems.
PW Consulting’s report pairs a rigorous quantitative outlook with granular operational guidance: procurement tools, vendor evaluation matrices, cost and ROI models, and legal/compliance checklists. If your 2026 plans include any form of 3D content at scale — from gaming and e‑commerce to digital twins and product visualization — this research is designed to turn market momentum into repeatable business outcomes.
For access to the full datasets, detailed vendor scorecards, case studies, and the actionable appendices referenced above, please consult the PW Consulting research portal or contact our industry team. The summary herein is a strategic preview; the full report provides the decision‑grade detail required to operationalize a 2026 3D generation strategy.
For detailed analysis of this topic, please visit the official page: Large Model for 3D Generatio Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Managed Security Services Market Set to Grow at a Robust 11.5% CAGR Through 2032, Driving Major Opportunity in MSS Systems
By PW Consulting, 2026-08-12
PW Consulting Releases Strategic Brief: Managed Security Services System Market — Essential Guidance for 2026 Enterprise Decisions
Executive summary
PW Consulting today publishes an executive briefing tied to our forthcoming Managed Security Services System Market report (base year 2025). This briefing synthesizes the report’s data-driven view of market trajectory, competitive dynamics, regulatory headwinds and practical playbooks that security and procurement leaders must use to shape 2026 strategy. The Managed Security Services market is no longer a niche outsourcing choice — it is a foundational element of enterprise risk reduction, cloud resilience and regulated-data stewardship. Our analysis shows sustained double-digit growth and meaningful vendor evolution driven by AI, network integration and sovereign-data pressures.
Worldwide Dissolved Nitrogen Flotation Systems Market
Market trajectory: a concise, data-driven snapshot
Across the historical window (2020–2025) this market demonstrated robust expansion, moving from an early-market scale in 2020 through accelerated adoption to a 2025 base. Our forecast period (2026–2032) projects continued strength, with a compound annual growth rate (CAGR) of 11.5% and an expected near-term uplift into 2026 as organisations operationalize cloud-native security patterns and managed detection and response (MDR) models. By 2032 the market is forecast to be more than double the 2020 scale, reflecting both increased outsourcing of security operations and rising spend per customer on advanced managed capabilities.
Site Accommodation Hire Market
- Base year: 2025 (full historical series: 2020–2025)
- Forecast horizon: 2026–2032
- Projected CAGR (2026–2032): 11.5%
This trajectory is not theoretical — it is visible in vendor investment in AI-enabled operations, certificate lifecycle automation, and integrated SASE/MSSP offerings, and is reinforced by enterprise risk appetites that favor expert-managed SOCs over large in-house expansions.
Worldwide Women's Trousers Market
What the full report contains — operationally focused, decision-ready intelligence
PW Consulting’s full report is designed as a working tool for CISOs, procurement teams, CTOs and board-level risk committees. It is structured to support vendor selection, contractual negotiation, program design and ROI validation. Key deliverables include:
- Validated market sizing and forward-looking revenue models (2020–2032) that underpin procurement sizing and budget planning;
- Demand-side segmentation and service-type overviews that map buyer needs to managed service constructs (note: detailed subsegment tabulations are reserved for the full report);
- Vendor benchmarking matrices covering capability depth (24/7 monitoring, incident response, XDR/MDR, cloud-native controls), go-to-market motion, certifications/FedRAMP readiness, and partner ecosystems;
- Procurement playbooks and RFP templates tailored to outcomes (mean time to detect/contain, SLAs, incident escrow, data handling and egress rights);
- Deployment and integration guidance for hybrid and multi-cloud environments, including control-plane instrumentation and telemetry normalization approaches;
- Operational KPIs and an MSSP maturity model to align internal teams and external providers around measurable performance;
- Risk and regulatory impact assessments with contractual language examples for data residency, cross-border incident management, and confidentiality of forensic data;
- Real-world case studies showing measured ROI, reduction in dwell time, and scenarios where managed services materially improved resilience.
To preserve strategic advantage for subscribers, the briefing intentionally omits granular subsegment numbers and regional splits that are available in the full research package.
Competitive landscape: who matters and why
The Managed Security Services ecosystem today blends global system integrators, large telcos, and purpose-built MSSPs. Market concentration remains moderate: the top three vendors account for a minority share of the market, and the top five still leave room for regional and specialist players to differentiate. This dispersion creates opportunity for both scale players and focused providers.
- IBM Security — Strengths: hybrid-cloud security services, depth in compliance and incident response across complex enterprise estates. Strategic implication: enterprises with multi-cloud and regulated workloads will prioritize partners with deep compliance tooling and hybrid orchestration capabilities.
- Verizon — Strengths: global network footprint, DDoS mitigation, SASE integrations. Strategic implication: vendors owning last-mile and backbone network can combine connectivity and security to reduce complexity for global enterprises.
- LevelBlue — Strengths: pure-play MSSP model, MDR and FedRAMP-authorized services. Strategic implication: focused specialists can outcompete on operational SLAs and public-sector trust frameworks.
- Tata Communications — Strengths: network-integrated security monitoring and global reach. Strategic implication: telco-integrated security can simplify managed perimeter and edge use cases for multinational customers.
- Secureworks — Strengths: Taegis XDR platform, analytics-led detection. Strategic implication: platform-led MSSPs can accelerate detection investments while enabling long-term telemetry monetization.
- Arctic Wolf — Strengths: concierge security model, strong SME adoption. Strategic implication: differentiated customer engagement models and SOC-as-a-service play well for mid-market buyers seeking hands-on support.
- eSentire — Strengths: expert-led 24/7 MDR with strong incident triage capabilities. Strategic implication: customers with acute threat exposure favour operator expertise and rapid containment.
Recent industry moves underscore these trends: AI-enabled MSS suites, cloud-provider managed security recognition programs, and next-generation certificate automation are reshaping service scopes and procurement criteria.
Regulatory and infrastructure dynamics shaping 2026 strategy
Macro policy and infrastructure developments increasingly define the operational constraints and cost models for managed security providers and their customers. Key dynamics to monitor:
- Energy and data center regulation: a proliferation of state-level bills addressing energy costs, grid reliability and special tariffs for large data center operators has emerged, with direct implications for providers who operate and scale security telemetry infrastructure.
- Federal pledges on ratepayer protection: national-level policies seeking to prevent energy cost socialization for hyperscalers and large AI/data center operators can affect provider operating costs and commercial agreements.
- Data sovereignty friction: ongoing trade and sovereignty debates continue to complicate cross-border managed service models; procurement teams must build contractual clarity around cross-border processing and lawful access.
- Specific cyber-data rules: new bulk-data rules and privacy-related mandates require tighter controls for certain types of aggregated personal data transfers and may increase compliance burdens for MSSPs handling bulk telemetry.
These shifts mean that vendor selection is not purely a capabilities exercise; it is increasingly an evaluation of a provider’s operational risk profile, energy exposure and legal posture on data sovereignty.
Actionable recommendations for 2026 decision-makers
Enterprises planning budgets and security roadmaps in 2026 should use the following pragmatic checklist derived from our full report:
- Align procurement to outcomes, not features: define measurable detection and containment KPIs (MTTD, MTTR, false-positive rate) and bake them into contract incentives.
- Stress-test energy and location risk: require vendor transparency on data center power contracts, resilience plans, and cost pass-through clauses to anticipate tariff volatility.
- Prioritize hybrid integration competency: ensure the MSSP has proven playbooks for telemetry normalization across cloud providers, on-premise appliances and edge devices.
- Validate sovereign-data controls: require specific contractual language for cross-border data handling, lawful access processes, and breach notification aligned to your jurisdictions of operation.
- Demand modularity and exit rights: insist on interoperability, data export formats, and playbooks for rapid provider transition to avoid vendor lock-in.
- Factor AI & automation maturity: assess providers’ investments in AI for alert triage, threat hunting and certificate lifecycle automation—these investments materially affect unit economics and response times.
- Adopt a staged adoption path: pilot MDR/XDR with well-defined runbooks, then scale to wider coverage as trust and integration stabilize.
Methodology, limitations and how to obtain the full intelligence
PW Consulting’s full-market model combines bottom-up vendor telemetry, contract-level pricing analysis, buyer interviews and macroeconomic scenario stress testing. The public briefing you are reading intentionally excludes detailed subsegment allocations and regional breakdowns — elements that are core to procurement decision-making and included in the subscriber-only deliverable. Our concentration analysis indicates a moderately fragmented vendor landscape, validating the need for rigorous vendor shortlisting.
For security leaders preparing for 2026, the full report is a practical toolkit: it contains the granular tables, vendor scorecards, RFP templates and negotiation clauses needed to move from strategy to execution. To access the complete report, including all supplemental data and appendices, please visit the PW Consulting Managed Security Services System Market report page.
Closing perspective
2026 will be the year enterprises convert exploratory MSSP pilots into long-term security operations strategies. With an anticipated continued expansion of the market and rapid vendor innovation around AI, network-security convergence and regulatory compliance, careful vendor selection and contract design will determine whether managed security becomes a cost center or a strategic enabler. PW Consulting’s full report translates these macro trends into concrete steps — but the most sensitive, transaction-level guidance and subsegment tables are available only in the full product.
For detailed analysis of this topic, please visit the official page: Managed Security Services System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aluminum Exhibits Market to Grow from USD 4,210 Million in Base Year 2025 to USD 7,088.63 Million by 2032 at 7.73% CAGR (Forecast 2026–2032) — Modular Systems, Europe and Trade Shows Lead; Top 3 Hold 32.4%
By PW Consulting, 2026-08-12
Aluminum Exhibits Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive snapshot
PW Consulting’s latest Aluminum Exhibits Market report (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes five years of market dynamics with scenario-driven projections to arm executive teams with decision-grade insight for 2026. The global market has expanded rapidly—rising from approximately USD 1,650 Million in 2020 to about USD 4,210 Million by 2025—and is forecast to continue growing through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 7.73%, reaching an expected market size in excess of USD 7,000 Million by 2032. This brief highlights the strategic value of the full report for commercialization, procurement, product strategy, and M&A decisions, while deliberately withholding granular segment tables to encourage direct access to the full dataset and proprietary models.
Lipid Nanoparticle Solutions Market
Why this matters for 2026 decision-making
- Market momentum: The industry’s sustained expansion, underpinned by accelerating demand for modularity, LED-integrated brand environments, and reconfigurable assets, creates both opportunity and complexity for manufacturers, exhibitors, and agencies looking to scale profitably.
- Margin pressure from input volatility: Elevated aluminum price levels and shifting trade policy are already compressing supplier margins and altering cost-to-serve economics across the supply chain.
- Competitive consolidation: With a moderate top-player concentration (CR3 ~32.4%, CR5 ~45.6%), there is room for strategic partnerships, vertical integration, and targeted M&A to materially shift competitive positions over a 12–36 month window.
What the PW Consulting report delivers (practical, executable)
We designed the report as a hands-on toolkit for executives who must convert market insight into action in 2026. Core deliverables include:
CuW Electric Contact Material Market
- Proprietary market sizing and growth scenarios calibrated to five years of primary and secondary data (2020–2025) and stress‑tested across three macroeconomic and regulatory paths for 2026–2032.
- Segment-level playbooks (by region, product type, and end application) that translate demand drivers into SKU rationalization, pricing levers, and service-model choices—presented as decision trees and tactical checklists.
- Supplier and competitor scorecards: performance benchmarks, capability heatmaps, and a strategic supplier segmentation to guide sourcing and contract negotiation.
- Cost-to-build and total cost of ownership models for modular systems, truss systems, and custom extrusions—built to be adapted by procurement teams to local cost pools and duty structures.
- Regulatory impact and scenario modeling: quantitative simulations showing how tariff actions, antidumping outcomes, and raw-material shocks change landed cost and feasible margin pools.
- Commercial playbooks for product innovation—covering LED and digital integration, circularity and refurbishment offers, and rapid-deploy “kit” strategies for event agencies and OEM customers.
Note: This news release intentionally highlights capabilities without publishing the granular tables and segment-level financials contained in the full report. Those assets include detailed regional, type, and application splits, interactive dashboards, and downloadable financial models.
Handheld PIM Tester Market
Market trajectory and what to expect in 2026
The market’s rebound and continued expansion through 2026 reflect a combination of pent-up event demand, accelerated adoption of reusable modular systems, and greater demand for immersive, LED-enabled environments. However, this growth is occurring within a more complex operating environment:
- Raw material environment: Aluminum prices have trended higher in early 2026, with market indicators signalling elevated levels compared with recent history—an input condition that raises marginal costs for extruders and fabricators and prompts a re-evaluation of sourcing strategies.
- Trade and regulatory shifts: Recent policy changes and ongoing administrative reviews affecting aluminum imports are introducing variable duty exposure for components and extrusions—impacting landed cost calculations and just-in-time manufacturing practices.
- Demand-side evolution: Buyers increasingly prioritize lifecycle cost, portability, rapid assembly, integrated digital features, and sustainability credentials—placing a premium on modularity and systems that minimize freight and storage footprint.
Competitive landscape—who matters and why
The industry is characterized by a mix of specialized systems builders, extrusion specialists, and vertically integrated fixture manufacturers. The report profiles market leaders and strategic challengers, assessing capability across R&D, global distribution, system integration, and sustainability credentials. Highlights include:
- Aluvision (Belgium): A recognized leader in LED-integrated modular frame systems and experience-centric brand environments. Recent strategic moves show a continued focus on tech-enabled systems and European distribution alliances.
- Agam (USA): Longstanding expertise in engineered modular solutions and a visible thought-leadership posture on trends toward smarter, more efficient builds—using research outputs to influence channel partners and customers.
- Skyline Exhibits (St. Paul, MN): A full-service designer and manufacturer with a strong project execution footprint; recent industry recognition underscores the company’s creative and delivery strengths in large-format exhibits.
- Specialist suppliers (e.g., Exhibit and Display Truss, Abex, Extrude-A-Trim, 80/20 Inc., Nova Display): These firms form the ecosystem backbone—supplying truss, extrusion, and T-slot systems that enable OEMs and agencies to execute at scale and at speed.
Each company’s profile in the full report includes capability maps, go-to-market vectors, recent commercial developments, and an acquisition readiness assessment—enabling buyers and investors to prioritize partners or targets based on strategic fit.
Recent industry developments to watch in 2026
- Notable corporate moves: Major vendors continue to signal investment in LED integration, modularity, and distribution partnerships—indicative of a shift toward system-level offerings rather than component sales.
- Policy and price signals: Elevated exchange-traded aluminum prices and newly revised tariff stances in key markets are increasing the urgency for procurement redesign, hedging, and near-shoring evaluations.
- Procurement behavior: Buyers are increasingly valuing total lifecycle cost metrics—driven by freight, storage, reconfiguration expense, and ESG reporting requirements—over headline materials price alone.
Action agenda for executives in 2026 (what to do now)
PW Consulting recommends a three-horizon approach to convert insight into defensible advantage:
- Immediate (0–3 months): Re-run landed-cost models for all major SKU families using current aluminum spot benchmarks and updated duty scenarios. Implement minimum viable hedging or supplier-flex clauses. Begin supplier risk assessments for any China-origin extrusion exposure.
- Near-term (3–12 months): Accelerate development of modular “fast-ship” kits and standardized digital integration packages. Pilot circularity offers for marquee customers to capture refurbishment and secondary-market revenue. Evaluate selective inventory localization in high-duty geographies.
- Medium-term (12–36 months): Pursue capability-driven M&A or distribution partnerships to close material gaps in global fulfillment and LED integration. Institutionalize scenario planning into product roadmaps and procurement contracts to ensure agility under fluctuating raw-material and policy regimes.
How PW Consulting’s report de-risks 2026 choices
Organizations using our analysis will be able to:
- Quantify how alternative tariff and aluminum-price paths change margin pools at product-family level.
- Prioritize SKU rationalization and systemization opportunities with a clear ROI horizon.
- Construct supplier engagement strategies that balance cost, agility, and regulatory risk.
- Model acquisition and partnership scenarios with transparent forward-looking synergies based on demand and cost forecasts.
Accessing the full intelligence
This press release presents executive-level takeaways and selected macro metrics to illustrate market direction. The full PW Consulting Aluminum Exhibits Market report contains the exhaustive segmentation tables, competitive scorecards, downloadable cost models, and the proprietary scenario dashboards referenced above—assets designed for direct operational use by strategy, procurement, and product teams. To review the complete dataset and the actionable annexes (including supplier heatmaps, procurement playbooks, and model templates), please visit our report page.
Concluding perspective
2026 will be a defining year for organizations operating in the aluminum exhibits value chain. Rapid market growth combined with elevated raw-material prices and shifting trade policy creates a narrow window to reposition: those who act with disciplined data, robust supplier strategies, and modular product architectures will secure durable advantage. PW Consulting’s report provides the analytical backbone to make those choices with confidence—clarifying where to invest, partner, or consolidate while preserving optionality in an era of higher volatility.
For detailed analysis of this topic, please visit the official page: Aluminum Exhibits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SocialFi NFTs Market to More Than Double — From USD 480 Million in 2025 to USD 1.09 Billion by 2032 at a 12.5% CAGR
By PW Consulting, 2026-08-12
SocialFi NFTs Market 2026: A Strategic Preview for Corporate Decision-Makers
Executive snapshot
As SocialFi NFTs evolve from niche experiment to commercial infrastructure, 2026 is shaping up to be the inflection year when strategy beats hype. PW Consulting’s new SocialFi NFTs Market research—built on a 2020–2025 historical analysis and a 2026–2032 forecast—shows a market that expanded from a modest base in 2020 to a materially larger platform economy by 2025, and that is expected to sustain a compound annual growth rate (CAGR) of 12.5% through 2032. In plain terms: this is not a short-term fad; it is a multi-year growth opportunity with meaningful implications for product roadmaps, partnerships, and capital allocation across media, gaming, consumer platforms, and Web3 infrastructure providers.
Tubing Running Services Market
Why this matters for corporate strategy in 2026
- Scale and velocity: The market’s historical trajectory demonstrates persistent, compounding adoption. From 2020 to 2025 the addressable SocialFi NFTs market scaled severalfold, and by 2032 our baseline forecast projects it will be measured in the high hundreds of millions to over a billion USD (revenue unit: USD Million). That trajectory alters assumptions for customer lifetime value, CAC payback, and network effects modeling.
- Monetization architecture: NFT-native monetization—ranging from creator collectables and access passes to on-chain identity—has shifted incentive design. Firms that treat NFTs as tokenized access layers rather than one-off collectibles unlock recurring revenue and deeper retention.
- Operational timing: 2026 is the window to cement technical and commercial partnerships. Early platform integrations and developer tooling investments now will compound through the forecast period, enabling outsized returns relative to late entrants.
What the PW Consulting report delivers (practical, actionable content)
We built the study for decision-makers who need to move beyond headlines and build executable plans. The report includes:
Bio-silicon Fertilizer Market
- A reproducible market-sizing model (2020–2032) with sensitivity scenarios reflecting token velocity, creator monetization uptake, and regulatory drift.
- Go-to-market blueprints for three enterprise archetypes: (a) consumer platforms seeking seamless Web2→Web3 conversion, (b) media and entertainment owners monetizing IP via time-limited NFTs, and (c) infrastructure providers offering identity and settlement layers.
- Product design playbooks: recommended tokenomics patterns, membership NFT mechanics, and anti-fraud measures for secondary markets.
- Partner and M&A playbook: priority targets by capability (identity, wallet UX, creator experience, on-chain governance), due-diligence scorecards, and valuation heuristics tailored to SocialFi economics.
- Operational KPIs and a 12–18 month pilot checklist designed to accelerate learning while limiting downside.
Market dynamics and competitive context
The SocialFi NFTs market is maturing into a market with both several deep specialists and a broad ecosystem of complementary providers. Market concentration is measurable but not prohibitive—leading platforms have meaningful share, while an expanding middle tier of specialists presents strategic partner and acquisition opportunities.
Semiconductor Equipment Vacuum Capacitors Market
Engagement metrics underline the scale of the opportunity: protocols and platforms report millions of daily active wallets, and creator monetization events have moved from experiment to substantial income streams for top creators. These signals confirm a two-sided dynamic—platforms that can reliably connect creators with paying communities see amplified network effects.
Competitive landscape: strategic positions to watch
- Friend.tech (San Francisco) : A pioneer in enabling social shares and creator monetization via tokenized interactions. Strengths: high-engagement product design and established creator workflows. Strategic question: can Friend.tech deepen stickiness through cross-platform NFT portability?
- Lens Protocol (United Kingdom) : A decentralized social graph designed for profile and content portability. Strengths: composability and a developer-centric ethos. Strategic question: will Lens become the default social layer developers target for reusable identity and follow mechanics?
- Farcaster (West Hollywood) : Recently acquired and transitioning to a developer-focused model. Strengths: strong community and protocol-level primitives. Strategic question: how will the new ownership shape incentive alignment for builders?
- Zora (New York) : Blending NFT marketplaces with social features; recent expansion introduces trading of social trends and attention as tradable assets. Strengths: experimentation with attention markets and multi-chain integrations. Strategic question: can attention marketplaces scale without undermining creator economics?
- BLAQclouds, Inc. (Robesonia) : Focused on creator tooling with marketplaces and SocialFi platforms, with recent product launches that broaden creator monetization options. Strengths: end-to-end creator commerce stacks. Strategic question: will vertical marketplace approaches beat horizontal orchestration strategies?
- CyberConnect (Singapore) and Cheelee (Singapore) : Regional leaders in social identity and short-video SocialFi respectively, both showcasing how local product-market fit and regional partnerships accelerate adoption. Strategic question: how will regional regulatory and payments ecosystems shape their scaling trajectories?
Recent developments to factor into 2026 planning
- Platform expansions and new product launches in early 2026 underscore ongoing product-market consolidation—some firms are shifting from consumer-centric launches to developer and protocol-focused strategies.
- High-profile acquisitions signal that strategic buyers are willing to pay for protocol-level assets and developer communities; integration plans after such transactions will determine winner-take-more dynamics.
- Experimentation with attention markets and trend-tokenization is accelerating—this introduces new monetization vectors but also requires careful guardrails to avoid commoditizing creator attention.
Strategic recommendations for 2026 (what to do now)
We recommend enterprises prioritize three parallel tracks that balance optionality with focus.
- Invest in composability, not ownership: Build or partner to provide modular identity and wallet experiences that can be embedded across consumer touchpoints. Prioritize APIs and developer SDKs that reduce friction for creators and third-party integrators.
- Design for recurring value: Reframe NFT products as membership, access, or utility layers that generate repeat engagement rather than single-sale events. Experiment with hybrid models—timed passes + secondary royalties + on-chain governance tokens—to align creator and community incentives.
- Lean into creator economics: Create pilot programs that incentivize top creators with clear revenue share and promotion mechanics; measure LTV:CAC and accelerate the ones that show community monetization beyond a single cohort.
- Build regulatory and compliance scaffolding now: Tokenized social interactions can trigger securities, consumer protection, and data-privacy obligations. Establish a cross-functional compliance playbook (legal, product, payments) before scale to avoid costly retrofits.
- Prepare for M&A and partnership plays: The mid-tier ecosystem contains assets that can accelerate timelines. Use the PW Consulting M&A playbook to validate tech fit, community strength, and tokenomics survivability before bid decisions.
- Measure what matters: Track a compact set of leading indicators—active wallets linked to economic behaviors, creator monetization frequency, secondary market liquidity, and revenue per engaged user—rather than vanity metrics.
Risk management and downside scenarios
Our scenario analysis identifies three structural risks that should be actively managed:
- Regulatory tightening: Sudden shifts in securities or consumer finance regulations could force product redesigns—maintain contingency technical architectures that permit rapid product pivots.
- Tokenomics fragility: Incentives that over-rely on speculative secondary market upside can collapse engagement—design multi-dimensional value capture (access, reputation, utility) to stabilize demand.
- Interoperability lock-in: Overly bespoke integrations can raise switching costs for users and partners; adopt open standards where possible to broaden market access.
What’s behind the curtain (and what you’ll get in the full report)
To respect the “preview” nature of this release, we’ve deliberately omitted segment-level dollar tables and regional breakouts in this press summary. The full PW Consulting SocialFi NFTs Market report contains:
- Granular historical and forecast tables (2020–2032) with scenario toggles and sensitivity analyses.
- Regional and application-level segmentation maps, including growth drivers and friction factors for each segment.
- Vendor scorecards and maturity assessments for the leading platforms and specialized providers, with suggested engagement models for enterprise partners.
- Detailed pilot templates, checklist for regulatory readiness, and an M&A scorecard tailored to SocialFi NFTs.
Closing perspective
For executives building 3–5 year plans, the SocialFi NFTs market represents a practical lever to monetize community, reimagine digital ownership, and create persistent creator–fan economic relationships. The numbers—a strong multi-year CAGR and a forecasted expansion into the billion-dollar range by the early 2030s—underline that this is a strategic market, not a transient novelty. That said, success will not come from replication of today’s leading products; it will come from disciplined product architecture, defensible tokenomics, and a partnership mindset that privileges composability and regulatory foresight.
PW Consulting’s full report equips you with the market models, playbooks, and vendor insights necessary to turn the promise of SocialFi NFTs into repeatable enterprise outcomes. Access the complete study on the PW Consulting site to unlock the datasets, segmental analysis, and tactical templates that support decisive 2026 planning.
For detailed analysis of this topic, please visit the official page: SocialFi NFTs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


