



Category: IT & Electronics
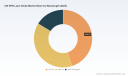
PW Consulting: CW DFB Laser Diode Market to Grow from USD 920.0 Million in 2025 to USD 1,592.15 Million by 2032 at 8.15% CAGR — Asia Pacific Leads with USD 416.7 Million
By PW Consulting, 2026-08-12
CW DFB Laser Diode Market: Strategic Imperatives for 2026 — PW Consulting Insight Brief
PW Consulting’s latest CW DFB Laser Diode Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes seven years of market dynamics and seven-year forward scenarios to equip executives with action-oriented intelligence for 2026. The market reached approximately USD 920.0 Million in 2025 and — at a compound annual growth rate (CAGR) of 8.15% across the forecast window — is projected to expand significantly through 2032. This briefing highlights the strategic signals that should shape capital allocation, product roadmaps, supplier strategy, and M&A playbooks over the next 12–18 months. In keeping with our “trailer” principle, we sketch the high-value implications and rigor of the report while preserving the detailed segment-level tables and proprietary forecasts for report subscribers.
SKR Filters Market
Why CW DFB Lasers Matter for 2026 Strategic Plans
-
Critical enabler for high-density optical interconnects: Continuous-wave distributed feedback (CW DFB) laser diodes are central to next-generation transceivers, co-packaged optics (CPO), and silicon photonics integrations that data centers and telecom operators are prioritizing for 800G–1.6T bandwidth classes.
Engineering Material Recycling Services Market -
Shift from component scarcity to differentiated supply: As capacity investments accelerate, the competitive battlefield is moving from simple supply constraints to differentiated product features — power-per-watt efficiency, wavelength stability in uncooled operation, and compliance with telecom reliability standards.
External High Power CW Light Source Market -
Investment horizon alignment: With the market already near USD 1 billion in 2025 and compelling growth ahead, 2026 is the inflection year for firms that want to lock in wafer capacity, qualification pipelines, and strategic partnerships to capture disproportionate share of growth through 2032.
Key Market Dynamics Shaping 2026 Decisions
-
AI-driven data center demand is the principal engine. Public announcements and product sampling by leading vendors indicate rising appetite for high-power CW sources tailored to silicon photonics and co-packaging. This is driving both new product launches and accelerated qualification cycles.
-
Reliability & standards tailwinds. Telcordia GR-468 guidance for non-hermetic, uncooled operation up to 85°C has become a hard requirement for many enterprise and hyperscale buyers. Qualification timelines can be a gating factor — firms that front-load testing and design-to-standard can outpace competitors.
-
Supply-side investments are materializing. Recent announcements indicate multi-fold capacity increases in InP epitaxial processing and chip fabrication. The competitive advantage will accrue to players who pair capacity with robust yield and thermal-performance roadmaps.
-
Product differentiation versus commoditization. As higher power devices (including QD-based platforms and advanced etched-facet processes) enter the field, value will cluster around thermal stability, single-frequency purity, and packaging options compatible with silicon photonics ecosystems.
Competitive Landscape: Who to Watch
The market exhibits moderate concentration: the top three suppliers account for roughly half the market, while the top five approach two-thirds — a structure that favors both incumbents with scale and nimble specialists offering technology differentiation.
-
MACOM (Lowell, MA, USA) : Known for etched-facet high-power CW DFB diodes optimized for uncooled operation and silicon photonics integration. Strength lies in ruggedized devices for datacom environments and patented manufacturing techniques that support higher operating temperatures.
-
Coherent Corp. (Saxonburg, PA, USA) : Focused on high-efficiency chips for ultra-high-bandwidth transceivers and AI data center optics; recent sampling of low-noise, multi-hundred-milliwatt CW devices signals an aggressive push into co-packaged optics segments.
-
Broadcom (San Jose, CA, USA) : Leverages scale and system-level partnerships; offers edge-emitting lasers targeted at silicon photonics and external modulator systems with emphasis on volume and qualification readiness.
-
Furukawa Electric (Tokyo, Japan) : Investing heavily in capacity expansion to meet high-output demand — a development that will reshape supply-side bargaining power when new lines come online.
-
Specialists and emerging suppliers — Innolume, DenseLight, Eblana, SemiNex, Frankfurt Laser Company, RPMC Lasers — are delivering complementary strengths: quantum-dot and InP platforms, wide wavelength ranges, and application-specific devices for sensing and LiDAR. Their agility in customization presents partnership opportunities for system integrators.
Recent Signals and Tactical Impacts
-
Capacity expansion announcements by established manufacturers point to a near-term easing of supply constraints. However, capacity alone is insufficient: wafer-to-package yield improvement and test infrastructure scale will determine who can fulfill hyperscaler timelines.
-
Product sampling of high-power, low-noise CW DFB lasers for co-packaged optics underscores a shift from proof-of-concept to deployment testing. Buyers should expect compressed qualification cycles and must prepare to accelerate in-house test benches and thermal stress validation.
-
New entrants and regional players are launching high-output uncooled chips, intensifying competition on price and customization. The net effect is bifurcated: broader availability for system builders, and margin pressure for suppliers that fail to articulate premium differentiated features.
Actionable Recommendations for 2026
-
Secure mid-term wafer and test capacity now. Lead times for epitaxial wafers and specialized chip fabrication can extend for quarters; execute supply agreements with step-down volume rights and built-in yield-improvement milestones to avoid last-minute premium sourcing.
-
Prioritize Telcordia-grade qualification early. Integrate GR-468-compliant testing into prototype cycles to reduce rework. Buyers who insist on supplier-provided qualification packages will shorten deployment timelines and lower integration risk.
-
Differentiate through system-level co-optimization. Collaborate with silicon photonics and modulator partners on co-design: electrical-thermal interfaces, SERDES alignment, and packaging thermal management will determine real-world performance for 800G+ modules.
-
Establish a two-tier supplier strategy. Combine a scale partner for validated high-volume needs with one or more specialist vendors for product innovation and rapid customization. This hedges supply risk while preserving access to disruptive technologies.
-
Scan M&A and strategic investment targets. Focus on firms with unique epitaxial IP, advanced facet or QD approaches, and proven thermal-stability roadmaps. Small, targeted acquisitions can accelerate roadmaps and secure capacity without incurring full greenfield timelines.
-
Build in-field monitoring & service contracts. For hyperscalers and cloud providers, operational uptime is king. Negotiate service-level agreements that include burn-in, lifetime drift characterization, and rapid replacement clauses tied to agreed KPIs.
Risk Factors and Early Warning Indicators
-
Supply-chain execution risk: delays in epitaxial capacity ramp or yield shortfalls — monitor wafer fab utilization rates and disclosed yield improvements from key suppliers.
-
Standards shift risk: sudden changes in thermal or reliability expectations by hyperscalers could render current device roadmaps suboptimal — track qualification criteria and buyer-specific test protocols closely.
-
Competitive pricing & commoditization risk: as higher-power devices proliferate, margins will compress unless suppliers demonstrate clear, measurable system benefits.
What the Full PW Consulting Report Delivers
Our comprehensive market study includes:
-
Proprietary revenue and shipment forecasts across 2020–2032 with multiple scenarios and sensitivity analyses;
-
Detailed supplier scorecards covering technology readiness, capacity roadmaps, reliability practices, and go-to-market models;
-
Supply-chain heatmaps that identify bottlenecks at wafer, chip, and packaging stages and recommend mitigation pathways;
-
Commercial playbooks for OEMs, hyperscalers, and component suppliers outlining procurement templates, qualification milestones, and contractual levers to de-risk 2026 deployments;
-
An M&A and investment matrix highlighting target profiles, valuation benchmarks, and integration risks;
-
Scenario-based guidance tied to market triggers — e.g., accelerated AI capex, disruptive packaging breakthroughs, or regulatory tightening — with tactical responses for each.
Conclusion — The 2026 Win Curve
2026 will separate the firms that merely survived the tight component era from those that capture disproportionate value in the next growth phase. The combination of rising AI-driven bandwidth demand, active capacity investments, and increasingly stringent reliability expectations means the market is maturing from scarcity to selective competition. Executives who treat 2026 as a decisive year — securing constrained inputs, accelerating qualification, and aligning product features with system-level value — will establish defensible positions into the 2030s.
PW Consulting’s CW DFB Laser Diode Market report translates these dynamics into a practical, executable roadmap. For organizations preparing capital budgets, supplier strategies, or M&A pipelines in 2026, the report is designed to convert market intelligence into measurable outcomes. Detailed segment tables, supplier-specific forecasts, and the full set of tactical templates are available in the full report.
To access the complete findings and subscription options, please visit the PW Consulting research portal for the CW DFB Laser Diode Market Report.
For detailed analysis of this topic, please visit the official page: CW DFB Laser Diode Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Subsea Umbilical Service Market to Expand at 4.82% CAGR During 2026–2032
By PW Consulting, 2026-08-12
Subsea Umbilical Service Market 2026: Strategic Imperatives from PW Consulting's New Report
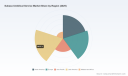
PW Consulting today releases its authoritative Subsea Umbilical Service Market report — an operationally focused intelligence product designed to inform boardrooms, procurement teams, and project planners making critical decisions in 2026. Built on a detailed historical review (2020–2025) and rigorous scenario modelling for 2026–2032, the report quantifies a market expanding at a steady compound annual growth rate (CAGR) of 4.82%. Our baseline sizing shows the market at approximately USD 1,450.0 Million in 2025, rising to an anticipated USD 2,015.65 Million by 2032 under the central scenario. These headline metrics frame a market that is predictable in aggregate growth yet complex and opportunity-rich at the asset and supply-chain level.
Compressor for Car Refrigerator Market
Why this report matters for 2026 decisions
-
Timing and capital allocation: With multi-year tender cycles and long lead times for umbilical manufacture and testing, 2026 is a pivotal year for finalizing supplier selection, securing manufacturing slots, and hedging material exposures.
Elevator Advertising Machine Market -
Risk-adjusted procurement: Rising raw material pressures and regulatory rigor are shifting the economics of umbilical projects; teams that deploy scenario-based CAPEX/OPEX models will materially improve tender competitiveness and lifecycle cost performance.
Dry Powder Storage Tanks Market -
Operational resilience: The forecasted market expansion creates capacity stress points for manufacturing and installation resources. Operators and EPCs need playbooks for contingency contracting and integrated lifecycle service agreements.
What’s inside the report — practical content for immediate use
-
Market sizing and forecast methodology: transparent assumptions, base-year calibration (2025), and sensitivity runs across commodity, schedule, and demand scenarios.
-
Actionable supplier benchmarking: capability matrices, manufacturing footprint analysis, technology strengths, and service scope comparisons for incumbent and emerging suppliers.
-
Procurement playbook and contract archetypes: RFP templates, penalty/bonus frameworks tied to installation milestones, and recommended warranty and spares clauses to de-risk projects.
-
CAPEX/OPEX modelling templates: modelled case studies that convert supply constraints and material price shifts into project-level NPV impacts and break-even analyses.
-
Qualification, testing & certification guide: practical checklists and test-cycle timelines to accelerate qualification without compromising compliance.
-
Supply chain mitigation strategies: recommended hedging approaches, alternative sourcing tactics, and manufacturing partnership structures to preserve schedule certainty.
-
Technology and service roadmaps: adoption pathways for digital monitoring, predictive maintenance, and integrity management that reduce lifecycle spend.
-
Executive decision support: a one-page strategic dashboard summarising the scenarios and recommended next-step investments for 2026.
Market dynamics and strategic implications
The subsea umbilical services market is being shaped by three concurrent dynamics that will determine winners and losers in 2026 and beyond. First, demand fundamentals remain anchored by continued investment in deepwater oil & gas developments and tie-back projects. This structural demand underpins the market’s mid-single-digit CAGR and offers a predictable backdrop for capacity planning.
Second, raw material and input-cost trends are exerting upward pressure on CAPEX. Increases in prices for high-grade steels and advanced polymer components — and the widening use of specialized alloys and polymer composites for dynamic steel tube umbilicals — are changing supplier cost structures. Procurement functions must therefore integrate material-price sensitivity into bid evaluation and consider forward-purchase or index-linked contract clauses.
Third, regulatory and qualification demands are rising. Modern offshore projects require rigorous testing, certification, and environmental compliance regimes. These requirements extend project timelines and add direct costs, but they also create a premium for suppliers with proven qualification capabilities and integrated testing facilities.
Competitive landscape — who matters and why
The market exhibits moderate concentration: the top three suppliers account for a significant share of industry revenues, with the top five representing the majority of capacity. This concentration reflects the scale and technical barriers to entry inherent in subsea manufacturing, installation, and lifecycle services. For buyers, the implication is clear: strategic supplier relationships — rather than transactional spot-buying — often yield better outcomes for schedule certainty and total cost of ownership.
-
JDR Cable Systems (Hartlepool, UK) — A leading specialist in subsea control umbilicals with strong manufacturing and testing capability. Recent contract awards illustrate continued competitiveness in both fabrication and integrated testing services. JDR is a go-to partner for operators prioritising bespoke control-system solutions and reliable delivery discipline.
-
TechnipFMC (London / Houston) — One of the few players with deep SURF engineering integration, combining design, manufacture, and full lifecycle services. Their global footprint and engineering depth make them an anchor supplier for complex SURF packages that require end-to-end integration.
-
Oceaneering International (Houston) — Known for a broad service offering including manufacturing, installation, repair, and refurbishment across both thermoplastic and steel tube technologies. Oceaneering’s recent Gulf of Mexico engagements highlight strengths in project execution for dynamic and technically demanding systems.
-
Aker Solutions (Fornebu) — Specialises in integrated subsea systems with an emphasis on engineering excellence and lifecycle support. Strong candidate for projects where long-term service partnerships are a priority.
-
Prysmian Group (Milan) — Focused on high-performance cable technologies and deepwater solutions. Their materials engineering capability is attractive where cable performance under extreme conditions is a critical differentiator.
-
OneSubsea (SLB, Houston) — Delivers robust control and power umbilical systems paired with field-proven service models. Their systems integration competence is valuable for operators seeking standardised, scalable solutions.
-
Subsea 7 (Luxembourg) — A leader in EPC and offshore installation, instrumental where complex installation sequencing and vessel coordination determine project success. Recent awards underscore their continuing role in integrated offshore campaigns.
-
Nexans (Paris) — Strong in high-quality cabling and subsea manufacturing with a heritage in electrical and fiber-optic systems; valuable for electrification trends.
-
Umbilicals International (UK) — Focused on design and manufacture for harsh environments, offering differentiated materials and bespoke solutions for high-performance applications.
Recent contract activity — including major fabrication and installation awards in 2025–2026 — highlights how incumbents are securing project pipelines and reinforcing manufacturing commitments. For 2026 procurement cycles, these developments should inform negotiation posture, lead-time expectations, and the relative premium for integrated versus modular supply solutions.
Recommendations for 2026 decision-makers
-
Embed material-price sensitivity and schedule-risk premiums into bid evaluation and project sanction decisions. Use the report’s CAPEX/OPEX templates to stress-test investment cases.
-
Pursue collaborative contracts with preferred suppliers that include capacity reservation clauses, staged payments tied to delivery milestones, and incentivised warranties to align interests.
-
Invest in supplier qualification acceleration: pre-approve testing and certification pathways, and co-fund early-stage qualification where strategic suppliers lack certain credentials.
-
Diversify manufacturing exposure where feasible — combine established global suppliers with regional fabricators for balance between technical capability and cost efficiency.
-
Adopt digital integrity and predictive-maintenance suites to convert monitoring data into lower OPEX and extended umbilical life, and demand interoperability in supplier proposals.
-
Consider bolt-on M&A or strategic partnerships to close capability gaps rapidly, particularly around installation vessels, testing facilities, or advanced materials engineering.
How to use PW Consulting’s report
This report is structured as an operational playbook: not just a market narrative but an executable toolkit. Procurement teams will find RFP templates and supplier scorecards; project teams will find schedule and testing roadmaps; executives will find scenario-driven dashboards that translate market movement into strategic options. Importantly, the full report provides detailed segmentation, project pipelines, and supplier-specific scorecards that we have deliberately summarised here to preserve the report’s role as the definitive source of record.
For executives and practitioners preparing for 2026 tenders, sanctions, or strategic sourcing, the PW Consulting Subsea Umbilical Service Market report is intended to shorten decision cycles, reduce implementation risk, and unlock value through smarter procurement and lifecycle management. To access the complete dataset, supplier matrices, and bespoke scenario outputs, please visit our report landing page to request the full brief and supporting Excel models.
For detailed analysis of this topic, please visit the official page: Subsea Umbilical Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Product Passport Software Market to Expand at 22.5% CAGR, Sparking a Global Traceability Boom
By PW Consulting, 2026-08-05
Digital Product Passport Software Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market research report on Digital Product Passport (DPP) software provides an executive-grade roadmap for companies that must convert regulatory obligation into competitive advantage in 2026. Built on a 2020–2025 historical foundation with a 2026–2032 forecast horizon, the study quantifies a high-growth market (22.5% compounded annual growth) and lays out the operational, regulatory and commercial playbooks that procurement, compliance, product and IT leaders will need to act decisively this year.
Digital Product Passport Software Market
Why 2026 is a make-or-break year
Several synchronized developments make 2026 the tactical pivot point for DPP investments. The European Union’s central DPP registry is scheduled to become operational in mid‑2026, and sectoral mandates — notably for energy storage and batteries — impose phased compliance obligations beginning in the immediate 2026–2027 window. At the same time, DPP systems that capture or link to personal data must satisfy stringent privacy regimes, which create legal and operational constraints that must be embedded into system design from day one.
Digital Product Passport Software Market
For enterprises, this confluence creates a binary outcome: early movers that align product data, lifecycle tracking and data governance will avoid market access risk, reduce compliance cost and unlock new services (e.g., certified resale marketplaces and circularity-enabled business models); delay increases regulatory exposure, rework costs and procurement friction with downstream customers and public buyers.
Digital Product Passport Software Market
What this report delivers — practical intelligence, not platitudes
- Proven market-sizing and forecasting methodology tied to adoption scenarios and regulatory timelines, enabling defensible investment cases for 2026 boardrooms.
- Actionable vendor diligence templates and a calibrated vendor landscape that highlights technical differentiation, interoperability, and go‑to‑market partnerships.
- Implementation playbooks: pilot scoping, integration templates (ERP/PLM/WMS), API and data schema guidelines, and a KPI set for production readiness and roll‑out phases.
- Regulatory compliance mapping across priority sectors, with practical checklists to translate ESPR and registry requirements into procurement and engineering specifications.
- TCO and cloud‑ops modelling that surfaces hidden operating costs — from data ingestion and governance to idle cloud capacity — and provides optimization levers for SaaS and hybrid deployments.
- Case studies and procurement artifacts including RFP language, SLA clauses for data portability, and a buyer’s scorecard for privacy, traceability and circularity capabilities.
The report is structured to support rapid decision cycles: from an initial compliance risk assessment to a piloting roadmap and an enterprise‑scale roll-out plan. Note: the full study contains the detailed segmented tables, vendor scorecards and model outputs necessary for procurement execution; those are available in the complete report.
Market dynamics: growth drivers and operational risks
DPP demand is driven by three converging forces. First, regulation is the primary accelerator — binding requirements force manufacturers and brand owners to capture provenance, material and chemical data in machine‑readable formats. Second, commercial opportunity is emerging as traceability becomes a service: authenticated ownership, verified repair histories and certified resale channels create new revenue lines. Third, corporate sustainability programs are increasingly using DPP data to substantiate claims, feed lifecycle assessments and support circularity KPIs.
These drivers underpin robust market expansion: the DPP software market has grown materially since 2020 and is forecast to sustain double‑digit expansion through the early 2030s. The size and trajectory of this market make it one of the fastest growing application domains within enterprise supply‑chain software, and the investment planning horizon for most organizations must now be measured in quarters, not years.
But growth brings practical risks. Data governance and privacy — including consent management and breach notification obligations — materially change solution architecture. Standards fragmentation and vendor lock‑in threaten portability, while cloud operating inefficiencies can inflate ongoing costs if not actively managed. Finally, interoperability between product IDs, supplier systems, and registries is an execution challenge that multiplies with the number of product lines and geographies.
Competitive landscape — who matters and why
The market is populated by specialist vendors, platform incumbents, and industry‑vertical players. Our report examines strategic positioning and product architecture implications for leading providers. Highlights:
- Spherity (Cologne) — focused DPP solution for batteries with compliance capabilities aimed at lifecycle management and aftermarket integration; a strong fit for manufacturers facing battery passport obligations.
- Kezzler (Oslo) — a connected products platform that emphasizes digital identities and GS1 Digital Link compatibility, suited to brands seeking wide supply‑chain visibility and standards alignment.
- TrusTrace (Stockholm) — end‑to‑end DPP for fashion and textiles with supplier traceability, consumer‑facing interfaces and a clear roadmap for sector‑specific registration workflows.
- Arianee (Paris) — blockchain‑native platform oriented to luxury and high‑value goods, emphasizing ownership and provenance capabilities that enable premium services.
- 3E (3E Exchange, Carlsbad) — combines DPP with chemical and regulatory data management, attractive to companies with complex hazardous‑materials or restricted‑substance obligations.
- Renoon, iPoint‑systems, Circularise, Avery Dennison and Carbonfact — each brings distinct strengths spanning sustainability data automation, material traceability, label/hardware integration and lifecycle emissions calculations.
Recent industry moves underscore the transition from pilots to production. Notable developments include strategic partnerships and pilot announcements across apparel and industrial sectors, collaboration initiatives to advance data integration at scale, and public confirmations of registry timelines. These signals confirm a market shifting rapidly from proof‑of‑concept to compliance‑driven production deployments.
Practical guidance for enterprise decision‑makers in 2026
- Start with a compliance exposure map: identify which product lines hit registry or ESPR obligations and what data attributes are required for market access.
- Scope pilots around high‑risk, high‑value product families (e.g., batteries, regulated textiles). Use pilots to validate integration patterns to ERP/PLM and to exercise registry workflows.
- Adopt a portability‑first procurement stance: require open APIs, GS1 compatibility, and data export formats to avoid later migration costs.
- Design privacy and consent into the data model: perform Data Protection Impact Assessments early and include breach‑response SLAs in vendor contracts.
- Model cloud operating costs separately from license fees: include estimates for storage, compute, and a governance uplift to limit idle spend.
- Insist on LCA and chemical‑module compatibility where environmental claims are strategic — integration with certified LCA engines speeds compliant DPP publishing.
- Build an internal cross‑functional team (product, compliance, procurement, IT, legal) with clear sprinted milestones tied to the registry operational dates.
Implementation runway and investment framing
Enterprises must treat DPP rollout as a multi‑stage transformation rather than a point purchase. The recommended phased approach is: compliance triage and minimum viable passport; platform selection and pilot integration; scale‑up with registry submission workflows; and finally monetization via circularity services. The market’s projected growth and the regulatory timetable justify allocating dedicated resources to DPP initiatives in 2026 to avoid both non‑compliance and missed commercial upside.
When presenting investment cases, use the report’s TCO templates to compare cloud subscription models vs. hybrid deployments, quantify avoided penalties and procurement exclusions, and model the value of new revenue streams enabled by certified product data.
Conclusion — a strategic decision, not an IT project
PW Consulting’s Digital Product Passport Software Market report turns regulatory pressure into an operational blueprint for value creation. For organizations operating in regulated sectors, 2026 is not a grace period — it is the execution window. The full report contains the granular segmentation, vendor scorecards, downloadable procurement artifacts and financial models necessary to mobilize programs within this calendar year.
To access the complete dataset, vendor comparisons and downloadable implementation checklists, consult the full report on the PW Consulting website. The summary above signals where value will be captured; the full study shows exactly how to capture it.
For detailed analysis of this topic, please visit the official page: Digital Product Passport Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Video Inspection Robot Market Poised to Rise from USD 2,450.0 Million in 2025 to USD 4,158.62 Million by 2032 at a 7.85% CAGR
By PW Consulting, 2026-08-05
Video Inspection Robot Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
Executive preview
PW Consulting today publishes a forward-looking industry briefing that synthesizes a multi-year analysis of the global Video Inspection Robot market. Built on a detailed historical base (2020–2025) and a robust forecast window (2026–2032), the study models market dynamics across technology, procurement, regulation and supply-chain stresses that will shape enterprise decisions in 2026 and beyond. Our core quantitative finding: the market, measured in USD (Million), grows at a compound annual growth rate (CAGR) of 7.85% from a base-year value in 2025 to a materially larger global market by 2032. This briefing explains why that trajectory matters to operators, OEMs, investors and procurement leaders — and what they should do now to convert growth into a competitive advantage.
Video Inspection Robot Market
Why this report matters for 2026 decision-making
-
Timing investments against an inflection curve: After sustained expansion through 2025, market momentum entering 2026 creates a narrow window for buyers to secure capacity, lock in technology roadmaps and negotiate favorable commercial terms before competitive pressure and component lead-times increase total cost of ownership.
Video Inspection Robot Market -
Aligning product strategy with service monetization: As video inspection systems move from point tools toward continuous-condition-monitoring platforms, vendors that couple hardware with analytics and recurring services capture higher lifetime value. The report shows practical pathways for product-to-service transitions that minimize margin erosion for incumbents and facilitate faster scale-up for entrants.
Video Inspection Robot Market -
Mitigating regulatory and supply-chain risk: Emerging policy actions and tariffs, combined with ongoing shortages of high-precision sensors and optics, create an execution risk vector that can surprise unprepared buyers. The study quantifies exposure across procurement strategies and offers scenario templates to stress-test supplier continuity plans.
-
Prioritizing R&D and M&A plays: With the sector exhibiting a measured level of concentration but substantial fragmentation at regional and niche levels, strategic acquisitions and targeted R&D investments are the fastest routes to secure technical differentiation and accelerate route-to-market.
Key quantitative takeaways (selective)
Our model uses 2025 as the base year and extends through 2032. Historical analysis (2020–2025) documents steady expansion in demand and ASPs driven by greater adoption of high-definition imaging, on-board processing and remote operations. Projecting forward to 2032, the market more than doubles in scale from the 2025 baseline at a 7.85% CAGR, reflecting both hardware replacement cycles and growth in recurring analytics and services.
What the full report delivers
-
Proprietary market-sizing and forecast model (2026–2032) with scenario variants — conservative, base and accelerated — that stakeholders can adapt to internal financial models.
-
Detailed vendor landscaping and a vendor-readiness playbook: comparative profiles, go-to-market strengths, technology stacks and a proprietary capability matrix (note: the capability scores and detailed splits are available in the full report).
-
Technology roadmaps: functional trajectories for autonomy, AI-assisted defect recognition, 3D laser profiling and sensor fusion, including time-to-adoption benchmarks and integration risk assessments.
-
Buyers’ toolkit: total cost of ownership (TCO) templates, contracting clauses to manage regulatory and tariff risk, and pilot-to-scale deployment blueprints for municipal, industrial and petrochemical environments.
-
Supply-chain diagnostics: single-point-of-failure mapping for critical optical and sensor components, alternatives assessment and onshore/nearshore cost-impact modelling.
-
M&A and partnership playbook: target screening criteria, valuation multipliers adjusted for synergies in software and services, and integration checklists for rapid capability absorption.
Competitive landscape — who to watch
The market is populated by a mix of specialized niche vendors and larger industrial RVI players. Our report profiles market participants across product archetypes and commercial models; below are strategic highlights on several notable suppliers and recent industry movements that will influence the competitive runway in 2026.
-
Envirosight LLC — A market-recognized specialist in sewer and pipeline inspection systems; recent product introductions emphasize HD video and AI-assisted defect recognition, signaling a push to embed analytics into the core offering and capture recurring revenue streams.
-
Deep Trekker Inc. — Known for versatile crawlers and underwater ROVs; competitive strengths include modularity and field ruggedization that suit both confined-space and submerged inspections.
-
Wuhan Easy‑Sight Technology Co., Ltd. — A producer of pipeline CCTV robots with integrated sonar and long-range detection; continues to expand sensing capability sets that are increasingly important in opaque or hard-to-access environments.
-
IBAK Helmut Hunger GmbH & Co. KG — Focuses on high-end modular systems combining panoramic video with laser profiling and 3D mapping; recent product updates move the market toward richer data capture for engineering-grade assessment.
-
CUES Inc. — A supplier of truck-mounted and crawler solutions, deeply embedded in municipal procurement channels; strong aftermarket and service networks are a competitive moat.
-
RedZone Robotics — Positions on autonomy and large-diameter pipe inspection, where robotics replace hazardous man-entry operations; expect this segment to be a focus for industrial customers seeking productivity gains.
-
Mini‑Cam Ltd., iPEK International, Waygate Technologies (Baker Hughes), Inspector Systems — Each brings regional strengths, compact-system expertise or industrial certification capabilities that matter depending on the use case (e.g., ATEX/IECEx for explosive environments).
Recent industry developments to factor into strategy
-
Product innovations are accelerating: industry-leading launches in late 2025 and early 2026 introduced AI-assisted inspection, wireless CCTV crawlers and integrated 3D profiling — features that are rapidly becoming procurement differentiators.
-
Regulatory and trade dynamics are creating cost and compliance pressures: trade investigations and tariff actions initiated in 2025, together with tariffs on certain electronic components, have increased the imperative for supply-chain diversification and local content strategies.
-
Component constraints persist: shortages and lead-time volatility for high-precision sensors and optical assemblies remain a material execution risk for firms relying on a single-source import model.
Market structure and consolidation outlook
Our concentration analysis shows a market that is neither highly consolidated nor completely fragmented — a structure that favors strategic consolidation through targeted M&A and partnerships. Incumbents that can couple hardware scale with software differentiation will create defensible positions; smaller innovators with specialized sensing or autonomy capabilities are attractive acquisition candidates for global platform providers looking to accelerate capability aggregation.
Strategic recommendations for 2026
-
Prioritize modularity and software monetization: design hardware that supports multiple payloads and enable analytics-as-a-service to create recurring revenue and higher margins.
-
De-risk supply chains proactively: qualify alternative suppliers for optics and sensors, and evaluate nearshoring or component re-engineering to reduce exposure to tariffs and export controls.
-
Invest in certification and safety readiness: gaining ATEX/IECEx and similar certifications opens doors in offshore and petrochemical segments where barriers to entry remain high.
-
Use pilots to demonstrate ROI and accelerate adoption: short, tightly scoped pilot programs that deliver measurable OPEX savings and safety improvements are the most effective route to scaled contracts.
-
Prepare M&A playbooks with modular integration plans: focus on targets that fill software gaps or bring proven autonomous capabilities that can be rapidly integrated into your platform.
Methodology and transparency
The study uses a mixed-methods approach: bottom-up device and service modeling, primary interviews with OEMs and end-users, secondary-source triangulation, and sensitivity testing across regulatory and supply-chain scenarios. Base year is 2025; historical windows cover 2020–2025 and our forecast extends 2026–2032. Our datasets, model assumptions and scenario logic are included in the full report and are provided in spreadsheet form for client validation and adaptation.
Next steps and how to access the full study
This briefing is intended to be an executive “trailer” that highlights the strategic value of PW Consulting’s full Video Inspection Robot Market report for decision-makers preparing budgets, product roadmaps and M&A pipelines in 2026. The full report contains the granular segmentation, vendor scores, downloadable models and implementation templates required to operationalize the insights summarized here. To obtain the comprehensive study and supporting datasets, please visit the PW Consulting reports page or contact our industry research team for a customized briefing and licensing options.
For detailed analysis of this topic, please visit the official page: Video Inspection Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Epoxy Electrocoating Market Set to Expand at a 4.5% CAGR Through 2032
By PW Consulting, 2026-08-05
Epoxy Electrocoating Market: Strategic Imperatives for 2026 — PW Consulting Market Insights
As organizations plan capital allocation and commercial strategies for 2026, PW Consulting’s latest Epoxy Electrocoating Market report delivers the sector-level intelligence required to make those decisions with confidence. Our analysis synthesizes historical performance (2020–2025), a 2026 base-year assessment, and scenario-based forecasts through 2032. Key topline context: the global epoxy electrocoating market expanded from USD 1,500 Million in 2020 to USD 1,850 Million in the 2025 base year, and is projected to grow at a 4.5% CAGR across the 2026–2032 forecast window, reaching roughly USD 2,517.6 Million by 2032. This growth trajectory masks material heterogeneity beneath the surface — an important consideration for executives looking to prioritize investments, secure margins, and navigate supply-chain volatility in 2026.
Epoxy Electrocoating Market
Why this report matters for 2026 decisions
- Actionable macro-to-micro linkage: We connect macro growth and raw-material volatility to plant-level economics, enabling CFOs to stress-test capex and procurement scenarios against realistic price and demand paths.
- Competitive positioning: With market concentration materially skewed toward a handful of incumbents (top 3 players account for a majority share and top 5 are substantially more dominant), the report outlines how scale, technology, and channel relationships translate into durable advantage.
- Risk and opportunity mapping: From antidumping rulings to regional feedstock shocks, we quantify the short- and medium-term impacts on margins and availability, and propose mitigants suitable for both suppliers and end-users.
Market dynamics — structural drivers and near-term shocks
The epoxy electrocoating market is responding to two simultaneous forces: steady end-market expansion supported by automotive and industrial demand, and episodic supply-side pressure driven by petrochemical feedstock volatility and trade-policy shifts. On the supply side, epoxy resin pricing has moved sharply in recent months — market data shows meaningful month-over-month increases in key regions — exerting upward pressure on finished-coating costs. At the same time, regulatory interventions and trade measures enacted in recent years have reshaped sourcing strategies and created near-term dislocations for firms dependent on cross-border resin flows.
Epoxy Electrocoating Market
Notable developments that inform the 2026 playbook include supplier price revisions from major resin producers, capacity investments from strategic coatings manufacturers, and regulatory outcomes that affect regional sourcing economics. PW Consulting’s scenario work incorporates these events to produce probabilistic forecasts and suggested decision triggers for procurement, pricing, and manufacturing investments.
Epoxy Electrocoating Market
Competitive landscape — what to watch in 2026
The sector is anchored by a mix of global coatings majors and regional specialists. Key participants we profile in the report include:
- PPG Industries, Inc. (Pittsburgh, PA, USA): A global leader with established cathodic epoxy electrocoat platforms targeted at automotive and heavy-duty industrial customers. Strengths include branded product families focused on corrosion resistance and consistent film builds across complex geometries.
- Axalta Coating Systems (Philadelphia, PA, USA): Offers cathodic epoxy e-coat lines designed for OEM automotive and industrial applications, emphasizing mechanical properties and process integration for high-throughput lines.
- BASF SE (Ludwigshafen, Germany): Competes with a technology-led portfolio delivering high throw power and sustainability features; recent capacity buildouts underscore its push into regional OEM supply chains.
- The Sherwin-Williams Company (Cleveland, OH, USA): Positions around edge coverage and corrosion performance for heavy machinery and industrial markets, leveraging distribution reach and formulation expertise.
- Nippon Paint Holdings Co., Ltd. and Kansai Paint Co., Ltd. (Japan): Regional champions with strong automotive OEM ties and formulation innovations such as low-temperature curing and low-voltage application capability.
- Regional suppliers (e.g., KCC Corporation, Tatung Fine Chemicals): Maintain strong footholds in Asia and selected industrial segments, often competing on service, localization, and bespoke formulation work.
Market concentration metrics indicate a consolidated competitive set: the top three players hold the majority of market share, and the top five approach three-quarters of the market. This concentration favors scale players in contracting cycles, but it also creates opportunity windows for nimble specialists and formulators that address niche performance demands or regional supply gaps.
Supply-chain and raw-material sensitivity — implications for pricing and availability
Raw-material volatility is the principal immediate risk to margins. Recent industry intelligence documents significant regional increases in epoxy resin prices, and major resin producers have announced upward price revisions driven by crude and petrochemical feedstock pressures. Separately, antidumping and countervailing duty determinations affecting imports from several Asian suppliers have compelled buyers and sellers to reassess sourcing strategies. PW Consulting’s supply-chain module maps the sourcing elasticity of epoxy resin and curing agents for the electrocoating value chain, offering hedging and contract-design recommendations tailored by regional exposure and production footprint.
Report contents — practical sections designed for executables
Our report is built to be operationally relevant to C-suite and business-unit leaders. Core deliverables include:
- Topline market sizing and growth scenarios: historical series (2020–2025) and base-year assessment (2025) with three demand scenarios (conservative, base, upside) through 2032.
- Segmentation and end-use analysis: detailed regional, formulation (one-component vs. two-component), and application-level (automotive, industrial machinery, appliances, others) breakdowns, with sensitivity testing for each node. (Note: granular tables and company-level segment revenues are available in the full report.)
- Supply-chain risk and raw-material dashboard: price-trend analytics, supplier concentration maps, and contingency playbooks for resin and curing-agent scarcity.
- Competitive intelligence and capability benchmarking: product- and technology-mapped profiles for leading suppliers, R&D focus areas, manufacturing footprints, and M&A activity monitoring.
- Policy and regulatory impact assessment: trade actions, environmental and VOC compliance trends, and how these influence sourcing and processing choices.
- Strategic playbook: prioritized actions, quick-win tactics, and a three-year roadmap for procurement, manufacturing, and commercial teams.
Strategic recommendations for 2026
PW Consulting’s synthesis produces a set of priority actions for market participants, organized by strategic objective and time horizon.
- Protect margins through proactive procurement: Negotiate multi-year supply agreements with volume flexibility, institute index-linked pricing mechanisms, and explore forward purchasing of critical feedstocks where balance-sheet capacity allows. Given recent supplier price revisions and region-specific resin surges, firms should run stress tests that assume sustained elevated resin costs for 18–24 months.
- Prioritize capacity and footprint agility: For coatings manufacturers, incremental capacity investments should be targeted to sites that reduce freight and import exposure—particularly in regions where trade remedies have increased landed costs. Expand toll-manufacturing arrangements to shift fixed costs off balance sheets and speed entry into adjacent geographies.
- Differentiate via formulation and process integration: R&D should concentrate on reducing total cost of ownership for end-users—improvements such as faster cure cycles, lower bath maintenance, and reduced volatiles will command a premium. OEM-facing suppliers must align product roadmaps with assembly-line electrification and lightweighting trends.
- Pursue targeted partnerships and M&A with discipline: Use bolt-on acquisitions or strategic JV structures to access localized production licenses, fill portfolio gaps, or gain rapid access to specialized low-temp or low-voltage formulations. Defense against supply disruption via vertical integration should be evaluated on a case-by-case basis.
- Embed regulatory and trade scenario planning into commercial KPIs: Incorporate alternative sourcing scenarios into sales agreements and price-adjustment clauses. For downstream manufacturers, build dual-sourcing capabilities for critical components to avoid production stoppages.
- Invest in sustainability as a margin-preserving lever: Products with demonstrable lifecycle benefits or reduced environmental compliance burden create stickier customer relationships and can justify higher ASPs in key OEM accounts.
Decision triggers and monitoring framework
To operationalize the analysis, the report provides a compact set of decision triggers linked to monitored indicators. Examples include:
- Material-cost trigger: sustained regional resin price increases beyond pre-defined thresholds that activate pricing pass-throughs or hedging layers.
- Demand trigger: OEM production adjustments or new model ramps that re-weight regional demand forecasts and justify short-cycle capacity allocation.
- Policy trigger: new trade measures or antidumping outcomes that shift landed cost calculus and trigger sourcing reconfiguration.
What we intentionally withhold in this public summary
In keeping with our “teaser” principle, this executive summary highlights analytical depth and actionable guidance while withholding some of the granular datasets that drive tactical decisions. The full PW Consulting Epoxy Electrocoating Market report contains the complete set of regional and application-level split tables, company-level revenue breakdowns, plant-by-plant capacity maps, and contract-template clauses that are essential for immediate deployment in 2026 procurement and commercial negotiations. Those granular exhibits are available through the report portal and are provided to clients with bespoke briefing options.
Closing perspective
The epoxy electrocoating market is maturing — steady growth underpinned by durable end-use demand is colliding with episodic supply-side shocks and policy-driven rebalancing. Successful firms in 2026 will be those that move beyond simple cost-cutting and instead adopt a suite of coordinated responses: proactive procurement and hedging, selective capacity and partnership investments, differentiated formulation roadmaps, and disciplined commercial triggers tied to monitored market indicators. PW Consulting’s report equips leaders with the data set, scenario toolkit, and strategic playbook to operationalize these responses and capture the value embedded in a market expected to grow to approximately USD 2.5 billion by 2032 under our base-case.
For access to the full dataset, detailed segmentations, and customizable briefings, please consult the report portal or contact PW Consulting’s Epoxy Electrocoating practice for a tailored executive session.
For detailed analysis of this topic, please visit the official page: Epoxy Electrocoating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pod Hotel Market Set for Robust Expansion — 7.15% CAGR Forecast Through 2032
By PW Consulting, 2026-08-05
Pod Hotel Market 2026: Strategic Imperatives from PW Consulting
The pod hotel segment is no longer a niche experiment — it is a maturing, investable hospitality archetype with clear strategic levers for 2026 decision-makers. PW Consulting’s latest Pod Hotel Market report (base year 2025; forecast 2026–2032) synthesizes five years of historical performance, forward-looking scenario models, and operator-level playbooks to help executives, investors, and developers convert market momentum into repeatable returns. By way of summary: the market grew from the low‑hundreds of millions of USD in 2020 to USD 245.5 Million in 2025 and, under our central projection, reaches roughly USD 398.1 Million by 2032 — a compound annual growth rate (CAGR) of 7.15% across the forecast window. These topline dynamics make 2026 a critical inflection year for strategic moves that prioritize speed, modular economics, and distribution sophistication.
Pod Hotel Market
What the Report Delivers
- Actionable financial models: five-year P&L and cash‑flow templates calibrated to pod-specific construction, operating, and revenue streams; scenario and sensitivity analyses for headline risks (demand shocks, construction inflation, regulatory delays).
- Go‑to‑market playbooks: site selection scorecards, urban vs. transit positioning, tenant-mix and ancillary revenue strategies (day-use, memberships, retail partnerships), and channel optimization (OTAs vs. direct sales).
- CapEx and build strategies: comparative analysis of modular factory-built pods versus on-site construction, procurement checklists, typical build timelines, and vendor shortlists for turnkey implementations.
- Operational playbooks: staffing models for lean front‑office operations, service-level design for shared facilities, technology stacks (IoT, access management, revenue management), and hygiene/privacy best practices.
- Regulatory and risk frameworks: compliance checklists, fire & ventilation design considerations, and playbooks for municipal engagement and community acceptance.
- Competitive dossiers: qualitative and strategic profiles of leading operators, recent expansion signals, and partnership case studies to inform M&A, franchising, and JV decisions.
Why 2026 Is a Strategic Turning Point
- Scale and predictability: the market’s steady rise to mid‑hundreds of millions of USD by 2025, combined with a robust forecast path, transforms pod hotels from pilot projects into scalable business cases suitable for institutional capital.
- Capital efficiency: modular pods materially change the investment calculus. Typical unit construction costs (industry reference ranges) make for significantly lower per‑room outlays than conventional hotels and can yield payback timelines measured in a few years when combined with disciplined revenue management.
- Speed to market: modular factory fabrication and prefabricated-fitout approaches compress delivery timelines into months rather than years — a decisive advantage for first movers in underserved micro-markets such as secondary airports and urban infill.
- Channel evolution: distribution and day‑use demand provide diversified revenue potential beyond overnight occupancy. Executives who plan for mixed-use monetization (overnight, daytime, events, membership) will capture outsized returns on the same physical asset base.
Market Dynamics and Operational Realities
Several structural dynamics are converging to favor pod hotel expansion in 2026:
Pod Hotel Market
- Cost structure and manufacturing: industry analysis indicates that capsule unit construction can fall well below that of traditional rooms. Combined with modularization, projects realize lower on‑site labor requirements, less material waste, and faster commissioning — often within a three‑month deployment window for standardized configurations.
- Payback and returns: lower per‑unit capex shortens burn time. Operators who couple cost discipline with diversified revenue stacks (night stays, hourly bookings, memberships, ancillary F&B and retail) materially increase IRR versus single‑channel hotel models.
- Regulation and compliance: compact accommodation formats must navigate local building codes, fire safety, ventilation, and privacy rules. Proactive design and early engagement with regulators are non‑negotiable and should be embedded into site selection and capex modeling.
- Demand heterogeneity: demand is shifting across traveler cohorts and use cases — from transit and airport sleep solutions to cost‑conscious urban travelers and flexible workspace users. Strategic operators tailor product variants (sleep‑optimized pods, cabin-style “premium” options, and multi‑purpose pods for day‑use) to capture these adjacent pools without massive incremental capex.
Competitive Landscape: Strategic Profiles and Recent Signals
The sector remains fragmented and competitive but with identifiable strategic archetypes. PW Consulting’s report profiles operators across airport, urban, premium‑capsule, and tech‑led segments and synthesizes recent activity to reveal playbook patterns:
Pod Hotel Market
- Sleep‑tech centric operators (example archetype): companies focused on sleep optimization and health integrations are pushing value beyond lodging — embedding biometric monitoring, curated light/noise environments, and science-backed sleep programming. A notable operator recently announced a major urban opening with an institutional partner to integrate clinical sleep monitoring into guest experiences — a signal that wellness partnerships can be a differentiator for higher yield.
- Premium cabin upscalers: a segment of operators is positioning “cabin” experiences between capsule and traditional hotels, pursuing higher ADRs through enhanced amenities and design. These players often serve business or premium leisure niches and selectively expand to gateway leisure markets.
- Airport and transit specialists: firms offering short‑duration sleeping cabins and day‑use pods for airports and workplaces are scaling through partnerships with airports, airlines, and corporate campuses. This model delivers strong unit economics where turnover and short-stay pricing are optimized.
- Tech‑native franchisors: several regional tech-first operators are combining IoT-enabled pods with modular build systems to accelerate national rollouts. These operators emphasize rapid site replication, remote operations, and OTA-driven customer acquisition.
Recent industry movements illustrate these archetypes in action: one sleep‑focused operator announced a major 206‑room opening planned for mid‑2026 with a university partner to formalize sleep and health monitoring; another regional player expanded to dozens of national locations in 2025 and is pursuing a second wave of openings; and construction starts for multi‑story capsule buildings in European city centers reflect growing investor confidence in urban applications.
Strategic Options for Executives in 2026
Leaders have multiple viable routes to capture value. Our report translates market realities into concrete strategic options:
- Fast‑follow modular rollout: license a proven modular pod design, prioritize sites with favorable regulatory profiles, and use a phased network approach to validate local demand before heavy capital commitment.
- Asset‑light franchising and JV models: accelerate footprint via local partners who supply real estate while you provide brand, tech, and operational systems — a model that preserves cash and multiplies market reach.
- Vertical integration of ancillaries: integrate ancillary revenue (hourly, memberships, F&B partnerships) into base offerings from day one to improve RevPAR-equivalent metrics and stabilize cash flow across demand cycles.
- Strategic partnerships: collaborate with sleep research institutions, airlines, or workplace operators to co-develop offerings that command price premiums and create defensible customer propositions.
- Selective premiumization: introduce tiered product lines (basic pod, premium cabin, hybrid workspace pod) within the same footprint to capture broader customer segments without the cost of entirely separate assets.
Risk Management and Critical Execution Challenges
Execution is rarely the limiting factor; rather, it is execution against complexity. The top hazards we model for 2026 are:
- Regulatory friction and permitting delays — mitigated by early municipal engagement and standardized compliance packages.
- Construction supply chain and inflation pressures — mitigated by locked vendor agreements and modular factory sourcing.
- Reputational risk tied to privacy and safety — mitigated by high‑quality ventilation designs, third‑party safety certifications, and transparent guest communications.
- Channel and demand misalignment — mitigated by adaptive pricing engines and a tested mix of OTA and direct channel strategies that prioritize lifetime value.
How PW Consulting Can Help
Our Pod Hotel Market report is purpose-built for executives who must decide in 2026 whether to build, buy, partner, or pass. The full deliverable includes granular regional demand models, site-level scorecards, vendor RFP templates, full competitor dossiers, bespoke financial model files, and a recommended 18‑month action plan for market entry or scale. The material is intentionally prescriptive — giving teams the tools to move from concept to proof‑of‑concept to scalable rollout within 12–24 months.
For teams evaluating investments, the topline growth trajectory (noted above) and capex economics make a compelling case for prioritized pilots in target micro‑markets. For incumbents seeking margin enhancement, the combination of modular build strategies and diversified revenue design offers a clear path to improved returns. And for corporate real estate owners, pod hotels present a compact, high‑utility reuse option for underperforming urban and airport-adjacent assets.
Next Steps
PW Consulting invites senior leaders to review the executive summary and request a custom briefing. The full report provides the proprietary datasets and scorecards necessary to operationalize the strategies summarized here. To obtain full access, please visit PW Consulting’s market research portal or contact our advisory team for a tailored engagement.
In an industry defined by compact footprints but expanding strategic horizons, 2026 will reward players who move quickly, think modular, and monetize beyond the night. PW Consulting’s pod hotel intelligence is designed to make those decisions faster and with confidence.
For detailed analysis of this topic, please visit the official page: Pod Hotel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Email Deliverability Services Market to Surge at a 11.78% CAGR Through 2032
By PW Consulting, 2026-08-05
Email Deliverability Services Market 2026: Strategic Imperatives from PW Consulting’s New Market Report
PW Consulting today publishes an authoritative market briefing grounded in our full Email Deliverability Services Market report (base year 2025). The market has moved from a specialist operational concern to a board‑level strategic priority. Our analysis shows sustained, high‑double‑digit expansion: a historical acceleration from roughly USD 820 million in 2020 to about USD 1.45 billion in 2025, and a forecast trajectory that reaches beyond USD 3.15 billion by 2032 at a compound annual growth rate (CAGR) of 11.78% through the 2026–2032 period. For executives planning 2026 budget cycles and multi‑year roadmaps, this briefing distills the practical implications, competitive dynamics, and implementation playbooks that will determine who captures value as the market scales.
Email Deliverability Services Market
Why email deliverability now drives strategic value
Email remains one of the highest‑ROI customer engagement channels. But as mailbox providers, regulators, and anti‑abuse technologies raise the bar on authentication, consent and send hygiene, deliverability has shifted from “marketing ops” to a cross‑functional systems problem. The cost of failed inbox placement is no longer limited to open rate erosion — it includes customer experience, increased remediation costs, brand reputation damage, and potential regulatory exposure in jurisdictions enforcing strict consent rules.
Email Deliverability Services Market
- Regulatory pressure: GDPR and evolving privacy frameworks require explicit consent and constrain telemetry used for deliverability optimization; non‑compliance risks significant fines and mailbox provider actions.
- Provider enforcement: Major mailbox operators now require robust SPF/DKIM/DMARC setups, one‑click unsubscribes, and operational complaint thresholds that leave little tolerance for systemic issues.
- Operational complexity: Effective deliverability requires integration across infrastructure (sending platforms, dedicated IPs, domain strategy), analytics, and policy teams — a multidisciplinary discipline that scales with organizational growth.
Market dynamics and what they mean for buyers
The market’s expansion is driven by increased demand for cloud‑native deliverability tooling, consulting services that remediate complex enterprise problems, and managed services for organizations that prefer outcomes over tool ownership. Our concentration analysis indicates that the top three vendors account for a meaningful but not dominant share of the market (CR3 ≈ 38.5%), with the top five reaching roughly 52%. This structure signals a market where leading platforms and specialist consultancies coexist: large providers offer scalable infrastructure while boutique specialists continue to win remediation and advisory engagements.
Email Deliverability Services Market
Benchmarks matter. Independent reports show global inbox placement averaging in the mid‑80s percent range in 2025 — an encouraging sign overall, yet variation across mailbox providers and industry verticals remains material. Infrastructure economics for cold and high‑volume sending also vary widely; cold email setups and domain warmup can range from sub‑dollar per inbox to several dollars monthly depending on architecture and risk posture, while dedicated IPs add recurring platform costs. These operational levers directly affect unit economics and should inform vendor selection and build vs. buy decisions.
Competitive landscape — strategic map for 2026
The competitive set includes specialist consultancies, verification and testing platforms, API‑centric delivery providers, and emerging AI‑assisted management tools. Each category brings differentiated value to buyer segments:
- Specialist consultancies: Firms such as InboxArmy (Grapevine, Texas) and Email Industries (Augusta, Georgia) deliver end‑to‑end remediation, reputation management, and tailored enterprise programs. These vendors excel at complex root‑cause analysis, stakeholder coordination, and bespoke policy work for high‑risk senders.
- Verification and hygiene platforms: Players like Kickbox and ZeroBounce provide essential pre‑send hygiene through list validation and scoring. Their value is tactical but high‑impact — reducing bounce rates and immediate reputational risk.
- API delivery and transactional specialists: Mailgun, Postmark and SendGrid (Twilio) combine send infrastructure with deliverability features and analytics, appealing to developers and teams that require high‑volume, low‑latency delivery alongside operational control.
- Monitoring and testing tools: GlockApps and Mailtrap focus on inbox placement testing, seed lists and sandbox environments that are indispensable during migrations, campaign launches and deliverability audits.
- AI‑enabled management: Emerging platforms such as Folderly are layering automation and domain warm‑up orchestration onto monitoring and remediation, reducing human overhead for routine optimization tasks.
Our competitive assessment evaluates each vendor on technical breadth, enterprise delivery capabilities, data transparency, and ecosystem integrations. Specialists retain an advantage in complex remediation, while platform providers win in scale and developer friendliness. The market will increasingly reward hybrid models that combine the repeatability of platforms with the advisory intensity of consultancies.
What our report contains — practical outputs for immediate deployment
PW Consulting’s full report is designed as an operational toolkit for 2026 decision cycles. Highlights include:
- Implementation playbooks for enterprise‑grade authentication (SPF/DKIM/DMARC) and consent alignment with privacy regimes.
- Vendor evaluation frameworks and RFP templates to compare platform, consultancy and managed‑service options on consistent ROI and risk criteria.
- Technical checklists for migrations, dedicated IP strategy, domain segmentation, and warm‑up sequencing that reduce reputation shock during scale‑ups.
- Cost models and sensitivity analyses that translate per‑inbox infrastructure assumptions into multi‑year TCO scenarios.
- Governance and organization designs for cross‑functional deliverability programs — clarifying roles between marketing, security, deliverability ops and legal.
- Executive dashboards and KPIs aligned to inbox placement, complaint rates, and regulatory compliance metrics so leadership can measure progress against both operational and legal thresholds.
These assets are purposefully practical: they move beyond theory to defined actions, timelines and owner responsibilities that are ready to drop into 2026 plans.
Strategic recommendations for 2026
Based on our synthesis of market trends, vendor capabilities, and regulatory dynamics, PW Consulting advises organizations to prioritize the following:
- Elevate deliverability to strategic governance: Create a C‑level or senior sponsor for deliverability programs with cross‑functional authority and budget to act decisively during incidents.
- Invest in authentication and consent hygiene now: Align technical authentication (SPF/DKIM/DMARC) with consent records and suppression logic. This reduces provider friction and regulatory exposure.
- Adopt a hybrid vendor strategy: Use platform partners for scale and reliability, and specialist consultancies for audits, migrations and complex remediation. Rely on verification vendors to pre‑empt list‑level risk.
- Model total cost of ownership (TCO): Include infrastructure, warm‑up, reputation remediation, and compliance in multi‑year cost models — especially when evaluating in‑house vs. managed service bets.
- Measure the right KPIs: Move beyond open rates to monitoring inbox placement, domain health signals, complaint rates and legal consent lineage as primary indicators of program health.
- Plan for mailbox provider divergence: Different providers enforce different tolerances; build controls that allow targeted adjustments per provider to optimize outcomes without broad risk.
Decision playbook: vendor selection and risk mitigation
For procurement and technical teams preparing RFPs in 2026, our report recommends a two‑stage evaluation. First, assess security, compliance and integration capabilities to shortlist vendors. Second, run a time‑bounded pilot focusing on a high‑risk cohort and measure placement delta, remediation velocity, and governance fit. Key selection criteria include:
- Proof of enterprise remediation experience and documented case studies.
- Data provenance and transparency around seed lists and testing methodologies.
- Integration maturity with sending infrastructure, analytics and consent platforms.
- Operational SLAs for incident response and reputation remediation.
- Pricing alignment with measurable business outcomes and TCO models.
Why PW Consulting’s report matters for 2026
Our work synthesizes market sizing and growth trajectories with tactical frameworks that leaders can implement immediately. The market’s scale and projected doubling toward 2032 underscore why deliverability will be an investment priority for organizations seeking predictable digital revenue streams. At the same time, vendor concentration data points to continued competitive opportunity for both scale players and specialist firms — a dynamic that creates strategic options for buyers.
We intentionally keep certain granular sub‑segment figures and proprietary vendor scoring matrices accessible in the full report and accompanying online data portal. Those detailed splits are indispensable for precise procurement and investment decisions; they are reserved for report subscribers and website visitors to ensure decision‑grade confidentiality and licensing integrity.
Next steps
- Download the executive summary and request the full report for vendor scorecards, RFP templates and our deliverability KPI dashboard.
- Contact PW Consulting to schedule a 60‑minute briefing: we will walk your leadership team through tailored scenarios and implementation timelines for 2026.
- Attend our upcoming webinar where we will deconstruct a live remediation case study and demonstrate the ROI mechanics in the report’s model.
Deliverability is no longer a checkbox — it is a strategic asset that sits at the intersection of marketing, security and compliance. PW Consulting’s Email Deliverability Services Market report gives leaders the context, tactics and tools to convert that asset into measurable business value in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Email Deliverability Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Rare Disease CRO Market Poised for Rapid Expansion with a 10.2% CAGR
By PW Consulting, 2026-08-05
Rare Disease CRO Service Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive summary
By the end of 2025 the Rare Disease Contract Research Organization (CRO) services market has matured from a niche support sector into a strategic battleground for biopharma sponsors, specialty CROs and data-rich life‑science platforms. Our new market study—anchored on historical performance from 2020–2025 and forward-looking forecasts to 2032—shows the market expanding at a compound annual growth rate (CAGR) of 10.2%. The market rose from roughly USD 3.9 billion in 2020 to about USD 6.5 billion in 2025, and is projected to approach the low‑teens billion mark by 2032 under our base case.
Rare Disease CRO Service Market
This preview explains why these macro dynamics matter for corporate decisions in 2026, what operational levers will determine winners and losers, and how leading CROs are positioning themselves. We intentionally present strategic depth while reserving the granular segmentation tables, provider scorecards and financial models for the full report—designed to be an operational playbook for deal teams, business unit leaders and portfolio managers.
Rare Disease CRO Service Market
Market trajectory and what it means for 2026 decisions
-
Scale and acceleration: The mid‑2020s acceleration in sponsor outsourcing reflects three converging forces—an increase in rare and ultra‑rare programs (including cell and gene therapies), tighter evidence flexibility from regulators, and improvements in decentralized trial modalities. For decision-makers this means larger absolute service spend and increasingly strategic use of CRO partners beyond transactional trial execution.
Rare Disease CRO Service Market -
Premiumization of services: Rare disease programs command materially higher per‑patient, per‑protocol effort due to specialized navigators, complex endpoint development and dispersed patient populations. Expect continued upward pressure on per‑patient economics for ultra‑rare, global Phase II/III programs—shaping pricing, contracting and risk allocation between sponsors and CROs in 2026.
-
Regulatory tailwinds and operational friction: New regulatory frameworks (notably the FDA’s Rare Disease Innovation Hub and Rare Disease Evidence Principles finalized in 2025, and the ICH E6(R3) GCP updates) create both opportunity and complexity. They lower traditional evidentiary barriers for ultra‑rare indications while increasing expectations for rigorous risk‑based monitoring and adaptive designs. At the same time, cross‑border genomic data privacy (GDPR, HIPAA intersection) increases the cost and complexity of multi‑jurisdictional registries and biomarker programs.
-
Consolidation with nuance: The market structure is moderately concentrated—there is a notable cohort of large, full‑service CROs and platform players alongside specialized boutique providers. M&A and capability‑expansion moves continue to reshape capability maps, creating windows for strategic partnerships as well as integration risk for incumbents.
What the full PW Consulting report delivers (practical, transaction‑ready)
-
Robust financial models: revenue and spend projections across multiple scenarios (base, downside, upside) calibrated to our 10.2% CAGR baseline and stress‑tested for regulatory, reimbursement and recruitment shocks.
-
Provider benchmarking: an operational scorecard covering capability depth (biomarkers, cell/gene, pediatric expertise), geographic reach, decentralized trial maturity, and unit economics—built to support partner selection, vendor consolidation and diligence.
-
Go‑to‑market playbooks: prescriptive recommendations for sponsor sourcing strategies (buy vs build vs partner), contracting structures (value‑share, milestone‑linked fees), and risk allocation tailored to rarity, therapeutic class and development stage.
-
Patient ecosystem maps: tactical guidance on registry activation, advocacy partnerships, and site network design to compress enrollment timelines—supported by localized recruitment case studies and cost multipliers for ultra‑rare cohorts.
-
Regulatory and evidence strategy templates: practical paths for leveraging recent FDA guidance, orphan incentives and adaptive evidentiary approaches to accelerate approval while keeping regulatory risk manageable.
-
M&A and partnership heatmaps: prioritization matrices identifying targets by capability gap, geographic importance and cost synergies—plus integration playbooks to protect value capture after transactions.
Competitive landscape: capabilities, moves and implications
The competitive set divides into three archetypes: integrated global full‑service providers, specialized rare‑disease boutiques, and data‑centric/analytics platforms. Each archetype presents distinct options and risks for sponsors in 2026.
-
Integrated global players (examples include IQVIA, Parexel, ICON and large CRO arms of diversified life‑science companies): these players offer scale, global site networks, and end‑to‑end regulatory and commercialization support. Their strengths are in handling dispersed registries, complex logistics and payer access planning; weaknesses can include slower niche innovation and higher baseline cost structures.
-
Specialized rare‑disease CROs (examples include Medpace, TFS HealthScience, Ergomed, Allucent, Veristat, Precision for Medicine): these firms differentiate on deep therapeutic expertise (neuroscience, metabolic, neuromuscular), adaptive trial designs, and patient location capabilities. They are often the best partners for novel modality programs and ultra‑rare indications, offering high touch recruitment and bespoke regulatory strategy.
-
Data and platform players (IQVIA, Precision for Medicine, and others with strong analytics labs): their advantage lies in population intelligence, biomarker integration and endpoint optimization. Sponsors choosing these partners can accelerate go/no‑go decisions and reduce screen‑fail rates, but must negotiate for access to derivative analytic assets and IP.
Recent industry developments reinforce these archetypes and their strategic implications. In 2026 we observed leadership expansions and acquisitions aimed squarely at scaling rare disease capability: specialist firms have fortified therapeutic leadership; mid‑sized CROs have executed bolt‑on acquisitions to broaden FSP and oncology linkages; and large platforms have sought to integrate endpoint‑data and decentralized trial technologies. For sponsors, these moves change the math on whether to contract multiple specialists or to consolidate with a single, integrated partner.
Operational and regulatory headwinds to budget for
-
Data privacy and cross‑border registries: compliance workstreams and technical safeguards add up‑front and recurring costs—impacting trial timelines and sponsor vendor selection for global programs.
-
Labor and specialist scarcity: the premium for experienced rare disease coordinators, outcome assessors and pediatric trial specialists translates to per‑patient costs materially above standard programs. This should be a core assumption in 2026 financial planning.
-
Evidence flexibility vs. evidentiary risk: emerging FDA and ICH guidance enable innovative designs but demand stronger early engagement with agencies and robust statistical planning to avoid downstream surprises.
-
Reimbursement and market access: orphan designation incentives remain powerful drivers of sponsor engagement, but market access strategies must be built into development plans early, particularly for small‑population indications where real‑world evidence will be critical.
Strategic recommendations for 2026 (what leading sponsors and CROs should do now)
-
Adopt a hybrid sourcing model: combine a primary integrated partner for global regulatory, logistics and commercialization planning with specialist boutiques for therapy‑specific endpoints and recruitment—use clear governance to avoid duplication and scope creep.
-
Invest in data interoperability and local registry partnerships: prioritize partners offering end‑to‑end genomic/phenotypic integration while ensuring contractual clarity on data ownership and reuse across geographies.
-
Negotiate outcome‑aligned contracts: for ultra‑rare programs, move toward milestone‑linked economics that share enrollment risk and incentivize speed and retention.
-
Build regulatory engagement early: use the FDA Rare Disease Innovation Hub and ICH E6(R3) frameworks proactively—submit adaptive protocols and seek early advice on surrogate endpoints and small‑population evidence packages.
-
Prepare for talent premium: create internal centers of excellence and rotation programs to reduce dependence on external navigators and preserve proprietary patient engagement approaches.
-
Maintain an M&A and partnership watchlist: be ready to act on tuck‑ins that close capability gaps in biomarkers, decentralized trials, or patient location services—while running pre‑defined integration playbooks to protect deal value.
Why PW Consulting’s report is decision‑useful for 2026
Our study converts macro momentum into practical actions: financial models calibrated to a 10.2% CAGR baseline, provider scorecards for procurement and due diligence, and step‑by‑step playbooks for trial design, recruitment and reimbursement strategy. The report translates trends into the specific tradeoffs you will face when allocating development budgets and negotiating vendor terms in 2026.
Because strategic advantage in rare disease development often depends on fine‑grained choices—timing of agency interactions, selection of endpoint providers, registry partnerships and contract mechanics—our full report includes the detailed segmentation, regional/service splits and vendor performance matrices that operational teams need. This preview highlights the directional insights; the granular data and executable templates are available in the complete PW Consulting Rare Disease CRO Service Market report.
Next steps
For leaders preparing 2026 budgets, vendor sourcing strategies or M&A diligence, we recommend three immediate actions: (1) run scenario models against the PW Consulting financial templates to stress‑test program economics, (2) shortlist potential providers by capability rather than price and convene focused proof‑of‑capability pilots, and (3) allocate resources to regulatory and patient ecosystem engagement now to compress enrollment timelines.
To access the full dataset, provider heatmaps, and our transaction playbooks, please consult the PW Consulting report portal where the complete Rare Disease CRO Service Market study is published. The full deliverable contains the segmentation tables and benchmarking detail necessary to operationalize the strategic recommendations summarized here.
PW Consulting — Senior Strategic Advisory & Industry Analysis. We translate market intelligence into practicable decisions. For bespoke briefings or subscription access to the full report, contact our Rare Disease Practice.
For detailed analysis of this topic, please visit the official page: Rare Disease CRO Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Finance Lease Market to Reach USD 344.8M by 2032 at 6.8% CAGR
By PW Consulting, 2026-08-02
Finance Lease Market — 2026 Strategic Primer (PW Consulting)
This briefing introduces PW Consulting’s full Finance Lease Market study (base year 2025, forecast period 2026–2032). It is written for senior leaders — CFOs, heads of asset finance, corporate strategy teams and institutional investors — who must make near-term capital-allocation and product decisions under new accounting and regulatory constraints. The market is projected to expand from an estimated USD 215.0 Million in 2025 to approximately USD 344.8 Million by 2032, reflecting a compound annual growth rate of 6.8% over the forecast horizon. This primer surfaces the strategic implications and operational playbook for 2026 while intentionally withholding the granular regional, type and application splits available in the full report.
Finance Lease Market
Why this study matters for 2026 decisions
- Regulatory inflection: 2026 brings broad practical implementation of lease-accounting changes (notably ASC 842 and IFRS 16 developments) that materially affect balance-sheet presentation, product economics and client demand patterns. Lessors and lessees must react to classification, disclosure and tax interactions in their product design and sales motions.
- Capital allocation under uncertainty: With interest rate normalization and evolving lifecycle economics for key asset classes, leasing businesses must rebalance funding, repricing and capital efficiency to sustain returns while protecting asset values.
- Competitive repositioning: The market remains structurally fragmented (top-three concentration is limited), so scale advantages exist in distribution and remarketing, but specialist providers and OEM-linked players retain defensive niches. 2026 is a window to consolidate selectively or double down on vertical differentiation.
- Digital and data edge: Companies that convert warranty, telematics and residual-value signals into real-time pricing and remarketing intelligence will compress credit cycle risk and materially improve ROE.
High-level market trajectory and drivers
Since 2020 the finance lease market has shown resilient expansion in spite of macro volatility. The combination of replacement cycles across core asset classes, rising demand for usage-based asset access, and corporate balance-sheet optimization has sustained steady growth. Over the 2026–2032 forecast window the market’s 6.8% CAGR reflects both recurring fleet and equipment refresh needs and new demand pockets created by digitalization, medical-capex expansion and infrastructure programs in multiple jurisdictions.
Finance Lease Market
Key demand drivers to watch in 2026:
Finance Lease Market
- Asset lifecycle reconfiguration: Companies are shifting from outright ownership to hybrid access models for vehicles, manufacturing equipment, IT stacks and healthcare capital, increasing the variety of lease terms and end-of-term options.
- Regulatory and accounting impacts: The practical application of ASC 842 criteria and tightening interpretations under IFRS 16 are changing lessee behavior and lessor contract design — from explicit residual value sharing to embedded service elements. Lessors who can model these impacts into contract terms will preserve margins.
- Capital markets and funding dynamics: While traditional bank syndication remains important, alternative funding — including securitization of lease receivables and balance-sheet optimization tools — will be critical for players looking to scale without diluting profitability.
- Technology-enabled efficiency: Digital origination, automated credit decisioning and connected-asset telemetry are shifting cost-to-serve curves and enabling continuous re-pricing on floating-rate and usage-based products.
- ESG and lifecycle services: Sustainability-linked leases, circular-economy refurb programs and end-of-lease recycling will become client-facing differentiators rather than compliance afterthoughts.
Competitive landscape — positioning and strategic moves
Market concentration metrics show that the sector is not highly concentrated: the top three and top five players account for a modest share of the total market, leaving significant room for regional specialists and vertical champions. Below we summarize the strategic posture typical of the market’s core player types and the specific strengths of prominent participants covered in our full study.
- Global bank-affiliates and universal lenders — Examples include major European and North American banking groups. These players leverage balance-sheet scale, cross-sell to corporate banking clients and bundle leasing as part of integrated capital solutions. Their strengths are pricing power on large-ticket deals and global distribution networks; weaknesses include slower product innovation cycles and exposure to bank-wide credit cycles.
- Industrial/OEM-linked lessors — Firms aligned with manufacturers use OEM partnerships to secure supply, embed services and manage residuals through captive remarketing channels. Their advantage lies in deep asset knowledge and preferential access to replacement pipelines, but they can be over-exposed to single-asset technology risks.
- Specialist equipment financiers and regional lessors — These providers focus on sector-specific underwriting, faster decisioning and tailored lifecycle services for SMBs and mid-market corporates. They win where specialization yields superior residual forecasting and service margins.
Representative company insights (high-level):
- Sumitomo Mitsui Finance and Leasing Co., Ltd. (Tokyo) — Emphasizes specialized finance lease offerings and portfolio diversification strategies anchored in long-standing OEM relationships and cross-border client flows.
- BNP Paribas Leasing Solutions (Paris) — Leverages group capabilities to offer equipment finance embedded with advisory and risk-management services, particularly for large corporates seeking turnkey asset solutions.
- HSBC Group (London) — Uses its global balance sheet to provide equipment financing with integrated cash management and cross-jurisdictional coverage, useful for multinational lessees.
- CIT Group Inc. (New York) — Focuses on commercial equipment leasing with streamlined execution for North American mid-market customers.
- Hitachi Capital and Mitsubishi UFJ Lease & Finance (Tokyo) — Represent the OEM/industrial and bank-affiliate playbooks respectively, combining deep asset insights with structured finance capabilities.
- Societe Generale Equipment Finance, Deutsche Leasing AG and DLL Group — Each brings a distinct mix of pan-European reach, sector specialization and vendor-finance expertise.
- Wells Fargo Equipment Finance, Crest Capital, Bank of America Leasing & Capital, Fifth Third Bank — U.S.-centric players that provide scale, distribution and SMB-focused leasing solutions with varying levels of product customization.
Operational implications: what to do in 2026 (practical playbook)
The following tactical steps synthesize the full report’s operational guidance into a prioritized 12–18 month roadmap that CEOs and heads of product can act on immediately.
- Compliance-first contract redesign: Revisit contract clauses, amortization profiles and residual-value sharing to align with ASC 842 and IFRS 16 interpretations; coordinate with tax and accounting early to avoid surprises in lessee demand elasticity.
- Dynamic pricing and credit engines: Invest in models that combine macro-factor overlays with live asset telemetry to enable dynamic repricing and more accurate provisioning across economic cycles.
- Funding diversification: Prepare issuance-ready lease receivable pools and explore non-bank funding channels (securitization, institutional investors, ESG-labeled assets) to reduce cost-of-capital sensitivity.
- Remarketing and residual-risk programs: Build or partner for secondary-market capabilities to extract higher end-of-term value; consider refurbishment-as-a-service and certified pre-owned channels to capture lifecycle margin.
- Channel and partnership optimization: Rebalance direct sales, broker networks and OEM channels by instrument — allocate premium distribution to products with the highest margin improvement potential and tightest compliance needs.
- Targeted M&A and portfolio pruning: Use the low concentration environment to acquire complementary origination capacity, or selectively divest non-core residual exposures that drag on ROE.
- ESG integration and product innovation: Launch sustainability-linked leases and circular-economy service bundles to attract corporate procurement mandates and access ESG-focused capital pools.
- Scenario planning and stress-testing: Build multi-factor scenario models (rates, residual values, supply-chain disruption) to validate pricing floors and cushion capital plans across 12–36 month horizons.
What’s in the full PW Consulting report (practical deliverables)
The complete study provides the operational datasets and analytic elements required to execute the roadmap above, including:
- Year-by-year market size and modelled forecasts for the 2026–2032 period, with sensitivity analyses under alternative macro and regulatory scenarios.
- Full competitive intelligence dossiers on the major players, covering product portfolios, distribution models, historical strategic moves and a tactical playbook for competing or partnering.
- Regulatory impact mapping, with a detailed ASC 842 / IFRS 16 checklist, contract redrafting templates and lessee-behavior simulations designed for immediate legal and finance integration.
- Go-to-market templates: channel segmentation frameworks, pricing-play matrices, a vendor-evaluation scorecard for remarketing partners, and operational KPI dashboards.
- Transaction-ready financial models for securitization and funding alternatives, plus an M&A target shortlist by capability and geography.
- Case studies that illustrate successful pivots — for example, a bank-affiliate that embedded usage-based telemetry to reduce residual losses, and an OEM captive that monetized remarketing to fund new product financing.
Note: This primer intentionally refrains from publishing the granular regional, type and application splits included in the full report. Those detailed breakdowns are essential for deal-level underwriting, channel strategy and capital planning and are therefore provided only via our full-market deliverable to ensure confidentiality and operational value.
Next steps — how to use our analysis in your 2026 planning cycle
- For CFOs and treasurers: Request the securitization and funding module to stress-test capital plans against issuance and investor demand scenarios.
- For heads of product and sales: Use the contract redesign toolkit and digital-pricing recommendations to launch pilot products within 90 days.
- For corporate strategy and M&A teams: Ask for the target shortlist and scenario models to evaluate bolt-on acquisitions and divestments aligned to your desired market position.
PW Consulting’s full Finance Lease Market study translates a complex regulatory and asset cycle transition into an executable strategy for 2026. To access the granular datasets, competitive dossiers and step-by-step implementation tools referenced here, please consult the full report on our site or contact your PW Consulting representative. The market opportunity is clear; the competitive advantage will go to organizations that combine accounting-ready product design, funding agility and a data-driven approach to residual risk.
For detailed analysis of this topic, please visit the official page: Finance Lease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
3D Printing & Additive Manufacturing in Aerospace & Defence: Strategic Preview for 2026 Decision-Makers
As defence and aerospace supply chains confront accelerating demand for lighter, more capable, and more resilient hardware, additive manufacturing (AM) is moving beyond laboratory proofs into program-level deployments. Our new PW Consulting market study — with a 2025 base year and a forecast window to 2032 — quantifies this transition. The global AM market serving aerospace & defence expanded from roughly USD 900 million in 2020 to about USD 1.7 billion in 2025, and is projected to nearly triple by the early 2030s, growing at a compound annual growth rate (CAGR) of 15.5% through 2032. For 2026 strategy cycles, these dynamics create a narrow window for pragmatic leadership: invest selectively, accelerate qualification pathways, and align procurement with certification and production-readiness milestones.
3D Printing & Additive Manufacturing in the Aerospace & Defence Market
Why this market matters for 2026 strategic choices
-
Scale and velocity: Double-digit CAGR and a near-term inflection point mean business models and sourcing strategies that rely on slow, incremental adoption will be outpaced. Program managers and supply-chain leaders must treat AM as a production-capable technology today, not merely a prototyping tool.
3D Printing & Additive Manufacturing in the Aerospace & Defence Market -
Qualification is the rate limiter: Certification and supplier accreditation remain the gating factors for program insertion. Recent industry moves — from Nadcap accreditations to multi-million dollar government contracts for expedited qualification services — demonstrate that regulatory alignment is becoming a competitive advantage rather than a compliance afterthought.
3D Printing & Additive Manufacturing in the Aerospace & Defence Market -
Concentration and competitive structure: Market concentration is meaningful. The top three firms account for roughly half of the sector’s revenues, and the top five approach two-thirds. This reality creates a dual-track ecosystem of large platform suppliers and specialised niche vendors — each offering different risk/reward profiles for primes and tier-1s.
-
Material and process precedence: Metal AM has moved into the strategic center for engines, propulsion and structural applications; polymer and ceramics continue to support secondary systems and rapid iteration. Technology selection today will lock-in certification pathways, supplier relationships, and lifecycle costs over the next decade.
What this PW Consulting report delivers (practical, acquisition-ready intelligence)
-
Actionable market sizing and forecasts (2020–2025 historical context, 2026–2032 scenarios) to inform CAPEX and program-level budgeting.
-
Decision-oriented segmentation across types, applications, and geographies with sensitivity analysis — structured to help procurement, engineering, and certification teams prioritise where to invest or partner. Note: this preview intentionally omits the granular splits; the full dataset and tables are available in the full report.
-
Supplier benchmarking: capability matrices and risk profiles for leading equipment vendors, service bureaus, material suppliers and vertically-integrated OEMs to support make-vs-buy decisions.
-
Certification and qualification playbooks outlining pragmatic pathways (time, cost, and audit dependencies) for AS, military, and civil aviation specifications.
-
Value-chain implications for sustainment, spare-part logistics, and distributed manufacturing models that reduce inventory and improve readiness.
-
Investment and partnership heuristics — a stratified set of use-cases that map likely ROI thresholds by application criticality and production volumes.
Competitive landscape: who matters and why
The aerospace & defence AM space is populated by established capital-equipment vendors, vertically-integrated OEM services, and high-growth specialised suppliers. Below we summarise the strategic posture of core players covered in our study:
-
Aerojet Rocketdyne Holdings (US) — Large-scale metal AM for propulsion. Their focus on powder-to-engine capability and defence contracts positions them as a partner for high-energy propulsion programs demanding both scale and certification rigor.
-
3D Systems, Inc. (US) — End-to-end AM solutions, from printers to materials and certification support. Their strength is in integrated stacks and services for AS9100-class production workflows.
-
Materialise NV (Belgium) — Certified AM services for prototypes and low-criticality end-use parts with EASA and EN9100 alignment. Materialise represents the service-bureau model that primes often use to derisk early insertions.
-
Norsk Titanium AS (Norway) — Rapid Plasma Deposition for high-deposition-rate titanium structural parts. Recent accreditations and operational updates indicate fast-moving OEM programs in both aerostructures and engines.
-
Renishaw plc (UK) — Metal powder bed fusion systems supplier with deep ties to aerospace component manufacturing and defence support ecosystems.
-
Nikon AM Synergy (US) — Specialist in metal AM design, simulation and production services oriented to mission-critical defence components.
-
Beehive Industries (US) — Focused on additively enabled jet engines and printed propulsion parts; recent Air Force awards underscore government willingness to fund domestically produced propulsion hardware.
-
Velo3D, Inc. (US) — Delivers aerospace-grade metal printing solutions targeting propulsion, structural and defence hardware with emphasis on qualified materials and processes.
-
Colibrium Additive (GE Aerospace, US) — Industrial-scale printers, powders and AddWorks qualification services; recent government contracts highlight their role in accelerated testing and certification at scale.
-
Stratasys Ltd. (US) — Production-scale polymer and composite printing with AS9100-certified offerings and Program of Record relationships with major defence organisations.
These firms represent a cross-section of capital equipment, materials, services, and vertically integrated OEM strategies. The competitive dynamics are being shaped by certification wins, large government contracts for qualification services, and operational accreditations that shorten time-to-program insertion.
Recent events shaping 2026 program decisions
-
Acceleration of qualification funding: Multi-million-dollar contracts awarded to expedite testing and certification indicate that governments are treating AM readiness as strategic industrial policy as much as a technology project. Expect increased funding windows for rapid qualification in 2026.
-
Accreditations and supplier trust: Nadcap and similar approvals materially reduce audit friction and supplier onboarding time. Facilities obtaining these accreditations gain prioritised access to prime contracts and aftermarket supply streams.
-
Program-of-record selections: When a vendor is selected as Program of Record by a service branch, primes typically adjust supplier lists and design-for-AM standards to that vendor’s process envelope, creating switching costs for later entrants.
Implications for procurement, engineering and investors
-
Procurement: Move from price-centric RFQs to capability-based sourcing. Include qualification timelines, audit readiness and materials traceability as bid gating criteria. Prepare to co-fund qualification phases with strategic suppliers to accelerate insertion.
-
Engineering & Design: Adopt design-for-additive standards early in the design cycle and lock in materials/process pairs that map to certified supplier capabilities. Modularize designs where AM provides largest life-cycle payoff (propulsion, primary structure, mission-critical brackets).
-
Investors & M&A: Prioritise firms demonstrating reproducible qualification deliverables and recurring revenue from defence programs. Value accreditations, long-term prime contracts, and vertically integrated service offerings higher than pure hardware plays.
Strategic playbook for 2026: five pragmatic moves
-
Map qualification choke points: Identify the shortest path to program entry for your parts and invest upfront in the specific testing and audit sequences required. Use pilot contracts with accredited suppliers to build the initial flight heritage.
-
Pilot at scale: Move beyond single-unit prototypes to small-batch flight trials that validate cost, cycle time, and supply continuity — the hard proof that unlocks larger production lots.
-
Secure supply diversity: Given concentration among leading suppliers, develop second-source strategies for critical parts or materials, including domestically-certified sub-tier partnerships.
-
Align incentives: Structure supplier contracts to share certification risk and reward. Cost-plus and milestone-based contracts can accelerate qualification without shifting all risk onto suppliers.
-
Operationalize data: Implement digital thread and lifecycle tracking from powder-to-part to demonstrate traceability, enable predictive maintenance and simplify airworthiness case development.
How to use this research in 2026 planning cycles
Use the report as a tactical reference when preparing budgets, RFPs, and supplier selection flows. The forecasting scenarios provide a foundation for CAPEX planning and sensitivity testing, while the supplier benchmarks and qualification playbooks enable realistic scheduling of certification milestones. For investors, the convergence of capital, contracts and accreditations provides an evidence-based lens to prioritise targets that will capture disproportionate share as the sector scales.
Next steps and where to find the full intelligence
This preview is designed to demonstrate the depth of our analysis while preserving the proprietary segmentation and dataset that drive program-level decisions. The full PW Consulting report includes the complete numerical tables, segmented forecasts, supplier scorecards and the downloadable dataset you will need to quantify trade-offs and model procurement scenarios for 2026–2032. To convert the insights above into executable plans — from RFP templates to qualification budgets — consult the full report on our research portal.
For detailed analysis of this topic, please visit the official page: 3D Printing & Additive Manufacturing in the Aerospace & Defence Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


