



Category: IT & Electronics
PW Consulting: Real-Time Shelf Monitoring Market Poised for Rapid Expansion — 13.52% CAGR Expected
By PW Consulting, 2026-07-13
Real Time Shelf Monitoring Systems: Strategic Imperatives for 2026 — PW Consulting Market Preview
As retailers and consumer-packaged-goods (CPG) companies accelerate their shift to data-driven store operations, real time shelf monitoring (RTSM) has moved from a pilot-stage curiosity to a mission-critical capability. PW Consulting’s latest market study — based on a 2020–2025 historical analysis and a 2026–2032 forecast horizon — synthesizes commercial realities, vendor capabilities, and practical decision frameworks that enterprise leaders will need to act on in 2026. This preview highlights the strategic value contained in the full report while preserving the granular segmentation and vendor scoring that subscribers will find in the source document.
Real Time Shelf Monitoring System Market
Market Trajectory and What It Means for Strategic Planning
The RTSM market has shown sustained, above-market growth: our topline analysis places the market at approximately USD 550 million in 2020, expanding to USD 1,125 million by the 2025 base year. Looking forward under current adoption and technology trends, we forecast continued rapid expansion — the market is projected to exceed USD 1.2 billion in 2026 and reach roughly USD 2.73 billion by 2032, representing a compound annual growth rate (CAGR) of 13.52% across the forecast period.
Real Time Shelf Monitoring System Market
Implication for 2026 planning: this rate of growth implies a maturing market where winners will be those who move beyond point solutions to platform plays, deliver measurable in-store ROI, and build integration pathways into retailers’ core systems (POS, WMS, ESL, analytics). Enterprises should treat RTSM as a multi-year program — not a one-off project — and allocate capital accordingly in 2026 planning cycles.
Real Time Shelf Monitoring System Market
What PW Consulting’s Report Contains (Practical, Actionable Items)
- Market sizing and forward-looking scenario analysis that supports budgetary planning and capital allocation for 2026–2028 initiatives.
- Vendor evaluation framework and comparative scorecards (technology capability, deployment model, data governance, integration depth, and commercial terms) to streamline RFP and shortlisting processes.
- Implementation playbooks and PoC templates — camera placement guidelines, sampling protocols, data labeling expectations, and KPI definitions (shelf compliance, out-of-stock reduction, replenishment lead times, sales uplift models).
- Technology decision matrices that help buyers evaluate trade-offs between computer vision, robotics, RFID/ESL-integrated solutions, and sensor-based approaches, including recommended architectures for edge versus cloud processing.
- Commercial tools: subscription vs. CapEx TCO models, SLA and outcome-based contracting templates, and a procurement checklist focused on interoperability and vendor lock-in mitigation.
- Privacy & compliance toolkit addressing GDPR and regionally evolving privacy regimes, plus a vendor-agnostic matrix for assessing privacy-by-design claims.
- Use-case ROI calculators and industry-specific adoption roadmaps for grocery, convenience, and specialty retail formats—presented as configurable templates for enterprise teams.
These deliverables are designed to move a retailer or CPG from strategy to pilot to scaled rollout within 12–24 months, with measurable governance and KPIs to track progress.
Competitive Landscape — How Leading Vendors Are Positioning
The market shows a balanced mix of specialized vision-first vendors, robotics innovators, and traditional retail-technology players extending into shelf monitoring. Current market concentration metrics (CR3 approx. 32.5%; CR5 approx. 44.8%) indicate a market that is neither a pure oligopoly nor highly fragmented — incumbents have meaningful share, but there is ample room for focused entrants and regional champions.
- Trax Retail (Singapore / Boston) — Trax’s strength is mature, AI-driven image recognition and deep experience in planogram compliance and execution analytics. Their platform orientation and large-scale deployments make them a default consideration for global retailers seeking a proven enterprise-grade partner.
- Focal Systems (USA) — Known for shelf-facing cameras and a Shelf AI platform, Focal targets operational automation and automated replenishment use cases. Their integrated hardware-software approach shortens time-to-value for replenishment-focused pilots.
- Pensa Systems (Austin, Texas) — Pensa has accelerated platform expansion into full retail formats and upstream supply-chain contexts. Their recent platform broadening (April 2026) makes them an interesting contender for retailers seeking a single partner for shelf and back-room visibility.
- Vispera (Istanbul) — With an image-recognition product (Shelfsight) tailored to shelf-facing camera deployments, Vispera combines lightweight deployment models with analytics oriented to out-of-stock detection and planogram compliance.
- VusionGroup (SES-imagotag) (France) — Vusion’s Captana solution is notable for integration with electronic shelf labels (ESL) and the use of mini-cameras designed to avoid monitoring individuals — an important privacy-forward engineering choice aligned with GDPR constraints.
- Simbe Robotics (San Francisco) — Simbe’s Tally autonomous robots and Store Intelligence platform deliver a robotics-driven data capture model. Recent product updates (Tally 4.0 in January 2026) extend runtime and edge AI capabilities, enabling more frequent and higher-fidelity shelf scans across large store fleets.
- ParallelDots (India/global) — ParallelDots offers the ShelfWatch image recognition platform, bringing a cost-competitive option that resonates with price-sensitive markets and regional rollouts.
Strategically, we observe three vendor moves worth watching in 2026: platform consolidation (bundling shelf intelligence into broader store operations suites), horizontal expansion into supply-chain/back-room operations, and deeper ESL/IoT integrations that convert shelf-state signals into automated pricing and replenishment actions.
Regulation, Standards, and Technology Convergence
Two industry dynamics are reshaping buyer requirements:
- Privacy compliance: GDPR and similar regional privacy regimes have pushed vendors toward camera designs and data-processing models that minimize person-identifiable data. Deployments that advertise “no-person capture” or on-device anonymization are becoming procurement table stakes.
- Standards-driven integration: The convergence between RTSM systems and electronic shelf labels (ESL) is accelerating. Live linkages between shelf imagery, product metadata, and price/label infrastructure enable new closed-loop automation opportunities but also raise integration complexity.
Practical Guidance for Enterprise Decision-Makers in 2026
For retailers and CPGs planning RTSM investments in 2026, PW Consulting recommends a three-track approach:
- Fast-Start Pilots (0–6 months) : Run constrained PoCs that target a single high-value aisle or store cluster to validate detection accuracy, operational integration, and uplift assumptions. Use our PoC templates to set realistic success criteria.
- Platform & Integration Planning (6–18 months) : Specify required integrations (POS, ESL, WMS, replenishment engines) and demand APIs/data contracts during procurement. Prioritize vendors with flexible integration modes (edge-first, hybrid cloud) to future-proof deployments.
- Scale & Governance (18–36 months) : Prepare to move from pilots to fleet rollouts with clear SLAs, data governance rules, and an outcomes-based commercial model. Build a cross-functional center of excellence (store ops, IT, merchandising, legal) to manage change and measure sustained ROI.
Risks and Mitigations
- Data quality risk — mitigate with strict ground-truthing, controlled lighting and camera mounting standards, and periodic model revalidation.
- Vendor lock-in risk — mitigate with API-first contracts, modular procurement, and rights to labeled datasets for model portability.
- Operational adoption risk — mitigate via change management programs that align store teams on replenishment workflows and exception handling processes.
- Privacy/regulatory risk — adopt privacy-by-design benchmarks from our compliance toolkit and require vendors to demonstrate anonymization and data minimization practices.
Why PW Consulting’s Report Matters for 2026 Budgets
Decision-makers often ask: should RTSM be treated as a technology investment, a store operations program, or a merchandising capability? Our analysis shows it is all three — and financial planning should reflect this hybrid nature. The market’s growth profile and vendor evolution make 2026 a pivotal year for establishing scalable, vendor-agnostic architectures and contracting models that convert shelf visibility into sustained margin improvement.
The full PW Consulting report provides the granular segmentation, vendor scoring, regional adoption patterns, and scenario-based financial models that operational and procurement teams need to finalize 2026 budgets and rollout schedules. This preview outlines the strategic contours; the complete intelligence — including vendor scorecards, detailed segmentation tables, and downloadable PoC artifacts — is available on our report page.
Next Steps
- Download the full PW Consulting Real Time Shelf Monitoring System Market report to access the complete dataset, vendor rankings, and downloadable implementation tools.
- Contact our advisory team for a tailored briefing or to commission a workshop that maps the report’s findings to your organizational priorities and 2026 operating plan.
PW Consulting is committed to helping retailers and CPGs translate shelf-level data into reliable, repeatable, and auditable operational outcomes. In a market expanding at a projected 13.52% CAGR, 2026 is the year to move from experimentation to enterprise deployment — with governance, measurement, and vendor strategy front and center.
For detailed analysis of this topic, please visit the official page: Real Time Shelf Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Glass Substrate Market for Hard Disk Drives Set to Expand at a 5.85% CAGR During 2026–2032
By PW Consulting, 2026-07-13
Glass Substrates for Hard Disk Drives — Strategic Outlook to 2032: A PW Consulting Preview
PW Consulting’s new market study on glass substrates for hard disk drives (HDDs) frames a clear growth trajectory and a compact competitive structure that will shape supplier strategy, OEM roadmaps, and procurement decisions through 2026 and beyond. Using 2025 as our base year and a 2026–2032 forecast horizon, the market expands from a historical USD 380 million in 2020 to USD 520 million in 2025 and is projected to reach roughly USD 774 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.85% across the forecast period. This preview highlights why the report is strategically actionable for executives planning capex, sourcing, and product roadmaps in 2026 while preserving the granular intelligence reserved for the full report.
Glass Substrate For Hard Disk Drives Market
Why this report matters for 2026 decision-makers
-
Timing capital and capacity: The market’s mid-single-digit CAGR masks inflection points driven by nearline demand cycles, higher platter counts, and technology transitions (e.g., HAMR readiness). Understanding the cadence of demand vs. lead times for glass-substrate capacity is essential to avoid over- or under-investing.
Glass Substrate For Hard Disk Drives Market -
Supplier concentration and negotiating leverage: The substrate supply chain is highly concentrated (our analysis shows the top three firms control a dominant share and the top five control an overwhelming majority). Executives need scenario-driven procurement playbooks that factor in supply-side tightness, qualification cycles, and strategic collaboration options.
Glass Substrate For Hard Disk Drives Market -
Design-for-supply and product strategy: Decisions about platter counts, drive thickness, thermal budgets (HAMR/LAMR), and form factors are materially affected by glass substrate capabilities. Early alignment between system architects and substrate suppliers shortens qualification times and reduces time-to-market for higher-density HDDs.
-
Risk-adjusted cost planning: Raw material volatility and environmental constraints in glass manufacturing introduce appreciable cost and schedule risk. Procurement and finance teams must incorporate sensitivity scenarios into 2026 budgets and multi-year forecasts.
Key themes shaping the market
-
Nearline storage demand continues to underpin growth. Cloud and hyperscale requirements for cost-per-TB and power efficiency sustain HDD adoption where cost-effective bulk storage is prioritized over pure performance.
-
Glass substrates enable technical progress. Glass provides rigidity, dimensional stability, and thermal resilience needed for higher platter counts, thinner stacks, and emerging heat-assisted recording designs — enabling OEMs to push areal density without compromising mechanical stability.
-
Supplier concentration drives strategic dependencies. A small set of capable substrate producers shapes qualification timelines, pricing behavior, and capacity availability — making supply-side intelligence a critical input to corporate strategy.
-
Raw material and regulatory pressure. Inputs such as soda ash and the energy intensity of furnaces are both cost levers and regulatory targets. Environmental regulation on CO2 and related emissions is catalyzing investments in cleaner technologies and recycled-content strategies across glass production.
-
Product milestones are accelerating ecosystem change. Recent OEM and component milestones are validating glass-based approaches for higher-capacity nearline drives, creating adoption windows that suppliers and system integrators must act upon quickly.
What the PW Consulting report delivers — practical, execution-ready modules
-
Executive brief and decision-trees tuned for 2026: One-page guidance for CEOs, CFOs, and VPs of Product that maps actions to three strategic postures (expand, partner, hedge).
-
Market sizing and forecast model (2020–2032): Transparent methodology and downloadable model with base-year calibration, demand drivers, and scenario toggles to test upside/downside assumptions.
-
Supply-chain map and capacity tracker: Facility-level visibility, typical lead times, and a timeline of announced and planned capex — enabling procurement to model delivery risk windows.
-
Cost-build and sensitivity analysis: Line-item cost models showing how inputs (raw materials, energy, yield curves) affect substrate unit economics and OEM bill-of-materials.
-
Competitive benchmarking and supplier scorecards: Capability, quality, technology roadmap, capacity, and commercial behavior assessments for incumbent players, plus an M&A/partnership scoreboard.
-
Technology adoption playbook: Qualification pathways for glass substrates across form factors and recording technologies, plus common failure modes observed during pilot runs.
-
Risk scenarios and mitigation strategies: Contingency planning templates for supply shock, raw material spikes, regulatory shifts, and demand compression.
-
Commercial and procurement templates: Model contracts, strategic sourcing checklists, and negotiation levers tailored to high-concentration supplier markets.
Competitive landscape — what matters and why
Our competitive analysis spotlights the single global-scale substrate manufacturer that dominates production for multiple HDD form factors and segments. This supplier’s technical leadership — particularly in producing high-quality glass that supports higher platter counts, thinner designs, and heat-tolerant recording technologies — gives it outsized influence over OEM design cycles and qualification timelines. Recent industry moves underscore this dynamic: the supplier announced a significant capacity expansion investment in Vietnam (announced April 2026), intended to align output with nearline HDD demand growth and operationalize scale advantages by the late 2020s.
At the same time, OEMs are validating glass-based platform architectures: recent product milestones and sampling programs from major HDD manufacturers indicate that glass substrates are moving from advanced qualification into early production for higher-capacity nearline products. These technical confirmations compress adoption risk but increase the value of fast, reliable substrate supply.
Market concentration numbers underscore a structural reality: a small group of firms capture the overwhelming majority of supply. For buyers, this means that strategic sourcing is not about spot-price wins but about securing alignment on capacity commitments, co-development roadmaps, and contingency sourcing in the event of supply disruptions.
Supply-chain and input-cost signals to watch in 2026
-
Soda ash pricing and availability: Soda ash is a primary flux in glass production and has a material impact on substrate costs and producer margins. Market intelligence in early 2026 shows divergent signals: one source reported Chinese domestic trading at about 2,600 RMB/ton in early May 2026 (Sunsirs), while broader datasets reflected a softening trend with levels nearer to 1,200 CNY/ton earlier in the year (Industry Market Data, Feb 2026). The disparity highlights regional spreads and the need for real-time procurement monitoring.
-
Energy and emissions regulation: Stricter environmental requirements in major markets increase operating costs for furnace-driven glass production and drive capital investment into lower-emission technologies and recycled content handling.
-
Capex timelines: Announced capacity expansions should be tracked against actual commissioning schedules. Even well-capitalized projects can slip, creating tightness windows that affect pricing and availability for OEMs and contract manufacturers.
-
OEM adoption rates: Monitor sampling-to-production conversion metrics and the rate at which system integrators increase platter counts and thinner-stack designs — these directly translate into substrate volume demand.
Concrete actions for executives during 2026
-
For procurement leaders: Recast supplier engagements around capacity commitments and co-development clauses rather than purely unit-price negotiations. Introduce raw-material pass-through clauses and establish hedging or index-linked mechanisms where appropriate.
-
For product and engineering: Prioritize early cross-functional qualification programs with substrate suppliers to reduce time-to-production for new high-capacity SKUs. Allocate engineering resources to thermal and vibration testing specific to glass-based platters.
-
For corporate development: Use the current concentration to rationalize M&A and partnership screens — targets include finishing/processing assets, niche substrate refiners, and vertically adjacent suppliers that could offer partial despecialization or near-term capacity relief.
-
For finance and strategy: Build stress-tested forecasts that incorporate raw-material price swings and regulatory capex. Maintain contingency reserves or flexible capital plans to accelerate alternative sourcing or supplier expansions if market tightness materializes.
Next steps — where to get the full intelligence
This preview outlines the strategic contours PW Consulting’s full Glass Substrate for HDDs Market report covers. The full study contains the detailed models, supplier scorecards, and scenario tools your leadership team will need to convert insight into action in 2026. To access the complete dataset, downloadable financial models, and execution templates — including the granular segmentation, capex timelines, and strategic playbooks — please visit the PW Consulting reports page or contact our research team to arrange a briefing.
PW Consulting’s analysis is built to transform market intelligence into executable strategy. In a market where a handful of suppliers and evolving technology milestones determine the pace of innovation and capacity, the right insight — delivered at the right time — is the differentiator between meeting enterprise storage demand profitably or falling behind.
For detailed analysis of this topic, please visit the official page: Glass Substrate For Hard Disk Drives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Multi‑Domain Controller Market to Surge from USD 3,200M in 2025 to USD 8,256.35M by 2032 at 14.5% CAGR — Cockpit‑ADAS Fusion Leads with USD 1,920M
By PW Consulting, 2026-07-13
Automotive Multi-Domain Controller Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest Automotive Multi-Domain Controller Market report (base year 2025, historical coverage 2020–2025, forecast 2026–2032) synthesizes market, technology, regulatory and supply-chain intelligence to inform high-stakes decisions by OEMs, Tier‑1 suppliers, semiconductor vendors and investors. At the macro level the market is undergoing rapid expansion: our model projects the global market to grow from approximately USD 3,200 million in 2025 to more than USD 8,250 million by 2032, representing a compound annual growth rate (CAGR) of 14.5% across the forecast horizon.
Automotive Multi Domain Controller Market
Why 2026 is a strategic inflection point
-
Convergence of compute, software and regulation: The combined acceleration of software‑defined vehicle architectures, advanced driver assistance and cockpit consolidation is crystalizing commercial requirements for multi‑domain controllers (MDCs). Practical implementations announced in 2024–2026 validate architectures that were once conceptual; 2026 is the year many OEM programs move from pilots to production commitments.
Automotive Multi Domain Controller Market -
Node-level semiconductor advances: Automotive-grade multi‑domain SoCs introduced at bleeding-edge process nodes enable concurrent ADAS, IVI and gateway workloads in a single package—redefining BOM architectures and supplier role cards.
Automotive Multi Domain Controller Market -
Regulatory and safety pressure: Evolving mandates for functional safety, cybersecurity management systems and active safety features are lowering tolerance for fragmented, function‑specific ECUs, creating a regulatory tailwind for consolidated MDC strategies.
Market trajectory — the big picture (macro figures)
Our bottom‑up model reconciles supplier bill‑of‑materials trends, OEM architecture roadmaps, software monetization scenarios, and vehicle production forecasts. Key macro takeaways: the MDC market scale shows a clear and durable expansion from the early 2020s into the early 2030s. The baseline estimate for 2023 and 2024 provides continuity into the 2025 base year (USD ~3.2B), with the 14.5% CAGR projecting the market to exceed USD 8.2B by 2032. This magnitude of growth creates both large addressable opportunity and intensifies competitive pressure across hardware, middleware and services.
Competitive landscape — who matters and why
The market is already contested by a mix of legacy automotive suppliers, Tier‑1 system integrators and semiconductor platform leaders. Our competitive benchmarking highlights differences in go‑to‑market vectors rather than raw share numbers alone. Key archetypes we observe:
-
Automotive systems integrators (example incumbents): firms combining vehicle‑level integration experience and long OEM relationships to take responsibility for cross‑domain HPC deployment and validation.
-
Semiconductor platform vendors: suppliers offering hardened SoC families and reference stacks to accelerate OEM time‑to‑integration (compute performance, functional safety, real‑time determinism).
-
Software and cockpit specialists: companies focused on middleware, UI/UX consolidation, AI integration and electrical/ECU consolidation for digital cockpits.
Market concentration is material but not monopolistic: the top three providers capture a significant share of market revenues while the top five extend that dominance further—creating an environment where partnership strategies and OEM selection criteria determine competitive prospects as much as raw IP.
Recent industry moves that shape 2026 strategy
-
Leading SoC introductions and platform debuts have compressed time‑to‑production for centralized MDC concepts; these technology milestones lower technical risk but raise commercial complexity around licensing, roadmaps and long‑run supply agreements.
-
Demonstrations and production‑level implementations by system integrators validate cross‑domain HPC architectures for cockpit, ADAS and vehicle functions, making procurement decisions in 2026 more binary: adopt consolidated MDCs or accept escalating costs and complexity from distributed ECUs.
-
Regulatory updates are practical levers: mandatory cybersecurity frameworks and functional safety expectations increasingly appear in procurement RFPs and supplier qualification protocols.
Supply‑chain and operational headwinds
-
Component tightness and price volatility: Memory supply dynamics in early 2026 pushed legacy DRAM price increases materially year‑over‑year, affecting MDC BOM economics and supplier margin models.
-
Qualification and validation burden: ASIL compliance, deterministic real‑time performance and software update management require extended test cycles and expanded certification budgets—factors that extend ramp timing and increase pre‑production costs.
-
Software ecosystem fragmentation: differing middleware stacks, hypervisors and security frameworks across suppliers increase integration cost unless OEMs define strict interface and update standards.
Strategic imperatives for 2026 decision‑makers
Based on scenario analysis and client engagements, PW Consulting recommends the following priority actions for stakeholders planning resource allocations and contracts in 2026:
-
Define a compute architecture taxonomy tied to program timelines. Map near‑term production programs to “conservative consolidation” approaches and target later programs for “full‑consolidation” MDCs where tooling and supply risk permit.
-
Negotiate supply continuity clauses and multi‑year pricing for volatile components. For semiconductors and memory, secure options or forward commitments that include service‑level guarantees for qualification silicon and software fixes.
-
Adopt an interoperability and middleware mandate. Require suppliers to support standardized APIs, OTA update mechanisms, and cybersecurity certification pathways to reduce point‑integration cost.
-
Invest in validation at scale. Create centralized testbeds and digital twins for MDC workloads that exercise ASIL‑level failure modes, real‑time deterministic constraints and OTA recovery scenarios prior to high‑volume production.
-
Prioritize strategic partnerships over purely transactional relationships. Co‑engineering agreements with SoC vendors and Tier‑1 integrators can accelerate time‑to‑market and lock in roadmap features aligned with OEM product differentiation.
-
Build an M&A and investment watchlist. The pace of consolidation and the value of software IP suggest targeted acquisitions (middleware stacks, validation tooling, cyber capabilities) will be accretive to OEM and supplier strategies.
What PW Consulting’s report delivers (practical chapter map)
The full report is structured to be immediately actionable for procurement, product and corporate strategy teams. Highlights include:
-
Proprietary market sizing and scenario forecasts aligned to program timelines (base year 2025; 2026–2032 forecast).
-
Supplier profiles and competitive benchmarking, assessing product roadmaps, safety/cyber posture, and go‑to‑market strengths.
-
Technology deep dives on SoC architectures, hypervisor strategies, middleware stacks and software‑defined vehicle enablers.
-
Regulatory and compliance playbook covering functional safety, UNECE cybersecurity requirements and safety testing implications.
-
Procurement checklists, validation matrix templates and sample contract language to mitigate supply and performance risk.
-
Strategic scenarios and M&A opportunity maps that quantify value creation across different consolidation and partnership models.
Note: This release follows the “trailer” principle—core subsegment granularity (regional breakdowns, controller‑type and vehicle‑type line items) and the complete set of tables and proprietary model outputs are intentionally omitted from this summary to protect client value and will be available with the report or a licensed excerpt on the PW Consulting portal.
Implications by stakeholder
-
OEMs — Use 2026 to lock in compute suppliers for next‑generation programs, establish shared validation infrastructure and codify application interfaces to de‑risk integration.
-
Tier‑1 suppliers — Differentiate by offering system‑level integration and compliance services (safety, cyber) rather than competing solely on hardware components.
-
Semiconductor vendors — Balance lead‑node investments with deterministic real‑time features and automotive lifecycle support to capture OEM design wins.
-
Investors — Evaluate players on combined hardware/software roadmaps, contract stickiness and recurring revenue potential from updates and service offerings.
Why PW Consulting
Our advisory combines hands‑on engagement with OEMs and Tier‑1s, primary research with suppliers and a scenario‑driven financial model that translates technical roadmaps into procurement and P&L impacts. The report distills that work into executable briefs, negotiation artifacts and a near‑term action plan tailored for 2026 program cycles.
Next steps
For executives preparing 2026 budgets and supplier strategies, the full report provides the granular segmentation, supplier scorecards and playbooks needed to move from intent to contract. To request a report extract, schedule a briefing, or commission a tailored workshop applying these findings to your program portfolio, please visit the PW Consulting report landing page or contact our Automotive Practice lead for a confidential consultation.
For detailed analysis of this topic, please visit the official page: Automotive Multi Domain Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lowdk Glass Fiber Cloth Market to Expand at 8.15% CAGR During 2026–2032, Fueled by Asia‑Pacific Demand
By PW Consulting, 2026-07-13
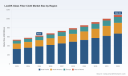
Lowdk Glass Fiber Cloth Market: Strategic Outlook 2026 — PW Consulting Preview
Executive summary
PW Consulting’s new market study on Lowdk Glass Fiber Cloth (base year 2025, historical 2020–2025, forecast 2026–2032) shows a robust growth trajectory underpinned by accelerating demand from AI servers, high-speed communications and advanced semiconductor packaging. The market is projected to expand at a compound annual growth rate (CAGR) of 8.15% across the forecast window, rising from approximately USD 625.5 Million in 2025 to an estimated USD 1,082.5 Million by 2032. This preview highlights the report’s strategic value for corporate decision-makers in 2026 — what to prioritize, which risks to hedge, and the high-return opportunities likely to shape supplier and OEM strategies over the next 18–36 months.
Lowdk Glass Fiber Cloth Market
Why this market matters for 2026 corporate strategy
Low dielectric (Lowdk) glass fiber cloth has transitioned from a specialized materials niche to a core enabler of high-frequency, high-density electronics. Key end-markets — from AI data centers and high-performance computing to 5G infrastructure and advanced automotive radar/ADAS — are raising technical requirements for dielectric constant (Dk), dissipation factor (Df), and coefficient of thermal expansion (CTE). As a result, demand is both growing and bifurcating into premium, supply-constrained grades and more commoditized offerings. For strategic planners, procurement leads, R&D heads and M&A teams, this means planning around availability, price volatility, and technology differentiation is now mission-critical.
Lowdk Glass Fiber Cloth Market
Market trajectory and what the headline numbers tell you
The headline forecast — CAGR 8.15% from 2026 to 2032 — signals sustained, above-market growth driven by structural factors rather than short-term cyclical demand. The 2025 market base provides a credible anchor: the sector has already scaled into the mid-hundreds of millions (USD) and is set to roughly double over the forecast horizon. This pace supports investment cases for capacity expansions, selective upstream integration, and targeted product development aimed at ultra-low-loss and low-CTE grades.
Lowdk Glass Fiber Cloth Market
Key dynamics shaping the near-term (2026) landscape
- Demand concentration in advanced electronics — AI servers, high-speed networking and semiconductor packaging are the primary growth drivers; their capital cycles and technology roadmaps will set procurement cadence for Lowdk cloths.
- Supply-side tightness — lead times for advanced low Dk / low CTE fabrics have extended, and capacity additions are unevenly distributed globally. Companies should expect constrained availability of premium grades through at least mid-2027 unless new capacity ramps faster than current guidance.
- Price stratification — advanced grades command multiples versus commodity E-glass; premium ASPs and announced supplier price actions reflect this tiering and persistent raw-materials tightness.
- Geopolitical concentration risks — high-end supply remains concentrated among suppliers in Japan, Taiwan and a handful of specialty producers in North America, which creates both supply risk and strategic opportunity for localized capacity expansion.
Competitive landscape — an investor and sourcing lens
The market exhibits moderate-to-high concentration: the top three players hold a material share of advanced-grade supply, and the top five capture a sizable portion of premium business. This structure creates a dual reality for buyers and investors: stable relationships and quality consistency with established suppliers, but also limited buyer leverage for cutting-edge grades when demand spikes.
Notable market participants include:
- Nittobo (Nitto Boseki Co., Ltd.) — Tokyo-based leader in integrated NE-glass and T-glass products; dominant in advanced low-Dk and low-CTE offerings, and a price/availability setter for premium segments.
- AGY — U.S.-headquartered specialty fiber producer expanding low-Dk capacity in Aiken, SC, and actively partnering to localize advanced fabric production in North America.
- Taiwan Glass, Fulltech Fiber Glass, Nan Ya Glass Fabrics and other East Asian specialists — collectively scaling high-end production to capture AI-driven demand.
- JPS Composite Materials — U.S. weaver partnering with fiber producers to deliver low-CTE fabrics for IC substrates and advanced packaging markets.
- Other regional producers in China and Japan that are adding volume, particularly for electronic-grade glass fiber and fabric production.
Strategic takeaway: supplier selection in 2026 should weigh technical fit and roadmap alignment more heavily than price alone. Securing offtake or strategic partnerships with technologically differentiated suppliers will be a differentiator for system houses and CCL manufacturers.
Recent industry developments that affect 2026 decisions
- Product innovation: December 2025 saw a new low-dielectric fiber launched for advanced semiconductors and AI servers, signaling continued upstream material innovation that will cascade into fabric capabilities.
- Capacity and investment: AGY announced a multi-million dollar capacity expansion in late 2025 and entered a strategic partnership with a North American weaver in early 2026 to produce low-CTE fabrics locally — a clear example of near-term supply de-risking.
- Regional expansions: Leading Taiwanese players increased capital allocation to high-end cloth production in 2026 to address AI-related demand; at the same time, large Chinese bases began ramping significant electronic glass fiber and fabric lines, shifting some dynamics on cost and volumes.
- Pricing & availability: Premium material suppliers instituted meaningful price increases in 2025 and signaled further uplifts in 2026 amid shortages — an important input for procurement and product-margin planning.
Strategic actions for 2026 — a practical playbook
- Prioritize dual-sourcing and forward contracts for premium grades. Where technical parity exists, favor suppliers offering capacity commitments and co-development support.
- Evaluate selective vertical integration or equity partnerships with specialty fiber producers or weavers to secure critical supply and capture margin uplift on premium products.
- Accelerate technical roadmaps: R&D investments in lamination, resin compatibility and panel processing can unlock higher-value applications for existing cloth choices and reduce sensitivity to raw-material price swings.
- Revise product-cost models to reflect higher ASPs for low-Dk grades; incorporate scenario planning for further price increases and extended lead times through mid- to late-2027.
- Use geographic diversification: align procurement with regional manufacturing strategies (e.g., CCL southward shifts) to reduce logistics risk and tariff exposure while maintaining access to advanced grades.
- Prepare M&A and JV playbooks: target technology-rich weavers and specialty yarn providers in regions with supportive investment incentives or lower labor-cost baselines.
What PW Consulting’s full report delivers (practical, operational intelligence)
Our full report goes beyond headline growth to provide actionable frameworks and tools for 2026 strategy execution, including:
- Demand-mapping by end-market and technology pathway to prioritize product investment and market entry sequencing.
- Supply-chain heatmaps identifying capacity by technology tier and projected lead-time windows through 2027, with contingency scenarios for accelerated AI investment cycles.
- Vendor benchmarking across technical parameters (Dk/Df/CTE), capacity scale, and commercial terms to support sourcing negotiations and long-term procurement contracts.
- Price and margin simulation models that enable CFOs and product managers to stress-test P&L under multiple pricing and supply scenarios.
- Deal flow and partnership guidelines for strategic investments, JV structures, and co-development agreements specific to the Lowdk ecosystem.
How corporate leaders should use this analysis in 2026
Decision-makers should treat Lowdk glass fiber cloth as a strategic raw material rather than a commodity. Tactical steps include embedding forecast sensitivity into capital allocation, renegotiating supplier terms to reflect longer lead times, and moving from transactional sourcing to strategic partnerships with producers that offer roadmap alignment and capacity guarantees. R&D and product teams should prioritize compatibility testing and qualification cycles now — lead times for qualifying new cloths into PCBs or substrates can exceed typical project timelines and will be a gating factor for next-generation product launches.
Final note — the intelligence gap and next steps
This preview outlines the structural growth drivers, competitive dynamics and practical decision levers that will shape corporate results in 2026. For procurement, product and corporate strategy teams seeking the granular segmentation, regional flows, price trajectories and vendor scorecards necessary to build execution-ready plans, the full PW Consulting report contains proprietary splits, scenario models and supplier-level analysis. These detailed tables and strategic appendices are intentionally withheld from this public summary to preserve competitive value and are available via our report portal.
Contact & access
Clients and executives seeking direct consultation on how these findings apply to specific portfolios, supply chains or M&A strategies can request tailored briefings and the full dataset through PW Consulting’s Lowdk Glass Fiber Cloth Market report page.
For detailed analysis of this topic, please visit the official page: Lowdk Glass Fiber Cloth Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Supply Chain IT Transformation Services for Retail Market to Grow at 9.85% CAGR, Reach USD 27.99 Billion by 2032
By PW Consulting, 2026-07-13
Supply Chain IT Transformation Services for Retail Market — Strategic Insights for 2026 Decision-Making
PW Consulting’s latest market research — Supply Chain IT Transformation Services for Retail Market (Base Year: 2025; Forecast: 2026–2032) — provides a concise, executive-grade intelligence package for leaders planning investments and programs in 2026. The global market reached approximately USD 14.5 Billion in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 9.85%, crossing the USD 27.9 Billion threshold by 2032. For senior executives, CIOs, and program sponsors, the report synthesizes growth vectors, regulatory imperatives, vendor positioning, and pragmatic implementation guidance designed to accelerate value capture while managing risk.
Supply Chain IT Transformation Services for Retail Market
Why this report matters for 2026
-
Capital allocation decisions in 2026 will determine which platforms, vendors, and architectures anchor retailers’ operations for the rest of the decade. The market’s steady near-double-digit CAGR signals both opportunity and competitive urgency: slower movers risk obsolescence as peers scale AI-enabled visibility and automation.
Supply Chain IT Transformation Services for Retail Market -
Regulatory complexity and labor-cost shifts are compressing timelines for compliance-driven modernization. Systems that cannot provide traceability, digital passporting, or robust data governance will create material operational and reputational exposures.
Supply Chain IT Transformation Services for Retail Market -
Technology maturity—especially in AI, orchestration, and cloud-native services—means early pilots can rapidly move to production. The report helps executives convert pilots into enterprise-grade programs with measurable ROI.
What PW Consulting’s report delivers (practical, hands-on content)
-
Executive dashboards and decision frameworks to prioritize investments by expected ROI, time-to-value, and strategic optionality—enabling 90–180 day playbooks for near-term wins.
-
Vendor evaluation toolkit: scorecards, weighted RFP templates, and contract negotiation playbooks that differentiate between delivery models (implementation, managed services, consulting-led transformation) and the risk profiles of each.
-
Implementation blueprints for common retail scenarios (omnichannel fulfillment, micro-fulfillment, demand sensing, and returns optimization) with integration patterns, estimated timelines, and TCO drivers.
-
Compliance and data-governance checklists tailored to new packaging/traceability mandates and data-privacy regimes—designed to accelerate audit readiness without blocking innovation.
-
AI adoption playbook: prioritized use-cases for visibility and forecasting, model governance controls, and a migration path from pilot to continuous learning operating models.
-
Workforce and operating model templates focused on labor optimization, role redesign, and vendor-supplier operating agreements that reflect evolving labor laws and pay-transparency regimes.
-
Risk and resilience scenario planning tools that quantify supply chain fragility and recommend layered mitigations across digital, physical, and contractual levers.
Market dynamics shaping 2026 strategy
-
AI and visibility. Adoption of AI-enabled visibility is accelerating. Current industry indicators show notable adoption today with a clear and measurable uplift expected within twelve months—this trend is moving from experimental projects to mission-critical services in 2026. Real-world implementations are driving faster inventory turns and measurable reductions in stock-outs.
-
Regulatory pressure. New rules on packaging, traceability, and recycled-content requirements are forcing retailers to embed compliance into IT transformation roadmaps. Traceability features, digital passports, and chain-of-custody workflows are now design considerations, not afterthoughts.
-
Privacy and data governance. Global privacy regimes (e.g., GDPR, CCPA) require architects to separate personal and operational data, apply consent-aware analytics, and maintain auditable processing logs—impacting design choices for telemetry, third-party integrations, and cloud residency.
-
Labor and cost dynamics. Rising labor costs and new work-hour regulations in key markets are increasing the ROI for automation, workforce optimization modules, and warehouse orchestration tools—shifting the calculus in favor of integrated IT+Ops solutions.
-
Fragmented buyer needs. The buyer landscape remains heterogeneous—some retailers prioritize rapid cloud adoption and packaged SaaS, while others need heavy customization due to complex store networks or legacy ecosystems. The market’s structure favors both scale players and specialized regional or vertical specialists.
Competitive landscape — how to read vendor signals in 2026
The competitive field combines global systems integrators, management consultancies, legacy technology incumbents, and specialized boutiques. The market concentration statistics indicate a moderately fragmented environment: the top three and top five providers command meaningful but not overwhelming shares, leaving ample runway for challengers and niche specialists. Below is a high-level synthesis of positional strengths among leading providers (profiled in the full report):
-
Tata Consultancy Services (TCS) (Mumbai) — Strengths include end-to-end transformation capabilities, advisory-led programs, and partnerships for digital core implementations. Recent industry recognition underscores maturity in executing large, complex retail and CPG transformations.
-
Cognizant (Teaneck, NJ) — Focused on IT modernization for planning, forecasting, and resilience. Effective where clients require rapid modernization of legacy planning stacks and integration of visibility use-cases across multi-threaded supply networks.
-
Accenture (Dublin) — Offers a broad portfolio across network orchestration, AI, and cloud-native implementations. Best suited for large-scale, end-to-end rewires of retail supply chain platforms where orchestration and cross-functional automation are priorities.
-
Deloitte (New York) — Combines deep consulting advisory with implementation partnerships, especially where clients want to pair strategic operating-model redesign with SAP or other ERP-centered transformations. Their recent guidance highlights measurable uplift from early AI deployments in retail visibility.
-
PwC (London) — Positioned around forward-looking supply chain architectures (the “supply chain of 2030”), with a strong emphasis on AI, automation, and flexible network design—high relevance for retailers seeking strategic roadmaps tied to regulatory and sustainability objectives.
-
IBM (Armonk, NY) — Brings advanced analytics and predictive capabilities to e-commerce and omnichannel players; a suitable choice where hybrid cloud and enterprise-grade AI governance are critical.
-
Parker Avery (Atlanta) & Brillio (Princeton) — Specialized boutiques focused on retail forecasting, inventory optimization, and modernization of supply chain operations; attractive for retailers seeking pragmatic, delivery-focused partners.
Implications for procurement and program architecture
-
Mix and match delivery models. Expect a hybrid of implementation projects, managed services, and consulting-led strategic programs. Procurement teams should design contracts that allow staged scope with clear KPIs and fast-fail milestones.
-
Buyer diligence matters. Use the vendor scorecards and RFP templates in the report to test delivery experience on compliance, AI governance, and multi-party data-sharing scenarios.
-
Prioritize interoperability. Architectural choices that favor open APIs, event-driven integration, and modular microservices reduce lock-in and support faster adoption of next-generation capabilities.
-
Embed compliance and traceability up front. Make traceability workflows and digital passporting mandatory requirements in vendor assessments rather than optional add-ons.
Practical recommendations for 2026
-
Start with targeted “value sprints”: pick two to three high-impact use cases (e.g., demand sensing, in-store replenishment, return processing) and deliver measurable KPIs within 3–6 months.
-
Require vendors to demonstrate production-level AI use-cases and provide model governance documentation during selection.
-
Design contracts with outcome-linked remuneration for initial implementations and transition to fixed-cost managed services once the solution reaches steady state.
-
Invest in an internal data-product function to own inventory, order, and customer signals—this accelerates reuse across initiatives and improves vendor governance.
-
Account for regulatory and labor changes in your scenario planning and capex approvals—run at least two regulatory stress tests before committing to long-term platform bets.
Next steps and how to access the full intelligence
This briefing is a strategic preview designed to accelerate executive alignment in 2026. PW Consulting’s full report contains the granular market tables, regional and application breakdowns, vendor scorecards, pricing benchmarks, and downloadable implementation artifacts that procurement and transformation teams use to build programs. To review the detailed segmentation, vendor evaluations, and the proprietary ROI models referenced here, please visit the report landing page for full access and supporting appendices.
For board-level briefings, bespoke vendor shortlists, or a tailored 90-day playbook aligned to your retail footprint and operating model, PW Consulting’s senior advisors are available for advisory engagements and rapid readiness assessments.
For detailed analysis of this topic, please visit the official page: Supply Chain IT Transformation Services for Retail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: GaN Wafers Market to Hit USD 8,350.15 Million by 2032, Growing at an 18.5% CAGR — Asia Pacific Commands USD 1,349.72 Million
By PW Consulting, 2026-07-13
PW Consulting Strategic Brief: GaN Wafers Market — A 2026 Playbook for Competitive Advantage
As organizations re-tool semiconductor roadmaps for accelerated electrification, high-frequency communications and next-generation optoelectronics, the GaN (gallium nitride) wafer market is entering a decisive phase. PW Consulting’s latest market study — anchored on a 2025 base year, a 2020–2025 historical review and a 2026–2032 forecast horizon — quantifies a high-growth trajectory driven by technology maturation, capacity reconfiguration and raw-material-driven supply dynamics. Key headline metrics from our analysis: the GaN wafers market reached USD 2,550 Million in 2025 and, under our base forecast, expands at a compound annual growth rate (CAGR) of approximately 18.5% through 2032.
Gan Wafers Market
Why 2026 Is a Strategic Inflection Point
-
Accelerating adoption cycles — Power electronics, RF and optoelectronics are shifting from early-adopter to scale-production phases. This moves GaN from a component choice to a core materials strategy for OEMs and fabs.
Gan Wafers Market -
Manufacturing scale and substrate innovation are converging. Announcements and proof points for scalable wafer diameters and novel substrates are shortening the time-to-volume for higher-performance devices; these technological transitions materially alter CapEx and supply decisions.
Gan Wafers Market -
Supply-chain volatility and geopolitics are reshaping sourcing strategies. Recent shifts in gallium export controls and a marked rise in unit import values have created an environment where raw-material access and price risk must be managed actively, not assumed benign.
What This Report Delivers — Practical Intelligence, Not Only Numbers
PW Consulting’s GaN Wafers Market report is designed as an operational playbook for 2026 decision-making. It blends rigorous market sizing with scenario-based strategic guidance and practitioner tools that buyers, investors and suppliers can immediately apply:
-
Comprehensive market sizing and a transparent forecast model covering 2026–2032, including upside/downside scenarios tied to substrate breakthroughs and capacity ramp timelines.
-
Technology pathway analysis that compares wafer/substrate approaches (including bulk GaN, GaN-on-Si, GaN-on-SiC strategies), process economics, manufacturability, and device-performance implications.
-
Supply-chain due diligence modules: supplier scorecards, raw-material sensitivity analyses, inventory and contract structures, and a recommended contract playbook for securing gallium and precursor supply.
-
Commercial and go-to-market tools: pricing elasticity models, buyer’s guide for wafer qualification, foundry engagement frameworks, and channel/stakeholder mapping for faster qualification cycles.
-
M&A and partnership playbook: target archetypes, valuation comps, integration-risk checklists and negotiation playbooks that reflect capex timing and IP considerations.
-
Decision-ready deliverables including Excel-based financial templates (CapEx/Opex scenarios), risk matrices, and a prioritized scoreboard of strategic actions tailored to OEMs, material suppliers and fabs.
Competitive Landscape — Who Matters and Why
The current GaN wafer ecosystem is a mix of specialized substrate producers, large-scale epiwafer players, and integrated materials-device companies. Our vendor analysis highlights strategic positions, technology moats and potential vectors for consolidation:
-
Eta Research Ltd. (Shanghai, China) — Bulk GaN specialist using an in-house HVPE process to deliver free-standing GaN wafers in small-to-medium diameters. Their control over bulk growth and materials variants (UID, doped, semi-insulating) gives them a strong position for laser diode and RF substrate markets where material quality and customization are decisive.
-
Sanan Optoelectronics / Sanan Semiconductor (China) — A high-capacity epiwafer and foundry player, notable for aggressive capacity expansion and integrated services. Their GaN-on-Si capabilities make them a pivotal partner for high-volume power electronics and UV/LED supply chains.
-
Sumitomo Electric Industries (Japan) — Focused on vapor-phase epitaxy and larger-diameter GaN-on-GaN wafers, Sumitomo’s work on enhanced substrates (including recent demonstrations on alternative substrates) positions them as a strategic supplier for high-performance power devices.
-
NGK Insulators (Japan) — Proprietary liquid-phase crystal growth delivering low-dislocation-density GaN substrates. Their high-crystallinity products are particularly relevant to RF and optical applications where defect density directly impacts device yield.
-
IQE plc (Cardiff, UK) — Epitaxy specialist across SiC, Si, GaN and engineered substrates with recent partnership activity to develop automotive-grade GaN platforms. Their ecosystem approach (epitaxy + partner foundries) is attractive to customers seeking platform-level assurances.
-
Wolfspeed, Inc. (Durham, NC, USA) — A leader in GaN-on-SiC and integrated device material solutions for RF and high-performance applications, with a strategic emphasis on quality and device integration for demanding markets.
Recent and Near-Term Catalysts
-
Infineon’s public roadmap for scalable 300mm GaN manufacturing with customer samples slated in late 2025 has accelerated OEM timelines for qualification and volume adoption.
-
Sumitomo’s demonstration of GaN-HEMT on a polycrystalline diamond substrate highlights substrate innovation that can materially improve thermal management and device efficiency.
-
IQE’s joint development agreement to create a 650V GaN power device platform signals consolidating demand from automotive and data-center customers and invites a new class of foundry partnerships.
Structural Risks: Raw Materials and Geopolitics
Material access and price volatility are now front-and-center risks for any strategic plan. In 2025, the average unit value of imported gallium into the U.S. increased significantly year-over-year; export controls and temporary policy reversals (including a time-limited easing of exports in late 2025) have introduced episodic supply windows. Additionally, U.S. import reliance for primary gallium remains effectively complete, underscoring the need for diversified supply contracts, strategic inventory policies and upstream co-investment where feasible.
2026 Strategic Imperatives — Five Actions for Immediate Implementation
-
Secure supply now: Move from spot purchase exposure to layered supply contracts (short-term + medium-term hedges + strategic volume options) and prioritize dual-sourcing across geopolitical blocs.
-
Adopt a stage-gated technology strategy: Structure CapEx around modular wafer-diameter scaling and qualification milestones rather than single-point bets on a substrate type.
-
Pursue co-investment and strategic partnerships: Consider minority equity in epi- or substrate suppliers, or long-term off-take agreements that include technology co-development to align roadmaps and reduce lead times.
-
Prepare to consolidate selectively: Identify high-value targets (IP-rich epitaxy shops, specialty substrate producers, or foundry partners) that can be integrated to secure technology differentiation and margin protection.
-
Embed scenario-driven procurement: Implement rolling scenario models to stress-test margins against raw-material price spikes, capacity delays and accelerated device adoption curves.
How PW Consulting Helps
For organizations needing to translate market dynamics into executable plans for 2026, PW Consulting offers tailored advisory packages that combine the full GaN wafers dataset with execution toolkits: customized CapEx and qualification roadmaps, supplier negotiation support, M&A target screening, and integrated risk-management playbooks. The full report contains the complete dataset, vendor scorecards, and downloadable models referenced in this brief — including the detailed forecast tables, segmentation matrices and exhaustive supplier profiles that we intentionally do not reproduce here.
Next Steps
For access to the full GaN Wafers Market report, detailed spreadsheets, and to schedule a briefing with our lead analysts, visit PW Consulting’s market reports page or contact your PW account lead. The coming 12–18 months will separate those who merely observe GaN’s promise from those who capture its strategic value — 2026 is the year to convert analysis into advantage.
For detailed analysis of this topic, please visit the official page: Gan Wafers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Broadband Router Market to Grow at 7.15% CAGR (2026–2032), Reaching USD 36,486.1 Million by 2032
By PW Consulting, 2026-07-13
Broadband Router Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Analysis
As broadband architectures, home connectivity expectations and regulatory regimes shift in near real time, corporate leaders need crisp, actionable intelligence that balances market-scale clarity with tactical discretion. PW Consulting’s latest Broadband Router Market report (base year 2025) delivers that combination: a data-grounded view of the sector’s trajectory — a global market that grew from roughly USD 19.6 billion in 2023 to USD 22.5 billion in 2025 and is forecast to expand at a steady compound annual growth rate of c. 7.15% across 2026–2032 — paired with operator-focused playbooks that protect competitive advantage while preserving commercially sensitive detail for report subscribers.
Broadband Router Market
Why this report matters for 2026 corporate decision-making
-
Timing: 2026 is a pivot year. Infrastructure deployment patterns (fiber reach and fixed wireless scale-ups), a wave of Wi‑generation upgrades, and newly intensified regulatory scrutiny are converging to reshape procurement, product roadmaps and channel strategies.
Broadband Router Market -
Scale and growth clarity: Our topline market sizing and forecast provide a reliable macro frame for capital planning and product investment. With the market expanding consistently into the early 2030s, executives can quantify portfolio growth potential while aligning to risk tolerances.
Broadband Router Market -
Action orientation: The report is designed as a decision tool — not just a descriptive study. It translates market signals into prioritized initiatives across R&D, manufacturing footprint, channel deployment, and M&A scouting.
Market outlook — what the numbers say (and what they don’t)
Our modeled forecast — built on historical patterns (2020–2025), operator CAPEX signals, technology migration rates and regulatory scenarios — points to persistent, mid-single-digit to upper single-digit CAGR expansion through 2032. This reflects sustained demand for upgraded home and enterprise edge devices, continued service provider investments in fiber and fixed wireless, and cyclical refresh waves tied to new Wi‑generation life cycles.
Importantly, while the aggregate opportunity widens, value capture will not be uniform: product differentiation (multi-gig throughput, mesh scalability, integrated security, managed services) and supply-chain resilience will determine margin trajectories. The report emphasizes where aggregate growth can be translated into outsized returns and where it risks becoming commoditized volume.
Regulatory and macro dynamics shaping strategy
-
National security and equipment approvals: Recent regulatory moves in some major markets have expanded lists of equipment subject to heightened authorization or conditional approvals. These policies materially affect the ability of vendors to introduce new consumer-grade devices without additional compliance steps and can change procurement windows for service providers.
-
Judicial and policy shifts on broadband classification: Changes in the regulatory doctrine governing broadband services are altering the contours of federal oversight and state-level policy levers. Market participants must model multiple regulatory scenarios into product and pricing strategies.
-
Infrastructure economics: Fiber is now serviceable to a majority of households in a leading market, but deployment costs — from labor to make-ready permitting — have risen markedly, changing the economics of capex-driven expansion. Simultaneously, spectrum policy and auctions are creating a growing runway for fixed wireless broadband as a strategic alternative.
-
Procurement and subsidy programs: Updates to major broadband subsidy programs emphasize technology neutrality and cost-effectiveness, accelerating competitive bids where suppliers can demonstrate rapid, low-cost installations.
Competitive landscape — strategic implications for core players
The router market today blends large enterprise-focused vendors with nimble consumer and platform players. A few strategic patterns emerge that are validated across our benchmarking and vendor interviews:
-
Cisco Systems: Strong enterprise and service-provider positioning, including cloud-native broadband routing platforms. Their prime strategic advantage is integration across access, aggregation and cloud orchestration layers. For Cisco, the near-term playbook centers on accelerating cloud-managed feature sets and deepening partnerships with large operators to convert capital spend into recurring software revenue.
-
TP‑Link / NETGEAR / ASUS / D‑Link / Belkin (Linksys) / Amazon (eero): These consumer and prosumer vendors compete intensely on feature-to-price ratios, brand trust and channel reach. As Wi‑generation upgrades (Wi‑6/6E → Wi‑7) and mesh adoption expand, differentiation will be driven by software ecosystems (security, parental controls, subscription services) and supply-chain agility. Regulatory constraints on imported consumer-grade equipment further elevate localization and compliance as priorities.
-
Huawei: Continues to be a supplier of advanced broadband gateways and ONTs globally. Geopolitical and regulatory headwinds impact market access in some markets; where accessible, Huawei competes on integration and cost, influencing price benchmarks for fiber and fixed wireless gateway devices.
-
Ubiquiti: Focused on scalable network management and hybrid consumer–SMB propositions. Their strengths in simplified enterprise-like management for SMB and venues make them a strategic partner for managed service rollouts.
Across the vendor set, several imperatives recur: (1) build regulatory-compliant SKUs and a compliance roadmap, (2) develop subscription-native services to lift lifetime value, (3) prioritize modular hardware platforms to accelerate new Wi‑generation introductions, and (4) secure diversified component sourcing to mitigate tariff and authorization disruptions.
Recent industry movements and tactical read-throughs
-
Regulatory lists and conditional approvals: The recent expansion of equipment lists requiring additional approvals has created both risk and opportunity. Vendors with exemption pathways or domestic-compliant product lines can convert short-term disruption into competitive share gains.
-
Product innovations — industrial and gateway: The introduction of TAA-compliant industrial 5G routers and demonstrations of next‑gen XGSPON gateways underscore two parallel trends: edge compute integration and readiness for extreme-density broadband endpoints. Service providers and enterprise adopters should re-evaluate edge compute roadmaps in tandem with access equipment refresh cycles.
-
Spectrum and fixed wireless: Planned spectrum auctions and growing interest in upper mid-band assets will expand fixed wireless viability, especially where fiber deployment faces steep incremental costs. Vendors that can deliver integrated customer premises equipment (CPE) for both fiber and FWA will hold strategic advantage.
What the PW Consulting report contains — operationally useful sections
-
Topline market sizing and 2026–2032 forecasting model with scenario toggles for regulatory and deployment variability.
-
Demand-driver analysis: household connectivity trends, gaming and OTT consumption, enterprise SD‑WAN and IoT access patterns.
-
Vendor benchmarking and go-to-market scorecards covering product architecture, software strategy, channel strength and compliance posture (note: granular segment shares and per-region revenue breakdowns are reserved in the full dataset to preserve commercial sensitivity).
-
Regulatory impact matrix mapping probable policy outcomes to product launch, certification and channel timing.
-
Supply‑chain and sourcing playbook with mitigation options for equipment authorizations, tariffs and supplier concentration risks.
-
M&A and partnership heatmap highlighting target archetypes and valuation sensitivities under different growth scenarios.
-
Actionable roadmaps for product teams, procurement and operator strategy groups — including a 90‑day playbook for urgent compliance and market access moves.
Recommended strategic moves for 2026 (prioritized)
-
Immediate compliance triage: Audit product lines against emergent authorization lists and secure conditional pathways or TAA/compliant alternatives where exposure is material.
-
Platform modularization: Invest in common hardware platforms that can be rapidly reconfigured for multiple regulatory markets and Wi generations to shorten time‑to‑market and lower SKU proliferation costs.
-
Monetize software: Bundle security, parental controls, and cloud management as subscription offerings to offset hardware margin pressure and stabilize revenue predictability.
-
Diversify access play: For network operators, pair fiber buildouts with fixed wireless pilots in cost-challenged geographies; for vendors, present converged CPE propositions for both access technologies.
-
Channel recalibration: Shift reseller incentives toward managed‑service enablement and recurring-revenue conversions rather than one‑time device pushes.
Concluding perspective — the strategic overlay
The broadband router market presents a classic “growth with complexity” opportunity. Aggregate demand and a predictable mid‑to‑late‑2030s expansion curve create a sizeable market context for investment, but regulatory shifts, infrastructure economics and technology transitions rework the routes to capture. PW Consulting’s Broadband Router Market report equips leaders with the contextualized forecasts, vendor intelligence and executable playbooks needed to convert growth into durable advantage — while reserving the granular segmentation intelligence that informs deal-level decisions for report subscribers.
Next steps
For leadership teams preparing budgets, product roadmaps or M&A pipelines in 2026, the report is designed to be a working document — not a summary. Access to the full dataset and vendor scorecards (including scenario models and the tactical 90‑day playbook) is available on our report landing page. Schedule a one-on-one briefing with PW Consulting’s broadband practice to translate the findings into a bespoke action plan for your organization.
For detailed analysis of this topic, please visit the official page: Broadband Router Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Prefabricated & Modular Data Centers Market Poised for Rapid Expansion at a 16.45% CAGR
By PW Consulting, 2026-07-13

Prefabricated and Modular Data Centers: Strategic Imperatives for 2026 — PW Consulting Industry Brief
As enterprises and service providers accelerate deployments for AI, edge compute, and resilient cloud capacity, the prefabricated and modular data center sector is moving from niche to mainstream. Our new market study — built on a 2025 base year, a 2020–2025 historical series, and a 2026–2032 forecast window — shows a sustained multi-year expansion driven by rising density requirements, time-to-deploy pressures, and shifting energy and regulatory constraints. The market expands at a projected compound annual growth rate (CAGR) of 16.45%, rising from a global market footprint in 2025 to more than double by the end of the 2032 forecast horizon. This briefing highlights why PW Consulting’s report is strategically essential for board-level and operational decisions in 2026 while preserving the detailed segment and supplier models contained in the full study.
Prefabricated And Modular Data Centers Market
Why this report matters for 2026 decision-makers
- Accurate timing for capacity investments. The rapid growth trajectory and compressing deployment windows make timing decisions critical — late commitments risk lost market share, while premature greenfield investments can lock in suboptimal energy profiles.
- Risk management against energy/regulatory shocks. New state-level rules and industry pledges shifting energy costs onto data centers create direct risks to total cost of ownership (TCO). The report models multiple regulatory scenarios so executives can stress-test site viability and contract structures before capital deployment.
- Supplier selection under performance constraints. As power density and liquid-cooling adoption accelerate, traditional supplier criteria (price, lead time) must be augmented with validated performance for high-density AI workloads. Our evaluation framework helps procurement teams prioritize vendor capabilities that matter in 2026.
- Faster, defensible go-to-market plays for edge and hyperscale. Modular approaches are no longer a single “build vs. buy” choice — they are a spectrum of factory integrations, pre-tested pods, and containerized units. The report’s deployment archetypes and decision trees convert that spectrum into actionable options for both capex and colo strategies.
What the PW Consulting report delivers — practical, board-ready material
- Comprehensive market sizing and a validated CAGR for 2026–2032, with scenario outputs to compare base, upside, and downside demand paths.
- Operational playbooks: step-by-step checklists for factory acceptance testing, standardized commissioning sequences for liquid-cooled pods, and integration templates for hybrid on-site/factory builds.
- Commercial tooling: capex/opex model templates, procurement scorecards, and sample contractual clauses to allocate utility upgrade and capacity expansion risk.
- Site-selection heuristics blending grid readiness, incentive overlays, latency needs, and constructability factors — with a ready-to-run matrix for prioritizing next-12-month investments.
- Supplier due-diligence kits: vendor capability maps, interoperability tests, and recommended warranty and spare-part programs tailored to high-density AI deployments.
- Scenario playbooks for regulatory outcomes: prescriptive advice for operating under incrementally stricter local rules on utility cost pass-through and grid contributions.
Competitive landscape — who is shaping 2026 deployments
The ecosystem spans global power and infrastructure incumbents, specialist integrators, and bespoke container manufacturers. Market concentration is moderate: the top three suppliers account for a material but not dominant share of the market, and the top five approach but do not exceed a simple majority — indicating room for differentiated entrants and specialist regional players. Below we summarize the strategic posture of leading firms and recent moves that will influence 2026 procurement and partnership decisions.
Prefabricated And Modular Data Centers Market
- Schneider Electric (Rueil-Malmaison, France) — Continues to position EcoStruxure Pods as turnkey solutions for high-density AI environments, with integrated liquid-cooling and high-power busway options. Recent partnerships with telecom and server OEMs underscore a strategy of vertical integration: bringing infrastructure, compute, and carrier ecosystems together to shorten deployment cycles.
- Vertiv (Columbus, Ohio, USA) — Accelerating product innovation with factory-integrated prefabricated lines focused on liquid cooling, overhead infrastructure, and scalable building blocks for multi-megawatt deployments. Global product launches and strategic collaborations with large-scale operators reflect a play to be the supplier of choice for accelerated AI rollouts.
- Huawei (Shenzhen, China) — Maintains a broad portfolio of containerized and modular units targeting telco edge and cloud-scale rollouts. Emphasis on compact, scalable modules enables rapid in-market buildouts particularly where telco partnerships matter.
- Eaton (Dublin, Ireland) — Plays to power-resilience strengths: UPS systems, integrated power distribution, and hardened container approaches for mission-critical and edge applications where uptime and redundancy dominate procurement decisions.
- Specialists and system integrators (BMarko, CenCore, Compu Dynamics Modular, PodTech, TAS, Delta Electric and others) — These vendors are the ecosystem’s flexible build-and-adapt layer. They offer customization, TEMPEST or defense-grade compliance, and tailored integration for hyperscale, colocation, edge, and government markets. Their role becomes pivotal where standardized factory kits do not meet unique site or regulatory requirements.
Notable recent developments to watch: Vertiv’s global rollouts and strategic collaborations in late 2025–early 2026 accelerate factory-integrated solutions for AI; Schneider’s late-2025 product introductions and early-2026 partnerships highlight the priority incumbents place on liquid-cooling and joint go-to-market approaches. These moves materially shorten procurement lead times and raise the bar for integrated testing and warranty offerings.
Prefabricated And Modular Data Centers Market
Regulatory and energy dynamics — constraints that will reshape sourcing and siting
- Shifting cost allocation — In 2026 several US states are enforcing rules that require data centers to bear the full cost of grid upgrades, and major hyperscalers have committed to pledges separating rate structures so households are shielded from data center-driven utility rate impacts. These developments force new TCO treatments: bids that once assumed utility-funded upgrades will now need explicit grid-upgrade line items and contingency allowances.
- Rising electricity prices — With residential rates appreciably higher in 2025 and utility filings linked to data center demand, location economics change. Our models show that energy-driven operating cost swings become a dominant differentiator among sites and solution architectures.
- Permitting and community acceptance — As lawmakers expand thresholds and local scrutiny, early engagement with regulators and commitment to community-impact mitigation are non-negotiable. The report provides templated stakeholder engagement plans and utility negotiation strategies to de-risk approvals.
Strategic recommendations for 2026 — action steps for executives
- Treat modular solutions as a portfolio, not a single option. Match module type (factory-integrated pod, containerized unit, or hybrid) to deployment velocity, density, and regulatory profile; use our deployment archetypes to select the right mix for near-term and scalable needs.
- Embed regulatory scenarios into capital approval gates. Require procurement bids to include alternative financing models for utility upgrades (e.g., customer-funded grid upgrades, utility deferral schemes) and to price regulatory pass-through risk explicitly.
- Prioritize liquid-cooling due diligence. For AI and HPC workloads, cooling architecture is a multi-year service agreement and interoperability challenge — require factory acceptance testing and field-replication validation as contract milestones.
- Accelerate partnerships with suppliers that offer integrated warrantees and spare-part support. Shorter lead times matter more than marginal capex savings when time-to-market is the strategic objective.
- Use our procurement scorecards and TCO templates. They standardize vendor comparisons across speed-to-deploy, energy performance, lifecycle service, and grid-impact allocations — transforming vendor selection from anecdotes to quantified tradeoffs.
How boards and procurement teams should use this report in 2026
- Run the report’s scenario suite during capital planning cycles to quantify upside and downside of different deployment cadences.
- Use the supplier scorecards in RFPs to accelerate objective vetting and to tighten performance SLAs tied to commissioning milestones.
- Leverage the regulatory playbooks to brief internal stakeholders and external partners (utilities, local government) before permit submissions.
- Deploy the TCO templates in vendor negotiations to ensure energy and grid-upgrade risks are contractually assigned and quantified.
Conclusion — what to expect and how PW Consulting can accelerate your 2026 agenda
Prefabricated and modular data centers are transitioning from a tactical gap-filler to a strategic capability that shapes time-to-market, operating economics, and regulatory exposure. With a 2026 operating environment marked by higher energy costs, new regulatory obligations, and intensifying demand for AI-scale density, organizations that formalize modular strategies and tighten procurement rigor will materially outperform peers.
PW Consulting’s full market study provides the detailed segmentation, supplier models, and quantitative scenario outputs required for executable 2026 strategies. This brief outlines the strategic contours and immediate priorities — the full report contains the granular tables, region- and application-level scenarios, and supplier benchmarking that boards and operators will use to finalize commitments. For the complete data, segment analytics, and downloadable toolkits, please consult the full report page.
For detailed analysis of this topic, please visit the official page: Prefabricated And Modular Data Centers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Workday HCM Consulting Market to Reach USD 6,156 Million by 2032, Growing at an 8.85% CAGR
By PW Consulting, 2026-07-13

PW Consulting Strategic Brief: Workday Human Capital Management (HCM) Consulting Services Market — A 2026 Playbook
As organizations accelerate digital HR transformations, Workday HCM advisory and delivery ecosystems are shifting from point implementations to multi‑phase, AI‑infused services portfolios. PW Consulting’s latest market research — anchored on a 2025 base year, historical analysis from 2020–2025, and a 2026–2032 forecast horizon — frames those shifts and translates them into actionable decision criteria for enterprise leaders, CIOs, CHROs, and procurement teams planning their 2026 investment and partner strategies.
Workday Human Capital Management Consulting Service Market
Market snapshot: growth trajectory and competitive structure
Key market metrics set the stage for near‑term capital allocation. The Workday HCM consulting services market expanded from roughly USD 2.88 billion in 2023 to about USD 3.4 billion in 2025, and is projected to reach approximately USD 3.7 billion in 2026. Underlying demand drivers and recurring revenue models position the market for continued expansion, with a forecast compound annual growth rate (CAGR) of 8.85% across the 2026–2032 period — approaching an estimated market size north of USD 6.1 billion by 2032.
Workday Human Capital Management Consulting Service Market
Concentration metrics indicate a market that combines scale advantages with meaningful space for specialist firms: the top three providers account for roughly one‑third of the market (CR3 ≈ 32.5%), and the top five approach mid‑forties (CR5 ≈ 44.8%). That structure favors both large systems integrators (who bring scale, global delivery and finance transformation capability) and specialized boutiques (which differentiate on vertical depth, managed services and rapid optimization).
Workday Human Capital Management Consulting Service Market
What this report delivers (practical, procurement‑ready content)
- Buyer decision framework: A pragmatic, stage‑based diagnostic spanning strategy, selection, implementation, and long‑term managed services — including procurement levers and contracting templates tailored for 2026 market dynamics.
- Implementation playbooks: Role‑based runbooks for Program Directors, HR Operations, Payroll leads and IT Release Managers that align Workday release cadence, testing regimes and AI feature flags with business risk tolerances.
- TCO and ROI modeling: Scenario calculators that incorporate licensing, implementation, internal change costs, and multi‑year managed services to quantify payback across alternative delivery models.
- AI readiness & governance toolkit: A compliance‑centric checklist and risk assessment aligning Workday AI features (e.g., recruiting recommendations, skills mapping) with EU and US regulatory developments.
- Skills & workforce planning module: A demand forecast for Workday‑specialized talent, role profiles, and a provider sourcing matrix (insourcing vs managed services) to balance cost, resilience and speed.
- Vendor scorecards and selection criteria: A repeatable vendor evaluation model covering technical capabilities, vertical experience, delivery velocities, IP assets (accelerators, integrations), commercial flexibility and post‑go‑live support.
- Case studies and contract clauses: Redacted, anonymized deployments demonstrating measurable HR and finance KPIs, plus recommended contractual language for data privacy, regulatory change and AI liability allocation.
Note: To preserve the advisory value of the publication as a strategic product, detailed segmentation tables (regional, service type, enterprise size splits), vendor scoring matrices and raw financial worksheets are not reproduced in this brief. They are available in full to report subscribers and corporate clients.
Competitive landscape — who matters and why
The 2026 Workday HCM consulting services ecosystem is defined by tiered players with distinct go‑to‑market positions. Our analysis profiles core firms that influence procurement outcomes and partner economics:
- Deloitte Consulting LLP (New York, USA): Longstanding Workday partner with broad HCM and Finance capabilities. Strengths include end‑to‑end transformation programs, global delivery footprint and industry regulatory advisory.
- Accenture (Dublin, Ireland): Deep systems integration muscle for large enterprises; notable for program management at scale, cloud transformation roadmaps and integration into enterprise data estates.
- KPMG (Amstelveen, Netherlands): Combines audit and risk credentials with Workday implementation services — a valuable proposition where governance, compliance and financial reporting are priority decision drivers.
- PwC (London, UK): Advisory and change management strength, with documented case experience bridging HCM and Financial Management deployments across complex global organizations.
- OneSource Virtual (Dallas, USA): Specialist provider focused on managed and optimization services; compelling for organizations prioritizing payroll and BPO continuity.
- Alight Solutions (Lincolnshire, USA): Noted for benefits administration and carve‑out migrations tied to Workday HCM projects.
- Cognizant (Teaneck, USA): Scale player with a global delivery backbone and a suite of accelerators following strategic acquisitions.
- Huron Consulting Group (Chicago, USA): Differentiates in higher education and healthcare verticals with tailored Workday offerings.
- Slalom (Seattle, USA): Market of choice for organizations seeking a consultative, local delivery model with strong advisory and optimization services across many markets.
- IBM Consulting (Armonk, USA) & Capgemini (Paris, France): Both bring extensive enterprise transformation experience and systems integration portfolios that appeal to global, matrixed organizations.
- Surety Systems (Charlotte, USA): A seasoned Workday advisory partner oriented to mid‑market and complex integration work with a decade+ domain focus.
Competitive dynamics are evolving: global SIs continue to extend commercial flexibility and platform integrations, while specialists are winning on speed, verticalization and managed services economics. Buyers should evaluate suppliers against four dimensions: speed to value, IP/accelerators, regulatory and privacy competency, and post‑go‑live continuity.
Regulatory and market dynamics shaping 2026 decisions
- Privacy and cross‑border data flows: Workday’s certifications to frameworks covering EU‑US, UK and Swiss data transfers (as of April 2026) mitigate some cross‑border risk, but organizations must still align contracts and technical controls to local laws.
- State‑level privacy regimes in the US: By January 1, 2026, multiple US states have enacted comprehensive privacy laws that materially affect HR data handling and vendor due diligence — impacting contract terms, data mapping and incident response obligations.
- AI regulation: The EU AI Act’s classification of employment‑related AI as high‑risk imposes transparency, documentation and risk‑management requirements for features used in recruitment, performance management and redeployment planning.
- Talent and labor cost pressures: Demand for specialized Workday HCM consultants (release managers, integration engineers, payroll experts, and AI ops roles) remains elevated, pushing firms toward nearshoring and managed services to stabilize costs and capacity.
Implications and strategic recommendations for 2026
For executives planning investments in 2026, PW Consulting emphasizes five priority actions:
- Embed regulatory and AI governance into vendor selection: Make regulatory proofs (data transfer certifications, AI transparency artifacts) pass/fail criteria in RFPs and require preserved audit trails for AI models used in HCM workflows.
- Define phased ROI milestones: Break multi‑year programs into discrete value increments (core HR, payroll stabilization, workforce planning, AI augmentation) to manage risk and unlock incremental funding.
- Choose delivery models aligned to capability gaps: Where internal Workday expertise is scarce, prioritize managed services or outcome‑based contracts to reduce operational risk; where IP transfer is strategic, emphasize knowledge transfer and joint delivery models.
- Plan for skills continuity and vendor concentration risk: Use blended sourcing (primary integrator + niche specialists) to avoid single‑vendor lock and to retain competitive tension during optimization phases.
- Test AI features in controlled pilots: Apply a staged rollout for recruiter/skills tools with performance/wrongful‑impact KPIs and human review gates to meet EU and US regulatory expectations.
How PW Consulting supports executive decisions
Our report is purpose‑built as an executive decision pack: it pairs market forecasts and concentration analytics with procurement‑ready templates, selection scorecards and operational playbooks. We combine quantitative market sizing and growth trajectories with qualitative supplier due diligence and practical mitigation controls for regulation, talent and cost pressure.
This release serves as a high‑signal briefing. For procurement teams preparing RFPs, transformation leads building program roadmaps, and boards seeking to understand regulatory exposures — the full Workday Human Capital Management Consulting Service Market report contains the supporting data tables, vendor scoring, redacted case financials and step‑by‑step contracting language that turn strategy into executable commitments.
Next steps
- Download the complete report or request a tailored briefing to obtain the full segmentation data, vendor scorecards and downloadable TCO models.
- Engage PW Consulting for a complimentary 90‑minute advisory session to map your Workday HCM roadmap to the 2026 regulatory landscape and our three‑year readiness plan.
PW Consulting — translating market intelligence into procurement and execution advantage. Contact our enterprise research team to schedule your briefing and receive the full report and annexes for board and procurement use.
For detailed analysis of this topic, please visit the official page: Workday Human Capital Management Consulting Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Special Airport Systems Market to Expand at a 6.5% CAGR
By PW Consulting, 2026-07-13

Special Airport Systems Market — Strategic Briefing for 2026 Decisions
Executive summary
PW Consulting’s Special Airport Systems Market Special Report synthesizes the strategic intelligence that airport operators, system integrators, equipment manufacturers and investors need to navigate 2026 and beyond. Built on a 2025 base year and a historical analysis spanning 2020–2025, the study forecasts market trajectories across 2026–2032 and demonstrates that the overall market is on a steady expansion path — growing at a compound annual growth rate (CAGR) of 6.5% and moving from an estimated USD 12.5 Billion in 2025 toward roughly USD 19.4 Billion by 2032. This growth is driven by converging forces: capacity upgrades to support post‑pandemic travel recovery, regulatory modernization around baggage and security handling, investments in resilience and sustainability, and accelerating digitalization of passenger and ground operations.
Special Airport Systems Market
Why this report matters for 2026 strategy
- Decision timing: 2026 is a hinge year. New ICAO and IATA standards and national runway safety programs introduced in late 2025–early 2026 create compliance deadlines and procurement windows that will affect capital planning, vendor selection and staged deployments.
- Budget prioritization: With market expansion predictable at a mid-single-digit CAGR, organizations must rebalance CAPEX toward systems that deliver operational throughput and automation while controlling lifecycle OPEX — a theme we quantify and model in the report.
- Vendor negotiation leverage: Our analysis maps vendor strengths, capability gaps and recent contract flows so buyers can calibrate procurement levers, adoption phasing and risk allocation in 2026 RFPs.
Macro outlook and market trajectory
The market entered the 2026 planning cycle from a position of normalized recovery: base-year analysis and historical performance (2020–2025) show steady rebuilding of passenger volumes and system replacement cycles. Applying a 6.5% CAGR across the forecast period (2026–2032) implies a near-term expansion that is large enough to support multiple investment waves — from immediate compliance upgrades to multi-year terminal modernizations. For executives, the arithmetic is straightforward: the market scale enables both incremental, tactical refresh programs and larger transformational projects; the strategic question is which mix yields the fastest capacity and ROI improvements while future-proofing against regulatory and technology shifts.
Special Airport Systems Market
Report contents — operationally focused and transactionable
Beyond market sizing and forecasts, the report is designed to be directly actionable for procurement teams, program managers and corporate strategists. Key deliverables include:
Special Airport Systems Market
- Scenario-driven demand models that translate passenger throughput assumptions into system capacity requirements and staging timelines.
- Technology readiness and interoperability matrices covering baggage handling, hold‑baggage screening, passenger processing, airfield lighting and navigation aids — with integration risk scoring for each pairing.
- Procurement playbooks: sample RFP language, commercial term templates, acceptance test criteria and performance SLAs tailored for different airport categories and project scopes.
- Vendor scorecards and shortlists constructed for specific procurement archetypes (greenfield terminal, refurbishment, security-centric upgrades), enabling rapid selection and negotiation.
- CAPEX/OPEX benchmarking tools and lifecycle TCO templates to assess trade-offs between automation intensity and staffing costs over 7–10 year horizons.
- Implementation roadmaps with phased milestones to reduce operational disruption during cutover and to align with regulatory compliance deadlines.
Competitive landscape — who matters and why
The competitive field blends large systems integrators and specialist suppliers. Our report profiles leading firms and evaluates them across technology breadth, integration depth, service footprint and recent commercial momentum.
- Honeywell International Inc. — With a diversified portfolio spanning security screening, building management and ground handling technologies, Honeywell is positioned to offer cross-domain solutions that combine operational efficiency with safety. Their strength lies in integrated building controls and long-standing client relationships in major hub airports.
- Thales Group — A comprehensive systems supplier for air traffic management, security, baggage integration and navigation aids. Thales competes on end‑to‑end orchestration and proven deployments in large, complex airports where system interoperability is critical.
- Vanderlande Industries — A specialist in automated baggage handling systems, Vanderlande’s engineering depth and high‑capacity solutions make it a frequent choice for projects prioritizing throughput and modular expansion.
- SITA — As a leader in airport IT and communications, SITA’s passenger processing and baggage management platforms are central to digital transformation programs that aim to unify disparate operational systems under a common data layer.
- Leidos — Focused on security enterprise solutions and screening systems, Leidos has increased its market presence through partnerships and joint ventures that expand its portfolio into integrated security and critical infrastructure programs.
- RTX (Raytheon Technologies) — Supplies navigation, surveillance and ground handling technologies; strong where airfield infrastructure modernization and avionics-level integration are required.
- Daifuku Co., Ltd. — Another key player in automated baggage and material handling systems with deep experience in efficient terminal logistics and modular installations.
- Amadeus IT Group — Provides passenger processing, departure control and airport IT platforms that often form the backbone of digital passenger journeys and real-time resource optimization.
- Siemens AG — An important supplier of integrated building and infrastructure systems, including energy management and airport automation. Siemens appeals to operators with strong sustainability and resilience agendas.
- Indra Sistemas, IDOM, Deerns, Leonardo, ADB SAFEGATE — These suppliers collectively offer specialized capabilities in air traffic management, engineering design, BHS technologies and airfield lighting. Their strength lies in niche expertise, regional project execution and targeted innovation.
Competitor dynamics are active: the report tracks recent contract awards and strategic partnerships. In early‑to‑mid 2026, multiple suppliers secured projects for baggage screening and handling system upgrades across Europe and North America, and several firms announced collaborative ventures to accelerate integrated security offerings. These developments signal that procurement cycles are accelerating and that suppliers who can demonstrate plug‑and‑play interoperability and proven lifecycle service models will have an advantage in 2026 bid processes.
Regulatory and industry drivers shaping 2026 decisions
- IATA standards refresh: The 2026 editions of key manuals (including handling and baggage reference materials) introduced nearly 100 changes affecting baggage handling and passenger support. These changes establish new baseline requirements for operations and technology — creating immediate compliance and capability implications.
- ICAO security evolution: Amendment updates expanding One‑Stop Security concepts for hold baggage raise expectations for end‑to‑end screening models and create impetus for harmonized cross‑border processes.
- Runway safety initiatives: National programs to install enhanced incursion detection technologies at major airports create an adjacent market for airfield safety systems and integration services within 2026 deployment windows.
- Long‑term demand trends: IATA passenger projections pointing to substantial growth over the next decade underscore why capacity planning and scalable automation must be central to decision frameworks.
Strategic implications and recommended actions for 2026
For airport CIOs, COOs and procurement leads, 2026 requires a balance between compliance, capacity and digital transformation. Our top recommendations:
- Prioritize interoperability in procurement: Insist on modular, standards‑based interfaces in RFPs to reduce vendor lock‑in and support phased rollouts that align with terminal availability windows.
- Adopt phased modernization: Combine tactical upgrades (screening, targeted conveyor modernizations) with a medium‑term program to implement platform‑level IT modernization; this reduces disruption while enabling data‑driven operations.
- Use vendor scorecards: Deploy the report’s scorecard framework to weight technical fit, operational service, financial terms and technology roadmaps — ensuring objective trade‑off analysis during negotiations.
- Hedge on technology: Invest selectively in automation and AI that demonstrably reduce dwell time and error rates, while keeping fallback manual processes certificated under updated regulatory guidance.
- Plan for sustainability and resilience: Integrate energy management and redundancy planning early in system design to realize long‑term OPEX savings and compliance with emerging ESG requirements.
What’s inside the full report (sample deliverables)
- Detailed forecast tables and sensitivity scenarios (2026–2032) by system family and procurement archetype.
- Vendor benchmarking dossier with technology, service and commercial strengths mapped against use cases.
- Implementation playbooks and test/acceptance templates.
- Regulatory gap analysis and compliance roadmaps aligned to IATA/ICAO updates.
- Executive dashboards designed for CAPEX committee presentations and board approval packages.
Next steps — where to get the full intelligence
This briefing outlines why the 2026 planning horizon is decisive and how organizations can translate market expansion and regulatory shifts into pragmatic procurement and modernization programs. For access to the complete datasets, vendor scorecards, and procurement templates — including downloadable Excel models and workshop materials designed for immediate adoption — please visit the report landing page. The full report contains the granular segmentation data, regional and system‑type breakdowns, and contract‑level case studies that organizations will use to finalize 2026 budgets and RFPs.
About PW Consulting
PW Consulting is a strategic advisory firm specializing in infrastructure systems and technology transformation. Our Special Airport Systems Market Special Report combines market modeling, hands‑on procurement tools and vendor intelligence to help clients convert market insight into executable programs and measurable outcomes.
For detailed analysis of this topic, please visit the official page: Special Airport Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


