



Category: IT & Electronics
PW Consulting: Construction Estimating Software Market to hit USD 3,673.54M by 2032 at 11% CAGR
By PW Consulting, 2026-07-09
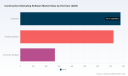
Construction Estimating Software Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As construction organizations move from tactical digitization to strategic process transformation, the construction estimating software market has shifted from a niche toolset into a critical node of preconstruction, procurement, and risk management. Our market model — calibrated to a 2025 base year — shows the market expanding from roughly USD 1.12 billion in 2020 to about USD 1.77 billion in 2025, and forecasted to exceed USD 3.67 billion by 2032, tracking at a compound annual growth rate of approximately 11% through the forecast horizon. Market concentration remains moderate: the top three and top five vendors account for materially smaller-than-monopolistic shares, underscoring both vendor strength and continued opportunity for differentiation.
Construction Estimating Software Market
Why this matters for 2026 strategy
-
Preconstruction is now profit center and risk center: estimating accuracy and speed directly influence margin preservation in the face of tight labor markets and material price volatility. Investments in modern estimating platforms pay not only through faster bid cycles but by reducing contract disputes and change orders.
Construction Estimating Software Market -
Cloud-first workflows and integrated data pipelines are the default for collaboration across distributed teams. Organizations that delay migration face hidden costs in coordination, auditability, and scalability.
Construction Estimating Software Market -
AI and automation are moving from pilot to production. Practical AI capabilities — automated symbol recognition, bulk item counting, and assembly generation — are reducing manual effort in repeatable projects and unlocking new bidding strategies for specialized contractors.
Report utility — what PW Consulting delivers
This research is deliberately practitioner-focused. It combines a top-down market model with granular, operational deliverables designed to support board-level and field-level decisions in 2026:
-
Actionable market sizing and trend narratives calibrated to our 2025 base year and a 2026–2032 forecast, suitable for financial planning and capex prioritization.
-
Adoption playbooks by customer archetype (general contractors, specialty trades, design-build teams) highlighting purchase triggers, procurement cycles, and integration blockers.
-
Vendor evaluation templates and a reproducible scoring rubric (security, integration, data quality, configurability, TCO), enabling internal procurement to run vendor qualification with predictable outcomes.
-
TCO and ROI models with sensitivity scenarios for labor rates, project throughput, and license/hosting options — these models are delivered in a format you can re-run with your own assumptions.
-
Implementation checklists and change-management playbooks that reduce time-to-value and mitigate common rollout failures.
-
Scenario planning modules that map technology investment choices to P&L and balance-sheet outcomes under different market conditions.
We intentionally withhold raw segment-level revenue tables in this preview — the full dataset and vendor scorecards are available in the complete report and accompanying data package.
Competitive landscape — who matters and why
The vendor ecosystem includes long-standing incumbents, construction software platforms branching into estimating, and fast-moving niche innovators. Each set brings distinct strengths for enterprise buyers and buyers operating at scale.
-
Bluebeam (US) — Known for Revu takeoff and mark-up workflows. Strength lies in digital plan review, collaborative RFI/workshare capabilities, and accuracy-centric drafting tools that appeal to teams emphasizing bid precision.
-
Sage (UK) — With Sage Estimating, the company targets database-driven estimating and multi-estimator collaboration. Its value proposition is depth in historical cost libraries and workflows oriented toward complex institutional bids.
-
Trimble (US) — Offers Accubid and AutoBid solutions favored by mechanical/electrical specialty contractors. Trimble’s advantage is its pre-populated databases, change-management hooks, and discipline-specific cost models.
-
PlanSwift (US) — Aimed at general contractors with rapid takeoff and emerging AI-assisted add-ons. PlanSwift competes on speed, ease-of-use, and low-friction adoption.
-
ConstructConnect (US) — Delivers integrated takeoff and estimating with a workflow focus on proposal readiness and bid-to-award management, appealing to contractors needing end-to-end preconstruction continuity.
-
Autodesk (US) — Through ProEst/Forma and BIM integrations, Autodesk’s differentiator is deep integration with design workflows and BIM data lineage, enabling model-based estimating at scale.
-
UDA Technologies (US) — ConstructionOnline provides an integrated platform that ties estimating to job costing and project management; recent product releases are sharpening its bid-tracking and package orchestration.
-
Procore (US) — Procore Estimating emphasizes seamless data flow from takeoff to proposal and into project execution, targeting organizations seeking a unified construction management stack.
-
OnCenter Software (US) — Focuses on digital takeoff workflows that feed into estimating operations, with emphasis on assemblies and integration.
-
Buildxact (US) — Positioned around residential and light-commercial workflows, leveraging AI assistants for rapid estimate generation and review.
-
STACK (US) — Cloud-native takeoff and estimating with AI-driven symbol recognition and ERP integration capabilities aimed at faster plan counting and tighter downstream handoffs.
Recent vendor activity in 2026 underscores these dynamics: UDA added a centralized bid tracking module; Buildxact launched a more sophisticated AI assistant for assembly and estimate review; and Procore enhanced direct takeoff data flow and plan overlay capabilities to tighten preconstruction accuracy. These moves reflect two concurrent trends — vendors extending horizontally into bid orchestration, and AI being embedded into core estimating workflows.
Market dynamics, risk and adoption inhibitors
-
Security and compliance are now purchase criteria, not optional features. Enterprise buyers increasingly require SOC 2 controls, encryption, and auditable trails for bid data as a condition of procurement. SaaS providers face escalating operational costs to maintain these controls and to comply with privacy regimes — a material item for vendor roadmaps and pricing strategies.
-
Labor and productivity: AI-enabled automation is delivering step-change productivity for repeatable tasks — field reports show dramatic reductions in manual takeoff time for standardized residential plans. However, gains are uneven across project types; buyers must pilot automation in representative workflows before rolling out broadly.
-
Data quality and integration: The value of estimating software compounds when it links to ERP, procurement, and project controls. Integration complexity — disparate cost databases, legacy ERPs, and inconsistent SKU systems — remains the most common barrier to realizing full ROI.
-
Commercial models and vendor lock-in: Subscription models, consumption-based pricing, and data egress provisions should be scrutinized. Our vendor scoring framework quantifies these commercial risks so buyers can structure contracts that protect future mobility and minimize supplier dependencies.
Practical recommendations for 2026
-
Start with targeted pilots: Validate AI and takeoff accelerators on two to three representative jobs (one repeatable residential, one complex commercial) and measure cycle-time and error-rate delta before full roll-out.
-
Prioritize integration over feature lists: Ensure your chosen platform can export normalized cost data into accounting and procurement systems with minimal manual reconciliation.
-
Embed security and auditability in procurement: Require SOC 2 attestation, clear data ownership, and defined egress terms — these are negotiable and materially affect long-term costs.
-
Leverage vendor scorecards: Use a weighted scoring approach that balances technical fit, implementation risk, and commercial terms rather than picking vendors solely on feature breadth.
-
Plan for continuous improvement: Estimating accuracy improves with feedback loops. Instrument bid outcomes and change-order drivers so models can be tuned and vendor databases enriched over time.
Next steps — how PW Consulting helps
Our full Construction Estimating Software Market report contains the complete dataset, vendor scorecards, downloadable financial models, and step-by-step implementation playbooks referenced above. It also provides proprietary segment-level revenue breakdowns, customer adoption curves, and a ranked vendor heatmap that are omitted from this preview to preserve actionable exclusivity.
If you are evaluating platform choices, preparing an M&A thesis, or building a 3–5 year technology roadmap, our team can run a focused workshop that leverages the report’s models against your corporate KPIs and delivers a tailored recommendation and sourcing shortlist.
Closing
The next 18 months will separate organizations that treat estimating modernization as tactical from those that use it as a strategic lever. With the market growing at a double-digit CAGR and vendor activity accelerating around AI and integrated bidding workflows, 2026 is a pivotal year to convert pilot success into enterprise advantage.
For detailed analysis of this topic, please visit the official page: Construction Estimating Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
InGaAs Image Sensors Market: Strategic Imperatives for 2026 — A Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive preview of our new market study on InGaAs (Indium Gallium Arsenide) image sensors. The study synthesizes five years of historical market activity (2020–2025) and projects the industry’s trajectory across 2026–2032. Our core conclusion for 2026 decision-makers is straightforward: this is a maturing yet strategically fluid market — growing at a steady compound annual growth rate (CAGR) of 7.1% — where technology choices, supply-chain posture, and targeted commercial plays made this year will determine market share and margin performance through the decade.
InGaAs Image Sensors Market
Why 2026 is a Pivotal Year
-
Market momentum: The InGaAs image sensor market has expanded from a modest base in 2020 to a materially larger industry by 2025, and our base-year analysis indicates continued growth through 2032. The market value transitions observed in the data show the industry moving from niche, application-driven deployments toward broader industrial and commercial adoption.
InGaAs Image Sensors Market -
Technology inflection points: Advances in hybridized ROIC bonding, improved room-temperature operation, and expanded spectral coverage up to ~2.6 µm are unlocking new use cases — from high-throughput industrial inspection to biomedical spectroscopy. Vendors that translate these technical gains into reliable, application-ready modules will capture disproportionate value.
InGaAs Image Sensors Market -
Supply-side constraints and regulation: The industry is exposed to raw-material concentration (indium/gallium), specialized foundry capacity, and an evolving regulatory landscape that already has translated into trade actions and tariff-related refund claims. These factors elevate the strategic importance of sourcing, onshoring / friend-shoring, and contractual protections.
Data-driven context (high level)
Our modeling uses 2025 as the base year and projects through 2032 under multiple scenarios. The baseline trajectory reflects a compound growth profile of approximately 7.1% CAGR across the forecast window. This growth is driven by both incremental adoption in established domains (defense, industrial inspection, surveillance) and emergent commercial opportunities enabled by improved detector performance and integration (e.g., visible+SWIR sensors for sorting, semiconductor inspection, and process control).
We intentionally withhold detailed subsegment revenues and regional splits in this preview, but the full analysis correlates growth vectors with product form factors (linear vs. area arrays), application verticals, and geographic demand patterns — producing a practical roadmap for resource allocation and go‑to‑market sequencing.
What the Full Report Delivers (practical, transaction-ready content)
-
Commercial playbooks: Decision trees for OEMs, camera integrators, and component suppliers that translate technology differentiation into go‑to‑market priorities (pricing, channel, and aftermarket strategies) tailored to both high-value defense contracts and volume industrial deployments.
-
Supply-chain and sourcing playbook: Detailed supplier mapping (foundries, epitaxial houses, and packaging/ROIC partners), near-term risk scenarios for critical raw materials, tactical hedges, and suggested contract language to mitigate tariff and geopolitical risk exposure.
-
Technology and product roadmaps: Comparative benchmarking of linear vs. area arrays, cooled vs. room-temperature architectures, and visible+SWIR integration. We show which capability investments move the needle commercially and which are likely to remain premium, low-volume differentiators.
-
Commercial modeling templates: Unit economics, ASP sensitivity to material and manufacturing cost swings, and ROI calculators for camera makers and systems integrators considering vertical integration or strategic partnerships.
-
M&A and partnership playbook: Identification criteria, valuation heuristics, and diligence checklists for bolt-on acquisitions (foundry, ROIC designer, optics house) that accelerate time-to-market or secure critical capacity.
-
Regulatory and compliance assessment: Practical steps to manage tariff exposure, export controls, and sector-specific certification pathways relevant for defense, medical, and industrial customers.
Competitive Landscape — Who Matters and Why
The InGaAs sensor ecosystem combines legacy optics and component specialists with newer entrants that leverage integration and volume-scale semiconductor know-how. The market is best characterized as fragmented at the top, with a handful of capable suppliers and many niche specialists. Our report includes forensic vendor profiles, product-level comparisons, and alliance maps. Below are concise strategic profiles of the principal players we monitor:
-
Hamamatsu Photonics K.K. (Japan) — Strengths: deep photonics expertise and a broad catalog of VIS–NIR–SWIR linear and area sensors with integrated CMOS ICs. Strategic posture: product breadth and customization for spectrometry and lab/industrial instruments. Recent activity: launched a high-speed linear series for foreign-object detection, signaling continued focus on inspection applications.
-
Teledyne Technologies Inc. (USA) — Strengths: wide-ranging detector portfolio including room-temperature and TE-cooled arrays (extended cutoffs), with proven performance in spectroscopy, biomedical, and aerospace applications. Strategic posture: serving high‑reliability and mission-critical markets where certification and thermal performance matter.
-
Sensors Unlimited (RTX Collins Aerospace / Raytheon, USA) — Strengths: defense-grade SWIR focal plane arrays and camera systems with long-standing adoption by military and surveillance integrators. Strategic posture: leveraging defense relationships and systems-level integration capabilities.
-
Exosens / Xenics (Belgium) — Strengths: designer/manufacturer of SWIR detectors and cameras, with a focus on hybridized ROIC photodiode arrays for line-scan and area-scan solutions. Strategic posture: customization and integration for industrial OEMs demanding line-scan performance.
-
New Imaging Technologies (NIT / LYNRED, France) — Strengths: SWIR sensors and cameras from line-scan to Full HD targeted at industrial inspection, security, and scientific markets. Strategic posture: rapid product updates for high-speed inspection; recent launches of new line-scan sensors and updated industrial camera assemblies reinforce their industrial market focus.
-
Sony Semiconductor Solutions (Japan) — Strengths: high-resolution SenSWIR™ devices with visible+SWIR coverage using advanced bonding techniques. Strategic posture: applying consumer-scale semiconductor expertise to raise resolution and integration for industrial and semiconductor-inspection use cases.
Collectively, the top suppliers do not dominate the market to the extent seen in some semiconductor sectors — the three- and five-firm concentration ratios indicate a market that remains relatively accessible to specialized challengers and system integrators willing to invest in differentiation. For many buyers, supplier selection is less about the single-best sensor and more about the supplier’s systems engineering, supply continuity, and certification processes.
Key Dynamics Shaping Strategic Choices
-
Raw-material and manufacturing economics: Epitaxial InGaAs growth and hybridized ROIC assembly require specialized facilities and high-purity materials, creating structural cost differentials vs. silicon CMOS. Buyers and investors must factor higher baseline CAPEX and longer lead times when evaluating vendor roadmaps.
-
Geopolitical and tariff exposure: Recent tariff actions under export-control frameworks have already forced manufacturers and customers to address refund claims and contractual exposure. For procurement teams, scenario planning for tariff shifts and logistics disruptions is now a basic requirement.
-
Integration and certification: Several vendors now offer room-temperature detectors with extended spectral responsiveness, making SWIR adoption simpler for many system integrators. The certification path (especially for defense and medical customers) remains a differentiator — not all suppliers can deliver the required documentation and lifecycle support.
-
Vertical integration and partnerships: Because yields and performance hinge on integrated cleanroom processes, strategic partnerships with foundries, ROIC designers, and packaging specialists materially reduce execution risk. Our report maps the viable partner ecosystems and evaluates trade-offs between captive vertical integration and outsourced specialization.
Implications for 2026 Strategy — Actionable Priorities
-
Establish resilient sourcing: Lock in multi-year supply agreements, qualify alternate epitaxial and packaging partners, and build tariff mitigation clauses into contracts.
-
Prioritize system-level differentiation: Focus R&D on integration challenges (optics, electronics, cooling) that turn detector performance into measurable end‑user value, not incremental pixels alone.
-
Segment go-to-market: Separate high-reliability defense/space pursuits from industrial volume plays; tailor certification and warranty offerings accordingly.
-
Prepare M&A and partnership options: Identify anchor acquisitions or JV partners that secure capacity or accelerate time-to-market for key modules (ROIC, cryogenics, optics).
Closing — Where to Go Next
This preview is designed to guide C-suite and business-unit leaders through the strategic choices that matter in 2026. The full PW Consulting InGaAs Image Sensors Market report delivers the proprietary subsegment models, region- and application-level revenue analytics, supplier scorecards, and executable templates that translate the high-level insights above into concrete actions. For teams evaluating sourcing, product investments, or M&A in 2026, the complete dataset and playbooks are essential to reduce execution risk and capture the upside presented by the sector’s steady growth trajectory.
Contact PW Consulting to access the full report and supporting decision tools — including the segmentation datasets and vendor diligence materials that are intentionally excluded from this preview to preserve the study’s commercial value.
For detailed analysis of this topic, please visit the official page: InGaAs Image Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wind LiDAR market set to surge to USD 1.16B by 2032 at 9.3% CAGR
By PW Consulting, 2026-07-09
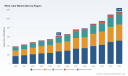
Wind LiDAR Market 2026: Strategic Preview for Executive Decision-Making
Executive snapshot
PW Consulting’s forthcoming Wind LiDAR Market study synthesizes seven years of market dynamics (2020–2025 historical baseline), and delivers an actionable forecast across 2026–2032. The global market has expanded rapidly—from roughly USD 390 million in 2020 to an estimated USD 623 million in the 2025 base year—and is projected to continue on a robust trajectory at a compound annual growth rate of 9.3%. By 2032 our model points to a market in excess of USD 1.1 billion. For corporate strategists, asset owners, turbine OEMs, and technology investors planning 2026 allocations, these headline metrics frame a market that is both scaling and fragmenting in ways that affect procurement, certification, and deployment strategies.
Wind Lidar Market
Why this report matters for 2026 decisions
- Capital allocation with confidence: The sector’s sustained CAGR and predictable near-term ramp provide a quantitative basis for re-prioritizing capex and partnerships across onshore and offshore portfolios.
- Bankability and risk reduction: As LiDAR-derived measurements move deeper into project underwriting and power performance verification, knowing how device-class validation, IEC and certification updates, and service models affect AEP uncertainty is essential.
- Procurement and supplier selection: The market is not winner-takes-all—leading vendors coexist with regional specialists and volume producers. Our report equips procurement teams with scorecards, bid-ready templates, and TCO scenarios tuned to 2026 pricing and service norms.
- Technology roadmap alignment: Advances in nacelle-mounted systems, pulsed scanning LiDARs, and floating LiDAR standards create near-term R&D and integration priorities for OEMs and sensor companies.
Market dynamics shaping 2026 strategy
The market’s growth is driven by converging forces: a maturing utility-scale wind sector that demands lower AEP uncertainty; accelerating offshore deployment where logistic complexity favors remote sensing; and the proliferation of nacelle-mounted systems for performance monitoring. Key regulatory and standards developments in 2024–2025 have compressed the timeline for device validation and acceptance in bankable assessments. In particular, the publication of an IEC technical specification for floating LiDAR systems in 2025 and continuing harmonization efforts between IEC and IEA task groups materially change how offshore projects are scoped and underwritten.
Wind Lidar Market
- Standards and bankability: IEC updates and third-party certifications (DNV, WindGuard and others) are establishing clearer acceptance pathways for LiDAR-derived evidence in AEP calculations and power curve verification. These rules are shifting procurement from cost-first to compliance-first.
- Product maturity and productization: The latest generation of ground-based, nacelle-mounted and scanning LiDARs emphasizes range, repeatability, and lower maintenance. Recent launches and product refreshes demonstrate vendors’ bet on verification performance (e.g., wider range classification and IEC-grade claims).
- Service-layer differentiation: Vendors and data service providers are bundling sensor hardware with analytics, long-term monitoring contracts, and AEP adjustment services. Data-as-a-service offerings are emerging as value-capture paths beyond one-off sensor sales.
- Offshore complexity and floating LiDAR adoption: New technical guidance for floating systems reduces uncertainty for offshore developers and increases the addressable market for purpose-built marine-grade LiDAR systems and integrated deployment services.
Competitive landscape — who to watch
The supplier ecosystem is diverse: established European laser specialists, consolidated meteorological instrument makers, high-volume manufacturers from Asia, and newer entrants offering vertically integrated sensor-plus-data services. Competitive positioning is now a function of technology platform, certification pedigree, channel access to turbine OEMs and developers, and service capabilities.
Wind Lidar Market
- ZX Lidars (Malvern, UK): Noted for continuous-wave and pulsed product lines optimized for onshore, offshore and nacelle applications. Their recent launches have emphasized IEC compliance to 200 m, aiming to neutralize a key underwriting objection. For buyers, ZX’s focus on test-backed performance reduces technical gating risk.
- Vaisala Oyj (Vantaa, Finland): A global incumbent with a broad WindCube family that serves wind energy, aviation and meteorology customers. Vaisala’s strength is validation for bankable deployments and a portfolio that spans nacelle and ground-based systems—making it a default consideration for projects where AEP certainty is mission-critical.
- HALO Photonics / Lumibird (Chepstow, UK): Focused on pulsed Doppler architectures and compact designs for harsh environments. New product introductions signal a push to capture scanning and long-range niches with low-maintenance claim sets attractive to offshore and remote deployments.
- METEK GmbH (Elmshorn, Germany): Delivers profiler-class systems and maintains credibility in turbulence and boundary-layer applications. Their profile suits buyers seeking research-grade performance alongside commercial applications.
- Nanjing Movelaser (Nanjing, China): A high-volume manufacturer with IEC/DNV certifications and strong OEM ties. Their competitive advantage is cost-competitive scale manufacturing combined with increasing certification credentials—particularly relevant for large, price-sensitive rollouts.
- Windar Photonics (Taastrup, Denmark): Specialist in nacelle-mounted solutions with demonstrated penetration on major turbine fleets. Recent capacity expansion and localized manufacturing moves highlight a strategy of scale and service proximity.
Overall, market concentration remains modest: incumbents exert influence through certification and channel access, but a sizable portion of demand is served by a wider set of regional specialists and data service providers. This fragmentation creates acquisition and partnership opportunities for strategic buyers and opens niches for vertical integration.
Practical content and tools inside the report
This study is built for practitioners. Beyond narrative analysis, it delivers hands-on assets that can be deployed directly in 2026 programs:
- Proprietary market model with annualized totals (2020–2025 historical), and a 2026–2032 forecast with scenario toggles for device cost, certification pace, and offshore deployment rates.
- Vendor scorecards assessing technical performance, certification status, warranty and service models, channel reach, and procurement readiness.
- Bankability playbook: decision trees and acceptance checklists aligned to current IEC and third-party certification expectations for both fixed and floating offshore projects.
- Procurement templates and TCO calculators that reflect realistic maintenance, calibration, training, and data processing costs over common contract tenors.
- Use-case migration maps showing how to move from campaign-style assessments to continuous, LiDAR-supported operational monitoring and AEP optimization.
- Risk matrices and mitigation measures covering sensor obsolescence, measurement uncertainty, supply-chain disruptions, and regulatory shifts.
How to apply the findings in 2026
- Investment prioritization: Use our scenario outputs to size R&D and deployment spend that aligns with expected market growth and your competitive positioning—whether you are an OEM, developer, or data services firm.
- Procurement strategy: Adopt the scorecards to structure RFQs and evaluate not just headline price but bankability, integration effort, and lifecycle cost.
- Partnership and M&A scouting: Identify targets that close capability gaps—sensor technology, marine deployment expertise, or analytics service lines—and model integration payback against forecasted demand pathways.
- Regulatory compliance and certification planning: Recalibrate product roadmaps and test programs to align with newly published IEC guidance and prevailing third-party certification expectations.
- Operational transformation: For asset owners, map a multi-year transition from spot LiDAR campaigns to hybrid continuous monitoring models that can unlock AEP gains and reduce performance uncertainty.
What the preview leaves intentionally unshared
To preserve the report’s value as a decision-grade asset, detailed segmentation tables (regional and application-level breakdowns), vendor-specific revenue splits, and the full set of model input assumptions are reserved for the full publication. The preview demonstrates our methodology and headline projections, but granular allocations and client-specific scenario runs are available only through the complete report or bespoke consulting engagements.
Next steps
For teams preparing budgets, procurement plans or M&A targets in 2026, this study provides the market context, tactical instruments and a roadmap for action. To access the full data tables, segmentation analysis, vendor revenue curves, and the interactive model that underpins our forecasts, request the full Wind LiDAR Market report or contact PW Consulting for a tailored briefing and scenario workshop.
For detailed analysis of this topic, please visit the official page: Wind Lidar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: InGaAs Photodiodes & Arrays Market to Grow at 6.98% CAGR Through 2032
By PW Consulting, 2026-07-08
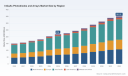
InGaAs Photodiodes and Arrays Market: Strategic Guide for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Consultant and Chief Industry Analyst, I present a focused briefing designed to inform executive decision-making in 2026 for companies operating in, investing into, or supplying the InGaAs photodiodes and detector arrays ecosystem. This note synthesizes the directional market sizing, competitive dynamics, supply-chain risks, and practical actions that should shape strategy over the next investment cycle — while intentionally withholding detailed segment tables and split-level figures to direct stakeholders to the full report for transaction-grade detail.
InGaAs Photodiodes and Arrays Market
Market trajectory you can bank on — but plan around volatility
The InGaAs photodiodes and arrays market has shown steady expansion through the early 2020s and enters the 2026 decision window from a position of durable, mid-single-digit growth. Our base-year assessment (2025) places the market in the low hundreds of millions of USD, reflecting healthy adoption across telecommunications, LiDAR and sensing, spectroscopy, and emerging imaging applications. From 2026 through 2032, we model a compound annual growth rate (CAGR) of approximately 6.98%, producing a material increase in absolute market value by 2032 under our central scenario.
InGaAs Photodiodes and Arrays Market
Two implications follow: first, the market is large enough to justify targeted capacity investments and product-line expansions; second, steady growth masks asymmetric risks from raw-material and geopolitical fluctuations that can produce abrupt supply shocks or price swings. Strategic plans must therefore combine growth capture with resiliency measures.
InGaAs Photodiodes and Arrays Market
What our research includes — how the report will change decisions
- Proven market-sizing methodology with transparent assumptions and a reproducible model that spans historicals (2020–2025) and scenario-based forecasts (2026–2032).
- Demand-driver analysis by application class and buyer archetype, linking technical requirements (bandwidth, noise-equivalent power, wavelength range) to commercial buyer priorities.
- Supply-chain mapping from wafer and III-V epitaxy through die assembly, packaging, and module integration — highlighting single points of failure and potential de-risking levers.
- Technology roadmaps and performance-cost curves for PIN, APD and array form factors, including integration pathways (ROIC, hybrid bonding, hermetic packaging) that influence BOM and time-to-market.
- Competitive landscaping and vendor benchmarking with product-level strengths/weaknesses, go-to-market capabilities, and candidate strategic moves (partnerships, foundry contracts, targeted M&A).
- Regulatory and material-risk assessment focused on critical inputs (notably indium and GaAs supply, impurity controls and export restrictions) and mitigation playbooks.
- Commercial playbooks: pricing strategy, channel design, qualification roadmaps for key end-markets (telecom, LiDAR, spectroscopy, security), and an M&A checklist with valuation sensitivities tied to concentration metrics.
- Scenario-based investment cases and sensitivity analyses to guide capex timing, inventory policy, and contract tenor for sourcing critical materials.
Concentration and competitive dynamics — succinct view
The market exhibits moderate concentration: our headline concentration metrics show that the top three firms capture a meaningful share of the market, and the top five consolidate substantially more. That structure produces a competitive environment where engineering differentiation and supply reliability are key commercial levers. For buyers, it means supplier selection is as much about performance as it is about continuity and contractual protections.
Competitive snapshot — who moves the needle
- Hamamatsu Photonics (Hamakita, Japan) — A long-standing specialist in high-speed InGaAs PIN photodiodes and array products for NIR detection. Their portfolio emphasizes spectroscopy and imaging with variants optimized for integration and system-level compatibility. Strengths: broad product breadth and reliability reputation. Strategic focus: continue differentiating through low-noise, high-uniformity array offerings and system partnerships.
- Teledyne Technologies / Teledyne Judson Technologies (Malvern, PA, USA) — Offers PIN/APD photodiodes and linear/quad arrays with extended wavelength options, targeting space, LiDAR and telco. Strengths: systems-level integration, quality controls for demanding environments. Strategic focus: leverage aerospace heritage to expand into safety-critical industrial sensing.
- OSI Optoelectronics (Hawthorne, CA, USA) — Known for high-speed InGaAs PIN photodiodes and APDs aimed at telecom/datacom packages. Strengths: speed and form-factor optimization for fiber comms. Strategic focus: grow share by matching evolving telecom receiver requirements and modular APD offerings.
- Excelitas Technologies (Waltham, MA, USA) — Competes with InGaAs APD modules and integrated solutions for LiDAR, OTDR and low-light detection. Strengths: system-module integration and fast time-to-market. Strategic focus: capitalize on recent module launches with integrated TIAs to grab design wins in LiDAR and distributed sensing.
- First Sensor (Wetzlar, Germany) — Produces APD/PIN arrays for LIDAR, rangefinders and safety sensors. Strengths: array expertise and vertical application focus. Strategic focus: push into automotive-grade qualifications and industrial safety systems.
- GCS Inc. (United States) — Foundry and Known Good Die (KGD) provider for InGaAs PIN detectors and arrays—an enabler for OEMs seeking flexible supply. Strengths: foundry services and die-level sourcing. Strategic focus: capture customers that prefer outsourcing epitaxy/processing to specialists.
- Marktech Optoelectronics (Latham, NY, USA) — Offers extended-wavelength InGaAs devices and robust hermetic packaging. Strengths: packaging expertise and wavelength breadth. Strategic focus: serve spectroscopy and gas-detection niches that demand wider spectral response.
- Laser Components (Germany) — Markets InGaAs detector families with extended spectral ranges for spectroscopy and gas sensing. Strengths: product breadth and application focus. Strategic focus: deepen partnerships with instrumentation OEMs.
- Xenics (Belgium) — Specialist in SWIR InGaAs detector modules with in-house ROIC integration for industrial imaging. Strengths: imaging modules and system-level solutions. Strategic focus: expand into automated inspection and machine-vision ecosystems.
- Aeluma, Inc. (United States) — Pushing scalable InGaAs photodetector arrays on large-diameter substrates for high-speed interconnects and AR/VR. Strengths: process scaling and large-diameter integration. Strategic focus: capture high-volume opportunities where cost-per-area matters.
Recent tactical developments to watch
- Excelitas launched new APD modules (notably a 1550 nm series with integrated TIAs and high-bandwidth variants) in late 2025 and early 2026 — a clear move to accelerate LiDAR and high-speed sensing wins.
- OSI introduced its next-generation avalanche photodiode series in early 2026 targeted at telecom, signaling sustained product refresh cycles across incumbents.
- Aeluma’s demonstrations of scalable arrays on large-diameter substrates (spring 2025) signal an important cost/scale vector for applications where array area and yield materially affect unit economics.
Collectively, these moves reflect two competing strategic paths: (1) incremental module integration and specialization for near-term system wins, and (2) longer-cycle process scaling to drive down cost per pixel and enable new volume markets.
Supply-chain and regulatory dynamics — material to strategy
Three practical realities must be operationalized into any 2026 plan:
- Indium and GaAs supply risks: indium availability and purity controls, together with geopolitical export controls, create supply vulnerability. Procurement strategies should include multi-year contracts, secondary sourcing, and recycled-material initiatives.
- Regulatory tightening on impurity levels and export policies: compliance costs and qualification timelines can delay new product introductions. Preemptive investment in compliance engineering and cross-border legal counsel will reduce time-to-revenue.
- Foundry and ROIC integration pressure: as system integrators demand tighter co-design, firms that secure foundry partnerships or internalize key assembly steps will retain pricing power and shorten qualification cycles.
Actionable guidance for 2026 — priority decisions
- Adopt a dual-path product investment: accelerate module-level differentiated offerings (integrated TIAs, hermetic arrays, extended-wavelength modules) to secure near-term OEM design wins, while selectively funding process-scale initiatives that lower long-term unit costs.
- Hedge supply through contractual and operational levers: staggered long-term supply contracts for indium, multi-sourcing for epitaxy, and consideration of vertical integration where economics permit.
- Structure M&A and partnership screens around three criteria: (a) unique process/IP that materially improves yield or spectral range; (b) customer relationships in target high-growth end-markets; (c) ability to close the reliability/qualification gap for safety-critical applications. Use concentration metrics to size accretive targets and anticipate regulatory review.
- Embed regulatory and materials scenarios into financial models: run conservative, central, and upside cases with the report’s CAGR (6.98%) as the baseline — model margins under raw-material price shocks and qualification delays.
- Prioritize customers and applications with the shortest qualification time and highest lifetime revenue (e.g., telecom, instrumentation, selected LiDAR lanes) to optimize 2026–2028 cash flows.
Why executives should read the full PW Consulting report
This briefing frames the strategic contours and immediate choices for 2026, but the full PW Consulting InGaAs Photodiodes and Arrays Market report contains the transaction-grade analytics executives need to act: granular segment-level forecasts by region, type and application; product-level feature/pricing matrices; vendor scorecards; a downloadable financial model; and a prioritized opportunity map with ROI thresholds. Those specifics are intentionally omitted here to preserve the report’s actionable value for subscribers.
Next steps
- If you are evaluating capital allocation, request the full model to stress-test CAPEX and inventory strategies under the three supply-risk scenarios we model.
- If you are a supplier or OEM, commission the vendor scorecard and qualification playbook to accelerate design wins and shorten supplier lead times.
- For investors and M&A teams, obtain the target-screen list and valuation sensitivities tied to concentration and strategic control metrics.
PW Consulting’s InGaAs market product provides the empirical foundation and practical roadmaps required for decisive action in 2026. Contact our research desk to obtain the full report and the underlying datasets that support the summary shown here.
For detailed analysis of this topic, please visit the official page: InGaAs Photodiodes and Arrays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Airbag Fabric Market to reach USD 4.38B by 2032 at 4.6% CAGR
By PW Consulting, 2026-07-08
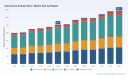
Automotive Airbag Fabric Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As the automotive industry transitions through electrification, advanced safety protocols and heightened regulatory scrutiny, the materials that form the first line of occupant protection are quietly reshaping supplier economics and OEM strategies. PW Consulting’s forthcoming Automotive Airbag Fabric Market study uses a consolidated base year of 2025 and a detailed historical window (2020–2025) to deliver an evidence-based roadmap for decision-makers preparing for 2026 and beyond.
Automotive Airbag Fabric Market
Market snapshot: scale, trajectory and what it means
At the macro level, the global automotive airbag fabric market demonstrated steady recovery from pandemic-era disruption, growing from approximately USD 2.72 Billion in 2020 to USD 3.25 Billion in 2025. Our forecast horizon (2026–2032) projects a compound annual growth rate (CAGR) of 4.6%, taking the market to roughly USD 4.38 Billion by 2032. The early forecast years show incremental growth as OEMs adapt vehicle architectures and regulatory environments continue to evolve.
Automotive Airbag Fabric Market
These headline figures mask important inflection points: regulation-driven demand spikes for multiple-airbag architectures, the rise of textile innovation (coatings, one-piece-woven constructions and PFAS-free chemistries), and supply-chain reconfiguration driven by nearshoring and Tier‑1 consolidation. For leaders making 2026 capital allocation decisions, these combined dynamics mean that modest top-line growth will coexist with accelerated pockets of technical differentiation and margin pressure on legacy products.
Automotive Airbag Fabric Market
What this report delivers — practical, transaction-ready intelligence
- Demand modeling calibrated to OEM program cycles and regulation timelines: granular scenario runs that map airbag fabric tonnage to vehicle platforms and policy changes for 2026–2032.
- Supply-side heatmaps and capacity overlays: production footprints, technology specializations (coating, lamination, one-piece-woven), lead times and bottleneck risk across primary producing geographies.
- Raw-material and cost sensitivity analysis: resin and filament input cost drivers, substitution pathways (e.g., nylon vs polyester trade-offs), and margin impact on fabric suppliers under multiple commodity scenarios.
- Technology and product taxonomy: comparative assessment of nylon 66, polyester, OPW (one-piece-woven), coated/uncoated fabrics, and emergent low-emission resin options — with practical guidance on qualification timelines for Tier‑1s and OEMs.
- Regulatory and standards playbook: implications of regional NCAP protocol changes, India’s multi-airbag mandates and anticipated environmental compliance requirements (including PFAS restrictions and recyclability targets).
- Commercial and M&A intelligence: supplier scorecards, partnership archetypes, pricing curves, and a prioritized list of acquisition targets and integration risks for strategic buyers.
To preserve competitive value for report subscribers, the public preview deliberately refrains from disclosing core segment tables and split-level revenue figures — information available in the full report and supplementary spreadsheets.
Competitive landscape — leaders, disruptors and what their moves signal for 2026
The airbag fabric supplier community remains relatively fragmented at the top; market concentration metrics indicate low top-line dominance among the largest players, leaving substantial room for commercial competition and targeted consolidation. This structural characteristic, combined with technological barriers to entry (specialized weaving/coating, OEM qualification timelines), creates a marketplace where strategic investments yield asymmetric returns.
- Hyosung Advanced Materials (GST) : As a globally recognized leader in OPW and coated/laminated solutions, Hyosung’s scale in proprietary processes positions it to accelerate supply for one-piece-woven cushions. Its recent North American restructuring underscores a playbook of capability expansion and direct Tier‑1 engagement — a blueprint for suppliers seeking to secure program allocations in mature markets.
- Autoliv, Inc. : With deep integration into safety systems and experience introducing recycled-polyester cushions, Autoliv blends product development and system-level testing advantages. Their approach highlights how Tier‑1s can internalize textile innovation to manage specification risk and reduce supply-chain complexity for OEMs.
- Toyobo Co., Ltd. : The consolidation of North American supply into a Thailand-based integrated yarn-and-fabric operation illustrates a regional optimization strategy — centralize high-value, integrated production in cost-advantaged locales while keeping proximity to OEMs through subsidiaries.
- Kolon Industries : The announced multi-billion-won investment in a new plant in Vietnam is emblematic of a broader shift: suppliers are expanding Southeast Asian capacity to capitalise on regional OEM growth and shortened logistics for large programs slated to enter ramp from 2028 onward.
- Teijin, Toray, Asahi Kasei : These established Japanese suppliers retain competitive advantage through specialty polyamide technologies, global production bases, and fast-track qualification capability. Notably, Asahi Kasei’s launch of PFAS‑free polyamide grades signals how material science leadership is converging with environmental compliance as a commercial differentiator.
- Milliken, Porcher, HMT (Xiamen) : These players broaden the competitive set — offering differentiated coatings, regional responsiveness and OEM-specific product lines. Their presence reaffirms the two-tiered market structure: a set of global technology leaders and a broader base of regionally focused specialists.
Recent corporate actions — plant investments, restructuring and product announcements — reveal the strategic priorities for 2026: securing program content, reducing qualification lead times, and meeting tighter environmental standards. For procurement teams, this means evaluating suppliers not only on unit cost but on program continuity, regulatory alignment and technology roadmap compatibility.
Dynamics shaping near-term strategy
- Regulatory incentives are realigning product portfolios: changes in NCAP protocols and national safety mandates are creating distinct demand pockets (e.g., external/pedestrian protection textiles, multiple-airbag systems). Suppliers that can certify weather-resistant and pedestrian-protection textiles will capture incremental value.
- Sustainability is rapidly moving from compliance risk to commercial opportunity: PFAS-free resins and recycled-polyester cushions are transitioning from R&D to production readiness. OEMs will increasingly select partners with verifiable circularity credentials as part of supplier scorecards.
- Supply-chain reconfiguration accelerates regionalisation: investments in Southeast Asia and capacity restructuring in North America reflect OEM footprint changes and the need for shorter lead-times on high-content programs.
- Material substitution and cost pressure: resin volatility and competing fibers exert margin pressures; however, the technical certification burden for safety textiles limits rapid substitution, creating windows for suppliers who invest in qualification throughput.
Actionable recommendations for 2026 planning
- Prioritize strategic supplier audits focused on qualification velocity, coating capability and environmental-compliance documentation. Near-term program awards will favour suppliers who can demonstrate fast-track qualification and low residual risk.
- Accelerate material R&D partnerships targeting PFAS-free chemistries and recycled-content solutions. Early entrants will secure OEM design wins as sustainability requirements tighten in 2026–2028.
- Reassess sourcing geographies with a two-axis lens: production cost and program proximity. For OEMs, localizing high-content airbag fabric supply in growth regions reduces inventory and integration risk; for suppliers, investing in capacity near major Tier‑1s yields preferential allocation.
- Design M&A and JV playbooks around capability gaps, not just capacity. Targets with coating, lamination or one-piece-woven expertise deliver more strategic value than scale alone.
- Embed scenario-based procurement contracts that account for raw-material shocks and qualification timelines — move away from simplistic volume-price models to hybrid contracts that protect program continuity.
Why PW Consulting’s full report is a 2026 must-have
Leading firms entering program negotiations, plant investments, or material R&D in 2026 will be judged on their ability to synthesize regulatory timelines, supplier capability maps and commercial levers into executable plans. PW Consulting’s full Automotive Airbag Fabric Market report provides the spreadsheets, supplier scorecards and scenario models required to operationalize those plans — including the full segmentation matrices, price curves, and an exhaustive vendor risk register.
Our preview here sketches the strategic contours; the full study contains the actionable, transaction-ready intelligence that informed sourcing, manufacturing and investment decisions in comparable programs across the automotive supply chain.
Next steps
- Procurement and strategy teams: request the full dataset to run your OEM program scenarios and supplier qualification timelines.
- R&D and sustainability leads: use our material substitution model to fast-track PFAS‑free and recycled-content trials with incumbent suppliers.
- Corporate development: identify acquisition or JV targets via our prioritized consolidation scorecard and capacity overlay.
PW Consulting’s Automotive Airbag Fabric Market study is designed to convert market-scale forecasts (base year 2025; CAGR 4.6% for 2026–2032) into executable strategies. For companies that view 2026 as a decisive year, the report turns ambiguity into an actionable playbook — revealing where to invest, partner and compete without disclosing the proprietary segment-level tables that form the backbone of program-winning insight.
For detailed analysis of this topic, please visit the official page: Automotive Airbag Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LEO Satellite Market to Reach USD 25.95 Billion by 2032PW Consulting: Probiotics Market Poised for 8.5% CAGR (2026–2032)
By PW Consulting, 2026-07-08
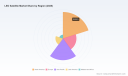
LEO Satellite Market — Strategic Brief for 2026 Decision-Makers
Executive snapshot
The Low Earth Orbit (LEO) satellite market is moving from early-stage scale-up into a mature commercial battleground. Our PW Consulting market model shows a clear and sustained expansion: the global market grew from roughly USD 6.1 Billion in 2020 to about USD 11.8 Billion by the 2025 base year, and — under our central assumptions — is projected to exceed USD 25.9 Billion by 2032. That trajectory reflects a compound annual growth rate of 11.9% for the 2026–2032 forecast interval and is accompanied by a moderately concentrated supplier landscape (the top three and top five groups account for a material share of revenue).
LEO Satellite Market
For investors, operators, infrastructure providers and enterprise consumers, 2026 is not merely another year of growth — it is the inflection point where decisions around spectrum, ground infrastructure, partnerships, and vertical integration will determine who captures the high-margin opportunities that remain.
LEO Satellite Market
Why this matters in 2026: converging catalysts and new realities
-
Regulatory acceleration — Recent regulatory moves have systematically lowered barriers to scale. Proceedings and reforms in key jurisdictions are unlocking spectrum and simplifying permissions for ground infrastructure, which together reduce time-to-market for new services and materially change the economics of network densification.
LEO Satellite Market -
Deployment momentum — Large-scale constellation deployments and rebranded launch programs have intensified competitive posture among hyperscalers and specialized operators. Network rollouts in 2026 are creating new wholesale and retail opportunities while compressing the window for first-mover advantage in many verticals.
-
Operational friction points — Despite momentum, hardware and supply-chain constraints persist. Multi-year program delays for critical on-board processors and ASICs, plus launch cadence volatility, create scenario-dependent timing risk for commercial rollouts and joint-go-to-market plans.
-
Market concentration and go-to-market dynamics — A relatively high revenue concentration at the top end of the market creates oligopolistic buyer-seller dynamics. This environment favors integrated operators with end-to-end service stacks but also opens niches for specialized data and services players.
Strategic implications for enterprise leaders in 2026
Executives must translate macro momentum into defensible, time-sensitive choices. The following imperatives summarize what companies should prioritize within the next 12–36 months:
-
Define a spectrum and ground-station strategy: Engage regulators proactively and secure long-lead approvals and land-rights for neutral-host or operator-owned ground infrastructure. Regulatory windows are widening — but competition to occupy them will be intense.
-
Optimize capex vs. opex exposure: Decide whether to invest in proprietary infrastructure or contract with hyperscalers and managed service providers. Our models show substantive differences in IRR depending on launch schedules and service adoption curves.
-
Prioritize vertical value capture: Pure connectivity is becoming a commoditized input. Differentiation will come from adjacent data sets, edge processing, analytics and industry-specific SLAs (e.g., maritime, aviation, utilities, and public safety).
-
Negotiate supplier relationships from a position of insight: Benchmarking vendor economics, service-level templates, and procurement KPIs—available in the full study—reduces execution risk and improves commercial outcomes.
-
Stress-test business models to hardware and regulatory scenarios: Build decision trees that reflect delayed ASICs, launch manifest shifts, and regulatory permutations so investment committees can select robust pathways rather than optimistic baselines.
Competitive landscape: actors, assets and strategic postures
The competitive field includes hyperscalers, traditional satellite operators, niche service specialists and vertically focused new entrants. Each group brings different assets and risks that should shape partnership and procurement choices.
-
Hyperscalers and large-scale operators — Firms executing large constellation programs are pursuing global broadband and platform plays. Their scale advantages translate into bandwidth economies, rapid route-to-market for bundled services, and the ability to subsidize terminal costs. Enterprises should evaluate partnership terms carefully: their power to influence wholesale pricing and feature roadmaps is significant.
-
Established satellite operators — Traditional players are leveraging capital and spectrum holdings to pivot into LEO or hybrid LEO-GEO offerings. For enterprise buyers, these incumbents provide stronger regulatory relationships and mission-critical service pedigrees; however, they face pressure to modernize hardware and accelerate rollouts.
-
Specialized players and data providers — Companies focusing on Earth observation, IoT telemetry, or direct-to-device connectivity are monetizing distinct value chains. Their appeal lies in vertical integration with analytics, lower-latency data products, and flexible SLAs suited to industrial and government clients.
-
What recent developments mean — The past six months have highlighted two structural themes. First, rapid network deployments by large entrants are reshaping capacity forecasts and partner bargaining power. Second, material program delays for some operators underscore persistent technology and supply-chain risks that can shift revenue timing materially. Both themes mean that procurement and partner-selection timelines should be adaptive rather than fixed.
What PW Consulting’s LEO Satellite Market study delivers (practical, decision-ready content)
Our report is built to support board-level and operating-level decisions. It intentionally balances methodological transparency with commercial confidentiality — providing the modeling logic, scenario outputs and executable tools you need while preserving the proprietary segmentation tables that drive negotiation advantage.
-
Transparent market-sizing and forecasting: methodology, assumptions, sensitivity ranges and scenario outputs for 2026–2032.
-
Concentration and competitive dynamics: CR3/CR5 analysis, revenue pools and provider positioning maps that explain where pricing power will reside.
-
Go-to-market playbooks: channel strategies, partnership architectures, pricing models and launch-phased commercial templates for enterprise, government and wholesale customers.
-
Operational economics: capex/opex templates, terminal and ground-station TCO models, launch cost sensitivity analysis and break-even frameworks under multiple deployment cadences.
-
Vendor scorecards and RFP frameworks: evaluation criteria, sample contractual KPIs and negotiation levers to preserve margin and mitigate supplier risk.
-
Regulatory playbook and advocacy checklist: jurisdictional tracking, spectrum engagement strategies, and recommended timing for regulatory filings.
-
Risk and resilience toolkit: supply-chain stress scenarios, contingency planning for hardware delays, and layered procurement approaches to maintain service continuity.
How to use this intelligence in 2026 — immediate next steps
-
Immediate (0–6 months): Perform an operator-fit analysis against your service requirements; open regulatory dialogues; lock preferred vendors for ground capacity where lead times exist.
-
Near term (6–18 months): Pilot with at least two different deployment models (one hyperscaler-led, one specialist-led) to validate SLAs and pricing in real operational contexts.
-
Medium term (18–36 months): Decide on strategic posture — integrator/operator vs. service buyer. Commit to either owning ground & spectrum assets or to structured long-term partnerships; align procurement and finance to your chosen path.
Final perspective — the strategic payoff
By 2032 the LEO ecosystem will support materially larger revenue pools and a richer set of downstream monetization pathways than in 2025. The crux for 2026 decision-makers is timing and architecture: whether to capture upside through early infrastructural commitments or to preserve optionality via commercial partnerships. In either case, a rigorous, scenario-driven approach — combining regulatory foresight, vendor benchmarking and operational modeling — will materially improve execution outcomes.
PW Consulting’s full LEO Satellite Market study contains the segmented forecasts, provider-level economics, and downloadable modeling tools that empower those choices. The executive brief above demonstrates the analytical depth of the work while reserving the granular segmentation tables and vendor-specific financials that give reading organizations a competitive edge. For access to the full data set, models and playbooks, please consult the PW Consulting LEO market landing page.
For detailed analysis of this topic, please visit the official page: LEO Satellite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: SiC Wafer Market to Reach USD 1,006.94M by 2032 at 14.66% CAGR
By PW Consulting, 2026-07-08
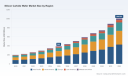
Silicon Carbide Wafer Market: Strategic Imperatives for 2026
Executive summary
Between 2020 and 2025 the silicon carbide (SiC) wafer market moved from early scaling into commercial momentum. Our analysis — built on a 2025 base year and a forecast window of 2026–2032 — shows the market expanding from a multi-hundred million USD base in 2025 and tracking at a compound annual growth rate (CAGR) of approximately 14.66% over the forecast period. Under a mid-case scenario the global SiC wafer market reaches roughly 1.0 billion USD (Million, USD) by 2032. This trajectory signals that 2026 is the hinge year for capacity commitments, vertical integration choices and geopolitical hedging for firms seeking to lead in wide-bandgap semiconductor stacks.
Silicon Carbide Wafer Market
Why this report matters to 2026 decision-makers
-
Timing and scale: The industry is transitioning from capacity-constrained commercialization into industrial-scale manufacturing. Decisions taken in 2026 — regarding fab formats, long-lead equipment investments and partner selection — will determine whether a firm participates in volume cost curves or remains a niche supplier.
Silicon Carbide Wafer Market -
Technology inflection: Moves to larger wafer diameters and continuous improvements in crystal quality are redefining unit economics and end-market applicability. Early adopters of next‑generation platforms stand to shape standards for power density, switching performance and thermal management.
Silicon Carbide Wafer Market -
Policy and market access: Regulatory regimes and public funding are reshaping where and how SiC supply chains consolidate. Firms must integrate export control risk, subsidy opportunities and localization pressures into capital allocation models.
Market dynamics and technology inflection points
Three converging forces are driving the SiC wafer market into a new phase: industrial-scale diameter expansion, vertical capture of epitaxy/process layers, and demand intensity from electrification and AI‑infrastructure power delivery. The move from niche 100–150mm production lines toward robust 200mm installations has advanced rapidly: several incumbents announced production ramp milestones in 2025, and by early 2026 there are public signals of even larger single-crystal wafer ambitions. These steps are not merely about throughput — they change defect density economics, yield profiles and equipment roadmaps.
At the same time, supply-side concentration is increasing but not absolute: the top-three and top-five companies together account for a meaningful share of the market (CR3 ~45%; CR5 ~55%), creating an environment where strategic partnerships, tiered supply agreements and capacity reservations can materially affect customer lead times and price dynamics.
Regulation and industrial policy are equally impactful. Targeted export controls on advanced SiC material and tighter U.S.-China licensing regimes are raising transaction friction for cross-border sourcing of advanced wafers. Counterbalancing that, major subsidy programs in North America and Europe and state-directed support in Asia are accelerating localized capacity buildouts. The net effect for 2026 decision-makers is a higher premium on supply chain diversification, compliance capability, and policy‑aware capital planning.
Competitive landscape — who’s shaping the next wave
The competitive map mixes specialist substrate producers, large integrated device manufacturers, and wafer converters. The companies we track combine native SiC crystal expertise with strategic moves into epitaxy, device integration and capacity scale. Key players profiled in the report include:
-
Wolfspeed, Inc. (Durham, NC) — recognized leader in SiC with a clear focus on scaling wafer diameter and integrating upstream substrate production with downstream device platforms.
-
Coherent Corp. (U.S.) — supplying production-grade substrates and expanding epitaxial wafer capabilities to support higher shipment volumes for device makers.
-
STMicroelectronics (Geneva/Catania) — shifting industrial footprint toward 200mm SiC production with automotive-grade ambitions for power chips.
-
Infineon Technologies AG (Neubiberg) — entering customer rollouts from 200mm wafer development, tightening device roadmaps for power semiconductor customers.
-
SK Siltron, GlobalWafers, X-FAB, SiCrystal and Sanan Optoelectronics — each contributing strategic capacity, conversion capabilities and regional reach in their respective segments.
Recent public developments illustrate the strategic vector: multiple firms announced 200mm production initiatives in 2025 and early 2026, and a breakthrough in single-crystal large-diameter wafer production was reported in 2026. These announcements accelerate the shift to platform-based economics and place a premium on scale-up execution, process stabilization, and yield improvement.
Regulatory and geopolitical overlay
Policy is not background noise — it’s a primary market driver. Export control measures on advanced wafer technologies, ongoing U.S.-China export control tightening, European capacity incentives under the Chips Act, and national industrial plans in China are altering the calculus for where to build fabs, which technologies to license, and how to structure commercial agreements. Public funding mechanisms in North America and Europe offer attractive co‑investment options but introduce compliance and reporting requirements that must be accounted for in financial models.
Strategic playbook for executives in 2026
-
Map supply risk to product roadmaps: Segment your product portfolio by sensitivity to wafer diameter and material grade, then align long‑term supply contracts and dual-sourcing strategies to those buckets.
-
Prioritize industrial partnerships over one-off purchases: Secure long‑dated offtake or JV structures with substrate and epitaxy specialists to lock-in capacity for critical nodes.
-
Stage capex with optionality: Structure investment in processes and tools to allow staged upgrades (e.g., 150mm → 200mm compatibility) and reduce stranded asset risk if technology or policy pivots occur.
-
Embed regulatory intelligence in procurement: Build licensing and export-control capabilities into commercial teams to prevent shipment hold-ups and accelerate cross-border deployments.
-
Build an IP and talent moat: Capture process know‑how around crystal growth, defect mitigation and epitaxy; recruit cross-disciplinary engineers who can bridge materials science and device engineering.
-
Consider M&A as a fast-track to capability: Identify tuck-in substrate producers, epitaxy specialists and tool suppliers that can close critical capability gaps faster than organic scale-up.
-
Create a dynamic pricing and inventory playbook: Anticipate periodical supply tightness and align contractual terms (price floors/ceilings, volume bands) to mitigate margin erosion.
What the full PW Consulting report delivers (practical contents)
The report converts strategic narrative into transaction-ready outputs for 2026 planning cycles. Highlights include:
-
An audited market model (historical 2020–2025, base year 2025) and transparent forecast engine (2026–2032) with scenario toggles for demand sensitivity, technology adoption curves and policy shocks.
-
Supply chain mapping from boule/crystal growth through epitaxy, wafer processing and device integration, including lead‑time heatmaps and bottleneck identification.
-
Technology roadmaps comparing cost-per-wafer and defect metrics across wafer diameters and epitaxial architectures, with unit-economics analysis for platform choices.
-
Supplier scorecards and due-diligence frameworks for partner selection, covering quality, capacity, IP posture and geopolitical exposure.
-
Commercial playbooks: procurement contracting templates, pricing strategy playbooks, inventory optimization tools and sample term-sheets for long-term offtake agreements.
-
Investment and M&A target shortlist with high‑level financial and operational rationales — enabling rapid screening for bolt-on vs transformational acquisitions.
-
Regulatory impact matrix aligning export controls, subsidy programs and local content rules to likely sourcing and go‑to‑market scenarios.
Risk factors and blind spots
Key risks for 2026 planning include technology execution (yield and defect reduction at larger diameters), concentrated equipment lead times, accelerating or tightening export controls, and unpredictable subsidy competition that shifts capital flows across regions. Our report quantifies these risk vectors and provides mitigation pathways — from staged investment to hedged offtake agreements and regulatory contingency playbooks.
Actionable next steps for business leaders
-
Re-run your 2026 capital plan under a 14.66% CAGR baseline and at least two downside scenarios; quantify the breakeven volume for each wafer diameter choice.
-
Initiate shortlists for capacity partners and negotiate conditional offtake terms to preserve optionality while reducing lead‑time exposure.
-
Assign a cross-functional SiC task force (procurement, R&D, compliance, corporate development) to crystallize a 12‑ to 24‑month road map that aligns technology sourcing with sales funnel milestones.
-
Engage with government relations to identify co‑funding or risk‑sharing opportunities under regional industrial programs.
Conclusion — the strategic moment
The SiC wafer market is no longer an exploratory niche; it is on a trajectory to become a cornerstone input for the electrification and high‑performance power infrastructure of the 2030s. For organizations that move decisively in 2026 — aligning supply, technology, funding and regulatory strategies — the upside is substantial. For those that delay, the combination of fabrication scale economics, regulatory friction and supplier concentration will raise the cost of market entry.
Where to obtain the granular intelligence
This article is a strategic trailer: it highlights the macro trends, competitive moves and decision levers that matter for 2026 without disclosing the granular regional, type and application splits that drive commercial negotiations. The full PW Consulting Silicon Carbide Wafer Market report contains the detailed segment-level analytics, price curves, supplier scorecards and downloadable modelling tools necessary to execute on the strategies outlined above. Contact PW Consulting to access the complete dataset, scenario models and bespoke advisory packages.
For detailed analysis of this topic, please visit the official page: Silicon Carbide Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Restaurant POS Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-08
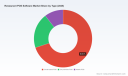
Restaurant POS Software Market — Strategic Imperatives for 2026 (PW Consulting)
This introduction previews PW Consulting’s full Restaurant POS Software Market study and its strategic value for decisions in 2026. The market reached a substantive milestone in the base year (2025) and—driven by digital ordering, cloud migration, and tighter security requirements—continues on a steady upward trajectory at a compounded annual growth rate (CAGR) of approximately 6.98% through our forecast horizon. From a disciplined historical base, the market is set to expand materially over the 2026–2032 period, creating a time-sensitive window for operators, technology vendors, and investors to re-position for advantage.
Restaurant POS Software Market
Why this report matters for 2026 decisions
-
Regulatory acceleration: PCI DSS v4.x updates that came into force in 2025 raise the bar for access controls and multi-factor authentication (MFA) for POS systems. Compliance is no longer a checkbox activity; it is a product and operational design requirement that affects vendor selection, vendor risk, and future upgrade paths.
Restaurant POS Software Market -
Labor and operational pressure: Nearly half of operators indicate plans to replace or significantly upgrade POS systems in 2026 to address labor shortages and efficiency shortfalls—making vendor choice and migration timing mission-critical.
Restaurant POS Software Market -
Technology transition: The market dynamic increasingly prizes cloud-native architectures, resilient offline modes, API-first integration, and embedded payment capabilities—attributes that materially affect total cost of ownership (TCO) and time-to-value.
-
Investor and M&A interest: A structurally fragmented competitive landscape and recurring-revenue SaaS models create pockets of consolidation opportunity for strategic and financial buyers, particularly for platforms that can demonstrate scale, margins, and product differentiation.
What the PW Consulting report delivers (practical, execution-focused)
-
Concise market sizing and validated growth scenarios (base year, historical trend analysis, and point forecasts through 2032) to support capex and portfolio planning.
-
Decision-grade vendor scorecards and capability maps that weigh security posture, integration breadth, product architecture, commercial model, and channel coverage.
-
Go-to-market (GTM) playbooks for vendors and channel partners: pricing levers, partnership models, and sales motions that accelerate adoption among independent restaurants, multi-location operators, and large enterprise chains.
-
Migration and implementation roadmaps with phased pilots, rollback plans, and operational KPIs to protect revenue during POS transitions.
-
Compliance and security checklists aligned to PCI DSS v4.x and emerging data-privacy expectations, plus vendor-neutral templates for security clauses and SLAs.
-
ROI and TCO models customizable by operator profile, including labor-savings scenarios and revenue uplift assumptions for digital ordering, loyalty, and analytics features.
-
M&A screening framework and financial sensitivity models to identify accretive targets and partnership opportunities without disclosing sensitive segment-level splits in this preview.
Market structure and competitive landscape — a high-level view
The restaurant POS software landscape remains meaningfully fragmented—no single vendor dominates across all buyer segments and geographies. Concentration metrics indicate ample room for market share movement and consolidation; strategic advantage accrues to platforms that successfully combine product breadth, embedded payments, and services capability.
-
Toast, Inc. — Positioned as an AI-enabled restaurant management platform, Toast combines integrated POS, digital ordering, team management, and payments. Its scale in product integration and focus on operational automation make it a benchmark for platform-first offerings aimed at the mid-market and above.
-
NCR Voyix (Aloha) — With a long heritage in hospitality POS, Aloha’s cloud and hybrid solutions cater to operators requiring proven enterprise-class features and deep integrations to legacy systems—an option for large multi-location operators with complex requirements.
-
Square, Inc. — Delivers a restaurant-ready POS with built-in inventory and analytics tools targeted at independents and SMBs. Square’s strength lies in a low-friction commercial model and ecosystem of adjacent services.
-
Lightspeed — Emphasizes cloud-native POS and restaurant management features, with a focus on omnichannel capabilities and international expansion via commerce integrations.
-
TouchBistro — Focuses on unified POS functionality with kitchen display systems and analytics tailored to on-premise operations; strong in the independent restaurant segment where kitchen workflow matters most.
-
Clover — Offers restaurant-oriented POS functionality plus marketing and operational integrations; notable for its developer and partner ecosystem that extends functionality via third-party apps.
-
Revel Systems — Targets multi-location chains with cloud POS that emphasizes centralized management and enterprise reporting—appealing for operators seeking a single-pane-of-glass view across sites.
-
Lavu — A tablet-based POS option aimed at independents and smaller chains, favoring ease-of-use and rapid deployment.
-
Upserve — Focuses on independent operators with an emphasis on restaurant-specific workflow improvements and analytics-driven insights.
-
Oracle (MICROS / Restaurant 365) — Serves enterprise hospitality customers with deeply integrated POS, property-management, and back-office systems; positioned as the enterprise standard for large chains and full-service resorts.
Recent industry recognition—such as a leading vendor being named the top restaurant POS by a prominent software review grid in late 2025—underscores the competitive dynamism and the importance of user experience and peer validation in purchase decisions.
Strategic recommendations for 2026 (operators, vendors, investors)
-
Restaurant operators: Prioritize compliance-first vendor selection (MFA, encryption, update cadence). Pilot cloud-native solutions that offer robust offline operation. Insist on open APIs and pre-defined integration paths for ordering aggregators, loyalty, and payroll to minimize hidden integration costs. Use phased rollouts anchored by ROI measurement and labor-saving KPIs.
-
Vendors: Accelerate productization of security and compliance features to reduce buyer friction. Invest in modular architectures and third-party developer ecosystems. Expand managed services and migration offerings to address operator risk aversion during upgrades.
-
Investors and acquirers: Target companies with high recurring revenue, differentiated integrations (payments + analytics), and demonstrated churn reduction through value-added services. Favor assets that address mid-market fragmentation and that have clear paths to margin expansion via platform monetization.
Risks and uncertainties to model in 2026 planning
-
Regulatory implementation timelines and enforcement intensity for payment and data-security standards.
-
Potential for data breaches and associated reputational and remediation costs—stress-test vendor incident response capabilities.
-
Operational risk during migrations, including revenue disruption and staff retraining requirements.
-
Macro demand variability that may delay capex among independent operators; scenario planning for slower adoption curves is imperative.
How PW Consulting’s report turns insight into action
Our full study couples granular, verifiable market sizing and scenario models with pragmatic execution tools—vendor scorecards, contract negotiation templates, compliance checklists, and step-by-step migration plans. The report is designed for three immediate uses in 2026: to de-risk vendor selection and migration; to size and prioritize product investments; and to identify consolidation or partnership targets with clear economics.
This preview omits detailed segment-level tables and specific regional/application splits to protect the report’s decision-grade intelligence. To access sector-specific breakouts, vendor benchmarking matrices, and our downloadable TCO/ROI models, please consult the full Restaurant POS Software Market report on the PW Consulting portal or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Restaurant POS Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 18650 Battery Market to Reach USD 10,280M in 2025 with 8.5% CAGR
By PW Consulting, 2026-07-08
18650 Lithium Battery Market — Strategic Briefing for 2026 Decisions
As PW Consulting’s senior industry analyst, I present a focused strategic primer on the 18650 lithium battery market designed to inform and accelerate executive decision‑making in 2026. This briefing synthesizes our proprietary market model, competitive intelligence, and scenario workstreams to show where value will be created — and where it is at risk — over the next investment cycle. The full PW Consulting 18650 report (base year 2025) contains the granular segmentations, supplier scorecards, and downloadable financial models referenced here; this article deliberately surfaces conclusions and actionable implications while withholding the confidential sub‑segment tables that power those recommendations.
18650 Lithium Battery Market
Market trajectory: growth with structural inflection points
Between 2020 and 2025 the 18650 market expanded rapidly, driven by rising demand across portable electronics, industrial tools, and early reuse in EV and energy storage applications. Our consolidated market size model places the industry at approximately USD 10,280 Million in 2025. Looking forward, our forecast horizon (2026–2032) reflects a compounded annual growth rate (CAGR) of roughly 8.5%, with the market expected to exceed USD 11,100 Million in 2026 and continuing to expand through the end of the forecast period.
18650 Lithium Battery Market
Two features of this growth profile matter for boardroom choices in 2026: first, steady structural momentum supports disciplined capacity additions for firms that can control costs and secure feedstock; second, episodic cost shocks (notably on raw materials and logistics) create windows where nimble players can gain share if they move faster than incumbents to hedge and reprice.
18650 Lithium Battery Market
Macro dynamics shaping near‑term strategy
-
Raw material price volatility — Lithium carbonate prices rebounded sharply from historical lows during April 2025–February 2026. This rebound has produced an upward reset in production cost curves for cylindrical cells, affecting long‑lead procurement assumptions and narrowing margin windows for commoditized 18650 SKUs.
-
Regulatory tightening — Since the 2025–2026 ICAO revisions, manufacturers and distributors of 18650 cells are required to provide UN 38.3 test summaries to operators. This administrative burden affects go‑to‑market timelines for new SKUs and increases the importance of test documentation and supply chain traceability.
-
Policy and industrial strategy — Longer‑term government initiatives (for example, national blueprints to decrease reliance on critical minerals) continue to incentivize local processing, recycling, and alternative chemistries. Firms that align product roadmaps and capital plans with these policies can access subsidies, off‑take contracts, and lower logistic friction.
Competitive landscape — concentration and strategic positioning
The 18650 market exhibits meaningful concentration: the top three firms control a material majority of capacity, and the top five represent an even larger share. These concentration metrics indicate significant barriers to scale (manufacturing know‑how, long supplier relationships, and capital intensity) but also leave opportunities for challengers that forge differentiated value propositions.
Key incumbent profiles in our competitive audit include:
-
Panasonic Corporation (Osaka, Japan) — A legacy leader focused on high‑energy‑density 18650 cells used in consumer electronics, power tools, and an evolving set of EV applications. In March 2025 Panasonic announced a new high‑capacity 18650 cell optimized for EV usage with improved thermal stability — a clear play for higher‑margin EV adjacencies. ( https://www.panasonic.com/global/energy/)
-
Samsung SDI Co., Ltd. (Suwon, South Korea) — Pursues high‑capacity cylindrical designs for EVs, stationary energy storage, and premium consumer devices. Samsung’s strength is in integration across cell chemistry and pack engineering. ( https://www.samsungsdi.com/)
-
LG Energy Solution (Seoul, South Korea) — Supplies industrial and consumer markets with a broad 18650 portfolio and benefits from scale manufacturing and global customer relationships. ( https://www.lgenergysolution.com/)
-
EVE Energy Co., Ltd. (Xiamen, China) — A fast‑growing manufacturer focused on consumer electronics and industrial applications; regional cost advantages support aggressive volume plays. ( https://www.evebattery.com/)
-
BYD Company Limited (Shenzhen, China) — Leverages deep EV value chain integration to channel 18650 production into both vehicle and portable product lines. ( https://www.byd.com/)
-
CATL (Ningde, China) — Extending cylindrical cell capabilities into energy storage and consumer applications; CATL’s global partnerships create distribution leverage. ( https://www.catl.com/)
-
Tianjin Lishen (Tianjin, China) — Focused on high‑cycle 18650 cells for industrial energy systems and announced next‑generation cylindrical modules in May 2025 targeting >1,500 cycles, signaling emphasis on lifecycle economics. ( https://www.lishen.com/)
Recent product launches and R&D pushes show incumbents pursuing two parallel plays: (1) premiumization — higher energy, thermal robustness, and cycle life to enter EV and ESS segments at better margins; and (2) cost leadership — scale and supply‑chain optimization to defend commoditized volumes. The net result is an environment where scale, technology differentiation, and supply security determine winners.
What the PW 18650 report delivers (actionable, not academic)
Our report is designed for commercial and strategy teams that must act in 2026. Highlights of the deliverables include:
- An integrated market sizing model (2020–2032) with sensitivity toggles for commodity prices, demand substitution, and regulatory shock scenarios — delivered as editable spreadsheets.
- A cost curve and breakeven map at cell and module levels, enabling you to simulate margin outcomes across chemistry choices and plant utilization rates.
- Supply chain heatmaps (tier‑1 to tier‑3), including mapped logistics chokepoints, single‑sourced inputs, and supplier financial strength indicators.
- Competitive scorecards for the leading companies with capability matrices (manufacturing processes, IP, thermal management, cycle life performance) and a short list of potential M&A and JV candidates aligned to strategic plays.
- Regulatory and compliance playbooks covering UN 38.3, transport restrictions, and country‑level incentives, plus a checklist to accelerate certifications and operator acceptance.
- Deal structuring templates for long‑term supply contracts and risk‑sharing mechanisms (indexation clauses, floor/ceiling pricing, shared cost of change provisions).
- Scenario‑based capital allocation frameworks that prioritize investments in capacity, R&D, or recycling based on quantified NPV and payback under alternate commodity paths.
These outputs are paired with consultancy‑grade recommendations and a prioritized implementation roadmap tailored to three archetypes: scale players, fast followers, and focused specialists.
Strategic actions for 2026 (prioritized)
Given current dynamics — continued demand growth, commodity price rebound, and regulatory tightening — we recommend the following prioritized actions for firms making near‑term capital and commercial decisions.
-
Lock procurement, but keep optionality: Convert a portion of medium‑term feedstock needs into hedged or indexed contracts to protect margins, while preserving flexibility to pivot to alternative chemistries if material prices remain elevated.
-
Accelerate certification and documentation processes: Invest in centralized test and compliance capabilities to meet ICAO and other transport documentation requirements without delaying shipments of new SKUs.
-
Differentiate via performance economics, not just price: For premium end‑markets (EVs, ESS), prioritize improvements in thermal stability and cycle life; for commoditized consumer volumes, optimize cost through manufacturing footprint and automation.
-
Evaluate partnerships over greenfield buildouts: Given the market’s concentrated structure and capital intensity (top three players controlling a material share), consider joint‑ventures or capacity share agreements to de‑risk expansion and access offtake.
-
Embed recycling and material recovery in product strategy: With policy momentum toward reducing critical‑material dependence, establish recycling trials and supplier partnerships now to capture recovered lithium and cobalt and improve long‑term feedstock security.
-
Model for volatility: Use scenario NPV models (included in our full deliverable) to size investments under both optimistic demand and high‑cost commodity paths — allocate discretionary capex to options that remain robust across scenarios.
Why this matters for boardrooms in 2026
2026 is a pivotal year in which the interplay between demand growth (CAGR ~8.5%) and supply‑side cost pressure will create asymmetric opportunities. Firms that move early to secure feedstock, document compliance, and sharpen product economic advantages will capture outsized margins and strategic customers. Conversely, those that wait for spot prices to stabilize risk facing compressed returns or being relegated to low‑margin supply pools dominated by the largest incumbents.
In short, the market reward in 2026 will favor calibrated scale, documented compliance, and technological differentiation. The full PW 18650 report supplies the numbers, models, and supplier diagnostics you need to operationalize these strategies without the guesswork.
Next steps — access and implementation
To translate these insights into 90‑ and 180‑day execution plans for procurement, product, and M&A teams, access the full PW Consulting 18650 Lithium Battery Market report and the editable model pack. The full report contains the region, chemistry, and application‑level tables that underpin the scenarios summarized here — intentionally withheld in this preview to preserve the competitive value of the underlying segmentation and price curves.
Contact PW Consulting to schedule a briefing where we’ll walk your team through the model, stress tests specific strategic options, and co‑develop a prioritized implementation roadmap tailored to your company’s risk tolerance and commercial objectives.
For detailed analysis of this topic, please visit the official page: 18650 Lithium Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Credit Insurance Market at USD 13.0 Billion in 2025, 6% CAGR to 2032
By PW Consulting, 2026-07-08
Credit Insurance Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
As corporate treasuries, insurer strategy teams and trade financiers plan through 2026, the credit insurance market presents a clear growth arc mixed with mounting complexity. PW Consulting’s new market study positions the industry as a growth engine for risk transfer and working capital management: the global short‑term credit insurance market expanded from an estimated USD 9.7 billion in 2020 to roughly USD 13.0 billion in 2025, and our baseline projection reaches about USD 19.6 billion by 2032 at a 6.0% CAGR. Those headline numbers frame the opportunity; the strategic task for executives is translating that macro momentum into commercially defensible moves amid evolving regulation, climate exposure, and technology-driven underwriting change.
Credit Insurance Market
Why this research matters for 2026 decisions
2026 is a hinge year. Insurers and corporates must reconcile near‑term operational resilience with longer‑term platform investments. Our study is designed to inform four classes of 2026 decisions:
Credit Insurance Market
- Underwriting strategy and product design — where to prioritize capacity, what risk appetites to tighten or expand.
- Distribution and channel economics — which partners, digital routes and pricing models will deliver profitable growth.
- Regulatory and governance readiness — how to operationalize new compliance requirements without killing speed to market.
- M&A and portfolio management — how to size inorganic moves versus organic capability buildups to capture the next phase of growth.
Market trajectory — what the numbers imply (without giving away the segmentation playbook)
The headline increase in aggregate market size over 2020–2025 and the projected 6.0% CAGR to 2032 tell a multi‑layered story. First, demand for trade credit protection is structurally rising as corporates externalize counterparty risk and optimize balance sheets. Second, growth is not uniform — pockets of accelerated demand intersect with regions and buyer types that respond differently to trade flows, commodity cycles and geopolitical shifts. Third, competitive dynamics reflect moderate market concentration (CR3 ~40.5%, CR5 ~48.2%), indicating room for challengers and specialist players to disrupt incumbents, while scale remains an important underwriting advantage.
Credit Insurance Market
We intentionally do not reproduce full regional, type or application splits here: PW Consulting’s full dataset and interactive dashboards include the granularity—detailed regional tables, buyer‑type cohorts and scenario outputs—that executives need to underwrite 2026 plans with confidence. Consider this article an evidence‑based compass, not the map itself.
Competitive landscape — who’s moving and what it means
The market is anchored by a small group of global incumbents and national export credit agencies, each pursuing different strategic vectors:
- Allianz Trade (Paris) continues to consolidate its thought leadership and client advisory role; its 2025 Sustainability Handbook and 2026 updates signal a pivot toward climate‑aware underwriting and sustainability‑linked solutions.
- Atradius (Amsterdam) is executing a geographic expansion and digital insight playbook — highlighted by a new DIFC hub in Dubai and regular risk mapping releases which position it to capture trade corridors affected by energy and infrastructure flows.
- Coface (Paris) reported strong 2025 results and solid capital metrics, reinforcing that disciplined underwriting and efficient claims management remain viable vectors for shareholder value.
- State‑backed players such as China Export & Credit Insurance Corporation (Sinosure) and agencies like Export Development Canada (EDC) continue to shape capacity, particularly around large export and political risk mandates.
Recent developments through mid‑2026 emphasize two points: incumbents are strengthening advisory capabilities and distribution reach, and state players remain decisive in underwriting large cross‑border exposures. For challengers, the openings are in data‑driven risk selection, modular product design for SMEs, and services that tie credit insurance more directly to receivables finance and supply‑chain resilience.
Dynamics, regulatory signals and climate as a commercial variable
The operating environment for credit insurers is being reshaped by regulation, climate risk and technology policy:
- Regulation: The EU AI Act has categorized AI‑based credit underwriting and pricing as high‑risk activity. Insurers using algorithmic models must expand technical documentation, explainability and governance. Meanwhile, U.S. rule proposals for short‑term export credit instruments and IAIS observations on supply‑chain vulnerabilities are nudging supervisory scrutiny higher. These shifts materially affect model deployment, product approval lead times and compliance costs.
- Climate and macro shocks: Extreme heat and other climate‑driven events are becoming structural economic risks, changing counterparty profiles and concentration risk within portfolios. Europe’s exposure to such events has already affected underwriting approaches and claims patterns, creating demand for climate‑sensitive policy clauses and stress testing frameworks.
- Macro‑geopolitics: Trade agreements, energy projects and commodity cycles are driving pockets of heightened export credit demand — a trend reflected in the Berne Union’s business confidence indicators for early‑2026.
For 2026 strategy, this means: (a) investing in robust model governance and audit trails, (b) prioritizing climate scenario analysis against concentrated exposures, and (c) designing products that flex with regulatory timelines.
What’s in the PW Consulting report — practical, executable content
The study intentionally blends market intelligence with tools you can act on in 90–180 day sprints. Key deliverables include:
- Macro synthesis and demand scenarios (base, upside, downside) through 2032, with an integrated sensitivity engine to test rates, default assumptions and trade flow shocks.
- Competitive diagnostic and strategic playbook for incumbents, challengers and national agencies — including capability heatmaps for underwriting, claims, analytics and distribution.
- Regulatory impact assessment and compliance roadmap covering AI model governance, export credit rule changes and solvency considerations.
- Climate risk overlay: scenario templates, stress testing matrices and recommended policy language for climate‑linked exclusions, extensions and mitigation incentives.
- Commercial tools — pricing benchmarking frameworks, channel economics templates and M&A scorecards — bundled with an Excel dashboard to test portfolio-level outcomes.
- Implementation blueprints: 90‑, 180‑ and 365‑day action plans for product launches, tech pilots and regulatory readiness with role‑level responsibilities.
We deliberately withhold detailed regional and application tables in this preview; those granular datasets and the interactive dashboard are available in the full report and are essential for underwriting thresholds and capex allocations.
Strategic implications and recommended 2026 moves
Based on the study’s synthesis of market growth, competitive shifts and regulatory trends, PW Consulting recommends that market participants prioritize the following actions in 2026:
- Operationalize “compliance by design” for AI underwriting — embed documentation, explainability and human oversight into models before scaling production.
- Launch targeted modular products for mid‑market exporters that link credit cover to receivables finance, enabling velocity and tighter loss experience monitoring.
- Invest in climate‑aware underwriting: implement scenario testing on portfolios and introduce product features that reward mitigation (e.g., supply‑chain diversification incentives).
- Pursue selective inorganic deals to acquire data assets or analytics teams rather than broad market consolidation — CR metrics suggest scale helps, but data advantage is a durable differentiator.
- Strengthen distribution partnerships in high‑growth corridors and test digital direct channels with limited, measurable pilots to refine pricing elastics.
How to use this preview — next steps for leaders
This article is intended to accelerate 2026 planning cycles. If you are setting budgets, launching a product or evaluating a portfolio, use the following staging approach:
- Immediate (0–90 days): Run the report’s quick‑scan diagnostic on your portfolio to identify climate and concentration hotspots; initiate AI model compliance gap analysis.
- Near term (90–180 days): Execute a pilot modular product or distribution test; validate assumptions against the report’s scenario engine.
- Medium term (180–365 days): Formalize governance changes, deploy enhanced data pipelines, and scope any M&A or partnership options identified during pilots.
Closing — the strategic premium of granular intelligence
The market’s growth trajectory to 2032 and the moderate concentration structure create a window for profitable expansion in 2026, but the path is non‑linear. Executives who combine the macro view with micro‑level segmentation, regulatory readiness and climate scenario work will capture disproportionate value. PW Consulting’s full Credit Insurance Market report provides the segmented datasets, competitor playbooks and executable tools required to convert the 6.0% CAGR narrative into concrete underwriting, distribution and M&A outcomes. For clients prepared to move quickly in 2026, the report is designed as a tactical manual and strategy catalyst.
To access the full dataset, interactive dashboards and implementation templates, visit our Credit Insurance Market research page or contact your PW Consulting advisor for a briefing and live walkthrough.
For detailed analysis of this topic, please visit the official page: Credit Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


