



Category: IT & Electronics
PW Consulting Forecasts AI in Telecommunications to Surge to USD 59,193.3 Million by 2032
By PW Consulting, 2026-07-02
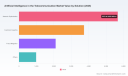
Artificial Intelligence in the Telecommunication Market — Strategic Outlook for 2026
Executive preview
PW Consulting’s latest market research, "Artificial Intelligence In The Telecommunication Market," serves as a strategic primer for executives planning investments and operational transformations in 2026. The global market has moved from an early-stage adoption curve into a phase of rapid commercialisation: total market value advanced from roughly USD 4.1 billion in 2020 to about USD 12.5 billion in our base year (2025), and under our scenarios is projected to exceed USD 59 billion by 2032. That trajectory implies a compound annual growth rate of approximately 24.85% across the forecast period. For senior leaders, these headline metrics are a signal — AI is no longer an experimental add-on for telcos; it is a foundational capability that will reshape network economics, customer propositions, and competitive boundaries.
Artificial Intelligence In The Telecommunication Market
Why this report matters for 2026 decision-making
-
Strategic timing: The confluence of mature model infrastructure, GPU-accelerated edge compute and operator-grade orchestration has turned pilot projects into enterprise deployments. Decision windows in 2026 favor organizations that can operationalize AI with disciplined governance, measurable ROI and scalable architecture.
Artificial Intelligence In The Telecommunication Market -
Capital and operational pressures: The energy and infrastructure context is a central constraint. Data center electricity consumption is rising fast globally, and US regional markets are already showing material wholesale price volatility tied in part to AI workloads. Policymakers and utilities are reacting with new regulations and cost allocation frameworks. Our report models how energy, siting, and grid-policy risks feed directly into vendor selection, total cost of ownership (TCO), and timeline decisions.
Artificial Intelligence In The Telecommunication Market -
Ecosystem realignment: Traditional network vendors, cloud hyperscalers and major operators are rapidly converging into partnership ecosystems. Recent industry moves — from hyperscaler-led AI-for-telco reports and live AI-RAN trials to vendor announcements of AI-native cores and AI-RAN strategies — underline that strategic differentiation will require selective partnerships, IP ownership decisions and regulatory-aware supply chains.
What’s in the report — practical, deployable intelligence
We designed this report as an operational playbook, not just market narrative. Key practical deliverables include:
-
Decision frameworks: A set of investment prioritisation tools that map use-case lift to implementation complexity, time-to-value, and energy sensitivity, enabling portfolio sequencing that protects margins while accelerating impact.
-
TCO and scenario models: Spreadsheet-ready TCO models that incorporate compute, energy, licensing and compliance costs under multiple regulatory and electricity-price scenarios. These models let CFOs and CTOs stress-test capital allocations and evaluate outsourcing vs. in-house options.
-
Pilot-to-scale blueprints: End-to-end deployment templates for common telco AI initiatives — from network optimisation and customer analytics to fraud mitigation and edge intelligence — including success metrics, governance checklists and vendor evaluation criteria.
-
Vendor due diligence playbook: A vendor scoring matrix that captures technical fit, integration risk, data sovereignty posture and commercial leverage — calibrated for negotiations in an environment where hyperscalers and OEMs pursue both competition and collaboration.
-
Organisational readiness guides: Role-maps, reskilling roadmaps and operating model adjustments that accelerate the transition to AI-native network operations while protecting service continuity and regulatory compliance.
-
Risk and regulatory mapping: A concise legal/regulatory heatmap and mitigation measures covering energy regulation, data-center siting, and emerging liability questions for autonomous network agents.
Competitive landscape — players, momentum and implications
The market structure is evolving rapidly. Top suppliers and platforms are redefining their roles, from infrastructure vendors to systems integrators and cloud providers. Our competitive assessment synthesises capability, market traction and strategic intent across leading firms:
-
NVIDIA Corporation (Santa Clara): Leading provider of GPU-accelerated compute and telco-tailored AI architectures. Recent industry activity includes a sector-focused State of AI report and partnerships advancing AI-RAN live trials. NVIDIA’s stack is increasingly central to operator and vendor proofs-of-concept that demand high-performance model inference at the edge.
-
Ericsson AB (Stockholm): Positioning as an AI-native network builder with a focus on AI-powered RAN and autonomous operations. Recent strategic collaborations with major operators signal deep ambitions in 5G/6G network autonomy.
-
Huawei Technologies (Shenzhen): Promoter of full-stack AI Core Network capabilities and agent-based autonomous network concepts. Their early productisation of AI-driven core components sets a benchmark for integrated vendor offerings in markets where they compete.
-
Nokia Corporation (Espoo): Emphasising software-defined, GPU-accelerated AI-RAN strategies and analytics platforms; Nokia’s approach highlights the role of software ecosystems and partner integrations in commercial rollouts.
-
IBM, Microsoft, Cisco and major operators (e.g., AT&T): Each brings complementary strengths — enterprise AI platforms, cloud scale and networking hardware — that influence operator choices between private, hybrid and public cloud-based architectures.
Market concentration indicators are instructive: the top three vendors account for a meaningful minority of market revenues, and the top five capture just over half of total market activity. This structure suggests both consolidation pressures and persistent opportunities for specialised entrants and regional champions — particularly for firms that can demonstrably reduce operational cost and energy intensity.
Industry dynamics that will shape 2026 decisions
-
Energy-policy friction: Initiatives that shift the cost of new generation and transmission onto hyperscalers and large consumers are changing commercial negotiations. Operators and vendors must bake these contingencies into contracts and site-selection models.
-
Regulatory differentiation: Subnational legislative activity and new federal-level pledges are producing a patchwork of obligations around energy, water and siting. That makes regional deployment strategies more complex and increases the value of flexible, interoperable architectures.
-
Operational acceleration: The shift from descriptive analytics to agentic and autonomous AI in network operations introduces new governance, explainability and resilience requirements. Pilots that ignore these operational elements often fail to scale; those that prioritise safety and observability succeed.
Actionable priorities for executives in 2026
Based on our analysis, PW Consulting recommends the following near-term priorities for telco and vendor leaders:
-
Sequence investments: Prioritise high-impact, low-friction use cases to build capabilities and internal credibility before expanding into agentic network autonomy. Use our investment prioritisation tool to balance time-to-value against operational risk.
-
Make energy a first-order procurement consideration: Negotiate power and capacity clauses, explore committed off-take or on-site generation models, and require vendors to share standardized metrics for energy efficiency and carbon intensity.
-
Adopt hybrid edge-cloud architectures: Preserve vendor flexibility by insisting on open interfaces and modular orchestration to avoid lock-in while enabling low-latency services.
-
Build AI-ops capability: Invest in observability, model governance, and incident playbooks now to prevent costly outages and regulatory scrutiny as autonomy scales.
-
Structurally manage partnerships: Adopt a portfolio approach to partnerships — combine hyperscaler compute, specialised AI telco vendors and systems integrators — with clear IP, data and liability split arrangements.
-
Prepare workforce transformations: Launch targeted reskilling for network engineers, data scientists and product managers; link incentives to operating metrics derived from AI deployments.
How PW Consulting’s report supports your 2026 roadmap
This release is intentionally a strategic “trailer”: it demonstrates the depth of our analysis and the practical utility of our models without publishing the granular region and application-level splits that many teams need to protect competitive strategy. Subscribers to the full report receive:
-
Complete regional and segment-level datasets and forecasts (with scenario toggles);
-
Vendor scorecards and integration risk assessments tied to procurement playbooks;
-
Downloadable TCO and scenario modelling workbooks that incorporate energy-price runways and regulatory shocks;
-
Case studies and deployment artifacts from recent operator pilots and vendor live trials.
Closing perspective
AI in telecommunications is entering a critical phase where strategic choices made in 2026 will determine which players capture disproportionate upside from network automation, new service monetisation and cost deflation. The market’s rapid growth and the evolving vendor landscape create both urgency and opportunity. PW Consulting’s report equips senior leaders with the frameworks, models and operational templates necessary to move from experimentation to durable advantage — while recognising that local energy, regulatory and partnership realities will shape the shape and pace of that transition.
To access the full analysis, models and vendor intelligence that underpin these findings, visit PW Consulting’s report centre and download "Artificial Intelligence In The Telecommunication Market" for the complete dataset and playbooks designed for 2026 strategic planning.
For detailed analysis of this topic, please visit the official page: Artificial Intelligence In The Telecommunication Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AC Capacitors Market to Reach USD 3,970.16 Million by 2032, Expanding at a 4.85% CAGR
By PW Consulting, 2026-07-02
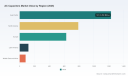
AC Capacitors Market 2026: Strategic Imperatives for Corporate Decision‑Makers
Executive snapshot
As we enter 2026, the AC capacitors market stands at an inflection point. Our PW Consulting market model, anchored on a 2025 baseline and a detailed 2020–2025 historical reconstruction, projects steady expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 4.85%. That trajectory takes the industry from a multi‑billion‑dollar base in 2025 to nearly USD 4.0 billion by 2032. For executives tasked with product strategy, supply‑chain resilience, and M&A prioritization, this creates a window for disciplined investment while exposing new operational risks that require active mitigation.
Ac Capacitors Market
Why 2026 is a tipping point
-
Demand normalization after component shortages: The market’s post‑pandemic recovery is giving way to more predictable demand patterns, but supply‑side frictions — particularly in polymer and foil feedstocks — are reshaping sourcing economics.
Ac Capacitors Market -
Technology consolidation across applications: Incremental improvements in film dielectrics, safety classifications, and packaging are creating product tiers that meaningfully affect BOM cost, certification timelines, and customer value propositions.
Ac Capacitors Market -
Capital allocation decision windows: With a mid‑single‑digit CAGR, companies must choose between share‑gaining investments (capacity, product development) and margin protection (vertical integration, hedging) — choices that will determine competitive positioning over the next business cycle.
Market trajectory: what the numbers tell us
Our scenario framework synthesizes market activity from 2020 through 2025 and projects forward to 2032. The market expanded from roughly USD 2.25 billion in 2020 to an estimated USD 2.85 billion in 2025, and under our base case grows to just under USD 4.0 billion by 2032. This path reflects a balance between continued electrification of end markets (HVAC, industrial drives, power electronics), incremental product upgrades, and periods of cyclic raw‑material pressure. The 4.85% CAGR embedded in the report is conservative relative to high‑growth electrification narratives, deliberately calibrated to account for substitution risks and raw‑material volatility.
Supply‑side dynamics that will shape 2026 decisions
-
Raw material inflation and availability: Recent industry intelligence indicates rising aluminum foil costs in key Asian markets and constrained availability of high‑purity foils. At the same time, polypropylene film — a core dielectric for many AC film capacitors — faces capacity tightness due to competing demand from packaging and electric vehicle applications. These forces are exerting upward pressure on input costs and compressing manufacturer margins unless offset by price adjustments or design optimization.
-
Extended lead times: Average delivery windows for capacitor technologies stretched to approximately 19 weeks as of late 2025. For procurement and production planners, this implies a shift from just‑in‑time toward buffer and tiered sourcing strategies, particularly for long‑lead assemblies and safety‑critical SKUs.
-
Certification and safety trajectories: Evolving safety standards are prompting new product introductions with higher voltage and safety ratings. The pace of regulatory alignment across geographies will affect time‑to‑market and qualification costs for global OEMs.
Competitive landscape — who moves the market
The AC capacitors industry is neither a fragmented commodity arena nor a tightly concentrated oligopoly. Our concentration analysis indicates a market where a handful of established firms have sizeable influence, while many regional and specialty manufacturers continue to serve niche or high‑reliability applications. This balance creates both entry points for challengers with differentiated technology and defensive positions for incumbents leveraging scale and service networks.
-
Barker Microfarads (BMI) (Hillsville, VA) remains a recognized supplier for high‑reliability motor start/run film capacitors focused on HVAC and refrigeration. Their product depth in the motor segment aligns with aftermarket and replacement demand cycles that are generally more stable than new OEM ramp ups.
-
AmRad Engineering (USA) continues to differentiate on domestically manufactured AC motor run capacitors, targeting customers that prioritize local supply and long life ratings — a persistent value proposition amid extended lead times and procurement risk aversion.
-
Cornell Dubilier Electronics (CDE) (Liberty, SC) maintains a broad portfolio spanning motor run and power film families. Recent product releases oriented to high‑temperature DC link applications indicate cross‑pollination of technologies between AC and power electronics use cases — a trend we see accelerating.
-
TDK (EPCOS) (Japan/Germany) leverages global R&D to advance safety‑rated capacitors; their recent extensions to higher AC voltage X2 safety film portfolios reflect strategic focus on industrial and automotive requirements for compact, robust components.
-
Vishay Intertechnology (Malvern, PA) combines scale manufacturing with a wide voltage range offering, enabling it to service high‑voltage industrial segments where reliability and certification are gating factors.
Recent product launches and platform extensions from major vendors illustrate how innovation and standard‑compliance playbooks are evolving. For example, TDK’s early‑2026 expansion of higher‑voltage X2 series capacitors and Cornell Dubilier’s 2025 high‑temperature DC link introduction both signal supplier moves to capture adjacent power‑electronics demand without materially changing the market’s structural dynamics.
Report coverage — actionable intelligence without the filler
PW Consulting’s AC Capacitors Market report is structured to be operationally useful for strategy, procurement, and product teams. We deliberately focus on decision‑grade analysis rather than raw tables. Key components include:
-
Market sizing and trend analysis with historical reconstruction (2020–2025) and base‑case forecasts to 2032, including sensitivity scenarios reflecting raw‑material shocks and accelerated electrification.
-
Demand drivers by end market and technology pathway, emphasizing functional substitutability and lifetime cost tradeoffs.
-
Supply‑chain mapping and supplier tier analytics, highlighting chokepoints in foil and polymer supplies and quantifying lead‑time exposure.
-
Vendor benchmarking and capability matrices for global and regional manufacturers, incorporating product portfolios, certification competencies, and manufacturing footprints.
-
Risk and opportunity playbooks for procurement (including hedging and dual‑sourcing), product management (design for cost and certification), and corporate development (bolt‑on targets and vertical integration).
-
Scenario planning tools with actionable triggers: when to accelerate capacity, when to adopt alternate dielectrics, and when to pursue alliance or captive supply strategies.
Note: While the report provides detailed segmentation tables and regional/application breakdowns, this release intentionally omits those granular splits. The full dataset — including segment models and supplier lists — is available through the report portal for subscribers and purchasers.
Strategic recommendations for 2026 corporate planning
-
Reconcile product roadmaps with realistic supply assumptions. Incorporate lead‑time and material‑cost scenarios into SKU rationalization and qualification pipelines to avoid prolonged launch delays.
-
Prioritize supplier diversification and dual‑sourcing in polypropylene and high‑purity aluminum foil. Consider long‑term offtake or strategic investments with polymer producers to anchor capacity.
-
Adopt modular certification strategies. Where possible, design capacitor modules that minimize requalification costs across geographies — this reduces time‑to‑revenue for global OEM programs.
-
Target selective vertical integration only when margin upside and risk reduction are quantifiable. For many players, nearer‑term returns will come from process optimization and strategic sourcing rather than heavy upstream CAPEX.
-
Scan the M&A landscape for complementary capabilities: specialist high‑reliability film suppliers, polymer coating innovators, and regional assembly hubs that can accelerate customer intimacy and reduce logistical risk.
-
Operationalize a pricing cadence. With periodic raw‑material cost shocks expected, develop transparent indexation clauses with key customers to maintain margin integrity while preserving competitiveness.
Implications for procurement, product, and M&A teams
Procurement leaders should move from transactional buying to strategic supplier partnerships, incorporating inventory and capacity options into contracting. Product teams ought to balance dielectric performance against manufacturability and certification cost; incremental dielectric improvements can unlock durability premiums in critical applications. Corporate development groups will find the most compelling value in targets that offer either proprietary dielectrics, localized manufacturing that shortens lead times, or access to alternative polymer feedstocks.
How PW Consulting’s report supports 2026 decisions
The AC Capacitors Market report is designed as an executable toolkit for 12–24 month planning cycles. It combines a defensible market baseline with actionable playbooks, supplier heatmaps, and scenario triggers calibrated to common board‑level decision points. We intentionally present the analysis in a way that enables rapid translation into procurement RFPs, product spec updates, and M&A screening criteria — without requiring clients to wade through raw segmentation dumps in their first pass.
Next steps
For executives preparing budgets and strategic plans in 2026, the central questions are clear: how much to invest in growth versus protection, how to structure supplier relationships in the face of constrained materials, and which product moves will preserve margin while meeting evolving regulatory and application needs. PW Consulting’s full report provides the detailed tables, regional and application splits, vendor scorecards, and model downloads required to answer those questions decisively. Access to the full dataset and custom briefing packages is available through our report portal.
For detailed analysis of this topic, please visit the official page: Ac Capacitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: GaN Wafers Market Set to Surge at 18.5% CAGR During 2026–2032PW Consulting Forecast: Platinum–Rhenium Catalysts Market Set to Hit USD 688.9 Million by 2032
By PW Consulting, 2026-07-02
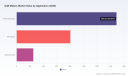
Gan Wafers Market 2026 Strategic Outlook: Why PW Consulting’s New Report Is Essential for Executive Decision-Making
PW Consulting’s latest Gan Wafers Market research report—anchored on a 2025 base year and projecting through 2032—arrives at a decisive moment for semiconductor executives, investors, and procurement leaders. The market has already expanded rapidly, rising from roughly USD 1.05 billion in 2020 to USD 2.55 billion in 2025. Our model projects continued acceleration at a compounded annual growth rate (CAGR) of 18.5% during 2026–2032, resulting in a multi-fold increase in absolute market value by the end of the forecast window. This trajectory, paired with concentration metrics that point to a market where the top three and top five players control a meaningful share, creates both immediate operational risk and strategic opportunity for stakeholders planning activity in 2026.
Gan Wafers Market
What the report delivers: practical, decision-ready intelligence
- Proprietary market model and downloadable financial workbook—scenario-ready and stress-tested—enabling CFOs and strategy teams to quantify revenue and margin sensitivity under alternative growth, price, and material-cost paths.
- Actionable supply-chain map that traces substrate-to-epitaxy flows and identifies chokepoints—material suppliers, specialty equipment, and capacity constraints—allowing procurement teams to prioritize mitigation levers.
- Technology maturity matrix that compares substrate approaches (bulk GaN, GaN-on-Si, GaN-on-SiC, and engineered substrates) on yield, cost-per-wafer, and scale-up risk—designed to inform R&D roadmaps and capex allocation.
- Competitive benchmarking and risk heatmaps for manufacturing scale-up (including 200–300 mm transitions), foundry service positioning, and IP ownership—useful for M&A screening and partner selection.
- Regulatory and raw-material scenario playbooks built around export-control shocks and price volatility—practical templates for supply agreements, hedging, and inventory strategies.
- Commercial go-to-market playbooks and segment adoption case studies that translate technical choices into demand forecasts for power electronics, RF, and optoelectronics—designed for business-unit planning.
We intentionally designed the report to be more than a descriptive survey: every chapter concludes with clearly prioritized recommendation sets and “if-then” execution templates so teams can move from insight to action within sixty to ninety days.
Gan Wafers Market
Why this matters for 2026 decision cycles
Three simultaneous forces are reshaping strategic choices in 2026. First, the market’s growth rate (18.5% CAGR in our baseline forecast) implies sizable near-term revenue opportunities, but this growth is not evenly distributed across technologies or supply chains. Second, market concentration—where leading groups command a significant portion of capacity—creates windows for both consolidation and targeted niche plays. Third, material- and policy-driven volatility (described below) injects supply-side risk that directly impacts commodity-intensive manufacturing economics.
Gan Wafers Market
For executives, this confluence implies that 2026 is the year to make irreversible bets: converting piloted processes to high-volume manufacturing, committing to substrate partnerships, or locking in long-term material contracts. Delay can mean losing preferential access to capacity or facing sharply higher input costs; premature commitment risks technology lock-in. The report’s scenario engine and decision-tree outputs are expressly tailored to help leaders pick the right moment and scale for each bet.
Competitive landscape: who matters and why
- Eta Research Ltd. (Shanghai, China; https://www.etaresearch.com/)—a bulk GaN specialist using an HVPE process that emphasizes free-standing wafers. Its product mix, including UID and semi-insulating variants, positions it as a materials-lead supplier for laser diodes, power, and RF device manufacturers. Strategic implication: forms a logical supply partner for companies seeking shorter lead-times on bulk substrates and flexible doping options.
- Sanan Optoelectronics / Sanan Semiconductor (China; https://www.sanan-semiconductor.com/)—large-scale epi and foundry capabilities with aggressive capacity expansion plans. Strategic implication: attractive foundry partner for OEMs wanting scale and integrated epi services; rival for vertically integrated players looking to protect downstream margins.
- Sumitomo Electric Industries (Japan; https://global-sei.com/)—focus on vapor-phase epitaxy and larger-diameter GaN-on-GaN wafers, plus materials innovation (e.g., performance-oriented substrates). Strategic implication: high-performance and high-reliability customers should track Sumitomo for premium substrate roadmaps and co-development opportunities.
- NGK Insulators (Japan; https://www.ngk-insulators.com/)—proprietary liquid-phase growth yielding low-dislocation substrates. Strategic implication: RF and optical-device makers prioritizing crystalline quality will find NGK’s offering strategically valuable for yield and performance gains.
- IQE plc (Cardiff, UK; https://www.iqep.com/)—broad epitaxy portfolio across substrates and an active partnership approach, exemplified by recent joint development activity. Strategic implication: firms seeking a partner for device platform development (e.g., 650V power devices) should evaluate IQE-led collaborations.
- Wolfspeed, Inc. (Durham, NC, USA; https://www.wolfspeed.com/)—established in GaN-on-SiC and RF power devices, with a strong device-manufacturing footprint. Strategic implication: incumbency in high-performance RF and power segments gives Wolfspeed leverage in setting technology and sourcing norms.
Across this competitive set, the pattern is clear: growth will favor organizations that combine material competence with foundry services or device-level capabilities. Partnerships and joint development agreements will be the fastest path to de-risking scale-up and entering high-value applications.
Recent developments and the policy-shock playbook
Key industry developments illustrate both opportunity and vulnerability. In mid-2025 several milestone events signaled a technology inflection: a leading semiconductor firm announced progress toward scalable 300 mm GaN wafers with customer samples slated for late 2025; another supplier demonstrated GaN-HEMTs on polycrystalline diamond substrates; and an epitaxy specialist entered a joint development arrangement to accelerate a 650V GaN power platform targeting automotive and data-center customers. These technical advances lower the cost-per-watt threshold for GaN adoption and expand addressable end-markets.
At the same time, raw-material and policy noise has become a persistent strategic input. Recent changes in gallium export policy and observed unit-price spikes (industry estimates show substantial YoY increases) have exposed a supply chain vulnerability: a handful of primary producers account for the vast majority of global mined gallium. For markets or regions dependent on imports, that concentration translates directly into procurement risk and margin pressure.
Our report therefore includes a “policy-shock playbook” with practical measures: multi-sourcing matrices, conditional inventory triggers, forward-contract templates with pass-through clauses, and a capital-program checklist for onshoring or recycling investments. These are built as executable items, not high-level suggestions.
How to use this report in practice (90‑day, 12‑month, and 36‑month roadmaps)
- 90 days: Run the supplied scenario model against your product roadmap—test price and material shocks, and produce a procurement action plan. Begin supplier due diligence for at least two non-correlated sources.
- 12 months: Lock in tiered supply agreements and evaluate one strategic equity or JDA with a substrate/epitaxy partner. For device OEMs, initiate pilot runs on alternative substrate options mapped in the report.
- 36 months: Execute capacity expansions or foundry agreements aligned to the highest-return segments identified in our scenario analysis; consider vertical integration where margins and market control justify capex.
Why PW Consulting’s approach is different
Many studies describe the Gan wafers market; few provide the executable link between wafer physics, supply-chain constraints, and boardroom capital decisions. Our report blends an engineer’s technical rigor with a strategist’s focus on implementable choices—complete with downloadable models, supplier scorecards, and playbook templates. Importantly, while this press summary outlines major themes and firm-level positioning, the full report contains the granular segmentation, supplier-level scoring, and interactive financial models that executives need to finalize 2026 budgets and partnership commitments.
Next steps
If your team is preparing capital requests, negotiating multi-year supply contracts, evaluating M&A targets, or scoping a production technology shift in 2026, PW Consulting’s Gan Wafers Market report should be your working document. The public summary demonstrates our analytic depth; the full report provides the confidential segmentation, supplier scores, and scenario-ready models required to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Gan Wafers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Broadband Router Market Poised for 7.15% CAGR Through 2032, Fueled by Wi‑Fi 6/6E Momentum
By PW Consulting, 2026-07-02
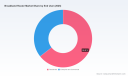
Broadband Router Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
Executive snapshot
PW Consulting’s Broadband Router Market report (base year 2025) frames an inflection point for vendors, service providers, enterprise buyers and policymakers. The global market reached USD 22,500 Million in 2025 and is forecast to expand at a 7.15% compound annual growth rate over the 2026–2032 forecast window, reaching approximately USD 36,486 Million by 2032. That steady, above‑category growth masks important structural shifts — from connectivity layer transformation to geopolitical supply‑chain reconfiguration and regulatory discontinuities — that will determine winners and losers through 2026 and beyond.
Broadband Router Market
Why this report matters for 2026 decision-making
-
Timing: 2026 is a breakpoint year. Infrastructure deployments (fiber and fixed wireless), Wi‑generation platform transitions, and updated regulatory treatments are converging to change buying criteria and procurement risk profiles.
Broadband Router Market -
Actionability: The report was designed as a strategic playbook — blending market-sizing, scenario economics, vendor scorecards, and go‑to‑market tactics — so C‑suite and commercial teams can move from insight to execution within quarters, not years.
Broadband Router Market -
Risk calibration: We quantify macro trajectories and provide an operational risk matrix that ties policy moves and supplier sourcing to revenue and margin outcomes for both OEMs and service providers.
Market trajectory and its strategic implications
Our baseline forecast assumes the broadband router market will grow from a 2025 base of USD 22.5B to roughly USD 24.1B in 2026 and continue on a path to USD 36.5B by 2032. That trajectory reflects sustained demand for higher throughput and smarter edge functionality — driven by multi‑gig residential broadband, increased enterprise WAN consolidation, and the penetration of Wi‑generation upgrades in both consumer and commercial product lines.
Strategically, three implications stand out for 2026 planning:
-
Product mix and upgrade cadence will dominate margin profiles. Vendors that can monetise software and managed services layered on multi‑gig hardware will sustain higher ASPs and recurring revenue streams.
-
Supply‑chain localization and compliance will not be optional. Regulatory disruptions and procurement policies will create regional windows of advantage for suppliers with TAA‑compliant, locally‑manufactured or approved product lines.
-
Channel transformation: ISPs and systems integrators will act less as distribution conduits and more as demand aggregators and service platforms; vendors must design OEM and channel programs that align incentives around subscriber retention and value‑added services.
Competitive landscape — what incumbents and challengers must consider
The broadband router market is moderately concentrated: the top three vendors account for roughly 35.4% of market revenue, and the top five account for approximately 48.2%. This structure produces persistent competitive pressure among global incumbents while leaving room for focused specialists to carve profitable niches.
-
Cisco Systems, Inc. — With mature enterprise and service provider portfolios and growing cloud‑native routing offerings, Cisco is positioned to capture enterprise WAN modernization spend and service provider migration to virtualized access. Strategic priority: accelerate cloud subscription models and partner plays for managed broadband services.
-
TP‑Link — A volume leader in consumer and SOHO, TP‑Link’s product breadth and aggressive pricing give it scale in Wi‑generation rollouts. Strategic priority: protect margins by upselling higher‑tier mesh and software subscriptions while addressing compliance pathways for regulated markets.
-
NETGEAR — Strong consumer and prosumer brand recognition and a focus on Wi‑7 mesh systems position NETGEAR to lead premium home segments. Strategic priority: use brand and channel strength to capture service bundling opportunities with ISPs and maintain supply exemptions where regulation constrains competitors.
-
ASUS, D‑Link, Belkin/Linksys — These vendors compete on product differentiation (gaming, AI‑tuned home routers, SMB propositions). Strategic priority: deepen vertical use‑case features (QoS, security, latency management) and pursue partnerships with streaming, gaming, and smart‑home ecosystems.
-
Huawei — Continues to offer advanced gateways for fiber and fixed wireless but faces persistent policy and market access challenges in several jurisdictions. Strategic priority: focus on regions with open procurement regimes and on software/cloud offerings that are decoupled from geo‑political constraints.
-
Ubiquiti, Amazon (eero) — Ubiquiti’s developer/SMB ethos and eero’s seamless whole‑home experience reflect divergent strategies: DIY scale vs. subscription convenience. Strategic priority: Ubiquiti must translate platform stickiness into managed services; eero should expand operator partnerships where regulatory exemptions and channel access are available.
Recent product and regulatory events sharpen these strategic imperatives. In March 2026, the FCC updated its Covered List to include foreign‑produced consumer‑grade routers, effectively banning new devices without conditional approval; limited exemptions were granted to a small set of manufacturers. That move, combined with court decisions that have altered the federal regulatory framework for broadband classification, creates a bifurcated market where procurement decisions now weigh product performance against approval and manufacturing provenance.
Regulatory and infrastructure environment — a new operating rhythm
Two concurrent infrastructure dynamics are particularly relevant to 2026 strategy. First, fiber availability has moved into the majority of U.S. homes, shifting the competitive battleground to multi‑gig residential equipment and value‑added services. Second, the commissioning of additional mid‑band spectrum (notably planned Upper C‑band auctions) and priority for fixed wireless in policy agendas will accelerate adoption of 5G fixed wireless access in under‑served geographies.
These shifts are occurring against a backdrop of rising deployment costs (including make‑ready and permitting) and adjustments to public funding programs that emphasize technology neutrality and cost‑effectiveness. For vendors and integrators, this means placing bets on two fronts: higher ASP, higher‑value multi‑gig offerings in dense markets; and cost‑competitive, ruggedized units for rapid fixed wireless or municipal deployments.
Practical content of the PW Consulting report — what you get
We designed this study to be operationally prescriptive. Key deliverables include:
-
Market sizing and scenarios: Base, constrained, and accelerated demand paths through 2032, with sensitivity to policy shocks and supply disruptions.
-
Commercial playbooks: Go‑to‑market models for consumer, SOHO, SMB and enterprise channels; partner incentive templates; and ARPA/CLTV optimization heuristics.
-
Vendor scorecards: Comparative assessments across product, software, service, channel coverage and regulatory posture for major OEMs — enabling quick benchmarking and M&A target screening.
-
Regulatory risk matrix: Jurisdictional exposure maps, approval timelines, and mitigation options (design changes, on‑shoring, compliance certifications).
-
Supply‑chain resilience playbook: Component concentration analysis, alternative sourcing routes, and cost‑impact models for near‑term procurement decisions.
-
Product and roadmap guidance: Prioritized features for Wi‑7 and future Wi‑generations, edge compute integration points, and software monetization pathways.
-
M&A and partnership playbook: Value creation levers for strategic acquisitions and JV structures tailored to capture synergies across hardware, cloud and services.
What to do next — seven tactical moves for 2026
-
Accelerate product compliance and local manufacturing where procurement risk is material; obtain necessary approvals ahead of bidding cycles.
-
Shift commercial models from one‑time hardware sales to bundled subscriptions and managed services that increase stickiness and life‑time value.
-
Prioritise Wi‑7 and multi‑gig product roadmaps for premium residential and enterprise segments, with simplified SKUs for large operator rollouts.
-
Negotiate strategic partnerships with ISPs and systems integrators to co‑design subscriber experiences and share recurring revenue.
-
Build a contingency supply chain with dual‑sourcing and critical‑component inventories to mitigate regulatory and geopolitically driven shocks.
-
Use targeted M&A to acquire software stacks or field‑service capabilities instead of only pursuing volume scale.
-
Adopt an outcomes‑based procurement approach for public‑fund projects that quantifies life‑cycle costs, service quality and upgrade paths.
Closing — the trailer invitation
PW Consulting’s Broadband Router Market study equips leaders with the market context, competitive insight, and executable playbooks needed to make high‑stakes 2026 decisions. This release intentionally highlights strategic findings and operational frameworks while withholding granular region, technology and end‑use segment tables and vendor market shares to preserve the full, actionable intelligence available in the complete report.
For boards, product chiefs, commercial leaders and procurement teams seeking to convert the market’s projected USD 22.5B base and 7.15% CAGR into defensible growth and margin plans, our report provides the next‑quarter implementation roadmap. Access details and the full dataset are available via PW Consulting’s report page.
For detailed analysis of this topic, please visit the official page: Broadband Router Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Workday HCM Consulting Market Poised to Reach USD 6,156 Million by 2032 on 8.85% CAGR, Led by North America’s $1.8B Share
By PW Consulting, 2026-07-02
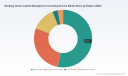
Workday Human Capital Management Consulting Services Market — 2026 Strategic Imperatives (PW Consulting Spotlight)
Executive snapshot
Organizations making decisions about Workday Human Capital Management (HCM) in 2026 face a market that is both expanding and maturing. PW Consulting’s latest market study — with a base year of 2025 and a forecast horizon through 2032 — models the global Workday HCM consulting services market growing at a compound annual growth rate (CAGR) of 8.85%. The market size, measured in USD (Million), moves from approximately 2,880 in 2023 and 3,130 in 2024 to 3,400 in 2025, with projected growth to roughly 3,700.9 in 2026 and beyond to an estimated 6,155.97 by 2032. These headline numbers signal continued investment momentum across implementation, managed services, and optimization practices, even as customers demand tighter alignment between HR technology and enterprise outcomes.
Workday Human Capital Management Consulting Service Market
- Growth at an ~8.85% CAGR through 2032 implies that HCM consulting will remain strategically material to CIOs, CHROs and procurement teams.
- Acceleration is driven by expanded Workday product scope (HR, Recruiting, Financials integrations, and new AI-enabled capabilities) and by regulatory and privacy dynamics requiring enhanced professional services.
- Decision-makers must weigh vendor scale, industry specialization, and IP-driven service models against rising labor costs and tighter compliance regimes.
Why this report matters for 2026 enterprise decisions
2026 is not a continuation of the old status quo — it is a pivot year in which legal frameworks, AI-infused product releases, and labor market pressures converge to change execution risk and buying patterns.
Workday Human Capital Management Consulting Service Market
- Regulatory complexity: Recent certifications and data privacy frameworks, together with a proliferation of state-level privacy laws and the EU’s AI Act classification for employment-related systems, mean that HCM implementations now carry higher compliance risk and require demonstrable privacy-by-design and AI-risk-management practices.
- Product innovation: Workday’s product cadence (including AI-enabled modules and workforce-skills features) creates both opportunity and integration complexity. Early adopters can capture measurable workforce productivity gains, but only if integration, governance, and change take precedence in the roadmap.
- Talent and delivery economics: Specialized Workday HCM advisory and delivery talent remains in tight supply. Firms must optimize sourcing models — blending large systems integrators (for scale and transformation) with boutique providers (for niche functional depth and managed services) — to control costs and maintain velocity.
What PW Consulting’s report delivers — practical intelligence for action
Our Workday HCM Consulting Service Market report is structured to be operationally useful to executives, program leads, and procurement teams. It intentionally balances strategic framing with hands-on tools while withholding the detailed segmentation tables in this public summary to preserve the report’s value as the source of record.
Workday Human Capital Management Consulting Service Market
- Decision frameworks: Vendor selection matrices mapped to business objectives (e.g., global rollouts, industry-specific requirements, or payroll consolidation) that help buyers prioritize capabilities and risk profiles.
- TCO and commercial models: Real-world approaches to modeling total cost of ownership across implementation, managed services, and multi-year optimization — including practical assumptions, escalation levers, and scenario analyses.
- Implementation playbooks: Phased roadmaps and governance checklists that translate product releases and regulatory obligations into sprint-ready workstreams for program managers.
- Service packaging and sourcing options: Comparative design for in-house delivery, co-managed models, and outsource arrangements, with negotiating heuristics to protect margin and future flexibility.
- Risk registers and compliance templates: Ready-to-use components for privacy impact assessments, AI governance checkpoints, and release management controls that align to jurisdictional variations.
- Vendor benchmarking and go-to-market signals: Qualitative profiles and capability maps of leading providers, supported by market intelligence on partnerships, go-to-market investments, and strategic motions.
To respect the “trailer” principle of this release, the detailed numerical segmentation, regional breakdowns, and company scoring tables that underpin these tools are available only in the full report and associated datasets.
Competitive landscape — how top providers are positioning in 2026
The competitive field spans global systems integrators, Big Four firms, specialist managed-service providers, and experienced advisory boutiques. Several observable themes shape supplier positioning:
- Scale and end-to-end transformation: Firms with global delivery networks and deep Workday alliances are packaging HCM services into larger transformation programs that combine HR, Finance, and technology modernization. These providers emphasize industrialized accelerators, international rollout experience, and integration toolkits.
- Managed services and optimization: Niche providers and JVMs (jobs-to-value-minded managed service firms) differentiate on continuous optimization and cost predictability — an attractive proposition for organizations that have moved beyond initial deployment to steady-state operations.
- Industry and functional specialization: Several consultancies leverage sector expertise (e.g., healthcare, higher education, logistics) to reduce time-to-value by pre-building templates and compliance controls specific to sectoral payrolls, union agreements, or credential tracking.
- Partnership and ecosystem plays: Strategic alliances and newly announced partnerships (including recent go-to-market agreements) accelerate customer acquisition and create differentiated joint offerings around AI-enabled HR services and industry-specific IP.
In sum, the vendor landscape is a mix of capability and choice. Buyers will face trade-offs between transactional price, delivery predictability, and specialty that are only resolvable with rigorous sourcing frameworks.
Recent market signals that reshape strategy
- Workday’s increasing partnership activity and product releases in early 2026 extend the platform’s capabilities for talent mapping and AI-infused HR workflows — expanding the potential scope of consulting engagements.
- Major consulting firms continue to publish case studies and pursue awards that reinforce their integrated transformation positioning; these signals should inform risk assessment for large, multi-year programs.
- Data privacy certifications and new regulatory enforcement in multiple jurisdictions are elevating the need for privacy and AI compliance expertise as standard deliverables in HCM programs.
Strategic implications and recommended actions for 2026
Executives and program leaders must translate market dynamics into unit-level actions. PW Consulting recommends a balanced set of measures to protect program outcomes and capture upside:
- Reframe procurement criteria: Move beyond lowest-cost proposals to include measurable compliance, AI governance capabilities, and run-the-business continuity. Incorporate scenario-based scoring for product roadmap alignment and data residency controls.
- Mandate compliance and AI controls in SOWs: Require suppliers to include privacy-by-design deliverables, model cards for algorithmic components, and periodic third-party audits tied to SLAs.
- Adopt hybrid sourcing: Combine a large partner for program orchestration with boutique vendors for niche modules and managed services to balance scale and specialized knowledge.
- Invest in internal capability uplift: Allocate budget for a small, in-house center of excellence that oversees release management, change adoption metrics, and vendor performance — reducing long-term reliance on external labor.
- Model multiple commercial scenarios: Use the report’s TCO templates to stress-test outcomes under different labor-cost inflation, release cadence, and compliance-cost trajectories.
- Operationalize adoption and ROI measurement: Define success metrics beyond go-live (e.g., time-to-hire improvements, payroll error reduction, compliance incident frequency) and tie vendor payments to measurable adoption milestones.
How to use this report in 2026
PW Consulting’s Workday HCM market study is designed as a working reference for board-level conversations, CHRO/CIO planning cycles, and procurement sourcing events in 2026. Use the report to:
- Shortlist vendors against your prioritized objectives and compliance constraints.
- Build defensible budgets informed by modeled TCO scenarios rather than vendor list prices alone.
- Establish governance artifacts (risk registers, AI review gates, privacy checklists) that can be embedded into program tickets and vendor SOWs.
Because the most actionable intelligence resides in the underlying segmentation, vendor scorecards, and financial models, those datasets and granular tables are available with the full report. If you are planning a Workday HCM program, procurement process, or transformation roadmap in 2026, that package provides the repeatable artifacts and negotiation playbooks needed to de-risk execution and maximize long-term value.
Closing perspective
Between a mid-decade acceleration in product capability, an evolving regulatory landscape, and persistent talent constraints, 2026 will separate the programs that realize measurable HR outcomes from those that underdeliver. PW Consulting’s analysis highlights where value is created — and where execution risk accumulates — allowing leaders to make informed, defensible choices. For practitioners seeking the underlying segmentation, vendor scoring, and downloadable playbooks, the full report is the source of record and the recommended next step.
For detailed analysis of this topic, please visit the official page: Workday Human Capital Management Consulting Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Special Airport Systems Market to Grow from USD 12.5 Billion in 2025 to USD 19.42 Billion by 2032 at a 6.5% CAGR
By PW Consulting, 2026-07-02
Special Airport Systems Market 2026: Strategic Intelligence to Shape Your Next Move
PW Consulting’s Special Airport Systems Market report (base year 2025) delivers a concise, decision-focused intelligence package designed for airport operators, systems integrators, OEMs, investors, and public-sector planners preparing for the pivotal investment cycle beginning in 2026. Grounded in five years of historical analysis (2020–2025) and extending through a 2026–2032 forecast horizon, the study situates special airport systems within a clear macro trajectory: the global market expands from USD 12.5 Billion in 2025 to an estimated USD 19.42 Billion by 2032 at a compound annual growth rate (CAGR) of 6.5%.
Special Airport Systems Market
Market Snapshot: What the Top-line Numbers Mean for Strategy
The market’s projected steady growth reflects a confluence of drivers—traffic recovery and long-term passenger growth, regulatory tightening around baggage and security, runway safety modernization, and sustained airport modernization programs worldwide. With market concentration remaining moderate (CR3 at 35.4% and CR5 at 48.2%), the sector balances incumbent strength with meaningful opportunity for specialist challengers and systems integrators. For 2026 decision-makers, the arithmetic is straightforward: the size and steady compound growth create a favourable environment for targeted CapEx and technology adoption investments, but returns will hinge on precise portfolio choices and execution discipline.
Special Airport Systems Market
Why 2026 Is a Strategic Inflection Point
-
Regulatory recalibration: Major standards bodies have advanced significant changes that materially affect procurement and implementation timelines. Recent releases and amendments from organizations such as IATA and ICAO introduce new baggage handling and security process expectations—changes that become actionable in 2026 and beyond. These standards not only influence technical specifications but also vendor eligibility and validation cycles.
Special Airport Systems Market -
Runway and airfield safety upgrades: National regulators have announced accelerated deployments of new runway safety technologies across prioritized airports, creating a near-term demand window for airfield detection, lighting, and guidance solutions integrated with airport operational IT.
-
Technology convergence: AI-driven screening, automation for baggage logistics, cloud-native passenger processing, and edge-enabled airfield monitoring are moving from pilots to rollouts. Procurement timelines in 2026 will reward readiness—proven integration stacks, cybersecurity-first architectures, and demonstrable lifecycle economic models.
-
Contract cadence and renewals: Several large-scale terminal expansions and BHS refurbishments announced or awarded in late 2025 and early 2026 signal clusters of procurement activity. These pockets create opportunities for vendors and integrators who can demonstrate rapid mobilization and interoperability with incumbent systems.
Competitive Landscape: Positioning the Major Players
Market structure combines global systems houses, specialist BHS manufacturers, IT-centric platform players, and engineering firms. Incumbents with broad portfolios continue to capture integrated project value, while focused specialists win on technical differentiation and total cost of ownership (TCO) advantages. Key players include:
-
Honeywell International Inc. (Charlotte, USA): Broad systems capability across security screening, building management, and ground handling technologies positions Honeywell to offer integrated solutions that align infrastructure modernization with sustainability and operational efficiency objectives.
-
Thales Group (Paris, France): A long-standing supplier of air traffic management, security solutions, and baggage integration, Thales leverages systems-level integration expertise to compete on end-to-end project delivery and lifecycle services.
-
Vanderlande Industries (Veghel, Netherlands) and Daifuku Co., Ltd. (Osaka, Japan): Both are recognized for high-throughput baggage handling systems and end-to-end airport logistics. Their technical depth in high-capacity, automated systems is a decisive factor in hub and high-growth airport projects.
-
SITA (Geneva, Switzerland) and Amadeus IT Group (Madrid, Spain): IT platforms and passenger processing suites are core to digital transformation efforts. These vendors are central to projects that prioritize passenger flow optimization, data sharing, and operational resilience.
-
Leidos (Reston, USA) and RTX (Arlington, USA): Strong in security enterprise solutions, surveillance, and navigation technologies, these companies are active where national security requirements and air traffic management modernization intersect with airport needs.
-
Siemens AG (Munich, Germany), Indra Sistemas, IDOM, and Deerns: Engineering, building automation, and systems integration capabilities make these firms competitive where airports seek holistic infrastructure modernization—energy efficiency, building systems, and operational control rooms.
-
Leonardo (Rome, Italy) and ADB SAFEGATE (Zaventem, Belgium): Specialized strengths in baggage handling innovation and airfield lighting/ground guidance, respectively, allow them to play pivotal roles in both new construction and targeted retrofit programs.
Recent vendor activity underscores the dynamic competitive environment: Leonardo secured multiple baggage handling contracts through late 2025 and early 2026, signaling strong demand for high-efficiency BHS solutions. Analogic Corporation was awarded a notable EDS installation at a major European hub in 2026, reflecting ongoing refresh cycles in screening equipment. And strategic partnering continues—Leidos’ 2026 joint venture with Altaris exemplifies how security providers are consolidating capabilities to win larger, integrated bids.
What the PW Consulting Report Delivers (Practical Tools, Not Just Projections)
Our report is engineered for execution. Beyond the headline forecasts and scenario analysis, it provides operationally relevant deliverables to inform 2026 decisions:
-
An actionable procurement playbook outlining RFP structures, scoring templates, and technical validation checklists designed specifically for baggage, screening, airfield lighting, and passenger processing procurements.
-
Vendor scorecards and capability matrices linked to procurement use-cases—allowing buyers to map technical, financial, and delivery risk against strategic objectives.
-
Implementation roadmaps and retrofit-vs-replace decision tools that quantify total lifecycle cost (CapEx + OpEx), downtime risk, and transition sequencing for airport operations.
-
A TCO/ROI model and sensitivity dashboards that operators can adapt to their network profiles, technology adoption rates, and funding scenarios.
-
Regulatory impact assessment and compliance timelines—integrating recent IATA and ICAO rule changes and national regulator programs so procurement & commissioning schedules align with enforceable deadlines.
-
Supply-chain and component risk matrices, highlighting critical single-source dependencies and mitigation strategies for vendors, from semiconductors to specialized detection modules.
How Leading Organisations Should Use This Intelligence in 2026
-
Airports (operators & planners): Prioritize projects that unlock operational capacity while de-risking regulatory compliance. Use the report’s retrofit decision tools to avoid premature large-scale replacements and to cost-effectively stagger upgrades.
-
OEMs & integrators: Align commercial strategies with cluster demand windows (e.g., terminal expansions, security standard rollouts). Prepare packaged, certified solution bundles that shorten procurement cycles and lower integration risk.
-
Systems integrators & engineering firms: Differentiate around verified interoperability and cybersecurity assurance. The ability to deliver integrated ops-room capabilities and digital twins will command premium margins.
-
Investors & financial sponsors: Focus on companies with demonstrable backlog convertibility and recurring services revenue. Market concentration metrics suggest acquisition opportunities to consolidate regional specialists into broader solution platforms.
-
Public-sector bodies & regulators: Use the report’s timelines to sequence funding, ensure competitive procurement, and support standard adoption through pilot-to-scale pathways.
Risk Considerations and Mitigation Priorities
Decision-makers in 2026 must weigh upside opportunity against several risks: regulatory implementation timing, equipment lead times, supply-chain bottlenecks, and interoperability failures during cutover. Our report provides prioritized mitigation strategies—contractual clauses for delivery certainty, modular upgrade approaches, and staged validation plans—to reduce operational exposure and protect passenger throughput.
Conclusion: From Insight to Action
As the special airport systems market accelerates through 2026, PW Consulting’s report is built to be a practical companion for executives who must convert macro opportunity into executable programs. With global market expansion, defined regulatory milestones, and clustered project pipelines, the next 18–36 months will set long-term competitive positions. The analysis in this report equips buyers, suppliers, and financiers to size opportunities, negotiate with precision, and sequence investments for resilient, high-return outcomes.
To access the full report—containing granular regional and application splits, vendor financial benchmarks, and the downloadable procurement toolkit—visit PW Consulting’s Special Airport Systems Market page and download the executive dossier. Our summary provides the strategic framing; the report delivers the operating models and templates you will use to act in 2026.
For detailed analysis of this topic, please visit the official page: Special Airport Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Prefabricated & Modular Data Centers Market Poised to Expand at a 16.45% CAGR Through 2032
By PW Consulting, 2026-07-02
Prefabricated and Modular Data Centers Market — Strategic Outlook for 2026 (PW Consulting)
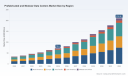
As organizations confront an inflection point where AI-scale compute, edge distribution, and tighter energy regulation collide, PW Consulting’s latest market study on Prefabricated and Modular Data Centers delivers a timed, decision-grade synthesis for boardrooms and engineering teams planning through 2026. Built on a 2025 base-year analysis and a 2026–2032 forecasting horizon, our model projects a sustained compound annual growth (CAGR) of 16.45% across the forecast window. The market we track has grown from the low‑30s (USD Billion) in 2020 to roughly USD 72.5 Billion in 2025 and continues toward a multi‑hundred‑billion-dollar opportunity by 2032 — an expansion that fundamentally reshapes sourcing, site selection, and energy risk calculus for enterprises and hyperscalers alike.
Prefabricated And Modular Data Centers Market
Why this study matters for 2026 business and technical decisions
- Structural demand drivers: Rapid adoption of high-density AI racks and distributed edge architectures is accelerating preference for factory-built modules and containerized pods that minimize on-site construction complexity and time to production.
- Regulatory and energy stress: New policy moves in 2026 — including multi‑state legislation in the U.S. requiring data centers to internalize the cost of new grid infrastructure, and voluntary Ratepayer Protection commitments by major hyperscalers — materially change the economics of site choice and utility procurement.
- Cost and capacity pressure: Rising residential electricity tariffs and the visible contribution of data-center-driven load growth to utility rate filings mean companies must integrate grid-upgrade exposure into TCO models, not treat it as an externality.
- Vendor innovation cycle: Leading suppliers are already delivering modular solutions purpose‑built for liquid cooling, high-power busways, and factory-integrated power/cooling stacks — creating differentiated value for AI and HPC workloads.
What the report delivers — practical, executable assets
PW Consulting deliberately frames this report as an operator’s toolkit, not a pure market narrative. Subscribers receive:
Prefabricated And Modular Data Centers Market
- Proprietary market-size model (2020–2025 historical, 2026–2032 forecast) with scenario toggles for adoption curves, cooling technology mix, and edge vs. hyperscale penetration.
- TCO and payback calculators configurable for CapEx/Opex profiles, grid-upgrade cost pass-through scenarios, and varying PUE and cooling technology parameters.
- Vendor scorecards and procurement playbook: capability matrices, integration risks, manufacturing lead‑time benchmarks, and negotiation levers to compress supplier SLAs into firm delivery timelines.
- Site-selection and regulatory heatmap: a pragmatic checklist mapping permitting risk, grid interconnection exposure, and state-level legislative trends that affect energy charges and upgrade obligations.
- Reference architectures and integration checklists for AI/high-density deployments, including liquid-cooling boundary conditions, containment strategies, and power distribution templates.
- Implementation roadmaps and pilot design templates for rapid validation (3–9 month pilots) to de‑risk larger rollouts.
- Risk register and mitigation playbooks addressing supply-chain disruption, raw-material cost volatility, and workforce constraints in factory vs. field assembly.
Competitive landscape — who matters and how to use this intelligence
Market concentration metrics show a market with meaningful leaders but ample room for specialist providers (our CR3 and CR5 measures indicate a mid‑concentration profile). Understanding supplier strategy and product roadmaps is table stakes for 2026 procurement. Highlights from our competitive analysis:
Prefabricated And Modular Data Centers Market
- Schneider Electric (Rueil‑Malmaison, France) — Continues to scale its EcoStruxure modular portfolio and Prefabricated Pod solutions. Recent product launches focus on high-density AI readiness, integrated liquid cooling, and high-power busway support, positioning Schneider as an end‑to‑end systems integrator for customers seeking rapid, low‑risk deployments.
- Vertiv (Columbus, Ohio, USA) — Aggressively moving to factory‑integrated platforms with its OneCore and SmartRun lines; recent global launches and strategic collaborations underscore a playbook centered on repeatable, high-throughput manufacturing and tight vendor‑end user integrations for AI-scale projects.
- Huawei (Shenzhen, China) — Offers a broad family of FusionModule products oriented to telco edge and scalable prefabricated solutions, emphasizing modular scaling and rapid field deployment in distributed architectures.
- Eaton (Dublin, Ireland) — Positions itself on power resilience and integrated UPS infrastructure, addressing customers for whom uptime and power-quality are primary constraints.
- Specialist integrators and fabricators (e.g., BMarko Structures, CenCore Group, Compu Dynamics Modular, PodTech, TAS, Delta Electronics) — These firms emphasize customization, security compliance (including TEMPEST and other mission-critical standards), and niche capabilities (containerization, custom pod design, or high-density liquid cooling). They often serve edge, colocation, and regulated verticals where bespoke engineering trumps scale.
Recent vendor moves (product launches and strategic partnerships in late 2025 and early 2026) indicate a competitive phase focused on AI‑ready features — liquid cooling, busway power distribution, and factory QA for rapid field integration. For buyers, this creates a clear bifurcation: engage a large systems integrator for end-to-end speed and interoperability, or select specialized fabricators when security, customization, or edge footprint matters more.
Strategic implications and recommended actions for 2026 decision cycles
- Treat grid exposure as a first‑order cost: Integrate utility‑upgrade risk into your financial model and require suppliers to quantify interconnection timelines and any dependencies on local utility reinforcement.
- Adopt a two‑track sourcing strategy: (1) standardized factory-built modules from large integrators for core, high-volume builds; (2) niche builders for edge or regulated sites where customization, security, or local compliance is critical.
- Prioritize modular architectures that minimize on‑site civil works and permit staged capacity increases — this reduces up-front capital and gives flexibility to pivot to denser cooling technologies as rack power increases.
- Negotiate vendor SLAs around upgradeability and retrofitability: ensure pods and modules are designed for lifecycle upgrades (e.g., converting from air to liquid cooling) without full replacement.
- Run accelerated pilots: validate factory acceptance procedures, transport logistics, and multi‑vendor interoperability before committing to volume buys.
- Build a regulatory-response playbook: monitor state legislation and utility filings and design contracts and tariffs that allocate responsibility for grid upgrades transparently.
- Embed supply‑chain resilience clauses: secure priority long‑lead items, and require vendors to publish manufacturing capacity and second‑source options for critical components.
How to deploy the report in your 2026 planning cycle
- Quarter 1: Use the market model and heatmap to finalize site shortlists and quantify utility exposure for each candidate site.
- Quarter 2: Run vendor scorecard assessments and initiate pilot contracts with staged acceptance and clearly defined performance gates.
- Quarter 3: Execute a procurement round leveraging our negotiation playbook to align delivery timelines to utility interconnection schedules.
- Quarter 4: Scale deployments using validated reference architectures, with continuous P&L tracking using our TCO templates and ongoing regulatory monitoring.
PW Consulting’s research is intentionally prescriptive: it does not stop at “what” is happening — it provides the operational tools needed to turn market insight into executable plans that reduce time to value and control energy and regulatory risk.
About the report and next steps
This executive overview is a condensed navigator. The full PW Consulting Prefabricated and Modular Data Centers Market report (base year 2025; forecast 2026–2032) contains the granular tables, region and application segmentations, supplier financial and capability matrices, and downloadable model files that enterprise teams use to build procurement RFIs, capital plans, and deployment schedules. In accordance with our “preview” approach, detailed segment-level figures and complete supplier scorecards are intentionally reserved for the full report to preserve the utility of those datasets for subscribers and clients.
To request the full report, schedule a briefing, or engage PW Consulting for a tailored vendor selection workshop or pilot design, visit our report page or contact the PW Consulting advisory team. We help clients translate the projected market momentum — reflected in the robust historic growth and the 16.45% forecast CAGR — into defensible, auditable deployment programs aligned with both performance and regulatory objectives.
For detailed analysis of this topic, please visit the official page: Prefabricated And Modular Data Centers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AI Speech Generation Systems Market Poised to Expand at 18.5% CAGR, New Insight Reveals
By PW Consulting, 2026-07-02
Ai Speech Generation System Market 2026: Strategic Imperatives from PW Consulting’s New Report
As enterprises accelerate the adoption of generative AI across customer experience, learning and development, and content production, AI-driven speech generation has moved from experimental proof-of-concept to enterprise-grade infrastructure. PW Consulting’s latest market study (base year 2025) synthesizes five years of historical data and a seven-year forecast to 2032, showing a sustained structural expansion in the sector—with the global market growing from USD 1,150 Million in 2020 to USD 3,200 Million in 2025 and projected to exceed USD 10,400 Million by 2032 at a compound annual growth rate (CAGR) of 18.5%. This research note outlines the strategic value of the report for corporate decision-makers planning investments and operating models in 2026, and highlights the practical analysis that differentiates our work from vendor marketing material.
Ai Speech Generation System Market
Why this report matters for 2026 decisions
-
Timing and scale: With a high-teens CAGR and market size trajectory that multiplies over the forecast window, 2026 is a pivotal entry point for scaling voice AI initiatives. The economics of voice—lower production labor costs, automation of repetitive interactions, and improved content velocity—mean that first movers who nail security, compliance, and experience design can capture disproportionate value.
Ai Speech Generation System Market -
Commercial architecture choices are consequential: Choosing between cloud-first API services, hybrid deployments, and on-premise implementations will determine cost exposure, latency, and regulatory compliance. Our report maps the trade-offs in total cost of ownership and time-to-market across these architectures, with vendor-specific integrations and migration playbooks.
Ai Speech Generation System Market -
Regulatory inflection points: With EU AI Act provisions and tightening enterprise requirements for SOC 2/GDPR and data residency, 2026 is a “now or later” compliance year for global rollouts. The report provides a compliance roadmap that aligns technical controls with procurement, legal, and audit processes.
What’s inside the PW Consulting report (practical, actionable content)
-
Market sizing and scenario analysis: A transparent, model-driven overview of the market from 2020–2025 and three forecast scenarios to 2032 that stress-test adoption rates, pricing compression, and enterprise monetization paths based on realistic assumptions.
-
Vendor and technology assessment: A vendor-agnostic evaluation framework that scores providers on voice quality, latency, language coverage, expressivity controls, enterprise features (security, auditability, model provenance), and commercial flexibility (licensing, volume discounts, SLA structures).
-
Implementation playbooks: Step-by-step operational templates for integrating TTS into contact centers, e-learning, and content workflows—covering data pipelines, human-in-the-loop processes, voice cloning governance, and performance monitoring.
-
Cost benchmarks and unit economics: Practical guidance on per-minute cost drivers (codec/quality tier, inference vs. pre-rendering, storage), along with templated calculations for internal business cases. Our analysis shows that audio-production cost reductions versus traditional voiceover methods can be material, and identifies where TTS still requires human augmentation.
-
Compliance and risk playbook: Concrete controls and contract clauses to manage regulatory exposure under emerging frameworks, plus recommended audit and watermarking practices for detection and provenance.
-
M&A and partnership strategic paths: A set of signals for corporate development teams—what to look for in acquisition targets, where partnerships accelerate market access, and how to structure equity-versus-deal incentives.
-
Executive checklists and KPIs: Ready-to-use metrics for product, security, legal, and procurement leaders to track during pilot and scale phases.
Competitive landscape — how leading players shape 2026 choices
The market exhibits a moderate degree of concentration: the top three vendors account for roughly one-third of market value, and the top five approach half the market. That structure supports a dynamic vendor ecosystem where hyperscalers, specialized platforms, and emerging open-weight models coexist. Our vendor coverage focuses on the capabilities that matter most to enterprises in 2026.
-
ElevenLabs — Recognized for ultra-realistic voice cloning and expressive models, ElevenLabs has positioned itself for creative and enterprise content workflows. Recent strategic partnerships that embed its TTS/STT into orchestration platforms illustrate how voice quality plus integration capability can accelerate adoption in agentic AI scenarios.
-
WellSaid Labs — Targets the enterprise training and compliance segment with studio-quality licensed voices and secure workflows (SOC 2/GDPR-aligned). Their focus on authorized, professional voice catalogs helps organizations mitigate brand and legal risk when replacing human narration in regulated content.
-
Murf.ai — Emphasizes an accessible creator experience with broad voice options and control primitives (emphasis, pacing). This lowers the barrier for SMBs and marketing teams to adopt AI voice at scale for explainers and social content.
-
PlayAI (Play.ht) — API-first and automation-oriented, PlayAI is built for scalable voice workflows and conversational use-cases where orchestration and multilingual support are critical.
-
Resemble AI — Marries custom voice cloning with enterprise-grade controls including on-prem/cloud options and deepfake detection—appealing to gaming, media production, and contact center modernization projects that need bespoke voices with provenance.
-
Hyperscalers (Google, AWS, Microsoft, OpenAI) — These incumbents are driving platform-level bets: they combine high-quality TTS with global infrastructure, fine-grained expressive controls, model watermarking, and deep integration into broader AI stacks. Their offerings matter for enterprises prioritizing scale, global coverage, and single-vendor integration economies.
Recent market developments that change the playbook
-
New model releases and open weights: The launch of frontier-quality open-weight TTS models has reduced the entry cost for building voice experiences and has broadened competitive dynamics between specialist providers and platform players.
-
Strategic partnerships: Integrations between vendor TTS technologies and enterprise orchestration platforms accelerate “agentic” deployments where speech is a primary interface. These partnerships shorten time-to-value for contact centers and virtual assistants.
-
Product innovations: Hyperscaler advances in expressive control and watermarking address two key enterprise needs—brand-consistent voice and safe, auditable usage—pushing the market away from “black box” audio generation.
-
Regulatory shifts: The upcoming enforcement of AI-specific provisions in major jurisdictions increases the need for documented risk assessments, transparency layers, and provenance technologies. Enterprises must plan for additional compliance costs that affect vendor selection and deployment architecture.
Strategic recommendations for enterprise leaders in 2026
-
Prioritize compliance by design: Treat data residency, logging, watermarking, and model governance as first-class requirements during vendor selection. Neglecting these will slow pilots and increase remediation costs.
-
Adopt a hybrid deployment stance: For many enterprises, a hybrid approach (cloud for scale; on-prem or private-cloud for regulated content) balances agility with risk mitigation. The report includes decision trees and cost tradeoffs to help procurement and cloud teams converge quickly.
-
Make voice quality and expressivity testable: Run blind perceptual tests and automated expressivity scoring against your critical use-cases (e.g., customer empathy, legal reading). Choose vendors based on fit-to-use-case, not only benchmark voice demos.
-
Embed human-in-the-loop controls: For high-risk or customer-facing utterances, maintain human approval gates and upgrade logging/traceability to ensure accountability and continuous improvement.
-
Design pricing playbooks: Negotiate contract structures that reflect your usage profile—pre-rendering vs. real-time, voice cloning premiums, watermarking and provenance features—while preserving optionality to switch providers as the market evolves.
-
Scan M&A and partner signals: For growth or defensive moves, identify targets with differentiated data assets (voice talent catalogs, annotated emotional speech datasets) and proven enterprise controls.
How to use the full PW Consulting report
This note provides a concise strategic orientation; the full report is structured to support program-level decisions in 2026. Subscribers will receive detailed vendor scorecards, scenario-modeled financials, procurement negotiation playbooks, and downloadable implementation templates. Crucially, proprietary subsegment matrices (region, type, application) and granular unit-cost tables are intentionally reserved for the full report—these are the operational levers that procurement and product teams will need to finalize budgets and contracts.
In a market growing at an 18.5% CAGR with structural tailwinds from automation economics and hyperscaler investments, leadership in AI speech generation will be less about “if” and more about “how” and “with whom.” PW Consulting’s analysis equips executives with the frameworks and practical tools to convert the macro opportunity into defensible, compliant, and profitable voice strategies in 2026 and beyond. For full access to the market segmentation, vendor scorecards, and downloadable playbooks, consult the complete Pw Consulting Ai Speech Generation System Market report.
For detailed analysis of this topic, please visit the official page: Ai Speech Generation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DDR5 RDIMM Memory Interface Chip Market Valued at USD 2,150.5 Million in 2025, Poised to Reach USD 7,930.15 Million by 2032 on a 20.45% CAGR
By PW Consulting, 2026-07-02
PW Consulting Releases Strategic Brief: DDR5 RDIMM Memory Interface Chip Market — Critical Intelligence for 2026 Decision-Making
PW Consulting’s new market research brief on the DDR5 RDIMM memory interface chip market (base year 2025; historical window 2020–2025; forecast 2026–2032) delivers a focused playbook for executives, product planners, and investors who must make high-stakes allocation decisions in 2026. The headline: the overall market has scaled rapidly over the past five years and, driven by AI-first data center architectures and hyperscale demand, is projected to grow at a compound annual growth rate of 20.45% through 2032. Our analysis drills into the structural drivers behind that growth, the supplier landscape, and the commercial levers that will determine winners in the next innovation cycle — while reserving certain proprietary subsegment detail to subscribers to preserve the integrity of our forward-looking scenario models.
DDR5 RDIMM Memory Interface Chip Market
Why this market matters in 2026
Memory interface chips for DDR5 RDIMMs have moved from enabler to differentiator in server and AI infrastructure. Between 2020 and 2025 the market expanded sharply as enterprises and cloud providers accelerated refresh cycles; our base-year synthesis shows a clear inflection as Gen3/Gen4 implementations became mainstream in server fleets. Looking ahead, our 2026–2032 outlook anticipates continued rapid expansion, with total market value multiplying several-fold by 2032 under a 20.45% CAGR. For strategic planners, these dynamics translate into immediate questions about supply chain resilience, design cycles, and IP positioning — decisions that compound over multi-year platform ramps and capital budgets.
DDR5 RDIMM Memory Interface Chip Market
Core market dynamics: what’s driving demand and price pressure
- AI and memory bandwidth intensity: Models with larger working sets and higher memory concurrency are materially increasing RDIMM content per server pod. This is accelerating demand for high-performance Registered Clock Drivers (RCDs), data buffers, and associated PMIC/management components.
- Module transition velocity: Shipment patterns indicate DDR5 RCD volumes have already overtaken DDR4 equivalents in multiple server tiers. This mainstreaming compresses qualification windows and raises the premium for rapid system-level validation.
- Supply-side friction: Regulatory shifts (notably tariff adjustments in early 2025) and component-level supply constraints are re-shaping sourcing strategies. Some OEMs are rerouting procurement into tariff-exempt geographies, while others are adopting dual-sourcing for critical interface chips to mitigate geopolitical risk.
- Pricing and raw material noise: Contract pricing volatility tied to DRAM and module supply is expected to increase in 2026 as AI-driven procurement spikes intersect with limited module supply and capacity expansion lags.
Competitive landscape — concentration and capability
The DDR5 RDIMM memory interface chip market is highly concentrated. The top three suppliers command a dominant share of total revenues, while the top five capture an even larger portion — a structural reality that shapes partner selection, licensing negotiations, and long-lead capacity commitments. Against this backdrop, we profile the strategic contours of the most consequential players:
DDR5 RDIMM Memory Interface Chip Market
- Rambus (San Jose, California, USA): Rambus offers a vertically integrated DDR5 server DIMM chipset portfolio, including high-frequency RCDs supporting very high data rates, PMICs, SPD Hubs, and thermal sensors. The company’s recent industry recognition for an 8000 MT/s RDIMM chipset underscores its leadership in performance-centric productization for data center and AI deployments.
- Renesas Electronics (Tokyo, Japan): Renesas has pushed the performance envelope with Gen6-class RCD solutions capable of the next wave of data rates and continues to expand its memory interface chipset roadmap. Renesas’ strategic focus on scalable platform support and localized growth initiatives (including accelerated deployment plans in China) make it a critical partner for OEMs targeting region-specific optimizations.
- Montage Technology (Shanghai, China): Montage has demonstrated mass-production readiness for Gen4 DDR5 RCDs and complements those products with PMICs and sensor ecosystems — a profile that appeals to high-volume module makers and regionally focused system integrators.
- PMIC specialists — Texas Instruments, Analog Devices, Infineon: These incumbents are key suppliers of power management and thermal efficiency innovations that materially affect module reliability and system-level TCO. Their role in enabling high-speed RDIMMs is increasingly strategic as thermal budgets tighten in dense AI racks.
Recent product and industry moves provide directional clarity: Rambus’ 2026 recognition for its 8000 MT/s chipset validates the market premium for performance leadership; Renesas’ late‑2025 Gen6 RCD launch signals the next architecture inflection; Montage’s mass production of Gen4 components highlights how cost and volume execution will influence market share shifts. Our competitive matrices map capability gaps vs. customer requirements and identify where partnerships, acquisitions, or IP licensing can de-risk development roadmaps.
What PW Consulting’s report delivers (practical contents)
Our DDR5 RDIMM Memory Interface Chip Market report is structured to deliver operationally relevant guidance, not just high-level forecasts. Key deliverables include:
- Market sizing and trajectory (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario modeling that isolates the impact of AI adoption curves, module supply shocks, and tariff regimes.
- Supplier capability maps and win-loss analysis tied to customer archetypes (hyperscalers, enterprise OEMs, module houses), with recommended engagement strategies for each archetype.
- Technology maturation timelines for RCD generations, buffer architectures, PMIC integration, and signaling ecosystems — highlighting critical path items for achieving target MT/s at module and system level.
- Commercial playbooks: procurement clauses for long-lead chips, dual-sourcing strategies, licensing negotiation frameworks, and suggested contract terms to hedge supply and pricing volatility.
- Implementation checklists that embed test/validation KPIs, thermal qualification gates, and production ramp milestones — designed to fit typical server platform development cycles.
Note on data access: in keeping with the “trailer” approach central to our research dissemination strategy, the report executive summary and our headline macro projections are public; detailed sub-segmentation (regional, type-level splits, and customer application-level revenue breakouts) and the full set of model assumptions are available exclusively through the downloadable report package and interactive dashboard.
Strategic implications and recommended actions for 2026
For executives planning capital allocation and product roadmaps in 2026, our analysis implies the following priority actions:
- Secure performance-tier supply: For organizations targeting next‑generation AI workloads, locking in supply of high-performance RCDs and advanced PMICs is a first-order priority. Given market concentration and lead times, early engagements — including non-cancellable volumes or design‑win guarantees — materially reduce program risk.
- Invest in thermal and power co-design: As data rates climb, PMIC efficiency and thermal management become key differentiators. Co-investing in integrated solutions with PMIC specialists can accelerate validation and reduce system-level TCO.
- Adopt portfolio hedging: Dual-sourcing and qualification of alternate RCD/PMIC combinations will protect deployments from regional supply shocks and tariff-driven cost shifts. Our report provides a prioritized list of candidate pairings and qualification sequencing.
- Leverage partnership models: Suppliers with full-stack offerings (RCD + PMIC + SPD/telemetry) offer faster time-to-market; however, pure-play vendors can provide pricing flexibility. Structuring long-term collaboration agreements with capacity commitments is a practical approach to balance speed and cost.
- Monitor regulatory and pricing signals: Procurement and product teams must incorporate tariff exposure and DRAM/module price scenarios into their rolling forecasts. We recommend monthly reviews during 2026 to trigger contingency procurement actions.
How to use the report for investment and M&A decisions
For investors and corporate development teams, the report’s scenario-based valuation overlays and supplier concentration analysis are designed to identify asymmetric opportunities. High concentration at the supplier level raises the strategic value of bolt-on acquisitions that add complementary PMIC or telemetry capabilities. Conversely, module houses that can internalize certain interface functions may create defensive advantages against pricing volatility. Our due-diligence checklists, risk-adjusted forecast tables, and acquisition valuation templates are intended to shorten the time from signal to action.
Methodology, confidence, and limitations
PW Consulting’s market size and forecast employ a bottom-up assembly of supplier financials, shipment data, module house contracts, and primary interviews with hyperscale and OEM procurement leads. We apply sensitivity testing across DRAM price scenarios, capacity additions, and adoption rates of Gen5/Gen6 DDR5 signaling. Confidence in the headline CAGR and total market trajectories is high given convergent supplier disclosures and program announcements; however, short-term pricing noise — especially in 2026 — can cause near-term deviations from the base forecast. For this reason, the report includes alternate scenarios and a probabilistic model that stresses regulatory and supply-chain events.
Conclusion — the strategic choice for 2026
The DDR5 RDIMM memory interface chip market presents a clear, high-conviction growth opportunity. But rapid growth and high supplier concentration create asymmetric risks that favor proactive strategy over reactive procurement. Enterprises that align early with performance leaders, secure diversified supply pathways, and integrate power/thermal innovations into system design will capture outsized benefit. PW Consulting’s report translates the market’s macro momentum — now backed by a 20.45% CAGR outlook through 2032 — into sector-specific actions that matter for 2026 budgeting, supplier negotiations, and platform roadmaps.
For decision-makers seeking the detailed subsegment economics, supplier-level benchmarking matrices, and the full set of scenario inputs — including our proprietary regional and application breakouts withheld from this public brief — please visit the PW Consulting report page to download the full DDR5 RDIMM Memory Interface Chip Market report and gain access to the interactive forecast dashboard.
For detailed analysis of this topic, please visit the official page: DDR5 RDIMM Memory Interface Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Embedded Storage (eMMC & UFS) Market to Climb from USD 4,100 Million in 2025 to USD 10,906 Million by 2032 at a 15.02% CAGR
By PW Consulting, 2026-07-02
Automotive Embedded Storage (eMMC & UFS): Strategic Imperatives for 2026 — PW Consulting Market Report Preview
As the vehicle architecture transitions from distributed electronic control to centralized, software-defined platforms, embedded storage has moved from a commoditized commodity to a strategic system-level enabler. PW Consulting’s new market study — with a 2025 base year, a documented historical window (2020–2025) and a forward-looking forecast to 2032 — quantifies that shift and translates it into actionable guidance for OEMs, Tier‑1 suppliers, semiconductor fabs, and investors. Our model projects a sustained compound annual growth rate (CAGR) of 15.02% across the 2026–2032 forecast window and traces the market trajectory from an established multi‑billion dollar base in 2025 to a materially larger market by 2032. This preview explains why the report is essential to 2026 decision-making while intentionally withholding core sub‑segment tables and granular splits to encourage stakeholders to consult the full report for privileged data assets.
Automotive Embedded Storage (eMMC and UFS) Market
Why 2026 Is a Pivotal Inflection Point
Several concurrent forces make 2026 the year to reset embedded storage strategy. First, after consistent expansion between 2020 and 2025, the market expands further in 2026 as vehicle compute consolidation, higher-capacity IVI (in‑vehicle infotainment) stacks, and ADAS/autonomy storage needs amplify demand. Our topline sizing shows clear acceleration: the market surpasses its 2025 base and continues on a high-growth path toward the 2032 forecast. Second, the industry technical curve is steepening — next‑generation UFS iterations and automotive-grade flash offerings are moving from sampling to production qualification, reshaping product roadmaps and supplier selection criteria. Third, supply-side dynamics (tight NAND capacity and rising contract prices) and extended qualification cycles are making procurement timing a decisive source of competitive advantage.
Automotive Embedded Storage (eMMC and UFS) Market
What the Report Contains — Practical, Executable Intelligence
- Comprehensive market sizing and scenario forecasts (base year 2025), including sensitivity runs that isolate the impact of NAND supply shocks, pricing volatility, and rapid UFS adoption on total addressable market (TAM).
- Technology roadmap mapping: eMMC → UFS migration patterns, timing of adoption across vehicle segments, and the implications of emerging JEDEC/industry protocol updates for software and hardware architects.
- Supplier scorecards and validation trackers: capability matrices that evaluate product portfolios, AEC‑Q100 and ISO 26262 readiness, qualification cycle history, capacity posture, and go‑to‑market footprints.
- Procurement and qualification playbooks that accelerate time‑to‑production: templates, test stacks, recommended KPIs for supplier qualification, and staged sourcing approaches to limit production risk.
- Commercial scenario modelling and TCO (total cost of ownership) frameworks linking contract vs. spot purchasing, inventory buffering, and design-for-supply tradeoffs for decision-makers in procurement and program management.
- Risk register and mitigation strategies prioritizing supply concentration, geopolitical exposure, and NAND price inflation with graded mitigation actions tied to program timelines.
- M&A and partnership decision frameworks: checklist-driven approaches for evaluating strategic acquisitions, minority investments, and co-development agreements in embedded storage and adjacent IP (controller, firmware, security).
Each element is accompanied by reproducible worksheets and a diagnostic questionnaire so teams can immediately use findings to stress-test their 2026 budgets and product roadmaps.
Automotive Embedded Storage (eMMC and UFS) Market
Competitive Landscape: Who Matters and Why
The market remains oligopolistic by design and economics; our concentration metrics underline the reality — the top three suppliers account for a significant share of the market, and the top five capture an even larger portion. This concentration raises both dependency risks and strategic opportunities for customers and new entrants.
- Samsung Electronics (South Korea): Market leader across automotive-grade UFS and eMMC lines, with a proven track record in high-volume UFS 3.1 production targeted at IVI systems. Strengths include vertically integrated NAND manufacturing and optimized low-power solutions tailored to modern cockpit ECUs.
- Micron Technology (United States): A strategic alternative for customers seeking ASIL‑compliant storage and advanced NAND nodes. In late 2025 Micron began shipping qualification samples of an automotive UFS 4.1 solution built with its G9 NAND — a signal that Micron is accelerating its automotive roadmap and aiming at intelligent vehicle storage segments.
- KIOXIA Corporation (Japan): Early mover in UFS sampling for automotive use-cases; its product cadence includes UFS 4.x lines and early evaluation samples for next-generation mobile-grade tech adapted to automotive requirements.
- SK hynix (South Korea): Competes on performance NAND and UFS integration for compute-heavy vehicle platforms where latency and throughput matter.
- Western Digital (SanDisk), Silicon Motion, Longsys (FORESEE), Flexxon, Kingston, ATP Electronics: Together these players provide a mix of industrial/automotive-grade eMMC and UFS solutions, controller IP, and specialized form factors. Notably, Silicon Motion’s validation of UFS solutions on leading cockpit SoCs in mid‑2025 underscores its role as a critical controller and firmware partner.
Recent supplier moves — product samplings, qualification shipments, and platform validations disclosed through 2025–early 2026 — are incorporated into our competitive heat maps, showing where suppliers are positioned on capability, automotive readiness, and delivery risk. These developments are early indications of which vendors will be able to support high-volume programs in 2026 and beyond.
Market Dynamics — Supply Tightness, Pricing, and Regulation
- Supply tightness: NAND flash availability remains constrained into 2026, particularly for legacy MLC capacity that many automotive projects still rely on. Suppliers are reallocating capacity to higher-margin mobile and datacenter segments, which has knock-on effects for lead-times and qualification scheduling.
- Price environment: Contract and spot pricing for NAND rose markedly through early 2026. Our commercial scenarios quantify the impact of price inflation on program margins and recommend structural responses — including hedged contracts, capacity reservations, and design adjustments to reduce raw flash consumption.
- Regulatory and safety qualifications: Automotive embedded storage must meet AEC‑Q100 vehicle-grade requirements and often operationalize ISO 26262/ASIL functional safety constraints for ADAS and cockpit domains. These certifications lengthen supplier selection timelines and create lock-in once a supplier is qualified.
- Supply chain concentration and geopolitical exposure: Global NAND production is concentrated in Asia, exposing OEMs and Tier‑1s to export controls, geopolitical frictions, and potential tariff risk that can materially affect lead times and inventory costs.
- Qualification timelines: Typical automotive qualification cycles for eMMC and UFS modules span 18–24 months. That timeline creates demand lock-in and makes early supplier engagement a strategic necessity for 2026 program launches.
Strategic Recommendations for 2026 Decision‑Makers
- Lock qualification paths early: Start supplier validation sequences immediately for any 2027 program to avoid 18–24 month bottlenecks. Use staged validation contracts to accelerate critical-path milestones.
- Adopt flexible architecture patterns: Design storage layers to support both eMMC and UFS variants where practical; abstracting the stack reduces switching cost if supplier allocation shifts.
- Hedge supply and pricing risk: Negotiate mixed procurement constructs (long‑term reserved capacity + capped spot exposure) and include price re-opener clauses tied to NAND indices to maintain cost predictability.
- Prioritize supplier diversification based on capability and concentration risk: Use our supplier scorecards to build “lead + secondary” sourcing pairs that balance performance, qualification lead times, and geopolitical footprint.
- Embed safety & security early: Integrate ISO 26262 and secure-boot/FOTA requirements into the procurement spec to avoid rework during qualification and to mitigate cybersecurity risk.
- Use scenario-driven portfolio planning: Test product roadmaps against upside/downside NAND scenarios in our model to determine when to accelerate UFS migration or when to conserve capacity for critical ADAS programs.
- Consider strategic partnerships: For firms lacking in-house flash integration skills, partnerships with controller IP vendors and specialist module suppliers can compress qualification timelines and reduce product risk.
Why PW Consulting’s Study Is Different
We built this study with an emphasis on executability. Beyond a market forecast anchored to a 2025 base and validated against supplier disclosures and recent activities, the report provides reproducible commercial scenarios, supplier validation trackers, and a runnable stress‑test model for executives to quantify program-level impacts of NAND scarcity, price swings, and accelerated UFS adoption. Our market concentration measures are included to illuminate dependency risk and negotiating leverage. The full report contains the granular supplier scorecards, qualification timelines, and region/application split analytics that procurement, engineering, and corporate development teams need to finalize 2026 strategies — content we deliberately do not replicate in this preview.
Next Steps
Executives and program leads preparing budgets, sourcing plans, or product roadmaps for 2026 should treat embedded storage as a strategic input, not a line-item commodity. PW Consulting’s full Automotive Embedded Storage (eMMC & UFS) Market Report supplies the models, checklists, and supplier intelligence to convert market insight into program-level action. For access to the complete dataset, supplier heat maps, and the scenario model referenced above, please consult the report’s landing page and contact PW Consulting for an executive briefing.
For detailed analysis of this topic, please visit the official page: Automotive Embedded Storage (eMMC and UFS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


