



Category: Machinery & Automotive
PW Consulting: E‑Beam Accelerators Market Poised for Steady 4.15% CAGR Through 2026–2032, New Insight Report Reveals
By PW Consulting, 2026-07-13
E Beam Accelerators Market — Strategic Preview for 2026 Corporate Decision-Making
Executive snapshot
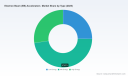
PW Consulting’s new industry briefing on the E Beam Accelerators market draws a clear line from historical performance (2020–2025) into a forward-looking forecast spanning 2026–2032. The market has expanded from an estimated USD 120.0 Million in 2020 to roughly USD 180.0 Million in 2025, reflecting steady uptake across industrial, medical and packaging end‑uses. Under our base-case assumptions, total industry revenues are projected to grow at a compound annual growth rate (CAGR) of approximately 4.15% through the 2026–2032 forecast window, reaching a market size in the order of USD 270.0 Million by 2032.
E Beam Accelerators Market
Why this preview matters for 2026 decisions
-
Timing capital allocation: 2026 is a transitional year for many adopters — systems ordered now will reflect a new wave of integrated service models (monitoring, performance guarantees) and modular hardware designs. Our analysis identifies the breakpoints where earlier deployments become operationally or financially suboptimal compared with next‑generation accelerators.
E Beam Accelerators Market -
Supplier selection and risk management: the market exhibits moderate concentration (CR3 ~45%; CR5 ~65%), indicating a small group of influential incumbents alongside a competitive tail of specialist integrators. This structure carries implications for lead times, aftermarket support and price negotiation power when committing to multi‑year service contracts.
E Beam Accelerators Market -
Regulatory and demonstration effects: recent contract wins and cross‑border deliveries are accelerating acceptance in new jurisdictions, changing the calculus for market entry and capacity expansion. Purchasers and investors need to factor in regulatory staging and certification timelines into 2026 procurement roadmaps.
What the report delivers — practical, decision‑grade content
This report was built for executives and investment teams who must translate technology trends into immediate actions. Highlights of the deliverables include:
-
Actionable market sizing and scenario modelling: an audited historical series (2020–2025), a base forecast (2026–2032) and upside/downside scenarios linked to key variables such as service‑contract penetration, capital equipment lifecycles and macroeconomic sensitivity.
-
Investment-ready financial tools: capex/opex templates calibrated to typical installation profiles, payback and IRR calculators for greenfield vs upgrade pathways, and sensitivity tables that stress-test ROI under energy price and throughput volatility.
-
Procurement and supplier evaluation frameworks: vendor shortlisting matrices, total cost of ownership (TCO) comparators that incorporate maintenance and yield impacts, and contract clauses to mitigate delivery and performance risk.
-
Technology and product roadmaps: comparative analysis of low-, mid- and high-energy architectures, modularity trade-offs, and likely near-term innovations (digital monitoring, remote diagnostics, hybrid EB/X-ray solutions) that buyers should require in RFPs.
-
Regulatory & compliance playbook: mapping of certification steps, typical timelines and mitigation strategies for jurisdictions that are opening to electron beam technologies.
-
M&A and partnership scouting: prioritized lists of target archetypes, diligence checklists, and estimated valuation multipliers consistent with the current market concentration and growth trajectory.
Competitive landscape — who to watch and why
The sector combines incumbent system manufacturers, regional integrators and specialized engineering houses. The following profiles summarize the strategic positioning and recent moves of core players, informing vendor negotiation and partnership strategies without disclosing proprietary market shares:
-
NHV Corporation (Japan) — A full‑spectrum manufacturer covering the entire energy range with integrated services. NHV’s recent commercial focus on production‑line monitoring reflects a broader industry shift: buyers increasingly demand operational continuity and process assurance. The company’s first‑use contract for an EPS monitoring system with a tire OEM (March 2026) and its visible presence at sector trade shows (wire 2026) signal an aggressive push to embed recurring service revenue alongside hardware sales.
-
CGN Dasheng Electron Accelerator Technology Co., Ltd. (China) — A vertically integrated designer and installer with experience in irradiation centers and high‑throughput applications. CGN Dasheng’s delivery of a system into the European market (October 2025) exemplifies cross‑regional expansion and the growing competitiveness of non‑Western suppliers on price, scale and delivery. Procurement teams should expect increasing competition on lead times and turnkey scope.
-
Vivarad S.A. (France) — Known for broad energy-range offerings and a global installed base. Vivarad’s strength lies in standardized platforms that reduce integration risk for industrial users. Their footprint is a reminder that robustness and field service networks remain decisive selection criteria for high‑uptime operations.
-
Wasik Associates (United States) — A specialist in custom, turn‑key systems geared toward niche industrial and medical applications. Wasik’s engineering‑led model is appealing for customers with non‑standard web speeds, product geometries or regulatory requirements; expect them to be a preferred partner for bespoke integrations.
-
Mevex Corporation (Canada) — Focused on linear accelerators for sterilization and materials modification. Mevex is a benchmark for performance and regulatory experience in high‑power applications; their technology roadmap is relevant for buyers prioritizing high throughput and validated sterilization processes.
-
IBA Industrial (Belgium) — Supplier of Rhodotron® accelerators and large industrial irradiation projects. IBA’s contract activity (e.g., multi‑accelerator installations) highlights the scale opportunity for OEMs that can deliver multi‑unit, high‑availability solutions.
-
Energy Sciences Inc. (United States) — A leader in low‑voltage EB systems for packaging and coatings. Energy Sciences’s product specialization underlines how targeted technology plays can command premium margins and rapid adoption in specific value chains.
Recent industry dynamics that will shape 2026
-
Service integration: the NHV EPS monitoring contract shows vendors moving beyond hardware to offer line‑level assurance services, changing how buyers assess lifecycle costs.
-
Cross-border technology flows: CGN Dasheng’s European delivery demonstrates a maturing export profile for Asian suppliers — a dynamic that is compressing price differentials and forcing incumbents to compete on service and lead time.
-
Large-scale installations: multi‑accelerator projects continue to be focal points for industrial consolidation and for players capable of end‑to‑end project execution.
Strategic implications and recommended 2026 actions
For corporates, investors and technology buyers, the report translates market trends into a concrete set of actions to prioritize in 2026:
-
Define investment triggers: use our ROI templates to identify whether to retrofit, upgrade, or greenfield — and at what throughput thresholds each option becomes preferable.
-
Negotiate for service outcomes: include performance SLAs and monitoring integration in procurement contracts to capture the value of uptime and yield improvements demonstrated by recent vendor offerings.
-
Prioritize supplier risk mapping: given moderate market concentration, create a ranked supplier map that incorporates delivery lead times, aftermarket footprint and regulatory track record to avoid single‑source exposures.
-
Adopt a staged deployment approach: pilot systems equipped with modular controls and standardized interfaces reduce upgrade cost and shorten validation cycles.
-
Explore strategic partnerships: consider co‑development or service partnerships with vendors that bring complementary strengths (e.g., an equipment supplier plus a digital monitoring specialist) to capture recurring revenue streams.
-
Use M&A pragmatically: the market structure and growth profile create opportunities to buy capability (service networks, regional approvals) rather than only capacity; our report highlights target archetypes and valuation considerations.
How to use the full report
This release is a strategic preview designed to orient 2026 planning. The full PW Consulting E Beam Accelerators Market report contains the proprietary detail needed to operationalise the recommendations above: granular scenario tables, supplier TCO models, stepwise procurement checklists, and an appendix of validated contacts for vendor due diligence.
Final note — what this preview does and does not disclose
We have provided verified macro metrics and a strategic reading of market direction to support executive planning. To preserve the investigatory value of our research and to protect client confidentiality, the report intentionally withholds specific sub‑segment revenue breakdowns and detailed region/application percentages from this public summary. For practitioners who require the full fidelity—down to segment forecasts, country‑level demand curves and vendor scorecards—the full dataset and interactive models are available through PW Consulting’s online report portal.
Next steps
-
Download the full report to access the interactive models and supplier scorecards.
-
Book a briefing with our industry team to walk through scenario outputs tailored to your use case (capex planning, supplier RFPs, M&A diligence).
-
Request a customized supplier shortlisting workshop that uses our validated frameworks and market contacts to produce an executable procurement plan within 6–8 weeks.
For detailed analysis of this topic, please visit the official page: E Beam Accelerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Used Tractors Market — Strategic Outlook for 2026: A PW Consulting Preview
As PW Consulting’s Senior Industry Analyst, I present a forward-looking briefing designed to equip C-suite leaders, dealer principals, and private equity sponsors with the strategic context they need to make high-consequence decisions in 2026. This preview synthesizes our full market study on the Used Tractors Market (base year 2025, forecast 2026–2032) — showing the high-level trajectories, risk signals, competitive moves, and the practical playbooks we provide in the full report. It intentionally demonstrates analytical depth while reserving segmented datasets and proprietary scenario outputs for the complete study.
Used Tractors Market
Market snapshot: size, trend, and what it means
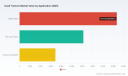
The used tractors market has emerged from a cyclical period of adjustment into a structurally larger opportunity. Our base-year assessment values the market at approximately USD 37.9 billion (2025), up materially from the start of the decade. Under the central-case assumptions embedded in our study, the market is expected to expand at a compound annual growth rate (CAGR) of 5.6% through the 2026–2032 forecast window, culminating in a market north of USD 55 billion by 2032.
Used Tractors Market
Two signals matter most for near-term strategy. First, while long-run demand fundamentals (mechanization, farm consolidation in selective geographies, and aftermarket service needs) underpin the medium-term expansion, second, near-term supply-side noise — tariffs introduced in 2025, tightening dealer inventories, and downward pressure on asking prices late in 2025 — creates a window where commercial agility will determine winners and losers.
Used Tractors Market
Contextual dynamics changing the playing field in 2026
-
Inventory and price dynamics: Used-trade inventories contracted meaningfully year-over-year entering 2026, and asking prices softened in late 2025 — a combination that compresses turnover and complicates valuation models for trade-ins and fleet purchases.
-
Dealer economics and demand: Dealer sentiment is polarized. A significant share reported declines in new-equipment sales in 2025, and nearly half reported declines in used-equipment volume — a dual headwind for traditional trade and refurb/re-sale channels.
-
Regulatory and input pressure: Broad tariff measures enacted in 2025 have squeezed margins for equipment manufacturers and altered import economics for certain models and components, driving reassessments of cross-border sourcing and refurbishment centers.
-
Digital and channel evolution: Leading OEMs and dealers are accelerating digital-direct and auction partnerships to shorten time-to-sale and broaden buyer reach — a structural shift that favors firms who can integrate inventory, inspection data, and financing at point-of-sale.
Competitive landscape — who’s shaping the market now
The used-tractors market is dominated by incumbent OEM-backed certified programs and a vigorous independent resale network. The competitive set is active on three fronts: certified pre-owned (CPO) programs with warranties and inspection protocols; refurbished-compact programs targeting smallholders and non-farm applications; and digital-auction or marketplace partnerships that expand buyer access.
-
Deere & Company — Strengthening its PowerGard Certified pre-owned channel, Deere has expanded warranty coverage and enhanced inspection protocols for high-value low-hour models, shifting more inventory through branded certified pathways and increasing buyer confidence for higher ticket second-hand purchases.
-
CNH Industrial N.V. — Through Case IH and New Holland dealer networks, CNH is pushing digital distribution, recently announcing a strategic partnership with a major online auction platform to accelerate used-equipment velocity in North America.
-
AGCO Corporation — AGCO’s certified pre-owned efforts emphasize rigorous reconditioning and extended service options across its marques, targeting value-conscious commercial operators who demand warranty-backed reliability.
-
Kubota Corporation — Kubota’s refurbishment programs for compact utility tractors focus on small-scale farmers and landscape applications in growth markets, a deliberate move to convert lifecycle units into repeatable revenue streams.
-
Mahindra & Mahindra Ltd. — Competitive pricing and broad dealer access underpin Mahindra’s strategy to capture value-led segments globally, including selective expansion in dealer channels in developed markets.
These OEM moves are complemented by independent remarketers, auction platforms, and local dealer chains — collectively keeping market concentration moderate and competition intense for high-quality trade-ins.
What the full PW report delivers (practical, executable modules)
Our full study is structured as a hands-on strategic toolkit designed to convert insight into action. Key deliverables include:
-
Executive dashboards: Interactive views of market size (historical and forecast), demand drivers, and scenario-sensitive P&L impacts tied to differing price, inventory, and financing assumptions (anchored on the 5.6% CAGR central case).
-
Dealer and OEM playbooks: Step-by-step approaches for rolling out / scaling certified pre-owned programs, optimizing refurbishment footprint, and structuring bundled warranty and service products to lift margins.
-
Channel and digital acceleration roadmap: Real-world templates for integrating auction partners, building direct-to-buyer inventory listings, and operationalizing remote inspections and logistics.
-
Valuation and M&A screens: A shortlist of capability gaps most efficiently closed via acquisition or JV, plus valuation sensitivities reflecting the current pricing volatility and tariff risk.
-
Risk & stress-testing toolkit: Tailored scenarios for tariff escalation, interest-rate shocks, and rapid inventory declines — with quantified implications for cash conversion cycles, working capital needs, and pricing floors.
Strategic priorities for leadership teams in 2026
Based on our synthesis, organizations that prioritize the following will materially improve their 12–24 month outcomes:
-
Operationalize a Certified Pre-Owned (CPO) funnel: Capture higher-margin inventory with standardized inspection, transparent history records, and warranty bundles to reduce buyer friction and recapture value that otherwise drains through informal channels.
-
Deploy dynamic pricing and inventory analytics: Build short-cycle pricing engines that incorporate ask-price trends, days-on-lot, local demand indicators, and finance availability to avoid margin erosion during transient demand softening.
-
Expand digital distribution through partnerships: Fast-track integrations with auction platforms and marketplaces to broaden buyer pools and accelerate unit turnover — critical when physical-destination demand is soft.
-
Design captive finance and warranty products: Use financing levers and extended-service contracts to increase effective buying power and smooth price discovery in buyer-constrained markets.
-
Audit supply sources and refurbishment footprints: Rebalance trade-in sourcing and regional refurbishment footprints to mitigate tariff impacts and to capitalize on arbitrage across geographies.
-
Adopt disciplined M&A and partnership scouting: Prioritize acquisitions that bring inspection technology, logistics, or digital-auction expertise rather than purely incremental unit volume.
Signals to monitor weekly
-
Inventory levels and average asking prices — early moves here presage margin compression or recovery.
-
Dealer orderbooks and finance-approval rates — tightening credit is a leading indicator of demand slowdown.
-
Regulatory developments on tariffs and cross-border movement of used equipment — these shift sourcing economics rapidly.
-
OEM program updates — warranty or inspection standard changes materially influence buyer confidence and secondary-market price realization.
Why PW Consulting’s study matters for your 2026 planning
Our research translates market-level projections (base-year 2025 and a 5.6% CAGR forecast) into executable decisions. Rather than presenting static slices, we analyze how each tactical choice (e.g., warranty terms, refurbishment depth, financing tenure) alters cash flow, inventory turn, and realized margins under stressed and optimistic demand scenarios. The deliverables bridge the gap between market intelligence and operational execution with templates, model files, and playbooks you can deploy immediately.
Importantly, this preview intentionally leaves out the granular segmentation tables and downloadable datasets — the exact regional and application-level splits, OEM-by-horsepower matrices, and the full dealer survey microdata are available exclusively in the full report. That level of granularity is essential for transaction diligence, regional network optimization, and roll-out prioritization; we reserve it for subscribers and clients who need to act on the insight.
Next steps
If you are evaluating channel investment, planning a certified pre-owned program scale-up, preparing for M&A in the remarketing space, or building risk-sensitive revenue forecasts for 2026 budgeting, PW Consulting’s full Used Tractors Market report will give your team the calibrated models, implementation checklists, and competitive intelligence necessary to move from strategy to execution. Visit the full report page to access the complete dataset, interactive scenario models, and our recommended implementation roadmaps.
For tailored briefings, bespoke scenario runs, or an executive workshop that converts the study’s strategic priorities into a 90-day operational plan, contact PW Consulting’s Industry Practice — we will co-create the playbook that aligns with your competitive position and risk tolerance.
For detailed analysis of this topic, please visit the official page: Used Tractors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Handheld Tester Market to Hit USD 774.25M by 2032 at 7.85% CAGR
By PW Consulting, 2026-07-13
Handheld Tester Market: Strategic Preview for 2026 Decision-Makers
Executive preview
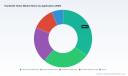
The handheld tester market is entering a strategic inflection point. After steady expansion through the first half of the decade, our baseline model shows total market revenue growing from approximately USD 312.5 million in 2020 to USD 456.5 million in 2025, with a projection to exceed USD 774.3 million by 2032. PW Consulting projects a compound annual growth rate (CAGR) of 7.85% across the 2026–2032 forecast window. These headline figures belie a nuanced landscape: pockets of high-velocity demand driven by telecom modernization and renewable deployment sit alongside mature, safety-driven volumes for electrical maintenance and industrial quality control. For executives planning capital allocation, product roadmaps, M&A, or channel investments in 2026, this preview explains where strategic value will be created — and what the full report contains to operationalize those insights.
Handheld Tester Market
Why 2026 is a decision-making pivot
-
Macroeconomic trajectory: The transition from mid-cycle stabilization (2023–2025) to renewed growth (2026 onward) amplifies the returns on investments that strategically capture expanding field testing use-cases, particularly those tied to digital infrastructure and distributed energy.
Handheld Tester Market -
Technology convergence: The convergence of RF/5G testing, integrated spectrum and vector analysis in compact handheld form factors, and smarter electrical diagnostics is reshaping product feature-sets and pricing elasticity. One recent market example is the April 2025 launch of a compact all-in-one handheld signal analyzer designed for 5G/LTE field testing — an archetype of where product development is heading.
Handheld Tester Market -
Regulatory and safety drivers: Compliance regimes (notably IEC 61010 safety requirements and relevant OSHA/NRTL expectations) reinforce ongoing replacement cycles for certified instruments, creating a durable base demand even as new segments expand.
Data-driven context (top-line only)
PW Consulting’s top-line model documents a steady recovery and acceleration of the handheld tester market. Revenues rose from roughly USD 312.5 million in 2020 to USD 456.5 million in 2025. Under our base scenario, the market reaches approximately USD 492.7 million in 2026 and sustains growth to an estimated USD 774.3 million by 2032. These figures, and the attendant 7.85% CAGR through 2032, underpin the strategic recommendations in this preview.
Competitive landscape: structure and strategic positioning
The market shows moderate concentration: the top three players account for about 38.5% of the market and the top five about 52.7%. That concentration level signals that while incumbents retain meaningful share and distribution advantages, meaningful runway exists for challengers that combine product differentiation with focused go-to-market execution.
-
Fluke Corporation (Everett, WA, USA) — Strengths in product breadth and brand trust across industrial and field applications. Fluke’s installed-base leadership and global distribution are defensive moats; future value will come from digitization of instrument telemetry and extended service offerings.
-
Megger Group (Dover, UK) — Deep expertise in insulation testing and power utility applications positions Megger to capitalize on grid modernization and asset health management tenders where domain-specific credibility matters more than feature parity.
-
Klein Tools (Lincolnshire, IL, USA) — Market credibility with electricians and contractors; channel intimacy and product ergonomics are Klein’s primary advantages. Their playbook centers on technician-centric workflows and ruggedness.
-
Siglent Technologies (Shenzhen, China) — Recent product moves into integrated RF/5G handheld analyzers signal an aggressive push on telecom field-testing. New compact all-in-one instruments illustrate a strategic bet on convergence of spectrum, VNA and cable/antenna testing in portable formats.
-
Hioki E.E. (Nagano, Japan) — Japanese manufacturing pedigree, strong multimeter and clamp-meter portfolio, and emphasis on measurement accuracy and safety certifications favor Hioki in precision-sensitive segments.
-
Seaward Electronic (Durham, UK) — Focused play in PAT testing, solar PV installers, and safety equipment channels. Seaward is an exemplar of a niche-focused strategy that extracts higher margins through adjacent services and certification training.
-
Sonel S.A. (Wroclaw, Poland) — Regional strength in Europe with offerings in insulation and power quality testing. Sonel’s value is anchored in localized service and specialized diagnostic tools.
-
Chauvin Arnoux Group (Paris, France) — Range across multimeters and environmental measurement instruments; strategic emphasis on test instruments for energy efficiency and environmental compliance.
Strategic implications by capability cluster
-
Platform and data capabilities: The winners will be those who convert handhelds into nodes within broader asset-management and field-data platforms. Investment in rugged connectivity, secure telemetry, and analytics-enabled services yields multi-year contract opportunities.
-
Product convergence: RF and electrical testing functions are converging in select handheld form factors. Vendors that reduce tool fragmentation for field technicians can command differentiated pricing and drive higher attach rates for software and consumables.
-
Channel execution: Relationships with electrical contractors, telco field crews, PV installers, and utilities remain a primary battleground. Tailored training, certification programs, and leasing/finance options materially influence procurement decisions.
-
Regulatory compliance as a growth lever: IEC and OSHA-related certification cycles create predictable replacement demand. Manufacturers that proactively certify new product lines and embed compliance workflows into devices accelerate adoption in regulated industries.
Market dynamics and near-term catalysts
-
Telecom modernization: 5G densification and ongoing tower/backhaul upgrades stimulate demand for compact RF and spectrum handhelds optimized for field calibration and antenna diagnostics.
-
Distributed energy resources: Growth in solar PV installations and microgrids increases demand for handheld PV installation testers and diagnostic tools used at point-of-installation and for service visits.
-
Industrial automation: Predictive maintenance use-cases and power quality diagnostics expand the TAM for multifunction testers that combine electrical, power-quality and environmental sensing.
-
Regulatory cycles: Safety standards and workplace certification requirements underpin a durable replacement market for certified handheld instruments.
What the PW Consulting full report delivers (practical, actionable content)
Our complete Handheld Tester Market study is built for executives who need to translate market intelligence into 2026 action plans. Key deliverables include:
-
Detailed market sizing and five-plus segmentation slices with historical and forecasted trajectories, including scenario-tested forecasts and sensitivity tables (note: segmentation detail is available in the full report).
-
Demand-driver analysis and buyer personas across contractor, utility, telco, OEM service, and industrial quality channels.
-
Vendor benchmarking matrices covering product portfolios, go-to-market models, pricing archetypes, and technology roadmaps for the core vendors profiled above.
-
Commercial playbooks: product launch checklists, channel scorecards, partnership frameworks, and a procurement-ready ROI calculator template for capex approvals.
-
M&A and inorganic growth opportunity assessment, with a prioritized list of subsegments and capability targets (including a risk-adjusted valuation model).
-
Regulatory compliance map and implementation checklist for IEC and OSHA/NRTL alignment, and a compliance-driven replacement schedule to inform service and trade-in programs.
-
Primary research appendices: interview summaries with operators, service managers, and procurement leads; supplier cost and margin models; and field-testing case studies.
Action agenda for 2026 (three pragmatic moves)
-
Prioritize platform-enabling products: If you control R&D budgets, accelerate development of connected handhelds that integrate with asset-management systems. The incremental revenue from subscriptions and data services can substantially improve lifetime customer value.
-
Lock the channel with training and financing: For vendors and distributors, invest in scaled training programs and flexible financing to lower adoption friction for higher-priced multifunction instruments.
-
Scan for bolt-on capabilities: For M&A-seeking strategists, target niche specialists that provide validated compliance credentials, localized service networks, or unique RF/antennal testing IP that accelerates entry into telecom and renewable segments.
Limitations and where to find the granular intelligence
This preview purposely presents top-line market dynamics and strategic implications to guide executive thinking. To preserve the value of our proprietary analysis and to support procurement and investment decisions, detailed segmentation percentages, region-by-region splits, application-level revenue breakdowns, and full vendor share tables are available exclusively in the full PW Consulting report. Those granular data and model files provide the precise inputs needed for capex approvals, channel deployment planning, and target valuations.
Closing: How PW Consulting helps you move from insight to impact in 2026
Our handheld tester study combines quantitative forecasting with field-level validation to create an operational roadmap. Whether you are a market leader defending installed base, a challenger seeking scaled growth, or a private equity sponsor evaluating consolidation plays, the full report contains the playbooks, templates, and model outputs to convert the projected 7.85% CAGR and the evolving competitive dynamics into executable advantage. For access to the complete dataset, vendor market shares, and the action-ready appendices, consult the PW Consulting report landing page or contact our industry team for a briefing.
For detailed analysis of this topic, please visit the official page: Handheld Tester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Belt Tensioner Market at USD 1,609.85M in 2025; 6.08% CAGR (2026–32)
By PW Consulting, 2026-07-13
Industrial Belt Tensioner Market: Strategic Preview for 2026 Decision-Making
Executive snapshot
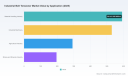
As supply chains recalibrate and industrial operators push for higher uptime and lower energy consumption, the industrial belt tensioner market is entering a phase of steady expansion. Our analysis places the market at approximately USD 1.61 billion in 2025 (base year), with a compound annual growth rate (CAGR) of 6.08% through the 2026–2032 forecast window. By the end of the forecast horizon, the market is projected to surpass the USD 2.4 billion mark — an incremental growth profile that carries meaningful implications for manufacturers, OEMs, aftermarket specialists, and industrial end-users planning their 2026 strategies.
Industrial Belt Tensioner Market
Why this matters for 2026 planning
For executives building 12–36 month plans, three market realities — predictable mid-single-digit growth, moderate industry concentration, and heightened input-cost volatility — should drive resource allocation decisions now. The reported CR3 of 38.5% and CR5 of 52.7% indicate a market where leading companies hold meaningful advantage but leave scope for challengers and niche specialists. That structure rewards scale and product breadth, yet also offers space for focused innovation and services-based differentiation.
Industrial Belt Tensioner Market
Macro trajectory and the strategic levers it opens
-
Growth with room to differentiate — The mid-single-digit CAGR translates into a market that is large enough to support investment in product development, but not so concentrated that incumbents are immune to disruption. Companies that link product performance to measurable energy or reliability gains can capture premium positioning across both OEM and aftermarket channels.
Industrial Belt Tensioner Market -
Aftermarket and services as margin multipliers — With industrial operators prioritizing uptime, predictable tension management, and simpler maintenance, aftermarket programs (condition monitoring, rapid-replacement kits, integrated service contracts) present an outsized opportunity to increase lifetime value beyond initial hardware sales.
-
Capital allocation must balance scale and agility — Given the market’s projected steady expansion, investments in modular manufacturing capacity and configurable platforms (to serve multiple belt types and environments) will offer faster payback than large, bespoke facilities aimed at single large customers.
Key strategic themes for 2026
-
Operational resilience vs. cost volatility — Raw material swings (natural rubber and steel have shown 20–35% annual fluctuations in recent industry data) materially affect BOM costs. Hedging programs, dual sourcing, and design-to-cost initiatives should be elevated in procurement and R&D roadmaps to protect margins without sacrificing product performance.
-
Energy-efficiency differentiation — Regulatory moves in major markets (e.g., EU emissions standards updates in March 2025 that encourage energy-efficient industrial components) create a commercial lever. Positioning tensioners as part of broader energy-optimization solutions (reduced slip, optimized tension curves) will accelerate adoption in regulated geographies.
-
Smart tensioners and digital services — Condition monitoring, predictive maintenance algorithms, and integrated sensor packages are emerging as purchase drivers among higher-value industrial customers. A phased approach — sensor-ready mechanical platforms in 2026 followed by subscription analytics — is a pragmatic commercialization route for many manufacturers.
-
Channel and aftermarket models — For many players, the fastest route to improved margins is expanding aftermarket coverage, technical training for distributor networks, and bundled service contracts rather than competing primarily on component price.
Competitive landscape — what to watch
The market is characterized by a mix of global diversified suppliers and regionally focused specialists. Key competitors include established industrial brands with broad portfolios and engineering depth, as well as ISO-certified niche manufacturers that offer customized solutions for specific industrial drives.
-
Large portfolio players (examples): These companies bring scale, distribution reach and product breadth. Their advantages include engineered systems for heavy-duty applications, global aftermarket footprints, and established OEM relationships. These firms are likely to compete on systems integration (tensioner + pulley + bearing) and aftermarket services.
-
Specialists and niche players: Companies with focused product families (e.g., timing-belt tensioners, self-adjusting rotary units) are well-positioned to win in verticals where precision and customization matter. They can command premium pricing in targeted segments by solving fit-and-function challenges that commoditized suppliers cannot match.
-
Recent competitive moves: Industry product expansion and trade-show showcases in 2025 signal continued investment in application breadth and aftermarket positioning. Select players launched heavy‑duty tensioners and expanded North American lineups, while others used exhibitions to highlight broader accessory drive portfolios — indicating that both product depth and market visibility will be active battlegrounds in 2026.
Strategic implications by capability
-
R&D: Prioritize modularity and sensor readiness. Short development cycles for retrofit-friendly designs win share in conservative industrial segments that resist full system redesigns.
-
Supply chain: Implement commodity hedging and qualify alternate raw-material partners. Where possible, re-engineer parts to reduce dependence on the most volatile inputs without degrading performance.
-
Commercial: Build aftermarket subscription pilots and develop distributor enablement programs. Emphasize total cost of ownership benefits in bid responses rather than component-level price cuts.
-
M&A and partnerships: Target acquisitions that add sensor/analytics capability, aftermarket service teams, or regional distribution density. Given a moderately concentrated market, bolt-ons can quickly lift CR positioning and expand addressable aftermarket share.
Report: what you’ll find inside (operationally oriented)
Our full Industry Belt Tensioner Market study is structured to be directly actionable for teams executing 2026 plans. Highlights include:
-
Market sizing and scenario-based forecasts (2026–2032) with sensitivity analysis for commodity price and regulatory shocks.
-
Commercial playbooks tailored for OEM, aftermarket, and channel strategies including pricing templates and warranty models.
-
Technology and product roadmaps mapping mechanical, electro-mechanical and sensor-integrated tensioner solutions by use-case.
-
Supply-chain risk registers and procurement playbooks (including dual-sourcing checklists, hedging options, and inventory buffers tuned to a 20–35% input-price volatility environment).
-
Competitive benchmarking and a prioritized M&A target list (qualitative fit/gap analysis focused on capability and geographic expansion).
-
Five executable 90‑day initiatives for commercial, engineering and procurement teams to generate early wins in 2026.
Risk register — what can derail 2026 plans
-
Input-cost shocks: Large swings in prices for rubber and steel can erode margins rapidly. Scenario planning and early supplier engagement are non-negotiable.
-
Regulatory divergence: As some regions accelerate energy-efficiency mandates, suppliers lacking energy-optimized solutions may face barriers to entry in key industrial markets.
-
Channel resistance to innovation: Many industrial maintenance organizations are risk-averse. New sensor-based approaches will require dealer training and proof points (pilot outcomes) to scale.
90‑day tactical playbook (for 2026 Q1 implementation)
-
Commercial: Launch two aftermarket subscription pilots targeting verticals with high downtime costs; structure pricing to demonstrate payback within 12 months.
-
Product: Freeze a "sensor-ready" mechanical platform and develop a retrofit kit targeting the top three industrial drive configurations identified in our research.
-
Supply chain: Execute dual-sourcing qualification for at least two critical inputs and set up quarterly price review triggers tied to hedging strategy.
-
M&A scouting: Open confidential discussions with one regional aftermarket provider whose technical footprint complements your distribution network.
Conclusion — the strategic choice for 2026
The industrial belt tensioner market presents a balance of steady, addressable growth and tactical battlegrounds where product, service and supply-chain choices determine winners. For 2026, the most defensible strategies are those that combine modular product platforms, expanded aftermarket offers, and procurement approaches that neutralize raw-material volatility. Market concentration leaves room for both scale players and nimble specialists to prosper — the winner will be the firm that pairs engineering depth with clear commercial models that demonstrate immediate operational ROI to industrial customers.
Next steps
This preview outlines the strategic value our full report delivers to executives preparing 2026 budgets and go-to-market plans. For the complete data tables, segmented forecasts, competitive scorecards and the detailed 90‑day templates referenced above, please view the full PW Consulting Industrial Belt Tensioner Market report on our website.
For detailed analysis of this topic, please visit the official page: Industrial Belt Tensioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Tailgate Radar Market to Grow at 8.65% CAGR to 2032
By PW Consulting, 2026-07-13
Electric Tailgate Radar Market — Strategic Briefing for 2026
This briefing distills the strategic implications of PW Consulting’s forthcoming Electric Tailgate Radar Market study and explains why procurement, product, and corporate strategy teams should prioritise the report when making decisions in 2026. The study consolidates five years of historical performance (2020–2025), uses 2025 as the base year, and projects the market across a 2026–2032 forecast horizon. At a compound annual growth rate (CAGR) of 8.65%, the market trajectory and concentration dynamics present both clear opportunities and specific risks for OEMs, Tier‑1 suppliers, semiconductor vendors, and investors.
Electric Tailgate Radar Market
Executive snapshot: what this briefing conveys
- Macro view: the electric tailgate radar market has more than doubled since 2020 and is on a steady growth path into 2032 (base year 2025, forecast period 2026–2032), driven by feature demand, cost declines, and regulatory alignment for mmWave operation.
- Why it matters in 2026: component availability, standards compliance, and the competitive supplier landscape will determine which OEM programs secure reliable, scalable hands‑free tailgate experiences.
- What PW Consulting’s full report delivers: actionable procurement playbooks, vendor scorecards, technology roadmaps, and scenario-based financial models designed for near-term sourcing and multi‑year product planning.
Market trajectory and the investment case
The broader market has expanded materially from the early 2020s into 2025 and is forecast to continue growing through 2032. This expansion is underpinned by three converging forces: consumer preference for convenience and perceived luxury, OEM standardisation of perimeter sensing for safety and regulatory compliance, and incremental cost reductions in millimetre-wave (mmWave) components and integration platforms. For decision‑makers, the headline numbers — including the 8.65% CAGR embedded in our forecast — quantify the scale of opportunity and justify near-term investment in integration, testing, and procurement pipelines.
Electric Tailgate Radar Market
Crucially, the market is not homogeneous. Adoption curves differ by vehicle architecture, regional regulatory timetables, and OEM platform strategies. That heterogeneity creates differentiated earnings potential for component suppliers and integration partners — and it is deliberately where the tactical value of PW Consulting’s study becomes most usable: to translate macro growth into programme-level decisions without overexposure to commoditisation risk.
Electric Tailgate Radar Market
Regulatory and supply‑chain environment (implications for 2026)
- Standards and frequency compliance: Updated regulatory frameworks for radar operation (including recent UN ECE and regional telecom authority updates) have clarified permissible bands and interoperability expectations for 79 GHz implementations. For vehicle programmes launching in 2026 and beyond, alignment with these standards is a gating factor for cross‑market rollouts.
- Functional safety expectations: Industry guidance reinforces ISO 26262 requirements for obstacle detection systems; ASIL‑B compliance is now a common expectation for radar sensors used in power tailgate obstacle mitigation. Programmes that treat functional safety as an afterthought will face integration delays and certification bottlenecks.
- Semiconductor supply dynamics: Supply‑chain normalisation has improved lead times for mmWave radar chips in early 2026, reducing component lead times materially versus the constrained years that preceded it. This change improves the feasibility of multi‑sourcing strategies and shortens new program ramp timelines.
Competitive landscape — what matters when choosing partners
The vendor landscape combines established automotive suppliers, specialist radar vendors, and semiconductor incumbents. Market concentration metrics reveal moderate consolidation: the top three firms capture a meaningful portion of sales, while the top five increase that share further, creating a marketplace where technical differentiation and program relationships matter more than pure scale alone.
- Tier‑1 integrators: Suppliers with electro‑mechanical system expertise and proven production ramps — particularly those offering turnkey electric tailgate drives and sensor integration — are best positioned to win vehicle content. Their value proposition is the consolidation of mechanics, control electronics, and validated sensor interfaces, which shortens OEM validation cycles.
- Radar specialists and module providers: Companies focused on mmWave sensing bring specialized detection algorithms and compact form factors that matter for packaging and false‑trigger robustness. Their competitive edge is product maturity in real‑world foot‑gesture detection and reduced nuisance activations in complex rear bumper environments.
- Semiconductor and IC suppliers: Chip providers enable system differentiation through advancements in signal processing, low‑power operation, and integration density. Their roadmaps constrain or enable product features; selection of an IC family is a multi‑year commitment for integrators and OEMs alike.
To illustrate the strategic positioning that matters (without disclosing proprietary dynamics), consider these vendor archetypes represented in the market: specialised radar companies that supply compact 79 GHz kick sensors optimized for hands‑free gestures; Tier‑1s that provide integrated power tailgate systems with validated radar interfaces; and semiconductor firms offering mmWave SoCs and radar front‑ends enabling feature differentiation. Recent market activity underlines these archetypes: a series production order for a 79 GHz kick sensor demonstrates OEM readiness for high‑frequency mmWave solutions; trade show showcases highlight integrators revealing hybrid sensor stacks combining UWB and radar; and SoC advancements continue to boost the performance envelope for contactless control.
Report contents — practical outputs for 2026 decision cycles
The full PW Consulting Electric Tailgate Radar Market study is structured to move teams from insight to action. Key deliverables include:
- Market sizing and forecast (2020–2032) with scenario variants tied to component cost curves and regulatory horizons.
- Vendor scorecards and procurement playbooks that evaluate suppliers across technical fit, production readiness, safety compliance, and commercial terms.
- Integration checklists and test protocols for radar kick sensor systems, including guidance on ASIL‑level testing, EMC/EMI strategies, and environmental validation.
- Supply‑chain resilience frameworks and dual‑sourcing decision matrices reflecting the improved but still fragile semiconductor environment.
- Go‑to‑market and product roadmap templates for OEMs considering platform‑level adoption versus optional content strategies.
- Financial models and TCO calculators that convert market forecasts into programme‑level revenue and margin projections under conservative and aggressive uptake scenarios.
Strategic playbook — 6 pragmatic moves for 2026
- Lock in standards compliance early: require suppliers to evidence UN/region‑specific frequency conformity and ISO 26262 artefacts during RFQs to avoid downstream re‑work.
- Prioritise integration partners with validated production ramps: choose vendors who can demonstrate series production orders or equivalently rigorous pilot programmes.
- Adopt hybrid sensing roadmaps: combine radar with UWB or proximity sensors selectively to optimise user experience and reduce false activations in complex rear‑end geometries.
- Mitigate single‑source risk: build dual‑sourcing strategies for critical mmWave components while negotiating volume de‑risk clauses tied to lead‑time improvements.
- Embed safety early: require ASIL‑level validation gates and obstacle detection failure mode analyses in supplier contracts to accelerate homologation and reduce recall risk.
- Use pilot programmes to de‑risk UX: short, instrumented pilot runs in diverse climatic and regulatory environments uncover edge cases that lab tests miss and protect brand experience at launch.
Why PW Consulting’s research is essential for 2026 decision‑making
Procurement and product leaders face a narrow window in 2026 to lock design choices and supplier commitments that will govern platform roadmaps through the late 2020s. The combination of steady market growth, evolving standards for mmWave operation, and improved component availability creates an environment where early but well‑informed investments yield sustained advantage. PW Consulting’s study converts macro signals — the measured CAGR and aggregate market size trajectory — into concrete vendor comparisons, risk matrices, and cost scenarios that materially reduce execution risk.
Importantly, this briefing purposefully omits the granular regional, type, and application split tables that underpin the full analysis. Those segment‑level datasets, supplier program timelines, and downloadable procurement templates are available only in the complete report — the content prospective buyers tell us delivers immediate ROI by shortening procurement cycles and improving launch predictability.
Closing: immediate next steps
Teams preparing for 2026 program decisions should prioritise three actions this quarter: (1) secure access to the full market study and vendor scorecards, (2) schedule cross‑functional workshops to align safety, procurement, and systems engineering on ASIL and frequency compliance requirements, and (3) commence pilot validations with at least two radar or hybrid sensor suppliers to validate real‑world gesture reliability and integration timelines.
PW Consulting’s Electric Tailgate Radar Market study is designed to be the single operational reference for those actions — marrying market sizing, regulatory context, supplier intelligence, and executable procurement collateral into a compact package for 2026 decision cycles.
For a guided walkthrough of the report’s practical modules and the vendor playbooks, request access through our publication page. Our research team can provide a tailored briefing that maps the analysis directly to your product roadmaps and sourcing calendar.
For detailed analysis of this topic, please visit the official page: Electric Tailgate Radar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Interior Lighting Market Forecast at 6.85% CAGR to 2032
By PW Consulting, 2026-07-13
Aircraft Interior Lighting Market — Strategic Preview for 2026 Decision-Makers
Executive preview
The Aircraft Interior Lighting market has evolved from a largely functional element within cabin outfitting to a strategic lever for airlines, OEMs and Tier‑1 suppliers. Our PW Consulting market study establishes a clear, actionable roadmap for 2026 planning cycles: the global market — measured in USD million — has expanded rapidly since 2020 and is projected to continue appreciating at a healthy mid-single‑digit compound annual growth rate (CAGR). By 2025 the industry reached roughly USD 1.45 billion, and under our base case projections the market is expected to surpass USD 2.3 billion by 2032, reflecting a 2026–2032 CAGR of approximately 6.85%.
Aircraft Interior Lighting Market
This paper previews the strategic implications of those macro dynamics. It demonstrates why lighting is no longer a commodity line‑item but a cross-functional investment that touches passenger experience, weight and power budgets, maintenance cycles, retrofit economics, and regulatory compliance. The goal here is to show the depth of our analysis and the practical frameworks we provide, while preserving the proprietary granular splits and sensitive segmentation data that are available in the full report.
Aircraft Interior Lighting Market
Why lighting matters to enterprise strategy in 2026
- Experience as differentiation: Airlines increasingly treat lighting systems as a brand medium—dynamic mood lighting, individualized reading lights, and circadian rhythm-aware systems now influence ancillary revenue, loyalty programs, and brand perception.
- Operational economics: The industry’s rapid LED/OLED adoption delivers measurable lifetime cost reductions through energy savings, longer service life, and lower maintenance man‑hours versus legacy systems. These benefits compound across fleets, making lighting upgrades an attractive investment for both newbuild and retrofit programs.
- Regulatory and certification gatekeeping: Compliance with EASA CS‑25, FAA TSO standards and SAE specifications remains a compulsory baseline. Successful certifications shorten time‑to‑market and open aftermarket opportunities—critical levers in 2026 decision models.
- Consolidation and supplier concentration: Market concentration metrics show a landscape where a limited number of Tier‑1 players command a meaningful share of industry revenues, creating both barriers and partnership opportunities for challengers and non‑traditional entrants.
Market trajectory and what it means for 2026 budgets
The historical trajectory from 2020 through 2025 demonstrates a robust recovery and structurally higher demand driven by fleet renewals, retrofit waves, and OEM platform launches. With the forecast path to 2032 underpinning a roughly 6.85% CAGR, CFOs and product leaders should reframe cabin lighting from capex cost center to a portfolio asset that influences fuel and maintenance economics, passenger metrics, and retrofit revenue streams.
Aircraft Interior Lighting Market
Practically, this implies shifting budget practices in three ways: (1) increase capital allocation for integrated lighting systems that bundle hardware, controls and software services; (2) fund certification and regulatory programs as part of product launch costs; and (3) reserve spend for after‑sales services and STC development to monetize the retrofit aftermarket.
Key dynamics shaping supplier strategy
- Technology transition: The move from legacy incandescent/fluorescent to LEDs and emerging OLEDs provides energy, weight and lifetime advantages. Technology selection increasingly emphasizes tunability, color rendering (high CRI) and reliability over unit price.
- Human‑centric lighting: Systems tuned for biological rhythms and passenger well‑being are gaining traction. Airlines are piloting circadian lighting profiles to reduce jet lag and improve customer satisfaction scores, creating product roadmaps that fuse psychology, software control and hardware design.
- Retrofit opportunity: A meaningful share of near‑term revenue will come from retrofit programs. Industry benchmarking shows typical LED upgrade packages for regional aircraft are in the order of magnitude that makes retrofit economically viable—opening a sizeable after‑market TAM for certified suppliers.
- Certification and standards: Regulatory scaffolding (EASA CS‑25, FAA TSO, SAE standards) both constrains and validates new entrants. Certification investments accelerate market acceptance and significantly increase addressable aftermarket opportunity.
- Supply chain and materials: Component availability (LED chips, controllers, optical materials) and materials costs are a recurring source of margin volatility. Suppliers with vertical relationships or diversified sourcing show resilience during supply disruptions.
Competitive landscape — strategic positions and implications
The market is dominated by established aerospace players and specialised lighting houses. Our competitive analysis highlights how leading firms are positioning around integrated systems, certification depth, and aftermarket service capabilities.
- Collins Aerospace (RTX): A broad, integrated portfolio spanning interior and exterior systems gives it scale advantages for OEM programs. Investments in advanced panels and color‑management systems make Collins a default partner for complete cabin programs. For challengers, winning small modules or retrofit niches requires clear differentiation on certification speed and STC portfolios.
- Diehl Aviation: With decades of cabin lighting leadership and deep OEM relationships, Diehl’s emphasis on human‑centric lighting and integrated cabin aesthetics makes it a prime partner for full‑cabin refreshes. Their presence at AIX underlines a go‑to‑market strategy that combines design and system integration.
- Safran Cabin: Safran’s strengths in high CRI solutions and modular galley/lavatory products position it well for airlines prioritizing passenger perception and durability. Safran’s retrofit supportability is a differentiator for fleet upgrades.
- Astronics Corporation: Focused innovation—particularly in RGBW ambient solutions—drives Astronics’ appeal across commercial and business aviation segments. Their niche focus on passenger experience technologies supports aftermarket growth.
- STG Aerospace (Heads Up Technologies): Specialization in full LED cabin systems and plug‑and‑play retrofit kits give STG agility in capturing mid‑market retrofit demand, particularly where fast STCs are a requirement.
- SCHOTT AG, Luminator, Bruce Aerospace, Aircraft Lighting International, American Bright LED: These firms provide a mix of decorative components, STC portfolios, customized module manufacturing and PMA‑certified systems that together form the long tail of the supplier ecosystem. Their strengths are customization, certification flexibility and responsiveness—key attributes for airlines seeking tailored solutions.
Recent trade show activity and certifications — from Diehl’s AIX showcases to Aircraft Lighting International’s FAA‑approved RGBW systems — reflect an industry balancing innovation with the deliberate pace of aviation certification. These developments signal where early adopter customers will direct 2026 procurement spend.
What our full report delivers (practical, implementable content)
PW Consulting’s full Aircraft Interior Lighting Market report goes beyond high‑level forecasts to provide the tools procurement, product and corporate strategy teams need for 2026 decisions. Deliverables include:
- Dynamic forecast models (2026–2032), sensitivity scenarios and revenue drivers segmented by the report’s established axes.
- Proprietary supply‑side database, supplier capability maps and a supplier selection matrix tailored to OEM, MRO and retrofit channels.
- Cost‑build and pricing benchmarks for LED and OLED systems, plus example retrofit ROI models that translate system-level specs into fleet economics.
- Regulatory playbook summarising certification pathways (EASA/FAA/SAE), timelines and cost envelopes associated with typical product introductions and STCs.
- Competitive profiles and M&A/partnership target shortlists ranked by technical competency, certification assets and market coverage.
- Commercial go‑to‑market frameworks for airlines and integrators—covering sales motion for newbuilds versus retrofits and post‑sales service monetization strategies.
- Case studies and implementation checklists that reduce time‑to‑value for pilots and fleetwide rollouts.
Strategic recommendations for 2026
- Prioritise modular, software‑enabled systems: Invest in lighting platforms that separate hardware from control software to accelerate upgrades and ancillary revenue (light profiles, subscription features, analytics).
- Accelerate certification investments: For suppliers, certification is a competitively defensible moat. Allocate development funding into EASA/FAA compliance early in the product lifecycle to shorten OEM qualification windows.
- Target retrofit economics: Develop standardized STC packages and installation playbooks to capture near‑term aftermarket demand. Rapid STC delivery is a commercial advantage.
- Leverage human‑centric differentiation: Airlines and integrators should use circadian and mood lighting as part of premium product bundles to enhance ancillary revenue and passenger loyalty.
- Plan for supply resilience: Secure multi‑source supply agreements for critical components and consider strategic inventory buffers for long lead items to avoid program delays.
- Consider targeted M&A: Buyers seeking rapid entry into higher‑value lighting systems should evaluate acquisitions that bring certification assets, STC portfolios or software stacks.
Closing — the strategic value of our study for 2026
For leaders making 2026 budget and portfolio decisions, the Aircraft Interior Lighting market is a high‑leverage domain: it influences operational cost, passenger experience, retrofit monetization and supplier strategy. PW Consulting’s study synthesizes a proprietary dataset, scenario forecasts and actionable go‑to‑market frameworks to help executives convert lighting investments into measurable financial and brand outcomes.
To access the complete datasets, detailed regional and application splits, supplier scorecards and the practical implementation checklists referenced here, please consult the full report and supporting annexes on our website. The strategic window for shaping fleet experience and capturing aftermarket value is open—companies that act with clarity on certification, modularity and retrofit enablement will consolidate advantage through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Aircraft Interior Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bottle Valve Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking synthesis of our Bottle Valve Market research designed to equip executives with the context and strategic options they need to act confidently in 2026. The sector is entering a sustained growth phase: after a recovery from USD 812.45 million in 2020 to USD 1,275.6 million in 2025, our model projects the market will reach approximately USD 2,216.06 million by 2032, representing an 8.2% compound annual growth rate across the 2026–2032 forecast window. This growth trajectory repositions bottle valves from a mature component market into a strategic battleground for innovation, consolidation, and regulatory compliance.
Bottle Valve Market
Why 2026 Is an Inflection Year
-
Regulatory reset and product reformulation: New regulatory moves — notably tighter U.S. EPA VOC standards introduced in January 2025 and continued enforcement of EU aerosol safety directives — are reshaping product formulations, packaging choices, and compliance costs. These rules increase the premium on valve and dispenser designs that enable lower-volatility chemistries, metered dosing, or inert propellant systems.
Bottle Valve Market -
Cost and margin pressure driven by technology choices: Emerging dispensing formats such as Bag‑on‑Valve (BoV) and smart metered valves deliver clear value propositions (longer shelf life, cleaner dispensing, improved dosing control), but they carry materially higher manufacturing costs versus legacy designs — a multiple rather than a marginal delta. That trade-off is now central to commercial decisions across personal care, pharmaceuticals, and household segments.
Bottle Valve Market -
Competitive consolidation accelerates: The industry sits in a middle zone of concentration — sufficient scale at the top to influence standards and cost benchmarks, and enough fragmentation elsewhere to make M&A an attractive lever for rapid capability acquisition. Recent transactions and leadership moves are already reordering supplier capabilities and go-to-market footprints.
-
End-market resilience and diversification: Demand drivers are broadening. Traditional volume engines such as personal care and household remain important, but the pharmaceutical and technical segments are growing faster in value terms due to tighter quality and traceability requirements. This mixes stable recurring demand with pockets of above‑average margin opportunities.
What the Full Report Delivers (Practical, Executable Content)
-
High‑resolution market sizing and forward scenarios: A validated time series (2020–2025) and scenario‑based projections for 2026–2032, with sensitivity analysis across raw‑material cost, regulatory stringency, and adoption rate of premium dispensing technologies.
-
Go‑to‑market playbooks by product strategy: Decision matrices for choosing between conventional valves, BoV, metered and smart dispensers — including total cost of ownership, margin impact, and time‑to‑market considerations.
-
Competitive scorecards and capability maps: Proprietary assessments of leading suppliers’ technology stacks, production footprints, regulatory certifications, and route‑to‑market strengths — enabling rapid shortlist construction for sourcing and M&A diligence.
-
Regulatory impact toolkit: Action checklists and compliance roadmaps tailored to the U.S. EPA VOC changes, EU Aerosol Dispensers Directive compliance, and tariff exposure scenarios relevant to filled aerosols and derivative articles.
-
Supply‑chain risk heatmaps: Supplier concentration analysis, critical component exposure (elastomers, specialized actuators), and recommended contracting strategies to minimize disruption and cost creep.
-
Commercial models and pricing playbooks: Elasticity frameworks calibrated to product type and end‑market sensitivity, plus playbooks for capturing premium pricing in pharma and high‑performance personal care segments.
-
M&A and partnership targets: A prioritized list of acquisition, JV, and co‑development candidates mapped to capability gaps and go‑to‑market ambitions (note: granular target financials and valuation models are available in the full report).
Competitive Landscape — Who Matters and Why
The industry’s top end combines legacy aerosol specialists, precision component manufacturers, and gas‑handling incumbents. The market concentration profile (three‑firm and five‑firm concentration indices) indicates enough room for both organic scaling and inorganic repositioning. Key players to watch and the strategic signals they send:
-
Precision Valve Corporation — A long‑standing leader in aerosol valves and actuators with deep product breadth across tilt, 360‑degree, metered, powder, and Bag‑on‑Valve solutions. Their recent leadership change and an award for new SMART 35 valve technology highlight a deliberate pivot toward innovation-led differentiation and premium product segments. For customers, Precision’s trajectory suggests a partner for high‑performance dispensing strategies and co‑development of next‑generation metering systems.
-
Control Devices / Sherwood Valve — The acquisition of Sherwood Valve (announced January 2026) expands Control Devices’ footprint into high‑pressure and compressed‑gas valve systems. This move underscores a broader consolidation trend and signals cross‑sell opportunities between industrial gas control and packaged‑goods dispensing technologies. Competitors and customers should reassess supplier roadmaps for integrated valve solutions that span both low‑ and high‑pressure applications.
-
AptarGroup — A major global provider with strong penetration in pharmaceutical and beauty markets. Aptar’s continued emphasis on validated dispensing systems and regulatory compliance makes it a natural anchor supplier for firms prioritizing launch speed and compliance in regulated end markets.
-
Lindal Group, Coster, Mitani — European and Asian specialists that collectively pressure the leading incumbents on technology, regional capability, and filling‑line compatibility. Their innovation pipelines for actuators and BoV designs make them go‑to partners for product variants and regional packaging strategies.
-
Cavagna, Rotarex, GCE Group — Firms rooted in gas cylinder valves and regulators that are increasingly relevant where cross‑application expertise (e.g., pressurized systems, safety standards) matters. Their competence in high‑pressure safety, standardization, and certification is becoming diffused into adjacent bottle valve opportunities.
Strategic Implications — How Executives Should Act in 2026
-
Reassess the product roadmap with regulatory scenarios in mind. Treat regulatory shifts as demand catalysts for metered and low‑VOC solutions rather than only as cost burdens. Prioritize development projects that improve compliance while delivering measurable consumer benefits (e.g., dosing accuracy, reduced waste).
-
Adopt a hybrid sourcing strategy. Combine partnerships with Tier‑1 innovators for premium dispensing needs and regional, cost‑competitive suppliers for high‑volume commodity valves. Lock in long‑lead supplier agreements for critical components where price and capacity risk are concentrated.
-
Targeted M&A and alliances. Use M&A to buy specific capabilities (smart metering, BoV expertise, high‑pressure valve technology) rather than scale for scale’s sake. The recent Control Devices–Sherwood deal illustrates how inorganic moves can rapidly fill capability gaps and open new adjacent markets.
-
Embed margin analytics into product design. Because premium valve formats carry higher unit costs, build margin models into early product development decisions to ensure pricing, claims, and channel strategies align with true landed cost and value capture.
-
Invest selectively in digital and smart capabilities. Metered and “smart” valves are a gateway to premium differentiation in regulated categories such as pharma and personal care. Prioritize interoperable architectures and data capture that can be monetized via services (e.g., adherence tracking, refill reminders) in regulated channels.
-
Scenario‑test tariff and trade policy risk. Filled aerosol packages and derivative articles face evolving tariff scrutiny; run scenario analyses on near‑term supply chain decisions and consider reshoring or regionalization where trade policy adds material cost or risk.
Using This Report to Shape Your 2026 Plan
Executives should use this research as a decision engine: combine the market’s macro trajectory with supplier scorecards to prioritize three to five initiatives for 2026 that will materially change your competitive position by 2028. Typical priority bundles we help clients operationalize include (1) a product+pricing reoptimization for premium formats, (2) a supplier consolidation and cost‑locking program, and (3) one inorganic move to add strategic capability.
PW Consulting’s full Bottle Valve Market report contains the underlying datasets, scenario models, company scorecards, and executable playbooks referenced above. To protect the commercial value of proprietary segmentation and target valuations we present a directional summary here; the full granular breakdowns (regional and application splits, supplier financials, and downloadable model files) are available in the expanded report and digital appendices on PW Consulting’s website.
If your 2026 plan depends on seizing share in evolving dispensing formats, capturing margin in regulated channels, or using M&A to leapfrog capability gaps, this research is built to be the operational blueprint you need to move from intention to impact.
For detailed analysis of this topic, please visit the official page: Bottle Valve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Precision Agriculture GNSS Guidance Market to Reach USD 3,530M by 2025 (CAGR 8.75%)
By PW Consulting, 2026-07-13
Precision Agriculture GNSS Guidance Systems: Strategic Imperatives for 2026 Decision-Makers
Executive preview
As PW Consulting’s lead industry analyst, I present a concise strategic briefing on the Precision Agriculture GNSS Guidance System market designed to inform boardrooms, product leaders, and corporate strategists preparing plans for 2026. The market has shifted from niche instrumentation to a core productivity lever in modern farming — driven by higher precision requirements, retrofit demand across mixed fleets, and a rising policy tailwind for technology adoption. Our full market study provides the granular segmentation, vendor benchmarking, and decision-grade tools to convert insight into commercial action. This introduction highlights the study’s strategic value while deliberately withholding the detailed sub‑segment matrices that make the full report a must‑have for tactical planning.
Precision Agriculture Gnss Guidance System Market
Market trajectory and what it means for strategy
- Macro growth dynamic: The global market for GNSS guidance systems expanded strongly through the early 2020s and reached approximately USD 3.53 billion in 2025. Our modeling projects continued expansion to roughly USD 3.88 billion in 2026 and to about USD 6.35 billion by 2032 — implying a compound annual growth rate of 8.75% over the forecast horizon.
- Commercial implications: A near‑double market scale compared with early‑decade baselines means product managers should assume a larger total addressable market, but one that is maturing. Incumbents can leverage installed bases and ecosystems; challengers must target niches or deliver disruptive TCO advantages to gain share.
- Concentration signal: Market concentration is meaningful — the top three vendors account for a majority share, with the top five capturing roughly seven in ten dollars. This concentration informs realistic go‑to‑market scenarios for new entrants (partnerships and retrofit channels), and for OEMs evaluating vertical integration versus open‑platform strategies.
Why this study matters to 2026 decisions
For strategic leaders, 2026 is a hinge year: the macro tailwinds for adoption — subsidies, improved correction services, and automation enablers — intersect with technology inflection points in sensor fusion, PPP/RTK performance, and vehicle autonomy. Decisions made in 2026 will define product roadmaps, channel investments, and M&A posture for the rest of the decade. This report is tailored to support those high‑stakes choices by translating market forecasts into operational priorities:
Precision Agriculture Gnss Guidance System Market
- Portfolio prioritization: identify which GNSS guidance modalities and integrated/autosteer solutions to accelerate in product roadmaps, and which to harvest or sunset.
- Channel and retrofit economics: quantify the commercial potential of universal retrofit devices versus factory‑installed solutions across mixed fleets and consolidation scenarios.
- M&A and partnership playbooks: map targets and partnership archetypes (correction services, autonomous implement steering, vision stacks) that accelerate market access without bearing full hardware cost and distribution risk.
Strategic themes that will shape winners and losers
- Resilience and performance: GNSS performance during ionospheric disturbance and nominal outages will be a competitive divider. Recent technology releases specifically addressing ionospheric resilience — and hybrid correction models combining RTK, PPP and local augmentation — create a new baseline for field reliability.
- Ecosystem vs. universality: Vendors that lock customers into end‑to‑end ecosystems can deliver higher per‑unit value via integrated telemetry, agronomic services, and financing. Conversely, universal compatibility and retrofit friendliness unlock larger retrofit TAMs on mixed fleets, especially in large‑scale commercial farming and custom hire segments.
- Software and data value capture: Guidance hardware is increasingly commoditized. Higher margin opportunities now stem from precision agronomy applications, fleet orchestration, implement automation, and data monetization — all of which depend on robust telematics and platform openness.
- Policy and incentives: Reimbursement programs and free augmentation services materially lower buyer acquisition friction. Strategic readiness for subsidy frameworks can shorten sales cycles and raise adoption rates among price‑sensitive primary producers.
Competitive landscape — what to watch
The competitive set comprises legacy OEMs, positioning specialists, and nimble retrofit vendors. Below are the core players whose moves are shaping market dynamics and will influence procurement and partnership decisions in 2026.
Precision Agriculture Gnss Guidance System Market
- John Deere (Deere & Company) — Strength lies in a vertically integrated machinery ecosystem with factory‑installed AutoTrac GNSS guidance and proprietary receiver networks. Strategic advantage: tight hardware‑software integration and strong customer lock‑in through dealer networks and financing.
- PTx Trimble (Trimble Agriculture / PTx Trimble) — Offers cross‑fleet compatibility with solutions like Autopilot and EZ‑Pilot and has introduced techniques for ionospheric resilience. Strategic advantage: universal retrofit positioning, robust correction services, and a software suite that appeals to mixed‑fleet operations and precision agronomy partners.
- CHC Navigation (CHCNAV) — Focuses on retrofit guidance with cm‑level accuracy options and PPP services, positioning itself as a value alternative in challenging geographies. Strategic advantage: price‑performance in retrofit markets and local adaptation agility.
- Hexagon (NovAtel / HxGN AgrOn) — OEM‑centric supplier of high‑precision receivers and correction services. Strategic advantage: deep OEM relationships and enterprise‑grade GNSS products suitable for machine manufacturers seeking to embed accuracy without re‑inventing receivers.
- Topcon Agriculture — Provides GNSS networks and autosteering across many farm operations and is pursuing vision‑based autonomy through partnerships. Strategic advantage: broad systems portfolio and strategic partnerships that accelerate autonomy integration.
- AG Leader Technology — Focused on console‑centric solutions and data management, bridging guidance with implement control and farm software. Strategic advantage: data integration and operator UX for precision tasks.
- CNH Industrial (Raven Industries) — Modular GNSS guidance and connectivity embedded in established OEM brands; plays to customers that prefer OEM continuity. Strategic advantage: channel synergies within large equipment brands.
- Hemisphere GNSS (Outback Guidance) — Supplies precision GNSS products and steering solutions complementary to retrofit and OEM channels. Strategic advantage: specialized GNSS know‑how and adaptability to diverse implement types.
Recent industry changes that demand near‑term responses
- Technology upgrades: New product launches and core enhancements (e.g., ionospheric‑resilient GNSS modules and active implement steering) require product roadmaps to prioritize robustness in degraded signal environments.
- Partnerships for autonomy: Collaborations between positioning vendors and robotics/vision companies are accelerating autonomy pilots. Expect integration timelines to compress — prepare engineering and go‑to‑market teams for rapid co‑development cycles.
- Regulatory shifts and public goods: Free augmentation services in some regions and national GPS datum modernization initiatives impose both opportunities and migration costs. Firms need a regulatory readiness plan to ensure continuity of mapping accuracy and field operations.
- Incentives and procurement: New agricultural subsidy structures in key markets dramatically alter buyer economics. Companies that can align product bundles with reimbursement processes will shorten the buyer conversion lead time.
What the PW Consulting report delivers (practical contents)
Our full report is designed as an operational playbook. Key deliverables include:
- Comprehensive market model with historical baselines (2020–2025) and granular forecasts (2026–2032), including sensitivity scenarios for adoption, price erosion, and correction‑service dynamics.
- Competitive benchmarking with product, channel and pricing matrices, plus vendor SWOTs and partner maps to accelerate partnership diligence.
- Strategic frameworks: go‑to‑market decision trees, retrofit vs. factory install ROI templates, and segment prioritization matrices tailored to enterprise buyers, OEMs, and channel partners.
- Regulatory and subsidy playbook: impact assessment of augmentation services, datum modernization, and reimbursement programs — and recommended compliance and commercial actions.
- Commercial annexes: procurement language checklists, pilot design templates, customer adoption roadmaps, and a customizable financial model to stress‑test investment cases.
How to use the intelligence in 2026 planning
Use the study to move from intuition to execution: quantify the size and profitability of target subsegments, stress‑test product roadmaps against signal resilience and autonomy adoption scenarios, and build a timeline for partnerships and M&A that aligns with public incentive windows. For boards and strategic planners, the core value is the ability to convert macro forecasts and vendor dynamics into a prioritized investment agenda that delivers measurable ROI within a three‑year horizon.
Next steps
This briefing intentionally omits the granular regional and application split tables, vendor volume shares, and the full set of financial matrices that underpin our recommendations — those are contained in the full PW Consulting report and interactive models. For access to the complete market model, competitive scorecards, and executable playbooks that will guide 2026 decisions, consult the full report or contact our advisory team to commission a tailored briefing for your organization.
For detailed analysis of this topic, please visit the official page: Precision Agriculture Gnss Guidance System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Noise Meter Market to reach USD 2,144.55M by 2032 at 5.85% CAGR - PW Consulting
By PW Consulting, 2026-07-13
Digital Noise Meter / Decibel Meter Market: Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concentrated, practice‑oriented preview of our new Digital Noise Meter Decibel Meter Market study. This piece is designed to orient executive teams making 2026 investments — showing the strategic contours of the market, the forces that will shape near‑term returns, and the practical levers companies should prioritize. We deliberately present high‑level, data‑driven insight here while omitting the granular segment tables and regional splits that are included in the full report—to preserve the “trailer” experience and direct decision‑makers to the full study for transaction‑level intelligence.
Digital Noise Meter Decibel Meter Market
Market at a Glance: Macro Trajectory and Strategic Implication
-
Base year dynamics: The digital noise meter market is materially larger today than five years ago, with the market reaching USD 1,440.15 Million in our 2025 base year.
Digital Noise Meter Decibel Meter Market -
Forward view: Under our central scenario, the market grows at a 5.85% CAGR across the 2026–2032 forecast window, reaching approximately USD 2,144.55 Million by 2032.
Digital Noise Meter Decibel Meter Market -
Concentration: Market concentration suggests room for both established OEMs and focused challengers—the top three firms control a meaningful share while the top five increase that footprint further, indicating a mix of specialization and consolidation pressures.
What this means for 2026 decisions: the market is large enough to reward focused scale plays (product platform expansion, service and SaaS tethering) while remaining sufficiently fragmented to allow disciplined entrants and partnerships to capture niche, higher‑margin positions. Capital allocation should therefore prefer strategies that combine product differentiation, data monetization, and channel acceleration.
Key Market Dynamics Executives Need to Embed in 2026 Strategy
-
Regulatory and standards pull: Occupational and environmental regulation remains the primary demand anchor. OSHA thresholds for hearing conservation programs and peak exposure limits continue to drive procurement cycles among industrial and public‑sector buyers. Simultaneously, IEC 61672 performance classifications and the updated ISO 9612 guidance are tightening admissibility criteria for measurement devices—raising the technical bar for market credibility.
-
Product evolution: Buyers are increasingly comparing instruments not just on baseline accuracy (Class 1 vs. Class 2) but on integrated functionality—wireless telemetry, native logging, edge analytics, and lifecycle calibration/traceability services. The market premium is migrating toward systems that reduce buyer total cost of ownership (TCO) through automation and cloud integration.
-
Industrial digitization and smart cities: There is clear momentum for embedding noise sensors into broader IoT and smart factory architectures. Partnerships between metrology equipment providers and factory systems integrators demonstrate a near‑term channel for sensor OEMs to monetize recurring services and software wrappers around measurement endpoints.
-
Procurement sophistication: Large buyers are moving from one‑off capex purchases to mixed models—capex for certified instruments complemented by subscription services for analytics, compliance reporting, and multi‑site fleet management.
What’s Inside the Full Report (Practical, Actionable Content)
Our study is built for corporate strategists, product leaders, and procurement heads who must act in 2026. The full deliverable extends beyond market sizing to deliver executable items you can use in boardrooms and program plans:
-
Validated market sizing and trend drivers (base year 2025, historical 2020–2025, forecast 2026–2032) with sensitivity scenarios for regulation‑driven spikes and faster IoT adoption.
-
Decision frameworks for product portfolio strategy—when to prioritize Class 1 accuracy versus cost‑optimized Class 2 deployments, and the breakpoints where software and services increase lifetime value.
-
Go‑to‑market playbooks by buyer archetype (industrial compliance, environmental monitoring programs, building acoustics, transportation authorities, occupational health managers), including RFP checklists and procurement negotiation levers.
-
Commercial models and pricing templates for hybrid offerings (instrument + SaaS + calibration services), with NPV simulations and subscription elasticity inputs tailored to different end‑user segments.
-
Integration and systems engineering guidelines for embedding noise sensing into smart factory and smart city deployments—sensor selection matrices, data pipelines, edge vs cloud processing tradeoffs, and calibration governance to meet IEC/ISO requirements.
-
Regulatory compliance map that translates OSHA, IEC, and ISO requirements into vendor product specs and enterprise deployment checklists—designed to speed procurement sign‑off and reduce audit risk.
-
Due‑diligence toolkit for M&A and partnership scouting—valuation multiples observed in recent transactions, integration risk checklists, and prioritized capability gaps to close through bolt‑on acquisition or alliance.
Competitive Landscape: Who Matters and Why
The market remains anchored by incumbent metrology and instrumentation specialists, with product and distribution strengths that differ by buyer profile. The report profiles leading firms and evaluates them against five commercialization dimensions: measurement pedigree, product breadth, channel reach, systems integration capability, and service/SaaS proficiency.
-
Brüel & Kjær (Nærum, Denmark) — Renowned for precision Class 1 instruments and deep acoustic expertise; strong pedigree in environmental and research applications with advanced wireless and analysis features. Their brand equity supports premium pricing in regulated deployments.
-
Extech Instruments (Nashua, NH, USA) — Competes on affordability and field usability; good fit for occupational safety teams and smaller environmental programs that prioritize cost and portability.
-
PCE Instruments (Meschede, Germany) — Offers a broad range across Class 1/2 segments and emphasizes industrial applications; well‑placed to compete on product breadth in EMEA manufacturing markets.
-
REED Instruments (Wilmington, NC, USA) — Focused on portable, easy‑to‑use devices for occupational and educational settings; strength in rapid deployment and basic data logging.
-
Larson Davis (Provo, UT, USA) — Strong in advanced occupational and environmental monitoring with recent product launches (e.g., Spartan 821IH) that emphasize integrated dose metrics and professional workflows—indicative of a strategy to deepen ties with occupational health purchasers.
-
Casella (Bedford, UK) — Known for compliance‑oriented instruments and national market penetration in occupational noise; frequently selected for regulated workplace programs.
-
Svantek (Warsaw, Poland) — Positioned in the high‑end professional and industrial analyzer space; strong engineering capability for complex measurement scenarios.
-
RION (Tokyo, Japan) — Provides precision meters conforming closely to local (JIS) and international standards; a preferred supplier in markets with stringent standardization demands.
-
Pulsar Instruments (Filey, UK) — Focuses on workplace monitoring and personal dosimetry—an area set to expand as hearing conservation programs digitize.
Recent vendor moves underscore the market’s push toward integrated solutions and faster time‑to‑value. Notable examples include Larson Davis’s product launch for occupational dose metrics in 2025, new low‑cost pocket meters entering adjacent channels, and partnerships to integrate sound monitoring into smart factory systems. These developments illustrate two converging themes: hardware differentiation remains necessary, but margin expansion increasingly depends on services, connectivity, and validated data workflows.
Strategic Recommendations for Executives Planning in 2026
-
Prioritize “platform‑led” product roadmaps: invest in firmware and cloud APIs that enable multi‑vendor interoperability. Buyers are rewarding vendors who reduce integration friction with factory systems and environmental dashboards.
-
Design hybrid commercial models: pilot subscription‑based compliance reporting and calibration services alongside traditional instrument sales to capture recurring revenue and improve customer retention.
-
Target compliance‑driven procurement windows: align product certification roadmaps (IEC/ISO) to anticipated regulatory review cycles in customers’ jurisdictions to be “procure‑ready” when budgets open.
-
Use targeted partnerships to accelerate scale: form integrations with metrology partners, smart factory integrators, and occupational health platforms rather than attempting full in‑house stacks immediately.
-
Focus on proof points: deliver case studies that quantify reduced audit cycle time, lower noise‑related incidents, and saved remediation costs—these financial outcomes are the most effective sales accelerants in 2026 procurement processes.
-
Prepare M&A playbooks for capability gaps: where time‑to‑market matters, prioritize tuck‑ins that add analytics, wireless telemetry, or channel depth rather than purely incremental sensor improvements.
Why PW Consulting’s Study Is a 2026 Imperative
For 2026 decision cycles, the combination of a clear macro growth trajectory, tightened regulatory and standards expectations, and accelerating digital integration creates a narrow window of asymmetry for strategic players. Acting without precise market timing, buyer segmentation, and commercial models exposes firms to missed procurement windows and suboptimal capital allocation.
Our full report supplies the missing granularity—validated segment forecasts, buyer willingness‑to‑pay benchmarks, pricing ladders, and downloadable procurement checklists—that transform the high‑level recommendations above into boardroom decisions and investment memos.
Next Steps
If you are evaluating product roadmap investments, channel partnerships, or potential acquisitions in the digital noise measurement space this year, PW Consulting can provide a tailored briefing that includes the granular segment data, regional and application splits, and executable financial models omitted from this preview. Contact our market team to schedule a private walk‑through of the full study and a 60‑minute strategic alignment workshop for your leadership team.
For detailed analysis of this topic, please visit the official page: Digital Noise Meter Decibel Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Body Repair Fillers Market at USD 3,600M (2025), 4.85% CAGR to 2032
By PW Consulting, 2026-07-13
Automotive Body Repair Fillers Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic briefing to orient senior executives, corporate strategy teams, and M&A practitioners ahead of critical 2026 planning cycles. This piece previews our full Automotive Body Repair Fillers Market study (base year 2025; historical horizon 2020–2025; forecast 2026–2032) and highlights the decision-useful insights within. We purposely surface analytical depth while preserving the granular segment-level data and proprietary scenarios contained in the full report — consider this a trailer that demonstrates method and value, and a prompt to access the complete dataset for transaction- and operations-level action.
Automotive Body Repair Fillers Market
Market trajectory: what the headline numbers mean for strategy
Over the 2020–2025 historical window, the global automotive body repair fillers market demonstrated resilient expansion as repair demand rebounded from pandemic impacts and product innovation improved workshop productivity. Our base-year view estimates the market reached USD 3,600 Million in 2025. Looking forward under our central scenario, the market progresses at a compound annual growth rate (CAGR) of approximately 4.85% across the forecast window 2026–2032, reaching a projected USD 5,015.4 Million by 2032.
Automotive Body Repair Fillers Market
These topline dynamics matter beyond the headline: modest but steady growth combined with pockets of differentiated innovation creates an environment where scale and specialty both win. For incumbent manufacturers, this implies an imperative to defend breadth across product formats while selectively investing in next-generation chemistries and channel models that deliver margin lift. For private equity and strategic buyers, the expansion supports buy-and-build theses aimed at technology consolidation and downstream access.
Automotive Body Repair Fillers Market
Industry structure and competitive math
The market’s concentration metrics indicate moderate fragmentation with meaningful leadership pockets. The three-largest players account for less than a third of industry revenue (CR3 ~28.5%), while the five-largest capture roughly four in ten dollars (CR5 ~41.2%). Such structure creates a dual strategic pathway: (1) regional or application-focused challengers can defend profitable niches through service and formulation differentiation; (2) larger players can pursue scale synergies, channel exclusives, and recipe standardization to drive unit economics.
Competitor positioning is already evolving along these lines. Major global names combine strong R&D platforms, distribution reach, and OEM/channel relationships, while a set of regional and specialist formulators compete on lightweight, workability, or fast-cure propositions. Examples profiled in our report include:
- ITW Evercoat (Cleveland, OH) — Deep professional OEM/collision credentials and a product portfolio emphasizing lightweight compounds engineered for easy sanding and minimal pinholes; recent product refreshes and new UV- and fast-cure variants signal a clear focus on shop throughput and finish quality.
- 3M (St. Paul, MN) — Leverages vacuum-processed formulas and cross-material adhesion claim sets (steel, aluminum, fiberglass) as competitive differentiators; brand equity supports both trade and retail channels.
- U.S. Chemical & Plastics (USC) (Ohio) — Known for workability and spreadability in professional palettes; appeals to high-volume collision workshops prioritizing application speed.
- Bondo (3M) — Iconic trade/DIY brand with deep awareness across independent shops and aftermarket channels.
- U-POL (UK) and AkzoNobel (Netherlands) — Emphasize high-performance finishing and refinish-compatible chemistries, including UV-curable options.
- SYNEW (China) — Represents the growing cohort of Asia-origin suppliers scaling capability for global distribution partners and price-competitive product families.
Notably, product and pack innovations — lightweight fillers, vacuum-processed systems, and UV-cure primers/fillers — are central levers for differentiation. ITW Evercoat’s product launches at SEMA in late 2025 are an early indicator of supplier emphasis on throughput-enhancing chemistries designed to shorten cycle time and improve surface finish consistency.
Supply-side dynamics and regulatory risk: the strategic implications
Three cross-cutting themes dominate the supply-side risk profile and should frame 2026 planning: raw material volatility, regulatory scrutiny on chemistry, and feedstock exposure to oil-cycle swings.
- Raw material volatility — Unsaturated polyester resin pricing experienced swings exceeding 40% between 2020 and 2025, driven by petrochemical feedstock volatility. This amplitude forced formulators to adopt dynamic raw-material sourcing, forward-purchasing, and substitution playbooks. In our full report we quantify margin sensitivity to common resin and filler cost scenarios and model hedging-related CAPEX for large formulators.
- Chemical regulation — Ongoing evaluation of key monomers (notably styrene) by European regulatory authorities presents a material downside risk for polyester-dominant fillers. Potential classification as a substance of very high concern (SVHC) would introduce authorization and usage constraints in key markets and accelerate R&D migration toward styrene-reduced or styrene-free recipes. Our scenario modules model the commercial impact of phased regulatory restrictions and estimate timelines for reformulation investment and market substitution rates.
- Oil-market exposure — Petroleum-based components remain vulnerable to price shocks stemming from macro oil-market instability. We outline practical levers — formulation diversification, blended sourcing, and agile contract structures — that mitigate input-price pass-through and protect gross margins in mid-cycle downturns.
Demand-side drivers and structural shifts
Repair volume fundamentals remain the single largest determinant of near-term demand. Vehicle parc age, miles driven, and accident frequency are the proximal demand engines; beyond these, three structural shifts deserve strategic attention:
- Material mix evolution — Broader adoption of aluminum, high-strength steels, and composite components in vehicles changes the adhesion and finishing requirements of fillers. Suppliers with validated cross-substrate performance and technical support for body shops gain share potential.
- Workshop productivity focus — Collision repair chains and high-throughput independents continue to prioritize products that reduce cycle time (fast-cure systems, UV cure) and rework. Product portfolios that materially cut booth time or sanding hours command premium pricing power.
- Environmental and worker-safety preferences — Low-VOC and water-based alternatives, and systems that reduce airborne particulates and hazardous monomer exposure, earn preference among chains with sustainability and compliance programs.
What the full PW Consulting study delivers — practical, transaction-ready output
This market briefing is deliberate in scope. The full PW Consulting report provides the operational detail and decision-ready modules that executives need to act in 2026:
- Granular market sizing and segmentations by product chemistry and application with historical and forecast volumes and revenues (2020–2032).
- Segment-level price and margin benchmarking, including sensitivity to primary resin and filler input prices.
- Competitive landscaping with capability maps, channel footprints, and M&A heat-maps highlighting inorganic targets by strategic rationale.
- Supply-chain stress-testing models and recommended hedging/sourcing strategies for common exposure scenarios.
- Regulatory impact simulations (including potential SVHC pathways) and stepwise compliance/transition playbooks.
- Commercial playbooks for premiumization, formulation migration, and workshop adoption pathways including pilot structures and ROI profiles.
- Investment case appendices for private equity and corporate development teams, including accretion/dilution modeling under multiple roll-up scenarios.
- Primary interviews with supply-chain executives, collision repair network managers, and leading formulators underpinning qualitative assumptions.
Strategic recommendations for 2026 planning
Based on our synthesis, executive teams and investors should prioritize three complementary moves in 2026:
- De-risk raw-material exposure — Implement a staged hedging and multi-sourcing program for polyester resins and key additives, combined with targeted reformulation capacity for styrene-reduced chemistries.
- Accelerate shop-centric innovations — Invest in or partner for UV-cure and fast-cure technologies that demonstrably reduce cycle time and rework. Pilot programs with national collision chains convert product claims into procurement commitments.
- Pursue focused consolidation — Pursue tuck-in targets that add specialty formulations, regional channel access, or proprietary cure technologies. Given current concentration metrics, selective roll-ups can rapidly improve scale economics and broaden technology portfolios.
Next steps — where PW Consulting adds value
For teams preparing budgets, M&A pipelines, or R&D commitments in 2026, the full PW Consulting study provides the quantitative underpinnings required to: prioritize CAPEX, size reformulation budgets, select acquisition targets with clear synergy pathways, and stress-test go-to-market pilots. The analysis marries primary market research with scenario modeling to transform strategic hypotheses into executable roadmaps.
If your 2026 planning cycle hinges on differentiated assumptions about regulatory timing, raw material cost trajectories, or competitive moves, our report’s scenario modules and transaction-focused annexes will be directly actionable. Access to the complete dataset and segment-level modeling is available through the PW Consulting market portal and will be essential for teams intending to execute on the recommendations above.
To obtain the full report, models, and tailored briefings for corporate or investor teams, contact PW Consulting for access and to schedule a strategy workshop.
For detailed analysis of this topic, please visit the official page: Automotive Body Repair Fillers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


