



Category: Machinery & Automotive
PW Consulting Forecasts Laser Distance Measuring Devices Market to Expand at a 6.15% CAGR Through 2032
By PW Consulting, 2026-07-07
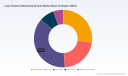
Laser Distance Measuring Devices Market 2026 Strategic Preview — Actionable Intelligence for Executive Decision-Making
PW Consulting | Senior Strategic Brief
As corporate boards and investment committees finalize agendas for 2026, decisions taken now will determine who captures the next wave of value in the laser distance measuring devices market. PW Consulting’s latest market study — grounded in a rigorous 2020–2025 historical base and forward-looking through 2026–2032 — translates market dynamics into a pragmatic, executable roadmap. The study shows the market expanding materially from a multi-billion dollar base in 2025 and accelerating through the forecast window at a compound annual growth rate (CAGR) of 6.15% (USD, revenue expressed in millions). This briefing highlights the strategic implications we expect to shape executive choices in 2026 while preserving the granular segment intelligence reserved for the full report.
Laser Distance Measuring Devices Market
Why this market matters in 2026
Laser distance meters are no longer peripheral tools. Convergence of digitization in construction, higher automation in industrial manufacturing, and tighter tolerances in automotive and aerospace sectors have elevated demand for devices that combine precision, robustness, and systems connectivity. Over the historical period (2020–2025) the market scaled significantly; our base-year assessment (2025) captures the adoption inflection points that will define near-term winners. Under conservative- and upside-scenarios, the market trajectory to 2032 indicates meaningful upside for firms that act decisively on product, channel, and partnership strategies.
Laser Distance Measuring Devices Market
What this report delivers — practical, decision-focused outputs
- Independent, auditable market sizing and trajectory: a year-by-year revenue model covering 2020–2032, with scenario sensitivity that isolates macroeconomic, supply-chain, and adoption variables.
- Competitive benchmarking and vendor scorecards: qualitative and quantitative assessments of capability across product breadth, go-to-market execution, channel strength, and innovation pipelines.
- Commercial playbooks for OEMs, distributors, and service providers: 90/180/365-day roadmaps with prioritized initiatives, estimated resource allocation, and outcome-based KPIs.
- Technology and product roadmaps: feature-pricing elasticity, connectivity and software integration requirements, and the implications of sensor evolution (e.g., green lasers, multi-return ranging, and hybrid sensor fusion).
- Regulatory impact & compliance matrix: localized requirements, labeling implications, and operational controls to limit market access risk.
- M&A and partnership heatmap: target profiles and valuation heuristics for tuck-ins and capability acquisitions, including integration playbooks and five-year synergy schedules.
Key market signals and strategic implications
Our analysis surfaces five signals that should shape capital allocation and product strategy in 2026:
Laser Distance Measuring Devices Market
- Steady, predictable growth with pockets of acceleration. The market’s compound growth through the forecast window creates an environment where category leaders can scale recurring revenue while niche specialists capture margin-accretive segments. Executives should prioritize scalable services and software monetization to amplify lifetime customer value.
- Platformization of measurement tools. Buyers increasingly value measurement-as-data — not just a distance reading. Integration with mobile apps, BIM platforms, and equipment telematics is a differentiator. Products without well-documented APIs and ecosystem partnerships face compression on price and share.
- Product differentiation is shifting from raw range to workflow integration. Accuracy remains table stakes; however, ergonomics, connectivity, and post-measurement data handling are now the primary purchase levers, especially in professional and industrial channels.
- Regulatory and labeling changes are operational risks. Updated standards — exemplified by recent revisions to laser safety labelling in major markets — create near-term compliance costs and can influence go-to-market timing. Firms must integrate regulatory monitoring into product launch calendars to avoid costly recalls or delayed shipments.
- Market concentration provides both opportunity and caution. While the top-tier players command a meaningful share of industry revenue, the market remains accessible for innovators and strong channel players. Execution on channel economics and after-sales service will determine whether challengers can convert product innovation into durable market share.
Competitive landscape — profiles and strategic postures
The competitive tableau comprises established industrial brands, precision-instrument specialists, and large tool OEMs. Across vendor types the winning plays differ, but several consistent themes emerge: leverage brand trust in professional channels, develop integrated software experiences, and consider service-led monetization.
- Robert Bosch GmbH (Gerlingen, Germany) — Known for the GLM series, Bosch combines hardware innovation with app-enabled workflows. Recent product introductions (for example, a mid-2025 release featuring green laser visibility and extended range) illustrate a focus on incremental hardware improvements paired with software functionality. Strategic emphasis for Bosch: deepen ecosystem hooks (tool-integrated workflows) and exploit scale for rapid retail penetration.
- Hexagon AB / Leica Geosystems (Stockholm, Sweden) — Leica’s DISTO line retains strength in surveying and construction where measurement precision and professional-grade features matter. Leica’s strategic advantage lies in high-accuracy positioning and premium channel relationships; defending margin requires continued investment in measurement accuracy and enterprise data integration.
- Fluke Corporation (Everett, Washington, USA) — Fluke’s industrial reputation enables premium pricing for ruggedized, calibration-backed instruments. Fluke should prioritize cross-selling into electrical and industrial maintenance suites while expanding service contracts that monetize calibration and certification workflows.
- Stanley Black & Decker (New Britain, Connecticut, USA) — Leveraging mass-market distribution and brand recognition, Stanley’s play is scale and accessibility. To protect margin from commoditization, Stanley can combine entry-level units with subscription services or bundled value-adds (e.g., cloud repositories for job-site measurements).
- Makita Corporation (Anjo, Japan) — Makita can uniquely leverage its battery and tool ecosystem to create stickier propositions for tradespeople. Strategic moves include tighter integration of laser meters into power-tool ecosystems and leveraging distribution into dealer networks.
- Hilti Corporation (Schaan, Liechtenstein) — Hilti’s strength in professional construction services suggests a portfolio play that blends product sales with rental and managed-service models. Hilti can deepen its service-led differentiation with site analytics and measurement-as-a-service offerings.
Regulatory development: a practical lens
In March 2025, updates to international laser safety standards tightened labeling requirements for certain classes of devices sold in Europe. This change is a reminder that product compliance is a live, value-chain issue. Companies should expect increased disclosure obligations, periodic audits, and potential requalification of devices. The PW Consulting report includes a market-ready compliance checklist and a cross-jurisdictional implementation calendar to help legal and product teams prioritize certifications and label redesigns without disrupting sales cycles.
Strategic recommendations for 2026
- Segment the product roadmap by value capture potential. Rationalize SKUs to focus R&D on features that drive market share in high-margin channels (connectivity, software integration, ruggedization). Delay commodity-focused features to cost-optimized lines.
- Invest in software & ecosystem partnerships. Establish APIs, SDKs, and certified integrations with leading BIM and field-data platforms. Consider co-marketing agreements with enterprise software vendors to accelerate adoption among professional users.
- Enhance after-sales and service monetization. Develop calibration, certification, and data-subscription services to turn transactional purchases into recurring revenue streams.
- Prioritize compliance and supply-chain resilience. Add regulatory gating to product launch workflows and diversify critical components to mitigate supplier concentration risks.
- Use targeted acquisitions to accelerate capability gaps. Pursue tuck-in deals for imaging sensors, software middleware, or distribution footholds rather than transformational M&A that dilutes focus.
- Align go-to-market by channel economics. Differentiate propositions for professional distribution, industrial direct channels, and retail — and deploy tailored margin structures and service bundles for each.
How PW Consulting’s report supports your 2026 decisions
The full PW Consulting study operationalizes the strategic recommendations above into executable plans. It contains downloadable models you can run with your own assumptions, a commercial due diligence framework for M&A, and vendor scorecards you can use in vendor selection or negotiation. For leadership teams making product, M&A, or capital-allocation decisions, this report reduces uncertainty by converting market trajectory and competitive context into prioritized action items and measurable outcomes.
Next steps — accessing the intelligence
This preview summarizes core findings and strategic priorities from PW Consulting’s Laser Distance Measuring Devices Market report. We have intentionally withheld the granular regional and application-level splits and proprietary company scoring that corporate teams require for execution. To obtain the full dataset, interactive models, and the operational playbooks that power 2026 plans, please visit PW Consulting’s market report portal or contact our client services team directly.
PW Consulting remains available to brief executive teams, run scenario workshops, and co-develop implementation roadmaps that translate the market opportunity into measurable business results in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Laser Distance Measuring Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Jet Engine Nozzles Market to Hit USD 847.58 Million by 2032, Fueled by a 5.85% CAGR
By PW Consulting, 2026-07-07
Jet Engine Nozzles Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive summary
As aerospace OEMs and tier suppliers prepare capital allocations and product roadmaps for 2026, the jets engine nozzles market emerges as a compelling arena where materials, thermal management, additive manufacturing, and regulatory pressure converge. Our latest market model shows the global jet engine nozzles market expanding from a post-pandemic baseline of roughly USD 412 million in 2020 to approximately USD 569 million in 2025, and continuing on an upward trajectory into the forecast period (2026–2032) at a compound annual growth rate (CAGR) of 5.85%. By 2032, the market is projected to approach the high hundreds of millions of USD in annual revenue.
Jet Engine Nozzles Market
This PW Consulting report is designed as a practical playbook for boardrooms, strategy teams, procurement chiefs, and technology scouts. It synthesizes quantitative forecasting with qualitative scenario work to turn market intelligence into executable decisions in 2026 — from supplier selection and vertical integration to investment in nozzle architectures and materials sourcing.
Jet Engine Nozzles Market
Why this market matters in 2026
-
Performance and compliance are simultaneously raising the bar. Stringent emissions standards worldwide and OEM efficiency targets mean nozzle design is no longer a marginal performance lever — it is central to achieving fuel-burn and emissions objectives across narrowbody and widebody programs.
Jet Engine Nozzles Market -
Materials and manufacturing are strategic chokepoints. Nickel-based superalloys and titanium alloys remain the backbone of high-temperature nozzle components; market dynamics for these inputs are a direct limiter on production scalability and unit economics. Our research flags concentrated supply dynamics and cost sensitivity in superalloys as a near-term procurement risk that should be stress-tested in 2026 sourcing plans.
-
Technology inflection points are creating winner-take-most opportunities. Additive manufacturing, advanced cooling designs, and variable-geometry and thrust-vectoring nozzles are shifting value capture toward firms that can integrate design, material science, and manufacturing at scale.
What senior leaders need from this report
For executives making or advising 2026 investment decisions, this report delivers four practical outcomes:
-
Decision-ready market sizing: a defensible top-line view of market scale and growth through 2032, enabling scenario-based revenue modeling and ROI calculation for product or plant investments.
-
Supply-chain stress tests: risk matrices and mitigation playbooks for critical inputs (superalloys, titanium, coatings), plus supplier concentration metrics and alternative sourcing pathways to underwrite continuity plans.
-
Technology positioning and competitor benchmarking: actionable intelligence on where to allocate R&D and CapEx to capture efficiency, weight, and thermostructural advantages while remaining compliant with tightening emissions rules.
-
M&A and partnership scouting: targeted criteria and shortlist methodology for potential bolt-ons, from AM specialists to advanced materials suppliers and nozzle repair houses.
Key findings and strategic implications
-
Structural growth with pockets of acceleration. After steady expansion from 2020 through 2025, the market enters an era of moderate but consistent growth driven by fleet renewals, defense modernization, and next-generation engine architecture programs. The forecasted CAGR of 5.85% through 2032 underpins conservative investment cases for capacity expansion and new product launches in 2026.
-
Concentration favors scale and integrated capabilities. The market exhibits significant concentration: the top OEMs and specialized suppliers control a substantial share of revenue and engineering capacity. For mid-tier suppliers, this implies a dual strategy: either pursue niche specialization (e.g., coatings, repair) or accelerate capabilities in core differentiators such as AM-enabled design and advanced metallurgy.
-
Aftermarket economics are underleveraged. Service, repair, and overhaul (SRO) pathways for nozzles represent outsized lifetime value per engine platform. Firms that can couple OEM relationships with robust MRO capabilities stand to capture long-term annuity streams as the installed base grows.
-
Regulatory and environmental drivers change product roadmaps. Emissions and noise regulations are actively pushing R&D toward fuel-efficient nozzle designs and acoustic-optimised geometries. This trend makes investment in noise-reducing nozzle concepts and open-fan-compatible architectures a defensible strategic priority in 2026 planning.
-
Material supply dynamics are not peripheral — they are a strategic variable. Nickel-based superalloys and titanium remain indispensable for many nozzle applications; disruptions, price volatility, or policy-driven export controls could materially affect program timelines and margins. Our stress-testing module provides scenario-adjusted cost curves for these inputs to inform hedging and vertical integration discussions.
Competitive landscape — who matters and why
Strategic positioning in the nozzle market blends OEM system integration with component-level specialization. Our competitive analysis focuses on firms that shape design standards, control manufacturing scale, or provide critical aftermarket services:
-
GE Aerospace (Cincinnati, Ohio, USA) — A pioneer in applying additive manufacturing to nozzle components, GE’s work on advanced fuel nozzles and open-fan RISE technologies underscores the value of combining design and production innovation to reduce weight and part count.
-
Safran Aircraft Engines (Paris, France) — Through joint ventures and legacy engine programs, Safran remains a key integrator for high-temperature exhaust and fuel nozzle systems, with a strong emphasis on materials that tolerate extreme thermomechanical loads.
-
Pratt & Whitney (East Hartford, Connecticut, USA) — With deep expertise in turbine and fuel nozzles across military and commercial platforms, Pratt & Whitney’s geared turbofan and defense workstreams make it a bellwether for nozzle performance innovation.
-
Rolls-Royce (London, UK) — Focused on widebody and military applications, Rolls‑Royce pursues advanced materials and scaling strategies that align nozzle design with large-engine thermal management requirements.
-
Wall Colmonoy / Aerobraze (Cincinnati, Ohio, USA) — A specialist in repair and refurbishment, this group is central to aftermarket value capture through coatings, overlays, and repair processes that extend nozzle life.
-
Moeller Aerospace (Wixom, Michigan, USA) — Known for precision machining, Moeller is positioned where tight tolerances and surface finish requirements determine component performance and lifecycle.
-
The Lee Company (Westbrook, Connecticut, USA) — Providers of compact spray and lubrication nozzles with niche but critical system-level roles in fuel, oil, and cooling subsystems.
-
ITP Aero (Zamudio, Spain) — A specialist in convergent-divergent and thrust-vectoring solutions for military platforms, active where maneuverability and compact performance matter most.
Recent industry developments — from thrust-vectoring showcases in airshows to university-led acoustic nozzle concepts and continued vendor program updates — validate our view that both high-end military capabilities and civil-efficiency innovations will coexist as investment priorities in 2026.
Report contents — what you will find inside
The PW Consulting Jet Engine Nozzles Market report is constructed to be directly actionable. Key deliverables include:
-
Proprietary market model with annualized revenue estimates (2020–2025 historical) and baseline/alternative forecasts through 2032, including sensitivity to fuel-price, regulation, and defense procurement scenarios.
-
Segment-level narratives (nozzle architectures, manufacturing methods, aftermarket vs OEM) with qualitative inputs and strategic implications. Note: detailed split tables and exact regional/application breakouts are reserved for the full report.
-
Supply-chain heat maps and supplier risk assessments for superalloys, titanium, coatings, and specialized machining & AM capacity.
-
Technology maturity curves, patent landscapes, and recommended R&D investment priorities tied to ROI windows valid for 2026 planning cycles.
-
M&A and partnership playbooks with screening filters, valuation benchmarks, and integration risk checklists tailored for nozzle-focused acquisitions.
-
Executive dashboards and scenario templates to plug into corporate strategic planning systems for immediate use in board-level discussions.
How to use this intelligence in 2026
-
Use the report’s scenario tool to stress-test CAPEX decisions under tighter material supply or accelerated regulatory timelines.
-
Prioritize investments that capture systems-level performance gains (e.g., AM-enabled integrated nozzle assemblies) rather than incremental part improvements.
-
Lock in strategic supplier relationships or consider equity partnerships with niche AM or coatings firms to secure proprietary advantages and capacity.
-
Embed aftermarket strategies into product bids; lifetime service economics alter the break-even calculus for pricing and product warranties.
Next steps and how to access the full analysis
This briefing is a curated preview intended to surface the critical strategic threads for 2026. PW Consulting’s full report contains the granular segmentation, regional and application splits, and downloadable financial models necessary to populate corporate planning decks and investment memoranda. For access to the complete dataset, interactive dashboards, and bespoke scenario analysis, please visit our official report page or contact PW Consulting’s Aerospace Practice for an executive briefing and tailored modeling session.
For detailed analysis of this topic, please visit the official page: Jet Engine Nozzles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Offshore Wind Turbine Market to Reach USD 93.5 Billion by 2032 at 13.5% CAGR — Asia‑Pacific and Fixed Foundations Drive Growth
By PW Consulting, 2026-07-07
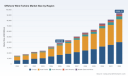
Offshore Wind Turbine Market 2026: A Strategic Playbook for Executives
Executive summary
As global energy strategies accelerate toward decarbonization, offshore wind has moved from niche deployment to a central pillar of utility-scale planning. PW Consulting’s latest Offshore Wind Turbine Market report—anchored on a 2025 base year with a historical lens from 2020–2025 and a forward view across 2026–2032—quantifies a sustained expansion trajectory. The market grew rapidly through the early 2020s and, with a forecast compound annual growth rate of 13.5% for the 2026–2032 period, is on course to more than double in size by 2032 relative to mid‑decade levels.
Offshore Wind Turbine Market
For executives making critical capex, procurement and partnership choices in 2026, the strategic value of this report is twofold: it distills macro momentum into decision-ready implications and it maps operational levers (supply security, technology choice, regulatory navigation) that materially affect project returns. This release functions as a strategic trailer—demonstrating the depth of our modelling, scenario work and vendor intelligence, while directing readers to the full report and data tools for the granular inputs required to finalize commercial commitments.
Offshore Wind Turbine Market
Market trajectory and what the headline numbers mean
PW Consulting’s market model places the offshore wind turbine market at an order of magnitude growth between 2020 and 2032. Using our standardized revenue unit (USD, millions), the market expanded markedly up to 2025 and is forecast to continue growing to a substantially larger scale by 2032 under our central case. That growth is driven by larger turbine platforms, aggressive country-level capacity targets, and an expanding pipeline of floating and fixed-bottom projects in deeper waters.
Offshore Wind Turbine Market
What matters for 2026 decision-makers is how that macro expansion translates into near-term volume and risk profiles: suppliers will face intense demand for steel, jacket and monopile fabrication slots, and turbine nacelle capacity; developers will compete for constrained installation windows and grid connection capacity; and financiers will re-price project risk as technology scale and regulatory clarity evolve. Our report converts headline growth into monthly and quarterly demand curves, enabling teams to align procurement, installation and financing timelines to minimize margin erosion and execution risk.
Strategic implications for 2026 corporate planning
- Secure upstream inputs now: Steel constitutes the majority of a turbine’s mass and recent studies highlight potential multi-billion-dollar domestic steel demand associated with new offshore programs. Suppliers and developers that lock in long-term material off-take or verticalize production capacity will reduce schedule risk and preserve margins.
- Decide technology bets at the portfolio level: The next wave of turbine platforms is pushing rotor diameters and rated capacities beyond previous practical limits. OEMs and large developers must balance investment in highest-capacity platforms against the integration and logistics complexity they create. Our scenario matrices allow portfolio managers to stress-test value under multiple technology adoption curves.
- Regional regulatory risk requires active mitigation: Regulatory reviews and policy reversals in key markets can pause project pipelines. Companies with exposure to markets undergoing regulatory transition should adopt a two-track approach: preserve optionality through staged contracting and pursue parallel market entries in jurisdictions with clearer lease trajectories.
- Commercial models need to reflect concentration dynamics: Market concentration remains meaningful: the top tier of OEMs captures a substantial share of supply, creating both counterparty risk and bargaining leverage. Procurement strategies that diversify across capable suppliers while engaging in early-stage co‑development agreements will improve execution certainty.
- Infrastructure and logistics are the hidden margin drivers: Port capacity, heavy-lift vessel availability and local fabrication yards are now primary constraints on annual installation. Investors should treat logistics commitments and berth allocation agreements as core to project finance packages.
What the report delivers — practical, transaction-oriented content
Beyond the headline forecasts, the report is built as an operational toolkit for 2026 decision cycles. Key deliverables include:
- Dynamic demand models mapping annual and sub‑annual turbine unit and nacelle flows across the forecast horizon (interactive Excel modules and a companion web dashboard).
- Scenario analyses that stress-test technology adoption, commodity price swings and policy shocks against IRR and levelized cost outcomes.
- Vendor performance and capacity scoring, combining technical maturity, factory footprint, and demonstrated offshore track record into procurement-ready shortlists.
- Project pipeline intelligence: a curated tracker of announced projects, procurement timelines and permitting status (project-level entries are available in the full dataset).
- Commercial diligence checklists for developers, OEMs and component suppliers—covering contracting structures, warranty exposure, and installation logistics.
To preserve competitive advantage for subscribers, the report’s public executive summary intentionally omits proprietary sub‑segment tables and granular regional allocations; these are available in the report portal where clients can run custom slices of the dataset.
Competitive landscape — who matters and why
Our market concentration analysis shows a marketplace where the leading OEMs occupy sizeable shares, creating a two-speed dynamic: a dominant group of global OEMs with scale advantages and a set of agile regional players focused on rapid iteration and cost disruption. The top three and five players together command a material portion of market revenue—highlighting both the barrier to entry and the opportunities for differentiated offerings.
- Siemens Gamesa Renewable Energy (Zamudio, Spain) — A global leader with deep offshore experience and high‑capacity platforms designed for harsh environments. Their competitive advantage is proven multi‑project reliability, which remains critical as projects move into deeper, more complex sites.
- Vestas Wind Systems A/S (Aarhus, Denmark) — A major supplier with an extensive installed base offshore. Vestas’ strength lies in scale deployment experience and integration with large‑scale project logistics.
- GE Vernova (Schenectady, USA) — Focused on very large turbine platforms, with recent regulatory clearance to proceed with higher-capacity prototype builds. GE’s bet on scale aims to drive levelized cost reductions but will require execution on prototype commercialization.
- Ming Yang Smart Energy (Zhongshan, China) — An aggressive technology and market expansion strategy, including membership in European industry associations to accelerate presence. Their semi‑direct drive platform represents a differentiated engineering path.
- Goldwind (Beijing, China) — Rapidly scaling with ultra-large rotor designs and progressive component production. Recent moves toward very-large-capacity equipment signal greater competition at the high-capacity end of the market.
Recent industry moves underline these dynamics: GE Vernova’s clearance to develop higher-capacity prototypes, Ming Yang’s active expansion into European industry networks, and Goldwind’s ramp of components for next-generation mega-turbines. Each development alters supplier availability, project timelines and the competitive bargain for developers.
Supply chain and regulatory dynamics that will shape 2026 outcomes
Two structural forces require executive attention in 2026: raw‑material supply and shifting regulatory regimes. Steel supply chains are particularly pivotal—steel broadly comprises the lion’s share of turbine mass and major offshore programs can translate into multi‑billion‑dollar incremental steel demand for target markets. Companies that preemptively secure fabrication capacity, form long-term supply agreements or localize critical component manufacturing will mitigate schedule and margin risk.
On regulation, several jurisdictions initiated major policy reviews and lease suspensions in late 2025. Such actions increase near‑term execution risk in affected markets while creating windows for competition in more stable regions. Our regulatory matrix ranks markets by permit predictability, economic incentives and national security considerations—enabling project developers and OEMs to prioritize effort where de‑risked value is highest.
How PW Consulting helps clients translate insight into action
- Custom scenario workshops that integrate client-specific asset lists with our market model to produce transaction-grade demand and revenue projections.
- Supplier engagement programs that combine negotiation playbooks with capacity risk mitigation plans (including port and vessel contracting templates).
- Regulatory and political-risk advisory specific to jurisdictions experiencing policy oscillation, supporting contingency contracting and staged procurement strategies.
- Due diligence and carve‑out analyses for financiers evaluating direct equity or debt exposure to single-project or portfolio deals.
Next steps — where to get the full view
This briefing is designed to demonstrate the strategic depth and operational relevance of PW Consulting’s Offshore Wind Turbine Market report while preserving the proprietary granularity that supports deployable commercial decisions. Executives preparing 2026 capital plans are encouraged to access the full report and interactive datasets to:
- Download the project-level pipeline and supplier capacity modules.
- Run tailored demand scenarios against internal procurement and installation timelines.
- Schedule a bespoke briefing with our industry team to translate report findings into an executable 12–36 month action plan.
PW Consulting’s research synthesizes macro growth, concentration dynamics and operational constraints into a single decision-ready framework. For companies that need to move from strategic intent to contracted execution in 2026, the difference between an informed versus an informed-and-prepared plan will be measured in months—and in tens of millions of dollars of realized value. Visit our report portal to access the full dataset and arrange a strategy session with our offshore wind practice.
For detailed analysis of this topic, please visit the official page: Offshore Wind Turbine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Row-Based Coolant Distribution Units Market Poised to Expand at a 21.2% CAGR During 2026–2032
By PW Consulting, 2026-07-07
Row-Based Coolant Distribution Units (CDUs): Strategic Insights for 2026 Decision-Makers
Executive Brief
PW Consulting's new Row-Based Coolant Distribution Units (CDU) Market report arrives at a pivotal inflection point for data center operators, hyperscalers, telcos, and equipment providers. Driven by a persistent shift toward liquid cooling to support AI, HPC and ultra-dense rack deployments, the global row-based CDU market has expanded rapidly — growing from a modest industry base in 2020 to an estimated USD 368.0 Million in 2025, and is forecast to continue at a compound annual growth rate (CAGR) of 21.2% through the 2026–2032 horizon. By 2032, the market is projected to exceed USD 1.4 Billion. For executives making 2026 capital, product and sourcing decisions, the strategic implications are immediate and operational.
Row Based Coolant Distribution Units Cdu Market
Why 2026 Is a Make-or-Break Year
-
Accelerated demand: AI and GPU-dense architectures have compressed procurement timelines and raised per-rack thermal loads beyond the reach of traditional air-cooled approaches. Row-based CDUs have moved from niche to mainstream as an efficient, deployable answer to these cooling intensities.
Row Based Coolant Distribution Units Cdu Market -
Regulatory and sustainability pressure: New energy codes and regional standards — including recent adoptions of ASHRAE 90.4 and state-level rules such as Title 24 — are reshaping acceptable PUE targets and incentivizing liquid solutions. Simultaneously, water-use concerns (U.S. data center water consumption was estimated at 17.4 billion gallons in 2023 and is projected to rise materially) are pushing teams to prioritize closed-loop, low-water footprint architectures.
Row Based Coolant Distribution Units Cdu Market -
Vendor evolution and product cadence: Leading vendors have released higher-capacity, modular row-based CDUs over the last 18 months, creating a dynamic landscape in which procurement windows in 2026 will determine which platform families become de facto standards in customer fleets.
What PW Consulting’s Report Delivers — Practical, Procurement-Ready Intelligence
This report was built for the practitioner and the strategist. It goes beyond headline market numbers to provide actionable toolsets tailored for 2026 execution cycles. Key deliverables include:
-
Transparent market-sizing and methodology: A reproducible model from 2020–2025 and forward forecasts to 2032, with sensitivity scenarios aligned to adoption curves and AI infrastructure rollouts.
-
Demand-driver analysis: Deep dives into the AI/HPC, telco and co-location demand vectors, plus near-term catalysts and structural inhibitors (e.g., facility retrofits vs. new builds).
-
Vendor profiles and pragmatic scorecards: Comparative evaluations of technology, modularity, redundancy schemes, monitoring/telemetry features, maintainability and near-term roadmap risk — designed for RFP and proof-of-concept (PoC) selection.
-
TCO and lifecycle models: Total cost of ownership templates that quantify CapEx/OpEx trade-offs across liquid‑to‑liquid and liquid‑to‑air architectures, factoring energy costs, service intervals, coolant chemistry, and water use impacts.
-
Deployment playbooks and checklists: Engineering-ready sequences for row-level integration, leakage risk mitigation, commissioning, and service contracts that shrink deployment time and reduce hand‑offs between facilities and IT teams.
-
Regulatory mapping and compliance impacts: Clear guidance on ASHRAE, OCP guidance and select North American state energy codes, including implications for design acceptance criteria and measurement of PUE targets.
-
Supply chain and obsolescence risk analysis: Component concentration mapping, commodity pressure (including coolant base fluids), and practical mitigation tactics for 12–36 month procurement cycles.
-
Scenario planning templates: Playbooks that translate market and regulatory scenarios into procurement triggers, hedging tactics and staging strategies for fleet rollouts.
Competitive Landscape — Who Matters and Why
The market is consolidating around a group of established thermal-management vendors and specialized liquid-cooling manufacturers. Market concentration metrics indicate that the top three vendors control a meaningful share of market revenues, and the top five further consolidate competitive advantage — a structure that influences pricing dynamics, aftermarket service availability, and innovation pace.
Profiles worth watching (detailed operational analysis included in the report):
-
CoolIT Systems — Rapidly scaling modular row solutions with high-capacity models targeted at AI/HPC customers. Recent product expansions demonstrate upward capacity moves that accelerate suitability for high-power racks.
-
nVent — Positioned with platforms that emphasize fault-tolerant architectures (N+1 redundancy) and alignment to emerging open standards, appealing to organizations prioritizing availability and standardization.
-
Airedale by Modine — Combining in-row and skid-based approaches, emphasizing flexibility for grey-space and retrofit scenarios.
-
Eaton (Boyd Thermal) — Bringing enterprise power systems expertise and high-capacity CDU variants targeted at AI workloads and integrated facility controls.
-
Vertiv — Focused on integrated systems with deep service networks and in-row product families designed for high-density deployments.
-
DCX Liquid Cooling Systems — Expanding seat at the table for facility-scale CDU solutions and warm-water-optimized products for hyperscalers and large campuses.
-
JetCool — Emerging supplier with SmartSense telemetry and scalable architectures that aim at GPU-dense rack configurations.
The report synthesizes product launches and roadmap moves from 2024–2026 into vendor risk/opportunity matrices. Recent high-impact launches — including several 2MW-class row-based units and an 8MW facility-scale CDU — are reshaping product tiers and enabling larger fractional deployments at the row level that previously required room-scale infrastructure.
Standards, Fluids, and Operational Constraints
Standards and coolant chemistry remain foundational to safe, repeatable deployments. Industry alignment around propylene glycol blends (PG25 reference fluids) and guidance from bodies such as ASHRAE TC 9.9 and the Open Compute Project reduce interoperability risk — but they also create procurement expectations. Facilities and design teams must reconcile the benefits of warm-water operation, reduced chiller duty and simplified heat reuse strategies with serviceability, leak detection and chemistry management practices.
Strategic Recommendations for 2026 Decisions
Executives and technical leaders should treat 2026 as a dual-track execution year: accelerate high-priority pilots while locking in standards and vendor relationships that de-risk scale rollouts. Key recommendations include:
-
Prioritize PoCs that mirror production density: Design pilots to replicate peak rack heat loads, redundancy needs and failure modes rather than nominal averages.
-
Standardize specifications early: Lock common interface, coolant chemistry and telemetry standards across sites to lower long-term integration and spare‑parts costs.
-
Negotiate modular commercial terms: Seek options for capacity upgrades, service-level-adjustable warranties, and spare-parts pools to manage rapid scale decisions without repeat RFPs.
-
Quantify water and energy externalities in procurement: Use the TCO templates in the report to translate water use and PUE constraints into contract KPIs and performance incentives.
-
Adopt a layered sourcing strategy: Combine primary agreements with leading CDU manufacturers and a vetted secondary supplier or systems integrator to hedge against lead‑time and single-supplier risk.
-
Embed operational telemetry requirements: Require vendor-supplied monitoring APIs, diagnostic tools and firmware roadmap commitments as part of acceptance criteria.
-
Plan for service ecosystems: Ensure local service coverage, spare inventories and training pathways are in place before committing to heavy rollouts.
-
Use scenario staging: Map rolling-capacity triggers tied to business growth and regulatory inflection points so procurement remains responsive but disciplined.
How To Use This Report in 2026 Planning Cycles
Procurement, facilities and IT infrastructure teams should use this report as both a market primer and an operational binder. The combination of proprietary market sizing, vendor scorecards, TCO tools and regulatory mapping supports three immediate workflows:
-
RFP and technical specification development: Reduce cycle time from draft to award by using pre-built spec language and acceptance criteria.
-
Pilot design and evaluation: Run side-by-side comparisons with standardized data capture templates to produce apples-to-apples performance baselines.
-
Capital planning and scenario budgeting: Incorporate the report’s forecast scenarios and sensitivity analyses into 3–5 year capex plans.
Closing — Where to Look Next
Row-based CDUs are no longer an experimental add-on; they are a core design lever for 2026 and beyond. The market’s rapid expansion — underpinned by a multi-year CAGR in excess of 20% and accelerating vendor innovation — creates windows of opportunity but also execution risk. PW Consulting’s report equips decision-makers with the analytical foundation, procurement tools, and vendor insight necessary to convert that opportunity into predictable deployment outcomes.
For organizations preparing RFPs, piloting liquid cooling, or updating capital plans this year, the full report contains the proprietary data tables, vendor scorecards and downloadable TCO models that operational teams will need to finalize 2026 commitments. Access the full practitioner report on PW Consulting’s website to retrieve those resources and schedule a briefing with our industry advisory team.
For detailed analysis of this topic, please visit the official page: Row Based Coolant Distribution Units Cdu Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Organic Rankine Cycle (ORC) Waste Heat-to-Power Market Poised to Reach $9.75B by 2032, Growing at a 10.65% CAGR
By PW Consulting, 2026-07-06
Organic Rankine Cycle Waste Heat to Power Market — Strategic Preview for 2026 Decision Makers
PW Consulting is pleased to release a strategic preview of our forthcoming market research report on the Organic Rankine Cycle (ORC) Waste Heat to Power (WH2P) market. As organizations reassess capital allocation and decarbonization roadmaps for 2026, this briefing explains why the ORC WH2P opportunity has moved from niche engineering projects to boardroom-level strategic initiatives — and why our full report will be an essential input for any corporate, investor, or project developer evaluating waste heat recovery investments.
Organic Rankine Cycle Waste Heat To Power Market
Why this matters in 2026
The ORC WH2P sector is at an inflection point. After five years of accelerated growth, the market has reached a scale in our base year (2025) that supports a professionalized supplier ecosystem, standardized contracting templates, and replicable project economics across multiple industrial verticals. With a forecast compound annual growth rate (CAGR) of 10.65% for 2026–2032, PW Consulting expects cumulative momentum to translate into growing project pipelines, improving manufacturing scale economies, and more attractive total cost of ownership for end users.
Organic Rankine Cycle Waste Heat To Power Market
- Scale and trajectory: Our market model shows a near-doubling of annual industry revenue from mid-decade levels through 2032, driven by both retrofit projects and new-build industrial deployments.
- Commercialization window: Improvements in modular ORC platforms, combined with rising industrial electricity prices and policy incentives in key jurisdictions, create a narrow window (2026–2029) where payback periods cluster around investor thresholds.
- Decision urgency: For energy-intensive enterprises, 2026 is the year to convert exploratory studies into capital projects if the goal is meaningful energy cost reductions and Scope 2/Scope 1 mitigation before the end of this decade.
Market sizing and what the numbers imply
Our analysis synthesizes historical performance (2020–2025) with a seven-year forecast horizon (2026–2032). The ORC WH2P market reached a substantive base in 2025 (reported in USD Million), and the model projects continued expansion to an even larger market by 2032 under a central-case CAGR of 10.65%. This growth reflects the combined effects of increased project deployments, larger average unit capacities in specific segments, and improvements in system-level efficiencies.
Organic Rankine Cycle Waste Heat To Power Market
Two practical takeaways for corporate strategists:
- Market momentum reduces technology risk: larger, repeated deployments mean suppliers and EPC contractors are moving from bespoke project work to productized offerings — reducing execution risk and improving comparability across vendor proposals.
- Financial metrics improve with scale: as projects aggregate (portfolio approaches) and standardized O&M packages emerge, lifecycle economics become more predictable — an important condition for corporate treasury teams to consider internal financing or green bond structures.
Note: In keeping with our “trailer” approach, core tabular segmentation (regional and application-level revenue splits) is not reproduced here. The full report contains exhaustive regional, application, and capacity-segment breakdowns, including sensitivity scenarios and downloadable spreadsheets for transactional diligence.
Strategic implications for enterprises and investors
- Prioritize screening over study: Move rapidly from single-site feasibility studies to portfolio-level screening. The marginal value of a standardized internal screening tool is high in 2026 because procurement teams can evaluate multiple sites using harmonized assumptions (fuel-equivalent pricing, operating hours, maintenance schedules).
- Embed ORC into decarbonization pathways: WH2P projects reduce grid electricity demand and provide on-site baseload power. For industrial firms balancing electrification and fuel-switching, ORC offers a non-grid, low-carbon power source with attractive incremental carbon abatement costs when combined with energy efficiency measures.
- Leverage contracting innovations: Developers and suppliers are offering output-linked commercial options (availability guarantees, performance-based tariffs). Corporates should negotiate warranty and performance language tied to energy delivery and heat availability rather than equipment specifications alone.
- Plan for fluid risk and regulatory changes: Anticipate transitions away from certain synthetic working fluids due to potential regulatory constraints. Procurement teams need a fluid transition strategy that avoids stranded assets while preserving thermodynamic performance.
- Consider modular vs. bespoke trade-offs: Modular micro-ORC solutions reduce schedule risk and simplify operations for lower-temperature streams, while larger, shaft-based systems offer better scale economies for high-temperature, continuous heat sources. The right choice depends on your operating profile and capital envelope.
What the PW Consulting report delivers — practical, actionable content
Our full report is engineered as a decision-support toolkit for 2026 investments. Highlights include:
- Market sizing and projected revenue curves to 2032 with scenario analysis (base, upside, and downside) and sensitivity to electricity and fuel price pathways.
- Project financial templates (editable) — CAPEX/OPEX modelling, payback and IRR calculators, and levelized cost of electricity (LCOE) comparators tailored to ORC projects.
- Commercial diligence materials — procurement checklists, standard contract clauses, performance guarantee templates, and vendor evaluation scorecards.
- Technology and supply-chain mapping — vendor capability matrices, component criticality assessments, and lead-time forecasts for key subsystems (turbomachinery, heat exchangers, controls).
- Implementation playbooks — step-by-step guidance for site assessment, brownfield integration, commissioning best practices, and O&M optimization to preserve unit availability and return on investment.
- Risk and mitigation heatmaps — regulatory, working-fluid, and raw-material exposures, plus recommended hedging or contingency approaches.
These resources are designed to be used directly by energy, sustainability, and operational teams as part of 2026 budgeting and capital planning cycles.
Competitive landscape — who’s shaping the market
The ORC supplier ecosystem is maturing but remains moderately fragmented: the top three suppliers account for under a quarter of the market by revenue, and the top five hold roughly a third — a concentration profile that supports both specialized engineering firms and scaled OEMs. Market leadership today is defined by technology differentiation, reference project portfolios in energy-intensive industries, and the ability to support long-term service agreements.
- Ormat Technologies Inc. — A U.S.-based leader with a long track record in recovered energy generation and proprietary Ormat Energy Converter technology. Strengths include end-to-end project delivery and service capabilities for industrial sites.
- Turboden (Mitsubishi Heavy Industries Group) — Notable for large-scale ORC turbogenerators and recent high-profile project wins, including the commissioning of a multi-megawatt plant in North America and additional contract awards for compressor-station deployments. Their position underscores how major OEM backing accelerates large-project adoption.
- Exergy International — An innovator with turbine designs optimized for industrial waste-heat conditions; strong traction in cement and chemical sectors where continuous, high-grade heat streams exist.
- ElectraTherm (BITZER Group), Orcan Energy, ENOGIA, Calnetix, Alfa Laval — A cohort of specialist vendors and equipment suppliers offering micro-ORC modules, modular packages, and integrated heat-exchanger solutions that lower project complexity for lower-temperature and distributed sources.
Recent market activity (e.g., major commissioning events and contract awards in 2025–2026) validates both the technical readiness and the commercial appetite for ORC WH2P projects. These events are summarized in our report alongside vendor scoring and reference-case financials.
Risks, regulatory drivers, and operational realities
- Regulatory tailwinds: Policies promoting industrial energy efficiency and decarbonization — such as targeted European initiatives — are creating incentives and grant programs that materially improve project IRRs in affected geographies.
- Working-fluid and materials risk: Potential restrictions on certain PFAS/HFC-type fluids can force retrofit or redesign costs if projects rely on affected fluids. Our report includes mitigation pathways and cost implications for transitioning to natural or low-GWP alternatives.
- Operational payback variability: Typical payback ranges for cement-plant retrofits fall into a multi-year band influenced by electricity pricing and heat availability. We provide benchmarking cases and sensitivity analyses so decision makers can avoid overly optimistic projections.
- Execution complexity: Successful projects blend process engineering with mechanical delivery and long-term O&M discipline. The vendors best positioned for growth are those combining robust turbomachinery with field service networks and digital performance monitoring.
How executive teams should use this intelligence in 2026
- Incorporate ORC WH2P into capital prioritization exercises for energy-intensive business units and assess cross-site rollouts with standardized screening criteria.
- Engage procurement early to lock preferred component suppliers and secure lead times, especially for projects targeting 2027–2028 commissioning windows.
- Use our supplied financial templates to stress-test projects versus market volatility (energy prices, carbon pricing) and to structure performance-linked contracting.
- Build a phased deployment approach: pilot a representative site to validate assumptions, then scale using a templated procurement and O&M model.
Next steps and where to get the full report
This preview highlights the strategic value of ORC WH2P intelligence for 2026 decision-making. PW Consulting’s full market report includes the detailed regional and application segmentation, vendor scorecards, modelled project economics, and downloadable tools referenced above. To access the complete analysis, proprietary databases, and scenario-level spreadsheets, visit our report page or contact our advisory desk for a briefing tailored to your industry and asset portfolio.
PW Consulting remains available to support executives with bespoke diligence, vendor selection support, and transaction advisory as companies move from intention to implementation in the accelerating ORC WH2P market.
For detailed analysis of this topic, please visit the official page: Organic Rankine Cycle Waste Heat To Power Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial Aircraft In-Seat Power Market to Grow from USD 164.78 Million in 2025 to USD 229.62 Million by 2032, Tracking a 4.85% CAGR
By PW Consulting, 2026-07-06
Commercial Aircraft In-Seat Power System Market: Strategic Signals for 2026 Decision-Makers
PW Consulting’s latest market study on the Commercial Aircraft In-Seat Power System Market delivers a tactical intelligence package for aviation executives entering 2026. Grounded in historical observation (2020–2025) and forward-looking forecasting (2026–2032), this report translates market dynamics into immediate actions for airlines, OEMs, Tier‑1 suppliers, and investors. The headline: after a pandemic-era trough, the in‑seat power market has recovered to roughly USD 164.8 Million in 2025 and is forecast to reach approximately USD 173.4 Million in 2026, growing at a compound annual growth rate (CAGR) of 4.85% through 2032 (targeting about USD 229.6 Million by 2032). This trajectory reframes in‑seat power from a passenger amenity to an operational baseline and a strategic battleground for cabin systems differentiation.
Why 2026 Is a Strategic Inflection Point
-
Normalization of passenger travel demand combined with an acceleration in BYOD (bring-your-own-device) behavior has elevated seat-level power from a premium feature to a network expectation. Carriers that treat power provisioning as a capacity and service KPI will gain immediate loyalty and ancillary revenue advantages.
-
Regulatory and materials pressures are converging to reshape product architectures: regulators are coalescing around more universal USB‑C standards, and supply‑chain constraints (notably on high‑grade copper) are accelerating higher‑voltage distribution strategies and lighter power electronics. These technical constraints create a narrow window in 2026 for suppliers to set design wins that persist for the next decade.
-
Commercial pressures on aircraft weight and cabin space — driven by fuel‑efficiency mandates — make compact, high‑efficiency power converters and slimline mounting solutions a procurement priority. Early adopters of optimized power architectures in 2026 will realize fuel and maintenance benefits beyond the device charging value proposition.
What the Report Delivers: Practical Tools, Not Just Projections
This study is intentionally operational. Beyond headline sizing and CAGR, the report contains a suite of practitioner-focused deliverables designed to inform procurement cycles, product roadmaps, and M&A evaluation in 2026:
-
Validated market-sizing methodology and a transparent reconciliation of historical data (2020–2025) with our 2026–2032 base-case and two alternate scenarios — upside (accelerated USB‑C adoption and retrofit cycles) and downside (supply‑chain shocks and slower airline capex).
-
Decision-grade supplier scorecards covering product breadth, linefit/retrofit capabilities, certification timelines, service networks, and integration readiness with IFE and cabin electronics — calibrated for procurement teams to shortlist finalists in a 90‑day vendor selection process.
-
Total Cost of Ownership (TCO) models and payback simulations that capture energy consumption, weight penalties, wiring strategy, maintenance roadmap, and ancillary revenue potential from seat-level charging services.
-
Integration playbooks for OEMs and seat vendors that map mechanical, electrical, and software integration checkpoints; certification risk matrices; and testing timelines to shorten time-to-service for new linefit programs.
-
A retrofit vs. linefit adoption curve and fleet prioritization matrix to help airlines allocate capital across fleet classes, route profiles, and customer segments — enabling staged rollouts that maximize short‑term ROI while preserving long‑term compatibility.
-
M&A and partnership blueprints illustrating value-creation levers (software-enabled services, aftermarket support contracts, regional aftermarket penetration), with sensitivity analyses tied to supply‑chain elasticity and regulation-driven technical requirements.
Competitive Landscape: Who Matters and Why
The market is moderately concentrated: the top three suppliers capture roughly half of current market value, while the leading five control approximately two‑thirds. That structure produces a dual landscape of established integrators and specialized innovators — a dynamic that favors strategic partnerships and selective vertical integration.
-
Astronics Corporation (East Aurora, NY) continues to set product benchmarks with its EmPower product line — most recently introducing the EmPower 1327‑27 Dual USB‑Type‑C outlet in April 2026. Astronics’ focus on high‑power USB‑C and proven linefit and retrofit installs positions it as the default choice for carriers seeking low‑risk rollouts and rapid certification pathways.
-
Collins Aerospace (Charlotte, NC) remains a systems integrator with strength in cabin electrics and data ports, offering integrated solutions where power is bundled with IFE and seating systems — a compelling value proposition for OEMs seeking single‑vendor integration and simplified aircraft contracts.
-
IFPL Group (Isle of Wight) and specialist OEMs such as Burrana (Cannon Hill, QLD) and KID‑Systeme (Buxtehude, Germany) are driving innovation at the module and UX level. Burrana’s RISE platform positioning and IFPL’s 30th anniversary showcase at AIX underline the focus on modular cabin ecosystems and long-term service footprints.
-
Panasonic Avionics (Lake Forest, CA) has demonstrated system-level differentiation by coupling high‑power USB‑C delivery with its Astrova IFE — a deployment that entered service with Air Canada in April 2026 and signals the commercial viability of integrated IFE‑power offerings for premium cabins and transcontinental widebody operations.
-
Component specialists such as Mid‑Continent Instrument Co. (True Blue Power) and Astrodyne TDI supply critical electrical subsystems — from TSO‑certified chargers to custom power modules — and therefore act as attractive acquisition targets for integrators seeking tighter control of supply chains and performance tuning.
Recent Developments and Strategic Implications
-
Astronics’ product launch of a dual USB‑C outlet (April 2026) accelerates the industry’s shift to high‑power, universal charging and raises the bar for retrofit packages — signifying that cargo‑weight tradeoffs must now include device power economics.
-
Burrana’s visible positioning at AIX 2026 and IFPL’s showcase activity underline trade show channels as primary deal‑making venues for 2026 — procurement calendars should align RFP cycles with major industry events to capture first‑mover integration advantages.
-
Panasonic’s Astrova deployment with high‑power USB‑C demonstrates the commercial momentum for tightly coupled IFE‑power propositions in airline product differentiation — a signal for carriers to revisit content‑plus‑power bundling strategies.
-
Regulatory momentum toward USB‑C standardization and aircraft efficiency mandates (including pressure to reduce cavity and weight by approximately a quarter for certain power components) make 2026 a critical year to adopt designs that will remain compliant and efficient for the next retrofit horizon.
Risks, Supply Constraints, and Mitigations
Our scenario analysis surfaces three primary risk vectors for 2026 decision-makers:
-
Supply-chain tightness for high‑grade copper and specialty semiconductors, which can delay certification and inflate retrofit costs. Mitigation: lock multi‑year supply agreements with alternative material strategies (higher‑voltage architectures) and dual‑sourcing clauses.
-
Standardization uncertainty around USB‑C power‑delivery profiles and airline policies for power management. Mitigation: deploy configurable power modules with field‑upgradeable firmware and negotiate standards‑aligned warranties.
-
Competitive displacement from bundled IFE‑and‑power offers. Mitigation: pursue commercial partnerships to bundle power with content and ancillary monetization platforms or focus on aftermarket service contracts that lock in long‑tail revenues.
Actionable 90‑Day Plan for 2026
-
Carriers: Audit fleet retrofit potential using our fleet prioritization matrix; pilot high‑power USB‑C on targeted narrowbody transcon and long‑haul aircraft to measure customer behavior and ancillary monetization.
-
OEMs and Seat Vendors: Finalize modular power integration standards and lock seat‑level mechanical interfaces to accelerate linefit time to service. Use the report’s integration checklist to reduce certification surprises.
-
Suppliers: Reassess BOMs for copper intensity and reprice offerings with higher‑voltage variants; prepare product line options that trade a small increase in initial unit cost for long‑term weight and maintenance savings.
-
Investors: Use the supplier scorecards and TCO scenarios to identify high‑margin retrofit specialists or vertically integrative candidates for selective M&A — targets that can deliver aftermarket service revenue and have clear paths to recurring software updates.
Why PW Consulting’s Study Is Decision-Critical
For 2026 planning cycles, the report offers more than market numbers: it synthesizes regulatory trends, supplier positioning, and engineering constraints into transaction‑ready guidance. Whether your objective is to accelerate retrofit rollouts, secure linefit design wins, hedge supply risk, or evaluate acquisition targets, the analyses — from TCO models to supplier scorecards and scenario stress tests — turn uncertainty into executable timelines and KPIs.
We intentionally present high‑confidence insights while withholding detailed segmentation tables and full numerical breakdowns in this summary. To access the complete datasets, regional and class-level splits, supplier scorecards, and downloadable financial models that underpin our recommendations, visit the PW Consulting report page or contact our advisory desk to arrange a briefing. For teams with immediate 2026 procurement windows, our analysts are available for short‑term workshops that convert the report’s findings into RFQ specifications and certification roadmaps.
For detailed analysis of this topic, please visit the official page: Commercial Aircraft In Seat Power System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerial Target Drones Market to Expand at 8.12% CAGR — From USD 6,250 Million in 2025 to USD 10,790 Million by 2032
By PW Consulting, 2026-07-06
Aerial Target Drones Market: Strategic Intelligence for 2026 Decision-Makers
Executive snapshot
As defense planners, program managers, and investors prepare budgets and strategic roadmaps for 2026, the aerial target drones market presents a clearly accelerating opportunity — one driven by sustained modernization, rising training tempo, and a growing need for realistic threat representation across joint forces. Our new market model projects the global market expanding from roughly USD 6,250 Million in the report base year (2025) to about USD 10,790 Million by 2032, reflecting a compounded annual growth rate (CAGR) of 8.12% across the 2026–2032 forecast window. Historic momentum through 2020–2025 confirms the structural demand drivers that underpin this outlook.
Aerial Target Drones Market
Why this matters for 2026 strategies
-
Procurement cadence and program sizing: The market trajectory signals a multiyear ramp in demand for expendable and reusable aerial targets, full-scale targets, and high-performance subscale jets. Agencies planning FY26–FY28 procurements should assume increased competition for production slots and consider multi-year contracting vehicles to lock in capacity and price certainty.
Aerial Target Drones Market -
Industrial base and supply resiliency: Structural supply-chain chokepoints — notably in rare-earth magnets, lithium-ion cells, and advanced semiconductors — are converging with policy-driven domestic sourcing preferences. In this context, sourcing strategies in 2026 must balance near-term availability with diversification of suppliers and qualified substitute components to avoid program slippage.
Aerial Target Drones Market -
Capability investment trade-offs: Decisions between fixed-wing, rotary, hybrid, and full-scale solutions are now as much about lifecycle logistics, survivability, and mission fidelity as unit cost. For many users, the premium for higher-fidelity targets is justified by reduced risk to manned assets and improved weapons-effectiveness measurement, but the value calculus varies by doctrine and fiscal environment — our report provides a scenario tool to inform these trade-offs.
Market dynamics shaping 2026 decision windows
-
Training intensity and realism: Elevating live-fire and integrated air defense training is a consistent priority among advanced militaries. Demand drivers include complex air-defense ecosystems, proliferation of advanced missiles, and the need to validate sensor-to-shooter chains under realistic threat conditions. These operational drivers translate into predictable demand for configurable threat-representation packages and expendable high-performance targets.
-
Policy and regulatory influences: Recent policy changes affecting export controls and defense acquisition are reshaping supplier access and partner selection. Notably, regulatory adjustments aimed at streamlining UAV exports to allied partners and concurrent emphasis on domestic sourcing for defense UAS components directly affect where program work is performed, how supply chains are structured, and which vendors are prioritized in RFPs.
-
Concentration and competitive pressure: The sector exhibits moderate concentration: leading vendors collectively hold a significant share of program awards and lifecycle service contracts. That structural concentration creates predictable centers of gravity for innovation and scale but also opens tactical opportunities for niche players that can deliver differentiated cost-to-capability propositions, rapid integration of sensors and signatures, or unique lifecycle support benefits.
-
Technology and standards convergence: Advances in telemetry, signature control, autonomous flight control, and data-fusion are enabling more realistic and reusable target constructs. Standards around interoperability with live-fire weapons systems and range instrumentation are coalescing, and suppliers who lead on open interfaces will capture follow-on sustainment and augmentation contracts.
Competitive landscape — what we analyzed and why it matters
Our competitive analysis synthesizes program pipelines, recent contract awards, and capability roadmaps across prime manufacturers and specialist target providers. The marketplace features a mix of large systems integrators — who bring full-scale conversion and program-management capabilities — and specialized OEMs that supply subscale jets, rotary targets, and modular signature kits for realistic threat emulation.
-
Prime integrators and full-scale conversion: Aerospace primes with large airframe inventories and conversion experience remain indispensable for full-scale target programs. They provide unique value for weapon-system testbeds and high-fidelity endgame training.
-
Specialist target OEMs and scalable providers: Companies that specialize in subscale, expendable, and reusable target drones are winning a steady stream of live-fire training and RDT&E missions due to favorable cost-per-shot economics and mission flexibility. Their ability to deliver end-to-end systems — including telemetry, scoring, and signature augmentation — is increasingly a competitive differentiator.
-
Service and sustainment plays: Follow-on service contracts (flight hours, spares, and target refurbishment) are a significant revenue pool and a key battleground for long-term customer relationships. Firms that secure multi-year sustainment contracts capture durable annuities and valuable operational data to inform product upgrades.
Recent program signals (selection)
-
Multiple recent awards and contract actions have reinforced vendor positioning in the North American and allied procurement communities — including follow-on production awards for established high-performance subscale targets and follow-on support contracts for uncrewed aerial target services.
-
Industry collaborations and overseas partnerships underscore the cross-border transfer of target-system know-how, particularly where partner nations seek local production or adaptation for regional training needs.
-
Follow-on conversions of legacy fighter aircraft into full-scale, non-crewed target assets continue to be an attractive option for customers requiring representative large-target signatures for weapons testing.
Strategic actions for defense buyers and suppliers in 2026
-
Buy-side: Lock in multi-year capacity, but require supply transparency. Given projected growth and supply-chain fragilities, program offices should prioritize multi-year awards linked to firm delivery milestones and supplier diversification clauses. Explicitly require component provenance disclosures for critical subsystems to mitigate downstream compliance and sustainment risks.
-
Supplier-side: Move up the value chain and secure lifecycle revenue. Target OEMs should bundle signature kits, telemetry services, and aftermarket refurbishment into subscription-style offerings that capture recurring revenue and raise switching costs for customers.
-
Investors and M&A teams: Look for capability adjacencies. Opportunities exist for strategic acquisitions that provide access to domestic production capabilities, secure supply of critical components, or unique modeling-and-simulation IP that enhances target realism.
-
R&D and partnerships: Prioritize component substitutes and hardened supply lines. Investment in alternative magnet sources, domestic cell production, and semiconductor resiliency will be rewarded by both customers and policy-makers. Joint ventures and supplier development programs are pragmatic ways to accelerate qualification cycles.
What PW Consulting’s report delivers (practical contents)
-
Transparent market model with historical baseline and forward-looking projections calibrated to program award pipelines and fielding timelines; scenario permutations to stress-test procurement plans against variations in geopolitical tension and supply-chain disruption.
-
Vendor scorecards that synthesize capabilities, proven delivery records, program wins, sustainment footprints, and interoperability readiness — presented to help contracting authorities short-list suppliers efficiently.
-
Actionable procurement playbooks and checklist templates for acquisition teams that cover contract types, performance incentives, compliance anchors, and recommended warranties/assurances for critical subsystems.
-
Supply-chain heat map that highlights chokepoints, second-source opportunities, critical lead-time sensitivities, and recommended mitigation options — tailored for program offices and supplier risk teams.
-
Regulatory and export-control briefing tailored to allied exchange programs and international cooperation cases, summarizing practical implications for transfer, co-production, and lifecycle support of UAS targets.
Why senior leaders should read the full report
This executive release intentionally highlights the strategic contours of the aerial target drones market without exposing the granular segmentation tables, regional allocations, or unit-price schedules that many operational decisions require. The full PW Consulting report includes the detailed splits, vendor-level financial modeling, contract pipelines, and procurement templates that program offices, prime contractors, and investors need to finalize 2026 commitments with confidence.
Closing recommendation
For leaders aligning budgets, negotiating long-term supplier agreements, or sizing investment roundups in 2026, the combination of a robust market upcycle, concentrated supplier dynamics, and policy-driven sourcing constraints requires deliberate, evidence-based choices. Use the market’s projected growth as a planning spine, but ground near-term commitments in supply-chain verifications and contracted sustainment pathways. PW Consulting’s full Aerial Target Drones Market report provides the granular decision-support tools to convert these strategic imperatives into executable plans.
Next steps
-
Request the full report and vendor appendices to access detailed regional and application splits, price curves, and program-level risk assessments that underpin the projections summarized here.
-
Engage PW Consulting for a tailored briefing: we provide scenario workshops to stress-test procurement strategies and supplier sourcing plans against the most likely 2026 policy and supply-chain scenarios.
For detailed analysis of this topic, please visit the official page: Aerial Target Drones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Wireless POS Terminal Market Projected to Reach USD 13.8 Billion by 2032, Says New Report
By PW Consulting, 2026-07-06
Smart Wireless POS Terminal Device Market — Strategic Insights for 2026 Decision-Makers
Executive summary
The smart wireless POS terminal market has moved from a specialized, hardware-centric niche into a strategic layer of commerce infrastructure. Between 2020 and 2025 the global market expanded materially, and our base-year analysis shows continued acceleration into the forecast horizon. PW Consulting projects sustained growth through 2032 at a compound annual growth rate of 9.25%, reflecting accelerating adoption of Android-based SmartPOS platforms, growing demand for mobility and contactless payments, and rising integration of payment capabilities with business applications.
Smart Wireless Pos Terminal Device Market
For 2026 planning cycles, this report provides decision-makers with the data, evaluation frameworks, and executable playbooks they need to align product roadmaps, procurement strategies, go-to-market models, and M&A activity to the shifting economics of retail, hospitality, transportation and adjacent verticals.
Smart Wireless Pos Terminal Device Market
Why this report matters in 2026
-
Strategic timing: 2026 is the inflection year for firms that either want to lead in integrated commerce experiences or secure defensive positions in omnichannel payments. Investments made this year will determine market share dynamics for the rest of the decade.
Smart Wireless Pos Terminal Device Market -
Risk management: Certification mandates (for example, the latest PCI PTS 7.x family for physical protection and cryptographic assurance) and EMV/NFC compliance for Android SmartPOS are reshaping procurement checklists. Non-compliant deployments create both regulatory and reputational exposure.
-
Vendor selection complexity: The market’s competitive structure is moderately concentrated — a handful of vendors capture a material portion of industry revenue — but there is meaningful room for specialist entrants and verticalized solutions. This makes vendor evaluation and integration strategy critical.
-
Actionable intelligence: The report is designed as an operational handbook, not just an academic forecast. Subscribers receive templates, vendor scorecards, and RFP artifacts that accelerate procurement and reduce time-to-deployment.
What the PW Consulting report delivers
-
Market sizing and validated forecasts (2026–2032) with scenario paths reflecting low-, base-, and high-adoption outcomes driven by payment rails, connectivity upgrades (4G/5G/Wi‑Fi), and OS migration cycles.
-
Vendor benchmarking and capability heatmaps that evaluate product security, platform openness (Android vs. proprietary OS), lifecycle management, firmware-update practices, and certification readiness.
-
Commercial playbooks for vendors and enterprise buyers: go-to-market segmentation, channel strategies for SMEs vs. large retailers, bundle pricing and subscription models, and service-level playbooks for hardware-as-a-service.
-
Integration and deployment toolkit: RFP templates, test-case matrices, a compliance checklist for PCI/EMV/NFC, and a practical guide to rollout phasing that minimizes POS downtime during upgrades.
-
M&A and partnership playbook: criteria for strategic acquisitions, diligence checklists for hardware/software combos, and value-capture models for vertical specialization (e.g., restaurants, transportation, healthcare).
-
Supply-chain & sourcing advisory: component risk scoring, alternative sourcing strategies for radio modules and secure elements, and planning for certification/lifecycle costs.
Competitive landscape — what leaders and challengers are doing
The market is characterized by a mix of long-standing payments OEMs, platform-integrated players, and software-first disruptors. The three-largest vendors capture a significant share of revenue, and the top five together represent a majority position — a construct that benefits scale players while leaving meaningful opportunity for differentiated propositions.
-
Ingenico (Paris, France) — strong in portable wireless devices and field-service terminals with established global certifications. Its focus on secure connectivity (Wi‑Fi, Bluetooth, 4G) and proven form factors makes it a default choice for large retailers and field operations where reliability and certification history matter.
-
Verifone (San Jose, USA) — maintains a broad portfolio of smart wireless POS products and deep enterprise relationships across retail and hospitality. Verifone’s strength is platform breadth and integration with enterprise payment ecosystems.
-
PAX Technology (Shenzhen / North America HQ in Jacksonville) — a leading proponent of Android-based SmartPOS, aggressively pursuing restaurant and mobility use cases with modern hardware that emphasizes extensibility and app ecosystems.
-
Newland Payment Technology and Castles Technology — competitive hardware OEMs that focus on secure Android devices and compact form factors for mPOS and countertop migrations.
-
NEXGO — positions with durable mini POS and IP-rated devices for mobile scenarios where ruggedness and compact design are differentiators.
-
Worldline — increasingly active in Europe with Android SmartPOS launches and integration of payment processing and business apps for SMEs; recent product launches indicate consolidation of its platform play.
-
Square (Block) and Toast — software-led providers that control both experience and payments stack for SMBs and restaurants; their advantage lies in frictionless onboarding and SaaS+hardware bundling.
-
NCR Voyix — focused on integrated solutions for retail and hospitality where back-office parity and enterprise grade support are essential.
Recent vendor moves in 2025–early 2026 — including platform launches and upgraded Android devices — confirm a market pivot toward software-enabled hardware and deeper ecosystem integration. Notably, several players emphasized Android SmartPOS rollouts and trade-show debuts targeting restaurants and SMEs.
Market dynamics that will shape 2026 decisions
-
Security & certification: The adoption of PCI PTS 7.x is becoming a gating factor for international deployments. Buyers must budget for certification cycles and expect longer lead times for devices that require updated physical and cryptographic protections.
-
Platform standardization: Android-based SmartPOS devices represent a major share of recent unit shipments, driving an app-centric model where third-party ISVs can extend device utility. This trend benefits providers that offer open SDKs and robust lifecycle management.
-
Contactless & user experience: Contactless payments (NFC/EMV) and mobile wallet integration are table stakes in Europe and North America. Devices that couple payments with CRM, loyalty and analytics capabilities win higher wallet share per location.
-
Concentration vs. specialization: While the market shows meaningful concentration at the top, specialized vendors win where vertical-specific features (restaurant order routing, transport fare collection) or ruggedized hardware are required.
Practical recommendations for 2026
-
Adopt a security-first procurement checklist: include PCI PTS 7.x readiness, secure element provisioning, and a vendor commitment to long-term firmware support in contract SLAs.
-
Prioritize platform openness: favor vendors offering Android-based SmartPOS with mature SDKs and app-store-like distribution for enterprise apps to reduce custom integration costs.
-
Design pilot-to-scale paths: execute narrow pilots focused on a single vertical KPI (e.g., table-turn time in restaurants or queue reduction in transportation) before committing to full-scale rollouts.
-
Incentivize lifecycle economics: evaluate hardware-as-a-service and managed-device models to shift CAPEX to OPEX, while ensuring clear SLAs for security patching and replacement cycles.
-
Insist on supplier transparency: include supply-chain and component-substitution clauses to mitigate radio-module shortages and certification rework.
-
Build integration-ready teams: create a cross-functional squad (payments, security, ops, product) to manage rollouts and reduce time-to-value.
How clients use this report
Procurement teams use the report’s vendor scorecards and RFP templates to reduce evaluation time by weeks. Product leaders use the technology roadmap and app-integration blueprints to prioritize investments that increase device attach rates. Investors and corporate development teams leverage the M&A playbook and vendor financial overlays to identify acquisition targets and partnership opportunities. Finally, operations teams use the deployment checklists and lifecycle models to avoid common rollout pitfalls.
Next steps — where to get the full intelligence
This announcement highlights the strategic findings and operational implications we believe are most material for 2026 decision-making. In keeping with our “trailer” principle, granular segment-level tables and confidential vendor splits are intentionally omitted from this release to protect proprietary analysis and to invite stakeholders who require the full data set to access the comprehensive report.
PW Consulting’s full Smart Wireless POS Terminal Device Market report includes the detailed segmentation, downloadable vendor scorecards, RFP templates, and a dynamic TCO model. For procurement teams, product executives, and investors planning actionable initiatives in 2026, the full report is the tool that shortens decision cycles and de-risks execution.
For detailed analysis of this topic, please visit the official page: Smart Wireless Pos Terminal Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Hybrid Cross Car Beam Market to Expand at a 6.0% CAGR Through 2032
By PW Consulting, 2026-07-06
Hybrid Cross Car Beam Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting’s new market study on the Hybrid Cross Car Beam market (base year 2025, forecast period 2026–2032) arrives at a pivotal moment for automotive decision-makers. Measured in USD (Million), the market expanded from approximately USD 1.48 billion in 2020 to USD 2.13 billion in 2025 and is projected to reach roughly USD 3.20 billion by 2032, reflecting a compound annual growth rate of 6.0% across the forecast window. This trajectory confirms hybrid cross car beams are moving from niche engineering experiments toward mainstream vehicle architectures — but the route to profitable scale is uneven and strategic choices made in 2026 will determine who wins the next wave.
Hybrid Cross Car Beam Market
Why 2026 is a strategic inflection point
-
Regulatory and sustainability pressures are accelerating adoption. New lightweighting mandates and corporate CO₂ targets are increasing the value of hybrid structural components that combine metal and high‑performance polymers or composites.
Hybrid Cross Car Beam Market -
Electrification is reshaping packaging, safety, and NVH requirements. Vehicle manufacturers must reconcile mass reduction with crash and airbag integration, HVAC routing and electronic architecture constraints — engineering trade-offs that hybrid beams can resolve when designed for multifunctionality.
Hybrid Cross Car Beam Market -
Material and process innovations are reaching production maturity. Thermoplastic injection molding with localized metal reinforcement, carbon‑fiber‑reinforced polyamides with recycled feedstocks, and aluminum‑hybrid approaches are now commercially validated. The next 18–24 months are about industrializing these solutions at platform scale.
-
Market structure is consolidating but not closed: the top three firms account for nearly half of current market capacity while the top five exceed sixty percent, signaling concentrated supplier power and attractive windows for specialist challengers.
What PW Consulting’s report delivers — operational, decision‑ready intelligence
We designed this study to be actionable for executives planning 2026 programs. The report goes well beyond descriptive market sizing to provide a toolkit for implementation:
-
Integrated market model (measured in USD Million) with scenario toggles for EV penetration, regulatory tightening and raw‑material price shocks — usable as an input to corporate planning and board materials.
-
Technology deep dives that map material options (thermoplastics, carbon‑fiber reinforced polyamides, aluminum/steel hybrids), manufacturing routes (injection molding with local metal reinforcement, hybrid stamping/insertion processes) and trade‑off matrices for weight, cost, cycle time and recyclability.
-
Practical cost and life‑cycle calculators — including a CO₂ footprint module — to quantify the effects of replacing metal‑dominant beams with hybrid alternatives across platform lifecycles.
-
Supplier benchmarking templates and a readiness scoring system that capture manufacturing scale, IP position, certification status, and integration capability — intended for procurement RFPs and joint development selection.
-
Validation protocols and assembly checklists that accelerate pilot‑to‑production transfer: tooling recommendations, cycle time optimization guidance, crash and airbag mount verification checkpoints, and recycling/reverse‑logistics flows.
-
Playbooks for partnerships, joint ventures and M&A — including target archetypes, valuation levers, and integration risk matrices tailored to OEMs and Tier‑1s pursuing verticalization or capability sourcing.
Key macro signals and implications for 2026 decisions
The reported market growth and the 6.0% CAGR reflect a shift from experimentation to industrial roll‑out. For executives, three high‑level implications matter:
-
Invest in platform‑level standardization now. The economic case for hybrid beams improves when common modules are designed across vehicle families; delaying standardization cedes cost advantage to early adopters.
-
Prioritize multifunctional design. The highest commercial upside accrues to beams that integrate attachments (airbag mounts, HVAC ducts, electronics) and reduce downstream parts count and assembly time.
-
Price and supply risk must be hedged. Access to high‑performance thermoplastics and recycled carbon fiber feedstocks is a differentiator — locking in supply or backing upstream suppliers mitigates volatility.
Competitive landscape — who matters and why
The report profiles the leading industrial players that will shape competitive outcomes. Our analysis combines capability mapping with strategic intent, highlighting where incumbents are defending share and where specialist suppliers are carving niches.
-
Röchling Automotive (Germany) — brings metal‑plastic hybrid expertise focused on combining structural metal stability with plastic lightness and integrated functions. Their approach emphasizes flexibility of design and functional consolidation.
-
ElringKlinger (Germany) — a leader in thermoplastic injection molding with local metal reinforcement, delivering highly functional, low‑weight beams tailored for e‑mobility requirements.
-
FORVIA / Faurecia (France) — pursues modular, PA‑based injected hybrid beams aimed at platform standardization and measurable weight/emissions reductions.
-
Envalior (Netherlands/Germany) and AKRO‑PLASTIC GmbH (Germany) — material specialists supplying high‑performance polyamides and recycled carbon‑reinforced resins that enable 20–30% weight savings against steel baselines while controlling cost and recyclability.
-
Magna International (Canada), Gestamp Automoción (Spain) and Benteler Automotive (Germany) — system suppliers focusing on integrative structural solutions for electrified platforms, combining lightweight metals and hybrid composites with established Tier‑1 integration capability.
Recent industry developments underscore strategic momentum. Notably, a major OEM’s low‑carbon hybrid beam design — replacing magnesium with a fibre‑reinforced plastic plus steel solution — is projected to reduce annual CO₂ emissions substantially, and a market‑leading EV chassis project captured a prestigious award for a carbon‑fiber‑reinforced polyamide/steel hybrid beam. These events are evidence that sustainability and performance are converging into commercially viable products today, not tomorrow.
Supplier selection and competitive positioning framework
Choosing partners in 2026 requires a structured evaluation beyond price:
-
Technology readiness and IP footprint — can the supplier demonstrate crash‑level performance and long‑term durability on comparable platforms?
-
Manufacturing scale and geographic footprint — does the supplier have proven, serial production lines and the ability to localize content for regional sourcing rules?
-
Sustainability credentials — transparency in material sourcing, recycled content, and measurable CO₂ savings through life‑cycle analysis.
-
Integration capability — experience embedding mounts, ducts and electronics into the beam to reduce downstream costs.
-
Commercial flexibility — willingness to co‑invest in tooling, amortization models, and risk‑sharing arrangements for early production ramps.
Manufacturing and supply‑chain implications
Operational readiness is often the gating factor for adoption. Our operational guidance includes:
-
Invest in hybrid tooling and validation rigs early. Tooling for thermoplastic/metal hybrids and associated insertion processes requires upfront capital and longer lead times than simple stamped metal parts.
-
Plan for mixed‑material repair and recycling. Design for disassembly and material identification protocols are essential to meet circularity and regulatory requirements without imposing excessive end‑of‑life costs.
-
Secure polymer and recycled‑carbon supply chains. Material suppliers that can deliver consistent properties and validated material certifications will shorten qualification cycles.
-
Optimize logistics for larger, lower‑density parts. Storage, transportation and assembly interfaces must be recalibrated — savings on vehicle mass can be offset by complexity in handling if ignored.
Finance, M&A and partnership plays
Given current concentration metrics and the technology intensity of hybrid beams, we see multiple value creation pathways:
-
M&A targets: material innovators with validated high‑performance resins, mid‑sized system integrators with platform integration experience, and regional manufacturers with complementary capacity.
-
Joint development: co‑fund tooling and validation with strategic suppliers to accelerate transfer to production while sharing commercialization risk.
-
Licensing and IP monetization: OEMs may find it efficient to license material/process IP rather than internalize all capabilities — the report includes templates for license valuation and royalty structures.
How to use the full report (and why it matters for 2026)
This briefing is intentionally diagnostic and strategic — a “trailer” of the deeper, operational intelligence inside the full PW Consulting study. The comprehensive report contains the granular segmentation, regional and application breakdowns, downloadable financial models, supplier scorecards and the detailed validation checklists that procurement, engineering and strategy teams need to finalize 2026 budgets and program roadmaps.
If your 2026 plan involves platform redesigns, electrified architectures, or aggressive CO₂ and weight targets, this is the moment to move from pilot projects to costed, board‑level commitments. The hybrid cross car beam market is maturing, supplier power is consolidating, and material/process winners are emerging — firms that translate these signals into disciplined investment, supplier partnerships and industrial readiness in 2026 will enjoy sustained advantages through the forecast period.
For organizations that want to convert these insights into action — from TCO models and supplier selection templates to M&A target lists and co‑development playbooks — PW Consulting’s full Hybrid Cross Car Beam Market report is designed as the operational companion to your 2026 strategy. Visit our report page to access the complete dataset, proprietary models and supplier evaluations.
For detailed analysis of this topic, please visit the official page: Hybrid Cross Car Beam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chromatography Cartridges Market Poised for Robust Expansion — 7.85% CAGR Projected Through 2032
By PW Consulting, 2026-07-06
Chromatography Cartridges Market — Strategic Brief for 2026 Decision‑Makers
Executive snapshot
PW Consulting’s new industry briefing on the Chromatography Cartridges market positions leaders and challengers for the next strategic cycle. Our analysis uses 2025 as the base year and projects the market through 2032. The market reached approximately USD 925 million by 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 7.85% across the 2026–2032 horizon, approaching an estimated USD 1.57 billion by 2032. For boards, corporate strategists, and investment teams planning moves in 2026, these dynamics translate into a defined window for capability building, M&A activity, and supply‑chain reconfiguration.
Chromatography Cartridges Market
Why this report matters for 2026 strategic planning
- Decision alignment: Translates macro growth into specific investment triggers for product development, manufacturing scale, and commercial expansion.
- Risk prioritization: Identifies near‑term operational exposures (raw materials, regulatory documentation, capacity bottlenecks) that could erode margins or delay time‑to‑market.
- Competitive posture: Maps concentration and capability gaps to reveal where incumbents are vulnerable and where scale or technological differentiation matters.
- Actionability: Presents prioritized playbooks — from short‑cycle product launches to medium‑term M&A — with clear KPIs for 18–36 month execution.
Market trajectory and underlying forces
The market’s sub‑10% CAGR masks a heterogeneous set of demand drivers. Continued expansion of biologics, the intensification of food and environmental testing regimes, and steady investment in university and industrial R&D underpin baseline demand. At the same time, rising regulatory rigor in bioprocessing — including GMP traceability and documentation requirements for large‑scale cartridges — elevates the value of compliance‑ready products and service offerings.
Chromatography Cartridges Market
On the materials and technology side, silica‑based stationary phases remain dominant. Spherical silica continues to be preferred where reproducibility and resolution are commercially critical (e.g., flash and HPLC applications), while innovations in monolithic and affinity media are shaping niche, high‑value use cases in bioprocessing. These technical preferences impose both product development imperatives and supply‑chain considerations for raw silica supply and particle engineering capabilities.
Chromatography Cartridges Market
Market structure and competitive concentration
The market is moderately consolidated. The top three suppliers account for roughly 38.5% of market revenue, and the top five capture approximately 52.7%, illustrating a competitive landscape where a small set of global players set technological and commercial reference points, while numerous specialized and regional vendors compete on price, customization, and service. This concentration suggests that scale and platform breadth remain meaningful advantages, but there is room for targeted entrants that bring differentiated technology or a services‑led model.
Competitive landscape — strategic implications
- BUCHI Labortechnik (Flawil, Switzerland) — Strength: prefilled flash cartridges (FlashPure series) in silica and bonded phases across a wide size range. Strategic implication: appeals to purification labs that prioritize throughput and reproducibility; an attractive partner or acquisition target for firms seeking bench‑to‑process product line extensions.
- Biotage (Uppsala, Sweden) — Strength: branded prepacked flash cartridges across normal and reversed phases supporting drug discovery and research scales. Strategic implication: deep ties to medicinal chemistry and CRO workflows; licensing or co‑development can accelerate adoption in discovery pathways.
- Restek Corporation (Bellefonte, PA, USA) — Strength: guard column cartridges and inert products aimed at protecting sensitive columns and metal‑sensitive compounds. Recent product introductions underscore an emphasis on protection and longevity for analytical workflows.
- Sartorius AG (Göttingen, Germany) — Strength: process‑scale monolithic and CIMmultus cartridges for large‑molecule purification. Strategic implication: well positioned for high‑value bioprocessing contracts but requires GMP grade supply chains and audit readiness.
- Agilent Technologies (Santa Clara, CA, USA) — Strength: HPLC columns and guard cartridges with ultra‑inert chemistries optimized for biotherapeutics. Recent Altura Ultra Inert launches signal a push into higher‑margin biopharma analytics.
- Waters Corporation (Milford, MA, USA) — Strength: advanced protein and affinity cartridges with precision purification technologies. Strategic implication: targets regulated biopharma workflows where performance is a premium purchase driver.
- Thermo Fisher Scientific (Waltham, MA, USA) — Strength: breadth across analytical to preparative offerings and strong distribution channels; remains a default supplier for many labs.
- Orochem Technologies (Naperville, IL, USA) — Strength: diverse portfolio covering flash, HPLC, UHPLC and GC products; competitive on customization and industrial scale solutions.
Notable recent product activity (illustrative): in mid‑late 2025, Restek launched new inert guard cartridge lines aimed at metal‑sensitive workflows, and Agilent released Altura Ultra Inert HPLC columns optimized for peptides and oligonucleotides. These moves underscore a trend: vendors are increasingly competing on inertness, robustness for biotherapeutics, and column protection, rather than purely on particle chemistry.
What the full report contains — practical, executable content
We designed this report as a strategic tool for executives, product leaders, and corporate development teams. Key deliverables include:
- Market sizing and 7‑year forecast model (2026–2032) with downloadable Excel model and scenario toggles.
- Demand analysis by product type, application segment, and region (with proprietary elasticity assumptions and adoption curves). Note: the headline summary above intentionally omits detailed splits to preserve proprietary segmentation; full tables are in the paid report.
- End‑to‑end supply‑chain mapping highlighting raw materials exposure (notably silica sourcing), critical process steps, and logistics chokepoints.
- Regulatory and quality matrix for bioprocess cartridges, including audit readiness checklists and documentation templates for GMP environments.
- Technology radar and innovation pipeline assessment, covering spherical silica, monolithics, affinity media, and cartridge formats optimized for low backpressure and high loading capacity.
- Competitive benchmark: in‑depth company profiles, recent developments, capability heatmaps, and an M&A target shortlist scored on strategic fit and integration risk.
- Go‑to‑market playbooks: product launch sequencing, pricing strategies, distributor vs direct channel decision trees, and sales incentive frameworks for 2026 rollout.
- Scenario analyses: supply‑shock, accelerated biologics uptake, and regulatory tightening — each with quantifiable revenue and margin impacts plus mitigation strategies.
Strategic recommendations for leaders planning 2026 moves
- Prioritize compliance‑ready offerings for bioprocessing: invest in documentation, traceability, and validated manufacturing to capture higher‑margin biopharma spend.
- Differentiate on inertness and protection: develop or partner for guard and inert cartridge technologies targeting metal‑sensitive analytes and delicate biologics.
- Secure raw material continuity: establish multi‑sourced contracts for spherical silica and consider strategic inventory or forward purchase arrangements to blunt price volatility.
- Build modular manufacturing capacity: favor nimble lines that can scale from analytical to preparative cartridges without long lead‑times; this reduces time‑to‑market for custom SKUs.
- Adopt a services layer: extend value via validation support, method transfer services, and lifecycle management contracts to increase switching costs.
- Pursue targeted M&A and alliances: prioritize acquisitions that plug technological gaps (e.g., affinity media, monolithics) or add direct access to regulated bioprocess customers.
- Implement a segmented pricing discipline: use performance‑based premium pricing in regulated and biotherapeutic segments while maintaining competitive cost options for routine analytical users.
Risk matrix and KPIs to monitor in 2026
Key risks include raw material supply shocks, accelerated regulatory scrutiny for bioprocess cartridges, and competitive pressure from vertically integrated suppliers who bundle cartridges with consumables and services. Recommended KPIs for executive dashboards:
- Regulatory readiness index (audit pass rate, documentation completeness)
- Supplier concentration ratio for critical raw materials
- Time‑to‑launch for new cartridge SKUs (days from design freeze to first shipment)
- Service revenue as a percentage of total (indicator of stickiness)
- Gross margin by application cluster (to prioritize high‑value segments)
Conclusion — the strategic window for 2026
The Chromatography Cartridges market presents both steady baseline growth and pockets of accelerated opportunity driven by biologics and heightened regulatory standards. For 2026, successful players will combine product technical differentiation (inertness, affinity, monolithic formats), operational resilience (silica sourcing and modular manufacturing), and commercial sophistication (service bundles and targeted pricing). PW Consulting’s full report provides the underlying datasets, proprietary segmentation, and executable playbooks needed to convert these strategic imperatives into measurable outcomes. Detailed segment tables, company valuations, and the downloadable forecast model are intentionally reserved for the complete report to preserve the depth required for transaction‑level decisions.
To access the full report, complete datasets, and the interactive forecast model, visit the PW Consulting Chromatography Cartridges market page or contact our industry practice for a tailored briefing and scenario workshop.
For detailed analysis of this topic, please visit the official page: Chromatography Cartridges Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


