



Category: Machinery & Automotive
PW Consulting: Steering Auxiliary Lamp Market Set to Grow at a 6.45% CAGR Through 2032
By PW Consulting, 2026-07-01
Steering Auxiliary Lamp Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting’s latest market study on steering auxiliary lamps offers senior executives, product strategists, and investors a compact but rigorous roadmap to navigate a market in steady expansion and structural change. Anchored on a 2025 base and projecting through 2032, the report translates quantitative trajectories into actionable choices for 2026 — the pivotal year when technology, regulation and supply-chain pressures converge to reshape supplier economics and OEM sourcing strategies.
Steering Auxiliary Lamp Market
Market Trajectory at a Glance
The steering auxiliary lamp market has grown materially over the past half-decade, expanding from under USD 900 million in 2020 to roughly USD 1.40 billion by the 2025 base year. Looking forward, our forecasts show continued expansion across the 2026–2032 horizon with a compound annual growth rate of 6.45%, reaching just over USD 2.16 billion by 2032. This steady growth is neither purely cyclical nor purely speculative; it is driven by a tight interplay of technology substitution, vehicle design trends, aftermarket demand and regulatory friction.
Steering Auxiliary Lamp Market
Why 2026 Matters: Confluence of Drivers
- Technology substitution and premiumization. The migration to higher-efficiency lighting architectures (notably advanced LED systems and emerging laser-based modules) is lifting average selling prices and changing BOM composition. Suppliers that can pair efficient emitters with intelligent beam control stand to capture disproportionate margin uplift.
- Systems integration and ADAS interaction. Steering-linked auxiliary lamps are moving from simple, mechanically-aimed fixtures to software-managed elements of the vehicle’s lighting and perception stack. Integration with steering-angle sensors and vehicle networks increases product complexity but also creates differentiation opportunities for Tier‑1s with systems capabilities.
- Regulatory constraints and compliance risk. Active standards and interpretations (for example, national rules on mounting and aiming, as well as safety mandates that prohibit auxiliary fittings from impairing required lighting equipment) are forcing engineering changes and compliance costs that will be felt most by smaller manufacturers and aftermarket brands.
- Input-cost concentration. Raw-material exposure — particularly to polycarbonate and related polymers used for lenses — accounts for a dominant share of production operating expenses. Suppliers must plan for volatility in polymer markets or face margin erosion.
- Aftermarket dynamics and off-road demand. While OEM programs remain the strategic prize, aftermarket channels and off-road applications continue to provide higher margin pockets and a testing ground for new beam patterns and high-lumen designs.
What the Report Provides: Practical, Deal‑Ready Intelligence
This study is deliberately practical. Beyond headline forecasts, PW Consulting delivers the kinds of deliverables that decision-makers use to set 2026 priorities, including:
Steering Auxiliary Lamp Market
- Rigorous market sizing and topline forecasts anchored to the 2025 base year and extending to 2032, with scenario variants for conservative, baseline and accelerated adoption paths.
- Segment-level demand drivers and adoption curves across type, application and region — modelled to support revenue and investment planning (note: detailed segment tables and regional splits are available in the full report and interactive data suite).
- Supply-chain cost models that quantify raw-material exposure and identify levers for cost-to-serve reduction, including lens material strategies and supplier consolidation pathways.
- Regulatory and standards matrix that maps compliance obligations to product development timelines and test-capability needs, with prioritized mitigation steps for markets where rules are tightly prescriptive.
- Competitive positioning dossiers and capability heatmaps for leading suppliers, plus an M&A and partnership tracker that identifies likely consolidation targets and areas ripe for joint development.
- Go‑to‑market playbooks for OEM, aftermarket and off-road channels — covering pricing architecture, warranty frameworks and data monetization opportunities tied to intelligent lighting systems.
Competitive Landscape: Strategic Implications for 2026
The market displays moderate concentration: the top three players account for a meaningful share and the top five capture a majority of the market’s value. This dynamic shapes both competitive behavior and supplier selection strategies across OEMs and large fleet operators. Key firm-level observations include:
- HELLA GmbH & Co. KGaA (Lippstadt). HELLA’s strength lies in its deep portfolio of automotive lighting and proven capability in dynamic steering-integrated lamps. Recent product introductions and catalog expansions underscore an aggressive product refresh strategy suited to OEMs demanding certified, system-level solutions. For 2026, HELLA is positioned to leverage scale and systems expertise to lead integration projects.
- OSRAM GmbH (Munich). OSRAM brings high-performance emitter technology and long-standing OEM relationships. Its dual focus on LED and halogen technologies gives it flexibility across program tiers, though margin expansion depends on migrating higher into intelligent, software-enabled lighting modules.
- Koninklijke Philips N.V. (Amsterdam). Philips’ catalog updates reflect continued investment in performance lighting for both OEM and aftermarket segments. Its brand strength in aftermarket performance lamps remains an asset, particularly where consumers prioritize retrofit solutions.
- Koito Manufacturing Co., Ltd. (Tokyo). As a major OEM supplier, Koito’s integration capabilities make it a natural partner for vehicle programs that require tight mechanical, optical and electronic co-design — an important advantage as steering-auxiliary functions become systemized.
- Valeo S.A. (Paris). Valeo’s work in adaptive and intelligent lighting positions it well to capture opportunities associated with ADAS and vehicle perception. Its systems-level view is a differentiator for programs that bundle lighting with sensing and control.
- Specialists and niche players (PIAA, KC HiLiTES, Rigid Industries). These firms command loyal aftermarket and off-road followings via high-performance lamps and ruggedized designs. They are likely acquisition targets or acquisition partners for Tier‑1s seeking quick entry into adjacent channels or premiumized product lines.
Recent Moves Signal Tactical Paths for 2026
- Product refreshes and catalog releases from established suppliers highlight a market in which product freshness and configurability matter for distributor and OEM purchasing cycles.
- Suppliers that combine optical performance with integration readiness — i.e., pre-validated sensor and control interfaces — will find reduced barriers to winning OEM platforms in 2026.
- Regulatory compliance programs and documentation are becoming buying criteria; suppliers that can demonstrate conformance and offer warranty-backed retrofit options will secure distributor shelf-space and fleet contracts.
Strategic Recommendations — A 2026 Playbook
Our research crystallizes a short list of practical moves that senior leaders should prioritize in 2026 to preserve margin and capture growth:
- Prioritize systems capability investments. Move beyond component supply into software-enabled modules that link to vehicle networks. Even incremental sensor fusion capabilities materially raise switching costs for OEMs.
- Secure lens and polymer supply through diversification or vertical integration. Given the outsized role of polycarbonate and related materials in manufacturing cost structures, lock-step procurement strategies and qualified secondary suppliers are essential hedges.
- Design for regulatory defensibility. Embed compliance margins and test-stand capabilities into the product development lifecycle to reduce last-minute redesign costs and accelerate time to production in regulated markets.
- Segment GTM by channel. Treat OEM, fleet and aftermarket as distinct businesses with tailored pricing and warranty structures; leverage aftermarket launches as pilots for higher-tier OEM features.
- Targeted M&A and partnerships. Acquire or partner with niche players to obtain ruggedized optics, high-lumen emitter IP or proven sensor interfaces rather than building all capabilities in-house.
- Scenario-based product roadmapping. Run two parallel tracks: a compliance-first track for regulated mass-market programs, and a premium innovation track for high-margin aftermarket and off-road segments.
Closing: The Strategic Value for 2026 Decision-Making
For companies charting strategy in 2026, the steering auxiliary lamp market presents a classic modern-industrial opportunity: steady, measurable growth underpinned by technology replacement and systems integration, paired with predictable regulatory and supply-chain risks. PW Consulting’s report turns these macro truths into micro decisions — from procurement levers to R&D prioritization and M&A scouting — that materially affect P&L outcomes across the forecast horizon.
We intentionally present high-level direction and decision-ready frameworks here while reserving complete segment tables, regional breakdowns and the interactive data dashboards for the full report. That detailed intelligence contains the granular inputs and scenario spreadsheets procurement teams and M&A desks require to move from strategy to execution.
Accessing the Full Intelligence
Executives and investors seeking the full dataset and bespoke advisory support — including interactive models, supplier scorecards and prioritized action plans tailored to specific corporate positions — can obtain the report and associated consulting services through PW Consulting’s market research portal.
For detailed analysis of this topic, please visit the official page: Steering Auxiliary Lamp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronic Bird Repellent and Control Devices Market Poised for 7.85% CAGR on Rising Agricultural and Aviation Demand
By PW Consulting, 2026-07-01
Electronic Bird Repellent And Control Devices Market: Strategic Insights for 2026 — PW Consulting
Executive snapshot
PW Consulting’s latest market study on Electronic Bird Repellent and Control Devices (base year 2025; forecast period 2026–2032) equips executives with the actionable intelligence needed to make confident decisions in 2026. The market, measured in USD Million, recorded notable expansion through 2020–2025 and stood at approximately USD 295.4 Million in 2025. Our forecast shows a sustained compound annual growth rate (CAGR) of 7.85% across 2026–2032, with the market trajectory pointing toward roughly half-a-billion dollars by the end of the forecast horizon. This growth is being driven by converging forces: technological innovation, changing biosecurity priorities in agriculture and aviation, rising commercial and municipal investments in humane wildlife control, and uneven regulatory landscapes that create both constraints and opportunities for differentiated solutions.
Electronic Bird Repellent And Control Devices Market
Why this report matters for 2026 decision cycles
-
Board-level planning: Our report translates market momentum into strategic options — buy, build, partner, or defer — with risk-adjusted scenarios calibrated to a 2026 planning window.
Electronic Bird Repellent And Control Devices Market -
Procurement and capex: We provide procurement-ready evaluation frameworks that quantify installation timelines, lifecycles, and payback ranges for key technology archetypes.
Electronic Bird Repellent And Control Devices Market -
R&D and product roadmaps: For technology owners and OEMs, the study highlights where investment in AI, sensors, and non-lethal deterrent mechanisms will most likely convert into commercial advantage.
-
M&A and corporate development: The competitive concentration metrics in the report show a market with clear leaders but meaningful opportunity for consolidation and bolt-on acquisitions in high-value niches.
What the report contains — practical, operational, and decision-focused
-
Robust market sizing and scenario modeling: We detail our methodology and assumptions used to derive the 2020–2025 history and 2026–2032 forecasts (USD Million basis), including sensitivity cases for accelerated AI adoption, regulatory tightening, and raw-material disruptions.
-
Segmentation intelligence without the noise: The market is segmented by product type (e.g., ultrasonic devices, laser systems, sound/acoustic repellers, electric track and visual deterrents), application (agriculture, aviation, commercial/industrial, residential), and region — each segment is analyzed for growth drivers, adoption barriers, and margin dynamics. Note: this release intentionally previews segment structures; granular figures and allocation tables are available in the full report.
-
Supplier heatmaps and capability matrices: We map vendors across technology readiness, service delivery, and geographic coverage to support shortlist creation for pilot and procurement rounds.
-
Operational playbooks: Includes deployment checklists, integration templates for combining electronic deterrents with physical barriers, and standardized testing protocols to measure efficacy across flight heights, species, and environmental conditions.
-
Commercial frameworks: Pricing benchmarks, channel economics, and tender templates tailored for airport authorities, agribusiness integrators, and municipal customers.
-
Regulatory and environmental compliance matrix: Jurisdiction-by-jurisdiction guidance highlighting where sonic/ultrasonic devices face legal limits or public pushback and how to design mitigation strategies accordingly.
-
Case studies and ROI calculators: Field-proven deployments with anonymized performance metrics, plus customizable ROI models to support business cases for pilots and rollouts.
Competitive landscape — who matters and why
The market displays a mix of long-standing manufacturers, specialist technology players, and newer entrants leveraging data and automation. Market concentration is meaningful but not prohibitive: the top three firms account for a significant share of revenue, while the top five widen that share materially, signaling room for mid-market vendors and innovators to gain traction in niche segments.
-
Bird-X, Inc. (Elmhurst, IL, USA) — A legacy player with a diversified portfolio spanning ultrasonic, sonic, and laser systems and deep distribution channels for both commercial and residential channels. Recent product introductions expanded their liquid deterrent and UV-marker offerings, and prior acquisitions have broadened their tech set. Bird‑X remains a model for scale-focused product diversification and route-to-market breadth.
-
Bird Control Group (Delft, Netherlands) — Known for AVIX automated and handheld laser systems, the company is a bellwether for laser deterrent adoption in agriculture and airports. Their patented approaches show how focused IP and performance claims can command specialized contracts, particularly where non-invasive methods are required.
-
Bird Gard LLC (Sisters, OR, USA) — A specialist in bioacoustic solutions. Their species-specific distress and predator-call systems illustrate demand for solutions tailored by ecology and crop type, underscoring the commercial value of behavioral science fused with electronics.
-
Bird Barrier America, Inc. (Carson, CA, USA) — Blends electronic deterrents with physical exclusion products; their integrated approach is increasingly attractive to customers seeking single-source providers capable of delivering both products and installation services.
-
Nixalite of America, Inc. (East Moline, IL, USA) — A manufacturing stalwart whose long-standing production base and emphasis on stainless steel and ruggedized components highlights the role of durable supply chains in preserving margins and field reliability.
-
iCHASE Co., Ltd. (Taipei, Taiwan / US presence) — A recent example of tech-led disruption: the company’s AI-powered deterrent with computer-vision tracking and adaptive strategies was introduced in late 2025 and signals a broader shift toward data-enabled deterrence, continuous monitoring, and closed-loop optimization.
Recent industry dynamics and implications
-
Innovation acceleration: The market is bifurcating between hardware-centric solutions and sensor/AI-driven systems that monetize data. The rollout of AI-enabled products that include tracking and adaptive behavior modification is a key inflection point for product roadmaps and service monetization.
-
Regulatory friction: Several jurisdictions are restricting sonic and ultrasonic devices on noise-pollution grounds. Where such restrictions exist, customers prefer laser, visual, or bioacoustic options — and suppliers must be prepared with compliance and community engagement strategies.
-
Supply chain realities: Electronic systems rely on specialized components (speakers, optics, stainless steel assemblies). Established manufacturers with local production capabilities or long-term supplier contracts are better positioned to manage lead times and quality control.
-
Consolidation signal: Given the reported concentration dynamics, M&A activity is likely to accelerate in adjacent niches — e.g., bioacoustics, AI analytics, or specialized laser systems — as larger firms seek to fill capability gaps quickly.
Strategic recommendations for 2026
For corporate leaders, public agencies, and investors, the following prioritized actions translate market understanding into concrete moves for 2026.
-
Immediate (0–6 months) — Launch targeted pilots with vendors that offer data capture and measurable efficacy; require vendors to provide anonymized performance baselines and standardized KPIs. If procurement spans urban/municipal settings, pre-screen suppliers for regulatory compliance and community-noise mitigation plans.
-
Near term (6–18 months) — Evaluate strategic partnerships or minority investments in AI-enabled specialists to secure access to telemetry and machine-learning models that improve deterrent performance over time. Standardize procurement templates and SLAs to include software updates, raw-data access, and translation of field metrics into ROI.
-
Medium term (12–24 months) — Build modular integration strategies that combine electronic deterrents with proven physical barriers. For multi-site operators (airports, large farms), prioritize vendors that can deliver managed services and remote monitoring to reduce on-site resource requirements.
-
Longer term (18–36 months) — Consider consolidation plays to internalize critical IP (bioacoustics, computer vision, laser optics) and to create compelling bundled offerings. Hedge regulatory risk by diversifying product portfolios across noise-neutral technologies.
How PW Consulting’s report supports these actions
The report is designed as an operational toolkit for decision-makers. It includes practical templates (tender language, test protocols, KPI dashboards), a prioritized shortlist of vendor archetypes, and scenario-based financial models to stress-test investment cases under different adoption and regulatory scenarios. For teams preparing 2026 budgets, the combination of a clear market growth rate (7.85% CAGR) and our practical deployment guidance reduces execution risk and shortens time-to-value for pilots and rollouts.
Next steps and access
This article previews the strategic depth inside PW Consulting’s full Electronic Bird Repellent and Control Devices Market report. If your 2026 planning requires detailed segment allocations, granular regional splits, vendor-level financials, or access to our supplier heatmaps and ROI calculators, please consult the full report. PW Consulting can also provide tailored briefings and a client workshop to translate these market insights into a bespoke action plan for your organization.
For detailed analysis of this topic, please visit the official page: Electronic Bird Repellent And Control Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Spiral Bevel Gear Boxes Market Set for 5.45% CAGR Through 2032
By PW Consulting, 2026-07-01
Spiral Bevel Gear Boxes Market — Strategic Briefing for 2026: PW Consulting’s Outlook and Executive Playbook
PW Consulting’s latest market research — the Spiral Bevel Gear Boxes Market Report (base year 2025; historical analysis 2020–2025; forecast 2026–2032) — is designed as an executive-grade decision support product for industrial equipment OEMs, component suppliers, investment teams, and strategic procurement leaders. The study synthesizes demand drivers, supply-side dynamics, competitive positioning, and forward-looking scenario planning to inform capital allocation and go-to-market choices as companies enter 2026.
Spiral Bevel Gear Boxes Market
Market at a glance
The global spiral bevel gear boxes market reached an estimated USD 1,955.4 Million in 2025. Our forecast sees continued expansion through the 2026–2032 horizon, reaching approximately USD 2,834.9 Million by 2032, representing a compound annual growth rate (CAGR) of 5.45% over the forecast period. These headline figures reflect a steady, structurally-driven demand mix — balancing replacement and aftermarket needs with new equipment deployment across transportation, industrial machinery, aerospace & defense, marine, and specialist motion-control segments.
Spiral Bevel Gear Boxes Market
Why 2026 matters: inflection points and strategic timing
-
Supply-chain normalization vs. cost volatility — Moving into 2026, manufacturers will confront a dual reality: improving lead-times for high-precision components while raw material price volatility (notably alloy steels and nickel/chromium inputs for stainless grades) continues to squeeze margins. Procurement strategies set now will materially shape cost curves through the next CAPEX cycle.
Spiral Bevel Gear Boxes Market -
Precision and miniaturization as differentiators — End markets demand higher efficiency and compactness (e.g., motion control and electric-drive systems). Firms that convert know-how in low-backlash, high-efficiency designs into producible product families will unlock premium positions in growth niches.
-
Standards and certification as market access gates — Conformance to standards (AGMA and ISO regimes such as ISO 23509 for bevel geometry) is increasingly table-stakes for supply to regulated verticals like aerospace and defense; certification roadmaps will be a gating factor for selective customer contracts in 2026.
-
Consolidation window — Market concentration metrics indicate a moderately fragmented ecosystem (CR3 ~31.8%; CR5 ~47.6%). That structure creates opportunities for strategic partnerships, bolt-on M&A, and carve-outs designed to rapidly enhance engineering capability or geographic reach.
What this report gives you — operational, boardroom and investment value
-
Actionable market-sizing and demand scenarios: granular annualized forecasts through 2032, plus upside/downside scenarios tied to raw material shocks, electrification pace, and defense procurement cycles.
-
Competitive playbooks: in-depth profiles and capability maps for the leading tier of suppliers, including manufacturing footprint, core technologies, product families, and go-to-market strengths and vulnerabilities.
-
Supply-chain and cost-pressure modelling: sensitivity analysis of typical bill-of-materials (with focus on commonly used alloys such as 8620 and case-hardening processes), freight and energy cost impacts, and recommended hedging and supplier diversification tactics.
-
Standards, testing and certification checklist: practical roadmaps for AGMA/ISO compliance and audit readiness tailored for manufacturers targeting high-spec verticals.
-
Commercial strategies and pricing templates: segmentation-based recommendations for value-capture (new unit sales vs. service & aftermarket), distributor mixes, and contract terms to protect margin in low volume/high complexity orders.
-
R&D and manufacturing roadmap: pragmatic investment priorities — tooling, heat-treatment, hard-finishing, and metrology — required to shift from small-batch custom work to scalable precision production.
Competitive landscape — who to watch and why
The report dissects capabilities and strategic orientation of incumbent and emerging suppliers. Rather than a superficial vendor list, our analysis maps engineering competence, manufacturing technologies, and commercial models to potential customer use-cases.
-
Amarillo Gear Company (Amarillo, Texas) — Strength: breadth of heavy-duty right-angle gear drives and experience with high-grade alloy steels for rugged, high-power applications. Strategic implication: partners exposed to irrigation, fans, and industrial power-transmission will find Amarillo’s engineering depth attractive for high-durability requirements.
-
TANDLER (Bremen, Germany) — Strength: high-precision, low-backlash spiral bevel gearboxes with multiple configurations (including stainless and hollow-shaft options), making it a go-to for servo and motion-control integrators. Strategic implication: superior for customers prioritizing positional accuracy and compact integration.
-
GAM Enterprises (Illinois, USA) — Strength: highly configurable miniature and compact designs (V-Series, VP-series), with high efficiency and motor-mount options. Strategic implication: ideal for OEMs chasing high torque density and flexible modularization.
-
KHK Gears (Japan) — Strength: global scale in standard and custom gear manufacturing, facilitating cost-effective sourcing for 90-degree shaft solutions. Strategic implication: price-competitive standardized components for volume-driven programmes.
-
Circle Gear & Machine Co. (Cicero, Illinois) — Strength: custom engineering, reverse-engineering services, and Gleason-system production for specialized applications. Strategic implication: rapid-response partner for obsolescence replacement and retrofit markets.
-
Bevel Gears (India) — Strength: long-established domestic production with a broad size range. Strategic implication: competitive option for cost-sensitive applications and regional sourcing strategies.
-
Superior Gearbox Company & Overton Chicago Gear (USA) — Strengths: OEM-focused designs emphasizing quiet operation, long life, and large-diameter high-precision parts. Strategic implication: suitability for marine, mining, and high-torque industrial systems that prize durability and certification readiness.
Recent industry movements — such as product launches and catalog/video rollouts — underscore how suppliers are investing in market education and feature differentiation. Examples include a multimedia product exposition of German precision ranges and the introduction of higher torque-density miniature products by a U.S. supplier — moves that accelerate customer evaluation cycles and shorten technical adoption timelines.
Risks, leading indicators, and watchlist for 2026
-
Raw-material price spikes and alloy availability — Watch lead indicators: futures curves for steel, nickel, and chromium; supplier capacity utilization; and inventory days at key heat-treatment vendors.
-
Standards evolution — Watch lead indicators: updates from AGMA/ISO committees, defense procurement technical bulletins, and major OEM specification revisions that could impose new qualification steps.
-
Concentration shifts — Watch lead indicators: announced M&A, capacity expansions by top-tier vendors, and strategic partnerships between gear manufacturers and motor/electronics suppliers that could reshape solution bundles.
-
Technology displacement — Watch lead indicators: adoption rates of alternative power transmission technologies (e.g., direct-drive systems) in targeted verticals, which would alter replacement cycles and aftermarket opportunities.
Practical strategic moves for 2026
-
Hedge and diversify raw-material supply now: lock strategic alloy contracts and develop secondary sources for key heat-treatment services to avoid single points of failure.
-
Product-platform vs. bespoke balance: implement modular design families that allow configuration for precision and heavy-duty variants without full retooling — enabling faster time-to-customer and healthier margins.
-
Push service-driven revenue: invest in condition-monitoring, predictive maintenance offerings and standardized exchange modules to capture aftermarket growth while differentiating on lifecycle cost.
-
Prioritize certification and test resources: for firms targeting aerospace/defense and marine, allocate engineering and quality budgets to expedite AGMA/ISO compliance and customer approvals.
-
Pursue targeted M&A and partnerships: consider bolt-on acquisitions that add precision grinding, hard-finishing, or reverse-engineering capabilities, or distribution partnerships in geographies where lead-times currently penalize sales.
How to use the full report
Think of this briefing as a strategic trailer — evidencing the depth and direction of the market while preserving the proprietary segment-level intelligence that drives competitive advantage. The full Spiral Bevel Gear Boxes Market Report contains the granular segmentation, supplier scorecards, customer buying-matrixes, pricing benchmarks, and plug-and-play financial models that enable tactical execution. Use it to:
-
Build one-page investor memoranda and capital-allocation recommendations grounded in scenario-tested forecasts;
-
Design procurement RFPs that reflect real lead-time and cost risks;
-
Map M&A targets and synergies using supplier capability overlays and margin decomposition;
-
Formulate product roadmaps and certification timelines that align with buyer procurement windows in 2026–2027.
Closing perspective
For decision-makers preparing plans for 2026, the spiral bevel gear boxes market represents a medium-growth, technically-intensive window of opportunity. The market’s projected expansion at a 5.45% CAGR through 2032 is driven by structural trends — electrification and precision motion control, defense-modernization programs, and refurbishment cycles across heavy industries. Success in the coming 12–24 months will be determined less by ambition than by execution: who secures resilient input flows, who converts engineering competence into producible platforms, and who captures the earliest aftermarket mindshare.
PW Consulting’s full report delivers the analytic depth and operational templates needed to convert those strategic imperatives into a 2026 action plan. Reach out to access the complete dataset, supplier scorecards, and executable playbooks.
For detailed analysis of this topic, please visit the official page: Spiral Bevel Gear Boxes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sulfuryl Fluoride Concentration Online Detector Market Poised to Reach USD 292.05 Million by 2032, Growing at an 8.45% CAGR
By PW Consulting, 2026-07-01
Sulfuryl Fluoride Concentration Online Detector Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting’s latest market research brief on the Sulfuryl Fluoride Concentration Online Detector market delivers the kind of actionable, board-level insight that executives, procurement leads, and regulatory affairs teams need as they set priorities for 2026. The sector is on a multi-year growth trajectory underpinned by regulatory tightening, expanded fumigation and post-treatment monitoring, and faster adoption of online continuous detectors. Our findings quantify that trajectory and translate it into decision-ready recommendations — while preserving proprietary segmentation intelligence that sits behind our full analysis.
Sulfuryl Fluoride Concentration Online Detector Market
Market snapshot: growth trajectory and concentration
The market for Sulfuryl Fluoride concentration detection is robust and accelerating. On a revenue basis, the market expands from a modest base in the early 2020s to reach USD 182.95 Million in 2026, and is projected to grow at a compound annual growth rate (CAGR) of 8.45% across the 2026–2032 forecast window. By 2032, our baseline scenario anticipates the market approaching roughly USD 292.05 Million. These dynamics reflect both rising demand for continuous online monitoring and an upgrade cycle driven by new device evaluation standards from major regulators.
Sulfuryl Fluoride Concentration Online Detector Market
Market concentration is meaningful but not prohibitive: the combined revenue share of the leading three firms sits below absolute dominance, while the top five suppliers command a clear majority of market revenue. This structure creates attractive opportunities for differentiated technology plays and regional specialists — especially those able to demonstrate verified performance at low parts-per-million thresholds and provide end-to-end compliance assurance.
Sulfuryl Fluoride Concentration Online Detector Market
Why this report matters for 2026 strategy
- Regulatory alignment drives procurement cycles: Recent updates from authorities including the U.S. EPA and the Australian Department of Agriculture have redefined clearance-device expectations and supplier lists. Buyers who can evidence device verification against these newer standards shorten procurement lead times and reduce compliance risk.
- Device validation is a strategic barrier: Performance at low-concentration thresholds (notably ~1 ppm clearance requirements) has become a decisive selection criterion. Organizations that invest early in verified hardware and documented field calibration processes will set the bar for incumbency.
- Market timing favors scale-ready innovators: With a mid-single-digit to high-single-digit CAGR and accelerating adoption among fumigation service providers and large industrial users, 2026 is a pivotal year for scaling pilots into recurring revenue models.
What’s inside the PW Consulting report (practical, operational deliverables)
- Executive dashboard: concise market metrics, scenario-based forecasts, and sensitivity analysis tailored for capital allocation conversations.
- Regulatory compliance matrix: mapping device performance requirements to jurisdictional rules and recent updates (including U.S. EPA guidance and Australian provider registration criteria).
- Technology comparator: side-by-side evaluation of sensor families, detection limits, drift characteristics, calibration windows, and lifetime cost of ownership.
- Vendor scorecards: disciplined, reproducible assessment across commercial readiness, verification evidence, service capability, and channel coverage.
- Field-validation playbook: practical protocols for on-site benchmarking, sample planning, and third-party verification to produce audit-ready acceptance artifacts.
- Procurement and implementation roadmap: procurement templates, performance SLAs, installation checklists for continuous online systems, and staff competency requirements.
- Commercial models and ROI tools: use-case-specific TCO calculators that incorporate equipment, calibration, service, and compliance risk reduction benefits.
Competitive landscape: what to watch in 2026
The market combines specialist instrument manufacturers with broader gas-detection firms. Key industry participants profiled in our report include established niche vendors and multinational suppliers who provide devices and services spanning portable, online, and fixed monitoring use cases. Representative companies include vendors that offer portable IR monitors, multi-zone continuous fumigation monitors, NDIR sensor modules engineered for Sulfuryl Fluoride (SO2F2) detection, and clearance-specific instrumentation designed to meet low-ppm verification requirements.
From a strategic perspective, three themes stand out:
- Product-to-service evolution: Several vendors are moving beyond point sales to offer calibrated monitoring-as-a-service, which reduces buyer friction and supports recurring revenue models.
- Verification as differentiation: Public recognition on regulator device lists and independent device evaluations are becoming table stakes. Firms with documented performance at sub-ppm levels and participation in formal device testing enjoy faster adoption in regulated markets.
- Channel and aftercare matter: The real-world performance of detectors depends on calibration cadence, certified service partners, and availability of certified consumables. Market leaders are investing in training networks and local calibration labs to maintain retention.
Regulatory and standards dynamics shaping vendor selection
Three recent regulatory developments alter the procurement calculus for 2026:
- U.S. EPA updates emphasize the need for clearance to 1 ppm or below with devices verified for accuracy at low concentrations; device evaluation listings now guide buyer decisions.
- Australian biosecurity rules require detection devices to read to 3 ppm in 1 ppm increments, and updated provider registration criteria emphasize current calibration certificates for service providers.
- State-level initiatives (e.g., multi-phase post-fumigation exposure studies) are increasing demand for validated long-duration monitoring in complex environments.
These policy moves create near-term demand for devices that can demonstrate trace-level repeatability and robust field calibration workflows — a point the report quantifies and operationalizes for procurement and R&D planning.
Technology and operational considerations for buyers
- Detection limits and accuracy: Selection should prioritize verified low-concentration performance with independent third-party validation where available.
- Continuous monitoring vs. spot checks: Online detectors reduce human error and produce richer datasets for compliance proofs, but they require disciplined calibration, remote monitoring infrastructure, and field-hardened sensor modules.
- Integration and data hygiene: SaaS-enabled platforms that integrate detector telemetry with compliance workflows and audit trails materially reduce administrative overhead in regulated programs.
- Supply chain resilience: Certified consumables, regional calibration services, and multi-vendor sourcing strategies mitigate uptime and regulatory exposure risks.
Strategic recommendations for 2026
- Embed regulatory verification into vendor selection: require evidence of participation in authoritative device evaluations and certification of calibration protocols as pre-qualification items.
- Favor pilots that validate both technology and operational practices: structure pilots with clear acceptance criteria tied to regulatory thresholds and defined performance observation windows.
- Invest in service partnerships early: build or contract for local calibration capacity and training to secure adoption in regions with strict biosecurity or occupational exposure regulation.
- Use procurement to shape product roadmaps: buyers with repeatable demand should consider joint development or controlled pilots to influence sensor features relevant to their environments.
- Plan for data governance: ensure that detector telemetry integrates with compliance recordkeeping and can produce audit-ready export formats.
How PW Consulting supports your decision cycle
Our full Sulfuryl Fluoride Concentration Online Detector Market report delivers the datasets, model assumptions, and vendor dossiers needed to move from insight to implementation. It includes reproducible financial models, a validated market-size time series, and a segmentation framework that explains where growth will be realized and why — without giving away the proprietary split-level intelligence that subscribers must access via the full report.
For organizations evaluating suppliers, designing compliant monitoring programs, or sizing R&D investments in detector technology, this research supplies a compact, operationally focused evidence base that accelerates decision velocity in 2026. To review the complete segmentation, vendor scorecards, country-level regulatory mappings, and downloadable TCO tools, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Sulfuryl Fluoride Concentration Online Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fan Convectors Market Forecast to Reach USD 2,046.19 Million by 2032 at a 5.85% CAGR, Led by North America and Asia Pacific
By PW Consulting, 2026-07-01
Fan Convectors Market 2026 Strategic Outlook — Actionable Intelligence for Executive Decision-Making
Executive teaser
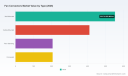
The global fan convectors market has moved from a niche HVAC subsegment into a strategic lever for firms positioning around building decarbonization, electrification, and space-efficient retrofit programs. Our PW Consulting market model shows the sector reaching an estimated USD 1,376.5 Million in 2025 and, under the baseline scenario, expanding at a compound annual growth rate of 5.85% through the 2026–2032 forecast window — a trajectory that takes the market into the range of roughly USD 2.05 Billion by 2032. For corporate leaders making 2026 capital, product and M&A choices, this report converts these top-line dynamics into prescriptive actions, risk-adjusted scenarios and go-to-market playbooks designed for near-term impact.
Fan Convectors Market
Why this report matters for 2026 decisions
-
Precision for capital allocation — Understand demand elasticity and timing across retrofit cycles so equipment and factory investments are sequenced to market windows, not legacy build plans.
Fan Convectors Market -
Product roadmap alignment — Convert regulatory trajectories (energy efficiency, low-temperature compatibility) into prioritized R&D features — low activation temperatures, ultra‑slim footprints, acoustic performance and smart controls.
Fan Convectors Market -
M&A and partnership screening — Identify the archetypal targets (technology specialists, regional installers, channel consolidators) and quantify the value levers that justify strategic deals.
-
Commercial strategy calibration — Build channel incentives and specification campaigns that accelerate adoption among heat pump installers, property managers and retrofit contractors.
-
Operational risk management — Stress-tested scenarios and sensitivity tables reveal how supply‑chain shocks, commodity swings and policy shifts affect margin and lead times.
What the PW Consulting report delivers (practical, executable content)
The study is intentionally hands-on. Beyond a validated market-sizing and CAGR projection, the report delivers:
-
Scenario-driven forecasts (baseline, accelerated electrification, and downside construction slowdown) with embedded decision triggers for CapEx and inventory policy.
-
Competitive vendor scorecards and playbooks that map product feature gaps to acquisition, licensing or co-development options — enabling an immediate tactical response without waiting for organic R&D timelines.
-
Go-to-market modules tailored to three strategic plays: retrofit acceleration, spec-driven new-build adoption, and product-servitization (subscription maintenance and performance guarantees).
-
Supply-chain mapping and a five-point mitigation plan for motor, electronics and sheet-metal sourcing that can be implemented within 90–180 days.
-
Customer economics and payback calculators for residential and commercial retrofit scenarios, enabling sales teams to present localized ROI cases that shorten sales cycles.
-
Regulatory and policy tracker outlining near‑term measures that materially affect design requirements and market access across major jurisdictions.
Competitive landscape — core players and strategic implications
The market is moderately concentrated: the top three vendors account for a meaningful share of industry volumes while the top five widen that share further — a structure that supports both strategic cooperation and bolt‑on consolidation. Against this backdrop, incumbent product and channel strengths differ markedly, creating clear white spaces for challengers and partners.
-
Smith's Environmental Products (USA) — Known for the Profile series and Caspian line, Smith’s strengths lie in a broad BTU range and a reputation for quiet, low-temperature operation. For buyers, Smith’s profile points to an attractive play: integrate high-performance residential models into bundled retrofit offerings where acoustic performance is a buying criterion.
-
Myson (UK) — Myson’s recent product updates (December 2025 announcement and January 2026 product revisions) center on compatibility with low-temperature heating systems; their models now activate at system temperatures in the low 30°C range. This technical repositioning reduces friction with heat pump adoption and signals an industry inflection point: suppliers that solve for low-water-temperature activation will capture disproportionate retrofit volume in heat‑pump‑led markets.
-
SPC HVAC (UK) — SPC’s portfolio, including the Tilevector series, highlights a commercial/RMI focus on ceiling-integrated solutions and minimal depth units that simplify retrofit installation in occupied spaces. Strategic implication: vendors that can deliver ceiling-tile form factors with plug-and-play controls can command premium channel positioning in spec-driven projects.
-
Jaga (Belgium) — Jaga’s Briza slimline units illustrate an ongoing miniaturization trend. Their high performance at low water temperatures and slim footprints make them natural candidates for partnerships with urban retrofit installers where floor/ceiling space is constrained.
-
Dunham‑Bush — With a commercial focus and a legacy in fan coils and larger systems, Dunham‑Bush demonstrates the scale play. For companies weighing scale vs. specialization, Dunham‑Bush’s model illustrates how breadth of portfolio supports large project pipelines but may lag on rapid low-temp innovation.
-
Frico (Sweden) — Frico’s PF Smart and similar lines emphasize rapid heat delivery and electric/hydronic versatility, pointing to opportunities where speed of thermal response is a critical specification (e.g., healthcare, schools).
Product and channel trends shaping 2026 adoption
-
Low-temperature compatibility is now a design imperative. With heat pump rollouts accelerating, devices that reliably operate at activation temperatures in the low 30s Celsius will be table stakes for retrofit specs.
-
Miniaturization and installation ergonomics (slim depths, ceiling‑tile modules) lower retrofit cost and occupant disruption, opening larger addressable markets within existing building stocks.
-
Acoustic performance and integrated controls are differentiators in both residential and commercial segments; pairing convectors with predictive controls and commissioning services drives higher lifetime margins.
-
Service-led models (performance contracts, remote monitoring) are becoming viable revenue streams as IoT sensors and analytics reduce lifecycle cost uncertainty for building owners.
Risk outlook — what can derail a 2026 plan
Key downside paths we model include slower-than-expected heat pump adoption, prolonged commodity inflation impacting BOM costs, and trade or logistics disruptions that extend lead times. Regulatory shifts (e.g., tightening energy efficiency thresholds) can either accelerate demand for compliant units or raise engineering costs if introduced with short lead times. The report contains quantified risk matrices and contingency playbooks that translate these scenarios into operational checklists for procurement, R&D and sales.
Recommended 2026 playbook for executives (practical steps)
-
Fast-follower product investments: Allocate a defined R&D tranche to low-temperature activation strategies, acoustic improvements and slimline form factors. Aim for modular platforms that can be field-upgraded via firmware and fan/control swaps.
-
Channel focus: Reorient sales incentives toward heat‑pump installers, retrofit contractors and large property management groups. Create ROI-based sales kits that quantify payback at the building level.
-
M&A and partnerships: Prioritize regional installers or niche OEMs with complementary features (ceiling-tile modules, integrated controls) as bolt‑on acquisitions to accelerate market entry.
-
Service monetization: Pilot performance‑based maintenance contracts in 2–3 key cities to develop repeatable service economics and capture recurring revenue.
-
Supply-chain resilience: Secure long-lead components through multi-sourcing agreements and strategic buffer inventory for motors and controllers to avoid blue-sky delays in retrofit seasons.
-
Regulatory engagement: Invest in regulatory horizon-scanning and participate in standards working groups to influence low-temperature and energy-efficiency requirements in core markets.
Call to action — where to find the full intelligence
This press release is a strategic summary designed to surface the market’s key directional signals and the immediate choices facing leadership teams in 2026. The full PW Consulting Fan Convectors Market Report (base year 2025; historical 2020–2025; forecast 2026–2032) contains the proprietary segment-level forecasts, regional and application breakouts, vendor scorecards with feature-by-feature comparisons, downloadable forecast tables in USD Million, and executable playbooks with implementation timelines. For clients and partners seeking the complete dataset, scenario workbooks and vendor negotiation templates, visit the PW Consulting report page to access the comprehensive package.
Contact PW Consulting to schedule a briefing demo; our analysts will walk your leadership team through the report’s models and tailor the playbook to your strategic priorities for 2026.
For detailed analysis of this topic, please visit the official page: Fan Convectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial & Industrial RO Market to Rise from USD 4,525.3 Million in 2025 to USD 7,682.75 Million by 2032 at a 7.85% CAGR (2026–2032) — Asia Pacific, Brackish RO Systems and Food & Beverage Lead Growth
By PW Consulting, 2026-07-01
Commercial and Industrial RO Water Treatment Equipment Market: Strategic Insights for 2026 Decision‑Makers
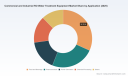
PW Consulting’s latest market research on the Commercial and Industrial Reverse Osmosis (RO) Water Treatment Equipment market provides an actionable intelligence package tailored for executives, procurement heads, plant managers, and investment committees preparing decisions in 2026. Anchored to a 2025 base year with a historical window covering 2020–2025 and projections through 2032, the study models a market expanding at a compound annual growth rate (CAGR) of 7.85%. The total market, which stood at USD 4,525.3 Million in 2025, is forecast to climb above USD 5,124.6 Million in 2026 and approach USD 7,682.8 Million by 2032—figures that reflect accelerating demand driven by regulatory pressure, industrial modernization, and the economics of water reuse.
Commercial And Industrial Ro Water Treatment Equipment Market
Why this report matters for 2026 strategic planning
2026 is a tipping point year for industrial water investments. Stricter discharge limits and rising expectations for process-water quality across power generation, pharmaceuticals, food processing, and oil & gas are moving RO systems from utility to strategic infrastructure. At the same time, energy and lifecycle costs are re-shaping procurement criteria: energy can account for 35–45% of seawater RO operating costs, and treated-water unit costs can vary meaningfully with plant design and operational discipline. For leaders, that combination elevates questions of vendor selection, system configuration (modular vs bespoke), and long-term service models—each of which can materially affect both near-term capital efficiency and multi-year operational expenditure.
Commercial And Industrial Ro Water Treatment Equipment Market
Market dynamics that should shape 2026 decisions
-
Regulatory tightening: New and more prescriptive effluent and reuse standards are accelerating replacement cycles and upgrades, particularly for processes with strict feedwater quality needs. Buyers should budget not only for capacity but for compliance-driven performance guarantees.
Commercial And Industrial Ro Water Treatment Equipment Market -
Energy and operating cost pressure: With a significant share of operating cost driven by energy, decisions that minimize footprint and optimize energy recovery (high-recovery RO, energy recovery devices, hybrid architectures) materially improve total cost of ownership (TCO).
-
Capital cost dispersion: Systems range from compact commercial units to mega-scale skid or plant solutions. CAPEX variance creates opportunity for staged investments—pilots and modular expansions that align cash flow to validated demand.
-
Service and model innovation: The rise of rental, outcomes-based contracting, and remote operations is changing risk allocation. Buyers need to compare not only equipment specifications but data contracts, membrane management approaches, and escalation SLAs.
-
Moderate market concentration: The market sits between fragmentation and consolidation—top three suppliers capture roughly one third of value, and top five approach half of market sales—creating a competitive space where niche specialists and global platform players co-exist.
Technology and procurement trends to watch
-
High-recovery and advanced membrane chemistries are shifting the economic calculus for brackish and recycling applications, particularly where wastewater reuse reduces intake costs.
-
Modular, skid-mounted systems and standardised series lines lower implementation cycle times and ease scaling—useful for companies that prefer predictable deployment windows over fully custom builds.
-
Digital enablement—remote monitoring, membrane analytics, and predictive maintenance—are becoming table stakes. Suppliers who bundle hardware with actionable operational data can command premium service terms and lower buyer risk.
-
Service models: Rental, managed services, and membrane-as-a-service options are growing, enabling firms to shift capital into operations and to buy performance rather than parts.
Competitive landscape — what the vendors are emphasizing
Our competitive analysis profiles the market’s spectrum of suppliers from bespoke fabricators to global platform providers. Key incumbent and challenger approaches include:
-
Custom skid and high‑capacity specialists: Firms that focus on custom skid-mounted systems and high‑purity series configurations bring deep engineering for complex industrial feeds, high-recovery packages, and integration into existing plant utilities.
-
Pre‑engineered modular players: Providers offering pre‑engineered series and modular formats target repeatable applications where fast time to operation and standardized maintenance reduce procurement friction.
-
Desalination and seawater expertise: Vendors with seawater desalination capability combine membrane technology with energy recovery choreography—critical where raw water salinity and energy sourcing are key drivers.
-
Service- and data-centric firms: Companies bundling rental options, membrane lifecycle management, and analytics position themselves as long-term partners rather than one-off suppliers.
Notable company archetypes reflected in the report include: modular skid manufacturers with high‑purity series for boiler feed and process water; global suppliers offering both brackish and seawater systems across thousands-to-millions-of-GPD capacity ranges; and integrators specialising in harsh environments and sector-specific compliance. Recent market activity—such as the launch of expanded modular commercial RO portfolios by a major water-technology firm in late 2025 and early 2026—illustrates the accelerating focus on scalable, higher-flow commercial offerings to capture larger commercial/industrial accounts.
What PW Consulting’s report delivers (practical, actionable content)
This research goes beyond high-level forecasts to equip decision-makers with executable analyses and tools:
-
Decision frameworks and procurement playbooks: Scored vendor selection matrices, shortlisting criteria, and an RFP template that aligns technical KPIs with commercial levers.
-
TCO and scenario models: Interactive-level guidance on CAPEX vs OPEX trade-offs, energy sensitivity runs, and break-even horizons for retrofit vs new-build pathways.
-
Vendor profiles and competitive benchmarking: Strategic positioning maps, capability heatmaps, and service-model comparisons to inform partner selection.
-
Operational playbooks: Commissioning checklists, membrane-replacement planning, and remote-monitoring KPIs designed to shorten ramp-up and constrain unplanned downtime.
-
Regulatory and risk matrix: Mapping of likely regulatory trajectories, permitting pinch points, and compliance costs that can be used in capex approval processes.
-
Case studies and deployment templates: Short-cycle pilots, phased scaling, and procurement timelines that companies can adapt to accelerate rollouts while preserving optionality.
How to use these insights in 2026 — prioritized actions for executives
-
Immediate (0–12 months): Run targeted pilots with modular systems that include clear performance SLAs and energy baselines. Use our TCO templates to stress-test supplier proposals under multiple energy-price scenarios.
-
Near term (12–36 months): Move from CAPEX-only evaluation to hybrid commercial constructs—rental, managed services, and performance contracts—to improve cash flow and transfer operational risk.
-
Strategic (3–7 years): Build water circularity and decarbonization into capital planning; prioritize suppliers with strong digital stacks and membrane-life optimization that materially reduce lifecycle energy and replacement costs.
-
Procurement and partnership play: Balance incumbent OEMs and specialised integrators—top-tier providers capture a meaningful share of the market but niche specialists can deliver sector-specific advantages and faster customization.
Closing — the strategic value of the report
For organizations evaluating RO investments in 2026, this PW Consulting report offers an evidence-based pathway from market intelligence to procurement action. The combined visibility of macro growth (CAGR 7.85%), near-term market expansion, supplier positioning, and operational levers enables teams to make defensible, financially robust choices that anticipate regulation, energy volatility, and service‑model innovation. While this summary outlines the strategic contours, the full report contains the granular regional and application splits, detailed vendor scorecards, and downloadable TCO modeling tools required to finalize capital approvals and supplier contracts.
To access the complete market dataset, vendor benchmarks, and decision-support tools, please visit our report page or contact PW Consulting’s Industrial Water practice. The 2026 planning window rewards speed and precision—this report is designed to give your team both.
For detailed analysis of this topic, please visit the official page: Commercial And Industrial Ro Water Treatment Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Quick Gear Clamps Market to Expand at a 5.85% CAGR Through 2032
By PW Consulting, 2026-07-01
Quick Gear Clamps Market — Strategic Insights for 2026 Decision Makers
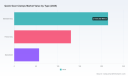
As manufacturers, distributors and investors prepare budgets and roadmaps for 2026, the global Quick Gear Clamps market is moving from steady niche growth toward a phase in which tactical choices this year will determine competitive position through the end of the decade. PW Consulting’s new Quick Gear Clamps Market report synthesizes an updated macro model, granular supplier intelligence, and action-oriented playbooks designed to support the critical decisions you will make in 2026. The market reached approximately USD 401.5 Million in our 2025 base year and is projected to continue expanding at a compound annual growth rate of 5.85% across the 2026–2032 forecast window — reaching roughly USD 598.3 Million by 2032. Our 2026 near-term estimate of about USD 433.4 Million is particularly useful for 2026 planning cycles, procurement commitments, and product launch timing.
Quick Gear Clamps Market
Why 2026 Is a Strategic Inflection Point
- Confluence of product innovation and distribution shifts: New rapid-action and ergonomic designs that debuted in late 2024–2025 are being commercialized, changing buyer expectations at the contractor and OEM levels.
- Material and standards pressure: Stainless-steel supply dynamics and tightening expectations for compliance with established performance standards are increasing the complexity of supplier selection and cost control.
- Moderate market concentration: With the top three and top five firms representing meaningful but not dominant shares of the market, 2026 is a window for both niche players and consolidators to expand footprint through differentiated offerings or bolt-on acquisitions.
- Inventory and lead-time sensitivity: Small changes in lead times or raw-material costs can materially affect margins in 2026 procurement cycles, requiring more precise forecasting and supplier contracts.
What PW Consulting’s Report Delivers — Practical Value for 2026
This report is structured for immediate operational use by procurement, strategy, product management, and corporate development teams. Core deliverables include:
Quick Gear Clamps Market
- Proven market-sizing and forecasting models (2020–2025 historical base; 2026–2032 forward), including sensitivity scenarios tuned to raw-material price swings and demand shocks.
- Actionable demand-driver analysis across product types, channels and end-users, paired with practical recommendations for assortment and stocking strategy.
- Supplier scorecards and a capability matrix that map manufacturing competence, quality certifications, and scalability — designed to be integrated into RFPs and supplier scorecards.
- Price and margin benchmarking, including cost-to-serve breakdowns by sales channel and product variant to support margin-improvement programs and negotiation plans.
- Competitive intelligence dossiers on leading firms, innovation signals, and playbooks for both incumbents and entrants.
- M&A and partnership screeners identifying targets and criteria for roll-up strategies, joint-venture opportunities, and strategic distribution alliances.
- Regulatory and materials impact briefings (e.g., implications of SAE J1508 performance expectations in industrial hose and worm drive clamp applications and the predominance of stainless-steel variants for corrosion resistance).
To preserve the value of our primary research while demonstrating expertise, the report refrains from publishing certain granular splits in this announcement — such as detailed regional and application percentage breakdowns, and company-level revenue allocations — which are available in the full report and accompanying datasets.
Quick Gear Clamps Market
Competitive Landscape — What 2026 Means for Players
The Quick Gear Clamps competitive environment combines global industrial suppliers, specialty woodworking brands, and long-established OEM manufacturers. Key firms we profile include Grizzly Industrial, Ideal Tridon, Dixon Valve, Murray Corporation, Bessey Tools, and Kreg Tool. Each has different strengths and routes to growth.
- Grizzly Industrial: Recently expanded its woodworking-focused Quick Gear Clamp line with a suite of rapid-action levers and varying throat depths. This move accelerates competition in wood-assembly channels and emphasizes ergonomics and rapid setup — features that will influence specification decisions for mid-market buyers in 2026.
- Ideal Tridon: Offers Snaplock® quick-release and worm drive systems across industrial and hose applications. Their industrial reach and product breadth position them well where integration into OEM assemblies and distributed maintenance programs matters.
- Dixon Valve: Focused on stainless-steel worm gear and quick-release clamps for hose and industrial segments. Their materials and corrosion-resistant portfolio make them a natural supplier where standards-driven purchasing and performance warranties matter.
- Murray Corporation: A traditional supplier with deep OEM relationships; its strength is in custom and embossed clamp tooling for scale production runs, a potential acquisition target for distributors seeking manufacturing control.
- Bessey Tools & Kreg Tool: Represent the specialized woodworking and metalworking bar clamp innovations, where internal-gear mechanisms and fast-action paradigms are differentiators for professional users.
From a strategic standpoint, these firms display a mix of product-focus and channel dominance. Our report maps which plays are likely to win in the next 24 months — whether that’s ergonomics-led woodworking gains, material-led industrial wins, or cost-led distribution consolidation.
Regulation, Materials and Supply-Chain Signals
- Standards compliance: Expect procurement teams to increasingly require documented compliance with SAE performance expectations in industrial hose and worm-drive applications. Certification and independent test data will be a competitive advantage in 2026 RFPs.
- Primary materials: Stainless-steel (201/301/304 series) continues to be the dominant material for corrosion resistance in marine and automotive environments. Price volatility and supplier concentration for these alloys have direct margin implications.
- Supplier risk: Single-source arrangements for specialty finishing or tooling represent a material operational risk for high-volume OEM contracts; mitigation through dual sourcing or captive tooling options is highlighted in our tactical playbooks.
Risk Matrix and Mitigation Tactics for 2026
- Raw-material price shock: Adopt staggered purchase windows, hedged contracts, and indexed pricing clauses to reduce exposure. Consider qualification of material substitutes where performance allows.
- Standards / warranty claims: Invest in independent performance testing and warranties aligned to buyer expectations to reduce return rates and downstream service costs.
- Channel disruption: Strengthen distributor partnerships with shared inventory forecasts and vendor-managed inventory pilots to keep fill rates high without inflating working capital.
- Competitive erosion: Protect margins through value-add services (assembly, pre-configuration, rapid-delivery kits) and SKU rationalization driven by our elasticity analysis.
How to Use This Report in Your 2026 Decision Cycle
- Quarter 1 — Strategy alignment: Use the report’s baseline forecast and scenario outputs to set topline and procurement budgets for 2026. Our 2026 estimate is calibrated to near-term demand signals and will help align inventory targets.
- Quarter 2 — Supplier commitments: Implement supplier scorecards and negotiate contracts with clauses that reflect volatility scenarios provided in the report. Prioritize dual-sourced lines for critical stainless-steel components.
- Quarter 3 — Product and channel execution: Launch ergonomic and corrosion-resistant SKUs timed to contractor and OEM procurement cycles; pilot distribution bundles and pre-configured kits for fast-moving segments.
- Quarter 4 — M&A and expansion: Review our M&A thesis and target list for tuck-ins or distribution partnerships that can be executed with 12–18 month integration plans to capture scale economies before 2028 demand acceleration.
Conclusion — A Practical Roadmap for 2026
For executives whose 2026 choices will define performance through the remainder of this decade, the PW Consulting Quick Gear Clamps Market report provides a structured set of tools: a defensible macro forecast, supplier and product scorecards, scenario playbooks, and tactical recommendations keyed to procurement timing, product development windows, and M&A opportunities. The market is forecast to grow at a steady mid-single-digit CAGR across 2026–2032, and our analysis shows clear levers for margin improvement and share capture if actions are taken with precision in 2026.
To review the full suite of proprietary datasets — including regional and application-level splits, company-by-company revenue estimates, price curves, and downloadable financial models — visit the PW Consulting Quick Gear Clamps Market report page or contact our advisory team to schedule a briefing. The right combination of supplier strategy, product timing, and disciplined execution in 2026 will materially change market position by 2028; this report is designed to be the operational playbook you deploy today.
For detailed analysis of this topic, please visit the official page: Quick Gear Clamps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PTFE‑Lined Dip Pipes Market to Rise from USD 199.1 Million in 2025 to USD 283.91 Million by 2032 at a 5.2% CAGR
By PW Consulting, 2026-07-01
PTFE Lined Dip Pipes Market — Strategic Intelligence to Inform 2026 Decisions
PW Consulting’s latest market study on PTFE lined dip pipes offers senior executives, procurement leaders, and product strategists a compact, action-oriented intelligence pack tailored for decisions in 2026. Built from an audited historical dataset (2020–2025), a seven-year forecast (2026–2032) and primary interviews across manufacturers, OEMs and end users, the report translates technical product attributes into commercial levers that materially affect margin, risk and growth options.
Ptfe Lined Dip Pipes Market
Market trajectory at a glance
The PTFE lined dip pipe market has demonstrated steady expansion over the past half decade, rising from approximately USD 149 million in 2020 to roughly USD 199 million in 2025. Our forecast models project a compound annual growth rate (CAGR) of 5.2% across 2026–2032, with total market value approaching the high two-hundreds (USD ~284 million) by 2032 under base-case assumptions. These results reflect a convergence of regulatory-driven demand for corrosion-proof containment, incremental adoption in high-purity sectors, and improving manufacturing reliability for larger-bore lined assemblies.
Ptfe Lined Dip Pipes Market
Why this matters for 2026 planning
- Investment timing: The 5.2% CAGR signals a maturing but still expanding market — a profile that favors targeted capacity adjustments and selective capital allocation over broad-scale greenfield expansions.
- Margin sensitivity: Raw material drivers and product complexity make cost structures volatile; procurement and pricing policies enacted in 2026 will determine realized margins for the next 24–36 months.
- Regulatory tailwinds: New and tightened environmental and process-safety regulations are reshaping specification mandates across chemical processing and water treatment—creating windows for premium, compliance-focused offerings.
What the PW Consulting report delivers (practical contents)
The report is designed to be directly operational. We translate market intelligence into tools you can use during vendor selection, product development and M&A screening without wading through raw tables:
Ptfe Lined Dip Pipes Market
- Market sizing and revenue forecasts (2020–2032) by product family and end-use category — modeled with scenario levers for raw material shocks and regulatory shifts.
- Supplier benchmarking and scorecards covering technical capability, production scale, geographic reach and aftermarket services.
- Cost architecture and sensitivity analysis — notably the impact of PTFE resin price volatility on manufacturing margins and price corridors.
- Go-to-market playbooks for OEMs, distributors and fabricators, including channel economics and tender-readiness checklists.
- Commercial models and pricing guidance — from meter-rate frameworks to premiuming strategies for high-purity and engineered configurations.
- M&A and partnership screening matrix with prioritized targets and integration risk profiles.
- Regulatory compliance roadmaps and an implementation checklist to align product specs with updated environmental and process safety standards.
Competitive landscape — who to watch and why
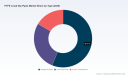
The PTFE lined dip pipe supplier base features a mix of specialized niche manufacturers and regionally focused fabricators. Market concentration is moderate: the top three firms account for just under 39% of market revenues, and the top five for about 51% — a structure that permits meaningful competitive moves by mid-sized players while still rewarding best-in-class scale and distribution.
- Corrosion Resistant Products (CRP) — Specialist in continuously lined designs with engineering depth in agitated services and pressure/stress calculations. CRP’s value proposition is engineering assurance for larger bore lined assemblies and higher-stress reactor applications.
- Micromold Products, Inc. — Known for FLUOR-O-FLO® PTFE lined and jacketed solutions; strength lies in standard platforms that simplify procurement for large-nozzle applications and in responsiveness on custom corrosion-resistant designs.
- Andronaco Industries (Ethylene) — Offers ChemTite® Ethylarmor® solutions tailored to aggressive injection and agitation environments; their product focus targets customers who prioritize extended service life under mechanical stress.
- Edlon (GMM Pfaudler) — Combines PTFE lining with deep experience supporting glass-lined vessels and semiconductor tank applications, positioning themselves strongly in high-purity markets.
- Regional fabricators (India and others) — A cluster of manufacturers from India and other regions provides competitive pricing and fast turnarounds. These suppliers are increasingly important for lower-cost repeat business and for customers pursuing cost-down strategies.
Our vendor scorecards highlight each supplier’s technical strengths, channel reach, lead-time performance and aftermarket capabilities — essential inputs when evaluating strategic partnerships, insource vs. outsource decisions, or bolt-on acquisitions. (Note: detailed vendor revenue splits and line-item scores are reserved for subscribers to the full report.)
Supply chain dynamics and raw-material risk
Two structural supply-side issues should drive immediate action planning in 2026:
- PTFE resin price volatility — PTFE raw material pricing has a disproportionate effect on product economics. Our analysis shows resin costs can represent a material portion of unit manufacturing cost for both solid and lined products; this translates directly into margin variability. We provide hedging alternatives, dual-sourcing frameworks and contract language that can limit exposure.
- Unit price dispersion — Lined PTFE dip pipes show significant unit-price variance depending on specifications and service conditions. Our market intelligence indicates common list ranges for lined products that procurement teams should use as reference points when negotiating long-term agreements.
Operationally, we recommend that manufacturers and buyers implement a three-step supply-risk program in 2026: (1) traceable resin sourcing and buffer inventory for critical grades, (2) cost-to-serve analysis by product family to defend premium positioning, and (3) dynamic price escalation clauses aligned to resin indices.
Regulatory and end-market forces shaping demand
Regulatory pressure — including updates to water quality and hazardous fluid containment standards — is a primary demand accelerator. Chemical processors and municipal utilities are increasingly specifying corrosion-proof, lined systems as part of capital projects and replacements. Meanwhile, high-purity applications (e.g., pharmaceutical, semiconductor wet-process tanks) continue to push demand for engineered PTFE solutions with stringent cleanliness and traceability requirements.
For 2026, two implications are paramount: first, compliance-driven tenders typically yield higher gross margins but longer procurement cycles; second, certification and documentation are becoming table stakes — vendors without robust QA traceability will lose share in regulated end markets.
Recent industry moves — momentum and signals
- Manufacturers continue to refine production — several firms reported investments in adhesion and lining technology that improve bond strength and reduce delamination risk in 2026 manufacturing processes.
- Distribution partnerships remain a fast route-to-market — recent alliances expand reach for branded, proprietary lined products into new geographies and aftermarket channels.
- High-purity product guides and technical literature from leading players signal more aggressive targeting of semiconductor and pharmaceutical end users, where pricing and service premiums are achievable.
Actionable strategic playbook for 2026
Based on our synthesis, PW Consulting recommends the following prioritized actions for executives planning 2026 initiatives:
- Procurement & Cost Strategy — Lock in multi-year supply with resin indexation clauses; diversify suppliers across geographies; implement cost-plus contracts for custom-lined assemblies.
- Product & R&D — Invest selectively in adhesion and lining technologies that reduce lifecycle cost and warranty exposure; develop a modular product platform to shorten lead times on custom quotes.
- Go-to-Market — Build accredited documentation packages for regulated customers; pilot service bundles (inspection, refurbishment) that create recurring revenue and higher switching costs.
- M&A & Partnerships — Target bolt-on acquisitions that fill capability gaps (e.g., larger bore continuous lining, high-purity certification) and strengthen distribution in priority regions.
- Risk Management — Operationalize scenario planning for raw material shocks and regulatory tightening; stress-test pricing models across +/- 30% raw material swings.
How to use the full PW Consulting report
The public summary above intentionally emphasizes strategic implications and supplier context while withholding granular segmentation matrices, full vendor scorecards and the complete set of scenario-model outputs. Subscribers receive:
- Detailed revenue and shipment matrices by product family and application (complete with sensitivity toggles).
- Full competitor benchmarking and acquisition target shortlists with financial proxies.
- Editable commercial templates (RFP language, supplier scorecards, price-indexed contract clauses) ready for immediate deployment.
For procurement leads evaluating tenders, product managers preparing roadmaps, or corporate development teams hunting targets, the complete dataset and tools materially reduce time-to-decision and administrative friction in 2026 execution.
Conclusion — where to focus in 2026
PTFE lined dip pipes sit at the intersection of regulatory demand, material-driven cost volatility and application-led premiuming. The market’s steady growth (5.2% CAGR through 2032) offers attractive incremental opportunities without requiring speculative, capital-intensive expansion — provided firms align procurement, product and go-to-market moves now.
PW Consulting’s full report turns these high-level conclusions into executable plans: modeled financials, supplier playbooks and deal-ready documentation. If your 2026 plan depends on optimizing margins, securing supply or entering high-purity segments, our analysis will shorten the runway from strategy to cash flow.
Learn more
To access the full report, vendor scorecards, and interactive models, please visit PW Consulting’s research portal or contact our advisory desk for a briefing tailored to your organization’s position in the PTFE lined dip pipe value chain.
For detailed analysis of this topic, please visit the official page: Ptfe Lined Dip Pipes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aeroengine Accessory Drive Train Market to Grow from USD 1,025.0 Million in 2025 to USD 1,629.47 Million by 2032 at a 6.85% CAGR
By PW Consulting, 2026-07-01
PW Consulting Releases Strategic Intelligence: Aeroengine Accessory Drive Train (ADT) Market — A 2026 Decision Playbook
PW Consulting today publishes a focused industry briefing accompanying its full Aeroengine Accessory Drive Train (ADT) Market report — designed to give C-suite teams, corporate strategy groups, and supply-chain leaders the actionable perspective they need for high-stakes 2026 decisions. The ADT ecosystem, long viewed as a niche within aeroengines, is now experiencing a multi-year acceleration driven by fleet modernization, defense platform upgrades, and renewed aftermarket demand. Our analysis synthesizes historical performance through 2025 and provides an integrated 2026–2032 forecast backbone, allowing executives to translate market momentum into firm-level playbooks.
Aeroengine Accessory Drive Train Adt Market
Why this report matters for 2026
Decisions taken in 2026 will shape partnerships, investments, and certification roadmaps that determine competitive positioning for the rest of this decade. PW Consulting’s ADT study quantifies the market’s structural growth: the global ADT market grew from approximately USD 682 million in 2020 to roughly USD 1,025 million in 2025, and is forecast to continue expanding to an estimated USD 1,630 million by 2032. The forecast period (2026–2032) reflects a compound annual growth rate (CAGR) of 6.85%, underscoring sustained demand across OEM new programs and the aftermarket.
Aeroengine Accessory Drive Train Adt Market
These headline figures frame two immediate realities for 2026 planning: first, the ADT value pool is large enough to justify targeted manufacturing capacity and automation investments; second, growth is steady but not runaway — meaning disciplined capital allocation and selective vertical integration are likely to outperform broad, unfocused expansion.
Aeroengine Accessory Drive Train Adt Market
What the full report delivers (practical, decision-grade content)
- Market sizing and validated forecast models: historical reconciliation (2020–2025), transparent assumptions for 2026–2032, sensitivity scenarios and downside/upswing stress tests.
- Commercially actionable segmentation frameworks: component, engine-type and geographic lenses with prioritized opportunity matrices (note: summary available here; the report contains full segmented tables and growth pockets).
- Supply-chain and raw-material risk maps: supplier-tier profiles, strategic single-source exposures, and tactical mitigation playbooks for critical alloys and titanium supply constraints.
- Regulatory & certification playbook: stepwise timelines and resource estimates to meet FAA/EASA certification gates for novel designs and material substitutions.
- Competitive benchmarking and capability heatmaps: CR3/CR5 concentration analysis, product roadmaps comparison, and manufacturing footprint optimization models.
- MRO and aftermarket strategies: lifecycle revenue capture models, spare-parts pricing elasticities, and recommended contracts structures for fleet operators.
- M&A and partnership diagnostics: valuation heuristics for small- and mid-cap targets, integration risk scoring, and a build-vs-buy decision toolkit tailored to ADT engineering and assembly capabilities.
Market structure and competitive landscape — what to know now
The ADT market presents a balance between incumbent engineering depth and pockets of entrant opportunity. PW Consulting’s concentration analysis shows a moderately consolidated supplier base: the top three suppliers account for just under half of the market by revenue, while the top five capture roughly two-thirds. This structure creates both defensive advantages for leaders and specific windows for challengers who can bring cost, lead-time, or certification advantages.
Key firms profiled in the study include established ADT integrators and component specialists. Avio Aero (part of GE Aerospace) remains a critical integrator with strong systems capability for inlet, transfer and accessory gearboxes. Safran Transmission Systems holds deep programmatic experience across commercial and military platforms and continues to leverage its design-to-production pathways. BMT Aerospace has demonstrated its ability to execute on flight-critical deliveries and to form strategic manufacturing partnerships, evidenced by recent high-profile program work. Liebherr-Aerospace, Triumph Group, Northstar Aerospace and The Timken Company complete the competitive set: together they represent the engineering, production and bearing/systems strengths necessary across ADT components.
Notable recent developments that influence 2026 strategies include BMT Aerospace’s delivery of a fully assembled flight-critical gearbox for a major business-jet engine program (April 2026), and a strategic manufacturing collaboration formalized between Safran Aero Boosters and BMT Aerospace for components tied to a defense fighter program (October 2025). These actions illustrate two important dynamics: first, the premium that prime contractors place on proven assembly and test capability; second, the market’s ongoing consolidation of program-level responsibilities via partnerships rather than pure in-house execution.
Supply chain and materials — rising as strategic battlegrounds
Raw-material constraints and volatility are now core determinants of ADT competitiveness. Our industry canvass highlights acute titanium market concentration risks and price volatility in nickel-based superalloys — factors that directly inflate manufacturing costs for high-precision gearboxes and shafts. Geopolitical exposures within titanium supply chains, and the pricing swings in superalloys, mean that procurement strategy and inventory posture materially affect margins.
Against this backdrop, the report provides tactical playbooks for procurement leaders, including: near-term inventory and hedging prescriptions; supplier diversification and dual-sourcing frameworks; qualification timelines for alternative alloys; and the cost-benefit calculus for relocating forgings and precision gear production closer to demand centers.
Certification and regulatory dynamics — the clock you must budget for
FAA and EASA certification requirements for new materials and ADT architectures remain a gating factor for market entry. The report maps realistic certification timelines, manpower and test-program budgets needed to validate novel gear treatments, bearing systems and composite-adjacent designs. For 2026 planners, this translates to hard decision points: allocate funding now to accelerate certification and capture program slots, or defer and accept longer tail growth via aftermarket participation.
Strategic implications and recommended moves for 2026
- Prioritize supply-chain de-risking: Secure critical titanium and superalloy supply via long-term agreements, strategic inventory build, or investments in alternative material qualification programs. Small increments in gross margin protection compound meaningfully given the market’s scale.
- Move early on certification: Allocate program funding to front-load FAA/EASA qualification activities for material or architecture changes that yield differentiated weight or reliability advantages.
- Adopt a modular product philosophy: Develop modular ADT subsystems to reduce program-specific customization costs and increase aftermarket retrofit potential.
- Target selective capacity investments: Use our capacity-utilization scenarios to right-size automation and test-cell investments; favor flexible lines that can pivot across gearbox families.
- Pursue focused partnerships rather than broad acquisitions: The market favors engineering and assembly competence — look to minority stakes or JVs with precision gearbox assemblers and bearing specialists to shorten time-to-market and share risk.
- Design aftermarket-first agreements: Negotiate life-cycle agreements with fleet operators that balance warranty exposure against recurring spares and overhaul revenues.
How PW Consulting’s report helps translate insight into action
Beyond headline forecasts, the full PW Consulting report equips teams with the tools they need to act decisively in 2026. These include downloadable Excel models for scenario planning, a supplier scorecard template for procurement negotiations, and a certification timeline planner calibrated to program-type and regulatory jurisdiction. We deliberately structure the deliverables to integrate with corporate capital planning cycles and procurement RFx windows.
Importantly, this press briefing follows the “trailer” principle: it highlights the analytical depth and strategic consequences of our study while reserving detailed segmented tables, customer-by-region demand profiles, and proprietary pricing elasticities for the full report and client portal. Firms serious about converting these insights into competitive advantage should review the complete dataset and model outputs, which are essential inputs to board-level investment memos and program bids.
Next steps for executives
- Download the executive summary to validate our headline market metrics and scenario framing.
- Schedule a bespoke briefing with PW Consulting to walk through the bespoke scenario model for your portfolio.
- Commission a supply-chain stress test or certification roadmap workshop to align 2026 budgets and milestones with program opportunities.
PW Consulting’s Aeroengine Accessory Drive Train (ADT) Market report is aimed at executives who must reconcile engineering complexity, certification lead times, and commodity risk with disciplined capital allocation. With the ADT market on a steady projected trajectory and program-level activity resurging, 2026 is the juncture to set strategy for growth capture or defensive consolidation. Our study gives leaders the prioritized intelligence and practical toolkits to make those choices with clarity.
For the full report, segmented analyses, and proprietary scenario models, please visit the PW Consulting report page or contact our industry team to arrange a confidential briefing.
For detailed analysis of this topic, please visit the official page: Aeroengine Accessory Drive Train Adt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Valve Solenoids for Pneumatics Market to Expand at a 5.45% CAGR During 2026–2032
By PW Consulting, 2026-07-01
Valve Solenoids for Pneumatics: Strategic Imperatives for 2026 — PW Consulting Market Brief
As capital cycles reset and automation roadmaps accelerate, the Valve Solenoids for Pneumatics market is entering a phase where near-term tactical choices will determine long-term market positioning. PW Consulting’s new market study — anchored on a 2025 base year and projecting through 2032 — synthesizes market sizing, competitive positioning, regulatory headwinds, and actionable playbooks tailored for executives making 2026 decisions. This brief highlights the report’s strategic value while preserving the granular segment intelligence exclusively available in the full release.
Valve Solenoids For Pneumatics Market
Market trajectory and macro outlook
Our analysis shows a steady expansion of the global valve solenoid market in pneumatic applications. The market grew from an estimated USD 1,850.8 Million in 2020 to USD 2,345.6 Million in 2025, driven by continued adoption in industrial automation and adjacent sectors. Looking forward, PW Consulting projects a compounded annual growth rate (CAGR) of 5.45% over the 2026–2032 forecast window, taking the market to approximately USD 3,421.9 Million by 2032.
Valve Solenoids For Pneumatics Market
This trajectory reflects a combination of gradual modernization of installed pneumatic fleets, rising demand for higher-performance direct-acting and pilot-operated architectures, and incremental product upgrades aimed at improving energy efficiency, diagnostic capability, and environmental resilience.
Valve Solenoids For Pneumatics Market
Why this report matters for 2026 decision-making
- Timing matters: 2026 is a pivot year for procurement cycles across OEMs and end-users. The report decodes where to prioritize CAPEX for immediate wins versus longer-term product bets.
- Risk-adjusted investment: We translate macro growth into investible themes and quantify the execution and regulatory risks that will influence supplier selection and product roadmaps.
- Procurement optimization: Our buyer-oriented guidance reduces total cost of ownership (TCO) through comparative lifecycle modelling, energy benchmarking, and maintenance-interval sensitivity analysis.
- Go-to-market clarity: For suppliers and investors, the study identifies whitespace opportunities for product modularity, service bundling, and aftermarket revenue capture that can be deployed within 12 months.
What the PW Consulting report contains (practical, actionable elements)
- Independent market sizing and scenario projections (base year 2025; forecast period 2026–2032), including high/medium/low demand scenarios driven by macro and sector-specific variables.
- Executive decision matrix for 2026 — a playbook that translates market scenarios into prioritized strategic moves (e.g., product investments, M&A targets, channel rebalancing).
- Supplier benchmarking and capability heatmaps that compare product portfolios across performance dimensions: flow efficiency, response time, power draw, and diagnostic telemetry readiness.
- Regulatory and standards impact assessment, mapping IEC, ISA/IEC safety/cybersecurity expectations, and ISO interchangeability norms to product design and qualification requirements.
- Raw material and supply-chain stress tests, focusing on stainless steel body requirements and high-grade seal sourcing strategies under different procurement models.
- Customer procurement playbooks and total-cost-of-ownership models for OEMs, system integrators, and end-users, including retrofit vs. replace decision trees.
- Commercial intelligence: pricing band analysis, distribution channel optimization, and service revenue levers for aftermarket and diagnostics-enabled offerings.
- Investment and M&A screening: company-level scorecards and deal priming recommendations for strategic and financial acquirers.
Market dynamics shaping 2026 strategies
Three converging dynamics will shape supplier and buyer strategies in 2026:
- Standards and safety expectations. Increasing adoption of IEC 61511 and ISA/IEC 62443 in safety instrumented systems raises the bar for solenoid valve qualification, diagnostic capabilities, and fail-safe design. Design teams must plan for diagnostic channels, redundancy strategies, and secure communications where applicable.
- Interchangeability and modularization. ISO 5599/1 continues to be a practical benchmark for directional control valves; adherence facilitates faster OEM integrations and reduces BOM complexity. Suppliers that offer modular manifolds and standardized interfaces will gain adoption in systemized purchasing environments.
- Materials and durability. In demanding industrial environments, stainless steel valve bodies and premium seal materials are becoming baseline expectations. Suppliers need to secure qualified material sources and validate longevity to win in critical applications.
Competitive landscape — strategic implications for suppliers and buyers
The market shows a moderate degree of concentration, with the top-tier incumbents collectively holding a meaningful share while room remains for specialized and regional players. PW Consulting’s competitive mapping emphasizes capability clusters rather than raw share numbers, because capability alignment matters more than headline share when designing 2026 strategies.
- MAC Valves, Inc. (Wixom, MI, USA) — Strengths: high-speed balanced poppet designs and "Bullet Valve" technology position MAC for performance-critical automation applications. Strategic implication: OEMs seeking cycle-time gains should engage MAC for co-development; MAC should scale manifold and IoT-enabled diagnostics to defend against platform commoditization.
- Festo AG & Co. KG (Esslingen, Germany) — Strengths: compact directional control solutions and deep system-level integration in factory automation. Recent catalog updates signal renewed emphasis on packaged solutions. Strategic implication: Festo will remain a go-to for integrators seeking turnkey pneumatic modules; challengers should focus on niche differentiation such as hazardous-location certifications or extreme-temperature performance.
- SMC Corporation (Tokyo, Japan) — Strengths: breadth of direct- and pilot-operated offerings with an emphasis on power efficiency and flow. Strategic implication: SMC’s scale provides procurement advantages for global OEMs; smaller suppliers must compete on customization speed and after-sales service.
- Parker Hannifin Corporation (Cleveland, OH, USA) — Strengths: ruggedized product lines for harsh environments and manifold system leadership. Strategic implication: Parker’s portfolio is particularly attractive for end-users in heavy industry; technology partners should offer complementary diagnostic and energy-optimization solutions.
- Emerson (ASCO) (Florham Park, NJ, USA) — Strengths: high-flow industrial valves with a track record of energy efficiency improvements. Recent MVC2 launches show continued product evolution. Strategic implication: Emerson remains a preferred choice for process and industrial applications; expect continued focus on reliability and lifecycle costs.
- Specialists and niche players (e.g., Solenoid Solutions Inc., Magnet-Schultz of America, Humphrey Products) — Strengths: custom designs, rapid prototyping, and specialized performance attributes such as ultra-low response time or specific seal compounds. Strategic implication: These players are acquisition targets and key partners for OEMs seeking bespoke solutions or accelerated time-to-market.
Recent moves that validate near-term trends
- Festo’s 2025/26 product catalog updates emphasize integrated pneumatic control modules and reflect investment in compact, high-flow designs that support high-density automation cells.
- Smaller innovators (e.g., VERSA Valves) continue to release compact direct-acting series tailored to space-constrained and hazardous-location markets — a reminder that product miniaturization and certification breadth remain market entry vectors.
- Emerson’s MVC2 series underlines an industry push on improved flow control and energy efficiency — a factor that will influence retrofit decisions by industrial end-users weighing energy payback against upgrade costs.
Strategic playbook — recommended actions for 2026
- For global suppliers: prioritize investment in modular manifolds and diagnostics. Roadmap 1–2 product lines for IEC/ISA compliance and certify variants for hazardous locations to capture premium pricing.
- For OEMs and system integrators: adopt lifecycle procurement models that include energy and maintenance KPIs; use the report’s TCO templates to renegotiate supplier contracts based on measured performance outcomes.
- For private equity and strategic acquirers: target niche innovators and rapid-prototyping specialists with complementary IP (e.g., specialized seals, miniaturized coils) to accelerate product breadth without lengthy internal R&D cycles.
- For end-users in regulated industries: embed valve qualification in safety instrumented system (SIS) planning, specifying diagnostic and fail-safe modes in procurement documents to avoid late-stage noncompliance costs.
- Supply-chain resilience: lock multi-year agreements for high-grade stainless and certified seal compounds; build dual-sourcing and certification playbooks to mitigate single-supplier disruptions.
How PW Consulting’s report supports execution
The full report equips executives with the data and tools needed to act in 2026: scenario-based investment matrices, supplier shortlists with capability heatmaps, downloadable TCO models, and a prioritized list of product development themes with estimated ROI horizons. We deliberately omit the most sensitive, granular subsegment tables from this brief to encourage decision-makers to access the full intelligence suite, which contains the segmentation depth and supplier scorecards required for contract-level negotiations.
In a market growing at a mid-single-digit CAGR to 2032, the difference between incremental and transformative outcomes will be determined by three choices made in 2026: where to place CAPEX, which partnerships to formalize, and how to align product qualification strategies with evolving safety and interoperability standards. PW Consulting’s Valve Solenoids for Pneumatics market study is built to make those choices clearer, faster, and more defensible.
To obtain the complete dataset, granular segment matrices, supplier scorecards, and the 2026 decision playbook, please consult the full report on PW Consulting’s market portal.
For detailed analysis of this topic, please visit the official page: Valve Solenoids For Pneumatics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


