



Category: Machinery & Automotive
PW Consulting: Ring Laser Gyroscope Market to Hit $10.9B by 2032, 9.2% CAGR
By PW Consulting, 2026-09-16
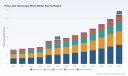
Navigating Precision: The Strategic Imperative of the Ring Laser Gyroscope Market in 2026
Introduction: The Precision Economy
In the landscape of modern navigation, stability is not merely a preference; it is a fundamental requirement for operational success. The Ring Laser Gyroscope, or RLG, stands as a cornerstone technology within this sector, enabling inertial navigation systems to maintain accuracy without reliance on external signals. As global industries increasingly depend on autonomous platforms, advanced aerospace systems, and secure naval operations, the demand for high-fidelity rotational sensing has escalated. This shift represents more than a technical evolution; it signals a substantial economic opportunity that demands rigorous analysis and strategic foresight.
For enterprise leaders operating in aerospace, defense, automotive, and marine sectors, understanding the trajectory of the RLG market is critical. The period extending from 2026 through 2032 promises to be a transformative era defined by technological maturation, supply chain realignment, and heightened competition. Our latest market research publication is designed to cut through the noise, offering a comprehensive view of where value is being created and how competitive dynamics are shifting. This article serves as a strategic primer, outlining the macro-economic currents and competitive forces that will define the landscape, while highlighting the depth of intelligence available in the full report.
Market Trajectory and Economic Scale
The financial magnitude of the Ring Laser Gyroscope sector underscores its importance as a strategic investment area. Historical data from 2020 through 2025 reveals a consistent upward trend, reflecting the gradual integration of RLG technology into more complex and demanding applications. The market valuation has demonstrated resilience and growth, culminating in a significant baseline as we enter the forecast period. Looking ahead, the revenue projections indicate a robust expansion trajectory that extends well into the next decade.
According to our analysis, the global market revenue is poised to grow from a established base in the mid-five billion USD range in 2026 to nearly eleven billion USD by 3032. This growth is not linear but reflects compounding demand drivers across multiple high-value industries. The Compound Annual Growth Rate during this forecast window is estimated at 9.2 percent, signaling a healthy velocity that outpaces many traditional industrial sectors. This rate suggests that capital allocated toward RLG-related technologies or capabilities has the potential for substantial return, provided the investment is targeted correctly within the value chain.
Laser Rangefinder Market
However, aggregate numbers only tell part of the story. The real strategic value lies in understanding the composition of this growth. The revenue stream is not uniform; it is distributed across varying technological configurations and end-use sectors, each with its own risk profile and growth potential. Decision-makers need to know which segments are driving the headline figures and which are lagging, without necessarily revealing the specific numerical breakdowns that could be used by competitors. Our full report dissects these variances, allowing clients to benchmark their position against the broader market rhythm without exposing sensitive comparative data publicly.
Competitive Landscape and Key Players
The structure of the RLG market is characterized by a moderate level of concentration, where a handful of specialized entities hold significant influence over supply chains and technological standards. With a CR3 concentration ratio hovering around 45 percent and a CR5 near 55 percent, the market remains accessible yet competitive. This structure implies that while large players set the tempo, there is room for specialized innovators and component suppliers to capture value through niche excellence. Understanding the identity and capability of these key players is essential for partnership strategy, procurement decisions, and competitive positioning.
Several companies have emerged as pivotal actors in this ecosystem, each contributing distinct value propositions. G&H Products, based in California, exemplifies the artisanal yet high-precision approach to manufacturing. They design and manufacture RLG frames and optical components by hand, supplying complete RLG component packages. Their operations are deeply entrenched in quality assurance, with facilities certified to ISO9001 and AS9100D standards. Furthermore, their compliance with ITAR legislation and registration with the US government underscores their role in the sensitive defense supply chain. By supplying entire component packages including Zerodur frames and precision mirrors, they occupy a critical upstream position that influences the final performance of the gyroscope.
On the optical component side, Excelitas Technologies Corp., headquartered in Pittsburgh, provides the foundational elements that make high-performance RLGs possible. Their precision mirrors and optics are optimized for RLG applications, achieving micro-roughness below 0.5 Angstrom and low scattering. These technical specifications are not merely marketing claims; they represent the physical limits required for maintaining laser cavity finesse, reported at levels up to 200,000. For system integrators seeking to minimize signal noise and maximize stability, the choice of optical supplier is a critical technical decision that impacts the entire navigation suite's reliability.
Completing the triad of innovation is Micro Magic, also based in the United States. They focus on developing and producing complete RLG-based inertial navigation systems, or INS. Their portfolio includes high-precision models tailored for defense and aerospace platforms. This vertical integration from component to system allows them to address end-user requirements directly. In late 2025, Micro Magic announced the launch of new solid-state RLG models, specifically the G-R90, G-R70, and G-R50. These launches target high-precision INS needs for defense and unmanned platforms, indicating a strategic pivot toward versatile, scalable solutions that can accommodate smaller unmanned aerial vehicles as well as larger defense assets. Tracking such product launches is vital for anticipating shifts in capability availability and pricing pressure.
Industry Dynamics and Supply Chain Considerations
The operational environment for RLG market participants is shaped by a complex interplay of regulatory, technological, and supply chain factors. For manufacturers operating in the United States, particularly those serving defense clients, regulatory compliance is not optional. The requirement to comply with ITAR legislation means that export controls and government registration are integral to business continuity. Companies like G&H Products maintain this status explicitly, which serves as both a barrier to entry for non-compliant competitors and a signal of reliability for government contractors. Understanding the regulatory landscape is necessary for assessing market accessibility and potential geopolitical risks that could disrupt supply.
Supply chain resilience is another critical dynamic. The production of an RLG requires specialized materials and precise manufacturing capabilities that are not easily commoditized. The use of materials like Zerodur for frames, supplied by key component vendors, highlights the dependency on specific material sciences. Any disruption in the supply of these high-grade materials can ripple through the production timeline. Our research delves into the sourcing strategies of major players, examining how they mitigate risk through vertical integration or long-term supplier partnerships. For procurement leaders, identifying single points of failure in the supply chain is a prerequisite for building robust inventory strategies.
Ring Laser Gyroscope (RLG) Market
Technological differentiation remains the primary battleground. While the basic physics of the ring laser gyroscope is established, incremental improvements in cavity performance, thermal stability, and size-weight-power profiles continue to drive market segmentation. The push toward solid-state models, as seen in recent developments, suggests a trend toward reduced maintenance and higher reliability, which is particularly valuable for unmanned systems that may lack onboard maintenance crews. Companies that can offer superior micro-roughness in optics or tighter tolerances in mechanical assembly gain a competitive edge that is difficult to replicate quickly. These technological moats are analyzed in depth to help clients understand where true differentiation lies versus where marketing hype may obscure reality.
Strategic Value for Enterprise Decision-Makers
Access to granular market intelligence provides a distinct advantage in formulation of corporate strategy. For investors, the projected revenue path offers a framework for valuation models, helping to determine whether current market sentiment aligns with fundamental growth drivers. For manufacturers, the segmentation data helps identify whitespace opportunities where competition is less intense but demand is growing. For defense contractors, understanding the supply chain positions of component providers like G&H Products or Excelitas ensures that sourcing strategies are aligned with long-term program requirements.
The full report goes beyond the macro trends summarized here. It provides detailed profiling of the ecosystem, mapping out the capabilities of key players against specific application needs. It examines the regulatory environment not just as a constraint but as a strategic filter that defines who can participate in high-value government contracts. The supply chain analysis extends to identifying potential bottlenecks and opportunities for vertical integration. Furthermore, the application analysis breaks down demand drivers across aerospace, marine, automotive, and other sectors, providing context on which industries are leading adoption and why.
Timing is also a critical component of strategic planning. With the forecast period extending to 2032, organizations need to plan capital expenditures and R&D investments today that will pay off in the latter half of the decade. Knowing when market maturity might lead to price compression allows companies to adjust their margin expectations and shift focus to service-based revenue or system integration. Conversely, identifying emerging segments early allows for first-mover advantages in securing supply contracts or intellectual property positions. The report is designed to support these timeline-dependent decisions with data that is both forward-looking and grounded in historical performance.
Conclusion: The Path Forward
The Ring Laser Gyroscope market stands at a pivotal intersection of technological capability and economic opportunity. The growth trajectory suggests that demand will continue to outpace supply in certain high-precision segments, creating leverage for established players while offering challenges for newcomers. The competitive landscape is defined by specialized firms that combine deep technical expertise with regulatory compliance, creating high barriers to entry that protect incumbents. For enterprise leaders, the ability to navigate this landscape depends on having access to accurate, detailed, and actionable intelligence.
This article has provided a high-level overview of the market dynamics, key participants, and structural factors influencing the sector. However, the true power of this research lies in the detailed data and specific strategic recommendations available in the full publication. To truly understand the nuances of the segmentation splits, the regional dynamics, and the specific financial projections required for robust planning, direct access to the comprehensive dataset is necessary. We invite stakeholders to explore the full report to equip their organizations with the insights needed to thrive in this evolving precision economy. Making informed decisions now will determine competitive positioning for the remainder of the decade and beyond.
For detailed analysis of this topic, please visit the official page: Ring Laser Gyroscope (RLG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Door Handle Sensor Market Hits $2.12B in 2025, Poised for 6.15% CAGR Through 2032
By PW Consulting, 2026-09-16
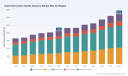
Strategic Intelligence for the Automotive Door Handle Sensors Market: Navigating the 2026–2032 Landscape
The automotive industry is undergoing a profound transformation in how vehicles are accessed, secured, and interacted with. At the heart of this evolution lies a seemingly minor component that carries outsized strategic importance: the door handle sensor. What was once a purely mechanical element has become a critical interface for keyless entry, gesture recognition, and hands-free operation, particularly in electric vehicle platforms where flush and hidden handle designs are increasingly preferred. To support executives, product strategists, and investment analysts in making informed decisions throughout 2026, we have assembled a comprehensive market study on the Automotive Door Handle Sensors Market. This article offers a focused preview of the research, highlights its strategic value, and outlines the operational intelligence contained within the full report.
Why 2026 Marks a Defining Moment for Door Handle Sensor Strategy
The base year of 2025 established a market valuation of approximately 2.12 billion USD, and the trajectory through the forecast window points to steady, compounding expansion. By 2032, the market is projected to reach roughly 3.22 billion USD, reflecting a compound annual growth rate of 6.15 percent over the 2026–2032 period. These figures are not merely backward-looking statistics; they signal a structural shift in vehicle architecture, consumer expectations, and regulatory scrutiny. Automotive door handles are no longer passive hardware. They are becoming integrated sensing nodes that must satisfy demands for reliability, aesthetics, user convenience, and, increasingly, safety compliance.
For decision-makers in 2026, the strategic question is no longer whether door handle sensors will become standard, but how quickly portfolios can adapt to varying sensor technologies, regional regulatory timelines, and OEM customization requirements. The market study is designed to give leaders a clear line of sight into these dynamics, enabling resource allocation that is aligned with long-term revenue opportunities rather than reactive to short-term fluctuations.
What the Research Delivers: Actionable Intelligence Beyond Headline Numbers
The study is built for practical application. It maps the market across sensor types, end-use applications, and geographic regions, while also examining concentration levels among leading suppliers. Rather than presenting static tables, the report translates data into strategic context, helping teams assess where growth is most durable, which applications are gaining traction, and how regional demand profiles differ in pace and character.
Below is a structured preview of the report’s core analytical sections:
- Market sizing and growth trajectory: A multi-year view from historical baseline years through the full forecast period, supporting planning for capacity, investment, and product roadmap decisions.
- Technology segmentation analysis: An evaluation of capacitive, infrared, ultrasonic, and other sensing approaches, with attention to integration complexity, false-trigger resistance, power consumption, and suitability for compact door handle designs.
- Application-driven demand mapping: A breakdown of how keyless entry systems, power door systems, and gesture control systems are shaping sensor requirements across different vehicle segments and OEM priorities.
- Regional demand patterns: A comparative look at how North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa contribute to overall market expansion, with implications for localization, supply planning, and market-entry timing.
- Competitive landscape and concentration: An assessment of market share distribution among leading participants, highlighting the degree of consolidation and the strategic room available for differentiation.
- Regulatory and safety dynamics: A review of policy developments that are reshaping engineering requirements, particularly around hidden or flush door handle designs in electrified platforms.
- Recent industry developments: A timeline-based synthesis of product launches, standards approvals, and investigative activity that are influencing near-term procurement and engineering decisions.
Each section is designed to be referenced independently or read as part of an integrated strategy narrative. The objective is to give automotive suppliers, tier-1 component developers, OEM strategy teams, and investors a reliable basis for scenario planning, risk assessment, and prioritization.
Sensor Technology Choices and the Real-World Trade-Offs They Create
Sensor selection in door handle applications is not a purely technical decision; it is a commercial one. The report examines how different sensing modalities align with distinct vehicle requirements and user experience goals. Capacitive sensing continues to attract strong interest for its ability to support sleek, flush-mounted designs and low-profile integration, especially when combined with gesture recognition and improved resistance to false triggers. Infrared-based solutions offer attractive proximity detection characteristics and can be well suited to specific detection ranges and environmental conditions. Ultrasonic approaches provide an additional pathway for hands-free activation, with relevance to both premium and mass-market vehicle programs. A broader category of alternative sensor designs also exists, often tailored to specialized use cases or OEM-specific integrations.
What matters strategically is that no single technology is universally optimal. The right choice depends on vehicle platform, power budget, aesthetic targets, cost constraints, and the intended user interaction model. The study helps decision-makers compare these trade-offs in a structured way, so that product planning teams can anticipate where demand will concentrate and how supplier capabilities will need to evolve.
Applications Are Reshaping Demand, Not Just Component Specs
Door handle sensors are being deployed across multiple functional domains, and each application creates a different demand profile. Keyless entry systems remain a major driver, reflecting the broader industry movement toward seamless access and digital key ecosystems. Power door systems introduce additional requirements for reliable detection, actuation coordination, and failure-mode resilience. Gesture control systems represent a more advanced interaction layer, particularly relevant where interior and exterior interfaces are being redesigned to support touchless operation and intuitive user experiences.
Automotive Door Handle Sensors Market
These application categories do not grow in isolation. Their adoption patterns are influenced by vehicle segment strategy, regional consumer preferences, electrification roadmaps, and the pace at which OEMs are willing to standardize new interaction models. The report analyzes how these forces interact, enabling readers to gauge which application areas are likely to generate the most consistent demand and which may remain more niche or region-specific over the forecast window.
Competitive Dynamics and the Shape of Market Leadership
The industry is shaped by a group of established players with distinct technical strengths and integration philosophies. NXP Semiconductors brings automotive NFC door handle reference designs and solutions optimized for compact integration. Melexis contributes Hall effect and low-power sensor solutions, including door handle wake-up switches and e-door handle applications. Continental AG has developed capacitive door handle sensor modules with features such as gesture recognition and enhanced false-trigger resistance. Valeo SA supplies ultrasonic-based flush handle sensor systems for hands-free activation across luxury and mass-market vehicles. Infineon Technologies supports door handle detection and control through microcontrollers and sensor ICs for proximity and position sensing. NMB Technologies Corporation manufactures vehicle door handle systems with integrated sensor solutions for OEM customization, including sensing and lighting. ADAC Companies provides vehicle access systems with integrated sensing technologies, capacitive sensors, and microswitches in exterior door handles and trim.
Taken together, these participants illustrate a competitive environment where differentiation is increasingly tied to integration quality, reliability, and the ability to meet OEM-specific design requirements. The report further examines market concentration indicators to provide a clearer picture of how consolidated the field is and where new entrants or niche solutions may still find room to compete.
Regulation, Safety, and the New Compliance Imperative
Regulatory developments are becoming a decisive factor in product planning. In January 2026, China’s Ministry of Industry and Information Technology approved the mandatory national standard GB 48001-2026, Safety Technical Requirements for Automotive Door Handles. The standard addresses safety concerns associated with hidden or flush door handle designs, particularly in electrified vehicle architectures. New vehicle type approvals must comply fully from January 1, 2027, with a transition period extending to January 1, 2029 for previously approved vehicles. This regulatory move reflects a broader scrutiny of electronic door release reliability and signals that safety performance will be a major engineering and procurement consideration in the near term.
At the same time, investigative coverage in the United States has drawn attention to potential defects in electronic door releases in certain Tesla models, with reports of occupants trapped and fatalities linked to crashes where doors would not open. While each case involves specific technical and legal contexts, the cumulative effect is clear: consumer safety, fail-safe design, and verifiable reliability are moving to the foreground of automotive access-system discussions. These dynamics create both risk and opportunity. Suppliers that can demonstrate robust safety performance, transparent validation, and compliance readiness may gain a meaningful advantage in OEM evaluations.
Recent Developments That Are Already Shaping Procurement and Roadmaps
The report incorporates recent events that are actively influencing market direction. In January 2026, both regulatory approval activity and high-profile safety investigations reinforced the importance of dependable door handle sensing and release mechanisms. Then, in February 2026, Continental AG introduced a new capacitive door handle sensor module featuring integrated gesture recognition and improved false-trigger resistance for premium EV platforms. This launch highlights the accelerating focus on user experience, false-trigger mitigation, and electrification-aligned design. Such developments are not isolated news items; they are indicators of how product roadmaps, qualification processes, and buying criteria are shifting in real time.
Automotive Door Handles Market
How to Use This Research for 2026 Decision-Making
The strategic value of the full study lies in its ability to convert market signals into executable insight. The report is intended to support several concrete decisions, including:
- Portfolio prioritization: Determining which sensor technologies and application segments deserve the greatest engineering and commercial focus in the coming years.
- Regional planning: Aligning supply, localization, and market-entry strategies with region-specific demand patterns and regulatory timelines.
- Competitive benchmarking: Understanding where leading suppliers are concentrating their capabilities and where differentiation opportunities remain.
- Risk management: Anticipating safety-related compliance requirements and integrating them into product validation and procurement strategies.
- Investment and partnership decisions: Identifying where long-term market growth is most credible and which capability gaps may create collaboration or acquisition opportunities.
Completing the Picture: Accessing the Full Market Intelligence
This article provides a structured overview of the themes, growth path, and competitive context that define the Automotive Door Handle Sensors Market. However, the full report contains the detailed sizing framework, segmentation comparisons, regional breakdowns, competitive profiles, and operational guidance needed to turn these themes into precise strategic actions. For teams planning product launches, capacity decisions, supplier negotiations, or market-entry assessments in 2026, the complete dataset and analytical commentary offer the depth required to reduce uncertainty and support confident choices.
To access the full market research and obtain the complete segmentation detail, regional analysis, and company-level intelligence, visit the official report page. The complete study is designed to serve as a working reference for strategic planning throughout the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Automotive Door Handle Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Micromanipulators Market Hits $81.5M in 2025, Projected 9.3% CAGR to $152.8M by 2032
By PW Consulting, 2026-09-07
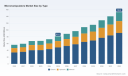
Precision at the Microscale: Strategic Imperatives in the 2026 Micromanipulators Market
The micromanipulation landscape is undergoing a decisive transformation. As laboratory workflows grow more complex and industrial tolerances tighten, the demand for sub-micron positioning accuracy has shifted from a niche requirement to a foundational capability. Our latest market research on the Micromanipulators Market provides a comprehensive, data-grounded lens into how this sector is evolving through 2032. For executives navigating capital allocation, R&D prioritization, and competitive positioning, this report delivers the strategic clarity required to act with confidence in 2026 and beyond.
Algae Based Plastics Market
The Macro Trajectory: Velocity, Scale, and Structural Shift
Over the past half-decade, the global micromanipulators market has demonstrated consistent, compounding growth. Revenue expanded from approximately USD 56.5 million in 2020 to an estimated USD 81.5 million in 2025, reflecting a sector that has not only recovered from pandemic-era supply chain friction but has accelerated into a new growth phase. Looking ahead, the forecast period from 2026 through 2032 projects a robust compound annual growth rate of 9.3 percent, with market revenue anticipated to cross the USD 150 million threshold by the end of the decade. These figures are not merely historical retrospectives; they are leading indicators of structural demand drivers that will shape procurement strategies, partnership decisions, and innovation roadmaps across life sciences, semiconductor fabrication, and advanced materials research.
Low Voltage LED Explosion Proof Light Market
Several converging forces explain this momentum. Sustained investment in neurology and cell biology research has intensified the need for repeatable, high-fidelity manipulation workflows. Simultaneously, the semiconductor and microelectronics sectors continue to push dimensional tolerances downward, requiring positioning subsystems that can operate with minimal drift and exceptional repeatability. The normalization of assisted reproductive technologies and the formalization of micro-operative protocols have further embedded micromanipulation into regulated clinical pipelines. Together, these dynamics create a multi-application demand base that is less vulnerable to single-sector downturns than earlier market cycles suggested.
Hydrogen Electronic Pressure Regulators Market
From Linear Growth to Compounding Value
The growth trajectory observed between 2020 and 2025 was not accidental. It was built on a foundation of iterative product refinement, expanding end-user training programs, and the gradual migration from legacy manual setups toward motorized and electric architectures. As research institutions and commercial laboratories scale their throughput, the total cost of ownership calculus has shifted. Buyers now weigh precision stability, integration compatibility, calibration drift, and service responsiveness alongside initial purchase price. This recalibration of buyer priorities is a critical insight for suppliers evaluating product roadmaps and for procurement leaders structuring multi-year equipment budgets.
Equally important is the market's increasing sensitivity to regulatory and standardization developments. Recent definitions and clinical guidance documents have formalized micro-operative techniques that rely on micromanipulation for procedures such as intracytoplasmic sperm injection and assisted hatching. While these standards do not dictate device specifications directly, they influence laboratory procurement policies, quality management expectations, and the documentation burden placed on equipment vendors. Organizations that anticipate these compliance trends will secure smoother adoption cycles and reduce time-to-deployment for new instrumentation.
Competitive Architecture: Focused Leaders, Regional Depth, and Consolidation Signals
The micromanipulators market remains characterized by a concentrated yet highly specialized competitive field. Industry data indicates that the top three participants collectively account for roughly 38.5 percent of total market revenue, while the top five expand that share to approximately 45.2 percent. This concentration pattern reflects the technical barriers inherent in precision mechanical design, sensor integration, and application-specific calibration. At the same time, the remaining market share is distributed among a long tail of capable manufacturers, regional integrators, and application-focused specialists, creating a landscape where differentiation is achieved through expertise rather than scale alone.
Several companies exemplify the strategic posture now required to compete effectively. Sensapex Oy, headquartered in Oulu, Finland, has built its reputation on patented ultraprecise micromanipulators and automated microscope workstations designed for electrophysiology and imaging, with in-house manufacturing supporting tight control over performance consistency. Sutter Instrument, based in Novato, California, continues to serve a broad electrophysiology and cell manipulation customer base through precision manual and motorized platforms that emphasize reliability and practical usability. Scientifica Ltd, operating from East Sussex, United Kingdom, has focused on the PatchStar micromanipulator line and electromechanical systems tailored for patch clamp and electrophysiology workflows, reinforcing a strategy of deep application specialization.
In the United States, Siskiyou Corporation, located in Grants Pass, Oregon, has maintained a strong reputation for high-precision micromanipulators and micropositioners used in microscopy and research applications, where customization and engineering responsiveness remain key differentiators. Narishige Group, headquartered in Tokyo, Japan, offers a distinct product philosophy through its NTX series hydraulic and motorized micromanipulators, addressing cell manipulation and microinjection requirements with a balance of mechanical robustness and fine positional control. World Precision Instruments, based in Sarasota, Florida, remains closely associated with manual micromanipulators for electrode positioning in electrophysiology and neuroscience, a segment where familiarity, service networks, and practical ergonomics continue to drive repeat purchases.
Larger systems players also shape the market's direction. Leica Microsystems, from Wetzlar, Germany, delivers integrated micromanipulator systems that align precision positioning with advanced microscopy and cell research environments, benefiting from cross-platform integration and brand trust in imaging ecosystems. Eppendorf SE, headquartered in Hamburg, Germany, contributes high-precision micromanipulation and injection systems that serve broad life science applications, reinforcing a portfolio strategy that connects sample handling, manipulation, and downstream processing in a cohesive workflow.
Recent Moves That Signal Strategic Direction
Recent corporate activity illustrates how quickly product portfolios and deployment models are evolving. In mid-2024, Sensapex released a revised manual for its uMp micromanipulation system, incorporating the uMp-TSC2 controller alongside uMp-3 and uMp-4 micromanipulators, a move that underscores a continued emphasis on usability upgrades and controller-level integration. By late 2024, New Scale Technologies completed delivery of a Modular Insertion System to the Allen Institute for Neural Dynamics, enabling order-taking for next-generation silicon probe micromanipulation and highlighting the growing importance of modular, research-grade insertion workflows in neuroscience. More recently, planning for SLAS Europe 2026 has featured sessions examining manual micromanipulation in an era of lab automation, signaling a broader industry conversation about where manual control still adds value and where automation is reshaping protocols.
These developments matter because they reveal how incumbents and innovators are responding to the same underlying pressure: laboratories want higher throughput, better repeatability, and clearer integration paths without sacrificing the fine control required for delicate procedures. Companies that can bridge that gap through modular architecture, improved controller interfaces, or application-tuned mechanical designs are likely to capture disproportionate attention from advanced research groups and commercial testing organizations.
Operational Content: What the Report Delivers for Decision-Makers
This market research is designed as an operational instrument, not a static summary of figures. The report is structured to help strategy, product, and commercial teams translate market signals into concrete actions. It provides a detailed examination of product architectures across electric, hydraulic, and manual configurations, mapping each category to the performance trade-offs, maintenance profiles, and application fit that drive adoption decisions. Rather than treating these segments as isolated statistical buckets, the analysis situates them within the purchasing logic of end users who must balance precision, throughput, training burden, and lifecycle cost.
The report also traces application-level demand patterns in a way that is actionable for go-to-market planning. Cell micromanipulation remains a dominant use environment, driven by life science research, reproductive medicine workflows, and advanced cellular engineering. Industrial micromanipulation applications form a distinct and growing demand base, shaped by micro-assembly, inspection, and precision handling requirements in manufacturing-adjacent settings. Additional use cases extend the market's reach into specialized research and imaging workflows. By examining how these application clusters interact with product type preferences, procurement cycles, and regional laboratory infrastructure, the study helps companies identify where to concentrate sales engineering resources and where to adapt messaging for different operational realities.
Regional Context Without Overgeneralization
Geographic analysis in the report is framed around deployment density, institutional demand profiles, and the practical realities of supply and support networks rather than simplistic share rankings. North America continues to reflect a mature buyer base with strong exposure to neuroscience, electrophysiology, and advanced imaging research. Europe maintains a substantial footprint shaped by established academic institutions, clinical research infrastructure, and a strong tradition of precision instrumentation. Asia Pacific's trajectory is gaining attention as research investment, semiconductor-related precision needs, and expanding laboratory capacity reinforce demand across multiple application domains. Latin America and the Middle East and Africa, while smaller in absolute scale, represent targeted opportunities where specialized support, affordability, and application training can influence adoption more than headline market size alone.
By maintaining this contextual framing, the report helps clients avoid the trap of treating all regions as homogeneous. Regional strategy requires understanding what local laboratories prioritize, how procurement cycles differ, and which service and calibration capabilities are expected as baseline requirements. The analysis provides the qualitative scaffolding needed to translate market potential into realistic entry or expansion plans.
Industry Dynamics: Cost Pressure, Standards, and Cross-Sector Pull
One of the most important dynamics shaping procurement behavior is the tension between precision expectations and total cost of ownership. Industry commentary has noted that certain low-cost electric micromanipulator assemblies can materially undercut the price of commercial hydraulic alternatives while eliminating the need for regular maintenance. This cost dynamic does not uniformly displace premium systems, but it does reshape comparison sets, especially in laboratories balancing performance requirements against budget constraints. For vendors, this environment rewards clarity about where value is created: in stability, in integration, in service responsiveness, or in application-specific calibration that lower-cost alternatives cannot easily replicate.
Regulatory and standards developments are exerting a parallel influence. Recent consensus definitions and clinical guidance have formalized the role of micromanipulation within micro-operative assisted reproductive techniques, including ICSI and assisted hatching. These references may appear clinical on the surface, but they have commercial implications. They influence laboratory purchasing criteria, documentation expectations, and the degree of procedural justification required for equipment selection. Suppliers that understand how such standards filter into procurement checklists and internal validation processes are better positioned to support customers through adoption and to avoid friction in regulated environments.
On the demand side, a broader macro trend continues to accelerate interest in high-precision micromanipulation across neurology, biology, and semiconductor-adjacent sectors. The rise in R&D activity is not simply expanding the user base; it is changing the sophistication of the user base. More laboratories now expect repeatable positioning, better integration with imaging or automation peripherals, and clearer documentation for method reproducibility. That shift increases the strategic importance of product reliability and supplier support, while also expanding the addressable market for systems that can serve multi-application labs without sacrificing specialized performance.
Why This Study Matters for 2026 Decision-Making
2026 is a planning year in which many organizations must reconcile near-term budget constraints with long-term capability needs. The micromanipulators market is at a point where historical growth, product evolution, and application expansion are aligning in ways that reward informed strategic positioning. Companies that delay analysis risk overindexing to legacy product assumptions, misallocating sales coverage, or underestimating the importance of integration and service in buyer decisions. Organizations that act early can align product development, pricing architecture, channel strategy, and customer education with the demand patterns that are already shaping procurement behavior.
The strategic value of this research lies in its ability to connect multiple layers of evidence into a single decision framework. It grounds narrative insight in verified market sizing and forecast direction, integrates competitive profiles with recent product and deployment developments, and contextualizes those findings within the practical realities of laboratory and industrial purchasing. For executives evaluating market entry, portfolio expansion, partnership opportunities, or competitive response, the report offers a disciplined starting point that reduces uncertainty without oversimplifying a technically complex sector.
What Is Reserved for the Full Report
To preserve the analytical integrity and commercial utility of the study, this preview intentionally omits the detailed segmentation breakdowns, region-specific share figures, application-level revenue distributions, and type-level quantitative splits that support the broader narrative. Those data are essential for building precise financial models, sizing submarket opportunities, and benchmarking competitive exposure. They are also the core reason the full report functions as a working intelligence asset rather than a high-level overview. Clients who rely on top-line macro signals alone risk missing the structural differences that determine where value is created and where competition is most intense.
The complete study unpacks those layers in a format designed for internal strategy discussions, product planning sessions, and commercial forecasting. It connects market size movement to segment-level dynamics, maps competitive positioning to product and application fit, and provides the granularity needed to assess which opportunities are large enough to justify investment and which require a more targeted approach. For teams planning 2026 initiatives, that level of detail is not optional; it is the difference between directional confidence and decision-grade evidence.
How to Use This Intelligence
Organizations derive the most value from this research when they treat it as a strategic framework rather than a single-use reading. Product leaders can use the analysis to pressure-test roadmap assumptions against application demand and buyer cost sensitivity. Commercial teams can align territory plans and value propositions with the segments and use cases most likely to drive near-term growth. Corporate development and partnership teams can identify where interoperability, service networks, or application expertise create more advantage than raw manufacturing scale. Executive leadership can use the forecast trajectory and market concentration context to frame investment timing and risk tolerance with a clearer view of where growth is structural rather than cyclical.
In a market defined by precision, repeatability, and increasing application complexity, the organizations that outperform will be those that understand not just that demand is growing, but why it is growing, where it is concentrating, and what buyers now expect from the equipment they trust with critical workflows. This study is built to provide exactly that understanding.
To access the full segmentation detail, competitive benchmarking, application analysis, and forecast scenarios that support planning-level decisions, we invite you to review the complete Micromanipulators Market research on the source page. The complete dataset and proprietary analysis are available there for teams that need to move from market awareness to actionable strategy.
For detailed analysis of this topic, please visit the official page: Micromanipulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Barcode Label Printer Market to Reach $344.8M by 2032, 6.98% CAGR
By PW Consulting, 2026-09-07
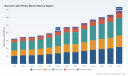
Executive Brief: Navigating the Barcode Label Printer Market 2026-2032
In an era where supply chain resilience and data integrity dictate competitive advantage, the barcode label printer has evolved from a peripheral utility to a strategic asset. As enterprises across logistics, healthcare, manufacturing, and retail confront mounting regulatory pressures and volatile input costs, the need for precise, forward-looking intelligence has never been greater. The updated Barcode Label Printer Market Research offered by PW Consulting delivers exactly that: a comprehensive, data-grounded examination of where the market stands, how it is shifting, and what decision-makers must anticipate through the end of the decade. This article serves as a strategic preview of the full report, outlining the executive value proposition and highlighting the analytical frameworks embedded within our latest publication.
Food Preservative Sodium Benzoate Market
The global landscape for barcode label printers is undergoing a phase of structural redefinition. Demand is no longer driven solely by volume replacement cycles; it is being reshaped by compliance mandates, automation trends, edge computing integration, and sustainability expectations. Understanding these forces requires more than a snapshot of current sales. It demands a disciplined look at historical trajectories, near-term inflection points, and the competitive architecture that will determine market share allocation in the years ahead. PW Consulting’s assessment is built to support exactly that level of strategic foresight.
PCB Automated Visual Inspection(AVI) System Market
Market Trajectory and Strategic Context: 2020-2032
The baseline figures in our analysis trace a clear upward arc across the historical window from 2020 through 2025, establishing a foundation of consistent expansion even amid macroeconomic disruptions. That momentum carries forward into the forecast horizon extending to 2032, with a projected compound annual growth rate (CAGR) reinforcing the market’s resilience and long-term relevance. For leadership teams evaluating capital allocation, operational readiness, or vendor partnerships, the scale of this expansion is meaningful. A market that crosses multiple hundred-million-dollar thresholds over the forecast window signals sustained demand for label printing solutions across both mature and emerging use cases.
Industrial Low-Temperature Heat Pump Systems Market
More important than any single headline figure is the rhythm of growth itself. The trajectory reflects a market that is not merely recovering but recalibrating around new operational priorities: higher print reliability at the edge of the warehouse floor, compact and ruggedized devices for mobile workflows, and printer portfolios aligned with connected inventory systems. The data narrative in the full report connects these demand-side shifts to revenue growth patterns, enabling readers to align procurement planning, product roadmaps, and regional expansion strategies with realistic quantitative expectations. Because the complete breakdown of regional contributions, technology preferences, application weightings, and device-type distributions is detailed within the report itself, this preview intentionally retains the macro-level framing. That approach preserves the analytical gravity of the dataset while directing readers to the source for the precise figures required to model their own scenarios.
What the Report Delivers: Operational Intelligence Beyond the Numbers
A strong market study does more than summarize past performance; it equips stakeholders with a usable framework for action. PW Consulting’s Barcode Label Printer Market research has been constructed with that standard in mind. The publication is organized to serve a range of internal functions, from procurement and supply chain leadership to product strategy, competitive intelligence, and financial planning. Each section is designed to reduce ambiguity around market structure and to clarify where investment and procurement decisions should be prioritized.
Core Components of the Report
- Historical sizing and forecast modeling spanning the full analysis window, enabling year-by-year context for revenue evolution and growth pacing.
- Structural segmentation analysis that maps the market across device categories, printing technologies, key application environments, and geographic regions, providing the scaffolding needed to understand where value concentrates and where opportunities are emerging.
- Competitive profiling of leading participants, including positioning summaries and technology focus areas, so that buyers and competitors alike can benchmark capability sets and strategic intent.
- Documentation of recent corporate developments, such as product launches, line extensions, and trade-show activations, offering a timely view of how major players are translating strategy into market-facing moves.
- Assessment of market concentration indicators, giving readers a sense of fragmentation, consolidation risk, and bargaining dynamics within the supplier base.
- Industry context review covering regulatory updates, raw-material cost pressures, and logistics disruptions that are reshaping manufacturing economics and lead-time reliability for printer hardware.
This structure is deliberate. By combining quantitative market sizing with qualitative event tracking and external factor analysis, the report functions as a decision-support tool rather than a static reference. Readers can use it to validate assumptions, pressure-test expansion plans, and identify which operational variables merit closer monitoring. For organizations that depend on label printing as part of broader identification, traceability, or fulfillment workflows, that blend of data and context is indispensable.
Competitive Landscape: Established Leaders and Specialized Challengers
The competitive environment in barcode label printing is defined by a blend of global automation incumbents, specialized identification technology providers, and regional specialists with strong cost-performance positioning. The report profiles a broad cross-section of these companies, capturing how each is shaping its offering for distinct operational environments. This matters because procurement decisions are increasingly tied not only to unit price but to integration readiness, durability, connectivity features, and alignment with sector-specific compliance requirements.
Major Participants and Strategic Positioning
- Zebra Technologies Corporation remains deeply embedded in the high-volume identification space, with printer solutions extending across industrial, desktop, mobile, and RFID-enabled formats for logistics, retail, and healthcare environments. Recent activity underscores a continued push toward faster print speeds, hygiene-conscious device design, and advanced RFID integration for warehouse and clinical settings.
- Honeywell International Inc. emphasizes rugged desktop and portable printers with integrated scanning functionality, targeting industrial and warehouse use cases where durability and hands-free data capture matter. Its recent portable printer series highlights an interest in embedding AI-assisted data processing functions for healthcare and retail workflows.
- SATO Holdings Corporation focuses on industrial and mobile thermal label printers optimized for high-speed output in manufacturing, logistics, and healthcare, reinforcing the importance of throughput and reliability in mission-critical environments.
- TSC Auto ID Technology Co., Ltd. positions cost-effective industrial and mobile printers for demanding warehouse and logistics conditions, appealing to operators that need robust performance without premium price structures.
- Brother Industries, Ltd. serves high-volume and point-of-sale applications with industrial desktop and mobile thermal barcode label printers, reflecting a balance between commercial print density and operational simplicity.
- Seiko Epson Corporation offers label printers and dedicated barcode printing devices for retail, shipping, and industrial applications, extending its imaging heritage into operational identification workflows.
- Toshiba Tec Corporation contributes industrial desktop barcode and label printers tailored to manufacturing and logistics, aligning printer capability with material handling and production-line identification needs.
- DYMO (Newell Brands) concentrates on compact desktop and portable label printers and label makers for office, retail, and shipping use, while also expanding toward eco-friendly label materials in response to sustainability-driven demand.
- Citizen Systems Japan Co., Ltd. delivers high-performance desktop and portable printers for POS and industrial use, supporting environments that require consistent output and quick deployment.
- BIXOLON Co., Ltd. brings mobile, desktop, and industrial label and barcode printers into retail, logistics, and healthcare contexts, with recent visibility at international retail technology events signaling continued portfolio expansion.
- GoDEX International Co., Ltd. offers high-resolution desktop and mobile barcode label printers for industrial and commercial applications, targeting users that prioritize print clarity and versatility across commercial workflows.
These profiles are not mere company summaries. They are structured to help readers understand how each participant competes: through ruggedization, integrated scanning, RFID readiness, cost-efficient industrial output, compactness for office and shipping use, or sustainability features. For procurement leaders comparing vendor shortlists, or for strategists tracking possible consolidation and capability migration, this competitive mapping offers a practical lens. The full report broadens this view with additional market context and development tracking, allowing users to connect corporate moves to the broader growth pattern described earlier in the analysis.
Industry Dynamics: Regulation, Materials, and Supply Chain Pressures
Market growth does not occur in a vacuum. The current cycle is heavily influenced by external forces that affect both demand and the economics of supplying hardware. The report integrates several of these dynamics so that readers can anticipate friction points and compliance-driven opportunities rather than react to them after the fact.
Regulatory and Standards Developments
In North America, updated industry guidance for standard case code labeling has reinforced best practices for GS1-128 barcode compliance in grocery and foodservice sectors. This type of standardization typically raises the baseline expectation for print quality, label durability, and data formatting consistency, which in turn influences equipment selection and integration planning for distributors and retailers. At the same time, the U.S. Drug Supply Chain Security Act continues to drive mandatory adoption of barcode-enabled tracking systems in healthcare and pharmaceutical distribution. For printer suppliers and end users alike, these regulatory currents increase the strategic importance of reliable, traceable, compliant printing equipment.
Input Costs and Trade Constraints
Hardware economics are being pressured by a combination of material cost escalation and export-control dynamics. Rising U.S.-China technology trade tensions, including restrictions on semiconductor-related exports, have contributed to higher costs for rare earth elements used in printer hardware components. This input-cost environment is a reminder that pricing stability in the barcode printer market can be influenced as much by global trade policy and material availability as by end-market demand. Organizations planning multi-year printer deployments should factor such volatility into total cost of ownership assumptions and inventory timing.
Logistics Disruptions and Lead-Time Exposure
Supply chain conditions remain a practical concern for hardware sourcing. Prolonged transit delays in key maritime routes have extended shipping timelines and increased per-container costs, disrupting component imports for barcode printers. For buyers, this translates into longer lead times, potential deployment schedule slippage, and a stronger case for risk-buffered procurement strategies. For suppliers, it reinforces the value of regional inventory positioning and demand forecasting discipline. These dynamics are not short-term anomalies to be wished away; they are part of the operating reality that the report’s market outlook incorporates when framing the path toward 2032.
Strategic Implications for 2026 Decision-Making
What does this body of analysis mean for executives making decisions in 2026? First, it confirms that the barcode label printer market remains a growth-relevant category with broad cross-industry demand. The scale of the forecast trajectory and the underlying growth rate indicate that label printing infrastructure should be treated as a long-duration capability rather than a discretionary purchase. Second, the competitive landscape shows that no single device category or supplier profile fits every environment. Industrial throughput, mobile flexibility, desktop simplicity, integration with scanning and RFID, and sustainability-oriented materials all represent distinct value propositions that must be matched to operational requirements.
Third, external pressures—regulatory compliance, raw-material cost exposure, and logistics disruptions—make timing, sourcing strategy, and vendor reliability more important than ever. Organizations that evaluate printer portfolios with these factors in mind can reduce procurement risk, improve deployment predictability, and align hardware choices with compliance expectations in healthcare, retail, and food distribution workflows. Fourth, recent product activity from major participants signals that the market is moving toward faster, more connected, and in some cases more hygiene- or sustainability-conscious devices. Keeping pace with these developments requires ongoing monitoring, which is precisely the role the full report is designed to serve.
Leaders in finance, operations, procurement, and product strategy can use the research to address questions that often remain under-examined until a disruption forces attention: Where is demand expanding most reliably? Which device types and technologies dominate different parts of the market? How concentrated is supplier power, and what does that imply for negotiation and roadmap flexibility? What external shocks could alter cost structures or delivery timelines? The report is built to support that level of internal discussion with documented data and current event context, while leaving the detailed segment-level breakdowns available for deeper modeling within the full publication.
Final Word: Why This Research Belongs on the 2026 Planning Agenda
The barcode label printer market may appear, on the surface, to be a mature hardware category. In practice, it is a bellwether for how well organizations are adapting to traceability mandates, edge-level automation, mobile operational models, and supply chain cost pressures. PW Consulting’s updated market research offers a rigorous, current, and decision-oriented view of that landscape, bridging historical performance, forward-looking growth, competitive positioning, and external dynamics in a single structured assessment.
This article has outlined the macro framework and the report’s practical value without exposing the full segment-level intelligence that makes the study actionable for specific planning scenarios. For teams that need exact market sizing by region, device type, technology, and application, along with the accompanying competitive and industry-context detail, the complete Barcode Label Printer Market report is the appropriate next step. It is designed to convert high-level awareness into procurement confidence, portfolio strategy, and risk-informed planning. In a market where compliance, cost, and continuity all matter at once, that level of clarity is not optional—it is a strategic necessity.
For detailed analysis of this topic, please visit the official page: Barcode Label Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting LED Street Lighting Market to Hit $13.48B by 2032 with 5.28% CAGR
By PW Consulting, 2026-09-07
Illuminating the Path: Strategic Intelligence for the LED Street Lighting Market 2026–2032
The global transition toward smarter, more energy-efficient urban infrastructure is no longer a speculative trend—it is a measurable capital reallocation. Within this shift, the LED street lighting market has emerged as a critical nexus where municipal policy, utility economics, and advanced optical engineering intersect. As city planners, EPC contractors, and manufacturing executives map out their capital expenditure pipelines for 2026, the need for a structured, data-backed view of market trajectories has never been more acute. PW Consulting’s newly released LED Street Lighting Market study provides precisely that vantage point, translating multi-year valuation trends, supply chain pressures, and competitive maneuvers into a decision-ready framework.
UCMSCs Exosomes Market
Recent historical data places the sector’s valuation at roughly 9.43 billion USD at the close of 2025, following a steady expansion from approximately 7.64 billion USD in 2020. That trajectory reflects not merely incremental volume growth, but a structural re-pricing of outdoor illumination assets toward solid-state technology. The forecast window through 2032 indicates a compound annual growth rate of approximately 5.28 percent, with market valuation projected to reach 13.48 billion USD by the terminal year of the model. These figures are more than retrospective accounting; they represent the baseline against which procurement budgets, production capacity expansions, and technology roadmap decisions will be validated throughout the coming cycle.
On-Tank Valve for Hydrogen Fuel Cells Market
Yet aggregate scale and compound growth rates only tell a fraction of the story. The real strategic challenge for market participants lies in parsing how technological substitution, material cost volatility, regulatory mandates, and regional procurement models converge to reshape competitive positioning. This analysis serves as the introductory overview to our full market intelligence release, outlining the methodology, structural coverage, competitive landscape, and operational implications that decision-makers must evaluate before committing capital in 2026 and beyond.
12V Linear Actuator Market
The Strategic Imperative of the 2026–2032 Forecast Window
The five-year forward horizon captured in this study is deliberately calibrated to align with municipal capital planning cycles, utility procurement schedules, and infrastructure funding release patterns. In practice, street lighting projects rarely move from specification to installation within a single fiscal year. They require feasibility assessments, engineering reviews, grant or bond alignments, and staged rollout logistics. By anchoring our projections from 2026 through 2032, the study provides a planning cadence that matches how infrastructure decisions actually materialize.
Two macro-inflection points shape this window. First, the ongoing displacement of legacy luminous sources by LED architectures has reached a maturity threshold where the conversation is no longer about basic adoption, but about performance optimization, networked controls, and lifecycle economics. Second, regulatory and sustainability mandates are accelerating procurement timelines across advanced economies and emerging markets alike. Public-sector owners are increasingly evaluated on energy intensity metrics, carbon reduction targets, and maintenance cost containment, all of which favor integrated LED solutions with embedded control capabilities.
For OEMs, system integrators, and specifiers, the forecast period offers a valuable lens: it signals where demand concentration will likely intensify, where retrofit pipelines will outpace greenfield installations, and where regional procurement models will reward differentiated value propositions. The report does not stop at directional commentary. It builds a structured, segment-aware assessment that enables stakeholders to align product development, channel strategy, and pricing architecture with the probability distribution of future demand rather than with legacy assumptions.
Structural Market Architecture: How the Study Segments the Opportunity
The full report deconstructs the LED street lighting market along three analytical axes—geographic reach, product technology classification, and end-use application—allowing readers to isolate the structural drivers most relevant to their operating context. Rather than presenting a monolithic top-line figure, the segmentation framework reveals how value creation concentrates across different corridors of the market and where substitution cycles, technical requirements, and procurement behaviors diverge.
Geographically, the study maps demand intensity across mature infrastructure markets, rapidly urbanizing regions, and jurisdictions undergoing policy-driven retrofitting programs. Each regional profile is contextualized against local energy economics, municipal asset transfer frameworks, and the maturity of smart-lighting control deployments. Product-level analysis distinguishes between fully solid-state LED configurations and remaining traditional lighting categories, emphasizing the ongoing migration of capital and specification share toward high-efficacy LED platforms. The application dimension tracks how demand is distributed across highway corridors, general roadway networks, and ancillary municipal or commercial outdoor installations, each carrying distinct photometric, durability, and control-integration requirements.
Because segmentation data carries direct implications for pricing, channel selection, and capacity planning, the complete percentages, share breakdowns, and regional revenue splits are reserved for the full report. This deliberate boundary ensures that briefing-level readers grasp the structural logic without eroding the proprietary granularity that enterprise subscribers rely on for precise scenario modeling. What can be stated at the overview level is that the analysis consistently ties each segment back to procurement readiness, replacement-cycle momentum, and the financial calculus of energy cost avoidance.
Navigating Supply-Side Pressures: Material Costs, Compliance Timelines, and Technical Redefinition
No market outlook is credible without confronting the operational realities shaping manufacturing economics and specification behaviors. The LED street lighting landscape in 2026 is being shaped by a combination of raw material cost pressure, evolving regulatory incentives, and engineering redefinitions of what constitutes a “complete” outdoor lighting solution.
On the input cost side, recent industry data indicates sharp upward movement in the prices of critical metals and conductive materials. Silver prices have risen substantially year-over-year, and copper has climbed past key price thresholds during early 2026, directly affecting the bill of materials for drivers, circuit boards, housing components, and thermal management assemblies. These pressures are not merely margin concerns; they influence product architecture decisions, supplier diversification strategies, and procurement timing for large-scale public tenders. The study incorporates these dynamics into cost-structure sensitivity discussions, allowing manufacturers to anticipate where design-for-manufacturability adjustments or alternate sourcing strategies may become necessary to preserve margin integrity.
Regulatory forces are simultaneously reshaping the demand environment. In the United States, public projections indicate that LED street lighting installations are expected to account for the majority of the installed base by 2035, delivering substantial annual energy savings at the national level. For market participants, this implies a long-run procurement tailwind for high-efficiency systems and a growing emphasis on integrated controls that maximize energy reduction beyond simple lamp replacement. In other markets, policy architecture has already altered who bears the cost of public illumination. For instance, municipal asset transfer frameworks in Brazil have placed direct energy cost responsibility on local governments, creating strong financial incentives for energy-efficient retrofits in jurisdictions where electricity expenses are a significant line item for municipal budgets. Such institutional shifts often determine whether demand is driven by capital-budget upgrades or by operational-expenditure optimization, and the report distinguishes between these procurement logics where relevant.
At the engineering level, the definition of market-ready LED street lighting continues to evolve. High efficacy remains table stakes, but the market increasingly rewards fixtures that combine low-glare optics, surge protection, modular serviceability, and asymmetric light distribution tailored to specific roadway geometries. These technical attributes are no longer niche differentiators; they are becoming default expectations for competitive bids in advanced procurement environments.
Competitive Arena and Recent Product Developments
The competitive landscape of the LED street lighting market is characterized by a mix of established multinational lighting manufacturers, specialized roadway luminaire producers, and regional players with strong distribution footprints. The overall market concentration profile indicates a moderately consolidated ecosystem, with a significant share of revenue clustered among leading firms, while still leaving meaningful room for specialized entrants and regional strongholds. This structure matters because it shapes bidding dynamics, specification loyalty, and the pace at which new product architectures gain acceptance in municipal and utility procurement channels.
Several companies anchor the competitive conversation through product breadth, smart-control integration, and municipal project credibility. Acuity Brands, headquartered in Atlanta, continues to advance LED roadway luminaires and integrated control platforms tailored to street and roadway applications. Signify Holding, based in the Netherlands, positions connected urban infrastructure systems alongside a comprehensive portfolio of road and street LED luminaires. Eaton Corporation, with a Dublin headquarters, supplies LED cobrahead and roadway luminaires focused on high-efficacy illumination for municipal projects. Cree Lighting, operating from North Carolina, concentrates on high-efficiency LED street and roadway fixtures for municipal and transportation use. LEOTEK emphasizes energy-efficient LED street light fixtures and citywide upgrade pathways. Evluma, headquartered in Seattle, contributes energy-efficient roadway luminaire series aimed at utilities and municipalities. TRT Lighting, based in the United Kingdom, offers configurable LED street and highway lantern ranges. ZGSM, operating from China, focuses on high-efficacy cobrahead-style LED street lights with tool-free maintenance concepts. Schréder, rooted in Belgium, provides full-spectrum outdoor lighting solutions including LED street luminaires for urban infrastructure.
Recent product activity illustrates how competition is intensifying around serviceability, optical precision, and environmental robustness. In February 2026, Evluma introduced a new roadway luminaire series spanning multiple lumen packages, engineered with modular architecture, elevated surge protection thresholds, and low-glare optical design. In January 2026, ZGSM announced a cobrahead LED street light series emphasizing high lumen-per-watt performance, asymmetric light distribution, tool-free maintenance, and recognized certification for road and urban applications. These launches are not isolated product news; they signal competitive emphasis on architectures that reduce total cost of ownership, simplify field replacement, and meet tighter photometric expectations.
The full study goes further by mapping each key player’s positioning, channel strengths, technological emphasis, and likely strategic moves across the forecast period. Because detailed competitive benchmarking and share sensitivity analysis form a core part of the proprietary intelligence package, the complete player-level evaluation is presented within the full report. The objective at the overview stage is to make clear that competitive advantage in this market is increasingly defined not only by luminaire performance, but by the ability to bundle efficient hardware with service models, control ecosystems, and specification support that aligns with municipal procurement realities.
What the Full Study Delivers: A Practical Blueprint for Decision-Makers
A market overview establishes direction; a rigorous market study provides execution-grade intelligence. The complete LED Street Lighting Market report is structured to support a range of operational and strategic use cases, from capital allocation modeling and product roadmap planning to pricing strategy and regional market entry assessment. Its design prioritizes actionable clarity over abstract market narrative.
Inside the publication, readers will find a comprehensive historical reconstruction of market valuation, a forward-looking forecast model with transparent assumption logic, and segment-level analysis that ties demand drivers to procurement behavior and technology substitution patterns. The study integrates competitive profiling with recent product and market developments, allowing readers to interpret announcements not as isolated events but as indicators of strategic priorities within the forecast period. Supply-side considerations, including material cost sensitivities and engineering differentiation trends, are evaluated in the context of margin sustainability and procurement timing. Regulatory and policy dynamics are selectively incorporated where they materially alter demand structures or ownership responsibility models.
To support comparative analysis and scenario planning, the report also includes market concentration indicators and structural assessment frameworks that help subscribers understand how value is distributed across the competitive field. This enables more precise questions: which subsegments command stronger pricing power, where retrofit pipelines create near-term volume opportunities, and how the convergence of controls and lighting hardware changes specification influence. By embedding these dimensions in a single structured reference, the study reduces the lead time required to move from market sensing to strategic action.
Translating Intelligence into 2026 Decision Confidence
Entering 2026, the strategic questions facing businesses in and around the LED street lighting market are becoming sharper. How should production capacity be aligned with regional demand concentration? Which product attributes will define competitive relevance beyond baseline efficacy? Where do retrofit cycles outpace new installations, and how should that rhythm influence sales planning? How should supply chain exposure to critical input costs be managed without ceding specification competitiveness? The answers to these questions depend on a clear, structured reading of where the market has been, what forces are currently reshaping it, and how demand is likely to accumulate across the coming forecast years.
This report introduction is intended to demonstrate the analytical depth and strategic orientation of the full market study without prematurely disclosing the granular segmentation, regional revenue splits, application-level breakdowns, and detailed competitive benchmarking that constitute the core intelligence deliverables. For organizations that depend on precise market visibility to guide investment, procurement, and product strategy, that deeper layer is precisely where the operational value resides.
The LED street lighting market is not simply expanding; it is reorganizing around efficacy, controls integration, material economics, and policy-driven procurement incentives. Businesses that interpret those forces through a structured, forward-looking framework will be better positioned to allocate resources with confidence and to anticipate competitive shifts rather than merely react to them. The complete market research publication offers that framework in full, translating macro trajectory and competitive complexity into decision-ready intelligence for the 2026–2032 planning horizon.
For detailed analysis of this topic, please visit the official page: LED Street Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Food Service Equipment Market to Hit $66.59B by 2032 at 7% CAGR
By PW Consulting, 2026-09-07
The 2026 Food Service Equipment Market: Strategic Imperatives for Investment, Innovation, and Competitive Positioning
The global food service equipment market stands at a pivotal inflection point as it enters 2026. Over the past half-decade, the industry has transformed from a cyclical, hardware-driven sector into a strategically complex ecosystem shaped by labor economics, regulatory mandates, energy efficiency requirements, and rapid consolidation. For operators, manufacturers, distributors, and institutional investors, navigating this landscape requires more than top-line revenue forecasts. It demands a disciplined, data-grounded understanding of where capital will flow, which product categories will command premium margins, and how competitive dynamics will reshape market access over the next seven years.
Disposable Medical Catheter Reprocessing Market
PW Consulting’s newly released Food Service Equipment Market research report is designed to meet that exact need. Drawing on a rigorous historical baseline spanning 2020 through 2025 and projecting forward through 2032, this study provides the strategic architecture required to make high-confidence decisions in a market characterized by both durable growth and structural disruption. The following insights outline the macro trajectory, competitive tensions, and operational forces that will define the sector in 2026 and beyond, while signaling the depth of intelligence available in the full report.
Test Fixture Kit Market
Macro Trajectory: Growth, Resilience, and the 2026–2032 Expansion Arc
The market has demonstrated remarkable resilience across a volatile period marked by supply chain recalibration, input cost fluctuations, and shifting consumer dining patterns. From a baseline of approximately $29.57 billion in 2020, the sector advanced to $30.66 billion in 2021, $32.86 billion in 2022, and $37.21 billion in 2023, reflecting a pronounced acceleration as commercial kitchens reinvested in capacity and modernization. Growth continued through 2024 at $39.57 billion and reached $41.47 billion in 2025, establishing a robust launchpad for the forecast period.
Worldwide Intelligent Relays Market
Looking ahead, the market is projected to expand from an estimated $44.54 billion in 2026 to $47.46 billion in 2027, $50.85 billion in 2028, $54.99 billion in 2029, $59.9 billion in 2030, $64.14 billion in 2031, and $66.59 billion by 2032. This trajectory reflects a compound annual growth rate of 7.0% across the 2026–2032 forecast horizon. Such a growth profile signals more than steady demand; it indicates a structural expansion driven by replacement cycles, capacity upgrades, technological differentiation, and operational efficiency mandates. For strategic planners, the key question is no longer whether the market will grow, but how growth will be distributed across categories, applications, and geographies, and which players will capture disproportionate value as the pie expands.
The full report dissects these macro movements with granular sensitivity analyses, scenario modeling, and demand-driver mapping that enable decision-makers to stress-test their investment theses against multiple economic and regulatory pathways. Rather than relying on static point estimates, the study provides the analytical scaffolding to anticipate inflection points, budget cycles, and category rotation patterns that will shape procurement and production strategies throughout the decade.
Market Dynamics: The Forces Reshaping Procurement and Manufacturing in 2026
Behind the headline growth figures lies a complex web of operational forces that are actively rewiring how equipment is specified, manufactured, financed, and deployed. Three dynamics are particularly consequential for 2026 planning.
Labor Economics and the Efficiency Imperative
The cost of labor continues to climb across food service operations, with average hourly earnings in food services and drinking places rising from $19.22 in April 2025 to $20.01 in March 2026. This incremental cost pressure is not merely a line-item concern; it is a strategic trigger. As labor becomes more expensive and harder to secure, operators are increasingly favoring equipment that reduces workflow friction, automates repetitive tasks, and maximizes throughput per labor hour. The demand shift is moving beyond basic functionality toward integrated, labor-saving systems that compress prep time, streamline cooking cycles, and minimize manual handling. Manufacturers and distributors that can articulate and deliver measurable labor efficiency gains will find themselves prioritized in procurement negotiations, while those competing solely on upfront price will face margin compression.
Regulatory Frameworks and Energy Efficiency Mandates
Compliance is no longer a back-office function; it is a gatekeeper to market access and incentive eligibility. ENERGY STAR certification has become a practical requirement for commercial kitchen equipment such as dishwashers, ice machines, and fryers if operators wish to qualify for utility incentives and align with energy-efficiency standards. Simultaneously, food service equipment must satisfy electrical safety, gas safety, pressure vessel, and food contact material regulations to secure market entry across regulated jurisdictions. These requirements create a dual-layer dynamic: they raise the barrier to entry for undifferentiated products while opening competitive advantages for manufacturers that can embed compliance and efficiency into their core design philosophy. Operators, meanwhile, are increasingly factoring total cost of ownership, utility rebates, and audit readiness into their purchasing criteria, which reshapes the value proposition across the supply chain.
Input Cost Volatility and Manufacturing Economics
Steel and aluminum price volatility remains a persistent pressure point for manufacturing costs across food service equipment components. Fluctuations in these foundational materials directly affect unit economics, pricing strategy, and inventory timing. In an environment where procurement teams are simultaneously managing labor savings expectations and regulatory compliance costs, manufacturers must navigate a narrow path between absorbing input shocks and passing costs through without eroding demand. The report examines how leading players are structuring supplier agreements, diversifying component sourcing, and aligning production schedules with demand forecasting to mitigate exposure. Understanding these manufacturing dynamics is essential for investors evaluating margin sustainability and for operators seeking to anticipate pricing trends in their capital expenditure planning.
Cartographic View: The Competitive Arena and Strategic Posture of Leading Players
The food service equipment market is neither fragmented nor fully consolidated; it occupies a strategic middle ground where scale, brand architecture, channel reach, and technological differentiation determine competitive outcomes. With a CR3 of 38.5% and a CR5 of 52.6%, the market exhibits meaningful concentration at the top while preserving substantial room for specialized players and regional champions to compete on niche value propositions. This structure creates a multi-tiered competitive environment where large multinational platforms leverage cross-brand portfolios and global distribution, while focused specialists compete through category leadership, innovation velocity, and service intensity.
Several companies exemplify the strategic postures shaping the market. The Middleby Corporation operates as a leading manufacturer and distributor of commercial foodservice equipment, spanning ranges, ovens, refrigerators, dishwashers, and related kitchen systems under multiple brands for both restaurant and institutional kitchens. Its breadth positions it to capture demand across diverse operational settings while cross-selling integrated solutions. Ali Group S.r.l. brings a highly diversified global footprint, managing more than 115 brands that cover ice machines, dishwashers, coffee systems, mixers, and refrigeration solutions for commercial kitchens. This brand architecture allows the group to address segmented demand pools while aggregating scale in procurement and distribution. Hoshizaki America Inc. has built a specialist reputation around ice machines, refrigerators, and beverage equipment, with a recognized emphasis on innovation in refrigeration and ice production. Its focused portfolio illustrates how category depth can support premium positioning and repeat procurement cycles.
On the heavy-duty and high-performance side, ITW Food Equipment Group produces commercial-grade mixers, dishwashers, fryers, and related food preparation equipment, while its Vulcan-Hart subsidiary extends the portfolio into fryers, griddles, and cooking equipment. This vertical integration within a larger industrial group enables shared engineering capabilities and supply chain leverage. Welbilt Inc., now operating under Ali Group, continues to function as a global brand owner and manufacturer of foodservice equipment including ovens, steam cookers, and kitchen systems, demonstrating how brand equity can be preserved and scaled within a broader corporate structure. Standex International Corporation contributes specialized strength in commercial refrigeration and ice equipment, while Alto-Shaam Inc. has carved out a distinct position in multi-cook ovens, hot holding solutions, and foodservice heating and holding equipment. Duke Manufacturing Co. complements this landscape as a provider of commercial refrigeration, warming, and holding equipment, reinforcing the importance of temperature management and holding solutions in everyday kitchen operations.
European and specialty players add further dimension to the competitive mosaic. Rational AG is recognized for combi-steam ovens and high-performance cooking systems, targeting operators that value precision, consistency, and throughput. Carpigiani Corporation of America focuses on beverage dispensers, ice cream machines, and related equipment, addressing niche but recurring demand in dessert and beverage service. Lincoln Foodservice Products Inc. supplies cooking and food preparation equipment including fryers and griddles for commercial use, while Melitta Professional Coffee Solutions USA Inc. concentrates on professional coffee brewing and vending systems, reflecting the continued strategic relevance of beverage quality and service speed.
These profiles are not static; they are being actively reshaped by recent corporate and product developments that signal where strategic energy is being directed. Hoshizaki America Inc. launched the Valiance line of refrigeration equipment, positioned as a cost-friendly option for operators, illustrating a deliberate move to capture price-sensitive demand without abandoning the refrigeration category. Paramount Food Service Equipment Solutions opened a new state-of-the-art facility that integrates a customer experience center, warehouse, manufacturing, and culinary design lab, signaling an investment in omnichannel engagement, service speed, and application-driven design. Vulcan Equipment, within ITW Food Equipment Group, partnered with the School Nutrition Foundation to provide equipment grants for school meal kitchen upgrades, aligning commercial capabilities with public-sector funding streams and community nutrition objectives. Ali Group announced leadership appointments effective May 11, 2026, impacting North American operations for foodservice equipment, a move that underscores the strategic importance of regional execution and governance in a globally coordinated portfolio. BouMatic exhibited its Opti-Stor Heat Recovery System at the National Restaurant Association Show to demonstrate energy efficiency improvements, reinforcing the industry-wide emphasis on sustainability-linked equipment features.
The full report evaluates each of these players through a structured competitive framework that examines product-portfolio alignment, geographic reach, innovation cadence, channel strategy, and responsiveness to regulatory and labor-driven demand shifts. Rather than offering a static directory, the analysis maps where each competitor is strengthening its position, where it faces exposure, and how its strategic moves are likely to influence pricing, availability, and specification preferences across key customer segments.
Segmentation Logic: Where Demand Is Concentrating and Why
A market growing at a 7.0% CAGR over the forecast period rarely expands uniformly. Demand concentrates where operational pain points are most acute, where capital budgets are most accessible, and where regulatory or efficiency incentives tilt purchasing behavior. The report structures segmentation to reveal these concentration patterns without reducing them to simplistic share tables. Instead, it connects category-level demand to the underlying operational logic that drives specification decisions.
In the type dimension, cooking equipment represents the largest value pool at $18.45 billion, reflecting the central role of cooking systems in kitchen throughput, menu execution, and labor productivity. Storage and handling equipment follows at $8.34 billion, underscoring the ongoing importance of organization, safety, and inventory control in high-volume environments. Warewashing equipment, food holding and serving equipment, and refrigeration equipment each register around $4.16 to $4.18 billion, highlighting the balanced but essential contribution of sanitation, temperature control, and holding quality to overall operational performance. A residual Others category accounts for $2.18 billion, capturing specialized and emerging needs that often serve as leading indicators for future category expansion.
On the application side, full-service restaurants dominate at $22.04 billion, consistent with their broader equipment footprint, higher per-location capital intensity, and more complex kitchen layouts. Quick-service restaurants follow at $11.04 billion, a segment where speed, consistency, footprint efficiency, and labor optimization are especially decisive. Caterers, hotels and clubs, and other applications collectively account for the remainder, with caterers at $4.08 billion, hotels and clubs at $4.14 billion, and others at $0.17 billion. This distribution shows how equipment demand tracks both the scale of operations and the complexity of service models, and it signals where manufacturers should focus application-specific engineering and where distributors should concentrate sales specialization.
Geographically, the market reflects a global but uneven distribution of value. Asia Pacific leads at $15.54 billion, consistent with rapid commercial dining expansion, urbanization, and modernization of food service infrastructure. Europe follows at $9.23 billion, North America at $6.38 billion, the Middle East and Africa at $5.62 billion, and Latin America at $4.7 billion. These figures point to distinct regional priorities: some markets are driven by capacity build-out and format modernization, others by replacement cycles and compliance upgrades, and still others by tourism-linked hospitality demand and institutional feeding programs. The report pairs these regional magnitudes with demand-driver narratives, regulatory profiles, and channel dynamics to help strategists calibrate market-entry priorities, localization requirements, and partnership structures.
Crucially, the study maintains a disciplined boundary around segmentation disclosure in public communications. Detailed sub-segment percentages, regional splits beyond the headline magnitudes, and application-level breakdowns are reserved for the full report to preserve analytical integrity and incentivize access to the complete intelligence package. This approach ensures that readers receive the structural logic and strategic direction while the precise quantification required for budgeting, forecasting, and competitive benchmarking remains protected within the proprietary document.
What the Report Delivers: An Operational Toolkit for 2026 Decision-Makers
PW Consulting’s Food Service Equipment Market report is built to be used, not just read. It translates macro trends and competitive intelligence into an operational toolkit that supports procurement strategy, product roadmap planning, channel optimization, and investment evaluation. The study is organized to answer the questions that senior leaders actually face when allocating capital and setting direction in a fast-moving sector.
At the foundation, the report establishes a comprehensive historical baseline and forecast architecture that spans the 2020–2025 retrospective and the 2026–2032 outlook. This structure enables users to validate internal assumptions against an externally calibrated trajectory, identify where their own demand expectations diverge from market reality, and adjust planning assumptions accordingly. The forecast is supported by scenario analysis that accounts for variations in labor cost progression, input cost volatility, regulatory enforcement intensity, and capital expenditure cycles across customer segments.
The competitive section goes beyond corporate description to deliver a strategic positioning map. It evaluates how leading manufacturers are balancing breadth versus depth, how brand portfolios are being orchestrated, how innovation pipelines align with labor-saving and energy-efficiency demand, and how recent leadership, facility, partnership, and product-launch moves are likely to influence market behavior. This analysis is particularly valuable for companies assessing potential partnership targets, distributors evaluating supplier mix, and investors gauging concentration risk and differentiation durability.
Segmentation chapters connect category and application demand to operational drivers, helping readers understand not just what is selling, but why it is selling and where future rotations are likely to occur. The report examines how equipment specification is increasingly influenced by total cost of ownership, utility incentive eligibility, labor productivity impact, and compliance readiness. It also addresses how raw material dynamics and manufacturing economics shape pricing behavior, lead times, and inventory strategy, providing a practical lens for both buyers and sellers.
Regulatory and standards content is integrated directly into the market dynamics discussion, reflecting the reality that compliance is now a market-access and competitive-differentiation issue. The study outlines how energy-efficiency certification, safety standards, and food-contact material requirements affect procurement criteria, market entry timing, and product design priorities. It also considers how reimbursement mechanisms and institutional grant programs can create structured demand pools, particularly in school nutrition and public-sector kitchen upgrade initiatives, expanding the opportunity set beyond traditional commercial channels.
Finally, the report is designed with decision-makers in mind. It provides clear frameworks for market-entry assessment, segmentation prioritization, competitive response planning, and capital allocation. It supports scenario-based budgeting for operators, product-portfolio optimization for manufacturers, and channel-strategy refinement for distributors. The objective is to convert market intelligence into actionable judgment, enabling leaders to move faster and with greater confidence in a market where timing, positioning, and specificity matter.
Strategic Takeaways for 2026 and the Forecast Horizon
As the market moves through 2026, several strategic implications are becoming increasingly clear. First, growth is real and durable, but it is being redistributed by operational pressure. Labor costs, energy mandates, and input cost volatility are not peripheral concerns; they are central determinants of which equipment categories gain preference and which suppliers win specification. Companies that can quantify and deliver efficiency, compliance, and total-cost advantages will capture disproportionate demand.
Second, the competitive structure rewards both scale and specificity. A CR3 of 38.5% and a CR5 of 52.6% indicate that leading platforms hold meaningful influence over pricing, channel access, and innovation direction, yet the presence of strong specialists ensures that category leadership, regional execution, and service intensity remain viable paths to differentiation. Strategic positioning, therefore, should be grounded in a clear choice: compete on breadth and integrated solutions, or compete on depth, innovation, and application-specific value. Attempting to do both without sufficient focus tends to dilute margin and confuse procurement positioning.
Third, regional strategy must be tailored to local demand logic. The headline geographic distribution shows where value currently resides, but the deeper opportunity lies in understanding why demand forms where it does, how regulatory and labor conditions differ by market, and which channel and partnership models best convert potential into recurring procurement. Generic global rollouts rarely outperform locally adapted strategies in this sector, particularly where compliance, service networks, and application familiarity shape purchasing decisions.
Fourth, innovation is increasingly tied to operating economics rather than feature novelty alone. Heat recovery systems, labor-saving automation, energy-efficient designs, and cost-aligned product tiers are not optional accessories; they are becoming core elements of competitive value. Recent product and facility moves across the competitive set demonstrate that manufacturers are investing in exactly these areas, and operators are correspondingly adjusting their specification criteria. The companies that can connect technological improvement to measurable operational outcomes will be best positioned to command preference and pricing power.
Accessing the Full Intelligence: The Case for Complete Market Visibility
The insights summarized here provide a credible, structured preview of the forces shaping the food service equipment market in 2026 and through 2032. They establish the macro direction, the competitive architecture, and the operational dynamics that should inform planning and investment. Yet the precision required for confident decision-making lives in the full report. Detailed segmentation quantification, scenario-based demand modeling, competitive positioning matrices, regional demand-driver narratives, and regulatory impact assessments are all packaged within the complete study to support budgeting, forecasting, market-entry evaluation, and portfolio strategy.
For executives, procurement leaders, product strategists, distributors, and investors, the difference between a general directional view and an actionable plan often comes down to access to granular, validated intelligence. The full PW Consulting report is built to deliver that advantage. It enables readers to test assumptions, benchmark positioning, prioritize segments, and align resource allocation with the market’s most probable trajectory. In a sector where timing, specificity, and execution discipline determine outcomes, complete visibility is not a luxury; it is a strategic necessity.
The food service equipment market is expanding with purpose, shaped by labor economics, regulatory requirements, input cost realities, and a competitive set that is actively reinvesting in product, facility, and governance capabilities. The organizations that will lead through 2032 are those that treat these dynamics not as background noise but as the central coordinates of strategy. PW Consulting’s latest market research provides the analytical foundation to do exactly that, and the complete report offers the depth required to transform insight into executed advantage.
For detailed analysis of this topic, please visit the official page: Food Service Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Cabin Air Quality Sensor Market to Reach $4.24 Billion by 2032
By PW Consulting, 2026-09-07
Navigating the Invisible: Strategic Imperatives in the Automotive Cabin Air Quality Sensor Market
The modern vehicle cabin has evolved from a purely transportation cocoon into a sophisticated wellness ecosystem. As automotive manufacturers pivot sharply toward electrification, software definition, and human-centric design, the air inside the vehicle is no longer an afterthought. The Automotive Cabin Air Quality Sensor Market stands at the convergence of these trends, driven by visible structural forces and aggressive deployment of advanced sensing architectures. As leaders preparing for the 2026 strategic planning cycle, understanding the trajectory of this market is not a peripheral concern; it is a core component of competitive positioning in both the passenger and commercial vehicle segments.
Photovoltaic EL Tester Market
This analysis serves as an executive preview of our comprehensive market intelligence. Drawing on historical performance from 2020 through 2025 and projecting forward through 2032, the underlying research maps a market defined by accelerating adoption, evolving regulatory pressure, and intensifying technological differentiation. The data indicates a rapidly expanding addressable opportunity, yet the precise allocation of resources, the identification of highest-value niches, and the timing of product integrations remain complex strategic decisions. We will outline the structural dynamics that define the market today, the competitive forces reshaping the landscape, and the specific intelligence our full research delivers to empower your 2026 decisions.
Worldwide Flexible Feed Packaging Market
The Macro Trajectory: From Incremental Growth to Accelerated Expansion
The market has matured significantly over the past half-decade, transitioning from early adoption cycles into a period of sustained volume growth. Historical analysis reveals a consistent upward trajectory, with industry-generated revenue climbing from approximately USD 2,040 million in 2020 to an estimated USD 2,730 million by the base year of 2025. This growth reflects not only broader vehicle production volumes but also the penetration of advanced sensing suites into mainstream platforms, replacing legacy single-function monitors with multi-parameter quality modules.
Fiber Cladding Power Stripper Market
Forward-looking projections indicate that this momentum will intensify. The market is forecast to expand to USD 2,787.45 million by 2026, and subsequently accelerate through the remainder of the decade. By 2030, the revenue baseline is projected to cross the USD 3,700 million threshold, culminating in a market size of USD 4,240 million by 2032. Structuring these projections around a compound annual growth rate of 6.98% throughout the forecast horizon, the data underscores a structural ramp rather than a transient spike. This trajectory is propelled by overlapping demand vectors: the electrification of fleets, heightened consumer awareness of indoor air quality following global health developments, and the proliferation of smart cabin architectures that treat air quality as a core vehicle function.
Strategic leaders must interpret this trajectory in the context of their own pipeline. A CAGR approaching 7% over a six-year forecast window implies that the addressable market will more than double in absolute terms. For suppliers, this signals sustained long-cycle demand but also raises the stakes for capacity planning, technological roadmapping, and supply chain resilience. For OEMs, the growth projection reinforces the need to lock in advanced sensor integration early in vehicle development cycles, as late-stage retrofitting becomes progressively more costly and technically constrained.
The Regulatory and Technical Flywheel: Why Cabin Air Quality Is Now Non-Negotiable
Market growth is not purely organic; it is structurally reinforced by a tightening regulatory and standardization environment. Since 2024, the European Union has applied in-cabin air quality standards to passenger car models, embedding air quality monitoring into the compliance framework for manufacturers selling in Europe. This regulatory baseline compels OEMs to validate cabin environments against measurable thresholds, directly fueling sensor demand across the regional value chain. Complementing this regional mandate, national-level standards such as China's GB/T 27630–2011 continue to anchor consumer and compliance expectations around specific pollutant thresholds, including formaldehyde concentration limits, reinforcing demand for precise gas and particulate monitoring in one of the world's largest automotive markets.
Beyond compliance, the technical discourse is rapidly elevating the role of cabin sensors from passive monitors to active control inputs. Recent SAE technical literature presents detailed studies on the real-time impact of varying usage conditions on automotive cabin air quality in severely polluted urban environments, highlighting the necessity of dynamic monitoring under real-world stressors. Parallel studies address adaptive HVAC strategies designed to optimize cabin thermal comfort, air quality, and energy efficiency simultaneously. Another critical line of inquiry examines vehicle interior material emissions and their contributions to overall passenger vehicle cabin air quality. Together, these technical developments signal that cabin air quality is increasingly understood as a system-level optimization problem, not an isolated sensor placement task.
This dynamic creates a powerful flywheel. Regulatory requirements establish a compliance floor, academic and industry standards raise the performance ceiling, and consumer expectations push for comfort, health, and sustainability as differentiating features. For market participants, this means the strategic question is no longer whether to integrate cabin air quality sensing, but how to do so with the precision, adaptability, and intelligence that contemporary platforms demand.
Segmentation Dynamics: Where Volume and Value Converge
The market's composition reveals distinct concentration patterns that inform strategic prioritization. In terms of sensor type, the market is anchored by a strong emphasis on particulate matter sensing, reflecting the heightened focus on fine particulate monitoring driven by urban pollution, wildfire events, and health-conscious cabin design. Gas sensing represents a substantial complementary category, addressing volatile organic compounds, formaldehyde, and broader chemical pollutant detection as vehicle interiors become more tightly sealed and HVAC systems operate in recirculation modes more frequently. Together, these two primary sensing categories define the technical core of the market, while the presence of additional sensor modalities points to ongoing diversification as cabin architectures integrate multi-parameter monitoring.
Application-wise, passenger cars account for the dominant share of sensor deployment, consistent with the broader shift toward premiumization, health features, and regulatory coverage in the consumer segment. Commercial vehicles represent a meaningful and growing secondary application domain, where air quality monitoring intersects with driver wellness, fleet compliance, and increasingly stringent operational standards. The breadth of applications across these segments indicates that cabin air quality sensing is not confined to a niche luxury tier; it is becoming a scalable requirement across vehicle classes, albeit with differentiated performance thresholds and integration complexity.
Regional dynamics further shape market opportunities. The historical and projected footprint spans mature automotive centers and rapidly industrializing markets, each presenting distinct compliance timelines, OEM consolidation patterns, and after-market integration pathways. While mature regions drive early regulatory adoption and high-margin sensor integration, emerging manufacturing hubs offer volume-driven scaling opportunities for suppliers that can align with local content expectations and cost structures. The interplay between these regional vectors means that market participants must simultaneously manage compliance-driven demand in established markets and volume-driven growth in developing ones. Our research maps these regional trajectories in detail, enabling participants to calibrate capacity, partnership, and market-entry strategies without exposure to misaligned assumptions.
Competitive Architecture: An Oligopolistic Foundation Tempered by Innovation Velocity
The competitive landscape reflects a measured concentration of market power alongside rapid innovation from both established tier-one suppliers and specialized sensor manufacturers. Analysis of market concentration indicates that the top three participants collectively command approximately 24.6 percent of market revenue, while the top five reach roughly 26.2 percent. This relatively moderate concentration suggests a market that remains open to competitive disruption, where incumbency provides advantages in scale, integration experience, and OEM relationships, but does not guarantee insulation from specialized entrants offering superior accuracy, durability, or intelligence-enabled features.
Bosch continues to anchor its portfolio with advanced cabin air quality sensors and modules purpose-built for in-cabin monitoring across passenger vehicles and electric platforms, leveraging deep systems integration expertise. Denso has advanced next-generation cabin air quality sensors with enhanced VOC detection capabilities, tailored for integration into automotive HVAC architectures where chemical pollutant awareness is increasingly prioritized. Valeo supplies smart cabin air quality sensor platforms designed for OEM integration, emphasizing real-time pollutant and particulate monitoring as a platform-level capability rather than a discrete component. Honeywell has pushed into the intelligence layer with AI-enabled cabin air quality sensors developed specifically for electric vehicles, pairing adaptive filtration with real-time analytics, a direction that aligns with the broader software-defined vehicle trend. Amphenol contributes a series of automotive cabin air quality sensors positioned around improved accuracy and durability, targeting global OEM requirements across diverse operating environments.
On the specialized sensor side, Sensirion manufactures particulate matter sensors and multi-parameter modules for in-cabin air quality monitoring, with product lines engineered for high precision and compact integration. Cubic Sensor and Instrument Co., Ltd. develops particulate matter sensors, such as the APMS-3302, emphasizing precise in-cabin PM2.5 monitoring and extended operational lifetime, an attribute that resonates strongly with commercial and high-utilization applications. Hella rounds out the competitive set with vehicle electronics and air quality sensors focused on passenger car cabin monitoring, reinforcing the linkage between cabin electronics architectures and air quality sensing.
This competitive diversity is further energized by a series of strategic moves observed throughout 2025. Honeywell introduced an AI-enabled cabin air quality sensor module for electric vehicles with adaptive filtration and real-time analytics, reinforcing its focus on intelligent air management for next-generation platforms. Sensirion announced a strategic partnership with Hyundai for the co-development of in-cabin air quality monitoring solutions for future Hyundai and Kia vehicles, illustrating how specialist sensor expertise can embed directly into global OEM roadmaps. Paragon AG secured a multi-year contract with a leading European automaker for cabin air quality sensors with deliveries beginning in 2025, demonstrating the commercialization pace in compliance-driven markets. Valeo unveiled a new smart cabin air quality sensor platform for OEM integration with enhanced VOC and particulate detection, broadening its platform offering. Amphenol launched a new series of automotive cabin air quality sensors offering improved accuracy and durability for global OEMs, underscoring the continuous performance race across the tier-one supply base.
The strategic implication for 2026 is clear: the market is not a winner-take-all arena, but it rewards participants who combine sensor accuracy, integration speed, and intelligent functionality. Suppliers that can demonstrate measurable improvements in pollutant detection, lifetime reliability, and software-enabled adaptability will strengthen their positioning as OEMs optimize cabin environments for health, comfort, and efficiency simultaneously.
Intelligence for Action: What the Full Research Delivers
A market of this complexity cannot be navigated effectively on headline figures alone. Our full research translates macro trends into structured, monetizable intelligence across multiple dimensions. The report begins with a rigorous historical reconstruction covering 2020 through 2025, providing a validated baseline for demand, pricing, and volume patterns. It then extends into a forward-looking forecast horizon through 2032, anchored by a compound annual growth rate of 6.98 percent, with detailed year-on-year projections that allow participants to align capacity, inventory, and investment timing with realistic demand curves.
Segmentation analysis forms a central pillar of the research. The report disaggregates revenue by sensor type, application, and region, revealing where growth concentrates, how value shifts across categories, and which vectors offer the most attractive risk-adjusted returns. Rather than presenting static splits in isolation, the research contextualizes each segment within the forces shaping its trajectory, including regulatory coverage, HVAC architecture evolution, electrification timelines, and OEM platform strategies. This segmental intelligence enables participants to prioritize development resources, refine go-to-market plans, and anticipate demand migration as vehicle architectures and compliance regimes evolve.
Competitive intelligence is delivered through detailed company profiles that map each major participant's headquarters, product portfolio direction, technical emphasis, and market positioning. Beyond static profiles, the research integrates a curated timeline of recent developments, capturing product launches, partnership announcements, contract awards, and platform unveilings throughout 2025 and into the 2026 planning window. These developments are analyzed for strategic signal: which companies are moving into AI-enabled features, which are locking in multi-year OEM commitments, which are expanding platform breadth, and which are emphasizing durability and accuracy for global deployment. This dynamic competitive view helps participants anticipate moves by rivals, identify partnership opportunities, and assess the risk of displacement in specific application or regional segments.
The research also embeds the regulatory and standards environment directly into market dynamics analysis. It tracks the EU's in-cabin air quality standards for passenger car models, the continued relevance of national-level concentration limits, and the evolving technical discourse captured in SAE technical papers on real-time pollutant impact, adaptive HVAC strategies, and interior material emissions. By treating regulation and standardization as active drivers rather than background context, the report equips participants to forecast compliance-driven demand shifts, understand where technical benchmarks are rising, and identify the performance thresholds that future platforms will need to meet.
Finally, the report is structured to support concrete 2026 decisions. It addresses questions that strategic teams face daily: Where should we allocate R&D resources to capture the highest-value sensing capabilities? Which OEM relationships and platform cycles present the most actionable near-term opportunities? How should we position around particulate versus gas sensing as regulatory and consumer priorities shift? Which regional markets offer the most favorable mix of growth, compliance tailwind, and competitive accessibility? By answering these questions with data-driven segmentation, competitive movement analysis, and forecast-grounded scenario framing, the research reduces ambiguity and supports more confident resource allocation.
Strategic Horizons for 2026 and Beyond
As the Automotive Cabin Air Quality Sensor Market moves through its forecast growth phase, the strategic stakes will only intensify. The convergence of electrification, smart cabin architectures, health-centered consumer expectations, and active regulatory frameworks means that cabin air quality is transitioning from an optional feature to a foundational system requirement. Participants that treat this shift as a long-cycle strategic opportunity, rather than a short-term volume play, will be best positioned to capture value across the forecast horizon.
The detailed intelligence within this market research is designed to convert that complexity into actionable clarity. It provides the segmentation depth, competitive movement tracking, regulatory anchoring, and forecast structure needed to support capacity planning, product roadmapping, partnership strategy, and market-entry decisions. The headline trajectory, a market moving from approximately USD 2.73 billion in 2025 toward over USD 4.24 billion by 2032 at a compound annual growth rate of 6.98 percent, frames the opportunity. The full report translates that frame into the specific, segment-level, competitor-aware, and region-contextualized intelligence that leadership teams require to move decisively in 2026.
The cabin of the future will be measured not only by how it moves, but by the air it delivers. Understanding who is shaping that measurement, where demand will concentrate, and how regulatory and technical standards will redefine performance thresholds is essential for any organization seeking durable advantage in the automotive sensing landscape. The full research provides that understanding in a form built for immediate strategic use.
For detailed analysis of this topic, please visit the official page: Automotive Cabin Air Quality Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fatigue Machine Market Hits $483.41M in 2025, Projected 6.2% CAGR to $731.77M by 2032
By PW Consulting, 2026-09-07
Decoding the Fatigue Machine Market: Strategic Intelligence for 2026 and Beyond
The fatigue testing equipment landscape is undergoing a quiet but profound transformation. No longer confined to laboratory backrooms or compliance checklists, fatigue machines now sit at the center of product longevity strategies, materials innovation roadmaps, and regulatory readiness frameworks. For engineering directors, procurement leaders, and strategy teams operating in 2026, the question has shifted from which equipment to purchase to how fatigue testing capabilities should be integrated into enterprise-wide reliability, sustainability, and time-to-market functions. This market research report examines that shift through a structured, decision-ready lens. It synthesizes historical trajectories, forward-looking projections, and competitive movements into a cohesive intelligence asset designed for boardroom relevance, not just technical reference.
CPP Propulsion System Market
The 2026 Inflection Point: Why Strategic Timing Matters Now
The fatigue machine market has demonstrated consistent expansion across the 2020–2025 historical window, with revenue growth reflecting sustained demand from industries that depend on cyclic-load validation for safety, performance, and compliance. Over that five-year span, the market moved from the mid-three hundreds million range toward the upper four hundreds, establishing a foundation that is now accelerating into the forecast period. The projected trajectory from 2026 through 2032 suggests a market that is compounding at a meaningful pace, with revenue expected to reach and surpass the seven hundred million threshold by the end of the forecast window. This is not a sector defined by marginal growth. It is a sector where capital allocation decisions made today determine whether organizations are preparing infrastructure for incremental demand or for a structural reorientation of testing requirements.
Hose Fabrication Systems Market
Several forces are converging to make this period strategically decisive. First, the coverage of fatigue testing is expanding beyond traditional metals and structural components into composite systems, additively manufactured parts, and battery-adjacent material assemblies. Second, the pressure to demonstrate long-term durability is intensifying across aerospace platforms, automotive programs, and construction applications where lifecycle validation increasingly shapes procurement and certification outcomes. Third, input cost volatility and competitive pricing pressure are compressing margins for broader suppliers, favoring providers with integrated supply chains, modular architectures, and the ability to deliver consistent specification-aligned performance. For enterprises evaluating testing capacity, these conditions create a narrower window for indecision. Underinvestment risks validation bottlenecks and compliance delays, while opportunistic investment without strategic alignment risks overcapacity in low-growth segments.
High-end Compact Digital Cameras Market
The forecast period’s growth path reflects a market that is not merely expanding in size but also changing in composition. Demand is being shaped by evolving standards, the broadening of materials portfolios, and the need for testing systems that can accommodate both routine quality confirmation and advanced developmental evaluation. Organizations that understand this shift early will be better positioned to align equipment roadmaps with engineering priorities and to use fatigue testing as a source of competitive differentiation rather than a back-office compliance expense.
What This Research Delivers: A Practitioner’s Map of the Market
This study is designed to move beyond generic market description and deliver actionable intelligence across multiple decision dimensions. The report architecture is organized to support both top-down strategic planning and bottom-up evaluation of testing capabilities. It combines quantitative sizing with qualitative assessment of competitive behavior, technological evolution, and demand drivers, offering a balanced view of where the market stands and where it is headed.
At the core of the analysis is a comprehensive revenue assessment that traces historical performance across the 2020–2025 base years and extends through the 2026–2032 forecast horizon. The report embeds these figures within trend interpretation rather than isolated tables, helping readers understand not just what the market has done, but why inflection points matter for investment timing, capacity planning, and demand forecasting. Growth drivers are examined in relation to industry adoption patterns, while constraints are assessed against the operational realities of procurement budgets, supply chain complexity, and compliance-driven equipment selection.
Segmentation is presented with strategic context rather than mechanical pie-sharing. The analysis breaks down the market by region, type, and application in a way that highlights where demand concentration is emerging and where cross-segment interactions are reshaping buying behavior. Rather than stopping at static shares, the report explores how segment dynamics reflect broader technical and regulatory trends. For example, frequency-based categorization is assessed in the context of testing requirements for different materials, load regimes, and validation purposes. Regional patterns are examined through the lens of industrial maturity, standards environments, and adoption cycles, allowing readers to infer where near-term procurement activity may be strongest and where longer-term development investment may be required. Application-side coverage is analyzed in relation to durability priorities and testing intensity across sectors such as automotive, aerospace, construction, medical, and laboratories and research institutes, as well as additional end-use categories that contribute to overall market growth.
The report also includes a detailed competitive landscape assessment built around major participants in the fatigue testing equipment space. Company profiles are evaluated across manufacturing scope, technology orientation, product modularity, and end-market alignment. The analysis distinguishes between firms with broad, integrated system portfolios and those with more specialized or regional positioning. This is accompanied by an assessment of market concentration, providing insight into how consolidated the sector is and what that means for pricing dynamics, supplier negotiation, and technology access.
Beyond sizing and segmentation, the study integrates current technical and institutional developments that are shaping purchasing decisions. These include recent symposia and standardization activity, product launches that point toward next-generation testing capabilities, and high-profile test program completions that illustrate the practical scale of fatigue validation in demanding programs. These developments are not treated as side notes; they are used to interpret the trajectory of standards adoption, sensor technology relevance, and the growing importance of testing infrastructure for advanced applications.
Taken together, the report provides a framework for evaluating fatigue machine investments in terms of engineering objectives, compliance needs, and commercial timing. It is structured to help leaders answer practical questions: Which machine categories are gaining traction and why? Where does specification compliance constrain or accelerate procurement? Which competitive profiles are best positioned for margin resilience under pricing pressure? How should organizations think about capacity expansion in the context of evolving demand patterns?
Competitive Landscape: Scale, Specialization, and the Battle for Procurement Relevance
The fatigue machine market is characterized by a mix of established multinational providers, specialized testing system developers, and regional manufacturers with growing technical capabilities. This structure creates both opportunity and complexity for buyers. On one side, a concentrated set of major participants commands significant share and influences expectations around reliability, calibration, servicing, and compliance support. On the other, specialized and regionally focused firms continue to compete through modularity, cost structures, and application-specific configurations. For enterprises selecting equipment, the strategic question is less about identifying a single dominant name than about matching provider capabilities to internal requirements, lifecycle support needs, and long-term testing roadmaps.
Among the broader incumbent set, several firms anchor expectations around high-cycle, low-cycle, and thermo-mechanical fatigue applications across demanding engineering sectors. Companies with strong instrumentation heritage and widely recognized testing platforms often compete on integration depth, standards alignment, and cross-industry validation experience. Their relevance is particularly pronounced in environments where testing programs must span multiple material classes and loading conditions while maintaining a consistent compliance posture. At the same time, modular and expert-driven system developers contribute to the market by emphasizing compliance-friendly architectures and configurable testing platforms. These offerings can be attractive in settings where flexibility, repeatability, and alignment with recognized testing methodologies are central procurement concerns.
A parallel competitive dynamic is visible among manufacturers offering dynamic fatigue systems, vibrophore-based solutions, and automated testing configurations for metals, composites, and elastomers. This segment reflects the growing importance of composite durability and high-throughput evaluation in contemporary materials development. In the electric vehicle and advanced mobility context especially, testing infrastructure is increasingly tied to battery-adjacent material validation and structural durability assessment. Recent product introductions in this area indicate a shift toward higher load capacity and biaxial capability, suggesting that the market is moving toward equipment that can support more complex fatigue conditions than single-axis or conventional configurations.
Eastern manufacturing presence is also an important part of the competitive picture. Providers based in China continue to expand their coverage of servo-hydraulic anchorage systems, industrial fatigue machines, and computer-controlled universal testing equipment. Their positioning often combines technical capability with competitive pricing and rapid deployment options. For cost-sensitive procurement teams or organizations building regional testing capacity, these participants can offer pragmatic alternatives, particularly where applications emphasize cyclic stress and vibration measurement under practical industrial conditions. The strategic implication is not that buyers should default to either premium global incumbents or value-oriented regional suppliers, but that competitive evaluation should be framed around total cost of ownership, support infrastructure, specification compatibility, and alignment with internal testing volume and complexity.
Market concentration data indicates that a relatively small group of participants accounts for a meaningful share of revenue, with the top three and top five holding substantial portions of the market. This concentration has multiple consequences. It suggests that pricing and technology expectations are partly shaped by a handful of influential suppliers, while also meaning that broader competitive pressure often emerges at the margins through specialization, regional execution, and application-specific innovation. In an environment where input cost volatility and pricing pressure are constraining margin expansion, scale capability and integrated supply chains become increasingly important. Manufacturers with stronger procurement leverage, broader component access, and more efficient production processes may be better positioned to protect margins while still delivering competitive equipment. For buyers, this reinforces the value of evaluating supplier resilience as part of purchasing decisions.
Market Dynamics: Standards, Sensors, and the Push Toward Certified Reliability
One of the most consequential forces shaping fatigue machine demand is the ongoing evolution of testing standards, quality expectations, and regulatory guidance. Fatigue testing is increasingly embedded in assurance frameworks that connect materials performance to product safety, lifecycle planning, and certification outcomes. In that environment, procurement is being structured toward equipment that can demonstrably support specification-compliant testing, traceable results, and consistent evaluation across program cycles. This trend favors suppliers who can align machine capability with recognized testing methodologies and who can demonstrate that their systems support the documentation and repeatability demanded by engineering and quality organizations.
Standards-related activity provides useful signals about where the market is heading. Recent symposia focused on sensor technologies for fatigue, fracture, and mechanical testing indicate a growing emphasis on measurement precision, signal fidelity, and instrument integration. As fatigue testing becomes more sophisticated, the performance of the machine depends not only on the actuator and frame but also on sensor quality, data acquisition, and interpretation workflows. The practical result is that buyers are increasingly evaluating fatigue systems as part of broader testing ecosystems rather than as isolated mechanical assets. This has implications for service requirements, calibration practices, software integration, and long-term upgradability.
Guidance related to fatigue and fracture control for additively manufactured parts is also relevant to the strategic outlook. As additive manufacturing moves beyond prototyping into production-adjacent applications, fatigue behavior becomes a central concern. Testing requirements for these materials often differ from conventional wrought components, requiring equipment and methods that can accommodate unique microstructures, residual stress patterns, and defect sensitivity. The implication for fatigue machine demand is not simply more testing, but more diverse testing demands within the market. That diversification can influence segment growth patterns, shape configuration choices, and create opportunities for manufacturers whose systems can flexibly support advanced materials evaluation.
At the same time, evolving quality standards and regulatory expectations are influencing procurement choices across sectors. Where testing is tied to certification or safety-critical validation, buyers tend to prioritize verified performance, standards alignment, and vendor credibility. Where testing is more developmental, flexibility, throughput, and responsiveness may matter more. The strategic challenge for enterprises is to avoid treating these contexts as uniform. Noise exists between them: margin pressure, cost volatility, and competitive pricing can push organizations toward cost reduction, but compliance and reliability requirements can pull in the opposite direction. Successful procurement strategies are those that acknowledge both pressures and design equipment selection around them.
Where the Market Is Heading: Strategic Questions for 2026 Decision-Makers
The fatigue machine market in 2026 presents a rare combination of growth visibility and structural complexity. The revenue trajectory suggests a market that will continue expanding, but the value of that expansion depends on how organizations interpret demand drivers, segment dynamics, and competitive positioning. The most important strategic questions are not about whether the market is growing, but about how growth is distributed, what it is being driven by, and which capabilities will matter most as testing requirements evolve.
One central question concerns alignment between equipment capability and future application mix. As testing extends into new materials, more complex loading scenarios, and higher-throughput evaluation, organizations need to determine whether current fatigue infrastructure will remain relevant or whether upgrades, reconfiguration, or new procurement will be necessary. This is not only a technical question; it is an investment timing question. Buying too late can create validation delays, while buying too broadly can tie up capital in underutilized capacity. The report is designed to help leaders assess those trade-offs with a clearer view of demand concentration and segment momentum.
Another strategic issue is supplier selection under margin pressure. In a market where pricing competition and input cost volatility can constrain profitability, not all participants will be equally resilient. Some will compete on integrated supply chain efficiency, others on modularity, and others on regional responsiveness or specialized application support. For buyers, this means procurement strategy should account for more than sticker price. It should incorporate servicing, calibration, upgrade paths, compliance support, and technology roadmaps. The report’s competitive and concentration analysis is structured to support that kind of evaluation by clarifying where market power sits and how different participants create value.
A third question relates to the role of testing in broader organizational strategy. Fatigue testing is increasingly connected to durability claims, lifecycle performance, materials selection, and product assurance. As a result, the equipment used for fatigue evaluation can have implications beyond engineering labs, extending into program planning, risk management, and market positioning. Organizations that treat fatigue testing as an isolated function risk missing opportunities to use it as an enabler of faster development cycles, stronger compliance posture, and more defensible durability narratives.
Why This Report Is Built for Action, Not Just Observation
This market research is intended to serve as a decision-support resource for leaders who need to convert market intelligence into operational and strategic choices. It brings together historical performance, forecast direction, segmentation context, competitive mapping, and dynamic developments in a format that can be used for capital planning, supplier evaluation, capacity strategy, and market positioning. By keeping the analysis anchored in practical adoption drivers and procurement realities, the report helps readers move from awareness of market growth to judgment about where to invest and how to prioritize.
The value of the study lies not only in what it discloses at the headline level, but in how it connects quantitative direction with competitive and technical context. It provides the framing necessary to understand why certain segments matter, why certain providers stand out, and why certain developments are meaningful for future demand. This is the kind of intelligence that supports internal alignment, sharpens procurement conversations, and reduces the risk of strategic decisions made on incomplete market understanding.
Access the Full Intelligence Asset
The executive overview above is designed to demonstrate the scope, depth, and decision orientation of the full Fatigue Machine Market research. It establishes the strategic context and shows how the study integrates market sizing, segmentation interpretation, competitive profiling, and dynamic market signals into a unified intelligence framework. The complete report builds on this foundation with detailed sizing across the forecast horizon, deeper segment-level analysis, structured competitive evaluation, and actionable implications for procurement, investment, and capability planning.
For teams that need a full view of revenue paths, market share context, segmentation patterns, and provider-level positioning, the full research deliverable provides the granularity required to support high-stakes decisions in 2026 and beyond. The complete analysis is available through the source page and is recommended for leaders who need more than directional insight and are preparing to act on the fatigue machine opportunity with precision.
For detailed analysis of this topic, please visit the official page: Fatigue Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Radar Level Transmitters Market to Hit 894 Million by 2032, CAGR 5.69%
By PW Consulting, 2026-09-07
Navigating the Radar Level Transmitters Market: Strategic Intelligence for 2026 and Beyond
The industrial instrumentation landscape is undergoing a decisive shift. As process industries face mounting pressure to enhance operational safety, comply with tightening environmental regulations, and optimize asset utilization, level measurement technology has moved from a commodity consideration to a strategic enabler. Radar level transmitters, once relegated to niche high-performance applications, are now central to modern automation architectures across oil and gas, chemical processing, water and wastewater management, and bulk solids handling. Our latest market research, the Radar Level Transmitters Market report, delivers a comprehensive, data-grounded view of this evolving landscape. This overview outlines the structural forces shaping the market through 2032, examines the competitive dynamics among leading manufacturers, and explains why accessing the full analysis is essential for executives making capital allocation and product portfolio decisions in 2026.
Worldwide Dual Plane Air Intake Market
Market Trajectory: A Decade of Compounding Growth and Structural Transformation
The radar level transmitter sector has demonstrated resilient expansion over the past half-decade, reflecting both cyclical industrial recovery and secular adoption drivers. Revenue climbed from approximately 425.0 million USD in 2020 to 606.11 million USD in 2025, a trajectory that underscores sustained demand across both contact and non-contact technologies. The momentum is projected to continue through the forecast horizon, with the market expected to reach 622.3 million USD in 2026 and expand further to 894.0 million USD by 2032. These figures translate to a compound annual growth rate of 5.69 percent across the 2026 to 2032 period, indicating steady, investment-grade expansion rather than speculative hype.
Worldwide Landscape Transformers Market
It is important to recognize that this growth is not merely a function of rising unit volumes. The market is being reshaped by technological maturation, regulatory cascades, and shifting application preferences. The transition from legacy ultrasonic and differential pressure solutions to radar-based measurement is accelerating in sectors where safety, environmental accountability, and precision are non-negotiable. Our report quantifies these shifts without obscuring them behind aggregate averages, providing decision-makers with the granularity needed to align procurement strategies, capacity planning, and R&D roadmaps with where demand is genuinely forming.
Digital Solar Power Irradiance Meters Market
Technology Architecture: Contact Versus Non-Contact Paradigms
The radar level transmitter market bifurcates into two broad technology philosophies: contact-based guided wave systems and non-contact radar architectures. Each serves distinct operational profiles, and the balance between them is evolving as end-users reassess total cost of ownership, maintenance burdens, and application flexibility.
Contact solutions, typically deployed as guided wave radar, remain favored in scenarios where direct signal coupling to the medium is advantageous, such as high-viscosity fluids, aggressive chemical environments, or precise interface measurements between immiscible liquids. These systems benefit from physical probe contact, which can reduce signal ambiguity in complex mixtures, but they also introduce mechanical considerations related to probe selection, coating, and cleaning. Non-contact variants dominate a substantial share of the market and are further divided into pulsed radar and frequency-modulated continuous wave (FMCW) approaches. Pulsed radar systems have long been valued for their robustness in standard industrial environments, while FMCW technology is increasingly associated with higher resolution, superior noise rejection, and more sophisticated signal processing across broader operating ranges.
Our segmentation analysis captures the revenue balance between these technology families and highlights where growth concentration is forming. Rather than presenting static splits, the full report evaluates how product roadmaps, certification pathways, and application migration are redistributing share between contact and non-contact categories. For engineering procurement teams, this distinction matters because technology selection is rarely a one-size-fits-all decision; it is a function of medium characteristics, vessel geometry, environmental constraints, and integration requirements. Understanding where each architecture is gaining traction enables more disciplined specification practices and reduces costly specification mismatches.
Application-Driven Demand: Liquids, Slurries, Interfaces, and Solids
Level instrumentation demand is fundamentally application-led. The radar level transmitter market reflects this reality through distinct consumption patterns across liquid handling, slurry and interface measurement, and bulk solids applications. Liquid measurement continues to anchor a significant portion of global demand, driven by tank gauging, process vessel control, and custody transfer-adjacent monitoring in sectors that require reliable, repeatable readings under variable temperature and pressure conditions. Slurries and interface measurement present a more specialized but high-value segment, where the ability to distinguish between layers, handle entrained solids, and maintain accuracy despite dielectric variability is critical. Solids measurement, meanwhile, represents a substantial and growing application area, particularly as industries managing powders, granules, and aggregated materials seek to replace manual inventories and unreliable point-level sensors with continuous, non-contact radar solutions.
The interplay between these application segments is not static. Shifting processing requirements, modernization of aging facilities, and the push toward digitalized monitoring are altering where end-users prioritize investment. Our research dissects these application flows in detail, showing how demand is distributed and where growth vectors are intensifying. Crucially, the full report does not simply aggregate application volumes; it connects application trends to procurement timing, specification trends, and regional industry rhythms, giving stakeholders a practical view of where near-term opportunities and substitution risks are concentrated.
Regulatory and Operational Catalysts Reshaping Deployment Economics
Market expansion in industrial instrumentation is frequently catalyzed by forces external to pure commercial demand. In the radar level transmitter sector, regulatory evolution and operational safety mandates are playing an outsized role in accelerating adoption and influencing technology selection. European regulatory environments, for instance, have increasingly mandated advanced overfill protection, prompting operators to replace ultrasonic gauges with 80 GHz radar solutions that offer superior reliability and reduced false-alarm risk. In parallel, methane-emission rules in Europe are requiring tighter tank-gauging accuracy, which directly favors high-precision radar sensors capable of delivering consistent performance under challenging atmospheric and temperature conditions.
Certification activity has also become a meaningful market signal. In the United Kingdom and broader European context, the achievement of MCERTS Class 1, WRAS, and Ex ia ATEX certifications for smart compact radar level sensors has opened pathways for deployment in water, wastewater, and hazardous applications that were previously constrained by compliance requirements. In the United States, regulatory clearance of W-band sensors for process use has helped unlock scale economies, gradually eroding historical price premiums and expanding the addressable base for advanced radar measurement. These developments are not isolated announcements; they represent structural changes in what is permissible, preferred, and economically viable across different jurisdictions and end-use environments.
The full report systematically maps these regulatory and certification dynamics to their commercial consequences. For executives responsible for compliance strategy, capital planning, or product positioning, understanding the timing and geographic concentration of these mandates is essential. A technology that is merely attractive today can become indispensable tomorrow if a regulatory threshold raises the cost of non-compliance or eliminates viable alternatives.
Competitive Landscape: Diversification, Differentiation, and the Battle for Share
The radar level transmitter market is characterized by a broad competitive field spanning multinational instrumentation conglomerates, specialized sensor manufacturers, and regional players with strong footholds in particular applications or geographies. The combined influence of leading participants is significant, with the top three firms accounting for approximately 28.5 percent of revenue and the top five collectively representing about 53.4 percent. This concentration indicates a market where scale, brand equity, and technological depth confer meaningful advantages, but where fragmentation still leaves substantial room for differentiated positioning and niche leadership.
Among the most prominent competitors, Emerson Electric Co. continues to leverage its Rosemount series, including non-contacting radar level transmitters such as the 3408 and 5408 models for liquids, solids, and interface measurement, complemented by smart diagnostics and wireless capabilities. Endress+Hauser Group maintains a strong presence through its Micropilot and FMR series 80 GHz radar level transmitters designed for process liquids, slurries, and solids, with emphasis on high precision and hygienic certifications relevant to regulated industries. Siemens AG competes with its SITRANS series, integrating advanced signal processing and IoT connectivity for industrial process monitoring, while ABB Ltd. supplies guided wave and non-contact models including the LWT series for total and interface level measurement in demanding environments.
VEGA Grieshaber KG has expanded its visibility with the VEGAPULS series of 80 GHz radar level sensors, offering Bluetooth connectivity, compact form factors, and certifications relevant to water, wastewater, and hazardous applications. KROHNE Messtechnik GmbH contributes the OPTIWAVE series, designed for liquids and solids with high accuracy and integration into process control systems. Other significant participants shape the market from different strategic angles: Honeywell International Inc. embeds radar level transmitters within its broader automation portfolio; Yokogawa Electric Corporation supplies level measurement solutions tailored to chemical, oil, and gas industries; and Ametek, Inc., through Magnetrol International, offers radar transmitters such as the Pulsar line for liquids, slurries, and solids. Schneider Electric SE incorporates radar instrumentation into its industrial automation range, while Automation Products Group (APG) targets hazardous locations with explosion-proof pulse radar transmitters such as the TRUE ECHO series.
Regional and application-focused manufacturers further enrich the competitive fabric. KOBOLD Instruments, Inc. provides non-contact 80 GHz radar transmitters with straightforward installation characteristics. Nivelco Process Control Ltd. supports liquid and solids measurement with 80 GHz FMCW offerings such as the PiloTREK series. FINE-TEK Co., Ltd., WIKA Alexander Wiegand SE & Co. KG, SOR Inc., Georg Fischer Ltd., L&J Technologies, Inc., Matsushima Measure Tech Co., Ltd., and Pepperl+Fuchs SE all contribute to the market through distinct product lines, application expertise, or regional strengths. This breadth of participation ensures continuous pressure on performance, pricing, and feature sets, but it also requires buyers and competitors alike to look beyond headline brand recognition and assess fit against specific technical and commercial criteria.
Recent Product and Certification Activity: Signals of Strategic Direction
Competitive dynamics in instrumentation markets are often best understood through recent product launches, certification milestones, and catalog expansions. These events reveal where companies are placing their bets, which performance attributes they believe will command preference, and how they are responding to regulatory and end-user pressures. Several developments in 2025 illustrate the current rhythm of innovation and market repositioning.
SKE introduced its new 80 GHz SKE series radar level transmitter as the flagship of the SK-E series, emphasizing integrated molding technology and improved performance. This launch underscores the continued industry-wide migration toward higher-frequency architectures and the pursuit of manufacturing efficiencies that support competitive pricing without sacrificing reliability. VEGA achieved MCERTS Class 1, WRAS, and Ex ia ATEX certifications for its VEGAPULS smart compact radar level sensors, reinforcing its eligibility for UK water, wastewater, and hazardous applications and highlighting the strategic value of compliance-driven market access. KROHNE expanded its OPTIWAVE lineup with the introduction of the OPTIWAVE 1500 series, including models 1520 and 1540, reflecting ongoing efforts to broaden application coverage within established product families. Emerson launched the Rosemount 1208 wireless non-contacting radar level transmitter, aimed at simplified installation in utility and process applications, which points to a growing emphasis on deployment speed, reduced integration friction, and operational convenience. Nivelco released its 2026 product catalog featuring new PiloTREK WP–200 and WT–300 compact 80 GHz FMCW radar level transmitters, signaling continued investment in compact, high-frequency solutions for liquids and solids.
These milestones are not isolated news items; they form a pattern. The market is consolidating around 80 GHz technologies, expanding certification coverage for regulated and hazardous environments, and increasingly prioritizing installation simplicity and wireless integration. For buyers, the implication is that specification decisions should account not only for current performance but also for ecosystem compatibility, certification status, and likely product lifecycle support. For competitors, the challenge is to differentiate in a space where baseline performance expectations are rising and where regulatory alignment can determine market access.
Strategic Implications for 2026 Decision-Makers
The radar level transmitter market in 2026 is best understood as a convergence point between mature industrial demand and accelerating technological and regulatory change. For executives across procurement, engineering, product management, and corporate strategy, several implications warrant close attention. First, investment timing matters. As regulatory mandates and certification expansions reshape permissible and preferred solutions, the cost of waiting for incremental price improvements can be outweighed by the operational and compliance advantages of early alignment with emerging standards. Second, technology selection must be application-disciplined. The coexistence of guided wave, pulsed non-contact, and FMCW architectures means that value is created by matching the right technology to the right medium, vessel, and environment rather than defaulting to a single brand or category. Third, competitive positioning is increasingly tied to integration and certification capabilities. Wireless options, Bluetooth connectivity, IoT compatibility, and verified compliance credentials are no longer optional differentiators in many segments; they are becoming baseline expectations.
Beyond near-term procurement and specification considerations, the broader market arc suggests that stakeholders should plan for sustained demand growth while preparing for continued fragmentation in competitive tactics. Scale players will continue to leverage portfolio breadth and global service networks, while specialized manufacturers will seek advantage through application-specific engineering, rapid certification, and regional responsiveness. In such an environment, intelligence that connects market size trends to technology preferences, application flows, regulatory timing, and competitor behavior is not a luxury; it is a requirement for avoiding misallocated capital and missed positioning opportunities.
Why the Full Radar Level Transmitters Market Report Is Essential
The overview presented here is intentionally selective. It captures the structural narrative of the market, highlights the forces shaping demand, and identifies the competitive themes that matter for 2026 planning. But the decisions that executives face are rarely made on narrative alone. They require precise segmentation, historical trend validation, forward estimates by category, and an understanding of where concentration and dispersion are likely to shift over the forecast horizon. Our full Radar Level Transmitters Market report delivers that level of operational intelligence.
Within the complete study, readers will find detailed segmentation analysis spanning technology types and application categories, with revenue distributions and trajectory insights that reveal where growth is accumulating and where substitution risk is most pronounced. The report provides regional market sizing and growth context, enabling stakeholders to calibrate expectations by geography without relying on generic global averages. It includes competitive profiling that goes beyond descriptive summaries to examine each major participant’s strategic posture, product emphasis, and likely response patterns in a market where certification, frequency migration, and integration capabilities are increasingly decisive. Recent developments and regulatory catalysts are analyzed not as standalone events but as inputs to market timing and share-shift scenarios.
Most importantly, the report is structured to support concrete actions. Procurement teams can use the segmentation and application data to refine specification criteria and tender strategies. Product and R&D leaders can use the technology and competitive analysis to prioritize development investments and identify white space. Regional and sales leaders can use the geographic and regulatory mapping to anticipate demand shifts and align go-to-market tactics. Executives can use the overall market trajectory and concentration data to frame capital allocation, M&A screening, and portfolio balance decisions with a clearer view of where the market is heading.
Accessing the Intelligence Required for Decisive Action
The radar level transmitter market is large enough to attract attention and complex enough to reward preparation. Its growth trajectory, technology evolution, regulatory sensitivity, and competitive breadth make it a sector where informed decisions can compound into durable advantage. Yet the full value of any market study is realized only when decision-makers have access to the underlying detail that connects high-level trends to actionable insight. The complete Radar Level Transmitters Market report provides that depth: verified historical context, forecast estimates through 2032, segmentation breakdowns that illuminate demand concentration, and competitor analysis that clarifies who is gaining traction, how, and why.
For leaders responsible for 2026 planning, this research offers more than a snapshot of market size. It offers a framework for interpreting where level measurement demand is forming, which technologies are becoming preferred in regulated and high-performance environments, and how competitors are positioning themselves around frequency advancement, certification, wireless integration, and application specialization. Accessing the full report transforms an industry overview into a decision-ready asset, giving your organization the confidence to specify, invest, and compete with a clearer view of the market’s actual shape and direction.
For detailed analysis of this topic, please visit the official page: Radar Level Transmitters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Medical Pressure Transducers Market to Hit $535M by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-07
Navigating the Next Wave: Strategic Insights from the Medical Pressure Transducers Market Forecast 2026–2032
The medical device landscape is shifting beneath the feet of even the most established players. As we move deeper into the decade, the Medical Pressure Transducers Market stands at a critical inflection point, driven by aging demographics, the proliferation of minimally invasive procedures, and an increasingly complex regulatory environment. For executive leadership, procurement officers, and R&D teams, understanding the trajectory of this segment is no longer optional—it is a prerequisite for sustained competitiveness.
DOE Homogenizer Market
At PW Consulting, we have just completed a comprehensive analysis of this sector, synthesizing five years of historical data with a robust forecast extending through 2032. This article serves as a strategic primer, outlining the macro forces shaping the industry and demonstrating why access to our full dataset is essential for informed decision-making in 2026.
Worldwide Hydraulic Vacuum Trailer Market
The Macro Trajectory: Growth Amidst Complexity
The numbers tell a story of steady, resilient expansion. Valued at approximately 280 million USD in 2020, the global market for medical pressure transducers has demonstrated consistent upward momentum, reaching an estimated 360 million USD by the base year of 2025. This growth reflects not merely inflation but genuine increases in procedural volume and the adoption of advanced monitoring technologies across critical care settings.
Super Sharp AFM Probe Market
Looking forward, the forecast period from 2026 to 2032 suggests a compound annual growth rate (CAGR) of 6.5%. This trajectory projects the market size to expand from roughly 379.5 million USD in 2026 to over 535 million USD by 2032. Such a trajectory indicates a maturing market that is still capable of significant expansion, likely fueled by emerging economies integrating advanced hemodynamic monitoring into standard care protocols and the ongoing replacement of legacy equipment in established markets.
However, raw revenue figures only scratch the surface. The value lies in understanding the velocity of adoption across different device configurations and clinical applications. Our full report dissects these layers, revealing which specific transducer channels are gaining traction and how application-specific demands are reshaping supply chain requirements. While the aggregate numbers provide a comforting sense of stability, the nuances within the segmentation hold the keys to tactical advantage.
Competitive Landscape: Concentration and Innovation
The market structure presents a moderately concentrated environment. Our analysis indicates that the top three competitors hold a combined market share of approximately 28.5%, while the top five extend this concentration to 35.2%. This fragmentation suggests that while dominant players exist, there is ample room for niche innovation and regional strongholds to thrive. The presence of established giants alongside specialized manufacturers creates a dynamic ecosystem where pricing power, technological differentiation, and regulatory compliance all play pivotal roles.
Key Players Shaping the Horizon
Several corporations define the current competitive terrain, each leveraging distinct technological strengths:
- Edwards Lifesciences Corporation (Irvine, California, USA): A dominant force in hemodynamic monitoring, notably through their TruWave disposable pressure transducers. Their focus remains on delivering high-fidelity data for invasive monitoring scenarios, though recent regulatory scrutiny, such as the FDA MAUDE Adverse Event Report in December 2025 regarding TruWave, highlights the operational risks inherent in high-volume disposable device markets.
- Smiths Medical (Minneapolis, Minnesota, USA): Competes strongly with the TranStar disposable pressure transducer systems. Their strategy emphasizes integration and reliability within broader hemodynamic monitoring ecosystems, catering to hospitals seeking streamlined workflows.
- ICU Medical, Inc. (San Clemente, California, USA): Offers the Transpac integrated and disposable pressure transducer systems, positioning their products as critical care essentials. Their focus on critical care settings aligns with the high-acuity demand drivers identified in our forecast.
- Merit Medical Systems, Inc. (South Jordan, Utah, USA): Provides the Meritrans pressure transducers and the Meritrans DTXPlus disposable systems. Their portfolio appeals to providers looking for cost-effective yet reliable solutions for routine and specialized monitoring.
- Argon Medical Devices, Inc. (Plano, Texas, USA): Specializes in pressure monitoring lines and transducer kits for interventional procedures. Their offering is particularly relevant as interventional cardiology and radiology volumes continue to climb.
These companies are not static. Recent developments signal shifting alliances and technological adaptations. For instance, in September 2025, Shanghai Draeger Medical Instrument Co., Ltd. received FDA 510(k) clearance for an IBP transducer adapter cable compatible with major brands including Argon, BD, Ohmeda, Edwards, and Smiths. This move underscores a trend toward interoperability and compatibility, potentially disrupting traditional bundled purchasing models and empowering hospitals to mix and match components based on cost and performance criteria.
Market Dynamics: Regulatory Headwinds and Supply Chain Realities
The path to revenue growth is paved with regulatory and operational challenges that cannot be ignored. The industry context has changed significantly since 2021, and the implications for market entrants and incumbents alike are profound.
Regulatory Tightening and Cost Implications
Compliance is becoming a heavier burden. The average certification timeline for the EU Medical Device Regulation 2017/745 has increased from 9 to 18 months between 2021 and 2025. Concurrently, associated costs have risen by 35 to 50%. For manufacturers of medical pressure transducers, this means longer time-to-market and increased capital expenditure just to maintain market access in key European regions. This regulatory friction acts as a barrier to entry for smaller players while forcing established companies to reassess their R&D timelines and pricing strategies.
In the United States, FDA Class II clearance governs the global blood pressure transducers market, ensuring strict adherence to biocompatibility and calibration accuracy. While this ensures patient safety, it also standardizes the baseline for competition, pushing differentiation toward performance stability and ease of use rather than mere regulatory approval. Furthermore, ISO 80601-2-34 governs transducer performance, yet actual calibration practices differ by hospital, manufacturer, and even individual clinician. This variability introduces quality control complexities that manufacturers must address through robust training materials and device design that minimizes user-dependent error.
Supply Chain and Material Considerations
The production of pressure transducers relies on a specialized supply chain. Raw material procurement involves the pouring of materials like silicon, stainless steel, specialty alloys, and plastics from various suppliers. Volatility in these material markets, coupled with the need for high-precision manufacturing, means that cost control is not simply a function of economies of scale. It requires strategic supplier relationships and potentially vertical integration to mitigate risks associated with material shortages or price spikes. Organizations that secure their supply chains for these critical inputs will hold a distinct advantage in maintaining margins as the market grows.
Application Drivers: Where the Demand Lives
Understanding where pressure transducers are deployed is crucial for forecasting demand. The market is propelled by several key clinical applications, each with unique growth drivers:
- Blood Pressure Monitoring: As a cornerstone of patient assessment in perioperative and critical care settings, this application continues to drive significant volume. The shift toward continuous invasive monitoring in high-risk surgeries sustains demand for high-accuracy transducers.
- Respiration Systems: The integration of pressure monitoring within respiratory care, particularly for ventilated patients, represents a substantial portion of usage. Trends in respiratory therapy and the lingering effects of recent global health events continue to influence the specification and adoption rates of transducers in this segment.
- Infusion Pumps: Pressure transducers play a vital role in ensuring the correct delivery of fluids and medications via infusion pumps. As smart pump technology evolves, the requirement for integrated pressure sensing solutions grows, linking transducer sales to broader capital equipment upgrades.
- Other Applications: Niche uses in specialized monitoring and interventional procedures contribute to the tail end of the market. While smaller in aggregate, these segments often offer higher margins and opportunities for specialized product development.
Each of these applications responds differently to economic conditions, clinical guidelines, and technological advancements. A breakdown of regional demand patterns reveals further complexity, as healthcare infrastructure maturity varies significantly across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Our detailed analysis maps these regional nuances, helping strategists identify where to prioritize sales force deployment and marketing spend.
Why the Full Report Matters for 2026 Decision-Making
In an era of data overload, strategic intelligence must be actionable. This article provides a high-level overview, but the decisions facing your organization require precision. Are you evaluating a potential acquisition in the critical care space? Do you need to benchmark your pricing strategy against the top five competitors? Is your supply chain resilient enough to withstand the material procurement challenges outlined above?
The full PW Consulting Market Research report on Medical Pressure Transducers delivers deep-dive segmentation data, granular regional forecasts, and detailed competitor profiling that goes beyond the summaries provided here. It includes:
- Historical and Forecast Volume Analysis: Beyond revenue, understanding unit volumes helps in capacity planning and inventory management.
- Segment-Level Growth Rates: Identify which transducer channels or applications are outpacing the market average to focus innovation resources effectively.
- Regulatory Impact Modeling: Assess how the increased EU MDR timelines and FDA clearance requirements might affect your product launch schedules and budget forecasts.
- Competitive Intelligence: Deep insights into the product pipelines and strategic moves of Edwards Lifesciences, Smiths Medical, ICU Medical, Merit Medical, Argon Medical, and emerging regional players.
The market is projected to reach over 535 million USD by 2032, but the share of that pie allocated to your company depends on the quality of your strategy today. Misreading the regulatory landscape, underestimating supply chain costs, or misallocating resources to stagnant segments can erode profitability even in a growing market.
Conclusion: Positioning for the Forecast Period
The Medical Pressure Transducers Market offers a compelling growth narrative, supported by a 6.5% CAGR and a clear trajectory toward 2032. However, the environment is characterized by heightened regulatory scrutiny, supply chain intricacies, and a competitive field where interoperability and compatibility are becoming new battlegrounds. The recent developments, such as new FDA clearances for adapter cables and adverse event reports for established products, illustrate that no player is immune to operational risks or competitive disruption.
For leaders navigating 2026 and beyond, superficial market sizing is insufficient. You need the granularity that reveals the hidden drivers of value and the specific pressures that will test your operational excellence. PW Consulting's comprehensive research is designed to provide that clarity, empowering your team to make data-backed decisions that align with the realities of the evolving healthcare landscape.
To access the complete dataset, detailed segmentation splits, and the full competitor analysis, we invite you to explore our latest report. The insights contained within are tailored to support strategic planning, investment analysis, and market entry strategies for the coming years.
For detailed analysis of this topic, please visit the official page: Medical Pressure Transducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


