



Category: Machinery & Automotive
Strategic Intelligence in the Small Angle X-ray Scattering Market: A 2026 Decision-Maker's Guide
The global landscape for Small Angle X-ray Scattering (SAXS) is undergoing a structural transformation. As laboratory-scale characterization becomes increasingly intertwined with industrial metrology, pharmaceutical development, and nanoscale material engineering, organizations that depend on precise structural analysis must look beyond short-term procurement cycles. This analysis introduces a comprehensive market study designed to equip executives, procurement leaders, and R&D strategists with the intelligence required to navigate the 2026 to 2032 horizon with confidence.
Underground Mine Positioning System Market
The SAXS ecosystem is no longer confined to academic curiosity. Standardization frameworks, detector innovations, and integrated software workflows have elevated the technique into a routine operational capability for enterprises handling polymeric systems, biological macromolecules, advanced ceramics, and semiconductor architectures. Understanding where capital should be deployed, which vendors warrant long-term partnership, and how regional demand vectors are shifting has become a strategic imperative rather than a tactical inventory exercise.
Live Line Insulator Tester Market
This market research publication is structured to serve as both a diagnostic tool and a forward-looking planning instrument. It synthesizes historical market behavior, forecasts demand trajectories through the end of the decade, and deconstructs the competitive dynamics that will define purchasing leverage, technology roadmaps, and service-level expectations. The following sections outline the strategic architecture of the study and demonstrate why its findings are directly applicable to organizational decision-making in 2026 and beyond.
Preschooler Magazines Market
Market Trajectory and Structural Growth Signals
Any credible strategic assessment begins with a disciplined examination of historical performance and the momentum it implies for the forecast window. The data assembled in this study traces the evolution of the SAXS market from 2020 through the base year of 2025, then projects forward across a seven-year horizon extending to 2032. The trajectory reveals a market that has moved from moderate expansion into a phase of accelerated, structurally supported growth.
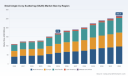
Historical figures show a consistent upward path. Revenue climbed from approximately 110 million USD in 2020 to roughly 124 million in 2021, followed by a modest leveling around 125 to 129 million through 2022 and 2023. A more pronounced inflection occurred in 2024, with revenue reaching 151.11 million, before advancing to a base-year valuation of approximately 170 million in 2025. This progression is not merely a recovery from prior slowdowns; it reflects broadening adoption across multiple industrial and research segments, improved instrument reliability, and the normalization of SAXS as a standardized analytical workflow rather than a niche capability.
The forecast period carries this momentum forward at a compound annual growth rate of 6.8 percent. By 2026, the market is projected to reach approximately 183.98 million USD, with further expansion to 190.38 million in 2027, 201.74 million in 2028, and 224.26 million in 2029. The curve continues through 2030 at 240.61 million, 2031 at 251.51 million, and arrives at a projected 266.01 million by 2032. These numbers convey more than size; they indicate a market in which demand breadth is deepening and where the rhythm of capital investment is shifting from sporadic, grant-dependent purchasing to recurring, production-aligned deployment.
For enterprise decision-makers, the implication is clear. Planning assumptions built on pre-2024 behavior will underestimate both the speed of adoption and the breadth of application-driven purchasing. Organizations that integrate this growth trajectory into their technology roadmaps, facility planning, and vendor negotiations will be better positioned to secure favorable terms, align internal timelines with supply-side readiness, and avoid the cost premiums that accompany reactive procurement.
Segmentation Dynamics and Demand Architecture
The market does not expand uniformly. Growth is carried by distinct product categories, application domains, and geographic clusters, each with its own adoption incentives, procurement cycles, and performance expectations. This study maps those segments in detail, but the strategic takeaway for 2026 is already evident from the aggregate structure: the SAXS market is product-heavy in hardware, application-diverse in demand, and geographically distributed in ways that create both concentration and emerging opportunity pockets.
On the product side, instruments dominate the revenue composition, reflecting the capital-intensive nature of the category and the continuous demand for upgraded detector systems, temperature-controlled stages, and multi-modal scattering configurations. Software and accessories form smaller but strategically important shares, representing the recurring and workflow-enabling layers that determine how effectively an organization can convert raw scattering data into actionable insight. The relative weight of these categories matters for budgeting strategy: capital allocation decisions must account not only for instrument acquisition but also for the software licenses, calibration standards, and supplementary accessories that determine operational throughput and data quality.
Application demand is similarly layered. Material science remains a foundational driver, given the technique's utility in characterizing porosity, particle morphology, and hierarchical structures. Life sciences and nanotechnology continue to expand as biological SAXS workflows mature and as nanoscale fabrication requirements become more rigorous. Pharmaceutical development and food science round out the application landscape, each contributing distinct validation requirements, regulatory contexts, and throughput expectations. The breadth of these applications means that a supplier or procurement strategy optimized for one domain may underperform in another, reinforcing the need for segment-specific intelligence rather than generic market assumptions.
Geographic distribution adds another strategic dimension. Demand is not concentrated in a single dominant region; instead, it spans multiple advanced and emerging markets, each with its own laboratory infrastructure, regulatory environment, and industrial priorities. North America, Europe, and Asia Pacific collectively account for the bulk of current activity, while Latin America and the Middle East and Africa represent smaller but developing footprints. For organizations evaluating expansion, partnership, or localization strategies, the relevant question is not simply where demand exists today, but where the growth rate and application alignment make near-term investment most efficient.
Crucially, this study provides the full segmentation detail necessary to support those judgments, but the precise percentage distributions, regional values, and application-level revenue splits are reserved for the complete report. That deliberate aperture ensures that decision-makers engage with the full analytical framework rather than relying on partial figures that may be misinterpreted outside their proper context.
Competitive Landscape and Vendor Positioning
The SAXS market is contested by a group of established manufacturers and specialized innovators, each pursuing distinct positioning strategies across instrument design, software integration, application focus, and geographic service networks. Market concentration, as captured in this study, indicates that a relatively small number of players command a substantial share of revenue, creating an environment where competitive differentiation is driven by technical capability, workflow completeness, and after-sales support as much as by price.
Anton Paar GmbH, headquartered in Graz, Austria, has built a recognized presence through laboratory SAXS and WAXS systems such as the SAXSpoint 500 and SAXSpoint 700 platforms. These instruments incorporate advanced detectors, temperature-controlled stages, and GISAXS capabilities aimed at nanoscale material characterization. The company's recent activity underscores a deliberate emphasis on user education and hands-on competency: in April 2026, Anton Paar jointly hosted the fifth edition of the SAXS and XRD excites symposium with Graz University of Technology, featuring workshops on the SAXSpoint 700 and 500 systems, followed by a dedicated SAXS workshop offering practical training in data collection and analysis. This pedagogical investment is strategically significant because it signals a vendor orientation toward long-term adoption, not merely capital equipment sales.
Bruker Corporation, based in Billerica, Massachusetts, USA, provides the D8 ADVANCE platform for SAXS and WAXS measurements alongside the DIFFRAC.SAXS software suite for one-dimensional and two-dimensional data analysis, with GI-SAXS capabilities for surface nanostructure evaluation. The integration of instrument hardware with a dedicated analysis environment reflects a broader industry trend toward reducing workflow friction. Bruker's continuing emphasis on software-supported interpretation aligns with the operational reality that data usability often determines whether a system becomes a sustained production asset or a limited-use research tool.
Malvern Panalytical Ltd, headquartered in Malvern, United Kingdom, has advanced its Empyrean Nano edition X-ray scattering platform, which supports USAXS, SAXS, bio-SAXS, WAXS, and PDF measurements on a single goniometer-based system. In May 2025, the company conducted a webinar introducing the Empyrean Nano edition platform for combined SAXS, WAXS, and ultra-SAXS measurements, emphasizing multimodal flexibility. For organizations that need to cover multiple scattering regimes without managing separate instrument footprints, this type of configuration offers a compelling operational argument.
Rigaku Corporation, based in Akishima, Tokyo, Japan, supplies SAXS and WAXS solutions and TSAXS instruments with a notable focus on semiconductor three-dimensional metrology and critical-dimension analysis. Its recent technical publications reinforce that orientation: in February 2025, the Rigaku Journal Winter 2025 issue featured SAXS shape metrology for 3D semiconductor devices using T-SAXS, and in November 2025, the company published a technical note detailing the TSAXS instrument for precise 3D semiconductor device structure metrology using the Rigaku XTRAIA CD series. These developments indicate a vendor strategy aligned with high-precision industrial metrology, where measurement reliability and application-specific validation carry substantial weight.
Xenocs SAS, located in Grenoble, France, produces the Xeuss Pro, Xeuss 3.0, Nano-inXider, and BioXolver SAXS, WAXS, and GISAXS systems, paired with high-performance detectors and integrated software. The XSACT Pro software, highlighted in 2025, supports comprehensive SAXS and WAXS data analysis for advanced research applications. Xenocs' product breadth across laboratory and biological configurations positions it for users seeking flexibility across research and applied workflows.
Shimadzu Corporation, headquartered in Kyoto, Japan, provides SAXS and WAXS instruments and systems for structural characterization in materials science and nanotechnology applications, reinforcing Japan's continued presence in precision analytical instrumentation. Hecus X-ray Systems GmbH, based in Austria, specializes in compact SAXS instruments and systems for laboratory nanoscale analysis, an orientation that appeals to organizations prioritizing footprint, accessibility, and focused functionality.
The competitive picture that emerges is one of differentiated specialization rather than undifferentiated commoditization. Some vendors emphasize multimodal platforms and software integration; others focus on industrial metrology, biological applications, or compact laboratory usability. For buyers, the strategic task is to match these positioning differences to internal use cases, service expectations, and future expansion plans. The complete study provides a deeper competitive mapping, including the structural factors that shape vendor leverage, switching costs, and technology migration paths.
Regulatory, Standardization, and Technical Dynamics
Market growth does not occur in a vacuum. It is shaped by standardization frameworks, calibration practices, and data-analysis conventions that influence both vendor development and user adoption. In the SAXS domain, these elements have become increasingly important as the technique moves from exploratory research into regulated and production-adjacent environments.
One significant reference point is ISO 17867:2020, which specifies a standardized method for applying small-angle X-ray scattering to estimate mean particle sizes in the 1 nm to 100 nm range. The standard also frames SAXS as a method for determining particle size distributions within that same size window. For organizations operating under quality systems or requiring traceable characterization, such standardization reduces ambiguity and increases confidence in method transferability across sites and instruments.
Calibration infrastructure is equally important. NIST Standard Reference Material 3600 provides an absolute intensity calibration standard based on glassy carbon for SAXS instruments. The availability of such reference materials supports comparability across systems and over time, which is essential when measurement results inform product development, process control, or cross-laboratory collaboration. Vendors and end-users alike benefit from a calibration environment that makes performance verification more routine and less interpretive.
Software and data-analysis standards further shape the market's evolution. Platforms such as Bruker's DIFFRAC.SAXS support one-dimensional and two-dimensional visualization and interpretation of scattering patterns, while Xenocs' XSACT Pro software enables comprehensive SAXS and WAXS data analysis for advanced research applications. As scattering workflows become more integrated, the ability to manage data consistently, reproduce analysis steps, and transition between visualization and quantitative interpretation becomes a competitive differentiator for both instrument providers and adopting organizations.
These dynamics matter strategically because they affect more than technical compliance. They influence procurement criteria, validate return on investment, and determine how quickly a new instrument can be integrated into existing workflows. A market study that ignores standardization and calibration realities would miss a significant part of the purchasing decision logic. This research incorporates those factors so that executives can evaluate not only what a system costs, but how readily it fits into a standardized, auditable, and repeatable analytical environment.
Strategic Relevance for 2026 Decision-Making
The value of this market study for 2026 lies in its ability to convert macro-level growth signals into operational and strategic clarity. The forecast horizon, extending to 2032, allows organizations to plan beyond the immediate budget cycle and to assess whether current technology choices will remain aligned with anticipated demand patterns. The historical record, meanwhile, provides a reality check on how quickly adoption can accelerate once certain technical and standardization thresholds are crossed.
Several decision contexts make this intelligence particularly relevant. First, capital planning for analytical instrumentation increasingly requires multi-year visibility. A system purchased today will often remain in service for many years, and its usefulness depends on how well it aligns with evolving application needs, software support, and vendor service availability. Understanding the broader market trajectory helps organizations time acquisitions, evaluate lease-versus-buy options, and anticipate when upgrade cycles may become necessary.
Second, competitive positioning among vendors creates both risk and opportunity. In a market where concentration is meaningful, buyers may face limited alternatives in certain high-performance categories, but they may also find leverage in adjacent segments where multiple viable solutions exist. The study's competitive analysis is designed to help organizations distinguish between categories where differentiation is genuine and categories where alternatives are largely interchangeable.
Third, application diversification is changing procurement logic. As SAXS usage expands across material science, life sciences, nanotechnology, pharmaceuticals, and food science, organizations must decide whether to invest in platforms optimized for a single dominant application or in more flexible systems that can serve multiple workflows. That choice has implications for throughput, training, validation burden, and long-term capital efficiency. The segmentation architecture in this study provides the context needed to make that choice deliberately rather than by default.
Finally, geographic strategy matters for organizations considering service coverage, localization, or cross-site standardization. Demand is distributed across multiple regions, and the practical realities of installation support, parts availability, regulatory expectations, and user training differ by market. A market-level view helps executives align laboratory strategy with regional operating conditions rather than assuming uniform conditions across sites.
What the Full Study Delivers
This introduction is intentionally framed as a strategic preview. It establishes the growth environment, outlines the segmentation logic, and characterizes the competitive and standardization dynamics that shape purchasing and planning decisions. The complete report builds on this foundation with detailed segmentation analysis, forecast breakdowns, vendor profiles, and operational intelligence that supports more granular decision-making.
The full study is designed to be immediately usable for a range of strategic tasks: technology roadmapping, vendor evaluation, budget forecasting, market entry assessment, and competitive benchmarking. It brings together historical data, forward projections, company-level developments, and standardization context in a single analytical structure so that decision-makers do not need to assemble these inputs from disparate sources.
Those seeking the complete segmentation values, regional revenue distributions, application-level projections, and the full competitive profiling will find them in the comprehensive report. That scope is deliberately positioned as the definitive reference for organizations that need to move from general market awareness to specific, numbers-backed action plans.
Conclusion
The SAXS market in 2026 is defined by a combination of sustained growth, expanding application breadth, and increasing maturity in standardization and workflow integration. The projected trajectory from a 2025 base of approximately 170 million USD toward a 2032 estimate of roughly 266 million USD, at a compound annual growth rate of 6.8 percent, signals an environment in which analytical capability is becoming more central to both research and industrial operations.
For executives and strategists, the practical task is not simply to acknowledge growth, but to translate it into procurement timing, vendor selection, application alignment, and geographic planning decisions that hold up over the full forecast horizon. This market study is built to support that translation. It offers the depth required to reduce uncertainty and the structure needed to turn market intelligence into disciplined corporate action.
The detailed segmentation, competitive mapping, and forecast decompositions that underpin these conclusions are available in the full report, where the complete analytical framework can be used to inform precise, evidence-based decisions across the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Small Angle X-ray Scattering (SAXS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV Market for Construction, Agriculture & Mining Hits $428M in 2025, 18.5% CAGR to 2032
By PW Consulting, 2026-09-07
Beyond the Diesel Era: Strategic Intelligence for the Electric Off-Highway Revolution
The construction, agriculture, and mining sectors stand at a decisive inflection point. For decades, diesel-powered machinery defined productivity, yet today’s regulatory mandates, carbon-neutral procurement policies, and total cost of ownership recalibrations are fundamentally rewriting operational playbooks. As the industry transitions from pilot programs to scaled deployments, decision-makers require more than anecdotal case studies or fragmented product announcements. They need rigorous, forward-looking intelligence that maps technological trajectories, competitive positioning, and regional adoption curves with precision. The newly released Electric Vehicles for Construction, Agriculture and Mining Market study delivers exactly that framework, providing a structured lens through which executives, investors, and supply chain strategists can navigate one of the most capital-intensive transitions in industrial history.
Three-stage Ball Valve Market
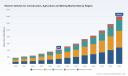
This analysis is not a static snapshot. It traces a clear growth arc: from approximately 181.56 million USD in 2020 to a projected 1,404.34 million USD by 2032, sustained by a compound annual growth rate of 18.5% across the forecast horizon. These figures reflect more than incremental replacement cycles. They signal a structural reallocation of capital toward electrification, driven by tightening emissions standards, evolving operator expectations, and the gradual commercialization of battery-electric and fuel cell platforms across heavy-duty applications. The base year of 2025 anchors the dataset in a period where early-adopter validation meets regulatory urgency, while the forward projection through 2032 captures the scaling phase where infrastructure, manufacturing capacity, and fleet turnover intersect.
Open End Blind Rivets Market
Market Architecture and the Strategic Imperative of 2026
Understanding where the market stands today requires recognizing the interplay between technological readiness, policy pressure, and operational economics. By 2026, battery-electric platforms are no longer confined to compact machinery or urban pilot sites. They are entering serial production across mid-size and heavy-duty categories, with articulated haulers, wheel loaders, and mining-grade excavators transitioning from demonstration units to commercially viable fleet assets. Parallel developments in plug-in hybrid and fuel cell architectures continue to address duty cycles where energy density, refuel speed, or grid independence remain critical constraints. The research dissects these technology pathways without oversimplifying their trade-offs, enabling procurement leaders to align equipment selection with site-specific energy availability, shift patterns, and decarbonization timelines.
Smart Ship Propeller Testing Machines Market
The forecast trajectory underscores a critical strategic reality for 2026 decision-making. As the market expands through the latter half of the decade, the margin for reactive purchasing decisions shrinks. Fleets that delay electrification planning risk locking into legacy maintenance ecosystems, facing escalating compliance costs, and forfeiting competitive positioning in bids that increasingly weight carbon footprint and noise reduction. Conversely, organizations that integrate electrification roadmaps with infrastructure investment, operator training, and supplier partnerships position themselves to capture productivity gains while meeting procurement mandates. The study’s longitudinal view equips leadership teams to model phasing strategies, balance upfront capital against lifecycle savings, and anticipate second-order effects such as grid load management, parts standardization, and dealer network adaptation.
Structural Shifts Defining Market Dynamics
Several interlocking forces are compressing the adoption timeline across construction, agriculture, and mining. Regulatory environments in the EU and UK, alongside evolving national green procurement frameworks, are elevating zero-emission equipment from optional specification to baseline requirement. Site-level environmental standards are tightening, particularly in quarrying, urban infrastructure, and enclosed mining operations where diesel particulate matter, noise, and ventilation constraints directly impact operational continuity. At the same time, corporate sustainability commitments are cascading down to contractor selection, meaning electrification is increasingly a market-access strategy rather than a purely operational upgrade.
Battery and charging infrastructure economics remain the most significant near-term friction point. The upfront cost differential between conventional and electric platforms is largely dictated by energy storage capacity, power management systems, and site-ready charging architecture. Yet this cost equation is shifting as manufacturers optimize pack integration, standardize high-voltage architectures, and introduce modular charging solutions tailored to off-highway duty cycles. The research contextualizes these dynamics by mapping where total cost of ownership advantages emerge earliest, which applications tolerate higher initial premiums due to regulatory or operational pressure, and how infrastructure partnerships can redistribute capital expenditure across fleet lifecycles.
Zero-emission mandates are not the only catalyst. The broader push toward carbon-neutral operations is reinforced by international standards and procurement policies that require demonstrable emissions reductions across project phases. Mining and construction enterprises are responding by integrating electric machinery into site development plans, synchronizing equipment turnover with grid upgrades, and aligning maintenance schedules with new powertrain requirements. Agriculture, meanwhile, is experiencing a parallel transition as electric tractors and specialized farm vehicles enter commercial channels, driven by labor efficiency, precision agriculture integration, and localized emissions restrictions. The study captures these cross-sector dynamics, illustrating how regulatory, economic, and technological variables converge differently across applications while sharing a common electrification trajectory.
Segmentation: Technology Pathways and Application Realities
Electrification in off-highway environments is not monolithic. Battery-electric platforms currently dominate commercial attention, reflecting their compatibility with stationary charging, predictable duty cycles, and rapidly improving energy density. Fuel cell variants continue to carve out niches where extended range, rapid refuel capability, or remote site logistics favor hydrogen-based energy delivery. Plug-in hybrid configurations serve as transitional architectures for applications that require blended performance during the early phases of fleet conversion. The report examines these technology branches with an emphasis on commercial readiness, operational fit, and manufacturing momentum rather than theoretical potential alone.
Across construction, agriculture, and mining, the adoption logic diverges in ways that directly influence procurement strategy. Construction sites benefit from centralized project logistics, predictable shift patterns, and increasing urban emissions restrictions that make electric excavators, wheel loaders, and backhoe loaders attractive for both compliance and community relations. Agricultural operations prioritize reliability, seasonal workload concentration, and integration with existing precision farming ecosystems, which shapes the demand for electric tractors and compact machinery designed for field versatility. Mining applications demand ruggedized platforms capable of sustained heavy-duty cycles, often under remote or grid-constrained conditions, making battery-electric haulage and excavation equipment a strategic consideration tied to ventilation savings, fuel logistics, and site decarbonization targets.
The study avoids presenting these application categories in isolation. Instead, it maps how each segment intersects with regional infrastructure readiness, manufacturer product roadmaps, and fleet replacement cycles. This structure enables readers to identify where early operational savings are most achievable, which applications face the steepest infrastructure hurdles, and how cross-segment learning accelerates broader commercialization. Detailed regional and application-level breakdowns are reserved for the full dataset, ensuring that strategic discussions remain grounded in verified figures rather than approximations.
Competitive Landscape: Leaders, Positioning, and Near-Term Movement
The competitive field reflects a blend of established heavy-equipment manufacturers, specialized electric-platform developers, and agricultural machinery producers expanding into electrified off-highway solutions. Incumbents are leveraging scale, dealer networks, and existing customer relationships to introduce battery-electric variants across excavators, loaders, articulated trucks, and mining machinery. Specialized players are concentrating on purpose-built electric architectures, often emphasizing rapid prototype-to-production cycles and integrated charging ecosystems. Agricultural manufacturers are adapting tractor platforms to electric and hybrid drivetrains while aligning with farm-level energy management and precision agriculture requirements.
Volvo Construction Equipment has emerged as a prominent reference point for full-electric portfolio expansion, progressing from compact machines to mid-size and heavy-duty platforms. Its introduction of battery-electric articulated haulers and updated wheel loader and excavator models signals a commitment to serial production rather than limited demonstrations. Partnerships focused on charging and power supply infrastructure further illustrate how leading manufacturers are extending their scope beyond the machine itself to encompass site energy readiness. Hitachi Construction Machinery continues to advance battery-powered excavators tailored for construction and infrastructure work, while simultaneously exploring human-machine interface innovations that may shape operator interaction in electric environments.
Global players such as SANY Group and Caterpillar are extending electric-drive and hybrid platforms across heavy-duty construction and mining applications, emphasizing reduced emissions and operational cost improvements at scale. Liebherr and Komatsu are reinforcing high-capacity electric excavators and articulated truck platforms for quarrying, construction, and industrial use, underscoring the industry’s movement toward heavy-duty electrification. John Deere and CNH Industrial are broadening electric loader, backhoe, and compact machinery offerings for commercial, municipal, and industrial projects, linking off-highway electrification to broader equipment ecosystems. Meanwhile, AGCO, CLAAS, Kubota, Mahindra, and Monarch Tractor are advancing electric tractors and farm vehicles that address agricultural decarbonization, operator efficiency, and next-generation precision farming needs.
Recent industry movements highlight how quickly product roadmaps are translating into commercial milestones. Unveils of battery-electric articulated haulers with serial production commencing and initial deliveries planned for the near term demonstrate that previously conceptual heavy-duty electric platforms are entering the market at scale. Simultaneous debuts of mid-size electric wheel loaders and updated electric excavators in key regions reflect coordinated launch strategies aimed at aligning product availability with demand centers. Collaborations targeting enhanced power supply and charging solutions further indicate that manufacturers are treating infrastructure enablement as a core component of adoption strategy rather than an afterthought. In parallel, zero-emission excavator introductions and prototype testing of machine voice control at major industry exhibitions suggest that electrification is converging with digitalization, creating integrated operator environments that influence purchasing decisions beyond powertrain considerations alone.
What the Research Delivers for Executive Decision-Making
The study is structured to support actionable strategy rather than passive observation. It integrates market sizing, technology segmentation, application-level analysis, and competitive profiling into a cohesive intelligence package that can be directly applied to capital planning, supplier negotiation, and fleet transition roadmaps. Readers gain access to a longitudinal view of market expansion, a structured comparison of battery-electric, fuel cell, and plug-in hybrid pathways, and an assessment of how regulatory and infrastructure variables influence adoption timing. The report also examines concentration dynamics within the competitive landscape, helping stakeholders understand where scale advantages are accumulating and how market leadership is being contested across regions and applications.
For procurement and operations leaders, the research provides a framework to evaluate total cost implications, identify applications where electrification yields the earliest operational alignment, and anticipate infrastructure dependencies before they become procurement bottlenecks. For product and engineering teams, the segmentation analysis offers context on where manufacturers are concentrating development resources, which duty cycles are driving architecture choices, and how cross-application learnings are accelerating design maturation. For investors and strategic planners, the combination of historical trajectory, forecast progression, and competitive mapping creates a basis for scenario modeling that accounts for regulatory acceleration, infrastructure deployment pace, and manufacturing scale-up timelines.
The report deliberately reserves its deepest quantitative breakdowns for the full edition. Regional revenue distributions, application-level contributions, technology-type splits, and concentration metrics are presented in integrated form within the complete dataset, allowing executives to benchmark internal assumptions against verified market structure without relying on partial proxies. This design ensures that the full research functions as a decision-grade asset rather than a high-level overview.
Forecasting to 2032: Navigating Scale, Infrastructure, and Competitive Realignment
The projected growth path toward 2032 reflects a market moving from early commercialization into broader fleet integration. As serial production expands across mid-size and heavy-duty categories, manufacturing scale, supply chain maturity, and infrastructure coordination will increasingly differentiate leaders from followers. Battery and charging cost trajectories will continue to shape procurement economics, but their impact will be mediated by site energy strategy, fleet utilization patterns, and the availability of standardized charging solutions. Regulatory momentum will likely reinforce procurement preferences for zero-emission equipment, particularly in jurisdictions where emissions targets and green procurement policies are already reshaping bidding criteria and site operating rules.
Strategic planning for the remainder of the decade requires explicit consideration of sequencing. Organizations that align machine procurement with infrastructure investment, operator training, and service-network readiness will be better positioned to manage transition risk and capture lifecycle value. Those that treat electrification as a standalone equipment purchase may encounter integration friction that delays return on investment and complicates compliance timelines. The forecast horizon in the study is designed to support this kind of phased planning by illustrating how market size evolves under sustained adoption pressure, where scaling is most probable, and how competitive positioning can shift as product portfolios mature and infrastructure partnerships become more integrated.
Conclusion: Converting Market Intelligence into Execution Advantage
The electric transformation of construction, agriculture, and mining equipment is no longer a speculative trend. It is a procurement reality, a compliance requirement, and a competitive differentiator rolled into one. The firms that succeed will be those that treat electrification as an integrated operational strategy—combining machine selection, energy infrastructure, service capabilities, and regulatory foresight into a coherent roadmap. The Electric Vehicles for Construction, Agriculture and Mining Market report provides the analytical foundation needed to build that roadmap with confidence.
To access the complete dataset, including regional and application-level breakdowns, technology-type distributions, competitive concentration metrics, and the full forecast series through 2032, explore the full report on our website. The detailed intelligence within is designed to support procurement strategy, investment planning, and competitive positioning with the precision required for high-stakes 2026 decision-making.
For detailed analysis of this topic, please visit the official page: Electric Vehicles for Construction, Agriculture and Mining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Door Handles Market Hits $3.94B in 2025, Projects 4.5% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Horizons in the Automotive Door Handles Market: Navigating Growth, Regulation, and Design Shifts
The global automotive door handle market is undergoing a period of structural transformation. What was once a mature, low-differentiation component category is now a strategic focal point for original equipment manufacturers, tier-one suppliers, and mobility startups alike. Flush-mounted exteriors, mechatronic access solutions, biometric authentication concepts, and evolving regulatory mandates are reshaping supplier roadmaps and procurement strategies. For executives planning capital allocation, supplier partnerships, and product pipeline decisions in 2026 and beyond, a rigorous, data-backed assessment of this market is no longer optional. The latest PW Consulting market intelligence briefing maps this landscape with the granularity required to support high-stakes decisions, while revealing the strategic tensions that will define competitive outcomes through 2032.
Linear Contact Position Sensor Market
This article previews the analytical depth, strategic frameworks, and decision-useful content available in our full report. It is designed to show professionals the contours of the opportunity and risk environment, and to guide readers toward the complete dataset, forecast scenarios, and actionable recommendations necessary for robust planning. Throughout, we intentionally hold back granular segmentation figures to preserve the value of the full publication, while still conveying the scale, trajectory, and structural drivers that matter for executive decision-making.
Worldwide SCADA Alarm Management Market
Macro Trajectory: Sustained Expansion Amid Design and Regulatory Shifts
Drawing on a five-year historical baseline and an extended forecast horizon, the automotive door handles market demonstrates steady, compounding growth from a base year of 2025 and projects forward through 2032. The trajectory reflects durable demand from passenger vehicle production, incremental gains from commercial vehicle platforms, and a gradual but meaningful transition toward smarter, more integrated access systems. Growth is not uniform across segments or geographies; it is shaped by regional manufacturing footprints, model mix shifts, and the adoption cadence of flush-mounted and mechatronic handle architectures.
Oil Filled Fluid Couplings Market
The headline growth rate, expressed as a compound annual growth rate across the forecast period, is moderate yet resilient. This is characteristic of an automotive component category that is increasingly influenced by platform consolidation, new product introductions in premium and mid-tier segments, and the integration of electronic access features. Importantly, the market’s expansion does not come from volume alone; it is reinforced by value migration toward higher-functioning systems, including passive entry, integrated sensors, and actuator-supported closures. For suppliers and OEMs, this means that scale advantages must be paired with engineering capability, validation rigor, and supply chain dependability.
Market leaders and challengers are vying for share in a landscape that is moderately concentrated, with a meaningful portion of industry revenue captured by a small set of established suppliers. This concentration is not static. Recent partnerships, product showcases, and concept demonstrations signal a market in motion, where incumbents are strengthening capabilities and where new technology demonstrations are beginning to influence platform requirements. At the same time, OEM qualification processes are increasingly tied to sustainability criteria, pushing suppliers to demonstrate lower-carbon production pathways and material stewardship without compromising performance or safety.
Structural Dynamics: Flush Designs, Mechatronics, and the Return of Manual Release
One of the most consequential shifts in the door handle segment is the rising prevalence of flush-mounted exterior designs across a growing share of new vehicle models. Flush hardware aligns with aerodynamic targets, contributes to cleaner exterior styling, and supports premium brand positioning. However, this aesthetic and functional shift carries engineering and manufacturing implications: precision injection molding, specialized surface coatings, and robust fastening systems are essential to preserve appearance quality, weather sealing, and long-term durability. The move toward flush handles is not simply a styling choice; it is becoming a platform-level requirement on many nameplates, elevating the role of door handle suppliers in body-side architecture and packaging.
Parallel to this design trend is the expansion of mechatronic and smart access features. Rotational flush mechanisms, parallel deployable systems, flap flush designs, and fixed configurations are being augmented with passive entry, sensor integration, and actuator-assisted operation. These features support keyless entry experiences, reduce exterior protrusions, and open pathways to contactless interaction concepts. Recent industry demonstrations have also begun exploring facial authentication and automatic door opening, hinting at a longer-term horizon where physical handles may be minimized or relocated in certain segments. Even so, safety requirements remain paramount: regulators and OEMs continue to prioritize reliable manual release pathways and fail-safe behaviors, particularly in regions with explicit mandates for emergency access.
A notable regulatory inflection point is emerging in China, where requirements for manual release hardware on electric door handles are expected to take effect for domestic sales beginning January 1, 2027. This mandate is designed to ensure emergency opening from both sides of the vehicle and has direct implications for models that otherwise rely on electronic-only or concealed handle mechanisms. The rule introduces additional cost and design complexity for manufacturers, may affect the packaging of actuators and release linkages, and is likely to influence regional product strategies, tooling decisions, and cost structures. For suppliers operating across multiple markets, reconciling segment-specific regulations with global platform efficiency becomes a core operational challenge.
Competitive Landscape: Incumbent Strength, Partnerships, and Technology Showcases
The supplier landscape is defined by a mix of long-established German and Japanese engineering houses, global dimensional and module integrators, and specialists expanding their access-system footprints. The market remains competitive, with differentiation increasingly tied to mechatronic capability, module integration, validation expertise, and the ability to support OEM-specific design language and packaging constraints.
Huf Hulsbeck & Fürst GmbH & Co. KG continues to represent a benchmark for breadth and integration, offering a full range of door handle systems—from rotational flush to parallel deployable, flap flush, and fixed designs—often paired with passive entry and sensor technologies for global OEMs. Its recent strategic partnership with Sodecia underscores a focus on strengthening supply chain resilience and innovation capacity, signaling that even market-leading positions are being augmented through collaboration and scale orchestration.
Magna International Inc. brings a module-level perspective, supplying integrated door module assemblies and SmartAccess systems that bundle mechanical and electronic door handles with actuators, regulators, and controls. Its emphasis on mechatronic door handle solutions, including recent showcases of advanced SmartAccess technologies and integrated door modules, illustrates a broader industry move toward consolidating functions within door-side architectures. This approach can reduce part count, streamline validation, and support OEMs seeking to optimize assembly complexity and serviceability.
Kiekert AG contributes deep expertise in side door locking systems, power closing actuators, and mechatronic solutions that support door handle operation and vehicle access comfort. Aisin Seiki Co., Ltd. supplies advanced door handle systems, keyless entry modules, and power closure components with a strong alignment to Toyota and other OEMs, focusing on integrated entry control technologies. U-Shin Ltd. manufactures both outside and inside door handles, lock sets, and power closure systems, emphasizing flush and smart access designs for Asian and global OEMs—a positioning that reflects the continued importance of fast-following and customizing solutions across regional model mixes.
WITTE Automotive GmbH specializes in exterior door handles, classic bow handles, and flush-mounted solutions, underpinned by advanced fastening systems that support robust assembly and tolerance management. Its August 2025 collaboration with trinamiX on a concept car featuring integrated facial authentication and automatic door opening—where traditional handles are eliminated in the B-pillar area—points to an exploratory frontier that may influence future design language and access paradigms, even as mainstream volume programs continue to prioritize proven, regulation-compliant hardware.
Minda VAST Access Systems Pvt. Ltd. rounds out the competitive picture by providing vehicle access systems and door handles for Indian and export OEMs, with a clear focus on security and mechatronic solutions. This regional capability is strategically relevant as Indian OEMs scale export ambitions and as global platforms adopt localized sourcing footprints to manage tariff exposure, logistics, and time-to-market.
Across this landscape, the combination of moderate market concentration and active partnership and product activity suggests that competition will be shaped as much by integration and qualification readiness as by unit cost alone. Companies that can demonstrate reliable performance across multiple handle architectures, support sustainability expectations, and adapt quickly to regulatory divergence will be best positioned to capture share and protect margins.
Strategic Implications for 2026 and Beyond
For executives planning in 2026, several strategic questions come to the fore. First, how should organizations balance investment in flush-mounted and mechatronic capabilities against the compliance requirements that increasingly differ by region? Second, what sourcing and partnership models best reconcile price, performance, and resilience in a moderately concentrated market? Third, how should product roadmaps accommodate both near-term manual-release mandates and longer-term access innovations such as contactless authentication and automatic opening?
On the demand side, the continued dominance of passenger vehicle applications and the steady, if smaller, contribution of commercial vehicles provide a reliable volume base. Yet value capture is increasingly linked to higher-functioning systems and integration depth. Suppliers and OEMs that treat door handles as a simple commodity risk missing the value migration occurring within door modules and access architectures. By contrast, those that align engineering, validation, and supply chain strategies with smarter access trends can build durable differentiation.
On the supply side, the market’s concentration creates both challenges and opportunities. Negotiating leverage, dual-sourcing strategies, and qualification lead times must be managed carefully, particularly for programs with aggressive launch schedules or stringent durability targets. Sustainability-driven qualification requirements also introduce a new dimension of supplier evaluation: lower-carbon processes and material choices are becoming part of the selection criteria, not merely a corporate-responsibility narrative. This raises the importance of transparent data, test evidence, and traceability across the supply chain.
What the Full Report Provides
The complete PW Consulting market research publication extends well beyond the overview presented here. It offers a structured, decision-oriented view of the sector with the kind of detail that planning teams need for scenario building, budgeting, and supplier strategy. Content includes:
- A base-to-forecast market size view spanning the historical window and the 2026–2032 projection period, with a clear explanation of the growth trajectory and the factors influencing it.
- A segmentation analysis that disaggregates the market by region, type, and application, enabling readers to understand where volume and value concentrate, and where growth is accelerating or moderating.
- An in-depth competitive landscape assessment covering leading suppliers, their capability profiles, recent activity, and strategic positioning, together with market concentration context to inform sourcing and negotiation strategies.
- A regulatory and technology dynamics section that synthesizes mandates such as manual-release requirements, the impact of flush-mounted design prevalence on manufacturing complexity, and the implications of ESG-related qualification standards for supplier selection.
- Practical frameworks for evaluating investment priorities, product portfolio alignment, and regional sourcing decisions in light of evolving design and compliance requirements.
To preserve the analytical integrity and commercial value of the publication, this introductory overview does not disclose the specific regional split, type mix, or application breakdown figures. Those data points, along with supporting tables, methodology notes, and forecast assumptions, are available in the full report. They are essential for precise segmentation planning, for comparing market opportunities across geographies and vehicle categories, and for stress-testing strategies against multiple scenarios.
Decision Use Cases for Executives and Strategy Teams
This research is designed to support a range of practical decisions. Procurement and sourcing leaders can use the segmentation and concentration analysis to evaluate dependency risks, identify alternative qualification pathways, and structure negotiations with attention to both unit economics and technical capability. Product planning teams can reference the dynamics discussion to anticipate how flush-mounted prevalence, mechatronic integration, and manual-release mandates will influence door-side packaging, cost structures, and timing. Business development and M&A teams can draw on the supplier profiles and recent activity to identify partnership targets, capability gaps, and potential consolidation scenarios.
The report also frames the market in a way that is useful for long-range planning. Because door handle architectures are increasingly tied to broader access and module strategies, decisions made in 2026 can affect program flexibility, supplier breadth, and compliance posture for years to come. By integrating market sizing, segmentation, competitive mapping, and regulatory context, the publication gives decision-makers a common set of facts and a disciplined basis for evaluating trade-offs.
Source the Complete Intelligence
The automotive door handles market is expanding with discipline, but its future shape will be determined by the interplay of design ambition, mechatronic capability, regional regulation, and supplier execution. Flush aesthetics, smart access features, and the return of manual release requirements reflect a market that is simultaneously chasing refinement and responding to safety and compliance imperatives. In this environment, strategic clarity depends on access to detailed data and structured analysis.
Readers seeking the full segmentation figures, forecast detail, competitive benchmarks, and actionable recommendations should consult the complete PW Consulting market research publication. There, the deeper quantitative and qualitative intelligence required for confident 2026 planning lives—enabling teams to move from directional understanding to precise, testable strategy.
For detailed analysis of this topic, please visit the official page: Automotive Door Handles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Capsule Filling Machines Market to Hit $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-07
Strategic Imperatives in the Capsule Filling Machines Market: Navigating Growth Through 2032
The global pharmaceutical and nutraceutical manufacturing landscape is undergoing a profound transformation, driven by accelerating demand for precise, compliant, and high-throughput encapsulation technologies. As industry leaders confront tightening regulatory frameworks, evolving product formulations, and intensifying competitive pressures, the Capsule Filling Machines Market has emerged as a critical nexus of operational efficiency and strategic investment. This analysis draws from PW Consulting’s latest comprehensive market research to illuminate the structural forces shaping the sector, offer actionable intelligence for 2026 decision-making, and frame the strategic questions that forward-looking organizations must address to secure long-term competitive advantage.
Adhesion Prevention Gel Market
Macro Trajectory and The Architecture of Growth
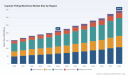
The sector’s historical performance reflects a sustained expansion trajectory. From a baseline valuation of approximately 153.44 million USD in 2020, market revenue climbed steadily through the mid-2020s, reaching 215.0 million USD by 2025. This upward momentum is projected to continue, with the market anticipated to attain 226.24 million USD in 2026 and accelerate toward 344.8 million USD by 2032. The compound annual growth rate of 6.98 percent underscores a moderate yet resilient expansion profile, one that is neither speculative nor saturated, but rather anchored in structural demand drivers across regulated manufacturing ecosystems.
Angular Contact Axial Bearing Market
This growth architecture is not uniform. It is shaped by divergent regional adoption curves, varying capital expenditure cycles, and the gradual migration of production capacity toward markets with expanding domestic pharmaceutical and supplement manufacturing bases. While specific regional revenue contributions and application-level breakdowns are detailed within the full research repository, the overarching narrative is clear: the market is consolidating around mature demand centers while simultaneously cultivating high-growth corridors that reward early-mover capital allocation and localized technical partnerships. Organizations that map their investment horizons to these geographic and application-specific inflection points will be best positioned to capture disproportionate share gains.
Piston Ring Wire Market
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The competitive environment exhibits moderate market concentration, with the top three players collectively commanding approximately 24.6 percent of global revenue and the top five holding roughly 26.2 percent. This fragmented-yet-consolidating structure creates a dynamic arena where scale, technological differentiation, and regulatory compliance capabilities determine market access and pricing power. A diverse cohort of manufacturers operates across this spectrum, each pursuing distinct value propositions tailored to specific production volumes, formulation complexities, and compliance requirements.
European engineering firms continue to anchor the high-end segment, leveraging decades of precision dosing expertise and advanced rotary or suction bowl architectures. One prominent German-based provider offers a flagship capsule filling series optimized for high-volume pharmaceutical and nutraceutical production, emphasizing precision dosing and high throughput. In Italy, multiple manufacturers have established strong footholds by delivering rotary and advanced dosing systems capable of processing up to 200,000 capsules per hour, while others focus on flexible E Series and IN-CAP platforms that accommodate powders, pellets, tablets, mini-tablets, and capsule-in-capsule configurations, all engineered to meet CE and cGMP compliance standards. A separate Italian manufacturer has expanded its automatic capsule filling portfolio with machines specifically engineered for pharmaceutical and supplement production, reinforcing the region’s reputation for high-accuracy encapsulation hardware.
Asia-Pacific and transcontinental players are increasingly shaping the mid-to-high volume segments through integrated solutions that balance operational simplicity, safety, and efficiency. An Indian-headquartered global supplier delivers integrated capsule filling systems tailored for pharmaceutical and nutraceutical applications, emphasizing reliability and streamlined operational workflows. In Japan, a Tokyo-based technology provider delivers encapsulation solutions and capsule filling equipment designed for global pharmaceutical manufacturers, reinforcing the importance of geographic proximity to advanced drug delivery research ecosystems. Meanwhile, United States-based manufacturers contribute to the domestic supply chain with USA-made capsule filling equipment and service capabilities, while a New Jersey-based firm specializes in encapsulation equipment for pharmaceutical and nutraceutical applications.
French and German packaging specialists further diversify the competitive field. A France-based entity under the Lonza Group umbrella specializes in hard capsule filling machines and encapsulation systems focused on advanced drug delivery applications. In Germany, another engineering firm develops high-efficiency capsule filling and packaging systems designed for integrated pharmaceutical production lines. Chinese and hybrid-market manufacturers also play a growing role, with several firms offering semi-automatic and industrial-grade capsule filling machines that bridge manual-automation workflows, alongside laboratory-scale and mass-production units designed for pharmaceutical and supplement manufacturing. These providers continuously refine their product portfolios, as evidenced by recent equipment upgrades aimed at improving precision and efficiency in pharmaceutical manufacturing environments.
2025–2026 Innovation Cycles and Product Lifecycle Acceleration
The past several months have witnessed a noticeable acceleration in product launches and technology showcases, signaling an industry-wide push toward human-centered design, advanced dosing combinations, and tighter weight control systems. In late 2025, one European manufacturer introduced a new platform within its E Series, featuring human-centered design principles, advanced dosing combinations, and integrated weight control systems designed to reduce batch variability and streamline operator workflows. Shortly thereafter, the same company debuted an automatic capsule filling machine at a major European trade fair, showcasing support for multiple fill types with throughput capabilities reaching 3,000 capsules per hour, alongside full CE and cGMP compliance alignment. These releases reflect a broader industry pattern: manufacturers are not merely iterating on mechanical performance but are increasingly engineering for flexibility, operator ergonomics, and real-time quality feedback.
Concurrently, other players have advanced their equipment modernization roadmaps. A notable equipment upgrade launched in mid-to-late 2025 targeted precision and efficiency improvements for a widely deployed capsule filling model, reinforcing the competitive imperative to reduce downtime, enhance dosing repeatability, and support faster changeover cycles. Such innovation cycles are particularly consequential for 2026 capital planning, as they introduce new benchmarking criteria for total cost of ownership, maintenance predictability, and integration readiness with existing packaging and inspection lines. Organizations evaluating equipment refresh cycles or capacity expansions must assess not only baseline throughput figures but also the trajectory of software-driven control systems, modular dosing adaptability, and vendor-supported compliance documentation.
Regulatory Dynamics as a Strategic Filter
Regulatory compliance has evolved from a baseline operational requirement into a strategic filter that shapes procurement decisions, vendor selection criteria, and market entry pathways. In 2026, capsule filling equipment deployed in pharmaceutical and nutraceutical production must align with stringent sanitation, reliability, calibration, inspection, and maintenance expectations codified under FDA cGMP regulations. Equipment intended for dietary supplement manufacturing must additionally satisfy compliance frameworks specific to supplement production, while pharmaceutical-grade systems must adhere to broader cGMP expectations for equipment safety, sanitation, and operator protection. These requirements do not merely influence equipment design; they dictate documentation rigor, validation protocols, and the ability to demonstrate consistent quality management across production runs.
Beyond domestic regulatory frameworks, international market access increasingly depends on standardized certification pathways. ISO 9001 and ISO 22000 certifications are expected for capsule filling machine manufacturers seeking to assure consistent quality management and food safety in regulated production environments. For pharmaceutical applications, CE marking and cGMP compliance have become de facto prerequisites for market access in regulated regions, meaning that procurement teams must evaluate not only mechanical performance but also the completeness of compliance portfolios, audit readiness, and the vendor’s capacity to support lifecycle documentation. Furthermore, equipment transactions involving domestic, import, and export flows are subject to mandatory electronic reporting requirements, adding an administrative compliance layer that procurement, legal, and logistics functions must coordinate. These regulatory dynamics collectively raise the bar for vendor qualification and reinforce the strategic value of partnering with manufacturers that maintain robust quality management systems and transparent compliance documentation.
Operational and Strategic Implications for 2026 Capital Allocation
For manufacturing executives, R&D leaders, and procurement strategists, the Capsule Filling Machines Market in 2026 presents a window of calculated investment. The combination of moderate but steady market growth, a moderately concentrated competitive field, and an accelerating product innovation cycle creates a favorable environment for strategic equipment selection, capacity planning, and vendor partnership development. Several operational implications warrant particular attention.
- Total cost of ownership extends beyond purchase price. Organizations must evaluate dosing precision, changeover flexibility, maintenance predictability, and compliance documentation as integral components of long-term value. Equipment that reduces batch variability and supports faster sanitation or reconfiguration cycles can yield measurable gains in throughput consistency and quality assurance.
- Compliance readiness is a procurement differentiator. As regulatory expectations intensify across pharmaceutical and nutraceutical production lines, vendors that provide comprehensive CE and cGMP alignment, robust quality management certifications, and transparent lifecycle support will command preferential positioning in supplier evaluations.
- Flexibility is increasingly tied to formulation complexity. The ability to handle powders, pellets, tablets, mini-tablets, and specialized fill configurations is no longer a niche requirement. Manufacturers developing multi-SKU production strategies or transitioning between dosage forms will prioritize machines that offer advanced dosing combinations and modular adaptability.
- Innovation cycles demand forward-looking refresh planning. Recent product launches and technology showcases indicate that equipment performance benchmarks are shifting toward operator-centered design, weight control precision, and higher throughput efficiency. Procurement teams should align capital planning horizons with vendor roadmaps to avoid stranded investments in rapidly evolving equipment categories.
- Regional demand divergence rewards localized strategy. While mature markets continue to drive stable demand, emerging manufacturing corridors are cultivating distinct procurement rhythms, regulatory nuances, and service expectations. Organizations that tailor their equipment sourcing, service agreements, and compliance strategies to regional operating conditions will gain agility in market expansion and supply chain resilience.
What the Full Research Delivers: A Practical Intelligence Framework
PW Consulting’s comprehensive Capsule Filling Machines Market research is structured to translate macro-level market dynamics into actionable, segment-specific intelligence. The report provides a detailed examination of revenue trajectories, segmentation architectures, competitive positioning, regulatory impact pathways, and innovation timelines, all calibrated to support 2026 strategic planning and multi-year forecasting. Rather than offering static snapshots, the analysis maps the structural relationships between equipment type adoption, application demand patterns, regional deployment trends, and vendor competitive strategies, enabling readers to model investment scenarios, assess supplier qualification criteria, and anticipate shifts in procurement prioritization.
The research framework is designed for cross-functional application. Manufacturing and operations leaders can leverage the segmentation and equipment-type analysis to benchmark capacity planning and changeover requirements. Procurement and supply chain teams can use competitive landscape and compliance data to refine vendor scoring matrices and total cost of ownership models. Executive strategists and investors can draw on the market trajectory, concentration metrics, and innovation cycle synthesis to evaluate market entry timing, partnership opportunities, and long-term sector resilience. By maintaining a disciplined focus on decision-ready intelligence—not merely descriptive market narration—the report equips stakeholders to convert market complexity into structured strategic action.
Conclusion: Positioning for Deliberate Growth
The Capsule Filling Machines Market is at an inflection point where steady expansion, regulatory rigor, and accelerating technological differentiation converge. The projected trajectory from 226.24 million USD in 2026 toward 344.8 million USD by 2032, supported by a compound annual growth rate of 6.98 percent, reflects a market that is expanding through structural demand rather than transient cycles. In this environment, the organizations that thrive will be those that treat equipment selection, compliance alignment, vendor partnership, and innovation readiness as interconnected strategic levers rather than isolated procurement tasks.
The full market research provides the granular segmentation data, competitive benchmarking, regulatory impact mapping, and scenario-based forecasting required to operationalize these decisions with precision. For executives and strategic planners seeking to align capital allocation with long-term manufacturing resilience, the report offers a comprehensive foundation for evidence-based action. We invite you to access the complete research repository to examine the detailed regional, application, and equipment-type breakdowns, competitive profiles, and forward-looking analysis that will further sharpen your 2026 strategic roadmap.
For detailed analysis of this topic, please visit the official page: Capsule Filling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Door Handle Sensor Market Hits $2.12B in 2025, 6.15% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Automotive Door Handle Sensors Market: Navigating Growth, Regulation, and Competitive Shifts Through 2032
The automotive door handle sector has evolved far beyond a passive mechanical interface. As electric vehicle architectures prioritize aerodynamic efficiency, silent operation, and seamless user experiences, door handle sensors have become critical enablers of keyless access, gesture-driven interaction, and fail-safe egress. The latest Automotive Door Handle Sensors Market research from PW Consulting synthesizes five years of historical performance with a seven-year forward trajectory, offering decision-makers a structured view of how this niche component market is scaling, consolidating, and reshaping itself around regulatory and technological inflection points.
Split-Type Colloid Mill Market
For executives planning capital allocation, supplier qualification, platform sourcing, and compliance roadmaps in 2026, this report functions as a decision-grade reference rather than a static data table. It connects macro growth signals to grounded competitive behavior, maps technology adoption pathways to application demand, and highlights how the intersection of safety regulation and consumer expectations will redefine acceptable design boundaries. The following overview outlines what the research delivers, why it matters for 2026 planning cycles, and which structural forces analysts should monitor as the market accelerates through the end of the decade.
Peripheral Drug Eluting Stent Market
Why This Research Matters for 2026 Decision-Making
Automotive component planning in 2026 requires more than observing headline growth; it demands clarity on timing, adoption intensity, and the operational implications of shifting standards. The market for door handle sensors entered a period of measurable expansion between 2020 and 2025, with annual revenue climbing from approximately USD 1.65 billion in 2020 to around USD 2.12 billion in 2025. This progression reflects sustained OEM interest in integrated access systems and a growing reliance on sensor-based touchpoints in both premium and volume-segment vehicles.
Centrifugal Carbon Capture Compressor Market
Compounding this historical momentum is a forecast period that points to continued expansion, with projected revenue reaching nearly USD 2.32 billion in 2026 and continuing upward through 2032. Across the forecast window, the overall market is expected to advance at a compound annual growth rate of 6.15 percent. While the aggregate trajectory is constructive, the real strategic value lies in understanding the rhythm of adoption: which application categories are pulling demand forward, which sensor modalities are gaining design wins, and how regional manufacturing and compliance environments shape sourcing strategies. The full segmentation detail, regional deployment patterns, and application-level revenue mapping are developed in the complete study, where the numbers are contextualized against platform volume, vehicle mix, and supplier readiness.
For 2026 specifically, the report is designed to support several planning objectives:
- Evaluating when to commit to sensor architectures for upcoming vehicle programs and platform refresh cycles
- Assessing supplier capabilities in proximity detection, low-power wake-up functions, gesture recognition, and false-trigger mitigation
- Gauging the operational impact of new safety requirements on hidden, flush, and electronically actuated door handle designs
- Determining where to prioritize qualification efforts across capacitive, infrared, ultrasonic, and hybrid detection approaches
- Aligning sourcing and localization decisions with regional volume concentration and regulatory timelines
What the Report Covers: A Practical Playbook for OEMs, Suppliers, and Investors
The study is structured to move from market foundation to execution-relevant analysis. Rather than presenting an isolated forecast, it ties revenue evolution to technology choices, application pull, competitive behavior, and regulatory drivers. The result is a reference that can be used for product planning, supplier evaluation, M&A scouting, and capital planning.
At the core of the research is a comprehensive market sizing and forecast model grounded in historical data from 2020 through 2025 and extended across the 2026 to 2032 forecast period. The analysis translates consolidated revenue into a forward view that highlights where growth is likely to intensify and where incremental adoption will be shaped by platform cycles and regulatory compliance. The full report unpacks this trajectory by type, application, and region, allowing readers to understand not just how large the market is becoming, but where value is being captured and by what mechanisms.
The segmentation framework is developed with a sharp focus on decision utility. By sensor type, the research examines how capacitive, infrared, ultrasonic, and other detection technologies compete on integration complexity, power consumption, environmental robustness, and user-experience performance. By application, the analysis follows the demand originating from keyless entry systems, power door systems, and gesture control systems, distinguishing between mainstream convenience features and premium or emerging interaction modes. Regional analysis is provided to help teams interpret where demand is most concentrated and how local vehicle production, safety mandates, and supplier ecosystems shape procurement strategy.
In addition to segmentation, the report delivers competitive and operational intelligence. Market concentration metrics are evaluated to clarify how revenue and design influence are distributed across the supplier base, giving readers a realistic view of consolidation risk, negotiation leverage, and dependency exposure. Company profiles are included for organizations with established or emerging roles in automotive door handle sensing, covering their technology orientation, integration strengths, and stated directions in compact, low-power, and application-specific solutions. The report also tracks recent developments that are reshaping the near-term landscape, including product introductions and regulatory actions that directly affect design priorities and compliance timing.
Key Dynamics Reshaping Demand and Design Strategies
Several forces are converging to make door handle sensors a strategically important subsystem in the broader vehicle access architecture. The first is the ongoing electrification and aerodynamic optimization of exterior body panels. Hidden or flush handle designs can improve drag coefficients and visual minimalism, but they also change how users interact with the vehicle and how reliably egress can be achieved in emergency scenarios. As a result, sensor solutions must balance convenience, detection accuracy, low-power wake-up behavior, and fail-safe performance.
The second force is the rising expectation for seamless keyless access. Drivers and passengers increasingly expect vehicles to recognize presence, respond to proximity cues, and support contactless interaction without compromising security or creating false activations. This expectation is pushing development toward sensor stacks that can deliver reliable detection with minimal power draw and stable performance across a wide range of environmental conditions. The report analyzes how this demand is reflected across keyless entry systems, power door systems, and gesture control applications, and where adoption is likely to accelerate as platforms mature.
The third force is regulatory action, which is becoming a defining factor in design feasibility. In early 2026, Chinese automotive safety regulators approved the mandatory national standard GB 48001-2026, Safety Technical Requirements for Automotive Door Handles. The standard introduces technical requirements intended to enhance safety, with particular attention to hidden or flush handle designs in electrified vehicle architectures. New vehicle type approvals are required to comply fully from January 1, 2027, with a transition period extending to January 1, 2029 for vehicles previously approved. This regulatory timeline matters because it intersects directly with development cycles, validation schedules, and the availability of sensor solutions capable of meeting stricter safety and reliability expectations.
Parallel scrutiny is emerging in other markets. In the United States, federal regulators are investigating multiple Tesla models for potential defects in electronic door releases, with incident reports tied to cases where doors would not open after crashes. Whether or not these investigations lead to direct mandates, they contribute to broader engineering caution around electronically dependent egress systems and reinforce the value of robust detection, redundancy, and fault-tolerant control strategies. These developments are discussed in the report not only as risk signals, but also as indicators of where future validation expectations may become more demanding across global programs.
Competitive Landscape: Technology Positioning and Recent Moves
The supplier landscape is characterized by a mix of semiconductor specialists, Tier-1 system suppliers, and component manufacturers with distinct technology strengths. The report profiles several companies whose solutions are shaping design choices around proximity sensing, wake-up functionality, gesture recognition, and integrated handle systems. Collectively, these players illustrate how the market is moving toward more tightly integrated, application-tuned sensing modules rather than generic discrete components.
NXP Semiconductors is positioned around automotive NFC door handle reference designs and solutions optimized for compact integration. Melexis offers Hall effect and low-power sensor solutions, including door handle wake-up switches and e-door handle applications. Continental AG develops capacitive door handle sensor modules that emphasize gesture recognition and enhanced false-trigger resistance. Valeo SA supplies ultrasonic-based flush handle sensor systems aimed at hands-free door activation across luxury and mass-market vehicles. Infineon Technologies contributes through microcontrollers and sensor ICs that support proximity and position sensing within door handle detection and control architectures. NMB Technologies Corporation manufactures vehicle door handle systems with integrated sensor solutions for OEM customization, including sensing and lighting. ADAC Companies provides vehicle access systems featuring integrated sensing technologies, capacitive sensors, and microswitches in exterior door handles and trim.
These company profiles are placed in the context of broader market concentration, where a meaningful share of revenue is associated with a limited number of influential suppliers. The report uses concentration indicators to help readers interpret negotiation dynamics, supply continuity risk, and the practical implications of relying on a small group of design leaders. For procurement and engineering teams, this is especially relevant when evaluating platform dependency and long-term sourcing resilience.
Recent industry activity underscores how quickly product expectations are changing. Continental AG introduced a new capacitive door handle sensor module featuring integrated gesture recognition and improved false-trigger resistance for premium EV platforms. This type of advancement matters because it reflects a dual priority now driving development: richer user interaction and more reliable behavior under real-world conditions. At the same time, the approval of GB 48001-2026 in China demonstrates that safety regulation is no longer a background consideration. It is becoming a direct determinant of which handle designs can move forward, when they can be approved, and which sensing approaches are best positioned to meet stricter performance requirements.
Taken together, these competitive and regulatory developments point to a market in which technical differentiation, compliance readiness, and system-level reliability are increasingly intertwined. The complete study goes further by mapping these dynamics against regional volume patterns, application demand, and sensor-type adoption, which helps readers distinguish between short-term product wins and longer-term structural shifts.
What 2026 Planning Should Prioritize
Given the growth trajectory, the technology mix, and the emerging regulatory calendar, several priorities stand out for organizations operating in or dependent on this market. First, teams should treat sensor selection as a platform-level decision rather than a late-stage component substitution. Detection modality, power behavior, integration form factor, and false-trigger performance can influence development risk, validation effort, and long-term uniformity across vehicle lines.
Second, compliance readiness should be factored into technical roadmaps early. With safety standards now introducing explicit requirements for automotive door handles and with phase-in timelines aligned to vehicle type approval cycles, engineering teams need to understand which sensor and actuator architectures are most compatible with anticipated safety expectations. The report's regulatory analysis provides context for where authorities are focusing attention and how compliance obligations may influence both hidden and conventional handle designs.
Third, sourcing strategies should account for market concentration and the pace of innovation among leading suppliers. As leading semiconductor and Tier-1 players continue to refine compact, low-power, and application-specific solutions, procurement teams should evaluate not only current sample performance but also roadmap alignment, qualification support, and the ability to meet future functional and safety requirements. This is particularly important for programs that depend on sensor-integrated door handles as a defining feature of the customer experience.
Finally, investors and strategy teams should use the forecast and segmentation structure to separate durable demand drivers from temporary platform cycles. The overall expansion from 2026 onward reflects underlying shifts in vehicle access interaction, electrification-driven body design, and safety-driven engineering discipline. Yet the distribution of growth across applications and technologies is likely to vary by region and by vehicle segment. The report is designed to make those distinctions visible so that decisions are based on differentiated insight rather than aggregate growth alone.
Accessing the Full Intelligence
This overview is intended to establish the strategic frame and demonstrate the depth of the underlying research. The complete Automotive Door Handle Sensors Market study extends the analysis into detailed segmentation, regional revenue distribution, application-level demand mapping, technology adoption patterns, competitive positioning, and regulatory impact assessment. It also provides implementation-oriented commentary for sourcing, engineering qualification, and plan-of-action development across the 2026 to 2032 horizon.
For executives who need to make 2026 commitments with confidence, the full report offers the granularity required to compare sensor pathways, interpret supplier capabilities, and align program timing with regulatory and market realities. The aggregate growth signals are strong, but the decisive advantages will come from understanding where exactly value is being created, which design choices are becoming standard, and how safety expectations will reshape what is commercially and technically viable.
PW Consulting's full market research provides that level of operational clarity. The complete edition is available through our official report page, where the segmented data tables, competitive evaluations, and strategic recommendations can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Automotive Door Handle Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Stainless Steel Floor Drains Market to Reach USD 2,133.1 Million by 2032 Amid 3.6% CAGR
By PW Consulting, 2026-09-07
Strategic Intelligence for 2026: Navigating the Stainless Steel Floor Drains Market
The global infrastructure landscape is undergoing a subtle but significant transformation, driven by stringent hygiene protocols, evolving construction standards, and renewed investment in public utilities. For stakeholders in the built environment, the stainless steel floor drains market represents a critical intersection of sanitary engineering and material durability. As we move into 2026, understanding the trajectory of this sector is not merely about tracking sales volumes; it is about anticipating compliance shifts, supply chain volatility, and competitive positioning.
Worldwide Roll Feeders Market
Our latest market research study offers a comprehensive examination of this sector, providing the granular intelligence required to make informed capital allocation and product development decisions. This article serves as a strategic overview, highlighting the macro-economic currents and competitive tensions that define the landscape, while outlining the depth of analysis available in the full report. The data presented here reflects a thorough analysis spanning historical performance from 2020 through 2025, with a detailed forecast period extending to 2032.
MW-class Wind Power Pitch Slip Ring Market
Market Trajectory and Growth Dynamics
The stainless steel floor drains market has demonstrated resilience and steady expansion over the past half-decade. Historical data indicates a consistent upward trend in revenue, reflecting the material's growing preference over traditional alternatives due to its corrosion resistance and longevity. In 2020, the market revenue stood at approximately 1,378.7 million USD. By 2025, this figure has evolved to 1,656.0 million USD, signaling a robust compound annual growth rate over the historical period.
Data Center Magnetic Levitation Compressors Market
Looking ahead, the forecast period from 2026 to 2032 projects further consolidation and growth. The market is anticipated to reach 1,757.32 million USD in 2026, with a forecast CAGR of 3.6 percent through 2032. This growth is not linear; it is punctuated by specific demand drivers related to infrastructure modernization and hygienic design requirements. While the overall trajectory is positive, industry participants must navigate fluctuating raw material costs and varying regional adoption rates to capitalize on these opportunities.
It is important to note that while the aggregate numbers suggest stability, the underlying segmentation reveals distinct pockets of volatility. The demand structure is influenced heavily by the type of drainage system required for specific environments, ranging from traditional water seals to specialized gravity-based systems. Furthermore, the application spectrum varies significantly, with commercial and municipal sectors often driving volume differently than household or industrial segments. Understanding the weight of each segment is crucial for targeting marketing efforts and production capacity, details of which are fully unpacked in the complete study.
Regulatory Pressures and Industry Context
The operating environment for stainless steel floor drain manufacturers and purchasers is increasingly shaped by regulatory frameworks. In 2025 and heading into 2026, compliance has become a primary differentiator. For instance, commercial kitchen drains must meet NSF/ANSI 14 and NSF/ANSI 51 standards, in addition to ASME A112.6.3 for performance. These standards are not optional; they are gatekeepers to entry in high-value commercial and foodservice markets.
Beyond general plumbing codes, specific industries are subject to rigorous hygienic design principles. Foodservice and commercial applications are subject to HACCP hygienic design principles and EHEDG guidelines for sanitary requirements. This regulatory layer adds complexity to product design and certification processes. Manufacturers who can demonstrate compliance effectively gain a competitive moat, whereas those lagging risk exclusion from key supply chains, particularly in pharmaceutical and food processing sectors.
On the infrastructure front, government spending continues to play a pivotal role. In 2025, the Infrastructure Investment and Jobs Act continued channeling billions into wastewater management and public facility refurbishment. This inflow of capital supports demand for municipal used drainage systems, providing a stable baseline for market growth regardless of private sector fluctuations. However, reliance on public funding cycles requires strategic timing in sales and deployment strategies.
Material costs also remain a critical variable. Stainless steel price per pound in 2025 depends on nickel costs and market trends, with 304 grade ranging from $1.45 to $2.06 per pound. This volatility impacts margins for manufacturers and final pricing for buyers. Strategic procurement and hedging strategies are becoming essential competencies for leading firms to maintain profitability amidst these input cost swings.
Competitive Landscape and Key Players
The market structure is characterized by a mix of specialized manufacturers and larger diversified entities. Market concentration metrics indicate a relatively fragmented landscape, with a CR3 of 24.6 percent and a CR5 of 26.2 percent. This suggests that while there are dominant players, there is significant room for niche specialists and regional competitors to thrive.
Several key companies define the current competitive arena. Josam Company, based in Elkhart, Indiana, offers 304/316L stainless steel floor drains, trench drains, cleanouts, and retrofit liners with fabricated and cast options for commercial and industrial hygienic applications. Their recent activity highlights a focus on specific high-profile installations, such as the Royal Winery Project in February 2025 and the Venn Brewing Project in January 2025, demonstrating their penetration into specialized facilities requiring high hygiene standards.
AWI Manufacturing, located in Montgomery, Alabama, manufactures stainless steel floor drains, hub drains, and related systems used in food, dairy, and commercial settings for over 50 years. Their long tenure suggests deep institutional knowledge regarding sanitary requirements in sensitive processing environments. Similarly, Jay R. Smith Mfg. Co., also headquartered in Montgomery, Alabama, produces stainless steel floor drains, sanitary drains, and specialty drainage products for commercial applications, reinforcing the strength of the US manufacturing base in this sector.
On the industrial and high-traffic end, Zurn Industries, based in Saginaw, Michigan, manufactures high-grade stainless steel floor drains, floor sinks, and trench drains for industrial and high-traffic environments. Their strategic moves are notable; in 2025, Zurn expanded its hygienic drainage product line specifically targeting pharmaceutical and food processing applications. This move signals a strategic pivot towards higher-margin, regulation-intensive segments.
The landscape also includes global players and custom specialists. Blucher, part of Watts Water Technologies and based in Vildbjerg, Denmark, is a global manufacturer of stainless steel drainage systems, including floor drains and channels. Their geographic reach provides a counterbalance to US-centric manufacturers. CustomDrains, operating out of the United States, specializes in custom stainless steel floor drain systems and accessories for commercial, industrial, food processing, and pharmaceutical facilities. Their focus on customization allows them to serve complex project requirements that off-the-shelf solutions cannot meet. Finally, Sioux Chief Manufacturing Company, based in Sioux Falls, South Dakota, provides residential and commercial stainless steel floor drains and related drainage products, covering the lower end of the market spectrum where volume and cost-efficiency are paramount.
Understanding the strategic moves of these entities is vital. Whether it is Josam's project-based references, Zurn's product line expansion, or CustomDrains' specialization, each maneuver reshapes the value chain. The full report provides a detailed profiling of these companies, including their specific product portfolios, regional strengths, and strategic positioning relative to the market segments discussed earlier.
Report Scope and Strategic Value for 2026
This market research study is designed to be a practical tool for decision-makers. It goes beyond surface-level observations to provide actionable intelligence. The scope covers a base year of 2025 and historical years from 2020 to 2025, ensuring that recent trends are fully contextualized before looking forward. The forecast period extends from 2026 to 2032, allowing for long-term planning cycles.
One of the core strengths of this analysis is the detailed segmentation. The report breaks down the market by region, covering key areas such as North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. This regional breakdown is essential for identifying export opportunities, assessing local competition, and understanding regulatory variations. For example, while North America and Europe represent significant portions of the market value, the growth dynamics in Asia Pacific or the infrastructure spending in Latin America may offer different risk-reward profiles for investors and manufacturers.
The product type segmentation is equally critical. The study distinguishes between Traditional Water Seal Floor Drains, Spring-type Floor Drains, Suction Stone Floor Drains, Gravity Floor Drains, and Others. Each type serves different functional requirements and price points. Knowing which type is gaining traction in specific applications can guide R&D priorities. For instance, the demand for hygienic applications might favor specific seal technologies over gravity-based systems in certain contexts.
Application segmentation further refines the view, categorizing usage into Household Used, Commercial Used, Municipal Used, Industrial Used, and Marine Used. The commercial sector often drives significant volume, but the industrial and municipal sectors may offer higher stability or value per unit due to infrastructure contracts. The report analyzes the revenue contribution and growth potential of each application, helping stakeholders align their sales pipelines with the most promising end-use markets.
For corporate strategists, the competitive landscape analysis offers benchmarks against key players. By comparing market share, product breadth, and recent developments, companies can identify gaps in the market or areas for consolidation. The inclusion of recent developments, such as project references and product line expansions, ensures that the competitive intelligence is current and relevant to the 2026 operating environment.
Implications for Decision Makers
In the context of 2026 planning, several strategic implications emerge from this market overview. First, compliance is no longer a back-office function; it is a front-line competitive advantage. Firms that integrate NSF, ASME, HACCP, and EHEDG standards into their design philosophy early will capture market share in regulated industries like food processing and pharmaceuticals. Second, raw material volatility requires agile supply chain management. With stainless steel prices fluctuating based on nickel markets, long-term contracts and diversified sourcing may be necessary to protect margins.
Third, the infrastructure spending landscape provides a tailwind, but it requires patience and relationship building. The continued flow of funds from acts like the Infrastructure Investment and Jobs Act means public sector projects will remain active. However, capturing this demand requires navigating procurement processes and demonstrating longevity and compliance. Fourth, the market concentration suggests that partnerships or niche positioning can be effective strategies. With a CR5 below 30 percent, there is no single dominant force controlling the entire market, allowing for strategic entry or expansion in specific regions or segments.
Finally, the regional dynamics suggest that a one-size-fits-all approach is insufficient. The market behavior in North America may differ significantly from Asia Pacific or Mideast and Africa due to varying construction rates, regulatory maturity, and income levels. A granular understanding of regional revenue splits and growth rates is necessary to allocate resources efficiently. The full report provides these specific regional and segment comparisons, enabling precise geographic targeting.
Conclusion
The stainless steel floor drains market stands at a juncture where material science, regulatory compliance, and infrastructure investment converge. The projected growth to 2,133.1 million USD by 2032 underscores the long-term viability of the sector, but the path to capturing this value is fraught with competitive and operational complexities. Companies that rely on aggregate data alone risk missing the nuances of segment performance, regional disparities, and competitor moves.
This market research report is engineered to close that gap. It transforms raw data into strategic narrative, offering clarity on where growth is concentrated, who is leading the charge, and what external factors will shape the next cycle. For executives, investors, and product leaders planning for 2026 and beyond, the detailed insights contained within this study provide the foundation for robust strategy formulation. We invite you to explore the full proprietary analysis to secure the comprehensive data sets, detailed competitor profiles, and segment-specific forecasts necessary to navigate this evolving market with confidence.
For detailed analysis of this topic, please visit the official page: Stainless Steel Floor Drains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Safety Glasses Market to Hit $225.5M in 2025, 4.05% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Eye Protection: Navigating the Safety Glasses Market Through 2032
As industrial environments grow increasingly complex and regulatory frameworks evolve, the safety glasses market has emerged as a critical intersection of compliance, innovation, and strategic procurement. PW Consulting’s latest market research report provides a comprehensive, data-driven examination of this sector, offering enterprise decision-makers the intelligence required to navigate competitive pressures, anticipate demand shifts, and align product portfolios with emerging occupational safety mandates. This overview articulates the strategic value of the report for 2026 corporate planning, outlining the macro trajectory, competitive dynamics, regulatory catalysts, and operational dimensions that define the landscape without disclosing the granular segment-level intelligence contained in the full study.
Compaction Equipment Rental Market
Market Trajectory and Revenue Context
The safety glasses industry has demonstrated consistent expansion over the past half-decade, with revenue trends reflecting steady procurement cycles across industrial, construction, and specialized application verticals. From a baseline exceeding $185 million in 2020, the market has advanced through successive growth phases, reaching approximately $225.5 million by 2025. Our forecasting framework projects this trajectory to continue through 2032, with a compound annual growth rate of 4.05 percent. By the close of the forecast horizon, total market revenue is positioned to approach the $300 million threshold, underscoring a sector characterized by mature demand foundations and moderate but reliable expansion.
Lawnmower Oil Market
It is important to recognize that historical performance and forward-looking projections are shaped by distinct structural drivers. Procurement patterns, regulatory compliance cycles, material innovation, and regional industrial activity all contribute to the revenue arc. The report dissects these drivers in detail, mapping how macroeconomic conditions, supply chain normalization, and workplace safety investments intersect to influence purchasing velocity. Rather than presenting surface-level aggregates, the analysis isolates the mechanisms behind revenue movement, enabling leaders to differentiate between cyclical noise and structural growth signals.
Power Bank Charging Station Market
Report Scope and Analytical Architecture
The study is engineered to serve multiple decision-making functions: portfolio planning, competitive benchmarking, procurement strategy refinement, and market entry assessment. Its architecture spans historical baselines, forward-looking forecasts, segmentation logic, and competitor profiling, all structured to translate raw market data into actionable strategy. The following components form the analytical backbone of the report.
Core Analytical Dimensions
- Historical performance tracking across the 2020 to 2025 evaluation window, establishing baseline momentum and identifying inflection points in demand behavior.
- Forward projection modeling covering the 2026 to 2032 horizon, with scenario-aware forecasting that accounts for regulatory timing, product lifecycle transitions, and regional procurement rhythms.
- Material and product-type analysis examining how lens composition, coating technologies, and frame engineering influence adoption patterns and pricing dynamics.
- Application vertical mapping that connects safety eyewear demand to operational environments, clarifying which sectors drive volume, which demonstrate higher margin potential, and where specialization commands procurement premiums.
- Competitive landscape profiling that evaluates market share distribution, product positioning, and strategic maneuvering among leading manufacturers.
- Regulatory and standard-development tracking that links compliance milestones to market behavior, enabling leaders to anticipate certification-driven purchasing shifts.
Each dimension is supported by data tables, analytical commentary, and contextual interpretation designed for executive review. The report avoids static listing in favor of connective analysis, demonstrating how material preferences interact with application requirements, how competitive concentration shapes pricing tolerance, and how standard revisions propagate through procurement pipelines. Decision-makers gain not just a snapshot of market size, but a working model of how the market operates and where leverage points emerge.
Competitive Landscape and Strategic Positioning
Market concentration data reveals a moderately consolidated environment. The three largest participants collectively account for a combined share just above one-third of total revenue, while the top five firms extend their footprint to slightly more than half of the market. This concentration profile indicates the presence of established players with durable distribution networks, brand recognition, and compliance-certified product lines, alongside sufficient fragmentation to allow specialized entrants and regional manufacturers to capture niche demand.
Our report profiles a cross-section of influential companies whose product strategies and certification portfolios illustrate the competitive dynamics shaping the sector.
Leading Participants and Strategic Profiles
Wiley X operates from a US base with a focus on ballistic and industrial safety eyewear engineered for high-impact resistance and chemical exposure scenarios. Its lens coating technologies and ANSI Z87.1-rated product lines reflect a positioning strategy that emphasizes protection performance in demanding operational contexts.
Bollé Safety , headquartered in France, emphasizes certified protection with anti-fog and anti-scratch performance as core differentiators. Its PLATINUM-coated offerings align with ANSI Z87.1 and OSHA standards, demonstrating how coating durability and optical clarity serve as recurring procurement drivers in environments where lens degradation accelerates replacement cycles.
uvex Safety Group brings a German engineering orientation to the market, offering safety glasses and goggles that meet ANSI/ISEA Z87.1 standards while extending into prescription and specialized models. Its portfolio breadth illustrates how manufacturers compete not only on impact performance but also on wearer comfort, optical precision, and integration with existing vision correction requirements.
MCR Safety supplies ANSI Z87.1-compliant eye protection with military-grade and UV-blocking options tailored to industrial applications. Its emphasis on performance-grade specifications positions it within segments where hazard intensity and certification rigor influence purchasing decisions.
Honeywell contributes a broad safety portfolio that spans impact, chemical, and splash protection use cases. Its certified product range reflects the advantage of scaled distribution and cross-category integration, allowing enterprise buyers to consolidate procurement across multiple personal protective equipment categories.
MSA Safety manufactures safety glasses and goggles with prescription options and ANSI Z87.1 certification for general industry and construction contexts. Its product strategy demonstrates how compliance certification paired with prescription adaptability supports sustained demand in settings where worker vision requirements intersect with hazard protection mandates.
Essilor’s prescription safety eyewear division operates through partnerships with frame manufacturers to deliver ANSI Z87.1 and OSHA-compliant prescription solutions. This collaborative model highlights the role of specialty vision correction in the broader safety glasses market, where ergonomic fit and optical performance influence adoption among workers requiring corrective lenses.
Radians Safety offers GLYF™ and ballistic-rated eyewear compliant with ANSI Z87.1, with a product emphasis on comfort and debris protection. Its recent GLYF™ and Crossfire BOLO™ introductions underscore the ongoing innovation cycle around wearer comfort, ballistic performance, and industrial usability.
Day Sun Industrial Corp. , based in Taiwan, produces ANSI Z87.1 and CE-certified safety glasses with anti-scratch and UV protection for industrial use. Its dual certification footprint illustrates how manufacturers adapt product lines to serve both regional regulatory expectations and export-oriented compliance requirements.
The report does not stop at descriptive profiling. It evaluates how these participants position themselves relative to one another, where certification alignment creates procurement lock-in, and where product differentiation enables margin expansion. It also examines how competitive concentration interacts with regional demand patterns, allowing buyers and sellers alike to understand where pricing tension exists and where substitutability is highest.
Regulatory Catalysts and Industry Dynamics
Regulatory and standards activity represents one of the most consequential forces shaping demand behavior, procurement timing, and product redesign cycles. In January 2026, The Vision Council published ANSI/ISEA Z87.1-2025, the sixth revision of the voluntary consensus standard for occupational eye and face protection devices. Developed by the Z87 Committee on Safety Standards for Eye Protection, this revision sets updated criteria for testing, marking, and use across occupational hazard scenarios. The standard emphasizes harmonization with global benchmarks and addresses performance requirements for diverse workplace hazards, including chemical exposure and radiation-related risks.
OSHA 1910.133 continues to function as a central compliance reference point. It requires safety glasses to comply with ANSI/ISEA Z87.1 editions including 2010, 2003, or 1989 with its 1998 revision, and it also accommodates the 2025 revision for hazard protection spanning impact, radiation, and liquid splash scenarios. The standard further mandates side shields for flying debris protection in general industry under ANSI Z87.1 requirements. For procurement leaders, these regulatory anchors create both continuity and transition pressure. Existing certified inventory may remain acceptable under legacy reference points, yet forward procurement increasingly aligns with the updated revision, prompting product refreshes, coating upgrades, and side-shield integration to meet evolving compliance expectations.
Recent corporate developments reinforce the significance of these regulatory and product cycles. In January 2026, MCR Safety released its 2026 Eye Protection Catalog, featuring updated styles, advanced coatings, and ANSI Z87+ impact-rated options. Radians Safety followed in February 2026 with the introduction of GLYF™ Safety Eyewear and Crossfire BOLO™ ballistic-rated eyewear, showcased at the NSC Expo. Later in the year, uvex Safety Group scheduled participation at INTERSCHUTZ 2026 in Hannover, presenting new product lines for safety glasses and goggles. These moves illustrate how manufacturers use catalog refreshes, product launches, and trade-show visibility to signal compliance alignment, technological advancement, and category leadership.
The report integrates these developments into a broader dynamics framework, mapping how standard revisions, certification references, and product innovation cycles interact to influence purchasing calendars, specification upgrades, and competitive repositioning. By contextualizing regulatory updates within procurement behavior, the analysis helps leaders anticipate when compliance-driven replacement demand may accelerate and how specification changes can alter supplier evaluation criteria.
Segmentation Logic and Strategic Intelligence Design
While the full report provides detailed segment-level revenue and share breakdowns, this overview deliberately preserves depth for the complete study. What can be outlined here is the analytical logic that underpins the segmentation framework and the strategic value it delivers to decision-makers.
Material and Product-Type Analysis
Safety glasses are commonly evaluated through the lens of material composition, with polycarbonate, glass, and other engineered materials each presenting distinct performance and cost profiles. Polycarbonate-based products typically command attention in high-impact contexts due to their ballistic tolerance and lightweight characteristics, while glass and alternative materials serve use cases where optical clarity, scratch resistance, or cost considerations shape procurement choices. The report examines how material preferences vary across application requirements, how coating technologies amplify or mitigate material limitations, and how procurement teams weigh performance trade-offs against total cost of ownership. Rather than presenting raw segment shares in isolation, the analysis connects material adoption to hazard profiles, replacement frequencies, and compliance specifications, enabling a functional understanding of why certain product types gain traction in particular environments.
Application Vertical Mapping
Demand for safety eyewear is distributed across industrial manufacturing, construction, and a broader set of application contexts. Each vertical exhibits distinct purchasing rhythms, specification priorities, and compliance drivers. Industrial manufacturing environments often emphasize impact resistance, chemical protection, and durable coatings that withstand continuous exposure. Construction settings may prioritize side-shield compliance, anti-fog performance, and ergonomic fit for workers moving across variable site conditions. Other application segments contribute additional complexity, with specialized hazard profiles that can elevate demand for prescription integration, radiation protection, or customized frame geometry.
The report maps these application dynamics without reducing them to static allocations. It examines how vertical-specific procurement criteria influence supplier selection, how replacement cycles differ by operational intensity, and where specialization creates pricing resilience. This vertical lens enables leaders to identify which environments offer steady volume, which present higher specification requirements that can support premium positioning, and how demand migration may occur as hazard exposure profiles evolve.
Regional Demand Awareness
Regional analysis forms another essential layer of the study. While specific regional revenue figures and share percentages are reserved for the complete report, the segmentation architecture acknowledges that demand patterns vary according to industrial activity, regulatory enforcement intensity, certification adoption, and distribution maturity. North American, European, Asia Pacific, Latin American, and Middle East and Africa markets each present distinct procurement ecosystems, with local standards alignment, channel structures, and competitive presence shaping how safety glasses are specified, sourced, and substituted. The report provides a comparative regional framework that helps leaders interpret where demand density concentrates, where certification harmonization influences sourcing decisions, and where growth acceleration may emerge as industrial safety investment expands.
Strategic Value for 2026 Decision-Making
The 2026 planning cycle offers a pivotal moment for enterprises operating in or adjacent to the safety glasses market. Standard revisions are translating into specification updates, manufacturers are refreshing catalogs and launching new product lines, and procurement teams are recalibrating supplier evaluation criteria around compliance, comfort, and durability. In this environment, strategic advantage depends on the ability to distinguish trend from noise, anticipate certification-driven purchasing shifts, and align product or sourcing strategies with durable demand drivers.
The report is designed to support that effort across several decision domains.
Portfolio and Product Strategy
For manufacturers and brand owners, the study provides context on where performance differentiation commands procurement attention and where specification convergence compresses competitive differentiation. It examines how coating technologies, lens materials, side-shield compliance, and prescription integration influence buyer preference, and it identifies the product attributes most closely associated with sustained demand in high-hazard environments. This enables portfolio leaders to prioritize development investments, refine product roadmaps, and align launch timing with certification and trade-show cycles.
Procurement and Sourcing Strategy
For buyers, the report clarifies how compliance references, certification editions, and standard revisions shape acceptable product specifications over time. It helps procurement teams anticipate when legacy-compliant inventory may remain sufficient and when updated revision alignment will increasingly drive replacement demand. By mapping application requirements to material and coating preferences, the study supports more precise specification writing, supplier comparison, and total-cost evaluation. This reduces the risk of over-specifying in low-hazard contexts or under-specifying in high-exposure environments.
Market Entry and Competitive Positioning
For organizations assessing expansion opportunities, the analysis frames the competitive landscape in terms of concentration, specialization, and regional demand heterogeneity. The moderate concentration profile suggests that established players hold meaningful share, but the environment also leaves room for entrants that can differentiate through certification alignment, application specialization, or regional channel strength. The report evaluates where competitive overlap is highest, where niche demand remains underserved, and how regional certification dynamics influence entry feasibility. This allows market developers to target segments where their capabilities create the strongest fit rather than pursuing undifferentiated volume plays.
Why the Full Report Matters
An overview such as this establishes the strategic terrain, but the complete study delivers the segment-level precision required for execution-grade planning. It contains detailed revenue trajectories, segmentation breakdowns, competitive share distributions, application-specific demand dynamics, and regional performance comparisons that transform high-level insight into operational intelligence. It also integrates the most recent regulatory developments, product launches, and trade-show activity into a forward-looking framework, enabling leaders to connect near-term events with multi-year demand behavior.
The full report is intended for executives, category managers, product strategists, and procurement leaders who need to make specification, sourcing, and investment decisions with confidence. It provides the evidentiary base for portfolio prioritization, supplier negotiation, market entry assessment, and compliance-aligned procurement planning. By consolidating historical performance, forecast modeling, segmentation logic, and competitive profiling into a single analytical structure, the study reduces the time required to reach informed conclusions and increases the reliability of the resulting strategy.
Closing Perspective
The safety glasses market is defined by a balance of steady growth, compliance-driven specification shifts, and continuous product innovation. With revenue advancing from a strong 2025 baseline toward a forecast near the $300 million mark by 2032 and a CAGR of 4.05 percent, the sector offers durable expansion for participants who can align product capability with workplace hazard requirements and procurement expectations. Yet the strategic value of this market lies not in its size alone, but in the precision with which leaders can interpret certification dynamics, material preferences, application demands, and competitive positioning.
PW Consulting’s Safety Glasses Market research is built to deliver that precision. It equips decision-makers with the analytical depth required to navigate a moderately consolidated, regulation-sensitive, and technology-evolving landscape. The complete report contains the segment-level detail, regional comparisons, and competitor evaluations necessary to convert strategic intent into executable planning. For organizations preparing for 2026 and beyond, this study provides the intelligence foundation needed to act with clarity, prioritize effectively, and maintain alignment with the standards and performance expectations that shape occupational eye protection today.
For detailed analysis of this topic, please visit the official page: Safety Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dental Autoclave Market to Hit $399.1M by 2032 as Revenue Surpasses $309M in 2025
By PW Consulting, 2026-09-07
Strategic Intelligence for the Dental Autoclave Market: Navigating Growth and Compliance in 2026
The global dental equipment landscape is undergoing a structural shift, driven by tightening infection-control mandates, digital workflow integration, and sustained capital investment in outpatient care infrastructure. At the center of this transformation sits the dental autoclave, a foundational sterilization asset that has evolved from a simple pressure chamber into a networked, compliance-critical node within the modern dental practice. This latest market research from PW Consulting is designed to give executives, procurement leaders, and product strategists a clear, decision-ready view of where the industry stands today and how it will unfold through the end of the decade.
Rotating Shield Tunneling Machine Market
The analysis is anchored in a rigorous historical-reconstruction methodology spanning 2020 through 2025, followed by a forward-looking forecast window that carries the narrative from 2026 into 2032. Rather than presenting a static snapshot, the study treats market size as a moving indicator shaped by regulatory momentum, purchasing cycles, and technology adoption curves. In 2025, the overall dental autoclave market reached 309.0 million USD in revenue, reflecting a compound annual growth trajectory of approximately 3.69 percent over the base-to-forecast span. The outlook extends this momentum into the late 2020s and early 2030s, with projected revenue climbing toward 327.58 million USD in 2026, advancing to 337.78 million USD by 2028, and reaching 359.63 million USD in 2030 before approaching 399.1 million USD by 2032.
Portable Oil Fume Recorder Market
These figures are more than macroeconomic placeholders. They are the connective tissue between clinical compliance requirements, capital-budget planning, and competitive positioning. For organizations evaluating capacity expansion, product-line evolution, or market-entry timing, the numbers serve as a shared reference point for scenario modeling. The report does not stop at aggregate sizing; it translates the trajectory into operational implications, helping teams align equipment investment with the pace of practice modernization and the cadence of regulatory change.
Stranding Dies Market
Why This Research Matters for 2026 Decision-Making
2026 is a pivotal inflection point for the dental sterilization sector because it sits at the intersection of two converging forces: the implementation of newly effective quality-management frameworks and the maturation of digitally enabled sterilizers. For manufacturers, distributors, and practice owners alike, the strategic question is no longer whether compliance will become more demanding, but how quickly traceability, cycle validation, and automated verification will transition from desirable features to non-negotiable purchase criteria. This report frames that transition in terms that support concrete action.
A second strategic driver is the shift in purchasing behavior across end-user profiles. Dental clinics, hospitals, and a broader category of service and support users each bring distinct procurement rhythms, volume expectations, and operational priorities. Understanding how these segments interact with product classes and regional pricing environments allows teams to allocate go-to-market resources more efficiently and to calibrate product configurations for the right mix of throughput, footprint, and connectivity. Where competitors often publish broad market narratives, this research is built to support granular decision-making without drowning readers in superficial categorization.
A third consideration is the regulatory environment itself. Recent FDA recognition of ISO 17665-1 in December 2024 established a benchmark for documented cycle validation and traceability, while the Quality Management System Regulation that took effect in February 2026 introduced end-to-end sterilization traceability expectations for dental devices. These developments have real procurement implications. They raise the cost of non-compliance and materially increase the appeal of equipment that can generate reliable, auditable sterilization records with minimal manual intervention. In parallel, CDC audit findings from mid-2024 indicated that a significant share of dental practices fail routine spore tests, reinforcing demand for autoclaves with automatic verification and reducing the tolerance for manual, error-prone workflows. Meanwhile, European standards developments have extended harmonized coverage to small steam sterilizers used in dental settings, further raising the baseline for product qualification in key export markets.
Taken together, these forces make the 2026 decision environment unusually sensitive to timing. Teams that wait for the market to settle risk losing ground to rivals who already understand where value is migrating and which product attributes are becoming table stakes. This report is designed to shorten that learning curve and give readers a defensible basis for planning in the coming twelve to twenty-four months.
Report Coverage: From Market Structure to Actionable Intelligence
A high-quality industry study earns its value by converting data into operational clarity. This research is built around that principle, with coverage organized to support both strategic oversight and tactical execution. The report begins with a fully reconciled market sizing framework that links historical performance to forward projections, giving readers a consistent reference for revenue trends, volume implications, and timing of expected growth phases. The forecast architecture is deliberately structured to support sensitivity analysis rather than single-point certainty, so decision-makers can test assumptions against different adoption speeds, regulatory enforcement levels, and capital-budget constraints.
The segmentation architecture is treated as a decision lens rather than a static taxonomy. Product-oriented analysis distinguishes automatic, semi-automatic, and manual configurations and examines how each category performs against workflow complexity, staffing models, and compliance expectations. End-user analysis separates dental clinics, hospitals, and other service environments to reveal how purchasing drivers differ across settings, while regional analysis maps demand patterns to local regulatory intensity, practice density, and investment capacity. For executives who need to decide where to prioritize channel investment or product specialization, this layered structure provides a practical roadmap without exposing the full quantitative splits in isolation.
Beyond sizing and segmentation, the report delivers a competitive landscape assessment that goes beyond nameplate recognition. The analysis examines how leading manufacturers are differentiating through cycle design, chamber volume, water and energy efficiency, digital monitoring, and cloud-connected service support. The report also traces recent product activity to show how incumbents are responding to the same compliance and workflow pressures shaping buyer demand. This approach allows readers to benchmark their own positioning, identify gaps in value propositions, and anticipate where competitive intensity is likely to intensify.
Operational coverage extends into procurement and deployment considerations that often get overlooked in high-level market summaries. The report addresses how validation documentation, cycle reliability, maintenance support, and remote-service capabilities influence the total cost of ownership over the equipment lifecycle. By integrating these factors with the broader demand narrative, the study helps purchasing teams evaluate options on more than initial price and helps manufacturers understand which service and software capabilities are becoming monetizable differentiators.
Competitive Landscape: Differentiation Shaping the Next Cycle
The market’s competitive structure reflects a broad spread of regional manufacturing strengths and product philosophies, but it is increasingly defined by a few recurring battlegrounds: automation, traceability, and workflow integration. The companies profiled in this research illustrate how those battlegrounds are translating into product strategy.
Tuttnauer has emphasized tabletop and bench-top dental autoclaves built around Class B cycles, fast-cycle options, and smart sterilization tracking for clinics. Its July 2024 introduction of the Elara11 autoclave, which added front or top water-fill options and upgradeable pre/post-vacuum cycles, highlights a design philosophy centered on configuration flexibility and procedural control. MELAG Medizintechnik, based in Germany, has pushed a complementary angle with fully automated high-capacity and tabletop sterilizers that emphasize sustainable water and energy use alongside digital monitoring. This positions MELAG as a specialist in efficiency-linked compliance rather than raw throughput alone.
Dentsply Sirona brings scale and integrated workflow thinking to the category, manufacturing dental-specific autoclaves with instrument-processing workflows built into the broader clinical ecosystem. Dürr Dental contributes the Hygoclave series, targeting dental practices with high chamber volumes and cycle reliability, an approach that resonates where throughput consistency is a primary procurement concern. W&H Dentalwerk has focused on smart digital integration and cloud connectivity through its B-type Lina sterilizer series, and its September 2024 launch of the Lina sterilizer Smart Edition reinforced the industry’s movement toward digitally enhanced sterilization efficiency.
In the large-capacity segment, Flight Dental Systems specializes in high-capacity steam sterilizers such as the Clave45+, designed for large dental and lab facilities. Its October 2024 launch of the Clave45+ with closed-door drying demonstrated a continued push toward dry-load reliability and higher-volume throughput. Mocom has pursued a cloud-centric bench-top strategy, with its upgraded B Classic+ featuring full cloud integration for cycle tracking and remote service alerts, a signal that smaller-footprint equipment is increasingly being evaluated as a connected device rather than a standalone appliance.
The Asian manufacturing landscape adds important competitive variation. Tomy Seiko produces ES-series tabletop dental autoclaves certified for high-volume sterilization in dental settings, while Hirayama Manufacturing offers HV-series and HV-Ⅱ dental autoclaves with vacuum drying and color touch-panel controls, an example of how user interface and drying performance are becoming part of product differentiation. Kenz rounds out the competitive field with CS-series dental autoclaves aimed at reliable tabletop clinic use. Outside these core groups, Eschmann Technologies supplies Ses series tabletop autoclaves for dental instrument sterilization, and Biobase has built a presence around cost-effective dental autoclaves with an emphasis on basic sterilization cycles.
What connects these companies is not product similarity but a shared need to adapt to a market where compliance documentation, verification reliability, and digital service capabilities are increasingly priced into purchasing decisions. The report examines where these strategies converge and where they diverge, giving readers a structured view of competitive pressure points rather than a simple company-by-company list.
Regulatory and Compliance Dynamics Redefining Buyer Behavior
Regulatory change has moved from a background risk to a foreground purchase criterion in the dental autoclave market. FDA recognition of ISO 17665-1 created a formal expectation for documented cycle validation and traceability, and the QMSR framework that took effect in 2026 reinforced the need for end-to-end sterilization traceability for dental devices. In practical terms, these developments increase the strategic value of equipment that can produce consistent, auditable records and reduce dependence on manual documentation practices that are vulnerable to inspection failures.
The CDC audit findings published in mid-2024 sharpened this trend by highlighting how widely spore-test compliance can vary across practices. Where a substantial share of dental practices fail routine spore tests, automatic verification becomes more than a convenience feature; it becomes a risk-management investment. That reality is reshaping how buyers evaluate manufacturers. Products that can embed verification into the cycle, surface anomalies quickly, and reduce manual test burden are gaining a structural advantage in procurement discussions, especially in environments where staff time and compliance exposure are both tightly constrained.
In Europe, the updated harmonized standards list for small steam sterilizers used in dental settings has added further clarity to qualification requirements. For exporters and multinational manufacturers, this matters because it affects product acceptance, documentation expectations, and the cost of maintaining market access across regions with different compliance baselines. The report treats these regulatory developments as a dynamic rather than a static backdrop, examining how they influence purchasing cycles, product design priorities, and the competitive weight of traceability-enabled equipment.
Buyer Behavior, Workflow Integration, and Total Cost of Ownership
As sterilization equipment becomes more digitally connected, buyer evaluation is increasingly extending beyond chamber size and cycle time. Practice owners and hospital procurement teams are asking how an autoclave fits into instrument flow, how much staff effort it demands, and how reliably it supports compliance documentation. This has elevated the importance of features such as automated cycle verification, remote alerts, cloud-based tracking, and service integration. In many cases, the purchasing decision is becoming a judgment about operational resilience as much as about sterilization performance.
The report analyzes these buying dynamics across the major end-user environments to show how priorities differ. Dental clinics tend to weigh footprint, cycle speed, and ease of use heavily, especially where space and staffing are constrained. Hospitals and larger facilities place greater weight on throughput consistency, integration with broader sterilization workflows, and service reliability. Other service and support environments introduce additional variability based on usage intensity, regional procurement norms, and equipment utilization patterns. By separating these perspectives, the study helps readers avoid the common mistake of applying one purchasing logic to all customer groups.
Total cost of ownership is likewise treated as a multi-layered concept. Initial price remains relevant, but lifecycle cost now includes validation support, service access, downtime risk, energy and water consumption, and the hidden labor cost of manual documentation or failed verification cycles. In a compliance-heavy environment, those hidden costs can become material. The analysis connects product features to these cost drivers so that procurement and product teams can make more disciplined comparisons across automatic, semi-automatic, and manual configurations.
Positioning This Research for Strategic Execution
This market research is intended to function as a decision framework rather than a passive reference document. For manufacturers, it supports product-roadmap planning by clarifying where compliance-driven demand is most likely to concentrate and which feature sets are becoming differentiating rather than optional. For distributors and channel partners, it helps prioritize market segments and geographies where purchasing intensity, regulatory pressure, and equipment refresh cycles are most aligned. For practice groups and hospital procurement teams, it provides a structured basis for comparing equipment options against long-term operational risk, not just immediate cost.
The study is also built to support scenario planning. Because the forecast period extends through 2032, readers can use the framework to test alternative assumptions about adoption speed, enforcement intensity, and competitive entry. That flexibility is important in a market where regulatory interpretation, practice economics, and digital-service expectations can shift purchase timing quickly. Rather than forcing a single prediction, the report gives decision-makers a defensible structure for evaluating multiple futures.
The insights in this introduction are deliberately framed at the level of strategic direction. The full report contains the detailed segmentation structure, comparative company analysis, regional demand patterns, and product-level evaluations needed to turn those directions into specific action. The macro trajectory, the regulatory context, and the competitive dynamics outlined here establish the rationale for deeper engagement, while the complete dataset and analysis are reserved for the full study.
What to Expect When You Go Deeper
The complete version of this research translates the market narrative into a set of actionable deliverables. Readers can expect a fully developed market-sizing model that connects historical performance with forecast pathways, a segmentation framework that clarifies how product, end-user, and regional categories interact with purchasing behavior, and a competitive assessment that maps company positioning against the features and service models now shaping demand. The report also contextualizes recent product launches and regulatory milestones within the broader sales environment, allowing teams to see not just what changed, but why it matters for near-term planning.
For executives who need to make capital-allocation choices, refine product strategies, or prepare for more stringent compliance expectations, the full analysis provides the granularity necessary to move from general market awareness to specific, defensible decisions. The teaser above is designed to show the analytical discipline behind the study and the strategic relevance it brings to 2026 planning. The detailed intelligence that supports precise segmentation, competitive benchmarking, and procurement-level evaluation is available in the complete report.
For detailed analysis of this topic, please visit the official page: Dental Autoclave Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hot Water Storage Tank Market to Hit $7,565M by 2032 with 4.71% CAGR
By PW Consulting, 2026-09-07
Navigating the Hot Water Storage Tank Market: Strategic Intelligence for 2026 and Beyond
The global hot water storage tank market stands at a pivotal inflection point. As infrastructure modernization, energy efficiency regulations, and evolving consumer expectations reshape the plumbing, heating, cooling, and plumbing (PHCP) landscape, industry leaders must look beyond surface-level trends to understand the structural forces driving volume, value, and competitive positioning. Our latest comprehensive market research report delivers the analytical depth required to navigate the 2026–2032 forecasting horizon with confidence. This overview outlines the strategic architecture of the study, demonstrating how granular execution data, regulatory mapping, and competitive intelligence converge to support capital allocation, product development, and market-entry decisions.
Super-Depth Digital Microscope Market
Macro Trajectory and the 2026 Decision Window
Historical performance from 2020 through 2025 reveals a market that has consistently expanded despite periodic supply chain friction and material cost volatility. The sector crossed the 4.5 billion dollar threshold in the early 2020s and has since maintained a steady upward trajectory, culminating in a 2025 baseline that exceeds 5.5 billion dollars. Looking ahead, the forecast period through 2032 projects a compound annual growth rate of approximately 4.71 percent, translating into a multi-year expansion path that pushes total market value toward the mid-seven-billion-dollar range by the close of the decade. These headline figures establish a foundational growth narrative, but the real strategic value lies in understanding the underlying drivers, regional divergence, and segment-level momentum that will determine which organizations capture disproportionate share during the forecast window.
UV Curable Marking Ink Market
For executives planning 2026 capital expenditure, inventory positioning, and channel strategy, the forecast is not merely a numbers exercise. It is a structural map of where demand will concentrate, which product architectures will gain regulatory tailwinds, and how material science innovations are reshaping warranty economics and total cost of ownership. The report isolates these variables, connecting macro growth to actionable decision nodes.
Three Point Bend Rig Market
Report Architecture: What the Study Delivers
This market research is designed as an operational intelligence toolkit rather than a static snapshot. The document is organized around several interconnected modules that translate high-level market sizing into executable strategy:
- Comprehensive market sizing and forecast modeling covering historical performance and a multi-year projection window, with explicit care taken to present top-line scale without diluting analytical rigor.
- Segment-level breakdowns that map product architectures, end-use applications, and geographic footprints, allowing leadership teams to identify high-velocity corridors and evaluate portfolio alignment.
- Competitive landscape profiling that examines established incumbents and emerging challengers, focusing on product breadth, certification footprints, manufacturing footprints, and recent commercial activity.
- Regulatory and standards mapping that tracks evolving efficiency mandates, potable water certification requirements, and plumbing code amendments influencing design specifications and compliance pathways.
- Material and construction analysis detailing how lining technologies, stainless steel formulations, and corrosion-resistant designs affect durability, warranty structures, and total cost of ownership.
- Distribution and channel dynamics that contextualize how manufacturers, wholesalers, plumbing contractors, and specification-driven commercial projects interact across the value chain.
Each section is structured to feed directly into planning workflows. Market sizing is cross-referenced with segment behavior. Competitive profiles are linked to regulatory exposure and product differentiation. The result is a report that can be used in board presentations, product roadmap reviews, and regional expansion assessments without requiring additional data synthesis.
Competitive Landscape: Incumbents, Positioning, and Recent Activity
The hot water storage tank market operates within a concentrated but differentiated competitive environment. Industry concentration metrics indicate that the top three players collectively command roughly 45.5 percent of market value, while the top five extend that footprint to approximately 65 percent. This concentration reflects the advantage of scale in manufacturing, certified production lines, and established distribution relationships, yet it also leaves meaningful room for specialized manufacturers and regional specialists to compete on customization, certification compliance, and application-specific engineering.
The competitive set spans a broad range of organizational profiles. Major manufacturers such as A.O. Smith Corporation, headquartered in Milwaukee, Wisconsin, and Rheem Manufacturing Company, based in Atlanta, Georgia, continue to anchor broad commercial and residential portfolios with durable tank solutions designed for high-demand applications. Bradford White Corporation, operating from Philadelphia, Pennsylvania, focuses on commercial storage tanks engineered to pair with large-volume water heaters, while State Water Heaters, located in Ashland City, Tennessee, targets restaurant and business environments where consistent hot water supply is a non-negotiable service requirement. Ruud Company, based in St. Louis, Missouri, extends commercial and residential coverage as part of a broader water heating portfolio.
Beyond the large-scale incumbents, a layer of specialized manufacturers competes on certification, configuration flexibility, and material performance. Hanson Tank, located in Los Angeles, California, specializes in ASME HLW certified units with horizontal and vertical configurations and NSF potable water certification. PVI Industries, operating from Piedmont, South Carolina as part of Watts Water Technologies, manufactures commercial storage tanks and related accessories. American Wheatley, based in Tulsa, Oklahoma, supplies glass-lined tanks with capacities reaching up to 5,700 gallons for commercial and industrial uses. Stiebel Eltron, headquartered in Holzminden, Germany with U.S. operations, produces indirect solar and geothermal storage tanks for residential and commercial installations. Vaughn Corporation, in Lubbock, Texas, manufactures lined and thermoplastic tanks for electric, hybrid, and solar applications. Sioux Manufacturing Corporation, from Sioux Falls, South Dakota, produces custom water tanks integrated with water heaters for industrial and commercial use.
Recent commercial activity underscores how actively this field is evolving. PVI Industries exhibited at the 2026 AHR Expo in November 2025, showcasing commercial water heaters and storage tank solutions. Stiebel Eltron followed with a product catalog release in February 2026, introducing the new SHC 6 mini tank model for domestic hot water storage, and then returned to the AHR Expo in April 2026 to highlight its range of indirect storage tanks. These moves illustrate a market where product refreshes, event-driven visibility, and application-specific introductions are central to maintaining relevance and capturing specification-driven demand.
Regulatory and Standards Dynamics: Efficiency, Certification, and Compliance
Regulatory change is no longer a peripheral concern in this market; it is a design constraint and a competitive differentiator. U.S. DOE regulations, as of October 2026, require at least 96 percent thermal efficiency for instantaneous water heaters and have tightened standby loss limits for storage units. These requirements place a direct premium on insulation performance, heat retention engineering, and system-level integration, rewarding manufacturers that can demonstrate measurable efficiency gains without compromising reliability or footprint constraints.
Certification and code compliance further shape procurement behavior. Hot water storage tanks exceeding 120 gallons operating pressure must comply with ASME HLW Section IV and NSF 61 standards for potable water, a requirement that influences manufacturing qualification, testing protocols, and downstream specification acceptance. The International Plumbing Code adds another layer, requiring third-party certification and safety devices such as dip tubes and vacuum relief valves for all hot water storage tanks. Together, these standards create a compliance environment where certification breadth, documentation rigor, and product transparency directly affect win rates in commercial and municipal projects.
For strategy teams, the regulatory landscape is best understood as a moving target that rewards early alignment. Manufacturers that proactively update product lines, secure necessary certifications, and communicate compliance advantages in sales collateral are better positioned to capture specification-led demand and reduce project-cycle friction.
Material Innovation and Construction Economics
Material selection has become a decisive factor in tank durability, warranty economics, and long-term operating cost. Stainless steel tank linings, including duplex stainless formulations such as AquaPLEX, are increasingly used in commercial hot water storage tanks to eliminate anode rods and support extended warranty periods, with 15-year warranties becoming a meaningful benchmark in certain commercial segments. This shift reflects a broader industry move toward reducing maintenance burden and improving lifecycle value, especially in applications where service interruptions or corrosion-related failures carry high operational costs.
At the same time, glass-lined or cement-lined construction remains a standard approach for ensuring corrosion resistance in potable water systems. The coexistence of advanced stainless approaches and established lining methods indicates a segmented material landscape in which the optimal choice depends on application severity, water chemistry, warranty expectations, and total cost of ownership calculations. The report examines these trade-offs in context, linking material decisions to segment suitability, certification pathways, and competitive differentiation.
Segmentation Currents: Type, Application, and Regional Momentum
The market’s structure is defined by the interplay of product type, end-use application, and regional demand patterns. Across product architectures, electric storage tanks represent a substantial share of market value, followed by gas storage tanks, with solar and heat pump storage tanks forming a smaller but strategically important portion of the mix. This distribution reflects both legacy adoption patterns and the growing relevance of hybrid and renewable-integrated systems as efficiency mandates tighten and customer expectations shift toward lower operational costs.
In application terms, residential demand forms the largest portion of market value, supported by replacement cycles, housing activity, and homeowner investment in reliability and efficiency. Commercial applications constitute a significant second tier, driven by restaurants, hospitality, healthcare, and other high-demand environments where consistent hot water supply is central to service quality. Industrial applications, while smaller in total value, remain important for specialized configurations and larger-capacity systems.
Regionally, North America represents the largest geographic concentration of market value, reflecting mature infrastructure, strong PHCP distribution networks, and ongoing retrofit and replacement activity. Europe follows as a major market, with Asia Pacific contributing a substantial additional share, and Latin America and the Middle East and Africa representing smaller but strategically relevant corridors for expanded presence and localized product strategies. The report examines these regional dynamics not as static percentages, but as operating environments with distinct specification practices, channel structures, and competitive intensity.
Strategic Implications for 2026 Planning
Translating market intelligence into 2026 action requires aligning product, compliance, and commercial strategy with where value is actually being created. Several strategic themes emerge from the study’s framework:
- Efficiency-aligned product development: With standby loss limits tightened and thermal efficiency expectations elevated, product roadmaps should prioritize insulation performance, heat retention, and system integration features that can be documented and validated for specification-sensitive buyers.
- Certification as a commercial asset: ASME HLW, NSF 61, and third-party certification requirements are not merely compliance hurdles; they are procurement enablers. Manufacturers that streamline certification pathways and communicate compliance clearly can reduce friction in commercial and municipal selling cycles.
- Material strategy and warranty positioning: The shift toward duplex stainless linings and extended warranty claims signals an opportunity to differentiate on durability and lifecycle cost. Engineering and commercial teams should evaluate how material choices affect warranty economics, service expectations, and segment fit.
- Portfolio alignment with demand concentration: Given the scale of residential and commercial applications and the distinct requirements of industrial configurations, portfolio planning should consider where to compete on breadth, where to specialize on capacity or application, and where customization creates margin advantage.
- Regional execution priorities: Concentration in North America and Europe does not imply uniform execution. Regional strategies must account for local code environments, distribution structures, and material or certification expectations that influence both product design and go-to-market approach.
These themes are not abstract. They inform inventory planning, specification marketing, channel partner selection, and capital allocation. The report provides the supporting structure to convert these themes into specific planning decisions, with enough granularity to guide team-level execution while preserving a coherent market-level narrative.
Why This Study Matters for 2026 Decisions
In a market defined by regulatory tightening, material evolution, and concentrated yet fragmented competition, broad directional awareness is insufficient. Decision-makers need a source that connects market sizing to competitive realities, compliance requirements, and application-specific demand behavior. This research is built for that purpose. It presents the overall market trajectory, outlines the segment and regional architecture, profiles the companies shaping competitive dynamics, and integrates the regulatory and material developments that will influence product viability and commercial success through 2032.
The full report extends well beyond the strategic frame presented here. It contains the detailed segmentation analysis, company-level competitive mapping, regulatory timeline, material and certification cross-references, and forecast detail that leadership teams require to set 2026 priorities with precision. The overview above is intentionally designed to demonstrate analytical rigor and contextual relevance while directing readers to the complete intelligence package for the data and breakdowns needed to execute.
For organizations planning product development, regional expansion, compliance investment, or competitive positioning in the hot water storage tank market, the strategic value of this study lies in its ability to convert complex market signals into a clear decision framework. The complete report is available through our official market research page, where the full segmentation detail, competitive profiles, and forecast architecture can be reviewed in full.
For detailed analysis of this topic, please visit the official page: Hot Water Storage Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Industrial Safety Gloves Market to Reach $20.52M by 2032, Growing at 7.41% CAGR
By PW Consulting, 2026-09-07
Strategic Imperatives in the Industrial Safety Gloves Market: A 2026 Perspective
The industrial safety gloves market stands at a critical inflection point. As operational hazards evolve and regulatory frameworks tighten, the demand for advanced hand protection has transcended basic compliance to become a cornerstone of workforce safety strategy. For decision-makers navigating the 2026 landscape, understanding the trajectory of this market is not merely an exercise in procurement; it is a strategic necessity that impacts bottom-line risk, operational efficiency, and corporate reputation. PW Consulting's latest comprehensive study on the Industrial Safety Gloves Market offers a detailed roadmap for stakeholders seeking to capitalize on emerging opportunities while mitigating systemic vulnerabilities.
Bearings for Rolling Mills Market
This article serves as an introductory insight into the broader research, highlighting the macro-economic drivers, competitive tensions, and regulatory shifts that define the current environment. However, the true depth of actionable intelligence—specific addressable markets, granular growth vectors, and precise share analyses—resides within the full report. We invite industry leaders to explore the complete dataset to empower their strategic planning.
BOP Control Hose Market
Market Trajectory and Growth Dynamics
The historical resilience of the industrial safety gloves sector is evident in its consistent expansion over the past half-decade. Our analysis tracks revenue movements from 2020 through the base year of 2025, revealing a steady climb in market valuation. Starting from a foundation of 8.7 billion USD in 2020, the market has demonstrated robust momentum, reaching 12.44 billion USD by 2025. This upward curve underscores the inelastic nature of demand for personal protective equipment (PPE) in industrial settings, where safety protocols are non-negotiable.
Heavy Duty Swash Plate Compressor Market
Looking forward, the forecast period spanning 2026 to 2032 projects a continuation of this growth trajectory. The market is anticipated to expand from 13.53 billion USD in 2026 to 20.52 billion USD by 2032. This progression reflects a Compound Annual Growth Rate (CAGR) of 7.41 percent over the forecast horizon. Such growth is not uniform; it is driven by specific catalytic factors that vary across industrial verticals and geographic zones. The full research delineates these variations with precision, offering a nuanced view of where capital allocation will yield the highest returns. Stakeholders requiring specific volume projections by segment will find the detailed segmentation analysis indispensable for budgeting and capacity planning.
The aggregate revenue figures mask significant underlying shifts in consumption patterns. While the top-line numbers indicate health, the distribution of value across different product types and application sectors tells a more complex story. For instance, the balance between traditional latex solutions and synthetic alternatives is shifting, influenced by both performance requirements and supply chain economics. Similarly, the application landscape is diversifying as industries such as automotive and construction adopt specialized hand protection standards. To understand exactly how these segments contribute to the total market value and their respective growth rates, access to the segmented data is essential.
Industry Dynamics and Disruptive Forces
The market does not operate in a vacuum. Several dynamic forces are currently reshaping the competitive landscape and influencing strategic decisions for manufacturers and buyers alike. Understanding these dynamics is crucial for anticipating market movements in 2026 and beyond.
Regulatory Evolution and Compliance Standards
Regulatory bodies are actively refining the standards that govern hand protection. In November 2024, the International Safety Equipment Association (ISEA) announced an updated ANSI/ISEA 105-2024 standard for hand protection classification. This update introduced a new pentagon-shaped pictogram designed to clearly display ratings for abrasion, cut, and puncture resistance directly on glove labels. This visual standardization aims to reduce confusion and ensure that workers select the correct protection for specific hazards.
Compliance with these standards is increasingly tied to legal obligations. The U.S. Department of Labor's OSHA requires employers to address hand protection for workers exposed to hazards under regulations 1910.138(a) and (b). While the ANSI/ISEA 105-2024 standard itself is voluntary, it is referenced in OSHA requirements for appropriate hand protection, effectively making adherence a de facto necessity for compliance in many jurisdictions. Companies must ensure their product lines meet these updated classification criteria to maintain market access and avoid regulatory friction. The full report provides a detailed mapping of how these regulatory changes impact product categorization and labeling requirements across different regions.
Raw Material Volatility and Supply Chain Risks
Cost structures within the industrial safety gloves market are under pressure from raw material fluctuations. Inputs such as latex, nitrile, and various polymers are subject to price volatility that directly affects production margins. The most acute impact of these fluctuations is being felt in Asia-Pacific manufacturing hubs, where a significant portion of global production capacity is concentrated.
Specific material segments have faced exceptional stress. For example, Nitrile Butadiene Rubber (NBR) prices rose sharply due to geopolitical tensions in West Asia. Industry supply chain reports from 2025 indicate that these conflicts impacted production costs by up to 70 to 80 percent for some manufacturers. Such spikes force difficult decisions regarding pricing strategies, supplier diversification, and inventory management. Companies that fail to adapt to these cost pressures risk margin erosion or supply interruptions. Our research examines the correlation between raw material indices and final product pricing, offering insights into cost mitigation strategies that leading players are employing. Specific cost modeling data is available in the full document.
Innovation and Product Launches
In response to these challenges, key market participants are accelerating innovation cycles. Midas Safety, for instance, launched its new CutXprt ISO D, ASTM A4 Series gloves in June 2025. This line represents a groundbreaking approach to cut-resistant PPE designed specifically for medium-risk tasks, signaling a trend toward specialized protection rather than generic solutions.
Simultaneously, there is a push toward material safety and alternatives. Wadi Surgicals announced the launch of India's first accelerator-free nitrile gloves under its Enliva brand in May 2025, certified under EN 455 and EN ISO 374. This development addresses health concerns related to chemical accelerators in glove manufacturing. Furthermore, INTCO Medical entered the global market in May 2025 with proprietary Syntex synthetic disposable latex gloves, offering an alternative to traditional natural latex products. These launches highlight the market's movement toward higher performance, safety, and material diversity. The report catalogs these developments and assesses their potential impact on market share and consumer preference.
Competitive Landscape and Market Concentration
The industrial safety gloves market exhibits a moderate to high level of concentration among top players. Our analysis indicates that the top three companies hold a Combined Revenue Share (CR3) of 54.2 percent, while the top five entities command a CR5 of 61.8 percent. This concentration suggests that established incumbents possess significant leverage in terms of distribution networks, brand recognition, and R&D capabilities. However, the remaining market share is distributed among a diverse array of specialized manufacturers and regional players, creating a dynamic environment where niche innovation can still capture significant value.
Key Market Participants
The competitive field is populated by companies with distinct strategic focuses and geographic footprints. Understanding the positioning of these key entities is vital for benchmarking and partnership considerations.
- Superior Glove: Headquartered in Ontario, Canada, this company has engineered safety gloves and sleeves since 1910. Their portfolio emphasizes specialized industrial hand protection and maintains key certifications such as UKCA and CE, positioning them as a trusted provider for rigorous industrial environments.
- Magid Glove & Safety: Based in the United States, Magid focuses on work gloves and cut-resistant gear tailored for industrial PPE applications. Their product range supports various operational needs where hand safety is paramount.
- Ansell: With headquarters in the United States, Ansell offers the AlphaTec line and a broad range of chemical-resistant industrial safety gloves. Their extensive industrial range makes them a significant player in sectors requiring robust protection against hazardous substances.
- SHOWA: Operating in the United States, SHOWA is known for its MFT PRO line and general-purpose industrial gloves utilizing microfiber technology. This focus on material innovation allows them to compete on performance and comfort.
- Midas Safety: Located in Canada, Midas Safety manages a vast catalog of 2500 unique SKUs of industrial gloves catering to chemicals, automotive, healthcare, and more. Their breadth of product allows them to serve multiple verticals simultaneously.
- Dursafety: As a top manufacturer based in China, Dursafety produces safety gloves and workwear products, serving as a critical link in the supply chain for cost-effective and high-volume PPE.
- United Glove, Inc.: This United States-based company provides industrial safety gloves and work protection products, contributing to the domestic supply of essential PPE.
- Southern Glove: Also based in the United States, Southern Glove specializes in safety gloves for industrial applications, maintaining a focus on core protective functionalities.
- Youngstown Glove Company: A United States manufacturer focused on industrial safety gloves, serving traditional industrial sectors with established protection solutions.
- Global Glove and Safety Manufacturing, Inc.: Based in the United States, this entity is engaged in the manufacturing of industrial safety gloves, adding to the competitive depth of the North American market.
- Hase Safety Gloves: A German manufacturer offering safety gloves for industrial use, bringing European engineering standards to the market.
- Digitx: Based in Singapore, Digitx is involved in the production and distribution of industrial safety gloves, serving the Asia-Pacific region.
- Pall's Enterprises: Operating in the United States under the Meachmates URL, this company is developing a new generation of industrial safety gloves, signaling innovation in design or material usage.
- Wadi Surgicals: Based in India, Wadi Surgicals produces accelerator-free nitrile gloves under the Enliva brand for industrial and healthcare use, highlighting the convergence of industrial and medical safety standards.
Note that some entities may appear under similar names or branding variations in the market; the report clarifies these relationships and consolidates market share data where appropriate. The strategic interactions between these companies—including pricing wars, patent disputes, and partnership agreements—are analyzed in depth within the full study.
Strategic Value for 2026 Decision-Making
Why does this market research matter for your organization in 2026? The answer lies in the convergence of risk and opportunity. As the market grows toward the 20.52 billion USD mark by 2032, the competition for market share will intensify. Companies that rely on outdated data or generic market assumptions risk misallocating resources.
First, procurement strategies must evolve. With raw material costs fluctuating and regulatory standards updating, the specification of gloves is no longer a static purchase. Buyers need to understand which certifications are becoming mandatory, which material innovations offer long-term cost savings despite higher upfront prices, and how supply chain disruptions in specific regions might affect delivery timelines. The report provides the intelligence needed to negotiate better terms and secure resilient supply lines.
Second, product development teams require insight into where the market is heading. The shift toward specialized protection, as seen in the launch of medium-risk cut-resistant lines, suggests that commoditization of basic gloves may be giving way to value-added solutions. Identifying these whitespace opportunities requires a clear view of unmet needs across applications like automotive and construction. The detailed application analysis in the report reveals exactly where demand is surging and what specifications are driving those purchases.
Third, competitive intelligence is paramount. Knowing the market concentration and the strategic moves of key players like Ansell, Midas Safety, and Superior Glove allows companies to anticipate competitor actions. Whether you are a manufacturer looking to expand your footprint or a distributor seeking exclusive partnerships, understanding the landscape of key companies and their recent developments is critical. The report includes profiles and strategic assessments of these key companies to inform your positioning.
Conclusion and Access to Full Intelligence
The Industrial Safety Gloves Market is poised for significant transformation. The combination of steady macroeconomic growth, regulatory tightening, and material innovation creates a complex environment that demands sophisticated analysis. PW Consulting's latest report provides the comprehensive data and strategic context required to navigate this landscape successfully.
While this article has outlined the broad strokes of market size, growth rates, key dynamics, and major competitors, the specific ratios, regional breakdowns, and granular segment forecasts are reserved for the full publication. These details are the building blocks of a winning strategy. To access the complete dataset, including precise market splits by region, type, and application, as well as the full competitive profiling and raw material cost analysis, please visit the PW Consulting source page. Equip your team with the definitive intelligence needed to lead in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Industrial Safety Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


