



Category: Machinery & Automotive
PW Consulting Tie-down Straps Market Hits $471.12M in 2025, Projects 4.53% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Tie-Down Straps Market: Navigating Growth, Regulation, and Competitive Complexity Through 2032
The global tie-down straps market stands at a critical inflection point. For logistics executives, procurement leaders, and industrial manufacturers, the period from 2026 through 2032 will be defined by tightening cargo securement regulations, evolving material standards, and a competitive landscape that rewards both compliance precision and strategic differentiation. PW Consulting's latest market research report on the Tie-down Straps Market is designed not as a static dataset, but as a decision-making architecture that maps the structural forces shaping this sector. This article previews the strategic depth of the full study, illustrating why forward-looking organizations are embedding these insights into their 2026 planning cycles, capacity allocation models, and competitive positioning frameworks.
Worldwide Egg-Free Dressing Market
Market Trajectory: What Historical Patterns Reveal About the Next Seven Years
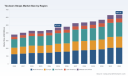
Understanding where the tie-down straps market is headed requires first acknowledging the trajectory it has already traveled. Between 2020 and 2025, the global market expanded from approximately 379.12 million USD to 471.12 million USD, a period that encompassed supply chain realignments, fluctuating freight volumes, and a steady professionalization of cargo restraint practices. The 2023 figure of 425.41 million USD reflected a temporary recalibration, but the subsequent rebound to 437.45 million USD in 2024 and further acceleration to 471.12 million USD in 2025 signals renewed momentum anchored in infrastructure investment, modal transport growth, and institutional demand for standardized load securement systems.
Worldwide Airless Tubes Market
The forecast horizon projects continued expansion, with the overall market size anticipated to reach 480.23 million USD in 2026 and climb to 637.57 million USD by 2032. The compound annual growth rate during this forecast period is estimated at 4.53 percent, a rate that is neither explosive nor stagnant, but rather indicative of a mature, structurally growing market where incremental gains are driven by regulatory tightening, replacement cycles, and geographic demand rebalancing rather than sudden volume shocks. This trajectory matters for strategic planners because it suggests that revenue opportunities will be captured not by speculative entry, but by disciplined positioning across product types, application verticals, and compliance-certification pathways. The full report decomposes the historical baseline from 2020 through 2025 and maps the forecast arc from 2026 through 2032 with a granularity that allows teams to test sensitivity assumptions around freight volume recovery, replacement demand, and regulatory adoption curves.
Ceramic UV Printer Market
Why the 2026 Decision Window Demands a Structured Intelligence Framework
The year 2026 functions as a strategic hinge for the tie-down straps industry. By this point, multiple regulatory frameworks have matured from draft guidance to operational enforcement expectations, material standards have been refined to reflect UV resistance, tensile performance, and elongation limits, and competitors have adjusted their portfolios to align with regional certification requirements. For enterprises making sourcing, pricing, channel, and product development decisions in 2026, the cost of relying on fragmented secondary sources is rising. Incomplete visibility into how strap types align with specific transportation modalities, how regional certification regimes create cross-border friction, and how raw material compositions influence lifecycle durability can translate into compliance gaps, inventory misallocation, or competitive exposure.
The PW Consulting research treats 2026 not as an isolated snapshot but as the launch point of a seven-year forecast that integrates historical calibration with forward-looking scenario logic. The report is built to support three core decision functions: first, evaluating whether demand expansion is broad-based or concentrated in specific application channels and product architectures; second, determining how regulatory divergence between American and European standards shapes sourcing, labeling, and export strategy; and third, mapping competitive intensity so that pricing, differentiation, and partnership choices are grounded in structural rather than cyclical reasoning. The full study delivers the segmented breakdowns necessary to perform these assessments, while this preview establishes the strategic rationale for acquiring that level of precision.
Market Dynamics: Regulation, Materials, and the New Compliance Calculus
The tie-down straps market is governed by a dense set of operational standards that directly influence product design, labeling, procurement specifications, and channel eligibility. One of the most consequential dynamic shifts is the emphasis on permanently marked working load limits and the alignment of cargo securement products with U.S. Department of Transportation and Federal Motor Carrier Safety Administration identification requirements. This regulatory posture elevates compliance from a documentation exercise to a product-construction imperative. Straps that cannot demonstrate manufacturer-assigned working load limits in a durable, legible, and standards-aligned format risk exclusion from professional transportation procurement channels, regardless of price or availability.
A parallel dynamic is the divergence between American and European certification regimes. In the United States, ratchet straps commonly referenced under WSTDA-T-1 expectations are associated with a minimum 3:1 safety factor and operate in conjunction with FMCSA and CVSA load restraint regulations. In Europe, EN 12195-2 standards generally apply a 2:1 safety factor. For companies operating across transatlantic supply chains or sourcing for mixed-region distribution, this divergence is not a trivial technical nuance; it shapes design specifications, testing protocols, inventory segmentation, and even marketing claims. The strategic implication is that market participants cannot assume a single product architecture will satisfy all regulatory environments without compromising either compliance fidelity or cost structure.
In air cargo applications, the compliance environment introduces additional constraints. Synthetic webbing tie-down straps used in aircraft transportation must meet burn rate and elongation limits under FAA TSO C-172, and certification expectations for truck, trailer, and air cargo securement frequently reference FAA TSO C-172 alongside DOT and WSTDA considerations. These requirements segment the market by application intensity: a strap suitable for general freight may not satisfy the performance thresholds required for regulated air cargo securement, and the margin for error in that vertical is narrower. For decision-makers, this means that application-specific compliance is a differentiator with direct commercial consequences, not a background compliance detail.
Material dynamics reinforce the regulatory story. High-strength polyester webbing with UV resistance and reinforced stitching has become the primary material benchmark in ratchet tie-down straps because it offers superior tensile strength and corrosion resistance relative to polypropylene alternatives. This material preference influences lifecycle durability, exposure to environmental degradation, and long-term cost-per-use calculations. When procurement teams evaluate total cost of ownership rather than unit price alone, material specification becomes a strategic variable. The research integrates these material considerations into its type and application analysis so that organizations can assess where premium constructions are justified by regulatory or operational demands, and where standardization can reduce complexity without compromising performance.
Regulatory and Standards Reality as a Competitive Filter
Regulations in this sector function as both a barrier and a filter. They create cost and engineering requirements that can limit casual or low-specification entry, while simultaneously rewarding manufacturers and distributors that can consistently document compliance, maintain certification alignment, and communicate working load limits clearly. The presence of multiple overlapping standards—DOT and FMCSA identification expectations, WSTDA-T-1 safety factor expectations, EN 12195-2 European parameters, FAA TSO C-172 burn and elongation limits, and ASTM B30.9 references in broader rigging contexts—means that competitive advantage increasingly depends on standards fluency. Enterprises that can align product lines with the standards most relevant to their target geographies and applications reduce friction in procurement evaluations and expand their addressable buyer pool.
This filtering effect also shapes M&A, partnership, and channel strategy. Organizations seeking to enter new regions or serve new transportation verticals may find that the fastest route to credibility is through product lines already aligned with recognized certification regimes rather than through generic repositioning. The report examines these dynamics as part of the broader market environment, highlighting where compliance complexity favors consolidation, where it incentivizes specialized product architectures, and where it creates negotiation leverage for suppliers who can demonstrably meet region-specific requirements.
Competitive Landscape: Differentiated Players in a Moderately Concentrated Market
The tie-down straps market is moderately concentrated. CR3 stands at 30.0 percent, and CR5 at 45.0 percent. This level of concentration suggests that while leading participants command meaningful share, the market still accommodates a broad field of regional manufacturers, specialized distributors, and application-focused producers. In practical terms, this means competitive strategy cannot rely solely on scale; it must also address certification breadth, product-range completeness, material quality, customization capabilities, and regional compliance readiness.
Several companies illustrate the diversity of strategic positioning within this landscape. Ancra International LLC, headquartered in California, is recognized as a leading provider of cargo restraint systems including ratchet tie-down straps certified to FAA TSO C-172, DOT, WSTDA, and ISO standards for truck, trailer, and air cargo securement. Its profile underscores the premium placed on multi-standard certification, particularly where air cargo and professional transportation overlap. Horizon Global Corporation, based in Michigan, specializes in commercial cargo and truck tie-down straps meeting FMCSA, CVSA, and WSTDA specifications for load restraint in transportation, reflecting a focus on road-transport compliance ecosystems. Keeper Products, located in Wisconsin, manufactures heavy-duty ratchet tie-down straps for cargo control in various lengths and widths with reinforced polyester webbing, emphasizing material durability and product range flexibility.
Nite Ize Inc, based in Colorado, produces ratchet tie-down straps and related cargo control accessories compliant with industry safety standards including WSTDA, positioning itself within the broader cargo-control accessories segment rather than solely as a strap manufacturer. Erickson B Manufacturing Ltd, operating from Ontario, Canada, supplies custom ratchet tie-down straps and cargo control products for North American markets, built to WSTDA and ASTM B30.9 standards, which signals a regional customization orientation alongside standards alignment. Dolezych GmbH & Co. KG, headquartered in Dortmund, Germany, is a European manufacturer of load-securing straps including ratchet tie-downs certified to EN 12195-2 and related lifting standards, representing the European compliance pathway and its associated product architecture. Macs Custom Tie-Downs, based in the USA, produces U.S.-made ratchet tie-down straps and axle systems for professional transportation and towing, emphasizing safety and custom configurations.
Rhino USA Inc operates as both distributor and manufacturer of heavy-duty tie-down straps and ratchet systems for cargo, vehicles, and off-road use with high WLL ratings, blending distribution reach with product performance claims. Kinedyne Corporation is recognized as a global leader in cargo control products, including 2-inch and 3-inch ratchet tie-down straps rated up to 5,400 lbs WLL, indicating a focus on higher-capacity product lines and broad operational recognition. Wristrong / WRIGGING, based in China, produces ratchet tie-down straps compliant with ASTM B30.9, WSTDA T-1, and EN 12195-2 standards for global export, reflecting a cross-standard manufacturing orientation designed for international distribution. XiangleRatchetStrap, also based in China, is a factory specializing in OEM/ODM ratchet tie-down straps for cargo, motorcycle, and powersports applications with custom lengths and certifications, highlighting the customization and end-use specialization path.
Additional participants further broaden the competitive field. Cargo Equipment Corporation, an Illinois-based WSTDA member, manufactures ratchet straps, cam buckle straps, and custom trailer tie-downs made-to-order in the USA, reinforcing the U.S.-based custom manufacturing segment. US Cargo Control, based in the USA, provides ratchet straps, E-Track systems, and flatbed tie-down products meeting WSTDA, FMCSA, and DOT regulations, extending into complementary cargo control systems beyond straps alone. PowerTye, headquartered in California, has made USA-manufactured ratchet tie-down straps for over 30 years, used in general cargo, towing, and shipping, illustrating long-standing domestic production continuity. Lift-All Co., Inc., based in the USA, manufactures tie-down straps and cargo nets as part of its rigging and load securing product line, demonstrating integration across load-control product categories.
Strategic Positioning Lessons from the Competitive Set
Taken together, these companies illustrate that competitive advantage in the tie-down straps market is multidimensional. Some participants compete on multi-standard certification and air cargo relevance; others compete on regional compliance specialization, material quality, high working load limits, customization capability, or product-range breadth across straps, buckles, and complementary cargo control accessories. The presence of both U.S.-based and Chinese manufacturers with different certification orientations also indicates that sourcing strategy is no longer a simple price-versus-country decision; it is a compliance-versus-applicability decision. The full report segments the competitive environment in a way that helps readers determine which competitors are most relevant to their target segments and what capabilities they must match or exceed to gain traction.
Recent Industry Developments and Their Strategic Implications
Recent company-level activity confirms that the market is actively recalibrating product portfolios, certification alignment, and catalog breadth. In October 2025, Macs Custom Tie-Downs released an updated professional tie-down systems catalog highlighting U.S.-made ratchet straps, axle straps, and wheel nets for transportation safety. This move signals a deliberate emphasis on domestically manufactured professional-grade systems and suggests that messaging around origin, safety, and application specificity is becoming more prominent in procurement-facing materials.
In March 2026, XiangleRatchetStrap published a 2026 new products catalog with updated ratchet strap SKUs, cam buckles, and custom configurations for cargo securement. The update points to continued product-line expansion in the OEM/ODM space, particularly where custom lengths and application-specific configurations are in demand. In May 2026, Wristrong launched North American-compliant ratchet tie-down straps under ASTM B30.9 and WSTDA standards, featuring reinforced polyester webbing. This launch is strategically notable because it showcases the deliberate alignment of export-grade products with North American compliance expectations, a move that can open doors to distributors and procurement channels that prioritize documented U.S.-relevant standards.
In February 2026, Kinedyne Corporation updated its catalog for 2-inch ratchet straps designed for flatbed tie-downs with working load limits up to 3,335 lbs. The update reflects ongoing refinement of capacity-specific product lines for flatbed and heavy-load applications, reinforcing the trend toward differentiated specifications rather than uniform product offerings. Collectively, these developments indicate that innovation in the tie-down straps market is less about radical product reinvention and more about standards alignment, capacity gradation, material reinforcement, and catalog clarity. For buyers and competitors alike, the implication is that the market is becoming more specification-sensitive, and specification sensitivity rewards manufacturers and distributors that can communicate performance parameters clearly and consistently.
Report Architecture: What the Full Study Enables
The complete PW Consulting market research report expands these dynamics into an actionable intelligence framework. Rather than presenting a single aggregate narrative, the study is organized to support operational and strategic use cases across sourcing, product planning, sales strategy, and risk assessment. The report integrates historical performance data from 2020 through 2025 with a forecast spanning 2026 through 2032, allowing readers to examine not only where the market has been, but how growth is expected to distribute across key structural dimensions.
A core strength of the research is its segmentation logic. The report analyzes the market by region, by type, and by application, enabling readers to identify where demand expansion is most pronounced, where product architectures align with distinct end-use requirements, and where regulatory or operational considerations create natural segmentation. This structure is essential because aggregate market size alone cannot inform practical decisions. A company focusing on flatbed cargo restraint, for example, requires a different interpretive lens than a supplier targeting aircraft cargo securement or individual user demand. The full study provides the segmented intelligence necessary to align product roadmaps and commercial strategies with the most relevant demand pools.
The competitive analysis section moves beyond company listings to contextualize strategic posture. It examines how leading participants differentiate through certification breadth, material construction, working load limit ratings, customization, regional compliance orientation, and product-range completeness. By mapping these differentiators against market concentration dynamics, the report helps readers evaluate where competitive intensity is highest, where white space may exist, and what capabilities are necessary to compete credibly in targeted segments. This is particularly useful for organizations assessing market entry, expansion, or repositioning, because it converts a crowded vendor landscape into a structured competitive map.
Practical Use Cases for Procurement, Product, and Channel Strategy
The research is designed to support multiple internal workflows. For procurement teams, it provides context for evaluating supplier claims around working load limits, standards compliance, and material durability, helping organizations distinguish between price-driven proposals and specification-aligned value propositions. For product and engineering leaders, the segmentation and standards discussion supports decisions about polyester versus alternative webbing constructions, reinforcement approaches, and capacity gradation across product families. For commercial and channel teams, the report's regional and application orientation helps clarify where certification alignment, origin messaging, and product-range completeness are most likely to influence purchasing decisions.
The study also supports risk and scenario planning. Because the market is shaped by regulatory divergence, material performance expectations, and moderate concentration, organizations benefit from understanding how changes in enforcement practice, certification expectations, or raw material preferences could shift competitive dynamics. The forecast structure allows readers to explore how sustained freight growth, replacement-cycle timing, or regional demand rebalancing could affect revenue planning over the 2026 to 2032 period. By integrating these considerations into a single research framework, the report reduces the need to aggregate scattered sources and enables more coherent strategic discussion across functions.
Conclusion: Turning Market Intelligence into 2026 Advantage
The tie-down straps market is not defined by dramatic volatility, but by the cumulative effect of regulatory clarity, material standards, application-specific performance demands, and competitive differentiation across a moderately concentrated field. That makes it a market where information quality directly influences decision quality. Organizations that understand how certification regimes diverge, where demand is expanding, which product types align with which applications, and how competitors are positioning around capacity ratings, material construction, and compliance documentation will be better equipped to allocate resources, negotiate with suppliers, and plan product development with confidence.
The full PW Consulting Tie-down Straps Market research report delivers the segmented depth, competitive context, and forward-looking forecast needed to support those decisions. It is built to translate macro trajectory into operational insight, so that strategy teams can move from general awareness to targeted action. For decision-makers preparing for the 2026 planning cycle and the years that follow, the opportunity is not merely to observe market growth, but to use rigorous intelligence to capture it more efficiently, more compliantly, and more competitively.
For detailed analysis of this topic, please visit the official page: Tie-down Straps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Gases Market Hits $14.51M in 2025, Projected to Hit $24.88M by 2032 at 8% CAGR
By PW Consulting, 2026-09-07
Beyond Breath: Strategic Intelligence for the Medical Gases Market 2026–2032
The medical gases sector is no longer a passive utility backbone of healthcare delivery. It has evolved into a strategically contested, highly regulated, and technologically dynamic industry where supply resilience, clinical integration, and sustainability mandates intersect. As hospital networks modernize aging infrastructure, home care expands beyond traditional boundaries, and pharmaceutical manufacturing demands ever-higher purity standards, decision-makers require more than historical summaries. They need a structured, forward-looking intelligence framework that translates macro-trends into executable strategy. Our latest Medical Gases Market study delivers exactly that: a rigorous, data-grounded assessment designed to inform capital allocation, competitive positioning, and operational readiness throughout the 2026–2032 forecast horizon.
Screw Cold Heading Machine Market
A Market in Structural Expansion, Not Cyclical Fluctuation
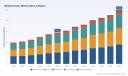
The industry has demonstrated consistent, compounding growth over the past half-decade, moving from a baseline just under ten billion USD in 2020 to a trajectory that places the market firmly above fifteen billion USD in 2026. This is not merely recovery momentum following pandemic-era supply pressures; it reflects durable shifts in patient acuity profiles, decentralized care models, and the expanding clinical reliance on high-purity respiratory and specialty gas formulations. Our baseline year of 2025 anchors a five-year historical analysis that isolates real volume and pricing drivers from temporary distortions, while the forecast period extends through 2032 to capture infrastructure lead times, regulatory adoption curves, and equipment refresh cycles.
Video Editing Computer Market
At an anticipated compound annual growth rate of 8.0 percent across the forecast window, the sector will add substantial cumulative value, with the market scale progressing steadily toward the mid-twenties billion USD range by 2032. Such a growth profile rewards operators who can simultaneously manage supply continuity, optimize distribution economics, and align product portfolios with emerging clinical protocols. It also elevates the strategic importance of anticipating where demand will concentrate, how procurement frameworks will evolve, and which technical capabilities will separate resilient incumbents from vulnerable followers.
Worldwide Automated Retailer Turnstile Market
Why This Study Matters for 2026 Decision-Making
Entering 2026, executives face a convergence of pressures that make generic market narratives insufficient. Capital budgets are being evaluated against tighter returns thresholds, hospital engineering teams are confronting code-driven infrastructure renewal timelines, homecare providers are scaling remote monitoring and portable therapy platforms, and pharmaceutical producers are negotiating purity, traceability, and on-site generation requirements with heightened scrutiny. In this environment, strategic planning requires granular visibility into demand segmentation, competitive capability mapping, regulatory sequencing, and supply chain bottleneck forecasting. The study is built to support each of these workstreams without relying on superficial aggregation.
Rather than presenting a single composite figure and stopping there, the analysis decomposes the market along clinically and commercially meaningful dimensions. It examines how therapeutic applications, diagnostic workflows, and pharmaceutical manufacturing requirements each shape volume, purity specifications, delivery formats, and contract structures. It also evaluates how product categories ranging from pure gas supplies to specialized gas mixtures and associated medical gas equipment interact to form bundled procurement opportunities and integrated service relationships. Regional dynamics are treated as structural factors—reflecting differences in hospital modernization pace, home-care reimbursement evolution, regulatory harmonization status, and distribution network maturity—so that leaders can calibrate expansion, partnership, and capacity decisions to the realities of each geography rather than applying a uniform global template.
What the Report Delivers: Operational Content for Strategy Teams
The study is structured to function as a working reference for strategy, procurement, engineering, and commercial teams. It moves beyond descriptive overviews to provide actionable analytical modules that can be integrated directly into internal planning processes:
- Historical reconstruction and baseline validation covering the 2020–2025 period, with explicit identification of the demand shifts, pricing behaviors, and supply events that shaped each year
- Forward projections through 2032 built on transparent assumptions for clinical adoption, infrastructure investment cadence, equipment replacement cycles, and supply-side capacity additions
- Segment-level analysis that separates therapeutic, diagnostic, and pharmaceutical manufacturing demand patterns, highlighting differences in purity thresholds, delivery frequency, contract models, and technology sensitivity
- Product-type evaluation spanning pure gases, gas mixtures, and medical gas equipment, with attention to how bundle offerings, service contracts, and equipment-integrated monitoring change customer economics
- Regional structural assessment that frames North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa in terms of healthcare infrastructure maturity, regulatory alignment, distribution density, and growth sequencing rather than static share rankings
- Competitive capability benchmarking that maps incumbent strengths in production scale, distribution reach, hospital pipeline systems, on-site generation, IoT-enabled monitoring, homecare devices, and sustainability-certified supply options
- Regulatory and standards tracking that connects FDA guidance evolution, EU GMP and distribution practice expectations, and U.S. piping and installer certification frameworks to practical compliance timelines and operational implications
- Supply chain and raw material considerations, including helium availability dynamics linked to federal system transitions and private ownership changes, and their downstream effects on imaging support gases and specialized breathing mixtures
- Strategic scenario framing that helps leadership stress-test capacity planning, pricing strategies, partnership structures, and geographic prioritization against alternative demand and regulatory pathways
Each module is designed to support concrete decisions: whether to invest in on-site generation versus bundled distribution, how to position portable concentrator and homecare offerings as hospital discharge patterns shift, where to prioritize IoT-enabled monitoring and smart gas management as a differentiator, and how to align product certifications and traceability practices with evolving regulatory expectations.
Competitive Dynamics and the Center of Gravity in the Industry
The market remains structurally concentrated, with a small group of multinational and regional leaders commanding a disproportionate share of production, distribution, and integrated service capabilities. Our analysis examines the strategic posture of core companies whose operations define the competitive baseline. Air Liquide Healthcare continues to build its position around a full-spectrum offering that spans medical oxygen, nitrous oxide, and medical air, complemented by hospital pipeline systems, portable oxygen concentrators, and low-carbon ECO ORIGIN supply concepts designed for both hospital and homecare environments. Linde Healthcare competes through high-purity gas provisioning, on-site generation plant solutions, advanced delivery architectures with IoT monitoring, and comprehensive hospital gas management services that emphasize operational reliability and digital integration.
Air Products and Chemicals Inc. leverages its extensive North American distribution network to supply medical oxygen, nitrous oxide, medical air, and specialty gas mixtures, while Airgas Inc. reinforces reach through a large physical footprint and truck fleet supporting medical-grade oxygen, liquid nitrogen, nitrous oxide, and related equipment distribution. The Messer Group emphasizes cost-effective medical gases and regionally optimized distribution networks across Europe and Asia, aligning price competitiveness with localized service density. Taiyo Nippon Sanso Corporation contributes manufacturing depth for medical gases and associated equipment with global supply capabilities, and Mathieson Tri-Gas Inc. operates as a focused producer and distributor of medical gases and equipment serving specialized customer needs.
Recent corporate activity reflects a clear strategic emphasis on capacity expansion, product modernization, and digital and sustainability differentiation. In early 2025, Linde plc announced a substantial investment to expand medical gas production facilities across North America and Europe, signaling a response to sustained demand and the need for supply-side scale. Air Liquide Healthcare advanced a compact portable oxygen concentrator with improved flow rate control and battery life, directly addressing homecare and emergency service requirements. It also introduced an ECO ORIGIN low-carbon medical gas supply solution covering oxygen, nitrogen, argon, and carbon dioxide with ISO carbon footprint certification, aligning clinical supply with sustainability commitments. Messer Group introduced a smart gas monitoring system integrated with IoT for real-time tracking of medical gas usage and pressure in healthcare facilities, reinforcing the industry’s shift toward connected infrastructure and operational visibility.
Regulatory Architecture and Infrastructure Standards as Strategic Variables
Regulatory and standards developments are not peripheral compliance tasks; they actively shape product qualification timelines, distribution practice requirements, and capital planning for hospital infrastructure. Recent FDA activity includes draft guidance for the Certification Process for Designated Medical Gases, accompanied by conforming amendments to current good manufacturing practice requirements, as well as earlier guidance on medical gases and current good manufacturing practice that established enforceable expectations. In parallel, the EMA’s EU GMP guideline on good manufacturing practice and good distribution practice for medicinal gases provides traceability requirements spanning cylinders, valves, and finished products, reinforcing quality assurance across the supply chain.
On the infrastructure side, medical gas piping systems in U.S. hospitals and clinics must adhere to NFPA 99-2024 and ASSE 6060 standards, with ongoing installer certification workshops continuing through 2026. These standards influence not only hospital engineering timelines but also the competitive positioning of providers that can integrate compliant pipeline design, installation support, and ongoing monitoring into their service models. For strategic planners, the practical implication is straightforward: regulatory sequence and standards adherence affect time-to-market for new product qualifications, the cost of maintaining compliant distribution and storage practices, and the value of partnerships that reduce implementation risk for healthcare facilities.
Segment-Level Forces Shaping Demand and Supply Strategy
Demand patterns across therapeutic, diagnostic, and pharmaceutical manufacturing applications are diverging in ways that require tailored commercial and operational responses. Therapeutic usage continues to anchor core respiratory and life-support requirements, but it is increasingly influenced by homecare expansion, portable device adoption, and hospital discharge planning that shifts certain therapy delivery outside institutional walls. Diagnostic applications depend on reliable gas quality and consistent supply for imaging, laboratory, and procedural environments, making continuity and purity assurance central to customer trust. Pharmaceutical manufacturing demand adds another layer of complexity, with high-purity specifications, traceability expectations, and on-site generation considerations shaping procurement structures and supplier qualification processes.
On the supply and product side, the distinction between pure gases, gas mixtures, and medical gas equipment is strategically significant. Pure gases remain foundational, but their commercial value is increasingly linked to reliability, delivery logistics, and integrated service agreements. Gas mixtures introduce formulation specificity and application tailoring, appealing to diagnostic and specialty clinical needs where precision and consistency carry direct operational importance. Medical gas equipment—encompassing delivery systems, monitoring technologies, concentrators, and pipeline components—creates additional touchpoints for differentiation, particularly as healthcare facilities seek to reduce downtime, improve pressure and usage visibility, and comply with evolving piping and certification standards.
Raw material and supply chain considerations further complicate strategic planning. Helium supply dynamics for MRI support and breathing gas mixtures have been affected by the U.S. Bureau of Land Management Federal Helium System transition to private ownership, following the Messer Americas acquisition completed in mid-2024. This shift underscores how federal asset transitions, private-sector consolidation, and logistics constraints can reshape availability and cost structures for specialized gases that sit behind critical clinical and imaging workflows. Leaders who incorporate such supply-side variables into scenario planning are better positioned to manage risk exposure and negotiate resilient supply arrangements.
Using the Study to Shape 2026 Strategy
The strategic value of this research lies in its ability to convert market complexity into decision-ready structure. For capital and capacity planning, the forecast framework supports evaluation of where production expansion, distribution reinforcement, and equipment portfolio investment will generate the strongest returns across the 2026–2032 window. For competitive strategy, the company profiles and recent development tracking clarify where scale, digital monitoring, homecare device innovation, and sustainability-certified supply are becoming differentiating factors rather than optional enhancements. For regulatory and quality leadership, the integration of FDA, EMA, NFPA, and ASSE developments provides a practical map of compliance sequencing and its operational consequences. For commercial and procurement teams, the segmentation analysis helps align contract structures, service bundles, and delivery models with the distinct requirements of therapeutic, diagnostic, and pharmaceutical manufacturing customers.
Most importantly, the study is designed to preserve analytical integrity while guiding readers toward the full intelligence package. The headline trajectory, growth rate, and structural themes presented here establish the context and credibility of the analysis; the detailed regional breakdowns, application-level splits, product-type decompositions, company capability matrices, and scenario models are reserved for the complete report. That depth is where strategy becomes executable—when leaders can see not only that demand is expanding and competition is intensifying, but exactly how each segment, region, and competitor is positioned to shape value capture over the next several years.
From Insight to Action
The medical gases market is entering a phase in which success will be determined by the quality of strategic foresight, not merely the scale of existing operations. Growth is durable, but it is uneven across applications, regions, and product categories; regulation is tightening, but it rewards prepared organizations with faster qualification pathways and stronger customer trust; and technology is advancing, but its value is realized only when integrated into clinical workflows, distribution economics, and compliance frameworks. Our Medical Gases Market study provides the comprehensive, evidence-based foundation needed to navigate these intersecting forces with confidence.
To access the complete segmentation analysis, competitive benchmarking, regulatory timeline mapping, and scenario-based forecasts that support 2026 planning and beyond, explore the full report and its detailed data modules. The macroeconomic trajectory outlined here is only the starting point; the operational intelligence within the complete study is where strategic advantage is built.
For detailed analysis of this topic, please visit the official page: Medical Gases Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cystoscope Market Hits $1,210.85M in 2025, Projected 6.35% CAGR to 2032
By PW Consulting, 2026-09-07
Strategic Intelligence for the Catheterization Era: Navigating the Cystoscope Market in 2026 and Beyond
The urological endoscopy sector stands at a pivotal inflection point. As healthcare systems globally recalibrate toward value-based care, infection control mandates, and decentralized procedural models, the cystoscope market has evolved from a mature hardware segment into a dynamic arena shaped by single-use innovation, digital imaging integration, and shifting reimbursement architectures. For executives, investors, and clinical operations leaders, understanding the trajectory of this market in 2026 requires more than retrospective revenue tracking; it demands a structured reading of product adoption curves, regulatory clearance patterns, and competitive positioning that will dictate procurement strategies, R&D prioritization, and market entry decisions over the next five years.
Contact Smart Card and Security Chip Market
PW Consulting’s newly released Cystoscope Market research study is designed to meet that exact requirement. This introduction outlines the strategic architecture of the report, demonstrates how macro-market signals are contextualized for actionable decision-making, and illustrates why the 2026–2032 forecast window serves as a critical planning horizon for stakeholders operating across urology, gynecology, and adjacent procedural ecosystems.
Automotive Lighting Aftermarket Market
The 2026 Decision Horizon: Why Timing Matters
The base year of 2025 anchors a historical trajectory that reveals consistent expansion across the 2020–2025 period. Revenue progression from the 2020 baseline through the 2025 close reflects a market that has absorbed pandemic-era procedural backlogs, accelerated adoption of sterile disposable platforms, and responded to tightening hospital infection prevention protocols. The forecast period extending through 2032 projects a compound annual growth rate that underscores sustained, rather than speculative, expansion.
Pre-fill Valve Market
For procurement directors and health-system administrators, 2026 represents the first full planning cycle where single-use cystoscope economics, reprocessing cost comparisons, and outpatient migration patterns can be modeled with post-clearance clinical adoption data. For medtech strategists and venture investors, the forecast window captures the maturation phase of several recently cleared platforms, the anticipated consolidation of imaging-integrated disposable systems, and the reimbursement adjustments that will influence procedure volume incentives. The report’s temporal design aligns analytical outputs with board-level planning calendars, ensuring that metric selection, scenario modeling, and competitive tracking are calibrated to the fiscal and regulatory realities of the current year.
Market Architecture: From Aggregate Signals to Strategic Context
High-level revenue trajectories establish the scale and momentum of the cystoscope segment, but strategic value emerges when those signals are interpreted alongside product-form evolution, procedural setting shifts, and regional demand dispersion. The research framework avoids static snapshots by treating market size as a living indicator of procurement behavior, clinical preference, and capital equipment substitution.
Several structural forces shape the directional read. First, the proportionality shift between reusable and single-use platforms continues to redefine cost-per-procedure calculations. Hospitals and ambulatory surgical centers are increasingly weighing upfront device pricing against downstream sterilization labor, scope repair frequency, and cross-contamination risk exposure. Second, video-enabled and digital-integrated platforms are transitioning from premium differentiators to baseline expectations in both flexible and rigid form factors, compressing the window for imaging-only legacy differentiation. Third, procedural migration toward office-based and outpatient environments is altering volume distribution, influencing device form preference, portability requirements, and integrated visualization needs.
The report contextualizes these dynamics without reducing them to simplistic substitution narratives. Instead, it maps how procurement committees evaluate total cost of ownership, how clinical teams balance workflow efficiency against image quality, and how manufacturers align product roadmaps with clearing pathways and coding environments. The result is a decision-ready architecture that helps readers distinguish between temporary pricing fluctuations and structural adoption shifts.
Competitive Ecosystem: Positioning, Innovation, and Market Concentration
The cystoscope competitive landscape is characterized by a notable concentration of revenue among a defined group of manufacturers, reflecting the capital intensity of imaging integration, the importance of regulatory track records, and the consolidation advantages held by established endoscopy platforms. The report examines the core players not as isolated profiles, but as strategically interdependent actors competing on infection control positioning, procedural versatility, digital workflow compatibility, and single-use economics.
Several companies define the current frontier. Ambu A/S has extended its single-use flexible video cystoscope portfolio with high-definition imaging and expanded procedural indications, reinforcing its position in urology workflows where disposable sterility and rapid turnaround are prioritized. Boston Scientific Corporation continues to emphasize office and operating room usability through single-use flexible platforms that align with infection control mandates and procedural simplicity. Coloplast Group integrates single-use cystoscopes into broader urology portfolios, targeting outpatient and hospital cystoscopy settings with a focus on portfolio synergy and clinical continuity.
KARL STORZ SE & Co. KG maintains a strong footprint in digital flexible cystoscopes and integrated imaging systems, leveraging its heritage in high-definition urology procedures and platform ecosystems. NeoScope Inc. advances compact single-use flexible designs with integrated LED and HD video modules tailored for office-based procedures, addressing the portability and setup-efficiency demands of decentralized care. Olympus Corporation balances reusable and digital cystoscope offerings, including diagnostic and therapeutic urology systems that serve institutions seeking mixed-device strategies. OTU Medical Inc. markets single-use flexible cystoscopes with digital capabilities and regional regulatory alignments, supporting segment-specific adoption pathways.
Richard Wolf GmbH contributes rigid and flexible cystoscopes alongside complementary urology equipment for hospital and clinic environments, preserving traditional form-factor relevance while adapting to digital imaging expectations. Stryker Corporation supplies single-use and reusable cystoscopes with emphasis on minimally invasive urology solutions, aligning device strategy with broader surgical platform integration. UroViu Corporation develops high-definition single-use sterile cystoscopes compatible with portable platforms for office bladder procedures, reflecting the convergence of sterilization, image quality, and mobility requirements. Zenflow, Inc. has introduced a single-use cystoscope with an expanded working channel specification, targeting enhanced visualization and instrument access in urology procedures.
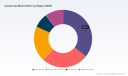
Market concentration metrics indicate that a relatively small set of manufacturers commands a significant share of revenue, a pattern that carries implications for channel dynamics, pricing leverage, and the feasibility of challenger entry. The report translates concentration data into strategic reading: which players control high-margin imaging integration, which segments remain open to differentiated form factors, and how procurement concentration influences negotiation leverage across health systems and group purchasing organizations.
Regulatory Catalysts and Reimbursement Realities
Regulatory clearances and coding environments function as market velocity modifiers. Over recent months, several developments have altered the adoption calculus for single-use and digital cystoscope platforms. In mid-2025, Ambu A/S received expanded regulatory clearance enabling use of its single-use flexible platform in percutaneous nephrolithotomy procedures, marking a notable extension of disposable flexible endoscopy into a procedure domain historically associated with reusable or larger-format instruments. Later in the year, Zenflow, Inc. secured clearance for a single-use cystoscope featuring a substantially larger working channel, a specification that directly addresses instrument passage and procedural efficiency considerations in urology. These clearances do not merely expand product catalogs; they signal regulatory willingness to accommodate single-use architectures in increasingly complex procedural contexts, which in turn influences hospital evaluation criteria and vendor qualification timelines.
Parallel to product clearance, reimbursement architecture shapes procedure economics. The Medicare unadjusted national average payment for relevant cystourethroscopy coding remains a reference point for procedural revenue modeling, with applicable C-codes providing tracking mechanisms that influence how outpatient and ambulatory volumes are measured and reimbursed. For health systems and device strategists, coding stability and payment clarity affect volume forecasts, capital budgeting for disposable inventories, and the attractiveness of office-based procedural expansion. The report embeds reimbursement context within adoption modeling, ensuring that volume assumptions are tested against payment realities rather than clinical demand alone.
Infection control requirements continue to serve as a persistent adoption driver. Stringent protocols in hospitals and ambulatory surgical centers reinforce the operational appeal of single-use platforms by reducing reprocessing burden, minimizing cross-contamination risk, and simplifying instrument tracking. This dynamic does not eliminate reusable systems from the market, but it reshapes the value proposition comparison: disinfection labor, repair cycles, scope replacement frequency, and clinical downtime are increasingly weighted in procurement decisions alongside upfront device cost.
Report Content Architecture: What Decision-Makers Will Find
The study is structured to move from macro directional indicators to operational intelligence. Readers will encounter a sequenced analytical flow that supports everything from high-level market sizing to segment-level positioning logic, with an emphasis on application in procurement strategy, competitive benchmarking, and investment prioritization.
Core content components include:
- Historical revenue progression and forecast trajectory analysis that contextualizes growth momentum across the 2020–2032 window
- Product-form and application landscape mapping that explains how flexible, rigid, and video-enabled platforms are positioned across urology, gynecology, and other procedural settings
- Regional demand dispersion analysis that identifies where procurement activity, clinical adoption, and channel dynamics concentrate, without reducing the discussion to static share tables
- Competitive profiling of core manufacturers, with attention to clearance timelines, platform integration strategies, single-use positioning, and working-channel or imaging differentiation
- Regulatory and reimbursement context integration that links recent clearances and coding references to adoption incentives and procedural economics
- Procurement and total-cost-of-ownership framing that helps health-system and ambulatory leaders evaluate reusable versus single-use trade-offs, including sterilization, repair, and workflow considerations
- Scenario-based interpretive guidance that supports planning under varying adoption speeds, reimbursement adjustments, and competitive entry dynamics
The report deliberately separates directional confidence from segment-level precision in the introductory view. This design allows executives to assess the strategic landscape quickly while preserving the detailed breakdowns required for procurement modeling, competitive response planning, and market entry evaluation within the full study.
How the Study Supports 2026 Strategic Decisions
For different stakeholder groups, the same dataset yields distinct decision support. Health-system procurement leaders can use the study to benchmark device-form preference trends, evaluate whether single-use expansion aligns with infection-control mandates and procedural volume shifts, and structure negotiations with concentrated supplier bases. Medtech strategy teams can use the analysis to identify where imaging integration, working-channel design, portability, and clearance momentum create differentiation opportunities, and where legacy reusable portfolios must be defended or repositioned. Investors and market analysts can use the forecast architecture to distinguish between cyclical volume recovery and structural platform adoption, calibrating expectations around concentration, competitive mobility, and reimbursement sensitivity.
Equally important, the report provides interpretive discipline. It avoids overstating the speed of single-use substitution, acknowledges the continued relevance of reusable systems in specific institutional settings, and recognizes that regional procurement behavior, clinical workflow preferences, and reimbursement tracking can diverge from headline growth signals. This balanced framing helps decision-makers avoid strategic overreaction to isolated product launches or clearance announcements, while still capturing the directional weight of regulatory and workflow shifts.
Accessing the Full Intelligence Package
The macro trajectory, competitive structure, regulatory catalysts, and reimbursement context summarized here establish the strategic perimeter of the cystoscope market. They demonstrate why 2026 serves as a decisive planning year and why the 2026–2032 forecast window is essential for aligning procurement, R&D, and investment decisions with the market’s next phase of maturation. However, the full study contains the segment-level breakdowns, competitive positioning detail, regional demand dispersion logic, and scenario framing required to convert directional insight into precise execution plans.
Readers seeking the complete dataset, proprietary interpretive frameworks, and application-specific guidance are encouraged to access the full report through the source webpage. There, the macro signals introduced in this overview are translated into the detailed intelligence necessary for procurement modeling, competitive benchmarking, reimbursement-aligned volume planning, and market-entry strategy development.
In a market defined by sterilization pressure, imaging integration, procedural migration, and concentrated manufacturing leadership, the difference between reactive procurement and proactive strategy lies in the quality of the underlying intelligence. The Cystoscope Market research study is built to provide that foundation, enabling organizations to move from observing growth to shaping their participation in it.
For detailed analysis of this topic, please visit the official page: Cystoscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Generator Control Unit Market to Hit $5,085M by 2032 at 5.6% CAGR
By PW Consulting, 2026-09-07
Generator Control Unit Market Intelligence: Strategic Foresight for 2026 and Beyond
Executive Overview: Navigating a Period of Significant Transformation
The global energy infrastructure landscape is undergoing a period of profound recalibration. As industries across the commercial, industrial, and transportation sectors confront tightening reliability requirements, evolving regulatory frameworks, and the persistent need for resilient power provisioning, the Generator Control Unit market has emerged as a critical nexus of technological advancement and commercial opportunity. The latest comprehensive market research released by our firm provides a rigorous, data-grounded examination of this sector, offering enterprise leaders a structured foundation for strategic planning throughout 2026 and into the subsequent forecast horizon extending to 2032.
LED Turn Signal Light Market
This report is engineered not merely as a retrospective snapshot, but as a forward-looking intelligence asset. Decision-makers operating in engineering procurement, supply chain management, product development, and corporate strategy will discover actionable frameworks that connect historical trajectory with near-term inflection points. The analysis deliberately emphasizes structural drivers, competitive positioning, and operational dynamics, enabling organizations to calibrate investment allocation, manufacturing planning, and partnership strategies before market shifts fully materialize.
Analog Multi-channel Multiplexer Market
Market Trajectory and Core Structural Indicators
The documented performance of the Generator Control Unit sector over the past half-decade reflects a consistent expansion narrative shaped by accelerating electrification demands, infrastructure modernization initiatives, and growing emphasis on auxiliary power reliability. Historical records from 2020 through 2025 illustrate a steady upward progression in total market revenue, establishing a robust baseline that validates the sector's resilience amid broader macroeconomic volatility. The full-year valuation for the base reference year closes at a substantial level, confirming that the market has successfully absorbed earlier transitional pressures and sustained commercial momentum.
Solid Sawn Lumber Fastener Market
Forward projections compiled through the primary forecast window indicate that this growth architecture is likely to persist, supported by enduring demand signals across both mature and emerging deployment ecosystems. The medium-term compound annual growth rate reinforces the view that the sector will continue to generate meaningful incremental value, positioning organizations that align their operational roadmaps accordingly to capture disproportionate share. Readers seeking precise numerical trajectories, year-by-year progression figures, and scenario-weighted estimates for each forecast interval are directed to the complete market intelligence document, where these variables are presented alongside sensitivity parameters and methodological transparency.
Critically, the market's concentration profile reveals a landscape that is moderately consolidated yet remains accessible to agile participants. A concentrated subset of established manufacturers commands a significant portion of aggregate throughput, while the remaining value distribution underscores ample room for differentiated positioning, regional penetration, and application-specific specialization. This structure invites strategic consideration: incumbent players must defend their foothold through continuous product modernization and compliance leadership, whereas smaller or regionally focused manufacturers can pursue targeted niches, hybrid energy integration, and cost-optimized control architectures to establish durable competitive advantages.
Sector Dynamics: Regulatory, Geopolitical, and Technological Pressures
The contemporary operating environment for generator control unit manufacturers is defined by a confluence of regulatory adjustments, trade policy recalibrations, and technical standardization requirements that collectively reshape cost structures and procurement pathways. Recent tariff measures enacted by the United States during the early months of the current cycle have propagated through global supply networks, altering component sourcing economics and prompting reassessment of assembly footprints. These adjustments do not merely affect unit pricing; they influence lead-time planning, inventory strategy, and the relative attractiveness of localized versus distributed production models.
In parallel, updated export control frameworks and compliance directives introduced in the spring of the current year have introduced additional layers of scrutiny around the international movement of electronic components and power conversion hardware. Organizations operating across multiple jurisdictions must now integrate compliance forecasting into their operational calendars, ensuring that sourcing agreements, logistics partnerships, and certification roadmaps remain aligned with evolving administrative expectations. Concurrently, the broader geopolitical risk landscape continues to inject uncertainty into cross-border operations, reinforcing the strategic value of supply chain diversification, buffer inventory design, and multi-source qualification programs.
On the standards and certification frontier, the trajectory of product validation has become increasingly rigorous and geographically differentiated. Leading manufacturers have systematically secured domestic and foreign approvals encompassing a broad spectrum of recognized certification regimes, reinforcing market access credentials and strengthening procurement confidence among large-scale buyers, marine operators, and industrial end users. This certification momentum functions as both a barrier to entry for fragmented competitors and a credibility multiplier for organizations that maintain compliance portfolios aligned with international engineering expectations.
Technological Architecture and Application Deployment Patterns
The commercial architecture of the Generator Control Unit market is structured around distinct product archetypes, each responding to different operational priorities and integration requirements. Digital control platforms have captured a dominant share of current throughput, reflecting their alignment with advanced telemetry, remote monitoring, load management, and automated synchronization capabilities. Analog control units continue to occupy meaningful market space, particularly in legacy integration scenarios, cost-sensitive deployments, and applications where operational simplicity and field-service familiarity remain paramount. The interplay between these two technology families underscores a broader transition: operators are not simply replacing hardware, they are upgrading information architecture, a shift that creates sustained demand for controllers capable of interfacing with distributed energy resources, microgrid controllers, and centralized energy management systems.
Application Deployment Patterns
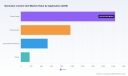
Deployment demand is distributed across a diverse set of end-use environments, each generating distinct performance expectations and procurement behaviors. Power generation facilities represent the largest concentration of consumption, driven by the need for reliable backup provisioning, peak-load support, and operational continuity in both grid-tied and isolated configurations. Transportation-related applications form a substantial secondary pillar, where control units support onboard auxiliary systems, mobile power infrastructure, and specialized fleet operations that demand compact, robust, and vibration-tolerant designs. Industrial manufacturing constitutes another significant demand center, leveraging generator control units for emergency backup, process continuity, and localized power balancing in facilities where grid instability or operational criticality necessitates autonomous power management.
Additional application categories, while individually smaller in aggregate value, collectively contribute to market resilience by absorbing demand from distributed commercial properties, specialized infrastructure, and regional projects that fall outside the primary verticals. These segments often exhibit higher customization requirements and longer qualification cycles, making them attractive for manufacturers with flexible engineering processes and strong regional distribution relationships. A complete breakdown of application-level sizing and regional distribution patterns is presented within the full market research document, where quantitative allocations and trend interpretations are provided with methodological clarity.
Competitive Landscape: Established Leaders and Evolving Capabilities
The competitive environment is anchored by a diversified roster of internationally active manufacturers, each pursuing distinct strategic differentiators while competing within overlapping application domains. Deep Sea Electronics, headquartered in the United Kingdom, has built recognition around its genset and automatic transfer switch control modules, with offerings engineered to support paralleling, load sharing, synchronization, remote start functionality, and comprehensive protection architectures. The company's emphasis on hardened field performance and integrated control logic positions it favorably within segments that prioritize operational dependability and advanced electrical protection.
ComAp, operating from the Czech Republic, has distinguished its portfolio through innovative control platforms designed for smart energy management, hybrid microgrid integration, and sustainable power generation strategies. Its controller series reflect a clear commitment to expanding functionality beyond basic genset oversight, aligning product development with the broader transition toward interconnected, efficiency-oriented power ecosystems. Recognition of its corporate management practices in the current year further illustrates how operational excellence and product strategy can reinforce one another in a competitive marketplace.
DEIF, based in Denmark, contributes state-of-the-art genset controllers and power management architectures that address both single-engine control and advanced paralleling requirements. Its controller platforms are engineered to support coordinated power distribution, engine integration, and operational stability under variable load conditions. The company's emphasis on sophisticated control logic and modular scalability resonates with buyers seeking to modernize plant-level power management without compromising reliability or service continuity.
Bernini Design, originating from Italy, has focused its efforts on automatic mains failure and automatic transfer switch controllers that coordinate generator auto start, engine interface operations, and mains monitoring functions. This specialization delivers targeted value to operators whose primary need is seamless transition management, failover assurance, and reliable monitoring across utility and backup power pathways. The company's product structure illustrates how application-specific refinement can create durable demand in segments where transfer reliability is non-negotiable.
SmartGen, headquartered in China, continues to expand its footprint through genset controllers, starter control hardware, and marine power management systems designed to meet diverse operational requirements across commercial and specialized deployment contexts. The company's recent product launch of its HMS360 starter controller, alongside a successful marine power management seminar, signals continued investment in both hardware expansion and customer engagement. Its certification breadth, covering numerous domestic and international standards, further demonstrates the importance of compliance-driven market access in globally contested segments.
Operational Intelligence Embedded in the Research
Beyond aggregate sizing and competitive profiling, the market research delivers operational content designed for immediate deployment in planning and execution workflows. The study systematically examines supply chain architecture, component dependency mapping, and regional procurement dynamics, enabling procurement teams to anticipate sourcing friction points and evaluate alternative qualification pathways. It also explores product roadmap indicators, including the integration of digital telemetry, cybersecurity considerations in control communication, and the growing expectation for interoperable interfaces across heterogeneous power assets.
Furthermore, the report incorporates scenario-based interpretation frameworks that allow strategy teams to test the implications of trade policy evolution, certification timeline adjustments, and demand cycle variability on revenue forecasts and capacity planning. These frameworks are structured to support sensitivity analysis rather than rigid point predictions, acknowledging that the Generator Control Unit market operates within a context of continuous regulatory and technological adaptation. Practitioners will find the research particularly useful for identifying where standardization offers scale advantages, where customization preserves margin integrity, and where partnership or licensing strategies can accelerate time-to-market without excessive internal engineering expenditure.
Strategic Implications for 2026 Decision-Making
For enterprises formulating or revising their operating plans for the current year, several strategic imperatives emerge from the evidence base. First, demand visibility must be coupled with supply chain agility. Organizations that maintain diversified sourcing arrangements, monitor compliance evolution, and design buffer strategies around electronic components and power conversion components will be better positioned to sustain delivery performance and margin stability as external conditions fluctuate.
Second, product strategy should reflect the dual reality of digital adoption and legacy coexistence. Investment in advanced control architectures that support remote management, data integration, and smart energy coordination addresses the highest-growth demand vectors, while maintaining capable analog or hybrid variants preserves access to cost-sensitive and compatibility-driven segments. Managers should assess whether their portfolio mix aligns with both the dominant digital trajectory and the persistent niche requirements that continue to generate reliable turnover.
Third, regional execution deserves renewed attention. Market participation patterns indicate that geographic strategy is no longer purely about scale; it is about regulatory alignment, certification readiness, and localized service capability. Companies that build repeatable qualification processes and maintain strong relationships with regional distribution and integration partners are more likely to convert market potential into sustainable share.
Fourth, competitive differentiation increasingly depends on system-level value rather than component-level price competition. Buyers in power plants, transportation fleets, and industrial facilities are evaluating control units not as isolated hardware purchases, but as components of broader reliability, efficiency, and compliance programs. Manufacturers that articulate and deliver measurable contributions to uptime, energy optimization, and protection integrity will command stronger positioning than those competing solely on unit cost.
Concluding Perspective
The Generator Control Unit market stands at a juncture where historical momentum, technological transition, and regulatory recalibration intersect to create both opportunity and complexity. The trajectory documented from the recent historical years through the current base year confirms sustained commercial expansion, while the forward forecast window suggests that this momentum is likely to persist under a structural growth framework. Yet the value of market intelligence lies not merely in confirming expansion, but in clarifying where expansion concentrates, which operational variables most influence outcomes, and how competitive positioning can be reinforced before inflection points become obvious to the broader market.
This research is designed to meet that need. It provides an integrated view of sizing, dynamics, competitive activity, and operational considerations, while deliberately preserving detailed quantitative decompositions for readers who require the complete analytical foundation for investment committees, procurement planning, or internal strategy reviews. Organizations prepared to move beyond general trend awareness and into structured, evidence-based decision-making will find the full report an essential reference for shaping action through 2026 and the subsequent forecast period.
For detailed analysis of this topic, please visit the official page: Generator Control Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Advanced HVAC Control Market Hits $22.3B in 2025, 9.2% CAGR to 2032
By PW Consulting, 2026-09-07
Navigating the Next Era of Intelligent Climate Management: Strategic Insights for the Advanced HVAC Control Market
The landscape of building management is undergoing a fundamental transformation, driven by the convergence of energy efficiency mandates, digitalization, and the urgent need for operational resilience. For enterprise leaders, facility managers, and investors, the Advanced HVAC Control Market represents more than just a component of infrastructure; it is a critical lever for sustainability compliance and cost optimization. As we move through 2026, understanding the trajectory of this sector is essential for making informed capital allocation decisions.
Worldwide Arc Ferrite Magnet Market
This article serves as a strategic prelude to our comprehensive market research publication. It outlines the macro-economic forces shaping the industry, the competitive intensity defining the landscape, and the regulatory pressures accelerating adoption. However, to truly equip your organization with actionable intelligence, one must look beyond the surface-level trends. Our full report provides the granular segmentation and forward-looking models necessary to navigate this complexity.
Customized Pressure Sensitive Safety Mats Market
Market Expansion and Economic Trajectory
The momentum behind advanced HVAC controls is outpacing many traditional building technology sectors. Over the past half-decade, the market has demonstrated robust resilience and growth, reflecting a global shift toward smarter, more responsive building environments. Historical data from 2020 through 2025 indicates a consistent upward trajectory in revenue generation, signaling that investment in control systems is no longer optional but a strategic imperative for modern infrastructure.
Worldwide All-terrain Off-road Vehicle Market
Looking ahead, the forecast period extending to 2032 suggests that this growth will not only continue but accelerate. The compound annual growth rate (CAGR) points to a significant expansion in value, driven by retrofitting projects in legacy buildings and the integration of sophisticated control layers in new constructions. This growth is not merely a function of increased construction volume but represents a deepening of technology penetration within existing assets. Organizations that recognize this scaling opportunity early stand to gain substantial operational advantages.
It is crucial for stakeholders to understand that this expansion is distributed across various vectors. While global aggregate figures provide a high-level view of health and potential, the real strategic value lies in understanding how these gains are distributed across different technology types and application sectors. The shift from legacy programmable systems to intelligent, smart HVAC control architectures is a key narrative thread that defines the revenue composition of the coming years.
Competitive Landscape and Industry Consolidation
The ecosystem of vendors serving this market is diverse, ranging from global industrial conglomerates to specialized control manufacturers. The market concentration metrics indicate a moderately consolidated environment where top players hold significant sway, yet there remains ample room for innovation and niche specialization. The top five entities in the sector account for a substantial portion of the market revenue, suggesting that stability and scale are heavily valued by end-users seeking long-term support and integration capabilities.
Leading organizations such as Johnson Controls and Honeywell International continue to reinforce their positions through comprehensive building automation platforms that embed HVAC control deeply within broader facility management ecosystems. Their strategies often focus on integrating AI-driven optimization to move beyond simple temperature regulation toward predictive maintenance and energy load balancing. Similarly, established industrial giants like Siemens and Schneider Electric are leveraging their extensive automation heritage. Siemens, for instance, continues to evolve its Desigo building automation systems, emphasizing energy optimization and scalable open architecture.
Meanwhile, the competitive field includes specialized players who drive innovation in specific niches. Trane Technologies and Carrier Global are focusing on platform-specific intelligence, such as Greenspeed and EcoWise, to enhance commercial efficiency. In the residential and light commercial space, companies like Ecobee are bridging the gap with smart thermostats that offer advanced control capabilities. Regional specialists and niche manufacturers like KMC Controls and Delta Controls also play a vital role, often providing the specialized hardware and software integration required for complex commercial applications.
Recent activities within the sector highlight a clear trend toward interoperability and platform enhancement. In mid-2025, Siemens announced a partnership with Microsoft to enhance IoT interoperability, integrating its Building X platform with Azure IoT Operations. This move underscores the industry's pivot toward cloud connectivity and seamless data flow. Following this, early 2026 saw significant product launches at the AHR Expo. Siemens introduced updates to its Desigo portfolio, including Desigo CC V9, focusing on scalable open building automation. Concurrently, Schneider Electric unveiled its SpaceLogic Touchscreen Room Controller for energy management, and ABB launched its next-generation ABB Ability BuildingPro platform. These developments signal a market where software flexibility and user interface sophistication are becoming key differentiators.
Regulatory and Macro-Economic Drivers
External pressures are acting as powerful accelerants for market growth. Regulatory bodies are increasingly mandating higher standards for building performance, directly impacting HVAC control requirements. In the United States, the Department of Energy's Smarter Small Buildings Campaign has highlighted the availability of numerous Building Energy Management Control System (BEMCS) products, pushing for wider adoption of proven technologies. Furthermore, state-level codes are tightening. The California Energy Code has adopted requirements for nonresidential HVAC controls based on Guideline 36 sequences of operation, setting a precedent that influences construction and alteration projects across the region.
Beyond compliance, the macro-economic drive toward grid stability and energy efficiency is reshaping control strategies. Model Predictive Control (MPC) has emerged as a promising technology in field demonstrations, particularly for grid-interactive efficient buildings. Implementations have shown the potential to reduce peak demand significantly and enable load shifting, aligning building operations with broader grid health needs. This capability transforms HVAC systems from passive consumers of energy into active participants in energy management ecosystems.
Strategic Implications for Decision Makers
For executives and strategists, the implications of these dynamics are profound. The transition to advanced HVAC controls is not merely a technical upgrade but a business case involving energy savings, asset longevity, and regulatory adherence. However, navigating the specificity of these opportunities requires detailed intelligence. General market trends can indicate direction, but they cannot define the specific value propositions for different building types or regional regulatory environments.
Consider the variation in application sectors. Commercial buildings continue to be a primary driver of demand due to the complexity of their environments and the scale of potential energy savings. Residential buildings also represent a significant volume, driven by consumer demand for comfort and connectivity. However, understanding the revenue mix and growth potential within these sectors without access to detailed segmentation data is akin to navigating without a map. The interplay between "Smart HVAC Control" and "Programmable HVAC Control" segments, for example, reveals critical insights into where the market is heading versus where it has been.
Similarly, regional dynamics play a crucial role. While North America and Europe remain key markets, the Asia Pacific region reflects substantial volume and growth potential, influenced by rapid urbanization and differing regulatory frameworks. Latin America and the Middle East and Africa present emerging opportunities that require distinct strategic approaches. A consolidated global view obscures the local nuances that determine successful market entry or expansion strategies.
Vendor selection is another area where depth of knowledge is paramount. With market concentration data indicating that a handful of companies control a significant share of revenue, understanding the specific capabilities, partnerships, and product roadmaps of these players is essential. Knowing which vendor is partnering for IoT interoperability versus which is launching new hardware controllers can influence procurement decisions and long-term infrastructure compatibility.
The Value of Comprehensive Intelligence
To move from general awareness to specific action, organizations require a detailed breakdown of market forces. Our full research publication delves into the precise revenue streams, growth rates by segment, and the strategic positioning of key competitors. It provides the foundational data needed to build robust business cases for HVAC control investments.
The report offers an in-depth description of the operational contents relevant to the market, covering technical specifications, integration challenges, and implementation timelines. It analyzes the competitive landscape with a focus on market share distribution, strategic moves, and recent developments that signal future directions. By examining the recent product launches and partnerships, stakeholders can anticipate shifts in vendor capabilities and market availability.
Furthermore, the research contextualizes these data points within the broader industry dynamics. It explores how regulations like the California Energy Code and campaigns by the U.S. Department of Energy are translating into market demand. It assesses the viability of technologies like Model Predictive Control in real-world scenarios, providing evidence-based guidance on technology adoption.
Without access to the segmented data—breaking down revenue by region, type, and application—decision-makers risk overlooking high-growth pockets or misallocating resources to saturated segments. The difference between knowing the total market size and understanding the specific contribution of Asian Pacific commercial buildings versus North American residential sites is the difference between a good strategy and a great one.
Our analysis ensures that you are not relying on aggregate numbers alone. We provide the clarity needed to distinguish between the performance of smart control systems versus programmable legacy systems, and how these segments are expected to evolve over the forecast period. This granularity allows for precise targeting of marketing efforts, R&D investment, or acquisition targets.
Conclusion: Preparing for 2026 and Beyond
As the Advanced HVAC Control Market continues its robust expansion toward the 2032 horizon, the window for strategic planning is now. The convergence of regulatory pressure, technological advancement, and economic incentive creates a fertile environment for growth, but also for complexity. Companies that rely on surface-level data may find themselves unprepared for the nuances of regional compliance or the shifting capabilities of major vendors.
To fully capitalize on the opportunities within this sector, depth of insight is required. Our complete market research study is designed to provide that depth. It transforms raw data into strategic narrative, offering the clarity needed to navigate the competitive landscape, understand regulatory impacts, and identify high-value segments. We invite you to explore the full findings to ensure your organization is equipped with the most accurate and actionable intelligence available for 2026 and the future.
For detailed analysis of this topic, please visit the official page: Advanced HVAC Control Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Permanent Magnet Measuring Device Market Hits USD 1.13 Billion in 2025, Projected to Reach USD 1.87 Billion by 2032 as Asia Pacific Leads Regional Share
By PW Consulting, 2026-09-02
Strategic Intelligence for the Permanent Magnet Measuring Device Market: A 2026 Executive Outlook
The global landscape for industrial metrology is undergoing a structural transformation, driven by the expanding deployment of high-performance permanent magnets across sectors ranging from electric mobility to advanced manufacturing. As magnetic circuits become central to efficiency, precision, and miniaturization, the instrumentation used to measure, characterize, and verify permanent magnet performance has evolved from a niche calibration function into a critical enabler of product quality, regulatory compliance, and supply chain resilience. Recognizing this shift, PW Consulting has prepared a comprehensive market study on the Permanent Magnet Measuring Device Market, designed to deliver actionable intelligence for corporate strategists, R&D leaders, procurement executives, and investment decision makers navigating the 2026–2032 horizon.
Permanent Magnet Measuring Device Market
This article serves as a strategic preview of the full research release. It explores the macro trajectory, structural forces, competitive architecture, and operational planning dimensions that define the present inflection point. In keeping with our analytical philosophy, we deliberately preserve the granular segmentation frameworks, regional calibration tables, and application-level valuation breakdowns for the complete report, ensuring that subscribers receive decision-grade precision rather than generalized industry commentary. The purpose of this preview is to establish the analytical foundation, demonstrate the depth of the underlying methodology, and clarify how the study maps to high-stakes enterprise choices in 2026.
Permanent Magnet Measuring Device Market
The Macro Trajectory: A Market Moving From Measurement Support to Strategic Infrastructure
Over the past half-decade, the permanent magnet measuring device sector has demonstrated a consistent growth cadence, reflecting sustained investment in magnet-intensive applications and the tightening of quality standards across downstream industries. The historical progression from 2020 through 2025 illustrates a market that has not merely expanded in nominal terms, but has matured in functional importance. What was once treated as a back-end verification step is now embedded earlier in design cycles, quality protocols, and materials qualification processes. This repositioning has broadened the value proposition of measurement instruments, shifting demand drivers from simple compliance testing toward process optimization, R&D acceleration, and real-time production feedback.
Permanent Magnet Measuring Device Market
Looking forward, the forecast window extends from 2026 to 2032, with the base year set at 2025. The study models a compound annual growth rate of 7.5 percent across the forecast horizon, signaling sustained expansion rather than a short-lived demand spike. By the end of the period, the broader revenue envelope is projected to reach a meaningful scale in USD-million terms, reinforcing the conclusion that permanent magnet characterization and measurement will remain a structurally important market segment. Importantly, this trajectory is not uniform. It is shaped by the interaction of several non-linear forces: the rapid scaling of certain magnet-intensive applications, the geographic redistribution of manufacturing capacity, and the ongoing recalibration of rare earth and specialty magnet supply chains.
The strategic implication for 2026 decision makers is straightforward. Surface-level market estimates are no longer sufficient for capital allocation, product planning, or capability investment. A credible view of this market requires a segmented understanding of technology adoption curves, application-specific reliability thresholds, and the evolving cost and availability dynamics of high-performance magnetic materials. The full report is structured to provide that layered view, combining historical context with forward-looking scenario modeling that can be integrated directly into internal forecasting processes.
Why 2026 Is a Decision Point: Volatility, Verification, and Vertical Integration
The year 2026 arrives at a moment when several long-running industrial trends have converged into a single, high-intensity planning environment. Permanent magnet-dependent industries are simultaneously confronting tighter dimensional and magnetic performance tolerances, heightened sensitivity to supply continuity, and a growing need to validate material consistency across geographically dispersed production networks. In this context, measuring devices are no longer passive test instruments; they are part of the operational controls that determine whether a company can maintain throughput, meet specification targets, and preserve customer trust under disruption.
One of the most consequential developments shaping the planning horizon is the regulatory reorientation of rare earth availability. China’s imposition of export restrictions in April 2025 on heavy rare earths, including dysprosium and terbium, and on certain permanent magnet materials such as samarium-cobalt and Dy/Tb-containing NdFeB magnets, introduced a persistent supply-side shock that rippled through magnet-dependent value chains. Subsequent expansion under MOFCOM Announcement No. 18 and related 2025 follow-on measures added medium and heavy rare earths, permanent magnetic materials, and related alloys to export control lists. The result was not a temporary disruption but a structural re-pricing and re-routing of critical inputs across global manufacturing networks.
At the same time, policy actors in other regions have moved to reduce exposure to the same concentration risks. A notable example is the U.S. Department of Defense’s July 2025 investment of $400 million in equity in MP Materials, which included a ten-year price floor of $110 per kilogram for NdPr output. This move was intended to bolster domestic rare earth and magnet capabilities, but it also reflects a broader strategic ambition: to stabilize input availability, support localized magnet production, and reduce dependency on constrained import channels. For measuring device stakeholders, these developments matter because material composition, coercivity profiles, and magnetic consistency become increasingly variable when supply networks are reshaped by policy, substitution, and regional sourcing shifts.
That variability elevates the importance of measurement. As magnet grades, processing routes, and supplier bases diversify, verification becomes a primary risk-mitigation layer. Instruments deployed in R&D labs, pilot lines, and production environments must be selected with greater scrutiny, calibrated against application-specific requirements, and integrated into workflows that can detect deviations early. In 2026, the companies that treat measurement as a strategic control point are far better positioned to manage rework costs, protect throughput, and maintain specification integrity than those that view it as a generic compliance expense.
What the Study Delivers: Operational Detail for Product, Sourcing, and Investment Decisions
The Permanent Magnet Measuring Device Market study is built to translate macro momentum into practical planning tools. Rather than stopping at high-level market sizing, the report examines the instrumentation categories, end-use requirements, and purchasing logic that determine where value is created and where bottlenecks emerge. It is designed for teams that need to compare technology options, evaluate supplier positioning, and anticipate demand shifts across industrial, automotive, electronics, aerospace, energy, and healthcare applications.
A central pillar of the study is its treatment of measurement technologies. The report distinguishes among the major instrument families used to assess magnetic properties, including Hall effect-based sensing platforms, magnetoresistive sensing solutions, fluxgate-based devices, and additional specialized measurement approaches. Each technology class carries different trade-offs in terms of sensitivity, range, integration complexity, calibration demands, and suitability for in-line versus laboratory use. The study maps these trade-offs against real operational requirements so that buyers and product planners can evaluate where a given technology class fits within their own measurement architecture.
The report also examines the demand structure by application category, covering industrial automation, automotive, consumer electronics, aerospace and defense, energy and power generation, and healthcare. These segments differ considerably in their measurement priorities. Some prioritize throughput and repeatability for high-volume production. Others demand extreme precision for materials characterization or qualification testing. A third group is governed by stringent certification or reliability standards that shape instrument selection and documentation practices. By analyzing these distinctions, the study helps organizations align instrument procurement and R&D investment with the actual constraints of their target segments.
Beyond applications and technology types, the study incorporates a geographic market structure that reflects how demand, manufacturing presence, and supply chain configurations vary across regions. The analysis accounts for the way regional manufacturing intensity, industrial policy, and magnet sourcing patterns influence measurement needs. This regional framing is essential for companies evaluating where to place inventory, how to structure service coverage, and which local specification norms must be addressed in product or service offerings.
Additional operational content includes a competitive landscape evaluation that profiles the major players shaping the market, a review of recent commercial activities and event participation that signal near-term strategic priorities, and an assessment of market concentration dynamics that help frame bargaining power, substitution risk, and innovation velocity. The report blends qualitative intelligence with quantitative structure so that readers can cross-check narrative insights against the underlying segmentation and sizing logic.
Core Structural Dimensions Covered in the Report
- Technology segmentation across Hall effect sensors, magnetoresistive sensors, fluxgate sensors, and other device categories, with attention to their practical fit for different measurement and characterization tasks
- Application-driven demand patterns spanning industrial automation, automotive, consumer electronics, aerospace and defense, energy and power generation, and healthcare
- Regional market structure reflecting manufacturing gravity, supply chain exposure, and localized specification expectations
- Competitive profiles for leading manufacturers and measurement specialists, including their focus areas, product families, and recent market activities
- Market concentration context that informs supplier dynamics, differentiation potential, and the realism of pricing or capacity strategies
Competitive Architecture: Technology Specialization and Regional Reach
The permanent magnet measuring device market is shaped by firms that have developed distinct technical identities around material characterization, production testing, and high-resolution inspection. The competitive set reflects a broad geographic footprint, with strong representation from European precision-instrument specialists, North American measurement and materials characterization players, and China-based manufacturers serving both domestic demand and export-oriented magnet ecosystems. This diversity matters because different competitors bring different strengths: some emphasize specialized magnet testing equipment for hard magnetic materials, others concentrate on magnetic field visualization and mapping, and still others build around turnkey characterization systems that link measurement with process quality control.
In Europe, several firms have built reputations around precision Gaussmeters, fluxmeters, and pulsed-field measurement solutions, as well as systems aimed at magnet characterization for production and R&D. These players are actively positioning themselves at major industry gatherings, using trade shows and technical presentations to showcase measurement and magnetizing solutions. Such visibility is not merely promotional; it signals where capabilities are being refined and which application communities are being targeted. A company exhibiting at events focused on magnet measurement and drive systems is often communicating a shift in emphasis, whether toward in-line quality control, higher-throughput characterization, or new instrumentation for evolving magnet grades.
In North America, the competitive presence includes organizations that provide vibrating sample magnetometers, Hall effect measurement systems, and broader magnetic characterization instrumentation for manufacturing and research environments. These firms are important to the market because they support detailed material property assessment, which increasingly feeds back into production qualification and magnet grade selection, especially as industrial users seek to validate performance under varied operating conditions.
In Asia, particularly China, a set of manufacturers supplies permanent magnet measuring devices, magnetic field distribution testers, hysteresis-based analysis systems, and automated measurement equipment for magnet parameter evaluation and calibration. This segment has grown alongside the broader expansion of magnet manufacturing and magnet-intensive product ecosystems in the region. Their activities are especially relevant in a period when rare earth restrictions and industrial policy are reshaping sourcing patterns, because measurement capability becomes a key enabler for evaluating alternative grades, verifying locally sourced materials, and maintaining consistency across changing supplier bases.
Additional competitors contribute complementary technologies, including magnetic field camera systems for high-resolution 3D mapping and inspection of permanent magnets and assemblies, as well as magnetizers, demagnetizers, calibrators, and related test equipment. Some firms emphasize PERMAGRAPH-class analyzers and magnetization-measurement technology, while others focus on custom field-strength measurement devices, zero-gauss chambers, and residual magnetism assessment for components and magnetic materials. Taken together, this competitive ecosystem reflects a market in which differentiation is increasingly determined by application-specific precision, integration into production workflows, and the ability to support both quality control and materials characterization.
Market Concentration and the Logic of Competition
The study places meaningful emphasis on concentration dynamics because they influence pricing behavior, supplier leverage, and the feasibility of competitive differentiation. A market with notable concentration does not necessarily imply stagnation; rather, it suggests that a relatively small group of firms holds significant share and therefore shapes expectations around instrument performance, service availability, and technical support. At the same time, the presence of multiple regional and technology-focused competitors ensures that the market remains contested across different use cases, from laboratory-grade characterization to production-oriented inspection.
For enterprise buyers, concentration has practical implications. Where supply is concentrated, qualification cycles, service agreements, and calibration standards can become strategically important, because switching costs may be higher and instrument selection more consequential. For manufacturers and entrants, concentration signals where differentiation can still be achieved: through faster measurement throughput, better integration with production data systems, improved handling of high-coercivity materials, or more flexible configurations for specific application requirements. The report examines these dynamics in a way that helps both buyers and suppliers interpret the balance of power in the market and plan accordingly.
Using the Study in 2026 Planning Cycles
The strongest value of this research lies in its applicability to concrete decision processes. In 2026, organizations are not simply asking whether the market is growing; they are asking where growth is concentrated, which applications will drive the most demanding measurement requirements, and how supply chain volatility will alter procurement and qualification strategies. The study is structured to answer those questions with enough depth to support product roadmap decisions, sourcing strategies, capacity planning, and geographic expansion analysis.
For product and R&D teams, the report provides a framework for understanding which measurement technologies are most aligned with emerging application requirements and which performance thresholds are becoming standard in magnet-intensive industries. For procurement and operations leaders, it offers insight into where regional demand structures and supply chain exposure may affect instrument availability, calibration support, and service expectations. For investors and corporate development teams, the competitive profiles, concentration context, and recent activity signals help frame where momentum is building and where differentiation opportunities may be durable.
Because the study is designed as a decision-support instrument, it avoids unnecessary abstraction. The emphasis is on actionable segmentation, practical application mapping, and competitive intelligence that can be integrated into internal models and planning discussions. The full release preserves the detailed breakdowns that allow users to allocate resources with greater confidence, prioritize the most relevant technology and application intersections, and anticipate the operational consequences of continued shifts in magnet supply and manufacturing geography.
Conclusion: A Market That Demands Precision Planning, Not Broad Estimates
The Permanent Magnet Measuring Device Market is entering a phase in which growth, technology choice, and supply chain exposure are tightly intertwined. As permanent magnets become more central to efficiency, miniaturization, and performance across industrial and high-tech applications, the instruments used to measure and verify them become inseparable from the quality and resilience of the products they support. The 2026 environment amplifies that relationship by adding regulatory and sourcing complexity to an already demanding technical landscape.
PW Consulting’s market study is intended to give leaders the analytical clarity required to act with precision. It traces the historical foundation, examines the forces shaping the forecast period, profiles the competitive players who define the market's direction, and connects all of this to the operational choices that businesses must make now. The complete report goes further, delivering the segmentation detail, regional structure, and valuation context needed for rigorous planning. For executives and analysts who need market intelligence that can be used directly in strategy, product, sourcing, and investment decisions, this research offers a grounded starting point for the 2026–2032 horizon.
For detailed analysis of this topic, please visit the official page: Permanent Magnet Measuring Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Shaped Charge Perforators Market to Reach $2,183.32 Million by 2032 with 5.85% CAGR
By PW Consulting, 2026-09-02
Strategic Intelligence for the 2026 Energy Transition: Inside the Shaped Charge Perforators Market
The global energy landscape is undergoing a profound transformation, driven by the dual imperatives of maximizing reservoir recovery and adhering to increasingly stringent operational standards. For oilfield services executives, investors, and strategic planners, understanding the nuances of subsurface engineering tools is no longer optional—it is a critical determinant of operational efficiency and capital allocation success. As we move through 2026, the market for Shaped Charge Perforators stands at a pivotal juncture, characterized by steady growth, technological differentiation, and intense competitive maneuvering.
Shaped Charge Perforators Market
PW Consulting's latest comprehensive study on the Shaped Charge Perforators Market offers more than a retrospective look at historical performance; it provides a forward-looking strategic compass. This article serves as an executive preview of the full report, highlighting the macro-economic trajectory, the competitive architecture, and the regulatory dynamics that will define the industry through 2032. To navigate the complexities of well completion and stimulation, stakeholders require granular intelligence that goes beyond headline figures. The following analysis encapsulates the core findings, demonstrating the value of the full intelligence package available through our detailed market research publication.
Shaped Charge Perforators Market
Market Trajectory and Growth Vectors (2026-2032)
The fundamental story of the Shaped Charge Perforators Market is one of resilient, moderate growth amidst volatile energy prices. Our analysis indicates that the global market revenue, measured in USD Million, has demonstrated a clear upward trajectory from the historical base years through the forecast period. Starting from a baseline of approximately 1,124.65 million in 2020, the market has evolved through various cyclical phases, reaching an estimated 1,465.8 million in 2025. This historical resilience sets the stage for the forecast period spanning 2026 to 2032.
Shaped Charge Perforators Market
For strategic planners targeting 2026 decision points, the projected market size of 1,591.04 million serves as a critical planning benchmark. This figure is not merely a statistic; it represents the aggregate capital deployment across onshore, offshore, and enhanced recovery operations globally. The Compound Annual Growth Rate (CAGR) of 5.85% over the forecast period suggests a mature but expanding market. This growth rate is significant because it outpaces general industrial inflation in several key regions, indicating specific demand drivers related to well complexity and aging reservoir management.
By 2032, the market is anticipated to approach the 2,183.32 million mark. This long-term view allows companies to justify R&D investments and capacity expansions today based on solidified demand curves tomorrow. However, the path to 2032 is not linear. The data reveals fluctuations, such as the slight contraction observed between 2023 and 2024, followed by recovery. Understanding the causes of these historical variances is essential for risk mitigation in future budgeting. The full report dissects these variances, linking them to specific macroeconomic indicators and drilling activity levels that are crucial for accurate forecasting.
Segmentation Dynamics: Type and Application
Success in this market requires more than knowing the total size; it demands a precise understanding of where value is generated. The market is segmented by product type and application, each carrying distinct margin profiles and technological requirements. Our research identifies three primary types driving the ecosystem: High Precision Shaped Charges, Multi Shot Perforators, and Automated Perforation Systems.
The segmentation data highlights that High Precision Shaped Charges currently command the largest share of revenue within the type category. This dominance underscores the industry's shift towards precision engineering, where consistent hole geometry and deep penetration are prioritized over sheer volume. Multi Shot Perforators and Automated Perforation Systems follow, representing growing avenues for efficiency gains. Automated systems, in particular, are poised to gain traction as operators seek to reduce human intervention in hazardous environments and improve shot timing accuracy.
On the application front, the breakdown reveals a heavy concentration in Onshore Well Completion. This segment represents the bulk of market activity, driven by the continued development of unconventional resources and the optimization of existing onshore fields. Offshore Reservoir Stimulation and Enhanced Oil Recovery (EOR) constitute significant but smaller portions of the revenue mix. However, the offshore segment often commands higher unit prices due to logistical complexities and harsh environment requirements.
The strategic implication for 2026 is clear: companies must align their product portfolios with the specific demands of these segments. A supplier focusing solely on onshore conventional wells may miss the growth potential in offshore EOR initiatives. The full report provides a detailed decomposition of these segments, offering revenue projections for each category without exposing the specific percentages here. This granularity allows clients to benchmark their own portfolio performance against the market average and identify white spaces for product development.
Geographic Distribution and Regional Opportunities
Geographical analysis is paramount for companies deciding where to allocate sales resources and manufacturing capabilities. The market distribution across regions reflects the global balance of oil and gas production activity. North America remains a dominant force in the shaped charge perforators market, reflecting the robust drilling activity in the United States and Canada. The revenue concentration in this region underscores the maturity of the market and the high adoption rate of advanced perforation technologies.
Asia Pacific represents a substantial revenue segment, driven by growing energy demands and increased exploration activities in key Asian economies. Europe, Latin America, and the Middle East and Africa collectively form the remainder of the global landscape. Each region presents unique challenges, from regulatory hurdles in Europe to logistical constraints in Latin America and high-temperature requirements in the Middle East.
For 2026 strategy, understanding the regional revenue mix is vital for market entry or expansion plans. Companies looking to diversify away from North American dependency must understand the specific growth rates and penetration levels in Asia Pacific or the Middle East. The report details the specific revenue values for each region, enabling a precise calculation of market share potential. However, the specific regional percentage splits and individual revenue figures are reserved for the full intelligence download to maintain the competitive advantage of our subscribers. What is clear is that regional dynamics are shifting, with some areas showing higher growth elasticity than others based on local reservoir characteristics and regulatory environments.
Competitive Landscape: Titans and Challengers
The Shaped Charge Perforators Market is characterized by a moderately concentrated competitive landscape. With a CR3 of 48.75% and a CR5 of 62.3%, the top players hold significant influence over pricing, technology standards, and supply chain stability. However, a 48.75% concentration also indicates room for specialized challengers to carve out niches through innovation.
The competitive arena is dominated by major oilfield services companies headquartered largely in Houston, Texas, alongside specialized manufacturers in Europe and emerging players in Asia. Key incumbents include Hunting PLC (Titan Division), SLB (Schlumberger), Baker Hughes, and Halliburton (Jet Research Center). These companies leverage vast R&D budgets and global service networks to maintain market leadership.
Hunting PLC, through its Titan Division, remains a pivotal player, offering iconic solutions like PerfECTA and EQUAfrac. Their recent activity highlights the pace of innovation; in early 2025, Hunting Titan unveiled the latest perforating technology including the H-4 Oriented Perforating System at the SPE Hydraulic Fracturing Technology Conference, building on their 2024 launch of the same system along with the Perf+ shooting panel for precise alignment in horizontal wells. These developments signal a strong focus on orientation accuracy, which is critical for maximizing drainage area in horizontal wells.
SLB and Baker Hughes compete fiercely on system integration and reservoir-driven charge performance. Baker Hughes supplies Predator ZX super deep-penetrating charges and DeepConnect reservoir-driven charges, tested to API RP-19B standards. Halliburton counters with its RockJet HMX charges for deepest penetration in stressed rock and MaxForce-FRAC consistent hole charges for fracturing applications. These product names are not just marketing; they represent specific technological answers to geological challenges.
In the European sphere, DynaEnergetics (DMC Global) offers formation-tuned shaped charges including HaloFrac, FracTune, and DPEX for both conventional and unconventional wells. Their 2023 introduction of the DS Gravity 2.0 self-orienting gun system and new Oriented FracTune (OFT) shaped charges demonstrates a commitment to solving orientation issues without external mechanisms. Meanwhile, specialized US manufacturers like SWM Technologies (AdvancedPerf) focus on the AdvancedPerf family, including AdvancedAlign and AdvancedFrac Equal-Entry charges, catering to operators needing specific entry consistency.
The landscape also includes significant manufacturing capacity in Asia. Shaanxi FYPE Rigid Machinery Co., Ltd. in Xi'an and Vigor Drilling Oil Tools in China supply shaped charge perforating guns and charges, often focusing on cost-competitive solutions for regional markets. The presence of these players adds pricing pressure and supply chain diversity, forcing Western incumbents to justify premiums through performance data and service reliability. The full report includes detailed company profiles, including headquarters, URLs, and specific product line assessments, allowing clients to benchmark competitors directly.
Regulatory and Technical Dynamics
Operating in the shaped charge perforators market is not solely a technological endeavor; it is a compliance-driven industry. The evaluation of well perforators is governed by strict standards, most notably API RP-19B. This Recommended Practice for Evaluation of Well Perforators includes Section I ambient testing and Section II stressed rock performance. Compliance with API RP-19B is a baseline requirement for market participation in many jurisdictions, influencing procurement decisions across all major operators.
Furthermore, perforating guns and shaped charges must comply with AESC/IME Perforating Gun Specifications for DOT classification and approval of jet perforating guns. These regulatory layers add complexity to product development and shipping logistics. For a company planning to expand its geographic footprint in 2026, understanding the specific regulatory friction points in target regions is essential. The report analyzes how these regulations impact time-to-market for new charges and the cost structure of compliance.
On the technical side, the choice of explosive material drives performance envelopes. Shaped charges utilize explosives such as RDX, HMX, and HNS with specific temperature ratings. A critical technical nuance is that HMX and HNS enable higher temperature operations compared to RDX. In high-pressure, high-temperature (HPHT) wells, this distinction determines whether a charge succeeds or fails. Manufacturers that can certify their charges for extreme temperatures using HMX or HNS gain a competitive edge in deepwater and geothermal-adjacent applications. This raw material dynamic influences both cost and performance, and the full study decodes how these material choices ripple through the supply chain and pricing models.
Strategic Recommendations for 2026 Decision Makers
Based on the synthesis of market size, growth rates, competitive moves, and regulatory frameworks, several strategic imperatives emerge for 2026. First, investing in orientation technology is no longer niche; it is becoming standard. The recent launches by Hunting Titan and DynaEnergetics regarding self-orienting systems indicate where the market is heading regarding horizontal well efficiency. Companies lagging in this technology risk losing tenders in mature unconventional basins.
Second, supply chain resilience regarding explosive materials needs attention. The reliance on specific compounds like HMX and HNS, which have specific temperature advantages, requires secure sourcing strategies, especially given global fluctuations in chemical supply. Diversifying suppliers or securing long-term contracts based on the regional demand forecasts provided in the full report can mitigate this risk.
Third, regional focus should be data-driven. While North America offers volume, the growth rates in Asia Pacific and specific offshore pockets may offer better margin opportunities for targeted players. The market concentration data suggests that while the top five players dominate, there is sufficient fragmentation for specialized firms to thrive if they target underserved segments or regions.
Finally, compliance cannot be an afterthought. With API RP-19B and AESC/IME standards actively enforced, certification status is a market access key. Strategic planning should include timelines for recertification or new certifications as part of the product roadmap, ensuring that innovation does not stall at the regulatory gate.
Conclusion: Unlocking Full Intelligence
The Shaped Charge Perforators Market presents a landscape of steady growth, technological differentiation, and rigorous compliance. The macro data indicates a path toward nearly 2,183 million in revenue by 2032, with a CAGR of 5.85%. The competitive field is defined by giants in Houston and specialized engineers in Germany and China, all fighting for precision and penetration supremacy. Regulatory standards like API RP-19B set the rules of engagement, while material science drives the performance limits.
This preview has highlighted the structural elements of the market, but the true value for your organization lies in the specific number crunching, the detailed competitor benchmarking, and the granular regional forecasts that inform capital allocation. To make informed decisions in 2026, you need access to the complete dataset, including the specific segmentation revenues, the full list of recent developments beyond the highlighted launches, and the deep-dive analysis on supply chain constraints.
PW Consulting's full market research report provides this comprehensive intelligence. It is designed to be the foundational document for your strategic planning cycle. Do not rely on high-level estimates when precise data is available. Access the full report to secure the detailed insights necessary to navigate the Shaped Charge Perforators Market with confidence.
For detailed analysis of this topic, please visit the official page: Shaped Charge Perforators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Automatic Feedback Suppressor Market to Reach $975.99 Million by 2032 Driven by 8.75% CAGR
By PW Consulting, 2026-09-02
Strategic Insights: Navigating the Automatic Feedback Suppressor Market Dynamics in 2026
Executive Overview
The professional audio landscape is undergoing a significant transformation, driven by the increasing demand for high-fidelity sound reinforcement and the need to mitigate acoustic disturbances in complex environments. Central to this evolution is the Automatic Feedback Suppressor Market, a specialized segment that has demonstrated remarkable resilience and growth potential. As organizations strive for seamless audio integration across live events, public address systems, and telecommunications, the reliance on sophisticated suppression technologies has never been higher.
Automatic Feedback Suppressor Market
PW Consulting has published a comprehensive market study designed to equip stakeholders with the critical intelligence needed to navigate this evolving terrain. This research offers a detailed examination of the market's trajectory from historical baselines through to the forecast period ending in 2032. The analysis underscores a robust expansion pattern, reflecting the broader adoption of advanced audio processing solutions across multiple verticals.
Automatic Feedback Suppressor Market
Market Trajectory and Growth Fundamentals
Understanding the macroeconomic drivers of the Automatic Feedback Suppressor industry is essential for strategic planning. The market has exhibited a steady upward trend over the past five years, moving from a valuation of approximately 312.45 million USD in 2020 to an estimated 542.8 million USD in 2025. This historical performance sets a strong foundation for the forecast period spanning 2026 to 2032.
Automatic Feedback Suppressor Market
Looking ahead, the market is projected to maintain a healthy compound annual growth rate (CAGR). Industry estimates suggest that the sector will continue to climb, reaching valuation points that indicate sustained demand. By 2026, the market size is anticipated to approach the 602.9 million USD mark, signaling a pivotal year for investment and product development. This growth curve extends through the forecast horizon, with potential valuations nearing 975.99 million USD by 2032. Such figures highlight the long-term viability of the sector and the increasing capital allocation toward audio safety and clarity technologies.
The growth is not merely a function of market expansion but is also influenced by technological maturity. As digital signal processing becomes more accessible and cost-effective, the integration of automatic feedback suppression into standard audio equipment is accelerating. This democratization of technology allows a wider range of users, from small-scale venues to large-scale installations, to benefit from professional-grade audio management.
Segmentation Dynamics and Technology Adoption
The market structure is defined by distinct technological categories and application areas, each contributing uniquely to the overall revenue stream. A deep dive into the segmentation reveals how different types of suppressors are gaining traction based on their specific performance characteristics and use cases.
Technology Types
The industry is primarily segmented by the nature of the suppression technology employed. Digital Feedback Suppressors represent a significant portion of the market, driven by their precision and flexibility in handling complex audio environments. These systems leverage advanced algorithms to identify and neutralize feedback frequencies without compromising audio quality. Analog Feedback Suppressors maintain a steady presence, often favored in specific legacy installations or scenarios where simplicity and reliability are paramount. Additionally, Hybrid Feedback Suppressors are emerging as a versatile solution, combining the strengths of both digital and analog processing to offer adaptive performance in dynamic settings. The interplay between these types dictates procurement strategies for integrators and end-users alike.
Application Verticals
In terms of application, the Live Events and Entertainment sector stands out as a major contributor. The high stakes of live performances require reliable systems that can prevent disruptive feedback loops instantly, ensuring an uninterrupted audience experience. Public Address Systems constitute another critical area, where clarity and safety are non-negotiable. In large venues, airports, and public gathering spaces, automatic suppression helps meet audio intelligibility standards and prevents potential hearing hazards caused by uncontrolled audio levels. Telecommunications and Conferencing have also seen increased adoption, particularly as remote work and virtual collaboration tools become standard. Clear audio transmission without feedback is crucial for professional communication, driving demand in this segment.
Regional Distribution
Geographically, the market shows varied intensity across different regions. North America continues to hold a substantial share, supported by a mature professional audio infrastructure and high spending on entertainment technology. Europe follows as a significant market, driven by strict regulatory standards for public audio safety and a strong cultural emphasis on live performances. The Asia Pacific region is experiencing growing adoption rates, fueled by rapid urbanization and an expanding events industry. Latin America and the Middle East and Africa represent emerging avenues with increasing investment in audio infrastructure, though at different scales of maturity compared to the established markets.
Competitive Landscape and Key Players
The competitive environment in the Automatic Feedback Suppressor Market is characterized by a mix of established audio equipment manufacturers and specialized technology providers. Market concentration indicates that a core group of companies commands a significant portion of the revenue, with the top three players holding a considerable market share and the top five firms controlling the majority of the industry output. This concentration suggests a market where brand reputation, technological innovation, and distribution networks play decisive roles in capturing market share.
Several key companies are shaping the dynamics of this sector through product innovation and strategic positioning:
- dbx Professional Audio (Sandy, Utah, United States): Known for its AFS2 Advanced Feedback Suppression processor, this company leverages patented algorithms and up to 24 filters per channel to serve live sound and installed systems. Their Wizard setup tools streamline integration for sound engineers.
- Behringer (Willich, Germany): A major player in the pro audio space, Behringer offers the FBQ2496 Feedback Destroyer Pro. This device is noted for its ultra-fast suppression capabilities, featuring 40 FBQ filters and a high sampling rate suitable for demanding live sound applications.
- VISSONIC Electronics Limited (Guangzhou, Guangdong, China): Focusing on conference and AV systems, VISSONIC produces the VIS-FS100-A, which incorporates an adaptive algorithm and a built-in automatic mixer. Their participation in major trade shows like ISE 2026 highlights their commitment to showcasing integrated audio solutions.
- Guangzhou DSPPA Audio Co., Ltd. (Guangzhou, China): This manufacturer produces professional models such as the D6576 and D2200F, utilizing adaptive notch processing tailored for pro audio installations. Their product line supports the growing infrastructure development in the region.
- Klark Teknik (Kidderminster, United Kingdom): Offering the DF1000 dual-channel automatic feedback suppression processor, Klark Teknik provides robust solutions with up to 32 filters per channel for instant elimination, catering to professional installation needs.
- Ashly Audio (Webster, New York, United States): Ashly integrates advanced suppression features directly into their Protea DSP matrix processors and Pema amplifiers. Recent updates to their Pema Protea media amps demonstrate ongoing enhancement of automatic feedback suppressor features.
- Yamaha (Hamamatsu, Japan): A global giant, Yamaha incorporates automatic feedback suppression into its MTX/MRX DSP platforms and powered mixers, targeting commercial installations where reliability and brand trust are critical.
The competition extends beyond hardware specifications. Strategic moves such as trade show participation, product updates, and integration partnerships define the current landscape. For instance, recent activities in early 2026, such as VISSONIC showcasing systems at ISE and Ashly Audio updating their amplifier features, indicate a market that is actively evolving to meet new standards and user expectations. Companies that can offer seamless integration with existing ecosystems and provide user-friendly setup tools are gaining a competitive edge.
Industry Dynamics and Regulatory Influence
The market does not operate in a vacuum; it is shaped by broader industry dynamics and regulatory requirements. One of the most significant drivers is the need to comply with audio safety and intelligibility standards. Automatic feedback suppressors play a vital role in helping public address systems for venues and conferences meet these regulatory benchmarks. As governments and industry bodies tighten standards regarding noise levels and audio clarity in public spaces, the demand for compliant technology increases.
Furthermore, the trend toward smarter venues and integrated AV systems is reshaping how suppression technology is deployed. Modern installations require systems that can self-calibrate and adapt to changing acoustic conditions without manual intervention. This push for automation aligns with the broader Industry 4.0 movement, where efficiency and reduced manual overhead are key priorities. The ability of a suppressor to integrate into digital audio networks and communicate with other system components is becoming a standard expectation rather than a luxury feature.
Another dynamic factor is the consolidation of audio equipment into multifunctional units. Instead of standalone suppression devices, there is a growing preference for DSP processors and amplifiers that include built-in suppression capabilities. This shift influences market sizing and revenue recognition, as the value of suppression technology may be bundled within larger system sales. Companies must navigate this complexity to accurately assess the true market potential and identify opportunities for standalone products versus integrated solutions.
Strategic Value for 2026 Decision-Making
For executives, investors, and product managers, the detailed insights provided in this market study serve as a critical tool for 2026 planning. The data allows stakeholders to validate investment theses, identify high-growth niches, and anticipate shifts in consumer preference. Understanding the historical performance and forecasted growth enables more accurate budgeting and resource allocation.
The analysis of competitive profiles helps in benchmarking against industry leaders. By examining the product specifications, headquarters locations, and recent developments of key players, organizations can identify gaps in the market or areas where competitors are vulnerable. For example, recognizing the emphasis on adaptive algorithms and high filter counts among top competitors can guide R&D priorities for firms looking to launch new solutions.
Moreover, the segmentation data provides a roadmap for market entry or expansion strategies. Whether a company is targeting the Live Events sector or focusing on Public Address infrastructure, understanding the relative size and growth potential of each application area is crucial. The regional breakdown further assists in prioritizing geographic markets based on current market size and growth momentum. Without access to this granular intelligence, decision-makers risk relying on assumptions that may not align with the actual market reality.
The report also addresses the nuances of market concentration. Knowing that a significant portion of revenue is controlled by a few key entities helps new entrants understand the barriers to entry and the strategies required to compete effectively. It highlights the importance of differentiation through technology, service, or niche targeting.
Conclusion and Forward Outlook
The Automatic Feedback Suppressor Market is poised for continued expansion, underpinned by technological advancements and regulatory demands. As we move through 2026 and beyond, the integration of suppression technologies into broader audio ecosystems will likely deepen. The convergence of digital processing power with affordable hardware costs will make these solutions accessible to a wider audience, further driving market volume.
PW Consulting's comprehensive research provides the necessary framework to understand these trends in detail. By exploring the segmentation splits, competitive maneuvers, and regional dynamics in full, stakeholders can develop robust strategies that capitalize on the opportunities presented by this growing market. The projection of reaching nearly 975.99 million USD by 2032 suggests that the sector will remain a vital component of the professional audio industry for the foreseeable future.
For those seeking to make informed decisions in this space, the complete dataset and detailed analysis offered in the full report are indispensable. The insights contained within go beyond surface-level statistics, offering actionable intelligence that can drive product development, marketing strategies, and investment decisions. Accessing the full depth of this research ensures that your organization remains ahead of the curve in a competitive and dynamic market environment.
For detailed analysis of this topic, please visit the official page: Automatic Feedback Suppressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Reports Semi Trash Pumps Market to Reach 824 Million Dollars by 2032 at 5.15 Percent CAGR
By PW Consulting, 2026-09-02
Navigating the Wastewater Frontier: Strategic Insights into the Semi Trash Pumps Market 2026–2032
In the complex landscape of industrial fluid management, few equipment categories embody the intersection of durability, mechanical engineering, and environmental necessity quite like semi trash pumps. As industries grapple with increasingly stringent environmental regulations and the physical realities of construction sites, agricultural drainage, and municipal maintenance, the demand for robust solids-handling pumping solutions has evolved from a niche requirement to a critical operational component. For stakeholders operating in this sector, understanding the trajectory of the Semi Trash Pumps Market is not merely an exercise in forecasting revenue; it is a strategic imperative for capital allocation, product development, and competitive positioning over the coming decade.
Semi Trash Pumps Market
This article serves as a high-level strategic overview derived from our latest comprehensive market research study. It is designed to equip executives, investors, and product managers with the macro-level intelligence necessary to frame their 2026 decision-making processes. While we provide a clear view of the market's growth trajectory and structural dynamics here, the granular data required to execute specific strategies—down to the unit level and segmented revenue streams—remains within the proprietary confines of our full report.
Semi Trash Pumps Market
Market Trajectory: Growth Amidst Operational Demands
The Semi Trash Pumps Market has demonstrated consistent resilience and expansion over the past half-decade. Reflecting on the historical performance from 2020 through 2025, the market has navigated supply chain fluctuations and shifting constructionActivity levels while maintaining a positive growth curve. The total market revenue, measured in USD Million, has shown a clear upward trend, signaling sustained confidence in the utility of these pumping systems across diverse sectors.
Semi Trash Pumps Market
Looking forward, our forecast period spans from 2026 to 2032. During this window, the market is projected to continue its expansion, driven by renewed infrastructure spending, ongoing agricultural modernization, and the perpetual need for effective flood control and dewatering solutions. The Compound Annual Growth Rate (CAGR) observed over the forecast period stands at 5.15%, indicating a steady, moderate growth environment rather than a volatile boom. This stability suggests that while the market is expanding, it remains mature enough to require nuanced competitive strategies rather than reliance on sheer market pull alone.
For enterprise leaders, this projected growth rate implies that organic expansion is possible, but capturing market share will likely depend on differentiation. The market size is expected to reach significant valuation milestones by the early 2030s, underscoring the long-term viability of investments in this sector. However, realizing this potential requires a deep understanding of where the growth concentrates—information that is dissected in detail within our full analysis.
Regional and Segmental Nuances
While the aggregate numbers paint a picture of growth, the real strategic value lies in understanding the geographic and segmental distribution of demand. The market is not uniform; it is a mosaic of regional regulatory environments, economic development stages, and industrial concentrations. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present unique opportunities and challenges for manufacturers and distributors.
Similarly, the segmentation by equipment type and application reveals where the value pools are deepest. Whether focusing on specific diameter configurations such as 2-inch, 3-inch, or 4-inch semi trash pumps, or targeting end-use sectors like construction, agriculture, industrial processing, and municipal services, the allocation of resources must be precise. The construction sector, for instance, typically drives high-volume demand due to site dewatering requirements, while agricultural applications focus on reliability and versatility in remote locations.
It is crucial for decision-makers to recognize that these segments behave differently over time. Some may mature faster, while others offer higher growth elasticity. Our full report provides the specific revenue breakdowns and regional valuations necessary to prioritize these segments effectively. Relying on generalized industry knowledge without access to this specific data can lead to misaligned product launches or inefficient distribution network expansions.
The Competitive Arena: Established Giants and Specialized Players
The competitive landscape of the Semi Trash Pumps Market is characterized by a mix of large, diversified industrial conglomerates and specialized equipment manufacturers. Market concentration metrics indicate that while no single entity dominates the entire space exclusively, a core group of players commands a significant portion of the revenue. The top three companies account for approximately 32.5% of the market, while the top five hold around 48.7%. This concentration suggests a moderately fragmented market where agility and niche specialization can compete effectively against economies of scale.
Several key companies define the current competitive boundaries. Gorman-Rupp, based in Mansfield, OH, stands as a heavyweight in the industry, offering an extensive line of self-priming trash and solids-handling pumps. Their inclusion of engine-driven models for industrial and municipal applications underscores their commitment to covering the full spectrum of semi-trash needs. Similarly, AMT Pump Company, a subsidiary of Gorman-Rupp located in Royersford, PA, focuses specifically on cast iron sewage and trash pumps designed for solids-laden liquids, highlighting the importance of material durability in this segment.
In the portable and contractor-focused space, companies like Multiquip (Cypress, CA) and Thompson Pump (Port Orange, FL) emphasize gasoline and diesel-powered solutions tailored for dewatering and abrasive material handling. Multiquip targets professional contractors with robust trash pumps, while Thompson Pump specializes in heavy-duty self-priming units for flood control and semi-trash uses. These players illustrate the demand for mobility and ease of deployment in field conditions.
International influence is also palpable. Koshin America, with headquarters in Schaumburg, IL and roots in Kyoto, Japan, offers STH/STV series semi-trash pumps featuring Honda engines. Their recent strategic move to extend a 3-year warranty on trash and semi-trash pumps in late 2024 signals a competitive focus on durability and consumer confidence. Honda Power Equipment itself remains a critical supplier of engines and centrifugal trash pumps with high-volume capacity and frame protection, serving both construction and rental markets.
Other notable participants include Generac (Waukesha, WI), which provides 2-inch semi-trash pumps targeting homeowners, farmers, and construction sites for muddy or sandy water transfer, and Simpson (FNA Group), which produces portable semi-trash pumps like the SSTP series with Kohler or CRX engines for debris-laden water. The presence of such diverse players indicates that the market serves a wide range of customer profiles, from heavy industrial users to individual landowners.
Recent Developments and Innovation Signals
Competitive dynamics are not static; they are shaped by recent product launches and catalog updates that signal shifting strategic priorities. In August 2025, Mi-T-M updated its product catalog to include offerings for trash and semi-trash pumps designed specifically for high-volume water and waste movement. This update suggests a responsiveness to customers requiring greater throughput capabilities.
Furthermore, in October 2025, FIRMAN Power Equipment introduced the FPG20T, a 2-inch water and semi-trash pump aimed at water transfer with debris handling. Such launches indicate that manufacturers are continuously refining their entry-level and mid-range offerings to capture broader market segments. These developments, when analyzed alongside warranty extensions and engine partnerships, reveal a market where reliability, warranty coverage, and engine compatibility are becoming key differentiators alongside raw performance metrics.
Industry Dynamics: Regulations, Materials, and Durability
Navigating the Semi Trash Pumps Market requires more than just understanding competitors; it demands a grasp of the external forces that shape product specifications and market access. Regulatory compliance, particularly regarding emissions, is a critical factor for gasoline-powered semi-trash pumps. EPA certification is required for these units, with specific limits on emissions for engines used in portable applications. This regulatory layer adds a layer of complexity for manufacturers and distributors, influencing product design and supply chain logistics. Ignoring these compliance requirements can lead to market access barriers, making regulatory intelligence a vital component of any market entry or expansion strategy.
On the technical side, the material composition of these pumps is driven by the harsh nature of the fluids they handle. Cast iron impellers and aluminum pump housings are standard in semi-trash pumps. This specification is not arbitrary; it is a direct response to the need for durability against abrasion from small solids. The choice of materials impacts the longevity of the equipment, maintenance intervals, and ultimately, the total cost of ownership for the end user. Manufacturers who innovate in material science or optimize these standard configurations for specific abrasive environments may find opportunities to command premium pricing or secure loyalty in high-wear sectors.
Why Comprehensive Data Matters for 2026 Strategy
As organizations plan their moves for 2026 and beyond, the difference between success and stagnation often lies in the granularity of the intelligence used to formulate strategy. High-level trends, such as the overall market growth rate and the presence of key competitors, provide the context. However, they do not provide the map. To allocate capital efficiently, a company needs to know exactly which regional markets are offering the highest returns, which pump types are gaining traction versus those facing saturation, and how specific applications are shifting in terms of spend intensity.
Our full market research report goes beyond the macro overview provided here. It delivers detailed segmentation analysis that breaks down revenue by region, type, and application without exposing the methodology to public scrutiny. It offers precise valuation figures that allow for accurate financial modeling and ROI projection. It includes a deep dive into the competitive profiles, analyzing not just who the players are, but how they are positioning themselves through product lines, warranties, and regional focus.
Furthermore, the report contextualizes industry developments within the broader economic forecast. By integrating historical data from 2020 to 2025 with our forecast through 2032, stakeholders can model various scenarios. What happens if regulatory pressures increase? How does a shift in constructionActivity in Asia Pacific affect global supply chains? What is the specific growth potential of the municipal sector compared to industrial dewatering? These are questions that require the structured data sets provided in the full study.
Conclusion: Positioning for the Next Cycle
The Semi Trash Pumps Market stands at a point of steady expansion, underpinned by essential industrial and agricultural needs. The projected CAGR of 5.15% through 2032 offers a reliable backdrop for growth, but the competitive landscape is sufficiently nuanced to reward those who look deeper. With key players ranging from global industrial giants to specialized regional manufacturers, and with recent product launches highlighting a focus on volume, durability, and warranty, the battlefield is defined by both specification and trust.
Regulatory compliance and material durability remain the guardrails of product development, ensuring that market participation requires technical competence. For executives and strategists, the opportunity lies in leveraging detailed market intelligence to navigate this landscape. The overview presented here establishes the strategic context, but the actionable insights required to win in 2026 reside in the comprehensive data of our full report.
We invite you to access the complete study to unlock the specific regional valuations, segment splits, and competitor intelligence necessary to refine your strategic roadmap. In a market where precision matters, having the full picture is the ultimate competitive advantage.
For detailed analysis of this topic, please visit the official page: Semi Trash Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Replenishment At Sea System Market Valued at 1035.4 Million in 2025 with 5.65 CAGR Forecast to 2032
By PW Consulting, 2026-09-02
Navigating the High Seas of Logistics: The Strategic Imperative of the Replenishment At Sea System Market
In the complex theater of modern naval operations, logistical endurance is not merely a tactical advantage; it is the foundational pillar of maritime sovereignty and power projection. As global naval doctrines shift towards prolonged expeditionary missions and distributed maritime operations, the capability to sustain fleets without returning to port—known as Replenishment At Sea (RAS)—has transitioned from a supportive utility to a critical strategic asset. PW Consulting is proud to introduce our comprehensive market research report on the Replenishment At Sea System Market, a detailed analysis designed to equip industry stakeholders, defense policymakers, and investment strategists with the intelligence needed to navigate the evolving landscape through 2032.
Replenishment At Sea (RAS) System Market
This report is not simply a collection of numbers; it is a strategic roadmap. It dissects the intricate interplay between geopolitical tensions, technological advancements in fluid dynamics and solid cargo transfer, and the procurement cycles of major naval powers. For decision-makers operating in the defense and maritime engineering sectors, understanding the trajectory of this market is essential for capitalizing on opportunities and mitigating risks in an increasingly volatile global environment.
Replenishment At Sea (RAS) System Market
Market Trajectory and Macro Growth Dynamics
The RAS system market is currently navigating a phase of mature expansion, driven by the urgent need to modernize aging naval fleets and enhance operational autonomy. Our analysis of historical data from 2020 to 2025 reveals a market that has demonstrated resilience and steady growth despite broader economic fluctuations. In 2020, the global market valuation stood at approximately 812.45 million USD. Following a period of adjustment during 2021, the sector accelerated significantly, reaching 895.31 million USD in 2022 and climbing to 955.07 million USD by 2023. This upward momentum continued through 2024 and 2025, with the market size reaching 1,019.47 million USD and 1,035.4 million USD respectively.
Replenishment At Sea (RAS) System Market
Looking forward, the forecast period from 2026 to 2032 outlines a robust growth path. While 2026 sees a slight stabilization at 1,030.79 million USD, reflecting immediate procurement cycles, the trajectory steepens thereafter. By 2027, the market is projected to reach 1,125.3 million USD, escalating to 1,244.36 million USD in 2028. The growth compounds over the subsequent years, pushing the market size to 1,251.26 million USD in 2029, 1,367.08 million USD in 2030, 1,430.11 million USD in 2031, and finally reaching 1,522.0 million USD by 2032.
This expansion correlates with a Compound Annual Growth Rate (CAGR) of 5.65 percent over the forecast period. This rate underscores a consistent demand for advanced replenishment technologies, fueled by increasing naval budgets and the necessity for interoperable logistics solutions among allied forces. The revenue unit across the study is maintained in USD Million, ensuring a standardized metric for evaluating investment potential and market penetration strategies.
Segmentation Dynamics: Volume, Value, and Operational Context
To truly understand the market potential, one must look beyond the aggregate figures and examine the structural composition of demand. While the total market size offers a macroeconomic view, the segmentation splits provide critical insights into where capital is being deployed and which operational requirements are driving procurement. Our research categorizes the market across three primary dimensions: Region, Type, and Application.
Geographically, the demand is distributed across key naval powers and emerging maritime security regions. North America represents a significant portion of the market value at 412.39 million USD, reflecting the substantial procurement plans of the US Navy and allied fleets in the hemisphere. Europe follows with a valuation of 248.52 million USD, driven by collective naval investments among European allies and Canada aimed at enhancing operational autonomy. The Asia Pacific region holds a substantial share at 290.68 million USD, highlighting the rapid naval modernization efforts in the Indo-Pacific theater. Emerging markets in Latin America contribute 52.09 million USD, while the Middle East and Africa region accounts for 31.72 million USD, indicating growing interests in localized logistical capabilities.
From a product perspective, the market is diversified into Fuel Transfer Systems, Dry Cargo Transfer Systems, and Solid Stores Systems. Fuel Transfer Systems dominate the landscape, valued at 621.25 million USD, which aligns with the critical necessity of keeping high-mobility vessels fueled during extended operations. Dry Cargo Transfer Systems account for 272.59 million USD, supporting the delivery of munitions, food, and spare parts. Solid Stores Systems, valued at 141.56 million USD, complete the logistical triad, ensuring that non-fuel consumables are available at sea.
In terms of application, Naval Fleet Support remains the primary driver, commanding 722.61 million USD of the market share. This segment reflects the core requirement of maintaining frontline combat vessels. Auxiliary Vessel Operations contribute 207.46 million USD, focusing on support ships and logistics providers, while Joint Logistics Operations account for 105.33 million USD, emphasizing interoperable capabilities during multinational exercises and coalition missions.
Competitive Landscape and Strategic Positioning
The market structure is defined by a mix of specialized engineering firms and large maritime conglomerates. Our analysis identifies a moderate level of concentration, with the CR3 percent standing at 38.5 percent and the CR5 percent at 52.7 percent. This indicates that while the top players hold significant market share, there is ample room for specialized innovation and niche disruption.
Van Halteren Technologies, headquartered in Boxtel, Netherlands, stands out as a provider of advanced RAS systems for both liquid and solid transfers. Their portfolio includes custom solutions for prominent naval assets such as the Dutch Combat Support Ship Den Helder and the Turkish TCG Derya. Recent activity includes their selection by Damen Naval in April 2025 for RAS systems on the Anti-Submarine Warfare Frigate programme, signaling strong partnerships within European defense procurement networks.
Kongsberg Maritime, based in Kongsberg, Norway, supplies electric RAS and Fuelling-at-Sea equipment, including winches and masts. Their footprint extends to major naval programs, including the Indian Navy Fleet Support Ships and Portuguese Navy replenishment ships. In December 2024, Kongsberg secured a contract with Hindustan Shipbuilding Limited for Indian Navy Fleet Support Ships. Further solidifying their position, in September 2025, they signed a contract with STM to supply FAS and RAS equipment for two Portuguese naval replenishment and logistic ships.
Hepburn Engineering, located in Toronto, Canada, specializes in single-purpose and dual solids/liquids RAS systems compliant with the Standard Tensioned Replenishment Alongside Method (STREAM). With over 50 years of experience, they maintain a strong reputation for reliability in navies worldwide. Hydrasearch Company, based in Annapolis, Maryland, USA, focuses on fluid conveyance products, hoses, probes, and hardware specifically for underway replenishment operations in defense markets. Meanwhile, KMT Submarine in South Korea leads as a manufacturer of underway replenishment equipment, covering components for fuel, munitions, stores transfer, and vertical replenishment.
These companies are not merely competing on price; they are competing on technological integration, compliance with rigorous safety standards, and the ability to meet specific sovereign defense requirements. The recent contract awards highlight a trend towards electric systems and standardized interfaces, which reduces operational complexity and enhances safety during high-sea transfers.
Regulatory Frameworks and Operational Safety
The RAS market does not operate in a vacuum; it is heavily influenced by standardized procedures and safety protocols that dictate equipment specifications. Adherence to regulatory frameworks is a non-negotiable baseline for market entry and sustained operation. For instance, the US Navy NWP 4-01.4 provides standardized procedures for underway replenishment operations, including detailed equipment requirements and safety protocols for RAS evolutions. Compliance with such publications ensures that systems meet the rigorous safety thresholds required for close-proximity operations in potentially hostile environments.
Furthermore, strategic procurement plans are directly shaping the demand curve. The US Navy plans to procure 20 John Lewis-class fleet replenishment oilers to support RAS operations, with multiple ships under construction or contracted as of late 2025. This large-scale acquisition program alone represents a significant driver for the Fuel Transfer Systems segment and associated componentry. Such initiatives ensure a steady pipeline of requirements that manufacturers must align with regarding capacity and technological capability.
Geopolitical Drivers and Future Outlook
The growth of the RAS system market is inextricably linked to the broader geopolitical landscape. Increasing naval investments by European allies and Canada in replenishment capabilities are aimed at enhancing operational autonomy and expeditionary reach amid global maritime security needs. This shift reflects a doctrinal move away from reliance on domestic ports towards self-sustaining fleet groups capable of projecting power over extended ranges without logistical vulnerability.
As maritime security needs evolve, the demand for Joint Logistics Operations is expected to gain prominence. The ability for different national navies to share replenishment resources seamlessly requires interoperable equipment and standardized procedures, a niche where companies with strong compliance records and international experience will thrive. The forecast data suggests that by 2032, the cumulative effect of these geopolitical drivers will push the market valuation to 1,522.0 million USD.
However, the path forward is not without challenges. Supply chain resilience, raw material costs, and the rapid pace of technological obsolescence in naval engineering require constant vigilance. Stakeholders must anticipate shifts in procurement priorities, such as the move towards automated transfer systems or enhanced digital monitoring during replenishment, to remain competitive.
Unlocking the Full Intelligence: A Call to Action
The insights summarized above represent only the surface layer of the analysis contained within the full PW Consulting report. The strategic value for your organization lies in the granular details that have been reserved for the comprehensive study. While the macro trends provide direction, the specific breakdowns of regional procurement cycles, detailed cost structures by segment, and precise competitive benchmarking data are essential for formulating precise investment strategies and bidding plans.
Our full report delves deeper into the nuances of the supply chain, offering detailed profiles of key manufacturers, extensive lists of recent contract awards with value implications, and a thorough examination of the regulatory environment across different jurisdictions. It provides the tactical intelligence needed to identify untapped niches within the Dry Cargo and Solid Stores segments, which are often overshadowed by the dominant Fuel Transfer market but offer unique growth vectors.
In an environment where logistical capability equates to strategic reach, having access to precise, verified, and future-oriented market data is a decisive advantage. We invite you to explore the full version of our Replenishment At Sea System Market research on our website. There, you will find the complete dataset, including the specific segmentation splits by region, type, and application, alongside the detailed competitive profiles and recent development timelines that define this critical industry. Equip your team with the intelligence necessary to navigate the complexities of naval logistics and secure your position in the evolving maritime landscape.
Visit the PW Consulting source page today to access the complete report and gain the full strategic depth required for high-stakes decision-making in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Replenishment At Sea (RAS) System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


