



Category: Machinery & Automotive

Rotary Indexer Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, this briefing previews our in-depth Rotary Indexer Market research (base year 2025) and explains why the report should be a primary input to capital allocation, sourcing, product road-mapping, and M&A decisions in 2026. The analysis synthesizes historical performance (2020–2025), a forward-looking forecast (2026–2032) and market structure diagnostics to give executives the contextual intelligence they need—while reserving granular segmentation and proprietary scoring behind the full report to preserve actionable value for subscribers.
Rotary Indexer Market
Executive snapshot: what the market looks like going into 2026
The global rotary indexer market has demonstrated steady expansion through the first half of the decade, accelerating as manufacturers across electronics, automotive, and food & beverage increased automation intensity. Our topline modelling shows the market continuing to grow through the forecast window at a mid-single-digit compound annual growth rate, reflecting persistent investment in precision motion solutions, modular automation, and flexible manufacturing cells. Market concentration indicators point to a fragmented ecosystem: the top three and top five suppliers together control only a modest share of market revenue, signaling abundant white space for niche specialists and regional challengers.
Rotary Indexer Market
Why this matters for 2026 corporate strategy
- Timing of capex and product bets: With predictable, steady growth rather than blockbuster acceleration, firms must prioritize investments that optimize unit economics and modularity rather than short-term capacity expansion alone.
- Sourcing and resilience: Supply chain frictions and geopolitical trade dynamics continue to be a dominant constraint on deliveries and lead times; procurement strategies must trade off cost with redundancy and lead-time predictability.
- Customer value propositions: End users are paying up for configurability (programmable motion, servo integration) and for turnkey integration support. Companies that commit to “systems plus services” win higher lifetime value.
- M&A and partnerships: Fragmentation creates opportunities for bolt-on acquisitions to assemble broader solution stacks quickly—especially where target firms offer complementary digital controls or regional channel strength.
Market trajectory and what the numbers imply
Historical dynamics show consistent year-on-year expansion through 2025, and our forecast projects continued growth across 2026–2032. The mid-single-digit CAGR embedded in the forecast reflects stable demand across long-cycle sectors—automation modernization in semiconductors and electronics, plant retooling in food & beverage, and continued adoption in automotive assembly lines. For decision-makers, that pattern signals a market where scale advantages exist but are not overwhelming; instead, margin upside is driven more by feature differentiation (precision, digital integration, safety certifications) and aftermarket services than by pure volume play.
Rotary Indexer Market
Strategic implications by value chain activity
- R&D and product strategy: Prioritize modular architectures and digital-ready platforms. Investments in servo-driven control, embedded diagnostics, and easier integration with PLCs/robotics yield outsized returns because purchasers value reduced commissioning time and process stability.
- Manufacturing & supply chain: Build a dual-track supplier strategy—retain low-cost, long-lead items in geo-diverse suppliers while qualifying local suppliers for critical subassemblies to protect delivery performance. Inventory strategies should shift from lean to “predictable buffer” for long-lead electro-mechanical components.
- Commercial & channel: Differentiate through solution-selling: packages that bundle hardware, commissioning, and performance guarantees shorten sales cycles and lower churn. Regional distributors and systems integrators remain instrumental for complex deployments.
- Aftermarket & services: Offer remote diagnostics, predictive maintenance subscriptions, and retrofit programs for legacy indexers. Service revenue will be a meaningful contributor to margin expansion as installed bases age.
Regulatory, certification, and risk factors
Regulatory and safety compliance is non-negotiable. Machinery that incorporates rotary indexers must meet occupational safety standards (e.g., OSHA provisions) and relevant Machinery Directives in major markets, alongside regional electrical and safety certifications. In many markets, local machinery-safety standards and electrical approvals are prerequisites for acceptance in regulated industries such as medical device manufacturing and food processing. Companies should treat certification pipelines as project-critical paths—delays or missed approvals materially increase time-to-revenue.
Supply chain risks remain acute. Geopolitical tensions and trade restrictions have produced periodic disruptions to procurement schedules and price volatility for key components. Successful firms mitigate these risks through multi-sourcing, strategic inventories for critical parts, and nearshoring of final assembly for prioritized accounts.
Competitive landscape — players to watch and their strategic postures
The market is populated by a mix of longstanding mechanical specialists, motion-control vendors, and systems integrators who have expanded into rotary indexing as part of broader automation portfolios. Notable vendors include:
- Motion Index Drives (Troy, MI, USA) — recognized for cam-driven indexing tables and engineered high-cycle solutions for demanding applications in aerospace and packaging. Strength: proven mechanical robustness for high-throughput lines.
- Nexen Group (Providence, RI, USA) — positioned in high-torque, precision servo and ring-drive solutions; appeals to users requiring heavy moment-load performance and integration with advanced motion platforms.
- WEISS GmbH (Buchen, Germany) — notable for programmable tables and digital control integration; recent trade-show presence and strategic partnerships indicate active focus on semiconductor and electronics customers.
- Destaco (Wixom, MI, USA) — combines mechanical and servo technologies, with product breadth for assembly and packaging OEMs; advantage in channel relationships within North American equipment builders.
- Sanko Automation (China) — leverages competitive manufacturing scale for programmable hollow and fixed-station tables, targeting cost-sensitive regional demand.
- Centricity Automation (USA) — focuses on PLC-integrated servo indexers that simplify controls integration for end-users seeking turnkey assembly modules.
- Taktomat GmbH and TallMan Robotics (Germany and China) — both notable for flexible division options and engineered motion drives; appeal to high-speed production lines and custom automation projects.
- Festo (Germany) — offers pneumatic solutions that are attractive where simplicity and cost-effectiveness matter, such as buffer systems and partially automated cells.
Recent vendor activity underscores the market’s orientation toward integration and partnerships: for example, a major European supplier showcased combined linear transport and rotary indexing solutions at a 2025 automation trade event and announced a technology partnership to deepen semiconductor automation capabilities. Such moves reflect an industry pivot toward bundled systems that reduce integration friction for end users.
What the PW Consulting report delivers (practical outputs for 2026 decisions)
Our full Rotary Indexer Market report is structured to be directly operational for strategy teams. Key deliverables include:
- Market sizing and forecast models at the global level (base year 2025) with scenario toggles for high/low demand and disruption assumptions;
- Competitive profiles and capability maps for leading and emergent suppliers, including strengths, weaknesses, and technology roadmaps;
- Decision tools: TCO and ROI calculators for buy/build/partner choices, vendor shortlists tailored to capability requirements, and a playbook for integration testing and commissioning;
- Commercial frameworks: go-to-market templates for solution-packaging, recommended channel architectures by end-market, and pricing levers to defend margin in competitive bids;
- Risk register and mitigation playbook addressing certifications, supply-chain interruptions, and regulatory timelines in major markets;
- Actionable M&A scaffolding: target screening filters, synergy levers, and example earn-out structures that accelerate time-to-value for bolt-on deals.
These outputs are designed to move leaders from insight to execution within 90–180 days: sourcing teams can implement qualified supplier lists, product management can reprioritize feature backlogs, and corporate development can start targeted outreach to acquisition candidates.
How to use this intelligence in 2026 planning cycles
- In budgeting: defer undifferentiated capacity expansion in favor of targeted investments in digital-enablement and aftermarket services that compound returns.
- In procurement: shift to hybrid sourcing strategies and include contract clauses for lead-time guarantees and penalty mechanisms tied to delivery performance.
- In product roadmaps: set a 12–18 month sprint to ship servo-enabled, PLC-friendly modules and introduce a subscription-based remote-monitoring option for installed indexer fleets.
- In M&A: prioritize tuck-ins that add controls IP or regional channel relationships rather than scale-only targets.
Final note — why you should read the full PW Consulting report
Our preview lays out the macro trajectory, strategic implications, and competitive contours that matter for 2026 decisions. However, the highest-value elements for practitioners—detailed segmentation maps, vendor scoring matrices, and financial impact models—are intentionally held in the full report to preserve the proprietary heuristics and modelling that allow executives to act with confidence. Accessing the complete study provides the quantification and playbooks necessary to convert strategic intent into measurable outcomes.
For executives building plans in 2026, the choice is simple: use broad industry intuition at your peril, or use disciplined, data-backed frameworks to align investments and capabilities. PW Consulting’s Rotary Indexer Market report delivers those frameworks and the operational tools to implement them.
For detailed analysis of this topic, please visit the official page: Rotary Indexer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Robot Tool Changers Market to Reach USD 1.35B by 2032 at 13.81% CAGR
By PW Consulting, 2026-07-22
Robot Tool Changers Market: Strategic Intelligence for 2026 Decision-Making
Executive snapshot
For executives planning capital allocation, product roadmaps, or M&A activity in 2026, the robot tool changers market presents both a clear growth runway and nuanced strategic trade-offs. Our latest PW Consulting study, anchored on a 2025 base year, shows the market more than doubling in scale over the coming cycle — rising from mid‑hundreds of millions (USD, Million) in 2025 to a horizon value above USD 1.3 billion by 2032 at a compound annual growth rate of approximately 13.8%. That expansion is not uniform: it is driven by intersecting forces in automation uptake, collaborative-robot (cobot) deployment, and system integrator demand for flexible, modular end‑effector ecosystems.
Robot Tool Changers Market
Why 2026 is an inflection point
-
CapEx cycles among OEMs and contract manufacturers: Many buyers are moving from pilot fleets toward scale deployments in 2026. This shifts procurement criteria from proof-of-concept metrics to total cost of ownership, uptime guarantees, and lifecycle services for tool‑changer systems.
Robot Tool Changers Market -
Standards and safety updates: The introduction of updated industry safety requirements in 2025 recalibrates integration practices and vendor certification needs; by 2026, procurement teams will demand compliance evidence as a prerequisite for supplier selection.
Robot Tool Changers Market -
Supply‑chain localization: Geopolitical pressures and tariff policies are prompting sourcing redesigns — favoring vendors with diversified manufacturing footprints or strong localized partnerships.
Market dynamics and growth trajectory
The market trajectory we model reflects sustained demand for both automatic and manual tool‑changing solutions across industrial and collaborative applications. Between 2020 and 2025 the market recorded robust expansion, and our forecast shows that continuing at an annualized rate near 13.8% through 2032 will produce an industry roughly two to three times larger than today’s. This macro momentum is useful to benchmark potential investment timing: early entrants that secure design‑wins in 2026 stand to capture asymmetric share gains as adopters scale in 2027–2029.
Importantly, market structure matters. The sector shows meaningful concentration among a small number of established incumbents; the top three and top five vendors together control a significant majority of commercial activity. That concentration raises both barriers and opportunities: scale players can leverage global service networks and validated interfaces, while specialized challengers can win by offering integration simplicity, lighter weight for cobots, or differentiated safety features.
Technology and application evolution — what matters to buyers
-
Automatic versus manual: Buyers are segmenting tool‑changer purchases by application complexity and takt time. High‑throughput machine tending and multi‑tool assembly favor automatic changers with integrated electrical/pneumatic pass‑throughs and standardized flanges; smaller, flexible cells and low-volume changeovers still justify manual solutions.
-
Cobot compatibility: As collaborative robots penetrate new use cases, lightweight, low‑force tool changers and modular gripper ecosystems are becoming table stakes. Vendors who package ergonomic mounting, quick-connect utilities, and simplified programming deliver faster ROI for system integrators.
-
Service and safety integration: Vendors who provide validated safety documentation, spare parts kits for field servicing, and retrofit kits for legacy robot families materially decrease integration risk for buyers and are preferred in tender evaluations.
Competitive landscape — positioning the key vendors
The report contains a practical vendor map and comparative scorecards. Below is a directional synthesis of the core players we profile and the strategic vectors they represent:
-
Stäubli — Premium automation specialist with modular automatic tool changers and strong ISO‑flange compatibility. Strengths: high payload capacity options and deep industrial validation. Strategic implication: favored by OEMs requiring heavy‑duty exchanges and standardized interfaces.
-
Zimmer Group — Broad portfolio spanning automatic, manual, pneumatic and magnetic changers. Strengths: solution breadth and configurability. Strategic implication: wins where procurement values a single‑vendor source for varied cell architectures.
-
SMC Corporation — Pneumatics leader extending into cobot‑grade tool changers and grippers. Strengths: pneumatic expertise and scale manufacturing. Strategic implication: attractive to buyers prioritizing pneumatic simplicity and global availability.
-
ATI Industrial Automation — Known for force/torque sensing and end‑effector accessories. Strengths: integration of sensing with changeover mechanics. Strategic implication: preferred in precision assembly and force‑sensitive applications.
-
SCHUNK — Offers pneumatically actuated automatic changers with safety‑centric features (e.g., self‑retaining designs). Strengths: reliability and focus on fail‑safe behavior. Strategic implication: chosen in safety‑sensitive machine tending deployments; recent product promotions (e.g., May 2025) underline active go‑to‑market acceleration.
-
Destaco — Focus on cobot end‑of‑arm tools and manual changers with pass‑through ports. Strengths: pragmatic designs for materials handling. Strategic implication: strong in retrofit and cobot feeder markets.
-
Robot System Products and SmartShift Robotics — Newer entrants with collaborative robot–focused systems and universal quick‑change concepts. Strengths: speed of deployment and redeployment. Strategic implication: compelling for contract manufacturers and high‑mix, low‑volume users seeking operational flexibility.
Regulatory, supply‑chain and raw‑material considerations
Two regulatory pillars are reshaping integration practices. First, the 2025 update to ISO safety requirements has tightened system‑level compliance expectations, which affects mechanical locking, electrical interlocks, and validation documentation required at purchase. Second, legacy U.S. standards continue to influence local integration protocols in North American projects. These dynamics increase the value of vendors who can provide third‑party validation kits and pre‑integrated safety packages.
On the supply side, tariff policies and raw‑material sourcing pressures are prompting manufacturers to rethink footprints and supplier diversification. For 2026 planning, scenario stress‑testing—examining lead‑time increases, alternate sourcing, and contract terms—must be part of procurement playbooks, particularly for components that have limited alternative suppliers.
What the report delivers — practical, transaction‑grade intelligence
PW Consulting’s full study is designed as an operational toolkit for 2026 decisions. Highlights include:
-
Market sizing and validated growth scenarios through 2032, with sensitivity analysis for regulatory and tariff shocks.
-
Buyer decision frameworks and ROI calculators that translate cycle time, changeover frequency, and downtime into NPV outcomes.
-
Vendor scorecards with comparative matrices across engineering attributes, compliance readiness, service footprint, and commercialization velocity.
-
Go‑to‑market playbooks for suppliers (channel strategy, OEM partnerships, retrofit market entry) and procurement playbooks for buyers (RFP templates, acceptance test scripts, warranty negotiation checklists).
-
Supply‑chain maps and mitigation options addressing material constraints and tariff exposures, plus recommended sourcing policies for 2026‑2028.
-
Case studies illustrating successful deployments in machine tending, electronics assembly, medical device handling, and food packaging, with anonymized metrics on throughput gains and cost payback timelines.
Strategic implications for 2026 — five actions for leaders
-
Prioritize validated interfaces: Require ISO‑compliant flanges and documented electrical/pneumatic pass‑through standards in all new procurements to reduce integration risk.
-
Lock in service agreements: As installations scale, field servicing and parts availability become primary determinants of lifetime cost — secure multi‑year spares and response SLAs.
-
Segment procurement by application value: Allocate automatic tool changers to high‑cycle, multi‑tool environments while reserving manual or semi‑automatic options for low‑volume/low‑capital cells.
-
Stress‑test supply chains: Run tariff and lead‑time scenarios to identify alternate sourcing and local assembly partners before contractual commitments in 2026.
-
Watch consolidation signals: Given the market’s concentration, monitor partnership announcements and product promotions (e.g., recent product activity from SCHUNK) for M&A catalysts that could accelerate product bundling and service integration.
Next steps — how to use this insight
This article previews the actionable intelligence contained in PW Consulting’s full Robot Tool Changers Market report. The study is structured to support procurement shortlists, product roadmap prioritization, and investment diligence for 2026. If your 2026 plans include scaling automation, investing in supplier partnerships, or evaluating acquisition targets, the full report supplies the granular segmentation, model assumptions, and vendor performance data needed to make confident decisions.
For decision‑makers who need a tailored briefing, PW Consulting offers executive workshops that translate the market scenarios into bespoke procurement strategies and implementation roadmaps for 2026–2028.
For detailed analysis of this topic, please visit the official page: Robot Tool Changers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Air Ambulance Market to Hit USD 29.63B by 2032, Growing at 8.5% CAGR
By PW Consulting, 2026-07-22
Air Ambulance Market 2026: Strategic Preview for Executive Decision-Making
As healthcare delivery models evolve under demographic pressure, regulatory change, and technological advances, air medical transport has shifted from a niche emergency service to a strategic element of integrated acute care systems. PW Consulting’s forthcoming Air Ambulance Market study (base year 2025, forecast 2026–2032) synthesizes five years of historical performance with forward-looking scenario analysis to equip executives with the insight needed to make high-stakes capital, network and M&A decisions in 2026.
Air Ambulance Market
Why this study matters for 2026 planning
Executives face three converging imperatives in 2026: secure access to time-critical care across dispersed populations, stabilize revenue under new reimbursement environments, and optimize capital allocation for fleet and personnel. Our market model shows the industry has grown materially over the past half-decade—rising from roughly USD 11 billion at the start of the last decade to approximately USD 16.75 billion in 2025—and is projected to expand to nearly USD 29.6 billion by 2032. That trajectory corresponds to a mid-single-digit to high-single-digit compound annual growth rate (CAGR) over the forecast window, underpinned by rising demand for inter-facility transfers, aging populations, and investments in critical-care-capable air platforms.
Air Ambulance Market
For 2026 strategy, the practical implication is clear: the market is large enough to justify both defensive plays (protect existing catchment areas and payer relationships) and offensive growth (fleet expansion, network partnerships, and selective acquisitions). But success will hinge on navigating regulatory, reimbursement and labor dynamics that materially influence unit economics.
Air Ambulance Market
Market dynamics shaping 2026 choices
-
Regulatory tightening and transparency obligations. The No Surprises framework and related federal measures have increased reporting obligations and constrained balance-billing practices. Operators must embed compliance into billing and dispatch workflows while redesigning pricing conversations with payers and patients.
-
Reimbursement normalization. Recent updates to public reimbursement schedules have reduced reimbursement uncertainty for many providers. That said, differential contract terms with commercial payers and public payors will remain a key margin driver; commercial negotiations and participation in membership networks will continue to shape revenue stability.
-
Labor and clinical staffing pressure. Air medical services require 24/7 access to flight nurses, paramedics and critical care clinicians—a structural labor cost that not only raises per-transport economics but also constrains geographic scalability absent targeted workforce strategies.
-
Safety and operational standards. Aviation authorities and accreditation bodies are extending data and safety expectations. Operators that invest in analytics-driven maintenance, crew training, and digital records will reduce risk and lower cost of capital.
Competitive landscape — who matters and why
The air ambulance ecosystem is a mix of national-scale operators, regional specialists and membership networks. Market concentration is meaningful: the leading players collectively control a sizable share of capacity and bases, creating both competitive barriers and partnership opportunities.
-
Air Methods (Greenwood Village, CO) — A large national operator focused on emergency air medical services. Their strength lies in a broad rotor and fixed-wing footprint, clinical capability for high-acuity transports and recent strategic moves to expand both partnerships and fleet capacity. Expect continued focus on scaling critical-care reach through hospital partnerships and base optimization.
-
Global Medical Response (Lewisville, TX) — A vertically integrated provider that bundles air and ground services. GMR’s integrated model offers advantages in coordination of interfacility transfers and cross-selling of managed services; their platform approach is attractive to health systems seeking a single outsourced partner.
-
PHI Air Medical (Tempe, AZ) — A high-capacity rotor-wing operator with a national presence and member-protection programs. Their networked base strategy and membership economics illustrate how operators are protecting patient access and out-of-pocket exposure while improving revenue predictability.
-
REVA Air Ambulance (Fort Lauderdale, FL) — A specialist in dedicated fixed-wing ICU-capable transport. Fixed-wing operators compete on long-range intercontinental capability, bedside-to-bedside clinical care and turnkey coordination for complex repatriation or specialty care transfers.
-
Acadian Companies (Lafayette, LA) — Regional operator with both helicopter and fixed-wing divisions focused on rural and corridor coverage. Their model underscores how strong community relationships and deep local clinical integration can sustain operations in lower-density markets.
-
AirMedCare Network (West Plains, MO) — A membership-driven network aggregating access to affiliated providers. The network model illustrates how financial-protection products (memberships) can smooth patient and payer friction while driving retention and referral flows for affiliated operators.
Recent market activity underscores strategic themes for 2026. Several large operators have announced network and fleet expansions and new hospital partnerships, signaling confidence in demand growth and the strategic value of scale. Simultaneously, multi-year government contracts and renewed base agreements are shifting the footprint calculus for operators that can win long-term public or system-level tenders.
What the PW Consulting report provides (practical, not academic)
Our study is designed for the executive who needs to act. It blends rigorous market sizing with tactical tools and decision-ready outputs:
-
Forward-looking financial model. Scenario-based revenue and cost models that allow you to test fleet, staffing and reimbursement permutations under conservative, base and upside demand assumptions for 2026–2032.
-
Go-to-market playbook. Actionable strategies for hospital partnerships, membership programs, and payer contracting—ranked by expected ROI and implementation complexity.
-
Network and fleet optimization framework. Tools to prioritize base locations, modal mix (rotary vs fixed), and incremental aircraft investment vs. third-party capacity arrangements.
-
Regulatory and compliance checklist. Practical steps to operationalize No Surprises reporting, accreditation preparedness, and data governance for billing audits.
-
M&A and partnership heatmap. A prioritized list of targets and partnership archetypes, scored on strategic fit, regulatory complexity and integration effort.
Note: while the report contains granular splits by geography, aircraft type and service model, we deliberately exclude those detailed segment figures from this preview to preserve the integrity of the full analysis available on the report page.
Strategic imperatives for 2026 — what leaders should do now
-
Hedge payer exposure through membership and contracting innovation. With transparency and reimbursement shifting, operators should expand membership offerings and negotiate bundled, outcome-linked contracts with health systems to protect revenue per transport.
-
Prioritize clinical capability as a market differentiator. Investments in ICU-level transport capability, clinical training and telemedicine-enabled in-flight support yield higher-case acuity capture and premium repositioning.
-
Invest in predictive maintenance and digital ops to lower unit costs. Data-driven maintenance programs reduce downtime and insurance exposure, improving aircraft utilization—especially important when deploying incremental fleet capacity.
-
Design workforce pipelines and retention incentives. Partnerships with academic nursing and paramedic programs, flexible scheduling models, and retention bonuses for critical-care clinicians are necessary to sustain 24/7 operations without prohibitive cost escalation.
-
Pursue selective scale through M&A and alliance playbooks. Consolidation and network affiliation can secure catchment areas and create scale efficiencies, but integration risks—clinical protocols, billing systems and unionized labor—require disciplined due diligence.
-
Build a compliance-first billing architecture. Ensure your revenue cycle and transport documentation workflows align with federal reporting expectations; this is both a risk mitigation and an efficiency opportunity.
Making the 2026 decision — an executive checklist
-
Validate your demand assumptions by modeling both inter-facility referral flows and emergent scene-call scenarios under multiple population and morbidity paths.
-
Stress-test payer contracts against downside reimbursement scenarios and quantify the role of membership revenues in smoothing cash flow.
-
Map critical base locations and simulate alternative fleet mixes; prioritize options that defer capital while preserving service-level commitments.
-
Create a 90–180 day plan to operationalize regulatory reporting and accreditation milestones—these are non-negotiable for access to certain public contracts and system partnerships.
Conclusion — the strategic horizon to 2032
The air ambulance market presents a compelling growth opportunity for operators and investors who can marry clinical excellence with disciplined commercial execution. With the market expanding from a mid-teens billion-dollar base in 2025 to a nearly threefold opportunity over the broader decade under a sustained growth path, the window to position for scale and longevity is now. However, this is a capital- and labor-intensive sector where regulatory shifts and payer dynamics materially affect returns; success in 2026 will require integrating operational rigor with proactive partnership and workforce strategies.
PW Consulting’s full report contains the quantitative segmentation, model inputs and decision tools to implement the strategies summarized here. For executives preparing 2026 capital plans or negotiating system-wide contracts, the report is a tactical briefing and financial playbook—designed to convert market insight into actionable decisions. Visit our report page for the complete study and interactive model access.
For detailed analysis of this topic, please visit the official page: Air Ambulance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Engine-Driven Welders Market to Reach USD 1,914M by 2032 at 4.91% CAGR
By PW Consulting, 2026-07-22
Engine‑Driven Welders Market: Strategic Preview for 2026 Decision‑Makers
This industry preview, prepared by PW Consulting, is a focused executive guide for business leaders, corporate development teams, and product strategists who must make high‑stakes choices in 2026. It synthesizes our quantitative market model (base year 2025; historical coverage 2020–2025; forecast period 2026–2032; currency USD; revenue unit: Million) and translates that evidence into the practical implications you will need for capital allocation, product roadmaps, and go‑to‑market execution. The goal: signal the structural trends and competitive moves you cannot ignore, while reserving the granular segment tables and proprietary breakouts for the full report.
Engine-Driven Welders Market
Why this research matters in 2026
-
The engine‑driven welder sector is at a crossroads where traditional value drivers (durability, duty cycle, fuel economy) intersect with accelerating service and emissions requirements. Decision cycles in procurement, fleet upgrades, and aftermarket agreements increasingly hinge on one‑to three‑year product and regulatory timelines.
Engine-Driven Welders Market -
Our model shows the market expanding from a 2025 baseline of USD 1,380.0 Million to an estimated USD 1,914.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of 4.91% across the forecast horizon. These macro numbers frame capital planning and revenue targets for the immediate strategic window (2026–2028).
Engine-Driven Welders Market -
Market concentration is meaningful: the top three players account for a dominant share of industry revenue, with the top five together representing over four‑fifths of the market—an important context for pricing power, distribution leverage, and M&A dynamics.
Market trajectory — what the numbers imply
Between 2020 and 2025 the market increased from USD 1,080.0 Million to USD 1,380.0 Million, showing resilience through commodity cycles and uneven capex in end users such as construction, pipelines, and mining. Our forecast anticipates continued steady growth driven by replacement cycles, fleet modernization, and the persistent need for combined welding and auxiliary power on remote jobsites. By 2026 the model projects market value of roughly USD 1,430.5 Million, climbing toward USD 1,914.0 Million in 2032 under the base scenario (CAGR 4.91%).
This trajectory validates several strategic implications: inventory planning should shift from strictly short‑run stocking to multi‑quarter phasing; R&D roadmaps must prioritize durability, serviceability, and compliance; and partnerships with engine suppliers will remain a critical source of differentiation.
What we examined (scope of the full study)
-
Market sizing and a bottom‑up revenue model (historical 2020–2025; forecast 2026–2032) with scenario analysis for demand shocks and fuel price volatility.
-
Segment economics across product families, fuel types, and end‑use contexts, illustrated with unit economics and margin ladders (note: detailed segment tables are available in the full report).
-
Value chain mapping from engine OEMs through integrators to service networks, highlighting cost levers and aftermarket capture opportunities.
-
Competitive heatmaps, capability assessments, and an M&A watchlist informed by recent product launches and strategic moves.
-
Regulatory impact assessment covering engine emissions compliance, testing protocols, and key certifications affecting field use in harsh environments.
-
Commercial playbooks for OEMs, distributors, and rental firms including pricing play tests, bundled service offerings, and field finance structures.
Competitive landscape — mapped and interpreted
The market exhibits a clear tiering of incumbents and specialized regional players. Leading multinational manufacturers maintain strong, integrated product lines and dealer networks; mid‑tier specialists focus on niche use cases and price performance; a third layer of regional builders and OEMs emphasize compactness, ruggedization, or cost leadership. The top three and top five concentration metrics underscore the relative ease with which market leaders can impose commercial terms and sustain R&D scale.
-
The Lincoln Electric Company (Cleveland, Ohio) remains a technology and brand stalwart with flagship Ranger® and Frontier® families. Recent product introductions signal continued investment in premium arc performance and robustness for construction and industrial segments.
-
Miller Electric (Appleton, Wisconsin) leverages deep product integration with engine suppliers and maintains strict compliance posture with EPA standards—an important consideration for customers operating in regulated jurisdictions.
-
ESAB Corporation (North Bethesda, Maryland) has shown rapid product refinement for demanding field applications; its recent Ruffian EMP 270G launch (tested for harsh construction environments) is emblematic of the competition to combine compact footprint with high duty cycle capabilities.
-
Hobart Brothers and Multiquip sit squarely in the professional/fleet segments, emphasizing reliability and dealer support, while companies such as Denyo, MOSA, Shindaiwa, and regional players extend reach in fuel efficiency, compact design, or localized service models.
-
Smaller manufacturers and new entrants (including select Chinese and Australian suppliers) focus on price‑sensitive bid markets and export niches, shaping near‑term competitive dynamics for fleet procurement and rental chains.
Recent product launches from ESAB (late 2025) and Lincoln (early 2026) underscore how incumbents are using hardware improvements—higher duty cycles, increased generator outputs, and optimized footprints—to defend share. For buyers, the outcome is a faster cadence of replacement and spec upgrades; for OEMs, it tightens the innovation horizon and increases the importance of reliable supply chains for engines and alternator components.
Key dynamics and strategic implications
-
Regulatory and compliance pressures: Stricter engine emissions and field safety standards are influencing specification strings and procurement decisions. OEMs that demonstrate early compliance and documented test performance secure preferential access to large fleet buyers and rental accounts.
-
Labor and operational economics: Engine‑driven welders reduce on‑site labor and support multi‑tasking (welding plus power generation). This benefit will remain a primary adoption driver in construction and maintenance markets where labor scarcity and productivity are constraints.
-
Supply‑chain sensitivity: Key subcomponents (engines, alternators, control electronics) expose manufacturers to raw material and supplier lead‑time risk. Manufacturers with deeper aftermarket channels and spare‑parts availability will materially outperform in uptime‑sensitive accounts.
-
Product positioning: Premium models are competing on duty cycle and serviceability; mid‑tier propositions will increasingly emphasize integrated service plans and field diagnostics to protect margins.
Actionable playbook for 2026
-
Prioritize spec‑based differentiation: Invest in demonstrable metrics that procurement teams value—duty cycle at rated output, time‑to‑service, and documented emissions conformance. Field performance data is now a commercial asset.
-
Recalibrate inventory and spare‑parts planning: Use our 2026–2028 demand curves to optimize safety stock by SKU class rather than flat percentage rules; allocate capex to parts with the highest service attach rates.
-
Design bundled solutions: Commercialize bundled offerings (equipment + scheduled maintenance + telematics) with predictable margins that appeal to rental fleets and large contractors.
-
Scan M&A opportunities: With CR3 and CR5 concentration high, bolt‑on acquisitions in regional niches or aftermarket services are efficient ways for leaders to expand footprint without commodity price wars.
-
Embed scenario planning: Build downside and upside forecasts around engine fuel price swings and rapid regulatory tightening; maintain flexible sourcing contracts for alternators and control modules to mitigate volatility.
What the full PW Consulting report gives you (select highlights)
-
Proprietary revenue model with quarterly cadence and scenario runs for sensitivity testing.
-
Comprehensive competitor scorecards with capability matrices, recent product timelines, and weakness/opportunity diagnostics.
-
Action templates for OEMs, distributors, and rental operators, including suggested KPIs and pilot designs for telematics and service bundles.
-
Regulatory and testing annex with recommended compliance milestones and certification playbooks.
Note: This preview intentionally omits the granular regional and application split tables, SKU‑level pricing matrices, and proprietary segment revenue breakouts that constitute the core of the paid deliverable—those datasets are essential for transaction diligence, SKU rationalization, and detailed pricing optimization and are available through the full report.
How to use this preview in your 2026 boardroom
-
Use the headline market trajectory and concentration metrics as anchors for strategy sessions on product investment and inorganic growth targets.
-
Adopt the playbook items as the starting point for a 60‑ to 180‑day implementation plan (pilot telematics on top SKU families, renegotiate parts SLAs, run two M&A screens focused on aftermarket).
-
Request selective deep dives from PW Consulting (e.g., scenario analysis under a rapid emissions tightening) to convert this directional view into transaction‑grade diligence.
Conclusion
The engine‑driven welder market in 2026 is neither a sprint nor a static legacy sector; it is evolving into a solutions industry where product performance, compliance, and aftermarket economics determine winners. With a projected market increase from USD 1,380.0 Million in 2025 toward USD 1,914.0 Million in 2032 (CAGR 4.91%), companies that align product development, service models, and supply‑chain flexibility to the near‑term trajectories will secure durable competitive advantage. For executives planning acquisitions, new product launches, or fleet renewal programs in 2026, this preview highlights the decision levers—while the full PW Consulting Engine‑Driven Welders Market report provides the granular inputs required to execute effectively.
Contact PW Consulting to access the complete dataset, industry appendices, and customized advisory support to translate this preview into a 2026 action plan.
For detailed analysis of this topic, please visit the official page: Engine-Driven Welders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Treadmill Machines Market to Reach USD 159.0 Million by 2032 at 6.8% CAGR
By PW Consulting, 2026-07-22
Treadmill Machines Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise yet incisive preview of our full Treadmill Machines Market study — designed to equip senior executives and investors with the strategic context required for high-stakes decisions in 2026. This preview synthesizes the market’s trajectory, competitive dynamics, regulatory shocks, and actionable playbooks. It deliberately signals analytical depth while preserving the proprietary segmentation and modeling that reside in the full report to drive direct engagement with our research offering.
Treadmill Machines Market
Market snapshot and trajectory
Using 2025 as the base year, the global treadmill machines market is positioned on a clear growth path through the forecast horizon. The market was assessed at approximately USD 101 million in 2025 and is projected to reach roughly USD 159 million by 2032 — reflecting a compound annual growth rate (CAGR) of 6.8% for 2026–2032. Historical dynamics from 2020–2025 show a recovery and reconfiguration phase after pandemic-driven shifts in consumer behavior, with growth increasingly underpinned by digital connectivity, premiumization in home fitness, and renewed investment in commercial fitness infrastructure.
Treadmill Machines Market
These headline figures mask important strategic contours: demand is being reshaped along the axes of user experience (immersive, connected training), sustainability (energy efficiency and materials), and spatial constraints (smaller living spaces prompting design trade-offs). Our full model provides granular scenario outputs — including upside/downside cases tied to regulatory timelines, raw-material price shocks, and channel reallocation — which are essential for capital allocation and product roadmaps in 2026.
Treadmill Machines Market
Why this study matters to 2026 decision-making
- Capital allocation and portfolio sizing. With mid-single-digit CAGR and clear premium segments expanding, management teams must choose where to concentrate R&D spend and production capacity. Our report maps revenue and margin sensitivity to product-tier mix and channel strategy, enabling CFOs and strategy teams to model ROI for new product launches and manufacturing footprints.
- Go-to-market and channel optimization. The interplay between direct-to-consumer digital channels, traditional retail, and commercial procurement is shifting fast. We quantify the strategic implications for pricing, bundled services (content subscriptions, maintenance), and trade promotions that preserve margin while expanding reach.
- Regulatory and compliance prioritization. New regulatory pushes on energy efficiency and data protection are already influencing design cycles and market access. Our operational checklists help legal and product teams prioritize compliance investments that avoid market exclusion or retrofitting costs.
- M&A and partnership screening. Moderate market concentration and continued product innovation create M&A opportunities to consolidate technology, scale manufacturing, or access distribution. We flag target profiles, valuation multipliers, and integration pitfalls relevant for 2026 deal pipelines.
Report contents — what you’ll find in the full study
- Methodology and transparent assumptions (base year 2025; historical window 2020–2025; forecast 2026–2032; currency USD, revenue unit: Million).
- Top-line market sizing and seven-year forecasts with sensitivity bands and scenario modeling (regulatory, tariff, and demand shocks).
- Segment-level analysis across product types, applications, and regions (detailed splits are part of the full report).
- Comprehensive competitive landscape: profiles, product portfolios, distribution footprints, recent strategic moves, and capability heatmaps.
- Supply chain and input-cost analysis, including raw material exposure, logistics risk, and manufacturing-location optimization.
- Regulatory impact assessment covering energy-efficiency rules, data/privacy compliance, and safety standards — with implementation timelines and incremental cost estimates.
- Strategic playbooks for product development, channel management, pricing strategies, and near-term tactical initiatives to protect margins and accelerate growth.
- M&A and partnership frameworks with screened target types, valuation assumptions, and post-merger integration (PMI) checklists.
- Operational scorecards and KPI templates to translate strategy into execution for 12–36 month planning cycles.
Competitive landscape — implications for incumbents and new entrants
The market shows a moderate concentration profile: the top three players together account for roughly 45% of industry revenue while the top five reach close to 58%. This structure creates both entry barriers and acquisition opportunities — it favors firms that can combine product differentiation with distribution scale.
- Life Fitness (Chicago, IL — https://www.lifefitness.com): Strong commercial pedigree and trusted service networks make it the partner of choice for health clubs and corporate wellness programs. Its Club Series+ and Atmos models are built for scale; strategic imperatives include digitization of service offerings and modular upgrades to meet evolving efficiency standards.
- TRUE Fitness (St. Louis, MO — https://truefitness.com): A leading privately-held U.S. commercial supplier with deep relationships in facility procurement. TRUE’s strength is reliability and aftermarket service; the opportunity is to leverage that trust into subscription-based maintenance and managed fitness services.
- SOLE Fitness (Salt Lake City, UT — https://www.soletreadmills.com): Positioned on durability and value for home and light-commercial buyers, with strong warranties. The strategic decision is whether to ascend into premium smart offerings or to double down on cost leadership and distribution penetration.
- Precor (Bothell, WA — https://www.precor.com): Premium commercial focus and specialty designs (e.g., slat-belt breakaway technology) give Precor a defensible niche. Key threats are commoditization and regulatory-driven redesign costs; partnerships on energy-efficient components are tactical moves to consider.
- NordicTrack (Logan, UT — https://www.nordictrack.com): A leader in home performance treadmills and immersive content, its competitive edge is integrated training experiences and incline/decline technologies. Maintaining content ecosystem exclusivity and meeting forthcoming data-security standards will be critical.
- Johnson Fitness & Wellness (Cottage Grove, WI — https://www.johnsonfitness.com): Broad retailer and distributor with ties to manufacturing groups. It is well-placed to optimize channel dynamics by co-investing in private-label smart equipment and omnichannel customer journeys.
Notable market activity outside the core incumbents: Peloton’s October 2025 launch of its Pro Series (including a Tread+ Pro) signals intensified competition in premium and commercial-light segments, challenging traditional players on content integration and brand experience. Competitors must evaluate defensive and offensive responses, from faster product refreshes to strategic alliances on content and distribution.
Dynamics shaping near-term strategy
- Regulatory pressure on energy efficiency. The EU’s 2025 directive targeting a 20% energy reduction by 2030 forces redesigns in drive systems, motors, and standby power — a direct input into R&D roadmaps and unit economics.
- Rising tariff and logistics volatility. Mid-2025 tariff hikes on steel and aluminum materially increased landed costs for equipment manufactured abroad. Companies with concentrated offshore production faced tangible overcharge exposures, underscoring the need for diversified sourcing and protective contract terms.
- Spatial constraints and product form-factor innovation. Demand for compact, foldable, or hybrid cardio solutions is rising as urbanization and smaller dwellings constrain in-home footprint tolerance. This drives trade-offs between motor size, durability, and feature sets.
- Cybersecurity and data-privacy requirements. Connected fitness devices now face elevated certification and compliance expectations in key markets, with developers needing robust data governance to maintain EU market access. Recent certifications highlight the new baseline for market entry.
Actionable recommendations for 2026
- Prioritize compliance-ready product lines. Fast-track energy-efficient and privacy-by-design features into 2026 product roadmaps. The cost of retrofitting post-market is typically higher than planned upfront investment.
- Diversify manufacturing and input sources. Implement dual-sourcing for key components and consider nearshoring options to mitigate tariff exposures and long lead times.
- Segment-based GTM plays. Separate commercial and premium home go-to-market strategies — commercial buyers prioritize uptime and lifecycle cost; premium home buyers pay for immersive content and ergonomics. Tailor bundles and service contracts accordingly.
- Monetize after-sales services. Convert maintenance, calibration, and connected-content into recurring revenue streams to smooth demand cyclicality and improve lifetime value.
- Screen M&A and partnerships. Prioritize targets that add proprietary content ecosystems, energy-efficient components, or distribution reach rather than bolt-on commodity manufacturing.
Conclusion — what this means for leaders
The treadmill market in 2026 is neither a mature, commoditized commodity market nor a hyper-growth, winner-takes-most sector. It occupies a pragmatic middle ground: predictable headline growth (CAGR ~6.8% through 2032), concentrated enough to reward scale, yet dynamic enough that product and data capabilities will re-rank market positions. Executives who align R&D, compliance, and channel strategies — and who invest early in energy efficiency and data security — will secure advantaged positions. Conversely, those who delay will face higher retrofit costs and potential market exclusion.
For operators, investors, and strategic partners mapping 2026 decisions, our full Treadmill Machines Market report delivers the granular segmentation, sensitivity models, and deal-level recommendations required to convert market intelligence into capitalized advantage.
Next steps
To access the complete dataset, detailed segmentation, and executable playbooks referenced here, consult the full PW Consulting report. The report contains the proprietary breakdowns and scenario models essential for precise budgeting and portfolio decisions in 2026; consider it a required tool for board-level planning and investor diligence.
For detailed analysis of this topic, please visit the official page: Treadmill Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oil Mist Separator Market Set to Reach USD 259.9M by 2032 at 5.3% CAGR
By PW Consulting, 2026-07-22
Oil Mist Separator Market — Strategic Briefing for 2026 Decisions
Executive summary
The oil mist separator market stands at an inflection point. After a steady recovery from the early 2020s, total industry revenues reached approximately USD 180.8 Million in the base year 2025, reflecting a compound annual growth trend that the report models at a 5.3% CAGR into the coming decade. Our forecast envelope anticipates the market expanding from just under USD 197 Million in 2026 to roughly USD 260 Million by 2032, driven by tightening emissions rules, renewed capital investment in advanced machine tools, and accelerating demand for energy-efficient aftermarket solutions.
Oil Mist Separator Market
For corporate strategists, procurement leads and product executives planning for 2026, these macro dynamics translate into concrete choices: where to invest in product R&D, how to reshape go-to-market models for industrial air quality, and how to size M&A and partnership plays to capture outsized value as demand consolidates around incumbents and innovative challengers.
Oil Mist Separator Market
Why this matters in 2026 — the strategic drivers
-
Regulatory tightening and compliance risk: New and updated standards — notably ISO 5011:2025 testing requirements, continued enforcement under regional industrial emissions directives, and longstanding compressed-air cleanliness rules such as ISO 8573-1 — are increasing the technical bar for oil mist separation performance and certifiable testing. This accelerates replacement cycles for legacy units and raises specification demands in tender processes.
Oil Mist Separator Market -
Occupational health and workplace continuity: Occupational safety frameworks (for example, OSHA exposure monitoring and TWA limits) are prompting manufacturers to treat air cleaning as a core reliability and ESG item. Buyers are prioritizing proven capture efficiency, lower maintenance footprints, and integrated monitoring to de-risk operations.
-
Operational economics and energy optics: The competitive premium for energy-efficient extraction and filtration systems is growing. Recent product introductions focused on energy-saving controls and smart-retrofit kits underscore a broader industry pivot: customers want measurable reductions in lifecycle operating cost, not just upfront filtration efficiency.
-
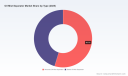
Market structure: The sector sits in a moderately concentrated competitive environment (our concentration metrics show the top three vendors account for roughly 40% of market value, and the top five around 55%). This structure creates room for scale advantages while leaving niches open for specialist vendors and aftermarket innovators.
What our full report delivers — practical, executable outputs
This study is organized around operational decision-making. It is intentionally structured to be usable within procurement cycles, R&D roadmaps and M&A screens without requiring readers to be filtration specialists.
-
Robust market sizing & forecast methodology: Transparent assumptions, scenario variants (conservative, base, upside) and sensitivity analyses tied to macro capex and regulatory timelines.
-
Demand-driver heat maps: Segmented demand levers across end-use categories and purchasing archetypes, prioritized by near-term conversion probability and ROI.
-
Procurement playbooks: Standardized RFP language, technical specs aligned to ISO/OSHA requirements, and evaluation rubrics to compare vendor offers on lifecycle cost rather than purchase price alone.
-
Supplier scorecards & supplier risk matrix: Comparative assessments of capability, product breadth, aftermarket support, and channel distribution — calibrated for integration into vendor management systems.
-
Technology and product roadmap templates: Time-phased recommendations for filtration media, IoT-enabled monitoring, energy-saving retrofits, and modular designs to accelerate adoption and reduce field service costs.
-
Regulatory impact and compliance playbook: Practical checklists and cost/benefit models to assess the business impact of new standards and to prioritize compliance investments.
-
M&A and partnership screening tools: A prioritized shortlist methodology for acquisition targets and partnership archetypes, and a preliminary valuation framework tailored to the sector’s margin profile and scale effects.
-
TCO models and pilot templates: Ready-to-use spreadsheets to estimate total cost of ownership (capex + energy + maintenance + downtime risk) and pilot project templates to accelerate validation in customer environments.
Competitive landscape — who matters and what they are doing
The market is dominated by a mix of long-established filtration specialists and industrial air-quality players. Leading suppliers in the landscape include Filtermist (UK), Donaldson Company (USA), MANN+HUMMEL (Germany), Absolent (Sweden), Kimre (USA), FRANKE-Filter (Germany), Camfil (Sweden), HEINZMANN IFT (Germany) and ESTA Apparatebau (Germany). These firms combine decades of product expertise with global service footprints and varying emphases on OEM relationships, aftermarket retrofits, and tailor-made extraction systems.
Recent vendor activity in late 2025 and early 2026 illustrates the tactical moves you should expect to see across the sector:
-
Product-led differentiation: Filtermist’s roll-out of an energy-saving device (marketed as an F Save solution) and related case studies highlight the near-term opportunity in smart retrofits that materially reduce operating expense for existing installations.
-
Precision and high-accuracy offerings: Absolent’s introduction of a new range aimed at high-precision machining environments signals a push into premium segments where cleanliness specs and low carry-over are non-negotiable.
-
Channel and OEM partnerships: Large air-filtration players and OEM specialists are deepening ties with machine-tool builders and compressor manufacturers to embed separators into new equipment lines rather than relying solely on aftermarket retrofits.
-
Service and digitalization: Expect an increasing split between product vendors that compete on price and those that bundle monitoring, predictive maintenance and extended warranties — the latter commanding higher lifetime margins.
For buyers and investors, the key takeaway is to differentiate between scale players that can deliver global support and specialists that own critical engineering IP for niche or high-spec applications. Our report offers vendor-by-vendor benchmarking that goes beyond boilerplate profiles to quantify aftermarket readiness, R&D focus, and channel penetration.
Strategic implications & recommended 90-day priorities
-
Immediate compliance audit: Map equipment fleets against updated testing standards and occupational exposure rules. Prioritize retrofit or replacement where non-compliance yields operational risk or regulatory exposure.
-
Pilot energy-saving retrofits: Run two controlled pilots (one retrofit, one OEM-integrated) to capture real-world energy and maintenance delta. Use our TCO template to quantify payback within 12–24 months.
-
Supplier consolidation and negotiation: Given the sector’s moderate concentration, combine volume commitments across business units to upgrade commercial terms and service SLAs with key vendors.
-
Product roadmap re-prioritization: For manufacturers, accelerate development of filtration media and IoT monitoring modules that meet ISO 5011:2025 test protocols — buyers are increasingly asking for certified performance data.
-
M&A readiness: Initiate an M&A screen to identify bolt-on targets that expand aftermarket capabilities or proprietary separation technology. Use the report’s valuation framework to fast-track initial diligence.
-
Customer-facing value propositions: Reframe sales messaging from “filtration efficiency” to “factory uptime, energy, and compliance economics” to shorten procurement cycles and justify premium pricing.
How to use this briefing — and where to go next
This briefing is a strategic executive preview designed to inform capital allocation and near-term tactical choices for 2026. It illustrates the forces shaping an industry that is projected to grow at a steady mid-single-digit pace through 2032 and where regulatory and operational drivers are converging to favor technically differentiated and service-rich offerings.
If your team requires the underlying granular intelligence — regional flows, detailed application segmentation, unit economics, vendor scorecards, downloadable TCO models and the complete M&A shortlist — those will be available in the full report. The full study contains the proprietary segmentation matrices, price curves and scenario workpapers that enable rigorous internal business cases and board-level presentations.
Final note from the industry desk
For 2026, the imperative is clear: treat oil mist separation not as a peripheral procurement line item but as a convergent question of emissions compliance, occupational safety and operating economics. The market’s path from the mid-2020s into 2032 rewards players who can pair proven filtration performance with energy intelligence, a resilient aftermarket network, and a sharp commercial proposition. Our full report equips leaders with the templates, models and vendor intelligence needed to translate those opportunities into measurable financial outcomes.
For detailed analysis of this topic, please visit the official page: Oil Mist Separator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cheque Scanner Market to Reach USD 1,464.36 Million by 2032 at 5.6% CAGR
By PW Consulting, 2026-07-22
Cheque Scanner Market 2026: Strategic Imperatives from PW Consulting’s Industry Brief
As PW Consulting’s lead industry analyst, I present an executive orientation to our latest Cheque Scanner Market study — a focused, decision-grade analysis designed to inform procurement, product, and investment choices in 2026. Built on a 2025 base year and a 2020–2025 historical window, the study projects the market through 2032 using transparent scenario techniques. At the macro level, the market reached approximately USD 1,000 Million (base year 2025) and is projected to grow at a compound annual growth rate (CAGR) of about 5.6% over the forecast period, reaching roughly USD 1,464 Million by 2032. Those headline figures mask materially different trajectories across use cases, deployment models and geographies — details that are intentionally reserved for the full report.
Cheque Scanner Market
Why this study matters for 2026 decision-makers
-
Real money, incremental margin: With the market expanding at a mid-single-digit CAGR, cheque scanners remain a meaningful hardware-and-services opportunity for banking channel modernization, branch rationalization programs and third-party integrators. The growth is neither explosive nor stagnant — it is strategic. Decisions made in 2026 on replacement cycles, service packaging, and software licensing will determine which vendors capture durable revenue streams.
Cheque Scanner Market -
Regulatory and compliance drivers are structural, not episodic: Image-based clearing legislation and central bank guidelines have codified technical requirements (image retention, minimum image quality, standardized transmission protocols). These mandates sustain baseline demand for compliant capture devices and create recurring value for vendors that can guarantee certified performance.
Cheque Scanner Market -
Hybrid capture environments increase complexity: Remote deposit capture (RDC), teller-line imaging, and back-office production coexist. Each environment has distinct reliability, throughput and integration requirements. The total-market forecast reflects both replacement activity in mature channels and incremental deployments tied to digital transformation efforts.
-
Technology inflection points matter: Advances in OCR/ICR accuracy, fraud-detection sensors (including UV/IR modalities), networked device management, and “zero-footprint” form factors change total cost of ownership calculations. Vendors that combine hardware with robust software and cloud-enabled device management will command pricing premiums.
What PW Consulting’s report delivers (practical content)
-
Transparent market sizing and forecasting methodology with scenario ranges (baseline, upside, downside) and sensitivity analyses around substitution risk from electronic payments.
-
Demand-model building blocks that procurement and finance teams can plug into enterprise CAPEX/OPEX planning templates — including replacement cycles, utilization profiles, and per-device service-cost assumptions.
-
Vendor scorecards and comparative capability matrices (hardware, software, services, integration footprint, certifications) to shorten vendor short-listing and RFx cycles.
-
Go‑to‑market playbooks for vendors and channel partners: recommended product-packaging, pricing levers, financing options, and partner enablement steps to accelerate adoption in bank branch and corporate treasury channels.
-
Operational checklists and integration guides for IT and operations teams: image-quality test procedures, onboarding protocols, remote monitoring KPIs, and failover strategies to maintain regulatory compliance.
-
Total cost of ownership (TCO) models and upgrade-vs-retain calculators that quantify the breakeven timelines for new scanner investments versus continued maintenance.
-
Risk heat maps and mitigation playbooks for supply-chain disruptions, regulatory change, and fraud-technology arms races.
-
Case studies and procurement templates that illustrate how leading banks and service bureaus have structured contracts, warranties and managed-services arrangements.
Market dynamics and regulatory context
Two regulatory vectors shape ongoing hardware demand. First, legislation enabling image-based clearing has created a persistent baseline requirement for institutions to capture, retain and transmit check images meeting defined quality thresholds. Second, central bank and clearing-house guidelines prescribe minimum technical specs for image quality and transmission — standards modern scanners must meet or exceed. Together, these rules convert what might otherwise be a discretionary IT refresh into a risk-managed compliance priority, especially for institutions with significant daily check volumes.
At the same time, payment behavior is evolving. Electronic channels are eroding some transactional volumes, but cheque-clearing workflows remain embedded in many corporate and retail use-cases. The net effect is a market characterized by steady replacement demand, selective new deployments (notably for RDC and specialized back-office imaging), and room for differentiation through software features, device manageability and fraud detection functionality.
Competitive landscape — who matters and why
The cheque scanner market remains fragmented: a small number of well-established manufacturers supply proven hardware across teller, desktop and production segments, and dozens of regional and niche providers compete on specialized capabilities and service models. Market concentration is low relative to many other banking hardware markets, leaving room for entrants and partnerships.
-
Digital Check Corp. (Northbrook, IL, USA) — Known for the TellerScan and CheXpress product lines, Digital Check is actively refreshing its portfolio. Recent product moves (including an ultraviolet-capable TellerScan update and a zero-footprint CheXpress model with new Smart Button ergonomics introduced in late 2025) indicate a dual focus on fraud detection and branch ergonomics. For banks and integrators, Digital Check’s extensive reseller network is an asset for scale deployments.
-
Panini S.p.A. (Turin, Italy) — Panini’s EverneXt and Vision X platforms position the company as a supplier of intelligent scanners for distributed capture and RDC. Panini plays to the needs of international banks that require multi-lingual support, robust device management and integration with diverse core processing systems.
-
Epson America, Inc. (Los Alamitos, CA, USA) — Epson targets desktop and teller-line use cases with compact, MICR-capable models. Its strength is reliability in high-volume POS and branch scenarios and leveraging broader maker ecosystem relationships for volume sales.
-
Canon U.S.A., Inc. (New York, NY, USA) — Canon’s imageFORMULA CR-series bridges desktop and transport applications; Canon competes on optical quality and brand track record in imaging and production scanners.
-
ARCA Tech Systems, LLC (Mebane, NC, USA) — ARCA focuses on teller and RDC devices and tends to win where ease-of-use and integration with bank teller workflows are priority selection criteria.
-
RDM Corporation (Waterloo, Ontario, Canada) — RDM’s networked EC-series is geared to organizations that prioritize centralized device management and high-reliability MICR operations.
-
NCR Voyix Corporation (Atlanta, GA, USA) — NCR leverages deep banking systems integration capabilities to deliver scanners as part of broader capture and retail solutions, often bundling hardware with software and service agreements.
Strategically, the vendor landscape rewards three capabilities: certified compliance to clearing standards; robust device management and telemetry; and fraud detection beyond basic MICR and OCR (including UV/IR sensing and real-time pattern analysis). The vendors that can align hardware refresh cycles with software subscription models and managed services will capture a disproportionate share of long-term revenue.
Strategic actions for 2026 — recommended playbook
-
For banks and corporates: adopt a lifecycle approach. Prioritize replacement for devices that fail to meet current image-quality or transmission standards; pilot cloud-enabled device management and fraud analytics before committing to enterprise-wide rollouts; negotiate service-level agreements that align with regulatory reporting obligations.
-
For vendors and OEMs: convert hardware relationships into recurring revenue by bundling analytics, remote monitoring and certified maintenance subscriptions. Differentiate with validated fraud-detection modules and streamlined certification pathways for clearing organizations.
-
For systems integrators and resellers: build turnkey propositions that include pre-tested integration packages for leading core-banking systems and provide rapid-deployment professional services. Emphasize compliance and audit-readiness in sales conversations.
-
For investors and M&A teams: target capabilities that expand software and services attach rates, and geographies with under-penetrated remote deposit models. Micro-consolidation is possible given the market’s fragmentation; look for tuck-ins that add device-management IP or clearing-certification expertise.
Risks, contingencies and blind spots
No market forecast is certainty. The primary downside risks are accelerated migration to electronic payment rails in regional pockets that materially reduce cheque volumes, or a sudden regulatory relaxation that reduces hardware compliance needs. Upside risks include faster-than-expected adoption of RDC in emerging markets and regulatory tightening around image-quality standards that force accelerated refresh cycles. Supply-chain pressure, semiconductor availability, and component price volatility remain execution risks for vendors in 2026.
Conclusion — how PW Consulting helps you act in 2026
This brief synthesizes the strategic contours of the cheque scanner sector as you plan 2026 programs. It provides the directional intelligence and operational checklists that reduce procurement uncertainty, shape vendor strategies, and highlight acquisition targets. For readers seeking the complete intelligence — detailed regional and application splits, vendor scorecards with quantified capability ratings, downloadable TCO models, and the scenario-based numerical forecasts underlying the headline CAGR — the full PW Consulting report contains the proprietary datasets and appendices you need.
Contact PW Consulting or visit our report page to access the comprehensive dataset, vendor benchmarking spreadsheets and prescriptive playbooks that will make your 2026 cheque-scanner decisions both defensible and value-creating.
For detailed analysis of this topic, please visit the official page: Cheque Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Isoparaffin Solvents Market to Grow at 3.5% CAGR (2026–2032)
By PW Consulting, 2026-07-22
Isoparaffin Solvents Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Consultant and Chief Industry Analyst, I present a focused, action-oriented primer on the Isoparaffin Solvents market designed to sharpen executive decisions in 2026. This briefing synthesizes macro trends, competitive dynamics, regulatory headwinds, and practical strategic options — while reserving the granular segment-level intelligence and proprietary financial models for the full report.
Isoparaffin Solvents Market
Executive snapshot
The global isoparaffin solvents market has demonstrated steady expansion through the early 2020s and continues to show resilient demand across coatings, metalworking, cleaning, agrochemical and personal-care applications. From a base of USD 761.33 Million in 2020, the market reached approximately USD 905.16 Million in 2025 (base year). Our modeled trajectory points to continued growth through the 2026–2032 forecast window, driven by regulatory substitution away from aromatics, premiumization toward low-odor, low-aromatic grades, and selective capacity investments by major producers. The model consensus projects a compound annual growth rate (CAGR) of ~3.5% over the forecast period, with an anticipated market size of about USD 1,144.78 Million by 2032.
Isoparaffin Solvents Market
Why this matters for decisions made in 2026
- Regulatory inflection points in 2023–2025, and continuing into 2026, materially alter product acceptability and total addressable demand for solvent grades. Companies must decide whether to compete on compliance-grade supply, premium product attributes, or cost leadership.
- Capacity moves by tier-1 suppliers in 2024–2025 have already shifted regional availability and commercial leverage. 2026 will be the year many firms either commit to mid-cycle expansions or pivot to differentiated offerings (e.g., lower-carbon feedstocks, narrow-boiling fractions).
- Feedstock volatility and tighter VOC enforcement compress margins for undifferentiated commodity-grade solvents; strategic procurement and hedging decisions executed in 2026 will determine cost resilience for the remainder of the decade.
Market trajectory and what the headline numbers tell you
High-level market metrics show steady, predictable growth rather than a boom-bust cycle. From the 2020 baseline to the 2025 measurement, the market expanded by a material single-digit cumulative rate, with the base year at USD 905.16 Million. Our forecast through 2032 reflects a continuation of this steady trajectory — reaching roughly USD 1,144.78 Million — under a central-case CAGR of 3.5%. The near-term ramp to 2026 (projected at around USD 940.0 Million) is supported by both regulatory substitution and replacement demand in industrial end uses.
Isoparaffin Solvents Market
Two structural observations inform commercialization strategies:
- Consolidation is moderate: the market concentration metrics show that the top three and top five players account for a non-dominant but meaningful share of industry revenue. This implies that scale brings advantages (supply security, product breadth, regulatory compliance investment), but regional and product niches remain contestable.
- Demand mix is shifting toward higher-purity, low-aromatic grades as regulators and formulators prioritize VOC reduction and human-safety attributes. This creates margin opportunities for manufacturers that can cost-effectively produce compliant, high-spec grades.
Key market drivers and constraints (what we watch in 2026)
- Regulatory pressure: Tightening VOC limits in major jurisdictions have accelerated substitution away from aromatic solvents. In 2023–2025 several South American countries tightened standards and global regulatory frameworks continue to push formulators toward compliant isoparaffinic grades. Compliance is not optional for market access; it is a product-portfolio and capex decision.
- Feedstock dynamics: Isoparaffin production remains exposed to feedstock volatility and refinery integration decisions. Raw-material price swings and feedstock availability will continue to influence margins and the cadence of new capacity.
- Product premiumization: Technical differentiation — narrow boiling ranges, low odor, low aromatics, lower lifecycle carbon intensity — is becoming a primary route to value capture versus competing on price alone.
- End-market exposure: Demand sensitivity differs by end-use — industrial coatings and metalworking show cyclical and replacement-driven demand, while personal care and pharmaceuticals favor higher-purity grades with stable, higher-margin consumption.
- Supply-side moves: Several leading producers have increased capacity or launched new plants and product datasheets in 2024–2025, reshaping regional supply balances and raising the bar on technical capabilities and service models.
Competitive landscape — what leading players are doing
The competitive field is composed of diversified energy & chemicals majors and specialized petrochemical producers. These participants pursue a mix of scale, technical differentiation, regional footprint and integrated value chains. Notable dynamics to monitor in 2026:
- Large integrated players (global majors) leverage feedstock integration, branded product lines and broad distribution networks to defend premium segments and serve multinational formulators.
- Regional and specialty producers focus on bespoke grades, fast technical support and localized supply resilience — particularly important where regulatory regimes have shifted quickly.
- Recent company moves illustrate the strategic priorities shaping the competitive set: targeted plant inaugurations to secure local supply, incremental capacity increases to meet demand pockets, and updated product datasheets to emphasize low-aromatic, low-odor attributes and regulatory compliance.
These behaviors create a marketplace where scale matters but technical service and regulatory alignment are decisive. Companies that can marry manufacturing flexibility with rapid commercial response will outcompete those relying on legacy cost advantages alone.
Strategic imperatives for 2026 — recommended actions
Executives must prioritize a short list of decisions in 2026 that will determine competitive positioning through 2032. Our top five imperatives:
- Portfolio clarity: Segregate commodity and specialty streams. Protect margins in premium, regulatory-compliant grades via assured low-aromatic production and differentiated service (technical support, formulary guidance, regulatory documentation).
- Capex alignment: Reassess near-term capacity projects through a regulatory and customer-contract lens. Where demand is concentrated in compliant, higher-spec grades, retrofit and debottlenecking can offer higher IRR than greenfield commodity plants.
- Procurement & feedstock strategy: Implement dynamic sourcing and hedging frameworks. Where possible, secure feedstock through integrated partners or long-term contracts to reduce margin volatility — and build contingency plans for periods of refinery tightness.
- Commercial and go-to-market redesign: Price for value in applications that demand low odor/low aromatics and push performance-based contracts with formulators (e.g., guaranteed VOC performance, documentation, and REACH/EHS dossiers). Invest in sales engineering capability in target verticals.
- M&A and partnerships: Pursue bolt-on acquisitions that add formulation expertise, regional distribution, or sustainable feedstock pathways. Partnerships with formulators or co-manufacturers can accelerate customer adoption of higher-spec grades without disproportionate capital outlay.
Risk management and scenario planning
Actionable strategy in 2026 should be predicated on scenario planning across three dimensions: regulatory tightening, feedstock price shocks, and demand revaluation for high-spec grades. For each scenario, prepare playbooks that map to production, commercial and balance-sheet responses — for example, contingency allocations to merchant inventory, accelerated R&D prioritization, and contractual renegotiation templates.
The PW Consulting deliverable — what our full report provides
Our comprehensive market study (base year 2025; forecast period 2026–2032) combines quantitative models and executable guidance without overwhelming decision-makers with raw tables. The full report includes:
- Proprietary market model with historicals (2020–2025) and multi-scenario forecasts to 2032, including sensitivity analyses and demand-driver elasticities.
- Commercial playbooks for suppliers, formulators and distributors covering pricing strategies, channel design and contract structures tailored to each end-use cluster.
- Supplier scorecards and capability maps evaluating technical, regulatory and supply-security attributes for every major producer.
- Regulatory matrix and compliance timelines for major jurisdictions, with recommended mitigation timelines and capex thresholds.
- Risk register and scenario playbooks focused on feedstock volatility, VOC enforcement, and supply disruptions.
- Actionable M&A and partnership pipeline suggestions prioritized by strategic fit and expected payback.
To preserve the commercial integrity of our analysis while offering immediate strategic insight, the executive briefing here intentionally omits segment-level revenue splits and granular regional/application percentages. These are available in the full report and interactive model.
How senior teams should use this briefing in 2026
- C-suite: Use the headline market trajectory and strategic imperatives to frame capital allocation committees and board-level reviews. Focus approval decisions on projects aligned to compliance-grade production and margin-protecting commercial models.
- Commercial & Sales: Recalibrate quotas and training to sell value (compliance, odor, performance) rather than commodity liters. Prioritize accounts where premium uptake can be accelerated via technical services.
- Supply Chain & Operations: Fast-track retrofit/dedicated-line projects for higher-spec grades; embed scenario triggers for procurement actions tied to feedstock price bands.
- M&A & Corporate Development: Use the supplier scorecards and partnership pipeline to prioritize bolt-ons that close capability gaps and accelerate market access in regulatory-tight regions.
Closing — the 2026 inflection
2026 is the transition year: regulatory momentum, supplier capacity adjustments and changing formulators’ preferences converge to create both risk and opportunity. Companies that act early — aligning product portfolios, securing feedstock, and shifting commercial models toward value-based pricing — will capture the growth premium implicit in a market expanding to an anticipated USD 1,144.78 Million by 2032 (CAGR ~3.5%).
For teams preparing strategic plans, investment memoranda, or commercial rollouts in 2026, our full Isoparaffin Solvents Market study provides the data, scenarios, and commercial playbooks necessary to convert insight into action. Contact PW Consulting to access the complete report and interactive forecast model, which contains the detailed segmentation and supplier-level analytics that informed the recommendations summarized in this briefing.
For detailed analysis of this topic, please visit the official page: Isoparaffin Solvents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial X-ray Market to Grow at 8% CAGR to USD 2,510.6M by 2032
By PW Consulting, 2026-07-22
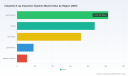
Industrial X-ray Inspection Systems Market — Strategic Outlook for 2026 Decision Makers
Executive preview
As organizations prepare capital allocation, product roadmaps, and go-to-market strategies for 2026, the industrial X‑ray inspection systems market is emerging as a structurally attractive, innovation-led sector. Our PW Consulting market study — summarized here as a strategic “trailer” — synthesizes macro growth, competitive posture, technology inflection points, and regulatory momentum that will shape winners and laggards over the coming strategic planning cycles. The intention of this preview is to demonstrate the depth and actionable orientation of the full report while preserving the granular segmentation tables and model‑level economics that senior teams will want to review directly in the source document.
Industrial X-ray Inspection Systems Market
Where the market stands — a concise macro snapshot
- Market trajectory: The industrial X‑ray inspection systems market expanded materially in the early 2020s and, under current assumptions, is forecast to continue growing at a steady compound annual growth rate (CAGR) of roughly 8.0% across the 2026–2032 forecast window.
- Scale and momentum: From a mid‑cycle base in 2025, the market demonstrates healthy demand tailwinds driven by regulatory compliance, electrification of transportation, semiconductor/consumer electronics quality demands, and increased use of additive manufacturing in mission‑critical industries.
- Concentration dynamics: Industry concentration is relatively high, with the top three and top five suppliers commanding a substantial share of industry revenues — a structural fact that raises both opportunity and caution for entrants and incumbents considering pricing and channel strategies.
Why the market matters for 2026 strategic decisions
Several converging forces make the next 12–24 months a critical window for corporate leaders to decide where to commit engineering, go‑to‑market, and M&A resources:
Industrial X-ray Inspection Systems Market
- Regulatory tightening increases baseline demand: Food safety authorities and aviation regulators are strengthening inspection requirements. These mandate higher detection sensitivity and more rigorous qualification processes — effectively lifting the floor for inspection capability and creating greenfield demand for modern X‑ray and CT solutions among operators who were previously under‑invested.
- Technology upgrade cycle: Detector and CT innovations are enabling new inspection use cases and higher throughput. Suppliers that bundle advanced detectors, software‑driven reconstruction, and automation will gain share from legacy suppliers who are slower to integrate direct‑conversion detectors, photon‑counting approaches, and AI‑enhanced defect recognition.
- Industry convergence: Additive manufacturing, high‑value castings for aerospace, and complex electronics assemblies now require end‑to‑end metrology and inspection. Buyers are increasingly seeking integrated inspection ecosystems rather than standalone machines — a shift that favors suppliers with software, service, and systems integration capabilities.
Actionable implications for executives
For product leaders, commercial heads, and corporate development teams, the market presents a distinct set of choices. Below are pragmatic, prioritized actions that emerged from our analysis and that can be operationalized during 2026 planning cycles.
Industrial X-ray Inspection Systems Market
- Prioritize detector and reconstruction R&D. Allocate near‑term investment to integrate next‑generation detectors (direct conversion and photon‑counting paradigms) and to certify metrology‑grade CT workflows for key verticals. The return on R&D will be twofold: defend technology leadership and enable premium pricing in regulated segments.
- Move up the stack with software and automation. Develop or acquire advanced image processing, AI‑based defect recognition, and production‑line orchestration modules. Buyers increasingly prefer systems that reduce operator dependence and deliver actionable inspection data directly into manufacturing execution systems.
- Design regulatory proof points into product launches. For sectors subject to strict oversight (e.g., aerospace and food safety), create documented qualification packages, audit‑ready traceability, and validated detection thresholds to shorten procurement cycles and reduce buyer friction.
- Pursue selective M&A and partnerships. Given the market’s concentration and technology premium, bolt‑on acquisitions (detector suppliers, AI startups, detector‑to‑system integrators) or strategic partnerships with metrology software firms can accelerate capability building while mitigating time‑to‑market risk.
- Calibrate go‑to‑market by vertical momentum. Focus sales and service investments on industries undergoing rapid inspection complexity increases (e.g., additive manufacturing, semiconductor packaging, critical aerospace components). These verticals buy premium capabilities and support higher service attach rates.
Report highlights — what the full study delivers
The full PW Consulting report translates market dynamics into operational guidance. Key deliverables include:
- Actionable market sizing and forecast models with scenario analyses (base, upside, downside) that reflect both macro demand and technology adoption curves.
- Proprietary supplier benchmarking that evaluates product portfolios, roadmaps, installed base, service networks, and pricing power — enabling you to identify strategic partners and white‑space opportunities.
- Decision frameworks for R&D vs. M&A allocation, including valuation sensitivities for detector IP, software modules, and turnkey inspection solutions.
- Commercial playbooks for sales motion, channel design, and aftermarket service models tailored to the inspection lifecycle.
- Regulatory impact assessment and compliance templates for principal verticals to accelerate customer qualification and procurement approval.
Competitive landscape — who matters and why
The competitive picture is shaped by established industrial players and specialized systems integrators. In the near term, success will hinge not just on X‑ray hardware, but on how companies integrate detectors, reconstruction algorithms, automation, and services.
- Comet Yxlon (Germany) — Strong in high‑end X‑ray and CT systems for aerospace and semiconductor inspection. Their emphasis on precision CT and systems engineered for defect detection positions them well for continued demand from mission‑critical verticals.
- Nikon Corporation — Industrial Solutions BU (Japan) — A recent product launch underscored Nikon’s intent to capture complex electronics and additive manufacturing inspection use cases with compact, metrology‑grade CT systems. Nikon’s robotics and metrology heritage gives them leverage to sell integrated inspection cells.
- DÜRR NDT GmbH & Co. KG (Germany) — Focused on digital detectors and system hardware; recent detector launches reflect an aggressive push into higher‑sensitivity isotope and high‑energy inspection applications, strengthening their competitiveness for industrial throughput environments.
- VisiConsult X‑ray Systems & Solutions GmbH (Germany) — Differentiates through custom systems and niche engineering for automotive and aerospace clients that require non‑standard inspection layouts and bespoke automation.
- VJ Technologies, Inc. (United States) — Brings strength in turnkey automated solutions and service capability for high‑value manufacturing lines, relevant for OEMs integrating inline inspection.
- Maha X‑Ray Equipments Pvt. Ltd. (India) — Plays a role in lower‑cost system supply and export markets, important for organizations balancing budget constraints with inspection requirements.
- Bosello High Technology srl (Italy) and 3DX‑RAY Ltd. (UK) — Specialists in high‑energy CT and tailored systems, addressing large casting inspection and bespoke manufacturing applications respectively.
Notably, the supplier landscape is being reshaped by incremental product launches and detector upgrades from several vendors during 2025–2026. These developments are accelerating a technology refresh cycle and raising buyer expectations for sensitivity, footprint efficiency, and metrology capability.
Technology and regulation — the twin accelerants
Two themes are particularly transformational:
- Detector technology transition. The industry is moving away from conventional amorphous silicon panels toward direct‑conversion detectors and photon‑counting CT technologies. This shift materially affects performance envelopes for low‑contrast detection, dose efficiency, and reconstruction fidelity.
- Regulatory enforcement and standards. Stronger mandates in food safety and stricter certification requirements in aerospace are making higher capability inspection non‑negotiable for many buyers. Suppliers that can demonstrate validated detection thresholds, reproducibility, and full audit trails will shorten procurement timelines and command premium placements.
Risks and mitigation strategies
Key risks for 2026 planning include supply chain pressure on detector components, potential delays in certification for new detector types, and competitive pricing erosion as more players introduce upgraded systems. Mitigation levers include diversifying detector sourcing, investing in validation labs to accelerate customer qualification, and structuring recurring revenue via service contracts and software subscriptions.
What this means for boardrooms and strategy teams in 2026
For CEOs and corporate development teams, the market presents a clear and actionable rule set: invest selectively in detector and software differentiation, acquire capability that accelerates time‑to‑market (particularly in AI and metrology), and prioritize channels into regulated, high‑value verticals. For product and operations leaders, the imperative is to shorten the time between R&D validation and field qualification so that new detector and CT capabilities reach revenue‑generating deployments within the next 12–18 months.
Next steps — how to use the full PW Consulting study
This preview outlines strategic priorities and the directionality of market forces. The full PW Consulting report provides the granular segmentation, regional and use‑case economics, supplier scorecards, and executable playbooks that senior teams need to operationalize these recommendations. If your organization is preparing capital budgets, adjusting R&D roadmaps, or evaluating M&A targets for 2026, the full dataset and supplier assessments in the report will be essential to move from strategic intent to execution.
To access the complete analysis, proprietary models, and supplier benchmarks that underpin these recommendations, please refer to the full Industrial X‑ray Inspection Systems Market report issued by PW Consulting.
For detailed analysis of this topic, please visit the official page: Industrial X-ray Inspection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Booster Pump Market to reach USD 306.47 Million by 2032 at 4.45% CAGR
By PW Consulting, 2026-07-22
Booster Pump Market — 2026 Strategic Briefing
Introduction
As PW Consulting’s lead industry analyst, I present a focused strategic perspective on the global booster pump market that is designed to inform executive decisions in 2026. Our latest study synthesizes historical performance, near-term disruptions, and a seven-year forecast horizon to convert market intelligence into executable strategy. The market has demonstrated steady expansion through the last half-decade and — under a baseline scenario — continues to grow at a mid-single-digit compound annual growth rate through the early 2030s. For leaders planning capital allocation, new product launches, channel investments, or M&A activity, this briefing highlights the practical implications of that trajectory while directing you to our full report for granular segmentation and model outputs.
Booster Pump Market
Market trajectory and macro outlook
From the 2020 baseline to the 2025 reporting year, the booster pump market has shown resilience amid supply-chain volatility and shifting end‑market demand. Using 2025 as our base year, our forecast to 2032 shows continued expansion, driven by a combination of infrastructure reinvestment, building‑efficiency retrofits, and increasing adoption of variable‑speed and digital control systems. The market’s compound annual growth rate (CAGR) in our core scenario is 4.45%, reflecting steady, predictable expansion rather than episodic spikes.
Booster Pump Market
For strategic planners, the implications are clear: demand is large enough to support differentiated product families and service models, yet growth is measured — favoring investments that improve margins (energy efficiency, digital controls, modular systems) and recurring revenue (service contracts, parts, lifecycle management) over undifferentiated volume plays.
Booster Pump Market
Why this matters for 2026 corporate decisions
- Capital allocation must balance growth and efficiency: With an established growth runway but modest CAGR, the highest ROI investments are those that reduce life‑cycle cost for customers (e.g., energy‑saving variable‑speed drives) or create lock‑in via after‑sales services.
- Product strategy should prioritize differentiation: Energy performance, embedded controls, and modular packaged systems are the vectors that create premium positioning against commoditized centrifugal units.
- Procurement and supply‑chain design need contingency layers: Recent project timelines and vendor announcements show that specialists and package suppliers can deliver tailored solutions faster than broad OEMs when logistics are stressed — an important consideration for large infrastructure projects.
- Regulatory compliance is now a design constraint: Regional minimum pressure, updated pump standards, and building energy calculators are increasingly incorporated into specifications; early engagement with standards bodies and code consultants reduces rework risk.
- M&A and partnership targets should be service- and niche‑technology focused: Given market fragmentation and the premium on lifecycle revenue, acquisitions that add service capability, digital telematics, or access to specific vertical channels (municipal, high‑rise, irrigation) are compelling.
What PW Consulting’s full report delivers (practical contents)
- Market sizing and validated historical time series (2020–2025) and scenario-based forecasts (2026–2032) with sensitivity testing.
- Granular segmentation by region, pump type, and application — with demand drivers and adoption curves for each segment. Note: our briefing intentionally omits core split tables; the report contains the complete breakdowns and model files.
- Competitive landscape and capability mapping of leading OEMs and specialist suppliers, including product portfolios, channel reach, and aftermarket strength.
- Pricing and margin benchmarking, purchase‑decision matrices for key buyer cohorts (municipal engineers, MEP contractors, OEM specifiers), and procurement playbooks.
- Technology and innovation roadmaps, including electrification, variable‑speed integration, digital controls/telemetry, and service‑oriented product design guidelines.
- Regulatory impact assessment and a standards watch tied to procurement specifications and product development milestones.
- Actionable go‑to‑market playbooks: how to launch a packaged system, scale a service offering, or integrate telematics into existing product families.
- M&A screening criteria and a shortlist of strategic archetypes (aftermarket consolidators, niche OEMs, digital control enablers) with valuation levers and integration risk checklists.
Competitive landscape — strategic implications
The market structure is best described as fragmented with a meaningful tier of global full‑range suppliers and a broad long tail of regional specialists and package integrators. Rather than disclosing exhaustive split statistics here, the most important strategic orientation is this: the leading firms are differentiating through breadth of offering and systems capability, while nimble regional players compete on customization, speed, and service.
- Global full‑range OEMs (e.g., Grundfos, Xylem, Wilo, Pentair): These players leverage R&D scale, branded packaged systems, and broad distribution. Their strategic advantage lies in energy‑efficient platforms, global aftermarket networks, and brand trust — making them default choices for large commercial and institutional procurements. Expect continued incremental innovation around smart controls and energy optimization.
- Specialist package suppliers and OEMs (e.g., Gorman‑Rupp, Penn Pump, US Pump Corp, Nickerson): These firms are the go‑to for bespoke booster stations, rapid project delivery, and serviceability. Their strength is customization; their path to scale is either geographic expansion or partnerships with larger distributors.
- Value and replacement-focused suppliers (e.g., Walrus of America, APEC Water Systems): These competitors compete on plug‑and‑play convenience and price/availability for residential and light commercial segments. Margin pressure is real here; differentiation comes from channel exclusivity and SKU rationalization.
- Technology and service innovators (e.g., Franklin Electric, Towle‑Whitney): Movement toward smart, variable‑speed packages with digital monitoring is concentrated among companies that can bundle control hardware, software, and service. The winner’s playbook is combining hardware reliability with a subscription or SaaS service layer.
Recent industry movements underscore these strategic dynamics: new multistage and variable‑speed product launches in 2026, price list updates from major suppliers, and completed custom installations signal active product refresh cycles and steady project demand. Several municipalities and institutions are also issuing RFPs for full station upgrades, emphasizing turnkey delivery and commissioning capability.
Regulatory and standards pulse — operational ramifications
- Minimum pressure regulations and building energy calculators are increasingly embedded in procurement specs; product teams must validate hydraulic performance under these constraints early in design.
- Standards updates for turbine and submersible equipment have spillover effects for booster station certification and interoperability; manufacturers should align type‑testing and documentation roadmaps accordingly.
- Industry conferences and standards forums remain critical go‑to venues to influence specifications and stay ahead of code changes that affect product acceptance and warranty exposure.
Critical strategic moves for executives in 2026
- Prioritize product upgrades that lower customer TCO: Focus R&D on variable‑speed drives, motor efficiency, and hydraulic optimization; demonstrate lifecycle savings through third‑party validation.
- Build service and digital revenue streams: Pilot telematics + predictive maintenance offers in select markets to prove unit economics before scaling to broader channels.
- Refine go‑to‑market segmentation: Separate propositions for municipal/infrastructure projects, commercial building systems, and residential replacements — each needs tailored sales motions and warranty structures.
- Use M&A to close capability gaps: Target acquisitions that add rapid commissioning teams, aftermarket parts networks, or software control expertise rather than broad revenue plays alone.
- Harden supply continuity: Diversify key component sourcing and build modular platform designs that tolerate lead‑time variability without redesign.
- Model multiple demand scenarios: Use the PW Consulting forecast models to stress‑test pricing, service penetration, and capex plans across conservative, base, and upside demand trajectories.
How to use this PW Consulting report
Our report is designed as a decision‑support tool across functions. Product teams receive prescriptive design constraints and competitor feature maps; commercial leaders get pricing benchmarks, channel optimization levers, and RFP win strategies; strategy and corporate development teams obtain M&A screening frameworks and valuations tied to aftermarket accretion. Procurement and supply‑chain managers can run parts‑level sensitivity analyses against our forecast scenarios to size buffer inventories and contract terms.
Closing — why read the full study
This briefing highlights the strategic contours that matter in 2026: steady market growth at a mid‑single‑digit CAGR, rising importance of energy and digital differentiation, a fragmented competitive field where systems and services win margins, and regulatory pressures that are reshaping specs. If your objective is to refine product roadmaps, prioritize service investments, or evaluate acquisition targets, the granular segmentation, regional demand drivers, pricing matrices, and proprietary scenario models in our full Booster Pump Market study are essential. The public summary signals where advantage can be won; the complete report supplies the segmented data, model files, and recommended playbooks you need to act with confidence.
Contact PW Consulting or visit our research page to access the full dataset, model workbook, and tailored advisory packages that translate this intelligence into a prioritized 12–24 month execution plan.
For detailed analysis of this topic, please visit the official page: Booster Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


