



Category: Machinery & Automotive
Aviation Oxygen Systems Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market research brief on the Aviation Oxygen Systems market positions executives to make informed, high‑impact decisions in 2026. The market has moved from a recovery phase into a sustained expansion driven by fleet modernization, tightened airworthiness oversight, and expanding aftermarket demand. Our base‑year synthesis (2025) and forward projections (2026–2032) show a robust trajectory — the market expands from an early‑decade base in 2020 through to a materially larger opportunity by 2032, with a compound annual growth rate (CAGR) of 6.8% across the forecast horizon. This briefing highlights the strategic implications of that growth, the competitive dynamics you must monitor, and the practical actions that will protect and grow revenue and margins this coming year.
Aviation Oxygen Systems Market
Market trajectory and what it means for 2026
-
Recovery to growth: After a multi‑year recovery in the early 2020s, the market reached a meaningful inflection point in 2024–2025 as airlines, business aviation operators, and defense fleets accelerated oxygen system upgrades and MRO activity.
Aviation Oxygen Systems Market -
Scale and momentum: Our model quantifies the market’s march upward through 2025 and projects continued expansion across 2026–2032. That expansion is driven by a mix of OEM fitment on new platforms, retrofits and upgrades (including on‑board oxygen generators and advanced delivery systems), regulatory compliance cycles, and aftermarket maintenance demand.
Aviation Oxygen Systems Market -
Concentration and competitive pressure: The sector exhibits moderate concentration — the top three players capture roughly half of the market, and the five largest vendors command well over sixty percent. This structure creates a dual opportunity for established suppliers to extract scale economies and for challengers to win niche share through service differentiation or technology specialization.
Strategic implications for 2026 corporate planning
-
Prioritize MRO and service‑based revenue. As fleets age and regulatory regimes (airworthiness directives, hydrostatic testing cycles, and purity standards) drive recurring work, aftersales service becomes a high‑margin, sticky revenue stream. Leading players will convert installed base visibility into scheduled MRO programs, subscription services for oxygen cylinder rotation and testing, and bundled compliance offerings.
-
Accelerate certification roadmaps. Regulatory actions in 2025–2026 have demonstrated that airworthiness authorities are actively reassessing portable breathing equipment and operational instructions. Firms that pre‑emptively invest in design validation, AD‑driven replacements, and transparent traceability for oxygen equipment will shorten time‑to‑market and reduce retrofit risk.
-
Invest in next‑gen delivery technologies. Pulse‑demand delivery, compact OBOGS implementations for specific aircraft classes, and smart regulator platforms with integrated sensors for purity and leak detection are adoption vectors with two benefits: product differentiation and longer lifecycle revenue through software and analytics services.
-
Build supply‑chain resilience for critical components. Cylinders, valves, regulators, and mask assemblies are subject to lead‑time variability and regulatory test requirements. Companies should develop diversified sourcing, in‑region repair stations, and forward test capacity to avoid revenue loss from grounding or deferred maintenance.
-
Pursue targeted M&A and partnerships. The market’s concentration profile favors bolt‑on acquisitions that expand MRO footprints, add FAA/EASA repair station approvals, or bring complementary technologies (pulse systems, sensor platforms). The Aerox acquisition activity in early 2025 typifies how strategic MRO capacity deals can immediately deepen service capabilities.
Competitive landscape — what to watch
Our report profiles incumbent OEMs, specialized manufacturers, and defense‑grade suppliers. Key players we analyze include Aerox Aviation Oxygen Systems, Safran Aerosystems (AVOX Systems), Collins Aerospace (RTX), Precise Flight (formerly Nelson Oxygen), Mountain High Equipment & Supply, Meggitt (now integrated under Parker Hannifin for certain capabilities), and Honeywell Aerospace. These vendors differ in several strategic dimensions:
-
Product breadth: Some firms compete across passenger, crew and military lines with integrated PSU/OBOGS solutions; others focus on portable and GA‑oriented systems where aftermarket and DIY installers remain important.
-
Service ecosystems: Leaders with repair‑station networks and certified MRO capabilities can monetize regulatory compliance cycles and cylinder testing obligations more effectively.
-
Regulatory exposure: Airworthiness directives and PBE rulings create short‑term product replacement demand but also raise certification costs. Recent ADs affecting portable breathing equipment underscore the need for proactive compliance programs and recall mitigation playbooks.
-
Defense vs. civil balance: Firms with defense OBOGS and precision regulator experience enjoy higher technical barriers to entry and often benefit from multi‑year procurement programs; civil suppliers rely more on airline retrofit cycles and GA adoption.
Regulation, safety and operational drivers
-
Operational mandates: International and civil aviation regulators enforce specific crew and passenger oxygen use thresholds, as well as oxygen purity and moisture requirements that differ from medical or industrial oxygen. These rules drive both product specification and recurring maintenance obligations (e.g., hydrostatic testing of cylinders).
-
Airworthiness actions: Recent EASA and FAA actions on portable breathing equipment illustrate how even a small subset of product failures can trigger fleet‑wide interventions. Companies must embed regulatory surveillance and rapid response capabilities into product management and customer communications.
What’s in the PW Consulting report (practical value for 2026)
This research is designed as an operational tool for strategy teams and commercial leaders. Highlights include:
-
Proprietary market model: A transparent, auditable model that reconciles historical performance (2020–2025) with a scenario‑based 2026–2032 forecast (anchored to a 6.8% CAGR). The model supports sensitivity testing for fuel price shocks, regulatory cadence, and retrofit acceleration.
-
Customer economics & procurement playbooks: Unit economics for OEMs and MROs, typical service contract structures, and recommended commercial terms to protect margins while increasing fleet penetration.
-
Competitive scorecards and vendor playbooks: Benchmarking across technology, certifications, MRO footprint, and service capabilities — useful for vendor selection and partnership negotiations.
-
Regulatory impact analyses: Detailed scenarios that quantify the near‑term revenue uplift from AD compliance and the long‑term cost of elevated certification requirements, with recommended mitigation steps.
-
Implementation roadmaps: Prioritized initiatives, estimated investment ranges, and KPIs for 12‑, 24‑, and 36‑month horizons to convert strategic intent into measurable outcomes.
Note: To preserve the tactical value of the report as a practical purchase decision for our clients, this public briefing intentionally omits granular regional and application segment tables and dollarized splits. The full intelligence pack contains those detailed breakdowns, company revenues, and product‑level forecasts.
Recommended near‑term actions (a checklist for 2026)
-
Audit your installed‑base visibility and certification status; prioritize customers with imminent hydrostatic or AD compliance windows.
-
Allocate capex to expand FAA/EASA‑approved repair stations or partner with certified MROs to capture cylinder rotation and testing pools.
-
Accelerate product roadmap items that reduce life‑cycle cost for operators (lighter cylinders, pulse‑demand electronics, predictive maintenance sensors).
-
Build regulatory monitoring and recall response teams; predefine logistics for rapid replacement campaigns in case of ADs or PBEs impacts.
-
Assess M&A targets that close service gaps, expand regional presence, or add platform certifications — prioritize deals that deliver EBITDA‑accretive service revenue within 12–18 months.
How to access the full intelligence
PW Consulting’s full Aviation Oxygen Systems Market report includes the exhaustive datasets, granular regional and application breakdowns, company financials, and downloadable models that are excluded from this briefing. Organizations planning capital allocations, supply‑chain investments, or M&A activity in 2026 will find the complete package essential to de‑risk decisions and capture growth opportunities.
For access to the full report, vendor scorecards, and the forecast model (including downloadable scenario variants), contact PW Consulting’s industry practice or visit our report page to request a sample chapter and purchase options.
— PW Consulting, Strategic Advisory & Industry Research
For detailed analysis of this topic, please visit the official page: Aviation Oxygen Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aerospace Aircraft Stainless Steel Market Poised for 5.45% CAGR Through 2032
By PW Consulting, 2026-07-13
PW Consulting: Strategic Brief — Aerospace Aircraft Stainless Steel Market Outlook (2026)
Executive summary
As aviation operators and aerospace OEMs enter 2026, stainless steels remain a central material choice for aircraft structures, engines, landing systems and high-reliability interior components. Our new Aerospace Aircraft Stainless Steel Market report (base year 2025; historical period 2020–2025; forecast 2026–2032) synthesizes market dynamics, supplier positioning and practical decision frameworks to help C-suite and procurement teams convert material and supply-chain uncertainty into defensible actions.
Aerospace Aircraft Stainless Steel Market
Key macro takeaways: the global aerospace stainless steel market has shown resilient expansion—from roughly USD 1.85 billion in 2020 to about USD 2.73 billion in 2025—and is forecast to approach USD 4.0 billion by 2032, growing at a compounded annual growth rate (CAGR) of 5.45% over the 2026–2032 forecast window. Market concentration is moderate: the top three suppliers account for a meaningful share of supply, and the top five firms capture a clear majority, indicating both opportunity and supplier risk for large-volume buyers.
Aerospace Aircraft Stainless Steel Market
Why this report matters for 2026 corporate decisions
- Timing strategic sourcing: 2026 is the inflection point where regulatory cost signals (carbon pricing, tariffs) and raw-material volatility converge. Buyers who time hedging, pricing clauses and supplier contracts against these signals will materially reduce cost and delivery risk.
- Capital allocation: Our scenario-driven forecasts allow planners to align capital expenditures for alloy qualification, inventory buffering, and near-term vertical integration with realistic demand curves and margin sensitivity to nickel and ferroalloy input costs.
- Supplier selection and partnership strategy: With an industry structure where a handful of firms hold substantial share, the choice between dual-sourcing, strategic partnerships, or minority investments will determine access to advanced grades and stable capacity.
- Regulatory and carbon strategy: Firms exposed to EU and transatlantic supply chains must now internalize carbon border adjustments and tariffs into landed cost models and supplier scorecards.
Market trajectory and drivers
The market’s ~5.45% CAGR in the 2026–2032 window is driven by a mix of volume recovery in commercial aviation, upgraded military programs, increasing demand for special stainless grades in advanced propulsion and the steady replacement cycle for regional and business aircraft. At the same time, raw material dynamics introduce scope for periodic price shocks: nickel remains the dominant variable input in higher-performance austenitic alloys, accounting for a very large share of variable production cost. For North American buyers, observed stainless steel pricing reached roughly USD 3.15 per kilogram in March 2026—an important reference point for procurement negotiations and cost-plus supplier contracts.
Aerospace Aircraft Stainless Steel Market
Regulatory policy is an accelerant for strategic repositioning. The European Union’s Carbon Border Adjustment Mechanism (CBAM) entered its payment phase at the start of 2026, introducing explicit carbon-related import costs that change landed-cost calculations for imported stainless steel. Meanwhile, U.S. Section 232 tariffs on steel and aluminum remain at elevated levels, and China’s 2026 policy emphasis on high-tech sectors—including aerospace—strengthens the strategic case for suppliers and integrators anchored in Asian production ecosystems.
What the report contains — practical, decision-ready modules
- Market sizing and risk-adjusted forecasts by scenario (baseline, upside and downside), including sensitivity to nickel, chromium and ferroalloy price paths.
- Regulatory impact models quantifying CBAM and tariff scenarios on landed costs and supplier competitiveness across trade corridors.
- Supplier heatmaps and capability matrices covering metallurgical grades, qualification credentials, capacity readiness and aftermarket support—presented at company level (confidential subsegment tables reserved for subscribers).
- Cost-model templates for total cost of ownership (TCO) comparisons between stainless steel grades and competitive alloys, integrating scrap recovery and recycling streams.
- Supply-chain resilience toolkit: lead-time stress tests, inventory optimization algorithms for safety stock vs just-in-time strategies, and contract clause templates for price escalation, force majeure and carbon pass-throughs.
- M&A and partnership playbooks identifying value-priced assets, bolt-on capabilities, and strategic JV archetypes for access to high-performance grades and tube/assembly manufacturing.
- Implementation roadmaps tailored to OEMs, Tier 1s, MRO providers and aerospace distributors—each with 12- to 36-month milestones and KPIs.
Competitive landscape — who matters and why
Our competitive analysis focuses on a mix of global producers, specialty mills and high-service distributors that together form the market’s backbone. The market’s mid-level concentration means that both scale and specialized metallurgical capability matter.
- Outokumpu (Helsinki, Finland) — A global stainless specialist with a strong portfolio of corrosion- and high-temperature grades. Outokumpu’s strengths are in material R&D and consistent quality for regulated aerospace specifications. Strategic implication: ideal partner for OEMs seeking advanced-grade continuity and long-term alloy roadmaps.
- Service Steel Aerospace (Fife, WA, USA) — A large aerospace-oriented distributor with recent capacity expansion in North America. The company’s investment in distribution footprint increases near-term availability and short-lead replenishment capability. Strategic implication: primary choice for procurement teams prioritizing delivery agility during ramp phases.
- Universal Stainless (Bridgeville, PA, USA) — Focused on specialty stainless and nickel alloys for structural and engine parts. Their metallurgical know-how is an asset where qualification cycles are long and performance margins are tight. Strategic implication: consider as a co-development partner for alloys needing OEM qualification.
- Carpenter Technology (Reading, PA, USA) — Supplier of high-performance specialty alloys with strong aerospace credentials. Carpenter’s offering is particularly relevant for high-stress engine components and exotic alloy requirements. Strategic implication: prioritize for mission-critical, high-margin subassemblies.
- BUTTING (Knesebeck, Germany) — Tubular products and ready-to-install assemblies; strength in precision manufacturing and tube-to-assembly integration. Strategic implication: attractive for programs seeking reduced supplier count via turnkey supply of assemblies.
- Continental Steel & Tube Co. (Fort Lauderdale, FL, USA) and Future Metals (Tamarac, FL, USA) — High-service distributors offering fast-turn products and small-batch flexibility. Strategic implication: strong tactical partners for MRO and aftermarket demand spikes.
Recent market developments underscore the competitive momentum: expanded distribution capacity in North America (Service Steel’s facility growth), trade-show activity showcasing new stainless offerings, and new advanced manufacturing centers coming online. These moves indicate supplier focus on capacity, qualification services and customer proximity.
Strategic implications for 2026 decision-makers
- Embed carbon and tariff scenarios into procurement price floors. With CBAM now active and U.S. tariffs persistent, landed-cost modeling must move beyond raw-material spot indices to include carbon and policy premiums.
- Act on nickel exposure. Because nickel accounts for a dominant share of variable cost in high-performance alloys, buyers should implement indexed contracts, multi-source strategies and alloy-substitution pilots where feasible.
- Qualify alternative grades deliberately. Controlled pilots of ferritic and duplex families can yield cost and carbon advantages for non-critical applications—accelerate qualification timelines where technical fit allows.
- Balance inventory vs agility. Use our stress-test outputs to decide whether to increase safety stock at strategic nodes or to fund supplier capacity expansions for guaranteed allocation.
- Invest in supplier co-development. For flight-critical programs, early-stage partnerships with specialty mills or distributors that offer metallurgical support reduce qualification lead times and downstream change orders.
- Consider M&A and JV options selectively. Target assets that add unique metallurgy, tube/assembly capabilities, or geographic proximity to critical production hubs—these bring outsized risk mitigation value.
Actionable 90-day checklist
- Run a quick TCO re-calculation for top five bill-of-material items using our cost-model template.
- Audit supplier contracts for CBAM and tariff exposure clauses; negotiate transitional carbon-sharing terms for 2026 deliveries.
- Identify two pilot parts for grade substitution and initiate metallurgical testing windows.
- Open conversation with one upstream mill and one distributor to secure allocation for the next 12–18 months.
About PW Consulting’s analysis and next steps
PW Consulting’s Aerospace Aircraft Stainless Steel Market report combines primary interviews, supplier audits, proprietary cost models and scenario-based forecasting to produce a pragmatic toolkit for executive decision-making. The report provides both the analytical rigor senior leaders require and the operational templates procurement and engineering teams need to act quickly.
To preserve the competitive value of the full dataset and keep this brief a strategic “trailer,” we have intentionally withheld granular regional, type and application-level segmentation tables in this public summary. Subscribers receive the full annexes: supplier-level heatmaps, grade-by-application demand models, and downloadable cost-model spreadsheets to run your own sensitivity tests.
For immediate access to the full report, bespoke briefings, or to commission a customized supplier due-diligence study aligned with your 2026 program schedules, contact PW Consulting’s Aerospace Practice. Our team will prioritize executive briefings and rapid-turn implementation playbooks tailored to your operating model.
For detailed analysis of this topic, please visit the official page: Aerospace Aircraft Stainless Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Open Hole Packers Market Surges to USD 1,051.23 Million in 2025
By PW Consulting, 2026-07-13
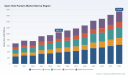
Open Hole Packers Market: Strategic Imperatives for 2026 — PW Consulting Insight
As energy companies and completion vendors position for a volatile 2026, PW Consulting’s new Open Hole Packers Market report delivers the strategic intelligence required to convert uncertainty into competitive advantage. The market for open hole packers — measured in USD Million — has shown resilient expansion through the first half of this decade, rising from roughly USD 682 million in 2020 to an estimated USD 1,051 million in 2025. PW Consulting forecasts continued growth through 2032, with the market expected to reach approximately USD 1,745 million by 2032 and to expand at a compound annual growth rate (CAGR) of 7.52% across the 2026–2032 forecast window. These headline figures provide a context for decision-makers; the report itself translates that growth into operational levers, competitive plays, and procurement strategies tailored to the 2026 planning horizon.
Open Hole Packers Market
Why this report matters for decisions in 2026
-
Immediate budget cycles and multi-year capex plans hinge on realistic demand scenarios. Our 2026-oriented analysis connects macro growth trajectories to actionable scenarios operators and vendors can deploy in annual planning.
Open Hole Packers Market -
Raw-material and trade-policy shocks are already shifting supplier economics. With documented tariff action and input-cost inflation affecting OCTG and downhole tool supply chains, the cost side of completion programs cannot be treated as static.
Open Hole Packers Market -
Technological inflection points — from novel cementitious swell packers to multi-stage open-hole systems for geothermal wells — are creating new product lifecycles and adjacent market opportunities. If you are allocating R&D and commercialization budgets in 2026, the timing, scale, and partner choice matter.
What the PW Consulting report delivers — practical, transaction-ready content
-
Actionable procurement playbooks: supplier selection matrices, negotiation levers tied to material-cost indices, and contract structures optimized for tariff and price volatility.
-
CapEx/Opex models: forward-looking unit-cost models that translate steel and elastomer price scenarios into completion cost per lateral/metre, enabling rapid “what‑if” evaluations for project approval committees.
-
Supply-chain resilience analysis: node-level risk mapping for OCTG and packer manufacturing, inventory optimization guidance, and recommended nearshoring strategies to blunt tariff exposure.
-
Technology adoption roadmaps: staged criteria and KPIs for piloting cementitious swell systems, compression-packers, and geothermal open-hole packers, including suggested field-test protocols and success thresholds.
-
Competitor intelligence and commercial playbooks: profiles of incumbents, threat/opportunity matrices for new entrants, and M&A/partnership scenarios calibrated to market concentration dynamics.
-
Regulatory and commodity sensitivity scenarios: modeled outcomes showing how steel‑price moves and tariff regimes change supplier margins, customer TCOs, and break-even prices for new completion techniques.
Market dynamics and near-term risks that will shape 2026 outcomes
-
Policy and input-cost volatility. Recent tariff measures and higher hot-rolled coil prices are transmitting directly into packer production costs and OCTG spend. Our analysis shows these shifts materially change supplier cost curves and can compress margins if not mitigated through hedging or localized sourcing.
-
Consolidation and competitive concentration. The market displays a notable degree of concentration at the top: leading firms capture a majority share of commercial activity, creating both barriers for new entrants and opportunity for mid‑market vendors to specialize on niche completions and service models.
-
Demand diversification beyond hydrocarbons. Geothermal, well-intervention, and remediation use-cases are emerging as credible demand-smoothing options. Early technical pilots suggest a multi-year window for scale-up — an opportunity set for OEMs and service companies ready to adapt packer designs and testing regimes.
Competitive landscape: how incumbents are positioned and what it means for 2026 strategy
-
Baker Hughes, Halliburton, SLB (Schlumberger), Weatherford and NOV remain full‑service competitors with deep field capability, global service networks, and broad product portfolios spanning mechanical, swellable and expandable steel solutions. Their scale provides execution advantage on large, integrated completion programs but also exposes them to material‑cost pressure and the need to drive efficiency across global supply chains.
-
Specialists and agile innovators — firms such as Packers Plus, Peak Completions, D&L Oil Tools, TAM International, and Frontier Oil Tools — are carving positions focused on multi-stage completions, hydraulic-set mechanisms, and niche performance features. These players can move faster on customization and pilot programs, an advantage for operators testing newer packer technologies or unconventional completions.
-
Smaller OEMs (e.g., Aventus Oil Tools, Tartan Completions) can exploit a ‘best‑of‑breed’ strategy: partner with larger service providers on system integration while capturing premium on specialized applications like multizone stimulation. The competitive dynamic favors collaboration in 2026 — suppliers able to offer integrated product-service bundles with clear performance guarantees will win large programs.
-
For buyers, a dual sourcing strategy that blends scale suppliers for baseline programs and niche vendors for innovation pilots reduces project risk and controls costs. For suppliers, the strategic choice is whether to invest in scale (factory modernization, vertical integration of raw materials) or in modular, high‑margin innovation.
Technology and innovation signals to watch
-
Cementitious swell packers: The recent industry presentation on cementitious swell packer concepts signals potential for a new family of solutions that combine cement chemistry and swelling behavior to improve long-term integrity. Early-stage adoption will require standardized test protocols and reliability data before widescale field deployment.
-
Precision mechanical/compression packers: Laboratory optimization work on high-performance compression packers (sized for common wellbore diameters) points to higher-pressure, repeatable sealing across variable lithologies — a near-term upgrade path for operations seeking reliability without extensive change to completion workflows.
-
Geothermal-ready open-hole systems: Development programs for multi-stage open-hole packers tailored to geothermal energy are underway; these efforts could unlock a substantial new market vector in the medium term and should be part of strategic roadmaps for suppliers and investors.
Strategic recommendations for 2026 planning
-
Operators: Adopt a two-track procurement strategy. Use large‑scale suppliers for proven, low‑variance completions while allocating a defined budget and KPIs for pilot testing of emergent packer technologies. Incorporate material-price escalation clauses and a regular review cadence tied to commodity indices.
-
OEMs and service providers: Prioritize modular product platforms that allow late-stage configuration for specific formations or regulatory regimes. Invest selectively in localized production or strategic partnerships to mitigate tariff exposure and shorten lead times.
-
Investors and portfolio managers: Evaluate suppliers on three dimensions — technology differentiation, supply-chain resilience, and commercial agility. Platforms offering integrated service models with validated pilots are likely to compound value as operators shift to multi‑stage and geothermal programs.
-
R&D leaders: Fast-track reliability testing for cementitious and compression-packers and publish field-validated performance metrics. Transparent, third-party-verified test results will accelerate operator confidence and shorten commercialization cycles.
How to use this report in boardroom and field programs
-
In boardroom debates, use the report’s scenario outputs to stress-test multi-year capex and to quantify the impact of material-cost and tariff shocks on margin and break-even points.
-
In procurement and operations, adopt the report’s supplier selection framework and unit-cost models when finalizing 2026 contracts and pilot schedules to ensure alignment between financial targets and field-level deliverables.
-
For R&D and business development, use the technology adoption roadmaps and test protocols to design de‑risked market-entry pilots with clear go/no-go criteria for 2026.
PW Consulting’s Open Hole Packers Market report is designed as a decision-support tool for 2026. It pairs market-scale context (USD Million metrics and a 7.52% CAGR for the forecast period) with operational playbooks, supplier intelligence, and actionable scenario modeling. To access the full dataset, proprietary segmentation, supplier scorecards, and step‑by‑step implementation templates that enable immediate use in planning cycles, visit PW Consulting’s briefing page and download the complete report.
For detailed analysis of this topic, please visit the official page: Open Hole Packers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Building Dedicated Outdoor Air System Market valued at USD 5,214.5 Million in 2025, poised for 7.85% CAGR to USD 8,856.75 Million by 2032
By PW Consulting, 2026-07-13
Building Dedicated Outdoor Air System Market: Strategic Outlook for 2026 — PW Consulting Preview
As organizations accelerate decarbonization, electrification, and healthier indoor environments, Dedicated Outdoor Air Systems (DOAS) are moving from niche to mainstream across commercial, industrial, and multi-family building portfolios. PW Consulting’s latest market study — base year 2025, forecasting 2026–2032 — quantifies this transition and translates it into actionable strategy for business leaders preparing decisions in 2026. This release is a preview: we present the high‑level trajectory, regulatory inflection points, competitive dynamics, and the practical decision frameworks contained in the full report. Detailed segmented tables and proprietary modeling are intentionally withheld to guide readers to the full report.
Building Dedicated Outdoor Air System Market
Market Trajectory: Growth, Momentum and What It Means for 2026
Our analysis shows the global DOAS market as a high-growth industrial vertical anchored by building electrification trends, stricter ventilation standards, and heightened interest in humidity control as part of indoor air quality (IAQ). Measured on a USD revenue basis, the market reached a definitive inflection in the mid‑2020s and, with a compound annual growth rate (CAGR) of 7.85% across the forecast window, is projected to expand markedly through 2032.
Building Dedicated Outdoor Air System Market
For executive planning in 2026, three takeaways emerge from the top‑line trajectory:
Building Dedicated Outdoor Air System Market
- Scale matters: growing absolute market size creates opportunities for modular product portfolios, aftermarket services, and retrofit business models that can capture higher lifetime value.
- Timing matters: early movers that align product roadmaps to 2025–2026 regulatory thresholds and electrification trends can preempt competitors and lock in preferred channel relationships.
- Unit economics matter: manufacturers and systems integrators must balance capital intensity with predictable service revenues; the expanding installed base amplifies the value of remote monitoring, spare‑parts strategies, and performance guarantees.
Regulatory and Standards Environment — a 2026 Decision Driver
One of the most consequential market accelerants is regulation. Important energy‑efficiency requirements for Direct Expansion DOAS units entered into force in 2025, aligning performance assessment to established AHRI testing metrics. This regulatory baseline is already reshaping product development priorities, procurement specifications, and compliance roadmaps worldwide.
- Compliance is now table stakes for procurement: product families that do not demonstrate compliance with the new testing and efficiency protocols face near-term exclusion from many commercial tenders.
- Policy elevates differentiation: advanced humidity‑management, energy recovery, and heat‑pump electrification options are becoming commercial differentiators rather than boutique features.
- Supply‑chain sensitivity: materials and component standards (for example, copper for refrigerant and coil applications) link capital budgets to commodity volatility and supplier risk management.
Competitive Landscape: Who’s Positioned and Where Opportunity Lies
The DOAS market exhibits moderate concentration. The top three firms account for a meaningful, but not dominant, share of the global market, and the top five similarly reflect a competitive mid‑tier structure. This dynamic supports both partnership plays and focused differentiation strategies.
Key supplier archetypes and strategic considerations identified in the report:
- Large OEMs with broad portfolios — exemplified by global HVAC conglomerates — leverage scale and channel reach to embed DOAS into full‑building offers, prioritizing compliance, large‑project credentials, and aftermarket service networks.
- Specialist manufacturers focus on high‑performance, configurable DOAS units and dehumidification expertise that serve pharmaceutical, data center adjacent, and high‑humidity industrial use cases.
- Regional and custom builders emphasize retrofit integration, modular offerings, and close collaboration with design‑build contractors to win projects where site constraints dominate.
Prominent industry players included in our competitive assessment include established OEMs offering packaged rooftop DOAS solutions, firms specializing in high‑precision dehumidification and DX‑DOAS configurations, and providers expanding electrified heat‑pump options. Notable recent developments that shape supplier positioning include a significant product expansion by a major rooftop DOAS manufacturer in mid‑2025 and the early 2026 extension of air‑source heat pump options on pre‑engineered lines — moves that accelerate electrification pathways and broaden application fit. These tactical shifts are discussed in the report alongside strategic scenarios for incumbents and challengers.
Practical, Tactical Intelligence in the Full Report
PW Consulting’s market study is built for decision‑makers who need operational playbooks, not just high‑level summaries. The full report contains:
- Decision frameworks for product strategy and portfolio prioritization (new product vs. retrofit vs. modular systems).
- Go‑to‑market playbooks for OEMs and channel partners, including tender specification guidance and warranty/service models optimized for recurring revenue.
- Regulatory compliance roadmaps, mapping testing standards and certification timelines to procurement windows and government incentives.
- Procurement and cost modeling templates to evaluate lifecycle cost, payback, and total cost of ownership thresholds across electrified and hybrid ventilation strategies.
- Scenario analyses (sensitivity to energy costs, copper price volatility, refrigerant availability) and their impact on margin and product sourcing strategies.
- Operational checklists and retrofit decision matrices for MEP engineers and facility operators to accelerate specification, installation, and commissioning cycles.
- Supplier profiles, competitive benchmarking, and a curated set of case studies demonstrating real‑world outcomes across commercial and industrial installations.
Strategic Actions for 2026: What Leaders Should Do Now
For manufacturing leaders, systems integrators, investors, and corporate facility operators, the report translates market intelligence into prioritized near‑term actions for 2026:
- Manufacturers: align R&D roadmaps to regulatory metrics, accelerate electrified DOAS variants, and structure modular platforms that reduce time‑to‑spec for architects and engineers.
- Channel partners/EPCs: develop retrofit bundles that combine DOAS with control upgrades and service agreements to capture higher maintenance margins and recurring data streams.
- Owners/Operators: deploy a prioritized retrofit pipeline that targets high‑impact assets first (where IAQ and humidity are measurable performance risks), leveraging available efficiency incentives and performance contracting.
- Private equity and strategic investors: evaluate consolidation opportunities among specialized DOAS technology providers to aggregate IP and aftermarket capabilities while de‑risking commodity exposure via multi‑sourcing strategies.
Why this Research Is a Strategic Asset for 2026 Decisions
2026 represents a strategic inflection point: the market is large enough to support multiple business models, standards have tightened, and electrification is materially influencing product architectures. PW Consulting’s study equips decision‑makers with:
- Quantified growth expectations and scenario‑based downside/upside analyses tied to regulatory and commodity sensitivities;
- Actionable playbooks that convert technology trends into revenue and margin levers; and
- Competitive intelligence that highlights where to compete, partner, or consolidate.
We emphasize that while this preview describes the structural forces and executive implications, the detailed segmented forecasts, regional and application level breakdowns, and company market shares are available only in the full report. Those granular data sets and proprietary models are the foundation for precise prioritization, procurement bid‑preparation, and investment underwriting.
Next Steps and How to Access the Full Intelligence
Executives preparing 2026 budgets and strategy briefs should treat this preview as a call to action: regulatory compliance, electrification, and product modularity will determine winners in the next 18–36 months. PW Consulting can provide bespoke briefings, model adaptations for your portfolio, and white‑glove market scans tailored to acquisition and product development decisions.
For access to comprehensive segmentation, detailed supplier benchmarking, pricing indices, and the decision support tools referenced above, please consult the full Building Dedicated Outdoor Air System Market report on our website or contact our advisory team for a customized executive briefing.
PW Consulting — translating market data into defensible strategy for the era of electrified ventilation and resilient indoor environments.
For detailed analysis of this topic, please visit the official page: Building Dedicated Outdoor Air System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wind Turbine Gearbox and Direct Drive Market Set to Grow at 5.85% CAGR Through 2032, Cementing Asia‑Pacific Leadership
By PW Consulting, 2026-07-13
Wind Turbine Gearbox and Direct Drive System Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest industry study on the Wind Turbine Gearbox and Direct Drive System market (base year 2025; historical coverage 2020–2025; forecast 2026–2032) equips executives with the evidence-backed perspective they need to steer capital, manufacturing, and product-strategy decisions in 2026. The global market reached approximately USD 32.9 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of roughly 5.85% through our 2026–2032 forecast window, reaching close to USD 49.3 billion by 2032. This trajectory reflects a maturing yet dynamically shifting powertrain market driven by scale-up in turbine ratings, regional policy interventions, component-level supply risks, and rapid innovation from both established OEMs and new challengers.
Wind Turbine Gearbox And Direct Drive System Market
Why this preview matters for 2026 planning
-
Timing investments: With predictable mid-single-digit CAGR and step changes in turbine size and powertrain architectures, 2026 is a pivotal year for committing to capacity expansion or technology pivots. Late entrants will face higher barriers from incumbent scale and integrated service networks.
Wind Turbine Gearbox And Direct Drive System Market -
Cost-to-revenue sensitivity: Small changes in commodity or tariff costs materially alter project economics for both gearbox-centric and direct-drive platforms. Procurement strategies and hedging approaches adopted in 2026 will determine margin resilience across the business cycle.
Wind Turbine Gearbox And Direct Drive System Market -
M&A and partnership windows: The market exhibits meaningful concentration among top suppliers (CR3 ≈ 52.3%; CR5 ≈ 68.4%), creating opportunities for bolt-on acquisitions or strategic alliances for mid-tier players seeking rapid capability acquisition.
Core market trajectory and macro drivers
Our analysis shows two concurrent forces shaping the market through 2032. First, aggregate demand expands steadily—supported by ongoing onshore repowering, nascent floating offshore projects, and electrification-driven policy pushes. Second, technology composition is changing: gearbox-based drivetrains remain central for many turbine classes, while direct drive architectures (including permanent magnet direct drive and other gearless concepts) increase their share where lifecycle reliability and reduced maintenance justify higher upfront procurement and material exposure.
Key macro drivers we model explicitly in the report include: project-level levelized cost of energy (LCOE) trajectories by drivetrain architecture, expected learning curves for direct-drive manufacturing, raw material price paths (critical for permanent magnet systems), and regional policy shocks such as trade interventions. We translate these drivers into scenario outputs that quantify the sensitivity of OEM margins, supplier EBITDA, and investor IRR to plausible 2026–2028 shocks.
Technology dynamics: gearbox vs. direct drive — strategic implications
-
Operational trade-offs: Gearboxes continue to benefit from a long supply chain, broad multi-brand service ecosystems, and modular upgrades that reduce lifecycle disruption. Direct drive gains traction where uptime and reduced O&M can offset material intensity and supply concentration of magnets.
-
Scale and test capability: New factory test rigs and larger validation facilities introduced in 2025–2026 materially lower technical risk for high-MW powertrains. Firms that invest early in end-to-end validation (component through full nacelle) will shorten time-to-market for next-generation machines.
-
Materials and circularity: The report models rare-earth exposure for PMDD systems and quantifies the potential cost impact of constrained neodymium/dysprosium supply, including upside scenarios where recycling and alternative magnet chemistries reduce vulnerability.
Competitive landscape — who matters and why
Our competitor analysis synthesizes public disclosures, recent product launches, test-facility investments, and home-market strategies to classify supplier roles and strategic postures. A handful of legacy drivetrain specialists and integrated turbine OEMs are shaping industry direction, with different plays on product modularity, torque density, and service coverage.
-
ZF Friedrichshafen AG — Operating with a modular gearbox platform that targets broad MW classes, ZF’s emphasis on torque density and reliability positions it well across onshore and offshore segments. Recent investments in test infrastructure underline a commitment to full-system validation.
-
Winergy Group (Flender) — With new high-torque-density gearbox concepts launched in 2025, the company is signaling an intent to compete on power-to-weight efficiency and serviceability for next-generation turbines.
-
Moventas — Niche specialization in service and high-reliability geared systems makes Moventas a go-to partner for operators prioritizing lifecycle uptime and refurbishment paths.
-
Chinese drivetrain and OEM players (including NGC Transmission, Chongqing Gearbox, Goldwind, Mingyang) — These companies combine domestic scale advantages with rapid product iterations; some have introduced very large direct-drive platforms and long-life designs for offshore markets.
-
ENERCON, Siemens Gamesa, GE Vernova — These larger OEMs continue to hedge across drivetrain architectures, offering both geared and gearless options while leveraging vertical integration and after-sales service to protect margin.
-
Smaller and regionally focused manufacturers — They remain important incumbents for localized projects and as acquisition targets for companies seeking manufacturing footprint or service network expansion.
Recent product and facility developments through 2025 (for example, new high-torque gearbox concepts, ultra-series long-life direct-drive models, and the commissioning of advanced test rigs) materially influence the technology risk curves we use. Our report contains supplier scorecards, technology readiness assessments, and service network mapping to help buyers and investors prioritize counterparty selection without relying solely on headline claims.
Supply chain, regulation and risk vectors
-
Trade policy shocks: Recent tariff actions and national security inquiries into turbine imports create near-term uncertainty on landed costs and component sourcing strategies. The report models tariff pass-through scenarios and their effect on procurement decisions in 2026.
-
Raw-material concentration: Dependence on rare earths for PMDD systems generates asymmetric supply risk. We examine mitigation strategies—dual sourcing, strategic inventory, recycling programs and alternative magnet chemistries—and quantify their cost and schedule impact.
-
Steel and commodity pricing: Expanded trade measures covering steel and aluminum components increase up-front cost volatility for drivetrain manufacturers. Our sensitivity matrices enable CFOs to stress-test CapEx plans against tariff escalations.
-
Service footprint and total cost of ownership: In many jurisdictions, the economic advantage of a drivetrain solution is determined less by nacelle price and more by predictable service costs and logistics complexity. The report includes multi-year TCO comparators that isolate those differences by architecture and geography.
What the PW Consulting report contains — operational tools (high level)
To support 2026 decision-making we deliver a package of practitioner-focused assets designed to convert insight into action while preserving confidentiality of proprietary sub-segmentation data:
-
Scenario models (fast, base, conservative) that map technology mix, tariff outcomes, and commodity trajectories to market demand and supplier margins.
-
Supplier scorecards and risk heatmaps evaluating manufacturing footprint, validation capability, service network, and IP strengths.
-
TCO and LCOE templates that let users input project-specific assumptions to compare gearbox vs. direct-drive economics over realistic operational horizons.
-
Commercial playbooks for OEMs and suppliers covering go-to-market options: vertical integration, licensing, strategic alliances, and target criteria for M&A.
-
Regulatory impact briefs and scenario-specific procurement checklists tailored to 2026 policy environments.
Practical recommendations for 2026
-
For OEMs: Prioritize validation capacity and service-network expansion. Early investments in full-power test rigs and digital condition monitoring will reduce perceived risk and accelerate adoption of higher-capacity drivetrains.
-
For drivetrain suppliers: Differentiate through modularity and retrofitability. Offer clear upgrade paths to capture repowering opportunities and multi-brand service contracts.
-
For investors and PE: Target mid-tier suppliers with strong service businesses and regional manufacturing footprints as consolidation candidates—CR metrics indicate a concentrated upper tier but meaningful value in specialty players.
-
For project developers and asset owners: Use scenario-based procurement with explicit tariff and material volatility assumptions and secure contractual protections (price collars, indexation) where feasible.
-
For policy-makers: Encourage diversification of critical material supply and recycling incentives to reduce system-level vulnerability while fostering domestic manufacturing to capture up- and downstream value.
Conclusion — the strategic edge PW Consulting offers
Decision-makers entering 2026 face a market that is expanding in aggregate size while undergoing structural shifts in technology, supply chain complexity, and regulatory exposure. PW Consulting’s Wind Turbine Gearbox and Direct Drive System market study marries quantitative forward projections with qualitative supplier intelligence and executable planning tools so leaders can translate uncertainty into competitive advantage. Our report reveals where to push for scale, where to hedge, and where to partner—without disclosing the proprietary sub-segmentation outputs that form the basis of those recommendations.
Next steps
To access the complete dataset, supplier breakdowns, and downloadable decision-support models referenced in this briefing, please visit the PW Consulting report page or contact our industry leads to request an executive briefing and tailored scenario run for your portfolio.
For detailed analysis of this topic, please visit the official page: Wind Turbine Gearbox And Direct Drive System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Interior & Exterior Trim Market Forecast to Expand at 4.7% CAGR from 2026 to 2032
By PW Consulting, 2026-07-13
Automotive Interior & Exterior Trim Market 2026: Strategic Imperatives for OEMs and Tier-1s
As the automotive supply chain enters a decisive phase in 2026, the interior and exterior trim market is shaping up as a strategic battleground for supplier selection, material innovation, and localization of production. PW Consulting’s latest market research — with 2025 as the base year and a 2026–2032 forecast horizon — shows a resilient industry trajectory, underpinned by a steady compound annual growth rate (CAGR) of 4.7%. The global market size in 2025 stood at approximately 43,590 Million USD and, under our base-case forecast, is set to expand meaningfully through 2032. For corporate leaders preparing budgets, M&A strategies, product roadmaps, and sourcing contracts this year, the intelligence in this report is engineered to convert macro visibility into implementable actions.
Automotive Interior Exterior Trim Market
Why 2026 is a Pivotal Year
-
Material cost volatility and regulatory shifts are compressing decision windows. Early-2026 feedstock price spikes—especially in polypropylene—have injected cost uncertainty into dashboards, door panels and exterior moldings. Suppliers and OEM commodity strategists must reconcile short-term margin pressures with longer-term material substitution and circularity mandates.
Automotive Interior Exterior Trim Market -
Policy clarity in key markets is moving from proposal to enforcement. Revised end-of-life vehicle (ELV) rules in Europe, which settle recycled plastic content targets at a defined level for new-vehicle programs, are already changing supplier material roadmaps and OEM specifications.
Automotive Interior Exterior Trim Market -
Competitive dynamics are accelerating consolidation and specialization. Recent transactions and corporate moves show private equity and strategic buyers reshaping the supplier landscape, while awards and design showcases demonstrate winners gaining program momentum.
What the Report Delivers (Practical, Executable Intelligence)
PW Consulting’s report is structured to support corporate decision-making across sourcing, engineering, product, and corporate strategy functions. Key deliverables include:
-
Market sizing and multi-scenario forecasts (2026–2032) calibrated to commodity scenarios and regulatory stress-tests — enabling CFOs to stress-test 3–5 year caps and working capital plans.
-
Supply-chain heatmaps and node-level risk assessments that identify single points of failure in tooling, resin supply, and localized assembly — designed for procurement and operations teams to prioritize dual-sourcing and buffer strategies.
-
Material transition playbooks outlining technical, cost, and timing implications of switching to higher recycled-content thermoplastics, bio-based polymers, and engineered hybrid laminates.
-
Supplier scorecards and integration checklists that benchmark technical capabilities, sustainability credentials, manufacturing footprint, and program delivery performance — ready-to-use templates that accelerate supplier selection and negotiation.
-
Technology adoption timelines for smart surfaces, integrated cockpits, and lightweight hybrid structures, paired with IP landscape maps and supplier capability corridors for co-development or licensing strategies.
-
Deal and capital allocation playbooks, including valuation sensitivities for M&A targets and carve-outs (useful given recent portfolio transactions in the interiors space).
Structural Outlook: Fragmentation, Scale and the CR Picture
The market remains neither purely fragmented nor tightly consolidated. Our concentration analysis shows that the three largest players control a material but non-dominant share of the market, while the five largest increase that share further—illustrating a competitive ecosystem where scale matters but specialization and regional capabilities preserve opportunities for mid-sized suppliers. For OEMs, this means supplier strategies must balance global platform standardization with regional-level agility.
Competitive Landscape: Strategic Profiles & Implications
Leading Tier-1s and specialist suppliers are pursuing differentiated paths—some doubling down on full-systems integration, others on material science or premium craftsmanship. Highlights and implications:
-
Magna International continues to position itself as a full-vehicle solution provider with strengths in exterior systems and integrated interior modules. Its breadth makes Magna an attractive partner for OEMs seeking program simplification and systems-level responsibility.
-
Grupo Antolin is reinforcing its position in interior architecture and ornamental surfaces; its recent financial performance and order intake momentum underline the value of deep OEM relationships and focused product leadership.
-
Yanfeng Automotive Interiors remains notable for scale and cockpit-level integration, especially across emerging-market platforms — a critical capability for OEMs balancing cost and feature density in global programs.
-
Toyota Boshoku illustrates the strategic advantage of OEM-affiliated suppliers: tight program alignment with manufacturing partners, and the ability to pilot sustainability projects (e.g., facility-level solar installations) that reduce Scope 2 exposure for trim production.
-
Lear and Adient demonstrate how seat systems and surface expertise remain central to interior differentiation. Recognition in OEM supplier awards signals program-level trust and can translate quickly into content wins.
-
Toyoda Gosei , Continental , DRÄXLMAIER , and IAC Group each occupy niches—from decorative and functional exterior trim to luxury interior assemblies—where design cachet, lightweighting, and integration of electronics determine win-rates.
These strategic profiles map to practical choices: partners for modular cockpit outsourcing, suppliers to accelerate recycled-material uptake, and specialists for premium or electrified architectures.
Recent Market Movements You Cannot Ignore
-
Strategic transactions are reshaping supplier portfolios and opening roll-up opportunities for private equity. A recent carve-out of a major interiors business highlights how investors see value in standalone interior platforms and the opportunity to consolidate.
-
Award wins and program recognitions (for example, major OEM supplier awards received by seating and E-Systems suppliers) can presage program volume increases — worth monitoring for tiering and capacity planning.
-
Material cost shockwaves—such as the early-2026 rises in polypropylene contract prices—are forcing immediate tactical responses: renegotiated supplier clauses, transient specification changes, and accelerated trials for alternative resins.
-
Regulatory movement on recycled content, notably in Europe’s ELV updates, is already prompting suppliers to redesign material bills of materials and push for certified supply streams for recycled polymers.
Top Strategic Recommendations for 2026 Decision-Makers
-
Hedge smarter, not just sooner: Treat resin volatility as a structural risk for 2026 program economics. Implement layered hedging—combining index-linked contracts, qualifying alternative materials, and short-cycle dual-sourcing—to reduce margin exposure without jeopardizing quality.
-
Prioritize regulatory-driven material transitions: Incorporate mandated recycled-content thresholds into 2026 platform specifications now. Early supplier co-development reduces certification bottlenecks and avoids last-minute redesign costs.
-
Rationalize supplier architecture by value pool: Use program-level value capture analyses to decide when to consolidate with full-systems suppliers (to reduce integration cost) versus when to retain multiple specialized suppliers (to protect innovation and design variety).
-
Invest in localized tooling and assembly near key demand centers: Shorten lead times and currency/transport risk by shifting high-variation or high-weight content closer to final assembly, especially for higher-trim or premium derivatives.
-
Accelerate partnerships for smart and sustainable surfaces: Digital surfaces, haptic materials, and certified recycled polymers are competitive differentiators. Create joint IP roadmaps with capable tier-1s to capture first-mover advantages on EV and premium interiors.
-
Prepare M&A and JV playbooks: Given ongoing portfolio trades and private-equity interest in interiors, maintain ready-to-execute frameworks for bolt-on acquisitions, minority investments, or carve-outs to secure capability gaps.
How PW Consulting’s Report Accelerates 2026 Execution
For executives needing a rapid path from insight to action, the report provides executable templates, prioritized opportunity maps, and supplier negotiation levers tied to quantified P&L and capex impacts under multiple raw-material and regulatory scenarios. It is built to be used in Q1–Q2 2026 planning cycles: procurement negotiation decks, engineering trade-off matrices, and integration checklists are all included as downloadable annexes. Importantly, the report is designed to be complementary to client-specific supplier audits and can be customized for program-level diligence.
Conclusion — Where to Focus in 2026
2026 will separate organizations that reacted tactically from those that reconfigured strategically. In a market growing at a mid-single-digit CAGR and undergoing simultaneous pressure from feedstock volatility and regulatory clarity, success will go to companies that combine disciplined commodity management, early compliance-driven redesigns, and targeted partnership strategies with suppliers that can scale sustainably. PW Consulting’s Automotive Interior & Exterior Trim market research translates these macro realities into actionable, program-level guidance that procurement, product, and corporate development teams can deploy immediately.
Next Steps
To access the full dataset, scenario models, and supplier scorecards referenced in this briefing — including the proprietary playbooks and downloadable templates — visit PW Consulting’s report page. The report preserves detailed subsegment figures and regional splits behind the paywall to ensure decision-makers obtain the granular inputs required for contractual and program-level commitments.
For detailed analysis of this topic, please visit the official page: Automotive Interior Exterior Trim Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oil Tank Sight Glasses Market to Expand at a 6.45% CAGR — 2025 Report Forecasts Strong Growth Through 2032
By PW Consulting, 2026-07-13
Oil Tank Sight Glasses Market — Strategic Outlook for 2026
PW Consulting’s latest market study on Oil Tank Sight Glasses provides a decisive, executive-grade briefing for leaders preparing capital, product and M&A decisions in 2026. Grounded in a meticulous historical reconstruction (2020–2025) and a multi-scenario forecast through 2032, the report quantifies a steady industry expansion—from an estimated USD 142.35 Million in 2020 to USD 215.0 Million in 2025—and projects continued growth at a compound annual growth rate (CAGR) of 6.45% across the 2026–2032 forecast window. Under our base scenario the market reaches roughly USD 225.41 Million in 2026 and climbs toward USD 332.99 Million by 2032.
Oil Tank Sight Glasses Market
Why this market matters to corporate decision-makers in 2026
- Predictable, capital-light growth: The mid-single-digit CAGR signals an industry with steady replacement and retrofit demand rather than boom-and-bust cycles—ideal for strategic investments in product differentiation, aftermarket services and selective capacity increases.
- Consolidation and partnership opportunity: Market concentration metrics show meaningful room for scale plays. The three- and five-firm concentration ratios indicate that leading vendors capture a material share of value, but a fragmented mid-market still exists—creating an attractive environment for bolt-on acquisitions and strategic alliances.
- Regulatory and standards-driven purchasing: Specification references such as API and DIN standards drive procurement behavior in upstream and process sectors. Compliance and certification matter more than ever when buyers evaluate suppliers.
- Material and systems innovation: Advances in glass chemistry and high-performance polymers, and the integration of condition monitoring, are reshaping product roadmaps and aftermarket propositions.
Key trends shaping the market
- Standards and safety as demand multipliers: API 610’s guidance and DIN norms for sight glass discs mean that equipment replacement cycles are often triggered by regulatory audits and reliability programs—creating predictable windows of opportunity for compliant suppliers.
- Materials evolution: Borosilicate glass remains the industrial reference for thermal and chemical resistance, while technopolymers and engineered copolyesters are expanding use cases where impact resistance and weight reduction matter. Suppliers that can offer certified material options across that spectrum win specification reviews.
- From component to service: Customer procurement is moving from one-off buys toward service-led models (inspection-as-a-service, spares-as-a-contract). This trend increases lifecycle revenues and raises total addressable serviceable market per installed asset.
- Digital augmentation: Condition-monitoring pods and electronic sensors—often paired with advanced sight-glass designs—are enabling predictive maintenance and creating cross-sell opportunities with OEMs and end-users.
What the PW Consulting report delivers (practical, decision-ready content)
- Proven market-sizing and forecast models (2020–2032) with transparent assumptions, sensitivity analyses and alternative scenarios to stress-test your business plan.
- Commercial playbooks for product managers and sales leaders: specification-mapping, tender response templates, and price-band benchmarks (confidential datasets reserved for report subscribers).
- Supplier and component risk assessment: lead-time analyses, single-source dependency mapping and mitigation checklists for procurement teams.
- Go-to-market strategies for OEMs vs aftermarket specialists, including channel economics and recommended distributor incentive structures.
- Regulatory impact matrix (API/DIN/ATEX) and a step-by-step compliance roadmap to accelerate approvals and shorten sales cycles.
- M&A and partnership evaluation toolkit: target scoring criteria, integration risk templates and quick financial screens to prioritize bolt-on acquisitions.
- Technology scouting and product roadmap recommendations that align materials engineering with digital monitoring capabilities.
Competitive landscape — practical implications for 2026
The market’s leading suppliers range from global industrial OEMs to specialist niche manufacturers. Our competitive analysis synthesizes public profiles, product focus and recent market activity to help you craft a defensible response—either as a supplier planning expansion or as a buyer rationalizing your vendor list.
Oil Tank Sight Glasses Market
- Alfa Laval (Lund, Sweden): Strengths lie in hygiene-focused sight glass solutions and deep channel access to food, beverage and biopharma sectors. Their emphasis on borosilicate-based inline and tank sight products means they are well-positioned where distortion-free clarity and regulatory pedigree matter. Strategic implication: if your exposure includes hygienic process markets, expect Alfa Laval to compete on certified performance and service uptime.
- Douglass (Nashville, USA): A specialist with focused capability in tank-level and flow observation for industrial fluids. Their depth in sight-glass equipment for oil and gas niches makes them a logical partner or acquisition target for companies seeking to strengthen direct field-installation competence.
- Luneta (USA): Notable for 3D oil sight glasses and condition-monitoring pods using high-clarity copolyesters. Their product set signals a clear move toward integrating mechanical sighting with digital condition monitoring—an area buyers will prize for predictive maintenance strategies.
- Elesa (Monza, Italy): Offers a broad materials portfolio (technopolymer, aluminum, brass, stainless steel) and temperature/ATEX-capable options for hydraulic and industrial systems. Elesa demonstrates how material and compliance breadth can be converted into specification wins in regulated environments.
- Des-Case (USA): Focused on visual oil analysis and BS&W bowl solutions; recent catalog updates underscore a continued play on contamination-detection and oil-quality monitoring—an area tightly coupled with API-driven maintenance regimes.
- Zight / United Glass LLC (USA) and GREATGLAS, Inc. (USA): Specialists in borosilicate tubular and circular gauge glasses; these firms are suppliers of engineered glass components for higher-pressure service. They form the critical upstream supply layer for many OEMs.
- PresSure Products Company (PPC) (USA): A full-range manufacturer of sight glasses and flow indicators, PPC competes on breadth and availability—an effective position for aftermarket and general industrial channels.
Strategic takeaway: leaders should anticipate selective consolidation and competitive bundling (hardware + monitoring services). Where scale matters—specifically in channels serving process and heavy industries—the market favors vendors that combine certified materials, reliable logistics and integrated service offerings.
Oil Tank Sight Glasses Market
Supply chain and materials considerations for 2026
- Borosilicate supply resilience: Given its dominant role for high-temperature and chemically aggressive applications, securing qualified borosilicate supply (and qualified fabricators) should be flagged as a strategic procurement priority.
- Alternate material qualification: Where weight, impact resistance or speed-to-market matter, technopolymers and engineered copolyesters provide viable alternatives—but they require validated endurance testing and, in some cases, additional certification to be accepted in regulated segments.
- Lead times and inventory strategy: Component lead times and finish machining create windows where build-to-stock vs build-to-order decisions materially affect cash and service levels. We recommend a tiered inventory strategy linked to installed-base criticality.
Technology and product innovation opportunities
- Integrated sensing: The convergence of sight-glass hardware with electronics (condition-monitoring pods) opens recurring revenue via SaaS-enabled diagnostics and predictive maintenance contracts.
- Advanced coatings and glasses: Anti-fouling, scratch-resistant and enhanced-transparency coatings are differentiators in markets where visual clarity equals diagnostic value.
- Modular designs: Standardized mounting and modular retrofit kits reduce installation friction and accelerate aftermarket growth.
Actionable recommendations for 2026
- Prioritize certification-led product upgrades: Allocate R&D spend to meet API/DIN and ATEX requirements in priority verticals—this shortens spec cycles and increases win rates.
- Move up the value chain: Bundle sight glasses with condition monitoring and service contracts to increase lifetime customer value.
- De-risk supply: Qualify at least two borosilicate fabricators and one polymer alternative supplier for each key product family.
- Targeted M&A and partnerships: Use the mid-market fragmentation to acquire complementary technology (sensor integration) or to secure regional aftermarket distribution.
- Commercialize retrofit kits: Fast-to-install retrofit kits are a capital-light path to aftermarket penetration and recurring revenue.
How to use the report
Executives should use the report as a playbook: plug our forecast and sensitivity runs into your 2026 planning, apply the supplier risk matrix to procurement decisions, and adapt the go-to-market templates to shorten tender cycles. The full report also contains the granular segmentation, regional demand maps, price-band tables and a ranked vendor scorecard that underpin the strategic recommendations summarized here—information available only in the subscriber edition.
For access to the complete dataset, supplier scorecards, downloadable financial models and the full list of segment-level forecasts (including regional and application splits), please consult the PW Consulting Oil Tank Sight Glasses Market report on our website or contact your PW advisor to request the subscriber package.
For detailed analysis of this topic, please visit the official page: Oil Tank Sight Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Open Circuit Combustible Gas Detector Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest market study on the Open Circuit Combustible Gas Detector market provides a focused, decision-grade vantage point for corporate leaders planning capital allocation, product strategy, and M&A activity in 2026. Anchored to a 2025 base year with a historical window covering 2020–2025 and a forecast horizon stretching 2026–2032, the study projects a steady expansion at a compound annual growth rate (CAGR) of 6.85% across the forecast window. The market has grown from roughly USD 142 Million in 2020 to about USD 201 Million in 2025, and our base forecast anticipates it reaching in excess of USD 320 Million by 2032. These headline figures frame a clear growth trajectory—but beneath them lie operational and strategic inflection points that will determine winners and laggards in 2026 and beyond.
Open Circuit Combustible Gas Detector Market
Why this matters for 2026 corporate decision-makers
- Safety compliance is increasingly non-negotiable. Performance standards and approvals (for example, industry-recognized criteria such as ANSI/ISA and FM approvals) are driving procurement toward devices with demonstrable field reliability and certification pedigrees.
- Technology differentiation is accelerating. Infrared open-path systems retain broad industrial relevance, while laser-based and other advanced detection modalities are competing on sensitivity, false-alarm rejection, and lifecycle cost.
- Supply-side dynamics are squeezing margins. Inflationary pressure on raw materials and sensor components is affecting manufacturing cost curves and time-to-market for next-gen products.
- Market structure allows for selective consolidation. The market concentration metrics indicate a moderate cluster of leading vendors alongside a robust long tail of specialist suppliers—creating M&A and alliance opportunities for scale, channel depth, and technology access.
Key strategic implications (executive summary)
- Prioritize certified product lines for core accounts. Buyers increasingly privilege devices with proven field performance and relevant certifications—invest in testing, certification, and transparent reliability data.
- Shift from CAPEX-only selling to lifecycle value propositions. Differentiation through service contracts, predictive maintenance, and remote diagnostics will create recurring revenue that offsets raw-material-driven margin compression.
- Accelerate selective investment in next-gen modalities. Laser-based and advanced IR sensors promise technical advantages in select use cases; pilot deployments in high-value sites will shape 2027+ procurement cycles.
- Hedge supply-chain exposure. Near-term inflation and component scarcity demand supplier consolidation, strategic sourcing, and inventory strategies to protect delivery commitments.
- Scan the M&A horizon. Moderate market concentration and technology gaps among incumbents make acquisitions of niche innovators and regional channel partners an efficient route to scale.
What the PW Consulting report delivers (practical contents)
- A transparent, model-backed market sizing and forecast (2026–2032) with scenario variants that stress-test upside and downside cases against energy transition, regulatory tightening, and raw-material volatility.
- A deployable commercial playbook: customer segmentation, procurement triggers, pricing sensitivity templates, and recommended service-pack architectures to convert pilots into recurring revenue.
- Competitive benchmarking and positioning grids that combine product capabilities, certification status, installed-base reach, and channel strength into investable insights (note: detailed sub-segment share tables and raw values are reserved for subscribers).
- Technology roadmaps and R&D priorities, including integration checklists for laser, infrared, catalytic, and hybrid detection approaches and practical test protocols for field validation.
- Supply-chain risk maps and a cost-driver model that quantify the impact of raw-material price moves on unit economics and margin scenarios.
- A curated shortlist of acquisition and partnership targets based on capability fit, commercial reach, and valuation heuristics.
Competitive landscape: profiles and strategic takeaways
- Emerson (Rosemount / Spectrex) — Emerson’s portfolio is anchored by field-proven infrared open-path products that serve harsh hydrocarbon environments. Its strength is an installed base and deep OEM/enterprise channel relationships. Strategic takeaway: incumbency and integration depth make Emerson a de facto partner or a competitor to be matched on service and certification rather than price.
- MSA Safety — With offerings spanning infrared detectors and next-gen connected portable devices, MSA is pushing both product innovation and connectivity. Recent product introductions in connected detection underscore its move to embed monitoring into broader safety ecosystems. Strategic takeaway: position against MSA by accelerating connected diagnostics and offering superior false-alarm rejection in industrial deployments.
- Teledyne Gas & Flame Detection — Teledyne’s preview of next-generation devices and laser-based detectors signals aggressive technology investment. Expect targeted wins where sensitivity to specific gas species or long-range detection is critical. Strategic takeaway: monitor new product launches closely and prioritize technical trials in customers with demanding detection specifications.
- GDS Corp — As a distributor and systems integrator, GDS is a key channel partner for manufacturers looking to broaden reach in industrial segments. Strategic takeaway: channel partnerships with distributors like GDS accelerate deployment in segmented industrial pockets—evaluate exclusive or prioritized distribution agreements where appropriate.
- Det-Tronics (UTC Group) — Det-Tronics’ open-path solutions are oriented toward continuous hydrocarbon monitoring with an emphasis on system reliability. Strategic takeaway: compete on demonstrable uptime, reduced false positive rates, and integrative capability with site safety systems.
Regulatory and supply-side dynamics to watch in 2026
- Standards compliance is a table-stakes requirement. Meeting established performance requirements and approvals materially affects buyer shortlists and insurance acceptance; manufacturers should accelerate certification timelines and publish third-party test results.
- Raw-material cost inflation is not transitory for all vendors. Rising component and sensor costs compress gross margins and create incentives for product redesign or price escalation; proactive cost-to-serve analysis and supplier hedging are practical mitigants.
- False-alarm rejection and data integrity will be differentiators. Buyers reward devices that reduce nuisance trips because these devices lower total cost of ownership and site disruption risk.
Market concentration and competitive opportunity
Market concentration metrics indicate a moderate degree of aggregation: the three largest firms account for a meaningful minority of market share, while the top five capture a clear majority. This structure implies that well-executed scale plays—whether through organic channel expansion or targeted tuck-ins—can rapidly change competitive dynamics. For incumbents, the task is defending margin and installed-base services; for challengers, the opportunity is to offer differentiated technology or local service excellence to win share.
Open Circuit Combustible Gas Detector Market
90-day action plan for executive teams
- Initiate certification fast-tracks for priority products and publish independent test results to shorten procurement cycles.
- Run cost-to-serve and component-sensitivity stress tests; identify top 3 cost levers to protect gross margin under +10% raw-material inflation scenarios.
- Set up 2–3 field pilots for next-gen sensors with strategic customers to gather performance and service data under real operating conditions.
- Conduct a rapid channel health check: top distributors, integrators, and service partners—identify single points of failure and redundancy plans.
- Compile a short M&A watchlist of 6–8 targets (technology specialists, regional leaders, service platforms) and commence initial diligence on cultural and systems fit.
How to use the full PW Consulting study
This briefing is intentionally selective—a “trailer” that surfaces the most consequential strategic insights while withholding granular sub-segment tables and confidential company scorecards. The full report contains the underlying market model, detailed segmentation by region, type, and application, complete competitive scorecards, pricing matrices, and downloadable datasets that operational teams can use in procurement, R&D prioritization, and M&A underwriting. Organizations that need executable plans—detailed product roadmaps, go-to-market playbooks, and a prioritized list of acquisition targets with valuation heuristics—will find those deliverables in the full study.
Open Circuit Combustible Gas Detector Market
Next steps
- Request the full report and dataset to access the withheld sub-segment detail and company-level scorecards.
- Engage PW Consulting for a tailored two-week diagnostic: we will translate the market model into a bespoke strategic plan aligned to your portfolio, channels, and balance sheet.
PW Consulting — We combine field-tested industry insight, rigorous modeling, and practical playbooks to help safety-technology firms and industrial operators translate market growth into profitable, sustainable advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Open Circuit Combustible Gas Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: One-Box Electro-Hydraulic Braking Systems Poised to Expand at a Robust 12.0% CAGR Through 2032, New Market Insight Reveals
By PW Consulting, 2026-07-13
One Box Electro-Hydraulic Braking Systems: Strategic Imperatives for 2026 — PW Consulting Market Brief
PW Consulting’s latest One Box Electro Hydraulic Braking System Market report (base year 2025, forecast period 2026–2032) synthesizes proprietary modeling, supplier diligence, and scenario-driven strategy work to equip executive teams for decisive action in 2026. The market has moved from a nascent systems integration challenge into a clear commercial inflection. Our modeling shows the global market expanding from roughly USD 1.7 billion in 2020 to USD 2.5 billion in 2025, and — at a compound annual growth rate of 12.0% — tracking toward just over USD 5.5 billion by 2032. For automotive suppliers, OEMs and private equity investors, that trajectory reframes product roadmaps, M&A appetite, and go-to-market priorities for the next 18–36 months.
One Box Electro Hydraulic Braking System Market
Why this report matters for 2026 decision-makers
-
Timing: 2026 will be the year when integration economics and regulatory push converge. Manufacturers who align product architectures, software stacks, and manufacturing footprints now will secure preferred OEM programs and margin recovery in the medium term.
One Box Electro Hydraulic Braking System Market -
Technology leverage: One-box architectures reduce system cost and packaging complexity but raise requirements for controls software, functional safety validation, and supplier cross-domain coordination. Our report identifies the most material technical and commercial levers — and the typical pitfalls firms encounter when scaling from lab to production.
One Box Electro Hydraulic Braking System Market -
Consolidation dynamics: The market exhibits meaningful concentration. The top three suppliers account for the majority share of the market and the top five for an even larger proportion, underscoring that scale, integration capability and global OEM relationships remain decisive competitive advantages.
What PW Consulting delivers — practical, action-oriented content
-
Rigorous market sizing and scenario framework: We provide a transparent methodology linking vehicle parc and platform forecasts to ASP and penetration curves. The report includes base, conservative and accelerated scenarios (sensitivity to EV uptake, regulatory timing, and supply constraints) to stress-test investment cases.
-
Decision-grade playbooks: For suppliers and OEM suppliers we deliver go-to-market templates tailored to four strategic archetypes — scale integrators, niche specialists, software-first players, and contract manufacturers — outlining near-term KPIs, investment sequencing, and partner ecosystems necessary to win.
-
Commercial and procurement tools: A supplier selection matrix, cost-down levers by Bill-of-Materials category, and a negotiation checklist for volume contracts designed to be used in 2026 sourcing rounds.
-
Technology & product roadmap analysis: Comparative assessment of one-box topologies, software partitioning strategies, and validation requirements for ASIL levels. We map recommended R&D focus areas by risk/impact for the next 24 months.
-
Supply chain and manufacturing guidance: Site selection criteria, modular assembly approaches, and a resilience playbook addressing critical component constraints (including electronic control modules and pressure actuation subsystems).
-
Regulatory and safety intelligence: Practical guidance to align product certification pathways with forthcoming regulatory milestones and to anticipate the most likely areas of increased compliance scrutiny.
-
M&A and partnership screening: A shortlist methodology to identify tuck-in targets or strategic partners, plus valuation sensitivities and integration checklists focused on capture of cross-sell and engineering synergies.
-
Executive dashboards and investor briefing packs: Condensed slide sets and talking points specifically prepared for 2026 board-level funding decisions or investor diligence.
Competitive landscape — strategic implications
The market is led by established tier-one systems integrators with global OEM relationships and deep cross-domain engineering capability. Key players include Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG and Hyundai Mobis. Each brings differentiated strengths that shape competitive dynamics and define the choice sets for OEMs and fleets:
-
Robert Bosch GmbH — strategic edge: deep systems integration expertise and proven actuation suites (including booster and control integration) position Bosch to capture programs that prioritize rapid validation cycles and global production scale. Their strengths make them a default partner for OEMs seeking lowest technical risk.
-
Continental AG — strategic edge: a strong portfolio of combined actuation and control modules and program execution experience enables Continental to compete on both cost and integration speed, particularly where packaging constraints are critical.
-
ZF Friedrichshafen AG — strategic edge: strong vehicle-dynamics integration and experience with electro-hydraulic subsystems enable ZF to pursue differentiated propositions where braking is coupled tightly with advanced stability and ADAS features.
-
Hyundai Mobis — strategic edge: focused product lines for electrified powertrains and close OEM alignment give Mobis rapid route-to-production advantages on certain EV platforms.
Strategic takeaway: incumbent strength is not immutable. Scale, software competence, rapid validation capability and manufacturing agility define the barriers to entry. Mid-tier suppliers who can demonstrate secure software stacks, validated functional-safety pathways, and stable sourcing for critical components can still win niche or platform-specific programs — but they must move decisively in 2026.
Key market dynamics shaping 2026 choices
-
Electrification and packaging pressure: As EVs and hybrids proliferate, packaging and energy recovery imperatives make one-box systems attractive. OEMs will increasingly request integrated modules that streamline assembly line processes and weight targets.
-
Software and system reliability: The marginal value in one-box systems is driven by embedded controls and software feature sets. Investment in modular, updatable software architectures will unlock aftermarket revenue and OTA (over-the-air) improvement cycles.
-
Regulatory trajectories: Safety and emissions-adjacent regulations are accelerating testing and certification demands. Manufacturers must align product release schedules with evolving test protocols to avoid costly program delays.
-
Supplier consolidation: Procurement teams will favor fewer, deeply integrated suppliers to reduce program management overhead — a structural tailwind for larger players and a headwind for fragmented suppliers.
-
Cost and localization pressures: Macro-cost inflation and OEM localization preferences will push suppliers to optimize regional manufacturing footprints and supply base strategies in 2026 planning cycles.
Concrete recommendations for 2026 — a practical checklist
-
For Tier-1 integrators: accelerate software modularization and invest in scalable validation rigs. Prioritize multi-OEM program wins where you can amortize validation and tooling costs.
-
For mid-tier suppliers: identify one OEM platform to win in 2026 as a beachhead. Use that program to validate your control stack and secure a reference case demonstrating manufacturability and functional safety.
-
For OEMs: consolidate supplier lists to 2–3 strategic partners per platform, but retain a nimble secondary suppliers pipeline for risk mitigation. Bake in phased qualification milestones to de-risk 2027–2028 production ramps.
-
For investors: prioritize targets with proven software IP, defensible margins via integrated BOM positions, and established validation processes. Avoid assets with unproven high-volume manufacturability unless acquisition includes experienced operational leadership.
-
Operationally: start 2026 with a six-quarter plan that sequences engineering validation, tooling investment, and supplier qualification. Add contingency runway for semiconductor lead times and test-lab bottlenecks.
What we deliberately withhold — and why
To preserve the commercial utility of this brief while respecting the “trailer” intent of our release, PW Consulting is intentionally omitting the granular regional, type and application split tables from this executive summary. The full report contains detailed, auditable segment tables, per-region and per-application penetration curves, supplier-level share models, and downloadable Excel workbooks used in our scenario simulations. These datasets are essential if you require line-item projections or intend to embed our models into your internal financial planning.
How to use the full report in your 2026 planning
-
Integrate our scenario outputs into CapEx prioritization to stress-test manufacturing investments under different EV adoption paths.
-
Use the supplier selection matrix during Q2–Q3 sourcing windows to shape long-lead component contracts and lock in price/downside protections.
-
Leverage the M&A screening tools to build a short-list of targets that accelerate your software or production footprint ambitions without requiring greenfield development.
Next steps — PW Consulting support
For leadership teams making budget and program choices in 2026, this report is structured to be an immediate operational asset: a strategy playbook and a modeling toolbox in one. PW Consulting can provide rapid-deployment advisory services to apply the report directly to your organizational context, including tailored scenario re-runs, supplier diligence support, and M&A target vetting.
To access the full dataset, detailed segment tables, and the Excel models referenced in this brief, please visit the PW Consulting report page. Our team will arrange a briefing and model handover so your 2026 planning process is informed by validated intelligence and executable recommendations.
For detailed analysis of this topic, please visit the official page: One Box Electro Hydraulic Braking System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Turbine Inlet Air Cooling Market to Rise from USD 1,074.3 Million in 2025 to USD 1,766.95 Million by 2032 at a 7.35% CAGR
By PW Consulting, 2026-07-13
Turbine Inlet Air Cooling (TIAC) Market — Strategic Imperatives for 2026: A PW Consulting Preview
PW Consulting’s upcoming Turbine Inlet Air Cooling (TIAC) Market report provides a concise, decision-ready intelligence package designed to inform capital allocation, procurement strategy, and product roadmap decisions in 2026. Built on a 2020–2025 historical baseline (base year 2025) and a 2026–2032 forecast horizon, the study projects the TIAC market to grow at a compound annual growth rate (CAGR) of 7.35% through the forecast period. The market, measured in USD Million, demonstrates meaningful momentum from the 2025 baseline and toward a materially larger market by 2032 — a trend that creates both opportunities and strategic risks for OEMs, utilities, and industrial end-users.
Turbine Inlet Air Cooling (TIAC) Market
Why this preview matters to 2026 decision-makers
-
Timing matters: 2026 is a pivot year for many operators planning mid‑life upgrades and capacity optimization programs. The TIAC market’s structural growth and technology evolution make it a timely lever for improving gas turbine output and unit economics.
Turbine Inlet Air Cooling (TIAC) Market -
Investment vs. optionality: With a sustained CAGR of 7.35% and clear year‑on‑year expansion from the 2025 baseline, capital planners must determine whether to treat TIAC as a core augmentation strategy or a staged operational hedge tied to fuel and weather volatility.
Turbine Inlet Air Cooling (TIAC) Market -
Regulatory and supply‑chain pressures: Standards bodies and commodity cost dynamics are reshaping supplier selection, contracting terms, and inventory strategies — all covered in the full report’s practical playbooks.
What the report delivers (practical, executable content)
-
Executive decision frameworks: A step‑by‑step assessment tool that translates market growth and operational drivers into an invest/hold/tiered pilot recommendation for asset owners.
-
CAPEX/OPEX and lifecycle models: Interactive templates and scenario outputs that quantify payback windows under alternative fuel, ambient, and capacity‑value assumptions (sensitivity-tested against the report’s central CAGR case).
-
Vendor due diligence toolkit: A standardized RFP checklist, technical scorecards, and post‑installation performance KPIs tailored to TIAC delivery models (evaporative, fogging, mechanical, absorption, and hybrid concepts).
-
Deployment playbooks: Practical guidance for site selection, integration sequencing, condensate and filtration strategies, and O&M protocols that reduce commissioning risk and protect turbine warranties.
-
Regulatory and materials risk tracker: Real‑time issue briefs explaining how standards activity and raw material inflation translate into schedule risk, cost escalation, and contract levers.
-
Commercial templates: Negotiation term sheets and aftermarket service models to capture predictable revenue and to de‑risk long‑tail service liabilities.
-
Benchmarking and case studies: Confidentialized performance examples across climate regimes and operating profiles to help teams size benefit pools without exposing sensitive counterpart data.
Macro drivers shaping TIAC strategy in 2026
-
Thermal performance arbitrage: Operators continue to seek deterministic ways to restore or augment gas turbine output as load patterns and renewable intermittency increase. TIAC technologies remain one of the fastest deployable interventions to boost peak output and capacity value.
-
Weather and demand volatility: More frequent heat extremes amplify the value of inlet cooling. The report quantifies how heat events translate to output loss and how targeted TIAC deployments can alter dispatch economics.
-
Technology convergence: Hybrid approaches (combining evaporative/fogging with mechanical chilling or thermal energy storage) are becoming commercially attractive as control systems and digital monitoring improve lifecycle performance.
-
Standards and knowledge exchange: The Turbine Inlet Cooling Association (TICA) continues to drive best practices and standards development as of 2026, which affects procurement specifications, acceptance testing, and cross‑vendor interoperability.
-
Input cost pressures: Rising commodity prices for steel and aluminum have increased manufacturing input costs, with direct implications for BOM pricing and lead times. The report models input‑cost pass‑through and proposes contracting approaches to mitigate escalation risk.
-
Concentration and market structure: The market exhibits a moderate degree of vendor concentration, with a handful of firms holding influential positions while specialist suppliers and system integrators capture niche verticals. This structure creates opportunities for strategic partnerships, bolt‑on M&A, and regional channel plays.
Competitive landscape — who’s influencing outcomes in 2026
-
Strategic acquirers and integrators: Market leaders are extending offerings through acquisitions and cross‑domain integration. A notable example in early 2026 is the completion of an acquisition that enhances thermal energy storage and data‑center cooling capabilities within TIAC portfolios. Such consolidation accelerates turnkey delivery models and tightens supply‑chain coordination requirements.
-
Fogging and evaporative specialists: Firms focused on high‑pressure fogging and engineered evaporative solutions continue to win awards and recognition for energy‑efficient augmentation approaches. Recent industry awards and white papers position these suppliers as high‑value partners for rapid, low‑capex deployment.
-
Packaged chiller suppliers: Global HVAC and chiller OEMs are delivering containerized mechanical chillers and packaged solutions that appeal to utilities seeking predictable performance under stringent warranty terms. These players often compete on integration, control systems, and service networks rather than on raw equipment price alone.
-
Ancillary system providers: Filtration and condensate management specialists are increasingly important as projects target sub‑micron particulate control and lifecycle water handling. Effective partnerships between air filtration and cooling vendors materially reduce turbine fouling risk and maintenance costs.
-
Recent vendor developments to note: award recognitions for fogging solutions (2026), high‑profile industry awards for excellence in inlet cooling (2025), and strategic M&A activity (early 2026) that reposition capabilities toward turnkey, integrated solutions. PW Consulting tracks these events to update supplier scorecards in near real‑time.
Strategic recommendations for 2026 (operational and corporate)
-
Adopt a scenario‑based capital plan: Run at least three TIAC scenarios (conservative, central, aggressive) tied to fuel price and extreme‑weather frequency assumptions; embed the report’s 7.35% CAGR view as the central case.
-
Pilot hybrid solutions: For sites with high seasonal volatility, pilot hybrid configurations combining evaporative or fogging subsystems with modular mechanical chillers or thermal storage to optimize CAPEX/OPEX profiles.
-
Prioritize digital enablement: Select vendors that include integrated monitoring, predictive maintenance, and performance‑guarantee telemetry to simplify contract enforcement and performance reconciliation.
-
Hedge procurement risk: Use fixed‑price supply agreements with material‑cost pass‑through caps, staged payments tied to milestones, and inventory reservation clauses to manage lead‑time and commodity exposure.
-
Monetize aftermarket: Design service contracts that capture spare parts, consumables (filters, nozzles), and performance‑tuning services to create annuity revenue and reduce total cost of ownership for customers.
-
Use standards as a competitive shield: Leverage TICA guidance and acceptance protocols to raise barriers to entry and to shorten commissioning dispute resolution timelines.
-
Assess strategic M&A and partnerships: For OEMs and integrators, consider alliances with filtration and thermal‑storage specialists to offer fully integrated, warranty‑backed TIAC systems.
-
Plan workforce readiness: Add skill sets for system integration, water treatment, and digital operations to maintenance teams to ensure sustained performance post‑installation.
What the full PW Consulting report contains (and why you’ll want it)
-
Comprehensive forecasting suite: Year‑by‑year market size projections across the 2026–2032 forecast window, with scenario modeling and sensitivity analysis rooted in our central 7.35% CAGR case.
-
Vendor benchmarking: Confidential scorecards, capability maps, and M&A/risk profiles for leading and specialist providers to accelerate supplier selection and negotiation.
-
Market concentration analysis: CR3/CR5 trends, entry barriers, and go‑to‑market dynamics that inform partnership strategies and competitive positioning.
-
Operational playbooks and financial templates: Ready‑to‑use tools to calculate payback periods, availability impacts, and dispatch economics under multiple operating regimes.
-
Implementation checklists and case studies: Real deployment narratives that highlight common pitfalls, commissioning shortcuts, and verified performance uplift metrics (confidentialized).
PW Consulting’s TIAC market preview is intentionally diagnostic and strategic — it reveals the forces, players, and levers you need to weigh in 2026 without disclosing the full set of granular segmentation tables that power procurement and competitive plays. For the full dataset, vendor scorecards, and executable playbooks referenced here, please consult the complete TIAC Market report and arrange a tailored briefing with PW Consulting’s TIAC practice.
For detailed analysis of this topic, please visit the official page: Turbine Inlet Air Cooling (TIAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


