



Category: Machinery & Automotive
PW Consulting: Automotive Premium Audio Market Poised for 5.63% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Automotive Premium Audio Systems Market — Strategic Outlook for 2026 Decisions
Executive trailer: why this research matters in 2026
As OEMs and suppliers enter a new rhythm of software-enabled differentiation and immersive content partnerships, premium in-car audio is no longer a niche amenity — it is a strategic battleground for brand affinity, EV acoustic masking strategies, and recurring revenue opportunities. PW Consulting’s Automotive Premium Audio Systems Market study synthesizes historical performance, near-term shocks, and a seven‑year forecast to equip C‑suite and business‑unit leaders with the evidence and frameworks needed to make defensible 2026 decisions.
Automotive Premium Audio Systems Market
At a glance: the global market recovered from pandemic-era volatility to reach an estimated USD 4.5 billion (base year 2025), with the study projecting a steady compound annual growth rate of 5.63% through our forecast horizon. Underlying that headline growth is a dynamic interplay of immersive audio adoption, consolidation among premium suppliers, and the rapid entanglement of audio with infotainment and cloud services. Our report translates these macro signals into practical go-to-market options without exposing the granular commercial intelligence that defines competitive advantage — intentionally reserving full segmentation and channel-level detail for the complete report.
Automotive Premium Audio Systems Market
What this research delivers (practical, decision-grade content)
- Actionable market sizing and trend attribution — a clear chronology from 2020 through 2025 and a scenario‑based forecast to 2032 that isolates demand drivers (technology adoption, vehicle mix, aftermarket dynamics) from one‑off shocks.
- Strategic playbooks for OEMs, Tier‑1s, audio specialists, and aftermarket players — including partnership archetypes, revenue models (hardware premiuming vs. software/subscription capture), and prioritized target segments.
- Competitive landscape mapping — a synthesis of capability, go‑to‑market intent, and recent strategic moves across the leading suppliers and technology partners, designed to illuminate white spaces and risk corridors.
- Commercial frameworks — pricing vs. perceived value matrices, supplier selection scorecards, TCO templates for bundled audio‑infotainment packages, and an integration checklist for immersive audio features (object‑based mixing, spatialization, and vehicle‑specific tuning).
- Supply‑chain and sourcing risk assessment — component concentration, strategic raw‑material considerations, and mitigation strategies for the premium audio bill of materials.
- Illustrative case studies and launch playbooks — detailing how leading luxury brands and selected mainstream OEMs introduced immersive features (e.g., Dolby Atmos integrations) without disclosing proprietary contract terms or segment revenue splits.
Market trajectory and what it implies for 2026 planning
The market’s trajectory through 2025 shows recovery and re‑acceleration, resulting in a mid‑single digit CAGR over the forecast period. For executives this means two simultaneous realities: first, a predictable base of hardware demand that continues to expand as vehicle complexity and consumer expectation rise; second, that marginal value creation is increasingly found beyond loudspeaker counts — in software, acoustic tuning ecosystems, personalized audio, and platform partnerships.
Automotive Premium Audio Systems Market
Consequently, 2026 should be treated as a pivotal operational year: companies with strong hardware heritage must accelerate their software and content strategies; software‑first firms must prove hardware integration competencies or secure closer OEM alliances; and aftermarket players must recalibrate value propositions as factory‑fitted immersive options proliferate.
Five strategic themes shaping the premium audio agenda
- Immersive audio as a mainstream differentiator — Object‑based formats and spatial audio are migrating from flagship models into broader portfolios through platform partnerships and infotainment integrations. The technology is no longer decorative; it is a design requirement for brands that sell emotional differentiation.
- Software and content economics — Audio experiences are now services: asset pipelines, licensing (e.g., Atmos), personalization engines, and OTA tuning represent recurring revenue levers that materially change lifetime customer economics.
- Consolidation and capability layering — The premium supply base is consolidating around a few leaders that combine global OEM reach with an extended brand portfolio and content partnerships. Market concentration metrics indicate material share held by the top suppliers, influencing negotiation dynamics for new entrants.
- Platformization of audio — Infotainment platforms and smartphone integrations (Apple CarPlay/Android Auto) are critical distribution vectors for spatial audio; OEMs are evaluating whether to embed capabilities in vehicle platforms or to defer differentiation to branded audio partners.
- Aftermarket versus factory-fit interplay — A growing set of consumers seeks upgraded sound via aftermarket products, but the rapid factory adoption of immersive standards narrows certain aftermarket opportunities while creating new niches (e.g., retrofittable spatial processors, personalized sound profiles).
Competitive landscape: who matters and why
The premium automotive audio ecosystem is diverse: legacy high‑fidelity brands, technology platforms, consumer electronics conglomerates, and specialist OEM integrators. The study profiles each major participant, assessing where they play (vehicle classes, OEM anchor relationships), their architectural strength (acoustics, DSP, software services), and indicators of future intent (acquisitions, partnerships, product launches).
- HARMAN International (Stamford, CT) — A cornerstone supplier in the automotive premium space, HARMAN’s brand breadth and recent portfolio expansion through strategic acquisitions position it as a one‑stop partner for OEMs seeking both brand cachet and scale integration. Expect continued emphasis on immersive system integration and bundled software services.
- Bose Corporation (Framingham, MA) — Bose’s SeatCentric and active noise management capabilities give it a unique value proposition for comfort‑focused premium experiences. Demonstrations at major trade shows and OEM relationships underline its role as a supplier that bridges acoustical engineering and user personalization.
- Bowers & Wilkins (UK) and Burmester (Germany) — High‑fidelity specialists that anchor luxury brand collaborations; their differentiation rests on studio‑grade transducers, bespoke vehicle tuning, and an artisanal product narrative that supports premium price points.
- Dynaudio, McIntosh Group, Pioneer, Panasonic, Sony, ALPS ALPINE — These players vary across OEM focus, aftermarket offerings, and component specialization. Together they form the competitive middle and upper tiers where innovation in speaker design, amplifier integration, and platform interoperability occurs.
- Dolby Laboratories (San Francisco) — As a technology and licensing partner, Dolby is an accelerant: its Atmos ecosystem has been adopted by dozens of manufacturers and over a hundred vehicle models, and recent OEM partnerships demonstrate how audio IP can determine product positioning across entire vehicle portfolios.
Recent developments — from Burmester’s series introduction of object‑based immersive “Audiofields” to Dolby’s public roll‑outs with OEMs and Pioneer’s aftermarket spatial audio receiver — signal two concurrent movements: immersive audio is becoming a baseline expectation, and suppliers are racing to own the software and playback stack that determines how consumers experience that immersion.
How to convert insight into 2026 action — recommended plays
- Prioritize platform partnerships over one‑off feature wins. Negotiations should secure rights to update tuning, profile delivery, and data‑driven personalization — not only hardware placement.
- Design an “audio as service” experiment. Test subscription or pay‑per‑feature models on a limited fleet or configurator SKU to understand monetization elasticity before a broad commercial rollout.
- Reassess supplier risk with concentration in mind. Given the market’s consolidation, build contingency pathways (dual sourcing, white‑label DSP stacks) for critical audio components and software licenses.
- Leverage brand equity through co‑development. Luxury OEMs and tier‑1 integrators should exploit co‑branded audio experiences to extract higher trim attach rates while protecting margins via shared IP and service agreements.
- Invest selectively in content and UX. Customer‑facing features — personalized sound profiles, acoustic presets for EV cabin noise, and integrated voice‑activated audio services — yield disproportionate perceived value relative to incremental hardware costs.
What we deliberately withhold here — and why
To respect commercial sensitivity and to preserve the strategic advantage for subscribing clients, this introduction does not disclose the full regional and application‑level split, nor the transaction‑level pricing matrices and contract templates included in the full study. Those granular segmentation tables and supplier contract exemplars are central to executing precise go‑to‑market moves and are available through the complete report package.
Final note — making 2026 the year you capture acoustic advantage
Premium automotive audio now sits at the intersection of hardware excellence, software services, and content licensing. The market’s mid‑single digit growth masks an important truth: the highest value is created by firms that rearchitect the offering from a set of bundled electro‑acoustic components into a platform platform-plus‑services proposition. For executives mapping 2026 priorities, this research provides the diagnostic, the competitive context, and the tactical playbooks needed to convert product differentiation into durable commercial returns.
To unlock the detailed segmentation, supplier scorecards, and executable contract templates referenced above, access the full PW Consulting Automotive Premium Audio Systems Market study and our bespoke advisory services for tailored 2026 strategies.
For detailed analysis of this topic, please visit the official page: Automotive Premium Audio Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Law Enforcement Recorder Market to Grow at 8.15% CAGR, Hits USD 249M in 2025
By PW Consulting, 2026-07-12
Police Law Enforcement Recorder Market: Strategic Primer for 2026 Decision-Making
As public safety agencies and vendors enter 2026, the Police Law Enforcement Recorder market is entering a consolidation and capability-acceleration phase. PW Consulting’s latest market research—anchored on a 2025 base year and a forward-looking forecast to 2032—shows a clear, data-backed growth trajectory (2020–2025 historical build and an 8.15% CAGR over the 2026–2032 forecast window). Our brief below synthesizes why this market matters for your 2026 strategy, what the regulatory and funding tailwinds mean in practice, how competitive dynamics are shaping commercial choices, and the practical workstreams we recommend for procurement, product and partnership leaders.
Police Law Enforcement Recorder Market
Why 2026 is a Strategic Inflection Point
-
Market momentum: After steady historical expansion from 2020 through 2025, the market base in 2025 provides a robust platform for the forecast period. Under current assumptions, demand and revenue expand materially through 2032, reflecting technology refresh cycles, increasing policy mandates, and new funding mechanisms that accelerate adoption.
Police Law Enforcement Recorder Market -
Policy and funding convergence: 2024–2026 developments—state grant programs, federal BJA initiatives, and updated legislative requirements—have moved the market from proof-of-concept projects into mainstream procurement. Agencies that align procurement timing and compliance planning with these windows can capture accelerated budget cycles and grant funding.
Police Law Enforcement Recorder Market -
Technology maturity and differentiation: Hardware improvements (higher-resolution capture, longer battery life, LTE/5G connectivity) combined with software advancements (edge AI for activation, cloud-based evidence management, automated redaction) are reshaping vendor value propositions toward integrated hardware+software+services offerings.
Market Dynamics That Will Drive 2026 Decisions
-
Funding as a catalyst: Recent state and federal funding programs have increased program starts and refreshes. Public agencies that effectively sequence grant applications, procurement timelines and pilot outcomes will reduce time-to-deployment and improve unit economics.
-
Regulatory pressure on policy and redaction: Multiple jurisdictions have tightened requirements for body-worn camera policy and data handling. Notably, state-level actions in 2025–2026 have introduced explicit redaction and disclosure rules with firm implementation dates—forcing agencies and vendors to embed compliant redaction workflows into product roadmaps and procurement specifications.
-
Concentration and competitive dynamics: The market exhibits significant concentration among a small number of global vendors. This creates a supplier landscape where rigorous vendor due diligence, interoperability assessments and contract terms (including data ownership, evidence chain-of-custody, and SLAs) matter a great deal.
-
Operationalization of AI: Expect increased buyer attention to demonstrable AI capabilities—automated event detection, redaction acceleration, transcription quality and accuracy metrics—rather than marketing claims. Pilots should be structured to validate these capabilities under operational conditions.
What’s in the PW Consulting Report (Practical, Actionable Contents)
-
Market sizing and forecasting model (2020–2032) with scenario analysis to inform procurement volumes and budget planning.
-
Demand-driver mapping that ties funding sources, legislation, and operational imperatives to expected procurement windows.
-
Vendor landscape and strategic position maps with capability matrices (hardware, connectivity, evidence management, AI, compliance) and go-to-market behavior.
-
Procurement playbook: RFP templates, technical acceptance criteria, pilot design, TCO and ROI models tailored for police departments and municipal buyers.
-
Integration guidelines: best practices for CAD/RMS, dispatch, and cloud evidence management coupling; API expectations and data sovereignty considerations.
-
Commercial implications for vendors: pricing strategies, subscription bundling, channel partnership frameworks, and M&A targets by capability gap.
-
Risk and compliance checklists: data protection, redaction workflow validation, FOIA/PII response procedures, and audit-readiness templates.
Competitive Landscape — Who Moves First Wins
The market is led by a group of vendors offering different strategic combinations of hardware, software and services. The competitive field is best understood through three commercial archetypes: integrated platform leaders (hardware + cloud + analytics), specialist hardware providers with ecosystem partnerships, and regional/niche players focused on compliance and tailored service models.
-
Integrated platform leaders: Companies in this group position end-to-end solutions—hardware (high-resolution cameras), evidence cloud, and AI-enabled workflows—targeting agencies seeking a consolidated supplier and simplified procurement. Their strengths include global product roadmaps, mature evidence management platforms and scale economies. For buyers, the trade-off is higher switching costs but faster time-to-value for fully managed programs.
-
Hardware-specialist vendors: These firms emphasize ruggedized capture devices, extended battery life, and OEM integrations. They often partner with software players for evidence management. Their advantage lies in competitive unit pricing and rapid hardware innovation; risks include dependence on third-party software integration and limited control over end-to-end user experience.
-
Compliance- and service-first vendors: Operating regionally or within constrained market segments, these providers emphasize data residency, CJIS/GDPR compatibility and tailored deployment services. They compete effectively where regulatory complexity and data sovereignty trump scale economics.
Selected vendor observations (strategic, not exhaustive):
-
Vendors offering integrated TASER/body systems and proprietary evidence clouds are leaning into arrest-event ecosystems—accelerating lock-in for agencies that standardize on unified hardware.
-
Providers with robust 4G/5G connectivity and livestream capabilities are winning bids where real-time situational awareness is a procurement priority; however, buyers must budget for network and data-plan costs in TCO calculations.
-
Regional vendors that demonstrate airtight compliance workflows and localized evidence management integrations remain attractive to European and privacy-sensitive jurisdictions.
-
Consolidation signals are visible: the market concentration metrics indicate that a small number of vendors account for a majority of revenues, which will increase the importance of competitive procurement tactics for mid-sized agencies.
Regulatory and Funding Signals You Can Act On in 2026
-
Grant alignment: Recent state and federal programs have created windows for program starts and refreshes. Agencies should map grant timelines to procurement and implementation roadmaps immediately to avoid losing grant-funded budget cycles.
-
Policy-driven requirements: New requirements to include redaction procedures and data disclosure obligations are setting fixed compliance dates. Vendors must accelerate redaction feature delivery; agencies must update policy and training materials concurrent with technical pilots.
-
Evidence access laws: Jurisdictions that require provision of unredacted camera data to entitled parties alter evidence-handling workflows and legal exposure. Implementation plans must include legal counsel and automated redaction as part of acceptance criteria.
Recommended 2026 Playbook — For Buyers and Vendors
-
Buyers (police departments, municipalities): Prioritize modular acquisitions—select hardware that meets minimal specification baselines and require open APIs for evidence management. Structure contracts with clear data ownership, redaction SLAs, and phased acceptance tied to operational pilot outcomes.
-
Vendors (hardware/software/service providers): Differentiate on measurable AI outcomes (redaction speed, transcription accuracy), integration simplicity, and compliance attestations. Consider subscription-led pricing to smooth revenue and align incentives for long-term evidence management services.
-
Both parties: Run operational pilots that stress-test the full chain—from capture to court-ready export—under live conditions. Include CA/FOIA test cases and disconnection/failover scenarios in acceptance test plans.
-
M&A and partnerships: For vendors with strong hardware but weak cloud capabilities (or vice versa), prioritized partnership or tuck-in acquisition opportunities are high-value plays in 2026 as agencies look for one-stop solutions.
What PW Consulting Recommends Next
2026 will reward actors that combine disciplined procurement, compliance-first implementation, and technical validation under operational conditions. Organizations that plan procurement around grant windows, require demonstrable AI and redaction capabilities in RFPs, and negotiate data-centric contract terms will reduce operational risk and maximize program ROI.
PW Consulting’s full report contains the detailed sizing model, vendor benchmarking matrix, RFP templates, and a step-by-step procurement playbook designed to inform 2026 capital and operating decisions. The executive summary above is designed as a strategic trailer—detailed segment economics, regional and application splits, and vendor-specific financial metrics are intentionally withheld here to preserve the value of the full report and to guide practitioners to the source for complete intelligence.
Next Steps
-
Contact PW Consulting for the full Police Law Enforcement Recorder Market report to access the complete datasets, interactive scenarios and procurement templates that operational teams can deploy in 2026.
-
Book a briefing with our analysts to align the report findings to your agency or corporate roadmap and to obtain a tailored implementation checklist tuned to your fiscal year and grant schedules.
For detailed analysis of this topic, please visit the official page: Police Law Enforcement Recorder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heavy Duty Encoders Market Poised for 7.33% CAGR Through 2032
By PW Consulting, 2026-07-12
Heavy Duty Encoders Market: Strategic Primer for 2026 Decision-Makers
Executive summary
As global industrial automation and heavy-industry modernization accelerate, heavy duty encoders have shifted from niche components to strategic system elements. PW Consulting’s newest market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—quantifies this shift and turns it into actionable guidance for executives planning capital allocation, product roadmaps, and supply‑chain resilience through 2026 and beyond.
Heavy Duty Encoders Market
Key headline metrics: the market expanded from the early‑2020s baseline into a mid‑2020s industry with clear double‑digit percentage growth vs. earlier years, and our forward projection runs at a compound annual growth rate (CAGR) of 7.33% across the 2026–2032 forecast window. Under PW Consulting’s scenario framework this implies a meaningful increase in absolute market scale between 2025 and 2032—growth that will amplify strategic stakes for OEMs, suppliers, and industrial end‑users.
Heavy Duty Encoders Market
Why this study matters for 2026 decisions
- Timing matters: 2026 is a turning point. Regulatory pressure, renewed CAPEX in steel, oil & gas maintenance cycles, and accelerated electrification projects are converging to increase demand for rugged, safety‑certified motion feedback.
- Risk is concentrated: Supply‑side shocks in late 2024–2025 exposed single‑source dependencies for key encoder components. Our study quantifies vulnerability vectors and models the real cost of downtime vs. the incremental investment needed to diversify suppliers or redesign for alternative ICs and interfaces.
- Feature arbitrage: Heavy duty encoders are no longer judged solely by IP rating and mechanical endurance. Functional safety, IO‑Link/Fieldbus integration, non‑contact sensing, and embedded diagnostics are now primary differentiators. Strategic product choices in 2026 determine access to high‑margin retrofit and new‑build segments through 2030.
Market trajectory: data‑driven context without the spoilers
Between the early 2020s and 2025 the heavy duty encoder market recorded steady expansion as industrial modernization projects picked up pace. Our market model—calibrated to 2025 as the base year—projects a sustained recovery and structural growth through 2032 at a 7.33% CAGR. That pace implies a near‑term imperative: vendors and integrators must choose between volume play (cost optimization and broad distribution) and value play (safety, redundancy, connectivity) to capture profitable growth.
Heavy Duty Encoders Market
Concentration dynamics are instructive: market share is meaningfully clustered among established suppliers, but our analysis shows meaningful room for focused specialist entrants—particularly those that can combine rugged hardware with software‑centric diagnostics or deliver differentiated service contracts for heavy‑uptime environments.
Regulatory, supply‑chain and cost dynamics shaping 2026
- Regulatory acceleration: EU directives introduced in 2025 raise the bar for interoperability, energy efficiency, and safety compliance in industrial encoders. Manufacturers will need to demonstrate compliance pathways and offer certified configurations to retain access to EU tenders and large OEM programs.
- Component scarcity and logistics risk: Semiconductor supply restrictions in mid‑2025 impacted availability of encoder‑grade sensor ICs, while container rerouting and geopolitical maritime disruptions increased lead times for modules from Asia. These events have shortened acceptable supplier‑qualification cycles and elevated inventory carrying costs as a deliberate hedging strategy.
- Cost headwinds: New tariff measures and localized labor cost increases have altered global sourcing equations. The net effect is a higher incentive to invest in product designs tolerant of alternate components and to relocate or dual‑source final assembly for key accounts.
Competitive landscape: what the vendor map tells you
We evaluated a representative set of incumbents and challengers—ranging from precision specialists to ruggedization experts and high‑volume producers. A few strategic observations emerge from our competitive analysis:
- Precision leaders (e.g., Heidenhain, Renishaw): These firms retain advantages in ultra‑high resolution and metrology markets where accuracy premium and integration with precision stages matter. Their R&D depth supports migration into additive‑manufacturing and semiconductor inspection niches.
- Rugged systems specialists (e.g., Pepperl+Fuchs, Dynapar, Leine & Linde): These vendors differentiate through IP ratings, shock/vibration tolerance, and marine/steel‑mill certifications. Their focus on heavy industrial environments makes them preferred suppliers for retrofit and brownfield projects.
- Safety and functional‑safety players (e.g., Kübler, Kubler Group, Baumer): Suppliers with SIL/PL certifications and redundant architectures are capturing a growing share of elevator drives, wind turbines, and critical‑process applications where safety drives procurement.
- Cost and integration challengers (e.g., Omron, Hopo Tech, Encoder Products Company): These companies compete on compact formats, connectivity (CANOpen, IO‑Link) and price‑performance for automation and robotics customers. Their modular designs are attractive to OEMs pursuing system‑level simplification.
- Specialist niche vendors (e.g., TR‑Electronic, Hohner Automation, US Digital, Global Encoder Systems, ifm efector): These firms exploit focused product lines—elevators, event technology, lift systems, and sensor‑integrated solutions—and can rapidly adjust to specific customer requirements or environmental demands.
Our vendor assessment uses multi‑dimensional scoring (technology, reliability, distribution, service, price) and maps each supplier against specific end‑market use cases. The complete vendor scorecards and supplier heatmaps are included in the full PW Consulting report, enabling procurement teams to run supplier tradeoff simulations tailored to their tolerance for lead‑time and substitution risk.
What the PW Consulting report delivers (practical content overview)
The study is built for boardrooms and product teams who need both strategic clarity and execution templates. Deliverables include:
- Detailed market sizing and demand‑by‑use‑case models (historical 2020–2025 and forecast 2026–2032) with scenario toggles for regulatory and supply‑chain stress events;
- Vendor scorecards, comparative RFP matrices, and certified compliance checklists to shorten supplier‑selection cycles;
- Five commercial scenarios (consolidation, premium differentiation, cost leadership, regional re‑shoring, and systems integration playbook) with P&L and ROI simulations for each;
- Technology adoption roadmaps that prioritize features (functional safety, non‑contact sensing, IO‑Link/fieldbus integration, embedded diagnostics) by value capture potential; and
- Supply‑chain stress tests and mitigation playbooks including dual‑sourcing templates, local assembly economics, and inventory policy adjustments tied to service‑level outcomes.
Note: This primer intentionally omits granular segmentation tables and proprietary vendor numeric rankings to preserve the value of the full report. The report contains the full, drillable segmentation data and model files necessary to run bespoke scenario analyses for your business.
Strategic implications and recommended actions for 2026
Based on our synthesis of market trends, regulation shifts, and supplier dynamics, PW Consulting recommends the following executive actions to be taken in 2026:
- For OEMs and machine builders: Prioritize encoder suppliers that offer certified safety variants and diagnostics. Negotiate multi‑year framework agreements with flexibility for alternative IC sources; include clauses for lead‑time compensation and change‑control cooperation.
- For encoder manufacturers: Accelerate modular platform strategies that allow swapping sensor IC families and communication modules with minimal re‑certification time. Invest selectively in IO‑Link and predictive health features that enable service and subscription revenue.
- For system integrators and service providers: Build retrofit packages that combine mechanical mounting kits with a software diagnostics subscription—this is a fast path to recurring revenue and differentiation in brownfield projects.
- For procurement and supply‑chain teams: Implement supplier‑risk scoring from the PW Consulting model and move to at least one qualified secondary source for critical components. Recalibrate inventory policy for strategic SKUs where lead‑time volatility is high.
- For investors and M&A strategists: Seek tuck‑ins that fill capability gaps (functional safety, IO‑Link stack, ruggedized enclosures) rather than broad geographic expansion. Consolidation is likely but success will hinge on technology and service integration rather than pure cost synergies.
Call to action
Heavy duty encoders are at the crossroads of mechanical robustness and software‑enabled value. The decisions you make in 2026—product architecture, supplier strategy, and compliance investments—will determine market position through the next PLM cycle. PW Consulting’s full Heavy Duty Encoders Market report delivers the segmentation, vendor scorecards, scenario models, and implementation templates you need to move from insight to business outcomes.
To access the full dataset, interactive models, and vendor heatmaps referenced here, please visit our full report page or contact PW Consulting’s advisory team to schedule a tailored briefing that aligns the study’s insights with your 2026 strategic plan.
For detailed analysis of this topic, please visit the official page: Heavy Duty Encoders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Greeting Cards Market Eyes USD 267.7M by 2032, 2.5% CAGR
By PW Consulting, 2026-07-12
Greeting Cards Market 2026: Strategic Preview for Executive Decision-Making
Executive snapshot
As companies prepare strategy and capital allocation for 2026, the greeting cards market presents a mix of steady demand, episodic innovation, and margin pressure. Our base-year analysis (2025) confirms a market that expanded from roughly USD 184 million in 2020 to approximately USD 224.6 million in 2025. The near-term picture includes a modest softening into 2026 (c. USD 223.3 million) followed by a return to growth under our central forecast: a 2.5% compound annual growth rate across the 2026–2032 horizon, driving headline revenues toward a late‑cycle peak before a slight normalization in the final forecast year.
Greeting Cards Market
Market concentration is meaningful but not prohibitive: the top three firms control a majority share, with the top five pushing that further — a structure that rewards scale, brand equity and channel control while still leaving pockets of opportunity for specialist players and fast followers.
Greeting Cards Market
Why this preview matters for 2026 planning
- Timing capital allocation. The combination of modest CAGR and short-term volatility means executives must prioritize flexible investments (test-and-scale) over heavy, irreversible CapEx.
- Balancing product portfolios. Legacy physical formats remain a core revenue base, but incremental premiumization, hybrid digital integrations and service layers are where margin expansion is most accessible.
- Managing cost and supply risk. Raw material and labor dynamics continue to shape manufacturing economics; operational agility and supplier diversification remain essential to protect margins.
- Commercial execution. With concentrated retail channels and evolving direct-to-consumer models, distribution strategy — retail partnerships, licensing, and digital-first channels — will determine who captures disproportionate share.
Market dynamics distilled for 2026 decisions
There are three interlocking dynamics that will define winners and laggards in 2026.
Greeting Cards Market
- Core market resilience with episodic inflection points. Consumers still buy greeting cards at scale (U.S. annual purchases number in the billions), which underpins stable baseline demand. However, growth is uneven: product cycles, holiday calendars, and adoption of hybrid gifting formats create episodic revenue spikes businesses must time for.
- Hybridization and premium formats as margin levers. Recent product launches that embed digital experiences into physical cards illustrate a clear commercial playbook: use the tangible asset as a carrier for continuing services (digital gift cards, AR experiences, subscription extensions). These hybrids lift average order value and create recurring revenue opportunities for brand owners and platform partners.
- Sustainability and provenance as procurement and brand differentiators. Buyers increasingly expect credible environmental claims and supply-chain transparency. Product and manufacturing strategies that deliver measurable improvements in material sourcing, recycled content, and production emissions are gaining commercial traction with both retail partners and end consumers.
Competitive landscape — what the market structure tells investors and operators
The market exhibits a mix of legacy incumbents, specialist artisans, and digitally enabled entrants. Key players illustrate distinct strategic archetypes:
- Large legacy brands (scale and channel control). Companies with deep retailer relationships and extensive product catalogs continue to dominate shelf presence and licensing agreements. Their scale allows for broad seasonal programs, significant marketing investments, and supply-chain leverage with paper and printing suppliers.
- Specialist manufacturers and artisans (product differentiation). Premium niche players that focus on design excellence — particularly in premium pop-up or high-craft formats — command higher per-unit pricing and open accessory cross-sell opportunities (gift packaging, bespoke inserts).
- Tech-enabled hybrids (distribution and convenience). Newer entrants that combine digital workflows, fulfillment-as-a-service, and hybrid mailing options capture value by simplifying personalization and logistics for consumers and corporate buyers.
Collectively, this structure rewards a portfolio approach: scale players should double down on channel optimization and new-service monetization, while specialists should protect margin through exclusive distribution, licensing, and premium brand positioning. Tech-enabled firms are natural acquisition candidates for incumbents seeking digital capabilities or for private equity looking to roll-up higher-growth, lower-capex businesses.
Recent inflection events and their strategic meanings
- Trade-show consolidation and channel visibility (mid‑2025). The relocation and expansion of a major greeting card expo into an integrated trade market has concentrated product discovery and accelerated buyer-supplier meetings. For 2026, exhibitors and retailers who invest in curated show experiences will capture licensing and seasonal lead time advantages.
- Embedding digital gifting into product lines (late‑2025). A notable incumbent introduced a card line that embeds a QR link to digital gift cards — a pragmatic acknowledgement that physical cards are increasingly vectors for broader payment and digital engagement services. This validates strategies that combine physical product excellence with low-friction digital monetization.
Operational playbook for 2026 (what to do now)
The following actions should be prioritized by revenue‑seeking teams and portfolio managers preparing budgets and pilots for 2026.
- Test hybrid propositions in one major seasonal program. Launch a controlled pilot pairing physical cards with a digital service (e.g., gift credentials, AR experiences, subscription entry) to quantify uplift in conversion, AOV, and repeat purchase.
- Optimize supply‑chain flexibility. Shorten lead times where possible, add dual-source capacity for critical paper and print inputs, and secure indexed pricing clauses to hedge commodity swings.
- Prioritize sustainability certifications that matter to B2B buyers. Target the top two retailer or corporate procurement requirements first — the commercial payback on gaining preferred‑supplier status is often faster than broad greenwashing efforts.
- Rebalance go-to-market mix. Increase investment in digital direct-to-consumer channels for personalization margins, while negotiating incremental in-store merchandising and licensing windows with retail partners to protect volumetric sales.
- Scan M&A and partnership windows. Identify tech-first firms or artisanal manufacturers that offer brand or capability adjacency — small, targeted acquisitions can accelerate capability uptake faster than organic builds.
What our full report delivers — practical modules for execution
This research is structured as an operator’s playbook rather than a purely academic study. Key deliverables include:
- Firm-level and channel-level market sizing and forecast (2020–2032) with scenario analysis and sensitivity tables tailored to commodity cost inputs and seasonal timing.
- Detailed go-to-market frameworks: retailer negotiation playbooks, D2C acquisition economics, personalization service models, and licensing valuation templates.
- Commercial diagnostics: SKU profitability matrices, assortment pruning guidance, and promotional cadence optimization based on consumer purchase behavior.
- Supply-chain assessment tools: raw material risk heatmaps, lead-time reduction roadmaps, and cost-to-serve analysis by fulfillment model.
- Innovation and product roadmaps: blueprint for hybrid card propositions, premiumization levers, and co‑brand/licensing strategies with IP owners.
- Competitive profiles and strategic options for the main market players, highlighting capability gaps, acquisition targets, and partnership match‑making.
- Risk matrix and mitigation playbook covering regulatory, commodity, and channel disruption scenarios.
Competitive highlights — select company implications
To illustrate how companies are already reacting:
- Scale incumbents are embedding digital payment and engagement layers into legacy SKUs to harvest recurring transaction value without abandoning shelf economics.
- Artisan and premium producers leverage craftsmanship as a barrier to entry; the strategic imperative for these players is to secure exclusive retail windows and premium licensing deals.
- Tech-enabled services focus on reducing friction — from design-to-mailing — and are natural partners for retailers seeking to offer end-to-end personalization without expanding in-house capabilities.
Profiles and URLs for leading names, including major incumbents and innovative challengers, are available in the report for benchmarking and outreach planning.
How to use this intelligence in board and investor conversations
- Frame 2026 budgets as options portfolios: define a small number of high-conviction scalable pilots and ring‑fence funds for M&A or partnerships to acquire digital capabilities.
- Set KPI targets that align with hybridization: conversion lift from QR-enabled or AR-enabled cards, incremental recurring revenue from digital add-ons, and margin improvement from supply-chain optimizations.
- Use concentration metrics to justify incremental trade or retail investments — where a few partners control distribution, targeted commercial concessions can deliver outsized share gains.
Next steps — where this preview leaves you
This introduction is a strategic primer designed to orient 2026 planning. The full PW Consulting Greeting Cards Market study contains the granular segment economics, pricing ladders, channel mixes, and company-level scorecards that commercial teams need to operationalize these recommendations. If you are preparing a 2026 plan — whether to defend share, to enter new formats, or to evaluate M&A — the detailed datasets and playbooks in the full report are the next step to convert strategic intent into measurable outcomes.
For access to the complete dataset, scenario models, and bespoke advisory support, consult the full report and our advisory team to translate these insights into a 90‑day action plan tailored to your organization’s risk tolerance and growth objectives.
For detailed analysis of this topic, please visit the official page: Greeting Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Amorphous Core Transformers Market to hit USD 7,973M by 2032 at 5.8% CAGR
By PW Consulting, 2026-07-12
Amorphous Core Transformers Market: Strategic Compass for 2026 Decision-Makers
As power systems decarbonize and utilities, industrial consumers, and policymakers tighten efficiency targets, amorphous core transformers have moved from niche technical curiosity to a strategic lever for reducing distribution losses. This briefing synthesizes the directional findings from PW Consulting’s new Amorphous Core Transformers Market study and explains how the report’s data and frameworks should shape corporate decisions in 2026. We surface the high-level trajectory, the structural dynamics that will determine winners and losers, and the practical choices that senior management teams must make now — while deliberately withholding detailed segment tables and proprietary forecasts that are available in the full study.
Amorphous Core Transformers Market
Executive snapshot: trajectory and scale
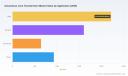
The market for amorphous core transformers has transitioned into a steady-growth phase. After moving from a lower base in 2020 to robust adoption through 2025, the market is projected to continue expanding at a mid-single-digit CAGR. Our consolidated view shows a compound annual growth rate of 5.8% across the 2026–2032 forecast window. In monetary terms, the market expanded materially during the 2020–2025 period and crossed the multi-billion-dollar threshold by the 2025 base year, with a projected rise toward the end of the forecast period as grid modernization, electrification, and minimum-efficiency regulations reinforce demand.
Amorphous Core Transformers Market
This trajectory is neither uniform nor unconditional: adoption will track regulatory push, utility capital cycles, ribbon-material availability, and the economics embedded in lifecycle cost assessments. The full report quantifies these linkages and models alternate regulatory and raw-material scenarios, which is essential reading for capital planners and procurement leads.
Amorphous Core Transformers Market
Why 2026 is a strategic inflection point
-
Regulatory cliffs and compliance windows are concentrating procurement and retrofit decisions within the next three to five years. Recent actions by major regulators have set efficiency baselines and transition timelines that will shape buying patterns and technology selection.
-
Raw-material concentration creates asymmetric supply risk. Amorphous ribbon production is concentrated at a few suppliers globally, which introduces potential bottlenecks and pricing volatility that could materially affect project economics and lead times.
-
Vendor positioning is crystallizing: global OEMs are integrating amorphous cores into broader digital and service propositions, while regional manufacturers and contract assemblers are exploiting local procurement policies and price-sensitive markets.
Regulatory and supply-side dynamics to weight into 2026 plans
-
Policy drivers. Recent regulatory moves — including finalized efficiency standards and regional ecodesign requirements — are elevating efficiency as a decisive specification in distribution transformer procurement. Some jurisdictions have already codified timelines extending into the early 2030s, shifting procurement from discretionary to mandatory in defined classes.
-
Regional standardization. Some national standards now require Tier-level efficiencies that materially favor amorphous core designs for specific transformer classes, creating concentrated demand where those standards apply.
-
Standards debate and design guidance. Ongoing industry standards discussions are refining how amorphous cores are modeled and tested. Expect further interoperability and testing specifications to emerge, which will change qualification timelines for new suppliers.
-
Supply concentration. The amorphous alloy ribbon supply base is narrow. Concentration at upstream suppliers means that buyers must treat ribbon availability and long-term purchase agreements as strategic inputs, not just procurement line items.
Competitive landscape: who is doing what
The competitive map is stratified across several archetypes, each with different strategic implications for partners, buyers, and investors:
-
Global integrated OEMs (for example, well-known multinational electrical and automation firms) are bundling amorphous core designs into integrated distribution portfolios and emphasizing digital monitoring and lifecycle services. Their scale, channel reach, and ability to integrate monitoring and grid-edge services make them preferred partners for large utilities pursuing turnkey modernization programmes.
-
Regional manufacturers and distribution specialists maintain competitive advantage through local certification, cost-competitive manufacturing footprints, and relationships with utilities and contractors. These players are often the first choice where procurement favors domestic content or rapid delivery.
-
Contract manufacturers and system assemblers are becoming more visible, offering low-cost assembly and customization for international clients. Their role expands as more OEMs pursue variable-capacity models and outsourcing to control capital intensity.
-
Niche technology vendors and specialists offer differentiated low-loss designs or application-specific products, frequently partnering with utilities for pilot projects and demonstrating compelling total-cost-of-ownership (TCO) economics in targeted applications.
Across the competitive set, market concentration is modest by industrial standards: the top three suppliers account for a minority share of global revenue, and the top five remain well below majority control. That structure favors competitive procurement and creates room for regional champions and technology upstarts to gain share, especially where local standards or procurement policies favor rapid deployment.
Practical implications and recommended actions for 2026
-
Procurement strategy: Move from price-per-unit sourcing to TCO-driven contracts. Incorporate loss-reduction metrics, availability of parts (notably ribbon supply), and digital monitoring into evaluation criteria. Where possible, negotiate multi-year supply agreements tied to ribbon availability to de-risk delivery timelines.
-
R&D and product planning: For OEMs, prioritize integration of condition monitoring and predictive maintenance services. For utilities, invest in pilot projects that quantify operational savings across multiple seasons and load profiles; these field data points materially change investment cases.
-
Supply-chain risk management: Formalize scenarios for ribbon shortage and supplier concentration. Evaluate co-investment or long-term off-take agreements with ribbon producers or consortium purchases for large fleet upgrades.
-
Regulatory engagement: Participate proactively in standards dialogues and national consultations. Shaping test procedures and compliance timelines can materially improve market access for newer designs and limit retroactive compliance costs.
-
Merger, acquisition, and partnership playbook: For investors and strategic buyers, opportunities exist to consolidate regional manufacturing or to acquire niche technology providers that offer measurable lifecycle benefits. Due diligence must include ribbon supply exposure and certifications against emerging test standards.
What the PW Consulting report delivers (practical, actionable contents)
-
A comprehensive historical baseline (2020–2025) and forward-looking forecast (2026–2032) with scenario analyses anchored to regulatory and supply-side regimes.
-
Demand drivers and elasticities: quantification of how utility procurement cycles, efficiency mandates, and electrification trajectories alter adoption curves under alternate cases.
-
Supply-chain mapping that highlights upstream concentration, lead-time sensitivities, and possible failure modes — paired with mitigation strategies and contract templates.
-
Company profiles and comparative capability assessment across global OEMs, regional manufacturers, assemblers, and niche technology providers — including go-to-market, certification posture, and service propositions.
-
Commercial playbook: procurement scorecards, TCO calculators, pilot design templates, and procurement negotiation levers tailored for utilities, large industrials, and EPCs.
-
Risk register and decision-frameworks that allow executives to convert market signals into capital-allocation decisions with clear trigger points and downside hedges.
Recent market signals that matter for near-term execution
-
Exhibitions and industry showcases in 2026 indicate persistent activity in both developed and emerging markets; suppliers are using trade shows to demonstrate new core technologies and application case studies.
-
Press activity from manufacturers highlights incremental technical advances and regional manufacturing scale-ups, signaling that competitive intensity will increase on cost as well as on efficiency performance.
-
Standards bodies and national regulators continue to recalibrate requirements. These discussions are actionable levers: companies that engage early can shorten qualification timelines and shape test methods to support broader adoption.
How to use this intelligence in your 2026 planning cycle
Treat amorphous-core strategy as both an engineering and a commercial problem. Engineering teams should quantify fleet-level loss reductions and integrate monitoring to prove value in the field. Commercial and procurement teams must translate those engineering benefits into contract terms and supply agreements that lock in ribbon supply and delivery. Executives should prioritize three near-term moves: (1) run focused pilots with measurable KPIs and clear escalation clauses, (2) secure strategic supply lines for ribbon and core components, and (3) establish regulatory engagement to anticipate rule-making that could accelerate or delay large procurement waves.
PW Consulting’s full report provides the segment-level forecasts, vendor benchmarking matrices, and model-ready TCO tools that will let teams convert these insights into executable 2026 roadmaps. This executive preview is intentionally high-level — the detailed segmentation, scenario outputs, and full set of vendor profiles remain behind the report boundary to preserve the actionable intelligence that will drive procurement and investment decisions.
For procurement leaders, technology strategists, and investors finalizing plans in 2026, the combination of modest concentration among incumbents, concentrated upstream supply, and tightening regulatory drivers creates both risk and opportunity. The key to capturing value will be disciplined scenario planning, early supplier engagement, and rigorous lifecycle accounting — all core deliverables contained in the PW Consulting Amorphous Core Transformers Market report.
For detailed analysis of this topic, please visit the official page: Amorphous Core Transformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Auto Dimming Mirror Market Poised for 5.27% CAGR Through 2032
By PW Consulting, 2026-07-12
Automotive Auto Dimming Mirror Market: Strategic Briefing for 2026 Decision-Makers
This briefing synthesizes PW Consulting’s latest industry-grade research on the Automotive Auto Dimming Mirror market and explains its strategic value for corporate decision-making in 2026. It is written to demonstrate the analytical depth and practical orientation of our full report while deliberately preserving the detailed subsegment figures and scenario tables that operational teams will need to execute plans—those datasets and model downloads are reserved for the full report.
Automotive Auto Dimming Mirror Market
Market Trajectory and What It Means for 2026
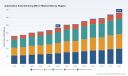
After a steady recovery and technology-led expansion during 2020–2025, the total global auto dimming mirror market reached an estimated USD 233.0 Million (base year 2025, historical period 2020–2025). Momentum continues into the forecast horizon (2026–2032), driven by ADAS integration, premium vehicle features, and aftermarket modernization. Our modeling indicates a compound annual growth rate (CAGR) of 5.27% for the forecast period, taking the market from an expected USD 252.96 Million in 2026 to roughly USD 331.6 Million by 2032 (USD, revenue unit: Million).
Automotive Auto Dimming Mirror Market
For executives setting 2026 strategy, these macro figures imply three practical conclusions: (1) the market is neither nascent nor saturated—there is room for both product innovation and share gains; (2) steady growth supports multi-year investments (R&D, tooling, and partnerships) but requires disciplined capital allocation; and (3) winners will be those who convert technology advantage into scalable, cost-competitive modules that meet OEM and aftermarket certification regimes.
Automotive Auto Dimming Mirror Market
Why This Research Is Decision-Relevant in 2026
- Timing of investment decisions: With growth projected to accelerate modestly after 2026, companies that commit to platform-level mirror architectures in 2026 can leverage supplier lead times and capture design wins in 2027–2029 model cycles.
- Technology roadmap alignment: The research allocates explicit scenarios for electrochromic layers, sensor fusion, and camera-mirror convergence—allowing product teams to prioritize development sprints against ROI thresholds.
- Supply-chain & sourcing strategy: Raw material cost volatility for electrochromic films and precision sensors is a material risk. Our analysis provides mitigation levers—dual sourcing, nearshoring & long-term offtake structures—that procurement leaders can operationalize in 2026.
- Regulatory and compliance positioning: Stricter ADAS and safety standards in major markets create both barriers to entry and differentiation opportunities; being certified early reduces homologation costs for subsequent vehicle platforms.
What the Full Report Delivers (Practical, Executable Content)
PW Consulting’s full market study is structured to be immediately actionable for product, commercial, and corporate strategy teams. Highlights include:
- Transparent market-sizing methodology and downloadable model (base year 2025, forecast 2026–2032) with scenario toggles for adoption rates, component-cost inflation, and ADAS penetration.
- Competitive benchmarking with supplier profiles, capability maps, and technology-readiness matrices for electrochromic, prismatic, and hybrid mirror systems.
- Supply-chain heatmaps identifying single-source vulnerabilities for electrochromic layers, rare materials, and sensor subsystems—together with recommended sourcing strategies and contingency plans.
- Go-to-market playbooks for OEM and aftermarket channels, including pricing elasticity tests, retrofit economics, and certification timelines.
- Investment cases and sensitivity analyses for M&A, joint ventures, and greenfield manufacturing—with a practical checklist for integration and synergies capture.
- Risk register and regulatory tracker that map near-term legislative drivers and homologation milestones across major automotive markets.
To preserve the strategic value of proprietary subsegment outputs, our public briefing intentionally excludes granular regional splits and application-level dollar figures—these are provided in the full deliverable alongside model access.
Competitive Landscape: Who Matters and How
The auto dimming mirror market shows relatively low concentration by revenue (CR3 ~25%, CR5 ~30%), which points to a competitive field with meaningful opportunity for consolidation and differentiation. Below is a concise interpretation of the positioning and trend lines for leading players identified in our research.
- Gentex Corporation (Zeeland, MI, USA) — Market leader in electrochromic rearview systems with deep OEM relationships and sensor integration expertise. Recent product activity (e.g., a slim-profile carbon-fiber auto-dimming mirror launched in late 2025) signals an increased strategic emphasis on premium aftermarket and lifestyle channels. Expect continued focus on design wins that combine lightweight materials with advanced control electronics.
- Magna International Inc. (Aurora, Canada) — Strong at integrating mirrors with camera systems and ADAS functions. Magna’s scale and systems integration capabilities make it a go-to partner for OEMs seeking multifunctional mirror modules that act as part of a vehicle’s sensor suite.
- Ficosa International S.A. (Barcelona, Spain) — Competes on lightweight electrochromic solutions optimized for EV and premium segments. Ficosa’s European footprint and supplier relationships align well with stringent EU safety standards.
- Tokai Rika & Murakami Corporation (Japan) — Both are highly respected for safety-oriented components and sensor integration tailored to Japanese OEM requirements; they emphasize reliability and precise quality control.
- Samvardhana Motherson Reflectec Group (Mumbai, India) — Offers end-to-end mirror systems and is positioned to capture both premium and high-volume OEM programs as Indian and export markets expand.
- Konview Electronics (Shenzhen, China) — Cost-competitive electronic mirror modules with connectivity features targeted at Asian markets; important to monitor for rapid price-based disruption and export dynamics.
- FLABEG (Germany) — Focused on electrochromic glass and European OEM relationships; technological depth in glass substrates and electrochromic coatings.
- Honda Lock & CIPA USA — Specialist suppliers with strong OEM ties (Honda group for Honda Lock, aftermarket focus for CIPA), representing the two strategic approaches to the market: captive OEM supply and aftermarket/replacement plays.
For a procurement or corporate development team, the competitive map suggests three tactical pathways in 2026: deepen strategic partnerships with Tier-1 integrators; invest selectively in EC material IP or vertical integration; or pursue bolt-on acquisitions to rapidly close capability gaps—each pathway is accompanied by modeled returns in the full report.
Dynamics, Risks, and Industry “Noise” to Watch in 2026
- Raw material & component cost pressure: The cost of electrochromic layers and precision sensors continues to be the dominant manufacturing expense driver. This restricts adoption in lower-tier segments unless cost-reduction programs are implemented.
- Supply-chain diversification: Trade tensions and sourcing risk are prompting automotive suppliers to diversify electrochromic and sensor suppliers. The full report maps alternative supply nodes and lead-time implications for 2026 purchasing cycles.
- Regulatory acceleration: Tighter safety regulations and ADAS integration mandates in several jurisdictions are increasing OEM uptake of multifunctional mirror modules as homologation pathways simplify integrated sensor solutions.
- Regional standards and OEM preferences: German and Asian OEM requirements are shaping product specs—European safety requirements and Asian quality expectations create distinct regional product development constraints.
These dynamics create both upside (accelerated adoption driven by regulation and ADAS) and downside (material costs, certification timelines, supplier concentration). Our report quantifies these trade-offs under multiple scenarios so that strategists can align budgets and R&D roadmaps to realistic timelines.
Concrete Strategic Actions for 2026
- Prioritize modular mirror platforms that decouple electrochromic glass, sensor modules, and software—this reduces BOM volatility and accelerates variant management across OEM programs.
- Initiate supplier hedging and strategic offtakes for electrochromic materials and sensor ICs with a two-tier sourcing strategy to manage cost and continuity risk.
- Accelerate homologation programs for targeted OEMs whose product cycles align with 2027–2028 launches; start qualification work in 2026 to secure early design wins.
- Evaluate aftermarket and retrofit offerings where margin profiles are favorable—premium aftermarket launches (as demonstrated by recent product moves) can serve both revenue and brand objectives while amortizing R&D.
- Use the market’s relatively low concentration to explore bolt-on M&A or JV opportunities that deliver immediate capability extension in sensor fusion or glass chemistry IP.
Next Steps and How to Access the Full Intelligence
This briefing is a strategic “trailer” designed to guide 2026 planning with high-confidence, macro-level insights while preserving the detailed subsegment analytics that operational teams require. PW Consulting’s full Automotive Auto Dimming Mirror Market report includes the complete regional and application breakouts, downloadable financial models (base year 2025; forecast period 2026–2032), supplier scorecards, and scenario-based ROI tables.
For companies preparing budgets, R&D roadmaps, or M&A pipelines in 2026, securing the full report removes the guesswork on supply-chain lead times, certification milestones, and segment-level profitability—enabling precise, executable plans. Contact PW Consulting to obtain the report and tailored advisory support for embedding these findings into your 2026 strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Automotive Auto Dimming Mirror Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wine Aerator Market to Reach USD 408M by 2032 at 4.95% CAGR
By PW Consulting, 2026-07-12
Wine Aerator Market 2026: Strategic Imperatives for Leadership
As companies prepare budgets, product roadmaps, and channel plays for 2026, the wine aerator market is transitioning from a niche appliance category into a maturating consumer-lifestyle segment with clear windows for premiumization, bundling, and channel-led expansion. PW Consulting’s latest market study (base year: 2025) synthesizes five years of historical performance (2020–2025) with a forward-looking forecast (2026–2032) to equip executives with the evidence base required to make confident, risk-calibrated decisions.
Wine Aerator Market
Executive snapshot
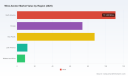
The global wine aerator market recorded steady expansion through the early 2020s, rising from USD 232.1 Million in 2020 to USD 293.0 Million in 2025. Our forecast anticipates continued growth through the 2026–2032 horizon, with a compound annual growth rate (CAGR) of approximately 4.95% and an expected market size approaching USD 408.0 Million by 2032. These headline figures reflect both durable consumer demand for at-home wine enhancement and accelerating product-innovation cycles that include smart, integrated, and premiumized solutions.
Wine Aerator Market
Why this study matters for 2026 strategic planning
-
Time-sensitive resource allocation: The market’s mid-single-digit CAGR transforms “incremental” decisions (SKU investments, packaging refreshes, channel pilots) into meaningful revenue outcomes when compounded across product lines and geographies.
Wine Aerator Market -
Portfolio prioritization: Distinct product archetypes (manual pourers, decanter-oriented systems, and electric/automated devices) are exhibiting divergent margin profiles and distribution dynamics — forcing trade-offs between high-volume, low-price skus and lower-volume, high-margin premium devices.
-
Channel optimization: Retail, direct-to-consumer, subscription, and commercial (on-trade) channels each require bespoke commercial playbooks — from packaging and merchandising to after‑sale warranties and service models.
Market trajectory and what the numbers imply
The meaningful growth from USD 293.0 Million in 2025 to an anticipated USD 305.71 Million in 2026 is indicative of both continuing consumer interest and the immediate impact of new product introductions and marketing campaigns. When taken across the full 2026–2032 forecast window, a near-5% CAGR signals a market that rewards steady investment rather than speculative, high-risk bets. Companies that plan for multi-year programs — combining product development, distribution ramp, and trade partnerships — will extract disproportionate value from this predictable growth path.
Key dynamics shaping the sector
-
Consumption and consumer behavior: Broader wine consumption trends remain foundational. For example, robust national-level consumption figures in leading markets continue to underpin at-home accessory demand; where consumption holds or grows, premium accessory penetration tends to accelerate.
-
Material and input cost pressure: Stainless steel is the dominant material used across many aerator designs. Fluctuations in raw-material pricing and supply reliability materially affect unit economics for both manual and electric solutions. Procurement strategies (forward buys, alloy substitutions, and alternative finishes) should be modeled in product-level margin scenarios.
-
Regulatory and customs considerations: Classification and tariff exposure matter for companies operating cross-border. A recent ruling classifying a specific electronic aerator model under an HTSUS code highlights the need to align product design and customs strategy early in development to avoid unexpected landed-cost increases.
-
Certification and trust signals: CE and ISO certifications for premium pourer spouts and electrical safety offer tangible marketing and channel advantages in regulated markets and premium retail channels. Certification leads to both higher price realization and reduced friction with large retailers and hospitality chains.
Competitive landscape — what incumbents and challengers reveal
The market remains relatively fragmented with a mix of heritage brands, direct-to-consumer innovators, and value-oriented entrants. This structure produces opportunity for both organic growth and inorganic consolidation. Below are strategic impressions of core participants featured in our research:
-
Vinturi (Lincolnshire, IL) — A recognizable legacy brand, Vinturi’s patented manual aerators and accessory ecosystem drive broad consumer awareness. Their brand equity makes them a natural partner for lifestyle collaborations and white‑label partnerships within larger housewares portfolios.
-
Aervana — Positioned at the premium electric aerator segment with a one-touch, tap-like experience, Aervana demonstrates how product design and convenience can command higher ASPs. Their model is instructive for firms pursuing hospitality and on-premise premiumization.
-
Zazzol — Multi-stage decanter designs target wine enthusiasts who value ceremony and sensory nuance. These models highlight how feature differentiation (multi-stage aeration, integrated filtration) can create category premiumization.
-
Coravin — Best-known for wine preservation, Coravin’s extension into integrated aeration systems shows the value of platform strategies: adjacent feature integration can increase wallet share among existing users.
-
Rabbit — Offers both manual and electric models with professional pourer variants. Rabbit’s multi-channel approach (mass retail, e‑commerce, and distributor networks) provides a template for scaling without sacrificing channel coverage.
-
Riedel — As a glassware specialist, Riedel underscores a non‑device route to aeration value — product pairing (glass + aerator), co-marketing, and experiential retailing in sommelier circles.
-
Final Touch, Uberstar, TenTen Labs — These players span premium design-led models, value options, and tasting-optimized pourers respectively; collectively they exemplify the spectrum of consumer price points and the importance of clear positioning.
Recent independent reviews and media placements (early 2026 editorial roundups and product reviews) have amplified consumer awareness and accelerated trial — a reminder that positive editorial momentum can influence retailer buy-in and amplify DTC conversion rates. Likewise, corporate reporting that references active brand performance in houseware portfolios points to continued retail consolidation interest.
What PW Consulting’s full report delivers (operationally actionable)
-
Validated market sizing and multi-scenario forecasts (base year 2025; forecast 2026–2032) with sensitivity analyses tied to volume, ASP, and substitution effects.
-
Channel and route-to-market playbooks that prioritize retailer segmentation, DTC economics, and hospitality partnerships while modeling promotional elasticity and inventory turns.
-
Product and pricing blueprints that map margin curves across manual, decanter, and electric archetypes, plus guidance on certification and compliance pathways to accelerate market entry.
-
Supply-chain diagnostics: component risk matrices, sourcing alternatives (including stainless-steel strategies), cost-down levers, and lead-time mitigation approaches for 2026 procurement cycles.
-
Innovation and NPD roadmaps: feature prioritization frameworks, Bundling and subscription concepts, and experiments for premiumization that maintain gross-margin integrity.
-
M&A and partnership candidates: a shortlist of strategic targets and partnership frameworks aligned to horizontal and vertical expansion plays (manufacturing scale, design IP, or distribution reach).
-
Commercial KPIs and implementation trackers: retailer scorecards, marketing test templates, and an 18-month playbook to convert pilot results into full-scale rollouts.
Strategic plays for 2026 — recommended priorities
-
Prioritize modular product architectures. Designing common platforms that can be configured into manual, hybrid, or electric SKUs reduces engineering cost and accelerates scale deployment across price points.
-
Invest in certification and safety early for electrified SKUs to reduce time-to-shelf in Europe and North America and to command premium placement in hospitality accounts.
-
Use editorial and influencer momentum deliberately. Coordinate product launches with targeted editorial outreach and sommelier endorsements to convert awareness into trial and to support international rollouts.
-
Hedge material exposure. Lock critical stainless-steel components through forward contracts or diversified suppliers and explore alternative finishes that preserve perceived quality while improving unit economics.
-
Develop hospitality-first propositions. The on-premise channel remains a high-leverage route for premium devices; pilots with hospitality groups can accelerate adoption and create visible social proof.
-
Model M&A opportunistically. Fragmentation creates chances for tuck-ins that add distribution, manufacturing, or brand equity — but disciplined valuation and integration playbooks are essential to capture synergies.
Methodology and the “trailer” approach
Our research synthesizes primary interviews with category buyers, engineering assessments, supply-chain costing, and public financials alongside a proprietary survey of consumer preferences. The report provides deep subsegment diagnostics, regional and application-level performance, and competitor scorecards — deliberately held back from this introduction to preserve the strategic value of the full deliverable.
For decision-makers preparing FY26 plans: the topline trajectory — from USD 293.0 Million in 2025 through an expected near-5% CAGR to roughly USD 408.0 Million by 2032 — frames a market where steady, well-executed investments compound meaningfully. The difference between market-share growth and margin erosion will be made in product architecture, certification planning, and channel orchestration — all covered with operational templates in the full PW Consulting report.
Next step
PW Consulting’s full Wine Aerator Market study contains the granular segmentation, regional and application breakouts, and competitive scorecards required to execute on the 2026 plays summarized above. Contact PW Consulting to access the complete report and the accompanying implementation toolkit that converts insight into measurable 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Wine Aerator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tire Market to Reach USD 215.0 Million by 2032 at 4.2% CAGR
By PW Consulting, 2026-07-12
Tire Market 2026: Strategic Outlook and Decision Playbook — A Preview
Executive snapshot
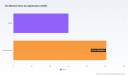
As companies prepare strategic plans for 2026, the tire market is entering a period defined by steady growth, concentrated competition and episodic volatility. Our PW Consulting Tire Market study — anchored on a 2025 base year and covering historical performance from 2020–2025 with a forecast through 2032 — projects a compound annual growth rate (CAGR) of 4.2% over the forecast window. The total market expanded from the low-130s (USD Million) in 2020 to approximately USD 161.3 Million in 2025 and is projected to reach roughly USD 215.0 Million by 2032.
Tire Market
This briefing outlines why that growth trajectory matters for 2026 corporate decisions, what practical intelligence the full report provides, and how leading manufacturers and suppliers are already positioning for the next phase of industry evolution. The narrative intentionally highlights strategic levers and operational implications while withholding the granular regional and application-level splits available in the full PW Consulting dossier—our “preview” approach is designed to inform decisions and motivate access to the complete dataset and playbooks.
Tire Market
Why 2026 is a pivot year for tire strategies
-
Growth with constraint: The market’s mid-single-digit CAGR masks important realities: demand growth is consistent but not explosive, meaning revenue expansion will increasingly be driven by share gains, product premiumization, and cost productivity rather than broad market expansion alone.
Tire Market -
Concentration creates opportunity: The market concentration metrics indicate that the top three and top five firms command a meaningful but not absolute portion of the market. This concentration encourages both defensive strategies among incumbents and targeted acquisition or niche specialization for challengers.
-
Input volatility and policy risk: Raw material swings and trade policy moves are introducing asymmetric cost and access pressures across supply chains. Strategic decisions in 2026 must therefore marry product roadmaps with supplier diversity, hedging and near-term scenario plans.
What the PW Consulting report gives you — practical content for 2026 action
Our report is built for executives and deal teams who need both evidence-based insight and operationally useful outputs. Key deliverables include:
-
Market baseline and forward scenarios: A transparent historical reconciliation (2020–2025) and three demand scenarios (conservative, base, upside) through 2032, enabling sensitivity testing of price, raw-material shock and regulation-driven outcomes.
-
Revenue and margin playbooks: Detailed modules that model pricing elasticity, material-cost pass-through, and gross-margin levers by product family—designed for CFOs and commercial leaders to stress-test 2026 P&L plans.
-
Go-to-market and channel strategies: Tactical guidance for OEM and replacement channels, including SKU rationalization frameworks, aftermarket promotion strategies, and a retailer-partner segmentation to prioritize distribution investments.
-
Supply-chain resilience mapping: Supplier criticality matrices, alternative-sourcing playbooks, and inventory optimization templates to reduce exposure to raw-material and logistics disruption.
-
M&A and portfolio playbook: A proprietary target-scoring model calibrated to market concentration dynamics, technology fit (e.g., EV, run-flat, sustainable compounds), and EBITDA conversion potential—supporting 2026 acquisition or divestiture decisions.
-
Competitive intelligence dossiers: Compressed, actionable profiles on leading manufacturers and emergent challengers that map product innovation, manufacturing footprints, and likely strategic moves over the next 18–36 months.
Market dynamics to factor into 2026 planning
Several cross-cutting dynamics will shape winners and losers in 2026. PW Consulting’s analysis synthesizes macro drivers into decision-quality implications:
-
Raw-material volatility: Natural rubber experienced meaningful fluctuations across 2025–2026, with a notable recovery into early 2026 after a mid‑2025 dip. This pattern underscores the need for dynamic material-cost scenarios and active procurement strategies (e.g., index-linked purchasing, forward contracts, and diversified regional sourcing).
-
Regulatory and trade uncertainty: Recent measures—ranging from tariff actions to multi-year reviews of import rules—are increasing the regulatory risk premium for cross-border sourcing and aftermarket supply. Manufacturers should build tariff-sensitive routing options and local capacity contingencies into capital planning for 2026.
-
Product innovation and EV transition: New product launches in 2025–2026 from multiple global manufacturers demonstrate continued investment into EV-tuned, low-rolling-resistance and all-terrain lines. For OEM suppliers, timing product qualifications and aligning performance claims with vehicle OEMs will be a competitive differentiator.
-
Channel and aftermarket dynamics: Replacement demand continues to be a critical revenue stabilizer. The interplay between OEM fitment trends and replacement-market behavior will shape inventory strategies and promotional spend allocations in 2026.
Competitive landscape — who’s shaping the market
The report includes focused competitive profiles of the industry’s most consequential players. These summaries capture strategic posture, core strengths and likely 2026 moves:
-
Michelin Group (Clermont‑Ferrand, France) — Known for premium passenger, SUV and EV tire programs and a strong focus on sustainable materials and durability innovations.
-
Bridgestone Corporation (Tokyo, Japan) — A diversified manufacturer with prominent premium and commercial lines, continuing product refreshes in high-performance segments.
-
Continental AG (Hannover, Germany) — Targeting high-performance and all-season segments with a heavy emphasis on engineering-led differentiation.
-
The Goodyear Tire & Rubber Company (Akron, USA) — Broad consumer and commercial portfolio with recent expansion into all-terrain and EV-focused models.
-
Pirelli (Milan, Italy) — A specialist in high-performance and premium vehicle tires, closely aligned with luxury and EV OEMs.
-
Sumitomo, Yokohama, Hankook, Toyo and others — These firms are active in premium and specialty segments and increasingly competing on global product programs, regional capacity investments and aftermarket channel plays.
Recent product launches across the industry—spanning premium POTENZA and P Zero refreshes, Michelin’s fuel-saving ranges, and Goodyear’s all-terrain EV-compatible lines—signal a market where incremental product advantage and platform fit will influence 2026 wins.
Strategic implications and recommended 2026 actions
Translating market trends into decisions falls into six priority actions for leadership teams:
-
Embed scenario-driven planning into budgets: Use the report’s demand scenarios to set guardrails on capex, pricing and inventory plans so leadership can pivot quickly if raw-material or trade shocks materialize.
-
Prioritize product investment by margin and channel: Redirect R&D and marketing spend toward product lines and fitments that generate superior margin and align with OEM EV roadmaps or higher-margin aftermarket niches.
-
Operationalize supplier and logistic diversification: Establish near-term tactical options (alternate suppliers, hedges) and longer-term strategic shifts (regional capacity adjustments) to reduce single-point risk.
-
Accelerate go‑to‑market experiments: Pilot differentiated aftermarket propositions and digital sales channels in prioritized regions or customer segments to accelerate share gains without broad rollout risk.
-
Use concentration metrics to guide M&A: With top players holding significant market share yet meaningful fragmentation remaining, targeted acquisitions—especially in technology or regional aftermarket platforms—can be accretive if integrated with disciplined synergies.
-
Monitor policy levers continuously: Design a regulatory early-warning dashboard tied to procurement and route-to-market triggers so trade or tariff changes translate into immediate operational responses.
How PW Consulting supports execution
PW Consulting’s Tire Market study is purpose-built for decision-makers who need to move from insight to execution in 2026. Beyond the data and analysis, we supply implementation-ready assets: scenario models, procurement negotiation playbooks, a prioritized M&A target list, and competitive dossiers mapped to likely strategic moves.
We intentionally keep this preview high-level: the full study contains the regional, product and application-level breakdowns, detailed price and margin models, and executable playbooks that companies rely on when they commit capital or choose growth paths. For boards, strategy teams, CFOs and business-unit leaders preparing 2026 plans, the full PW Consulting report turns the market’s steady growth and episodic disruption into concrete pathways for revenue, margin and resilience.
Next steps
For access to the comprehensive dataset, scenario tools and tailored briefings, contact PW Consulting to arrange a demo and executive workshop. Use the preview insight above to prioritize which modules—pricing, supply chain, M&A or go‑to‑market—you want to accelerate as you finalize 2026 budgets and strategic initiatives.
For detailed analysis of this topic, please visit the official page: Tire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hose Clamps Market 2026: Strategic Imperatives for Decisions That Matter
As PW Consulting’s Senior Industry Analyst, I present a concise, decision-focused briefing to orient executives who must translate the Hose Clamps market’s technical nuance into near-term strategic moves. This introduction distills macro trends, competitive dynamics, regulatory inflections, and practical playbooks that will shape purchasing, sourcing, product, and M&A decisions in 2026 — while preserving the detailed segment-level intelligence available in our full report.
Hose Clamps Market
Why this market matters in 2026
Hose clamps are deceptively simple components embedded across transportation, industrial equipment, water and wastewater systems, HVAC, marine, and general industrial segments. Yet their performance, specification compliance, and cost position materially influence OEM product reliability, aftermarket service economics, and regulatory risk exposure. The market’s macro trajectory underscores this strategic significance: after a contraction from a 2020 high, total market revenue stabilized around the mid-2020s and, per our modeling, is positioned to resume growth across the 2026–2032 forecast window at a compound annual growth rate of approximately 4.5%. Our base-year analysis (2025) anchors that view and shows a path from near-term stabilization to steady expansion, reaching an estimated market size in the early 2030s that reverses the prior downturn.
Hose Clamps Market
Top-line dynamics shaping strategy
- Cyclical recovery and structural demand: The market’s recent trough reflected a confluence of supply-chain disruptions, end-market softness, and raw-material pressure. From 2026 onward, demand drivers — automotive production rebounding, infrastructure upgrades, and increased regulatory scrutiny on component safety — support recovery and growth.
- Raw-material volatility as a margin lever: Nickel and stainless-steel pricing volatility has shown a direct impact on manufacturers’ margins and distributor pricing strategies. This dynamic is accelerating technical and commercial interest in material substitution (for example, lower-alloy stainless grades where acceptable) and in procurement strategies that emphasize price-risk sharing and hedging.
- Concentration and competitive balance: The market exhibits moderate concentration: top-tier firms collectively hold a meaningful share, while a long tail of specialized regional players serves niche applications. This structure rewards scale in production efficiency and certification capability, but also leaves room for targeted innovation and differentiation.
What the full report provides (practical, actionable content)
Our Hose Clamps Market study goes beyond headline sizing to equip commercial and supply-chain teams with operational playbooks. Key deliverables include:
Hose Clamps Market
- Robust market-sizing and trend models (historical 2020–2025 and forecast 2026–2032) with scenario runs that quantify sensitivity to raw-material prices, automotive production cycles, and regulatory shocks.
- Segment-level maps by type, application, and region (presented with transparent methodology) to support prioritization of sales and capex deployment — note: this introduction intentionally omits the granular splits to preserve the value of the full dataset.
- Supply-chain heat maps highlighting single-source risks, lead-time drivers, and finishing/treatment bottlenecks (passivation, plating, high-torque forming capabilities).
- A regulatory and standards dossier detailing material, design, and manufacturing compliance obligations (including machine crimp vs. adjustable clamp rules, marine and naval constraints, and import/export classification impacts).
- Commercial playbooks: pricing strategy templates, long-term contract clauses to manage commodity volatility, OEM qualification roadmaps, and aftermarket channel strategies.
- M&A and partnership screening: acquisition targets by capability (e.g., constant-tension technology, multi-crimp tooling), synergies, and integration risk assessments.
- Supplier negotiation checklists and a procurement toolkit that includes sample hedging strategies for stainless inputs and clause language for pass-through adjustments.
Competitive landscape — who to watch and why
The competitive field blends global platform players with specialized innovators. The following firm-level observations are drawn from primary research, company disclosures, and trade activity:
- Clampco Products (United States): A strength in engineered clamps and heavy-duty applications; recent Nadcap welding accreditation and approval under the US/Canada Joint Certification Program position it well for defense and high-spec industrial OEM opportunities. Their playbook emphasizes certification-driven differentiation and nearshoring for critical supply.
- YDS EVEREON (Taiwan): A high-volume OEM/ODM with a broad product set and active international trade-show cadence. Their participation at multiple 2026 events signals an offensive push into premium and customized clamp segments, leveraging cost-competitive manufacturing and design flexibility for automotive and aftermarket customers.
- NORMA Group (Germany): A platform player with a diversified clamp portfolio and deep OEM relationships; strong in systems-level partnerships and module supply to global vehicle platforms.
- Oetiker Group (Switzerland): Historically strong in ear clamps and low-profile solutions; their engineering heritage is an asset in regulated markets where dimensional control and fatigue performance matter.
- Murray Corporation and Ideal Clamp Products (United States): Both bring custom-engineering capabilities and established Tier-1 OEM credentials; their strength is in co-development for constant-tension and specialty clamp solutions.
- Mubea (Germany): Focused on constant-force and spring band technology, particularly suited to dynamic sealing applications in automotive powertrains and emissions systems.
Collectively, the market’s top firms account for a non-trivial share of revenue, but they differ in go-to-market focus — some emphasize certifiable, mission-critical supply while others compete on cost and breadth. This differentiation creates white space for targeted entrants and for incumbent players to lock in value through certification, aftermarket service offerings, and integrated system solutions.
Regulatory and standards landscape — risks that require operational fixes
- New and evolving standards are creating both constraint and opportunity. For example, marine and small-craft LPG system requirements now explicitly mandate corrosion-resistant materials for certain hose connections — a procurement and product-design issue for both OEMs and aftermarket suppliers.
- Some jurisdictions impose strict limits on adjustable clamps in food-service and special-event contexts, effectively favoring machine-crimped solutions and opening revenue opportunities for compliant suppliers.
- In high-assurance defense and naval applications, hose clamps are explicitly excluded from use on pressurized hoses under certain standards; this drives demand for alternative retention systems and creates specification-led procurement cycles.
- Harmonized tariff classifications and export-controls are stable enough to permit predictable cross-border sourcing, but buyers must keep a close watch on origin rules and any material-specific trade measures that could affect stainless-steel inputs.
Strategic recommendations for 2026 decisions
For executives deciding on sourcing, product development, pricing, and inorganic growth in 2026, our advice is pragmatic and prioritized:
- Hedge material risk and introduce graded-material SKUs: Negotiate multi-year supply arrangements with price adjustment mechanisms and explore certified use-cases for lower-cost stainless grades where regulatory and performance criteria permit.
- Invest in certification and production capabilities: Attainment of accredited welding and defense certifications materially expands addressable opportunities. If rapid market access is needed, consider contract manufacturing partnerships with certified suppliers rather than greenfield builds.
- Differentiate through systems thinking: Move up the value chain by bundling clamps with hoses, clamps-as-a-service for critical installations, or offering traceability/QR-coded parts for regulated industries. OEMs increasingly favor suppliers who reduce their qualification and logistics burden.
- Rethink pricing and contract terms: Embed commodity pass-through clauses and volume-flex mechanisms into OEM agreements. For distribution, package value-added services (kitting, just-in-time delivery) to protect margin against pure price competition.
- Pursue targeted M&A and technology partnerships: Bolt-on acquisitions that add constant-tension technologies, machine-crimp assets, or surface-treatment capacity can accelerate time-to-market and lock in OEM approvals.
- Prepare for regulatory-driven product shifts: Where standards effectively ban adjustable clamps or require machine crimping, proactively adapt lines and sales channels to avoid sudden disqualification from spec-driven projects.
How PW Consulting helps — what’s behind the paywall
This article is intentionally crafted as a strategic “trailer”: it reveals the analytical framing, risks, and recommended decision levers while withholding the detailed segmentation tables, regional/application percentage splits, and granular price curves that underpin our recommendations. The full report and accompanying datasets provide the following proprietary assets to convert insight into action:
- Complete segment-by-region and type-by-application demand matrices with adjustable scenario toggles.
- Supplier heat maps and single-sourced component risk registries with mitigation options ranked by cost and lead time impact.
- Contract clause templates, procurement negotiation playbooks, and a sample OEM qualification timeline tied to certification milestones.
- M&A target shortlists with valuation sensitivity to commodity prices and integration case studies from recent sector activity.
Next steps for leaders
For procurement leaders: prioritize material risk mitigation now. For product and engineering leaders: audit specifications against new standards and plan certification campaigns. For corporate development: evaluate bolt-on targets that close capability gaps rather than only adding volume. PW Consulting’s full Hose Clamps Market study supplies the data and templates necessary to execute these actions with confidence.
To access the complete dataset, scenario models, and executable playbooks referenced above, please consult the full report landing page or contact a PW Consulting advisor for a tailored briefing. Our team can also run a short, confidential workshop to translate the insights into a 90-day action plan aligned to your commercial and supply-chain objectives.
For detailed analysis of this topic, please visit the official page: Hose Clamps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Distributed Fiber Optic Sensing (DFOS) Market — Strategic Brief for 2026 Decision-Makers
Distributed Fiber Optic Sensing (DFOS) is accelerating from a niche instrumentation technology into a strategic monitoring platform across energy, infrastructure and security domains. This brief — prepared by PW Consulting’s senior strategy team — synthesizes the market dynamics you need to shape investment, procurement and partnership decisions in 2026. It demonstrates the depth of our analysis while preserving the detailed segment-level intelligence available in the full market study.
Distributed Fiber Optic Sensing (DFOS) Market
Market snapshot: scale, momentum and trajectory
DFOS has entered a high-growth phase. From a baseline in 2025 of USD 1,638 Million (base year), the market is projected to expand at a compound annual growth rate (CAGR) of 10.8% through the 2026–2032 forecast window. Under our base-case model, the market rises above USD 3.3 Billion by 2032, reflecting accelerating adoption across legacy oil & gas, power and utility networks, and emerging perimeter/security and civil-infrastructure use cases. The near-term inflection point is already visible: 2026 is modelled as the year when system-level deployments and product innovation combine to shift buyer behaviour from pilots to scaled implementations.
Distributed Fiber Optic Sensing (DFOS) Market
Why this matters for corporate strategy in 2026
- Capital allocation — managers must reconcile relatively high upfront DFOS capex and logistics with multiyear OPEX reductions and risk mitigation benefits. Our modelling translates sensing CAPEX into discounted lifecycle returns for typical energy- and infrastructure-owner profiles.
- Portfolio choices — DFOS now supports differentiated value creation: continuous integrity monitoring, faster incident response, and new operational data that enable predictive maintenance and asset optimization. Each of these value streams maps to different investment horizons and payback profiles, which our study quantifies for board-level evaluation.
- Go-to-market timing — with a structural CAGR above 10% and several vendor-led product innovations launched in early 2025–2026, market windows are compressing. Corporates that defer strategy formation risk higher implementation costs and weaker vendor leverage.
What the full report delivers — practical, transaction-ready intelligence
We designed this study to be directly actionable for decision-makers who must move from awareness to deployment within 12–18 months. The full report includes:
Distributed Fiber Optic Sensing (DFOS) Market
- Proprietary market model (2020–2032) with scenario variants and sensitivity testing to guide CAPEX/OPEX trade-offs.
- Use-case economics: quantified ROI templates for oil & gas, power systems, perimeter security and civil engineering, including failure-mode cost avoidance and service continuity metrics.
- Procurement playbooks: vendor selection scorecards, RFP language, integration risk checklists and sample SLAs.
- Deployment dossiers: logistics and installation templates, lead-time benchmarks, and common integration pitfalls for fiber routing and analyzer siting.
- Regulatory and standards tracker: a rolling watchlist of telecom and industrial standards, plus likely compliance milestones through 2027.
- M&A and partnership guides: due-diligence checklists and capital deployment scenarios for strategic buyers and private equity investors.
Competitive landscape — vectors of differentiation
The DFOS vendor field combines specialised start-ups with diversified industrial incumbents. Market concentration metrics indicate a moderate concentration: the top three players capture roughly one-third of the market by revenue, a dynamic that preserves room for specialist entrants while rewarding scale players that integrate DFOS into broader service offerings.
- Sintela (UK) — Deep expertise in customised DAS/DFOS deployments. Their ONYX™ family is oriented toward complex monitoring projects (rail, mining, borders). Sintela’s strength is bespoke systems engineering and long-tail service agreements; strategic partners should consider them for custom sensor-to-analytics integrations.
- Sensuron (US) — A disruptive entrant on cost and form factor. Sensuron’s static-strain DFOS platform is positioned at price points similar to single-point sensors (the company publicly lists a system price in the mid-five-figure range), making distributed strain economical for higher-volume applications such as automotive, aerospace and certain civil-engineering pilots. Their approach materially changes the ROI calculus for distributed strain adoption.
- AP Sensing (Germany) — Strong product breadth across DTS/DAS/DVS and an expanding R&D footprint. Recent capacity expansion signals intent to accelerate product development and production scaling — important for customers seeking long-term supplier roadmaps.
- Baker Hughes, Halliburton, Schlumberger — Energy-sector incumbents are integrating DFOS into broader well and reservoir service portfolios. Baker Hughes’ 2025 launch of integrated sandface-ready fiber/electrical solutions exemplifies the push to lower deployment friction and embed sensing into completion architectures.
- OFS Fitel — Fibre manufacturers are moving beyond commodity fiber to engineered fibers that boost backscatter and sensing distance. This upstream play changes system performance boundaries and increases differentiation between cable+analyzer combinations.
- Luna Innovations, Omnisens, FISO, OptaSense — These vendors offer modular sensing and analytics platforms, each presenting different trade-offs among sensitivity, spatial resolution and system openness. Buyers must prioritise integration compatibility and lifecycle support.
Recent developments and tactical implications
- Product innovation: OFS’s DataSens Enhanced Optical Fiber and its integration into cable platforms (showcased at OFC 2026) extend sensing distances and signal fidelity. For operators, this can reduce repeater count and improve long-span monitoring economics.
- Integrated completions: Baker Hughes’ SureCONNECT FE (announced 2025) removes a common operational barrier by enabling direct DAS/DTS/DSS readings at the sandface without intervention. That reduces deployment cost and time-to-data for well operators and raises the bar for completions vendors.
- R&D scaling: AP Sensing’s facility expansion (2025) signals increased manufacturing and innovation velocity — an important hedging signal for adopters who require secure, long-term supply.
- Standards and ecosystem enablement: ITU-T work on a telecom DFOS Recommendation (targeted for late 2025) is the watershed regulatory event that could materially accelerate adoption in metro/access networks by clarifying interoperability and consent processes.
- Cost architecture shifts: high analyzer cost has historically constrained DFOS adoption. We are seeing new low-cost digital analyzer architectures and product pricing strategies (e.g., Sensuron’s low-cost static-strain systems) that materially lower the entry threshold for distributed sensing pilots.
Key risks and deployment constraints
- Upfront capital and complex logistics — especially for energy-infrastructure rollouts — remain the largest adoption brakes. Realistic deployment plans must budget installation contingencies and multi-stakeholder coordination time.
- Siloed procurement processes — DFOS sits at the intersection of OT, IT and telecom. Without cross-functional governance, deployments tend to stall or be under-scoped.
- Standards uncertainty — while standards progress is positive, lingering gaps in interoperability and certification can slow enterprise procurement cycles until vendor-neutral benchmarks become common.
Action agenda for 2026 — five pragmatic moves
- Run “value capture” pilots that pair DFOS with existing asset-management systems. Require vendors to deliver measurable KPIs (MTTR reduction, leak-detection lead time, avoided downtime) within 6–12 months.
- Prioritise procurement clauses for supply continuity and fiber/cable specs. With engineered fibers becoming differentiators, lock in technical acceptance tests and lifecycle support commitments.
- Establish cross-functional DFOS governance (OT/IT/legal/operations) and a single integrator accountability model to prevent handoff failures.
- Pursue vendor partnerships where sensing is embedded into core equipment (e.g., well completions, cable systems). Integrated offers lower deployment friction and accelerate time-to-value.
- Monitor standards and regulatory milestones closely. The ITU-T telecom DFOS work and other standardisation efforts will change procurement qualifying criteria; be ready to update vendor scorecards as the standards landscape converges.
Conclusion — why the full study matters
DFOS is transitioning from an engineering curiosity to an operationally critical sensing platform. For 2026, the strategic imperative is clear: move beyond proof-of-concept to disciplined, ROI-driven deployments that account for capex, integration risk and vendor roadmap realities. PW Consulting’s full Distributed Fiber Optic Sensing Market study provides the granular segmentation, vendor benchmarking and financial models required to make those decisions with confidence. This brief highlights the contours and strategic choices; the complete report contains the detailed segment breakdowns, vendor scorecards and downloadable financial models needed to execute.
For the full dataset, including regional and application-level segmentation, vendor scorecards and our downloadable CAPEX/OPEX templates, visit the PW Consulting DFOS Market page.
For detailed analysis of this topic, please visit the official page: Distributed Fiber Optic Sensing (DFOS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


