



Category: Machinery & Automotive
PW Consulting: Hand Trucks Market to Hit USD 1,390M by 2032, Growing at 3.85% CAGR (2026-2032)
By PW Consulting, 2026-07-12
Hand Trucks Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused preview of our new Hand Trucks Market study — a practical, decision-grade intelligence package designed to shape boardroom decisions in 2026. This preview synthesizes the study’s most consequential themes: the market trajectory, structural dynamics, competitive behavior, and the actionable levers that matter for manufacturers, distributors, private equity sponsors, and large end-users.
Hand Trucks Market
Why this study matters in 2026
The hand trucks market is no longer a commodity story driven solely by price. Between supply-chain volatility, trade-policy shocks, and accelerating product innovation (including electrification and modular designs), the industry is entering a consolidation and premiumization phase. Our base-year analysis (2025) finds the global market sits north of a billion USD (reported in Million USD terms), and under the baseline scenario we model a steady expansion through 2032. The compound annual growth rate embedded in our forecast is 3.85% across the 2026–2032 horizon — enough growth to justify capacity investments, but selective enough that capital must be deployed against differentiated value propositions rather than scale alone.
Hand Trucks Market
Market trajectory — what the headline numbers tell you
-
Base year context: 2025 is the analytical pivot in the study. From that starting point, our scenario suite projects a measured recovery and expansion through 2032, with the market reaching a materially larger size under the base case by the end of the forecast window.
Hand Trucks Market -
Mid-term inflection: 2026 is an important tactical year — our near-term forecast for 2026 shows meaningful top-line growth from 2025, reflecting pent-up demand in logistics, retail reconfiguration cycles, and inventory restocking following raw-material-led cost spikes.
-
Longer-term view: At the sector level, the implied CAGR of 3.85% signals steady market health. That pace supports investments in automation, product innovation (powered and stair-climbing solutions), and aftermarket services — but it also warns against undisciplined capacity expansion where differentiation is unclear.
Structural dynamics shaping strategic choices
-
Raw material and input-cost pressures: Policymakers reshaped cost dynamics in 2025 with higher tariffs on steel and aluminum imports, and that continues to reprice the supplier-to-manufacturer equation. Companies that can insulate margins—through hedging, nearshoring, or design-for-material-efficiency—will sustain pricing flexibility.
-
Trade-policy risk and regulatory friction: A pending five-year review by a major trade body on antidumping orders introduced in early 2026 introduces upside and downside scenarios for import-dependent players. The possibility of duty revocations or extensions materially affects sourcing strategies for firms reliant on low-cost imports.
-
Standards and safety: Updated verification practices to established ISO requirements are increasing the measurement and compliance burden for industrial users. Safety-centric features are becoming table-stakes for procurement teams in logistics and large retail chains.
-
Product innovation and premiumization: Beyond material selection, the product layer is evolving — convertibility, powered assist options (including stair-climbing units), and modular attachments are creating new value pools (premium hardware, service contracts, and rental models).
Competitive landscape — what leaders and challengers are doing
The industry remains moderately fragmented. Our competitive mapping shows concentration that leaves room for regional champions and specialized global players. Top manufacturers have different playbooks: some double down on scale and breadth, others on configurable product engineering, and others on manufacturing excellence and “Made-in” country positions.
-
Harper Trucks (Wichita, Kansas) — a volumetric leader in the U.S., with deep heavy-duty product heritage. Harper’s investment in advanced manufacturing and product innovation in late 2025 reinforces its defense of core appliance and heavy-duty segments.
-
Magliner (Standish, Michigan) — differentiated by configurability and conversion capability. Magliner’s product portfolio expansion, including next-gen convertible and powered stair-climbing units announced in early 2026, signals a push into higher-margin, feature-rich applications.
-
Vestil Manufacturing (Angola, Indiana) — broad industrial portfolio and recent launches that blur the product boundary between hand trucks and complementary material-handling equipment (e.g., hydraulic booms, electric tuggers). This horizontal diversification alters competitive sets in several end-markets.
-
B&P Manufacturing — a long-standing “made-in-USA” manufacturer that recently pursued distribution partnerships to extend reach. Its ISO certification and heritage are assets in procurement processes that emphasize domestic supply and traceability.
-
American Cart and Equipment and Wesco Industrial Products — both represent focused plays on specialty carts and industrial duty models. Wesco’s capacity expansion in early 2026 is a direct response to localized demand and cost reshoring trends.
Recent activity during 2025–2026 underscores a market that is simultaneously innovating and fortifying supply chains: product launches, manufacturing-capacity upgrades, and strategic distribution partnerships have been concentrated among established U.S. players. That combination creates opportunities for mid-sized OEMs to capture share where incumbents are distracted by integration and expansion challenges.
Strategic implications for executives in 2026
-
Prioritize material strategy: With tariffs and input-price volatility persistent, procurement and product-development teams must jointly optimize material mixes, supplier portfolios, and design-to-cost. For many firms, a hybrid approach — localized production for premium lines, selective offshore sourcing for commodity SKUs — will be optimal.
-
Differentiate through services and configuration: The growth implied by the 3.85% CAGR favors players who convert product to platform — adding attachments, maintenance contracts, and digital telemetry for higher lifetime value.
-
Protect and exploit product safety credentials: Compliance with ISO and related verification regimes is a commercial differentiator. Turn regulatory adherence into a sales asset for large logistics and retail accounts.
-
Scan the M&A landscape proactively: Fragmentation means attractive tuck-in targets exist — particularly firms with strong OEM distribution relationships, niche product IP, or manufacturing footprints in strategic geographies. Our scenario work highlights sweet spots where acquisition multiples can be justified by post-deal synergies.
-
Invest in modular innovation, not just scale: Capacity expansions should be paired with modular product roadmaps that enable rapid customization without large per-SKU cost increases. The convertibility trend and the rise of powered-assist models make modular engineering a high-return investment.
What our full report delivers (practical tools and deliverables)
This study is designed for immediate operational use. It contains:
-
Robust market sizing and a transparent forecast model (base year 2025, forecast 2026–2032) with scenario toggles for tariff, demand, and innovation shocks.
-
Granular segmentation by region, product type, and application — with unit economics, ASP trends, and margin benchmarks for each node. (Note: detailed regional and application splits are reserved for report subscribers.)
-
Vendor scorecards and a synthesis of competitive moves — including capability matrices, capacity maps, and vulnerability assessments for the leading OEMs and prominent regional players.
-
Go-to-market playbooks tailored to manufacturers, distributors, and large end-users, including procurement templates, RFP language, and total-cost-of-ownership calculators for electrified and conventional fleets.
-
M&A and partnership pipelines with prioritized target lists, valuation frameworks, and integration checklists — calibrated to a range of buyer archetypes (strategic acquirers, financial sponsors, and distribution consolidators).
-
Supply-chain resilience tools: stress-test scenarios, dual-sourcing templates, and inventory optimization heuristics aligned to the volatility observed since 2020.
-
Regulatory and standards tracker with recommended compliance roadmaps to convert regulations into commercial advantage.
How executives should use this intelligence in 2026
-
Immediate triage: Use our short-form decision memos to prioritize initiatives for H1 2026 — which SKUs to price-protect, which capacity projects to defer, and which channels to redouble on.
-
Medium-term investment planning: Apply the forecast scenario that aligns with your business model to stress-test CAPEX and product-development plans through 2028.
-
Commercial capture: Leverage our buyer persona work and vendor scorecards to tailor proposals to large logistics operators and retail chains pursuing safety and ergonomic upgrades.
Final note — where this preview leaves you
The hand trucks market in 2026 is characterized by cautious growth, selective premiumization, and an operational environment reshaped by trade and materials policy. Our report arms you with the market-size baseline and the analytic instruments to convert that environment into playbooks: where to invest, where to partner, and where to consolidate or divest.
For the full dataset, proprietary segmentation, and the plug-and-play model you can deploy in financial planning and procurement, access the complete PW Consulting Hand Trucks Market report. The full study contains the granular splits and scenario model controls that underpin the strategic recommendations summarized here — essential for executives making binding capital and M&A decisions this year.
For detailed analysis of this topic, please visit the official page: Hand Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Radar Level Transmitters Market at USD 606.11M in 2025, 5.69% CAGR to 2032
By PW Consulting, 2026-07-12
Radar Level Transmitters Market — Strategic Outlook for 2026 Decision‑Makers
Presented by PW Consulting. Base year: 2025. Historical window: 2020–2025. Forecast horizon: 2026–2032.
Radar Level Transmitters Market
Executive preview
Between 2020 and 2025 the global radar level transmitters market expanded from approximately USD 425 million to about USD 606 million, reflecting a multi‑faceted move toward higher‑precision, certified sensing across industrial and municipal applications. Our forecast through 2032 assumes a compound annual growth rate (CAGR) of 5.69%, bringing the market to an estimated ~USD 894 million by the end of the projection horizon. For strategy teams preparing budgets, product roadmaps, procurement cycles or M&A programs in 2026, these trajectory assumptions are the starting point for near‑term decisions and longer‑term positioning.
Radar Level Transmitters Market
Why this report matters in 2026
- Calibration of capital and R&D spend: The market is in an active technology inflection — 80 GHz and W‑band radar, FMCW architectures, and wireless/smart compact designs are changing BOMs, unit costs and feature differentiation. Knowing realistic growth rates and adoption timelines avoids over‑ or under‑investment.
- Regulatory timing and compliance risk: New overfill, methane‑emissions and water‑sector regulations have concrete implementation windows. Our analysis links regulatory triggers to replacement cycles, enabling procurement teams to prioritize certified units ahead of enforcement deadlines.
- Commercial and channel planning: Scale economies from wider acceptance of W‑band sensors are compressing price premiums. Vendors must balance volume strategies with value‑added services; buyers can exploit timing windows for price negotiations.
- M&A and partnership scouting: Fragmentation and pockets of specialization create attractive tuck‑in targets. The report identifies capability gaps (e.g., compact certified devices, robust solids measurement, IoT‑native platforms) where acquisitions or alliances yield rapid market access.
What’s changing: technology and regulatory drivers
The dynamics driving the market today are simultaneous and reinforcing. On the technology side, 80 GHz and W‑band (76–81 GHz) sensors are becoming the de facto solution for applications that previously relied on ultrasonic or legacy radar devices — offering improved accuracy, smaller antennas and stronger immunity to foam, vapour and foam. FMCW techniques and enhanced signal processing are enabling longer ranges and better discrimination in cluttered tanks and silos. At the same time, compactness, Bluetooth commissioning and wireless telemetry are shifting total cost of ownership calculations in favor of next‑generation designs.
Radar Level Transmitters Market
On the regulatory front, several regionally specific but globally influential rules are accelerating replacements and upgrades: stricter overfill protection in Europe, methane emission monitoring mandates, and water industry certifications that create hard market access barriers for non‑certified devices. Importantly, regulatory approvals—such as US clearance for W‑band process sensors and various European water/waste certifications—are changing the product economics by enabling higher production volumes and narrowing price differentials.
Recent product and certification signals worth watching
- Several vendors launched new 80 GHz families and compact models with integrated molding or wireless capabilities in 2025–2026, signaling product migrations that will shape procurement cycles.
- Key certifications (water sector approvals, ATEX/Ex ia, SIL ratings) recently awarded to leading compact sensors directly translate into rapid adoption in regulated verticals such as municipal water and hazardous process sites.
- Vendor roadmaps indicate continued emphasis on simplified installation (wireless/plug‑and‑play), advanced diagnostics and cloud/IoT integration — features that increasingly influence procurement specifications beyond raw sensor price.
Competitive landscape: strategic positioning of core vendors
The market combines global automation incumbents, specialised instrumentation players and a growing set of regionally focused innovators. Each cluster follows a different playbook:
- Global automation leaders (scale + systems integration): Established names offer broad instrumentation portfolios and systems‑level integration into DCS/SCADA platforms. Their strengths include deep channel networks, extensive service footprints, and bundled solutions that appeal to large process operators. These vendors typically compete on reliability, lifecycle services and integration ease.
- Precision instrumentation specialists (technology + certification): A number of European and Japanese suppliers concentrate on high‑frequency radar, hygienic certifications and domain excellence in liquids, slurries and bulk solids. Their differentiation lies in high‑frequency performance, compact certified devices and application‑specific tuning.
- Fast followers and niche innovators (cost and convenience): Smaller firms and new product entrants are focusing on compact, lower‑cost 80 GHz models, explosion‑proof pulse radars, and wireless commissioning. These players often target retrofit opportunities and underserved regional markets.
Representative examples of vendor positioning (non‑exhaustive): Emerson and other long‑standing players emphasize proven series products with wireless and smart diagnostics for broad industrial use; Endress+Hauser and VEGA stress 80 GHz, hygienic certifications and high precision for process and water sectors; Siemens and ABB tie radar products into IoT and automation ecosystems; KROHNE, Magnetrol (Ametek), and Nivelco are examples of focused product innovation in FMCW and compact designs. Collectively, these firms shape purchasing expectations and accelerate standardization around certain architectures and certifications.
Strategic implications for 2026 procurement, product and M&A leaders
- Procurement: Time purchases around certification roll‑outs and vendor product cycles. Short‑term savings from legacy devices are often offset by higher lifecycle costs when compliance or accuracy requirements force early replacement.
- Product management: Prioritize modular platforms that support multiple frequency bands, hybrid sensing (guided‑wave + non‑contact) and over‑the‑air firmware updates. A clear path to certifications (water, Ex, SIL) should be a gating criterion for new product investment.
- Aftermarket and services: Service contracts, remote diagnostics and retrofit kits are high‑margin levers that differentiate vendors as the hardware market commoditizes.
- M&A and partnerships: Look for targets that accelerate certification timelines, add compact 80 GHz IP, or bring regional channels into core markets. Partnership models with system integrators accelerate adoption in established process industries.
What PW Consulting’s radar level transmitters study delivers
Our full report goes beyond high‑level trends to provide operationally actionable intelligence for 2026 planning cycles. Key deliverables include:
- Market sizing and validated forecasts (annual series across 2020–2032) with sensitivity scenarios tied to regulatory timelines and technology adoption curves.
- Vendor benchmarking and capability heatmaps — covering product breadth, certification status, service models and channel reach.
- Technology roadmaps mapping pulse vs FMCW vs guided wave adoption by application cluster, with recommended R&D priorities and cost‑down pathways.
- Regulatory impact matrix that ties specific rule sets to replacement waves and procurement windows in major markets.
- Commercial playbooks for OEMs, distributors and end‑users: pricing levers, negotiation checklists, and retrofit vs replacement decision frameworks.
- M&A and alliance playbook including target profiles, valuation sensitivities and integration checklists focused on the instrumentation space.
- Templates and calculators for ROI on sensor upgrades, including installation time, downtime risk, certification delays and emissions compliance benefits.
How to use the intelligence in Q1–Q3 2026
- Run a rapid audit of installed base criticality: identify assets where regulatory non‑compliance or measurement inaccuracy creates immediate exposure.
- Prioritise projects where certification timing aligns with procurement cycles—these windows create negotiating leverage and lower total cost of ownership.
- Map vendor roadmaps against your digital strategy: edge diagnostics, cloud integration and remote servicing capability should be procurement filters rather than afterthoughts.
- For product teams, convert regulatory requirements into product requirements: certifications and hazardous‑area approvals often define the addressable market before price or performance do.
Final note — the signal amid the noise
The radar level transmitters market in 2026 is neither a commodity race nor a closed oligopoly; it is a market undergoing technical convergence, regulatory acceleration and service re‑definition. The numbers paint a clear trajectory — solid, mid‑single‑digit growth from a base of roughly USD 606 million in 2025 to an estimated USD 894 million by 2032 at ~5.69% CAGR — but competitive advantage will accrue to organizations that convert product certification, systems integration and aftermarket services into durable customer lock‑in.
PW Consulting’s full study contains the detailed segmentation, regional and application splits, vendor market share analytics and downloadable datasets that underpin the strategic guidance summarized here. For teams that must make procurement, R&D or M&A decisions in 2026, the complete report is the practical playbook for converting market trajectories into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Radar Level Transmitters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Capsule Filling Machines Market to reach $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-07-12
Capsule Filling Machines Market: Strategic Implications for 2026 Decision-Making
Executive snapshot
As PW Consulting’s lead industry analyst, I present a forward-looking briefing on the capsule filling machines market that frames the high-level strategic choices executives will confront in 2026. Our baseline analysis uses 2025 as the reference year and applies scenario-driven forecasts through 2032. At the aggregate level, the market is on a steady expansion path — our base-year estimate sits in the low hundreds of millions (USD), with a compound annual growth rate of approximately 6.98% across the 2026–2032 forecast window. By 2032 the market is projected to be materially larger than in 2025, reflecting durable demand drivers across pharmaceuticals, nutraceuticals and adjacent end-markets.
Capsule Filling Machines Market
Why this study matters for 2026 strategy
- Capital allocation under uncertainty: 2026 will be a decisive year for capital deployment in manufacturing assets. Firms that can time investments—whether in high-speed, automated rotary lines or flexible semi-automatic cells—to anticipated product pipelines will capture cost and time-to-market advantages.
- Regulatory compliance as competitive moat: Tightening cGMP and food-safety expectations, alongside international certification regimes, are elevating the minimum viable product for equipment vendors. Buyers that prioritize validated, audit-ready solutions will reduce release cycle risk and protect market access.
- Service and lifecycle economics: As machines become more instrumented, aftermarket services (predictive maintenance, parts-as-a-service, digital validation bundles) will be central to total cost of ownership and vendor selection.
Market trajectory and macro interpretation
The market’s mid-single-digit CAGR masks structural shifts. On one axis we see steady, volume-driven growth stemming from expanding nutraceutical demand and ongoing pharmaceutical formulation innovation. On another, rising regulatory and quality expectations push buyers toward higher-spec automation and validated platforms. The net effect: manufacturers face simultaneous pressure to scale throughput and to build in flexibility for diverse fill types and tight compliance regimes.
Capsule Filling Machines Market
For executives planning 2026 capital and operational budgets, the practical implication is that incremental investments in automation and digital enablement — even if relatively modest upfront — can compound into outsized reductions in lot-release cycle time, deviation events and validation burden over a 3–5 year horizon.
Capsule Filling Machines Market
Report coverage — actionable intelligence you can use
This research was designed as a working playbook for commercial, engineering and M&A teams. Highlights of the report’s operational utility include:
- Trusted market sizing and trend validation to support CapEx prioritization and funding requests, with scenario models that translate market growth assumptions into expected machine demand by capacity tier.
- Validated purchasing criteria matrixes that map regulatory, operational and product-mix requirements to machine classes and vendor capabilities — enabling rapid shortlisting for RFPs.
- Unit economics and payback templates that accommodate throughput, recovery rates and maintenance regimes to model ROI across automated, semi-automatic and manual solutions.
- Risk registers and mitigation playbooks addressing supply chains, regulatory audits, spare-parts availability and third-party validation dependencies.
- Competitive intelligence dossiers and supplier scorecards for expedited vendor negotiation and selection.
Competitive landscape — themes and vendor positioning
The supplier universe spans global engineering leaders, regional specialists and niche suppliers focused on hybrid/manual systems. Notably, market concentration is modest — the top vendors account for less than one-third of aggregate market revenue — which creates opportunity for both consolidation and differentiation plays.
- Syntegon Technology (Heidelberg, Germany): Known for high-throughput GKF Capsylon platforms that emphasize precision dosing and pharmaceutical-grade robustness. Syntegon’s strength is in validated, high-capacity lines suitable for large-scale producers prioritizing throughput and regulatory readiness.
- IMA Group (Bologna, Italy): A leader in rotary and suction-bowl technology that balances speed and dosing flexibility. IMA’s equipment often targets high-volume use cases with advanced automation options for complex formulations.
- MG2 S.r.l. (Milan, Italy): Offers a portfolio spanning flexible E Series machines to the new IN-CAP family, engineered for multi-format fills and operator-centric interfaces — attractive to mid-size manufacturers and CMOs seeking adaptability.
- ACG Worldwide (Mumbai, India): Positions for broad accessibility — integrated solutions that combine simplicity with safety and throughput efficiency, often appealing to cost-sensitive nutraceutical producers and emerging markets.
- Harro Höfliger, Qualicaps, Torpac, Capsugel (Lonza), Dott Bonapace: Each brings niche strengths — from highly integrated packaging line integration, encapsulation science and global service networks to specialized automatic fillers — enabling buyers to match vendor capabilities to specific product and compliance requirements.
- Regional and small-scale suppliers (e.g., Finetech, Index Capsule Fillers, Feton): These vendors are important for low-to-mid volume needs, laboratory use, and markets where hybrid/manual solutions are still the pragmatic choice.
Recent product developments — such as MG2’s introductions and Finetech’s precision-oriented launches — illustrate a vendor-level pivot toward human-centered design, more granular dosing control and compact automation that reduces floor space and validation complexity. These trends lower the barrier for mid-sized manufacturers to adopt automation without committing to large monolithic lines.
Regulatory and standards dynamics
Regulatory alignment is non-negotiable. FDA cGMP requirements (21 CFR Parts 210 & 211 for pharmaceuticals and Part 111 for dietary supplements), ISO 9001/ISO 22000 quality and food-safety frameworks, CE marking and mandatory reporting regimes are shaping buyer behavior. Equipment must be sanitary by design, support routine calibration and facilitate traceability across material flows and electronic records. For many buyers, the cost of non-compliance — delayed approvals, product recalls and remediation audits — far exceeds the incremental capital cost to buy compliant machines.
Strategic playbook for 2026
- Prioritize flexibility in procurement: Specify modular architectures that allow capacity scaling and rapid changeovers. This preserves optionality as product pipelines evolve and regulatory demands shift.
- Integrate digital validation early: Insist on vendor-supplied, audit-ready validation packs and digital signatures to compress qualification timelines and simplify lifecycle documentation.
- Reorient service contracts: Transition from time-and-materials models to outcome-based service agreements that include uptime SLAs and predictive maintenance credits.
- Leverage supplier diversity: Use a two-tier sourcing strategy — established global vendors for core, high-throughput lines and agile regional partners for niche formats or pilot capacity.
- Consider M&A and partnerships: For manufacturers seeking rapid capability expansion, tuck-in acquisitions of regional equipment makers or long-term co-development agreements can accelerate access to specialized fill technologies.
How PW Consulting helps
Our capsule filling machines market study is purpose-built for executives who need data-backed, implementable recommendations rather than general commentary. The full report contains granular segmentation, regional demand models, vendor scorecards, scenario financials and sourcing playbooks. Importantly, to preserve the strategic advantage of our clients, we present both a neutral market baseline and alternative scenarios that stress-test investment assumptions under varying regulatory and supply-chain conditions.
For 2026 decision cycles, PW Consulting can provide rapid deliverables: tailored vendor shortlists, ROI calculators calibrated to your product mix, and a validation readiness checklist that reduces qualification time by weeks. These deliverables are structured to plug into procurement and engineering processes, enabling faster, less risky deployment of new filling capacity.
Closing — the practical next step
Executives should treat 2026 as a year to convert strategic intent into realized manufacturing capability. The macro trajectory indicates reliable growth and a compelling business case for selective automation and service innovation. Yet the optimal path for any organization depends on detailed segmentation — machine class demand by application, regional supply constraints, and vendor-specific delivery and validation timelines. Our report preserves those critical datasets and modeling tools behind an accessible subscription gateway. For teams that need to act quickly, PW Consulting offers targeted advisory engagements to translate the report’s insights into procurement roadmaps, validation plans and contract strategies that reduce time-to-value.
Contact PW Consulting to obtain the full capsule filling machines market study and begin converting 2026 strategic choices into measurable operational outcomes.
For detailed analysis of this topic, please visit the official page: Capsule Filling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Door Handles Market to Reach USD 5,335M by 2032 at 4.5% CAGR
By PW Consulting, 2026-07-12
Automotive Door Handles Market 2026: Strategic Preview for Executive Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our full Automotive Door Handles Market study — a decision-grade intelligence product designed to shape capital allocation, product roadmaps, and commercial strategy through 2026 and beyond. This preview synthesizes the high-level market trajectory, competitive dynamics, regulatory fault lines, and concrete playbooks that senior leaders will need when allocating R&D budgets, negotiating supplier contracts, or evaluating M&A targets. It intentionally demonstrates analytical depth while reserving the granular segmentation tables and proprietary model outputs for the full report.
Automotive Door Handles Market
Market Snapshot: Where the Opportunity Lies
The global automotive door handles market stands at an important inflection point. By our base year (2025), total industry revenues reached approximately USD 3.94 billion and the market is projected to expand at a steady compound annual growth rate of about 4.5% through the 2026–2032 forecast window. Under that trajectory the market crosses the mid-single‑billion threshold in nominal terms over the decade, driven by incremental content per vehicle, adoption of mechatronic access systems, and replacement demand in mature fleets.
Automotive Door Handles Market
Two high‑level structural observations are critical for 2026 planning: first, the market is neither a pure commodity nor a small bespoke niche — it is characterized by modular, engineered components that sit at the intersection of mechanical, electronic and software domains. Second, concentration is meaningful: the largest three suppliers account for roughly half of global revenues, and the top five approach two‑thirds market share. Those numbers imply that mid‑tier players can still scale, but must choose disciplined specialization or system‑level integration to remain competitive.
Automotive Door Handles Market
Why This Research Matters for 2026 Decisions
- Capital allocation and product roadmap validation: Our forecast and scenario overlays translate macro growth into demand curves for mechatronic versus mechanical content, enabling CFOs and product leaders to size investment needed for new manufacturing cells, tooling, and firmware roadmaps without overcommitting to product types that will be constrained by regulation.
- Procurement and supplier diversification: With the market’s concentration profile and ongoing supply‑chain risks (material cost volatility, regional regulations), procurement teams need a validated supplier scorecard and risk heat‑map — elements we provide — to prioritize tier‑1 relationships, dual‑sourcing strategies, and localization plans for 2026 contracts.
- M&A and partnership funneling: Strategic buyers and PE sponsors can use our valuation sensitivity frameworks and integration checklists to identify targets that offer product differentiation (e.g., flush actuators or biometric integration) or margin expansion through modularization and aftermarket channels.
Technology & Product Trends Shaping Strategy
- Mechatronics and SmartAccess integration: SmartAccess — the bundling of mechanical hardware with actuators, sensors and software — is no longer optional for premium segments. Suppliers that can deliver validated actuator‑firmware bundles with predictable MTBF will command price premia and preferred OEM positioning.
- Flush‑mounted aesthetic and aerodynamic demands: A growing proportion of new vehicles are adopting flush or recessed handle designs for aero and design reasons. This trend drives upstream demands on precision injection molding, specialized surface coatings, and tighter assembly tolerances — all of which increase entry barriers for generic stamp‑and‑bend suppliers.
- Biometric and sensor fusion: Collaborative showcases and concept integrations point to biometric access and touchless opening concepts appearing on near‑production concept cars. These represent optional content streams for OEMs seeking a premium UX and for suppliers with strong embedded‑software capabilities.
- Regulatory countercurrents: Notably, some jurisdictions are imposing manual‑release or physical‑hardware requirements for electronic handles for emergency egress. Suppliers and OEMs must reconcile aspirational designs with compliance realities — a structural constraint that alters bill‑of‑materials, cost, and qualification timelines.
Regulatory & Cost Headwinds: The New Normal
Regulatory changes are a material driver for supplier strategy in 2026. Several jurisdictions have introduced rules requiring mechanical release mechanisms on certain classes of electronic handles, directly affecting design complexity and cost. Additionally, OEMs’ tightened ESG qualification requirements mean procurement teams are demanding demonstrated lower‑carbon manufacturing and recycled material usage in componentry — increasing the non‑price criteria in supplier selection.
From a cost perspective, the migration to flush designs and increased mechatronic content requires higher precision, more complex surface treatments, and additional electronics — all of which translate into longer qualification cycles and higher upfront capex. Supplier strategies that offload qualification risk to themselves (i.e., offering pre‑qualified modules) will be rewarded with longer lead contracts and higher margins.
Competitive Landscape: How Leading Players Are Positioning
The competitive set combines global systems suppliers with regionally entrenched specialists. Leading players have converged on two strategic responses: (1) integrating mechanical and electronic subsystems to sell higher‑margin door modules and SmartAccess packages; and (2) forming partnerships or alliances to manage supply-chain complexity and accelerate innovation.
- Huf Hulsbeck & Fürst: Market leader that offers a full spectrum of handle systems and mechatronic passive entry technologies. Their strategy centers on systems depth and global OEM validation — a blueprint for incumbency preservation.
- Magna International: Leveraging its modular door‑module capability, Magna pushes integrated assemblies that simplify OEM assembly and risk. Their showcasings of SmartAccess underscore the pivot to combined mechanical/electronic offers.
- Kiekert AG: Strong in locking systems and actuators, with mechatronic solutions that tie directly into handle operation and user comfort. Their product set is essential for suppliers aiming to deliver functionally complete subsystems.
- Aisin Seiki and U‑Shin: Both combine Japanese OEM heritage with tight integration into vehicle platforms; they represent how supplier OEM‑lock can be translated into sticky long‑term contracts.
- WITTE Automotive and Minda VAST: Regional specialists that are transitioning from component vendors to system suppliers, pursuing partnerships to access biometric and touchless concepts demonstrated in concept vehicles.
Recent moves illustrate the consolidation of capability: product collaborations showcasing biometric access and the formation of strategic partnerships to shore up supply chains and co‑develop next‑gen solutions. For 2026, watch which suppliers convert demonstration projects into validated production lines — that conversion is where revenue uplift and margin capture happen.
Scenario Planning: Strategic Choices for 2026
- Defend and deepen (incumbent suppliers): Double down on system offers, warranty‑backed actuator‑software stacks, and OEM co‑engineering. Invest selectively in coatings & precision molding cells to secure aesthetic‑sensitive platforms.
- Specialize and scale (mid‑tier suppliers): Focus on niche differentiation — e.g., low‑power actuation, emergency mechanical release sub‑assemblies or retrofit aftermarket modules — and pursue geographic partnerships to bridge qualification timelines.
- Acquire and integrate (financial buyers and strategic acquirers): Target firms with validated mechatronic IP, short qualification pathways into top OEMs, or complementary localized manufacturing footprints to hedge regulatory localization needs.
- Platformize (OEMs and system integrators): Adopt platform approaches where a single validated handle module can be adapted across trims, reducing variant proliferation and speeding time to market while ensuring regulatory compliance across markets.
What the Full Report Delivers: Practical Tools for Immediate Use
Our full Automotive Door Handles Market study is built for action. It includes:
- Detailed demand and revenue models (historical and forecast) with scenario toggles (regulatory, EV adoption, aesthetics penetration) to stress‑test capex decisions.
- Supplier scorecards and risk heat maps covering technology capability, quality track record, pricing position, and ESG readiness.
- Go‑to‑market playbooks for suppliers — from product modularization and co‑development contracts to pricing levers and warranty design.
- Procurement negotiation templates and total cost of ownership models that incorporate qualification and localization costs introduced by new regulatory requirements.
- M&A screening lists with high‑probability targets, valuation ranges, and integration checklists aligned to synergies in mechatronics and software IP.
- Regulatory tracker and impact matrix showing which design choices face the highest compliance risk in key markets and how that alters lead times and unit economics.
Closing: How to Use This Preview in Your 2026 Planning Cycle
The near‑term horizon (2026) will be defined by choices: invest in electrified/mechatronic product lines now and assume longer qualification windows, or focus on cost leadership in mechanical designs and accept segmentation risk as OEMs migrate to SmartAccess. Our study provides the scenario logic, the supplier benchmarking, and the executable playbooks that allow executives to convert market direction into defensible investment plans.
For strategy teams preparing budgets, for procurement leaders negotiating multi‑year contracts, and for investors sizing exit multiples, the full report contains the hidden pages behind this preview — the granular segmentation, price curves, and supplier‑level financials you need to validate your next move. PW Consulting’s deeper model outputs will show exactly how sensitivity to regulatory shifts and material cost variances alter ROI on a per‑platform basis.
To unlock the complete dataset, supplier rankings, and executable templates referenced here, access our full Automotive Door Handles Market report. Use the insights to calibrate 2026 roadmaps, accelerate or de‑risk product launches, and structure partnerships that capture the upside of a market growing at roughly 4.5% annually through the decade.
For detailed analysis of this topic, please visit the official page: Automotive Door Handles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Centrifugal Compressors Market to hit USD 4,250 Million in 2025 with 6.26% CAGR (2026–2032)
By PW Consulting, 2026-07-12
Centrifugal Compressors Market 2026: Strategic Imperatives for Decision‑Makers
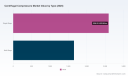
As PW Consulting’s lead industry analyst, I present a concise, decision‑focused primer to the Centrifugal Compressors Market — a companion to our full market study (base year 2025) designed to inform capital allocation, product strategy, procurement and M&A choices in 2026. The global market is large and expanding: our model places total industry revenue at approximately USD 4,250 Million in 2025, with a compounded annual growth rate of 6.26% across the forecast window that runs from 2026 through 2032. By the end of that horizon, market revenues trend toward roughly USD 6,436 Million under our central scenario. This trajectory represents both a steady replacement cycle and pockets of disruptive, high‑growth opportunity driven by energy transition, digitalization and regulatory tightening.
Centrifugal Compressors Market
Why this study matters in 2026
-
Regulation is no longer peripheral. Changes to compressor test procedures and mandatory testing regimes introduced in 2025 materially affect vendor claims, procurement specifications and warranty exposure.
Centrifugal Compressors Market -
Technology bifurcation is accelerating. Oil‑free platforms, magnetic bearings and hydrogen‑capable designs are moving from niche demonstrations to commercial deployments, shifting CAPEX/OPEX tradeoffs.
Centrifugal Compressors Market -
Service and aftermarket economics are emerging as the primary margin pool. With a moderately fragmented vendor landscape, service excellence and digital predictive maintenance are differentiators for both OEMs and purchasers.
-
Strategic timing matters. Investors and corporate buyers who align procurement, R&D and M&A roadmaps to the 2026 regulatory and technology inflection points will capture disproportionately higher TSR and operational resilience.
What the report delivers (practical, actionable outputs)
-
Proprietary sizing and forecasting model (2020–2032) with buildable assumptions so clients can re‑run scenarios with their own uptakes and price decks.
-
Regulatory impact matrix and a compliance checklist tied to product testing changes that became effective in 2025 — for procurement and product teams to validate vendor claims.
-
Technology adoption roadmaps (oil‑free, magnetic bearing, hydrogen‑ready) that translate engineering attributes into procurement specifications and TCO calculators.
-
Supplier scorecards and an M&A watchlist that combine capability, scale, aftermarket penetration and go‑to‑market strength — calibrated to identify roll‑up and partnership targets.
-
Commercial playbooks: contract templates, warranty structures, spare‑parts inventory strategies and digital maintenance offers to maximize uptime and margin capture.
-
Investment memos that distill valuation sensitivities for acquirers and private capital, including scenarios for accelerated hydrogen adoption and electrified process loads.
Market dynamics and catalysts to monitor
-
Policy and testing: The US Department of Energy updated compressor test procedures in early 2025 and enforced mandatory product testing as of mid‑2025. Procurement teams must require DOE‑compliant test reports and factor regulatory audit risk into supplier selection.
-
Technology migration: Oil‑free centrifugal systems and magnetic‑bearing architectures have progressed from energy‑efficiency narratives to operational imperatives in sensitive applications (e.g., data centers, clean hydrogen, and critical industrial plants). Expect accelerated specification of oil‑free units where contamination risk or lifecycle energy is a priority.
-
Hydrogen and decarbonization: Demonstrations of hydrogen‑dedicated compressor platforms and hydrogen‑compatible designs are moving into field trials. Early adopters will need to balance higher upfront costs against strategic optionality for future low‑carbon molecules.
-
Scale and specialization: Large multi‑shaft machines for air separation and industrial gas remain capital‑intensive engineering projects that reward proven systems integration and stringent QA; projects of record size signal continued demand from industrial gas expansion and decarbonization projects.
-
Supply‑chain localization: Manufacturers maintaining significant local production footprints are insulating customers from logistics shocks and may carry higher near‑term cost bases but deliver resilience benefits — an increasingly valued attribute in procurement evaluations.
Competitive landscape — what the recent moves tell us
-
FS‑Elliott (Export, Pennsylvania): Continues to lead in oil‑free centrifugal air compressors for high‑capacity applications and has reinforced its market credibility with industry awards in 2026. Its US manufacturing base and local supplier ecosystem (supporting substantial indirect employment) underline a strategy that prioritizes supply‑chain control and service proximity — a competitive advantage for customers valuing lead‑time and localization.
-
Atlas Copco (Stockholm): The company’s focus on certified oil‑free compressors and energy efficiency positions it well for buyers prioritizing Class‑0 hygiene and low life‑cycle costs. Expect Atlas Copco to compete on integrated energy management and retrofit offerings.
-
Garrett Motion Inc. (Plymouth): By showcasing oil‑free centrifugal units for HVAC, data centers and BESS across 7–500 ton equivalents and signaling production ramp‑ups in late 2026, Garrett is targeting a high‑growth segment where reliability and modularity matter. Its move underscores the expanding role of centrifugal technology outside traditional industrial uses.
-
Danfoss Turbocor (Denmark/US): Magnetic‑bearing centrifugal compressors for chillers represent a disruptive low‑friction proposition that reduces maintenance and improves part‑load efficiency. HVAC and refrigeration OEMs will find this design attractive for reducing lifecycle service costs.
-
Kawasaki Heavy Industries (Japan): Demonstrations of a hydrogen‑dedicated centrifugal compressor mark an important step in industrial‑scale hydrogen infrastructure. Early field trials funded under government innovation programs indicate pathways for commercialization in hydrogen liquefaction and transport.
-
Himile (China): Delivery of very large multi‑shaft compressors for air separation projects shows the continued appetite for scale plays in industrial gases — a segment where supply reliability and API compliance are procurement deal breakers.
-
Sundyne (USA): With a focus on high‑speed process gas compressors, Sundyne occupies the high‑precision niche where customization and thermodynamic optimization command premium margins.
Taken together, these vendor moves reveal three strategic currents: (1) a race to own the oil‑free and magnetic‑bearing value chains for cleanliness and efficiency; (2) an emergence of hydrogen‑capable solutions as strategic optionality for buyers; and (3) aftermarket and service capabilities becoming the decisive lever for long‑term margins. Market concentration metrics indicate a moderately fragmented market (top‑three and top‑five shares leave substantial room for scale consolidation and niche dominance), so both inorganic and focused organic plays remain viable strategies.
Actionable recommendations for 2026 decision‑makers
-
Revise procurement specs to require DOE‑compliant test data and third‑party energy and pressure‑ratio verification. This reduces claim risk and future warranty exposure.
-
Prioritize pilot projects that compare oil‑free, magnetic‑bearing and hydrogen‑ready designs under real‑world duty cycles. Use side‑by‑side TCO models over a 7–10 year horizon rather than headline CAPEX metrics.
-
Create a modular procurement strategy: secure a short list of OEMs for critical assets, negotiate spare‑parts pools and service agreements upfront, and structure contracts that align incentives for uptime and energy performance.
-
Hedge technological risk by stipulating upgradeability in new purchases (e.g., hydrogen compatibility, sensors for predictive maintenance). For large industrial projects, include clear acceptance tests tied to performance milestones.
-
Pursue small bolt‑on acquisitions or strategic partnerships to acquire aftermarket capabilities — especially diagnostics, predictive maintenance software and field service networks that materially improve margin capture.
-
Build supply‑chain resilience by mapping single‑source inputs, validating alternative suppliers and evaluating localized manufacturing or consignment stocking for critical spares.
How PW Consulting supports your 2026 decisions
-
Custom scenario runs of our 2026–2032 forecast model, with client‑specific uptake curves and price decks.
-
Due‑diligence packs for M&A targets, including tech readiness, aftermarket potential and integration risk scoring.
-
Procurement and specification workshops that translate new regulatory and testing regimes into executable RFP language and acceptance testing protocols.
-
Implementation roadmaps for product teams to reposition portfolios toward oil‑free, magnetic bearing and hydrogen‑capable solutions while protecting near‑term revenue.
Our full Centrifugal Compressors Market report contains the detailed regional and application splits, supplier market‑share tables, unit‑economics worksheets and the proprietary scorecards referenced above. For decision‑makers preparing budgets, R&D pipelines or acquisition strategies in 2026, this intelligence converts ambiguity into prioritized action. Contact PW Consulting to access the complete dataset, bespoke scenario analysis and our vendor due‑diligence toolkit.
For detailed analysis of this topic, please visit the official page: Centrifugal Compressors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EVs for Construction, Agriculture & Mining to hit USD 1,404.3M by 2032 (18.5% CAGR)
By PW Consulting, 2026-07-12
Electric Vehicles for Construction, Agriculture and Mining: Strategic Outlook for 2026 Decision‑Makers
At PW Consulting we believe 2026 is a decisive inflection point for electrification in heavy off‑road sectors. This research introduction frames why procurement leads, OEM strategists, fleet operators, energy providers and investors should treat the next 18–36 months as a window of opportunity to lock in competitive advantage. We summarize the market trajectory, the forces reshaping buyer economics, the emergent competitive configurations, and the practical deliverables in our full Electric Vehicles for Construction, Agriculture and Mining Market study — while deliberately reserving the granular segmentation intelligence for licensed access.
Electric Vehicles for Construction, Agriculture and Mining Market
Market trajectory: a rapid scale phase
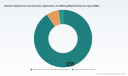
Measured on a total‑market basis, adoption of electric off‑road vehicles has moved from early demonstrations to commercial rollout. By our base year the market reached USD 428.0 Million (base year 2025) and, under the central scenario, is projected to grow at a compound annual growth rate (CAGR) of roughly 18.5% through the forecast horizon. That pace produces a multi‑fold expansion toward the end of the outlook period, putting aggregate market size firmly into the higher‑hundreds of millions into the low‑billion USD range by 2032. For executives, that trajectory signals two things: first, scale economics will start to compress unit costs and TCO dynamics in favor of electric powertrains; second, the commercial structure of supply chains and aftermarket services will materially change — quickly.
Electric Vehicles for Construction, Agriculture and Mining Market
Why this research matters for decisions made in 2026
- Time‑sensitive investment choices: Capital allocation decisions taken in 2026 — for manufacturing capacity, battery partnerships, or charging infrastructure — will either capture a disproportionate share of the first‑mover returns or cede advantage to better‑positioned rivals.
- Procurement and fleet transition planning: Operators who begin systematic electrification pilots in 2026 will be positioned to validate TCO and reliability assumptions before widespread regulatory and customer pressure forces accelerated replacement cycles.
- Partnerships and ecosystem plays: The next 18 months will separate opportunistic collaborations from strategic alliances that control value across battery supply, energy management, and integrated site services.
Core dynamics reshaping demand and economics
- Regulatory acceleration: Stricter emissions targets and procurement rules (notably in Europe and several national markets) are shifting OEM roadmaps from hybrid first‑then‑electric to prioritizing full‑electric architectures for many use‑cases. Public tenders and green procurement standards are already surfacing as non‑price selection criteria for major infrastructure and mining contracts.
- Energy and charging as a competitive lever: Charging logistics — availability, power levels, grid integration and negotiated time‑of‑use energy contracts — are becoming as important as machine specification. Vendors that can offer turnkey charging + fleet management bundles will unlock higher adoption.
- Battery cost and supply chain pressure: Battery systems and charging infrastructure remain the primary drivers of up‑front price differentials versus conventional machines. However, expected declines in battery pack cost, coupled with modularization of electric drivetrains, will compress incremental cost curves across the forecast window.
- Carbon and operational mandates: Standards such as ISO 14001, and corporate decarbonization targets in mining and construction, are converting customer preferences into procurement requirements — creating a steady demand floor irrespective of short‑term fuel price swings.
Competitive landscape: concentration and capability
The vendor environment is already concentrated. Market concentration metrics indicate that a small group of global OEMs control a meaningful majority of current market revenues, with three firms accounting for a very large share and five firms expanding that share further. For market entrants and investors this concentration implies both barriers and rapid consolidation opportunities: incumbents can leverage scale, dealer networks and service capability, while challengers can win by specializing in modular electric platforms, battery swapping or integrated energy services.
Electric Vehicles for Construction, Agriculture and Mining Market
Key players include legacy heavy equipment manufacturers and newer electric‑native challengers. Each occupies a distinct strategic posture:
- Volvo Construction Equipment (Gothenburg, Sweden): Rapidly scaling a full electric portfolio across wheel loaders, articulated haulers and excavators; serial production of electric articulated haulers and mid‑size wheel loaders is a milestone that shifts OEM credibility from prototype to production readiness.
- SANY Group (Changsha, China): Pursuing aggressive electrification across dump trucks and large excavators with a cost‑competitive manufacturing base — a play that pressures global price dynamics and distribution footprints.
- Hitachi Construction Machinery (Tokyo, Japan): Focused on battery‑powered mid‑ and small‑class excavators and experimenting with human‑machine interfaces and voice control to enhance field productivity.
- Caterpillar Inc. (Irving, USA) and Komatsu Ltd. (Tokyo, Japan): Both leverage deep dealer networks and service contracts to integrate electric drive systems into heavy‑duty segments, while incrementally adapting warranty and service models to new powertrain realities.
- Liebherr and Doosan Infracore: Competing in heavy‑capacity machines for quarrying and mining — segments where electric drivetrains can deliver large operational emission reductions but require heavy investment in charging or onsite power.
- John Deere, CNH Industrial, AGCO and Kubota: Addressing the agricultural segment with electric tractors and compact machinery — where cadence of replacement and operating profiles create distinct TCO dynamics versus construction and mining.
- New entrants such as Hevi and Monarch Tractor: Positioning as specialists with all‑electric platforms, targeting niches where tailored product architecture and rapid iteration beat incumbent scale.
Recent product and partnership moves validate this multi‑vector competition: high‑profile product launches in 2025 signalled serial production intent, while 2026 partnerships — notably between OEMs and energy systems partners — are starting to bundle machine and power solutions into integrated offerings. These developments mark the transition from experimental trials to scalable deployments and are the signals procurement and supply chain leaders should read as proof of technology and commercial readiness.
What the full PW Consulting report delivers (practical, operational answers)
Our full study combines rigorous market sizing with operator‑level modelling and executables for corporate strategy. Deliverables include:
- Bottom‑up market sizing and scenario runs across 2026–2032 calibrated to historical adoption from 2020–2025 and underpinned by component‑level cost curves.
- Proprietary TCO models for construction, agriculture and mining use‑cases that isolate the sensitivity of fuel, battery replacement, charging infrastructure and resale assumptions.
- Supply chain heatmaps: battery cell sourcing, inverter and motor OEMs, power electronics bottlenecks, and critical raw material risk assessments — with suggested mitigation strategies for procurement and vertical integration.
- Detailed competitor dossiers and playbook analysis for leading OEMs and challengers, mapping product roadmaps, manufacturing scale, dealer networks and aftersales strategies.
- Site‑level adoption templates and charging rollout plans that connect fleet schedules, shift patterns and energy procurement to optimal charging architectures.
- Regulatory and procurement trackers that translate regional environmental requirements into operational obligations and expected timing for enforced adoption.
- Investor decision frameworks and M&A heat maps identifying consolidation targets, technology licensing candidates and partnership archetypes.
How to use the intelligence in 2026
Executives should convert insight into immediate action across three horizons:
- Now (0–12 months): Validate internal TCO assumptions with our models; launch targeted pilots that instrument charging, uptime and operator feedback; and initiate discussions with battery and energy partners to secure preferred commercial terms.
- Near (12–36 months): Scale charging and depot investments aligned with fleet replacement cycles; negotiate dealer and service contracts that reflect electric‑specific support needs; and pursue strategic partnerships or minority investments to secure technology access.
- Medium (36+ months): Reconfigure product and service portfolios to monetize lifecycle software, energy optimization services and reclaimed battery second‑life programs as residual value becomes a material margin item.
Why PW Consulting’s analysis is uniquely actionable
We combine OEM product intelligence, operator case studies and energy systems analysis to produce evidence‑based recommendations. Importantly, our report does more than describe trends: it prescribes specific contractual language for energy supply agreements, outlines dealer compensation models for electric machines, and provides step‑by‑step retrofitting and charging configuration guidance for greenfield and brownfield sites. For organizations that need quick wins, we include rapid diagnostic tools that prioritize initial sites and quantify near‑term emissions and cost savings.
Next step — where to get the full intelligence
This overview intentionally showcases the depth and relevance of the research while withholding detailed segmentation and proprietary model outputs that are part of the licensed report. For decision‑grade data — including the full breakdowns, downloadable TCO calculators, company dossiers and scenario workbooks — access the full Electric Vehicles for Construction, Agriculture and Mining Market report. PW Consulting clients and partners may contact our market leads for tailored briefings and integrated project scopes that translate insights into executable roadmaps for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Electric Vehicles for Construction, Agriculture and Mining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Safety Glasses Market to USD 296.5M by 2032 (4.05% CAGR)
By PW Consulting, 2026-07-12
Safety Glasses Market — 2026 Strategic Outlook and Executive Trailer
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a focused, decision-oriented preview of our newest Safety Glasses Market study. This briefing synthesizes the macro trajectory, strategic inflection points, competitive posture, and practical playbooks that procurement chiefs, product heads, and corporate strategists should prioritize in 2026. It deliberately signals the most consequential insights while withholding granular segment tables and line-item breakdowns — those are available in the full report and accompanying datasets.
Safety Glasses Market
Macro trajectory: steady growth with structural drivers
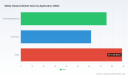
The safety eyewear market emerges from the 2020–2025 period with demonstrable resilience. Our baseline reads the market at approximately USD 185.2 Million in 2020, expanding to about USD 225.5 Million by 2025. Looking ahead under our central scenario — informed by regulatory alignment, industrial activity, and product innovation — the market is projected to grow at a compound annual growth rate (CAGR) of roughly 4.05% through the 2026–2032 forecast window, reaching an estimated USD 296.5 Million by 2032.
Safety Glasses Market
This steady expansion reflects three structural forces: (1) regulatory tightening and harmonization that raises minimum performance expectations for workplace eye protection; (2) persistent end-market demand from construction and manufacturing verticals adapting to automation and new hazard profiles; and (3) ongoing product evolution (advanced coatings, ballistic ratings, and prescription integration) that elevates unit values and widens addressable use cases.
Safety Glasses Market
Why 2026 is a strategic inflection year
- Standards reset: The publication of ANSI/ISEA Z87.1-2025 (January 2026) reframes certification baselines globally, creating an immediate compliance opportunity and a procurement reset for large organizations.
- Product premiumization: Suppliers are migrating from commodity polycarbonate offerings toward differentiated lenses and coatings that command higher ASPs and longer replacement cycles.
- Concentration & consolidation potential: Market concentration metrics indicate a moderately consolidated landscape; leading suppliers control meaningful share but do not preclude tactical M&A or private-label growth.
Report value: what leaders will find inside
The full PW Consulting study is built as an execution toolkit, not an academic catalog. It includes:
- Actionable procurement templates (specification checklists tied to ANSI/ISEA Z87.1-2025 clauses, supplier audit scorecards, and RFP language).
- Commercial playbooks for product managers (feature roadmaps, value-based pricing frameworks, and launch plans for coatings and prescription lines).
- Scenario-driven demand models (baseline, regulatory-tightening, and accelerated-industrialization cases) that translate macro assumptions into SKU-level stocking guidance and CAPEX timing for manufacturers and distributors.
- Supplier benchmarking and risk heatmaps (manufacturing footprint, certification compliance, SKU breadth, and margin pressure indicators) — redacted here to preserve the report’s proprietary value.
- M&A screening filters and synergy matrices for private equity and corporate buyers evaluating bolt-on targets or vertical integration (sightlines on near-term consolidation opportunities given current CR3 and CR5 dynamics).
Competitive landscape: capability maps and strategic postures
The competitive field is both global and capability-driven. A sample of incumbent profiles illustrates the range of competitive playbooks you will evaluate in the full report:
- Wiley X (USA) — Product engineering focused on high-impact and ballistic-rated eyewear with advanced lens coatings; positions itself in premium safety segments where certification and performance matter most.
- Bollé Safety (France) — Emphasizes anti-fog/anti-scratch coating technologies and European design pedigree; appeals to customers seeking performance-differentiated replacements for commodity lenses.
- uvex Safety Group (Germany) — Broad portfolio spanning industrial and prescription safety solutions; plays to safety-conscious buyers who demand extensive product families and certified fit-for-purpose options.
- MCR Safety (USA) — Distribution-anchored player with a strong catalog presence (recent 2026 catalog) and emphasis on ANSI-compliant, impact-rated lines — good at channel execution and scale procurement.
- Honeywell (USA) — Global systems supplier with cross-sell advantages across PPE categories; leverages enterprise relationships to bundle eyewear into larger safety programs.
- MSA Safety (USA) — Offers prescription-capable options and comprehensive compliance support for industrial and construction clientele.
- EssilorPrescription Safety Eyewear (France) — Specialist in prescription safety partnerships — attractive to occupational-health-focused employers requiring optical correction integration.
- Radians Safety (USA) — Product innovator; recent launches (GLYF™ and Crossfire BOLO™) highlight ballistic and comfort claims — nimble at trade-show-driven commercialization.
- Day Sun Industrial Corp. (Taiwan) — Cost-competitive manufacturing partner with CE and ANSI-certified SKUs, useful for supply security and tactical sourcing.
These firms represent archetypes: premium innovators, channel-scalers, global bundlers, and price-competent manufacturers. The interplay among them drives segment-level margin dispersion, R&D investment priorities, and M&A targets. The report contains granular supplier scorecards and strategic movesets to help you pick the most relevant archetype for your organization.
Regulatory and standards dynamics — practical implications
The ANSI/ISEA Z87.1-2025 revision is the most consequential near-term event for corporate decision-makers. PW Consulting’s analysis translates the standard’s changes into procurement actions:
- Immediate audit triggers for buyers: review existing PPE inventories against the new marking and performance clauses; adopt a verified phased replacement plan rather than issuing blanket recalls.
- Specification upgrades: mandate specific test-method compliance and marking on procurement contracts to avoid ambiguity during supplier qualification.
- Training and fitment: augment procurement budgets with fit-for-purpose training and inspection protocols — compliance is increasingly a service deliverable, not just a product buy.
OSHA’s referencing practices mean that ANSI revisions quickly become de facto expectations; the report includes a compliance roadmap tying standard clauses to supplier attestations and inspection cadences.
Innovation vectors and margin levers
Key product and process levers that will separate winners from laggards over the next three years include:
- Advanced coatings (anti-fog, anti-scratch, chemical resistance) that increase ASPs and reduce replacement frequency.
- Prescription integration and modular design that expand B2B value capture in occupational health programs.
- Ballistic- and high-impact-rated lines that command premium pricing in specialized verticals (defense, emergency response, heavy industry).
- Digital-enabled services (traceability, digital certificates of compliance, lifecycle analytics) which create recurring revenue opportunities for suppliers and lower TCO for buyers.
Risk map: procurement, supply chain, and market threats
Decision-makers must weigh short-term cost pressures against long-run compliance and safety imperatives:
- Raw-material volatility (polycarbonate resin, specialty coatings) can compress margins rapidly; hedging and multi-sourcing are recommended.
- Counterfeit and non-compliant imports proliferate when standards change — enhanced incoming inspection and supplier audits are non-negotiable.
- Channel disintermediation via e-commerce and private-label programs requires distributors to move up the value chain (services, training, integration) to defend margins.
Strategic recommendations for 2026 decision cycles
For executives preparing budgets and strategy this year, prioritize the following five moves:
- Compliance-first sourcing: Conduct a standards-mapping audit to identify SKUs that require immediate replacement or recertification under ANSI/ISEA Z87.1-2025.
- Supplier segmentation and dual-sourcing: Separate strategic partners (R&D, co-development) from tactical manufacturers (cost, scale) and negotiate outcome-based SLAs tied to compliance and lead-times.
- Invest in product differentiation: Allocate R&D or co-development funds to coatings and prescription integration that increase lifetime value and reduce churn.
- Use concentration analytics for M&A screening: Given current CR3/CR5 dynamics, targeted bolt-ons can rapidly expand footprint or add missing capabilities without triggering price competition in core markets.
- Embed digital certificates and traceability: Reduce procurement risk and increase resale confidence with immutable compliance proofs linked to each SKU.
What the full PW Consulting report unlocks
This executive trailer intentionally omits the granular segmentation tables, regional and application-level percentage splits, and SKU-by-SKU forecasts that constitute the core commercial value of the full study. Subscribers and licensed customers receive:
- Complete regional and application breakdowns, with rolling forecasts and sensitivity analyses.
- SKU- and material-level margin models, including coating adoption scenarios and unit economics by distribution channel.
- Supplier scorecards, audited certification documents, and an editable RFP/RFQ package for immediate deployment.
- M&A and partnership candidates prioritized by strategic fit, integration complexity, and potential EBITDA uplift.
In short, the full report converts macro growth and regulatory change into operational checklists, sourcing actions, and investment roadmaps for 2026. For leaders who must balance safety, compliance, and profitability, the study is designed to be a hands-on playbook rather than a distant forecast.
Next steps
If your organization is updating procurement specifications, evaluating supplier consolidation, or planning product investments this year, PW Consulting’s Safety Glasses Market report is calibrated to inform those exact decisions. The companion dataset and supplier analytics are available through our portal; they contain the proprietary segment matrices and scoring models referenced above. Contact PW Consulting to access the full study and to commission tailored scenario work for your rollout or sourcing calendar.
For detailed analysis of this topic, please visit the official page: Safety Glasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hot Water Storage Tank Market — USD 5,510M in 2025, 4.71% CAGR to 2032
By PW Consulting, 2026-07-12
Hot Water Storage Tank Market — 2026 Strategic Preview for Corporate Decision-Makers
Executive preview
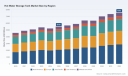
As the market enters its next planning cycle, PW Consulting presents a focused strategic preview that distills the implications of our Hot Water Storage Tank Market study (base year 2025) for executive decision-making in 2026. The market has progressed from roughly USD 4.6 billion in 2020 to about USD 5.51 billion in 2025, and our forecast path—with a compound annual growth rate of 4.71% through the 2026–2032 horizon—targets a market above USD 7.5 billion by 2032. These macro trajectories mask important inflection points driven by regulation, material technology, and shifting application economics. This preview highlights those inflection points, the competitive stakes, and the actionable choices that should sit at the top of C-suite agendas in 2026.
Hot Water Storage Tank Market
Why this study matters for 2026 decisions
-
Strategic timing: 2026 is a hinge year. Old product ladders optimized for low-cost steel and legacy efficiency thresholds are colliding with tightening U.S. and international performance and safety requirements. Companies that align roadmaps to the new regulatory and materials landscape early will avoid costly retrofits and warranty exposures.
Hot Water Storage Tank Market -
Portfolio prioritization: The market’s steady growth gives room to scale new offerings (e.g., low-standby-loss tanks, hybrid storage for heat pumps) without cannibalizing legacy shipments—provided launches are coordinated with channel, warranty, and certification readiness.
Hot Water Storage Tank Market -
Capital allocation: With market expansion forecasted across the decade, management teams must decide whether to allocate incremental CAPEX to scale manufacturing, invest in stainless-lining capabilities, or pursue bolt-on acquisitions to secure premium niches.
Market trajectory — the numbers that inform strategy
Our historical analysis covers 2020–2025 and identifies a steady recovery and expansion path, culminating in a base-year market of USD 5,510 million (2025). The forecast period (2026–2032) incorporates technology adoption curves, regulatory scenarios and commodity price sensitivity, producing a mid-case trajectory that reaches roughly USD 7,565 million by 2032 under a 4.71% CAGR. The series reflects episodic volatility—notably short-term softness and rebounds tied to material-cost cycles and policy announcements—underpinning the importance of flexible production and procurement strategies.
Dynamics shaping 2026 strategy
-
Regulatory tightening: New and pending regulations are recalibrating the performance baseline. For example, updated U.S. regulatory thresholds and tightened standby-loss limits raise the bar for design and performance testing; compliance will be a gating factor for market access in key markets.
-
Certification & safety: Larger capacity storage units are subject to ASME HLW and potable water standards such as NSF 61, and plumbing codes increasingly require third-party certification plus defined safety devices. Certification lead times can be long; manufacturers must sequence product launches to accommodate testing and approvals.
-
Materials and warranties: Advanced stainless linings (e.g., duplex alloys) are displacing sacrificial-anode approaches in commercial tanks, enabling 10–15+ year warranty positioning. That choice has supply-chain, cost, and service implications worth modelling at the product-line level.
-
Channel & application shifts: Residential, commercial, and industrial buyers are re-evaluating lifecycle cost versus upfront cost in light of energy-price volatility and sustainability mandates. This shifts demand toward higher-efficiency solutions and aftermarket service propositions that extend lifetime economics.
Segmentation view (high level)
Our model segments the market by product type (electric, gas, solar, and heat-pump compatible storage), by application (residential, commercial, industrial), and by geography. Each segment behaves differently under regulation, energy-price swings and installation complexity. The full report contains detailed shipments, ASPs, and growth-rate differentials across these segments. In this preview we emphasize the strategic implications rather than disclose granular splits: companies must weigh product-architecture investments (e.g., heat-pump-ready tanks) against channel demand and installation labor constraints.
Competitive landscape — what winners look like in 2026
The market displays moderate concentration: the top three manufacturers account for a material share of industry revenue, and the top five capture roughly two-thirds of industry sales. This structure favors incumbents with broad distribution, deep OEM relationships and scale manufacturing; it also creates niches for differentiated players who can deliver certification-led, high-reliability systems.
Profiles and strategic takeaways
-
A.O. Smith Corporation (Milwaukee, WI) — Scale and channel depth: A.O. Smith’s breadth across residential and commercial makes it a natural consolidator of aftermarket and service opportunities. Strategy: prioritize retrofit kits and digital service offerings that lock in replacement cycles.
-
Rheem Manufacturing Company (Atlanta, GA) — Durability and high-demand applications: Rheem’s emphasis on ruggedized commercial tanks positions it for vertical integration with large facility contractors. Strategy: pursue specification wins in foodservice and healthcare where uptime commands premiums.
-
Bradford White Corporation (Philadelphia, PA) — Contract and specification focus: Known for reliable commercial-grade storage, Bradford White is well-placed to convert specification updates into share gains. Strategy: invest in certification throughput to shorten specification-to-procurement timelines.
-
State Water Heaters (Ashland City, TN) and Ruud Company (St. Louis, MO) — Channel specialization: Strength in contractor networks allows these firms to exploit replacement cycles swiftly. Strategy: couple product upgrades with contractor training and digital installation support.
-
Specialists (Hanson Tank, PVI Industries, American Wheatley, Vaughn, Sioux, Stiebel Eltron) — Niche engineering and compliance: These players compete on custom configurations, ASME-certified vessels, and specialty linings. Strategy: target partnerships with OEMs and large system integrators who require engineered solutions.
Recent evidence of market activity underscores these strategic postures: PVI (Watts Water Technologies) showcased commercial water heaters and storage solutions at the AHR trade event, signaling continued product-platform investment; Stiebel Eltron released a compact domestic mini-tank in early 2026 and highlighted its indirect storage capabilities at the 2026 AHR Expo—concrete examples of product refreshes timed to channel events and procurement cycles.
What the report provides (practical, operational content)
Beyond headline market numbers, our full study is built for immediate commercial use. It includes:
-
Actionable TAM/SAM/SOM models with sensitivity levers for commodity costs, regulatory scenarios and adoption curves by application.
-
Scenario forecasts (base, accelerated, constrained) with decision trees for product launch timing and capacity investment.
-
Competitive playbooks: detailed profiles, product portfolios, certification statuses, and go-to-market strengths/weaknesses for the leading vendors.
-
Procurement and supply-chain diagnostics: major component cost drivers, vendor maps for stainless and glass/cement lining, lead-time stress tests and sourcing alternatives to de-risk production.
-
Compliance matrix: regulatory timelines (including anticipated efficiency and standby loss requirements), testing lead times, and certification impacts on route-to-market.
-
Commercial templates: price erosion curves, aftermarket service economics, and channel incentive structures calibrated by segment.
How leadership should use this intelligence in 2026
-
Prioritize compliance-first roadmaps. Regulatory milestones—especially efficiency and standby-loss changes—should be translated into engineering requirements and release gates today to avoid last-minute redesigns.
-
Invest selectively in materials that reduce total-cost-of-ownership claims. Stainless-lining strategies that eliminate frequent anode replacement can underpin longer warranties and higher ASPs; quantify supplier concentration and long-term price exposure before committing.
-
Channel alignment is a multiplier. Retrofit and replacement volumes are managed through installers and institutional specifiers; invest in training, digital install aids and warranty-backstop programs to accelerate acceptance of premium products.
-
Model service-led revenue. Aftermarket service, spare modules and extended warranties are credible profit pools that can offset slim product margins in commoditized segments.
-
Pursue bolt-on M&A for capability gaps. If internal development of ASME-certified, high-capacity tanks or solar/heat-pump integrations is slow, consider acquiring specialist vendors who bring certification, niche IP, and established project pipelines.
Concluding guidance
For 2026 planning cycles, the essential strategic choice is not whether the market grows—the macro trajectory is clear—but how to participate: as a cost leader in legacy product flows, a premium provider of high-reliability systems, or a hybrid player that monetizes aftermarket and service. The right trade-offs require granular segmentation, supplier-level cost models, and a compliance-aware product roadmap. Our full Hot Water Storage Tank Market report provides the detailed splits, scenario models, and proprietary competitive diagnostics that will allow leadership teams to convert this macro preview into executable 12–36 month plans.
To access the complete dataset, segment-level forecasts, and our proprietary decision-support tools that underpin the recommendations above, please visit the full report page. PW Consulting’s analysts are available for bespoke briefings to translate the study’s findings into an actionable 2026 roadmap for your organization.
For detailed analysis of this topic, please visit the official page: Hot Water Storage Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Pressure Transducers Market USD 360M in 2025; 6.5% CAGR to 2032
By PW Consulting, 2026-07-12
Medical Pressure Transducers Market — Strategic Imperatives for 2026
Executive summary
As healthcare systems recalibrate after successive years of cost pressure, capacity expansion, and regulatory tightening, medical pressure transducers sit at an inflection point. Our PW Consulting analysis shows the global market expanded from approximately USD 280 Million in 2020 to USD 360 Million in 2025 (base year), and is forecast to grow through the 2026–2032 horizon at a compound annual growth rate of 6.5%, reaching roughly USD 535 Million by 2032 (all values in USD Million). For executives planning investments, partnerships, procurement strategies, or M&A in 2026, this market trajectory demands targeted, time-sensitive decisions that balance growth capture with regulatory and operational resilience.
Medical Pressure Transducers Market
Why this study matters for 2026 decision-making
-
Timing of capital allocation — The market’s steady mid-single-digit CAGR creates opportunities for scale plays (volume-driven consumables) and premium-product differentiation (integrated monitoring systems). Firms that commit capital in 2026 can position for the next three budget cycles across hospitals and OEM customers.
Medical Pressure Transducers Market -
Regulatory crosswinds — Prolonged EU certification timelines and growing documentation burdens mean product-to-market lead times are extending; regulatory strategy is no longer a compliance cost but a competitive moat.
Medical Pressure Transducers Market -
Procurement & risk management — The growing importance of disposables, compatibility accessories, and service-level reliability reshapes purchasing criteria for health systems that must weigh unit cost against clinical safety and supply continuity.
-
Technology and interoperability — Incremental improvements in sensor fidelity, connector interoperability, and system integration are unlocking premium pricing for solutions that demonstrably reduce clinical variability and alarm fatigue.
What this report delivers — practical, actionable content
Our Medical Pressure Transducers Market study is designed for executives who need to act in 2026. The report blends market intelligence with decision-oriented tools:
-
Validated market sizing and a 2026–2032 forecast model, with scenario-based sensitivities tied to regulatory timelines and raw-material cost shocks.
-
Competitive benchmarking: product portfolios, distribution models, and go-to-market playbooks for major suppliers and credible challengers.
-
Procurement playbook: total cost of ownership frameworks for hospitals and system integrators, including consumable bundling and service-level contracting.
-
Regulatory pathway mapping: pragmatic timelines and evidence templates for FDA Class II and EU MDR filings, with mitigation plans to shorten approval cycles.
-
Supply-chain and materials analysis: mapping of key inputs (e.g., silicon, specialty alloys, stainless steel, plastics), single-source risks, and inventory strategies to withstand disruption.
-
Risk heatmaps and clinical-safety monitoring protocols, integrating adverse event reporting (e.g., MAUDE signals) into product lifecycle management.
-
M&A and partnership target screens oriented to scale consumable supply, adapter technologies, and aftermarket services.
-
Operational playbooks for contract manufacturing, nearshoring options, and CAPEX sizing for in-house production of transducers.
-
Data appendices and modeling assumptions so teams can rerun scenarios under different pricing, regulatory, or demand assumptions.
Competitive landscape — who matters and why
The transducers market is characterized by a mix of established medical-device OEMs and specialized consumable suppliers. Market concentration is moderate: the leading three players account for a material but far-from-dominant share of industry revenues; the top five firms widen that share modestly. This structure favors both small-scale consolidation and nimble niche competitors who can exploit product adjacencies or compatibility advantages.
Key competitors and strategic postures we analyze in the report include:
-
Edwards Lifesciences Corporation (Irvine, CA) — Known for its TruWave disposable pressure transducers targeted at invasive hemodynamic monitoring. Strengths include strong clinical relationships and brand recognition in critical care. Vulnerabilities include heightened scrutiny on post-market events and the need to defend premium positioning against lower-cost interoperable alternatives.
-
Smiths Medical (Minneapolis, MN) — The TranStar offering positions Smiths as a supplier to both acute-care and perioperative markets. Competitive advantages are breadth of product lines and established distribution; strategic choices revolve around investment in digital calibration and low-cost manufacturing to defend margin against commoditization.
-
ICU Medical, Inc. (San Clemente, CA) — The Transpac family combines integrated and disposable systems for critical care, emphasizing infection control and workflow integration. Opportunities exist to extend services and aftermarket consumables, while maintaining regulatory dossiers across multiple product variants.
-
Merit Medical Systems, Inc. (South Jordan, UT) — With Meritrans solutions, Merit competes on consumable reliability and cost-efficiency. The company is positioned to benefit from procedural growth and cross-sell into existing vascular and interventional portfolios.
-
Argon Medical Devices, Inc. (Plano, TX) — A strong player in pressure monitoring lines and transducer kits used in interventional procedures. Argon’s network and OEM-compatible components make it a strategic supplier for hospitals seeking interoperability and cost control.
Recent developments you cannot ignore
-
Adverse-event reporting has immediate commercial impact: a December 2025 FDA MAUDE entry tying an incident to a major disposable transducer line prompted increased procurement reviews among several purchasing groups. Even single-event MAUDE reports can trigger contract re-evaluations, accelerated user training programs, and defensive field-service expenditures.
-
Interoperability and third-party adapters are reshaping value chains: a recent 510(k) clearance for an invasive blood pressure (IBP) transducer adapter cable expands compatibility across multiple OEM brands. This technically simple but commercially potent innovation accelerates aftermarket competition and forces OEMs to prioritize lock-in strategies through bundled consumables and integrated services.
Regulatory and standards dynamics — practical implications
Three regulatory realities are reshaping product and commercial strategies:
-
Longer certification timelines and higher costs in the EU (multi-fold increases in review duration and 35–50% higher certification costs) demand earlier submission planning and contingency budgets.
-
FDA Class II oversight remains the global benchmark for clinical and biocompatibility expectations; firms should anticipate harmonized evidence requests focused on calibration stability and biocompatibility across reusable and disposable formats.
-
ISO 80601-2-34 governs transducer performance; however, clinical calibration practices vary by facility and clinician. Suppliers that can reduce inter-user variability through design, instructions, and embedded calibration routines earn durable clinical preference.
Strategic recommendations — actionable moves for 2026
-
Adopt a dual-track procurement strategy: qualify at least two suppliers per major site category to reduce service and supply risk; negotiate performance-based contracts with penalties tied to clinical downtime and adverse-event incidence.
-
Invest in compatibility and adapter ecosystems: either through targeted partnerships or in-house adapter families, ensure your solution works seamlessly with leading monitor platforms — compatibility buys access and defends against third-party encroachment.
-
Pursue product differentiation via calibration intelligence: embed low-cost calibration verification and digital traceability so hospitals can document compliance and reduce clinician variability — a clear value add for premium pricing.
-
Mitigate regulatory risk by front-loading evidence generation: initiate clinical and bench testing in 2026 to compress time-to-market for 2027 launches; leverage pre-sub and notified-body engagement to limit surprises.
-
Secure raw-material pathways: lock long-term purchase agreements for critical inputs (silicon components, specialty alloys, polymers) and diversify suppliers to blunt price shocks and single-source failures.
-
Evaluate M&A and JV opportunities that add scale in consumables, adapter technology, or aftermarket service networks—transactions that add predictable recurring revenue will be accretive in a market driven by disposables.
How PW Consulting supports execution
PW Consulting combines syndicated market intelligence, bespoke scenario modeling, and hands-on regulatory and supply-chain advisory to convert the market’s growth runway into executable advantage. Our report gives you the quantitative forecasts, but more importantly, the operational templates — procurement scorecards, clinical evidence plans, and integration checklists — that your teams can deploy in weeks, not months.
Next steps
For teams making 2026 resource-allocation decisions, the choice is straightforward: act now to translate mid-single-digit growth into reliable, defensible margin expansion. Our full report provides the granular segmentation, region- and application-level insights, and company benchmarking necessary to finalize vendor selections, capital plans, and M&A screens. Visit the PW Consulting report landing page to access the complete intelligence package and supporting datasets.
For detailed analysis of this topic, please visit the official page: Medical Pressure Transducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
SAXS market set to reach USD 266.01M by 2032 at 6.8% CAGR — PW Consulting
By PW Consulting, 2026-07-12
Small Angle X‑ray Scattering (SAXS) Market — Strategic Preview for 2026 Decision Makers
Executive preview
The SAXS market is entering 2026 from a position of steady, commercially meaningful expansion. Our base-year view shows the global market grew from USD 110.0 Million in 2020 to USD 170.0 Million in 2025. The market is forecast to continue expanding at a compound annual growth rate (CAGR) of 6.8% through a multi‑year horizon, with a near‑term estimate of roughly USD 184.0 Million in 2026 and a long‑range target approaching the high‑two‑hundreds (USD 266.0 Million by 2032). For executives planning 2026 budgets, these macro figures translate into a market that is neither hyper‑cyclical nor saturated — it rewards timely product and commercial choices, especially where technology and service differentiation exist.
Small Angle X-ray Scattering (SAXS) Market
Why this study matters for 2026 strategic decisions
- Capital allocation: If your organization faces competing R&D, manufacturing or M&A choices, a market growing at ~6.8% CAGR requires targeted investments rather than broad, undirected spending. The right timing (early 2026) can capture share as instrument upgrade cycles re‑accelerate.
- Product roadmap prioritization: SAXS demand favors platforms that lower user complexity, integrate advanced detectors, and bundle analytics — decisions that should be reflected in 2026 product roadmaps and FY26 R&D budgets.
- Go‑to‑market and services: The installed base is a durable source of aftermarket revenue (training, calibration, consumables and software subscriptions). Service model choices made in 2026 will determine recurring revenue profiles into the next decade.
- M&A and partnerships: With a moderately concentrated vendor landscape, targeted acquisitions or alliances (software, detectors, niche application specialists) can accelerate capability builds that would otherwise take years of internal development.
What the PW Consulting report delivers (practical contents)
This research is designed as an operational playbook for commercial, product and corporate strategy teams. Highlights include:
Small Angle X-ray Scattering (SAXS) Market
- Market sizing and scenario modelling — transparent methodology, base‑year reconciliation and alternative demand scenarios through 2032 with sensitivity tests against instrument cycle length and capital budgets in key end markets.
- Go‑to‑market blueprints — segmentation of buyer personas (core academic, industrial R&D, semiconductor metrology, biopharma), procurement pathways, typical CAPEX approval triggers, and decision timelines.
- Product and technology roadmaps — prioritized feature sets (e.g., GISAXS/GI‑SAXS, USAXS capability, temperature‑controlled stages, detector upgrades) tied to willingness‑to‑pay and incremental margin models.
- Commercial benchmarking — pricing bands, bundling architectures (instrument + software + service), channel strategies and subscription vs perpetual licensing tradeoffs.
- Aftermarket and services strategy — calibration, ISO/NIST alignment, training programs, and recurring revenue playbooks for 2026 planning.
- Regulatory and standards mapping — implications of ISO 17867:2020, NIST SRM controls, and the pathways to differentiate through compliance and traceable calibration.
- Competitive playbook and M&A targets — company profiles, capability gaps, and integration approaches to accelerate market entry or expand addressable use cases.
Note: this preview intentionally omits granular segment percentages and line‑item revenue splits — those core intelligence elements are reserved for the full report and supporting data tables.
Small Angle X-ray Scattering (SAXS) Market
Market dynamics and emergent themes
Three structural dynamics are shaping vendor economics and buyer behaviour as we enter 2026:
- Technology consolidation around user simplicity and integration. Buyers are moving away from stitch‑together configurations toward platforms that combine SAXS/WAXS/USAXS/GISAXS capabilities on a single goniometer or modular suite. Detectors with higher sensitivity and lower noise, and systems offering temperature‑controlled or in‑situ stages, are competitive differentiators.
- Analytics and software as a value lever. Advanced data processing, visualization and automated interpretation reduce time‑to‑result and lower skill barriers. Vendors that couple hardware sales with robust analytics (including native support for standards and reference materials) are capturing higher lifecycle value.
- Industrialisation of niche applications. Semiconductor metrology (T‑SAXS/TSAXS) and certain high‑value industrial workflows are changing the buyer profile — purchase decisions increasingly factor in traceability, throughput and integration into production metrology chains.
Standards and calibration infrastructure matter. ISO 17867:2020 and reference materials such as NIST SRM 3600 create a baseline expectation for measurement traceability; vendors that embed compliance workflows and offer easy calibration packages reduce adoption friction.
Competitive landscape — how incumbent and specialist players are positioning
The SAXS vendor ecosystem blends established instrument OEMs and nimble specialists. Market concentration is meaningful: the top three players collectively hold a majority share and the top five widen that lead. That concentration creates both barriers and opportunities — incumbents have scale, but focused innovators can win by solving narrowly defined, high‑value use cases.
- Anton Paar GmbH (Graz, Austria) — known for the SAXSpoint series, Anton Paar is leveraging advanced detectors, temperature‑controlled stages and GISAXS capabilities. Recent field engagement includes a symposium and hands‑on workshops in April 2026 that reinforce customer education and shorten purchase cycles.
- Bruker Corporation (Billerica, MA, USA) — a full‑stack provider with the D8 ADVANCE platform and DIFFRAC.SAXS analytics. Bruker’s strength is its integrated hardware‑software ecosystem and broad instrument portfolio that appeals across academic and industrial users.
- Malvern Panalytical Ltd (Malvern, UK) — offers the Empyrean Nano edition designed for combined SAXS/WAXS/USAXS and bioSAXS workflows. Their approach targets multi‑modal users seeking a single goniometer solution.
- Rigaku Corporation (Akishima, Tokyo, Japan) — focused on industrial applications including TSAXS for semiconductor metrology; recent technical notes (2025) and journal features position Rigaku for increased uptake in critical‑dimension and 3D device metrology.
- Xenocs SAS (Grenoble, France) — delivers high‑performance platforms (e.g., Xeuss family) and analytical software; Xenocs is investing to bridge high‑end research and routine industrial workflows.
- Shimadzu Corporation (Kyoto, Japan) — a broad instrumentation vendor with strong materials and nanotech footprints; Shimadzu’s global channels help commercial reach in territories with active manufacturing sectors.
- Hecus X‑ray Systems GmbH (Austria) — a specialist in compact laboratory SAXS systems targeting customers that prioritize footprint and cost‑efficiency.
Recent developments across these players — conferences, workshops, technical notes and webinars — demonstrate an emphasis on customer education, application validation and faster onboarding. These activities are signals that vendors are competing not just on hardware specs but on lowering adoption friction.
Strategic playbook for 2026 — choices that matter
- Prioritize modularity and software: If you are a hardware OEM, accelerate modular product variants and secure software IP or partnerships that make data interpretation turnkey for non‑specialists.
- Invest in standards‑aligned calibration as a service: Build calibrated reference kits and subscription calibration services aligned to ISO 17867 and NIST SRM workflows to shorten procurement cycles in regulated industries.
- Leverage training and community: Workshops, webinars and university partnerships (as seen in recent vendor activity) are cost‑effective channels to seed demand and build a pipeline of trained users who will prefer your platform.
- Consider tuck‑ins in analytics or detector tech: With top vendors concentrating share, strategic acquisitions in software or detector IP can be a faster path to capability than internal development alone.
- Design for recurring revenue: Aftermarket, consumables and software subscriptions can materially lift margins; define clear metrics and targets for 2026 to shift commercial mix.
Signals to monitor and KPIs to set for 2026
- Order intake and lead times for instruments (quarterly cadence).
- Installed base growth and utilization rates (number of active systems vs service contracts).
- Software conversion rate (instrument sale → analytics subscription) and average revenue per user (ARPU) for services.
- R&D milestones for detector sensitivity, automation and integration with metrology lines.
- Adoption of standards (ISO 17867, NIST SRM usage) across customer segments.
Conclusion — how to use this preview
For 2026 strategy cycles, SAXS is a growth market with defined technical and commercial levers. The macro trajectory — from USD 110 Million in 2020 to USD 170 Million in 2025, a projected USD 184 Million in 2026, and a long‑range market approaching USD 266 Million by 2032 at ~6.8% CAGR — supports selective investment. The competitive landscape is concentrated but dynamic; differentiation through integrated analytics, standards‑aligned calibration, and value‑added services will determine winners.
This article is a strategic preview. The full PW Consulting SAXS market study contains the granular segmentation, regional and application breakdowns, pricing bands, and deal‑level benchmarks necessary for executable plans. Access the complete report and datasets to convert these directional insights into precise FY26 investments and go‑to‑market actions.
For detailed analysis of this topic, please visit the official page: Small Angle X-ray Scattering (SAXS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


