



Category: Machinery & Automotive
PW Consulting: Intelligent Hearing Protection Market to Reach USD 895M by 2032 at 8.5% CAGR
By PW Consulting, 2026-07-08
Intelligent Hearing Protection Device Market — A Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a strategic preview of the Intelligent Hearing Protection Device market designed to orient executive teams, corporate development functions, and product leaders as they plan for 2026. This briefing synthesizes the macro trajectory, regulatory inflection points, technology and cost dynamics, and competitive posture that will determine winners and laggards over the next business cycle. It deliberately demonstrates analytical depth while reserving the granular segment matrices and proprietary subsegment allocations for the full report—delivered to subscribers seeking transaction- and product-level intelligence.
Intelligent Hearing Protection Device Market
Why 2026 Is a Strategic Pivot
Several converging forces make 2026 a make-or-break year for entrants and incumbents in intelligent hearing protection. First, regulatory clarification in late 2024 and early 2026 redefined employer obligations and audiometric practice in occupational environments—raising minimum functional and documentation requirements for hearing protective equipment. Second, advances in sensor fusion, edge AI for speech-in-noise, and low-power wireless architectures have matured to the point where product differentiation is technical rather than speculative. Third, component cost volatility—driven by raw material swings in 2024–2025—has compressed pricing flexibility and shifted margin economics across the value chain.
Intelligent Hearing Protection Device Market
Executives who act in 2026 with a clear understanding of these dynamics will be positioned to reshape their portfolios, supply chains, and commercial routes for the next growth phase.
Intelligent Hearing Protection Device Market
Market Trajectory: The Big Numbers You Need to Plan Around
-
Market scale and momentum: The intelligent hearing protection market reached a base-year size of USD 505.0 Million in 2025 (base year).
-
Near-term outlook: Our model projects expansion in 2026 and through the 2026–2032 forecast period at a compounded annual growth rate (CAGR) of 8.5%.
-
Longer-term view: Under our central case assumptions—reflecting regulatory normalization, steady commercial adoption in industrial and defense sectors, and ongoing product premiumization—the market advances materially through 2032.
These headline figures create the investment envelope for R&D allocation, go-to-market scaling, and M&A sizing. They also serve as guardrails when stress-testing pricing strategies and margin recovery scenarios under component cost pressure.
Primary Demand Drivers and Structural Restraints
-
Regulatory uplift: Revisions to personal protective equipment standards and audiometric practice have increased the functional baseline for acceptable hearing protection in occupational settings. These changes raise minimum performance requirements and create a near-term replacement cycle for legacy passive devices.
-
Workforce safety economics: Employers are increasingly calculating total cost of ownership for hearing loss prevention (liability, productivity, and retention), tipping procurement toward smarter, data-enabled solutions.
-
Technology enabling adoption: Breakthroughs in active noise cancellation, adaptive speech enhancement, and multi-channel Bluetooth connectivity reduce the trade-off between protection and situational awareness that historically limited adoption.
-
Raw material and component cost volatility: Industry data indicates that component-level costs for electronic PPE were the primary driver of price variation through 2024–2025. Margin sensitivity to component costs is a strategic operational risk for firms that lack hedging or supplier diversification.
-
Adoption friction: Total cost, device comfort, and integration with legacy communications systems remain adoption hurdles—especially for highly conservative procurement environments such as defense and heavy manufacturing.
Competitive Landscape: What the Market Structure Tells Us
The market exhibits moderate concentration—top-three firms account for roughly 53% of industry revenue, and the top-five capture approximately 65%. This structure produces a dual dynamic: established brands retain scale advantages in distribution and compliance-sensitive accounts, while smaller, technology-focused specialists are potent sources of innovation.
-
3M Company: Well-positioned with an established industrial and defense channel presence and strong IP in electronic hearing protectors and protective communications systems. 3M’s advantage is breadth—product lines that combine active suppression, environmental listening, and Bluetooth integration—making it the default supplier in many safety programs.
-
Sensear: A pure-play innovator that leverages patented audio processing to enhance speech intelligibility in high-noise environments. Sensear exemplifies a high-velocity commercialization model that pairs specialized hardware with tailored service agreements for high-value industrial accounts.
-
Hellberg Safety AB: Focused on ergonomic and connectivity features (Bluetooth, multi-point connections), Hellberg competes on integration and user experience—especially in shooting sports and select industrial niches.
-
Phonak / Sonova Group: Leveraging hearing-aid heritage, these firms are accelerating the application of adaptive speech-in-noise and AI techniques to protection products. Their advantage lies in digital signal processing expertise and access to clinical validation resources.
-
Honeywell, MSA, Etymotic: These players bring scale in safety distribution, established customer relationships, and the ability to bundle hearing protection with broader safety systems. Their strategic options include deeper integration with wearable safety ecosystems and subscription services for monitoring and analytics.
Collectively, these competitors demonstrate two sustainable routes to advantage: branded system sales supported by regulatory and channel strength, and narrow, high-margin technical differentiation sold into premium use cases. Strategic entrants must choose and invest in one path—or build a credible hybrid architecture that can be scaled without sacrificing margin.
Commercial & Product Strategy Playbook for 2026
-
Prioritize regulated channels: With OSHA clarifications and PPE fit mandates, procurement in construction and industrial accounts will increasingly prefer vetted suppliers. Gaining inclusion on approved safety vendor lists will accelerate volume and reduce sales cycles.
-
Design for integration: Products that deliver seamless interoperability with existing communications and safety monitoring platforms have a decisive edge. Open APIs and modular firmware update strategies reduce buyer friction and lengthen product lifecycles.
-
Hedge the supply chain: Secure dual or regionalized sourcing for key electronic components and prioritize contract terms that mitigate raw-material-driven price shocks.
-
Move toward outcome-based commercial models: Subscription and managed-service arrangements—bundling devices with compliance reporting and analytics—unlock sticky revenue and convert price-sensitive buyers into lifetime customers.
-
Invest selectively in clinical and field validation: Evidence of efficacy in preventing hearing loss and improving communication under real-world conditions accelerates enterprise adoption and reduces procurement risk perceptions.
Regulatory & Policy Imperatives
-
OSHA updates on PPE fit and audiometric practice materially affect device acceptance criteria. Firms must align product testing, user-fit protocols, and documentation to the new standards to remain eligible in key accounts.
-
Policy shifts are also an opportunity: vendors that proactively engage with regulators and provide usable compliance tools (e.g., fit records, device downtime logs) gain a commercial differentiator.
Where Investors and M&A Teams Should Focus
-
Buy-side: Look for targets that offer proprietary signal-processing capabilities, proven field validation, and established entry points into regulated enterprise accounts. Scale assets—distribution agreements and government contracts—raise deal multiples but reduce integration risk.
-
Sell-side / Exit planning: Companies that can demonstrate recurring revenue (managed services, analytics) command premiums. Standardize contracts and documentation around regulatory compliance to de-risk due diligence.
-
Partnerships: Strategic alliances with safety distributors, hearing health clinics, and industrial OEMs can accelerate adoption without large upfront CapEx.
What PW Consulting’s Full Report Provides (Practical, Transaction-Ready Intelligence)
-
Comprehensive market sizing and peer-validated forecasts (historical 2020–2025 base and granular 2026–2032 scenarios).
-
Actionable go-to-market playbooks for four archetypal entrants (global incumbent, regional challenger, clinical/audiology-focused player, and pure-play innovator).
-
Supply-chain vulnerability heat maps and mitigation recipes aligned to component categories and cost drivers.
-
Regulatory readiness checklists and model contract language to streamline procurement acceptance in regulated industries.
-
Competitive scorecards and strategic positioning matrices for the leading vendors, including capability gaps and M&A fit analyses.
-
Scenario-based valuation ranges that convert growth and margin assumptions into acquisition pricing guidance for private equity and strategic acquirers.
Note: This preview intentionally omits detailed regional and application-level splits and the granular segment tables that are central to transaction modeling. Subscribers receive the complete segmentation and the empirical tables required to build TAM/SAM/SOM models and to support definitive M&A bids.
Immediate Actions for 2026
-
Complete a regulatory readiness audit for product portfolios to identify gaps versus the updated PPE and audiometry requirements.
-
Quantify margin sensitivity to component-cost scenarios and implement selective supplier hedges or dual-sourcing arrangements.
-
Decide on a commercial model pivot: prioritize either channel breadth (safety distributors and enterprise procurement) or depth (value-added managed services and compliance solutions).
-
Initiate targeted partnerships or bolt-on acquisitions that fill technical gaps (speech enhancement, Bluetooth/mesh connectivity) rather than attempting full-stack in-house development under time pressure.
Closing Perspective
The intelligent hearing protection market sits at an inflection: regulatory tightening and technical maturation make 2026 a high-leverage year for strategic action. The market’s growth envelope—anchored by the 2025 base and an 8.5% CAGR in our central forecast—creates substantial opportunity for firms that can combine technical credibility, regulatory alignment, and resilient supply economics. However, the market’s current concentration means incumbent relationships and distribution scale continue to matter. Tactical clarity—choosing which axis of advantage to pursue—will separate market participants that capture disproportionate value from those compelled into commoditization.
For teams preparing bids, shaping product roadmaps, or evaluating M&A opportunities, PW Consulting’s full report provides the granular segmentation, valuation inputs, regulatory matrices, and go-to-market templates required to convert strategic intent into successful execution. Contact PW Consulting to obtain the complete dataset, competitive models, and bespoke advisory support necessary to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Intelligent Hearing Protection Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: NIR Spectroscopy Analyzers — USD 596.9M in 2025, 5.8% CAGR to 2032
By PW Consulting, 2026-07-08
Near‑Infrared Spectroscopy (Analyzers) Market — Strategic Outlook for 2026 Decision‑Makers
As organizations plan capital allocation and product strategy for 2026, Near‑Infrared (NIR) spectroscopy is shifting from a specialized laboratory technique to a broadly deployed quality, compliance, and process control technology. Our PW Consulting Near‑Infrared Spectroscopy (Analyzers) Market study — built on a base year of 2025 with a historical window covering 2020–2025 and a forecast horizon extending through 2032 — synthesizes quantitative market trajectories and qualitative strategic guidance that leaders can act on immediately. The market reached an estimated USD 596.9 Million in 2025 and is projected to grow to roughly USD 643.7 Million in 2026, following a compound annual growth outlook of approximately 5.8% across the forecast period. This trajectory reflects accelerating adoption across manufacturing, food safety, agriculture, and regulated life‑sciences environments.
Near-infrared Spectroscopy (Analyzers) Market
Why this research matters for 2026 planning
-
Investment prioritization: Capital budgets in 2026 will favor assets that deliver faster time‑to‑value and reduce regulatory risk. NIR analyzers increasingly meet both criteria by enabling inline and at‑line quality assurance and by dovetailing with regulatory frameworks such as the FDA's Process Analytical Technology (PAT) initiative.
Near-infrared Spectroscopy (Analyzers) Market -
Technology convergence: Portable and cloud‑connected NIR platforms are unlocking new use cases in field sampling and supplier validation. Our study isolates the commercial and technical inflection points where handheld devices and in‑line systems deliver differentiated ROI.
Near-infrared Spectroscopy (Analyzers) Market -
Supplier engagement strategy: The NIR vendor landscape exhibits moderate concentration (CR3 ~45%; CR5 ~60%), indicating both dominant OEMs and a meaningful long tail of specialized suppliers. That structure creates options for strategic partnerships, selective insourcing, or targeted M&A depending on a buyer’s scale and objectives.
Market trajectory and what it implies
The near‑term market momentum is underpinned by two complementary dynamics. On the demand side, regulated industries (notably pharmaceutical/biotech and food) are accelerating deployment of NIR for rapid compositional analysis, process control, and non‑destructive testing. On the supply side, instrument miniaturization, improved signal‑to‑noise performance, and integrated analytics reduce barriers to adoption for non‑specialist users. Historical data covering 2020–2025 shows resilient growth through multiple macro cycles; our forecast to 2032 projects steady expansion as NIR penetrates new use cases such as remote sensing, OEM embedded instrumentation, and AI‑driven material identification.
For 2026 decision‑makers, the practical implication is straightforward: treat NIR as a scalable platform rather than a single product purchase. Investment choices should prioritize interoperability (data standards, 21 CFR Part 11 readiness), lifecycle support (calibration, model maintenance), and business process integration (ERP/MES connectivity). Doing so preserves optionality — allowing organizations to adopt handheld spot checks today while migrating to inline process control as volume and regulatory requirements increase.
What the report delivers — practical, action‑oriented content
-
Proven market sizing and forecast models (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario analysis and sensitivity testing to support budget planning and downside risk assessment.
-
Vendor benchmarking templates and a supplier scorecard framework that evaluate technical fit, regulatory readiness, support footprint, and total cost of ownership — designed to be adapted to enterprise procurement cycles.
-
Use‑case playbooks and decision trees for rapid piloting: lab replacement, at‑line quality verification, inline process control, field verification, and OEM integration. Each playbook includes KPIs, sample project timelines, and a three‑year ROI model.
-
Regulatory compliance checklists and mapping (including alignment with FDA PAT principles and 21 CFR Part 11 evidence controls), which help reduce implementation friction for life‑sciences and food companies.
-
Commercial considerations: pricing and procurement levers, service and calibration economics, and aftermarket/software monetization scenarios — to sharpen vendor negotiations and capital planning.
-
Launch readiness and go‑to‑market guidance for companies seeking to commercialize NIR‑enabled offerings, including channel strategies for OEMs and system integrators.
Competitive landscape — how incumbents and challengers are positioning
The NIR ecosystem combines established instrumentation OEMs, specialists focused on portable and field systems, and photonics component suppliers. Key strategic archetypes we observe are: integrated instrument vendors that offer end‑to‑end validation and service; portable‑first challengers that emphasize field usability and cloud analytics; and component/OEM suppliers enabling white‑label integrations. Selected vendor profiles from the study highlight how these archetypes map to practical strengths:
-
Bruker Corporation — offers dedicated FT‑NIR instruments tailored for process control and high‑precision lab environments; strong in engineered solutions for industrial applications.
-
FOSS A/S — notable for feed and food analyzers with cloud connectivity and AI analytics, positioning for high‑volume, field‑oriented customers needing rapid, standardized outputs.
-
Metrohm AG — focuses on validated NIR analyzers that meet stringent regulatory documentation needs, with platforms designed for liquid, solid, and viscous samples.
-
Thermo Fisher Scientific & PerkinElmer — legacy lab instrumentation providers extending into food and process markets, leveraging global support networks and proven calibration frameworks.
-
Agilent & Shimadzu — emphasize integration of NIR into broader analytical portfolios, attractive to enterprises that prefer single‑vendor relationships for multi‑modal testing.
-
Galaxy Scientific, Viavi, Ocean Insight, and Spectral Evolution — represent the portable, embedded, and remote sensing segments, pushing performance boundaries in ruggedized and OEM‑embedded applications.
-
Ibsen Photonics — a critical provider for OEMs seeking compact spectrometer modules, enabling downstream system differentiation.
-
908 Devices — increasingly relevant after strategic acquisitions, focusing on AI‑powered handheld analyzers with cloud subscription models for rapid material identification.
These positioning differences matter when selecting a supply partner in 2026. Enterprises should score vendors not only on instrument performance but also on cloud strategy, model maintenance services, regulatory documentation, and lifecycle cost.
Signals to watch in 2026 — near‑term tactical priorities
-
Regulatory adoption: Watch how PAT framework adoption and documentation expectations evolve within key jurisdictions. Vendors with pre‑built validation packages will lower time‑to‑deployment risk for regulated customers.
-
Platform convergence: The pace at which handheld devices incorporate robust cloud analytics and subscription services will determine where value shifts — toward hardware sales or recurring software revenue.
-
M&A and partnerships: Recent activity (for example, a notable acquisition that added integrated hardware and cloud subscription capabilities to a handheld NIR provider) signals consolidation that incumbents and challengers can leverage to accelerate route‑to‑market.
-
Performance breakthroughs: Product introductions offering step‑change spectral resolution and signal‑to‑noise in field instruments expand high‑resolution remote sensing and library‑driven applications.
How to use this research in your 2026 decision cycle
-
Procurement strategy: Use the vendor scorecard and TCO templates to run parallel procurement tracks (best‑of‑breed vs. single‑vendor) and to stress‑test budgets against adoption scenarios spanning lab replacement to full process integration.
-
Pilot design and scaling: Apply our use‑case playbooks to design 3‑month pilots with clear go/no‑go criteria and five‑step calibration and model governance playbooks to avoid common scale‑up failures.
-
Regulatory readiness: Leverage the compliance checklist as a gate in your supplier selection process — requiring demonstrable evidence of 21 CFR Part 11 capabilities and PAT alignment where applicable.
-
Strategic partnerships and M&A: Assess acquisition targets and partner fits using our consolidation framework that maps tech capability, addressable market adjacency, and recurring revenue potential.
Transparency and the “trailer” approach
Consistent with the “trailer” principle of this briefing, we present firm‑level positioning, market dynamics, and the high‑level sizing that matter for 2026 decisions while deliberately reserving granular segmentation outputs and vendor‑specific share tables for the full report. The study contains detailed regional and application splits, product‑type breakdowns, and downloadable financial models that are essential for procurement negotiations and board‑level investment approvals. If your 2026 plans require segmentation‑level forecasts or supplier share analysis to support investment committees, those elements are available in the full deliverable.
Final takeaways
NIR spectroscopy is maturing into a platform technology with clear, measurable benefits for quality, compliance, and operational efficiency. For 2026, the smart playbook balances immediate productivity wins from handheld and at‑line deployments with longer‑term investments in inline, validated process control and cloud‑native analytics. PW Consulting’s market study gives executives the analytical scaffolding and practical tools to convert market opportunity into repeatable business outcomes — while preserving the detailed segmentation and supplier intelligence that underpin expert procurement and M&A decisions.
Contact PW Consulting to access the full report, supplier scorecards, and the interactive forecast toolkit that will enable your 2026 NIR strategy to move from concept to execution.
For detailed analysis of this topic, please visit the official page: Near-infrared Spectroscopy (Analyzers) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Embedded Computer Market to Grow at 6.8% CAGR Through 2032
By PW Consulting, 2026-07-08
Embedded Computer Market — Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
PW Consulting’s Embedded Computer Market research (base year 2025) synthesizes five years of historical evidence and a seven‑year forecast horizon to 2032, delivering an actionable view for executives making capital, product and supply‑chain choices in 2026. At the macro level, the market has grown steadily from the 2020 baseline and, with a 6.8% compound annual growth rate (CAGR) in our central forecast, is projected to approach the mid‑hundreds of millions of USD by 2032. Market concentration is moderate: the top three and top five suppliers account for a meaningful but not overwhelming share of industry revenues, creating a competitive landscape where scale and specialization coexist.
Embedded Computer Market
Why this study matters in 2026
-
Strategic timing: 2026 is a pivot year. Emerging architectures (notably RISC‑V), AI‑native edge compute, and wafer allocation shifts in semiconductor supply chains are re‑shaping procurement and product roadmaps. Decisions made this year will determine product relevance and node access through the next design cycle.
Embedded Computer Market -
Risk management: structural memory and high‑end DRAM allocation to AI servers is constraining legacy embedded components. Our report outlines mitigation strategies that preserve time‑to‑market while protecting margin.
Embedded Computer Market -
Commercial differentiation: with CR3 and CR5 figures indicating neither pure commoditization nor dominant monopoly, targeted product positioning and focused partnerships remain high‑impact levers for growth.
What the research delivers — practical contents
The report balances strategic analysis with hands‑on tools for procurement, R&D and business development teams. Key deliverables include:
-
Robust market sizing and growth scenarios: historical (2020–2025) and forecast (2026–2032) trajectories under base, upside and downside assumptions calibrated for supply‑chain shocks and accelerated AI demand curves.
-
Technology deep dives: comparative analysis of processor families (including the rapid transition of RISC‑V from “alternative” to mainstream in embedded systems), AI accelerators, memory architectures and thermal/ruggedization approaches for edge deployments.
-
Vendor benchmarking: a framework that scores product portfolios across functional performance, long‑term availability, ecosystem openness, and integration readiness—designed for buyer selection and partner prioritization.
-
Supply‑chain playbook: scenario planning for semiconductor scarcity, procurement levers to lock long‑lead components, and alternate sourcing strategies for embedded DRAM and flash.
-
Integration checklists and reference architectures to accelerate OT–IT convergence, secure edge compute rollouts and certified pathways for regulated verticals.
-
Commercial go‑to‑market templates and pricing sensitivity matrices for suppliers entering or expanding in the embedded space.
-
Case studies: vendor and end‑user implementations across industrial automation, automotive, medical and mobile vehicle platforms—showing tradeoffs between compute density, power consumption and operational reliability.
Competitive landscape — what matters to buyers and strategists
The embedded computer market combines specialist OEMs, established industrial automation incumbents, and vertically focused providers. Buyers face a choice between platform breadth and vertical depth. Our vendor analysis highlights the strategic positioning of core players:
-
Advantech (Taiwan) emphasizes industrial IoT convergence with box PCs and edge platforms tailored to OT environments—strengths include extensive solutions for automation and a broad integration ecosystem.
-
Siemens (Germany) brings PLC‑grade embedded controllers and logic systems with deep integration into manufacturing process stacks—appealing where long product life cycles and certification matter.
-
Beckhoff Automation (Germany) leverages EtherCAT and real‑time embedded modules for high‑performance control—differentiated in applications requiring deterministic behavior.
-
AAEON, OnLogic, IEI Technology, Cincoze, Neousys, GIGAIPC and similar OEMs (primarily Taiwan and the U.S.) occupy the rugged/industrial edge and AI module niche—competing on customization, thermal design and AI‑ready platforms.
-
Specialists such as Gaisler provide high‑reliability, radiation‑hardened systems for space and extreme environments, while Eurotech and Premio position through bespoke solutions for sectors like medical and transportation.
-
Component and systems adjacents—Innodisk and Cohu, among others—differentiate through embedded storage, network modules, and test/automation integration services.
These vendor archetypes map onto buyer priorities: long lifecycle, certified ecosystems, AI acceleration, or cost‑optimized scale. Our report contains a decision matrix that matches enterprise procurement goals to vendor capabilities and supplier risk profiles.
Market dynamics and risk vectors
-
Semiconductor allocation: foundries and IDMs are prioritizing wafer capacity for AI accelerators and server DRAM, diminishing the availability of legacy memory and NAND intended for embedded systems. This is a persistent structural risk through 2026 and beyond—requiring firms to plan memory‑neutral architectures or secure supply via contractual commitments.
-
RISC‑V adoption: the open ISA has transitioned into production‑grade use cases in 2026, especially for automotive‑grade, AI‑native embedded designs. Its adoption accelerates supplier diversification but increases short‑term integration complexity for teams used to ARM/x86 toolchains.
-
Event-driven innovation: product showcases at embedded world 2026 reinforced two themes—an intensifying AI focus at the edge, and Taiwan’s prominent role in European market launches. These events also foregrounded new modular AI platforms and integrated network modules that change deployment economics.
-
Regulatory and certification trends: award‑winning innovations at industry events show a move toward adaptive displays, trusted AI primitives and functional safety extensions—factors that change time‑to‑market and validation timelines.
How to use this analysis to inform 2026 strategy
-
Make architecture bets with a hedged plan: for new product lines, favor modular stacks that can switch between processor ecosystems (RISC‑V/ARM) and support multiple memory suppliers. Our architecture checklist reduces rework risk while preserving differentiation.
-
Lock critical components early: use multi‑year offtake clauses, co‑engineering agreements and consortia buying for high‑risk items such as embedded DRAM, SLC NAND and specialized AI accelerators.
-
Prioritize edge software portability: invest in abstraction layers and containerized inference paths to make hardware swaps lower cost and faster—particularly important as AI inference moves closer to sensors.
-
Assess supplier concentration vs. specialization: given the market’s moderate concentration, consider partnering with niche specialists for high‑value verticals and with larger integrators when lifecycle and certification are core buying criteria.
-
Operationalize scenario planning: establish trigger‑based playbooks tied to memory price, lead time, and geopolitical events to accelerate procurement or pivot design choices when thresholds are met.
What we are intentionally withholding — and why
This executive introduction demonstrates the analytical approach and strategic line of sight of our full study but omits proprietary granular subsegment tables and detailed regional/application split values that are included in the paid report. Those datasets—and the vendor scorecards that use them—contain the tactical numbers enterprises need to execute supplier selection, pricing negotiations and capital allocation. The omission is deliberate: the full dataset is available in our downloadable report, which also contains interactive models and supplier comparison dashboards for immediate use.
Next steps for leaders
-
Procurement & supply‑chain heads: request the supply‑chain playbook and scenario models to harden sourcing strategies for memory and AI accelerators.
-
Chief product officers: use the architecture checklist and vendor decision matrix to converge on a platform roadmap that balances RISC‑V readiness with long‑term software support.
-
Business development teams: leverage our vendor benchmarking and go‑to‑market templates to structure partnerships with system integrators and regional channel leaders showcased in the report.
Conclusion
The embedded computer market in 2026 sits at the intersection of industrial digitization, AI diffusion to the edge, and constrained component economics. PW Consulting’s research translates those macro forces into pragmatic steps—sizing risk, prioritizing vendor relationships, and aligning product architecture to market realities. For organizations that must decide on platforms, suppliers or investments this year, the study offers the evidence base and playbooks necessary to move from strategic intent to operational execution. For the granular subsegment metrics, supplier scorecards and interactive scenario tools that operationalize these recommendations, download the full report from PW Consulting.
For detailed analysis of this topic, please visit the official page: Embedded Computer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Turntables Market to Reach USD 619.7M by 2032 at 4.85% CAGR
By PW Consulting, 2026-07-08
Turntables Market — 2026 Strategic Preview
As the vinyl revival matures into a structurally significant market segment, PW Consulting’s Turntables Market study provides executives and investors with a practical, decision-grade roadmap for 2026 and beyond. Built on a base year of 2025 and a historical window covering 2020–2025, the study projects the market through 2032 using a rigorous mix of primary interviews, channel sell-through data, and component‑level supply analyses. The global market is sizeable and expanding: from an estimated USD 450.06 Million in 2025 it is projected to grow to roughly USD 619.72 Million by 2032, driven by a forecast CAGR of 4.85% across the 2026–2032 period. These topline dynamics matter because they convert cultural momentum into investible growth.
Turntables Market
Why this research matters for 2026 corporate decisions
- Timing of investment: A steady mid‑single-digit CAGR creates windows for targeted product investment, manufacturing scale‑ups, and margin improvement without requiring speculative blockbuster hits. Companies that act in 2026 can lock in supply, validate higher‑margin SKUs, and refine channels before saturation in adjacent price bands intensifies competition.
- Portfolio tradeoffs: The market increasingly bifurcates around authentic high‑fidelity experiences and convenience‑oriented, connected products. Our work quantifies the tradeoffs across cost, feature mix, and channel economics so teams can design SKU ladders that protect brand equity while seeding volume.
- Regulatory and rights risk: Ongoing copyright and royalties deliberations create a two‑way risk: higher mechanical or performance royalties would affect pricing and margin calculus for digital‑enabled turntables and value‑added services; conversely, stable outcomes clear the way for subscription or streaming‑adjacent product bundles.
Market trajectory and structural forces
Vinyl is no longer a nostalgic footnote — it has become a persistent, monetizable format that crosses demographics. Our historical analysis (2020–2025) shows recovery, premiumization, and product feature convergence (Bluetooth, USB capture, integrated phono preamps) that have shifted the basis of competition. Looking ahead to 2026–2032, the market’s projected growth at a 4.85% CAGR is underpinned by three durable forces:
Turntables Market
- Consumer willingness to pay for physical experience: Physical album sales outpaced CD sales globally in 2025, signaling that collectors and new buyers alike value ownership and tangibility.
- Product democratization of features: Bluetooth and USB recording have become baseline expectations even in sub‑$250 models, compressing differentiation and elevating areas like cartridge performance, motor stability, and aesthetic craftsmanship as the new battlegrounds.
- Channel evolution: A hybrid retail ecosystem — specialty audio dealers, e‑commerce direct channels, and lifestyle retailers — demands different margins, inventory turns, and marketing strategies. Our report models these channel economics and their sensitivity to price and lead times.
Report content — action-oriented deliverables
PW Consulting’s full report is tailored to executives who must translate market observation into measurable actions. Key deliverables include:
Turntables Market
- Topline market sizing and forecast (2026–2032) with scenario variance and sensitivity to price bands and component cost shocks.
- Practical GTM playbooks for premium, mid‑market, and entry tiers covering assortment, retail vs. D2C economics, and promotional cadence.
- Product roadmap frameworks: modular designs, upgradable phono stages, cartridge partnerships, and wireless‑first variants that balance margin and manufacturability.
- Supply chain resilience checklist: critical components (motors, belts, platters, tonearms, cartridges, phono stages), lead times, and recommended inventory buffers by scenario.
- Competitive landscaping and capability mapping, including M&A targets and partnership opportunities that reflect current market concentration and consolidation dynamics.
- Implementation templates: 12‑ and 36‑month action plans with budgetary bearings, channel pilots, and KPI scorecards targeted at revenue, gross margin, and ROIC thresholds.
Competitive landscape — what matters in 2026
The turntables market exhibits moderate concentration: the combined share of the three largest players sits at a level that enables scale advantages without creating insurmountable barriers to entry, while the five‑firm concentration underscores significant differentiation among established brands. The practical implication for incumbents and challengers alike is clear — scale helps, but brand and feature‑led specialization can still win meaningful share.
- Audio‑Technica (Tokyo): A balanced portfolio spanning belt‑ and direct‑drive models, plus a strong accessory and cartridge business. Recent high‑end cartridge developments reinforce its vertical integration in analog reproduction components — a defensible moat for premium product rollouts.
- Technics (Osaka): Deep engineering credibility in direct‑drive motors and precision platforms. Their heritage in high‑performance drive technology positions them to lead where rotational stability and low noise are premium purchase drivers.
- Pro‑Ject Audio Systems (Mistelbach): European design and handmade quality appeal make Pro‑Ject a go‑to for premium audiophile segments. Their catalogue strategy demonstrates how limited editions and design collaborations can justify higher ASPs.
- Fluance (USA): Focus on reference‑grade builds and natural finishes targets buyers seeking audiophile aesthetics and performance at competitive pricing — a template for margin uplift without radical R&D spending.
- Sony Electronics (San Diego): Strong brand reach and distribution combined with wireless‑first, beginner‑friendly models offer a channel advantage: mass awareness plus a pathway to upsell audiophile peripherals or higher‑end models.
- Rega Research (Cambridge): Precision engineering and a reputation for low distortion make Rega a niche leader among purists; their approach underscores the value of engineering pedigree in preserving pricing power.
- Victrola (USA) and U‑Turn Audio (USA): Victrola’s lifestyle‑oriented, portable models and U‑Turn’s democratized, high‑value offerings illustrate two different, yet lucrative, routes to market entry — lifestyle appeal and community‑driven value plays.
Recent market moves in early 2026 — from cartridge introductions to new wireless models and high‑end previews at trade shows — show continuing product innovation across the spectrum. These developments are directional: incumbents are solidifying technical moats while challengers use features and pricing to disaggregate legacy brand advantages.
Strategic implications & recommended moves for 2026
Based on our analysis, PW Consulting recommends executives consider a balanced set of tactical and strategic moves in 2026:
- Product & portfolio: Make Bluetooth/USB a baseline offering across entry and mid tiers while reserving differentiated mechanical engineering (tonearm geometry, platter mass, motor control) for premium SKUs. Consider modular phono stages and cartridge upgrade paths to extend customer lifetime value.
- Go‑to‑market: Test hybrid channel pilots that combine specialty audio partners for premium SKUs with D2C bundles and lifestyle retail placement for mainstream models. Optimize promotional calendars around vinyl release cycles and holiday seasons.
- Supply & manufacturing: Lock long‑lead contracts for precision components, diversify cartridge and stylus suppliers, and factor in inventory buffers for critical subassemblies to insulate against micro‑supply shocks.
- Mergers & partnerships: With moderate market concentration, there are tactical M&A opportunities for companies seeking rapid access to distribution, manufacturing, or intellectual property — especially in cartridge tech and motor design.
- Regulatory preparedness: Monitor outcomes of ongoing copyright royalty proceedings and model their margin impact on devices that enable digital capture or streaming‑adjacent features.
- Service & aftermarket: Build aftermarket services (cartridge upgrades, calibration, trade‑ins) to capture recurring revenue and deepen brand relationships.
What the full report unlocks
The briefing here is intentionally high‑level. PW Consulting’s full Turntables Market report contains the operational detail necessary for execution: channel‑level margin models, SKU profitability heatmaps, component‑cost sensitivity runs, and a prioritized list of M&A targets and partnership candidates scored by strategic fit and execution risk. It also includes playbooks for marketing segmentation, SKU rationalization, and a timeline for rolling out connected features without cannibalizing premium analog propositions.
For teams making resource allocation decisions in 2026 — whether capital investment, product R&D, or market entry — this research converts cultural momentum into executable commercial strategies. To preserve the competitive advantage of our clients, the full segmentation tables, channel forecasts, and granular scenario outputs are published in the complete report available at PW Consulting.
For detailed analysis of this topic, please visit the official page: Turntables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ice Cream Machine Market to Top USD 9,720M in 2025, 3.83% CAGR Ahead
By PW Consulting, 2026-07-08
Ice Cream Machine Market — 2026 Strategic Preview
Executive snapshot
As corporates re-calibrate capital, product and channel strategies for 2026, PW Consulting’s Ice Cream Machine Market study provides the evidence base required to act with conviction. The market expanded from approximately USD 8.08 billion in 2020 to roughly USD 9.72 billion in 2025 (base year), with the 2026 outlook at about USD 10.03 billion. Our forecast horizon through 2032 anticipates a steady compound annual growth rate of 3.83% (USD, Million basis). Market concentration is meaningful: the top three players capture roughly 70% of industry value while the top five account for about 80% — a structural feature that shapes pricing, distribution and innovation strategies.
Ice Cream Machine Market
Why this study matters for 2026 decision cycles
- Capital allocation clarity: The market’s steady growth and concentration profile helps CFOs and capital planners prioritize investments between new-product lines, retrofits and service-network expansion while preserving margin resilience in a consolidating supplier landscape.
- Product and R&D roadmaps: Energy-efficiency regulation and the rebound in foodservice demand change product specifications. R&D leaders can align next‑generation compressor and motor investments with forecasted demand windows to optimize payback periods.
- Sourcing and supplier strategy: With several large incumbents and fast-scaling Asia-based OEMs competing on cost and throughput, procurement teams must adopt segmented supplier scorecards and dual-sourcing approaches to reduce single‑source risk.
- Go-to-market and channel decisions: The evolving mix of foodservice, retail and direct-to-consumer adoption calls for differentiated commercial models — from OEM-led leasing and managed service agreements to channel partnerships and franchise enablement.
- M&A and partnership screening: Market concentration and clear growth pockets create acquisition arbitrage opportunities — especially for firms seeking scale in service, digital diagnostics or regional distribution.
What’s inside the PW Consulting report (practical deliverables)
The full study is designed as a toolkit for executives, not just a descriptive paper. Highlights include:
Ice Cream Machine Market
- Robust market sizing and method appendix — base year 2025, historical window 2020–2025, and a 2026–2032 forecast built on bottom‑up units and price modelling (USD Million).
- TAM/SAM/SOM frameworks and scenario trees that incorporate regulation, energy costs and evolving foodservice demand to stress-test capacity plans.
- Buyer-journey and procurement playbooks for major customer segments (foodservice chains, artisanal producers, industrial manufacturers and self-service vending operators).
- Actionable TCO and payback models for hard and soft-serve equipment, including sensitivity to energy tariffs, maintenance intervals and consumable costs.
- Supplier scorecards, negotiation playbooks and an RFP checklist tailored for high-volume and premium‑segment procurement.
- Standardized service KPIs and predictive-maintenance templates that translate IoT signals into field-service scheduling and spare-parts optimization.
- Regulatory compliance roadmaps (Ecodesign, Energy Star alignment, nutrition labeling impacts) and energy-efficiency design priorities.
- Commercial playbooks for launching IoT-enabled product-as-a-service offers and retrofit conversion kits to monetize installed bases.
- M&A screening templates: synergy levers, integration pitfalls, and valuation multipliers specific to this manufacturing niche.
Competitive landscape — interpretation, not a catalogue
The industry’s supplier map combines century-old OEMs, specialized European artisans, North American foodservice specialists and high-volume Asian manufacturers. A few illustrative positioning insights:
Ice Cream Machine Market
- Heritage European artisans (e.g., Italian and Danish OEMs): These firms hold premium positioning through product quality, process automation for gelato and artisan ice cream, and increasingly, sustainability claims tied to efficient production lines and material sourcing. Their strategic focus is on margin-rich segments and co‑development with leading foodservice customers.
- North American foodservice specialists (U.S. firms): Companies with deep foodservice channel relationships emphasize robustness, uptime and service ecosystems (mix-in blenders, milkshake integrations, and on-site support). Recent trade-show participation signals continued investment in product line refreshes and channel marketing to large operators.
- Japanese and other precision manufacturers: These players target high-throughput, reliability and integration into large-scale production lines, making them preferred suppliers for industrial and co-manufacturing clients.
- Chinese and other Asia-based producers: Rapid capacity scaling and improved feature parity have positioned several suppliers as cost competitive for large-capacity deployments; many are also investing in faster lead times and local service footprints.
- Systems and integrators: A handful of conglomerates and systems providers offer end‑to‑end production and packaging systems, representing attractive partnership targets for OEMs seeking to upsell to factories and contract manufacturers.
Trade-show activity in early 2026 reinforced these trends: multiple vendors highlighted IoT connectivity, automation for throughput consistency, new soft‑serve and self‑service vending formats, and a renewed emphasis on energy-efficient compressors and blast/freezing technologies.
Regulation, consumer signals and supply-side dynamics
- Consumer provenance and ingredient control: An industry survey (2025) shows ingredient control is now the primary motivation for consumers making ice cream at home — a marked shift that informs product features for small-format and countertop machines as well as recipe and packaging strategies.
- Energy and efficiency mandates: EU Ecodesign requirements and North American programs like Energy Star are accelerating design change. Manufactures will need to prioritize motor efficiency, standby power reduction and more accurate energy labelling to avoid market access friction.
- Labeling and transparency: Updated nutrition labeling rules are reshaping consumer perception and nudging suppliers to offer more transparent, low-energy and low-waste solutions — with implications for ingredient portioning systems and dispensers.
- Cost inputs and workforce: Raw-material volatility and localized labor-cost differences are creating opportunities for equipment that reduces waste, shortens production cycles and automates manual tasks to protect margins.
Priority strategic moves for 2026 (practical guidance)
- Short-term (90–180 days): Run a prioritized retrofit pilot on the largest installed base cluster to validate IoT predictive-maintenance ROI; renegotiate spare-parts agreements with dual-sourcing clauses; deploy energy‑efficiency labelling on best-selling SKUs.
- Medium-term (6–18 months): Launch a new service subscription offering in select regions, combining remote diagnostics with fast-response field teams; accelerate development of next‑gen compressors to align with Ecodesign timelines; formalize JV discussions with packaging/system integrators.
- Long-term (18–36 months): Consider bolt-on acquisitions to secure regional service networks or digital platforms; invest in modular production lines that reduce SKU time-to-market and enable rapid customization for franchised operators.
How PW Consulting’s full report supports execution
The complete study delivers the quantitative granularity and annexes required for execution: downloadable unit shipment matrices, region‑and-application heatmaps, supplier financial benchmarks, and an acquisitions shortlist. In keeping with the “trailer” philosophy, we intentionally withhold detailed regional/applicational splits and granular company revenue tables in this preview — these are included in the subscription report and interactive dashboards so decision-makers can validate hypotheses and run bespoke scenarios.
Next steps
- Download the full report for the detailed segmentation, supplier financials and the executable playbooks referenced above.
- Engage our advisory team for a rapid 4‑week “decision accelerator” to translate the intelligence into a prioritized 2026 investment plan.
For boards, CEOs and functional leaders preparing 2026 roadmaps, this study converts market momentum into an actionable agenda — protecting margins through energy efficiency, unlocking new service revenue with IoT, and exploiting consolidation dynamics through disciplined M&A and supplier strategies. The market’s steady growth and structural concentration create both discipline and opportunity; the right moves this year will determine who owns the value chain in the next cycle.
For detailed analysis of this topic, please visit the official page: Ice Cream Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Textile Digital Printing Market to Hit USD 3,920M by 2032 (6.8% CAGR)
By PW Consulting, 2026-07-08
Textile Digital Printing Machine Market — Strategic Outlook for 2026 Decision-Makers
Executive summary
The textile digital printing machine market has matured from a disruptive niche into an essential pillar of modern textile manufacturing. Measured on a global basis, the industry expanded from roughly USD 1.8 billion in 2020 to about USD 2.5 billion in 2025 and is expected to continue its upward trajectory into the next decade. Under our forecast framework, the market is set to grow at a 6.8% compound annual growth rate across the 2026–2032 period, approaching nearly USD 3.9 billion by 2032. For executives making 2026 capital-allocation, product, and go-to-market decisions, this translates into a window of scaling opportunity for manufacturers, service providers, and vertically-integrated brands — but the opportunity is heterogeneous and demands differentiated strategic responses.
Textile Digital Printing Machine Market
Why this research is essential for 2026 planning
- Capital prioritization: Firms must decide whether to prioritize single-pass high-throughput systems, versatile roll-to-roll platforms, or direct-to-garment lines. The timing and scale of those investments materially affect payback periods under the prevailing growth scenario.
- Profitability under cost-pressure: Raw-material and energy cost volatility, alongside environmental compliance, changes the unit economics of inkjet textile printing. Understanding total cost-of-ownership (TCO) drivers is now a strategic necessity, not a procurement afterthought.
- Sustainability and regulation: New color and process standards and increasing scrutiny of chemicals and waste streams are reshaping OEM and user choices. Early alignment with standards reduces rework risk and shortens time-to-market for sustainable collections.
- Service and operational resilience: As digital printing supports shorter production runs and on-demand models, installing equipment without the right pre-treatment, post-treatment, and service architecture can erode expected margins.
What PW Consulting’s Textile Digital Printing Machine Market research delivers
This report is constructed to be operationally actionable for C-suite and investment teams planning 2026 moves. It combines a quantitative market forecast with executable deliverables:
Textile Digital Printing Machine Market
- Proprietary market-sizing and scenario modules that let you stress-test demand paths under inflation, raw-material cost, and regulation shocks.
- ROI and TCO calculators tailored to different technology archetypes (single-pass, multi-pass, roll-to-roll, direct-to-garment, direct-to-fabric) that integrate ink, consumables, energy, labor, and service contracts.
- Vendor scorecards and a strategic supplier matrix covering technology maturity, after-sales footprint, integration capability, and financing options.
- Supply-chain maps and risk heatmaps identifying single points of failure in spare parts, print-head supply, and solvent/ink sourcing.
- Regulatory and standards playbook, including implications of the emerging color and process standards for print quality and cross-site consistency.
- Go-to-market playbooks for equipment manufacturers and service providers, including channel strategies, partnerships for pre/post-treatment, and blueprints for local assembly and spare-parts networks.
- Case studies and benchmark installations illustrating time-to-ramp, quality yields, and sustainability performance under real operating conditions.
As a “trailer” of our analysis, this introduction is engineered to show methodological depth while reserving granular, segment-level datasets and vendor ranking tables for the full report and dashboards.
Textile Digital Printing Machine Market
Market dynamics you must embed in 2026 decisions
- Technology bifurcation: The market is consolidating around two value propositions — ultra-high throughput single-pass systems for large-volume home and industrial textiles; and flexible, lower-capex direct-to-garment/direct-to-fabric platforms that enable fast fashion and on-demand personalization. Choosing the right side of the trade-off is foundational to capital deployment strategy.
- Raw-material and process innovation: A diverse set of ink technologies — water-based, reactive, acid, and pigment systems — enables printing across fiber types while addressing environmental and wash-fastness requirements. Inks are becoming a strategic differentiator because they influence color gamut, fixation processes, and post-treatment requirements.
- Standards and compliance: Regionally-driven color and process standards are emerging as gatekeepers to market acceptance. The first provincial digital printing color group standard introduced in 2024 illustrates how standards can accelerate interoperability while creating compliance tasks for device makers and users.
- Integration of pre/post-treatment: Inline pre- and post-treatment systems are no longer optional for high-efficiency lines. Integrated workflows that eliminate fabric unloading materially improve throughput and quality consistency.
- Service and local presence: Operational uptime in digital printing is as much a function of spare parts and service expertise as it is of machine reliability. Companies with local assembly, quick-curing service networks, and training capabilities reduce buyer risk and shorten payback horizons.
Competitive landscape — themes and implications
The competitive field includes a mix of longstanding industrial OEMs, digitally-native players, and regional specialists. Market concentration is moderate: the leading firms capture a meaningful share of revenue, leaving ample room for regional champions and niche specialists to capture adjacent value.
- Industrial OEMs and full-solution providers: European incumbents and specialist players position themselves on high-precision, integrated single- and multi-pass systems with strong R&D, ink portfolios, and workflow integration. Their play is to sell higher-priced, higher-margin systems with service contracts and consumables.
- Digital-first entrants: Firms focused on on-demand apparel and short-run customization emphasize sustainability, rapid fulfillment, and cloud-enabled workflow management. Their advantage is speed-to-market and flexible production models that serve brand-driven demand.
- Regional specialists and cost players: Several Asia-based manufacturers increasingly compete on cost, speed, and localized support, offering rapid installations and aggressive financing to capture domestic manufacturing growth and regional export demand.
- Open innovation and co-development: We observe win-win partnerships where ink formulators, print-head suppliers, and machine builders co-develop tuned solutions to optimize color fidelity and reduce post-processing. These partnerships shorten innovation cycles and raise switching costs for customers.
Recent product and commercial moves underscore these themes. There have been high-profile product introductions from established and regional vendors that illustrate both technology push and market pull: new high-head-count, high-speed printers focused on scale; launches of latex-based direct-injection machines that improve environmental profiles; and multi-unit installations that highlight the economic case for scale and vertical integration. These developments point to a competitive environment that will reward both technological leadership and operational reach.
Strategic implications: five priority actions for 2026
- Align technology choice with portfolio strategy: If your business depends on predictable high-volume runs, prioritize investments in integrated, high-throughput systems and pre/post-treatment lines. If your strategy centers on personalization, prioritize flexible, lower-capex platforms and cloud-enabled color management.
- Model TCO, not just capital cost: Incorporate ink type, fixation energy, maintenance cadence, service SLAs, and scrap/waste profiles into your financial models. Small differences in ink or curing requirements can swing payback by years.
- Lock in supply-chain resilience: Build redundancy for critical components (print heads, control electronics, specialty inks) and evaluate service-partnerships or local assembly to reduce lead times.
- Embed standards and sustainability early: Design production and sourcing choices to comply with emerging color/process standards and to meet increasing corporate sustainability commitments. This reduces future rework and opens premium channels.
- Use acquisitions and partnerships strategically: Consider M&A or minority investments to secure new ink chemistries, cross-border service networks, or digital workflow capabilities — particularly where the market is moderately concentrated and scale matters.
How to use the full PW Consulting package
Our full report and interactive dashboard provide the granular datasets, vendor scorecards, and scenario models that operational teams need to execute the five priority actions above. If you are preparing board-level capital requests, negotiating supplier contracts, or designing a regional roll-out in 2026, these resources will translate macro forecasts into line-item investment decisions.
The material presented here demonstrates the rigor of our analysis while purposefully reserving granular segmentation tables, vendor ranking matrices, and downloadable ROI spreadsheets for the full study. For a guided walkthrough, scenario customization, or to license the underlying data and calculators, visit the PW Consulting Textile Digital Printing Machine Market page or contact our industry practice.
Final thought
The window for decisive action is open in 2026. Market growth at a mid-single-digit CAGR, faster product innovation, and evolving standards create both risk and differentiation opportunity. Companies that align capital choice, supply resilience, and sustainability integration will capture disproportionate returns as the industry scales. PW Consulting’s report converts the macro trajectory into implementable steps — the full dataset and models are the next step for teams ready to act.
For detailed analysis of this topic, please visit the official page: Textile Digital Printing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Radome Market 2026: Strategic Imperatives from PW Consulting’s Executive Brief
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive introduction to our latest Radome Market research. The study synthesizes primary interviews, proprietary RF performance benchmarking, supply‑chain cost models, and regulatory pathway mapping to convert technical complexity into boardroom‑ready guidance for 2026 decision cycles. This article outlines the strategic value of the research for executives, program managers, and investors — while preserving the granular segmentation tables and numeric breakdowns as premium content on the source page.
Radome Market
Why Radomes Matter in 2026: Market Context at a Glance
Radomes sit at the intersection of aerospace structures, RF engineering, and defense procurement. Over the recent historical window (our study’s baseline covers 2020–2025, with 2025 as the base year), the global radome market showed steady expansion — moving from a market that we quantified at approximately USD 163 million in 2020 to roughly USD 215 million in 2025. Our forecast period (2026–2032) projects a compound annual growth rate of 6.98%, bringing the industry to an estimated USD 345 million by 2032 under the central scenario. Two structural signals emerge from that trajectory: durable demand driven by modernization and new platform introductions, and margin and product mix shifts driven by materials innovation and certification costs.
Radome Market
What This Means for 2026 Decisions
- Program Prioritization: Procurement leads must weigh lifecycle cost against RF transparency and certification timelines. Our models show that small variations in material loss tangent and structural integration requirements cascade into program schedules and total ownership costs.
- Supply‑Chain Strategy: With material sourcing and processing concentrated in specialist suppliers, decisions made in 2026 on dual‑sourcing, qualifying alternative prepregs, and stockpiling critical fabrics materially affect program risk.
- M&A and Partnerships: Given a relatively low market concentration (CR3 and CR5 metrics indicate a fragmented competitive landscape), targeted acquisitions or technology partnerships can create disproportionate capability lift for system integrators and tier‑1 suppliers.
- Technology Investment: Investing in low‑dielectric thermosets, higher temperature composites, and integrated RF‑structure design tools yields differentiated product roadmaps that accelerate wins in both civil avionics and tactical defense markets.
Key Demand Drivers and Market Dynamics
Three forces are reshaping the radome ecosystem in 2026:
Radome Market
- Platform Modernization and New Architectures: Upgrades in air defense, maritime surveillance, and next‑generation commercial avionics are increasing demand for radomes that balance stealth, thermal tolerance, and RF performance.
- Materials & Manufacturing Evolution: Advances in quartz and carbon fiber prepregs and novel thermosets are enabling lower dielectric constant options with better structural properties. Our technical benchmarking identifies performance thresholds where switching materials produces net program benefits after certification and tooling costs.
- Regulatory & Certification Pressure: Recent regulatory actions—most notably European and U.S. certification updates finalized in 2025 and enforcement directives affecting lightning protection on production aircraft—have increased the compliance burden on airframe and radome suppliers, with implications for lead times and aftermarket programs.
Supply Chain, Raw Materials and Risk
Material inputs matter. Carbon fiber pricing for aerospace applications has stabilized in a range that supports ongoing composite adoption, but volatility remains a tail risk for program economics. Of particular relevance to RF performance, low‑dielectric thermoset systems (e.g., cyanate ester matrices with quartz reinforcement) are now delivering dielectric constants in the low‑single digits and loss tangents that materially improve system sensitivity. However, export controls and geopolitical fragmentation continue to complicate sourcing of advanced fibers, fabrics, and autoclave equipment — a systemic risk that our scenario suite explicitly quantifies.
Regulatory Environment — Practical Implications
Certification and airworthiness guidance finalized in 2025 altered the operational calendar for many programs. EASA’s certification memorandum and U.S. FAA directives require program teams to integrate structural and lightning protection verification earlier in development flows. These shifts increase up‑front qualification costs for new radome materials and favor suppliers who can demonstrate NCAMP or equivalent processes and test evidence. The report’s regulatory tracker translates those policy changes into a certification calendar and decision tree that procurement and engineering teams can use immediately.
Technology Trends and Materials Innovation
Our RF and structural lab benchmarking shows that material choices and layup architecture drive three controllable levers: RF loss, mechanical fatigue life, and environmental resilience. Emerging low‑dielectric prepregs and hybrid quartz–glass architectures deliver performance close to legacy high‑cost solutions but require revised bonding and repair processes. Trade shows and prototype milestones through 2025–2026 document how industry participants are moving from demonstrators to production‑intent designs — an acceleration that smart investors and program managers must not overlook.
Competitive Landscape: Who Moves the Market
The industry remains competitively diverse. A handful of global defense primes, aerospace OEMs, and specialist composites firms shape technology and procurement dynamics. Key players covered in our report include system integrators with deep platform relationships, traditional composites suppliers with broad aerospace portfolios, and agile niche firms pushing alternative prepreg and manufacturing approaches. Highlights:
- System Integrators and Tier‑1 OEMs: Major defense and aerospace groups continue to integrate radome design into broader RF and mission systems. Their platform scale gives them leverage in long‑lead procurement and aftermarket upgrading.
- Composites Specialists: Established materials suppliers and composites houses are converting lab innovations into production‑ready radomes, focusing on certification, repeatable processing, and sustainment documentation.
- Innovative Niche Players: Agile firms that specialize in low‑dielectric prepregs and NCAMP‑oriented processes are narrowing the performance gap with legacy materials, and their prototypes are already passing RF test campaigns.
Our competitive profiles consolidate public disclosures, supply‑chain mapping, and benchmarked performance. The report analyzes how each named organization leverages R&D, certification posture, and platform relationships to defend or expand market positions — and where white space remains for entrants and collaborators.
Recent Developments That Matter Now
- Prototype breakthroughs: NCAMP‑certified low‑dielectric epoxy‑quartz radome prototypes demonstrated RF parity with traditional high‑cost materials, which changes the economics of qualification and serial production.
- Materials and market visibility: Major composites suppliers used international expos in 2025–2026 to display high‑temperature, lightweight demonstrators and to signal readiness for electric aircraft and space applications.
- Certification updates: Regulatory clarifications in 2025 and continuing FAA directives on lightning protection have forced some OEMs to update inspection and replacement programs earlier than planned.
What PW Consulting’s Radome Report Contains (Practical, Actionable)
- Market sizing and scenario forecasts (historical 2020–2025, base 2025, forecast 2026–2032) with sensitivity to material pricing and platform cadence.
- Proprietary RF performance and structural benchmarking across material families and lay‑ups, expressed in actionable thresholds for procurement and engineering.
- Supplier capability matrix and qualification checklist for NCAMP and equivalent pathways, including a recommended test regime and schedule.
- Regulatory tracker mapping EASA, FAA, and key export‑control developments to program milestones and compliance costs.
- Commercial playbook for OEMs and tier‑1s: partnership archetypes, make vs. buy decision framework, and go‑to‑market strategies for new materials.
- M&A and investment heatmap identifying capability gaps and consolidation levers in a fragmented market.
- Scenario planning toolkits for supply‑chain disruption, material price shocks, and rapid platform cancellations.
Strategic Recommendations for 2026
- Qualification Acceleration: Start material and process qualification now. The earlier a supplier completes demonstrated NCAMP or equivalent evidence, the faster it can capture production run‑rate orders when platform programs ramp.
- Dual‑Path Sourcing: Structure contracts to allow rapid switching between qualified material families; hedge against export control and raw‑material disruption risks.
- Invest in Integration Capabilities: Firms that can bundle radome design with RF systems integration will win higher‑value work and create lock‑in with OEMs and defense primes.
- Targeted M&A: For investors and strategic acquirers, pursue bolt‑on capabilities in low‑dielectric prepregs or rapid qualification expertise rather than broad composites portfolios — the market’s fragmentation means small acquisitions yield outsized capability gains.
- Regulatory Readiness: Treat certification as a program milestone, not a checkbox. Embed certification risk mitigation into the program’s critical path and budget accordingly.
Conclusion — The Strategic Value of the Full Study
The radome market’s projected climb from mid‑2020s levels to the end‑of‑decade forecast encapsulates a deeper realignment: materials science, certification regimes, and geopolitical supply‑chain frictions are reordering who wins. Our study translates these forces into program‑level levers that executives can act on in 2026 — from procurement strategies and R&D prioritization to M&A and certification roadmaps.
This article intentionally highlights trends, benchmarks, and strategic implications while withholding detailed segmentation tables and proprietary scenario spreadsheets reserved for subscribers. For the complete datasets, regional and application segmentation, and the full supplier scorecards and models that support these conclusions, visit the report page to access the complete Radome Market research package.
For detailed analysis of this topic, please visit the official page: Radome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Temperature Data-Loggers Market to Hit USD 295.1M by 2032 (7.14% CAGR)
By PW Consulting, 2026-07-08
Temperature Data-loggers Market — Strategic Imperatives for 2026
As temperature-sensitive products become central to healthcare, food safety, and high-tech manufacturing, the market for temperature data-loggers is moving from a niche instrumentation category into a strategic platform for compliance, quality assurance and supply‑chain visibility. Our PW Consulting Temperature Data‑loggers Market study (base year 2025) synthesizes historical performance, regulatory drivers and vendor dynamics into a decision-grade playbook for corporate leaders preparing plans in 2026.
Temperature Data-loggers Market
Market trajectory at a glance
Between 2020 and 2025 the global Temperature Data‑loggers market expanded steadily, with measured revenues rising from approximately USD 148.7 Million (2020) to USD 182.5 Million (2025). Our baseline forecast projects continued expansion through 2032, reaching roughly USD 295.1 Million by the end of the forecast horizon. The underlying compound annual growth rate for the forecast period is 7.14%, reflecting steady demand driven by stricter regulation, broader digitalization of cold chains and renewed investment across pharmaceutical and food industries.
Temperature Data-loggers Market
Why this report matters for enterprise decision-making in 2026
- Compliance is now strategic: Evolving norms — from EN 12830 measurement baselines to FDA/EMA traceability expectations and WHO PQS prequalification — mean logger selection and data pipelines are material to product approvals, audit readiness and loss reduction. The right logger strategy reduces both regulatory risk and product waste.
- Visibility underpins resilience: Organizations are moving beyond point-sampling to continuous, auditable telemetry. That creates choices about one‑time single‑use devices versus reusable assets and about edge versus cloud processing — choices that affect unit economics, operational cadence and service models.
- Technology choices cascade: Connectivity options (Bluetooth, Wi‑Fi, 4G/LTE, GPS), sensor fidelity, multi-parameter sensing (temperature plus humidity, acceleration) and secure data-handling determine whether a logger is a commodity or a strategic device that integrates with ERP, LIMS and distribution management systems.
- Market structure creates opportunities: The market shows a relatively low level of concentration. That fragmentation favors targeted partnerships, regional scale-ups and bolt-on acquisitions for established instrument or logistics players seeking immediate capability.
What the PW Consulting study delivers — practical, transaction‑ready assets
This study is structured as a practical toolkit for commercial, procurement, regulatory and R&D leaders. Key deliverables include:
Temperature Data-loggers Market
- Transparent market sizing and methodology notes (historical 2020–2025 and forecast 2026–2032), with scenario-based sensitivity to price, regulation and technology adoption.
- Actionable vendor benchmarking: comparative scorecards across accuracy, connectivity, certification status, total-cost-of-ownership (TCO) and post‑sales support, enabling rapid vendor shortlisting for RFPs.
- Regulatory mapping and audit playbooks: alignment matrices showing which logger features and data workflows satisfy EN 12830, FDA/EMA expectations and WHO PQS considerations, and a validation checklist for supplier qualification.
- Procurement and deployment playbooks: buy-versus-lease models, single‑use vs reusable TCO calculators, and a 90/180/365-day pilot-to-scale rollout roadmap.
- Integration and data‑architecture guidance: recommended telemetry stacks, edge‑compute vs cloud trade-offs, encryption/chain‑of‑custody controls and analytics templates to derive early ROI.
- Scenario explorer and executive dashboards: downloadable templates to model impact of cold‑chain improvements on waste reduction, regulatory exposure and net operating margin.
Competitive landscape — who matters and why
The vendor field comprises established instrumentation specialists, logistics-focused providers and digitally native IoT entrants. Below are the strategic profiles and implications for 2026 planning:
- Vaisala Oyj (Vantaa, Finland): Positioned around high‑accuracy offerings tailored for ultra‑low temperature freezers and regulated environments. For pharmaceutical manufacturers and cold‑storage operators, Vaisala represents a defensible option where measurement precision and long-term calibration support matter.
- Testo SE & Co. KGaA (Titisee‑Neustadt, Germany): Known for validation‑grade loggers; recent launches emphasize Bluetooth and USB-C connectivity combined with companion apps. Their product roadmap targets GMP/GDP audit use-cases and streamlines validation workflows — attractive to QA/QC teams prioritizing regulatory traceability.
- Onset Computer Corporation (Bourne, MA, USA): With HOBO MX and InTemp lines, Onset focuses on environmental and cold chain monitoring with GPS and wireless options. Their recent cloud integrations and mobile offload workflows make them a strong fit for distributed environmental monitoring and research projects.
- Sensitech Inc. (Beverly, MA, USA): Specializes in single‑use and reusable trackers for cold chain logistics. Sensitech is a go‑to for logistics providers and large shippers where turnkey tracking and scale matter.
- Rotronic AG (Bassersdorf, Switzerland): Offers precision temperature and humidity logging for HVAC, cleanrooms and industrial control. Rotronic is attractive where environmental control and regulatory documentation intersect (e.g., cleanroom qualification).
- OMEGA Engineering Inc. (Norwalk, CT, USA): Covers industrial multi‑channel RTD and thermocouple solutions. OMEGA is typically selected by manufacturing and process industries demanding multi‑point, ruggedized monitoring.
- ELPRO‑BUCHS AG (Buchs, Switzerland): Integrates with validation workflows and partners with calibration and compliance toolsets — a natural fit for pharmaceutical validation and cold chain auditability.
- Dickson (Addison, IL, USA): Emphasizes cloud platforms for real‑time remote monitoring. Their SaaS orientation appeals to customers seeking low‑touch operations and centralized compliance oversight.
- Freshliance and Tzone (China): Competitive on cost and rapid feature iteration (real‑time Wi‑Fi/GPS/4G/Bluetooth). These vendors are increasingly relevant for large fleets and price‑sensitive supply chains, especially where regional manufacturing footprints are expanding.
Recent product and certification moves matter. For example, Testo’s introduction of a compact Bluetooth/USB‑C mini logger and Onset’s cloud integration are signals that connectivity and mobile workflows will be decisive purchase criteria in 2026. Certification events (including WHO PQS prequalification for multi‑sensor models) further tilt preference toward vendors who can demonstrate audited compliance.
Risks, frictions and decision triggers
Executives should monitor a short list of risk vectors that will materially affect procurement and product strategy:
- Regulatory tightening: New or clarified measurement and data‑retention rules can suddenly elevate device requirements and lifecycle costs.
- Data integrity and auditability: Logged data must survive the audit trail; devices and cloud stacks that lack tamper evidence or secure chain‑of‑custody will become commercially risky.
- Obsolescence and feature velocity: Rapid connectivity shifts (e.g., LPWAN, 5G, edge analytics) can shorten the useful life of commodity loggers.
- Sustainability and waste management: The trade‑off between single‑use convenience and environmental externalities is increasingly material to procurement policy and brand risk.
- Supplier concentration and geopolitical exposure: Fragmentation provides options, but supply chain disruption or regional certification gaps can create vendor bottlenecks.
90/180/365‑day playbook for 2026
- 90 days: Conduct a compliance gap analysis of current logger estates versus EN 12830/FDA/EMA expectations; run a 30‑day pilot of two shortlisted vendors covering both single‑use and reusable models to capture operational differences.
- 180 days: Finalize integration architecture with LIMS/ERP and cloud platforms; negotiate supply agreements that include certification SLAs and data escrow for audit resilience.
- 365 days: Scale preferred solutions across critical sites, instrument lifecycle management and calibration schedules; evaluate strategic partnerships or tuck‑in acquisitions to fill capability gaps (connectivity, certification, analytics).
How PW Consulting can accelerate your 2026 program
Our Temperature Data‑loggers Market study is designed as both a strategy brief and an execution kit. Clients receive not only the quantitative model underlying the growth projections, but also the templates, vendor scorecards and regulatory checklists that convert insight into procurement and product decisions. To preserve the strategic value of this work the report intentionally layers high‑level market sizing and trend disclosure while keeping detailed segmentation tables and vendor scorecard scores accessible only within the full report package.
For executives who must decide in 2026: this is a market where the technical minutiae (sensor drift, sample interval, certification status, connectivity stack) become strategic levers. Capturing the projected growth opportunity and avoiding regulatory and operational cost requires a coordinated plan across procurement, IT, QA and supply chain. Our study provides the map and the ready-to-use tools; your next move is to convert those insights into a prioritized execution program.
To obtain the full intelligence package — including the complete segmentation, proprietary vendor scores and downloadable implementation templates — please visit the PW Consulting report page or contact our Temperature Data‑loggers practice for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Temperature Data-loggers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Magnet Wire Market to Reach $48.55B by 2032 with Copper Leading at $24.8B
By PW Consulting, 2026-07-08
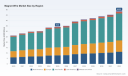
Magnet Wire Market Outlook 2026: Strategic Preview for Corporate Decision-Makers
As PW Consulting’s lead industry analyst, I present a forward-looking executive primer designed to orient senior executives, procurement leaders, product strategists, and M&A teams as they plan for 2026. This is a strategic trailer — a high-signal, operationally focused briefing that demonstrates the depth and rigor of our full Magnet Wire Market study (base year: 2025; historical coverage: 2020–2025; forecast horizon: 2026–2032). The full report contains the granular segmentation, proprietary models, and drill‑down datasets that underpin the insights summarized here.
Magnet Wire Market
Why magnet wire matters to 2026 corporate strategy
- Magnet wire is a foundational input in electrified systems — from motors and transformers to EV traction systems and renewable infrastructure. Decisions on wire sourcing, alloy selection, and insulation technology cascade through product performance, warranty exposure, and total cost of ownership.
- Our market-size synthesis shows a clear expansion trajectory: the market grew steadily through the early 2020s and reached a substantive size by 2025 (base year). Under a mid-cycle scenario the sector is projected to expand at a compound annual growth rate of roughly 5.05% through 2032, with the market size increasing meaningfully across the forecast period (2026–2032). This pace is high enough to justify near-term capacity investments and long-term supply commitments, but not so rapid as to eliminate the need for disciplined capital allocation and smart hedging.
- For 2026, the strategic inflection points for buyers and manufacturers are clear: secure cost stability against raw-material volatility, align compliance and specifications to the latest industry standards, and optimize geographic footprint and product breadth to serve electrification end-markets efficiently.
Macro trajectory — what the numbers tell us
From 2020 through 2025 the market recorded sustained expansion, reflecting accelerating electrification investment and steady demand from industrial and appliance segments. Our time series shows that the market rose from the low‑twenties in 2020 to a notably larger base by 2025 (all figures reported in USD Billion), and our forecast through 2032 anticipates continued growth to a substantially larger market by the end of the period. This trajectory — coupled with a mid-single-digit CAGR of 5.05% — supports multiple strategic actions: selective capacity additions, multi-year supply agreements, and prioritized R&D in high-value conductive and insulation systems.
Magnet Wire Market
Key dynamics shaping 2026 decisions
- Raw-material volatility and procurement mechanics. Global copper pricing exhibited meaningful volatility in the recent cycle, prompting OEMs and wire manufacturers to adopt more granular hedging strategies and contract escalators tied to commodity indices. For procurement teams, this translates into three practical options: adopt indexed long-term contracts with defined floors/ceilings; pursue synthetic hedges using financial instruments; or diversify to alternative conductor chemistries where technical trade-offs permit.
- Standards and regulatory change. The latest ANSI/NEMA magnet-wire standard update in 2025 reshapes qualification timelines for new products and can extend testing and certification lead times. Product managers should factor revised compliance milestones into development roadmaps to avoid late-stage rework and customer delays.
- Trade and tariff noise. Tariff surcharges and the renewed emphasis on near-shoring have increased landed-cost dispersion across supply chains. Supply-chain leaders must now layer customs and tariff scenario analysis into supplier selection and total-cost modeling rather than relying on headline unit costs alone.
- End-market electrification drivers. Continued growth in electric motors across industrial and mobility segments sustains demand for higher-performance magnet wires, including multi-strand and high-temperature insulations. The pace of EV adoption and industrial automation will be the primary demand multipliers through 2026–2028.
Competitive landscape — what to watch and why it matters
The magnet wire sector remains dominated by a set of established, technically capable manufacturers. Our competitive review examines product portfolios, channel reach, vertical integration, and geographic footprints to surface likely winners and strategic moves in 2026.
Magnet Wire Market
- Condumex (Mexico City). A major producer with a broad product mix for electrical apparatus. Condumex’s combination of regional scale and product breadth positions it as a preferred supplier for projects emphasizing proximity and rapid logistics in the Americas.
- Elektrisola, Inc. (Boscawen, NH). A NEMA-member manufacturer with deep technical know-how in magnet wire. Elektrisola’s strengths are in specialty insulations and certifications — key differentiators where qualification barriers protect margin.
- Essex Solutions (Fort Wayne, IN). Global leader with a pronounced automotive and industrial orientation. Essex’s integration with motor manufacturers provides it with early insight into design trends and demand cycles, enabling prioritized capacity allocation for growth segments.
- Magnekón (San Nicolás, Mexico). Another NEMA-member supplier with a strong presence in industrial applications. Its manufacturing footprint in North America supports near-shore sourcing strategies.
- MWS Wire Industries (Westlake Village, CA). Specialty and custom magnet wire supplier; recently published guidance on tariff surcharges and the impact on specialty wire costs — an indicator that smaller, highly specialized vendors are responding proactively to policy-driven cost pressures.
- Rea Magnet Wire Company (Fort Wayne, IN). One of the world’s largest magnet wire producers with visible investments toward EV and motor applications. Rea’s scale supports large contract awards and longer-term supplier relationships.
- Sumitomo Electric Industries (Osaka). A global producer with significant capability in wires tailored for renewable energy and traction systems. Its upstream integration and diversified end-market exposure provide resilience against localized demand shocks.
Recent industry developments reinforce these strategic themes. The announcement of new manufacturing capacity outside Europe and companies publishing tariff guidance are direct responses to customer demand for resilient, tariff-aware supply chains. These moves should be read as signals: suppliers are hedging geopolitical risk, and buyers should expect more overt contract clauses addressing trade and commodity impacts.
Strategic implications and actionable choices for 2026
- Procurement playbook: Recast sourcing RFQs to include modular contract terms — commodity pass-throughs, multi-sourcing options, and service-level KPIs for qualification speed. Ask suppliers for scenario-based landed-cost models that incorporate tariff and copper-price stress tests.
- Design and product strategy: Prioritize design-for-manufacture choices that reduce sensitivity to conductor and insulation cost swings. Where performance allows, evaluate aluminum-based conductors or hybrid solutions to mitigate copper exposure; however, assess lifecycle impacts and warranty trade-offs rigorously.
- Capacity and footprint decisions: Given the market’s steady growth trajectory, greenfield or brownfield expansions can be justified selectively — but target investments toward modular, quick-ramp lines and flexible insulation capabilities to respond to shifting application mixes.
- M&A and partnership posture: Look for bolt-on acquisitions that add unique insulation technologies, proprietary multi-strand processes, or regional logistics advantages. Companies with accessible certification assets or local regulatory know-how are especially valuable.
- Risk management: Implement layered risk controls: financial hedging for copper exposure, supplier audit programs for quality and compliance, and commercial clauses that allocate macro-policy risk transparently between parties.
What the full PW Consulting report provides (practical, operational outputs)
- Proprietary market model (2020–2032) with scenario toggles for commodity, tariff, and end-market demand shocks;
- Differentiated supplier scorecards that rank manufacturers by technical capability, vertical integration, cost competitiveness, and time-to-qualify metrics;
- Procurement playbook templates (RFP language, escalation clauses, sample hedging approaches) tailored for magnet wire buyers;
- Capital investment decision tools (NPV and payback scenarios) calibrated to magnet wire manufacturing lines and insulation-changeover economics;
- Regulatory and standards compliance roadmap aligned to the 2025 ANSI/NEMA update, including expected qualification timelines and testing cost drivers;
- Risk register and mitigation matrix addressing raw-material volatility, tariff scenarios, and supply-chain concentration risks.
Closing recommendations — immediate actions for 2026 planning cycles
- Integrate the magnet wire demand signal into product and factory planning cycles now. Lead times for qualification and insulation rework can compress your ability to capture late-cycle demand.
- Issue pre-qualification enquiries to multiple suppliers and request scenario-based landed-cost models that include tariff and copper-price variability. Use these to stress-test 2026 budgets.
- Consider targeted strategic inventory for critical conductor grades and high-value insulated wire types to buffer short-term supply interruptions while avoiding full stock builds that erode working capital.
- Pursue selective partnerships or acquisitions that provide immediate access to proprietary insulation or multi-strand capabilities — these generate asymmetric value as electrification accelerates.
PW Consulting’s full Magnet Wire Market study contains the source datasets, competitor profiles, and action templates referenced above. This preview is purposefully selective — it surfaces the levers that matter for 2026 while preserving the detailed segment-level analytics and financial tables that we reserve for subscribers and licensed purchasers. For procurement teams, product leaders, and corporate strategists ready to translate insight into competitive advantage, the complete report provides the executable intelligence needed to make confident decisions in 2026.
Contact PW Consulting to access the full report, download the data model, or commission a tailored supplier workshop. Our advisory services can accelerate your 2026 planning by translating market scenarios into prioritized roadmaps and commercial contract language that mitigate the risks outlined here.
For detailed analysis of this topic, please visit the official page: Magnet Wire Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oven Controlled Crystal Oscillator (OCXO) Market set to grow at 4.03% CAGR
By PW Consulting, 2026-07-08
Oven Controlled Crystal Oscillator (OCXO) Market — Strategic Preview for 2026 Decision-Makers
As enterprises and system integrators prepare capital and product strategies for 2026, the OCXO market presents a classic technology-market inflection: steady, technically demanding growth underpinned by defense, aerospace, telecom, and precision-industrial demand — yet increasingly shaped by power, miniaturization, and supply-chain friction. Our PW Consulting OCXO Market study (base year 2025) synthesizes five years of historical performance (2020–2025) and delivers a pragmatic 2026–2032 forecast horizon built for executives who must convert technical nuance into commercial advantage.
Oven Controlled Crystal Oscillator (OCXO) Market
Why this study matters for 2026 strategy
-
Clear market trajectory: The OCXO market reached USD 485 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of approximately 4.03% across our 2026–2032 forecast window, reaching roughly USD 639 million by 2032. This is not hypergrowth, but it is predictable, enabling disciplined portfolio planning and capital allocation.
Oven Controlled Crystal Oscillator (OCXO) Market -
High technical and regulatory barriers: OCXO product development and qualification require specialized manufacturing, precision calibration, and compliance with domain-specific standards (for example, space and military qualification regimes). These barriers protect incumbents but also raise the cost of entry — a central finding for M&A and partnership strategies.
Oven Controlled Crystal Oscillator (OCXO) Market -
Structural pockets of opportunity: Improvements in power efficiency, MEMS-enabled approaches, and NewSpace demand create targeted windows for disruptive entrants and for established vendors to capture premium pricing. The relative stability of the market allows companies to prioritize R&D bets with controllable downside.
What the report delivers — practical, executable intelligence
-
Market sizing and validated forecasts: We provide a transparent model from 2020 through 2032, clearly documenting assumptions and sensitivity ranges. The top-line trajectory above is supplemented by scenario analysis (base, downside, upside) so procurement and R&D roadmaps can be stress-tested against macro shocks.
-
Actionable competitive benchmarking: A vendor scorecard that evaluates technical depth, product breadth, vertical market exposure, manufacturing footprint, and strategic intent. This is crafted to support sourcing decisions, partner selection, and acquisition targets.
-
Technology and product playbooks: Comparative analysis of oven architectures, miniature OCXO trade-offs, MEMS hybrids, and the emerging challenge from miniature atomic references. For engineering leaders, we include recommended R&D investment profiles tied to target performance thresholds (phase noise, stability, power budget) and likely time-to-market implications.
-
Supply-chain and cost-to-serve tools: Line-item BOM benchmarks, a supplier risk matrix (including raw quartz blank sourcing and purification constraints), wage and skill-scarcity impact models, and templates for near-term cost-reduction initiatives without compromising reliability.
-
Regulatory and qualification playbook: Practical checklists and timelines for MIL-PRF and space-qualification pathways, plus recommendations for test-lab investments and third-party certification strategies to accelerate qualification in defense and space programs.
-
Commercial playbooks: Pricing elasticity guidance, channel strategies for telecom versus aerospace customers, and go-to-market frameworks for low- to mid-volume defense opportunities versus high-volume telecom deployments.
Market structure and competitive dynamics — what you need to know
The market is concentrated, but not monopolistic. Our concentration analysis indicates a market structure where the top three to five suppliers together control a meaningful share, leaving room for specialist players to command premium niches. That structural balance has important implications for entrants, incumbents considering consolidation, and procurement teams seeking leverage.
Key incumbent archetypes and strategic implications:
-
Large diversified suppliers (example profiles: Seiko Epson, Microchip): These players combine deep engineering, global manufacturing, and channel reach. Their advantage is the ability to bundle OCXO with broader system offerings and to invest in high-reliability programs. For them, the strategic choices center on whether to prioritize scale and cost or to pursue high-margin, space- and defense-qualified product lines.
-
Specialist high-reliability houses (example profiles: Rakon, Nihon Dempa Kogyo, Daishinku): These firms are differentiated by extreme stability, low phase-noise designs, and long qualification pedigrees. They are the natural partners for NewSpace, satellite comms, and radar. Competitive levers include IP protection, certification speed, and bespoke engineering services.
-
Miniature and MEMS innovators (example profiles: TXC, SiTime): They pursue miniaturization and power reductions, aiming at 5G, small-satellite, and mobile infrastructure markets. Their roadmap choices will determine whether MEMS-based timing becomes a disruptive substitute in selected segments.
-
Ruggedization and defense-focused manufacturers (example profiles: Mercury Electronic Industries, Bliley, KYOCERA AVX, Q-Tech): These vendors emphasize mechanical and environmental hardening, radiation tolerance, and defense compliance. Partnerships with systems integrators and defense primes are a primary distribution route.
Recent product launches and workshop findings underscore shifting technical priorities. Notably, a late‑2025 space-grade OCXO announcement signaled vendor intent to compete with miniature atomic solutions for NewSpace timing references, and industry workshops in 2026 emphasized aggressive power-consumption reduction targets (notably a 150 mW benchmark). These moves are not merely incremental — they foreshadow a bifurcation of the market between power-sensitive miniature platforms and the classically stable, oven‑controlled high-reliability installations.
Operational and supply risks that matter in 2026
-
Skilled labor and assembly complexity: Precision oven assembly and calibration are specialist processes; labor scarcity and wage inflation in advanced-feat manufacturing will sustain premium pricing in high-reliability segments.
-
Quartz blank supply and material purity: High-stability OCXO requires quartz blanks with stringent purity controls. Supplier concentration and quality gating can create pinch points that directly affect lead times and qualification timelines.
-
Testing and infrastructure needs: Achieving sub-ppb frequency stability requires dedicated, temperature-controlled testing infrastructure — a capital and facility consideration that affects both capex planning and contract lead-times for program wins.
-
Standards and qualification timelines: Compliance with military and space-grade standards imposes long lead times; procurement and product roadmaps must incorporate certification timelines as deterministic gating factors for revenue recognition.
Strategic recommendations for 2026 decision cycles
-
Prioritize targeted R&D for energy efficiency and miniaturization. For companies exposed to 5G edge-infrastructure or NewSpace, investing to meet the new power benchmarks and reduced SWaP (size, weight, and power) targets is now a commercial imperative.
-
Hedge raw-material exposure. Establish dual-sourcing or qualification pipelines for quartz blanks, and consider strategic equity or supply agreements with upstream specialty quartz producers to de-risk lead times.
-
Align M&A with capability gaps, not volume alone. Look for tuck-ins that add radiation hardening, space‑grade qualification, or miniature MEMS capability rather than simply adding capacity.
-
Invest selectively in test infrastructure. For suppliers targeting defense and space primes, owning or co-investing in qualification labs shortens procurement cycles and can command price premium through faster delivery.
-
Adopt a segmented go-to-market: differentiate pricing, service-level agreements, and R&D roadmaps between high-reliability, low-volume contracts and high-volume telecom or industrial OEM deals.
-
Monitor regulatory and standard shifts closely. Emerging workshop outcomes and industry consortium targets (e.g., power reduction goals discussed in 2026 forums) can rapidly change procurement specifications for tier-1 customers.
What you will not find here — and why you should read the full report
This preview intentionally highlights the strategic contours, technical inflection points, and actionable recommendations you need to shape 2026 decisions. The full PW Consulting OCXO Market report contains the detailed segment-economic tables, vendor share overlays by region and application, and downloadable decision-support spreadsheets that procurement, product, and strategy teams require for execution. If you are evaluating supplier consolidation, preparing an RFP, or building an OCXO-enabled product roadmap for 2026–2028, the full dataset and vendor scorecards are essential.
Next steps for executives
-
Download the full report for validated segment-level tables, supplier scorecards, and the executable playbooks that translate these market dynamics into P&L and engineering milestones.
-
Engage PW Consulting for a tailored workshop: we can map the study’s findings to your product portfolio, run a supplier-sourcing simulation, or build a certification roadmap aligned to your prioritized contracts.
OCXO is a mature, specialist market — but one in the early stages of meaningful technical change. For firms who treat 2026 as a year to align R&D, supply resilience, and certification pacing, the opportunities are clear. PW Consulting’s OCXO study equips decision-makers with the empirical forecasts, risk models, and commercial playbooks to act with confidence — without losing sight of the engineering discipline that defines success in this sector.
For detailed analysis of this topic, please visit the official page: Oven Controlled Crystal Oscillator (OCXO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


