



Category: Machinery & Automotive
PW Consulting: Hydraulic Accumulator Market to Rise from USD 179 Million in Base Year 2025 to USD 262 Million by 2032 (2026–2032 Forecast) at 5.6% CAGR — Asia Pacific Commands ~54%, Bladder Accumulators Lead
By PW Consulting, 2026-06-29
PW Consulting: Hydraulic Accumulator Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting today releases a strategic briefing that synthesizes our latest Hydraulic Accumulator Market research (base year 2025, forecast 2026–2032). This release distils the report’s most consequential, decision-ready conclusions for executives planning capital allocation, product strategy, supply-chain moves, or M&A activity in 2026. The market has demonstrated steady expansion — rising from approximately USD 130 million in 2020 to USD 179 million in 2025 — and our baseline forecast projects continued growth at a compound annual growth rate (CAGR) of 5.6% across 2026–2032, reaching roughly USD 262 million by 2032. What follows is a precise, pragmatic summary of the strategic implications; the full dataset, granular segment breakouts, and scenario modeling are reserved for the complete report.
Hydraulic Accumulator Market
Why this research matters in 2026
-
Timing: 2026 is a pivot year for many industrial OEMs and tier suppliers. Capital budgets are being re-approved post-pandemic modernization cycles, and hydraulic subsystems—including accumulators—are being re-evaluated for energy optimization, safety compliance, and lifecycle cost.
Hydraulic Accumulator Market -
Regulation & certification: Recent regulatory movements, including an important transport authorization update issued in late 2025 and persistent applicability of EN and ISO safety standards, materially affect design choices, cross-border logistics, and aftermarket services.
Hydraulic Accumulator Market -
Cost pressure: Volatility in high-grade steel alloys and specialty elastomers (observed price swings of 15–25% within a single year in recent market monitoring) is creating margin leakage for manufacturers that lack hedging, supplier diversification, or pass-through mechanisms.
-
Consolidation and competition: The market exhibits moderate concentration (our CR3 and CR5 metrics indicate top-tier firms hold meaningful but non-dominant share), leaving room for differentiated entrants, niche consolidation, and bolt-on acquisition strategies.
High-level analytical highlights
-
Growth trajectory and demand drivers — The accumulator market’s steady historical growth (2020–2025) and our 5.6% forecast CAGR reflect a broad mix of replacement demand, expanded use in mobile and industrial hydraulics, and incremental adoption driven by energy-efficiency initiatives in construction, machine tools, and agricultural equipment sectors.
-
Market structure — Competitive dynamics are defined by several engineering-led global players with deep installed bases and aftermarket networks, alongside regional specialists and OEM captive suppliers. Measured concentration affords incumbents pricing power on engineered solutions but leaves commoditized segments exposed to price erosion.
-
Regulation & safety architecture — Compliance with established standards (including prevalent EN and ISO norms and the EU Pressure Equipment Directive) remains a gating factor for cross-border sales. A November 2025 revision clarifying transport authorization for certain accumulator constructions materially eases commercial logistics for some manufacturers, while simultaneously raising audit expectations for documentation and traceability.
-
Input-cost volatility — Raw-material swings are now an explicit strategic risk. Suppliers that can demonstrate supply continuity, vertical integration of critical elastomers and steel, or indexed pricing clauses with customers will outperform peers on margin stability.
What the full report delivers (practical modules for 2026 action)
-
Executive playbooks — Targeted decision frameworks for five distinct 2026 Executive priorities: profitability recovery, aftermarket expansion, product modularization, compliant international growth, and opportunistic M&A. Each playbook contains step-by-step actions, P&L impact levers, and a 6–24 month implementation timeline.
-
Market sizing & scenario suite — Granular historical and projected market models (base year 2025) with downside, mid, and upside cases. The dataset is delivered with interactive sensitivity toggles for input-price shocks, regulatory changes, and adoption curves.
-
Competitive benchmarking — Detailed profiles, capability maps and strategic intent assessments of leading players, including HYDAC International, Parker Hannifin, Danfoss Power Solutions, Bosch Rexroth, Eaton, Freudenberg Sealing Technologies, and a set of regional specialists and certified service providers. Benchmarks cover engineering depth, aftermarket penetration, channel reach, and certification coverage.
-
Supply-chain & procurement toolkit — Supplier risk heatmaps, recommended sourcing strategies for elastomers and alloy inputs, cost-pass-through templates, and negotiation playbooks to protect margins against raw-material volatility.
-
Regulatory compliance & logistics dossier — Practical checklists for compliance with applicable EN/ISO standards and PED requirements, plus implications from recent transport authorizations affecting seamless steel accumulators. Also includes recommended QA/traceability protocols and an audit timeline to avoid market-disrupting noncompliance.
-
Go-to-market & aftersales playbook — Revenue models for spare parts and service, recommended warranty structures, remote monitoring propositions, and bundling strategies that favor recurring revenues over one-time hardware sales.
-
M&A & partnership heatmap — Prioritized target lists by capability gap (materials, testing/certification, regional footprint, aftermarket logistics) and transaction thesis templates for tuck-in or scale plays aligned to the observed market concentration dynamics.
Competitive landscape: what to watch in 2026
The market is anchored by well-capitalized engineering firms with global distribution and deep systems expertise. HYDAC, Parker Hannifin, Danfoss, Bosch Rexroth, Eaton and Freudenberg continue to lead on product breadth, certification portfolios and aftermarket service footprints. Specialist manufacturers and regional brands remain highly relevant in price-sensitive and customized segments; their localized manufacturing and service capability create meaningful barriers to rapid consolidation.
Independent testing and certification providers (for example, globally recognized labs) play a pivotal role in market access and commercial trust — an essential consideration given evolving transport and pressure-vessel documentation requirements introduced since late 2025. Leading OEMs that integrate third-party testing into their go-to-market collateral achieve faster procurement cycles and higher price realization in regulated sectors.
Strategic recommendations for 2026 decisions
-
Treat materials as a strategic input: establish multi-year contracts, explore strategic inventory buffers for elastomers and specialty steels, and investigate forward-coverage or supplier equity to reduce exposure to 15–25% price swings.
-
Prioritize aftermarket and digital services: design remote monitoring retrofit kits and service contracts that convert one-time sales into recurring revenue streams and provide defensible margins.
-
Accelerate compliance readiness: update design and supply documentation to align with EN/ISO/PED standards and assess the implications of the late-2025 transport authorization change on logistics and type-approvals.
-
Focus M&A on capability gaps: seek targets that add materials control, rapid certification throughput, or aftermarket logistics rather than broad geographic scale alone; the market’s current concentration means well-executed tuck-ins can quickly improve margin profiles.
-
Use scenario-enabled pricing: incorporate cost-indexed clauses for critical materials and a two-tier pricing approach to protect margin while remaining competitive in commoditized channels.
How to use this briefing as a board-level decision tool
This briefing is designed to convert market intelligence into board-level decisions for 2026. Use it to:
-
Set priority investments for product safety and compliance over the next budget cycle.
-
Re-evaluate supplier strategies and procurement KPIs to capture margin volatility risks.
-
Identify near-term acquisition targets that deliver capability rather than only scale.
-
Design aftermarket propositions that materially improve lifetime customer economics and balance-sheet resilience.
Final note and next step
PW Consulting’s Hydraulic Accumulator Market report delivers the evidence base and executable playbooks necessary for competitive advantage in 2026. We have intentionally presented the high-impact, strategic conclusions here while reserving the granular breakouts, interactive models, and proprietary segment-level data for the full report. Executives and strategy teams who require the underlying datasets, competitor scorecards, and scenario models can access the complete study and supporting tools through PW Consulting’s research portal.
For organizations preparing 2026 strategies—whether focused on procurement resilience, product roadmaps, or M&A—this research converts market dynamics into priorities and implementable actions. Contact PW Consulting to obtain the full report, data extracts, and an advisory session tailored to your organization’s strategic objectives.
For detailed analysis of this topic, please visit the official page: Hydraulic Accumulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laser Drilling Machine for Aerospace Market Forecast to Expand at 6.98% CAGR Through 2032
By PW Consulting, 2026-06-29
PW Consulting: Strategic Brief — Laser Drilling Machine for Aerospace Market (2026 Decision Playbook)
Executive snapshot
PW Consulting today publishes a targeted strategic briefing derived from our full market research report on the Laser Drilling Machine for Aerospace market. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study combines quantitative market-sizing with actionable decision frameworks to guide procurement, R&D, and investment choices in 2026 and beyond. At the macro level, the market is expected to expand at a compound annual growth rate of 6.98% from the 2025 base, reflecting accelerating demand for precision micro-drilling across turbine, engine and airframe supply chains.
Laser Drilling Machine for Aerospace Market
Why aerospace leaders should read this now
-
Certification and time-to-qualified-supplier have become determinative procurement gates. Delays in NADCAP or OEM approvals can add months to program timelines and materially alter supplier selection economics.
Laser Drilling Machine for Aerospace Market -
Technology choices made today — laser type, axis architecture, and integrated software — lock in performance, throughput and maintainability for a decade. Our report quantifies trade-offs for capital and operating models used by OEMs and tier suppliers.
Laser Drilling Machine for Aerospace Market -
Aftermarket and service economics are an increasingly important source of margin for machine vendors and a critical cost for operators. The report provides a pragmatic services playbook to align maintenance strategies with utilization targets.
Data-driven view: market trajectory and what it means
From a measured base year in 2025, the overall market continues to scale as aerospace programs push higher-density cooling designs, lighter engine architectures and increased production rates. Our topline sizing and forecast show a clear expansion through 2032, driven by elevated OEM program activity, rising aftermarket throughput, and steady substitution of legacy processes with high-precision laser systems. For decision-makers, the takeaway is simple: procurement windows are opening for those who have clarified their production and qualification timelines.
Core growth drivers and operational levers
-
Thermal management design complexity — modern turbine cooling strategies require dense arrays of effusion holes that are only practical with high-throughput, high-precision laser drilling.
-
Shifts toward fiber-laser architectures and multi-axis kinematics — these technologies deliver repeatable micro-holes and lower maintenance footprints, enabling better unit economics at scale.
-
Stringent certification regimes and OEM approvals — NADCAP and OEM-specific standards drive supplier selection and create an advantage for vendors with existing aerospace accreditations.
-
Automation and software integration — closed-loop monitoring, advanced CAM suites, and inline inspection are moving from “value-add” to “table stakes” in production environments.
Process and performance benchmarks
Laser drilling in aerospace is highly engineered: contemporary multi-axis systems can achieve sub-0.05 mm micro-hole capability with sub-10 µm positioning accuracy and, in high-throughput configurations, hundreds of bores per second on suitable geometries. These process benchmarks underpin comparative evaluations between laser types and machine architectures: throughput per shift, quality yield, and secondary processing needs (deburring, inspection) are sensitive to those choices.
Competitive landscape — what the market looks like to buyers
-
Established machine-tool OEMs have product lines purpose-built for turbine and engine work, offering integrated hardware + software stacks that simplify qualification for larger programs.
-
Specialist providers emphasize NADCAP/OEM approvals, process expertise on exotic alloys and composites, and vertically integrated service footprints that appeal to MROs and tier suppliers.
Notable vendor archetypes profiled in the report include multi-axis industrial OEMs with bundled software capabilities, regional specialists with deep certification portfolios, and agile service-centric firms that complement their equipment offerings with calibrated process know-how. While several vendors are often referenced by aerospace buyers for their technology leadership, the market remains sufficiently fragmented that partnership choice has measurable program-level consequences.
Recent industry signals and their implications
-
Trade events and industry fora over the last 12–18 months highlighted 3D drilling capabilities and integrated modules for automated drilling workflows — a signal that systems integration and process automation are market differentiators.
-
New product introductions and show demonstrations emphasize throughput scaling and automated toolpaths, reflecting supplier responses to OEM cycle-time pressures.
-
Regulatory and certification requirements continue to shape adoption; NADCAP and OEM-specific approvals are non-negotiable in many program flows and remain a key gate for suppliers and service providers.
What’s inside the full PW Consulting report (practical deliverables)
-
Proprietary topline sizing and seven-year forecast model with scenario toggles for production cadence, certification lag and replacement cycles.
-
Decision frameworks that translate process benchmarks into procurement criteria: throughput-per-capital, quality yield sensitivity, and total cost of ownership templates customized for aerospace workflows.
-
Vendor scorecards and a phased supplier-selection playbook that weigh technology fit, certification status, service footprint, and integration risk.
-
Operational checklists for qualification roadmaps (NADCAP timelines, OEM approval pathways), including a sample Gantt for a one- to three-machine onboarding program.
-
Aftermarket and spare-parts strategies, with monte-carlo style stress tests on uptime assumptions and their impact on unit economics.
-
Case vignettes from production settings capturing how machine configuration choices affected yield, cycle time and downstream inspection load.
Strategic recommendations for 2026 decision cycles
-
Align procurement to program milestones, not calendar years. Start machine qualification and NADCAP-related activities early in the program lifecycle to avoid costly production ramp delays.
-
Prioritize integrated solutions where process repeatability is mission-critical. Machines with proven CAM/inspection stacks shorten time-to-qualify and reduce first-pass yield risk.
-
Model service economics explicitly. For many operators, service contracts and spare-part availability eclipse capital amortization as primary drivers of lifetime cost.
-
Use proof-of-process gates to de-risk supplier selection. Run parallel qualification trials with shortlisted vendors to capture real-world throughput and secondary-processing impacts.
-
Consider staged automation: modular upgrades (e.g., Smart Driller-type modules) can defer initial CapEx while preserving a clear path to higher automation levels as production scales.
How PW Consulting’s analysis helps buyers, vendors and investors
For buyers, the research provides procurement-ready artifacts — scorecards, inspection criteria, and TCO templates — that speed decision cycles and increase confidence in supplier commitments. For vendors, the competitive intelligence and product benchmarking reveal where to invest in certifications, software, and service footprints to win aerospace business. For investors, the forecast and scenario analyses surface where consolidation, specialization, or service-enabled differentiation are likely to compress risk and create value over the coming planning cycle.
A reminder about the "trailer" approach
This strategic brief surfaces core trends, benchmarks and vendor archetypes to establish the context needed for 2026 decision-making. To preserve the tactical edge for organizations that require executable detail — including unit-level segmentation, regional dynamics, vendor scorecards, and modeled CapEx/Opex templates — the report’s full datasets and appendices are available through PW Consulting’s report distribution channels. The full deliverable contains the granular intelligence operational teams use to execute procurement and qualification programs.
Next steps
-
Procurement teams: use the included qualification Gantt and decision matrices to set internal deadlines aligned with program milestones.
-
Engineering and operations: request the report’s process benchmark annex to calibrate acceptance criteria and institute inline inspection metrics.
-
Senior leadership and investors: consult the forecast scenarios to stress-test CapEx plans and aftermarket service strategies over a seven-year horizon.
PW Consulting invites program managers, OEM sourcing leads, suppliers and private capital interested in the Laser Drilling Machine for Aerospace market to review the full report for actionable datasets and operational playbooks tailored for 2026 deployment decisions. For access to the complete analysis, vendor profiles, and the decision-support toolkit, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Laser Drilling Machine for Aerospace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Gas Engines Market to Grow from USD 5.84 Million in 2025 to USD 8.55 Million by 2032 at a 5.6% CAGR
By PW Consulting, 2026-06-29
Gas Engines Market 2026 Strategic Briefing — PW Consulting Industry Insight
As organizations finalize capital allocation and product roadmaps for 2026, the gas engines market presents a nuanced growth opportunity shaped by decarbonization imperatives, evolving fuel quality standards, and an accelerating shift toward service-centric business models. PW Consulting’s latest Gas Engines Market study (base year 2025; forecast period 2026–2032) synthesizes five years of historical trends and a forward-looking scenario suite to equip executives with the actionable intelligence needed to navigate this transition. The market has expanded from approximately USD 4.45 Million in 2020 to USD 5.84 Million in 2025 and is projected to reach roughly USD 8.55 Million by 2032, implying a compound annual growth rate of 5.6% across the forecast window.
Gas Engines Market
Why this report matters for 2026 decision-makers
-
Capital allocation: With constrained budgets and competing priorities (grid resilience, renewables integration, emissions control), procurement and investment teams need clear, defensible scenarios to prioritize engine types, retrofit strategies, and lifecycle service commitments.
Gas Engines Market -
Product strategy: OEM and Tier‑1 leaders must reconcile short‑term demand for high‑efficiency natural-gas assets with mid‑term needs for hydrogen-ready or low‑carbon alternatives. Our analysis identifies which technical levers create differentiated value and which are commoditizing.
Gas Engines Market -
Regulatory compliance: New reporting and standards regimes are increasing compliance costs and influencing specifications. Operators and OEMs must anticipate these shifts to avoid warranty and operational risk.
-
M&A and partnerships: The market structure points to selective consolidation and buy-and-build opportunities for service-oriented players seeking scale in aftermarket parts and digital services.
Market trajectory: measured growth, persistent opportunity
Across the historical period (2020–2025) the sector has demonstrated steady expansion, rising from about USD 4.45 Million to USD 5.84 Million. The forecasted trajectory to roughly USD 8.55 Million by 2032 (CAGR 5.6% for 2026–2032) reflects a market that is neither hyper‑cyclical nor saturated — instead offering predictable, investment-grade growth. Importantly, concentration metrics indicate a fragmented supplier base: the top-three vendor share remains modest, and even the top-five combined share suggests significant room for differentiated specialization and local service plays. For corporates, that fragmentation translates into both execution risk and procurement leverage, depending on how a buyer approaches supplier rationalization and long‑term service contracting.
Strategic themes shaping outcomes through 2026 and beyond
-
Hydrogen readiness and fuel flexibility: OEM roadmaps increasingly cite hydrogen-capable platforms or dual‑fuel capability as core product differentiators. Buyers need a clear view of the trade-offs between upfront premium and future-proofing benefits.
-
Decarbonization via lifecycle approaches: Emissions reduction is shifting from discrete engine performance metrics to lifecycle emissions strategies that include fuel sourcing, electrification of auxiliaries, and integration with renewables and storage.
-
Service-led revenue models: Given the aftermarket margin profile and the importance of uptime for critical applications (data centers, grid stabilization), suppliers are investing in condition‑based maintenance, digital twins, and outcome‑based contracts.
-
Standards and fuel quality: International guidelines and regional reporting obligations are raising the bar for guaranteed performance, especially in marine and oil & gas segments.
-
Distributed energy and grid dynamics: Gas engines retain strategic relevance for peaking, CHP/COGEN, and remote power applications where flexibility and fast dispatchability are critical.
Competitive landscape — how incumbent strategies are evolving
The competitive set is diverse, spanning specialists with deep installed bases to multi‑platform industrial OEMs. Our assessment of leading participants highlights the strategic differentiation each brings to the market:
-
INNIO Jenbacher (Jenbacher, Austria) : With a large installed base measured in the tens of gigawatts, Jenbacher’s portfolio emphasizes dedicated gas engines and clear progress toward hydrogen-capable platforms. Their strength lies in application engineering for cogeneration and power generation, making them a reference point for long‑term reliability and fuel‑transition programs.
-
Caterpillar Inc. (Peoria, Illinois, USA) : Caterpillar leverages an extensive dealer and service network alongside natural gas and compression engine offerings. Their strategy centers on integrated power systems and lifecycle support, which is attractive to large industrial buyers seeking single‑vendor accountability.
-
Cummins Inc. (Columbus, Indiana, USA) : Cummins’ newer natural gas platforms and near‑zero emissions engines position them as a flexible player across heavy‑duty and stationary markets. Their emphasis on emissions compliance and modular electrification pathways is likely to accelerate adoption in regulated markets.
-
MAN Energy Solutions (Augsburg, Germany) : With an offering that spans small to mid-range power outputs, MAN focuses on low‑pollution engines and cogeneration. Their engineering depth supports industrial customers with bespoke configurations.
-
Rolls‑Royce Power Systems (mtu) (Friedrichshafen, Germany) : Mtu’s positioning targets high‑reliability applications such as data centers and grid stabilization. Their generator-set integration capabilities and fast‑response portfolios are differentiators where reliability is paramount.
-
Wärtsilä (Helsinki, Finland) : Wärtsilä’s range of 4‑stroke spark‑ignited engines is oriented to power plants and cogeneration, with strength in system integration for larger power projects and hybridization with energy storage.
-
Perkins Engines (Peterborough, UK) : Perkins competes on robustness for harsh environments, making them a preferred choice for remote or heavy industrial applications requiring rugged, serviceable platforms.
-
DEUTZ AG (Cologne, Germany) : DEUTZ targets water‑cooled gas and gasoline engines for industrial and off‑highway uses, addressing customers seeking compact, durable solutions for non‑road applications.
Together, these vendors demonstrate the plurality of routes to value: deep installed bases and application engineering, broad service networks, emissions leadership, and niche reliability plays. For potential acquirers or alliance partners, the market’s modest top‑tier concentration suggests inorganic consolidation and exclusive service partnerships remain viable strategies to capture aftermarket margin and lock‑in customers.
Regulatory & standards developments that will reframe procurement in 2026
-
Reporting obligations: Regional reporting deadlines for engine emissions—for example, medium and large engine reports due May 1, 2026 for the 2025 calendar year in certain jurisdictions—are increasing the administrative and technical burden on operators. Buyers must factor compliance‑related upgrades, metering, and recordkeeping into TCO models.
-
Fuel quality standards: The CIMAC Guideline 05 (2025 edition) on the impact of gas quality on gas engine performance introduces new expectations for marine applications and has broader implications for engine tolerance to variable fuels. This increases the importance of fuel quality risk assessments and may accelerate demand for conditioning and monitoring solutions.
What’s in the PW Consulting report — practical deliverables
-
Executive summary with strategic implications tailored to OEMs, utilities, independent power producers, and oil & gas operators.
-
Market sizing and forecast model (2020–2032), including scenario sensitivity and downside stress cases (methodology transparent and audit‑ready).
-
Technology and product maturity matrix, highlighting hydrogen readiness, dual‑fuel capability, and retrofittability.
-
Supplier scorecards and go‑to‑market playbooks: commercial KPIs, margin pools, service strategies, and partnership archetypes.
-
Regulatory impact assessment and compliance cost engineering templates for 2026 planning cycles.
-
M&A screening grid and a prioritized list of target archetypes (by capability, service access, and aftermarket potential).
-
Operational readiness checklists and procurement templates to accelerate RFP and contract negotiation cycles.
Recommended next steps for buyers and suppliers in 2026
-
Prioritize modular upgrades: Target platforms that allow staged hydrogen integration to protect near‑term ROI while preserving retrofit optionality.
-
Secure aftermarket coverage: Negotiate outcome‑based service agreements with clear performance SLAs and shared‑risk maintenance models.
-
Upgrade compliance capabilities: Invest in standardized reporting and fuel‑quality assurance to preempt enforcement and warranty disputes.
-
Build digital operations: Deploy condition monitoring and digital twin pilots focused on high‑value assets to validate service economics before scaling.
-
Evaluate inorganic moves: Use the report’s screening framework to assess targets that immediately strengthen aftermarket scale or proprietary sensor/software capabilities.
Why review the full report
This briefing is intentionally concentrated on strategic takeaways. PW Consulting’s full Gas Engines Market report contains the granular segmentation, regional demand curves, and supplier financial benchmarks necessary to run procurement simulations, build investment memos, and support board‑level decisions. For teams that must translate strategy into procurement language and financial models in 2026, the full dataset and scenario models are essential.
To access the complete report, including detailed segment-level intelligence, supplier dashboards, and the downloadable forecasting model, visit PW Consulting’s Gas Engines Market report page. Our team is also available to run bespoke workshops that translate the report’s findings into a 90‑day implementation plan aligned with your portfolio and risk appetite.
For detailed analysis of this topic, please visit the official page: Gas Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marine Propeller Market Hits USD 4.48 Billion in 2025, Poised for Strong Growth
By PW Consulting, 2026-06-29
Marine Propeller Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
As a foundational element of ship performance and lifecycle emissions, the marine propeller market is transitioning from cost-driven replacement cycles toward technology-led value creation. Our PW Consulting Marine Propeller Market study (base year 2025) shows the global market expanding from roughly USD 3.56 Billion in 2020 to USD 4.48 Billion in 2025, and we forecast continued growth at a compound annual growth rate (CAGR) of 6.6% through our planning horizon (2026–2032), reaching an estimated USD 6.94 Billion by 2032. This briefing distills the report’s most decision-relevant implications for executive teams planning investments, procurement, or M&A in 2026, while intentionally reserving core segmented datapoints to encourage direct engagement with the full study.
Marine Propeller Market
Why this report matters for 2026 decisions
-
Strategic procurement: With lead-times, material prices, and regulatory constraints tightening, procurement teams that adopt demand-forecast linked contracting will reduce cost volatility and shipment delays.
Marine Propeller Market -
Product development: Propeller performance is increasingly a systems issue—blade design, hub technology, surface treatments, and integration with variable-speed drivetrains now determine commercial returns on fuel-efficiency investments.
Marine Propeller Market -
M&A and partnerships: Fragmentation persists alongside pockets of consolidation; 2026 is a window for bolt-on acquisitions that deliver manufacturing scale, proprietary tooling, or access to retrofit channels.
-
Aftermarket and services: Repair, scanning, and retrofitting services are a higher-margin growth path as owners seek to extend vessel life and meet life-cycle GHG intensity expectations.
Market dynamics shaping 2026 strategy
-
Regulatory acceleration: The adoption of new standards (e.g., ISO 18581:2026 for fixed-pitch hub cap design) and IMO lifecycle GHG guidance is shifting buyer requirements from purely mechanical specifications to lifecycle and compatibility requirements. Companies that embed compliance into design and validation workflows will shorten sales cycles.
-
Decarbonization as a purchasing vector: Shipowners are increasingly evaluating propulsion components through a Tank-to-Wake lens. Propeller selection and retrofits that demonstrably reduce fuel intensity will command preference and premium service contracts.
-
Raw material and shipbuilding cost volatility: Recent upward pressure on ship prices and material indices has a twofold effect—deferring some new-build propeller orders while accelerating aftermarket repairs and upgrades. Risk-managed sourcing strategies and strategic inventory positioning can mitigate margin erosion.
-
Geopolitical and trade friction: Proposed tariff actions on maritime products have raised procurement risk in 2025–2026. Suppliers and buyers should stress-test supply chains, evaluate near-shoring opportunities, and incorporate tariff scenarios into bid models.
-
Manufacturing innovation compresses lead times: Recent production-scale innovations demonstrate a step-change in responsiveness. For example, collaborative manufacturing approaches have reduced typical cast-and-produce cycles from months to weeks, unlocking aftermarket responsiveness and enabling just-in-time retrofit programs.
Competitive landscape — what to watch in 2026
The market sits between concentrated OEMs and a broad base of specialized manufacturers and service providers. Measured concentration indicates meaningful incumbent strength without insurmountable barriers for innovative entrants (CR3 ~55%; CR5 ~62%). The competitive field is evolving along three axes: materials and casting capability, precision machining/CNC specialization, and aftermarket scanning/repair services.
-
Michigan Wheel (Grand Rapids, MI; https://www.miwheel.com/) — Historically strong in recreational and commercial inboard/outboard propellers. Their strategic repositioning—illustrated by a recent sale of UK operations—signals focus on core markets and potential reallocation of capital to R&D and aftermarket channels.
-
VEEM Marine (Perth, Western Australia; https://veemmarine.com/) — Known for CNC-machined, performance-grade propellers including specialized high-speed designs. VEEM’s engineering-centric play is an archetype for premium, performance-sensitive OEMs.
-
Sharrow Marine (Detroit, MI; https://www.sharrowmarine.com/) — A technology-led small-fleet manufacturer with patented blade architectures. Their recent production-scaling collaboration with an automotive OEM demonstrates how cross-sector manufacturing partnerships can dramatically compress turnaround times and scale advanced casting techniques.
-
Nakashima Propeller Co., Ltd. (Okayama, Japan; https://www.nakashima.co.jp/eng) — A global supplier with depth across ocean-going and specialist vessels; their strategic M&A activity in 2025 highlights a consolidation play in select geographies.
-
AccuTech Marine Propeller (Dover, NH; https://accutechmarine.com/) — Exemplifies the high-margin aftermarket: advanced prop-scan diagnostics and precision repair/tuning tailored to vessel operators looking to avoid full replacement.
-
PowerTech! Propellers , Quality Castings Wisconsin , and Anchor Miami Propeller — These suppliers represent the diverse middle-market: standard stainless/aluminum producers, precision casters, and performance-focused regional providers that together supply the aftermarket and niche OEM segments.
Recent developments that change the playbook
-
Strategic industry moves: A notable 2025 strategic sale saw a North American supplier divest European operations to a global propeller manufacturer—an example of targeted geographic consolidation that reallocates resources toward R&D and high-margin segments.
-
Production scaling breakthroughs: A 2026 announcement from a leading propeller innovator revealed a collaboration with an automotive manufacturer that reduced sand-casting production timelines from roughly 130 days to about two weeks—reshaping aftermarket turnaround economics.
-
Market convenings and product evolution: The 2025 Annual Marine Propulsion Expo and new product launches throughout 2024–2026 have accelerated the diffusion of multi-blade, low-noise designs and integrated hub technologies.
What the full report provides (practical, executable content)
-
Robust demand model and scenario forecasts (2026–2032) calibrated to new-build vs. retrofit drivers, fuel-cost elasticity, and regulatory adoption pathways.
-
Supplier and capability maps that identify manufacturing capacity, precision machining clusters, and aftermarket service footprints—designed for sourcing and site-selection decisions.
-
Competitive heatmaps and capability overlays for the leading OEMs, highlighting technology specialisms and market moves without disclosing client-level confidentials.
-
M&A playbook and valuation sensitivities tailored to propeller businesses, including synergy templates for bolt-on acquisitions and carve-outs.
-
Procurement checklists and sample contract clauses that address tariff risk, IP protection for blade geometries, supply continuity, and compliance with ISO/IMO developments.
-
Aftermarket monetization templates—price/volume sensitivity, lifecycle breakeven for retrofit campaigns, and maintenance-as-a-service commercial models.
-
Technical appendix: testing protocols, performance metrics (efficiency, cavitation, NVH), and recommended validation templates for new propeller concepts.
Actionable recommendations for 2026
-
For OEMs and manufacturers: Prioritize capital allocation to near-term manufacturing capacity and digital quality controls (3D scanning, CNC automation) that shorten delivery cycles and support higher mix, lower-volume production economics.
-
For shipowners and operators: Commission prop-scan diagnostics as standard during scheduled dry-dock windows and evaluate retrofits when the projected fuel savings under plausible 5–7 year fuel price paths exceed replacement costs.
-
For investors: Target acquisitions that unlock aftermarket service networks or proprietary manufacturing methods; use the included valuation sensitivity models to stress-test assumptions around material costs and regulatory adoption rates.
-
For procurement leaders: Build contractual flexibility for tariff and supply shocks—layered sourcing, near-shoring pilots, and buffered consignment stock where total-cost-of-ownership analysis supports it.
-
For R&D leaders: Integrate lifecycle GHG metrics early in product development to align with IMO guidance and to create defensible differentiation in lifecycle-based procurement tenders.
Methodology & scope
The study uses a mixed-methods approach: bottom-up ship-class demand modeling, aftermarket replacement cycles, supplier capacity analysis, and scenario-based macroeconomic overlays. Base year is 2025 with historical observation from 2020–2025 and a forecast window of 2026–2032. All monetary values are stated in USD (Billion) and the central forecast assumes a 6.6% CAGR for the forecast period. Detailed segmentation matrices (by region, type, and application) and granular unit economics are available in the full report—released as part of PW Consulting’s 2026 maritime portfolio.
Next steps — access and engagement
This brief outlines the operationally relevant signals we believe will determine winners and losers in the marine propeller market over the next three years. For procurement-ready datasets, proprietary segmentation tables, and our interactive decision-support models (including the retrofit breakeven tool and supplier risk heatmap), please consult the full PW Consulting Marine Propeller Market report or schedule a tailored executive briefing. The full study contains the granular numeric splits, regional and application tables, and vendor-level benchmarking intentionally withheld here to preserve the strategic value of the complete deliverable.
For detailed analysis of this topic, please visit the official page: Marine Propeller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Nail Gun Market Set to Grow at a 6.4% CAGR Through 2026–2032
By PW Consulting, 2026-06-29
Nail Gun Market 2026 Strategic Brief — PW Consulting Releases Executive Intelligence to Guide High-Stakes Decisions
Executive summary
PW Consulting’s latest Nail Gun Market report (base year 2025) delivers a forward‑looking framework designed to inform boardroom and investment committee decisions in 2026. Our bottom‑up market sizing shows the industry expanding from approximately USD 3.14 billion in 2020 to roughly USD 4.01 billion in 2025, with a compound annual growth rate (CAGR) of 6.4% across the forecast window. Under our core scenario the market continues to scale, reaching just north of USD 6.1 billion by 2032, driven by technology transition, renovation cycles, and rising professional adoption of cordless and high‑efficiency pneumatic platforms.
Nail Gun Market
Why this report matters for 2026 strategy
- Capital allocation with confidence: Our size and growth projections allow CFOs to model investment returns and prioritize R&D, manufacturing capacity, and M&A targets against realistic revenue trajectories for the next five to seven years.
- Product roadmaps that de‑risk adoption: With accelerating electrification and battery performance improvements, product teams will need clear trade‑off analyses between weight, cycle time, and cost to hit professional acceptance thresholds.
- Go‑to‑market prioritization: Channel leaders can use our demand signals and scenario sets to decide where to scale distribution, rental partnerships, and after‑sales networks without overinvesting in low‑velocity corridors.
- Compliance and safety integration: As regulation and workplace safety expectations tighten, procurement and engineering teams must anticipate design requirements and training obligations that affect total cost of ownership.
What’s in the PW Consulting Nail Gun Market report — practical, actionable content
The report is structured to be used, not just read. It blends quantitative market modelling with tools executives can deploy immediately:
Nail Gun Market
- Robust market sizing and demand scenarios (historical 2020–2025, base year 2025, forecast 2026–2032), with sensitivity testing under alternative macroeconomic and construction activity assumptions.
- Competitive benchmarking and concentration analysis, including CR3/CR5 measures that illuminate the degree of consolidation and where disruption opportunities exist.
- Product and technology matrixes comparing pneumatic, combustion‑powered and electric solutions on metrics that matter: productivity, ergonomics, lifecycle servicing cost, and regulatory compliance risk.
- Channel and pricing playbooks — distribution, rental, direct OEM, aftermarket parts and consumables — with execution checklists for pilots and scale programs.
- Supply‑chain resilience planning, identifying single‑source risks, strategic insourcing thresholds, and nearshoring tradeoffs supported by cost‑to‑serve models.
- Regulatory and safety impact assessments with actionable supplier and training partnership templates to reduce liability and improve field uptake.
- Three investor‑ready strategic options: organic product leadership, bolt‑on M&A consolidation, and platform plays via service + consumables monetization.
Competitive landscape — how to read the field
The Nail Gun market remains moderately concentrated, with the top three players controlling a meaningful share and the top five increasing the competitive moat. This structure creates a mix of stable incumbency and niche innovation pockets — a dynamic that informs different playbooks for market entrants vs. entrenched suppliers.
Nail Gun Market
- Adolf Würth GmbH & Co. KG (Germany) — strong distribution network and fastener portfolio; well positioned to bundle tools with supply services for professional contractors.
- AEG Powertools (USA) — leverages cordless tool expertise to push battery‑driven nailer propositions into pro segments where cordless convenience equals productivity gains.
- Basso Industry Corp. (Taiwan) — volume manufacturing strength and competitive cost positions make them a go‑to OEM for white‑label and private‑label programs.
- Bosch Production Tools (Germany) — innovation leader on precision, safety integration and digital tool ecosystems; a reference point for premium positioning.
- Bostitch (USA) — long heritage in fastening equipment; strong brand equity among framers and specialty trades.
- DEWALT Industrial Tool (USA) — focuses on ruggedized, professional offerings and broad aftermarket support, with distribution scale that shapes specification decisions.
- Everwin Pneumatic Corp. (Taiwan) — specialist pneumatic portfolio and active participation in regional trade shows; good pipeline for OEM partnerships and export growth.
- Ferplast (Italy) — niche manufacturing and European channel presence; plays in specialised segments that value design and certifiable quality.
- HITACHI KOKI (Japan) — engineering emphasis on reliability and lifecycle durability; influences procurement criteria in industrial applications.
- Itecma (Italy) — regional footprint with focus on tailored solutions for specific civil and industrial applications.
- Makita U.S.A., Inc. (USA) — market signaling through product refreshes, including a May 2025 launch of new 18V cordless framing nailers that underscore the cordless migration strategy.
- MAX USA CORP. (USA) — strong presence in coil and specialized fastening platforms; tight links with trade channels.
- MCC Corporation (USA) — product breadth across pneumatic segments and competitive pricing for fleet sales.
- Paslode (Canada) — combustion‑powered niche expertise and brand recognition among renovation specialists.
- Senco (USA) — enduring brand in finish and framing nailers; R&D focused on ergonomics and reduced recoil.
- SPIT‑IMPEX (France) — European specialist with application know‑how in masonry and heavy civil fastening.
- TJEP (Denmark) — Scandinavian design and product safety focus, appealing to markets prioritizing certified ergonomics.
Recent industry signals and their strategic implications
- Product refreshes such as Makita’s May 2025 18V framing nailers highlight an industry pivot: cordless platforms are closing the productivity gap with pneumatic systems, forcing incumbents to fast‑track battery investments and new ergonomics.
- Everwin’s exhibitions (International Hardware Expo Taiwan 2025; EISENWARENMESSE 2026) signal continued supplier investment in OEM/channel relationships and export expansion; trade show activity remains a reliable lead indicator for forthcoming product launches and partnership announcements.
Regulatory and safety dynamics — operational imperatives
Safety regulation and employee protection obligations are not peripheral — they materially affect product design, training programs, and commercial risk. Two facts matter for 2026 planning:
- Empirical safety guidance indicates that the risk of injury is substantially higher when using multi‑shot contact triggers compared with single‑shot sequential triggers, which has direct implications for product specifications and procurement choices.
- Standards and employer obligations (including requirements for personal protective equipment such as ANSI Z87.1 eye protection, hardhats and hearing protection, and formal training on powder‑actuated tools) raise the bar on the services and documentation OEMs must provide at no additional cost to employers in some jurisdictions.
For suppliers, incorporating safer trigger systems, providing certified training modules, and packaging compliant PPE and training as part of commercial offers can materially improve win rates with large contractor accounts and reduce post‑sale liability.
Strategic recommendations for 2026 (executive checklist)
- Prioritize cordless R&D and modular battery strategies where professional productivity gains can justify premium pricing; establish clear TCO models that compare battery, pneumatic and combustion options over typical fleet lifecycles.
- Develop a bundled services offering (training, certification, consumables subscription) to capture recurring revenue and create higher switching costs for large account customers.
- Use selective M&A to close capability gaps (battery chemistry, motor controllers, or digital telematics) rather than broadscale roll‑ups that dilute margins in a moderately concentrated market.
- Implement compliance‑first product roadmaps: incorporate sequential‑trigger options, documented training packages and PPE bundles into new launches to accelerate procurement approvals in safety‑sensitive buyers.
- Pilot rental and subscription models in contractor hubs to accelerate field trials and gather behavioral data; monetize consumables and expedited service levels.
- De‑risk sourcing via dual‑sourcing and near‑market inventory buffers for critical components to protect against regional supply shocks.
How PW Consulting supports your 2026 decisions
We offer a suite of advisory services that translate the report’s findings into executable programs: investor diligence packages, product commercialization playbooks, distribution optimization engagements, and bespoke scenario modelling tailored to your balance‑sheet and strategic horizon. For procurement and product teams we deliver supplier scorecards, safety‑compliance checklists and bench tests designed to shorten specification cycles.
To access the full dataset, market maps, and execution templates that power these recommendations — including the granular regional and application splits and the full competitive profiles — please visit the report landing page. PW Consulting’s Nail Gun Market analysis is intended to be a decision‑grade resource: deep enough to act on, selective enough to protect competitive nuance, and structured to convert insight into measurable outcomes in 2026.
Base year: 2025. Historical window: 2020–2025. Forecast period: 2026–2032. Currency: USD, revenue unit: Million.
For detailed analysis of this topic, please visit the official page: Nail Gun Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Power Quality Analyzer Market Poised for 5.2% CAGR (2026–2032), Reaches USD 279.4 Million in 2025
By PW Consulting, 2026-06-29
Power Quality Analyzer Market — Strategic Imperatives for 2026: A PW Consulting Brief
Executive summary
In an operating environment shaped by updated measurement standards, accelerating grid-edge complexity, and rising attention to reliability and energy optimization, power quality analyzers are rapidly moving from niche diagnostic tools to core infrastructure for utilities, industry and critical facilities. PW Consulting’s new market study (base year 2025; historical window 2020–2025; forecast period 2026–2032) quantifies this transition and translates it into decision-grade guidance for executives planning 2026 initiatives.
Power Quality Analyzer Market
Key macro takeaways: the global Power Quality Analyzer market grew from approximately USD 217 Million in 2020 to roughly USD 279 Million by 2025, and our forecast shows expansion into the high hundreds of millions by 2032—propelled by a compound annual growth rate of 5.2% across the 2026–2032 horizon. These headline numbers frame an enduring, predictable growth runway that supports both tactical procurement and strategic investments.
Power Quality Analyzer Market
Why 2026 is a watershed year for buyers and vendors
- Standards and compliance are resetting vendor and buyer requirements. The most recent revision to the key measurement standard (IEC 61000-4-30) has clarified measurement methods and transducer guidance, raising the bar for what constitutes “Class A” compliance and shifting expectations for accuracy, sampling, and reporting. Organisations that do not align testing and monitoring strategies with this updated baseline risk inspection friction and costly retrofits.
- Product innovation has consolidated around portability, higher-resolution waveform capture (including supra-harmonics), environmental sensing at the measurement point, and integration with cloud analytics for continuous diagnostics. Recent product introductions demonstrate a clear preference for fast-deploy, low-friction devices optimized for commissioning and rapid field diagnosis as well as for permanent monitoring use cases.
- Operational drivers—renewable integration, inverter-driven loads, electrification of transport and process plants—are increasing the frequency and complexity of power quality events. This is stimulating demand for both short-term troubleshooting instruments and permanently installed analyzers that combine waveform capture, statistical trending and event forensics.
Where this report helps: decisions we support in 2026
Our research is crafted to support three classes of strategic decisions in 2026:
Power Quality Analyzer Market
- Procurement and fleet rationalisation: which analyzer classes to standardise on (portable vs. permanently installed), how to size procurement for field services and capital programs, and how to balance cost, accuracy and compliance risk.
- Product and go-to-market strategy for vendors: feature prioritisation (sampling rates, supra-harmonics, environmental sensors), certification roadmaps post-standards update, and partner strategies to reach grid-edge and industrial customers.
- M&A, partnerships and service model design: where consolidation creates value, which technology gaps are best addressed through acquisition versus partnership, and how to monetise analytics and managed monitoring services.
What’s in the report — practical deliverables for 2026 planning
The study is intentionally operational. It combines quantitative forecasting with hands-on templates and scenario tools so that decision makers can act quickly:
- Market sizing and seven-year forecast (2026–2032) with methodology notes and sensitivity scenarios exploring standard-change and technology-adoption paths.
- Competitive benchmarking and vendor capability matrices that map measurement accuracy, sampling capability, use-case fit (commissioning vs. continuous monitoring), and software/API readiness.
- Buyer playbooks: procurement checklists, RFP templates, and total cost of ownership (TCO) calculators tailored to utilities, industrial OEMs and service providers.
- Deployment blueprints: field-test protocols, commissioning templates aligned to the latest measurement standards, and recommended KPIs for service-level agreements in managed monitoring contracts.
- Scenario-based investment guidance: probability-weighted outcomes for product development, channel expansion, and target customer segments that are resilient across regulatory or technology shocks.
Competitive landscape — what leading vendors are doing
The market displays moderate concentration; the top three firms account for nearly half of the market by revenue, while the top five approach two-thirds—indicating a landscape where global incumbents coexist with specialised niche players. The result is active technology differentiation rather than pure price competition.
Key strategic positions observed among leading vendors:
- Fluke Corporation: continues to capitalise on a broad portfolio of portable and stationary three-phase analyzers, emphasising field robustness and regulatory compliance. Fluke’s strength is brand trust and channel depth, which matter for utility-scale rollouts and long-term service contracts.
- A. Eberle GmbH & Co. KG: doubling down on rapid-deployment Class A devices for low-voltage commissioning. Their recent compact single-phase Class A mobile release underlines a strategy targeting time-to-measurement and reduced installation effort—attributes attractive to contractors and distribution network operators.
- Averna Technologies: emphasises modularity and high-frequency measurement up to supra-harmonic ranges. Its product family strategy positions it well where advanced power electronics and high-sampling diagnostics are required.
- Powerside: focusing on grid-edge diagnostics and environmental-sensor integration, enabling multi-parameter monitoring that supports modern distribution automation and DER integration workstreams.
- Eaton, Hioki, OMICRON and several European manufacturers: competing across stationary meters, calibration/test equipment, and compliance verification toolsets, offering strong systems integration and long-term service warranties for permanent installations.
These vendors are not only competing on hardware; they are increasingly bundling analytics, remote diagnostics and managed services. The competitive moat is shifting toward software ecosystems that convert episodic measurements into continuous asset intelligence.
Market dynamics and growth drivers (data-driven)
The numerical trajectory is instructive for 2026 planning. Between 2020 and 2025 the market grew from roughly USD 216.9 Million to approximately USD 279.4 Million; in our baseline forecast the market modestly expands in 2026 and then accelerates through the early 2030s, reaching close to USD 399 Million by 2032. This path implies a steady mid-single-digit CAGR of 5.2% across the forecast window—sufficient to support both new entrants and incumbent product refresh cycles.
Primary growth drivers:
- Regulatory alignment and certification demand following the standards update.
- Higher adoption of continuous monitoring by utilities and large industrials to mitigate outage costs and comply with increasingly granular performance standards.
- Technology upgrades—higher sampling frequencies, supra-harmonic capability and easier commissioning—making advanced analyzers practical for a wider set of field teams.
- Services-based monetisation: analytics subscriptions, managed monitoring and predictive maintenance contracts that increase lifetime revenue per device.
Risks, disruptors and what to watch in 2026
- Standards interpretation risk: differing national interpretations of the new measurement standards can create friction for device certification and customer acceptance. Early alignment with test houses and calibration bodies reduces this risk.
- Commoditisation of basic features: low-cost instruments commoditise entry-level diagnostics, pushing vendors to compete on software, analytics and service offerings.
- Supply-chain constraints and component pricing volatility: these can extend lead times for new devices and affect margins in price-sensitive segments.
- New entrants and regional OEMs: niche players offering specialised capabilities (e.g., supra-harmonics, high-speed waveform capture) can disrupt incumbents in targeted verticals unless incumbents accelerate feature parity.
How to use this research in 90, 180 and 365 days
- 90 days: align procurement specifications to the revised standard; pilot one Class A measurement upgrade in a critical facility using the report’s RFP templates and field-test protocol.
- 180 days: deploy a cross-vendor pilot that compares portable vs. permanent monitoring strategies across a representative asset class and build a TCO model for scale deployment.
- 365 days: implement a vendor ecosystem strategy (product, analytics, managed services) informed by the scenario analysis and competitive benchmarking in the report.
Closing — an invitation
PW Consulting’s Power Quality Analyzer market study is built around actionable decision tools, rigorous forecasting and vendor-level insight. To preserve strategic advantage, this brief purposefully omits detailed subsegment tables and regional splits; those granular data and the complete set of benchmarking matrices are available in the full report and the accompanying Excel models.
For procurement teams, product leaders, and M&A strategists shaping their 2026 playbooks, the report provides a compact, implementable roadmap to convert the projected 5.2% CAGR and near-term standards-driven demand into market share and service revenue. Contact PW Consulting to access the full dataset, custom scenarios, and our hands-on implementation workshops tailored to your organization’s 2026 objectives.
For detailed analysis of this topic, please visit the official page: Power Quality Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dot Peen Marking Machines Market Set to Expand at a 6.5% CAGR Through 2032
By PW Consulting, 2026-06-29
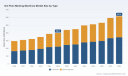
Dot Peen Marking Machines Market 2026 Strategic Brief — PW Consulting Releases Actionable Intelligence for Traceability Investments
Executive snapshot
PW Consulting’s new market research brief on Dot Peen Marking Machines positions operators, OEMs, and industrial investors to make high-confidence strategic decisions in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecasting horizon, the study shows a durable expansion trajectory: the global market has grown from the low‑hundreds of millions (USD) in 2020 to an estimated USD 398.5 million in 2025 and is projected to reach roughly USD 615 million by 2032, reflecting a compound annual growth rate of 6.5% over the forecast window. The structure and metrics in this brief are expressly designed to convert that topline momentum into executable plans for procurement, integration and service delivery.
Dot Peen Marking Machines Market
Why dot peen matters for 2026 decision-makers
-
Compliance is a primary driver. Permanent, low‑disturbance marking by dot peen is explicitly used to meet product identification and traceability requirements under regulatory frameworks such as the MDR for medical devices and U.S. FDA UDI rules. It also supports conformity to quality and sector standards including ISO 9001, ISO 13485, IATF 16949, AS9100 and other vertical mandates.
Dot Peen Marking Machines Market -
Durability underpins specification choices. Dot peen marks routinely pass abrasion and corrosion challenges used in qualification campaigns (for example, standardized salt spray and related tests), making the technology a go‑to where marks must survive harsh environments.
Dot Peen Marking Machines Market -
Cross‑industry demand is stable and broad. Automotive, aerospace, medical devices, heavy fabrication, and energy sectors continue to require deterministic traceability on metal components, and dot peen remains a preferred option where deep, permanent indenting is required.
-
Market structure informs supplier strategy. The sector shows a moderate level of concentration — the top three suppliers account for under half of market share and the top five slightly less than half — indicating a competitive marketplace with room for specialist suppliers and localized service players.
What the PW Consulting report delivers — practical, executable content
This research is purpose-built as a tactical toolset for procurement, product development, and corporate strategy teams. Highlights include:
-
Market sizing & forecasting with scenario modelling: baseline, accelerated adoption, and disruption cases that quantify exposure and upside under different adoption assumptions.
-
Granular segmentation frameworks by technology type, installation format, application, and region — fully traceable to our data sources. (Note: this press brief intentionally omits the detailed tabulations; subscribers can access the full split tables and interactive dashboards on the report page.)
-
Supply‑chain maps and channel economics: BOM sensitivity, critical components (actuators, controllers, stylus assemblies), lead‑time risk and single‑source exposures highlighted for risk mitigation.
-
Vendor scorecards and procurement playbooks: comparative capability matrices, service network evaluations, RFP templates, and a buyer’s checklist that maps capability to production use cases.
-
Operational playbooks for integration: MES/ERP interface patterns, inline marking best practices, quality verification loops, and automation checklists for mixed‑flow lines and high‑mix environments.
-
TCO & ROI models tailored to CAPEX/OPEX trade‑offs and use‑case classes (e.g., portable marking for maintenance vs. integrated marking for serial production).
-
Regulatory and qualification matrix: how dot peen supports MDR, UDI, ISO family standards and sector‑specific requirements such as API Q1 for oil & gas.
-
M&A and partnership playbook: acquisition targets, integration synergies and valuation heuristics for scale, IP, and service footprint expansion.
Competitive landscape — how incumbent and specialist vendors are positioning
The market is populated by a diverse mix of heritage manufacturers, industrial OEMs and regional specialists. Our competitive profiles focus on product differentiation, channel reach and service models rather than headline pricing. Notable vendors covered in the report include:
-
Pryor Marking Machines (Sheffield, UK) — boutique engineering heritage and focus on low‑stress permanent part marking; strong in applications where minimal material disturbance is essential.
-
MarkinBox (Tokyo) — offers both portable and line‑integrated systems and is positioned for high‑quality precision in demanding electronics and automotive environments.
-
Telesis Technologies (USA) — ruggedized product lines designed for heavy industrial production; strength in PINSTAMP and bench solutions for continuous operations.
-
Brady (formerly MECCO, USA) — depth in deep and rapid marking solutions; visible in trade shows and vendor ecosystems where heavy fabrication and speed dominate.
-
Pannier Corporation (USA) — emphasis on battery‑operated and portable systems for shop‑floor traceability and maintenance marking.
-
Kwik Mark Inc. (USA) — compact benchtop and heavy‑duty machines for tag, nameplate and shop‑floor requirements.
-
Automator (Italy) — long legacy in portable marking and line integration for European production lines.
-
SIC Marking and Gravotech (France) — broad portfolios that cover dot peen alongside laser and scribe technologies, enabling multi‑technology offers to traceability programs.
-
TechnoMark Inc. (USA) and CNMarking (China) — integration‑friendly solutions and cost‑competitive electric/pneumatic units that serve automotive and upstream manufacturing segments.
Recent trade show activity and product demos through 2025 illustrate active product cycles and channel engagement (for example, multiple exhibitors spotlighting pin‑marking and laser combinations in late 2025). Such activity signals opportunities for product refresh cycles and aftermarket services in 2026.
Strategic implications and recommended actions for 2026
-
Procurement alignment: Lock in supplier performance KPIs (mark depth, cycle time, stylus life, verification throughput) rather than raw unit price. Structure contracts with clear service levels and spare parts clauses to mitigate lead‑time volatility.
-
Compliance-first specification: If your product falls under MDR, UDI or sectoral standards (ISO/IATF/AS), specify marking solutions with documented qualification test results (abrasion, corrosion, legibility over lifecycle) and include mark verification tools in the acceptance criteria.
-
Integration pilots: Run two short pilots — one portable/maintenance use case and one integrated inline use case — to validate software interfaces, cycle influence and inspection gating before large capital commitments.
-
Service and retrofit strategy: Evaluate vendors for retrofit kits and software upgrades; aftermarket revenue and service footprint are strong indicators of sustainable vendor relationships.
-
Technology hedging: Where production handles mixed materials, consider hybrid marking strategies (dot peen for ferrous deep marks, laser for non‑ferrous finishes) and require vendors to demonstrate interoperability with verification systems.
-
M&A & partnerships: Seek targets that extend distribution in high‑growth regions or fill capability gaps (e.g., software for UDI data management, or electro‑mechanical IP for higher throughput).
How PW Consulting brings immediate value
Clients should expect quick, actionable returns from three offerings aligned to the priorities above: a vendor selection and RFP package (two‑week engagement), a pilot design and verification protocol (four‑week engagement), and a full commercial diligence package for M&A or strategic sourcing (six‑to‑eight week engagement). Each deliverable maps directly to the datasets and scenario models in our full report so organizations can move from insight to procurement or investment with minimal lag.
Next steps
This brief highlights the strategic contours of the market while preserving the granular datasets, regional and application splits, and vendor benchmarking that underpin procurement and investment decisions. For the full segmentation tables, company scorecards, downloadable ROI models and the complete scenario workbook, please consult the PW Consulting Dot Peen Marking Machines Market report page. Our analysts are available to walk through a condensed workshop that translates the report’s findings into a 90‑day action plan for your operations or sourcing teams.
For detailed analysis of this topic, please visit the official page: Dot Peen Marking Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ice Maker Market Valued at USD 5.78 Billion in 2025 — Healthcare Leads with USD 2.93B, Poised to Reach USD 7.47B by 2032 at 3.73% CAGR
By PW Consulting, 2026-06-29
Ice Maker Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
PW Consulting’s latest Ice Maker Market research—anchored on a 2025 base year with historical analysis from 2020–2025 and forecasts through 2032—arrives at a pivotal moment for manufacturers, distributors, equipment specifiers, and capital allocators. The market has shown steady expansion through the pandemic recovery and into 2025, and our modelling points to a continued compound annual growth rate (CAGR) of 3.73% across the 2026–2032 forecast window. Total industry revenue moved from approximately USD 4.8 billion in 2020 to roughly USD 5.8 billion in 2025 and is projected to approach USD 7.5 billion by 2032—growth that is meaningful, predictable, and actionable for 2026 planning cycles.
Ice Maker Market
Why this brief matters for 2026 decision-makers
The Ice Maker Market is simultaneously mature and unsettled: mature in that baseline demand across foodservice, healthcare, retail and residential remains resilient; unsettled because regulatory timelines, refrigerant transitions, materials cost pressure and an accelerating consumer preference for smart and speciality formats are reshaping product roadmaps and commercial models. For leaders planning capital allocation, product launches, channel expansion or M&A in 2026, the report provides the analytical scaffolding required to move decisively rather than defensively.
Ice Maker Market
- Regulatory inflection points have compressed timelines for compliance and product refresh—these are not distant risks but near-term operational constraints that affect inventory, sourcing contracts and certification pipelines.
- Raw-material and component cost volatility has altered cost-to-serve across commercial modular machines and consumer countertop units in different ways; procurement strategy is now as important as R&D prioritization.
- Fragmentation in supplier power and end-market concentration creates space for targeted consolidation, platform plays and value-added aftermarket services.
What the report contains — the practical toolkit
PW Consulting structured this study to be a practitioner’s reference for 2026 execution. The deliverables include:
Ice Maker Market
- Top-line market sizing (historical and forecast) with scenario sensitivity to energy regulation and refrigerant policy shifts.
- Segment-level heatmaps and growth drivers across product formats and end-use clusters (note: detailed segment tables are contained in the full report).
- Competitive landscaping with in-depth vendor profiles, product feature matrices, and innovation roadmaps—covering major commercial and consumer players.
- Supply-chain vulnerability assessment, including supplier concentration, raw-material exposure for copper, steel and plastics, and critical component sourcing (compressors, controls, heat-exchange systems).
- Go-to-market playbooks for OEMs, distributors and service networks, including channel economics, pricing levers and aftersales monetization strategies.
- Regulatory readiness checklists, certification timelines, and a priority matrix for retrofit vs. redesign decisions informed by model-level harvest capacity and local standard requirements.
- Interactive dashboards and financial models that allow users to stress-test forecast outcomes under alternative price, regulation, and demand scenarios.
We intentionally present a compact synopsis here. The full dataset, model workbooks and proprietary segmentation tables are accessible through the report portal and are essential for teams that require line-item planning detail.
Competition and positioning — a strategic read of core players
The Ice Maker Market is characterized by a mix of global incumbents, specialized commercial equipment manufacturers and agile consumer-tech entrants. Market concentration remains relatively low by industrial standards (CR3 approximately 24.6%, CR5 approximately 26.2%), indicating a fragmented supplier landscape with multiple opportunities for differentiation and consolidation.
- Hoshizaki America — A long-standing commercial equipment specialist emphasizing efficiency, durability and North American production capability. Their product set—crescent, cubelet, flake and specialty machines—remains a benchmark for foodservice and hospitality operators prioritizing uptime and serviceability. Strategically, Hoshizaki’s manufacturing footprint offers resilience against near-term tariff and logistics friction.
- True Manufacturing — Positioned on energy efficiency and robust, modular designs for foodservice. True’s emphasis on class-leading efficiency and smart controls aligns with buyers reacting to stricter energy standards and operators seeking lifecycle cost reductions.
- Naixer Refrigeration — A China-based OEM with undercounter and high-capacity cube models, notable for feature sets such as self-cleaning and air/water-cooled options. Naixer’s global certification focus and trade-show activity signal aggressive distribution expansion in hospitality and distributor channels.
- GE Appliances & Frigidaire — Iconic consumer brands focusing on countertop and residential nugget/compact formats. Product refreshes and new finish/colorways underscore a strategy to convert lifestyle demand into premium ASPs through design and brand positioning.
- Govee Technology — Represents the new wave of consumer-oriented, smart appliance entrants. Recent product introductions emphasize low-maintenance operation and IoT-enabled convenience, targeting consumers who prioritize connectivity and modern aesthetics.
Recent product and commercial moves—new smart nugget launches, expanded finish options, and aggressive trade-show participation—demonstrate concurrent investment in both consumer-facing innovation and traditional commercial distribution. For 2026, companies that can bridge robust mechanical engineering with digital service layers and regulatory compliance will gain a sustainable edge.
Regulatory and input-cost dynamics to prioritize in 2026
- U.S. energy and refrigerant policy: New DOE energy conservation standards for automatic commercial ice makers and tightened refrigerant restrictions materially impact allowable product specifications and the sell-through of existing inventory. Compliance windows are short, making program management and model certification near-term priorities.
- International standards: Other jurisdictions have adopted similarly stringent measures that affect global product homologation timelines. Exporters must integrate multi-jurisdiction certification planning into product launch calendars.
- Raw-material pressure: Rising copper, steel and plastics prices—plus compressor availability—are altering bill-of-material assumptions. Long-term contracts, strategic pre-purchases and supplier diversification are effective mitigants.
Actionable 2026 playbook — prioritized moves for leadership teams
From the vantage of 2026, PW Consulting recommends the following prioritized initiatives.
- Regulatory-first product triage. Immediately classify product families by compliance exposure and harvest-capacity thresholds; accelerate certification for models with near-term marketability and plan phased obsolescence for non-compliant SKUs.
- Sourcing and cost hedging. Renegotiate supplier contracts with embedded indexation clauses, secure multi-year compressor allocations, and evaluate nearshoring or localized production for high-volume commercial lines to reduce logistics risk.
- Service and aftermarket monetization. Convert installation and service into recurring revenue—extended warranties, consumable filters, remote diagnostics subscriptions and retrofit kits can offset margin compression from material costs.
- Product differentiation through efficiency and digital features. Given the market’s regulatory tilt toward efficiency and the consumer appetite for smart features, prioritize energy and water savings innovations alongside intuitive connectivity that supports OTA updates and predictive maintenance.
- M&A and partnership criteria. Target acquisition or alliance candidates that strengthen controls/software, compressor supply, certification capabilities or service footprints rather than only scale. Given the market’s fragmentation, bolt-on plays can accelerate time-to-compliance and expand aftermarket economics.
- Channel and inventory optimization. Align distributor inventory policies to regulatory timelines and offer trade-in or buy-back schemes to accelerate replacement cycles and capture up-sell into compliant models.
How PW Consulting supports execution
Beyond the market brief, PW Consulting offers executive briefings, interactive dashboards and model customization workshops to translate these insights into 90–180 day roadmaps. Clients can request scenario runs that stress-test product portfolios against combinations of energy standards, refrigerant availability, commodity shocks and demand shifts by end-use cluster.
This research is designed as a strategic “trailer”: it demonstrates our rigorous methodology and the immediacy of market forces, while reserving model-level, region-by-region and end-use breakouts for the full report and client workstreams. That deeper layer contains the exact segmentation, SKU-level risk profiles and financial implications necessary for execution planning.
Next steps
For commercial teams, procurement heads, product leaders, and investors preparing budgets and product roadmaps for 2026, the time to act is now. Schedule a briefing with PW Consulting to access the full report, interactive models, and a tailored implications memo for your organization. Our team will walk through scenario outputs, certification timelines and the supplier actions required to secure production and market access throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Ice Maker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sliding Door Hardware Market Set to Reach USD 261.7 Million by 2032 at a 5.2% CAGR — North America Leads with USD 74.8M (2025)
By PW Consulting, 2026-06-29
Sliding Door Hardware Market 2026: Strategic Signals from PW Consulting’s Forward-Looking Study
Executive snapshot
As lead industry analyst at PW Consulting, I’m presenting a distillation of our latest Sliding Door Hardware Market research (base year 2025, historical 2020–2025, forecast 2026–2032). This market is no longer a niche fixture category; it is a growth vector for manufacturers, specifiers, and institutional buyers seeking durable, space-efficient, and standards-compliant architectural solutions. Our study shows the market expanding from roughly USD 145.3 Million in 2020 to USD 185.6 Million in 2025, with a projected run to approximately USD 261.7 Million by 2032. The central assumption driving that trajectory is a compound annual growth rate (CAGR) of 5.2% across the 2026–2032 forecast window.
Sliding Door Hardware Market
Why this matters for 2026 decision-makers
-
Momentum and optionality: The mid-single-digit CAGR indicates steady, investable growth rather than episodic spikes. For strategic planners, this translates into a choice architecture—prioritize incremental capacity and product-line enhancements now, rather than committing to large, lumpy investments that presume rapid market consolidation.
Sliding Door Hardware Market -
Fragmentation creates acquisition runway: The market concentration metrics in our report show a relatively fragmented competitive landscape (top-three players account for about one quarter of the market, and the top five cover slightly more). That combination of scaleable demand and fragmentation creates attractive windows for targeted M&A and bolt-on acquisitions—especially for regional or capability-driven plays.
Sliding Door Hardware Market -
Regulatory and materials volatility reshape product roadmaps: New standards and raw material dynamics are already influencing product specifications, quality testing, and supplier selection. Firms that synchronize product development, certification, and procurement strategies will reduce time-to-spec and increase win rates in mid-to-large commercial projects.
What the PW Consulting report delivers (practical, actionable content)
We designed the report to be a decision-useful tool for C-suite leaders, commercial directors, product managers, and strategic procurement teams. Highlights include:
-
Market modeling and scenarios: A calibrated baseline model (2020–2025) and three forward scenarios (conservative, base, upside) with transparent assumptions across construction activity, retrofit cycles, and component pricing.
-
Demand-logic segmentation: Proprietary demand drivers and use-case maps that link end-market dynamics (new residential builds, commercial fit-outs, renovation cycles) to SKU-level sensitivity—enabling SKU rationalization and go-to-market prioritization.
-
Cost and supplier stress-testing: Line-item sensitivity models for stainless steel, aluminum extrusion, and labor inputs that show margin impacts under varied price paths and lead-time disruptions.
-
Regulatory readiness playbook: Actionable steps to align with recent ANSI/BHMA revisions and ISO recertification expectations, including test-plan templates and suggested third-party labs for accelerated certification.
-
Competitive benchmarking: Comparative capability matrices for leading suppliers and emergent challengers—covering product breadth, vertical integration, geographic reach, and innovation posture—plus a prioritized list of potential partnership targets for distribution and OEM supply.
-
Commercialization accelerators: Channel and pricing playbooks for premiumization, retrofit-focused bundles, and specification-driven sales in healthcare and multi-family projects.
Competitive landscape: capability vs. opportunity
The competitive fabric of the sliding door hardware market mixes long-established European and Japanese engineering houses with regional manufacturers focused on cost and speed-to-market. Key profiles and strategic takeaways include:
-
Häfele (Germany) — Known for comprehensive systems spanning top-hung and bottom-rolling solutions. Their strength is integrated system design and distribution reach, which positions them well for spec-driven architectural projects. Strategic implication: incumbent advantage in premium segments, but exposure to slower retrofit cycles.
-
P.C. Henderson (UK) — Specializes in heavy-duty commercial and industrial systems. Their engineering focus makes them a preferred vendor for large-scale, performance-critical installations. Strategic implication: opportunity to leverage industrial relationships into façade and logistics markets.
-
Sugatsune (Japan) — Precision hardware and concealed soft-close systems aimed at high-end residential and furniture markets. Strategic implication: high-margin niches exist for premium, low-noise solutions—licensing or co-development can accelerate market entry for rivals.
-
KN Crowder & Pemko (USA) — North American players that emphasize compliance and purpose-built systems for pocket, barn, and healthcare applications. Recent product introductions and catalog updates highlight a focus on faster specification-to-install cycles. Strategic implication: differentiation via certification, lead-time, and service is decisive in institutional channels.
-
Koil India; SeaLink Hardware (Asia); RW Hardware; Klein — Represent cost-competitive and niche offerings, from high-capacity systems to closet-specific hardware. Strategic implication: these firms are natural partners for geographic expansion, contract manufacturing, and low-cost SKU production.
Recent vendor activity underscores these trends: updated catalogs that compress lead times, targeted product launches for lightweight/healthcare systems, and major trade-show reveals of safety and convenience enhancements. Collectively, these moves signal a market where product refresh cadence and supply agility will be decisive for 2026 wins.
Industry dynamics and disruptive inputs
-
Materials and cost pressures: Stainless steel content in hardware components rose materially year-over-year as demand for corrosion-resistant rollers and tracks increased in commercial projects. Aluminum extrusion pricing also saw an uptick tied to North American supply adjustments—both trends that can erode gross margins without compensating price or design changes.
-
Regulatory tightening: Updated ANSI/BHMA standards effective 2025 require enhanced soft‑close testing for multi-family and commercial applications. Meanwhile, ISO recertification requirements now include stricter vibration and durability testing for bi-fold and pocket systems. These are not compliance footnotes—they change product development timetables and testing budgets.
-
Urbanization and design trends: Space-saving sliding solutions continue to gain share in high-density housing markets. The shift toward integrated, concealed, and low-noise systems means manufacturers must invest in mechanics and finishes, not just in price-competitive rails.
Action framework for 2026 (six strategic moves)
-
Recalibrate SKU portfolios: Rationalize low-velocity SKUs, and reallocate R&D to soft-close, corrosion-resistant, and lightweight systems that align with codes and buyer willingness-to-pay.
-
Lock in supply flexibility: Negotiate index-linked contracts for stainless steel and aluminum or diversify to alternate alloys/components to blunt input price shocks.
-
Invest in certification as a route to premium: Prioritize third-party testing and documentation to shorten specification cycles for healthcare and multi-family tenders.
-
Pursue bolt-on M&A in target geographies: Leverage the market’s fragmentation to acquire distribution, tooling, or niche IP that accelerates time-to-market while spreading fixed costs.
-
Pilot outcome-based offers: Launch retrofit-as-a-service or lifetime-maintenance bundles in selected metro markets to capture recurring revenue and deepen client relationships.
-
Strengthen channel analytics: Use tender win/loss data and spec-aggregation to prioritize specifiers and contractors that deliver the highest conversion rates and lifetime value.
Next steps and how PW Consulting can help
Our report is intentionally structured as a “trailer”—it demonstrates the analytic depth and practical modules that inform boardroom decisions while reserving detailed segment-level datasets and interactive dashboards for the full deliverable. For teams planning 2026 capital allocation, product roadmaps, or M&A pipelines, the full study provides the granular inputs and scenario outputs needed to finalize investment decisions.
-
Request a tailored executive briefing to map the model outputs to your P&L and balance-sheet constraints.
-
Commission a rapid due‑diligence package on targeting acquisition candidates identified in our competitive matrix.
-
Engage our regulatory readiness team to convert ANSI/BHMA and ISO changes into an operational test-and-certification timeline.
Closing perspective
In sum, the sliding door hardware market presents a measured but attractive growth runway through 2032. The blend of reliable demand growth (our base case CAGR of 5.2%), a fragmented provider set, and accelerating regulatory and material shifts creates strategic levers for firms that prioritize certification, supply resilience, and selective M&A. PW Consulting’s full report translates these levers into executable roadmaps—if you are evaluating capital deployment or product repositioning for 2026, our study is designed to be the evidence base for the choices that follow.
For detailed analysis of this topic, please visit the official page: Sliding Door Hardware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Grain Combine Harvester Market to Rise from USD 165.0 Million in 2025 to USD 235.0 Million by 2032 at a 4.85% CAGR — Track Type Leads with USD 119.96M
By PW Consulting, 2026-06-29
Grain Combine Harvester Market — Strategic Brief for 2026 Decision Makers
PW Consulting’s latest Grain Combine Harvester Market report (base year 2025) delivers a pragmatic, scenario-based roadmap for executives who must make capital, product, and go-to-market decisions in 2026. Anchored in five years of historical observation (2020–2025) and a forward-looking forecast through 2032, the study synthesizes demand drivers, competitive dynamics, technology adoption curves, and regulatory headwinds to translate market movement into boardroom action. Figures cited in this brief are expressed in USD Million unless otherwise noted.
Grain Combine Harvester Market
Market snapshot: size, growth, and what it means
The global combine harvester market expanded steadily during the 2020–2025 period, reaching a total market value of USD 165.0 Million in 2025. Our baseline forecast projects continued expansion through 2032, reaching a modeled USD 235.0 Million by 2032 with a compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window. These macro dynamics point to a structurally growing market, driven by productivity investment, technology upgrades, and selective fleet replacement cycles.
Grain Combine Harvester Market
For 2026 specifically, the market is positioned at an inflection where incremental automation, enhanced throughput designs, and aftermarket services will determine winners and losers. The numbers validate a market large enough to sustain differentiated offerings, yet concentrated enough that scale and channel presence remain decisive advantages.
Grain Combine Harvester Market
Key strategic imperatives for 2026
- Reframe capital allocation around lifecycle economics: With mid-single-digit CAGR ahead, capital deployment should prioritize solutions that compress total cost of ownership (TCO) for large operators—high-capacity platforms, telematics-enabled uptime guarantees, and retrofit kits that extract value from existing fleets.
- Prioritize automation and operator aids: OEMs that accelerate operator-assist capabilities and predictive automation will see faster adoption in constrained-harvest-window environments. Product roadmaps that layer automation onto proven mechanical platforms reduce adoption friction.
- Strengthen dealer and service networks: Given the market’s concentration and the value of uptime, a dense parts and service capability is a near-term revenue moat. Investment in parts logistics, technician training, and performance-based service contracts should be front-of-mind for 2026 planning.
- Design aftermarket-first business models: Consumables, wear parts, and software subscriptions will contribute disproportionate margin uplift versus new-unit sales. Positioning aftersales offerings behind telematics data and predictive maintenance will accelerate capture.
- Embed regulatory resilience into powertrain strategies: Emissions regulation is already shaping engine choices and SCR integration. Product teams must align powertrain roadmaps with near-term emission standards to avoid retrofit risk and market access friction.
- Use scenario planning for supply-chain risk: Raw-material cost swings and localized production constraints argue for multi-sourced components and finite-supplier contingency playbooks—move from ad hoc to contractual resilience in 2026.
Dynamics shaping near-term execution
The market is being reshaped by three converging dynamics. First, precision agriculture and data-driven operations are moving from optional to expected for fleet buyers—telemetry, yield mapping, and automation suites are procurement differentiators. Second, productivity demand pressures (shorter harvest windows and labor constraints) are favoring machines with higher throughput and operator-assist features. Third, regulatory and sustainability expectations are nudging OEMs to commit to advanced aftertreatment and fuel-efficiency improvements; manufacturer-adopted SCR solutions exemplify this shift.
Readers should note there is variance in near-term growth estimates across sources: some industry datasets cited a more conservative rise through 2026. PW Consulting’s forecast methodology reconciles these inputs with our proprietary demand model and supply-side intelligence, explaining the stronger medium-term CAGR we report. The takeaway for executives: interrogate underlying assumptions (scope, vehicle classes, and aftersales inclusion) before aligning strategy to any headline growth number.
Competitive landscape — strategic read on leading players
The market shows meaningful concentration among the top OEMs, with the top three firms accounting for a significant share of global supply and the top five capturing a dominant share of revenue value. This concentration amplifies the importance of distribution reach, product breadth, and brand trust as competitive levers.
- John Deere (Moline, Illinois, United States): John Deere’s X9 and S7 series combine platforms exemplify the incumbency advantage—high-capacity grain handling, integrated precision systems, and continuing investment in operator automation. Their recent 2026 series updates enhance harvest automation and predictive ground-speed control, reflecting a strategy to tighten performance windows and reduce operator variability.
- CLAAS (Harsewinkel, Germany): CLAAS pursues availability and operational uptime through modular platform design and serviceability. Its product portfolio emphasizes versatile headers and throughput-focused engineering—positioning CLAAS strongly in regions where continuous operations and machine uptime drive purchase decisions.
- New Holland (Amsterdam, Netherlands): New Holland’s CR and CX/CH/TC lines target high-capacity harvesting and grain quality preservation. Recent model-year enhancements (announced 2025) focused on header versatility, electronics, and operator ergonomics—indicative of a strategy that balances peak performance with ease-of-use.
- AGCO (Duluth, Georgia, United States): AGCO’s product approach—hybrid threshing solutions and durable designs—targets operators prioritizing robust field performance and lifespan economics. Partnerships with powertrain suppliers to meet emissions requirements illustrate a pragmatic, engineering-first play.
- Wuhan Wubota Machinery Co., Ltd. (Wuhan, China): As an export-focused, ISO-certified manufacturer, Wubota competes on accessible value and parts availability for staple crops. Its position highlights an opportunity set for cost-competitive players to serve crop-specific and regional requirements.
The tactical implication: incumbents will defend share through feature parity, scale-driven pricing, and service coverage. Challenger strategies that succeed will deploy razor-focused plays—crop-specific optimization, aftermarket subscription models, or regional manufacturing/assembly to undercut logistical cost.
What the PW Consulting report delivers (practical contents)
- Proprietary market-sizing model (2020–2032) with transparent assumptions and sensitivity levers.
- Scenario-based forecasts tied to mechanization, crop prices, and input-cost pathways—optimized for board-level decision framing.
- Competitive positioning matrices and feature-mapping across product families to inform product roadmap trade-offs.
- Go-to-market playbooks for OEMs, distributors, and aftermarket players including pricing strategy, channel segmentation, and KPIs for dealer performance.
- Supply-chain risk maps and contract templates for strategic parts procurement and second-source planning.
- M&A screening criteria and a prioritized list of target archetypes (technology, distribution, aftermarket) with financial thresholds and integration risks.
- Operational scorecards and implementation timelines to convert strategy into 12–24 month tactical plans.
- Appendices with interview transcripts, vendor benchmarking templates, and a library of commercial terms and warranty structures.
These materials are designed to be plug-and-play for corporate strategy teams: the report includes fully editable models and presentation-ready slides so leaders can accelerate decision cycles in 2026.
How to use this brief in your 2026 playbook
- CEOs: Use the market sizing and concentration analysis to set resource allocation between new units and aftermarket expansion; stress-test the balance sheet for targeted acquisitions.
- CFOs: Recast investment appraisal templates to include subscription revenue and uptime-linked warranties; run sensitivity on commodity-driven replacement cycles.
- Head of Product: Prioritize features that materially shorten harvest windows and reduce operator demand; accelerate retrofit-compatible designs for quick-to-market differentiation.
- Head of Sales & Service: Reconfigure dealer targets and parts inventory buffers using our serviceability and parts-turn models to improve service-level economics.
- BD & M&A: Screen targets using our archetype framework—seek bolt-on aftermarket platforms, telematics specialists, or regional assembly options to de-risk logistics.
Conclusion — why this report matters for 2026
As OEMs and ancillary players balance growth and margin pressures, the PW Consulting Grain Combine Harvester report offers the analytical scaffolding to convert broad market trends into precise strategic moves. We provide the quantitative backbone (market sizing and CAGR), competitive diagnostic (concentration and capability benchmarking), and execution playbooks that translate 2026 uncertainty into prioritized actions. In keeping with the “trailer” principle, this brief presents the strategic conclusions you need to consider now while reserving the granular segmentation tables and downloadable models for the full report available on our website.
For access to the complete dataset, regional and application segmentations, editable financial models, and the full suite of appendices, visit our report page or contact PW Consulting’s grain-harvester practice lead. The full intelligence pack contains the disaggregated tables and deal-ready artifacts that empower rapid execution in 2026.
For detailed analysis of this topic, please visit the official page: Grain Combine Harvester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


