



Category: market research
PW Consulting: Global Automotive Cast Iron Cylinder Head Market Reaches USD 4,120.5 Million in 2025; Projected 1.92% CAGR from 2026–2032
By PW Consulting, 2026-08-18
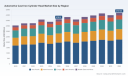
Worldwide Automotive Cast Iron Cylinder Head Market — Strategic Outlook for 2026 Decision-Makers
Executive Summary
PW Consulting’s new market study on the Worldwide Automotive Cast Iron Cylinder Head Market positions 2026 as a pivotal year for OEMs, tier suppliers, foundries and private equity investors evaluating powertrain portfolios. Anchored on a robust historical time series (2020–2025) and a detailed forecast through 2032, the report delivers a clear topline: the global market, measured in USD, recorded steady recovery through 2025 and is projected to grow at a moderate compound annual growth rate (CAGR) of 1.92% over the 2026–2032 forecast window. Market concentration metrics indicate a mid-tier oligopolistic structure, with the top three and top five players controlling a meaningful share of the industry—underscoring both entry barriers and acquisition opportunities in 2026.
Worldwide Stainless Steel Retaining Ring Market
Why 2026 Is a Strategic Inflection Point
-
Transitional demand patterns: After a period of volatility and gradual structural decline in certain light-vehicle segments, demand in heavy-duty and commercial applications remains resilient. Suppliers that calibrate 2026 capacity and product roadmaps to this bifurcation will capture the most stable margins.
Dermal Drug Delivery System Market -
Regulatory acceleration: Stricter global emissions and fuel-economy regimes continue to shape material choice and head design. Compliance-driven redesigns create short windows for contract wins and technology migration in OEM programs.
Women Business Loan Services Market -
Material innovation adoption: Compacted Graphite Iron (CGI) and other advanced variants are now migrating from proof-of-concept into scaled programs. Choosing when and where to introduce CGI (versus traditional gray or ductile iron) will materially affect cost, weight and NVH trade-offs.
Market Dynamics — What the Data Tells Us
Our longitudinal analysis (2020–2025) shows the industry moving through a recovery phase into a period of modest growth. Using 2025 as the base year, the market demonstrates a stable foundation from which the projected 1.92% CAGR emerges—reflecting balanced upward pressure from diesel and commercial vehicle demand and downward pressure from electrification and aluminum substitution in some passenger vehicle segments.
Key structural drivers examined in the report include raw material cycles, foundry emissions regulation (including the applicability of standards such as NESHAP for iron and steel foundries), and the competitive response to OEM lightweighting mandates. Thermal management and vibration damping properties of gray cast iron continue to underpin its preference in heavy applications, while CGI’s mechanical advantages make it the material of choice where weight-to-strength ratios are prioritized without full migration to aluminum.
Competitive Landscape — Leaders, Challengers and Strategic Moves
The market’s competitive map presented in the report synthesizes company-level strategy, manufacturing footprint, capability stack and customer exposure. Leading suppliers we profile include global and regional specialists whose strategic choices in 2024–2025 set the tone for 2026 negotiations:
-
Tupy (Joinville, Brazil) — A recognized global leader in cast-iron and CGI cylinder heads for heavy-duty and commercial OEM programs. Tupy’s scale and CGI know-how make it a natural partner for high-output diesel programs.
-
Eisenwerk Brühl GmbH (Brühl, Germany) — A century-plus of series production experience in gray cast iron for passenger car applications positions Eisenwerk Brühl to serve high-precision European OEM needs.
-
Teksid (Carmagnola, Italy) — With expertise spanning aluminum and iron heads and affiliation to a major OEM group, Teksid remains strategically positioned where OEMs seek integrated casting-to-assembly relationships.
-
Linamar / Montupet (Ontario, Canada) — Offers casting and machining breadth, including cast iron variants; competitive on integrated machining and low-variance supply for North American programs.
-
Nemak (Monterrey, Mexico) — Recent portfolio expansion into additional commercial vehicle cast iron heads underscores Nemak’s intent to consolidate supply positions across powertrain platforms.
-
Toyota Industries Corporation & Yamaha Motor Co., Ltd. (Japan) — Both bring high-volume OEM integration, regional capacity expansions and engineering depth, particularly across Asia.
-
Specialized foundries (Tafalla Iron Foundry, Cerdic Foundries, Silbitz Group, Impro Precision) — These players remain critical for bespoke programs, small-to-medium series and high-precision castings for industrial engines and niche automotive programs.
Recent notable industry actions—such as Summit Racing’s mid-2025 product launch leveraging enhanced casting techniques, Aisin Seiki’s contract awards, Nemak’s portfolio expansion and Toyota Industries’ capacity increases—are analyzed for strategic implications and near-term supply-chain ripple effects in 2026.
What the Report Contains — Operationally Actionable Modules
PW Consulting’s report is deliberately practical for 2026 decision-making. Key deliverables include:
-
Topline market model and scenario-based forecasts (2026–2032) with sensitivity testing around raw material volatility and regional demand shifts.
-
Company-by-company profiling with capability matrices, customer exposure mapping and a strategic heatmap identifying likely winners and acquisition targets.
-
Supply chain exposure analysis showing critical nodes in casting, machining and assembly, and an emissions-compliance readiness index for foundries.
-
Cost-to-serve and break-even modeling for material choices (gray iron vs. CGI vs. alternatives) under different duty cycles and volume tiers.
-
Regulatory impact toolkit: a decision-playbook that translates emissions and workplace regulation into CAPEX and OPEX estimations for foundries.
-
M&A and partnership playbook: prioritized target lists, valuation benchmarks and integration risk checklists tailored to 2026 market conditions.
-
Commercial negotiation levers and sample RFP language for OEMs and tier suppliers procuring cylinder heads and assemblies.
Strategic Recommendations for 2026
-
Prioritize heavy- and commercial-vehicle interfaces: Suppliers should protect and expand presence in segments where cast iron retains technical superiority. OEMs should lock long-cycle sourcing agreements in these segments to blunt spot-price and capacity risk.
-
Adopt a phased CGI pathway: For programs requiring weight reduction with minimal redesign, adopt CGI in a phased manner—beginning with high-stress applications—while preserving gray iron capabilities for cost-sensitive lines.
-
Invest in compliance-led CAPEX early: Foundries exposed to stringent emissions regimes should accelerate abatement investments to avoid sudden shutdowns or contractual penalties; our regulatory impact scenarios quantify the trade-offs across CAPEX timelines.
-
Use 2026 as consolidation window: The market concentration profile indicates room for bolt-on M&A. Strategic buyers with machining and logistics synergies can secure rapid margin accretion by acquiring complementary foundries or component specialists.
-
Build flexible contract clauses: OEM procurement teams should negotiate flexibility clauses tied to raw material indices and emissions compliance costs to share downside and avoid supply shocks.
Provenance, Methodology and What We Intentionally Withhold
The study synthesizes primary interviews with OEM program managers, senior executives at foundries, trade association data and detailed desk research. Our topline figures—anchored on 2025 as the base year and extrapolated through 2032 using a 1.92% CAGR—reflect demand-side trajectories and supply-side capacity constraints.
In keeping with the report’s role as both an evidence-based strategic instrument and a commercial product, we deliberately withhold granular segmentation tables (region-by-region splits, application-specific revenue lines and certain unit price curves) from this public release. These high-resolution data points, along with downloadable financial models and editable scenario workbooks, are available within the full report package.
How to Use This Analysis in Boardroom Decisions
-
Board-level planning: Use our scenario outputs to stress-test capital allocation for foundry upgrades, CGI adoption and potential acquisitions.
-
Commercial negotiation: Configure contract terms and hedging strategies using our supplier concentration and cost-to-serve analyses to protect margins over multi-year OEM programs.
-
R&D and product roadmap: Align material selection timelines with regulatory milestones highlighted in the report, accelerating CGI or hybrid material programs where ROI is compelling.
Next Steps & Access
For licensing the full Worldwide Automotive Cast Iron Cylinder Head Market report—containing the proprietary regional and application-level datasets, the detailed company models and the scenario workbooks tailored for 2026 strategic planning—visit the PW Consulting report page. The comprehensive dataset and editable financial models are designed for immediate integration into 2026 budgeting, procurement planning and M&A diligence.
PW Consulting’s industry team remains available for bespoke briefings, board workshops and 1:1 advisory sessions to translate these insights into executable 90- to 180-day plans for suppliers and OEMs.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Cast Iron Cylinder Head Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Oudh Extract Market Poised to Reach USD 413.11 Million by 2032, Growing at a 5.42% CAGR
By PW Consulting, 2026-08-18
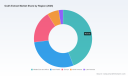
Worldwide Oudh Extract Market — Strategic Preview: What CEOs and Category Heads Must Know for 2026
Executive snapshot
PW Consulting’s forthcoming Worldwide Oudh Extract Market report (base year 2025, forecast 2026–2032) consolidates independent primary research, trade-level intelligence, and scenario modelling into a single operational playbook for leadership teams. The market for Oudh extract has exhibited steady expansion over the last half-decade — rising from roughly USD 218 million in 2020 to an estimated USD 285.5 million in 2025 — and is projected to continue growing at a compound annual growth rate of 5.42% through 2032, reaching an anticipated USD 413.1 million. With market concentration modest (CR3 ≈ 22.6%), the sector combines specialist manufacturing traditions with emerging plantation-scale supply, creating both opportunity and structural complexity for buyers, brand owners, and investors.
Slime Pump Market
Why this report matters for 2026 decision cycles
-
Actionable timing: procurement cycles and innovation roadmaps that begin in 2026 will be executed into the late-2020s environment mapped in our forecasts. Knowing where supply tightening, premiumization, and regulatory friction are likely to intersect is now a strategic imperative.
Worldwide Porcine Heparin Market -
Risk-adjusted sourcing: as cultivated supply and artificial inoculation techniques scale, the risk profile of raw material sourcing shifts from scarcity-premium to quality-differentiation. Our analysis translates those dynamics into procurement levers and contract structures.
Worldwide Electronic Bookkeeping Service Market -
Portfolio prioritization: fragrance houses, personal care brands, and ingredient distributors must align product designs and margin targets with a market that rewards provenance, traceability, and documented sustainability at a premium.
What’s in the report: operational, not academic
This is a hands-on report designed for teams that must act. Among the components:
-
Market sizing and demand archaeology — historical 2020–2025 movement and a granular forecast to 2032 under three adoption and price scenarios. (We present topline market values and scenario outputs while reserving core subsegment tables for report access.)
-
Supply chain map — from seedling and plantation protocols to resin induction techniques, distillation pathways (steam and solvent extraction), and post-extraction quality control. Where single-origin claims matter, we show the documentary trail required for compliance and premium pricing.
-
Procurement playbook — supplier selection scorecards, contract clauses addressing volume, quality variability, and force majeure in biological commodities, and hedging approaches for price and availability volatility.
-
Regulatory and sustainability toolkit — practical checklists for CITES compliance, national export permit processes, and audit-ready traceability templates that institutional buyers can deploy within 90 days.
-
Innovation & go-to-market playbooks — product concepts, sensory positioning, and pricing band guidance for luxury and mass-premium segments, as well as recommended trial flows for R&D and co-development partnerships.
-
Competitive intelligence and M&A signal matrix — benchmarking of incumbent players, capability gaps by node (plantation, distillation, distribution), and a prioritized list of acquisition or partnership archetypes aligned to three corporate strategies: (1) vertical integration, (2) brand-extension, and (3) ingredient specialization.
Key strategic takeaways for 2026
-
Provenance premiums will become table stakes. Buyers that cannot demonstrate cultivated, documented origin — with third-party certification where relevant — will face increasing pushback from high-end customers and regulators.
-
Scale alone is not a substitute for quality differentiation. Several producers combine plantation-scale supply with artisanal extraction techniques; the winners will be those that can operationalize both scale and sensory consistency.
-
Compliance is a value driver, not just a checkbox. CITES controls and national export regimes are shaping which sources can be scaled for international markets; integrating compliance into commercial proposals unlocks access to premium channels and reduces counterparty risk.
-
Supply diversification is an essential hedge. Given biological variability in resin formation, procurers should blend multi-origin sourcing, long-term offtake, and structured R&D partnerships that accelerate plantation inoculation efficacy.
-
Company consolidation opportunities exist. With a market concentration that leaves room for regional champions and niche specialists, 2026–2028 is a window to acquire complementary capabilities — particularly distillation technology, traceability platforms, and established export channels.
Competitive landscape — the players to watch
Our primary intelligence profiles several leading producers and integrators that illustrate the range of successful operating models:
-
Hoang Giang Agarwood Ltd. (HAGA Oud) — a vertically integrated Vietnamese player controlling planting, resin stimulation, hand-cleaning and distillation. Their approach demonstrates how plantation-level control supports consistent output and export readiness for fragrance markets.
-
D.D. Oud Oil — a Thai operator with large organic plantations and traditional distillation practices; notable for combining scale plantings with product variants that preserve heritage sensory profiles.
-
Biolandes — a European supplier that emphasizes CITES-compliant sourcing from cultivated Aquilaria in Laos, serving fine perfumery clients focused on sustainability and documented provenance.
-
Ajmal Perfumes — a Middle East incumbent with substantial upstream investments and extensive experience integrating plantation output into fragrance and attar production at scale.
These profiles are augmented with recent market actions — trade-show participations and shifts in regulatory quotas — that signal how companies are investing in channel access and regulatory engagement ahead of the 2026 buying cycle.
Regulation, trade policy and the new compliance frontier
Regulatory shifts in 2024–2025 have immediate commercial implications for 2026 strategies. Notable developments include adjustments to export quotas in certain producer countries and clarified personal exemptions in customs guidance. Meanwhile, CITES status for key Aquilaria species continues to govern cross-border flows, reinforcing the need for robust documentation and registered plantation origin claims. Our report synthesizes these inputs into a practical risk matrix that links regulatory exposure to specific commercial actions — from revised contract warranties to revised inventory buffers.
Supply and raw material dynamics
Oudh extract is inherently biological: only a subset of trees produces commercially viable resin without intervention, which is driving techniques like artificial inoculation and plantation cultivation. The short-term effect is a bifurcated market where artisanal wild-sourced material commands scarcity premiums while cultivated-sourced material scales in volume and lowers unit cost pressure over time. For procurement teams this creates a decision tree: secure limited wild-sourced lots for ultra-premium SKUs and develop long-term cultivation partnerships for mainstream portfolios.
How to use this report in 90/180/365 day plans
-
90 days — operationalize supplier audits and deploy our traceability templates to remediate non-compliant vendors. Begin sensory revalidation for critical SKUs using our recommended panel protocols.
-
180 days — finalize strategic offtake agreements with staged price and quality milestones; start R&D pilots to optimize inoculation and distillation parameters in partnership with chosen suppliers.
-
365 days — execute one bolt-on acquisition or strategic JV guided by the M&A signal matrix, and launch a provenance-marked product line supported by the marketing playbook included in the report.
Methodology and data integrity
The report is grounded in mixed-method research: supplier interviews across producing countries, buyer and brand surveys, on-site plantation assessments, import/export disclosure reconciliation, and price discovery across wholesale channels. We triangulate public regulatory records with confidential commercial intelligence and validate model outputs against historical trade movements (2020–2025) and market signals. Where we present topline market values and growth rates, those figures are conservative — modeled to support prudent commercial decision-making rather than aggressive upside scenarios.
Next steps and how to access the full intelligence
This piece is designed as a strategic preview. If your decisions in 2026 will touch procurement, brand innovation, M&A or regulatory compliance in Oudh extract, PW Consulting’s full Worldwide Oudh Extract Market report contains the proprietary segment-level data, supplier scorecards, contract templates, and trade-by-trade annexes necessary to act. We intentionally withhold core subsegment tables from this preview to preserve the operational value of the primary research and to direct readers to the full report portal where downloadable tools and bespoke advisory slots are available.
To request the full report, executive briefing, or a customized workshop for your leadership team, visit our report page or contact PW Consulting’s Strategic Commodities Desk. Market windows are open now — companies that combine provenance, compliance and scalable quality will define winners across the next procurement cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Oudh Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Static Hydraulic Transmission Device Market Forecast to Reach USD 8.81 Billion by 2032, Growing at a 4.4% CAGR
By PW Consulting, 2026-08-18
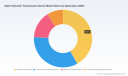
Worldwide Static Hydraulic Transmission Device Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
PW Consulting’s latest market study on the Worldwide Static Hydraulic Transmission Device market positions decision-makers to act with clarity in 2026. Our base-year market sizing (2025) places global revenues at USD 6,517.68 Million, and our forward-looking model projects growth to USD 8,810.41 Million by 2032, implying a compound annual growth rate (CAGR) of 4.4% across the 2026–2032 forecast window. These headline figures reflect steady, equipment-driven demand amid incremental efficiency gains, electro-hydrostatic integration, and modernization across construction, agriculture, and material-handling segments.
Ball Tow Hook System Market
Why this matters for 2026 corporate strategy
- From incremental to structural decisions: The market’s mid-single-digit CAGR creates a strategic choice: pursue steady organic optimization or reposition for differentiated capture via product-platform investments and M&A. 2026 is the inflection year for translating engineering advantages into commercial scale.
- CapEx and R&D prioritization: Investments in electro-hydrostatic modules, low-loss pumps and motors, and integrated control electronics will disproportionately affect long-term competitiveness. Companies that reallocate R&D budgets to system-level efficiency and low-emission drivetrains will widen performance and cost leadership gaps.
- Aftermarket and services as margin levers: With hardware commoditization pressure in some segments, aftersales, predictive maintenance, and retrofit solutions provide higher-margin, recurring-revenue opportunities that can offset product-price compression.
- Supply-chain resilience is not optional: Hydraulic fluids, precision components, and high-pressure sealing materials are concentrated risk points. Our sector analysis flags hydraulic fluid demand approaching ~1.84 billion liters in 2026, with mineral oils still dominant — a reminder to incorporate raw-material scenarios into sourcing strategy.
Market dynamics and near-term drivers
The market’s growth is being shaped by three durable vectors. First, equipment modernization in construction and agriculture continues to be a primary demand engine, driven by requirements for higher power density and precise control. Second, regulatory and performance pressures are accelerating efficiency optimizations and prompting hybrid electro-hydrostatic solutions that preserve hydraulic advantages while reducing fuel use and emissions. Third, component and fluid supply chains are tightening attention to cost and continuity — from pumps and motors to filtration and fluids.
Worldwide School Playground Equipment Market
PW Consulting’s research highlights that these forces are uneven across use cases and product types. Some product families are entering periods of incremental performance improvements, while others are ripe for disruptive system-level redesign. The report therefore models multiple scenarios — baseline, accelerated electrification, and supply-constrained — so executives can stress-test capital allocation and partnership timelines under realistic contingencies.
Worldwide Subscription Billing Software Market
Competitive landscape: how to read the vendor field
The global vendor landscape displays moderate concentration: the three-largest suppliers capture a meaningful share of the market, with the top five approaching a clear majority. This creates a two-tier dynamic — incumbent global-platform suppliers and a diverse set of focused specialists — and yields distinct strategic options for each type of player.
- Danfoss Power Solutions (Denmark) : Broad hydrostatic product range and closed-circuit transmissions for mobile and industrial applications. Danfoss’s strength is platform breadth and system integration capability for high-power mobile uses.
- Parker Hannifin Corporation (USA) : Known for integrated hydrostatic transmissions and Torqmotors; strong reputation for reliability across industrial and mobile machinery. Parker’s advantage lies in system engineering and diversified industrial relationships.
- Eaton Corporation (Ireland) : Designs both components and complete hydraulic systems for propulsion and work functions. Eaton tends to focus on system-level engineering and aftermarket services.
- Bosch Rexroth (Germany) : Specialist in axial piston pumps and motors for open/closed circuits; strong position in heavy machinery where durability and high-pressure performance matter.
- Hydro-Gear (USA) : Niche player focused on hydrostatic drives and transaxles for mowers and outdoor equipment. Strength is product specialization for small-vehicle markets.
- Linde Hydraulics (Germany) : Produces high-pressure transmissions and components for mobile working machinery, with a reputation for robustness in demanding field applications.
- Kawasaki Heavy Industries (Japan) : Offers high-efficiency pumps and motors with emphasis on low noise and reliability; a strong partner for OEMs in industrial vehicle segments.
- Dana Incorporated (USA) : Known for hydrostatic drivelines and decades of drivetrain expertise; well-positioned in telehandlers and off-highway equipment.
- Tuff Torq Corporation (USA) : Concentrates on compact hydrostatic transmissions for mowers and small equipment, prioritizing smooth handling and durability.
- John Deere (USA) and Komatsu (Japan) : OEMs that both source and integrate hydrostatic systems; they exert product-direction influence and present strategic partnership or in-sourcing pressure for component vendors.
- Poclain Hydraulics (France) : Focus on articulated loaders and compact tracked machinery with emphasis on traction and maneuverability.
- Hengli Hydraulic (China) : Large-scale producer with global manufacturing reach and competitive cost base; relevant for supply and price-pressure dynamics.
For executives, the key takeaway from the competitive map is this: incumbents compete through platform depth and global service coverage, while smaller specialists capture margin via focused product performance and application-specific integration. Any market-entry or defense plan must assess which axis — breadth, cost, or specialization — is the firm’s sustainable differentiator.
Recent signals to watch in 2026
- Trade-show and product previews (CONEXPO-CON/AGG 2026 and related events) indicate renewed OEM interest in fluid-power control systems and transmission flushing/control technologies.
- New product introductions in telehandlers and compact tractors highlight demand for higher top-speed hydrostatic transmissions and eco-focused powertrains.
- Industry-level emphasis on electro-hydrostatic integration is increasingly explicit in product roadmaps, consistent with regulatory and operational performance pressures.
What PW Consulting’s report includes (practical content for executives)
Our full study is designed as an executable intelligence package for C-suite and business unit leaders. It includes:
- Market-sizing and trend model (historical 2020–2025; forecast 2026–2032) with scenario sensitivity to raw-material pricing, supply-chain disruptions, and accelerated electrification.
- Competitive benchmarking across product families, capability matrices for pumps, motors, and integrated hydrostatic transmissions, and strategic profiles of established and emerging players.
- Go-to-market playbooks for products and services, including channel strategies, aftermarket monetization frameworks, and pricing levers tied to component cost models.
- Supply-chain stress tests and sourcing strategies for fluids, seals, and precision machining; includes recommended hedging and supplier-partnership constructs.
- M&A and partnership decision frameworks: valuation triggers, capability gaps to target, integration risk checklists, and illustrative deal-sourcing scorecards.
- Regulatory and technology-impact analysis focused on efficiency standards, emissions-related operational norms, and the implications of electro-hydrostatic electrification on component roadmaps.
- Downloadable datasets, interactive dashboards, and executive-ready slide sets to accelerate board-level and investor communications.
Note: In keeping with our “trailer” approach, this preview intentionally omits detailed regional and application-level breakdowns. The full dataset and drill-down matrices — the decision-useful pieces that operationalize strategy — are available on the report landing page and via direct engagement with PW Consulting.
Actionable playbook for 2026 (five priorities)
- Rebalance R&D toward system-level efficiency: Prioritize projects that improve whole-system energy use (pump-motor-control triple) and enable easy retrofit into existing fleets.
- Scale aftermarket services now: Build remote-monitoring and predictive-maintenance pilots to convert field-data advantages into recurring revenues within 12–24 months.
- Secure strategic raw-material exposure: Establish long-term supply arrangements for hydraulic fluids and key components, and model at least two downside raw-material scenarios in capital planning.
- Partner selectively on electrification: Pursue co-development with power-electronics and motor firms rather than in-house retooling unless you already have core competencies in control electronics.
- Adopt a modular-product roadmap: Deliver configurable transmission modules that reduce SKU complexity, ease integration for OEMs, and simplify aftermarket servicing.
Final perspective
The static hydraulic transmission market in 2026 remains a dependable base for industrial growth, but its next chapter will be decided by strategic moves that transcend component-by-component competition. Companies that secure supply lines, convert aftermarket opportunities into stable revenue streams, and invest tactically in electro-hydrostatic and system-level efficiency will define winners over the 2026–2032 horizon.
PW Consulting’s full report provides the operational detail and proprietary scenario models that senior leaders need to convert the high-level opportunities above into executable plans. To access the complete segmentation, interactive data, and company-level scorecards that underpin our forecasts, visit the PW Consulting report page or contact your PW Consulting account director for a briefing and data license.
For detailed analysis of this topic, please visit the official page: Worldwide Static Hydraulic Transmission Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Worldwide 1,4‑Cyclohexanedimethanol Dibenzoate Market Poised to Expand at 4.65% CAGR During 2026–2032
By PW Consulting, 2026-08-18
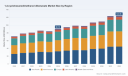
Worldwide 1,4-Cyclohexanedimethanol Dibenzoate Market — Strategic Preview for 2026 Decision-Makers
Executive synopsis
As global manufacturers and procurement teams prepare strategies for 2026, the 1,4-cyclohexanedimethanol dibenzoate (CHDM dibenzoate) market will present a mix of predictable growth, supplier concentration risk and episodic feedstock-driven volatility. Our new PW Consulting report uses a rigorous supply‑demand model and scenario planning to show why CHDM dibenzoate is transitioning from a niche specialty ester into a portfolio-level consideration for formulators across adhesives, coatings and polymer compounding. The total market, measured in USD Million, expanded from the low‑70s in 2020 to roughly 90 in our base year of 2025 and is forecast to approach the low‑120s by 2032 — a compound annual growth trajectory of approximately 4.65% over the forecast period. These headline numbers mask material differences at the application, geography and product‑form level; the full report provides controlled disclosure of those splits to support supplier selection, pricing strategy and M&A assessment.
Worldwide Nonprofit Payment Gateway Software Market
Why this market matters in 2026
- Substitution dynamics are accelerating. Regulatory pressure against legacy phthalate plasticizers in several jurisdictions is redirecting formulation choices toward benzoate esters such as CHDM dibenzoate. That regulatory momentum is creating procurement urgency for downstream users — especially those in consumer‑sensitive segments where compliance timelines are firm.
- Feedstock sensitivity raises operational risk. Benzoic acid — a principal feedstock — has shown marked price gyrations in recent years, including a pronounced spike in late 2022 that compressed producer margins. While recent months have seen regional easing, price normalization is uneven, and feedstock volatility should be treated as a core scenario in 2026 planning.
- Concentration amplifies supplier leverage. The market exhibits significant supplier concentration, with the top three and top five suppliers commanding the majority of capacity. This concentration changes the negotiating posture for large buyers and raises the importance of multi‑tier sourcing and contractual protections.
Market dynamics and near‑term outlook
Our forecast period runs from 2026 to 2032 and is underpinned by bottom‑up analysis of demand drivers, conversion capacity and recent price movements. The market’s steady mid‑single‑digit CAGR belies episodic supply pressure that can materially affect year‑over‑year pricing and availability. Two structural drivers merit special attention:
3D HMI Market
- Regulatory substitution. Restrictions on certain phthalates across major regulatory regimes are creating a durable substitution tailwind for benzoate esters. This is not instantaneous — conversion timelines, performance validation and supplier qualification extend over multiple quarters — but the direction is clear and creates a multi‑year runway for growth.
- Feedstock cycles and input pass‑through. Benzoic acid and other upstream inputs remain the primary source of margin volatility. The industry experienced a significant input price spike in late 2022, and although feedstock prices have softened in several regions since, procurement teams should prepare for asymmetric shocks driven by feedstock supply disruptions or energy cost shocks.
Supply concentration — a strategic risk
The CHDM dibenzoate market is not fragmented. A small number of established chemical producers and distributors control the lion’s share of commercial production and go‑to‑market channels. That concentration supports price discipline and allows integrated producers to manage capacity utilization and contractual allocations. For buyers, the result is that a single supply disruption or a coordinated commercial move (price adjustments, allocation policies) from a leading producer can have outsized effects on availability and commercial terms. Our report quantifies these concentration metrics and models stress scenarios to identify which buyer profiles are most exposed.
Worldwide Drillboats Market
Competitive landscape — what to watch
Key industry players combine global distribution reach with differentiated production footprints or specialized product forms. In examining principal suppliers and distributors we highlight strategic positioning, operational strengths and potential constraints:
- Eastman Chemical Company (Kingsport, Tennessee, USA) — A vertically integrated supplier with proprietary esterification know‑how and North American production. Eastman’s product positioning as a high‑performance benzoate plasticizer and its active commercial management (including periodic list price adjustments) make it a price‑and‑supply leader for many downstream accounts. Buyers evaluating long‑term contracts should weigh Eastman’s reliability and service footprint against its commercial pricing posture and account allocation practices.
- Trigon Chemie (Germany) — A specialist European supplier offering high‑purity solid polyol benzoate grades used in polymer processing and roll cleaner applications. Trigon’s strength lies in customization and technical support for extrusion and metallic coating processes; however, its scale is more regional, which has implications for global sourcing strategies.
- Parchem Fine & Specialty Chemicals (USA) — A global distributor model oriented toward formulation markets such as hot‑melt adhesives and packaging adhesives. Parchem’s value proposition is market access and inventory availability, useful for formulators seeking multi‑origin sourcing without large technical re‑qualification cycles.
- Unitex Chemical Corp. (USA) and Yueyang Scichemy Co., Ltd. (China) — Both present as regional manufacturers with emphasis on specialty applications and cost‑competitive product forms. They are important contenders for buyers focused on total delivered cost and for suppliers exploring alternative channel partnerships.
Recent commercial actions — including a regional price increase announced by a major producer in 2024 — are evidence that leading suppliers will use commercial levers to manage demand and margin. Our competitive analysis maps each player’s likely behavior in tightening and loosening markets and includes supplier scorecards for procurement negotiation planning.
What the PW Consulting report contains (practical, actionable modules)
- Market sizing and forecast model — A transparent, worksheet‑level model covering historic performance and demand drivers through 2032, with sensitivity toggles for regulatory acceleration, feedstock shocks and substitution rates.
- Supply chain heat map — Node‑level capacity, common logistics bottlenecks and a supplier concentration matrix that supports scenario stress‑testing and continuity planning.
- Feedstock economics module — Inputs, break‑even curves and pass‑through assumptions for benzoic acid volatility; this section presents practical hedging and contract clause options for procurement leaders.
- Commercial playbook — Negotiation levers, multi‑source contracting templates, and an M&A checklist for buyers evaluating strategic acquisitions or minority partnerships to secure feedstock or capacity.
- Regulatory and compliance appendix — Jurisdictional summaries, near‑term regulatory proposals (including historical and proposed significant‑activity notifications), and recommended product stewardship actions for manufacturers and importers.
- Use‑case dossiers — Technical briefs for major end‑use classes (adhesives, coatings, film/PVC applications) that translate material properties into specification checklists and qualification roadmaps.
How to use this intelligence in 2026 planning
- For procurement leaders: Convert market concentration and feedstock scenarios into prioritized dual‑sourcing plans and tiered contract language. The report’s supplier scorecards enable shortlisting strategic partners for long‑form supply agreements versus tactical spot purchases.
- For R&D/product managers: Use the use‑case dossiers to accelerate validation of benzoate‑based formulations and to build a phased substitution roadmap that mitigates performance and regulatory risk.
- For corporate development teams: Leverage the M&A checklist and valuation sensitivities to size bolt‑on or greenfield investments that improve margin capture or secure feedstock integration.
- For senior executives: Incorporate our scenario projections into three‑year capital allocation plans — especially where capacity additions or conversion projects are required to meet anticipated growth.
Risks, blind spots and recommended mitigations
Principal risks we model include sudden feedstock price spikes, capacity outages among concentrated suppliers, and faster‑than‑expected regulatory bans that accelerate substitution timelines. Recommended mitigations include: multi‑tier contracting with defined allocation mechanisms; strategic inventory buffers tied to validated quality acceptance; and targeted investments in downstream testing capacity to reduce conversion time for alternative plasticizers.
FAQ and regulatory note
- Is CHDM dibenzoate regulated? The product has been the subject of regulatory review in some jurisdictions historically, including proposed activity notifications. Manufacturers and importers should consult the regulatory appendix for jurisdiction‑specific guidance and timeline implications.
- Will feedstock prices return to pre‑2022 levels? We do not assume full normalization. Instead, our base case models mean reversion tempered by episodic volatility. Procurement should plan for both mid‑cycle dips and spike scenarios.
- Can small formulators access reliable supply? Yes — but the terms differ. Distributors and specialist regional producers can provide access with higher per‑unit costs; our commercial playbook quantifies breakpoints where direct supply or long‑term contracts become preferable.
Next steps
PW Consulting’s full report provides the complete dataset, granular segmentation, and downloadable models that underpin these conclusions. This release is intentionally a strategic preview: it exposes the macro levers and supplier dynamics you need to know for 2026, while reserving detailed segment allocations, region‑by‑region demand curves and unit‑price forecasts for the full report. For procurement teams, R&D leaders and corporate strategists, the report is designed to be immediately operational — from contract redlines through to acquisition screening.
To access the full report and the interactive forecast model, visit our webpage (link in the report distribution) for secure download and to schedule a brief strategy session with our CHDM dibenzoate practice team.
For detailed analysis of this topic, please visit the official page: Worldwide 1,4-cyclohexanedimethanol dibenzoate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Aloe Vera Derivatives Market to Reach USD 1,793.0 Million by 2032, Growing at a 7.85% CAGR — Asia‑Pacific Leads with USD 406.6M in 2025
By PW Consulting, 2026-08-18
Worldwide Aloe Vera Derivatives Market — 2026 Strategic Outlook for Decision-Makers
Executive summary
As companies plan their 2026 strategies, the aloe vera derivatives market presents a blend of predictable growth and emergent complexity. PW Consulting’s new Worldwide Aloe Vera Derivatives Market report synthesizes historical performance (2020–2025) with a robust forecast (2026–2032) and models the strategic choices that will determine winners and laggards over the next investment cycle. The global market reached approximately USD 1.06 billion in 2025 and, under the central scenario modelled in our study, is expected to expand at a compound annual growth rate (CAGR) of 7.85% through 2032 — approaching roughly USD 1.79 billion by the end of the forecast period. These headline dynamics matter, but the value for 2026 decision-making lies in the granular, actionable levers that translate growth into margin and resilience.
Tissue Slide Market
Why this report matters for 2026 planning
-
Market momentum with strategic inflection points: Growth is substantial but not uniform. The reported CAGR masks episodic volatility driven by raw-material supply shocks, regulatory clarifications, and shifting buyer preferences in cosmetics, food & beverage, and pharmaceutical channels. Our report isolates those inflection points and quantifies their P&L and sourcing impacts under alternate scenarios.
Worldwide Line Striper Market -
Practical deliverables, not just numbers: Senior leaders will find playbooks for procurement, quality control, and product differentiation that are ready for operational adoption in 2026. These include supplier scorecards, sample specification templates aligned to USP standards, and actionable workstreams for achieving or verifying organic or pharma-grade claims.
Worldwide Account Takeover Protection Market -
Decision support for capital allocation: Whether targeting capacity expansions, M&A, or vertical integration, the report maps where incremental investment is likely to generate the highest risk-adjusted returns across product types and channels.
Market trajectory and implications
The market’s expansion to roughly USD 1.06 billion in 2025 followed a steady recovery from pandemic-era disruptions and accelerated as consumer demand for natural actives and clean-label formulations intensified. Our forecast to 2032 incorporates technology adoption in extraction and drying, evolving regulatory requirements for food and pharmaceutical use, and consumer-driven premiumization in personal care. For 2026, the practical implication is clear: companies that secure consistent, verifiable input quality and lock in cost-efficient supply chains will convert market growth into outsized margin improvement. Conversely, firms exposed to single-supplier risk or weak QA systems face input-cost and recall risks that could erode earnings despite revenue growth.
Segmentation and go-to-market considerations (high level)
-
Product forms: Gel, powder, whole-leaf extracts and a range of specialty derivatives each serve distinct formulations and processing workflows. Choice of form affects shelf-life, transport costs, regulatory testing, and margin structure. Our report provides an operational view of which form factors are most suitable for specific downstream manufacturing footprints and packaging technologies.
-
End-markets: Cosmetics & personal care, food & beverages, and pharmaceuticals & healthcare are the primary application buckets. Each channel has different tolerances for variability, certification requirements, and traceability expectations. The report offers channel-specific sourcing and quality-control checklists tailored to those expectations.
-
Regional market dynamics: Geographic demand centers and supply clusters are mapped qualitatively to inform distribution strategies and logistics choices. For commercial negotiations and route-to-market design, the report provides scenario-based guidance rather than raw regional shares, preserving the competitive intelligence we captured in market models.
Competitive landscape — who matters and why
The industry remains characterized by a middle-weight concentration: the top three suppliers account for a meaningful portion of market output, and the top five extend that presence further, indicating moderate consolidation pressure but ample room for nimble entrants. Our competitive analysis combines company-level capability mapping, recent strategic moves, and supplier risk profiles to produce a transactional playbook for procurement and partnership.
-
Aloe Laboratories (Texas, USA) — A leading U.S. producer with a focus on organic gels, concentrates and powders. Their 2025 launch of a high-polysaccharide concentrate signals a move upmarket into nutraceutical-grade inputs; this product-level innovation alters the supplier bargaining dynamic for firms seeking differentiated active content.
-
Forever Living Products (Arizona, USA) — A vertically integrated, direct-sales player with proprietary plantation sourcing. Their recent USDA Organic recertification expands capacity for organic gel production and demonstrates how plantation control enables certification-driven product premiums.
-
Lily of the Desert (Utah, USA) — An established organic processor and active exhibitor in the natural products ecosystem; their trade-show presence highlights channel-focused product introductions for dietary and functional-food customers.
-
Aloecorp (Texas, USA) — A supplier with emphasis on high-purity polysaccharides and decolorized products suitable for pharmaceutical and premium cosmetic formulations. Their product positioning underscores the technical differentiation available through downstream purification.
-
Terry Laboratories (Texas, USA) — Specializes in spray-dried powders and concentrates; their recent capacity expansion was explicitly aimed at EU demand, illustrating how regulatory and market access factors are shaping capital deployment.
-
India-based exporters — Firms such as Aloevera Bio Organics and VedaOils exemplify how lower-cost origin suppliers are scaling to meet global cosmetic and beverage demand while pursuing international certification and traceability upgrades.
-
Vertically integrated growers — Players with in-house plantation-to-processing capabilities (e.g., Sanderson Farms’ Aloe Division) are able to capture margin across the value chain and to offer tighter supply assurance for strategic customers.
Notable recent developments (strategic read)
-
Capacity and certification moves by established players are reducing one dimension of supply risk but raising the bar for newcomers that lack comparable traceability or certification investments.
-
Product-level innovation — particularly high-polysaccharide concentrates and decolorized pharmaceutical grades — is creating pockets of premiumization that reward technical know-how and third-party validation.
Regulatory, supply and pricing dynamics to watch in 2026
-
Raw-material volatility: Aloe leaf prices experienced a notable uptick in 2025 due to supply disruption in key growing regions. Buyers should assume elevated price elasticity and stress-test contracts for force majeure and diversification clauses when negotiating for 2026 supply.
-
Food and supplement safety: The EU’s hygiene and food-safety requirements for ingredients used in supplements require documented microbial testing and controls. Procurement and quality teams must align supplier test panels and batch-release criteria to these regional standards to avoid market access delays.
-
Pharmaceutical standardization: The USP monograph for aloe leaf sets expectations for polysaccharide content and related quality attributes for pharmaceutical-grade inputs. For companies targeting nutraceutical or medicinal claims, supplier validation against pharmacopeial criteria is now table stakes.
-
Trade and labelling constraints: Tariff treatments and labelling obligations vary by origin and end-market — for example, certain HTS codes carry preferential treatments that influence sourcing economics, while jurisdiction-specific labelling requirements (including limits on aloin content) are shaping formulation and testing strategies.
How the report supports immediate action in 2026
PW Consulting framed this market study around executive decisions and operational actions. The report bundles:
-
Forward-looking supply risk maps and supplier heatmaps to prioritize dual-sourcing or nearshoring where it materially reduces business interruption risk.
-
Procurement negotiation playbooks with clause templates, price-indexing recommendations, and contract durations calibrated to the observed market cyclicality.
-
Quality and compliance checklists matched to cosmetics, food, and pharmaceutical end-market checkpoints — including microbial testing, aloin thresholds, and USP-aligned specification tables.
-
Commercial scenarios covering premiumization, cost pass-through, and private-label expansion — each with modeled P&L sensitivity and break-even timelines for capacity investments or M&A targets.
-
A competitive intelligence appendix with supplier capability matrices, recent strategic moves, and M&A/partnership windows where rolling up or collaborating makes strategic sense.
What we recommend to clients planning for 2026
-
Prioritize verification: For any product claiming organic, pharmaceutical-grade, or low-aloin status, insist on batch-level certificates and independent testing before onboarding new suppliers.
-
Mitigate raw-material shocks: Move to staggered, multi-origin sourcing for key inputs and include indexed-price mechanisms in multi-year contracts to manage margin volatility.
-
Invest selectively in differentiation: Technical upgrades (e.g., high-polysaccharide concentrates or decolorized gels) can unlock premium channels — but require commensurate marketing and compliance investments.
-
Align market access and labeling: Ensure formulations comply with regional labelling laws and aloin limits where applicable to avoid market withdrawals or reputational damage.
About the report and how to access the full intelligence
PW Consulting’s Worldwide Aloe Vera Derivatives Market report is built from primary supplier interviews, proprietary trade-flow modelling, and an integrated regulatory and price-insight engine. It covers the period 2020–2025 (historical) and provides a base-year of 2025 with a forecast to 2032. To preserve the competitive value of our proprietary segmentation and supplier models, this release intentionally summarizes strategic conclusions while omitting the detailed regional, type, and application-level tables. The full report contains the complete datasets, segmented forecasts, supplier scorecards, and transaction-ready appendices for procurement and product development teams.
For executives and teams preparing 2026 budgets and strategic plans, the full report provides the operational detail needed to turn market growth into sustainable, risk-adjusted returns. To request the complete study and access our bespoke consulting services for implementation support, please visit the PW Consulting reports page or contact your account lead.
For detailed analysis of this topic, please visit the official page: Worldwide Aloe Vera Derivatives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide HVAC Terminal Units Market Poised for 5.19% CAGR Through 2032
By PW Consulting, 2026-08-18
Worldwide HVAC Terminal Units Market — Strategic Imperatives for 2026
Executive trailer
PW Consulting’s latest market study on Worldwide HVAC Terminal Units synthesizes five years of historical performance (2020–2025) and delivers a comprehensive forecast through 2032. The global market, estimated at approximately USD 5.14 billion in our 2025 base year, is projected to grow at a compound annual growth rate (CAGR) of 5.19% and approach roughly USD 7.32 billion by 2032. This briefing outlines why those headline figures matter for senior executives, procurement leaders, product teams, and private equity sponsors making decisions in 2026 — and what practical levers they can pull now to shape outcomes in a market defined by technical regulation, raw‑material volatility, and fragmented competition.
Outboard and Inboard Engines Market
Why this report matters to 2026 decision-makers
- Capital allocation: Translate macro growth and scenario-driven demand into prioritized capital projects and product investments with modeled ROI horizons aligned to 2026–2028 procurement cycles.
- Product strategy: Reconcile regulatory milestones (efficiency testing updates, refrigerant transitions) with R&D roadmaps to avoid late-cycle redesigns and lost approvals.
- Supply‑chain resilience: Quantify the near‑term cost impact of metal inflation and simulate sourcing strategies that protect margins without forfeiting competitiveness.
- M&A and inorganic growth: Use market fragmentation and concentration metrics to identify attractive consolidation targets and value-accretive bolt‑on opportunities.
- Commercial go‑to‑market: Convert forecasted volume and retrofit waves into sales territory plans, channel incentives, and service packages that capture after‑sales recurring revenue.
Market dynamics shaping 2026 strategy
Three categories of forces are jointly steering the terminal units market: regulatory and standards changes, input cost inflation, and built-environment demand trends.
Electret Microphone Amplifier Market
- Regulation and standards — The industry’s technical baseline is shifting. Updated efficiency testing and regional performance rules (notably SEER2-related regimes) and ASHRAE guidance revisions are raising the bar for how terminal units are specified, tested and certified. Simultaneously, regulatory-driven refrigerant transitions (accelerating adoption of low‑GWP A2L refrigerants) are influencing system architectures and compatibility requirements for new installations and major retrofits.
- Input cost pressure — Recent, large moves in industrial metal indices and mill‑level producer prices (notably aluminum and steel) have introduced material cost swings that materially change BOM-level economics for fabricated terminal units. These shocks amplify the importance of procurement hedges, design-for-manufacture initiatives, and alternative material strategies.
- Demand-side transformation — Owners and design teams are tuning systems for energy efficiency, indoor air quality, acoustic performance, and flexibility. In commercial and institutional settings, this is accelerating adoption of variable air volume (VAV) solutions, fan‑powered options, and low‑energy active beams in select applications — creating windows for product differentiation and services-based monetization.
Competitive landscape — who is doing what now
The market remains fragmented, with the top three vendors accounting for a modest share of total revenue and the top five still well under one‑third of the market, creating fertile ground for both focused incumbents and ambitious challengers. Key players are executing different playbooks:
Worldwide LCD Panel Sealant Market
- Daikin Applied (part of Daikin Industries) is leveraging global scale and product breadth to push high‑performance single‑duct and fan‑powered terminal lines that emphasize energy efficiency and acoustic performance — positioning for major commercial projects where total cost of ownership (TCO) matters.
- Johnson Controls combines a wide portfolio of VAV and fan coil options with systems integration capabilities, giving it an advantage in large, integrated building projects and public‑sector procurement where interoperability and warranties are critical.
- ENVIRO‑TEC (a Johnson Controls brand) and similar niche specialists are exploiting quiet‑operation and precise airflow control as a differentiator for premium commercial and healthcare segments.
- Regional and product specialists such as Price Industries, Titus, Nailor and Carnes continue to capture specification wins through localized innovation, custom configurations, and relationships with MEP consultants and contractors.
- Solutions providers like Halton, Dadanco and Greenheck are pairing terminal products with system-level offerings (e.g., chilled beams, IAQ technologies) to create bundled value propositions in design‑spec markets.
Recent industry activity — trade show launches at the AHR Expo and the ASHRAE Handbook updates — underscore a near‑term window where product refreshes and testing compliance will determine specification momentum. For companies evaluating M&A, product extension, or channel expansion in 2026, the landscape rewards clarity of execution and speed to certify new variants under updated standards.
What’s inside the full PW Consulting report (practical deliverables)
- Market sizing and validated forecasts to 2032 with scenario analysis for high, base and downside cases aligned to raw‑material and regulatory shocks.
- Regulatory impact matrix mapping refrigerant phase‑ins, regional testing standards and ASHRAE revisions to product design and certification timelines.
- Supplier and cost‑build models (including sensitivity to metal price pathways) that enable margin preservation strategies and bid/no‑bid decisions.
- Product benchmarking and performance scorecards across acoustic, efficiency, footprint and lifecycle maintenance criteria.
- Go‑to‑market playbooks for new product launches, specification capture with architects/engineers, and post‑install service monetization.
- M&A heatmaps and valuation frameworks tailored to roll‑up scenarios in a fragmented market — plus diligence checklists and integration playbooks.
- Commercial retrofit opportunity maps identifying near‑term project pipelines by building archetype and procurement cadence.
We deliberately withhold detailed segment‑level tables in this release to preserve the report’s commercial value; the full dataset contains granular regional, product‑type and application splits that inform precise target selection and financial models.
Strategic recommendations for 2026 (actionable priorities)
- Hedge procurement and redesign BOMs: Lock long‑lead contracts for critical metals where feasible, and accelerate design‑for‑alternative‑materials programs to reduce exposure to aluminum/steel swings.
- Certify forward‑compatible products: Prioritize product testing and certification to reflect ASHRAE 130 updates and regional SEER2 protocols; ensure new units are compatible with A2L refrigerant architectures where system interfaces matter.
- Shift portfolio emphasis toward services: Convert product sales into recurring revenue through commissioning, remote monitoring, and performance‑based service contracts that improve TCO and customer stickiness.
- Target retrofit corridors: Focus commercial building retrofit campaigns where efficiency and indoor air quality regulations are driving replacement cycles; structure financing aids to shorten customer payback timelines.
- Explore bolt‑on M&A: Use the fragmented market to acquire complementary fabricators or controls specialists to achieve production scale and margin uplift; prioritize deals that fill product gaps or add channel access.
- Pursue acoustic and IAQ differentiation: Market winners in premium segments will combine low noise, fine airflow control and IAQ sensors — make these non‑negotiable in new development specifications.
- Operationalize rapid compliance: Create a cross‑functional certification sprint team (R&D, quality, regulatory affairs) to compress time‑to‑market under evolving standards.
How PW Consulting partners with clients
We support strategic outcomes with hands‑on execution: validation of forecasts through primary market checks, custom scenario financials, supplier negotiation playbooks, and M&A diligence support. For teams planning 2026 investments, our advisory engagements move from strategic intent to executable plans — including Excel‑based models, commercial trackers, and implementation roadmaps.
To access the full Worldwide HVAC Terminal Units Market report — including granular regional, product and application breakdowns, detailed company profiles, and downloadable modeling templates — contact PW Consulting or visit our report download page. The complete dataset and playbooks are indispensable for decision‑makers who need to convert headline growth into defensible market positions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide HVAC Terminal Units Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide E‑Government Market Set to Reach USD 56,776.67 Million by 2032, Growing at an 11.5% CAGR
By PW Consulting, 2026-08-18
Worldwide E-Government Market 2026: Strategic Signals from PW Consulting’s New Report
PW Consulting today releases its authoritative Worldwide E-Government Market report (base year 2025), delivering the intelligence that public sector leaders, system integrators, and technology vendors need to shape high-impact decisions in 2026. Built on a robust historical series (2020–2025) and a forward-looking forecast to 2032, the study quantifies the market trajectory (compound annual growth rate of 11.5%) and translates that macro momentum into pragmatic, risk-aware guidance for procurement, product investment, and partnership strategies.
Worldwide Oxidized PAN Fiber Market
Why this report matters for 2026 decision cycles
Governments and their technology partners are at an inflection point: accelerating citizen expectations, pervasive cloud adoption, and intensified regulatory scrutiny are converging with new production-grade AI and zero-trust security requirements. Our analysis shows that the global e-government market has more than doubled in scale over the past five years, moving from an aggregate of USD Million 15,200 in 2020 to USD Million 26,500 in 2025, and the model projects continued expansion through the forecast period to 2032. That macro growth (CAGR 11.5% across the forecast horizon) is not evenly distributed—creating asymmetric pockets of opportunity and risk that demand differentiated strategies.
Worldwide Activated Alumina Sorbent Market
For 2026 planning rounds, the report is designed to be decision-centric: it converts market-size dynamics into procurement timing, platform selection frameworks, go-to-market plays, and program-level ROI guards. Whether you are a procurement officer evaluating multi-year cloud contracts, an incumbent vendor defending enterprise accounts, or a venture investor sizing exits, the report converts high-level growth into executable options.
Heavy Duty Cable Protector Market
Key market signals we highlight (teaser)
- Persistent acceleration in digital public services. The recent upward trend in online service adoption has hardened into sustained demand for modular, mobile-first citizen interfaces and end-to-end digital transaction processing.
- Cloud-first accelerators and sovereign constraints. Cloud infrastructure continues its ascent as a central delivery model for e-government, while sovereign data and compliance regimes are shaping distinct sourcing choices for national and regional buyers.
- Security and AI as table stakes. Zero-trust mandates and production AI governance requirements are now procurement gating criteria rather than optional enhancements; this is reshaping supplier shortlists and delivery cadences.
- Consolidation and specialization co-exist. The market concentration metrics reveal a moderate level of concentration among leading providers, leaving room for specialized companies to capture meaningful niche share through verticalized solutions and local compliance expertise.
Report contents: what PW Consulting delivers (practical, not theoretical)
This study is structured to be immediately usable by practitioners. Key deliverables include:
- Topline market model (historical 2020–2025; base year 2025; forecast 2026–2032) with multiple demand scenarios driven by policy, technology, and economic variables.
- Procurement decision frameworks that map use cases to delivery models, security postures, and lifecycle cost drivers—enabling RFPs that close procurement gaps and reduce vendor lock-in risks.
- Vendor assessment matrices (capability, compliance readiness, delivery scale, partner ecosystem) and playbooks for public-sector sales cycles.
- Actionable due diligence templates for investors and M&A teams: integration risks, recurring revenue profiles, and customer concentration stress tests tailored to e-government buyers.
- Operational blueprints (implementation accelerators, API strategies, data governance checklists) that shorten delivery timelines and improve citizen adoption metrics.
To preserve competitive value for report subscribers, the release intentionally omits posting granular revenue breakdowns for every segmentation cell in this press summary. The full dataset—regional and application splits, detailed vendor revenue estimates, and downloadable scenario models—is accessible on our report page for licensed users and clients.
Competitive landscape: dynamics and strategic positioning
The e-government supplier ecosystem blends hyperscale cloud platforms, enterprise software vendors, specialist eGov providers, and global integrators. Our competitive review synthesizes corporate positioning, recent product moves, and forward-looking plays. Notable characteristics include:
- Hyperscaler-led platformization: Major cloud providers are embedding compliance and sovereign-cloud variants into their public sector offerings, creating platform advantages for partners that can harness native PaaS capabilities and pre-approved compliance artifacts.
- Enterprise software retooling: Large enterprise vendors are re-packaging CRM, ERP, and analytics suites specifically for public sector workflows—prioritizing case management, identity linkage, and data residency features.
- Vertically focused specialists: Companies that concentrate on permitting, civic engagement, or secure signatures are carving defensible niches through deep integration with government business processes and established client relationships.
- Systems integrators and consultancies: Delivery clarity—combining policy consulting, change management, and technical integration—remains a competitive differentiator as governments prioritize outcomes over point solutions.
Representative company insights (selection):
- Large cloud and enterprise players are leveraging global cloud platforms and sector-specific cloud variants to win backbone contracts and platform deals—focusing on scale, compliance, and partner ecosystems.
- Specialist vendors with productized modules for permitting, licensing, civic engagement, and digital signatures maintain advantages where localized workflows and integrations with legacy registries are decisive.
- Professional services and systems integrators are expanding outcome-based offerings that tie payments to measurable service-level improvements and citizen-experience KPIs—sharpening competitiveness against do-it-yourself procurement approaches.
Market concentration is meaningful but not insurmountable: the top three players account for a material share of overall market activity, with the top five representing a larger but still not overwhelming majority. This structure favors strategic partnerships and localized specialization—especially for vendors that can demonstrate compliance-ready architectures and measurable delivery velocity.
Regulatory and infrastructure forces shaping vendor and buyer choices
The operating environment is being reshaped by several regulatory and technical forces. Highlights that drive procurement and vendor strategy include:
- Regulatory transparency and platform accountability are rising—new laws and frameworks require intermediaries and service providers to embed transparency, risk management, and content governance into platforms that serve public-facing government services.
- National data localization and sovereign cloud expectations are prompting hybrid sourcing strategies: buyers increasingly require proven local handling for sensitive registers while using global platforms for elastic workloads.
- Cybersecurity mandates such as zero-trust initiatives set formal timelines for architectural shifts. Organizations without a credible zero-trust migration roadmap will face procurement disqualification in many jurisdictions.
- Cloud spending is becoming a dominant component of public sector ICT budgets; in many OECD contexts cloud now represents a large share of e-government infrastructure spend, changing procurement calculus from capex to predictable opex models.
Priority actions for 2026 — tailored recommendations
- For government IT leaders: institutionalize a multi-year cloud transition roadmap that aligns zero-trust milestones with sovereign-data controls and measurable citizen-outcome KPIs; include modular procurement vehicles to accelerate pilots into production.
- For vendors: differentiate by packaging compliance-ready stacks for specific workflows (e.g., licensing, tax, identity) and demonstrate rapid deployability with pre-built connectors to legacy registries.
- For system integrators: invest in repeatable implementation accelerators and outcome-based contracting skills; quantify uplift in service levels and cost-to-serve metrics for procurement win rates.
- For investors: prioritize companies with sticky, recurring-revenue models and defensible integration IP in regulated environments; look for go-to-market proof points in at least two jurisdictions with distinct compliance regimes.
- For product teams: embed privacy-by-design and explainable-AI controls into citizen-facing services to meet both regulatory and public trust thresholds.
How to use the full report
The summary above is intentionally curated to highlight strategic implications without publishing the full segmentation and granularity that our subscribers rely upon for bidding, contracting, and portfolio decisions. The full report includes detailed regional and application breakdowns, vendor financial benchmarking, downloadable forecast datasets, procurement templates, and scenario models calibrated to policy and macroeconomic sensitivity. These assets turn insight into executable plans for 2026.
PW Consulting’s Worldwide E-Government Market report (base year 2025; forecast 2026–2032; currency USD, revenue unit: Million) is available for licensing and for clients seeking custom briefings. Visit the PW Consulting report page to request an executive briefing, view the subscriber datasheet, or arrange a workshop to translate these findings into your 2026 operating plan.
For detailed analysis of this topic, please visit the official page: Worldwide E-Government Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Wall Cladding Market Poised to Reach USD 372,966.34 Million by 2032 at 5.42% CAGR; Asia Pacific Commands USD 108,824.54 Million in 2025
By PW Consulting, 2026-08-18
Worldwide Wall Cladding Market — 2026 Strategic Preview for C-Suite and Investment Teams
Executive snapshot
PW Consulting’s upcoming Worldwide Wall Cladding Market report frames the cladding sector at a pivotal junction. The global market, measured at USD 257,763.15 Million in our 2025 base-year, is projected to continue expanding — our model points to a steady compound annual growth rate (CAGR) of 5.42% over the 2026–2032 forecast window. That trajectory reflects a blend of steady replacement cycles in mature markets, accelerated retrofit demand driven by fire-safety and energy codes, and material substitution dynamics influenced by input-cost shocks and supply-chain repositioning.
Vacuum Sealing Drainage Market
Why this matters for 2026 decision-makers
- Capital allocation: With the sector growing at mid-single digits, near-term capital deployment must prioritize margin protection and capability densification (e.g., insulated panel capacity, engineered fiber-cement platforms) over broad geographic expansion without targeted value propositions.
- Risk management: Volatility in metals and resin prices, coupled with recent tariff and standards shifts, necessitates active hedging, supplier diversification, and modular contract structures to limit input-cost pass-through to end customers.
- Regulatory alignment: Heightened fire-safety testing and green-building requirements are reshaping spec & procurement. Non-combustible and heavily insulated systems are becoming default choices for public and high-rise projects — influencing product roadmaps and certification investments.
Market trajectory and structural drivers
The 2020–2025 historical view captures recovery from pandemic disruptions, followed by secular investment in urbanization, retrofit activity, and durable façade solutions. Looking into 2026, three structural forces will dominate executive agendas:
Fixed Flow Anesthesia System Market
- Demand-side regulation: Fire performance standards and sustainability codes are expanding the addressable market for non-combustible and high-thermal-performance systems, accelerating adoption beyond traditional use-cases.
- Supply-side shocks: Aluminum and steel spot premiums and higher tariff floors have elevated costs for metal-based systems. These pressures are prompting end-users and specifiers to reconsider material mixes, opening white space for alternatives that balance lifecycle cost and compliance.
- Labor and total installed cost calculus: Differences in installation labor intensity between material families mean that procurement choices increasingly weigh Installed Cost per Square Meter alongside material cost per unit, influencing channel strategies and contractor partnerships.
What the report delivers — actionable intelligence, not just numbers
This is a practitioner’s study designed to be operationally useful for 2026 planning cycles. Key deliverables include:
Worldwide E-Notary Software Market
- Scenario-based revenue models calibrated to macro sensitivities (input-price shocks, stricter fire codes, tariff rollouts) that allow CFOs to stress-test P&L outcomes and ROI timing.
- A procurement heatmap and supplier-risk matrix highlighting where upstream concentration and single-source exposures could create bottlenecks for common cladding systems.
- Go-to-market playbooks for OEMs and contractors — priced roadmaps for premium vs. value propositions, channel segmentation, and specifier engagement strategies tailored to regulatory regimes.
- Total Installed Cost models for major material families, incorporating material, labor, transport, and compliance testing costs to help quantify trade-offs at contract tendering.
- An IP and innovation tracker mapping proprietary coatings, composite cores, and insulation integrations that are most likely to drive differentiation through 2028.
- A transaction & partnership radar identifying likely consolidation targets, JV opportunities in emerging markets, and technology licensing candidates based on capability adjacencies.
Competitive landscape — what leading companies are doing now
The cladding arena remains commercially diverse, with established materials players, specialized panel manufacturers, and composite innovators each carving distinct strategies. The report includes an in-depth competitive assessment of system leaders and fast followers, summarised here as strategic profiles and implications.
Major players — strategic takeaways
- James Hardie Industries plc: Maintains leadership in fiber-cement through scale, channel relationships in residential markets, and a strong brand for durability and fire performance. Strategic focus for 2026 should be on accelerating value-added façade systems and contractor productivity programs to offset higher installation costs.
- Kingspan Group: Positioned as a technology-led envelope player emphasizing insulated metal panels and energy performance. Kingspan’s advantage is its integrated thermal-insulation proposition — a template for competitors to emulate via partnerships or bolt-on insulation assets.
- Etex Group: Etex’s fiber cement and facade brands benefit from an explicit sustainability and fire-safety narrative; their playbook centers on certified systems and architect engagement. Expect targeted offerings for regulated high-rise segments.
- Saint-Gobain: With a broad material portfolio, Saint-Gobain can cross-sell gypsum, composite, and interior systems into large construction projects. Their strategic edge is project lifecycle integration and specification intimacy with global contractors.
- Trespa International B.V.: Specialty HPL panels offer differentiated longevity and aesthetic options. Trespa’s pathway forward is category premiumization and selective market concentration where high-performance façade materials command pricing power.
- 3A Composites (Alucobond): As a leader in ACM, Alucobond’s strategic priorities include product certification, surface-treatment innovations, and supply-chain localization to mitigate metal-cost volatility.
- Alucoil and Tata Steel: Steel- and aluminum-based systems continue to serve industrial and institutional demand. Their playbooks emphasize supply reliability, long-roll capabilities, and integration with roofing and structural suppliers to defend margins under metal-price swings.
- Nichiha, Rockwool, UNIFLOOR, NewTechWood: These firms represent niches — engineered wood aesthetics, stone-wool insulation-integrated panels, and wood-composite systems. Their strategic trajectories involve targeting retrofit, mid-market residential, and sustainability-focused projects where lifecycle narratives win.
Recent industry movements to watch in 2026
- Trade shows and exhibitions continue to accelerate product visibility and spec adoption — recent showcases highlighted rigid recycled-PVC honeycomb systems and new fiber cement rainscreen designs, underscoring a parallel push on circularity and certified fire performance.
- Input and policy noise remains material: Aluminum premium spikes and tariff resets are actively influencing sourcing decisions; simultaneously, building codes like advanced fire-performance testing are closing windows for combustible cladding in many jurisdictions.
Strategic imperatives and recommended plays for 2026
- Re-balance product mix toward compliance-led value: Invest selectively in non-combustible and thermally efficient systems to capture specification share where regulation is driving demand.
- De-risk supply chains: Establish dual-sourcing, localized inventory hubs for high-volatility inputs, and supplier-collaboration contracts that share upside when commodity costs normalize.
- Capture installed-cost leadership: Pilot productivity initiatives with installation partners (pre-fabrication, integrated clips, digital installation guides) to reduce labor intensity and accelerate project cycles.
- Monetize certification and testing: Fast-track BS 8414 and equivalent certifications for new systems, turning compliance into a marketable credential that shortens procurement cycles and reduces specification friction.
- M&A and partnerships: Target bolt-ons that add insulation, coating technologies, or local manufacturing footprints — prioritize speed-to-specification over scale alone.
- Sustainability & circularity: Build transparent lifecycle narratives with recycled content and take-back schemes for façade panels to address growing specifier demand and regulatory expectations.
Risks, watchpoints, and scenario pivots
- Commodity shock scenario: A prolonged metal-price surge or higher tariff environment will widen margins for alternative-material providers and shorten payback timelines for pre-insulated systems. Executives should stress-test product profitability against a 12–24 month elevated-cost window.
- Regulatory shock scenario: Rapid adoption of tougher fire-safety standards in additional markets can make certain combustible systems non-viable for high-rise or public infrastructure projects — necessitating accelerated product recertification.
- Labor dislocation scenario: Persistent installer shortages or wage inflation will alter the winner-take-most dynamic in markets that value low installed cost and rapid delivery.
How to use the report in your 2026 planning cycle
For boards, strategy teams, and investors, the report is designed to be directly executable: use the scenario models to size downside and upside cases for capital projects; apply the supplier-risk matrix to renegotiate long-term purchase agreements; and adopt the go-to-market playbooks to pilot differentiated value offerings in priority segments. Commercial teams will find the pricing and installed-cost models especially useful for competitive tenders and margin preservation.
Closing — the trailer and the full feature
This brief has surfaced the strategic contours that will shape 2026 decisions: an expanding global market base, mid-single-digit CAGR growth, shifting material economics, and an accelerating regulatory overlay that privileges certified, high-performance systems. PW Consulting’s full Worldwide Wall Cladding Market report contains the granular segmentation, regional modeling, competitive market shares, and downloadable financial models that underpin the recommendations above. We intentionally limit segmented figures here to preserve the full analytical value available in the complete report.
To access the detailed datasets, regional forecasts, and customizable scenario tools that finance, operations, and commercial teams will rely on this year, visit our report page and download the executive package for board-ready briefings and implementation templates.
For detailed analysis of this topic, please visit the official page: Worldwide Wall Cladding Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Heated Socks Market Tops USD 203.45 Million in 2025; Poised to Expand at 8.25% CAGR from 2026 to 2032
By PW Consulting, 2026-08-18
Worldwide Heated Socks Market — Strategic Briefing for 2026 Decisions
Executive summary
PW Consulting’s latest market study on the Worldwide Heated Socks Market clarifies why 2026 will be a strategic inflection year for manufacturers, retailers, and investors. Our analysis synthesizes five years of historical dynamics (2020–2025) and provides a 2026–2032 forecast built on proprietary scenario modeling, channel economics, supply-chain stress testing, and competitor benchmarking. At the macro level, the global heated-socks market has expanded from a modest base in 2020 to a materially larger market by 2025, with our model driving an expected multi-year compound annual growth rate (CAGR) of 8.25% across the 2026–2032 forecast window. That growth trajectory underpins attractive commercial opportunities — but also intensified competitive and regulatory complexity that require targeted, pragmatic strategies in 2026.
Worldwide Hydraulic Augers Market
Why 2026 is an operational inflection point
Several converging vectors — product electrification, premiumization in winter-sports and professional-use apparel, and the maturation of integrated power-tool ecosystems — reposition heated socks from a niche accessory into a core wearable-thermal category. PW Consulting’s topline sizing places the total market at just over USD 200 million in our 2025 base year and forecasted to exceed USD 220 million in 2026, accelerating toward well over USD 350 million by the end of the forecast horizon. These aggregate dynamics create a window for decisive moves in product roadmaps, channel investments, and supply-chain de-risking that should be executed in 2026 to capture disproportionate share during the next growth phase.
Electric Toothbrush Pressure Sensor Market
What the numbers mean for strategy
- Market scale and momentum — The growth rate we model (CAGR 8.25% for 2026–2032) signals sustained consumer and professional demand, not a transitory spike. Strategic bets on tech-enabled differentiation (battery integration, control apps, modular systems) will compound returns as category adoption broadens.
- Fragmentation and consolidation opportunity — The market remains moderately fragmented (our concentration analysis shows the top three players capture less than one-third of market value, with the top five under 40%). That structure favors both specialist brand builders and acquisitive platforms seeking scale through selective M&A.
- Channel composition matters — Growth is uneven across routes to market. An integrated omni-channel playbook that aligns product tiers to consumer acquisition costs and lifetime value is essential. Sellers who optimize digital funnels while preserving premium in-store experiences for higher-touch segments will outcompete pure-play strategies.
Supply-side dynamics and near-term risks
Manufacturers and procurement teams must interpret growth alongside supply-side volatility. Key risks include raw-material price swings that affect rechargeable-battery costs, rising textile labor costs in important manufacturing hubs, and trade-policy frictions that alter landed economics for imports. Additionally, safety and standards oversight related to batteries and consumer electrical goods is intensifying: compliance with household and commercial battery safety standards is already a non-negotiable requirement in many jurisdictions and will influence time-to-market and claims costs.
Worldwide Citation Tools Market
Competitive landscape: who to watch and why
PW Consulting’s competitive review focuses on players that collectively define product archetypes and route-to-market playbooks. Our field research and secondary validation highlight several strategic segments — premium winter-sports innovators, affordable USB-rechargeable consumer brands, integrated tool-platform entrants, and specialized occupational products. Representative firms include:
- Gerbing’s (Coeburn, USA) — A lineage brand focused on battery-powered heated socks for motorcycling and outdoors. Strengths: purpose-built voltage systems and heat-level customization; strategic emphasis on niche channel loyalty.
- ActionHeat (Mississauga, Canada) — Product breadth across rechargeable lithium-ion lines for skiing, hunting, and cold-weather work; built on sizing and fit variety that supports seasonal retail programs.
- SunWill (Dongguan, China) — Cost-competitive, USB-rechargeable offerings targeted at global consumer markets; plays to broad-volume channels and fast product iteration cycles.
- Lenz (Leipheim, Germany) — Premium, app-controlled systems that bundle GPS-enabled features for winter-sports applications; positions on technology and data-enabled services.
- Milwaukee Tool and DEWALT (USA) — Tool-platform incumbents that extend proprietary battery ecosystems into heated apparel for professional trades and jobsite use; this integration creates durable platform lock-in for pro buyers.
- Hotronic (Vienna, Austria) — Modular systems focused on extreme-cold performance and battery-insole combinations for mountaineering and specialized use.
Recent industry developments underscore how product and channel plays are evolving: app-enhanced product generations exhibited at industry shows, expanded sizing lists in seasonal catalogs, and updated certifications for consumer electronic safety. Market participants that combine credentialed safety compliance with differentiated product functionality will capture premium segments; those that rely solely on price competition will face margin compression as cost inputs fluctuate.
What PW Consulting’s report delivers — practical contents for 2026 action
This study is designed as an operational playbook for executing in 2026. Core deliverables include:
- Topline market sizing and scenario-based forecasts through 2032, with clear boundary conditions and sensitivity to battery-cost and tariff shocks.
- A decision-grade competitive map and capability grid that highlights product archetypes, channel strategies, and partnership opportunities (M&A targets flagged for diligence).
- Go-to-market frameworks for premium versus value tiers, including acquisition economics, promotional levers, and retail assortment guidelines.
- Supply-chain and manufacturing playbooks that identify cost-to-serve breakpoints, near-shore versus off-shore tradeoffs, and a practical roadmap for battery sourcing under tightened safety oversight.
- Regulatory and safety compliance primer focused on electrical-battery standards, recommended certification timelines, and cost implications for product launch.
- Commercial due diligence templates and a buy-side checklist for investors performing target screens and post-acquisition integration plans.
- Scenario planning modules that quantify the impact of raw-material swings, tariff adjustments, and technology substitution on unit economics.
Key recommendations for executives and investors
- Prioritize safety and certification as go/no-go constraints: include third-party battery safety testing early in time-to-market plans and budget for iterative fixes.
- Lock in diversified battery supply with staged in-house validation: given material-price volatility and quality risk, multiple vetted suppliers and pooled inventory are prudent.
- Build platform stickiness through ecosystem plays: tool-platform incumbents demonstrate the value of battery compatibility; consider alliances or OEM agreements to access locked-in professional channels.
- Differentiate through experiences not only heat-output specs: app integration, fit engineering, and service features (warranty, replacement batteries) materially affect willingness to pay.
- Execute a hybrid channel strategy in 2026: scale digital customer-acquisition while preserving experiential offline presence for premium segments and key wholesale partners.
- Target acquisitive scale early: low-to-mid consolidation activity is expected; prioritized targets include high-margin niche brands and ergonomic IP owners rather than volume-only producers.
Methodology, limitations, and how to use the report
Our study synthesizes primary interviews, product-level reverse engineering, trade-channel sell-in and sell-through triangulation, and quantitative demand modeling. While our headline numbers reflect the aggregate market trajectory, the granular segmentation matrices and scenario runbooks in the full report are intentionally gated: PW Consulting reserves the detailed splits and proprietary assumptions for subscribers and clients to preserve the commercial integrity of our modeling work and to provide tailored decision support.
Final note: mobilize for decisive 2026 moves
The heated-socks category is transitioning from early-adopter experimentation to scale commercial reality. For executives and investors preparing 2026 plans, the choice is clear: treat this as a product-architecture, channel, and supply-chain problem simultaneously. PW Consulting’s research and operational toolkits are purpose-built to inform capex sizing, channel investments, M&A prioritization, and product go-to-market sequencing that will determine winners in the next phase of growth.
To access the sector-specific dashboards, detailed competitor scorecards, and the full set of scenario models that support the above guidance, please consult the PW Consulting report page for the Worldwide Heated Socks Market. The full data appendices include the granular segment matrices, price-elasticity tables, and target diligence checklists that we withhold here to preserve the value of the primary research.
For detailed analysis of this topic, please visit the official page: Worldwide Heated Socks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide D‑Sub Mixed Contact Connector Market Set to Expand at a 6.2% CAGR Through 2032
By PW Consulting, 2026-08-18
Worldwide D-Sub Mixed Contact Connector Market: Strategic Guidance for 2026 Decision‑Makers
Executive summary
As systems across aerospace, industrial automation, medical electronics and telecommunications demand denser, mixed-function connectivity, the D‑Sub mixed contact connector market presents a pragmatic arena for strategic investment and tactical repositioning in 2026. PW Consulting’s latest market study — with 2025 as the base year — places the global market at approximately USD 425.5 Million (revenue unit: Million USD) and forecasts growth to USD 449.0 Million in 2026, underpinned by a compound annual growth rate (CAGR) of 6.2% across the 2026–2032 forecast horizon.
Automated Test Equipment for Biomedical Market
This release is not an extract of the full dataset; rather, it is a concise executive briefing highlighting where CFOs, heads of product, supply‑chain leaders and corporate strategy teams should focus in the coming 12–18 months. The analysis is intentionally substantive while withholding core granular splits to preserve the report’s commercial value and direct readers to our full resource for definitive, transaction‑grade intelligence.
Worldwide Electroretinogram Market
Market snapshot and what it means for 2026 planning
-
Market momentum: From the 2020 reference point, the D‑Sub mixed contact segment has expanded steadily, demonstrating resilience through supply‑chain shocks and regulatory shifts. Revenue expansion into 2026 reflects both replacement cycles in established industries and incremental design‑wins in adjacent applications.
Polymer Solid-State Lithium Battery Market -
Consolidation and concentration: The market exhibits moderate concentration at the top, with the leading three and five suppliers commanding a meaningful share of revenue and channel influence. This concentration shapes supplier negotiation dynamics, qualification timelines and standards adoption across OEMs and subcontractors.
-
Value drivers: Buyers are increasingly prioritizing hybrid functionality (power + signal + coax/high‑voltage options), robust environmental sealing (IP ratings), and installation ergonomics (push‑pull and quick‑lock systems) — features that materially influence BOM cost, time‑to‑service and lifetime total cost of ownership.
Strategic implications for enterprises
-
Product strategy — specify for serviceability: For system integrators and OEMs targeting long service lives (e.g., defense, aerospace, industrial automation), mandating modular mixed‑contact options with clear replacement and upgrade paths reduces life‑cycle risk. Push‑pull and coding variants that decrease maintenance time should be evaluated not just for unit cost but for field economics.
-
Procurement strategy — diversify with qualification discipline: Recent trade measures and materials tariffs have introduced asymmetric cost pressure across geographies. Procurement teams must balance dual‑sourcing strategies with accelerated supplier qualification playbooks, ensuring that second‑source components meet ISO/AS/MIL standards without creating hidden integration costs.
-
Supply‑chain resilience — redesign for raw‑material volatility: Copper‑intensive contacts remain exposed to tariff regimes and raw‑material scarcity. Component designers and buyers should prioritize contact metallurgy choices and plating alternatives that meet regulatory requirements while preserving electrical performance and long‑term availability.
-
R&D and roadmap — invest in hybridization and robustness: Product roadmaps that accelerate mixed contact density, high‑current/power contacts, and sealed, ruggedized housings (IP67/68) are most likely to capture share from legacy single‑function incumbents. Time‑to‑market advantage accrues to organizations that marry mechanical innovation (e.g., push‑pull housings) with validated electrical performance.
-
Compliance and certification — build into procurement SOWs: Certification overhead (AS9100, MIL‑DTL‑qualified variants, UL recognition and lead‑free standards) materially affects qualification timelines and per‑unit cost. Embed certification requirements in initial RFQs and technical SOWs to reduce redesign cycles and avoid post‑qualification hold‑ups.
Competitive landscape — reading the leaders and niche specialists
The market’s competitive architecture is a blend of global platform suppliers, regionally specialized manufacturers and niche, high‑reliability houses. The differentiated strategies observed among the leading players point to clear partnership archetypes for buyers:
-
Global platform integrators (e.g., Amphenol, TE Connectivity, Molex): These organizations excel at breadth—offering catalog depth across power, signal and coaxial combinations, high‑density variants and MIL‑qualified lines. They are the default choice for customers needing rapid availability and comprehensive catalog coverage combined with global distribution reach.
-
Modular and systems innovators (e.g., HARTING): Companies focused on modularity and installation efficiency have introduced systems-level innovations such as push‑pull housings and extensive coding options, delivering meaningful reductions in assembly and maintenance time for industrial applications.
-
Rugged and high‑reliability specialists (e.g., Glenair, Positronic, ITT Cannon): These vendors have deep expertise in MIL‑spec and harsh‑environment designs, making them preferred partners where qualification rigor and environmental performance are non‑negotiable.
-
Cost‑competitive and IP‑sealed manufacturers (e.g., Signal Origin, CONEC, NorComp): Focused on sealed mixed‑contact and custom variants, these suppliers tend to be attractive to OEMs designing for outdoor or heavy‑industrial deployments where ingress protection and price are key differentiators.
-
Regional and contract manufacturers (e.g., EDAC, Phoenix Contact, AUK Connector): These firms serve varied OEM needs with flexibility in termination styles and local support, often providing the bridge between large platform suppliers and bespoke contract manufacturing requirements.
Our competitive analysis also highlights a practical insight: procurement value is frequently realized not in marginal unit price negotiation but in early alignment on lifecycle services, environmental qualification, and repair/upgrade frameworks.
Supply‑chain, regulation and pricing dynamics
-
Tariffs and raw materials: Recent trade policy developments — including elevated duty levels on certain imports and ad hoc measures affecting copper — have increased landed costs and introduced incentive pressure for near‑sourcing or alternative metallurgy. These changes should be modeled into multi‑year cost baselines and scenario plans.
-
Regulatory and standards complexity: Mixed‑layout D‑Sub connectors sit at the intersection of multiple standards regimes. Expect OEMs supplying aerospace, defense and medical to require MIL‑grade, AS9100 and UL recognized components alongside lead‑free and RoHS‑compatible plating options.
-
Installation and after‑sales economics: Innovations such as push‑pull housings materially reduce mean downtime in fielded systems; quantifying this benefit can shift procurement decisions from cost‑per‑piece to cost‑per‑operational‑hour metrics.
What PW Consulting’s full report contains (practical, actionable elements)
-
Scenario‑based forecasts and sensitivity analysis calibrated to commodity and tariff assumptions, under multiple demand trajectories — enabling CFOs to stress‑test capital allocation and hedging strategies.
-
Commercially actionable supplier scorecards with qualification timelines, risk indices and sourcing recommendations mapped to application classes — structured to shorten RFQ cycles.
-
Technology adoption roadmaps and BOM migration blueprints for mixed‑contact substitution, including engineering checklists that reduce integration and certification rework.
-
Deal playbooks for strategic sourcing — including negotiation levers, volume consolidation scenarios and contingency sourcing templates for rapid supply‑chain pivoting.
-
Field economics calculators that translate connector design choices (e.g., push‑pull locking, IP rating, contact metallurgy) into total cost of ownership and mean time to repair improvements.
Recent industry moves worth noting
New product introductions underscore why time‑to‑market matters. For example, HARTING’s 2025 launches of push‑pull compatible housings and locking systems — which promise substantial installation time savings and expanded coding flexibility — illustrate how mechanical innovations are reshaping buyer priorities across industrial segments. These shifts create immediate opportunities for suppliers who can pair mechanical ease‑of‑use with validated electrical performance.
How to use this intelligence in 90, 180 and 360 days
-
90 days — Rapid supplier triage: Execute a two‑month supplier qualification sprint for critical mixed‑contact families, prioritizing dual‑source readiness and ensuring contractual alignment on certification deliverables.
-
180 days — Design‑for‑service implementation: Update engineering standards to incorporate modular housings and sealed connector options for new platforms, and model field service savings into product pricing and warranty terms.
-
360 days — Strategic positioning: Recalibrate sourcing footprints and enter strategic supplier partnerships that lock innovation roadmaps (e.g., push‑pull variants, MIL‑qual capabilities) while hedging material exposure through contract terms or alternative metallurgy strategies.
Conclusion and call to action
For organizations that rely on robust, mixed‑function connectivity, the decisions made in 2026 will shape product platform resilience and aftermarket economics for years. PW Consulting’s Worldwide D‑Sub Mixed Contact Connector Market report equips decision‑makers with the forecasts, supplier intelligence and execution playbooks required to convert industry complexity into competitive advantage.
To access the full dataset, segmented forecasts, supplier scorecards and executable playbooks — including the granular regional, type and application splits that underpin our scenario models — please visit the report landing page for subscription and licensing options.
For detailed analysis of this topic, please visit the official page: Worldwide D-Sub Mixed Contact Connector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


