



Category: market research
PW Consulting: Worldwide E‑Waste Management Market to Expand at 14.5% CAGR Through 2032, Fueling a Global Recycling Boom
By PW Consulting, 2026-08-18
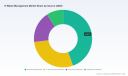
Worldwide E-Waste Management Market: Strategic Imperatives for 2026 — PW Consulting Intelligence Brief
As enterprises and policymakers plan for 2026, the global e-waste management sector has moved from peripheral compliance activity to a core component of corporate resilience and resource strategy. PW Consulting’s new Worldwide E-Waste Management Market report (base year 2025; forecast 2026–2032) synthesizes historical trajectories and forward-looking scenarios to equip executives with the intelligence required to make decisive moves in a market growing at a projected 14.5% CAGR over the forecast window.
Worldwide Data Center Outsourcing and Hybrid Infrastructure Managed Services Market
Market Momentum: From Volume Shock to Value Opportunity
Our quantitative model shows the market more than doubling from its early-2020 scale to reach a distinct inflection in 2025, with continued acceleration in 2026 and beyond. After a multi-year compound expansion driven by regulatory tightening, material recovery economics, and lifecycle service growth, the market is forecast to exceed USD 230 billion by 2032 under the central case. This rapid expansion underscores two linked transitions: (1) e-waste is increasingly treated as an industrial feedstock rather than a disposal challenge; and (2) services around secure data destruction, refurbishment, and urban mining are evolving into high-margin business lines for firms that can execute integrated solutions.
Endotoxin Testing Kits Market
Why This Report Matters for 2026 Decision Cycles
For 2026 planning, stakeholders need more than trend charts — they need executable strategy. The PW Consulting report provides that bridge. Key decision-use cases we address:
Industrial Control MCU Chip Market
- Capital allocation: An evidence-based view of where processing scale, material recovery technologies, and regional logistics investments generate the highest risk-adjusted returns.
- Policy and compliance planning: Scenario maps linking Basel Convention amendments, the EU Circular Economy agenda, and expanding Extended Producer Responsibility (EPR) regimes to operational and balance-sheet impacts.
- M&A and partnership screening: Benchmarks and playbooks for identifying bolt-on acquisitions, capacity partnerships, and joint ventures that accelerate route-to-market for circular services.
- Commercial go-to-market: Positioning guidance for ITAD, data center decommissioning providers, OEMs, and waste-management incumbents aiming to capture higher-value recycling revenue.
What’s Inside — Practical, Actionable Content
PW Consulting’s offering is deliberately practical. Rather than a theoretical sweep, the report contains:
- Scenario-driven financial models calibrated to 2020–2025 observed performance and stress-tested across policy, commodity, and technological pathways for 2026–2032.
- Operational playbooks for facility design, throughput optimization, and downstream material recovery to close the loop on electronics and batteries.
- Regulatory impact matrices that translate global, regional, and national policies into compliance cost ranges and competitive implications for producers and processors.
- A proprietary vendor assessment template that standardizes evaluation across ESG credentials, certification (e-Stewards, R2, NAID AAA), processing footprint, and downstream offtake security.
- M&A diligence checklists and valuation deltas for common plays (capacity buys, technology licensing, and ITAD platform acquisitions).
Competitive Landscape: Leading Players and Capability Gaps
The market remains meaningfully fragmented — our concentration analysis indicates that the top national and global players do not dominate supply to the same extent as in many other industrial recycling markets. That fragmentation is an opportunity for consolidation by strategic buyers and for specialized firms to scale niche advantages.
Core participants profiled in the report include global diversified processors, metals refiners, dedicated IT lifecycle providers, and integrated waste-management firms. Representative firms and their strategic positioning are:
- Veolia Environnement S.A. — global end-to-end collection, treatment, and circular solutions for electronics and IT waste; emphasis on integrating recycling into broader circular service lines.
- Umicore SA — advanced closed-loop precious metals recycling and refining capabilities that make it a natural partner for recovered-metal offtake and high-purity streams.
- Sims Lifecycle Services (Sims Limited) — extensive global electronics recycling and ITAD operations, with significant processing infrastructure supporting refurbishment and metal recovery.
- Aurubis AG and Boliden AB — metallurgy-centric recyclers leveraging integrated smelting operations to process complex e-waste streams into saleable metal outputs.
- Electronic Recyclers International (ERI) and TES-AMM — leaders in secure ITAD, data destruction, and regional-scale refurbishment networks, catering to corporate and government customers.
- Stena Metall (Stena Recycling), Waste Management Inc., and regional specialists — strong in collection, sorting logistics, and integration with municipal and industrial waste flows.
- Enviro-Hub Holdings and other Asia-Pacific players — growing regional capacity that supports cross-border flows and processing specialization.
For 2026, the strategic question for incumbents and new entrants is twofold: can you secure reliable feedstock and can you lock in downstream offtake for refined materials? Firms combining secure collection/ITAD capabilities with advanced metallurgical or refining partnerships will capture disproportionate value as material yields and traceability premiums grow.
Recent Industry Dynamics and Their Strategic Implications
Several practical developments are reshaping the competitive and regulatory landscape:
- Basel Convention amendments (effective January 1, 2025) have tightened controls on cross-border e-waste shipments. This reinforces the value of localized processing capacity and increases the importance of compliance-enabled logistics and certified downstream partners.
- Expanded EPR programs, notably in parts of Europe, India, and select U.S. states, are raising recovery targets and transferring end-of-life costs back to producers — accelerating demand for compliant take-back and certified recycling services.
- Capacity expansions and strategic corporate moves (e.g., recent processing facility launches, battery recycling campus rollouts, and targeted acquisitions) signal that players are vertically integrating to capture a greater share of battery and electronics urban mining economics.
- Rising electricity consumption in data center gravity points (exceeding 400 TWh in recent estimates) implies a growing stream of IT hardware e-waste; this trend favors specialists in secure ITAD and refurbishment who can monetize redeployment or high-quality material recovery.
Collectively, these dynamics make 2026 the year to pivot from reactive compliance to proactive assetization of e-waste flows — treating them as predictable supply chains underpinning material-security strategies.
Risk, Uncertainty, and Tactical Responses
Our stress-tested scenarios highlight three principal risks for 2026 planners:
- Policy variability: Where national frameworks lag, operators face regulatory arbitrage and uncertain compliance costs. Recommended response: adopt conservative compliance buffers and diversify collection footprints.
- Feedstock volatility: Shifts in consumer replacement cycles and device lifespans can alter stream composition. Recommended response: modular processing designs that can pivot between IT, consumer electronics, and battery streams.
- Market fragmentation: Low concentration creates price competition and margin pressure for undifferentiated processors. Recommended response: move up the value chain via certified processing, proprietary recovery technologies, or downstream offtake contracts.
How PW Consulting Supports 2026 Execution
For clients making 2026 bets, our report is paired with advisory offerings tailored to implementation:
- Transaction advisory for M&A and JV structuring, including synergy models and integration playbooks;
- Site-selection and capex optimization for new processing hubs, with techno-economic analysis and permitting risk mapping;
- Commercial transformation programs for OEMs and IT operators to implement EPR-compliant take-back and certified vendor networks;
- Supply-chain risk dashboards that map material provenance, certification status, and counterparty credit for recycled-material offtake.
Why the Report Uses a “Trailer” Approach — and What You’ll Need to Access
In keeping with our client-first intelligence strategy, this briefing highlights the high-level evidence and strategic implications while preserving the granular segment-level tables, region-by-region value matrices, and company financial benchmarks for the full report. Those detailed breakouts contain the specific regional, material, and source splits, vendor scorecards, and downloadable financial models that are essential for transaction execution and operational planning.
To make a confident 2026 decision, teams will need access to the full dataset and drilldowns. PW Consulting’s complete report provides the exact segment figures, sensitivity assumptions, and vendor-level financials required to translate strategy into deployable plans.
Next Steps for Executives
If your 2026 plan involves capital deployment, partnership formation, or regulatory lobbying in the e-waste space, begin with a focused diagnostic using three questions:
- Do we have secured, compliant feedstock and the logistics to scale it sustainably?
- Can we capture downstream value through certification, refined-material offtake, or refurbishment channels?
- Are our capabilities resilient across the policy scenarios likely to materialize in 2026?
PW Consulting’s Worldwide E-Waste Management Market report provides the empirical inputs, scenario maps, and execution templates to answer these questions. For access to the full report — including the detailed segment-level tables, vendor scorecards, and downloadable financial models — visit PW Consulting’s intelligence portal or contact our advisory team to arrange a briefing and model walkthrough.
Prepared by PW Consulting — actionable intelligence for leaders turning e-waste into a strategic asset in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide E-Waste Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Antimony (Sb) Evaporation Materials Market Set for a 6.18% CAGR Through 2032, 2025 Insight Report Reveals
By PW Consulting, 2026-08-18
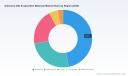
Worldwide Antimony (Sb) Evaporation Materials Market — Strategic Outlook for 2026 Decision-Making
Executive summary
PW Consulting’s new market study on Worldwide Antimony (Sb) Evaporation Materials provides senior executives, procurement leaders, and technology strategists with a compact, action-oriented intelligence package tailored for decisions in 2026. The market has exhibited steady expansion through the 2020–2025 base period and is forecast across 2026–2032 to grow at a compound annual growth rate (CAGR) of 6.18%. In monetary terms, the market increased from roughly USD 182.2 Million in 2020 to USD 245.8 Million in our 2025 base year, and our baseline projection anticipates total market value approaching USD 374.1 Million by 2032. These headline dynamics mask material sub-segment shifts, purity-driven demand pockets, and supply-side stress points that will materially influence sourcing and technology roadmaps in 2026.
Worldwide Printer Copier and Service Market
Why this matters for 2026 strategic planning
Antimony evaporation materials sit at the confluence of advanced thin-film manufacturing, specialty coatings and certain electronic device stacks. The sector’s mid-single-digit CAGR disguises pockets of accelerated demand tied to higher-purity grades, novel device architectures, and regional policy moves. For 2026, the most consequential implications for corporate leadership are threefold:
5G Indoor CPE Market
- Risk-managed supply strategies: Price volatility and shifts in upstream feedstock availability require a calibrated mix of spot, medium-term, and strategic-contract exposure to avoid inflationary procurement shocks.
- Product-spec alignment: R&D roadmaps that anticipate purity escalation and form-factor requirements (pellets, pieces, alloys) will be rewarded with lower qualification time and higher yields in production.
- Competitive supplier positioning: The market exhibits a noticeable level of supplier concentration that advantages well-capitalized producers and flexible specialty suppliers—creating both entry barriers and acquisition opportunities for larger players.
Market trajectory and what the top-line numbers conceal
The headline market grew by a material margin from 2020 to 2025 and continues to show growth into the forecast window to 2032. However, aggregate growth belies significant heterogeneity: purity tiers are not expanding uniformly; demand drivers in optical coatings, semiconductor-related evaporation, and emerging photovoltaic/photonic niches follow distinct cycles. Equally important, the pricing environment has shown episodic volatility: industry data indicate antimony metal prices around USD 51.80 per kg as of April 2026, a level reflecting recent swings from 2025 peaks. These price dynamics flow through to evaporation-grade materials differently depending on form, alloy content and purity requirement.
AI-powered Software Market
Supply-chain and geopolitics — a 2026 inflection
Geopolitical developments in the past 18 months have elevated antimony on the critical-materials agenda. Policymakers in key consuming markets have enacted measures to bolster domestic capacity and reduce single-source dependencies. Notably, in March 2026, a prominent U.S. upstream producer received a Title III Defense Production Act award to modernize and expand refining and production capacity — an intervention explicitly framed to support defense and industrial feedstock needs, including evaporation-grade materials. At the same time, new exploration results in North America (including high-grade intercepts and encouraging metallurgical recoveries reported in 2026) suggest a potential for incremental near- to mid-term oxide supply outside traditional hubs.
Concurrently, export licensing regimes and state-traded quotas in major producing countries continue to shape trade flows and risk premia. One major producer maintained export authorizations for a select group of exporters into 2026–2027, while temporary relaxations or suspensions of certain dual-use controls have led to episodic easing of trade friction. For 2026 procurement planning, the interplay of these policy levers and market interventions means scenario-based sourcing — not single-point forecasts — is the prudent default.
Competitive landscape — structure and strategic behavior
Concentration metrics highlight a market where a limited set of specialized suppliers command a substantial share of evaporation-materials supply. Our analysis shows that the top three firms account for a clear majority of the market footprint, and the top five consolidate roughly three quarters of market activity, creating scale advantages in quality assurance, logistics and product development.
Key players include a mix of longstanding U.S.-headquartered specialty producers, European niche suppliers, and rapidly maturing Asian manufacturers. Representative firms covered in the report include:
- Kurt J. Lesker Company (Jefferson Hills, Pennsylvania, USA) — established thin-film materials supplier offering Sb pieces and pellets suitable for conventional evaporation workflows.
- Stanford Advanced Materials (Lake Forest, California, USA) — supplies high-purity Sb powders, granules and customized forms; also markets antimony sulfide evaporation chemistry for specific coating applications.
- American Elements (Los Angeles, California, USA) — a broad specialty materials business with evaporation-grade Sb and related compounds for both commercial and research thin-film deployments.
- Heeger Materials Inc. (Colorado, USA) — focuses on antimony oxide evaporation materials used in thermal evaporation and coatings R&D.
- AEM Deposition (China) and ATT (China) — regional producers expanding alloy and ultra-high-purity offerings, with ATT advertising quality assurance protocols up to five-nines purity.
- MSE Supplies (Tucson, Arizona, USA), PhotonExport (Spain) and MetalsTek (China) — suppliers spanning high-purity pieces, antimonides, and custom geometries for thin-film integrators.
Each supplier’s strategic play differs: some emphasize tight purity certification and lot traceability for semiconductor qualification, while others compete on alloy and customized-form flexibility for research labs and small-scale coating houses. This bifurcation creates distinct supplier tiers, and the report maps these tiers against manufacturing scale, geographic reach, and certification readiness.
Recent developments and near-term catalysts
- U.S. domestic industrial policy interventions in March 2026 have unlocked capital for upstream capacity increases targeted at ensuring feedstock for strategic applications — a development likely to recalibrate long-run import-dependency assumptions for some buyers.
- New exploration milestones reported in 2026 indicate promising domestic oxide antimony prospects in North America that could feed higher-purity processing chains if metallurgy and permitting proceed as anticipated.
- Price indices in Europe and spot prices globally show recent downward adjustments from 2025 highs, driven by a combination of import flows and softened demand in traditional consuming sectors — a dynamic that could provide transient procurement windows for buyers willing to hedge.
What PW Consulting’s report delivers (practical, operational intelligence)
This study was designed to be immediately operationalizable. It contains:
- Validated market sizing and a transparent forecast model covering 2026–2032 with scenario toggles for price, supply disruptions and demand shocks.
- Supplier due-diligence templates and a procurement playbook that translate quality requirements and purity tiers into contractual clauses and audit checkpoints.
- Supply-chain maps and contingency matrices that show likely chokepoints under alternate geopolitico-policy scenarios.
- Product-spec rationalization guidance to reduce qualification cycles and cost-per-wafer through materials engineering trade-offs.
- Executive-ready risk dashboards and scorecards that benchmark the competitive set on capacity, quality, lead times and certification readiness.
- Actionable M&A and partnership opportunity frameworks that identify where bolt-on capacity or technology licensing could accelerate time-to-market.
To respect client sensitivity and maintain the “trailer” principle, the public summary deliberately omits detailed segment-level tables, proprietary supplier scoring matrices, and granular regional or application percentage splits. These items are included in the full report and interactive data workbooks.
Practical recommendations for 2026
- Establish layered contracts: combine short-term spot access to take advantage of transient price softness with multi-year agreements that include volume-flex and quality-index clauses to mitigate supply shocks.
- Prioritize qualification of a second-tier supplier with complementary capabilities (e.g., alloying or custom geometry) to de-risk single-supplier dependence for critical production lines.
- Run a purity-cost curve test program: evaluate whether incremental purity (and its associated cost) delivers commensurate yield or performance gains for target applications; in several use-cases the marginal return is asymmetric.
- Monitor policy developments and early-stage upstream investments as leading indicators: new refining capacity or large-scale exploration success can compress risk premia, but only when paired with mid-stream processing capability.
How to use this research
For procurement heads, the report functions as a decision-support tool to design contracting strategies and supplier audits. For R&D and production leads, it offers a materials-specification playbook that aligns purity and form with manufacturability. For strategy and corporate development teams, it surfaces acquisition targets and partnership pathways while outlining the regulatory scaffolding likely to influence returns.
Next steps — where to get the full intelligence
PW Consulting has packaged the full market model, supplier scorecards, scenario dashboards and a procurement playbook as a single deliverable for corporate subscribers. The public summary above highlights the strategic imperatives for 2026 while intentionally reserving the granular segmentation, detailed supplier rankings, and downloadable data tables for licensed purchasers. Contact our research team to obtain the comprehensive report and the interactive forecast workbook needed to operationalize these findings in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Antimony (Sb) Evaporation Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Drone Frame Market to Jump from USD 1,291.6 Million in 2025 to USD 3,435.7 Million by 2032 at a 15% CAGR — Carbon Fiber Dominance and Asia‑Pacific Lead
By PW Consulting, 2026-08-18
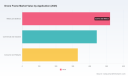
Worldwide Drone Frame Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As the drone economy accelerates into a new cycle of operational scaling and regulatory scrutiny, the global market for drone frames is transitioning from component commodity to strategic hardware asset. PW Consulting’s latest Worldwide Drone Frame Market report — anchored on a 2025 base year and a 2026–2032 forecast horizon — quantifies that transition and translates it into executable guidance for executive teams planning spend, sourcing, and product strategies in 2026. At a compound annual growth rate (CAGR) of 15.0%, the market is projected to expand from approximately USD 1.29 billion in 2025 to roughly USD 3.44 billion by 2032. This brief highlights the report’s practical insights while preserving the proprietary segmentation that drives our premium analysis.
Titanium Sternal Fixation System Market
Why 2026 is a Strategic Inflection Point
Several converging forces make 2026 the year when boardrooms must move from exploratory pilots to industrialized, compliance-ready drone programs. First, sustained end-market demand and a healthy CAGR underpin higher unit volumes and elevated aftermarket economies. Second, material and supply‑chain dynamics — particularly the sustained preference for carbon‑fiber composites for high-performance airframes — are shifting procurement and supplier-risk strategies. Third, regulatory pressure (notably U.S. national security sourcing priorities and updated FAA guidance) is changing how organizations qualify vendors, validate airworthiness, and architect dual-source strategies. Taken together, these shifts mean that 2026 is not merely another planning year: it is an execution year for companies that want to lock in resilient supply, certify mission-ready platforms, and capture the margin upside in drone-enabled services.
Smart Network Managed Switches Market
Topline Market Context (High‑Level)
- Market size (2025, base year): ~USD 1,291.6 Million.
- Near-term positioning (2026): market entry and scale decisions should assume continued growth as 2026 demand expands beyond pilot programs and into fleet deployments.
- Long-term outlook (2026–2032): at 15.0% CAGR, the market is expected to more than double through the forecast window, reaching ~USD 3.44 billion by 2032.
- Market structure: the sector shows moderate concentration (top-3 firms account for a meaningful share; top-5 firms hold a material majority), creating both partnership opportunities and competitive headwinds for entrants.
What This Means for Corporate Decision‑Makers
- Sourcing strategy must be outcome-driven: Companies should move beyond unit cost discussions and evaluate frames according to life‑cycle cost, certification overhead, damage tolerance, and reparability. The dominance of high‑performance composites means suppliers who can prove consistent material batches and traceable supply chains will command premium pricing.
- Supply‑chain security is a board-level risk: With geopolitical and procurement requirements tightening in several markets, firms must map their supply base by material origin, production footprint, and compliance posture. Dual-sourcing and allied-sourced manufacturing become practical imperatives for sensitive programs.
- R&D and product roadmaps need to prioritize modularity: Modular airframe architectures that separate payload, avionics, and structural elements reduce certification scope for incremental upgrades and accelerate time-to-market for mission-specific variants.
- Testing and standards readiness is a differentiator: Institutional buyers and regulated industries will demand empirical structural testing (vibration analysis, damage assessment) and documented maintenance protocols. Investing in third-party testing and digital twins now shortens procurement cycles in 2026.
- M&A and partnership playbook: Given the market concentration, acquisitive entrants should prioritize bolt-on targets that supply composite expertise, testing labs, or regionally strategic production capacity rather than chasing volume-only players.
Competition and Supplier Landscape — Practical Takeaways
Our competitive analysis builds profiles of incumbent platform and specialized airframe manufacturers, assessing strategic positioning across product completeness, manufacturing capability, and go-to-market channels. Key archetypes include global OEMs offering integrated UAV systems, specialist high‑end frame manufacturers focused on cinema and heavy-lift platforms, and nimble suppliers providing bespoke composite frames and kits to system integrators.
Worldwide Language Learning Software Market
- Integrated OEMs — Companies that deliver end-to-end UAV platforms with optimized composite frames continue to dominate enterprise and consumer channels through bundled value propositions that simplify procurement.
- Professional-Grade Frame Specialists — High-end cinema and heavy-lift vendors that emphasize modular carbon‑fiber airframes capture the premium payload and mission-critical segments where reliability is non-negotiable.
- Autonomy-Centric Platforms — Firms marrying advanced autonomy with lightweight composite frames carve out inspection, mapping, and public‑safety niches where operational efficiency trumps lowest cost.
- Component OEMs and Niche Suppliers — A robust ecosystem of frame manufacturers, kit suppliers, and specialty fabricators supports customization and aftermarket replacement parts; their agility is attractive to system integrators and defense programs.
Representative firms profiled in the report include leading global manufacturers, high-end cinema and heavy-lift specialists, autonomy-centric enterprises, and a selection of regional frame makers — each evaluated on manufacturing footprint, materials competency, certification experience, and strategic fit for different buyer personas.
Recent Industry Signals to Monitor in 2026
- Production capacity expansions among component manufacturers signal readiness to support defense and large commercial orders — firms expanding output are prioritizing frame lines alongside other critical subsystems.
- Innovations in additive manufacturing and modular frame concepts (including academically led and nonprofit prototypes) are lowering the cost and time to field experimental platforms for environmental and scientific missions.
- Advances in structural testing methodologies, including vibration and damage diagnostics, are maturing. Organizations adopting these protocols early will shorten qualification cycles and reduce in-service failure rates.
Report Deliverables — What PW Consulting Provides
Designed as a workbench for strategy teams, the full report contains the following practitioner-oriented assets (note: detailed segmented tables and proprietary datasets are available only in the full release):
- Macro market sizing and scenario forecasts (2020–2032) with deterministic and downside cases to support budgeting and capital allocation.
- Competitive benchmarking with supplier scorecards, manufacturing maps, and supplier risk matrices to guide sourcing decisions.
- Materials and cost-model templates that allow procurement teams to stress-test supplier quotes under alternate commodity and capacity scenarios.
- Regulatory and compliance tracker that ties UAS guidance and procurement rules to certification impact and potential sourcing restrictions.
- Testing and certification playbook (including recommended test protocols and supplier qualification checklists) for technical teams and pilots.
- M&A and partnership screening tool with pre-built filters for capability, geography, and compliance posture to accelerate target identification.
How to Use This Intelligence in 90, 180, and 365 Days
- 90 days: Map current suppliers against the regulatory tracker and risk matrix; initiate qualification audits for primary composite vendors and identify a contingency second source.
- 180 days: Pilot modular-frame variants and run third-party structural testing to build data packages required for procurement and certification. Start supplier negotiation using life‑cycle cost models from the report.
- 365 days: Execute scaled procurement with qualified suppliers, implement maintenance/repair standards, and, where appropriate, close strategic partnerships or bolt-on M&A to secure capacity critical to mission programs.
Why PW Consulting’s Approach Delivers Practical Value
We combine granular technical understanding of composite materials, empirical testing protocols, and commercial market dynamics into a single decision-ready product. Our analysis intentionally couples quantitative topline forecasts with qualitative supplier and regulatory intelligence so that procurement, product, and corporate development teams can make defensible decisions in 2026 without starting from scratch.
Next Steps — Accessing the Full Intelligence
This brief is a preview of the depth contained in PW Consulting’s full Worldwide Drone Frame Market report. For access to complete segmented datasets, supplier-level revenue tables, and downloadable cost-model templates — or to commission a custom deep-dive on supply‑chain risk or M&A targets tailored to your fleet profile — please visit our report page. The full package is designed to convert the market’s 15.0% structural growth trajectory into concrete, risk-adjusted strategies that procurement, engineering, and strategy teams can implement this year.
PW Consulting stands ready to support executive teams in converting market momentum into durable competitive advantage. In a market moving as quickly as drone frames, the difference between leading and lagging will be decided by who prepares in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Drone Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Technical‑Grade Salicylic Acid Market to Rise from USD 516.64 Million in 2025 to USD 791.31 Million by 2032 at a 6.28% CAGR — Asia Pacific and Powder Form Lead
By PW Consulting, 2026-08-18
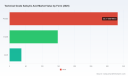
Worldwide Technical Grade Salicylic Acid Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s latest market study on the Worldwide Technical Grade Salicylic Acid Market (base year 2025; forecast period 2026–2032) provides a compact but powerful toolkit for corporate leaders planning capital allocation, sourcing, and commercial strategy in 2026. The technical‑grade salicylic acid market has grown materially over the past half‑decade — from USD 382.45 Million in 2020 to USD 516.64 Million in 2025 — and, under our central scenario, is projected to expand to approximately USD 791.31 Million by 2032 at a compound annual growth rate (CAGR) of 6.28% during the forecast window. This release highlights the strategic implications of those trends while intentionally withholding detailed segment tables and company‑level share data to encourage direct engagement with the full study.
Worldwide Valve Prostheses Market
Why this report matters in 2026
- Investment timing: The mid‑decade inflection in demand and supply dynamics means capacity decisions made in 2026 will determine competitive positioning through 2030. Our forecast horizon quantifies the window of opportunity and risk under multiple market scenarios.
- Procurement & feedstock risk: Technical‑grade phenol and associated upstream benzene/crude oil links make feedstock strategy a primary margin lever. Our modelling isolates the sensitivity of factory economics to phenol and CO2 costs and provides hedging and supplier diversification playbooks.
- Regulatory planning: Increasing environmental and product compliance requirements (for example, EU REACH) require capex for waste‑treatment and process upgrades. We quantify the cost envelope for compliance investments and the breakeven implications at different scales of operation.
- M&A and partnership signals: Market concentration and recent consolidation moves indicate an active window for bolt‑on acquisitions and strategic partnerships. Our competitive heatmaps and acquisition priority matrices help investment committees shortlist targets and synergies.
Key market dynamics shaping 2026 strategies
- Demand composition and end‑use momentum: Technical‑grade salicylic acid continues to serve a diverse set of industrial end uses — from pharmaceutical intermediates and personal care/cosmetic supply chains to dyes, pigments and industrial preservatives. Growth is being driven by incremental downstream demand in synthesis intermediates and expanding industrial applications where cost and consistent quality are decisive.
- Feedstock economics and price dispersion: Production economics are tightly coupled to technical‑grade phenol availability and pricing, which itself is influenced by benzene and crude oil market cycles. In early 2026 we observed pronounced regional price dispersion: Northeast Asia spot levels softened materially while European landed prices remained elevated following a late‑2025 cost spike. These regional differentials are creating arbitrage corridors and reshaping trade flows.
- Process innovation and capacity reallocation: Manufacturers have accelerated process intensification, single‑step synthesis adoption and capacity realignment toward technical/industrial grades. Such operational improvements are compressing unit costs and changing the competitive baseline — favoring players that can scale low‑cost, compliant production.
- Regulatory and sustainability pressures: Tighter environmental regulation in major markets raises the bar for capital expenditure and process hygiene. Compliance profiles are now a differentiator in tendering and long‑term offtake agreements, especially for supply into regulated chemical synthesis and pharmaceutical intermediate chains.
Supply‑side snapshot and competitive implications
The market exhibits moderate concentration: the top three suppliers control a meaningful share of global supply while the top five further increase that concentration cushion. This structure yields room for scale advantages (cost, logistics, compliance) while still leaving tactical openings for regional and specialty suppliers. Recent industry activity validates this dynamic:
Worldwide PLA Fiber Market
- March 2026 — Seqens Group (Novacyl) announced a capacity consolidation and asset integration program designed to expand salicylic acid output and shore up supply for both pharmaceutical and technical grades. As the only large vertically‑integrated European producer with a proprietary single‑step process, Seqens’s move is a signal: regional supply security and compliance are strategic priorities.
- October 2025 — Multiple manufacturers advanced process innovations and targeted capacity projects aimed at industrial and technical grade supply. These moves broaden low‑cost supply options and raise the bar for operational excellence.
Selected competitor profiles we analyze in depth (supply chain position, process footprint, compliance posture, and commercial strategy):
Brushless Hollow Cup Motor Market
- Seqens Group (Novacyl) — France: sole prominent European producer with vertical integration and a proprietary route from phenol; positions itself as a high‑purity supplier for intermediates and specialty industrial uses. ( https://www.seqens.com)
- Major Indian manufacturers — Examples include Siddharth Carbochem, Alta Laboratories (Lona Industries), and Muby Chemicals: cost‑competitive exporters focused on reagent and technical grades with broad industrial application coverage and export orientation.
- Chinese producers — Examples include JQC (Huayin), Hebei Jingye, Zhenjiang Gaopeng, and Achilles Chemical: large volume players supplying global industrial markets; several are pursuing international certification (REACH, ISO) to support export growth. ( https://www.achilleschem.com)
What the full report delivers — practical, actionable content
PW Consulting’s full study is structured to move decision‑makers quickly from strategic assessment to execution. Core deliverables include:
- Proprietary historical and forecast market model (2020–2032) with scenario toggles and sensitivity to feedstock price trajectories and regulatory cost shocks.
- Cost build‑up and pricing model at plant level (feedstock, utilities, waste treatment, logistics) with modular inputs for bespoke client modelling.
- Supply chain risk heatmap and supplier scorecards that incorporate capacity, compliance status, lead times, and commercial posture.
- Competitive playbook including M&A prioritization framework, integration synergies, and a tactical supplier negotiation checklist.
- Regulatory matrix covering key jurisdictions with quantified compliance capex estimates and timeline impacts on producibility.
- Template commercial strategies for producers (capacity sequencing, premium product positioning) and for buyers (dual‑sourcing, long‑term offtake clauses, pass‑through pricing mechanisms).
Note: this release intentionally omits full segmentation tables and detailed company revenue shares. The full datasets and company‑level financial matrices are accessible in the complete report.
Strategic recommendations for 2026
- For producers (mid‑sized and large): Accelerate process intensification and REACH‑aligned upgrades where exposure to European demand exists. Prioritize feedstock integration or long‑dated phenol supply agreements to stabilize margins. Consider bolt‑on additions in adjacent intermediates to capture vertical synergies.
- For lower‑cost regional suppliers: Invest selectively in certifications (REACH, ISO) and quality controls to access higher‑value industrial contracts and to mitigate margin pressure from price arbitrage. Use export logistics optimization to improve landed cost competitiveness in Europe and North America.
- For industrial buyers (dyes, resins, rubber auxiliaries): Move from spot‑only sourcing to blended procurement strategies that combine long‑dated contracts for security with limited spot exposure to capture transient arbitrage. Incorporate supplier compliance scoring into procurement KPIs.
- For investors and private equity: Target companies that combine process know‑how, regulatory compliance and flexible capacity. Prioritize assets with upgradeable technology and identifiable arbitrage channels to Europe and North America.
- For chemical distributors and traders: Leverage regional price dispersion and logistics arbitrage while building service‑based differentiators (e.g., blended inventory, custom packaging, regulatory documentation) to protect margins as commoditization increases.
How to use this intelligence now
- Run a 90‑day strategic sprint: use our executive summary and modelling engine to stress‑test planned capex, offtake and procurement contracts against adverse feedstock scenarios.
- Run a supplier readiness audit: deploy our supplier scorecard to triage sourcing partners for compliance and delivery risk and to design a prioritized remediation plan.
- Workshop M&A options: apply the report’s acquisition priority matrix and synergy calculators to short‑list targets and prepare valuation ranges for 2026 bid activity.
- Engage for a tailored briefing: PW Consulting offers rapid custom analysis — from bespoke cost‑of‑production modelling to a competitive diligence pack focusing on selected producers and trade lanes.
Conclusion — The technical‑grade salicylic acid market is at a strategic inflection: demand diversity and mid‑cycle feedstock volatility are creating opportunities for prudently timed investments, supply chain reconfiguration, and selective consolidation. PW Consulting’s report equips decision‑makers with the data, models, and commercial playbooks required to convert those conditions into defensible advantage in 2026 and beyond. To access the full datasets, segmented forecasts, and supplier‑level analysis, request the report or schedule a briefing through PW Consulting’s market research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Technical Grade Salicylic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide LED Tube Covers Market to Grow at a 5.5% CAGR Through 2032, New Report Forecasts
By PW Consulting, 2026-08-18
Worldwide LED Tube Covers Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s new market research, prepared by our Industrial Lighting & Components practice, delivers a timely strategic roadmap for organizations preparing decisions in 2026. Anchored on a historical review (2020–2025) and a forward forecast (2026–2032), the study captures the commercial dynamics shaping LED tube covers — from raw material volatility and regulatory disruption to intellectual‑property pressure and shifting procurement economics. The global market reached approximately USD 1,204.1 Million in 2025 and, at a projected compound annual growth rate (CAGR) of 5.5% through 2032, is expected to expand substantially by the end of our forecast horizon. This briefing highlights the report’s practical utility for 2026 planning while preserving the detailed segment-level intelligence available in the full report.
In-Car Navigation Chip Market
Why this report matters in 2026
-
Regulatory inflection points have accelerated replacement and retrofit cycles. Ongoing restrictions on legacy fluorescent technology in key jurisdictions, combined with a string of state-level bans on linear fluorescent lamps, have materially increased the addressable market for LED tubes and their associated covers.
On-grid Hybrid Solar Panels Market -
Supply‑side pressure from raw material markets and trade actions is reshaping cost models. Polycarbonate pricing and regional spreads, together with recent tariff movements on steel and aluminum, are raising input costs and altering the economics of aluminum‑base + polycarbonate cover assemblies versus fully integrated tube designs.
Worldwide Cloud Management Software Market -
The market remains structurally fragmented: our concentration analysis shows low top‑tier share (CR3 ~18.5%; CR5 ~28.35%), signaling both continued competition on price/performance and opportunities for consolidation by strategic acquirers and platform builders.
-
IP and standards risk is now a board‑level topic. Recent patent litigation and heightened safety/UL expectations in the 110–120V US market are increasing the importance of proactive IP strategy and compliance engineering.
What the PW Consulting report delivers (practical contents)
-
Actionable market sizing and a 7‑year forecast framework (2026–2032) that supports scenario planning and sensitivity analysis for procurement and capital planning.
-
A modular segmentation approach (by material, surface finish, end‑use, and region) with downloadable datapacks for financial modelling — designed so commercial teams can prioritize SKU-level investments without re‑creating baseline research.
-
Supply‑chain cost models that trace bill‑of‑materials to finished‑goods pricing, including worked examples for PC (polycarbonate), PMMA, and glass covers and for aluminum base integrations.
-
Due‑diligence toolkits: supplier scorecards, technical compliance checklists (UL/CE/RoHS mapping), and an M&A playbook with a defensible valuation framework for rollups in manufacturing and distribution.
-
Competitive intelligence dossiers and an IP watchlist: company profiles, manufacturing footprints, go‑to‑market positioning, and a boiled‑down summary of recent legal and product moves that materially affect licensing and freedom‑to‑operate decisions.
-
Commercial playbooks: differentiated product strategies (finish, optical diffusion, fire‑retardant formulations), channel strategies for retrofit vs. new build, and procurement levers to protect margin in volatile raw material environments.
Competitive landscape — how to read the field in 2026
The LED tube covers ecosystem is populated by a mix of specialized component makers, integrated OEMs, and global lighting brands. Manufacturing incumbents in Asia continue to supply large volumes of extruded polycarbonate covers and aluminum profiles, while multinational lighting firms pair those components with systems thinking — service warranties, trade catalogs, and channel distribution. Key dynamics we observe:
-
Specialist extruders and hardware suppliers remain critical to cost and lead‑time management. Several China‑based manufacturers continue to dominate high‑volume extrusion capabilities and rapid customization for opal, frosted, and clear finishes.
-
Integrated lighting manufacturers (global brands and regional leaders) are leveraging warranties, UL/CE compliance, and broader commercial catalogs to protect margin and defend channel relationships in retrofit programs.
-
Legal and IP events are catalyzing strategic reassessment. A recent patent infringement action filed in early 2026 by a major tube manufacturer underscores the need for active IP due diligence and contingency planning for design changes or licensing negotiations.
For commercial leaders evaluating partners and targets, our company briefs synthesize strengths and go‑to‑market signals: manufacturers focusing on PC cover extrusion and aluminum bases; assemblers offering high‑lumen integrated tubes with proprietary housings; and multinational brands promoting professional trade ranges with standardized cover options. The practical implication is clear: partnerships and licensing arrangements will be a differentiator in 2026.
Cost, compliance and supply‑chain pressures
Polycarbonate remains the dominant material choice for tube covers due to its impact resistance and thermal performance, but regional price volatility and transport differentials materially affect landed cost. Separately, measures increasing duties on metallic inputs have raised the cost base for aluminium profiles commonly paired with PC covers. These twin pressures amplify two choices for manufacturers and buyers in 2026: (1) optimize designs to reduce material intensity and improve yields, or (2) lock supply via forward contracts and broaden qualified supplier pools to wield sourcing leverage.
On compliance, heightened demand for fire‑retardant formulations and UL‑rated designs for North American 110–120V markets is already altering product roadmaps. Firms that align early to these standards will reduce time‑to‑market friction and lower customer churn in large retrofit projects.
Strategic implications & recommended actions for 2026
-
Prioritize compliance engineering: accelerate UL/region‑specific certification programs for target SKUs and document test protocols to shorten procurement cycles with large systems integrators.
-
Hedge material cost exposure: implement multi‑tier supplier agreements and selective long‑term purchase agreements for high‑use polymers; consider regional sourcing alternatives to offset tariff impact.
-
Differentiate through application optics and safety: invest in surface finish R&D and fire‑retardant material blends that meet both photometric and regulatory requirements.
-
Pursue selective consolidation: target bolt‑on deals that add extrusion capacity, regional logistics hubs, or IP portfolios — valuation models in the report identify accretive tuck‑in profiles.
-
Strengthen IP and litigation readiness: maintain an IP watchlist, stress‑test products for design‑around scenarios, and budget for licensing where avoidance is cost‑prohibitive.
-
Adopt scenario planning: use the report’s three demand trajectories to stress procurement, production and working‑capital plans across rapid, baseline, and slow adoption pathways.
Closing — how PW Consulting supports your 2026 roadmap
Our Worldwide LED Tube Covers Market study is designed as an operational playbook, not a high‑level summary. It combines market sizing (historical and forecast), supplier economics, regulatory mapping, and executable templates that procurement, product and corporate development teams can deploy immediately. For executives preparing strategic bets in 2026 — whether launching a new cover product line, negotiating supplier contracts, or evaluating M&A — the full report provides the granular segment intelligence, supplier scorecards, and legal briefings necessary to execute with confidence.
Access to the full dataset, model files, and extended company dossiers is available through PW Consulting’s market research portal. The preview above highlights the key strategic takeaways while reserving the detailed, actionable intelligence that will materially change how teams act in 2026. Contact PW Consulting to obtain the complete report and tailored advisory support for implementation.
For detailed analysis of this topic, please visit the official page: Worldwide LED Tube Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Honeycomb Optical Breadboards Market to Grow at 6.25% CAGR, Reach USD 294.11 Million by 2032 as Top 5 Firms Command 72.15%
By PW Consulting, 2026-08-18
Worldwide Honeycomb Optical Breadboards Market — Strategic Briefing for 2026 Decisions
PW Consulting today releases a strategic industry briefing accompanying our full Worldwide Honeycomb Optical Breadboards Market report. Designed for C-suite leaders, procurement heads, R&D directors and corporate strategy teams, this executive summary highlights the macro trajectory, key competitive dynamics, material and supply-chain inflection points, and six pragmatic decision levers that should shape capital allocation and sourcing strategies in 2026. The full report contains the detailed subsegment modeling, vendor scorecards and transaction-ready benchmarking that buyers and investors use to act decisively.
Golf Insurance Market
Market trajectory and what it means for 2026
Between 2020 and 2025 the honeycomb optical breadboards market demonstrated resilient expansion, rising from a baseline in 2020 to an estimated USD 192.4 Million (revenue unit: Million) in 2025. PW Consulting projects the market to continue its steady climb underpinned by precision photonics demand, modular laboratory infrastructure upgrades and increased aerospace & defense spending. Our base forecast for 2026 is approximately USD 202.0 Million, with a compound annual growth rate of 6.25% across the 2026–2032 forecast window and a projected market size approaching USD 294.1 Million by 2032.
Hysteroscopic Surgery Simulator Market
This growth profile signals three practical realities for corporate decision-makers in 2026: (1) the market is large enough to sustain specialized suppliers and new entrants, (2) established vendors retain meaningful pricing power and channel control, and (3) technology and material innovation — not volume alone — will differentiate winners. The market concentration metrics are instructive: the top three vendors account for a majority share (CR3 ~58.4%), and the top five consolidate roughly 72% (CR5 ~72.15%), underlining persistent advantages for incumbents while leaving room for niche disruptors.
Worldwide DEET Repellents Market
What the report contains — practical, actionable modules
- Market-sizing model (historical 2020–2025 and forecast 2026–2032) with scenario outputs tied to demand drivers and macro scenarios.
- Supply-chain and raw-material mapping that links core materials to cost volatility, lead times and single-source risks — including a focused analysis on aluminum and alternative core materials.
- Vendor profiles and scorecards covering product portfolios, manufacturing footprints, aftermarket services and estimated competitive moats.
- Technology and product appendix comparing construction approaches (steel honeycomb, aluminum honeycomb, hybrid machined monoliths, composite skins) against vibration-damping, stiffness-to-weight, thermal stability and cleanroom compatibility.
- Commercial playbook for procurement and pricing: negotiation levers, volume bundling strategies, warranty and performance test clauses, and lifecycle TCO templates.
- M&A and partnership heat-map highlighting target characteristics and integration risks for strategic acquirers and private equity.
- Executive-ready dashboards for board and investor updates, with buy/hold/accelerate recommendations tailored to vendor or buyer archetypes.
We deliberately structure the full report to be execution-oriented: every analysis is paired with a recommended action, a confidence rating and an estimated timeline for implementation.
Key market dynamics shaping supplier and buyer strategies
- Material trade-offs are central. Aluminum-based cores remain widespread across the broader honeycomb material landscape; PW Consulting’s sector analysis indicates aluminum cores represented a significant share of the broader honeycomb core materials market in 2025. Simultaneously, thermoplastic alternatives (notably polypropylene) show above-market expansion potential—projected to grow at roughly an 10.98% CAGR to 2031—driven by recyclability and moisture-resistance attributes. Buyers must therefore weigh cost, environmental goals and performance under lab conditions when specifying core materials.
- Customization and modularity continue to accelerate. Aerospace OEMs and research institutions increasingly require configurable platforms that integrate vibration isolation, cable routing and rapid reconfiguration. This trend favors suppliers with flexible manufacturing and responsive engineering-to-order capabilities.
- Regulatory and technical expectations emphasize performance. Honeycomb architectures deliver high stiffness-to-weight and inherent structural damping — features now embedded in buyer RFPs for precision photonics and laser applications. This technical baseline raises the bar for commoditized offerings and prioritizes validated performance data in procurement decisions.
- Concentration and channel control. With a market structure where the top suppliers hold a dominant combined share, large buyers encounter asymmetric supplier power in certain geographies and product niches. Diversification strategies and dual-sourcing arrangements are effective hedges.
Competitive landscape — strategic positioning of core vendors
- Thorlabs (Newton, NJ, USA) — Strengths: well-known Nexus series with all-steel construction and damped platforms tailored for precision photonics setups. Strategic implication: strong channel access to research labs and academic institutions; competitors face cost-and-service trade-offs when pursuing that end market.
- Newport Corporation (Irvine, CA, USA) — Strengths: broad scientific-grade product portfolio with constrained-layer core options and flexible skin thicknesses. Recent move: product rationalization in late 2025 (discontinuation of an industrial-grade model in favor of a scientific-grade replacement) signals portfolio sharpening to protect margins and simplify service logistics. Strategic implication: expect selective rationalization and targeted new SKUs rather than broad price-driven expansion.
- Technical Manufacturing Corporation (TMC, Peabody, MA, USA) — Strengths: hybrid and monolithic machined aluminum honeycomb structures emphasizing stiffness-to-weight and flatness. Recent move: active exhibition presence at SPIE Photonics West (2025), reinforcing brand leadership among professional optics buyers. Strategic implication: TMC is positioned for premium segments where performance justifies price premiums.
- EKSMA Optics and Standa (Vilnius, Lithuania) — Strengths: European manufacturing footprint, specialized series for optical tables and anodized aluminum variants; capability to serve continental research and OEM channels. Strategic implication: well suited for buyers prioritizing regional supply security and customization.
- Base Lab Tools, Holmarc, DAEIL Systems, OptoSigma — Strengths: variant-focused portfolios including lightweight aluminum honeycomb, magnetic stainless top skins and high core-density options for rigidity. Strategic implication: these players form a long tail of global supply; they represent logical partners for local distribution, cost-competitive bids and tailored engineering services.
Across the competitive set, differentiation is built on three pillars: demonstrable vibration performance, manufacturing flexibility, and after-sales support. Sellers that can combine engineered materials expertise with validated test results and global service coverage will command premium positioning.
Six strategic imperatives for 2026
- Prioritize validated performance over nominal specs. Require third-party vibration/damping and flatness test reports as contract conditions to avoid specification risk.
- Lock dual-sourcing arrangements for critical SKUs in regions where supply concentration is highest. Use staged contracts that increase volume as vendors demonstrate on-time delivery and performance.
- Reassess material strategy with an eye to sustainability and lifecycle cost. Consider pilot programs substituting thermoplastics where moisture resistance or recyclability matters; maintain aluminum or steel cores where thermal stability and rigidity are non-negotiable.
- Negotiate bundled service-level agreements that include calibration, reconditioning and a clear spare-parts roadmap—these are high-leverage negotiation points often overlooked in initial quotes.
- Monitor incumbents’ portfolio rationalizations and trade-show footprints as leading indicators of strategic focus (e.g., recent product consolidation moves and major trade-show investments). Use these signals to time procurement windows or to identify acquisition targets.
- Adopt modular specifications in RFPs to enable future retrofits. Standardize hole patterns and mounting interfaces across new buys to reduce long-term integration friction and reconfiguration cost.
How buyers, OEMs and investors should use PW Consulting’s full report
- Buyers: to create a defensible procurement specification, identify two preferred vendors per SKU, and run a short proof-of-concept period to validate manufacturer claims before committing to multi-year contracts.
- OEMs: to shape component sourcing strategies that balance technical performance, weight targets and sustainability goals—particularly where modular architecture is a differentiator in system integration.
- Investors and strategic acquirers: to screen targets by capability (machining vs. laminated vs. monolithic), regional reach, and aftermarket revenue potential. Use the vendor scorecards and CR analysis in the full report to fast-track diligence.
PW Consulting’s full Worldwide Honeycomb Optical Breadboards Market report contains the granular segmentation, subregional demand splits, vendor share tables and downloadable vendor scorecards that informed the executive conclusions above. These subsegment tables are intentionally gated: they are provided to license holders and report purchasers so decision-makers can act with precise, proprietary inputs rather than directional estimates.
Next steps
- If you are planning procurement cycles, R&D product roadmaps or M&A activity in 2026, schedule a strategy briefing with our industry team to map the report outputs to your enterprise decision calendar.
- For sample data extracts, vendor benchmarking templates, or to commission a custom scenario run (e.g., supplier disruption, material price shock, rapid adoption of thermoplastic cores), contact PW Consulting’s industry desk to arrange a research license.
PW Consulting’s analysis synthesizes primary interviews, vendor disclosures and our proprietary demand model to translate market trends into actions. The high-level context provided here is intended to guide initial strategy. For the full data, scenario models and vendor-validated intelligence that supports capital deployment in 2026, access the full report and appendices via PW Consulting.
For detailed analysis of this topic, please visit the official page: Worldwide Honeycomb Optical Breadboards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Low Vision Devices Market to Reach USD 1,115.24 Million by 2032, Forecast to Grow at 7.2% CAGR (2026–2032)
By PW Consulting, 2026-08-18
Worldwide Low Vision Devices Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market study on Worldwide Low Vision Devices frames a pivotal inflection for industry participants, health systems, and investors as they plan 2026 strategies. The market demonstrated steady expansion through the recent historical window (2020–2025), rising from an estimated USD 597.45 Million in 2023 to USD 685.5 Million in the base year 2025. Our forecast (2026–2032) projects continuation of this trajectory, with the market reaching approximately USD 1,115.24 Million by 2032 at a compound annual growth rate (CAGR) of 7.2%. These macro dynamics—combined with intensifying technology convergence, evolving reimbursement norms, and regulatory activity—create a distinct set of opportunities and risks for incumbent suppliers and new entrants alike.
Long-distance Wireless Connection MCU Market
Why this report matters for 2026 planning
-
Timing: 2026 is the first forecast year in our model; choices made now shape product roadmaps, clinical programs, and channel investments that yield returns over the full forecast window.
Worldwide Military GNSS Anti-Jamming and Anti-Spoof Solutions Market -
Market momentum: Historical growth and a healthy mid-single-digit CAGR create an environment where scale and differentiation both matter—early, targeted actions meaningfully influence market share trajectories.
Worldwide XML Databases Software Market -
Regulatory & reimbursement inflection: Recent regulatory clearances and emerging reimbursement nuance (e.g., device vs. rehabilitation service coverage) require calibrated regulatory strategies and payer engagement plans to accelerate adoption.
Report content — what’s inside (practical, useable intelligence)
-
Forecast model & methodology: Transparent bottom-up market sizing for 2020–2025 and forward-looking projections for 2026–2032, with sensitivity scenarios that illuminate downside, base, and upside paths.
-
Segment & channel architecture: Multi-dimensional segmentation by product type, end-user, and region, together with distribution channel maps and pricing benchmarks. (Note: detailed segment tables and granular regional splits are reserved for the full report.)
-
Competitive playbooks: Strategic profiles, capability matrices, product roadmaps, and go-to-market tactics for the leading players and fast-moving challengers.
-
Regulatory & reimbursement navigators: Practical guidance on 510(k) pathways, exemptions, HCPCS usage, and Medicare/Medi-Cal nuances that materially affect commercialization timing and unit economics.
-
Commercial execution tools: Sales channel optimization, value-based contracting options, clinical evidence generation templates, and a prioritized list of clinical partnerships for accelerated adoption.
-
M&A and investment intelligence: Acquisition candidate typologies, valuation multiples observed in adjacent assistive-technology deals, and an M&A heat map identifying strategic gaps for bolt-on consolidation.
-
Primary research assets: Executive interviews, payer roundtables, clinician panels, and end-user usability testing that underpin our demand assumptions and buyer personas.
Market structure and competitive landscape — what leaders are doing
The low vision device ecosystem today combines classic optics, electronic video magnifiers, and emerging AI-enabled wearables. Market concentration is moderate: our analysis shows the top three vendors account for roughly one-third of market revenues, while the top five collectively approach half the market—indicative of meaningful incumbency advantages but also substantial room for disruption.
-
Electronic-video specialists and digital integrators (e.g., established makers of desktop and portable video magnifiers) continue to defend share through incremental innovation—improvements in OCR, contrast algorithms, and text-to-speech are common product differentiators.
-
Optical specialists and premium optics houses retain a stable clinical position for tasks demanding high-fidelity imaging (e.g., reading, near work), supported by long-standing clinical relationships and fitting services.
-
AI wearables and head-mounted systems are moving from early adopter clinical use into broader commercial rollout, supported by regulatory clearances and improving real-world performance data.
Key organizations profiled in the report include global and regional leaders across these categories—each evaluated on technology stack, clinical evidence, distribution reach, pricing strategy, and M&A posture. Organizations profiled range from companies specializing in portable and desktop electronic magnifiers to manufacturers of AI-powered wearable readers and bioptic optical systems. For competitive benchmarking, the report provides an actionable matrix linking capability gaps to acquisition and partnership targets.
Regulatory and reimbursement dynamics — implications for go-to-market
-
Regulatory pathways: Several device types are subject to FDA classification (e.g., electronic vision aids, telescopic systems), with many electronic and optical devices following 510(k) requirements while some low-risk optical aids remain exempt. Manufacturers must align product design and clinical evidence planning to the applicable pathway early to avoid time-to-market drag.
-
Reimbursement nuance: Medicare and other public payers typically fund low vision rehabilitation services rather than the device purchase itself, creating a gap between clinical utility and patient out-of-pocket costs. State-level programs and HCPCS-coded pathways (where applicable) can materially affect uptake in targeted markets.
-
Strategic implication: Vendors should triangulate regulatory cost-timing with payer engagement—investing in claims support, durable medical equipment (DME) strategies where feasible, and bundled rehabilitation offerings can increase effective addressable demand.
Technology inflections and clinical breakthroughs
Our research catalogs rapid progress at several technology frontiers that will re-shape competitive dynamics during 2026 and beyond:
-
AI-enabled audio-visual assistance: On-device OCR, object recognition, and context-aware UI are improving usability for daily tasks, compressing the time between clinical demonstration and real-world adoption.
-
Wearables: Head-mounted and glasses-like solutions are becoming more clinically credible as regulatory clearances accumulate and battery/image processing trade-offs improve.
-
Neuroprosthetics and implants: Breakthrough regulatory milestones and clinical trial activations in early 2026 signal a longer-term potential shift toward restorative technologies that could re-frame the severe-vision-loss segment—requiring incumbent players to consider adjacent R&D and partnership strategies.
Recent industry developments and strategic takeaways
-
Breakthrough device designations and clinical approvals in early 2026 highlight an acceleration in restorative technology development. These events elevate the strategic value of early-stage clinical partnerships and emphasize the need for scenario planning across conservative and disruptive adoption curves.
-
Notable device-level regulatory clearances for AI-enabled wearable readers in late 2025 reflect a pathway for rapid commercialization—companies that marry regulatory dexterity with post-market evidence generation can secure premium positioning.
-
Actionable recommendation: Sponsors should prioritize modular product architectures and open APIs to enable rapid integration of best-in-class AI and sensing modules, thereby reducing development lead times and preserving capital flexibility.
Practical recommendations for 2026 corporate strategies
-
Portfolio prioritization: Reassess R&D and marketing investments through the lens of use-case economics (reading, mobility, ADL support) and reimbursement levers. Prioritize product variants that align with funded service pathways or that enable subscription and services models.
-
Clinical evidence & regulatory sequencing: Build staged evidence plans—start with usability and real-world performance data to accelerate market acceptance, then layer on controlled studies to support premium claims and payer negotiations.
-
Channel & pricing: Strengthen relationships with rehabilitation providers and vision clinics that influence patient adoption; pilot bundled service + device offerings to reduce acquisition friction and create recurring revenue opportunities.
-
M&A and partnerships: Use a strategic playbook to identify targets that fill critical capability gaps (e.g., AI algorithms, wearable optics, patient engagement platforms) and accelerate time-to-market with lower capital burn than greenfield development.
-
Supply chain & manufacturing: Near-term demand growth favors suppliers with flexible manufacturing and component diversification—invest in alternative sourcing and extended warranties to protect margins during scale-up.
How PW Consulting’s intelligence supports decision-making in 2026
This report is designed as a strategic toolkit for C-suite leaders, corporate strategists, BD teams, and investors who need to convert market trends into executable plans within 12–24 months. We combine quantitative models (transparent assumptions, scenario outputs, and sensitivity analyses) with qualitative insight (clinician interviews, payer perspectives, and end-user voice) so that recommendations are testable and immediately actionable.
Next steps and how to access full findings
The analysis above intentionally highlights high-level drivers and recommendations while reserving granular segment-level shares, regional breakdowns, and detailed vendor revenue tables for the full report. Organizations that require the segment tables, pricing curves, and the complete vendor benchmarking matrix should consult the comprehensive report page on PW Consulting’s website—where downloadable datasets, slide decks, and bespoke advisory options are available to inform 2026 planning cycles.
For leadership teams planning capital allocation, clinical programs, or M&A activity in 2026, this report provides the evidence base to de-risk decisions and to accelerate value capture across a market that is expected to more than 60% expand from the 2025 base by 2032 under our base-case forecast.
For detailed analysis of this topic, please visit the official page: Worldwide Low Vision Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Enclosed Track Conveyors Market to Grow at 5.85% CAGR Through 2032
By PW Consulting, 2026-08-18
Worldwide Enclosed Track Conveyors Market: Strategic Preview for 2026 Decision-Makers
Executive teaser from PW Consulting — actionable intelligence without spoiling the verdict
As companies finalize capital plans and line-reconfiguration programs for 2026, enclosed track conveyors are moving from niche finishing tools to mission-critical infrastructure across manufacturing and distribution. Our latest PW Consulting report, with a 2025 base year, sizes the global market at USD 784.5 Million in 2025 and projects steady expansion through the 2026–2032 forecast window at a compounded annual growth rate (CAGR) of 5.85%. This briefing distills the strategic implications of those trajectories and highlights the operational trade-offs executives must weigh — while reserving the granular segmentation and deal-level figures for the full report.
Worldwide Media Monitoring Software Market
Market snapshot and what the topline means for strategy
-
Market momentum: A mid-single-digit CAGR reflects a balance of tailwinds — automation demand, contamination control requirements, and e-commerce fulfillment complexity — against headwinds such as cyclical capex and upstream steel/motor supply volatility.
Worldwide Spy Cameras Market -
Concentration and competitive posture: The market shows moderate concentration, with the three largest suppliers accounting for roughly one third of global revenues and the top five approaching half of the market. This structure creates space for specialized regional players and component suppliers to capture service, retrofit, and niche-application value.
Worldwide Bag Heat Sealer Market -
Timing signal: With total market volumes increasing but not exploding, 2026 will prioritize targeted investments that maximize throughput gains and minimize disruption — incremental automation, modular layouts, and service agreements will dominate procurement criteria.
Why enclosed track conveyors matter now
-
Automation without footprint bloat: Enclosed track systems allow overhead routing that preserves floor space and simplifies the integration of robotic pick/place and work-in-process (WIP) buffers — a critical capability as manufacturers densify production lines and logistics centers.
-
Contamination control and safety: Enclosed chains and trolleys reduce particulate shedding and provide cleaner environments for powder coatings, food-grade lines, and sensitive electronics assembly. The updated ASME B20.1-2024 safety standard, including new guidance on dust hazards, raises the compliance bar and influences specification language in procurement contracts.
-
Service and lifecycle economics: Given the mechanical orientation of the technology, aftermarket support, spare-part availability, and retrofitability frequently outweigh initial price in total cost of ownership (TCO) models — especially for mid-life asset refreshes.
Competitive landscape — what differentiates winners from followers
The market combines legacy OEMs with deep install bases and newer, agile suppliers focusing on specific verticals or componentry. The full report contains vendor scorecards and go-to-market maps; below is a strategic summary of the types of competitors shaping 2026 procurement decisions.
-
Legacy systems integrators leverage decades of installed systems, broad catalogs, and service networks. Their strengths are uptime, standardization, and compatibility with heavy-production environments.
-
Modular and specialized vendors bring compact, configurable platforms targeting light-to-medium loads, powder-coating lines, and tight footprints. These players often win where installation time, flexibility, or cost sensitivity are decisive.
-
Component and chain specialists supply the high-wear elements — tracks, trolleys, and chains — and can influence procurement via aftermarket agreements and parts availability.
Representative firms profiled in the report include established overhead monorail providers, manufacturers of enclosed-chain components, and regional systems houses. Notable vendor trends we flagged in our analysis include product modularization for faster installs, integrations with robotic cells for warehouse automation, and an increased emphasis on enclosed-chain designs for contamination-sensitive processes.
Recent industry moves and regulatory context
-
Product and integration momentum: Vendors are demonstrating integrated solutions that combine enclosed track conveyors with robotics and vision systems for order fulfillment tasks — a trend showcased by major OEM exhibits in 2025 trade events.
-
Standards and compliance: The 2024 revision to ASME B20.1 added a focus on dust hazards, directly affecting specifications for enclosed track conveyors used in powder coating and other dusty processes. OSHA reiterations linking conveyor safety to ANSI/ASME standards reinforce the need to bake compliance into procurement and maintenance contracts.
-
Supply-chain sensitivity: Systems rely on specialized steel profiles, chain, and motor subassemblies. Our supply-chain review identifies lead-time variability and raw-material cost exposure as primary operational risks that can affect project schedules and margin assumptions.
What the PW Consulting report delivers (practical contents)
The full study is built for action-takers. It contains:
-
Validated market sizing and a transparent forecasting model for 2026–2032, including scenario analysis for macro slowdown and accelerated automation adoption.
-
Vendor scorecards with product footprints, regional strengths, and aftermarket capabilities — enabling shortlist creation for RFPs.
-
Procurement playbooks and technical specifications templates that align safety standard requirements (including ASME B20.1-2024) with commercial terms and SLA clauses.
-
Capex/Opex and TCO models for head-to-head comparisons of overhead enclosed track vs. alternative conveyance (I-beam, towlines), including sensitivity to labor and part-replacement cycles.
-
Use-case deep dives — automotive, industrial finishing, e-commerce fulfillment, food & beverage, and electronics — with retrofit vs new-build decision matrices.
-
Supply-chain risk maps and sourcing strategies for steel and drivetrain components, plus a checklist for qualifying component suppliers and service partners.
-
Near-term M&A and partnership scenarios identifying likely targets for strategic buyers and private equity, based on capability stacks and aftermarket revenue streams.
Strategic recommendations for 2026 planning
Below are the executive-level actions we advise based on our analysis of market dynamics, vendor capabilities, regulatory shifts, and supply risks. These are structured to be implementable within 6–18 months.
-
Design for modularity: Prioritize conveyor architectures that allow phased deployment. Modular enclosed track systems reduce downtime risk and accelerate payback when paired with incremental automation.
-
Prioritize aftermarket and service contracts: When evaluating vendors, weight spare-part availability, predictive-maintenance support, and defined SLA remedies more heavily than unit price. Our TCO scenarios show service regimes materially affect lifecycle cost.
-
Embed compliance into RFPs: Update technical specifications to reference the latest ASME/ANSI requirements and dust-hazard mitigations. Require proof-of-concept test runs for critical dust-prone and food-grade lines.
-
Diversify component sourcing: To mitigate steel and motor lead-time risk, qualify at least two vendors for critical chain and track components and include price-escalation triggers and lead-time remedies in contracts.
-
Capture digital lift: Seek conveyors with retrofit-friendly sensor mounts and open control architectures to enable condition monitoring, digital twin simulations, and incremental robotics integration.
-
Plan service-part inventory strategically: Maintain a calibrated spare-parts inventory for high-wear items aligned to throughput risk tolerances rather than blanket stockpiling; use usage-based reorder points informed by vendor reliability data.
-
Consider partnership plays: For OEMs and integrators, look for component specialists and regional systems houses with complementary service footprints as acquisition or alliance targets to expand aftermarket revenue.
How to use the report in RFPs and board discussions
For procurement teams, the report’s vendor scorecards and specification templates shave months off RFP drafting and create a defensible selection trail for audit. For C-suite and board members, the scenario analyses provide clear downside buffers and upside capture plans to quantify the ROI of investments in enclosed track systems versus alternative conveyance strategies.
Closing — a preview, not a spoiler
Enclosed track conveyors are no longer just “material-handling” accessories; they are strategic enablers for throughput optimization, contamination control, and modular automation. The market’s measured growth profile — underpinned by a 5.85% CAGR across the 2026–2032 forecast window and a 2025 baseline of USD 784.5 Million — rewards disciplined deployment: choose vendors for reliability and service, design for modularity, and hardwire compliance and supply-risk mitigation into contracts.
PW Consulting’s full Worldwide Enclosed Track Conveyors Market report contains the granular regional, type, and application splits, vendor-level financials, and the procurement-ready tools referenced above. If your 2026 capital plan touches finishing lines, distribution automation, or overhead material handling, the study is intended to be the tactical playbook you bring to the negotiation table.
Contact our research desk to access the full report and the interactive financial model.
For detailed analysis of this topic, please visit the official page: Worldwide Enclosed Track Conveyors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide BOPS Sheet Market to Reach USD 687.1 Million by 2032, Growing at a 3.79% CAGR from USD 529.23M in 2025
By PW Consulting, 2026-08-18
Worldwide BOPS Sheet Market: Strategic Preview for 2026 Decisions
Executive summary
PW Consulting’s latest Worldwide BOPS Sheet Market report (base year 2025; historical 2020–2025; forecast 2026–2032) offers a strategic, action-oriented intelligence package designed to inform C-suite, procurement, and investment decisions in 2026. The market reached USD 529.23 Million in 2025 and is forecast to grow to USD 687.10 Million by 2032, reflecting a compounded annual growth rate (CAGR) of 3.79% over the 2026–2032 forecast window. Market concentration is meaningful: the top three players account for a material share of global supply (CR3 ~38.5%), while the top five consolidate roughly half the market (CR5 ~52.1%).
Worldwide Automatic Flight Control System (AFCS) Market
Why this report matters for 2026
2026 is a pivotal planning year for organizations that rely on biaxially oriented polystyrene (BOPS) sheets — from food-packaging OEMs to pharmaceutical blister manufacturers and thermoforming processors. Two structural dynamics converge now: (1) feedstock and input-cost volatility, exemplified by a sharp bout of styrene monomer price pressure in early 2026, and (2) accelerating regulatory and corporate commitments to recyclability and lower-carbon packaging solutions. Senior leaders who treat BOPS as a strategic raw material — not a commoditized film — will capture margin upside, secure supply, and accelerate product differentiation.
Worldwide Penetration Testing and Information Security Training Market
Headline market trajectory
- Market scale and momentum: USD 529.23 Million in 2025, projected to expand to USD 687.10 Million by 2032.
- Forecast growth: a steady CAGR of 3.79% across 2026–2032 under PW Consulting’s central scenario.
- Competitive structure: moderate concentration with several regional and global champions; CR3 ≈ 38.5% and CR5 ≈ 52.1% reflect a market where both scale and regional footprints matter.
Near-term dynamics shaping 2026 decisions
PW Consulting models show three immediate dynamics that should dictate board-level priorities this year.
Worldwide Bibliographic Management Tool Market
- Feedstock and input-cost risk: Styrene monomer — the primary upstream feedstock — experienced significant tightening in early 2026. Northeast Asian styrene prices reached approximately USD 1.13/kg in March 2026, roughly 15% higher than late-2025 levels, driven by maintenance turnarounds and robust demand from polystyrene producers. That pressure propagated into polystyrene markets in Asia, raising conversion-cost baselines and squeezing producers that lack forward coverage or flexible feedstock strategies.
- Regulatory and policy tailwinds for recyclable packaging: Major producers continue to certify BOPS for food contact under FDA and EU frameworks, and national packaging strategies — for example, recent five-year plans that promote recyclable materials — are supporting demand. These policy signals accelerate adoption in markets prioritizing single-material, circular solutions.
- Sustainability as a product differentiator: Leading manufacturers have begun to deploy mass-balance and biomass-derived inputs to create lower-carbon BOPS options. Early movers gain both procurement and brand-approval advantages with downstream food and pharma customers that have decarbonization targets.
Competitive landscape — who matters and why
The BOPS sheet value chain blends global technology leaders with high-capacity regional producers. PW Consulting’s competitive analysis — combining capacity mapping, public disclosures, and technical benchmarking — highlights three archetypes of suppliers:
- Technology-driven incumbents — firms that combine proprietary sheet formulations, advanced thermoformability, and global sales channels. Example: Denka Company Limited (Tokyo) markets the THERMOSHEET BOPS range, known for transparency and thermoformability, and has introduced a Biomass BOPS variant using a mass-balance approach to address sustainability goals.
- Diversified chemical majors — global polymer businesses producing premium-grade BOPS with strong regulatory compliance and R&D depth. Example: Mitsubishi Chemical Corporation (Tokyo) with Santoclear™ and Softclear™ product families emphasizes transparency and thermoformability for food applications.
- High-volume regional producers — large-capacity manufacturers that compete on cost, scale, and fast-to-market product variants. Several Chinese and other regional manufacturers drive volume supply into food and pharmaceutical packaging chains; their scale is a competitive advantage in price-sensitive segments.
PW Consulting’s in-depth supplier profiles in the report include production footprints, product portfolios, food-contact certifications, and innovation roadmaps for all major players, enabling procurement teams to shortlist suppliers based on technical fit and risk exposure rather than price alone.
Recent developments to watch
- Product innovation: December 2024 saw Denka introduce a Biomass BOPS sheet using the mass-balance method — an early commercial response to customer decarbonization mandates and a useful benchmark for peers evaluating similar moves.
- Input-price volatility: early-2026 styrene and polystyrene pricing trends underscore the need for sophisticated raw-material strategies (forward purchasing, captive integration, or strategic tolling arrangements).
- Standards and compliance: ongoing adherence to FDA and EU food-contact regulations remains table stakes; companies are differentiating by adding documented recycling pathways and post-consumer content claims.
What the PW Consulting report delivers — practical, executable content
Our market study goes beyond forecasts to provide a toolkit that enables actionable decisions in 2026:
- Scenario-based financial models: multiple price-path simulations that quantify margin impact under differing styrene/polystyrene trajectories and energy-price assumptions.
- Supply-risk heatmaps: supplier-level exposure assessments that combine concentration metrics, capacity cyclicality, and certification status to rank counterparty risk.
- Commercial playbooks: procurement contracting templates, recommended hedging approaches, and supplier-bundling strategies to secure continuity while preserving optionality.
- Product and portfolio roadmaps: guidance for packaging OEMs on migrating to single-material solutions, integrating anti-fog or barrier functionalities, and selecting suppliers for biomass or mass-balance offerings.
- M&A and investment thesis: prioritized targets and due-diligence checklists for roll-up, vertical-integration, or technology-acquisition plays, including valuation sensitivity to raw-material swings.
- Regulatory and sustainability compliance matrix: mapping of global food-contact certifications, recycled-content claims, and country-level packaging policy trajectories that will influence procurement and product spec decisions.
The full report contains detailed tables, supplier scorecards, and downloadable model files intended for immediate incorporation into 2026 planning cycles.
Strategic recommendations for 2026 decision-makers
Based on our analysis, PW Consulting recommends five priority moves for executives in 2026:
- Recalibrate procurement strategies: Move beyond spot buying. Secure layered coverage with a mix of short-term hedges, multi-year supply agreements, and conditional call-off contracts tied to feedstock-indexed pricing.
- Segment products by value capture: Identify SKUs that justify premium BOPS features (anti-fog, high-gloss, biomass claims) and prioritize dedicated supply streams for those lines to avoid leakage into commodity pools.
- Stress-test margins against feedstock scenarios: Use the report’s scenario models to define trigger points for price pass-throughs, promotional cadence changes, and temporary SKU rationalization.
- Pursue sustainability strategically: Evaluate mass-balance and bio-attributed BOPS not just for compliance but as a route to differentiated tenders with retail and pharma customers that will pay for verified lower-carbon packaging.
- Optimize M&A and partnership bets: Target assets that expand regional coverage or incrementally improve feedstock security (e.g., upstream styrene access, tolling arrangements, or recycling partnerships).
How to use this intelligence in 2026 planning
Procurement, operations, and corporate development teams should integrate PW Consulting’s outputs into three governance forums this year: (1) monthly procurement pulse with price-scenario updates, (2) quarterly product portfolio reviews aligning specs with supplier capabilities and sustainability targets, and (3) annual strategic investment committees that re-evaluate capex and M&A priorities using the report’s risk-adjusted return models.
Final note and call to action
This release is a strategic preview designed to demonstrate the depth and operational focus of PW Consulting’s Worldwide BOPS Sheet Market study. The report contains the full segmentation tables, supplier scorecards, and downloadable financial models needed to convert insight into 2026 decisions. For access to the complete dataset, supplier-level analytics, and executable templates, visit our report landing page or contact PW Consulting’s industry desk.
For detailed analysis of this topic, please visit the official page: Worldwide BOPS Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Bio-based Ethylene Glycol Market Set to Reach USD 2,177.15 Million by 2032, Riding an 8.25% CAGR
By PW Consulting, 2026-08-18
Worldwide Bio-based Ethylene Glycol Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market study on Worldwide Bio-based Ethylene Glycol (Bio-MEG) frames a rapidly maturing market whose macro trajectory is now clear: after growing from approximately USD 890.5 million in 2020 to USD 1,250.0 million in 2025, the market is projected to cross USD 2.17 billion by 2032 under the forecast scenario. Our 2026–2032 forecast period assumes a compound annual growth rate (CAGR) of 8.25%, a pace that materially changes the risk-reward calculus for investments, offtake agreements, and strategic partnerships in the renewable glycols value chain.
Worldwide Spiral Ore Washing Machine Market
Why this preview matters for 2026
-
Capital deployment windows are tightening. Several projects that were conceptual in 2023–2024 are moving toward engineering and FID in 2026–2028; timing and scale decisions made this year will determine market share capture through the first half of the next decade.
Worldwide Photography Software Market -
Feedstock strategy will define margins. As cost and availability dynamics for sugar-based and lignocellulosic inputs evolve, feedstock choice will be a primary determinant of unit economics and sustainability claims.
Black LiNbO3 and Black LiTaO3 Wafers Market -
Certification and traceability are no longer niceties. Access to premium European and corporate sustainability channels increasingly requires recognized chain-of-custody schemes and demonstrable life-cycle benefits.
Market trajectory and structural signals
The market’s historical volatility — from the sub‑billion-dollar base in 2020 to a USD 1.25 billion market in 2025 — reflects a combination of feedstock price swings, nascent capacity additions, and evolving commercial demand from packaging and fiber producers. Our forecast sees Bio-MEG shifting from a specialized renewable input to a broadly adopted drop-in for PET and polyester supply chains, with total revenues reaching USD 2,177.15 million by 2032 under the central case.
Concentration metrics in the current landscape indicate moderate consolidation: the top three producers account for roughly 42.5% of the market, while the top five represent about 61.2%. These figures highlight an industry where a small number of scale-capable players can exert meaningful influence on pricing, technology roadmaps, and feedstock sourcing strategies.
Key dynamics shaping 2026 decisions
-
Feedstock economics and sourcing flexibility. Sugarcane and molasses-based ethanol have been the most commercially mature routes; however, second‑generation lignocellulosic feedstocks (corn stover, straw, bagasse) are now demonstrably reducing feedstock cost exposure by an estimated 25–35% at scale. The trade-off is higher technical complexity and longer lead times to commercial operation.
-
Technology and scale-up risk. Pilot plants and demonstration units have advanced in multiple jurisdictions, including Chinese efforts converting corn stalks and straw sugars with over 40 patents supporting potential scale-up. The learning curve for catalytic and bioconversion routes will determine which platforms can meet mid-decade commercial throughput without compromising yields.
-
Regulatory and certification requirements. ISCC Plus and equivalent chain-of-custody frameworks are becoming gating factors for access to European and corporate procurement pools. Certification timelines and audit readiness must be included in any project FID model.
-
Capital intensity and project economics. Recent project announcements in North America and Europe indicate multi-hundred‑million-dollar greenfield investments for commercial-scale plants; these commitments necessitate granular techno-economic modeling and off-take security to justify execution.
Competitive landscape — players to watch (and why)
-
India Glycols Limited (Noida, India): One of the largest commercial producers of bio-MEG using molasses-based bio-ethanol. Its advanced commercialization history gives it operational experience and established routes to PET and polyester markets — an advantage when converting pilot learnings into reliable throughput.
-
Braskem (São Paulo, Brazil): Leveraging sugarcane ethanol expertise via its Sustainea joint venture, Braskem is positioned to supply renewable glycols into packaging and textile supply chains. The company’s existing feedstock integrations and sustainability credentials make it a strategic partner for downstream brands seeking scale and traceability.
-
Avantium (Amsterdam, Netherlands): Developer of PlantMEG via proprietary Ray Technology. Avantium’s differentiated technological approach targets premium sustainable PET applications and is an example of how licensing and technology partnerships can accelerate market penetration without the need for full-scale production ownership.
-
UPM (Helsinki, Finland): Working on wood‑sourced renewal of MEG at the Leuna biorefinery, UPM exemplifies the second‑generation strategy of reducing reliance on food-grade sugars. Projects of this nature are strategically important for players targeting fiber and packaging customers with stringent non-food-feedstock requirements.
-
Sustainea (Braskem‑Sojitz JV): The JV’s planned deployment in the United States — including a commercially scoped facility targeted to convert corn dextrose into MEG — signals a transatlantic push to supply North American demand with renewable glycols via existing ethanol infrastructure.
Recent developments that matter
-
Braskem is actively evaluating capacity expansion options tied to corn dextrose routes in the United States, reflecting a strategic assessment of localization and feedstock arbitrage.
-
Sustainea has public planning documentation for a USD 400 million facility in Lafayette, Indiana, with commercial start-up ambitions in the latter half of the decade — a clear indicator of private capex readiness to serve regional demand pools.
-
UPM’s Leuna biorefinery is preparing to introduce large‑scale wood‑sourced Bio‑MEG volumes, marking one of the first full‑scale examples of lignocellulosic-derived glycols aimed at packaging and fiber markets.
What our report delivers — practical assets for 2026 strategy
PW Consulting’s full report is structured to move decision-makers from high-level conviction to executable actions. Highlights include:
-
Market sizing and scenario models: transparent base-case, upside, and downside pathways to 2032 with sensitivity to feedstock prices, conversion yields, and policy shocks.
-
Investment readiness playbook: stepwise requirements for FID, from permitting and feedstock contracts to EPC timelines and ramp profiles, including a modeled capex range by technology route.
-
Feedstock cost curves and sourcing matrix: comparative economics for sugarcane, molasses‑derived ethanol, corn dextrose, and lignocellulosic inputs, with scenario-adjusted breakeven analyses and recommended hedging instruments.
-
Certification and market access checklist: ISCC Plus implications, traceability workflows, and supplier audit templates to accelerate market entry into European and corporate sustainability channels.
-
Commercial go‑to‑market playbooks: contractual structures (take-or-pay vs. tolling vs. JV), pricing levers, and channel strategies for selling into PET, fiber, and industrial applications.
-
Competitive intelligence and M&A radar: profiles of incumbent and emerging players, technology licensors, and priority acquisition targets organized by strategic fit and execution risk.
-
Risk matrix and mitigation options: operational, feedstock, regulatory, and reputational risks with practical mitigation approaches and staged contingency triggers.
How 2026 decisions should be framed — practical guidance
-
Prioritize feedstock optionality. Contracts and plant designs that maintain flexibility between sugar-based and lignocellulosic inputs materially reduce asset stranding risk as supply economics shift.
-
Synchronize certification with commercial launches. Obtain chain-of-custody certifications well ahead of product deliveries to avoid margin erosion from delayed market access.
-
Adopt staged capex deployment. Consider modular capacity additions and tolling partnerships to de‑risk early cash flows while preserving upside optionality as demand materializes.
-
Negotiate offtake structures tied to sustainability premia. Where buyers are willing, capture value through contracts that reflect verified life‑cycle performance and traceability credentials.
-
Monitor patent landscapes and pilot learnings. Recent pilot-scale wins, including patent-backed Chinese pilot plants, suggest technology leadership may be transient; proactive IP due diligence is essential for licensing or partnership strategies.
Closing — the strategic value of timely intelligence
As the Bio-MEG market transitions from early commercialization into scale-up, 2026 will be the inflection year for many strategic choices: who builds, who licenses, who partners, and who opts for tolling versus ownership. PW Consulting’s report equips executives with the market forecasts, operational models, and decision frameworks necessary to choose wisely.
We intentionally withhold granular regional and application-level revenue splits in this public preview to preserve the commercial integrity of our proprietary segmentation work. For access to the full dataset, interactive scenario models, and company-level TEA assumptions, please visit the report landing page and request the comprehensive package tailored for executive decision cycles in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Bio-based Ethylene Glycol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


